Small Cap Value Report (Thu 2 Nov 2017) - FEVR, BOO, EGS, NXR

Good evening, Paul here! I'm getting into the routine of putting up a placeholder article the night before, and I think it's working quite well - meaning that we can swap RNS ideas on trading updates & results, from 7am in the morning (tomorrow).
Talking of which, see you in the morning! Regards, Paul.
Good morning! It's Paul here.
The roaring bull market continues. Although I've noticed that a lot of UK small caps seem to be wobbling. Take Fevertree Drinks (LON:FEVR) for example - a previous high flyer, it's dropping sharply again today. Peaking recently at 2500p, I've just picked up a few (more as a trade than an investment) at about 1900p - that's a 24% drop from the recent high, quite a considerable retracement. A lot of other high flyers have done the same - e.g. Boohoo.Com (LON:BOO) is down 26% from the recent high (roughly 196p now, versus recent high of c.266p). It's interesting how so many companies have similar charts.
My broker has just flagged up to me that there's been a broker downgrade for FEVR today apparently. I probably should have checked out why it was falling before buying some! Oh well. It does reinforce though, that highly rated shares don't leave any room for disappointments.
The trouble is too, that I think so many market participants are now following Mark Minervini-style momentum trading, that once a stock breaks through the 50 or 200 day moving average, then a stampede of selling occurs. Could it be a buying opportunity? Who knows - only time will tell.
eg Solutions (LON:EGS)
We bid a tearful goodbye to this little software company, and its bizarre CEO, Mrs Gooch. The shares are suspended, following a scheme of arrangement to sell the company. We should get through 112.5p per share in cash fairly soon.
Supermarkets
I saw an interesting article yesterday, saying that major brands are signing up for a new service which will offer cheaper groceries direct to consumers. Apparently the idea is to use blockchain technology to cut out the middlemen (supermarkets), and offer groceries direct to consumers at wholesale prices.
This sounds fascinating, and could spell the end for supermarkets. I'm going through the numbers, with a view to opening short positions on supermarkets, which are potentially doomed, with their onerous fixed costs.
I wonder about shorting commercial property companies too. It seems to me that rents on retail premises are likely to collapse, long term. Although more & more warehouses are likely to be needed, as disruptive companies need distribution centres. Or are they? Maybe manufacturers might end up supplying customers direct, via fleets of self-driving electric delivery vans? So warehouses might also end up being a thing of the past? Fascinating times!
I think we have to be terribly careful with "value" shares at the moment. Mean reversion may not happen this time - a lot of low PER companies could be at the early stages of their death throes, due to the seismic changes occuring, driven by technology?
Norcros (LON:NXR)
Share price: 177.5p (down 2.9% today)
No. shares: 61.7m
Market cap: £109.5m
Acquisition & Placing/Open Offer - a reader has asked me to look at this. Norcros is a bathroom fittings group, operating in the UK & S.Africa. Today it announces another acquisition - of Merlyn Industries Ltd - a designer & distributor (hence by implication not a manufacturer) of mid to high end shower enclosures.
This is a major acquisition for Norcros, which is paying £60m for Merlyn, which is 55% of Norcros's market cap. This is being funded through a placing & open offer at 172p, to raise £31.4m before expenses. Numis is doing the fundraising - they're very good at raising money. The balance of the acquisition funding is debt - through a new £120m borrowing facility. That seems a rather large facility - I hope the company doesn't over-gear again, as it got into trouble with too much debt in 2008.
Merlyn seems to be highly profitable, so looks a nice acquisition. Although you have to bear in mind that private companies often don't pay Directors salaries, paying them via divis instead. So real profits can be lower than reported profits. That may or may not be the case here, I don't know;
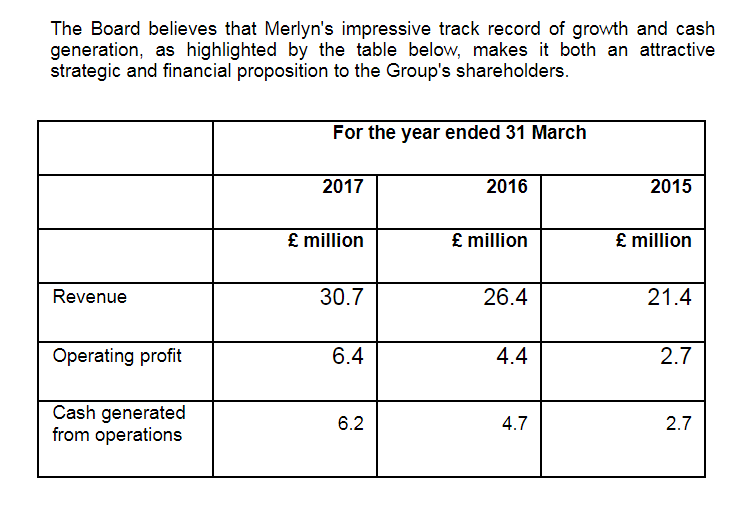
In the year ended 31 March 2017, Merlyn reported revenue of £30.7 million and operating profit of £6.4 million.
The track record at Merlyn looks terrific;
Trading update - there is an in line with expectations trading update in section 5.2 of today's announcement. Market conditions are described as "challenging".
My opinion - this looks like another good acquisition. I like the strategy at Norcros - to buy & build complementary bathroom fittings companies. This has worked well so far. Joining the Norcros group enables acquired companies to improve their routes to market. That sounds like management speak! I just mean that Norcros can sell more stuff through its existing sales network, when it acquires other companies.
The really good thing about making decent acquisitions, is that it enables Norcros to dilute its gigantic pension schemes. The pension deficit becomes less of a problem, as the group grows through sensible acquisitions. That should, in time, trigger a re-rating of the shares from the current extremely low PER.
I suppose the downside risk is that Norcros could be gearing up again at the top of the economic cycle - if that's where we are, nobody knows for sure. I'm tempted to buy a few NXR shares.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
It's not just the supermarkets - I read last weekend that Amazon in the US now have 30 of their own private label brands.
"On any given morning, you could smooth out your Pinzon Egyptian cotton sheets before tossing on a Goodthreads poplin dress shirt, Franklin Tailored sharkskin-gray suit and a pair of Franklin & Freeman penny loafers. Breakfast might be a bowl of 365 Everyday Value organic quick oats and Wickedly Prime dry-roasted almonds with a cup of Happy Belly organic Fair Trade coffee, as you lean back into your Strathwood chaise lounge.
Despite not bearing Amazon’s signature arched arrow, they’re all part of an army of more than 30 private labels that belong to the increasingly ubiquitous e-commerce behemoth, a bounty waiting to be innocently discovered online as modern shoppers ditch old-school name brands and seek out stuff that’s cool but cheap."
https://www.investors.com/news/target-amazon-private-label-exclusive-brands/
I dipped my toe into Elektron technologies Elektron Technology (LON:EKT) yesterday. No broker numbers which is in some ways a good sign that this is an under researched company. My work colleague alerted me to this company.
The skinny is that the Bulgin business which is "widely recognised as a leading manufacturer of environmentally sealed connectors and components" is v profitable (gross margin over 45% and net margin 20%) and growing fast. It's been around for 95 years, so is not just a flash in the pan. These are connectors that are used in harsh environments and prevent say water getting in.
The company is reinvesting much of the Bulgin cash flow into a product called Checkit. Checkit automates the testing process for food industry e.g. Temperature testing in supermarkets or in cafes. It claims 1) reduces regulatory risk as it ensures the testing is done and 2) saves the client money. So a bit of win win if it can get enough clients to use it. Should someone like Compass or Sodexo use it then that would be game changing and a real validation of the technology. Anyway Checkit is loss making, eating up much of Bulgins profits. Thus optically the profitability doesn't look great but you have to look behind the numbers. Bulgin makes annualised c£5m of EBIT, Checkit lees nearly this much. Hence low EPS and a PE of 50x.
But (and it's a big but)
If Checkit can get to profitability then this is a company trading on EV /EBIT of c7x. Ie cheap
If Checkit itself gets profitable then this company is going up a long way.
cash on B/S is £2m
Hi VegPatch,
I value your insights eg re CLI, so had a gander at EKT.
The advfn board (I know, I know ;->) has some stuff that might give pause for thought....
ATB
If supermarkets are selling more own brand goods which is all shoppers can afford then a consequence is branded goods have to find a way to survive too. I think it is the branded goods which are on a sticky wicket.
You could be right there, I notice in the recent results of companies such as £UNL they are struggling to grow. I rarely buy branded goods now, only if they are on sale, I find many own brands in Aldi are just as good or better (washing up liquid, washing liquid, cleaning products), why pay for all the advertising and marketing of big brands. Yes sometimes they are better.
Hi, I just thought I'd mention Best Of The Best (LON:BOTB) - they gave a trading update this time last year and then declared a special dividend a week later. However they did update us only 2 months ago which they didn't last year.
Profit forecasts have been affected by a deliberate increase in marketing costs and the price has been drifting recently. As a result Stockopedia currently categorise them as a "Falling Star" (low value and momentum).
I've done some quick research (Alexa, Google Trends, Facebook followers) and I can see no evidence that marketing investment is paying off with Alexa / Google Trends around or below this time last year and Facebook followers only up 13% since January (which I fear equates to stagnant or falling active interest).
On the plus side, the local newspapers (often operating on a skeleton staff nowadays) continue to be very happy to give them free advertising in exchange for a easy good-news story: https://www.botb.com/about/press.
That might explain some of the share price decline lately. I would much rather they focus on expanding internationally to help drive the SP. (I know they ship anywhere in the world but I can't see any evidence that they actively promote themselves in new markets). If they maintain the dividends it would still be a decent hold even if revenue remains flat.
Talking about technology changing everything, in our office today we were due to watch a nationally streamed video of how digitisation was happening. Unfortunately our cheapo PCs loaded with patched up, out of date software didn't have the right browser codec so turns out no-one could watch it. Meanwhile all the phones were down in every office in the country.
The blockchain stuff is everywhere. A Bloomberg columnist I follow, Matt Levine, covers it directly. A lot of the blockchain chat is just marketing. Most of what people are talking about could be done with a centrally managed distribution ledger, using existing software. Say like excel?
If I say I'm launching a food delivery company that's not interesting. But if I say I'm launching a blockchain enabled disintermediated sustenance supply chain management technology company then suddenly I'm the next big thing!
(See this from Matt Levine for an illustration of what I mean! https://www.bloomberg.com/view/articles/2017-08-23/blockchain-mania-and-mifid-ii)
Ref NXR
Those Meryln numbers look almost too good to be true - should one be a little bit skeptical that those numbers may be on steroids? - i guess time will tell
I guess my one concern with regard to NXR is that with such a lowly rating is there good value for current holders by issuing a large number of new shares - probably not unless one doubles down and buys some more. hmmmmm i may already have done that recently with NXR - hey ho lets have a basket full of eggs why not..
On a more positive note i am guessing that with a larger combined entity the pension issue will hopefully become slightly less of an issue (all other things being equal) and that may give one hope that that may lessen the adverse affect that this seems to permanently have on the shareprice - my presumption here
Regarding BlockChain, would you not still be better ordering from the supermarkets online service.
You still need an aggregator somewhere to bring all the products together so you can order them in one go.
"Reports of my demise are grossly exagerated" methinks for supermarkets
I'm interested to see your Norcros (LON:NXR) analysis Paul. I've also thought it is a play on interest rates (rises help to reduce its pension deficit). I don't want to be premature, but it is interesting to note how it has performed better recently with the interest rate speculation.(Although higher interest on loans might offset gains from pension deficit reduction).
Re FEVR, Royal Bank of Canada lowered price target from GBX2400 to GBX2000.
Paul, ref your musing above on the future of retail, Research Tree will be offering a series of reports on the changing face of the British high street.
The first has just been put online. A taster of it is:
"The changing face of retail in the UK
Brits have always loved to shop, and nothing typifies this love for spending more than the quintessential British High Street- the main retail strip found in every village, town, and city throughout the UK.
It's hard to believe that Christmas, the busiest shopping season of the year, is just 8 weeks away. And with the UK's most recognisable High Street, London's Oxford Street, set to turn on its famed Christmas lights in the coming days, we thought we'd take a deeper look at the changing face of the British High Street in our "Shifting High Street" series.
Whilst the High Street isn't set to die per se, it has changed and will continue to change, as it adapts to the shifts in consumer habits and spending and as we move away from shopping in brick and mortar retail sites.
This mini-series will cover a handful of sectors which have been markedly impacted by these changes in consumer habits and expectations. In this issue, we'll cover retail, and in the coming weeks, the banking sector, the real estate sector, and the casual dining sector.
For a headstart on our look at the casual dining sector read finnCap's Consumer quarterly sector note, called Shopping Trolley. It takes a deep dive into recent trends in the leisurely dining sector, and how these trends are impacting investors."
There was a discussion a couple of days back on the value of a subscription to Research Tree. For me, the value is as much in sector reports, such as the finncap note referred to, as in reports on individual companies. I find it not too difficult to research particular companies but (perhaps because I do not live in Britain) always wonder whether I understand completely the sector and macro picture.
"Brits have always loved to shop"
Most men I know hate shopping, if they said British women love shopping I would mostly agree.
Most high streets/shopping centres have the same shops, it's getting worse as rates rise it is forcing out the independent shops to be replaced by a national chain. Some high streets seem to be dying with large department stores closed, shops such as Argos moving out and other shops replaced by charity shops. Due to Argos takeover they have now gone from 3 shops to 1 in my local town in about 1 year.
I think some large shops such as Debenhams, could consider have food courts, as they do in Asia in shopping centres.
Anyone else getting security warning when going into ResearchTree, google says it's security certificate expired yesterday?
"Anyone else getting security warning when going into ResearchTree, google says it's security certificate expired yesterday?"
I am getting the certificate expired warning too.
The fact security certificate expired does not mean anything wrong with the site providing it is one you trust. You need to white list it on your addblocker. click to enter site, when warning comes up click on addblocker then click on 'enable for this site'
Thanks but it was a google warning. The problem seems to have gone now.
I was getting the message on my ipad which does not have addblocker.
I was reading today that Morrisons has grown now for 8 consecutive quarters, I must say I'm struggling to believe that whether via block chain technology, or any other method, (trendy though that sounds), I'm going to be ordering my ketchup seperately from my cornflakes direct from the manufacturer. Even if I could, how much saving would there be left when I have to pay for delivery ?
And am I now going to have to be in for all the individual deliveries ? and keep track of any that have got lost and chase them up individually ? Is this more convenient than ordering through a supermarket, or vi amazon (perhaps on alexa).
Personally I think we're already seeing the novelty of the budget supermarkets waning, with lfl' s up at tesco and morrisons. They have re aligned to the margin people are willing to pay to shop somewhere with more choice and not have to queue for so long on the way out.
Could be I'm being an old stick in the mud here but I'm thinking that the pendulum is swinging back, and while I might buy big items on line, weekly shops ? perhaps not so much. If I do I'll probably buy from one place, a place that has a really good range, good value and maybe free delivery (or pick up from somewhere nearby, like say my local supermarket ?), Not sure I can see the supermarkets being hit too badly. For my money the challange will be finding things to sell to fill their space, hence it looks like a good deal for sainsburys to buy argos. But time will tell,
K
Re: supermarkets... J Sainsbury (LON:SBRY) have half year results out in 1 weeks time. Should be interesting reading. If you look at their last trading update (from back in July included below) - you'll see that it is full of positive news.
https://www.investegate.co.uk/sainsbury-j--plc--sbry-/rns/first-quarter-trading-statement/201707040700059996J/
Either things have gone horribly wrong since then or they were pumping things up.
In the last few years J Sainsbury (LON:SBRY) has attracted a lot of shorters. And after the trading update in July the shorters started attacking again, although it looks like they are beginning to reverse out in the last few days:
https://shorttracker.co.uk/company/GB00B019KW72/
So hard to judge whether the supermarkets are fighting back or about to get flattened.
I sold my Norcros (LON:NXR) shares when the announcement was made this morning. Few reasons, really
- Now arguably not the time to load up on debt
- Enormous acquisition relative to mkt cap thus dramatically increasing risk
- PE sellers keen to exit
- Unsure if price is right to buy
- UK&I consumer loaded up on debt to max with wages failing to keep pace?
Re Norcros (LON:NXR), I'm a little concerned about this acquisition.
Norcros (LON:NXR) are funding the deal by placing their own shares at 0.4x sales, to acquire a business on 2.0x sales. Merlyn is a higher margin business but not sure it justifies the rationale outlined above.
My belief is that this deal has been proposed is due to:
1) To get Norcros (LON:NXR) closer to the revenue target for 2018
2) Numis convincing Norcros (LON:NXR) so that they get their lucrative fees.
"Acquisition expected to be earnings enhancing in the first full year of ownership, and return on investment expected to exceed Norcros' cost of capital" - so Merlyn's profit in Y1 will exceed the fees related to the acquisition, investment for synergies and transition costs (I would hope so!), and the return will exceed the cost of capital due to the current extremely low cost of capital. This doesn't make it a good investment however.
Also I am concerned whenever a company acquires a company from PE shareholders. I think there might have been smaller bolt on acquisitions at better value.
Previously Norcros (LON:NXR) have made good value acquisitions. Abode and Croydex were done on EV:EBITDA multiples of c. 6x, whereas this is on an EV:EBIT of c. 10x. (not entirely comparable, as i dont have the DA figures for Merlyn), but it doesn't appear as good value as previous acquisitions.
The General Meeting could be interesting.
Norcros (LON:NXR)
My initial thought was that the Price / Op Profit multiple of c. 9.4x looked a bit on the steep side.
Growth in earnings though has been very strong over the last two years (63%, 45%) and if this is organic and sustainable it's not unreasonable to assume an Op. Profit for the year to March-18 (On which there much be quite good visibility already) to be north of £8m, bringing the ratio down to 7.5x or so.
I don't know if the previous acquisitions had such embedded growth, but I suspect not.
Also with cash generation from Merlyn Ops matching Operating Profit, it can effectively pay down the costs of acquisition quite quickly.
(I do agree though with the worry that this might not be the best time in the cycle to be buying!)
With regard to the following comment:
...I've noticed that a lot of UK small caps seem to be wobbling. Take Fevertree Drinks (LON:FEVR) for example - a previous high flyer, it's dropping sharply again today. Peaking recently at 2500p, I've just picked up a few (more as a trade than an investment) at about 1900p - that's a 24% drop from the recent high, quite a considerable retracement. A lot of other high flyers have done the same - e.g. Boohoo.Com (LON:BOO) is down 26% from the recent high (roughly 196p now, versus recent high of c.266p).
I guess FEVR are dropping because of the stratospheric rating... but IMHO I don't feel that they can be compared to BOO in this commentary - BOO have specifically fallen to their current level based on worries about margins, and as such have a right to be clobbered, I don't believe there is any specific negative news about FEVR (I don't hold either).
I read Fevertree Drinks (LON:FEVR) fall is due to competition, Schweppes have rebranding and doing a media campaign. There maybe a trading statement out soon. I should have sold around £25 will hold on for now.
I don't think a rebranding by Schweppes will be enough. Now (and once) FEVR have embedded themselves in the supply then I dont see many outlets changing back without good reason. Here to stay, imo.
I agree with you, just reporting what some think is reason for the fall.
I saw the new Schweppes advert the other day and it was obvious that they're aiming right at FeverTree and the premium market. Pretty good summary: http://uk.businessinsider.com/coca-cola-schweppes-relaunch-fever-tree-fentimens-2017-10
Hi Paul, can you direct me to that article / link re: supermarket disruption via blockchain service?
I'd love to see that article too.
The use of Blockchain or distributed ledgers is supposedly going to be transformational for every step of the food industry (the so called Blockchain of Food). So I agree that the incumbent system will be disrupted - how soon and what the new world will look like is anyone's guess. This recent article makes for interesting background reading. https://www.forbes.com/sites/themixingbowl/2017/10/23/the-blockchain-of-food/#5bb6fe6a775f
It's probably this one:
https://blog.ins.world/how-blo...
The world is full of stories about how blockchain will change everything, but in reality all the blockchain is, is a distributed ledger - a record of transactions that's shared transparently between all the participants and which may be hard to fake - although that depends on the type of ledger and the immutability protocol being used.
Connecting a blockchain - a record of digital transactions - to the real world is easier said than done although IoT technology offers some interesting opportunities. But at the moment the best use cases are where the asset itself is digital - so maybe house deeds or insurance policies.
Above all the biggest issue with blockchain solutions is getting everyone to integrate with them, to agree standards and agree to share their data. Once you can do that you can certainly start to shape the supply chain and you may be able to replace the trust mechanism embedded in supermarket and food supplier brands with a chain of trust embedded in a blockchain.
Basically the article is largely correct in outline, but the idea that this will reshape the food industry and pose a major threat to supermarkets in the near future is a fantasy. Although supermarkets have their own competition problems anyway ...
timarr
Thanks, timarr. Must admit I am getting very concerned by the number of clouds and cuckoos around at the moment! It reminds me of when I first joined The Motley Fool in 2000 when all kinds of pie in the sky claims were being made about technology. You'd know far better than me why so many people always expect far more from technology than it actually ever delivers. Perhaps it's just me as I'm surrounded by the hype and BS every day!
All the best, Si
Hi Si,
I read that Forbes article and thought the same. If folk are shorting the supermarkets based on that then we are truly in the mad phase at the end of the bull market.
"Tech is disrupting everything, this is tech, it's got lots of buzz words I've heard before but don't really understand, it must be important, I must press the Sell or Buy button"
I shall give a free public lecture on Blockchain next January at the Museum of London (Gresham College). Details are here: https://www.gresham.ac.uk/lectures-and-events/will-bitcoin-and-the-block-chain-change-the-way-we-live-and-work and the video, slides and transcript will be there after the lecture. It will be live streamed on the Gresham College Facebook page.
It's part of a three-year series to demystify computing and to explain just how badly written most software is (and why, and what we can do about it), and how vulnerable we are to cyberattack as a consequence.
Some of the safety consequences are here: http://www.hse.gov.uk/events/i...
Hi FREng,
It's part of a three-year series to demystify computing and to explain just how badly written most software is (and why, and what we can do about it), and how vulnerable we are to cyberattack as a consequence.
Some of the safety consequences are here: http://www.hse.gov.uk/events/i...
I see your opinion of software engineers and the mess they are creating for the interconnected world in writing poor quality and badly verified software matches my own :) Of course, one of the main reasons for this is that no-one has the time to do anything properly these days such is the emphasis on time to market for new products. From reading your notes I assume you are familiar with the output of my favourite blogger, Bruce Schneier?
All the best, Si
Si
Yes, Bruce Schneier is always worth reading on cybersecurity. I get his monthly email.
Ross Anderson and his colleagues on lightbluetouchpaper.org are good too.
FREng
I think big changes in tech usually under deliver in the short term but over deliver in the long term. Take the www expectations in 2000 vs the actual world now with it used in so many ways that no-one anticipated.
I think big changes in tech usually under deliver in the short term but over deliver in the long term. Take the www expectations in 2000 vs the actual world now with it used in so many ways that no-one anticipated.
Hi Richard,
Yes, I completely agree and that was the point I was trying to make i.e. it's no good just being right about which technologies will take-off commercially and which will not (which is almost impossibly difficult) but you also need to get the timing right from an investment perspective. There are too many completely hopeless small technology companies around at the moment on crazy valuations which reminds me greatly of the market 18 years ago. Buyer beware...
All the best, Si
Too true, Richard
I remember getting excited by the prospect of 3G mobile telephony back in 2000.. but had to wait for years before it became a commercial reality!
Gartner publish an annual 'technology hype cycle' to illustrate how expectations get ahead of the implementatiton of any new technology. From their latest chart, it would appear that expectations for Blockchain will soon begin to plummet:
And then of course we have the hype cycle hype. Not criticising your post Richard, just rather wary of these types of charts from consultants and analysts.
What is the evidence that these individual technologies are actually on this shape curve for expectations at all? And how do they know where they are on this curve? Has it been tested in some way to actually verify that it has predictive power? Are the techniques to measure level of expectation comparable one innovation to another? Is this something as crude as measuring frequency of certain keywords appearing in the media?
Who’s to say that expectations of autonomous vehicles have now peaked and that people are becoming disillusioned with the idea?
While this curve may be a very general illustration that is often true, it is far from being a universal truth. Take the iPod and iPhone for example. They created new product categories. Where was the trough of dissolution for those?
To me it is a nice picture but pretty much an arbitrary view that has little usefulness for investment decisions for any specific innovation. It does however serve as a reminder that pretty much anything new may be clouded by hype. That can go for a new fashion retailer as much as a bit of tech.
Thanks @Graham Ford and @Howard Marx. It's a fun exercise that makes an excellent point but I don't think it's meant to be the basis of investment decisions except in the most general sense. As you say, there are practical issues!
Look at the bottom category on the far left of the curve "smart dust".
WTF?
Maybe the analyst has been smoking too much of it himself (or herself)?!
No, it's a real thing:
But perhaps most mind-bending of all is considering what happens when sensors, antennas, and even computing equipment can be combined into information gathering devices on the microscale. This is a concept known as “smart dust,” and it’s been kicked around in science fiction and research communities for awhile.
https://singularityhub.com/201...
timarr
Hi Paul, Elektron Technology (LON:EKT) has issued a positive statement with a decent outlook.
"Q3 trading has been strong. The Board now expects full year performance to be ahead of its previous expectations."
Shares have also been heading in the right direction. I don't know much about the business (i think there may be some history of overpromising) but would appreciate your views if you have a chance to cover. Ta!
FOOT IPO looks interesting. Placing at 164, trading over 200
A lot of IQE activity this morning with over 11m shares traded already this morning - share price on the move again.
Any thoughts on 4Imprint (FOUR)? They are being a bit coy about their forecasts but if I read it right they are saying:
* revenues growing
* margins holding
* profits might be a little bit ahead
My morning smallcap tweet:
Norcros (LON:NXR), Elektron Technology (LON:EKT), Amphion Innovations (LON:AMP), GALS-Development PAO (LON:HALS)
Norcros (NXR) Big acquisition of £60m for Merlyn, mfr of shower enclosures. Placing £31.4m at 172p, a 6% discount. Earnings enhancing in a full year. I hold.
Elektron Technology (EKT) Q3 rev up 34%. Board expects full year performance to be ahead of its previous expectations.
Amphion Innovations (AMP) has its patent claim case against MicroStrategy dismissed due to the withdrawal of its legal counsel and the inability appoint a successor counsel in the short time frame set by the Court. Seeking funding to restart case. Did the counsel think AMP didn't have the readies to pay up if it lost?
Hals Development (HALS) very peculiar wording in announcing a property sale: "has concluded with the Joint-stock company "The Agency for Housing Mortgage Lending" (the Buyer) the contract for the sale of a future thing." Price 25bn Rouble.
Hi Paul,
Managed to get just a brief flick through the news this morning - Read enough here to at least get me interested in watching Water Intelligence (LON:WATR) this morning. Appreciate any input you have on them - I like the growth in Revenue here!
Thanks in advance as always.
Just had a quick glance at Water Intelligence (LON:WATR) , an interesting read.
I think they are trying to tell us that revenues are up, but with no caomparison with the GDP of Guatemala or Christiano Ronaldo's monthly pay packet it's not entirely clear.
A new board appointment too :
Totally irrational I'm sure, but the language puts my guard up somewhat. Still will have a proper look later.
I didn't get very far looking further in to Water Intelligence (LON:WATR) as I was looking at other things and I see that Paul hasn't got to it yet either.
However there is an excellent little thread on ADVFN (it turns out that is not an oxymoron) kicked off by "Effortless Cool".
Just a few observations from that thread :
I have completely lost interest at this stage and will not be looking at this any further -who knows that could well be to my loss, but I cannot get the two words that often proceed 'plain sight' out of my head.
Actually I lied, one further observation : on 7-September two senior managers simultaneously retired and on doing so excercised options to buy 80k shares (between then) at 67 cents - which the company immediately bought back from them at $1.24 (admittedly this was c. 10% below the then market price - although with such an illiquid stock who knows what the market price actually means.)
There is probably a good logic to those transactions, but I am obviously not smart enough to interpret ANY of the above, so I will stay well away.
Thanks, Gromley.
There is a similarly excellent little thread for Water Intelligence (LON:WATR) on this site, too .....
https://www.stockopedia.com/content/water-intelligence-the-long-story-195763/
Thanks Mr Cool - sorry I didn't recognise the moniker so I didn't realise you were here too!
I had my finger on the trigger for Water Intelligence (LON:WATR) several times in the past but resisted purchasing. Some thoughts:
Hopefully I won't come to regret not buying as the price has rise significantly since I first came across this share...
Sizeable (£60m) acquisition of Merlin Industries by Norcros (LON:NXR) announced this morning together with a 6% discounted placement (@172p) and open offer to finance a substantial part of it. Purchase price represents roughly 1/3 of current Norcros market cap.
https://www.investegate.co.uk/norcros-plc--nxr-/rns/proposed-acquisition-of-merlyn-industries-limited/201711020700053627V/
At first glance looks to be immediately earnings enhancing although arguably buying at the top of the cycle. Interesting from a strategic perspective in that it tilts the focus of this perennially lowly p/e rated company more towards the UK and Ireland away from South Africa. Might this be a longer term catalyst towards better market perception of the company?
Gus.
this one caught my eye today. I think it bodes well for future earnings and the stock it usually so illiquid that perhaps paying for it with placing new shares could help that matter too.
Interesting acquisition announced by Norcros (LON:NXR) this morning for £60m (£30m of which raised through placing/open offer).
Earnings positive in the first year, so sounds good.
Thx for flagging up the Norcros (LON:NXR) acquisition - I shall write up a section on that later.
P.
Paul,
I would be interested in your thoughts on Water Intelligence (LON:WATR), which released a positive trading statement this morning.
I'd like to second Effortless Cool for a look at Water Intelligence. In particular do you have any thoughts on whether the revere takeover that created this business in this form provides a reasonable justification for a business that trades mainly in the States to be listed in the UK? I have dipped my toe in this morning, though the spread (7%) is a bit painful.
And yes, the initial placeholder process seems to be working well.
Hi EC,
OK - I'll review Water Intelligence (LON:WATR), seeing as your request has already got 3 thumbs ups!
Regards, Paul.