Small Cap Value Report (Thu 20 June 2024) - WTB, VCP, APH, YOU, FTC. Brief: KETL, TMO, FUM, CNC

Good morning from Paul. I prepared some more sections last night, so we hit the ground running today!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
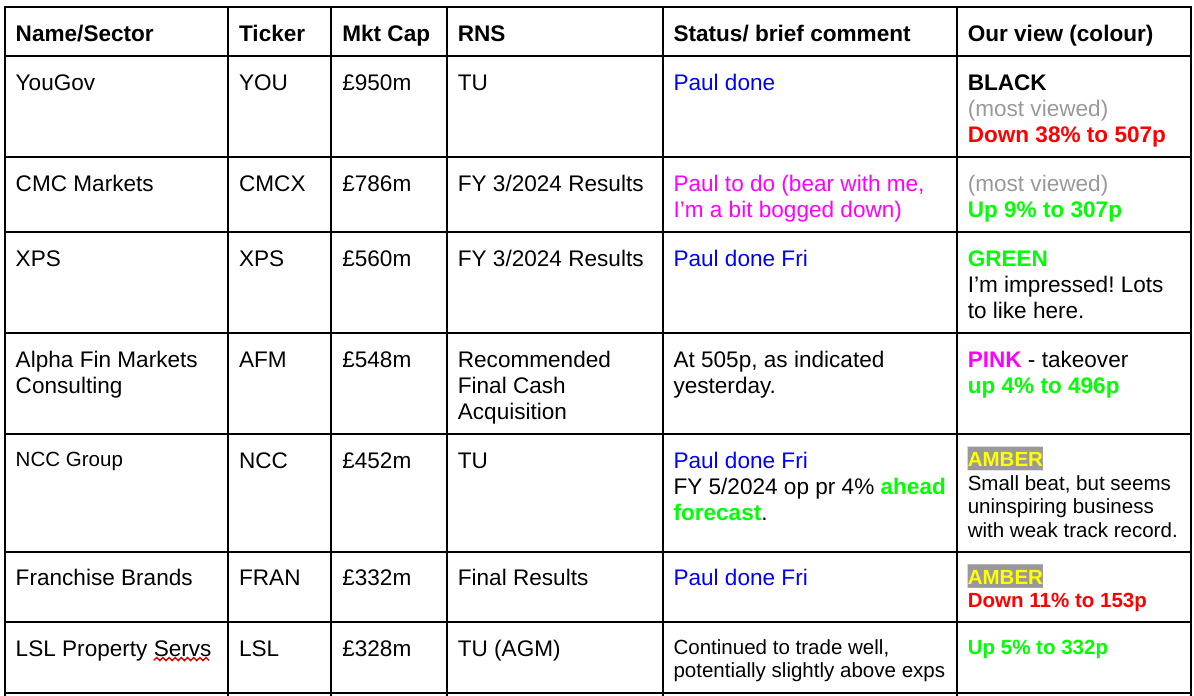
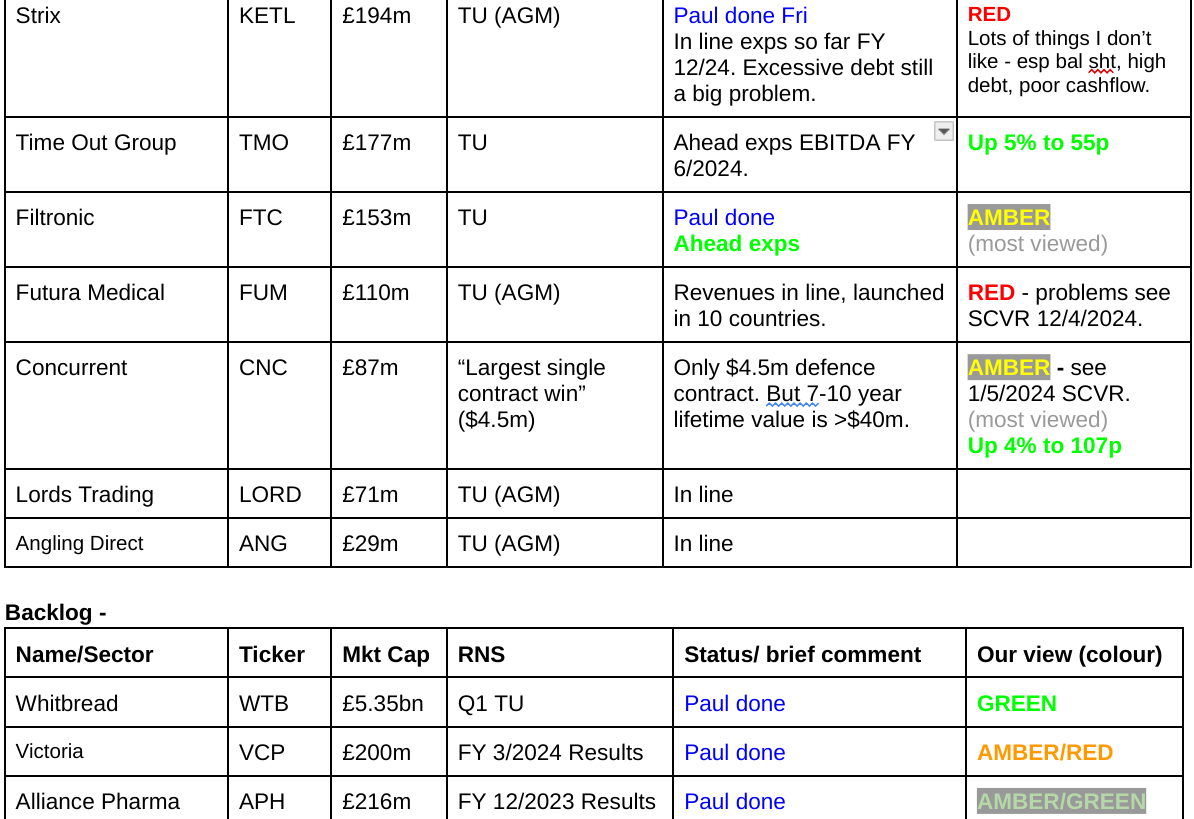
Summaries
Whitbread (LON:WTB) - 2,940p (£5.35bn) - Q1 Trading Update - Paul - GREEN
One of my favourite mid caps, so I've looked at yesterday's Q1 (Mar-May 2024) update. It seems a bit soft to me, glossed over by the PR. However, FY outlook is held (note brokers have edged down their forecasts in the last 3 months!), so nicely finessed. Bottom line, it's an excellent, well-funded and cash generative business in my view. I see shares as very attractive longer term, and explain why below.
Victoria (LON:VCP) - Up 2% to 176p (£200m) - FY 3/2024 Results - Paul - AMBER/RED
No recovery in trading yet, and an uncertain outlook. That's a big problem, because the clock is ticking on debt maturities beginning in 2026. Management horribly over-geared the business on cheap debt, and are now stuck in a corner. Equity could go either way, a zero, or multibagger, but at least mgt has 2 years to sort things out, if they can. Impossible to value, it's just for gamblers at the moment.
Alliance Pharma (LON:APH) - Up 13% y’day to 40p (£216m) - FY 12/2023 Results (delayed) - Paul - AMBER/GREEN
In an SCVR first (!), I've moved straight from red to AMBER/GREEN due to much more positive news. The delayed accounts, and other issues, turn out to be nowhere near as bad as feared, and I reckon this share might have put in a bottom. Worth a fresh look I think. Details below.
YouGov (LON:YOU) - down 39% to 501p (£580m) - Update on current trading (profit warning) - Paul - BLACK (AMBER/RED on fundamentals)
A frustrating profit warning that gives revised down profit guidance without telling us what it was previously (and I can't find anything in the H1 results, and no broker notes are available). So I'm in the dark until revised broker consensus forecasts filter through. I'm wary of the balance sheet weakness, after it took on too much debt to fund a large acquisition in Jan 2024. So for now, I'm wary at AMBER/RED until we have more information. Things like this usually recover from profit warnings though.
Filtronic (LON:FTC) - down 2% to 71.4p (£155m) - Trading Update - Paul - AMBER
Ends the financial year 5/2024 with a flourish, ahead of expectations, with Cavendish today raising forecast EBITDA by £0.3m to £4.8m. Real profit is forecast at £3.6m. Hence the £155m market cap is pricing in a continuation of very strong profit growth. It looks an exciting situation, but I have no idea how to value it, so will sit on the fence with AMBER. Well done to holders, who have enjoyed a stellar bull run.
Paul’s Section:
Whitbread (LON:WTB)
2,940p (£5.35bn) - Q1 Trading Update - Paul - GREEN
These days, Whitbread’s main business is hotel chain Premier Inns, mainly in the UK, but with a small but growing operation in Germany. It also has co-located food & beverage businesses - ie bar/restaurants attached to Premier Inns (some underperforming ones are being converted into more hotel rooms).
For reference, I reviewed WTB shares in some detail here on 21/1/2024, most of which is still relevant now. In particular I showed how the balance sheet is very strong, with tons of freehold properties. The net debt shown on the StockReport is a red herring because it includes hefty lease liabilities under IFRS 16. I have challenged this, and asked if the net debt could be changed to pre-IFRS 16, but the response from the data provider is that they provide data which complies with current accounting standards, including IFRS 16. Therefore we have to remember that, for any company which has multiple leased properties (ie almost all retailers, and hospitality companies), the net debt numbers will include leases, and hence need to be manually adjusted down to focus on actual debt. Annoying, but that’s the way it is I’m afraid.
WTB’s current financial year end is FY 2/2025, so this Q1 update covers Mar, Apr and May 2024.
Q1 Trading Update
Headline - has been PR’d a bit I’d say -
“Strengthening trading performance in the UK and continued progress in Germany”
This glosses over what I see as a rather lacklustre Q1 sales performance, as this table below demonstrates. The growth in Germany is much better, but it’s so small relative to WTB’s UK operation that it barely moves the dial. Germany is expected to reach breakeven during this calendar year - and hopefully then move into profits in future. That could be a catalyst for a re-rating, if it works.
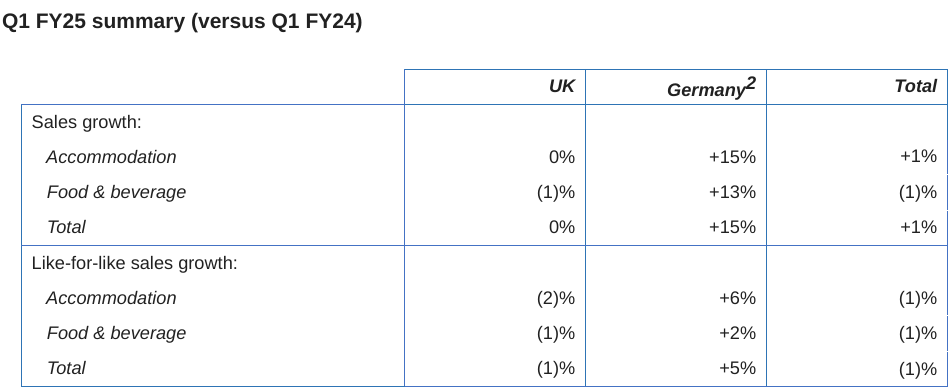
Bear in mind that staff wages costs are about 30% of WTB’s revenues, and these have seen two years’ large increases from minimum wage, so LFL sales being down 1% in Q1 isn’t good enough. Set against that, I imagine that food and energy costs might be moving down somewhat, which is what we’re hearing from some other hospitality companies. The last results guided cost inflation at 3-4% overall this year, since efficiency savings have offset a lot of the wage inflation.
I’m struggling to reconcile the upbeat-sounding commentary and bullet points with the weak figures in the table above.
Share buybacks - you’ll see that “transaction in own shares” announcements dominate the list of RNSs from 1/5/2024 when the programme began -
“£150m share buy-back: on track with 3.2m shares purchased so far for a total consideration of £96m”
WTB passes my simple tests for share buybacks to be a good thing, namely -
Shares must be cheap on fundamentals, and
The company must have a strong balance sheet to be able to easily afford the buybacks.
The share count is heading down nicely now, over several years, thus enhancing EPS and DPS.
Outlook -
“Our UK trading results strengthened during the quarter and we continued to grow accommodation sales ahead of the market. “
“Confident in full year outlook, underpinned by our strong commercial programme and good progress on cost efficiencies”
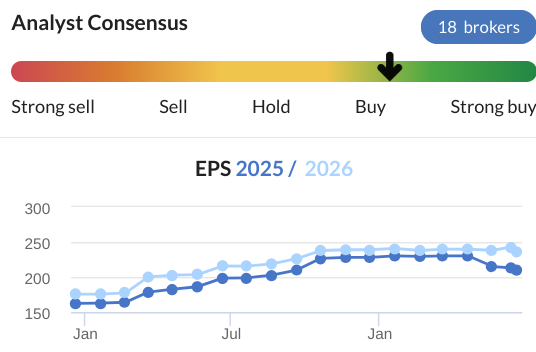
As you can see below, the trend of broker forecasts has been up, although in recent months current year forecast FY 2/2025 has been trimmed from 230p to 210p. At 2940p, the current year PER is about 14x - I think that’s a reasonable price, given the upside potential from a cyclical economic recovery, more growth in Germany, and a reducing share count from the buybacks. Meanwhile shareholders also receive a useful dividend yield of about 3.4%
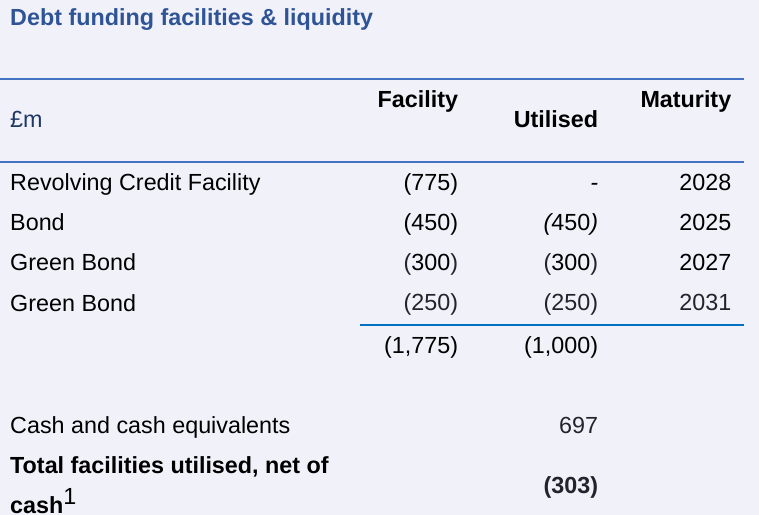
Balance sheet - as mentioned before, this is very strong indeed, full of freehold property, and has minimal net debt of only £303m, as you can see from this table in the FY 2/2024 results -
Pension schemes - this is the latest news, as of Feb 2024, which is a little confusing, but my conclusion is that we probably don’t have to worry about pension schemes being significant, given the size and profitability of the company - although the large size of the property held as security raises an eyebrow -
“There are currently no deficit reduction contributions being paid to the Pension Fund, however annual contributions continue to be paid to the Fund through the Scottish Partnership arrangements which amount to approximately £11m. The Trustee holds security over £532m of Whitbread's freehold property which will remain at this level until no further obligations are due under the Scottish Partnership arrangements, which is expected to be in 2025. Following that, the security held by the Trustee will be the lower of: £500m; and 120% of the buy-out deficit and will remain in place until there is no longer a buy-out deficit. The Pension Fund is currently in the process of conducting the triennial actuarial valuation of the Fund as at 31 March 2023.”
Paul’s opinion - recent performance looks a bit soft, confirmed by broker forecasts having been trimmed. The Q1 update seems a little over-PR’d to me, I prefer a more honest style of reporting which admits that recent trading has been challenging, but the outlook is fine, thanks to efficiency gains and continued self-funded expansion.
What you’re getting here is a superbly well funded business with a bulletproof balance sheet (which could well attract private equity bidders), that is a market leader with a strong brand in a fragmented hotels market, generating excellent profit margins, with cyclical recovery potential, Germany moving into profit, nice divis and buybacks, what more do you want?! All for a PER of 14x.
I remain of the view that recent share price weakness looks a good opportunity, and that this share should re-rate in the fullness of time. It’s GREEN from me.
Victoria (LON:VCP)
Up 2% to 176p (£200m) - FY 3/2024 Results - Paul - AMBER/RED
Revenue and earnings in line with market expectations
Cautious outlook for FY2025, but strong operational fundamentals in place as demand normalises
Poor results for FY 3/2024, with revenue down 14% to £1,257m - so it’s a substantial group, having been built rapidly from multiple acquisitions, funded by now excessive debt. Hence the no.1 issue here is whether it can recover from its deeply indebted position, or will equity be engulfed by debt and wiped out? You always have to remember that equity legally ranks behind all creditors.
Adj PBT has dropped 65% to only £27m. That is after the benefit of adjustments which once again are >£100m (mostly goodwill impairments). Statutory PBT was a £(108)m loss.
Balance sheet - for me this is the most important consideration. Liquidity actually sounds OK -
“The Group boasts a strong liquidity position with cash and undrawn credit lines in excess of £250 million.
Almost all debt financing takes the form of Senior Notes, which have no financial maintenance covenants. Although the earliest tranche is not due for repayment until August 2026, the Board has started working on refinancing options to allow adequate time to optimise the terms of the replacement funding and management remain focussed on reducing Group leverage ratio ahead of the refinancing.”
Overall though the balance sheet is an over-geared mess. NTAV is negative by a huge £(376)m. Management did an acquisition binge on borrowed money, when financing was cheap, and customer demand was strong.
There’s not just £673m of long-term debt, there’s also another £274m of preferred equity.
I cannot see how all that debt can possibly be refinanced sensibly, now that interest rates are so much higher. VCP management seem to have taken a gamble that interest rates would remain low forever, and they got it wrong.
The danger is obviously that future refinancing might involve heavy equity dilution, which could be a big problem for shareholders if the share price continues its downward trajectory. The worst case scenario is that if lenders don’t play ball when bond expiries come up, then equity could be wiped out, and lenders own the business. Hence there is a very wide range of potential outcomes at VCP, from multibagger upside, to a zero downside if it ends up insolvent.
As we’ve seen with many other financially stretched companies, once the market smells blood, it can exact a heavy price for additional support for companies that are trying to secure fresh funding (debt or equity) from a position of weakness.
That said, management at VCP are experienced, and have got out of tight corners before as the long-term share price demonstrates. You have to decide if the wheels have come off this time, or if Mr Wilding is just fixing another puncture before setting off again! I genuinely cannot decide or predict which it is, this share could go either way in my view, but the eventual up or down move is likely to be big.
Hyperinflation - this is interesting, and relates to accounting adjustments required in VCP’s two Turkish businesses, a country where economic mismanagement has caused hyperinflation. If I’m reading this right, the hyperinflation adjustments seem to have boosted PBT by £16.2m in the group accounts, but has I think been removed from the underlying results. See note 2 for more details.
Audit problems - this issue caused a lot of consternation some time ago, but according to VCP it now sounds resolved -
“Through the course of FY2024 Grant Thornton continued their work on addressing the concerns expressed in their FY2023 report in relation to Hanover Flooring Limited, a small subsidiary contributing 1.25% of Group revenue. These extensive additional procedures evidenced that there was no financial misconduct and all payments due to Victoria have been received, no money is unaccounted for, and Victoria has suffered no loss. Consequently, the auditors have confirmed in the FY2024 Audit Report that their concerns have been appropriately satisfied.”
Outlook - no immediate signs of recovery -
“Commenting on Victoria's Outlook, Geoff Wilding, Executive Chairman, said:
"Whilst we remain cautious about near-term trading conditions and cannot predict precisely when demand will normalise, we are (logically) continually moving closer to that point. As interest rates fall, housing transactions and deferred residential renovation, improvement and repair purchases will rebound, driving flooring demand. We expect the market outperformance and productivity improvements secured over the last 24 months to then be rapidly reflected in Victoria's earnings and cash flow. Until this occurs, we remain focussed on minimising controllable costs and driving market share gains."...
Alongside all other global flooring companies, Victoria has suffered from the large drop in flooring demand over the last 24 months. However, critically, the fall is not structural and, as the macro-economic factors that have contributed to the low demand abate, the fundamental need for flooring will result in volumes rebounding to the long-term mean - that is the very essence of cyclical industries.
In calendar 2023, flooring volume across Victoria's key markets was estimated to be some 20% below the levels of 2019 (which were broadly in line with the 25-year average growth rate). Simple reversion to the mean therefore suggests demand normalisation should deliver a volume uplift from 2023 levels of more than 25%. Whilst the Group's FY2025 financial outlook is largely based on current demand, it is interesting to note the potential impact normalising demand could have on the business as each 5% increase in volume is expected to drive a £25 million increase in Victoria's earnings.
Net debt - is way, way too high, at £632m, which is over 3x the market cap of £200m. There’s a footnote saying -
3 Net debt shown before right-of-use lease liabilities, preferred equity, bond issue premia and the deduction of prepaid finance costs.
Dividends - none, and I wouldn’t expect any for the foreseeable future.
Acquisitions - on hold, for the same reason - it has to get debt down as its main priority.
Cashflow statement - is not good. More than all the cashflow generated is used up by finance costs, capex, and lease payments. So there’s nothing available to reduce debt, which has actually gone up a little.
Make no mistake then, VCP is in a deep hole, and need a substantial uplift in trading just to survive, and will then have to somehow refinance its massive debt load.
Paul’s opinion - I’m mindful that in a recovering economy, highly indebted companies that also take self-help measures, can miraculously recover. The standout case in the last year has been McBride (LON:MCB) - for this reason, I’m reluctant to condemn VCP too much, as it could recover.
However, the extent of its balance sheet problems are far worse than MCB, and with poor cashflows, I’m struggling to see how VCP can recover enough to even make a small dent in its massive debt pile before refinancing is required in about two years.
Hence the equity needs to be seen as a high risk gamble.
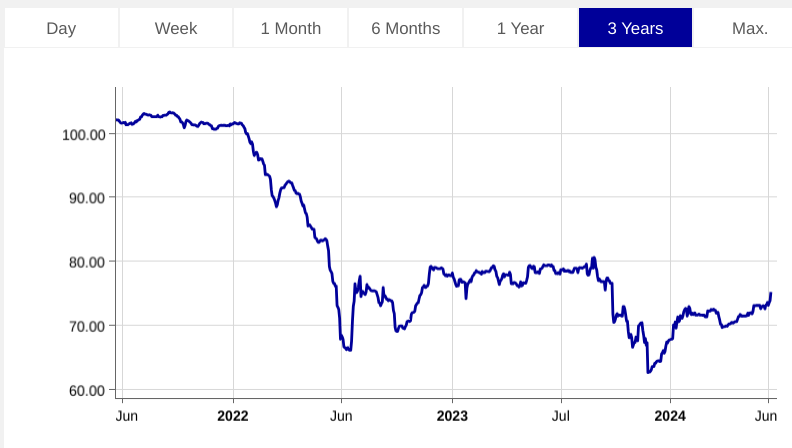
The Frankfurt Bourse seems to be the only easy place to get bond prices, and this shows VCP’s 2028 3.75% coupon bond falling in value when interest rates rose in 2022 -
The 2026 VCP bond looks a healthier price, so it seems as if these particular bondholders are expecting to get their money back, taking into account the low coupon -
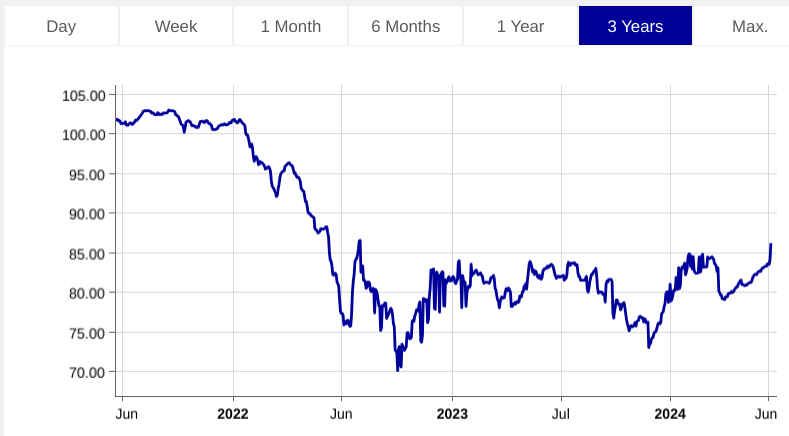
Although bondholders might be sitting reasonably comfortably because they expect equity dilution to occur, which of course helps them, whereas it hurts shareholders.
Sentiment could change rapidly with VCP shares, once the commentary becomes more bullish with a recovery in demand starting hopefully soon, maybe in 2025? With no immediate debt maturities to worry about, above all VCP seems to have a 2-year window to turn itself around enough to refinance.
I’m finding it impossible to value this share.
The terrible balance sheet, with vast, seemingly unpayable debt, which of course will get a lot more expensive once it is refinanced (if it can be refinanced at all) from 2026, means it has to be either red or amber/red. As last time, I’ll go with AMBER/RED again, since there’s no immediate liquidity issue. That buys 2 years for management to pull a rabbit out of the hat. Overall though, this one is really for gamblers only at this stage.
Alliance Pharma (LON:APH)
Up 13% y’day to 40p (£216m) - FY 12/2023 Results (delayed) - Paul - AMBER/GREEN
I last looked at this on 8/5/2024, concluding RED because of these issues - unspecified audit problems delayed the 2023 accounts twice. CEO stepped down. Very weak balance sheet with horribly negative NTAV, and way too much bank debt of c.£120m gross. So things looked pretty scary, hence I had to flag the risk with RED.
There was a 13% relief rally yesterday, so I’m happy to look at things with fresh eyes, to see if a positive corner has been turned. Getting the audited accounts out is in itself a positive thing, as another 10 days delay would have caused suspension.
The highlights table below looks fine, if you’re happy to use “underlying” profits, which are actually slightly up on prior year. Although note the statutory numbers are heavy losses in both years, due to impairments of intangible assets - ie writing down the value of drugs rights it acquired which are now assessed to be worth less than they paid for them (I'm assuming they're in the books at cost, not a revalued basis), including “valuation errors” in the restated 2022 accounts -
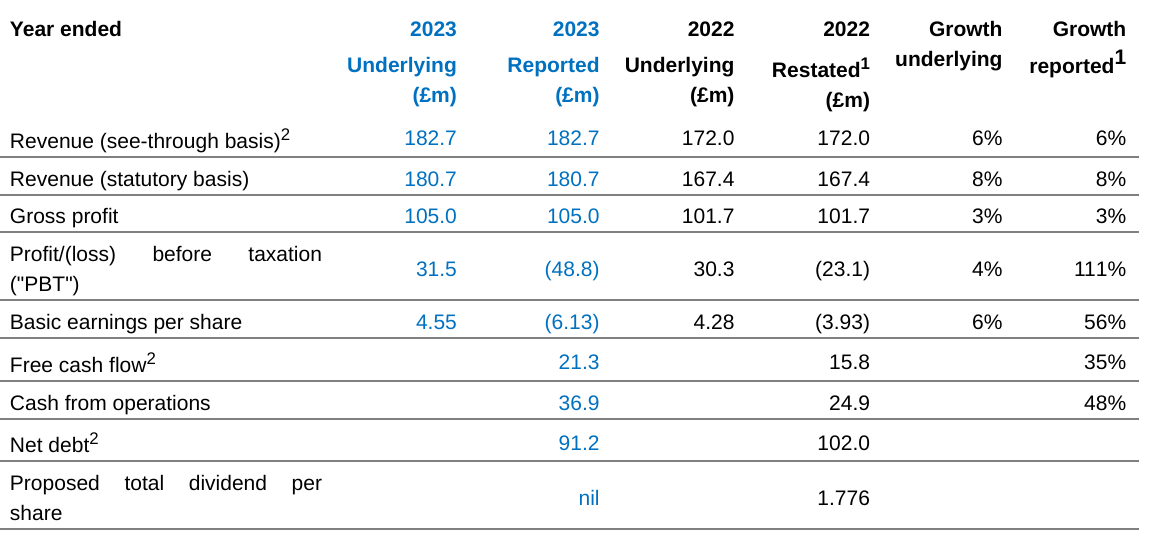
Net debt is high, although reduced by c.10%, and dividends have stopped. It says the leverage multiple has fallen from 2.69x EBITDA in June 2023 to 2.05x at Dec 2023, a much more comfortable level of gearing. This section on net debt reassures me, although note that finance costs almost doubled in 2023 to £10.5m due to higher interest rates, consuming a quarter of operating profit, so continued debt reduction is important, although not a crisis in my view.
Important points here about debt -
“Free cash flow (see note 15 for definition) for the year rose 35% to £21.3m (2022: £15.8m), due to the strong trading performance in H2. Cash generated from operations increased by 48% to £36.9m (2022: £24.9m).
This solid cash generation supported a reduction in net debt of £10.8m to £91.2m at 31 December 2023 (31 December 2022: £102.0m), with Group leverage (the ratio of net bank debt to EBITDA) decreasing to 2.05 times (31 December 2021: 2.57 times). Interest rate cover (the ratio of EBITDA to finance charges) decreased to 4.82 times (31 December 2022: 7.39 times) reflecting the increase in net interest cost on rising interest rates.
Net debt and Group leverage are both expected to fall further during 2024, particularly in the second half, with Group leverage expected to be below 2.0 times by the end of 2024.”
CMA (Competition & Markets Authority) - good news that a £7.9m provision for a potential fine has been released, given a successful appeal. This also seems to reflect positively on management integrity.
Outlook - here it is in full below, which suggests an unexciting outlook, but in line trading so far in 2024. No profit growth in 2024, but stabilising things is a pretty good outcome given how wobbly everything looked in the last update -
“Outlook for 2024
Alliance's clear focus on the core Consumer Healthcare business, in addition to our well-established, scalable platform, is expected to deliver continued modest revenue growth. Group performance in the five months to end May is in-line with the Board's expectation.
As we continue to refine our strategy we intend to move towards smaller, more regular order fulfilment, to create a more consistent revenue stream, reducing the stocking and destocking cycles we've experienced over the last two years as we've changed distributors, moved manufacturing and managed through the COVID environment.
In 2024 we will continue to increase investment in sales, marketing and innovation to maintain our brand leadership position in key categories.
The Board continues to anticipate that profits in FY 2024 will be in-line with FY 2023. As in previous years, performance is expected to be H2 weighted, particularly in Nizoral.
We remain confident in our ability to further capitalise on identified organic growth opportunities within the business and to deliver positive financial performance which will help drive the de-levering of our balance sheet.
Balance sheet - I’ve been critical of the weakness in NTAV, and too much debt in the past.
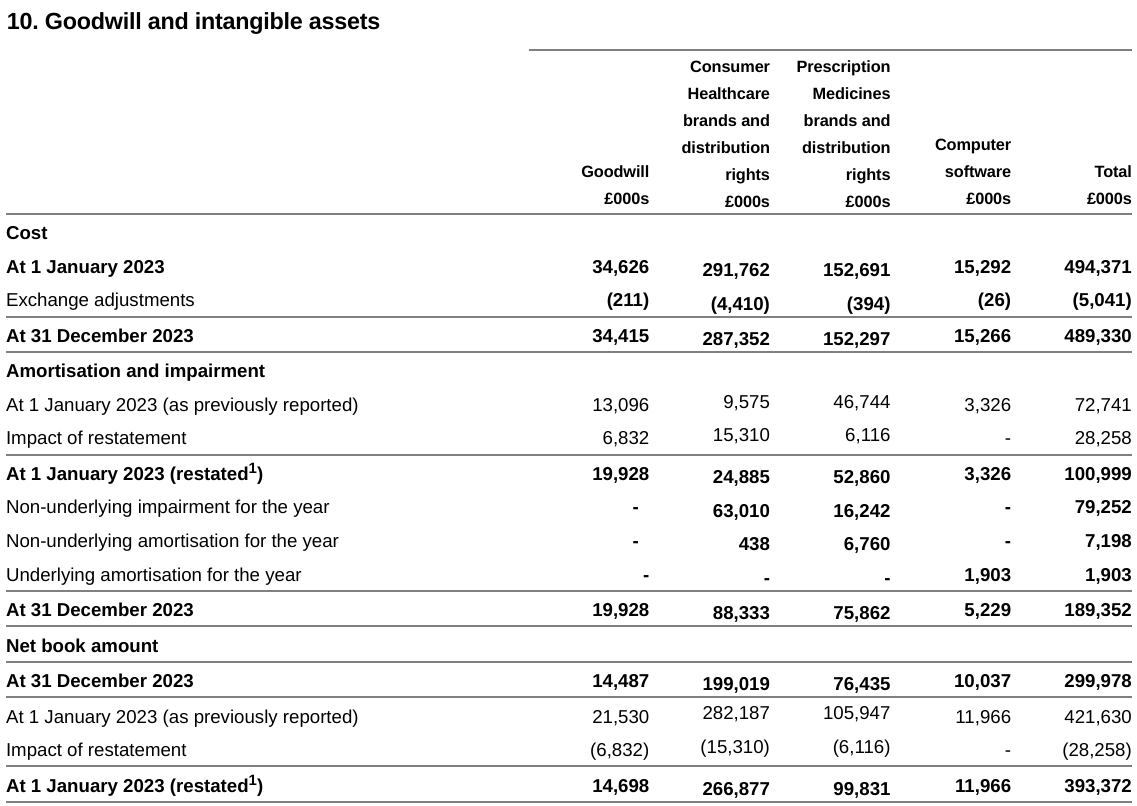
However, I’m taking a more lenient view now on seeing the latest numbers, because the intangible assets are mainly rights over drugs, which presumably do have resale value. Hence we shouldn’t be just writing them off as worthless. The problem is that APH seems to have been inaccurately valuing them, and well done to the auditors for spotting this, and forcing APH to write down values to a more robust basis. I like the humility of APH’s commentary on this, where it says valuable lessons have been learned. And to be fair, as a former CFO myself, you tend to be focused on running the business, and things like impairment reviews, leases, revenue recognition policies, etc, many of which have changed a lot recently, are generally left to the year end, and often even calculated by the auditors. So that does increase the risk that something big and nasty could emerge during the audit. It’s not ideal of course, but in this case I think APH mainly failed in its communications to the stock market. It should have been far more open with investors about what the precise issues were, instead of causing panic amongst investors with its opaqueness.
As you can see below, these drugs rights are reduced by about a quarter, but it’s still a big asset value -
Paul’s opinion - I don’t recall ever jumping from RED straight to AMBER/GREEN, but I’m going to do that here.
The various audit delays, combined with worryingly high gearing, and abrupt CEO departure, clearly spooked a lot of people (including me) earlier this year, understandably.
Yet the 2023 figures actually look OK to me, and I can forgive the sloppy procedures for placing notional values on its drug rights assets - I don’t see that as a commercial or cashflow issue, and there are still substantial assets, measured on a more prudent basis now.
Cash generation is good, and with dividends stopped, I reckon APH has the capacity to reduce net debt by about £20m pa. That’s important because finance costs are currently consuming about a quarter of operating profit, and almost a third of cashflow. Hence there should be scope to refinance at lower rates, and for a smaller amount, in say 1-2 years.
I imagine a small divi might return in future, but for now debt reduction is more important.
I’ll stick my neck out here, and say that I suspect APH shares might have now put in a bottom, and this seems an interesting-looking value situation for you to do some deeper research on. Let me know what you think, once you’ve delved a bit deeper!
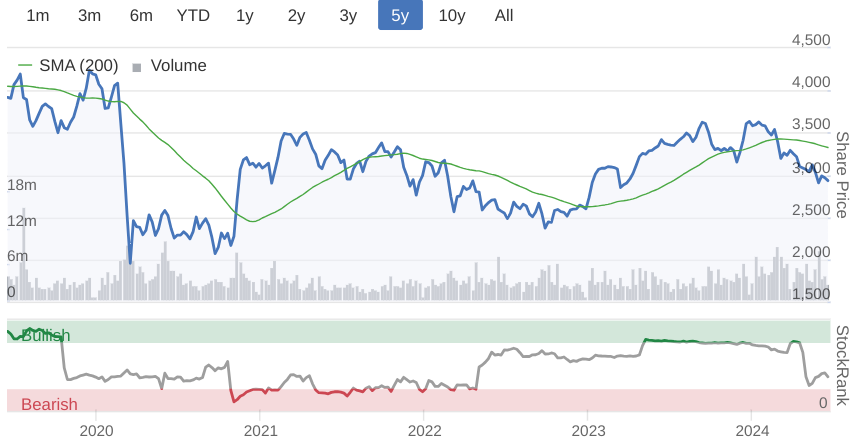
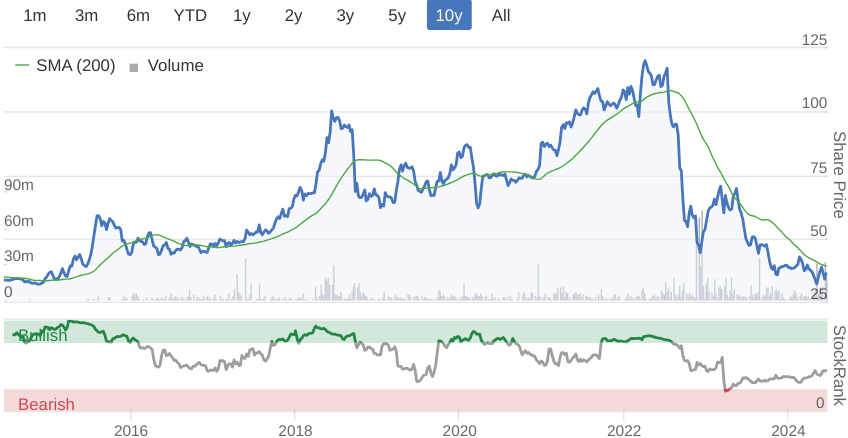
Shares have almost done a round-trip over the last 10 years - not very good, particularly when you adjust for inflation -
YouGov (LON:YOU)
Down 39% to 501p (£580m) - Update on current trading (profit warning) - Paul - BLACK (AMBER/RED on fundamentals)
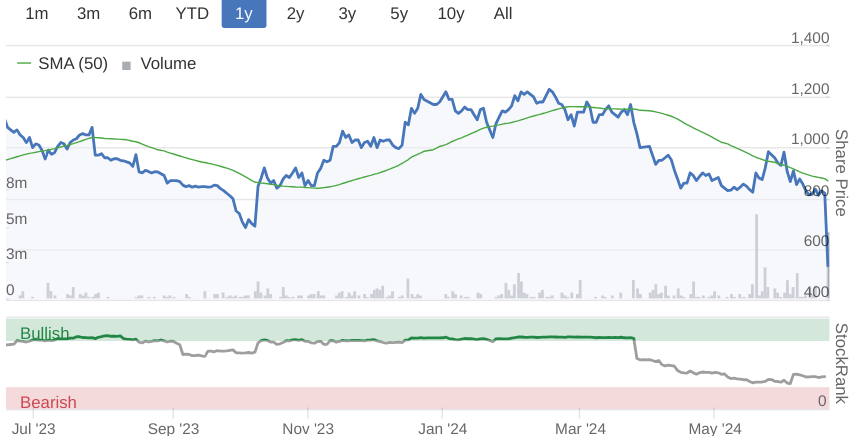
A savage 39% drop in share price this morning for this “international research and data analytics group”.
The peak share price was 1,600p at end 2021, so this is now down by more than two thirds. Is it a buying opportunity, a disaster, or somewhere in between?
YOU is not a share we cover much here, due to its size (not a problem any more). My notes show we last looked at YOU on 12/10/2023 concluding AMBER, noting superb FY 7/2023 results and long-term track record, but that a large acquisition pending was about to gear up the balance sheet. I also flagged concern over some accounting adjustments.
On to today’s bombshell, a profit warning for FY 7/2024.
What’s gone wrong? Sales are lower than expected, now guided at £324-327m. It had increased costs in anticipation of higher sales in H2. Revised adj operating profit guidance is now £41-44m. Maddeningly, it doesn’t put this in context by saying what the previous guidance was! How ridiculous is that.
The big acquisition in Jan 2024 (part of GfK I seem to recall) is integrating well, although “slight” shift of revenues into next year due to aligning its accounting policies with YOU’s.
What are they doing about it? Trying to drum up more sales, and cost-cutting, is my interpretation of this -
“As we move into FY25, we will focus on optimising our cost base and prioritising investment in key growth areas such as upgrading our Data Products, continuing to build out our AI capabilities and enhancing our sales organisation to further capitalise on YouGov's unique asset: its high-quality global panel and proprietary dataset.”
Broker updates - nothing for the plebs. So I’ll have to try and work it out for myself.
H1 results (to Jan 2024) showed adj operating profit of £27.9m. So the guidance today of FY 7/2024 adj operating profit of £41-44m suggests H2 will be between £13.1m, and £16.1m, significantly below H1.
I’m not happy with adj operating profit because the adjustments are too aggressive at YOU in my view, and also it geared up with loads of bank debt in Jan 2024 to make a very large acquisition. Hence there will be substantial finance charges on the bank debt in H2, that obviously doesn’t appear in operating profit because it’s the next line down. Hence we need to know what PBT guidance is, not operating profit.
The H1 figures say that leverage was 1.6x EBITDA. Now we’ve had a profit warning, presumably the leverage multiple will have worsened. Investors therefore need to check what the bank covenants are, as there could be a risk of the balance sheet needing repair from an equity fundraise.
Balance sheet - this is a concern now. At H1, the NAV of £189m included a huge £416m in intangible assets (mainly goodwill), leaving NTAV badly negative at £(227)m. I did raise concerns last year over the wisdom of taking on so much debt to finance a large acquisition in Jan 2024, so there couldn’t be a worse time to encounter softer trading and issue a profit warning, just after taking on a ton of debt.
Paul’s opinion - I need more information to properly judge this, in particular what the previous guidance was, as I can’t find anything in the H1 results. In this situation I would usually go amber. However, my balance sheet concern means it has to be AMBER/RED for the time being, whilst information on revised forecasts takes time to filter down to us plankton.
I should say though, that former mid caps like this do usually recover from profit warnings, and YOU has a strong historical track record. Although my main concern is that it’s possibly bitten off too much with the 315m Euro acquisition of CPS, mostly funded with debt.
Overall, I think this share could go either way, sorry I can’t give a more helpful view on it!
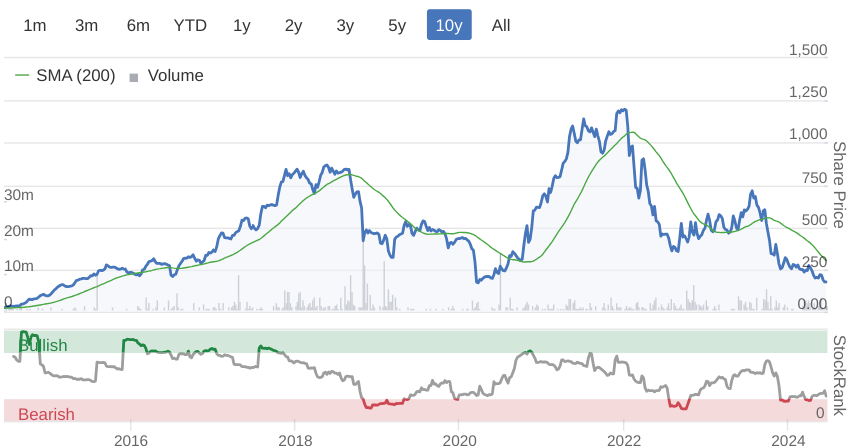
Shares have more than halved so far in 2024 -
Filtronic (LON:FTC)
Down 2% to 71.4p (£155m) - Trading Update - Paul - AMBER
Filtronic plc (AIM: FTC), the designer and manufacturer of products for the aerospace, defence, telecoms infrastructure and low earth orbit ("LEO") space markets, is pleased to provide the following trading update for the financial year ended 31 May 2024 ("FY2024").
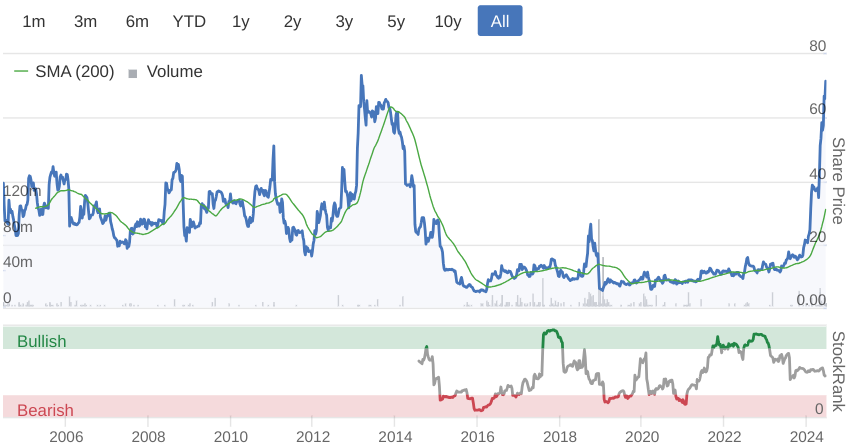
Says it’s performed ahead of expectations, yet the share price has fallen slightly this morning (after a fabulous bull run though) -
“Revenue and earnings before interest, taxation, depreciation and amortisation ("adjusted EBITDA") has been delivered ahead of market expectations as trading momentum continues to build, in what has been a transformational year for the business, after entering into a Strategic Partnership with SpaceX as we previously announced on 24 April 2024.”
Useful guidance is provided, showing a large year-on-year increase in profit (although bear in mind the market cap has soared to £155m, so the numbers need to be good) -
“Trading has been strong in H2 of the financial year and the Board, subject to audit, expects to deliver FY2024 revenue of approximately £25.4m (FY2023: £16.3m) and adjusted EBITDA of no less than £4.8m (FY2023: £1.3m).
Cash at bank on 31 May 2024 was £7.2m (30 November 2023: £4.1m). Net cash (net of all lease obligations except right of use property leases) at 31 May 2024 was £5.2m (30 November 2023: £2.4m).”
Broker update - Cavendish helpfully updates us, raising adj EBITDA from £4.5m to £4.8m, a useful but not huge beat.
What about real profit? Adj PBT is forecast at £3.6m, a large uplift from breakeven in the previous year.
Adj EPS is 1.4p, so the PER is a whopping 51x, hence the market is pricing in roughly a tripling of future profits to a steady state of c.£10m, the way I look at it.
FY 5/2025 forecast (unchanged today) is another big rise to adj PBT of £6.4m, or 2.7p EPS, taking the PER down to a still quite punchy 26.4x.
Outlook sounds exciting -
“Nat Edington, Chief Executive Officer, said: "The space market continues to present significant growth potential for Filtronic. The recent Strategic Partnership we entered with SpaceX is exciting for all of our stakeholders. It gives a platform to develop the business and puts us in a stronger position to capitalise on the plentiful opportunities in the core markets we serve. We enter the new financial year with a very strong order book, a growing list of customers, including key strategic targets that we have secured in the year, and an opportunity pipeline that continues to grow and mature."
Paul’s opinion - doesn’t really matter, as this share is all about anticipating further growth, and trying to work out how to value the shares on unknown future results. Hence there’s a fair bit of guesswork involved, and well beyond the scope of my reviews of the numbers here.
Profitability has transformed upwards in FY 5/2024, which has been reflected in a large increase in the share price & market cap. There’s a lot more growth already priced-in.
I don’t have any idea how to value this share, so will go with AMBER. Well done to investors who spotted the opportunity. It’s very impressive that a small UK company, with a lacklustre track record over many years of boom & bust products, seems to have hit a rich vein of new business. How high can it go? How long will this boom last? No idea! If I held this share, I’d probably top slice some of the profits for safety’s sake, then let the rest run, and keep some cash back to buy the dips, providing the newsflow remains good.
I see one of the biggest shareholders (a couple, surname Newlands) are thinking along the same lines, having top-sliced from 12.2% to 11.3% two days ago, announced today.
What a glorious chart here - a reminder that multibaggers can come from the most unlikely sources sometimes - but also a warning that previous glories faded away -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
News that NVIDIA (NSQ:NVDA) is now worth more than all the shares in the FTSE100 as also are Apple (NSQ:AAPL) and Microsoft (NSQ:MSFT) shows surely both how expensive these shares are but also the incredible value available on the UK market.
This value is reflected in the extraordinary number of shares and Investment Trusts that are paying exceptionally high dividends, and often not because that reflects the dividend being unsustainable but because they are so cheap. So much so that some are increasing their already big dividends year on year.
Yields at 10% and more sometimes give a respectable annual return even without any share price gain.
In case anyone wants to follow up on any of these, my portfolio, is now stuffed full of these big dividend paying bargain priced (some of the shares are so cheap that the PE ratio is lower than the dividend yield) to take full advantage before surely investors, including the big Pension Funds wake up to the incredible value still available here in the UK.
All the yields shown are the current yields.
SHARES:-
Abrdn (LON:ABDN) 10% dividend.
Aviva (LON:AV.) 7% dividend
Barratt Developments (LON:BDEV) only 6% for now but housebuilders pay big dividends in housing bull runs.
Legal & General (LON:LGEN) 9% dividend.
Jupiter Fund Management (LON:JUP) 8.6% dividend.
Liontrust Asset Management (LON:LIO) 9.5% dividend
M&G (LON:MNG) 9.6% divi
Polar Capital Holdings (LON:POLR) 8.2% dividend
Persimmon (LON:PSN) only 4.4% dividend …for now.
Reach (LON:RCH) 7.8% dividend
Smiths News (LON:SNWS) 7.9% dividend
TP Icap (LON:TCAP) 7% dividend
Chesnara (LON:CSN) 9.6% dividend and increased for multiple years but unlike many in this list also with so far lousy share price performance.
Phoenix group (LON:PHNX) 10.7% dividend ….and along with Chesnara the only ones down on my buy price. Both are down 10%.
Best winner of this lot is TP Icap (LON:TCAP) which has doubled so my dividend yield is now a very useful 14%.
INVESTMENT TRUSTS:-
Most of these are on big discounts to NAV.
Amedeo Air Four Plus (LON:AA4) 20% dividend …but risk of capital loss depending on the terminal value of the planes they’ve leased to Emirates. As with all these a must obviously to check each one for negatives and plus points.
abrdn Equity Income Trust (LON:AEI) 7.6% dividend
Aew UK Reit (LON:AEWU) 8% dividend
European Assets Trust (LON:EAT) 6.7% dividend
Tritax EuroBox (LON:EBOX) 7% dividend and possible bid soon.
GCP Asset Backed Income Fund (LON:GABI) 9.2% dividend
Gore Street Energy Storage Fund (LON:GSF) 11.3% dividend
Henderson Far East Income (LON:HFEL) 10% dividend
CQS New City High Yield Fund (LON:NCYF) 8.7% dividend
Schroder European Real Estate Investment Trust (LON:SERE) 8% dividend
Schroder Real Estate Investment Trust (LON:SREI) 7.3% dividend
Twentyfour Select Monthly Income Fund (LON:SMIF) 8.8% dividend paid monthly.
Supermarket Income REIT (LON:SUPR) 8.5% dividend.
Foresight Solar Fund (LON:FSFL) 8.9% dividend.
Finally, it’s perhaps worth pointing this out too. It’s not the case that big dividends always mean limited share price gains.
e.g among the biggest winners in my portfolio are CQS Natural Resources Growth and Income (LON:CYN) now up 236% and though the current dividend yiekds is modest, it’s 11% at my buy price. BlackRock World Mining Trust (LON:BRWM) is up 120% and yield at the buy price is 14%….and that’s after a substantial cut. Big Mining sector boom ahead and big dividend increases as renewable demand and supply shortages due to lack of big new mining projects? That’s already happening with big increase in copper price. Good for copper producers like Antofagasta (LON:ANTO) .
News that NVIDIA (NSQ:NVDA) is now worth more than all the shares in the FTSE100 as also are Apple (NSQ:AAPL) and Microsoft (NSQ:MSFT) shows surely both how expensive these shares are
If that’s your main take on these companies, then I think you might be missing something, Ken. Nvidia has grown revenues 5-fold inside two years from a position then as already the third largest company in the world. If that isn’t something truly remarkable then I don’t know what is.
I do take your point about value in ITs of late and I appreciate your thoughts. But don’t those belong on your daily updated IT threads? Do you not think that cluttering up the small/mid cap thread with extraneous detail could get a little tiresome for readers. Keep it up. - but in the right place please.
SCVR is the core Stocko general discussion thread. Unless and until Stocko comes up with a different/better way of organising things, it's the place to post anything that you consider to be of general interest. Sure, detailed follow-up discussions probably belong elsewhere. But SCVR is where to post first if you have a point to make that you would like to receive attention.
But SCVR is where to post first if you have a point to make that you would like to receive attention.
Fair comment but Ken has posted similar commentary regarding his high income / investment trust strategy, personal investments and views on multiple occasions on SCVR.
We've heard it all before and many may wish he would please give his repetition a rest on SCVR.
The investment trust thread is the proper place for his commentary such as this.
Snazzy
Indeed ... and yours is fair comment , too. And, I can well see how this sort of posting, especially if repetitive, can be irritating to subscribers who follow the SCVR thread specifically because of its focus on small caps.
But...inadvertently, I presume...this issue is 'designed in' to the Stocko model. There is no general core discussion thread that subscribers can post to, which can then branch to specific topic discussions. By default, SCVR ... which is the principal (effectively, only) curated thread on the Stocko site...ends up performing this function.
I know next to nothing about how to design and build a discussion forum. But I know a basic design problem when I see one.
That’s fair comment and justified criticism about my post but I also agree with DaviStoVest’s comments about Stockopedia bulletin boards.
The simple fact is that the only thread that is really active every day and sees multiple posts is this one. So if we want a post to get some attention and responses be they positive or negative the temptation is either to post here or not at all. And it’s obvious from the reduced number posting on this thread that that has already happened. There are still a lot of posts but an increase in several a day from the same posters.
Stockopedia doesn’t seem too bothered about this even though these comments apply to posts from Stockopedia staff including Ed Croft.
I use this link to access Stockopedia:-
https://www.stockopedia.com/di...
A quick look backs this up. There are fewer follow up posts and replies in weeks and months on any of the sometimes excellent threads on Stockopedia than are seen on this one in a single day.
e.g scroll a long way down to find Ed Croft’s “How to pick winning styles to for your portfolio,” thread. There were just 26 posts and replies to it. Already today there are 82 posts here!
e.g go even further down to Ed Shing’s “Beware the narrowing of Mag7 performance,” thread. This time only 13 posts after it.
e.g go even further down to what was a weekly thread by Megan Boxall headed “The week ahead thread.” The final post before she appeared to abandon it, presumably through lack of interest, saw just 28 posts and it was the same in previous weeks.
I’ve done posts on the Investment Trust and other threads that got no replies and a couple of ticks. Occasionally I pasted the post to this thread and on 2 occasions there were over 100 ticks and multiple replies.
So it’s obvious there’s a need for a catch all thread if this one is to be limited to small caps only….as I tend to agree it should be, and then mainly on the shares covered by Paul and Graham.
Without that and with the criticism of posts like mine by posters here, then more and more quality posters are going to give up on posting on Stockopedia. Already a lot of previous “regulars” seem to have disappeared .
Finally on my post today. I believe rightly or wrongly that a fair number of readers of the posts here welcome posts like mine including valuable investment information, and perhaps more than they do posts with no investment information that criticise a well intended investment post.
There’s incredible value right now available on the UK market and all I was doing with the best of intentions was highlighting some I hold that might appeal to others. And there are plenty of alternatives that are just as good value. Why on earth can’t we post somewhere here on opportunities like that where it gets some recognition?
Hi,
Posts about where posts should be, and arguing about it are generally not a good thing in my opinion, we just go round in circles.
For me, as the writer of these reports (but I don't control or even influence the moderation), I'm happy with any comments here which are interesting and relevant. I like being the epicentre of a vortex that draws in lots of interesting input! That's the idea - the articles are conversation starters, then subscribers lob in your additional thoughts. We get maybe 100 comments per day, which is perfectly manageable. I think the discussion section is terrific actually, now that everyone's being civil.
Bottom line is what the subscribers think, and ken's original post above got 36 thumbs, so that tells us people found it interesting, so case closed I think!
Best wishes, love and peace to all!
P.
Commented but changed mind and won't let me delete, just edit. Hence some low level brains below, sorry.
I am into mid/large caps, minerals, defence, energy all the stuff the SCVR is not best on, but still like to read the working of the small caps and looking for the buyouts of tomorrow.
Subscribe to Seeking Alpha, US focused and there are loads of Mr Scotts on there but not for US small caps.
JPmorgan US Smaller Companies Investment Trust (LON:JUSC) to play that space. It does say 'smaller companies' maybe 500m plus lol.
Agree- but given the number of posts on the Monthly Investment trust discussion surprised it is not possible to have a placed on the main page. Not coded websites for 15 years, but would seem to be pretty straight forward to create such a placement.
Hi BnB
Very good and straight to the point comments.
I get the impression that very few understand the AI and what and how it will change our lives (like what the internet and the mobile phone did).
Also I believe even fewer realise the importance of Bitcoin miners and their valuable data centres and the role that they will play in this new AI world.
All the best
Hi Ken
I couldn’t disagree more with you!
Tell me which one of these shares that you mentioned will grow at the pace of NVIDIA (NSQ:NVDA) Apple (NSQ:AAPL) (in the AI now) or Microsoft (NSQ:MSFT).
NVIDIA (NSQ:NVDA) will grow its revenues for the next 4 years 35% CAGR while PEG ratio is 1.2X and will generate profits of £350B-which means massive buybacks!
NVIDIA (NSQ:NVDA) I have no doubt that it will grow to a $10T company with its ups and downs on the way.
All the best
Yiannos
Thanks for replying but I wasn’t suggesting that the shares and Trusts in my post yesterday would now outperform shares like NVIDIA (NSQ:NVDA) .
It’s been a big mistake not investing in US shares and especially so the big Tech shares.
e.g of you’ve held NVIDIA (NSQ:NVDA) for a good while yiannos you’ve already had a fabulous return. It’s up 176% year to date and has tripled over 1 year and has gained an extraordinary 3444% in the last 5 years.
Ken, I do have a screen for p/e lower than yield. Has worked out OK.
CMC Markets (LON:CMCX) - Looking forward to Paul's review but in the meantime any comments on the below welcome, particularly how to account for the cash and valuation.
FY24 - rev 333m, op expenses 267m (inc. impairment charge, variable remuneration and one-off staff restructuring costs. PBT - 66m, - interest gives PBT of £63.3m and PAT 46.9m and 16.7eps. EPS is up to 20p if you exclude impairment.
FY25 - guidance 320m-360m, take £350m (interesting that they did £210m in H2 24), op expenses £225m (exc. variable remuneration and one-offs). If we assume no one-offs and the same variable remuneration of 17.7m thats a PBT of £107.3, minus interest of £2m, call it £105m. Use TAX rate of 26% to give PAT £77.7m and EPS of (280m shares) 28p.
SP at 300p, gives current year PE of 11
They have own funds of £325m (most of which is cash or liquid assets I think) which a lot is required for margin but it's still cash if the business was closed tomorrow. M/C is 300px280m shares is £840m (anyone know why stocko shows £786?), adjust for cash £515m give an adjusted PE of 6.5
There's surely got to be some sizeable broker upgrades after today, stocko has 17.1p for this year!
TU on 25th July.
Thanks for this summary on CMC Markets (LON:CMCX) - if we say adjusted EPS of 20p for the year, then that means they did around 21p for H2 (H1 was a slight loss of around 1p). So if they continue at this rate they could be dong 42p EPS - perhaps more if we factor in the lower costs they mention.
In terms of adjusting out net cash, I would use the net available liquidity figure of £192m (which is basically the surplus cash above what they need to hold back for regulatory purposes) - this is around a quarter of market cap. If we go with the current run-rate EPS of 42p noted above, then this gives a cash-adjusted PE of around 5.5. The big proviso is earnings here are extremely volatile and hard to predict - but even so this still looks decent value providing they can maintain their current momentum.
Hopefully the company are being overly cautious on revs with their guidance. You could see that is they did £420m revs you could get to 42p. And like you say that's without any further efficiencies. Hopefully the new product launches support that sort of revenue, particularly when they did £210 in H2.
Sorry guys, I know many were waiting for the speedy hire write up, but unfortunately it's dissappeared off the list....
We did think this would happen, so let's try not to he too Suprised.
Dear Stocko - Can we please have a block profile button
Sorry guys, I know many were waiting for the speedy hire write up, but unfortunately it's dissappeared off the list....
That's untrue. I didn't put Speedy Hire (LON:SDY) on the list today.
Hi Paul, hoping you'll be able to circle back and cover Franchise Brands (LON:FRAN) tomorrow.
Currently down 10.5% based on the numbers, but reading through the statements, it's clear they have a clear game plan to pay down the debt by 2027 and have used the latest acquisition to revisit the business areas that each franchise arm covers. Lower price for recycled oil and enhancements to their proprietary software have held back profits, as well as a change of accounting policy to move to more conservative recognition of franchise profit. Looks like they've kitchen sinked as much as possible this year and next year's accounts will show the result of all these changes.
Renold (RNO)- anyone any thoughts on the sp action. Down another 6% today and now nearly 20% down in not much more than a couple of weeks. Slightly concerning.
No idea but agree price movement is odd. I have just sold, given the "leaky" nature of news around stocks recently decided to take a decent profit even though was more a few weeks ago.
Yes am thinking the same although volume not huge so with no bad news will sit tight for now..
AJ Bell's dealing costs are so low I just took the cash and will watch with interest. Unless some bad news comes out will look to buy back in.
Zotefoams (LON:ZTF) has followed RNO down to be fair- but slightly different in that one news release re the new packaging could see the share price rocket.
I think with Renold (LON:RNO) you have to remember that it nearly doubled in a few months on essentially very little news. It is still up over 50% from where it was on 1st April and still 10p up on where it was following the latest trading update. If anything it got a little over extended and there are people taking profits. It seems like the FTSE100 and FTSE250 have started to turn around after the recent pull back. AIM is still heading down in contrast, it usually lags the other two. Happy to hold through this in the knowledge it could drop lower, the broker fair value is up at 78p and everything is being upgraded for FY25 and FY26 so its a safe bet longer term.
Zotefoams (LON:ZTF) drop is more of a mystery to me as at any moment that could pop when they announce how they will be partnering/funding the rollout of Rezorce. I have topped up my already large holding today as it think the price is being walked down and the investment story hasn't changed. Today it dropped down 10% in just 4 mid sized trades, which admittedly caused an increase in liquidly afterwards bringing it back up to 2-3% down. The same pattern has happened for the past few days.
Share price can’t go straight up. It’s over bought so there will be profit taking. If you are into charts it also hit the breakout target so again profit taking. Longer term chart target is higher than 65p a I expect a period of weakness after which the sp will carry on upwards. IMO 54p might be the low of this pull back. Possibly worth buying more.
Can there be a better listed company than World Chess (LON:CHSS)
Stock rank 0. Loss making. Forecast more losses.
Debt. Market cap 24million. Revenue 2 million. Directors pay 0.5million
Insiders own enough to probably take it private anytime they want.
Spread is 29% if ever you're drunk enough to consider buying.
This little nugget from their broker was funny tho- " Like cricket, which has seen a renaissance following the introduction of a shorter T20 format, chess is seeing a similar resurgence with rapid and blitz formats revolutionising the game"
I immediately thought of Street Countdown
One of the very best episodes, enjoyed the link.
Cheers
Chris
If you get a chance could you take a look at XPS
thanks
Hi Alexdonnelley. In support of Paul (who I think is running the SCVR on his own today) - he has already written by my checking, over 5,900 words covering 6 companies !
Politely If your not aware, Paul quite naturally responds best to a request if given reasons to take a look at a particular company.
XYZ have announced today that they have they won a major new contract based on a new unique product that has been sold at a very good margin
Or similar, might get his and the rest of our attention and interest
Happy to give my two pennies worth (as a holder).
One of my reasons for buying XPS Pensions (LON:XPS) is that fees are index linked, combined with 3 yearly valuations creating repeat business.
This week's discussions regarding legacy pension scheme deficit and offloading schemes to insurers highlights another source of their income, which may see an up tick as pension deficits fall.
High PE (31 which is set to fall) but with profit above forecast I'm happy to keep holding having recently added at 260p on recent pause
Only red flag is negative NTAV, but as an asset light services company that's to be expected.
Franchise Brands (LON:FRAN) The annual results for FY23 were released today, nearly 6 months after its year end. No wonder for CFO had to go! Given that, the SP going down 10% seemed extreme, as most factors were already in the public domain. In fact, prospects going forwards look promising.
It is my style of investing that I tend to take a small initial investment in a new holding and let it help get me more informed before I commit further. Franchise Brands (LON:FRAN) has been just such a holding and today’s announcements, although trashing the price seem to me be a moment to increase my holding.
FRAN is growing its revenues, showing a good positive cash flow and although having more debt than before (to buy Pirtek) I don’t see the balance sheet as representing any threat. In addition the company has taken the excellent decision, while chucking the CFO overboard, to “kitchen sink” everything they can. Allenby, although a house broker, gives a well reasoned basis for a long term positive view and with an experienced Chair (holding 11.7%) backed by some notable shareholders (Nigel Wray, 11.8% and Slater 10.9%) I am buying with a view to a turnaround in market opinion.
hi Paul
A big thank you for your stunning level of reviews and input today making the stocko subscription look great value for the community.
Seems like your break in Washington has recharged your batteries big time.
Keep up your great work.
Snazzy
How kind, thanks Snazzy! I'm in limbo at the moment re time zones - so a flat out morning responding to news, then a long siesta, then another good session in the evenings ready for posting early the next day. Seems to be working out alright so far! :-)
I have to say, Washington DC was just marvellous. I had no idea it's such a lovely city. Meeting my American cousins for the first time was fantastic! It turns out that my married great grandfather had something of an indiscretion with a local girl c.1906, with the end result being my grandfather's appearance in 1907! (who went on to become a headmaster of a large school in Liverpool). This was a huge scandal in a small Welsh village, so great grandfather was expelled to America, where he did well and created a new family. I met some of them for the first time last week, and they're wonderful people! So I think DC might overtake Gozo as my future working abroad destination, although the time difference is a big challenge (RNSs starting at 2am).
Apologies for off topic! But yes, it has all given me a nice boost :-)
DC is great and if you are going to make it a regular excursion, try Aer Lingus, cheaper than BA and you do all the immigration in Dublin and just walk out the other side.
Tate & Lyle (LON:TATE) - Strictly too large for Stocko commentary but wonder what thoughts on the deal announced today, with purchase of American company. Such complicated financial wheeler dealing always gets me but its there all the time - Market seems unimpressed - down near 5% this morning - but who knows Maybe Buffet would have bought it in previous years but now just crumbs off the table - he has grown so big.
My only comment on the Tate & Lyle (LON:TATE) deal is that it looks less than conservative to continue with the share buyback of the Primient proceeds when you have just added nearly £1bn of debt to buy CP Kelco. Surely debt reduction is the priority after a major acquisition?
The market reaction to TATE sums up a lot of what is wrong in the UK market. For ten years they have sold lower quality businesses at very good prices and shares derate in response, now they make an acquisition of a better business, the shares fall. Until we return to an environment where there are large, long term, institutional investors, large companies that seek to grow will be frustrated.
Not sure about that assessment. Tate & Lyle (LON:TATE) may have done the right thing in focusing on higher growth/higher margin businesses, but disposals of low margin/low growth inevitably means selling on low multiples and buying on high. That can work long term if the growth comes through from your focus area. The speciality business has consistently underwhelmed and probably doesn't merit the EV/sales multiple expansion that has still occurred despite the share price weakness.
Today's deal also looks expensive and risky to me. Look at what has happened to the Kelco numbers in the past two years.
Current Whitbread (LON:WTB) buyback is a modest one and done as Paul wrote while the shares look good value.
Don’t know how many know this but it’s interesting from the are buybacks a good idea perspective. Whitbread got almost £4 billion from their sale of Costa to CocaCola in September 2018. They decided to “reward their shareholders” by returning more than half those proceeds via a big £2.5 billion buyback which was completed in July 2019. The share price throughout that period hovered around the £40 mark.
By November 2019 the share price had fallen to £36. Did that £2.5billion buyback really reward Whitbread (LON:WTB) shareholders?
Unfortunately in 2020 came covid. Covid was an extreme example of an unforeseen shock, but Companies can always be hit by unforeseen events and hence sometimes those profits warnings. That buyback “reward” saw a further share price fall.
Then in May 2020 Whitbread (LON:WTB) announced a heavily discounted £1 billion rights issue at just £15 which not only upped the share count the previous buybacks had reduced, but meant that those “rewarded” shareholders needed to cough up real cash of they didn’t want to be diluted! The share price bottomed at £20 in October 2020 and that was half the price of that big £2.5 billion buyback “reward” or “returning money to our shareholders.”
The share price is now £29 and has never got near to the price it was at the time they started buying back. I don’t believe it was a “reward” and that applies to far too many buybacks which are too often undertaken regardless of whether or not the share is good value. They can be effective and Next (LON:NXT) is a very good example where over the years they’ve halved the share count by only buying back when thinking the share is good value.
But for very Company using buybacks effectively there are so many more like Abrdn (LON:ABDN) . They started their £multi million buybacks over5 years ago when the share price was about £5. Their buybacks have continued every year since then with the share price falls relentless throughout, and the share price is now down 70% to just £1.50. So much for their buybacks rewarding their shareholders! It was those who got out fast taking advantage of Abrdn (LON:ABDN) being a willing buyer of their shares who were the ones “rewarded” by their buybacks.
I often use news of a big buyback as a reason to get out and time and again it proved the right decision as the share price subsequently fell. It worked well when I sold Abrdn (LON:ABDN) at about £4.50 as soon as the share price fell away once they started their big buybacks. I bought back a while ago around the current price because the dividend is now 10% and the share looks so oversold thanks to incompetent Management decisions that it could be a sitting duck for a bid, or ripe for recovery anyway if better Management ahead.
YouGov (LON:YOU) Finally getting somewhere. So EPS 2025 (July) cut to around 44p? valued around 12.5x at 550p just now if you believe forecasts
"Berenberg said it was moving its forecasts to the bottom of the range and reducing its FY24 revenue and adjusted EBIT forecasts by 4% and 37% respectively, hence the target price cut.
The bank said: "Management commented that it will look to take action on costs in FY25E and therefore we anticipate a margin recovery from the trough margin in FY24E. In terms of FY25E estimates, we reduce our revenue, adjusted EBIT and adjusted EPS by 5%, 18% and 19% respectively."
Taken until 10:30am . YouGov could have given us this information at 7am, but they couldn't be arsed.
Last year's h2 was lower than H1 with no explanation. The opposite the year before. So the trend was clearly down and has continued.
National World (LON:NWOR) if interested in this cheap newspaper publisher, Downing have now sold their whole position. The trade has not printed yet as far as I can see but the regulatory filling shows them with a zero holding.
National World (LON:NWOR)
"The trade has not printed yet as far as I can see"
If you read the RNS you will see that the trade date was the 18th -
National World
Disgrace of a company with zero interest in shareholders .
It’s the “vehicle” of egotistical David Montgomery to enrich himself and his cronies above and beyond shareholders who should be happy to support him .
Wish he would stick to his Robin reliant as his vehicle .
Avoid like the plague .
Clear breach of the golden rule .
YouGov (LON:YOU) have now missed for 24 as the H2 pick up has failed to materialise.... in a year of elections, Euro Football and Olympics. The shares have been weak anyway and it doesn't look a huge miss but following a decent acquisition and a medium term plan to grow at mid teens .... they "look" like actual growth is in the 2-3% range. It's hard to say since we don't know what the CPS revenue is.... but the comments re revenue recognition policies and a "small" shift to 2025 are unhelpful. They may however mean the core business is performing slightly better than I suggest. Either way, you did have a potential GARP stock looking cheap.... now looking a little low on the growth.
Seems little sense jumping on board even if gets a little whacked today... since its become a somewhat hopeful trade on better trading coming through and Id say you can wait to read the finals and see how their 2025 has started. Shame for now but all is not lost, stays a watch list share for me.
PS... just seen the open price -30%.... I expected a 10% ish hit so maybe more to this than I suggest!
Wow, had to double check YouGov (LON:YOU) down 37%
Wondered why it had been so weak lately, thought like you RD maybe down 10%. Must be a chainsaw job to the forecasts that us plankton cant see.
Anything in your supercalifragilistic morning broker roundup Paul?
Wow, had to double check YouGov (LON:YOU) down 37%
Wondered why it had been so weak lately, thought like you RD maybe down 10%. Must be a chainsaw job to the forecasts that us plankton cant see.
It’s in the RNS loud and clear. FY24 fc PBT cut by a third. Now lower than FY23. Instantly re-priced priced for ex-growth, as if the previous big fall since Feb hasn’t been savage enough.
Now a serious candidate for a bid, perhaps? Gartner would gobble this one up with relish.
Hi BnB
Re YouGov (LON:YOU)
You said -
"It’s in the RNS loud and clear. FY24 fc PBT cut by a third. Now lower than FY23."
I've read the RNS four times, and I don't see anything saying that. Please could you elaborate where you get that info?
The only profit guidance I can find in today's YOU RNS is this bit -
"therefore we now expect full-year Group adjusted operating profit to be £41-44 million"
But it doesn't state what previous guidance was! No broker notes available either. So I just looked at the H1 to H2 movement, which shows a sharp fall.
Very unsatisfactory reporting. If companies give profit guidance (helpful) they must provide a comparative number for previous guidance.
Wolf asked above if there was anything in my morning broker roundup (pre-market)? Yes, one broker expected a 10% drop in share price today, instead of the c.-38% early price.
Regards, Paul.
Thanks Paul, appreciated.
Thomas, the 62m was from a Bloomberg article this morning. Imagine a billion £ company hiding forecasts like this. Why not use PBT or EPS which are available, or include what the forecast are in the RNS, and an update on debt is surely appropriate. Instead I have to spend half an hour messing around googling this mornings news.
Latest snippet of info -
"Peel Hunt analyst Jessica Pok said this indicated downgrades to forecasts for financial 2024 of around 6% to revenue, and 38% to adjusted operating profit.
"This was a disappointing statement from YouGov, given the high visibility reported at the interims," she commented."
There is a Bloomberg article quoting Berenberg who consider the current guidance for EBIT 32% below consensus. There are actually a couple of notes on the companies website ....one of which has £60m as a forecast. I agree with all.... but most of all I find this statement woefully lacking in explanation for such a fall following an equity raise last year and a directors sale highlighted below by Wolf. Im afraid although the fall today is seductive I want to see the full year nos ... year end 31 Jul. One fears 2025 becomes a year of transition with a nice exceptional to achieve margin forecasts. Their mid term guidance to double revenue at current margins is in tatters. For a company that compounded at 19% in the last cycle this is very disappointing.
Hi Paul, I was working on the assumption that everyone could see the forecast PBT in their feed (presumably Stocko) as I have figures from both Sharepad 66k and Refinitiv 61k. The 30%+ fall was immediately anticipated and endured - I held, until this morning, ouch.
Apologies for not picking up on the hole in the Stocko data - it hardly seems the moment to quibble that Stocko has a blank in the relevant field when the other providers’ numbers turn out to be so wrong. But they can only reflect consensus after all.
re YouGov (LON:YOU) in the year to Dec 2022 CPS did Revenue of £113m and PBT £20m ... the deal completed in Jan so should add about £10m with a lower than group margin. It was trading well when half year results were announced in March. So looking at the rather aggressive reaction today and the flimsy revised guidance of £41-44m .... seems to be well short of 2x H1, £56m which is about the same as last year £45m + £10m from CPS..... so the comment re some contribution shifting to 2025 ...suggests quite a bit actually. OR the core is doing much worse than the relatively small miss in revenue suggests. Still the reaction seems severe but the wording of this statement is very poor.
Thanks RD. Didn't realise Ad Operating profits had been hit so hard in H2. Ad op profit to be £41 million -£44 million, compared with estimates of £62 million.(From Bloomberg article)
Peel Hunt said “The shares have tumbled by c.25% since the 1H results in March, suggesting that the market had been anticipating a downgrade. However, today’s downgrade is larger than we expected,” They plan to revise their forecasts in due course after the “disappointing” statement today.
Well played to Mrs Shakespeare. Sweeter timing than David Gower.
Thank you, Wolf of Small Street. Please could I ask where do you find the estimate of £62m? I have been looking for the previous guidance/estimates and can't find them anywhere.
Please could I ask where do you find the estimate of £62m?
I can see it on Sharepad
Yougov - Isn't this the company a certain tory cabinet minister established and sold on then more recently resigned after a hiatus over taxation issues - legal but questionable - or was it another company ?
I am sure I read it here that profit warnings come in threes. Does anyone know if this is their first profit warning in recent times or have they and more? Thank you.
On the YouGov (LON:YOU) banking covenants, the AR23 says “The facility includes half-yearly covenant test for EBITDA leverage and interest cover”. The thresholds are not stated in the AR or in the RNS announcing the acquisition.
The going concern statement in AR23 says: "“A severe but plausible downside scenario has been modelled where revenue targets are missed by up to 20% (existing YouGov business) and a 10% miss for the planned acquisition, due to reduced revenue (e.g. from clients’ delays and a slowdown in securing new business). These revenue sensitivities are considered appropriate given the relative proportion of recurring revenue streams for each business. Even in this scenario, the Group has strong liquidity and does not breach any banking covenants for the new term loan facility. Mitigating actions within this downside scenario and all within management’s control are: • lowering sales commission and bonus payments; and • reduced capital expenditure.”
Taking the lower revenue figure guided by YOU (£324m), this is a 5% miss vs. forecast (£341m), so well below the scenarios modelled for going concern purposes.
The revenue miss has a large impact on profit in part because operational gearing is large with GM at 85% (although the profit downgrade is a bit more than 0.85 x the revenue downgrade, so it's not the whole story).
"I am sure I read it here that profit warnings come in threes"
Not here - here you would have heard that only 4.9% come in threes. Although a while ago now this webinar was for me one of the best produced by Stocko and I would highly recommend it to anyone who hasn't seen it:
YouGov (LON:YOU) was in Ed's multibaggers presentation.Biggest 1 day fall since 2008-2009 i think.Hopefully it's one of those quality shares which occasssionally do have profit warnings like every other company now and then and just spooked the market and the shorts took advantage.A fair number of fund manager interviewees mentioned the company in Paul Hill's interviews in the last year too.
Need to see how the new acquisition plays out amongst other things i'm guessing.I was surprised too that election polling is actually a smaller proportion of their overall business nowadays as folk were mentioning it during the electioning years both sides of the pond here.
Broker forecasts.
Paul commented on Bloomsbury Publishing (LON:BMY) -
"BMY doesn’t seem to arrange for any broker notes to get through to pond life like us, I just cannot understand why some companies have this silly blindspot in their investor (lack of!) communications".
Yesterday I had a look at large cap Spectris (LON:SXS) following a TU and came across this on their investor website:
https://www.spectris.com/asset...
Brilliant. If they can do it why can't every company?
Every IR department maintains such a spreadsheet. Very easy to share it.
Bloomsbury Publishing (LON:BMY) Spectris (LON:SXS)
Hi Sharw
Thanks very much for sharing that on Spectris (LON:SXS).
You're right, that's very helpful and it would be great if other companies could provide something similar where broker notes exist.
On a similar if different note:
I think Bloomsbury Publishing (LON:BMY) have been terrible when it comes to Investor Relations, especially their communication with PI's, which is odd given their intention to improve this.
Their inability to answer, and sometimes even respond to, my questions over the years hasn't help, in contrast to nearly every other IR department out there. I only continued to hold (until now) as the numbers just looked too good not to.
I initially put this down to the CFO being busy, but things haven't improved since the appointment of a dedicated person. Has anyone else had more luck than me?
The above certainly contributed to my decision to start exiting my position. If there's future upside to come, I certainly can't see it, and sadly there are no broker notes I can access nor anyone at the company willing to answer my questions or at least steer me in the right direction.
It's a shame as it's been a wonderful holding over the last few years and grew into the largest position in my portfolio :(
RIP Bloomsbury - it was lovely knowing you.
BMY. They appointed a Hd of IR in Tamsin Garrity in January of this year. She is either still growing into the role or harbours a touch of disdain for PIs....
Hi Sharw
I understand your frustration with Bloomsbury Publishing (LON:BMY) but I think the nature of their business makes it difficult for them to provide much additional useful information.
As no doubt you read their RNSes and watch their regular video presentations, I am sure you have a good understanding of their multi-pronged strategy.
From year to year, their performance can be massively affected by a small number of authors having huge international bestsellers (or not).
Hence, most years, broker forecasts will be very conservatively set and will probably be upgraded. IMHO they no choice other than to take this app.
Additionally, given the significant cash generated over time, one knows £BMY will be on the lookout for earnings enhancing acquisitions. There have been a series of these over the years.
What else is it you want from them?
Bloomsbury Publishing (LON:BMY)
Hi Shanklin100
"What else is it you want from them?"
Personally, I'd appreciate some responses to what I think are reasonable questions.
For example, prior to the recent IMC presentation I submitted a question on the barely profitable Adults and Special Interest channels and questioned whether the plan was to keep these channels going.
The Adult channel actually posted a £3m loss in H2, so this seems like a fairly reasonable question.
How did the company answer?
They didn't. No response whatsoever.
Then in the annual report published last week there was one paragraph hidden away stating that they're going to invest in a new strategy for the Adult channel, which could be risky.
They've never spoken about this before. Ever.
How much are they investing?
What's the risk?
What returns are they hoping for?
What exactly is this strategy?
Why not just talk about during the IMC meeting given that someone has asked?
---
There are now no profit metrics for the BDR product.
They used to publish these and even set a target of a 30% Operating Margin.
Sadly we have no idea how they're doing against their own targets. They did not respond when I asked if this was still the target.
I'm genuinely curious to know if BDR margins are being eroded by licensing in external content (which I think they are doing - again, no answer).
I appreciate that most PI's won't look at this detail or do models, but I do and I would hope that a dedicated IR team for a relatively small company would respond, otherwise what's the point in having this department?
The larger companies certainly reply when I've asked for additional details.
---
I completely understand the swings and roundabouts associated with the publishing industry, but it's quite clear that Bloomsbury is all about Maas.
By my calculations 40% of revenues last year came from her books - a remarkable result, but of course remarkably concentrated too.
I fully appreciate that the company can't share too many details about one author, but I would therefore hope for additional details on the rest of the business when asked.
---
I also have my doubts over the recent acquisition, specifically around additional BDR profit that might be generated and possible Academic channel margin dilution, but sadly I'm sure that my questions would not be answered.
That's a shame as there seem a lot of unknowns for us little guys/gals for one of the most important growth drivers of the business. I have a feeling that analysts will, however, be privy to this information.
Bloomsbury Publishing (LON:BMY)
Hi Abtan
Following our earlier exchange I emailed IMC to ask them to remind BMY for the answers to those questions not dealt with at the time. It is 2 weeks now.
Hi sharw,
My apologies, I take your point re Bloomsbury Publishing (LON:BMY) . What were your questions?; they're not visible at IMC.
I must admit Bloomsbury Publishing (LON:BMY) completely ignored a question I asked a while back on IMC about their continuing activity in Specialist books; it perpertually appears to make little or no money and certainly no return on the investment they make in this area. Its almost as though the prestige of some of the titles outweighs its financial usefulness to the company.
Interesting detailed comments abtan, thank you. As you say, there is no reason for Bloomsbury Publishing (LON:BMY) not to respond to your questions.
Any thoughts from the community on the share buy-back announcement from Metals Exploration (LON:MTL), (I hold), this morning would be much appreciated.
Debt issue solved. Grumpy shareholder off the register. Seems good to me. But maybe people were hoping it didn’t have to come to this?
Although we as shareholders seem to have coughed up 15% interest on a lone and paid a 20% premium to get the grumpy shareholder off the share register. Result even more grumpy shareholders.
The deal looks generous to me. RTL are being paid in full on the disputed (small) amount, they are being bought out at a price based on the recent highs, and they get a sweetener if Runruno turns out to have more gold than is currently thought. MTL ends up with over 50% - presumably they want freedom of action for the Abra project. Do outside shareholders benefit? Only if Abra goes well. I hold.
Many Thanks WTT, Dave787 and SundayTrader.for you input on Metals Exploration (LON:MTL)
Ref Metals Exploration (LON:MTL) Nice to get the debt all sorted out, but what I certainly do not like is the £19.5M in shares they are buying are to be held in treasury instead of being cancelled.
I can't think of any positive reasons why that would be.
Metals Exploration (LON:MTL) maybe I don't understand fully but when shares are bought back and held in Treasury, that doesn't benefit shareholders at all. The wheeze seems to be to wheel them out later when no one is looking for the benefit of directors in particular. I would vote against this option.
My morning smallcap tweet: Crash register
Active Energy (LON:AEG) LSL Property Services (LON:LSL) Filtronic (LON:FTC) Alpha Financial Markets Consulting (LON:AFM) Franchise Brands (LON:FRAN) NCC (LON:NCC), Futura Medical (LON:FUM), Angling Direct (LON:ANG), Lords Trading (LON:LORD), Strix (LON:KETL)
◄Active Energy (AEG)► if offer for Coalswitch assets not concluded co will propose de-listing and a members' voluntary liquidation. Also FY audit will be late and shares will be suspended on 1 July. [SP=0.2 Cap=m]
◄LSL Property Services (LSL)► AGM stmt - outlook for FY in line and potentially slightly better than our updated expectations [SP=316 Cap=328m]
◄Filtronic (FTC)► guides FY-May rev £25.4m and adj EBITDA £4.8m, both ahead of market expectations. [SP=70.2 Cap=153m]
◄Alpha Financial Markets (AFM)► confirms bid leaked yesterday. Rec offer of 505p.a 29% premium to the pre-leak price. [SP=478.5 Cap=548m]
◄Franchise Brand (FRAN)► FY-Dec. Cautions on FY24 due to softening demand and the change in the accounting treatment of sale of franchise territories income. FD scarpers after only 9 months; he is not thanked. [SP=168.4 Cap=326m]
◄NCC (NCC)► guides FY-May adj op profit c.£31m, ahead of F/C of £29.7m. [SP=143.8 Cap=451m]
In line: FUM, ANG, LORD, KETL
Strix (LON:KETL) - AGM statement offers encouragement to investors - link to new note: https://www.equitydevelopment....
Ahead of today’s AGM, Strix has issued a trading update. Encouragingly, management note signs of recovery within the kettle controls market ahead of peak season, and adj. PBT expectations for the full year remain unchanged. YTD cash conservation actions have resulted in cash generation running ahead of internal expectations which, combined with the recent placing, means reductions in net debt/EBITDA leverage are ahead of plan. We retain our prior estimates and a fair value of 167p/share almost twice the current share price.
We maintain our fair value/share of 167p and think the shares remain materially undervalued relative to the average of our valuation models.
Maybe but it’s RED based on Paul’s review in Oct last year . What has changed ?
Hi Caper4
I don’t hold but quite a lot has changed at Strix (LON:KETL) since OCt last year. Debt has been cut materially and with the recent 5% placing with an existing institutional shareholder reducing debt further (and accelerating the move to a debt/ebitda ratio of 1.5 by 6 months) there is far less risk associated with the company. That debt reduction also means significantly less interest payments adding to profits.
Added to this trading has picked up so profitability and gearing will be increasing.
I was watching this at 66p at the nadir and was also then flagging the large amount of debt which felt like it could swallow the company. I didn’t want to leap early so have been sitting on the sidelines as it has gradually drifted upwards but given the progress made I would begrudgingly admit that’s probably deserved.
Very different risk profile to Oct. As Paul always says his RAG status is based on the day, so you need to look at the progress and assess that against the very valid warning points that were in there then. If he looked at it today I’d guess at Amber/Green. (lol - we could start a book on guessing Pauls RAG status as events unfold :-) )
Strix (LON:KETL)
Hi David
I have vague recollections of us discussing the precariously high debt levels here and wanting to wait until this came down (or maybe I read one of your comments and it aligned with my own thoughts at the time.)
For me debt still seems very high. I knew there was a placing recently, but I only got around to looking at it this morning. It looks like it reduced debt by 10%, which almost seems insignificant given how much debt there was to start with. Why did the company not try and raise more cash?
For me debt is still too high relative to the cash generation, even with the now slightly reduced interest payments, and I personally would prefer to see the next set of financial statements before deciding whether to invest.
Sticking with the colour coding theme, I'd probably go with Amber.
Thanks
A
Today's FY results from Mountview Estates P.L.C. (LON:MTVW) might qualify for the record of the shortest FY results ever issued...
I often grumble about long results reports, but this one is in the complete opposite direction!
(I hold in the Boon Fund)
Filtronic
If Carlsberg did RNS’s this would be it .
As opposed to the previous cloak and daggers and guesswork as to who their customers were now they can drop the space X bomb quite freely .
Now seems to be spitting out some cash as well as significant increase in turnover .
That’s quite interesting, It’s not usually the case with rapid growth that cash gets generated . This indicates very high margin .
Filtronic has become my “get out of jail card” as most of my portfolio (except transesnse) goes slowly sideways or gently downwards .
Guess this proves what Paul hill spoke about a while ago , one or two runaways can outweigh 6-8 underperformers .
153 million market cap doesn’t look crazy though not sure where this is heading . Looks orbital at least .
Agreed. Looks like a marginal beat on both revenue and EBITDA. It was the CEO's comments that filled me with excitement, ''a very strong order book''. Think this may have a lot further to go!
Hi Planetx,
If you engage in stock picking we all have periods of under performance and over performance so patience is required along with a medium term view. Unless you are a trader of course which actually is no different other than your medium time period is shorter.
The challenge is that when you are under performing someone else will be highlighting how well their portfolio is doing and that gives a lot of investors FOMO.
You need to find a process that works for you over the longer term and measure your performance over a relevant period - sometimes you will be shooting the lights out and other times your stocks will be frustrating laggards. One of the values of dividends imo (rather than share buy backs) is that in frustrating times you have a regular interest stream which beats sitting with cash in a bank.
Take this year - Paul Hill I think said his portfolio is slightly negative by 3% whereas others are having standout years but his long term annualised return is something like 16% compound. Our own Paul Scott mentioned that whilst his 2024 picks are up 25% his own portfolio was quite moribund but then he had a very high return last year (two different approach’s in one with Paul). My portfolio as an example is tracking ahead at 16% for the mid year but didn’t have anything to write home about particularly last year. What matters though is long term performance which is often weakened when investors keep chopping and changing style chasing someone else’s return.
hi David
What matters though is long term performance which is often weakened when investors keep chopping and changing style chasing someone else’s return.
What an excellent point. I hadn't previously looked at things through that lens but you are spot on.
Thanks for highlighting this.
Snazzy
David
Funnily enough I’m running circa 20% up in 10 months .
Remember I only hold 8 positions , 6 have gone sideways ish , one has tripled , and one up 30% one down 20-%.
I’m actually pretty confident on the sideways movers also .
Concurrent Technologies (LON:CNC) largest ever contract win announced this morning in a positive RNS. This is a Lord Lee favourite commented on by him at a previous Mello. One of my best UK performers this year and shortly to go ex-div.
Not going to request CMC Markets (LON:CMCX) as I am sure it's the reason Paul got up early this morning, thanks for those early bird specials.
I top sliced CMC Markets (LON:CMCX) some time ago and have a mechanical 20% trailing stop loss on the rest, in my mind not set with broker. The question I have for the maestro, is there any indicator that we could use that says sell, or just continue to let it run until the stop loss is hit.
At around 8.20 am CMC Markets (LON:CMCX) put out revised RNS, so, Gloucester Bob, you may not need the maestro's thoughts after all. I hold CMCX having doubled down successfully for a change and will continue to hold.
I can't find such a revised RNS from CMC Markets (LON:CMCX) Silver Moon, either in LSE website or Investegate. What does it say?
Cheers
Chris
It's here, on Stocko:
** Shares of British investment platform CMC Markets CMCX.L up 8.5% at 305p
** Sees net operating income of between 320-360 million pounds ($406.69-$457.52 million) in FY25 on a cost base
** FY adj pre-tax profit jumped 52% to 80 mln pound
** "Current trading proving encouraging with positive trends seen early in the new fiscal year," said CMC
** CMCX shares rose 190.5% YTD
Actually this came later than the revised RNS but is more optimistic in my view.
Silver
CMC Markets (LON:CMCX) The 8:22am post was an updated news post not an RNS, in other words it wasn't an update from the company.
Sorry slopsjon, didn't know there is a difference but hey, any good news is good news!