Small Cap Value Report (Thu 21 April 2022) - G4M, NRR, CARD, CHH, CFX

Good morning, we have Paul & Roland on duty today. Sorry for all the typos in my (Paul) sections yesterday. I was en route back from a week in Malta/Gozo, and wrote my part of the SCVR from a Hard Rock Cafe inside Malta Intl Airport. Not the easiest place to concentrate in a packed airport, on my travel laptop! Also a framed cream jacket that Madonna had worn on stage somewhere a while ago, kept distracting me.
Agenda -
Paul's Section:
Gear4music Holdings (LON:G4M) - a mild profit warning for FY 3/2022, with EBITDA guidance lowered by 8%. Cautious outlook comments too, given macro conditions, which shouldn't really come as a surprise, but seems to have done, as the share price has opened down about 27%. Forecasts slashed by about half for FY 3/2023. Tough in the short term, but at some point the market might start anticipating recovery.
Card Factory (LON:CARD) - excellent news for shareholders, with details announced of a bank refinancing which removes the previous need for an equity fundraise. Risk:reward has therefore greatly improved. Although I think it remains to be seen if the company's longer term prospects are any good, considering online competitors now dominate that space. No divis for c.2 years, as bank debt takes priority. The bounce today is justified, but what happens after that?
Colefax (LON:CFX) - ahead of expectations update. Looks an interesting value share.
Roland's Section:
Newriver Reit (LON:NRR) - this retail property REIT has made good progress with disposals and deleveraging and appears to be nearing the end of a demanding turnaround. I’m impressed by today’s update and tempted by the high yield and potential value I can see here.
Churchill China (LON:CHH) - this family-owned AIM business supplies crockery to the hospitality trade. Sales rebounded strongly during the second half of last year and today’s results are ahead of expectations. The balance sheet looks bulletproof and cash generation is strong. The shares have fallen by 25% since 1 September. I think Churchill is starting to look reasonably priced.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Gear4music Holdings (LON:G4M)
360p (pre market open)
Market cap £76m
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a year-end trading update covering the 12 months to 31 March 2022.
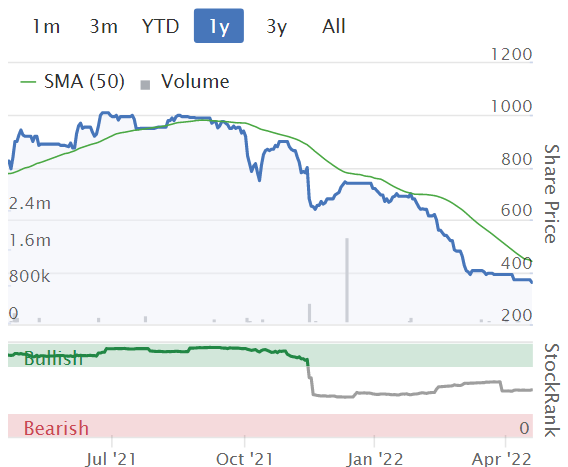
This looks like a miss, so a profit warning. Given that the share price has already dropped by about two thirds from a peak around 1000p in Oct 2021, it’s difficult to know whether investors would sell on a slight profit miss, or sit tight? We’ll soon find out.
Key points in today’s FY 3/2022 update -
Revenue of £147.6m is down -6% on last year’s pandemic-boosted result. This is only a slight miss, as a drop in revenues from last year’s peak was already expected and flagged previously.
Overseas revenues are down -18%, compared with +5% for UK. So a key question mark is whether G4M can return to growth in overseas markets, with its additional recently opened distribution centres? The jury's out.
EBITDA guidance is now £11.0m - an 8% miss against £12.0m forecast market expectations (helpfully provided in footnote 3)
Weaker demand in Feb & Mar 2022 caused this miss against expectations.
Outlook comments sound cautious short-term, which shouldn’t really come as a surprise to anyone, given the much reported cost of living squeeze. That’s why the share price has already dropped by two thirds, as investors anticipated a slowdown -
Short term inflation-linked overhead cost pressures and weaker consumer confidence across the broader retail landscape will mean the best opportunities for stronger growth during FY23 are likely to be in H2. We are, accordingly, moderating our overall growth expectations for the new financial year, which we believe is the prudent approach in the current environment.
During what may be a more challenging FY23 H1 retail environment, sales and margins will be supported with good levels of inventory across our distribution centres, continuing expansion of our European operations to drive European website conversion, and sufficient working capital to continue investing where appropriate.
We believe we have the right operating structure to continue accelerating our market share gains and remain confident in our medium and long-term profitable growth strategy. We look forward to providing further details of our progress when we publish our full FY22 results in June."
Forecasts - many thanks to Singers for revised numbers this morning.
EPS is a much more useful figure than EBITDA, so I’ll focus on that, as usual.
For FY 3/2022, Singers is now forecasting 15.5p, down from previous expectations of around 20p. This gives a PER of 23 times, which looks too high now, so I imagine the share price is likely to take a dive today.
Probably sensibly, Singers is not expecting any earnings growth in FY 3/2023, with a drop to 14.9p EPS forecast (roughly halving from previous expectations for c.30p), then a recovery in FY 3/2024 to 18.8p - although I don’t think anyone can forecast accurately that far out, given all the uncertainties.
My opinion - I’m sitting on the sidelines at the moment with G4M. As mentioned previously, I was effectively forced to clear out or reduce a lot of positions held in a leveraged account earlier this year, and G4M had to go. There had been one too many large Director sales also, which tilted risk:reward downwards for me.
Would I be buying back in now? Not yet, because I think the valuation could reset further down, given today’s reduced expectations.
The other issue is whether it should still be valued as a growth business at all? The same quandary we have with lots of online companies, that did well in the pandemic, but are now struggling to deliver growth, and experiencing increased costs, squeezing profits. Can they re-establish a decent growth trend? We don’t know at this stage, although it seems to me the shift online for many sectors look permanent, not a flash in the pan.
On the upside, I think G4M is a fundamentally good business, is still profitable, and has an OK balance sheet. There have been acquisitions too, which should boost future profits.
As with everything consumer-related, it depends what your investing timescale is. We all know that short-term company profits are under a lot of pressure, so it’s perplexing why the market reacts so negatively when companies confirm the obvious fact that trading is more difficult at the moment. Hence share prices seem to be punished twice - once in anticipation of bad news, and again on release of bad news. At some stage, that’s going to mean some seriously good bargains, for the longer-term, but it’s a brave person who tries to predict the turning point.
I see G4M has just opened down 27% at 262p (market cap of £55m). It’s getting tempting at that level. It’s a fundamentally sound business, so why sell now, that it’s lost ¾ of its value due to a soft period of trading that should pass once the world has digested higher inflation? If the fall continues, then I’ll be looking to rebuild my position here, let’s see where the dust settles.
There’s nothing in today’s update that is a serious concern to me, it’s just going through a soft patch, as you would expect given the macro picture.
.
.
Card Factory (LON:CARD)
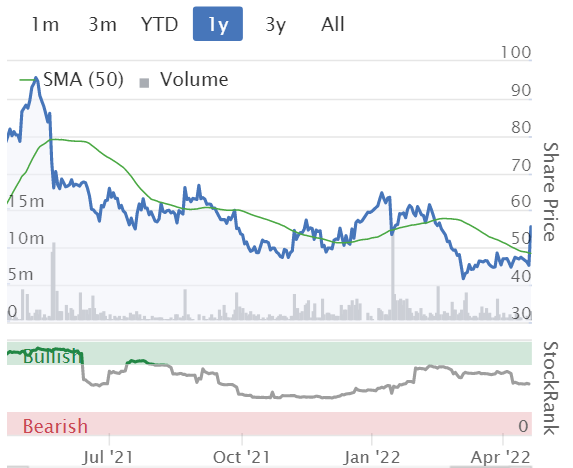
57.5p (up 27% at 09:13)
Market cap £196m
Excellent news for shareholders in this greetings card retailer.
The background is that stretched finances (way too much debt when the pandemic hit) put CARD at very high risk of needing to do a heavily dilutive fundraise, or at one stage it even looked a candidate for possible insolvency.
Hats off to management, as they’re managed to scrape through without dilution, as today’s announcement concerns a refinancing of the bank facilities, with no equity raise. That removes a significant risk, so I can see why the market has reacted so positively this morning.
To be fair, the situation was improving last year, as I reported here in Nov 2021.
Reading through old SCVRs to refresh my memory, this one in Jan 2022 flagged up that CARD was warning of a large increase in costs.
More recently, the share price has slipped down further, to almost 40p, but I think that was just the general market panic we saw, which affected almost everything in small caps, so not company-specific.
Today’s update - I’ll just summarise the key points, see the RNS for full details.
Card Factory, the UK's leading specialist retailer of greeting cards, gift, wrap and bags, today announces that it has agreed terms of a refinancing with its current banking syndicate.
Good progress made on reducing bank debt from cashflows.
Revised bank facilities agreed, of £150m (reduced from £225m previously).
Main facility is £100m RCF, available until Sept 2025.
The other £50m is now term loans, repayable in stages between 2023-25, so this limits any future divis, as cashflows are prioritised (rightly) towards debt reduction. Restrictions on divis likely to end Jan 2024, if debt:EBITDA is below 1.5x
Actual bank debt was £79m at 31 March 2022 - which looks reasonable, and is usefully down from £96.5m reported in the last interim results at 31 July 2021. Although note the balance sheet as a whole is still very weak, with NTAV negative at £(119)m at end July 2021.
For shareholders, this is the key part, and it’s really good news -
The best efforts commitment given by Card Factory to its banks, to raise net equity proceeds of £70m by 30 July 2022 has been removed from the revised facilities. The Board has no current intention of completing an equity raise.
Directorspeak sums it up well -
"I am pleased to be able to announce the successful completion of Card Factory's refinancing today. This is an important milestone for our business, ensuring we have the financial foundations in place to capitalise on the opportunities ahead. We are now well positioned to continue our strategic transition from a store-led card retailer to a market leading omnichannel retailer of cards and gifts. I look forward to updating you on our progress at our full year results next month."
My opinion - an excellent development, which I think management has handled with great skill over the last 2 years.
Remember that dilution/insolvency risks might often be avoided, but that doesn’t mean the risk wasn’t there. So shareholders at CARD got lucky by ignoring risk, rather than having any brilliant insight, in my opinion (especially in 2020, when the risk of dilution/insolvency was very high indeed).
It does worry me that we might be too complacent about balance sheet risk, because interest rates have been so low, for so long, that banks are usually happy to let problem debts reduce gradually over time.
What happens in a higher interest rate environment has historically been very different. If debts are constantly rising due to accrued interest, then banks tended to pull the plug.
Anyway, that now looks academic re CARD, which has reduced its debt a fair bit, and negotiated a good deal with the banks, for gradually reducing facilities. Hence no divis likely for a couple of years, unless it can pay down debt faster than planned.
Now that solvency/dilution risk has gone away, the big question is whether CARD can deliver a meaningful online performance? The CARD shops are nice cash cows, but what worries me is that online competitors in greetings cards are so well-established & have spent a fortune embedding their jingles & brand names into our brains, e.g. Moonpig (LON:MOON) ,that it might be too late for CARD to gain meaningful online market share? Or require such a big marketing investment that it might not be viable, and could cannibalise shop sales possibly?
So as things stand, I think the jury is out on how successful CARD is likely to be in future.
However, the key point is that at least we can now invest (if we wish) without the risk of a bombshell discounted placing being announced at a moment’s notice. That has to be seen as a big improvement in risk:reward for investors.
There’s also the current & impending squeeze on disposable income - how much is that likely to impact CARD? It’s not going to help, that’s for sure.
.
.
Colefax (LON:CFX)
650p (up 8% at 11:02)
Market cap £51m
I last reviewed Colefax here in 2014! It’s a luxury fabric & wallpapers designer/distributor, with 5 brands. Looking at its product website here, these look traditional designs, described as “timeless elegance”. The main difference with Sanderson Design (LON:SDG) (I hold) seems to be that Colefax outsources all production, whereas SDG has its own factories for at least some of its production.
Also, Sanderson is a bit bigger in terms of revenue, and makes a higher profit margin. Hence why SDG is about double the market cap of CFX.
Today Colefax says -
Since we announced our interim results on 27 January 2022 trading in our two major markets the US and the UK has been ahead of expectations reflecting strong demand for home-related spending. In addition our Decorating Division will deliver an exceptional performance this year due to the timing of completion of a major UK project.
Fabric Division profitability is highly operationally geared and as a result of higher than expected sales the Board now expects the Group's profits before tax for the year ended 30 April 2022 to be ahead of market expectations.
Like many businesses we are experiencing significant inflationary pressures so although demand is currently strong this adds a note of caution to prospects for the year ahead.
That’s good overall, although the caution on costs, operational gearing, and a major project, are all potential warning signs for us not to get too carried away with a strong year for FY 4/2022, as it may not be repeatable. There’s also the potential for macro/household budgets to come under strain. Although I reckon customers of luxury fabrics are not going to be worrying about the ‘leccie bill. So this could be a relatively safe part of the market when we’re worrying about a consumer downturn.
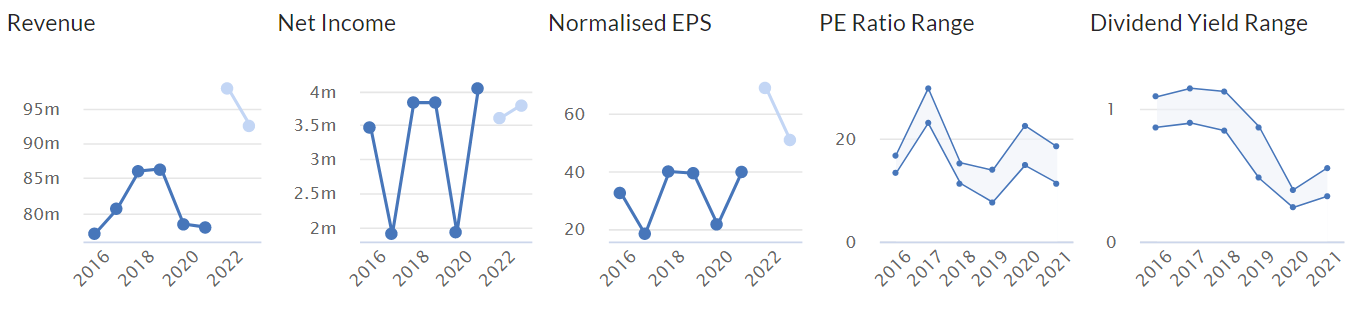
Market consensus is 68.6p on the StockReport for Colexfax. Actual is running ahead of that, but we’re not told how much. So maybe 75-90p is my guess? That gives an estimated PER of between 7.2 and 8.7 - an attractively low multiple. As always with PERs, it depends whether earnings can be maintained or grown from that level. Or should we be looking more at the historic earnings in a 20-40p EPS range as shown below?
.
.
The divi yield is very low, but the company seems to prefer doing buybacks, with a significant tender offer done in 2021. This creates an unusual situation where the share count has been steadily going down - so a nice share for people who hate dilution!
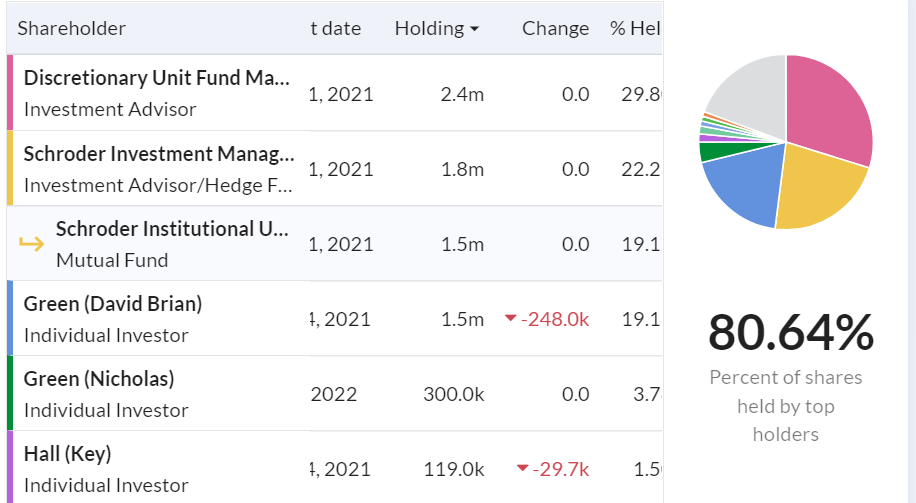
This is a hideously illiquid share, with the top 4 holders owning about 75%. Hence the quoted spread is extremely wide, but I usually ignore that, because the real price is usually well inside the spread. With an illiquid share you can even bid the market any price you like, and sometimes there’s a willing seller known to a market maker. That’s why generally the published quotes are best treated with a pinch of salt.
.
.
Interim results - I’ve had a quick look through, and the company’s doing well, with a strong balance sheet. The cashflow statement is positive too, a genuinely cash generative business.
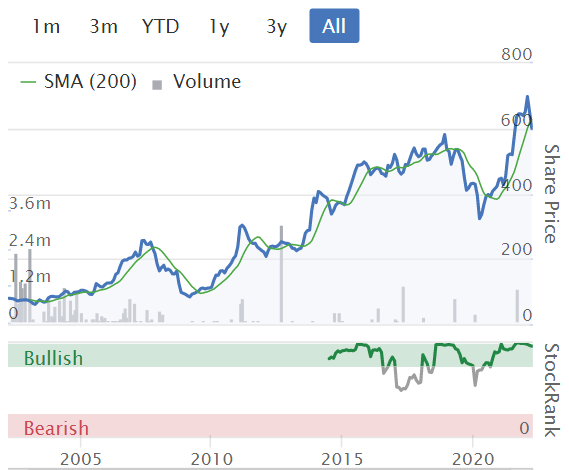
My opinion - not a company I’m familiar with, but this share looks an attractive value share to me. It’s 6-bagged since the 2008 lows. Although looking at the chart, I’d be a bit worried that now may not be the right time to buy.
.
Roland’s section
Newriver Reit (LON:NRR)
Share price: 86p (pre-open)
Shares in issue: 308.2m
Market cap: £267m
Trading update - return to capital growth
“Portfolio returned to capital growth in H2”
This retail property REIT is focused on community shopping centres and local retail parks. It’s been through a difficult period, but a string of disposals have aided deleveraging and the stock now offers a tempting dividend yield of nearly 8%.
Today’s update strikes a positive note, reporting a return to capital growth for the REIT’s portfolio and strong cash performance. With the stock trading around below NAV and offering such a high yield, I’m wondering if this could be an attractive value opportunity.
Financial highlights
In recent years, I’ve had three main concerns about NewRiver:
- Debt levels
- The quality of its property assets
- The sustainability of its dividend
Today’s update seems to address all of these issues.
Portfolio valuation: NewRiver says that an independent valuation of its portfolio as of 31 March 2022 has shown capital growth of 2.5% during the second half of FY22 (y/e 31 March).
This compares to a 3.1% LFL fall in the value of NewRiver’s retail portfolio during the six months to 30 September 2021.
No updated net asset value figure was provided today, but NewRiver’s half-year results showed an EPRA NAV of 131p per share. I’d guess the full-year figure will be lower, as £69m of disposals were completed in H2, from a portfolio valued at £702m at the end of September. However, debt reduction might offset some of these disposals.
I’ve estimated an FY22 NAV figure of 120p-125p per share, but this is only a loose approximation.
Unsurprisingly, the portfolio’s capital growth has been led by retail parks, which performed strongly during the pandemic. However, the group’s Core and Regeneration shopping centres are also said to have returned to growth.
The only area of weakness was the group’s Work Out shopping centres. As their name suggests, these are troubled assets in line for disposal or repositioning.
Disposals and debt reduction: NewRiver has completed £305m of disposals since April 2021. The majority of this came from the sale of the Hawthorn pubs portfolio for £222m last July.
The majority of retail disposals are said to have been in line with last-reported book value. So not fire sale prices.
A combination of disposals and a return to capital growth have enabled NewRiver to reduce debt and leverage.
- Net debt was £222m at 31 March 2022, down from £493m one year earlier
- NewRiver’s loan-to-value ratio is now said to be under 35%, compared to 50.6% at 31 March 2021. The company’s guidance is for LTV of 40%.
These numbers look healthy to me. In my view, they put to rest any remaining concerns that the company might be forced into an unfavourable refinancing.
Cash performance, rent collection and occupancy: Rent collection for the year ending 31 March currently stands at 95% of rent demanded. Rent collection for Q1 FY23 said to be tracking ahead of the same period last year, as I’d hope.
Leasing volumes have improved and long-term leasing deals signed in FY22 were an average of 7.4% ahead of latest ERVs (Estimated Rental Values).
Occupancy remains stable at 95.6% (March 2021: 95.8%).
As a result of this solid occupational performance, underlying funds from operations are expected to be at the upper end of analysts’ estimates for FY22. Essentially, this is a measure of rental profits from the REIT’s portfolio.
This performance should mean that the forecast dividend is assured.
My view: NewRiver was already suffering from difficult retail property market conditions before the pandemic. The trust has been through a brutal downturn and I think CEO Allan Lockhart deserves credit for having made it this far without diluting shareholders.
Mr Lockhart now appears to have returned the business to a stable footing, with the potential for steady growth.
Although I wouldn’t want to overpay for NewRiver’s assets, some of which are fairly uninspiring in my view, I think the stock could be good value at current levels.
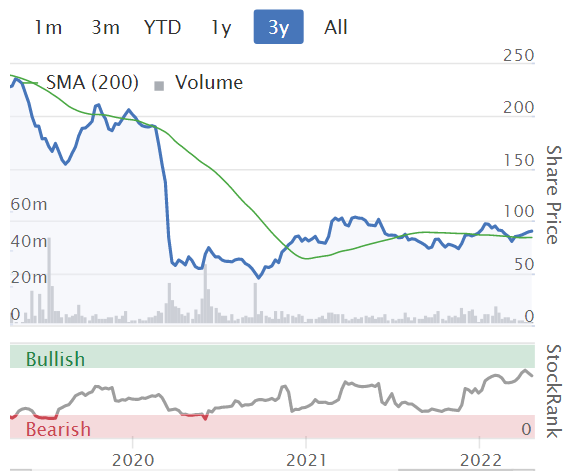
Based on my simplified NAV estimate of 120-125p per share, NewRiver stock could be trading at a 25% discount to NAV after this morning’s gains. When paired with a near-8% dividend yield, I think this could be an attractive high-yield stock.
.
Churchill China (LON:CHH)
Share price: 1,500p (+7% at 08.30)
Shares in issue: 11.0m
Market cap: £154m
“Full year results are ahead of expectations”
Churchill China supplies crockery to the hospitality market. It’s one of the leading players in this sector in the UK. Based on my random tableware inspections, Churchill’s client list includes J D Wetherspoon (LON:JDW) and many smaller cafes.
The company says that it saw a strong recovery in sales during the second half of 2021, as hospitality returned to normal. As a result, today’s full-year results are ahead of expectations. Let’s take a look.
Financial highlights: Churchill has always had a strong balance sheet and – in normal times – attractive double-digit profit margins.
Today’s results cover the 12 months to 31 December 2021 and suggest to me that we’re seeing a return to form.
- Revenue: £60.8m (2020: £36.4m, 2019: £67.5m)
- Operating profit: £6.1m (2020: £0.9m, 2019: £11.2m)
- Operating margin: 10.1% (2019: 16.5%)
- Adjusted earnings per share: 37.8p (2020: 6.5p, 2019: 81.7p)
- Total dividend: 24p (2020: nil, 2018: 20.3p)
- Net cash and deposits: £19m (2020: £14.0m, 2019: £15.6m)
- Cash generated from operations: £10.6m (2020: £1.8m, 2019: £11.3m)
Trading report: Churchill says that group sales during the second half of 2022 were 4% ahead of 2019 levels. Sales to the hospitality sector during the period were 7% ahead of 2019.
The company reports further market share gains and strong demand from customers. Although rising input costs are a potential concern, Churchill says that to date, these have been “offset by sustainable sales price increases”.
The company flags up its continued investment in UK manufacturing, a reminder that this Stoke-on-Trent business has a history stretching back more than 200 years. The Roper family, who took control in 1922, continue to control more than 20% of the stock:

Profitability: Given that 2021 was a year of two contrasting halves, I’m very encouraged by today’s numbers. An adjusted operating profit margin of 10% for the year seems very credible, when compared to the company’s historic performance.

Management expects a stronger margin performance in 2022 – broker forecasts ahead of today suggested that Churchill’s operating margin could return to 12% this year.
Free cash flow: My sums show free cash flow of £5.8m, giving a free cash flow yield of around 4%.
This compares to an after-tax profit of £4.2m for 2021, showing excellent cash conversion.
This level of free cash flow covers the dividend twice, making the payout very safe indeed.
Balance sheet: Churchill’s balance sheet is extremely strong, with net cash and equivalents of £19m, no debt and minimal lease liabilities.
I’d imagine that property and other fixed assets valued at £21m would also provide ample collateral, if the group ever needed to raise short-term funding.
We’re starting to see pension deficits fall as a result of rising interest rates. This is the case here. Churchill’s pension deficit fell from £10.4m to £7.2m last year. Although the company contributed £1.4m during that period, the majority of this reduction came from an increase in the discount rate used to value the scheme’s assets.
If this trend continues, I think that we could see pension deficits fall sharply across the market over the next couple of years, potentially leading to reduced employer contributions.
Outlook: Churchill says that productivity and margins are still being affected by “a less than predictable business environment”.
However, the company says that it’s benefiting from growing revenue and “record levels of demand”. So far at least, Churchill says its order volumes have not been affected by concerns that inflation could cause a fall in discretionary spending [on eating out].
Despite various Covid and geopolitical risks, management remain confident they can deliver an improved performance in 2022.
My view: There’s not much doubt in my mind that this is a good quality business.
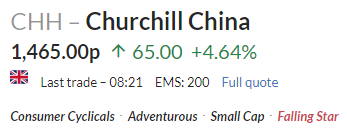
The question is whether the good news is already reflected in the share price. Ahead of today’s numbers, Stockopedia was flagging Churchill as a potential falling star.
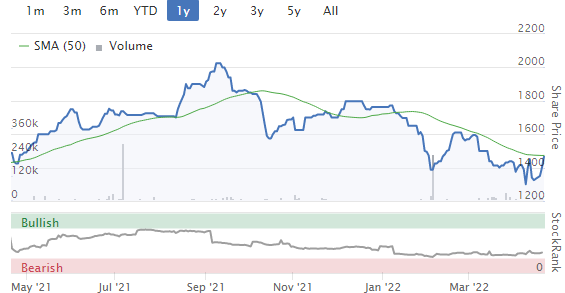
The shares have fallen by 25% since we last covered the stock in the SCVR on 1 September last year.
Today’s numbers value the stock at 38 times earnings. Consensus forecasts for 2022 suggest this P/E ratio could fall to 23 times for the current year, with a prospective dividend yield of 2%.
These numbers don’t look cheap, but if we strip out Churchill’s net cash balance, the forward P/E falls to 20x for 2022. That doesn’t seem too unreasonable to me.
I’d like to pay a little less if I bought this stock. But in truth, I suspect that Churchill is probably fairly valued as a long-term investment at current levels. It’s a stock I’d be happy to own and tuck away for the next decade.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
I notice that Blackrock has increased its stakes (although not by much) in Marks and Spencer(MKS), Royal Mail(RMG) and ITV (ITV). I hold all of these and the share prices of all have been punished over recent months. Should I look upon this as a vote in confidence in those businesses or should I put my cynical accountants hat on and a treat it as a self serving attempt to raise the share prices and therefore the values of their stakes by Blackrock ? Many thanks for any opinions.
On Colefax (LON:CFX) I hear that Boris and Carrie may soon have to relocate, so next year could be another bumper year for luxury wallpaper.
FT has an article today with interesting views from both AJ Bell and Interactive Investors. They believe that investors are adding less funds to their investment accounts than before, due to rising household costs.
Share investments definitely fall in the discretionary spending camp. Food for thought.
UK households investing less as cost of living rises, warns AJ Bell - https://on.ft.com/37xFAuY via @FT
Gear4music Holdings (LON:G4M) (no position)
I was expecting today's update to be full of doom and gloom, but I actually come away tempted to have a nibble.
That has totally surprised me.
I appreciate that it's versus a weak comp (Jan-March 2021 was of course not a good time to be exporting to Europe) but I wonder if this is a glimmer of hope for those continental sales?
These have been operational for years.
- capitalised development spend;
- PPE;
- interest/lease spend;
there isn't actually any cash generation.
This isn't a problem for me where there's growth, but this is of course lacking right now.
Having said all that the market cap is only £55m and there doesn't seem to be much risk of insolvency.
If the company were able to grow just a tad, whilst pulling some levers to control costs, it's looking mighty tempting as a value purchase.
A
Gear4music Holdings (LON:G4M)
These have been operational for years.
What excuses ? struggling to find any in todays update
They did say the following previously (last november) that doesnt seem anything out of the ordinary to me - the rules were completely different pre brexit in that there would have been less need to hold stuff specifically in europe rather than the uk - seems natural to me it would take time to bed down how where and when stuff is stored - presumably tyhey need to store more in europe now than previously which presumably requires more space staff blah blah
As our new hubs in Ireland and Spain scale-up to build upon our existing
European infrastructure, we are confident that the remaining Brexit related
challenges will be resolved by FY22 Q4 and our European customer proposition
will be significantly strengthened.
Gear4music Holdings (LON:G4M)
Hi rmillaree
There was definitely a comment today on European operations still coming up to speed, which I find remarkable given that the rules changed over 12 months ago and everyone knew they were coming.
Here's an extract from 2019:
"Our strategy of establishing a physical footprint in Europe continues to benefit the Group and provides a solid platform for growth in the future.
As our European business continues to grow, we are expecting to fulfil a higher proportion of orders from our European distribution centres located in Sweden and Germany, which have significant spare capacity."
The text formatting is mine.
Note that European sales are only 10% higher than that they were 2 years ago so I'm not sure what the company meant when they said "significant spare capacity."
The European hubs should be up and running by now without any problems given the tepid sales growth.
A
Re Gear4music Holdings (LON:G4M) and European warehouses, I think the points are that
i) Since 2019, we have had both Brexit regulations, Covid and related disruption to shipping containers, and now Ukraine - I am willing to cut some slack!
ii) The new hubs in Ireland and, more significantly, the one in Spain also mean much more of Europe is now covered in cheaper and overnight delivery. If/as those businesses build, costs should be falling and customers better served
The key issue is demand. Can they grow demand to fill those warehouses? My belief is that they can since I remain of the view that online has much further to go and that Europe is behind. Clearly they have lost some growth momentum (so there is 'spare capacity') but I am a LT buy-and-hold person and think at some point in the next 2-3 years we will see another upcycle. I hold and will be on the other side of the small traders currently selling.
Decent uplift in travel stocks today (united airlines update yesterday). I see this continuing, as even financial bad news seems overturned by the 'return to normal'.
Hi Paul & Roland, Hope you're both well!
If either of you have time, is it possible to circle back to Mj Hudson (LON:MJH) interim results from the 12th April as I don't believe they were covered?
I think it ticks a lot of boxes- growth markets (inc being an ESG play), increasing margins, long term sticky recurring revenue, broad customer base inc some blue chip clients with decent cross selling opportunities, potential expansion to US, high % of equity in m'ment hands (around 40%- they didn't sell down in the IPO)
I think the question is whether its now close to reaching an inflection point? The share price had almost halved prior to these interims on earnings upgrades and PDMR purchases (albeit small compared to overall holdings). I'm wondering if this is the start of an upturn in fortunes as acquisitions start to bear fruit and a slight change in business mix (towards faster growing, higher margin data&analytics) takes hold. Financials appear a little messy and contain various adjustments- struggling with the adjustment primarily related to deferred consideration fair value loss :) but potentially not far away from producing a clean set of figures?
Would appreciate your thoughts
Wolfy
Re Mj Hudson (LON:MJH) I'm always intrigued by companies at inflection points.
But with Jun 2022E forecast revenue being similar to that achieved in Jun 2021 (£39m Vs £40m), I see that the forecast net profit improves by a huge £9m (from a loss of £5m to a profit of £4m).
Has the company made convincing operational improvements to achieve this swing?
Hi Epsilon, there's a distinction here between statutory revenue and net revenue. Net revenue being a non GAAP measure defined as "gross revenue less direct costs of sales". Didn't I say I needed help with the figures! Net revenue is forecast to increase from 25.5m (FY21A) to 39m (FY22E) per NOMAD (cenkos) and within this there is a more favourable business mix to higher margin, higher growth areas. However, like I said, we're still looking at adjusted figures so the net profit you quote will be different from the actual bottom line
Pg 160 of the annual report and accounts 2021 defines and shows the growth over the years
Re all the interesting discussion on Gross Margin, would it be helpful if on Stockopedia's pages (the ones for overview of individual shares) they included Gross Margin as well as Operating Margin?
Gear4music Holdings (LON:G4M) fall looks overdone. The recently acquired AV business should prove a good purchase- that sector of business activity is still strong.
Potentially interesting opportunity at £ESYS (Essensys plc). After a recent slowdown in growth due to Covid hit the share price hard, they are now valued at c£54m with c£30m cash in the bank. So the EV is c£24m with run-rate recurring revenues of c£20m and their market place (owners of flexible working offices) are starting to expand/invest again. It's a niche business, but they are (apparently) one of the best, and investing in global growth. Worth noting that they are currently loss-making and have a history of marginal profitability, but £20m+ of recurring revenue should be worth more than a c£24m EV, potentially to a competitor if not to public market investors. They are presenting tomorrow morning on IMC.
Essensys (LON:ESYS) (no position)
Hi Acorninvestor
I was a holder here until last year when I lost faith and sold out.
I've just been through today's interims and must admit to being confused by the +36% (!) move.
You make a good point on the £20m recurring revenues (ARR) and this should make the company worth much more. If they can grow this metric faster I'll be much more interested to buy back in.
For context ARR in FY19 was £16.3m and the gross margin was 70%; today it is 65%.
A few more observations:
It was 5.9:1 when covid kicked off and has been falling since.
That seems quite low.
The pipeline is 523 connect sites...so the max potential revenue is £24.7m?
Forecast revenue for this year is £23.7m.
That's an estimate of course but still seems low.
I'm still intrigued so will be listening to the presentation tomorrow morning. If growth can take off again I'd be more inclined to buy back in.
A
I have been watching Gear4music Holdings (LON:G4M) from the side lines for a few years, and the current SP is absolutely no surprise to me (sorry Paul) True we saw rapid growth through Covid as would be musicians sitting at home with nothing to do decided that now was the time to learn an instrument and internet sales took off. So where are those instruments now? Guitars are under beds or in lofts and digital keyboards gather dust or are on the pages of eBay. Musical instruments are largely a one-off purchase and learning to play one even moderately is a real challenge requiring lots of persistence and patience. Even bands play with old beaten up amps - certainly many years ago mine did. My shining Steinway thrills me every day I play, but I am not about to buy another and my 5 guitars have not been played in years. Music is sadly not taught in schools either and is largely played by middle class kids. This is rightly now termed a niche market where incidentally shops still have a role too. So, my point is that companies can do all the right things - the fundamentals rightly referred to here, but sometimes the actual market sector won't support the volumes required for growth. I believe Gear4music Holdings (LON:G4M) is a case in point. Tra La.
All this may be true Chriskay but you're a little late with your analysis . The time to factor this in was when the share price was 800p+ and the chart uptrend was broken/then large insider sale at £7.30
Very good point Gringo but have you tried posting a neg comment on the darling share of the day when everyone believes the story. I only posted today as Gear4music Holdings (LON:G4M) seems not to have died as a recovery play, so I thought I would share my experiences of the music sales business - now where was I with that sonata.
Hi Chriskay,
Not sure why you included this bit -
"I have been watching Gear4music Holdings (LON:G4M) from the side lines for a few years, and the current SP is absolutely no surprise to me (sorry Paul)"
No apology necessary.
My view on 20 Jan 2022 couldn't have been clearer here -
I should add (for full disclosure) that I’ve down-sized my G4M position from medium to small. That was partly due to another large founder CEO share sale, and also worries about the cost of online marketing, and supply chain. It’s a good company though, so I’ll be looking to increase my position size potentially in future, depending on newsflow. I can’t afford any more profit warnings, hence down-sized a few things late last year, also pushed by margin calls on my geared account, as mentioned previously.
So there were obvious worries as you say.
Where do we go from here? I reckon G4M has recovered well from previous setbacks, so it's a decent company. With a bit of patience, it might do well, again, as it has before after short-term disappointments.
Hence I like the company, and management.
Say anything you like about it. The whole idea of these reports is that we welcome all views. Bearish views could maybe do a bit better than the "oh it's rubbish, now it's dropped 75%, as I'm a complete genius and you're all fools" type of style? Boring & unpleasant! (memo to self there, sometimes, so let's all lighten up a bit!)
P.
Crikey Chriskay, I'm not sure I agree with much of your explanation for the fall in £G4M share price.
Firstly, you talk about musical instruments being a one-off purchase but then completely contradict it with your own experience of owning 5 guitars. It's well known that people who persist with learning and playing guitar go on to accumulate multiple instruments. I own several guitars myself and I'm far from done!
You then go on to say, “Music is sadly not taught in schools either....” Really? After centuries of teaching music to children are we now to believe that it's all over? I've heard this argument a lot, the one which says, now that everyone's bought a musical instrument and packed it in, who's going to buy the next lot? Well, the answer is, the next age group, the new kids who are introduced to music either by their school or parents. There's a new group every year and there always will be, as long as music lasts.
I think the other thing to be aware of is the explosion in free or low cost teaching online over the last few years. This is especially so for guitar and there are countless, and in many cases, first class teaching resources for anyone who wants to look for them. I read somewhere that the number of girls now learning and playing guitar has risen sharply recently.
I think medium to long term, a company like Gear4music Holdings (LON:G4M) are well placed to particularly serve the beginner end of the market. I certainly wouldn't judge the company based on the share price movements. Anyone looking at the share price graph over the last 5 years would imagine it was a company lurching from one crisis to another, rather than a company which has consistently built market share and effectively managing the operational side of the business.
Thanks for the comments Gnome2 Yes people who 'persist' with learning but probably not many who unpacked a lovely shiny guitar from Gear4music Holdings (LON:G4M) SP during the pandemic. I do own 5 guitars accumulated over decades as I was professionally playing then - all gathering dust - wont be buying any more.
As far as music not being taught in schools is concerned there is plenty of evidence for that - it fell from the curriculum years ago. Here in the West Country a well established concert organiser recently offered free tickets to all the local schools. From memory I think just one replied.
I only wish your description of young eager musicians was accurate but outside London and private schools it sadly isn't. Concerts with world class classical players in the West Country in large venues seldom get more than a handful attending under 60 - no future generations coming up here. It is actually quite depressing.
Sorry if my answer is a bit of a diversion but if ever there was a time to buy a musical instrument it was during the pandemic, same with gym equipment, delivery companies could not pack them quickly enough. I really think that time has passed and the market has significantly contracted but it's only my view.
Perhaps if everyone on here would pick up an instrument and start learning the market might explode and they would get a lot of enjoyment too. Now I wonder what Paul would play? Hm got to be the drums?
Any chance for a look at Solid State. It's Trading Update seems to be remarkably good.
Hi nettle,
Sorry we didn't get round to Solid State (LON:SOLI) today, there were so many company announcements today - we reported on the usual 5 companies, but there were 8 more companies that I wanted to cover, but ran out of time & energy by lunchtime.
I note that SOLI rose 13% today, we usually try to focus on the big risers/fallers, but were overwhelmed with the quantity today.
Apologies, Paul.
Done tomorrow! Check out Friday's SCVR
Re: Gear4music Holdings (LON:G4M)
The reality is, it is a very poor quality business. It's a distributor basically isn't it? Any company crowing about gross margins of 29% is having a laugh, frankly. That's way below average for the specialty retail sector and is about the same as other poor quality companies like Shoe Zone. I have no idea why so many words get wasted on this company on this blog.
"It's a distributor basically isn't it?"
Nope wrong (or at least half wrong)
"It's a distributor basically isn't it?"
Nope wrong (or at least half wrong)
But the rest of what I said is correct. It's a rubbish company with poor gross margins for a retailer which puts it nearer to being a distributor like a building merchant (Travis Perkins) than a retailer with a defensible brand position like Next or Burberry, or even for that matter Pets At Home and Dunelm; all of whom are far better companies IMO with gross margins north of 40% which is more like it.
Why bother with a company which celebrates 29% gross margins and has little pricing power and fixed overheads, and that has generated nothing much in the way of free cashflow in its entire history? It's a simply dreadful proposition.
simoan,
The point you're missing about the low margins at G4M are these -
1. The average transaction value is high, at about £130. Therefore, the cash margin (ex VAT) is quite good, at £31 per transaction.
2. Low returns rate, as it doesn't have to fit, like clothing, so a lower margin works.
3. G4M covers all its marketing costs on the first transaction only, so doesn't need to rely on repeat business.
4. With low margins, there's little incentive for new entrants to come along and undercut.
5. G4M has volume relationships with the branded prospects, especially guitars. So it can be worth trading off some margin for volume.
As an aside, I'm finding the strident tone of some comments rather boring, and reserve the right to not bother replying in future. It's meant to be a pleasure discussing shares & the markets.
P.
Gear4music Holdings (LON:G4M)
The fact it won't be for you doesn't mean that others will be equally picky - the company does have a reasonable niche and does have its "own brands" which to me separates it somewhat from your "no barrier to entry" average distributor that generally sells others products only. I won't disagree ref quality metrics here - they don't look great and performance has been patchy , but in 2021 they delivered £9 mill net profit which to me is a "proper" business whatever the margins may be - particularly as they would have had the normal issues that growth companies tend to encounter. Its not all about the bottom line number when you are investing for growth. I am sat on the fence here as i don't curently own but i can see route back to 1000p shareprice - must admit it does not strike me as a high conviction play at present.
The point you're missing about the low margins at G4M are these -
1. The average transaction value is high, at about £130. Therefore, the cash margin (ex VAT) is quite good, at £31 per transaction.
2. Low returns rate, as it doesn't have to fit, like clothing, so a lower margin works.
3. G4M covers all its marketing costs on the first transaction only, so doesn't need to rely on repeat business.
4. With low margins, there's little incentive for new entrants to come along and undercut.
5. G4M has volume relationships with the branded prospects, especially guitars. So it can be worth trading off some margin for volume.
These points are all very well and good but sometimes the devil is not in the detail. Sometimes, in fact quite often, it pays just to take a step back and look at a company in the round, and ask yourself whether it is in fact just another Boondoggle Enterprise.
At a very simplistic black box level, a company is a machine that takes in debt and equity to create revenue from which it generates free cashflow for it's equity holders. It can pay out the cash as dividends, reinvest it back into the business at good rates of return, or a combination of both. If very little, or no cash ever comes out, as in the case of Gear4music Holdings (LON:G4M), then you have to ask yourself what the point of the company being listed is other than a jolly wheeze for management and employees. There are so many better quality companies listed on various stock markets that generate healthy cashflows, that I am genuinely puzzled why anyone would invest good money in a company like Gear4music Holdings (LON:G4M) let alone spend so much time writing about it.
As an aside, I'm finding the strident tone of some comments rather boring, and reserve the right to not bother replying in future. It's meant to be a pleasure discussing shares & the markets.
Well, there are plenty of strident posts on a daily basis here, sometimes even from yourself. Do I take it that only positive strident posts are non-boring?
I am genuinely puzzled why anyone would invest good money in a company like Gear4music Holdings (LON:G4M) let alone spend so much time writing about it.
I keep a framed picture of G4M mgt behind my penthouse door in Bournemouth. Because G4M shares paid for it (not the door, before you come back to me about that).
Can we have the nicer version of Simoan back please?!
Paul and Simoan - As with any investment it depends on when you buy and your view on the time you hold. So in a way both your comments may be entirely justified
Paul and Simoan - As with any investment it depends on when you buy and your view on the time you hold. So in a way both your comments may be entirely justified
The point is that by avoiding poor quality companies like Gear4music Holdings (LON:G4M) we improve our chances of success over the longer term. Yes, it's possible to buy and sell shares in any company to make a profit if you get your timing right, but doing that consistently over the longer term is not possible for the vast majority of investors.
All the best, Si
I keep a framed picture of G4M mgt behind my penthouse door in Bournemouth. Because G4M shares paid for it (not the door, before you come back to me about that).
Can we have the nicer version of Simoan back please?!
I'm sorry you feel I'm not being nice. Surely I'm allowed to make perfectly valid negative points about a company in this comments section? And this is not the first time I've made the point about this company either, so it's unfair to describe my comments as:
Bearish views could maybe do a bit better than the "oh it's rubbish, now it's dropped 75%, as I'm a complete genius and you're all fools" type of style? Boring & unpleasant!
In particular, I made a serious and valid point about the quality of Gear4music Holdings (LON:G4M) and the danger with investing in poor companies like it with low gross margins. When we are in an environment of high input cost inflation this really matters. There's a lot of chatter currently on Stockopedia and other forums about how to mitigate against inflation and yet very little discussion on avoiding low quality companies with low gross margins and little pricing power.
You and I can do the math but others may not. All other things being equal, a 10% increase in COGS for a company with a 30% gross margin causes a a 33% fall in gross profit whilst for a company with 80% margins it only results in gross profit decreasing by 12.5 %. The company with 80% margins is also more likely to be able to maintain margins by increasing prices. I know which company I'd rather be holding.
Obviously, I'm very happy about you being able to buy a flat with the gains made from Gear4music Holdings (LON:G4M) but I don't find that kind of direct connection helpful from an investment perspective. It will now forever influence your attitude towards the company. And think of all those readers that have had a quite different experience of investing in this company and were not so fortunate with their timing.
I'm trying to be nice, but we all know that it is possible to get a good outcome from investing in poor companies by buying and selling at the right time, however that doesn't make the company a worthwhile longer term investment. Just look at the long term chart for Gear4music Holdings (LON:G4M) - it looks like the humps of a Bactrian camel!! So long term holders have had a rotten time and have not seen a single penny in dividends due to the non-existent free cashflow.
All the best, Si
Agreed Simoan, Gear4music Holdings (LON:G4M) is a low quality box shifter.
I find looking at gross margins is a useful first step in assessing the quality of a business. (*)
A lot of positive comment on this blog is awarded to Volex (LON:VLX) , the so called ' global leader in integrated manufacturing for performance-critical applications'. Yet with a gross margin of just 22%, the reality is more of a low value added manufacturer.
The current management have done well in improving operating margins which led to some large profit growth which investors appear to be anchored to, but a comparison with peers Nexans or Prysmian suggests margin-wise, this is as good as it gets.
(*) not useful for some service companies such as recruitment agencies or vehicle retailers.
Newriver Reit (LON:NRR) looks like it may have finally turned a corner. Liberum have nudged up NAV per share estimate to 134p. Roland - disposals have all been carried out roughly in line with book value so this should be NAV neutral (while reducing LTV). I think your 120-125p estimate looks to low.
yes, I too find Roland’s projection of a fall in NAV/share a bit odd. The NAV should have increased slightly given the 2.5% rise in property values from September and fresh disposals at book value. So, NAV per share should rise from the September level prior to any dividend to be announced.
Re Gear4music Holdings (LON:G4M) - What a roller coaster of a share price!
My take is that the underlying business has been growing at a moderating rate, now at around 10% as it benefits from being a leading and dedicated online player in a niche. This structural tailwind remains but is being moderated as even independent shops get online strategies. Has Brexit screwed up some Euro sales short term - yes; but by exporting jobs and taking on extra costs it now has a plan in place to resume growth. Over time some of those costs will go or their effect be moderated.
Europe remains behind the UK in online selling so it has some degree of early mover advantage and the warehouse logistics are now there. We know retail is local but guitars and amps are pretty universal so own label product and brand relationships should travel.
The key variable to me is AV.com. Any kind of success here would really add reveenue and value and I think they have a good chance, although they are starting to compete with bigger places and with less moat.
Looking out on a 2-3 yr horizon I think this should be a bigger and more profitable business and I am willing to park some cash and wait. I made money on the up well, sold, bought back in and am now underwater on my new holding but willing to average down. This is a literally blood on the street moment and good companies will be back.
Attraqt (LON:ATQT) published full year 2021 results 7.4.22. Here is the analysts' presentation including a demo of the software which aids search, upselling & actual transaction. Video & podcast. They are looking to build in mid market beyond their larger Enterprise clients. They work with some big well known high street brands, which frustratingly can't be named. For FY21, revenue grew 9%, the gross margin is 71%. Adj EBITDA £0.7m. Cash at the year end was £3.5m, they aim to be cash neutral in 2022. They have a strong sales & pipeline in Q1, total new bookings £1.5m and £500k ARR signed in the quarter and a pipeline of Enterprise opportunities of 6x gross coverage of the Q2 target.
Bad update from Gear4music (LON:G4M) this morning. In the last update it looked as if "New European distribution centres are scaling up well to address post-Brexit challenges" might cause a corner to be turned but no mention of them this time.
Progressive has issued a note available here:
The halving of the current year eps forecast was enough for me to exit my holding today at a nasty loss. With the benefit of hindsight I should have sold when the CEO ditched 1,650,000 shares @ 730p - almost 3 times this morning's price.
"Mr Wass has advised the Company that his sale of ordinary shares in the Company is to satisfy existing market demand". B*ll*cks.
Edit - written before I had seen Paul's report, for which thanks.
Thanks sharw, what's interesting from the table you took from Progressive's note, is how the % falls get steadily worse as you move down from revenue, through EBITDA, to EPS. This is one of the reasons I dislike EBITDA, because it disguises the real fall in profitability. There are some uses for EBITDA, but it's risky to use as a main valuation measure, in my opinion, particularly when profits are falling.
I initially thought that G4M looked a mild profit warning. But then got a jolt when I saw brokers were halving EPS forecasts for the new financial year FY 3/2023.
This often happens actually, with lots of companies. I read the RNS, and think oh that's not too bad, then can't understand why the share price has crashed say 30-50%. Of course, it ends up being because brokers have often slipped out notes to their clients, slashing forecasts, before the rest of us get to see anything.
Hence why I always thank the brokers which do publish updates on Research Tree, as they're helping to give us a more level playing field in a timely manner.
Regards, Paul.
Gear4music Holdings (LON:G4M)
Cheers for that sharw exactly the kind of info us pi's need - some nailed to the mast numbers and straight talking from the company. It's not great that the news here is bad (unless you are on the sidelines waiting to add on bad news) - but well done to the company and Progressive for hastily providing us the exact info i want to look at - hopefully these numbers speak for themselves with regard to where the shareprice is now - massive downgrade today practicably speaking. Note we look at things in % terms its clear that small differences here affect the bottom line unduily so everyone should be expecting this to be a share with wild swings in price - if you buy in here be reasy for that. To me their short term objectives are clear deliver operationally to ensure things "don't get out of control" - i would say its reasonable to presume that they have possibly/probably not done much wrong operationally and are just finding thigs tough for the obvious reasons.
Hi millaree,
As an aside, I tend not to copy anything from broker notes into the reports here, because I think that would possibly be breaching copyright. Hence why I always just mention a few key numbers from broker forecasts within my text.
In this case, when sharw copied in a table of forecasts from a broker note, it should be OK because it's from a commissioned research company, Progressive.
I should probably ask some brokers if they would let me copy in tables into the SCVRs, as then I would at least find out if it's possible or not.
Regards, Paul.
Paul
"As an aside, I tend not to copy anything from broker notes into the reports here, because I think that would possibly be breaching copyright."
Thanks for that - i fully understand the tightrope that needs to walked ref copyrighted material (thankfully advfn is like the wild west) - to me although its highly frustrating that what the company refers to often as in the "public domain" is in reality a closed shop - i take what i can get in that regard with thanks - generally rather strangely i am more interested in furthest dated info into the future i can get , i am aware that forecasts for year after this/year soon to start may not be worth the paper they are written on - but if they are written and exist i want to see them. Particualrly if company sees worsening of numbers more than 12 months into the future - that clearly seems to be the case for G4M at present although hopefully its just setting low bar to beat for holders - i do get the impression with this company they tell it how they see it which is reassuring - just give us summit and change it as time goes on as appropriate thats all I ask.
Regarding copying a table from Progressive's report to here I considered that acceptable as it is openly available unlike other brokers who require you to declare yourself to be HNW or a professional investor and whose reports come with your email diagonally across and "Prepared solely for yourname. Not to be distributed anywhere. Strictly for personal use" at the bottom of each page.
I was careful to provide a link to the report. This requires a login so if you haven't used Progressive before you will be added to their database (the larger the better when pitching to prospective clients!). That will mean that in future you receive the report by email as I did at 07 15 this morning allowing me to make a decision before the market opened - I sold at O8:00:59.
Vertu motors is not in favour with Mr Market at the moment and looks a good buying opportunity .
Looks overdone to me .
Gear4music Holdings (LON:G4M) issued a Year End TU today. Paul I know that you hold although you had downsized your holding as at January 22. Any chance you can cover this today please as market have not reacted well. SP currently 26% down. Seems an overreaction to me as results looking favourable compared with 2019.
Hi Bristolian,
That's right, I explained in the SCVR of 20 Jan 2022 why I'd downsized my Gear4music Holdings (LON:G4M) position from medium to small, saying -
Gear4music Holdings (LON:G4M) (I hold)
690p (per market open) - mkt cap £145m
I should add (for full disclosure) that I’ve down-sized my G4M position from medium to small. That was partly due to another large founder CEO share sale, and also worries about the cost of online marketing, and supply chain. It’s a good company though, so I’ll be looking to increase my position size potentially in future, depending on newsflow. I can’t afford any more profit warnings, hence down-sized a few things late last year, also pushed by margin calls on my geared account, as mentioned previously.
Of course, I didn't know it was going to warn on profits today, and lower the outlook considerably.
Having said all that, markets do seem incredibly short-termist at the moment, I think because it seems full of traders, who move the prices up & down a lot, often on quite small volume.
We're not just buying this year's earnings. We're buying all earnings for perpetuity. That's why I'm trying to keep focused on businesses which should be much larger & more profitable in say 3-5 years' time, and am ignoring the short term volatility on my core positions.
There's a good chance G4M could resume growth, and then have another big spurt up, as has happened twice in the past, which has been very lucrative for many shareholders who had the good sense to sell when the price got a bit toppy. Easy to say with hindsight though isn't it!
I'm not at all convinced that the coffee can approach is a good idea right now! So contradictory thoughts are swirling through my brain, and I haven't really decided what is the best approach. Maybe a hybrid approach? Having some locked in long term stuff, and also some additional trading shares in the same companies?
Regards, Paul.
Gear4music Holdings (LON:G4M) today's fall is a classic example of how market punishes companies twice - first on the expectation of a slowdown, and again when this is confirmed. Lesson here - avoid anything where a bad trading update seems likely, irrespective of whether this may have already been priced in.
Hi Bouden54,
Gear4music Holdings (LON:G4M) today's fall is a classic example of how market punishes companies twice - first on the expectation of a slowdown, and again when this is confirmed. Lesson here - avoid anything where a bad trading update seems likely, irrespective of whether this may have already been priced in.
Absolutely, I agree, and made the same point in today's section on G4M before I had read your comment! So not plagiarism, I promise!
The interesting point will come when profit warnings barely move prices, or they rebound quickly, as that could be an indicator that anyone likely to sell has gone. Hence leaving the upside clear for a recovery. It doesn't feel like we're there yet, does it? Getting close though, I reckon, for some shares anyway.
Regards, Paul.
Broker update from Singer wont help Gear4music Holdings (LON:G4M) Progressive slashed EPS by even more.
"We have downgraded EBITDA by £3.2m in Mar’23 and £3.9m in Mar’24, driving EPS downgrades of 48% and 45% respectively. On a pre-IFRS16 basis, we now forecast EBITDA margins of 6.2% and 6.6% in Mar’23 and Mar’24, with EPS -3% then +24% YoY. Our ND forecasts are £12.8m and £9.8m"
Could be a decent long term buy at 280p but I'll wait to see if 200-220p comes. Too much uncertainty and risk at current price for me. As others have said, the big director sell 4 months ago was the signal to jump ship here.
Gear4music Holdings (LON:G4M)
today's fall is a classic example of how market punishes companies twice - first on the expectation of a slowdown, and again when this is confirmed. Lesson here - avoid anything where a bad trading update seems likely, irrespective of whether this may have already been priced in.
I simply don't agree - if the market has worries then i would expect that may cause an element of expectations that there could be a profit warning - however in the absence of specific warning surely market is saying - we have 25%-50% or 75% chance of warning -only there must be a % chance there will be no profit warning and when it arrives we should alwasy fully expect further declien IMHO.
The company has confirmed today that they have missed targets that were in place yesterday practicably speaking so we should always expect dip downwards - as they are only now 21 days later advising they missed revenue and ebitda targets we should expect reaction to be brutal - the marekt doesnt like tardy after the fact stuff like that - note perosanlly i understand it can take 21 days to work out ebitda numbers so i have no criticism in that regard.
In summary profit warning is real and late although very minor in nature.
Are you not also missing the elephant in the room here perhaps ? - in that they appear to now be downgrading expectations for year just starting too - thats bound to cause drop in itself when announced - as the expectations yesterday would have already been factoring in "current tough market conditions" to a certian degree. Again probably slight tardy downgrading now when the reality of where we are has been clear for some time now - hey ho small buisness so i am not being over critical in this regard - news seems fairly styraight talking and thats enough for me.
"Short term inflation-linked overhead cost pressures and weaker consumer confidence across the broader retail landscape will mean the best opportunities for stronger growth during FY23 are likely to be in H2. We are, accordingly, moderating our overall growth expectations for the new financial year, which we believe is the prudent approach in the current environment. "
One final issue with retailers is that i have heard it said that the proper money has inside track of how companies are trading before the "bad news is announced" - so now for companies like this i would be super wary about adding with drifting price prior to update - if i would be loooking to buy here now is the time for me to take a look as we are reasonably up with events so will be interested to see if this one does come back into bargain basemant territory - problem is there are plenty of similar companies struggling at present - not convinmced we are anywhere near the bottom here but i do quite like the fact this company seem to have their "niche"
Yes having looked at this in more detail I think you're right - the update was even worse than expected so big fall today probably justified.
Hi
Has anyone any insights into why Serica Energy (LON:SQZ) fell over -7% on the open.
Its results to 31 Dec seemed strong to me. What have I missed?
Here is a copy of a news flash on it
April 21 - Serica Energy PLC SQZ.L :
* FY PRETAX PROFIT 135.1 MILLION STG VERSUS 12.5 MILLION STG YEAR AGO
* FY OPERATING PROFIT 246.1 MILLION STG VERSUS -18.7 MILLION STG LOSS YEAR AGO
* FY PROFIT AFTER TAX 79.3 MILLION STG VERSUS 7.8 MILLION STG YEAR AGO
* PRODUCTION GUIDANCE RANGE FOR 2022 NARROWED AND SLIGHTLY REDUCED FROM 27,100-33,600 BOE/D TO 26,000 BOE/D-30,000 BOE/D
Full RNS is here ....
https://www.investegate.co.uk/...
Regards
Howard
Serica Energy (LON:SQZ) , I suspect the price reaction today is a a result of the downward revision in the production guidance for 2022 which you highlight above and possibly a lower dividend than may have been expected.
Interestingly Stockopedia had forecast earnings per share of around 100pps but it has come in at 30pps, so I'm not sure what was going on with broker forecasts...
Hi OldSchool05
Thanks for the response. Thinking about I suspect after the strong price rise from around 21st Feb for £SQZ profit takers are at play as well.
I hope the low PE and it now making profits might attract new buyers.
Regards
Howard
Hi Howard. Ref Serica Energy (LON:SQZ) one of the brokers recently updated its price target to £6.
I suspect that OldSchool & yourself have probably nailed the reasons; lower than anticipated divi, lower prod f.casts for next year, profit takers etc. For myself I am still comfortable with my holding (Top-3 in my PF although I have top-sliced some over the last couple of months) and will continue to hold whilst gas prices remain high and Serica Energy (LON:SQZ) continue to deliver solid results.
I suspect that once things settle down we should see a continued strengthening of the SP and hopefully further good news later in the year on ongoing investments by £SQZ
Serica Energy (LON:SQZ)
These are the numbers that significantly affect SQZ ’s EPS.
The big number is a noncash revision of £110.6 million recorded as a charge in the Income Statement. SQZ takes a provision for future decommissioning costs. Decommissioning costs are shared in a complicated way with the previous owners of the assets. SQZ’s contribution to these costs is related to the cash flow from the assets over their lifetime, etc., etc. I am not in a position to estimate these or to know if future revisions of provisions of this size may recur. Management has this to say on the topic:
Given the multiple input variables and judgements used in the calculations, and the inter relationships between changes in these variables, an estimate of a reasonable range of possible outcomes of undiscounted value of the contingent consideration (mainly or entirely decommissioning liability) has not been considered feasible.
From FY21 published today-the notes are not included in the RNS, so please see note 22, pg. 98-102 here: https://www.serica-energy.com/downloads/reports/Serica-Energy-plc-2021-accounts.pdf
c. £81 million, mostly in profit share costs, will not recur in FY22.
As others have mentioned, hedging is a material cost.
-and, of course, the future price of gas could be anything.
Disclosure: I own fewer of these than I owned in 2016. I bought a few more this morning.
Hi Laurie
Many thanks for your insights into Serica Energy (LON:SQZ) that is a useful comment.
Also, many thanks to all the others who have offered comments so far.
I hold a small amount but might add a bit if price stabilises.
Regards
Howard
Production guidance reduced 10% - that explain most of the SP drop - probably more divi, return to shareholders was also expected.
Re Serica Energy (LON:SQZ) I suspect that some people were spooked by the PBT coming in at £135mm versus the £300mm shown on the Stocko estimate, but this was heavily impacted by the hedging provisions. However if these hedging provisions become payable in full because the price of gas remains at this level going forward there will be a much larger increase in revenue as less than 20% of production is hedged. The other positive is the big increase in the economic benefit of production from the BKR fields this year as the 40% of value realised from them payable to BP, Total and BHP in 2021 will all accrue to SQZ from 1 Jan 2022. I hold.
Solid State (LON:SOLI) ( I hold ). They make rugged IT gear for challenging environments and have been performing consistently well in recent years. They tick most of my boxes for a high quality company and have submitted a reassuring update today .
re Solid State (LON:SOLI), I thought the update was rather better than reassuring. The valuation was looking rich last year, but is looking attractive now. I hold.
I love the snippets of travel chat. More roving reports please.
Not small cap... but Thg (LON:THG) reported FY results today and a trading update.
In the commentary: "You will all be aware that there has been significant speculation about possible third party interest in THG. I can confirm that the Board has received indicative proposals from numerous parties in recent weeks. The Board has concluded that each and every proposal to date has been unacceptable, failing to reflect the fair value of the Group, and confirms that THG is not currently in receipt of any approaches"
Surely the board has a responsibility to publish details of the offers they have received, and also state on what valuation grounds they rejected (i.e. the board should publish what they think is a fair value and acceptable price per share they would accept an offer?)
(I hold)
Thg (LON:THG)
Surely the board has a responsibility to publish details of the offers they have received, and also state on what valuation grounds they rejected (i.e. the board should publish what they think is a fair value and acceptable price per share they would accept an offer?)
I think the simple answer to your question must be no if the board are not furnishing such information - i have seen talk recently about this area needing reform and that is probably the case that the current system does create unfair market in the shares which is not right.
I take a somehwat middle ground here - to me if there is firm offer materially above current sharepirce (10%?) then yes full details should be out in the open. For sketchy indictive chancing your arm approaches that might be for nefarious reasons - perhap some brief mention perhaps.
I am presuming the board have the normal obligations ref price sensitive info - but i do sort of understand if they are trying to run business and have week unsolicited expression of interest the reality is that may be a million miles away from being proper offer to buy shares at meaningful premium and that situation probably deserves - "lip service".
Thg (LON:THG)
Hi Boon
I'd be interested to hear your thoughts on today's update and whether you plan to continue holding.
I don't hold, nor have I done much research, but after a quick glance at today's results I see that the company's adjusted items amounted to £142m, which is massive in the context of an adjusted EBITDA of £161m.
After the £531m of adjustments in the prior year (or c£200m if one wants to exclude the £331m of share-based payments) I'm not sure it's fair to call these movements one-offs.
I certainly wouldn't be removing additional covid transportation costs from this year's results as a) everyone has had to deal with them, and b) they're still elevated.
Perhaps there's something special here - and yes, I recall us discussing automated warehousing for 3rd parties in the past - but I still don't fully understand why this company gets so much attention.
Cheers
A
I haven't had a chance to go through the results in detailed and planning to this weekend.
My initial investment thesis was:
- good quality ecommerce sites, strong brands in their verticals, high margin (beauty, nutrition)
- Ingenuity has a compelling offering as many companies can't afford or have the skills and appetite to build sophisticated in-house eCommerce operations.
- enough M&A chatter to signify that others, more professional and institutional investors with ££££ than me think its undervalued. And thus a potential profitable exit route in the short term.
But I agree the financials are very weak or bad. The net cash is going to run out soon. And the days of the market being easy on cash burning, low/no profit, high revenue growth companies is over.
Interesting, thank you for that.
Cheers
A
I've never really got the appeal of Hard Rock Cafes. Went once, paid too much for a bad burger. This was probably 30 years ago though, am I missing out on something?
If you were limited to the choices in Malta Airport the Hard Rock Cafe might get a second visit.
If you were limited to the choices in Malta Airport the Hard Rock Cafe might get a second visit.
Exactly! It was the only place where I could work in moderate comfort, with a ledge for my laptop, and a charging point.
Their cooked breakfasts looked OK, but were 12 Euros, whereas I was only paying 6 Euros in Gozo, but you expect that in an airport anywhere!
I had to rattle out the section on Naked Wines (LON:WINE) yesterday at the departure gate, with my laptop wobbling literally on my lap! Still, all good fun.
Also, it always mystifies me why people pay Easyjet extra money to be a "speedy boarder!". I like to be the last person on the plane, as it means fewer minutes getting stressed out as people cram their bags into the overhead lockers, and start having disputes with each other. Also it's a shorter wait for a G+T from the trolley! I managed to knock over my plastic cup of chardonnay right into my lap, early on in the flight. So it was a wet & smelly flight for me & everyone around me.
And the weather was terrible in Malta/Gozo, whilst you were having a heatwave here. Not a surprise though, given how everything else is going this year!
Paul.
This wasn't a judgement on Paul's choice of eatery in particular. More on Hard Rock as a brand.
Card Factory (LON:CARD)
Chompingly good news for card factory in that their financing issues have been sorted without need for specific equity raise “now”. Brilliant result for management here not sure what they were risking doing what they did ? But their cunning plan (bury head in sand and hope covid issues subside) has worked.
The shareprice really has gone into reverse here imho that’s all fine to the previous trading update where they indicated bottom line was facing severe issues - so the funding issues have been replaced with concerns as to whether they will make the level of profits we might have expected.
Note there is still very chunky debt here so there may still be financing issues going forward but things seem semi stable for now.
To me after last trading update I cannot invest for now but sit on the sidelines wandering if the future might not be as bad as the prior downbeat update - fair play to management if they have been open and transparent in that regard - I will only really sceptical if they load up on freebies at low price for trading to bounce back and not be as bad as expected.