Small Cap Value Report (Thu 21 Jan 2021) - CRW, GETB, SCE, IDP, AIR, SOM, SDG, HEAD, BEG, ZTF

Good morning, it’s Paul and Jack here with the SCVR for Thursday.
Timing - update at 13:15 - mostly done for today. The sun has just tentatively appeared, so I'm downing tools now to stretch my legs, as lockdown in foul weather is sending me stir-crazy! Let's say all done for today, but I might cover a few more things this evening, for tomorrow's report.
Paul's Section:
Agenda - I prepared some sections last night:
Craneware (LON:CRW) - trading update FY 12/2020
Getbusy (LON:GETB) - trading update FY 12/2020
Air Partner (LON:AIR) (I hold) - trading update FY 12/2020
On to today's trading updates/results:
Somero Enterprises Inc (LON:SOM) - a sparkling end to FY 2020
Sanderson Design (LON:SDG) (I hold) - Trading update for FY 01/2021 - ahead of expectations
Headlam (LON:HEAD) (I hold) - Strong H2 recovery & resumption of divis
Jack:
Begbies Traynor (LON:BEG) - red flag report
Zotefoams (LON:ZTF) - Operational & trading update
Craneware (LON:CRW)
2240p (up 2.3% yesterday) - mkt cap £601m
20 January 2021 - Craneware (AIM: CRW.L), the market leader in Value Cycle solutions for the US healthcare market, is pleased to provide an update on trading for the six months ended 31 December 2020 (H1 FY21).
“Strong performance”
H1 revenue & adj EBITDA up >5% on LY H1
Customer retention rate above 90%
… building the foundation for a return to double-digit growth in the future.
Long-term visibility of contract revenues
Capitalising R&D at similar levels to prior periods
Cash reserves “healthy”
Good cash conversion
Confident of meeting market expectations for FY 06/2021, with a useful footnote -
1 Company compiled, publicly available market expectations comprises the published estimates of 5 analysts from Peel Hunt, Investec, Berenberg, Panmure Gordon and N+1 Singers. For FY21: Revenue of $74m (range $71.5m to $76m) and Adjusted EBITDA of $25.3m (range $23.7m to $27m)
My opinion - it’s a good quality business, but growth seems a bit pedestrian. Forward PER of 45 suggests investors must see upside against existing forecasts. The share price has done well recently, it looks very expensive now. I’d want much faster growth to justify paying such a high multiple.
.
Getbusy (LON:GETB)
94p (up 13% yesterday) - mkt cap £46m
GetBusy plc ("GetBusy" or the "Group") (AIM: GETB), a leading developer of document management and task management software, is pleased to provide an update on trading for the year ended 31 December 2020.
Strong revenue growth and a robust foundation to scale
I’ve reported on this company quite positively several times in the past, including its last (rather waffly) update here on 28 Sept 2020.
Let me summarise the latest update yesterday -
- Performance has continued to be strong, the company says
- Revenues slightly ahead of market expectations (despite currency headwinds in H2)
- Recurring revenues up 15%
- Customer churn in H2 reduced from H1
- Net cash better than expected, at £2.3m due to early receipt of UK tax credit (plus undrawn £2m borrowing facility) - so liquidity sounds OK
- Diary date - 3 March 2021 for FY 12/2020 results
My opinion - I like this share. It’s got a profitable, cash cow business, called Virtual Cabinet, which is growing, but quite slowly (+6% in 2020). It’s using the cashflow from that, to develop 2 other products. How to value it? Probably on a sum of the parts basis. We’re in a roaring bull market for tech shares, so you could value this share at anything you want. Is the growth exciting enough to get onto a mega-valuation? Probably not, at this stage, in my opinion. Others may disagree.
I need more detail, so will wait until the figures are published in March to look at it more closely, but my view is broadly positive, because it has an established, cash generative division. So there’s a proper business here, plus the more blue sky stuff thrown in as potential future excitement. That’s much lower risk than a heavily loss-making blue sky type of share.
.
Surface Transforms (LON:SCE) - has done a big placing, raising £18.0m (gross) at 50p per share. It’s certainly on a roll. How to value it though? Very tricky.
Innovaderma (LON:IDP) - Many thanks to muzmano for flagging yesterday in the reader comments section, that IDP has got away a £4.0m equity fundraising.
In both these cases, I think they look more investable now that they’re properly funded.
.
Air Partner (LON:AIR)
(I hold)
70p (up 4% yesterday) - mkt cap £44m
Trading Update
We discussed this one in the comments section yesterday. The company said -
... However, despite global travel restrictions, the Group has performed better than expected and ahead of market expectations. Accordingly, the Board now expects to announce an underlying profit before tax of no less than £11.5 million for the full year.
That sounds amazing, but it’s not telling the full picture. The company made £10.5m in H1. So it’s only forecasting £1.0m in H2.
My opinion - I’ve got a small position in this, and am not particularly impressed with a trading update that I think gives quite a misleading impression on first reading. It was only when I checked the interim results that I realised it was such an extreme H1 weighting.
To be fair to the company though, it had previously emphasised that H1 benefited greatly from one-off covid-related contracts.
Just shows, it’s always important to check the detail.
.
On to today’s news, and there’s lots of it!
Somero Enterprises Inc (LON:SOM)
380p (up 9% at 08:18) - mkt cap £214m
This is one of my favourite value shares. It’s a well-managed, cash generating machine, making strong margins, paying good divis, as well as having a strong balance sheet.
Somero® provides the following update on trading for the financial year ended 31 December 2020 (the "Period").
Strong finish to 2020 significantly exceeding previous guidance driven by healthy North American market
It’s had a really good end to the year -
The Board is pleased to report that with strong, profitable trading in the fourth quarter, and in particular December, that exceeded the Board's previous expectations, revenues for the six-month period ended 31 December 2020 significantly increased from H1 2020 and surpassed revenues reported pre-pandemic in H2 2019, driven by robust trading activity in the Company's largest market, North America.
There’s a big increase in forecasts for 2020, which is remarkable since it comes at the end of the year -
As a result, the Board is pleased to report that it now expects to report revenue of approximately US $88.0m for the Period, significantly ahead of market expectations of US$ 80.0m, and annual adjusted EBITDA of approximately US$ 26.0m, also significantly ahead of market expectations of US$ 21.0m. These estimates remain subject to any audit adjustments.
Net cash - also stronger than expected, at $35.0m (guidance was $26.0m) although a one-off boost of $5.0m is mentioned. This will trigger a supplemental dividend.
New products - 3 have been launched, and generated £7.0m revenue in 2020, which seems good at 8% of total revenues for the year. Rapid market acceptance, helped by customer-centric product development strategy.
Growth Y-on-Y has all come from USA, its largest market. With more economic stimulus & Govt infrastructure planned by the new Biden administration, then I assume this market should remain strong. Somero confirms 2021 is looking good -
Our positive view of US non-residential market conditions remains unchanged as we enter 2021 based on consistent customer feedback indicating extended project backlogs that carry well into 2021.
China - poor. The company still isn’t gaining traction in this big market.
Europe & RoW - modest improvement in H2, but below 2019. Lockdown tighter than in USA (I heard something similar yesterday from another, unconnected company in a Zoom)
Outlook -
- Confident about new products
- Recruiting more sales & support staff - necessary to drive long-term growth
- “Meaningful” increase in operating costs in 2021
- Modest financial growth in 2021, offset by cost increases - sounds like they’re guiding for flat profitability in 2021 (but will probably beat guidance,as they tend to under-promise)
- Lingering uncertainty of covid-19
With a combined view of all these factors, the Board expects 2021 will be another profitable year with healthy cash generation, modest revenue growth and EBITDA comparable to 2020 due to the aforementioned planned investment in resources for future growth.
My opinion - a terrific company. See Finncap’s update note this morning, either on its own research portal, and Research Tree.
FY 12/2020 forecast is now 33.2c, at £1 = $1.37 that becomes 24.2p
PER is 15.7, not expensive for a company of this quality, particularly as it is sitting on surplus cash too.
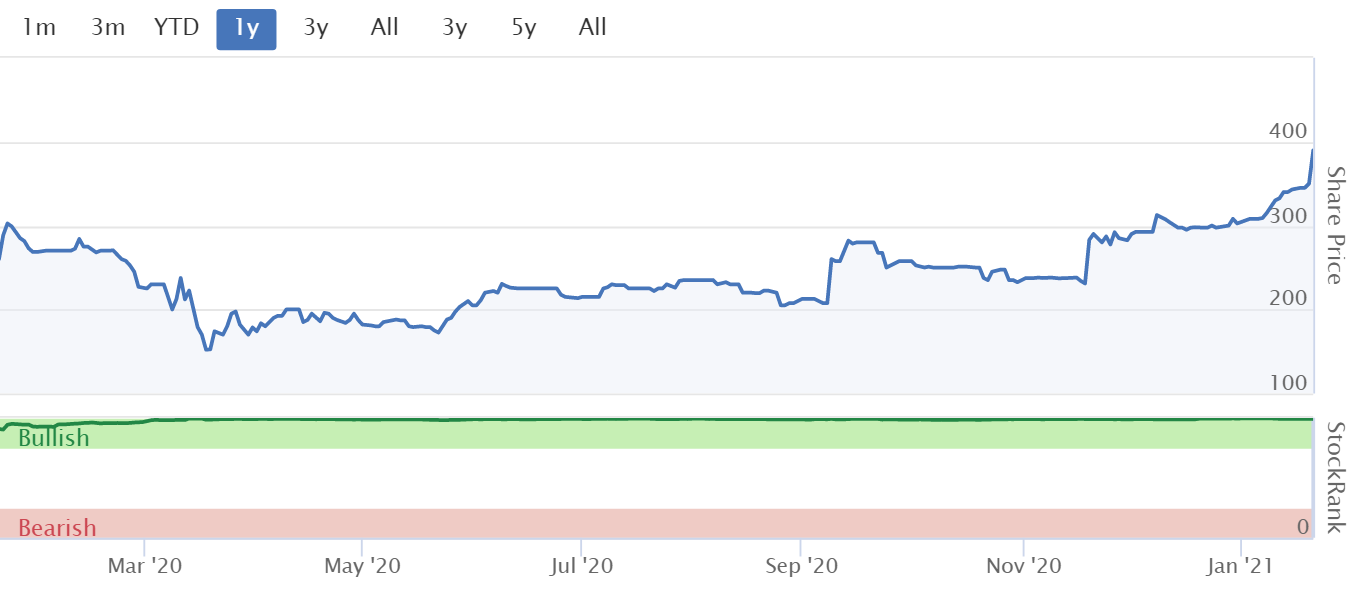
Note the StockRank is jammed on maximum - don't think I've ever seen one like that before!
.
.
Sanderson Design (LON:SDG)
(I hold)
115p (up 9% at 09:03) - mkt cap £81.6m
This wallpapers & soft furnishings group has been a quiet star in my portfolio lately - seemingly going up a bit every day, on no news, so perhaps someone might be accumulating stock in the background?
I see from the RNS that the Employee Benefit Trust has recently bought 50k shares at 88p, for the CEO’s bonus. Given the positive trading update today, I don’t begrudge her a bonus at all!
Also note from the RNS that the biggest shareholder in SDG, Octopus, has recently increased from 11.99% to 12.33%
Trading Update today
Dec 2020 better than expected - monthly sales +15% Y-on-Y [year-on-year], up from +7% in Oct/Nov
Jan 2021 - started well, but “tempered” by lockdown 3
Manufacturing division has performed better, sales up 33% in Dec 2020, and still performing well in January
PBT FY 01/2021 not less than £6.3m Operational gearing & cost savings have helped
This performance in both brand product sales and manufacturing has resulted in revenues being ahead of Board expectations and which, owing to the Group's operational gearing and the cost savings already implemented, has translated largely into profit.
Balance sheet “remains robust” - often companies that claim to have a strong balance sheet actually don’t, so this can be an amber flag. I’m happy to report that SDG does indeed have a robust balance sheet, I’ve double-checked back to the interims. There is a pension deficit, but not large, at £9.2m.
Outlook - ongoing uncertainty.
My opinion - I’m wishing I’d bought more of these, having been bullish about it for a while. Looking back at previous comments here, note that:
9 Nov 2020 I covered an announcement for a licensing deal with Next (LON:NXT) . There have been previous licensing arrangements, e.g. with H&M for clothing ranges. It occurred to me that SDG would make a good acquisition for Next, to gain exclusive use of its extensive back catalogue of designs.
21 Dec 2020 - a positive trading update, I reported on it here.
Today’s update gives us specific profit guidance, which is very helpful. I’m really impressed with £6.3m profit guidance for FY 01/2021, that’s considerably more than I was expecting, given what a turbulent year it’s been.
Note that H1 was only just above breakeven, at £0.4m adj u/l PBT. Hence H2 has been a bumper half, at £5.9m profit. Who would have predicted that? Even if it includes catch-up revenues/profit, that’s a good thing - i.e. it means sales were just deferred, not lost. Encouraging for the current lockdown.
I can’t find any broker coverage (grrrrr! Why do they make it so difficult for us?). We create the liquidity & set the share price, so it drives me mad that some brokers actively withhold information from us. Instead giving privileged info (sourced from, confirmed with, and paid for by the company!) to their broking clients only, hiding behind regulatory rules as the excuse (which don't seem to stop other brokers keeping us informed). It’s very wrong, the whole system needs a big shakeup.
Working on what I’ve got, the StockReport shows broker consensus of £2.8m net (i.e. after tax) profits, and 5.28p EPS.
The company today says £6.3m pre-tax profit, so take off my estimate of corporation tax at 19%, gives £5.1m net of tax earnings - that’s 82% above consensus!
Working out EPS, take my £5.1m net profit, divide by 71.0m shares in issue = 7.2p EPS which is 36% above broker consensus. I’m not sure why this is so much lower than the 82% mentioned above. Maybe some broker figures are out of date, or withdrawn? Or it could be to do with tax?
At 115p/share that gives a PER of 16.0 times - good value, considering how terrible market conditions have been.
Given that it’s cut costs, then it’s likely earnings should rise in future, which would bring down the PER maybe even into single figures.
Looking good, I think the fundamentals justify the strong recovery in share price, and looks like there could be more to come, taking a medium term view. I tend to think 2-3 years ahead with most of my investments, I’m not a trader. So I’ve got no idea what the shorter term share price will do, and that doesn’t matter to me. I’ll be buying more of SDG, if there’s a significant pullback.
Dividends - not mentioned today, but given strong trading, I imagine we should be back on the dividend list later in 2021, another reason to sit tight I think.
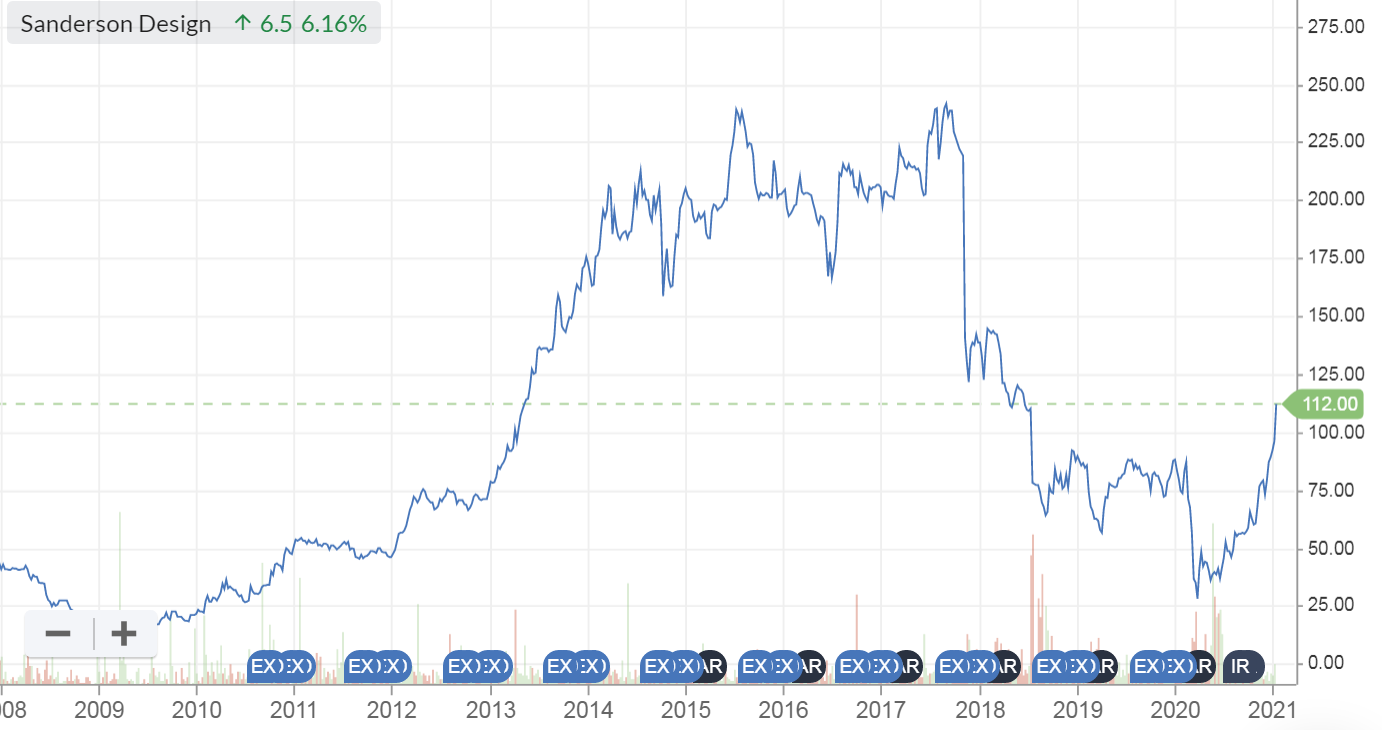
Looking at the long-term chart, it's on a very strong recovery trajectory at the moment, but still well below its heyday share price of c.200p. The share count has gone up from 62m to 71m over the past 5 years, which is only 15%. Therefore the historic chart is still a fairly good indication of what the upside might be. With cost-cutting done in 2020, maybe profits could exceed previous highs? That's an interesting prospect with lots of companies that were forced to restructure due to covid - maybe laying the foundations for a better business, not just recovering to previous levels of profit? Time will tell on that, but it's an interesting investment theme generally at the moment.
.
.
Headlam (LON:HEAD)
(I hold)
398p (up c.5% at 12:24) - mkt cap £340m
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor, is pleased to provide a trading update in respect of the year ended 31 December 2020, and ahead of announcing its final results on 9 March 2021.
This is another of my favourite value/recovery shares.
The appeal is that it seems obvious this company should get back to pre-covid profitability (maybe higher?) fairly easily, and then it’s likely to be producing c.40p+ EPS, and paying out over half in divis. That’s a future PER of 10, and a yield of about 6%, a very attractive proposition in a low interest rate world. Plus it has a smashing balance sheet, with tons of freehold property (c.£100m from memory) thrown in.
As an aside, I like to segment my portfolio, and allocate some of it for value shares, most for GARP & turnaround companies, another pot for growth companies, and finally a bit of fun with one or two mad speculative things too.
There’s no firm rule that we have to stick to one strategy, it’s our money, we can do what we want with it after all.
So HEAD is in my value pot. There’s also some growth potential, from market share growth, and some interesting ideas I think management could be toying with, about pivoting more towards eCommerce. Although they sounded unsure about this in a webinar last year.
They’ve given it a short summary, which are becoming more in vogue these days - and are quite useful I find, when they’re strictly factual, to save time when we’re under time pressure from 7-8 am -
Strong and sustained recovery maintained through the second-half
Intention to reinstate dividend
Good recovery in H2:
Whilst trading in Q2 2020 was significantly impacted by COVID-19, trading in the second-half was characterised by a strong and sustained recovery to 2019 levels. Accordingly, total revenue for the full year was only 15.3% below the prior year at £609.1 million, compared to 30.6% below for the first-half….
In the second-half, residential sector revenue was up 8.8% against the prior year compared to a decline of 17.8% for the commercial sector, albeit this still represented a strong recovery from the 34.4% decline seen in the first-half.
UK residential sector performed “exceptionally well” - compensated for weaker commercial sector. No surprises here, we already knew people are revamping their homes
European businesses did better, with revenues only down 4.1% on LY in 2020
Underlying PBT towards the top of the £14-16m range which was indicated on 19 Nov 2020 trading update - encouraging, but not earth-shattering.
Net cash - £50.5m at 31 Dec 2020, which includes a £12.0m boost from deferred VAT (thank you to the company for this transparency - if only all companies were this open).
Average net debt - again, an excellent disclosure, all companies should report average daily net debt/cash, which is far more meaningful than a snapshot on one day, which can easily be manipulated. The figures are:
H1 avg net debt £35.3m
FY avg net debt £8.6m
That seems to imply that the company was running in net cash on average throughout H2, to have pulled up the full year average to not far off breakven.
There’s also tons of liquidity on largely undrawn bank facilities - so it looks very strongly financed.
Dividends are being reinstated, although initially just a “nominal” amount (what’s the point? Maybe just to get back on the dividend list, so that income funds can remain invested?)
Another divi is expected to be declared in Sept 2021.
Capital allocation priorities - this is a really interesting disclosure, and I think demonstrates that the company is well managed, with a logical strategy. I’d like to see more companies publish their strategies in this way, because it shows they’ve thought about what level of financial reserves are necessary to cope if another pandemic were ever to happen:
As signposted in the November 2020 Trading Update, listed below, in order of priority, are the Board's Capital Allocation Priorities including targeted parameters:
1. Maintain a strong balance sheet, with targeted average net debt² during a financial year of not more than 0.75x EBITDA, unless exceptional or unforeseen circumstances prevail.
2. Investment, both opex and capex, in the core distribution business to optimise performance and growth.
3. Provide income to shareholders through a bi-annual ordinary dividend distribution paid out of cash with a target cover ratio of 2x earnings for the combined pay-out, and an interim and final dividend payment split of approximately 1/3 : 2/3.
4. Consideration of investment in acquisition opportunities aimed at growing the Company's core market position, including extending the product portfolio and weighting in certain customer segments.
5. After applying the priorities and parameters above, return any surplus cash to shareholders. The Board will keep under review and determine at the appropriate time the most effective method of returning surplus cash, including consideration of special dividends and share buybacks for cancellation.
The Board will review these priorities on a regular basis.
Current trading -
- Jan 2021 - seasonally quietest month. Revenue is down -5.1% vs LY - that’s fine, considering lockdown 3 is underway.
- Remaining fully open throughout lockdown 3
- Efficiency projects underway are being accelerated - more details to follow
- Brexit - very limited disruption to date
My opinion - what a superb update - full of the facts & figures that investors need. This gets a 10/10 score from me. It gives me so much more confidence in a share, where management report openly & honestly, like this. Honesty is always the best policy, in the long run, as it builds trust & hence shareholder loyalty, hence ultimately a better outcome for everyone.
Obviously the 2020 figures are not how we should be valuing the share, because it’s such an aberration. 2021 consensus forecast seems to be for about 28p EPS, for a PER of 14.2, but I’d say that looks too cautious, so personally I’m valuing this share on my own forecast of 40p EPS as mentioned above. Maybe it won’t get all the way there in 2021, but it should in 2022, or exceed it, given the efficiency gains being worked on now.
As before, this share gets a solid thumbs up from me. Despite a decent recovery, it still looks good value in my opinion, plus lovely divis to flow again over the next few years, I reckon. This is an ideal share for a SIPP in drawdown, in my view - generating a fairly reliable dividend stream (albeit paused in 2020).
.
.
Jack’s section
Begbies Traynor
Red flag report
The recent acquisition made by Begbies Traynor (LON:BEG) of CVR Global appears to have moved the shares and the stock does look attractive based on forecast earnings growth:

So this insolvency and restructuring specialist might still be worth looking into despite the strong share price performance already - but it’s Begbies’ most recent Red Flag Report covering the health of UK business in general that we’re covering today.
With the country once again in lockdown, it is no surprise to hear that 630,000 UK businesses are now in significant financial distress. This 13% increase from Q3 to Q4 marks the ‘largest numerical quarterly increase since Q2 2017’.
It’s a 27.5% year-on-year increase in 'significant distress’ since Q4 2019, with London experiencing a 33% increase in that same time period. Northern Ireland was also hit hard, showing the sharpest deterioration with a 40% increase since Q4 2019. This has likely been complicated by post Brexit border complications.
Against a backdrop of generally favourable share prices, these are very sobering statistics.
Splitting ‘significant distress’ out into industry groups, no prizes for guessing that hotels and accommodation increased by 32% (5,659 - Q4 2019, 7,494 - Q4 2020). But financial services has also been hit hard, up 38% (12,587 - Q4 2019, 17,423 - Q4 2020), as has real estate and property services, where the number has risen by 39% (53,224 - Q4 2019, 73,952 - Q4 2020).
On the whole, every one of the 22 sectors monitored by the Red Flag Alert research exhibited an increase in significant distress, with 18 sectors experiencing double digit increases.
On the one hand this is expected, but on the other it is still quite something to actually read.
What’s more, there is probably a backlog. The coronavirus pandemic has limited the number of CCJs3 and winding up petitions being issued against indebted companies and there has been a ban on winding up petitions for Covid-related debts.
Julie Palmer, Partner at Begbies Traynor, said:
Although the Government has extended its Covid-19 financial support, this simply won't be enough for thousands of businesses who likely will not survive in the interim. Although the UK's announcement of a trade deal with the EU and the roll-out of Covid-19 vaccines offer some light at the end of a very dark tunnel, the situation is going to remain bleak over the next quarter and beyond.
Conclusion
There’s a lot of pain out there, and we have at least one tough quarter ahead.
But we deal with publicly listed companies - you have to be of a certain size to reach that status. And when you get there, you have greater access to liquidity and funding. Note the recent placing by JD Wetherspoon, for example.
That option is not open to everyone. It’s quite possible the severe stress being felt by many business owners up and down the country will simply not be fully reflected on the stock market.
These sectors are complex systems so mapping out exactly how the dominos will fall, and how things will look after, could be a wasted task.
But an underlying truth to all this is that the best operators strengthen their market position in weak markets, so perhaps focusing on how quality operators are taking advantage of current events, and what that implies in the medium term assuming an eventual normalisation of society, is a good way to go.
Zotefoams (LON:ZTF)
Share price: 420p (up 1.9% at 09:22)
Shares in issue: 48,301,234
Market cap: £203m
Operational and Trading Update
Zotefoams (LON:ZTF) is a ‘world leader’ in cellular materials technology.
The claim does seem to be backed up by strong H2 momentum ‘resulting in record six-months sales’, although a quick look at the share price chart suggests it has not all been plain sailing here given that the shares are still below their highs.

Breaking this performance down into ZTF’s business units, HPP sales increased by over 10%. Here footwear sales grew strongly, up 65% and now making up 25% of group revenue. Foam revenue to the aviation market was down c50%, while sales of its T-FIT technical insulation grew modestly.
AZOTE polyolefin sales were in line with last year, although a decline of 20% in sales to its traditional markets was offset by project-related PPE sales to UK government programmes, which has now ended. The group does add that there was a ‘notable recovery in demand from these sectors in the fourth quarter’.
MuCell Extrusion sales declined by over 40%, mainly in equipment, impacted by the travel restrictions imposed by COVID-19 and a refocus of management time towards its ReZorce® mono-material barrier packaging technology.
ZTF concludes that ‘operational performance has been strong and, consequently, adjusted profit before tax and exceptional items for the year ending 31 December 2020 is anticipated to be at the top end of market expectations.’
The kickstarting of long term investment is encouraging and the group has commissioned its third foam manufacturing factory, in Poland, for early February. This completes the planned spending on major capital projects and increases group capacity, so it paves the way for a potential step change in production and cash generation.
And a quick look at the Financial Summary shows that ZTF could do with that step change - it has been burning up cash on these capex projects:

Conclusion
The improving backdrop means ZTF can reinstate investment into its ‘long-term growth drivers’, which were prudently put on ice. Solid cash generation has also returned net debt to EBITDA ‘closer to 2x’.
But that implies that leverage has recently been uncomfortably high for an organically growing small cap. This alongside long term investment being paused raises the question of whether or not trading was a little bumpier through the lockdowns than management are letting on.
It’s just a hunch for now, and this has undoubtedly been a tough period for many, with severe trading disruptions across the majority of sectors.
That aside, the introduction of the third factory in Poland will mark the end of a significant capex programme, so it’s possible in the near future holders will see a step change in production capacity and free cash flow generation.
One to watch on that basis, but at current levels and with risks remaining (albeit, hopefully, reducing), I am waiting for signs of that organic free cash flow generation.
All done for today! See you tomorrow.
Best wishes, Paul & Jack.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

106 comments
Surface Transforms (LON:SCE)
Hi Paul, You asked.
How to value it though? Very tricky.
My answer would be "move along, nothing to see here". 2 million in sales after 20 yrs for a company valued around £100M. I remember them from OFEX 20 years ago and they still are driving with the brakes on and passing around the collection plate regularly.
Hi Samsgrandad,
I recently saw their presentation at a Mello Monday event (and found a similar one here). Basically, the disk brake product has been in development for 10 years! This development time is the barrier to entry in to their market. It probably explains why there is only Brembo in the market today (yes, one competitor!). Surface Transforms (LON:SCE) have about4 - 6 car models signed up to use their line of disks, with another couple. Surface Transforms (LON:SCE) refer to these as OEM lines.
Surface Transforms (LON:SCE) have a modular approach to their factory and the latest fundraising was to double the manufacturing capacity (by building cell 2), so they can handle the demand they have signed up to deliver for the OEM contracts.
I agree its very hard to value and they do look expensive on a PER of appx 40. You can see this as a jam tomorrow type of share, however, it does look on the bring of a turn around.
Given electric cars are heavy and need more efficient disks, I think there is opportunity here , fingers crossed (I'm a new holder).
All the best, Andy
Hi Andy, maybe you should check the stock report again. The price to SALES is 40 ish. Their forward per is nearly 500 but it's your money you're giving away. And its 20 years since they floated on OFEX and 2 years later on AIM with their carbon-ceramic disk , not 10. See "about us" on their web site.
Good luck, but you'll find much better opportunities on Stocko.
Hey Guys,
A random one, but has anyone else noticed a really worrying trend coming from the US these past few days, whereby folks' on CNBC/ DC politicians have elected to use the term "normalcy" instead of normality ?!
Let's all pray to god that it doesn't catch on over here !
Spl183
it’s not a new trend, normalcy has long been American for normality.
yes, 'envision' rather than 'envisage' too - it's gotten to be a terrible version of English
Yes ! I even raised the normalcy reference on a US chat group I'm a member of and it seemed only those situated near the DC area were familiar with the term.
Apparently "normalcy" was never a word until the 1920 Presidential Election where Harding first used the phrase "Return to normalcy". After that, it seems to avoid embarrassing the president for making up a word, it became acceptable to use. So, it appears a politician made up that word. Been a regular watcher of CNBC for approx 6 months, and it's only been said over the past few days. Then former president Clinton goes and says it at the inauguration !!
Or 1857, according to Wikipedia
https://en.m.wikipedia.org/wik...
Ahh, yes of course, the credible source that is Wiki (!)
But, thank you as the link led me to learn about terms; "malaproprism" and "neologism" !
Have a good day @Westway001
IG Group (LON:IGG)
Graham Neary always liked IG Group (LON:IGG) this was his take on today.
https://cube.investments/cube-uk-report-21-jan-2021-tasty-acquisition-at-ig/
Probably best summarised as loved the results but horrified by the acquisition.
Phil
re Saga (LON:SAGA)
for all those who have commented rightly that customers will be waiting for vaccine #2 to land before they can step on board safely (I'm assuming that customers are likely early-ish vaccine candidates - ie older than the average, and the presumably younger staff are instead just tested);
this is a fair point and it might mean that initial sailings might be delayed by a few weeks or so.
however, I think the pent up demand to 'just get out' is almost bubbling over and I suspect some people would still cruise even if they remained on-board for covid safety.
Remember that these ships are floating luxury hotels with shows, bars, dancing, and for most of these people who have been isolated from their families and friends for nearly a year now, the main ingredient - merely other like minded people to gossip with in real-life rather than on a webcam whilst enjoying some sunshine, nice views and a 24 hour bar. Actually, I quite like the sound of that.
Even if that isn't enough to keep us as investors intrigued, remember that people also pay up front to reserve spaces and many will have the ability to postpose actual dates without cancelling/getting refunds if it is just a little bit longer a wait.
I see the return to the oceans as a "in the very near future" not "eventually", and I think the cash will come quickly enough to book what few spaces there may be to get away for some relief from all the negativity of the UK (winter, covid, brexit, family still locked down and can't see them).
Give it 12 months and I would expect them to be back to demand and earnings being close enough to pre-covid times. From the current price that feels like a good recovery investment to me.
100% agree with this opinion. I know many friends who are desperate to go on a cruise as soon as possible. I have a fairly large position in Saga but also Carnival as the latter has a strong enough balance sheet to survive even if cruises cannot start until 2022. And no doubt some competitors will fall by the wayside .
Although barely commented on so far today, it is good to see that Cloudcall (LON:CALL) has not lost its talent to amuse.
The market cap of £41mm is only £10mm below the amount it has raised in the market since 2010., the cumulative revenue over the same period is only £47mm. It is kinder not to dwell on the net loss position, and indeed the company obviously feels the same way since, despite a plethora exciting KPIs, todays trading update does not mention the profit or loss or even a mangled EBITDA.
When will all this "investment" start to show some return? Well I cannot do better than repeat the company's extraordinary statement -
“the Board remains confident in its ambition to now reach monthly EBITDA breakeven by mid-2023 and achieve a £50 million revenue run-rate during 2026.”
In discussing this a couple of years ago Paul described himself as having a "glass half full" view of CALL, as opposed to my "glass half empty" position. As a matter of record I now see my glass as 95% empty
Cloudcall (LON:CALL)
Aislabie
despite a plethora exciting KPIs, todays trading update does not mention the profit or loss or even a mangled EBITDA.
Thanks for flagging this one up Aislabie. I would say they did actually confirm losses (lol started typing profits silly me) will be "broadly" in line with expectations.
The Group is pleased to confirm it has achieved total revenues at the upper end of the revised guidance issued during the second half of 2020, whilst cash, operating expenses (which include one-time COVID-19 related savings) and losses before tax are all expected to be broadly in-line with market expectations, subject to year-end financial close and audit procedures.
I remember thinking myself what are they playing at quoting targets 6 years into the future when being frank they won't have the foggiest what will happen in te latter part of that period - i guess it kicks the can down the street bringing that same line out every 6 months for the next couple of years. Do they not relaise the stupiness of what they are saying or do they simply have nothing more positive to say?
The good news is we may be 6 months closer to the deadline compared to when they prevuously mention it - so they are approximately 1/12 of the way there - 1/12 being way more than 5%!! - so i think you need to upgrade your glass to 8% full rather than 95% empty.
As an ex holder i will remain an ex holder until i see something more tangible with regard to trend to profit and/or much higher growth in sales. I would say the company is not without hope though so who knows when things may takeoff.
Paul comments on Air Partner (LON:AIR) today and yesterday I pointed out the usual frustration of the company saying 'ahead of market expectations' without revealing what they were.
I contacted their Financial PR company who have replied that the expectation was underlying profit before tax of £10.5 m. In other words the broker had taken the company's phrase 'modest profit in H2' to mean just above break-even. Hence yesterday was saying 9.5% above forecast.
That still raises the question as to where the forecast of £7.3m on Stocko came from.
The better way from Sumo (LON:SUMO) today:
".....expected to be ahead of consensus market expectations* with Adjusted EBITDA for the year of at least £16.0m.
* Consensus market expectation for Adjusted EBITDA in FY 20 is currently £14.8m".
Greetings, sharw,
That still raises the question as to where the forecast of £7.3m on Stocko came from.
I don’t know where the estimate comes from, but when it came was December 2019. After this point forward guidance was suspended. Stockopedia merely states the last recorded profit estimate.
Air Partner (LON:AIR) reported earnings regularly during the spring and stated that profit for the second half would be modest. I assumed from the wording of updates that this meant the second half would be marginally above breakeven, which corresponds to the broker’s estimate of 10.5mil. AIR is made up of many businesses, some of which will have had little work due to travel restrictions; I assumed that the businesses benefiting from the current situation would be supporting those that had no work, and the result would be 0-.5mil pretax. Today’s update says that the result is a bit better, which I am pleased about. I had hoped that there would be a greater profit, but the company had been clear. AIR still trades below historic averages despite having had an exceptionally financially successful year.
I hold.
Stirling effort today! Thanks Paul and Jack.
I see no discussion around the Best Of The Best (LON:BOTB) RNS released today, which tells me its insignificant. However, it has left me what it actually means? What is rule 2.9 and how does it apply to acquisitions re Takeover code? And why has this resulted in 5000 ordinary shares being issued? Any ideas? :)
Rule 2.9 states:
When an offer period begins, the offeree company must announce, as soon as possible and in any case by 7.15 am on the next business day, details of all classes of relevant securities issued by the company, together with the numbers of such securities in issue. An offeror or publicly identified potential offeror must also announce the same details relating to its relevant securities as soon as possible and in any case by 7.15 am on the business day following any announcement identifying it as an offeror or potential offeror, unless it has stated that its offer is likely to be solely in cash. Any such announcement should include, where relevant, the International Securities Identification Number (“ISIN”) for each relevant security.
Essentially the point of it is, is to give everyone a official up to date share count so they can work out their % ownership for disclosure purposes.
Thanks, much appreciated
Delighted by the stock price rebound in Angle. After a long wait I had nearly thrown in the towel, which is what I stupidly did with Solero a year or so back. Now to see if what is really pretty straightforward micro mechanics is workable in the real world.
Angle (LON:AGL) For info - the Webinar on the 27th - A technology review of CTC harvesting methods – what are the differences and why does it matter? - will be made available on the company website a few days after the event. No need to pre-register.
Paypoint (LON:PAY)
Have released a trading statement today I believe.
Their shares are up 3%, so far.
I find it a little bit difficult to pick the bones out of what the state of the nation is as they have three business priorities they assign to certain activities.
Revenues have dropped 3% due to a change in the British Gas billing contract, which has been old news in the market for some time. It has an arm that deals with the 'last mile' of delivery services, in terms of using corner shops etc as drop offs. Revenues have increased. Payments using their payment services have dropped in volume but increased in value due to less frequent shopping trips during Covid.
They have a quarterly dividend policy and are maintaining current levels.
They sold their Romanian business, so look to be reinvesting those funds in developing more services.
A very cash generative business to date, in which there could be some gold nugget opportunities perhaps, but in transition with a new CEO and a shifting market.
I hold
Any updates for Paypoint (LON:PAY) on the Ofgem competition probe? That's the unknown risk.
I hold SDG.
It is quite interesting that H1 saw a loss of £.0.8m. Full year they now suggest a profit of no less than £6.3. which says £7.2m pbt in H2 ? Market cap £80m
Also in the coming year they have a deal with Jane Clayton to sell their Scion products online, the cost of development of the site being borne by Jane Clayton (janeclayton.co.uk). This will bring in an excellent sales stream imo. Also SDG have a license deal with Next where Next will make furniture and home furnishings under license of the William Morris brand. Again, no cost to SDG of any note but pure profit from licensing fees.
The new CEO Lisa Montague is former Mulberry and LVMH and seems to be rather good at getting the most from brands imo.
Perhaps I'm dreaming but if they can do £7.2m in H2 then double that next year isn't out of the real s of possibility or perhaps more with those license deals kicking in but you can sort of see the potential and growth and the PE isn't stretched at all imo.Ppreviously carrying debt they now should be net cash I think.
Well worth doing your own research on and making your own conclusions imo, all just my humble opinion and of course I could be completely wrong.
Hi Paul. Re Air Partner (LON:AIR) (I hold) Good point about average H2 earnings being hidden in single headline. I don't believe they intended to mislead as the announcement is the same format as the previous two 6-monthly updates. Assuming they can return to normal trading in 2021 then they are better value than before the pandemic. Air Partner (LON:AIR) is still making money and is ranked as one of the best value small cap stocks (Greenblatt). Looks like there are plenty of buyers at around 68p and trend line supporting this price .
Thanks Robert.
Yes, I'm sitting tight on my Air Partner (LON:AIR) shares (only a small position) but have decided not to buy any more. With all the disruption to global supply chains being reported widely, then I imagine there could be decent opportunities for AIR in air freight. I'm a bit surprised they didn't make more money in H2.
Regards, Paul.
Thanks Paul. I was expecting better in H2 and did increase my exposure accordingly, so a little disappointed yesterday. However, it looks like there is a fund selling down their holding, so I believe the price will rise in the short to mid term.
"I can’t find any broker coverage (grrrrr! Why do they make it so difficult for us?). We create the liquidity & set the share price, so it drives me mad that some brokers actively withhold information from us. Instead giving privileged info (sourced from, confirmed with, and paid for by the company!) to their broking clients only, hiding behind regulatory rules as the excuse (which don't seem to stop other brokers keeping us informed). It’s very wrong, the whole system needs a big shakeup."
Thinking out loud here but wondering if someone (Stocko?) were able to provide some kind of analysis which compared (by valuations, stockranks, something else?) the shares of companies where we do get helpful, sharing brokers, and those where we don't? If it were to show a significant difference, it would act as an incentive to the brokers / companies to change their ways.
Re Lindsell Train Investment Trust (LON:LTI) - please scroll past if of no interest. For the avoidance of doubt, I hold.
I found the Interactive Investor interview with Nick Train very worthwhile. His humility and genuine undogmatic style shine through and are quite disarming. Of most interest to me was the part in the interview where he said that he had forced himself to make a conscious decision many years ago to always be confident about the future whether that is of the economy or or of the stock market. So far that decision has rewarded him and investors in Lindsell Train Investment Trust (LON:LTI) and Finsbury Growth & Income Trust (LON:FGT) .
https://www.youtube.com/watch?v=78ljNaQeleY&feature=youtu.be&ab_channel=interactiveinvestor
Re Jack's comment on Zotefoams (LON:ZTF) (good write up BTW - thanks Jack.)
It was certainly pretty bumpy but they were transparent about this in my view.
The debt issue resulted from Covid disruption coming at a time of high capex re the expansions.
Aside from general belt tightening, they took two key steps.
1. Canned the final dividend for last year (retaining c. £2m cash)
2. Negotiated an increase in the Net Debt / EBITDA multiple to 4x at Jun-20 from the standard 3x.
At June they actually came in at 2.6x so presumably they did better than their worst case predictions.
I am frustrated that there were not clearer today about the debt level but reducing the multiple "closer to 2x" suggests a reduction in debt of anywhere between 1 & 7m (I suspect the low end) after having paid out £1m in reinstated dividends in H2.
Debt is of course high following the major capex programme, but in the end they have stayed comfortably within their covenants.
Re Ig Group (LON:IGG) and the comments as to why it has gone down today, isn't part of the answer the anticipated dilution of 61 million shares to be issued to tastytrade's shareholders. The price of those shares is circa £8.42, so I would have thought that's a relevant benchmark to today's opening price of over £9 for IGG shares. Overall, I think the potential acquisition looks very interesting, but I agree with a few others that it doesn't look particularly cheap for something with such regulatory risks. The counter to that is this a huge potential growth area for IGG. So I suspect I'll just sit this out unless the price comes down a bit more. All the best, Will
Many of the objections so far to the acquisition by Ig Group (LON:IGG) is the multiple paid for the earnings.
However, there are two hidden value here:
I have not looked at Tastytrade’s platform. As a new user of IGs platform I’m disappointed at how basic it is. I have been looking at Robinhoods platform which is one of the free us ones and I must say I’m very impressed with the ease, speed and information, this is what I expected from IG and other U.K. platforms. It can’t be that difficult can it.
I will have look at Tastytrades. Maybe IG can learn something to improve their own platforms.
The Headlam (LON:HEAD) update is interesting. Strong residential results, which I don't see as particularly surprising as it seems lots of people are doing home renovation at the moment. Walking around my neighbourhood the past few months for my daily exercise there's always been a healthy amount of trade work that seems to be happening.
The commercial front is where things look more intriguing - sales significantly down for Headlam. I went into their 2019 annual report and looked at how they describe their market, here's what they had to say about commercial customers:
"While demand in both the residential and commercial sectors
has a cyclical profile and is influenced by consumer and business
confidence and economic and political backdrops, the
commercial sector has a lesser discretionary aspect to it and
hence a higher degree of resilience in the face of weaker market
backdrops. This is attributable to increased H&S regulations and
the requirement for clean, comfortable, fit-for-purpose
environments meaning that, for example, while deferral can
occur due to limited budgets, replacement of floorcoverings has
to be undertaken periodically."
This suggests to me that there is pent up demand that hasn't been released yet. Many companies are still having their people working from home, and there's a lot of uncertainty surrounding the future of current office buildings and retail spaces. It makes sense that orders are deferred until there's more certainty, but ultimately the need to periodically replace the floors doesn't go away due to the regulation.
Ig Group (LON:IGG) interims look reasonably strong. They have also announced that they are buying a US derivatives platform.
The market seems to have been expecting more
Paul: “This is one of my favourite value shares.”
Do you hold?
I don’t but did from 2016 to 2020 and wish I still did!
Regards
Michael
Regarding £SOM I know the feeling! Purchased at beginning of 2017. Sold c. 50% of holding for decent profit May 2019 only to see profit warning send my remaining shares plummeting to below £2.00 - this profit warning combined with it falling well below a very generous manual stop-loss meant selling the balance at a small loss in September 2019. As often seems to happen, at least with my holdings (!), the share price has recovered dramatically even before the Covid-19 dip and subsequent bounce back. The investment advice would seem to be buy good companies and hold for ever even through temporary setbacks and profit warnings. Perhaps that is why I hold Smithson Investment Trust (LON:SSON) !
Hi Michael,
Paul: “This is one of my favourite value shares.”
Do you hold?
No, sadly not (I think you're referring to Somero Enterprises Inc (LON:SOM) ). I'm ashamed to admit that I've held it on & off, but am guilty of getting bored/uncertain in between announcements. And/or having to cull positions every now and then, when I get margin calls.
Pity, as a buy & hold would have worked well with SOM, and the value was obvious too. Even so, its update today does show a superb end to 2020, and I reckon they'll probably beat 2021 guidance too, it's just that type of company. And with loads of stimulus happening in the USA, I'd say the upside is more likely than downside.
Regards, Paul.
Any view from anyone as to why Sensyne Health (LON:SENS) never gets a mention on these excellent pages. I imagine Lord Drayson is not to everyone's taste and the shares had a horrible 2019/early 20 for totally self-inflicted reasons. However real progress now being made on both sides of the business with 6.8mn anonymised patient NHS patient records enhanced by AI a real asset for pharma partners. Recently raised GBP 27mn which party funded a 10% stake in Phesi which gets them access to clinical trail data and thus offers bundled resource for clinical trial design and P4 studies. Good progress on the software app side of the business with launch in US in tandem with Cognizant. Tight with Microsoft. Tiny market cap compared to US comps. Results today as ever lot of strategic progress but not much financial benefit yet. perhaps that's it. Call at 1pm
Wow Paul and Jack you're on a roll today, thank you!
In the meantime, piworld have just published Simon Sitwell, CEO at Bonhill (LON:BONH) who embellishes yesterday's trading update. How the company responded to CV19, their transition to virtual events, the positive margin impact, and the cost savings, together with the outlook for 2021. Interestingly, Simon suggests Asia will be the first to return to live events, and perhaps the US the last, with the UK somewhere in the middle, around late Autumn.
Video & Podcast
Why is Somero quoted in London when it's head office and most / all it's business is in the USA
IIRC Somero Enterprises Inc (LON:SOM) were brought to market by a UK PE outfit, which is said to be why it is listed in London.
I'm not sure how much sense that actually makes?
I do tend to be a bit wary of overseas companies listed in the UK, but when I looked at this some time ago, I couldn't find any concerns in this case.
Gromley is right, Somero Enterprises Inc (LON:SOM) was bought to AIM by a private equity firm
The Somero Enterprises Inc (LON:SOM) CEO explains how this happened (c2:00-3:30 mins)
https://www.piworld.co.uk/2019/03/29/somero-enterprises-som-2018-full-year-results-presentation/
(p.s. I have to say thank you to Tamzin and piworld, for providing such a excellent source of information - keep up the good work)
I have often wondered whether the Board decided on an AIM listing as theCompany would be less vulnerable to a takeover, than if listed in USA. When I listen to them they have concrete in their blood!!
They must be a delightful holding for the Institutional Stockholders (who seem mainly based in the UK) given the solidity of the business, cash generation and dividend payment history over several years.
One snippet of info which can be gleaned from the web site is that Somero have moved from using agents to having their own operations in both Australia and also to cover Far East markets in the past year.
SM
Yes I agree, especially as surely they would get a higher valuation in the US ? I wonder if there's any likelihood a moving the listing, and whether that might trigger a re rating ?
Yes, Paul has been writing about them for years - the accounts seem genuine and they pay a divi which suggests the cash is actually being generated. I read, though I haven't verified, AIM listings are pretty cheap so that's possibly got something to do with it.
RE: Somero Enterprises Inc (LON:SOM) (I hold)
Yes, Paul has been writing about them for years - the accounts seem genuine and they pay a divi which suggests the cash is actually being generated.
This has been discussed multiple times on Stockopedia but the lack of a search function makes it impossible to find the references. However, from memory, at the time Somero listed in London then AIM was the easiest place for PE to get a float away.
The company was listed with a ton of debt - as usual with PE - which nearly took it under in 2008 / 2009 but they traded their way out and are now exactly what they seem. That is, a very good niche company making real money which is exposed to the construction sector in general and the growing warehouse market in particular.
Unlike many overseas companies listed on AIM it's squeaky clean. Good management who seem to like their UK shareholder base. A bit of an anomaly, but a very nice one to have in the portfolio (especially today).
timarr
Hi Paul
I agree with your comments about Craneware (LON:CRW), excellent company, very fully valued. (I don't hold.) But a forward PER of 40 plus is almost becoming the norm across the software sector. I think that's too high, as do you, so what is Mr Market saying that we are missing?
Hi Sunday Trader,
Various commentaries I get by email seem to be increasingly moving towards alternative valuation metrics becoming the norm - e.g. EV/Sales multiples. That doesn't make any sense at all to me. Revenues are just pass through numbers. What matters is what's left behind (i.e. profit)!
It's feeling more & more like 1999 at the moment. So many warning signs flashing for exuberance & bubble valuations in pockets of the market (especially tech).
Regards, Paul.
Agree.
Paul - Would welcome your comments on Luceco (LON:LUCE) whose Q4 sales have leapt +23% and %gross margin has improved. I see Liberum are suggesting 450p (<300p now).
Sure, Luceco (LON:LUCE) is on my list to do later today.
Sorry, I'm too tired now to look at any more companies. Will review Luceco (LON:LUCE) tomorrow instead, I've highlighted it on my to do list :-)
Paul - Would welcome your comments on Luceco (LON:LUCE) whose Q4 sales have leapt +23% and %gross margin has improved. I see Liberum are suggesting 450p (<300p now).
Yes, the Luceco (LON:LUCE) Q4 update makes good reading, stating "we expect to report record full year profits at the top end of the most recently guided range".
Helpfully, October's Q3 update provides the figures: "we increase our guidance for full year 2020 Adjusted Operating Profit from at least £23m to between £28m and £30m", so we should be seeing FY Adjusted OP of around £30m, which equates to around 18p Adj OP per share.
Interestingly, investment company Epe Special Opportunities (LON:ESO) holds 40,064,372 shares in Luceco (24.9% of the Company) after selling 4mln Luceco shares recently to raise £10mln "for new investments". Note that ESO spent some of this cash on share buybacks.
ESO's last reported NAV (after LUCE sale and own share buybacks) on Dec 31 2020) was 430p (when Luceco was priced at 256p according to Stocko). If Luceco holds at around 280p that would make the NAV of Epe Special Opportunities (LON:ESO) circa 459p. ESO is currently 280p to buy (so 39% discount to newly calculated NAV).
ESO and LUCE are related parties as Giles Brand, the chair of LUCE is effectively ESO's investment manager. ESO's other investments are a bit of a mixed bag including Whittards of Chelsea (UK stores bad/online growing), and Pharmacy2U (presumably doing well ATM, but is it making any money?).
ESO is pretty illiquid so it's not easy to get in and out of. It used to get mentioned fairly often in Moneyweek and was the favourite of a few investment managers, but the SP dived after LUCE's annus horribilis and has never got close to former highs, despite LUCE now trading higher than it was before its own SP crash.
Disclosure: I don't hold LUCE, but I do hold ESO
I know it not a small cap, but it is mentioned regularly as a comparison to it's rivals, so does anyone have any thoughts on Ig Group (LON:IGG) and the acquisition? Specifically the fact that they've bought a sizeable, profitable business yet it will only add single digits to the EPS in the first full year of ownership. Reading the notes it may be that related costs are set against this but I'm not confident in my understanding.
Otherwise a good update, and probably a good acquisition.
Looks like a good day with updates from Somero Enterprises Inc (LON:SOM) and Zotefoams (LON:ZTF) too. Updates are particularly nervy events these days but things look like they're getting back to normal.
Ig Group (LON:IGG) a purchase of a company with a strong position in the USA seems like a good idea.
My year-end fair value has increased by 1500p. (see graph below.)
DYOR
BSV
Expansion into the US is a good idea as that is the next market that speaks English.
If they intend to 'converge' the businesses, as many businesses have found out, US English and culture is not UK English and culture and that is reflected in the design of the IG site and how it works.
If they do not it seems they spent a lot of money.
I hold and will continue to do so but am rather nervy.
Re. Ig Group (LON:IGG) - Net profit and EPS up 126% met by a lukewarm response from the market. I just have no idea what Ig Group (LON:IGG) have to do to impress the market. 55% increase in active clients too. I'd love to hear from anybody with an insight as to why Ig Group (LON:IGG) is so rarely rewarded for knocking it out of the park. I dread to think how they would fare with a profit warning! Clearly I am missing something because the market must know better than me. I'd love to understand what it is that I'm not seeing in these apparently stellar figures.
RE: Ig Group (LON:IGG) (I hold).
Clearly I am missing something because the market must know better than me. I'd love to understand what it is that I'm not seeing in these apparently stellar figures.
As mentioned previously on this thread you're probably missing the fact they're shelling out a billion for an acquisition that will only have a small impact on earnings next year.
timarr
I agree Ig Group (LON:IGG) (I hold) do seem to have paid a rather full valuation (about 20 times 2020 earnings) for the US acquisition, although the notes do seem to suggest the low single digits increase is a result of acquisition costs, so maybe more earnings enhancing into next year. One thing that concerns me is the options and derivatives market has been on a tear recently, particularly in the US, are they paying a full price at the peak of the market? I would like to see more of these big m&a deals better timed, but never seems to happen for some reason. That would be a slight concern for me, though intend to continue to hold onto these.
Thanks Timarr. Your assessment seems a little harsh. They're paying out cash of $300m for a decent foothold in an enormous, growing market. Whilst it may not be greatly earnings enhancing in the first year, we don't buy stakes in businesses for just the next year's earnings. The strategic rationale appear sensible to me and the growth looks impressive: 105,000 active accounts (85% yoy). Revenue of $116.2 million growing at a clip (44% yoy). It appears to diversify the overall risk profile of the group too. Time will tell but I'm happy that they appear to be delivering on their global ambitions.
RE: Ig Group (LON:IGG)
Your assessment seems a little harsh. They're paying out cash of $300m for a decent foothold in an enormous, growing market. Whilst it may not be greatly earnings enhancing in the first year, we don't buy stakes in businesses for just the next year's earnings.
Nor do we want to buy them at the top of the market.
I'm still holding but having seen this kind of deal go wrong multiple times it gives me the heebie-jeebies. The good bit is that it appears to require next to no integration.
But it's going to require more than a cursory read of the acquisition documents to decide whether to stick or twist.
timarr
IG Group (LON:IGG)
johnsmith68
Re. Ig Group (LON:IGG) - Net profit and EPS up 126% met by a lukewarm response from the market. I just have no idea what Ig Group (LON:IGG) have to do to impress the market.
Note revenue to end of November was previously flagged up in december so i am guesing numbers today are not particularly unexpected?
IG are very cautious - todays outlook says the following
Should we see further normalisation in financial market volatility, or a stabilisation in the macro environment we would anticipate some reduction in the level of client acquisition and activity.
The market is always looking forward so a "neutral at best " very short tem outlook (i omitted the slightly more positive next line !) isn't really going to set pulses racing. IG always tend to do this though play down expectations - i sold out when they thought profits were going into reverse and they were spending money for future expansion that would have unkown timing benefit - it turns out things medium term were much better than they had expected. Market doesn't like uncertainty and this lack of visibility i think gives then an unfair "discount" - however as things are uncertain lets face facts they could run into regulatory or other headwinds so not without risk.
I'd love to hear from anybody with an insight as to why Ig Group (LON:IGG) is so rarely rewarded for knocking it out of the park.
Well the share price hasnt done too bad if we look back to the 650p ish range back in january you have had a 40% return on your money - not too shabby. So with IG i think hanging around and waiting for the overall future results to consistently come in an dyou will be rewarded again. I am struggling to think why i have not bought back in here - i did replace this with 888 which i thought was a similar risk protfolio but that has gone out with the bathwater now due to the share price appreciation - so i even have a slot available in my random attempts at sector diversification.
Final note at present stocky figures show a material decline in expected 2022 earnings - these figures may be outdated perhaps and if not are probably glass 2/3 empty ?- but you can't really expect top wack premium rating while official forecasts show the company going materially into decline profits wise in the future.
Ig Group (LON:IGG) (I hold)
To add my 2p to the discussion:
It's not a big change, but from experience (from investing and as someone who used to work in finance) this is usually an immediate sell signal. Prior year numbers should not be changing without a good reason. Can anyone see why before I contact the company and possibly look silly?
a) £700m payment, including c.£150m net assets, so possibly a true net outlay of £550m.
b) £35m Adj EBITDA, which I assume is equivalent to cash generation given the supposed asset-light model of the business.
I assume there will be operating leverage with growth, but putting that aside some rough EBITDA scenarios until we know more:
a) 20% annual growth for 5 years = c £90m
b) 40% annual growth for 5 years = c £190m
Given the price being paid, I would be happy with both of the above scenarios.
I'm still wary of the changing OPEX figure from last year, but I will hold for now as I continue to believe that it is undervalued.
A
The net assets are not all being passed on to £IGG.
from the footnotes at the bottom of today's announcement:
The terms of the transaction stipulate that tastytrade will be acquired on a cash free / debt free basis subject to a minimum agreed level of cash to be retained in the business. Prior to closing, it is expected that tastytrade will distribute to tastytrade shareholders any cash that is on the balance sheet at such time in excess of this amount. As at 31 December 2020, tastytrade had $112.0 million of cash & cash equivalents.
disclosure: I hold £IGG. From what I can see from this morning's announcement, I feel that IGG is slightly overpaying for Tastytrade, and paying a slightly high-ish fair value for the opportunity.
Ig Group (LON:IGG)
Hi Laurie
I can't imagine the excess cash of whatever has been agreed will amount to much, so I stand by my assumptions.
I do wonder what makes up the rest of the $185m net assets though?
Cheers
The thing about Ig Group (LON:IGG) seems to be about those IP's with short term views versus those with long term views. To cut my story short I bought in at 459 pence in September 2012, saw the price rise to 950 pence in August 2016 after writing myself a reminder to sell soon. I forgot and saw the price halve in September 2016. Something about new Regulation perhaps. Now I'm looking forward to a second chance, Stock Ranks likes it, and I like the divi anyway.
Silver
IG Group (LON:IGG) Personally, I like both the results and, on balance, the acquisition.
Within the results, I was particularly happy that share dealing revenue reached a new quarterly high, even as OTC leveraged and Exchange traded derivatives dropped back a bit. I make share dealing net trading revenue for the last 6 quarters to be: 2.3, 2.1, 1.7, 7.5, 7.6, 7.9, with the 7.5 quarter being Q4 last year when the virus hit and derivative revenue went through the roof. I really like to see the share trading revenue holding up since I see it as having much less regulatory risk than the rest of the business, probably more sticky customers (and they have stated in the past that multi-product customers are more sticky), and if share dealing reaches scale then potentially a higher multiple could follow based on the AJB and HL valuations.
I also cautiously welcome the acquisition. The US is an anomalously small part of their current global revenue, and since the departure of the founder and the installation of a US management team I guess this was always on the cards. I don't normally like large US acquisitions, but in this case I think IG has to try to diversify away from UK derivative revenue. There was an article in the Telegraph about a week ago suggesting that all derivative trading could eventually be banned to UK retail traders, and whilst I hope this is just journalistic speculation and not any actual knowledge, the current UK derivative proportion of IG's income still represents a risk. With the acquisition, they both diversify geographies, and in the event of UK regulatory pressure they will likely by then be a FTSE100 company operating globally, and hence maybe have a bit more weight given to their views in pushing back.
Just my 2p worth! I hold IG Group (LON:IGG).
I nearly missed an unscheduled update from Sanderson Design (LON:SDG) this morning (another of my holdings).
The last issued a trading update 21st December, predominantly covering September & October. Now they tell us that December performance was stronger than expected (I'm guessing they cannot track this in absolute real time then !) The current lockdown has moderated performance somewhat.
They now expect PBT to be not less than £6.3m - which I think translates to around 7-8p EPS.
That looks well ahead of the consensus as per the StockReport (5.28p)
The share price has been on a bit of tear recently, but there could be more to come?
Yes, Gromley, it appears that you were right and analysts have been too cautious regarding improved trading and the impact on earnings at £SDG.
Credit I think must go to the new management team and its strategy of individualising the company's brands so that they can stand alone rather than been seen as a collective, and simplifying the corporate structure. They have also achieved some attractive licensing agreements, such as that with Next to monetise the extensive historic design archive.
I have held for sometime and added since. Where the share price goes from here and what the future holds? Do you have any thoughts?
Hi jonno,
I recall that I have you thank for putting Sanderson Design (LON:SDG) (or WGB as was then) back on my radar a little over two years ago. Although it then took a few months before deciding to pull the trigger and then deciding I had bought too soon. I subsequently bought back last June.
As you'll know this became subject of my when to sell experiment . Within that I set an upside criteria of a maximum Year2 PE forward PE ratio of 13x .
This seemed like a somewhat racy valuation for boring old Walker Greenbank.
With Stocko currently showing 2022 forecast EPS of 7.2p we are already ahead of that price.
However, there are two problems I think now with that view.
Firstly I believe that forecast is too conservative (although I don't currently have a view of what that should be and indeed what the 2023 forecast should be, given that will shortly become Year 2.)
Secondly, I don't know how far they have transformed (wallpaper is really not my thing!) but I suspect that they may no longer be "boring old Walker Greenbank", but perhaps a vibrant growing consumer brand. If that's so then a forward PE of 13x may no longer be racy.
What I guess I am long-windedly saying is that I really don't know where the share-price goes from here! Upwards further yet I suspect, but I don't have a scooby how far.
All else being equal, I don't expect to sell now before reviewing the FY results whenever we see those. They were April in 2019, but pushed back to June last year. Given their confidence in already calling a minimum value for PBT he I would hope we'll see the results at the earlier end of that scale.
Clipper Logistics (LON:CLG) is pleased to announce that it has entered into an initial term of 5 years agreement with Farfetch to provide pan-European e-fulfilment and returns management services from a new facility in Venray, Netherlands, eventually employing 600 personnel at the site, representing a significant extension of Clipper’s activities in mainland Europe, currently employing 1,500 personnel. I happily hold.
REG - Clipper Logstcs Plc - New e-commerce operation for Farfetch | Clipper Logistics News (CLG) | Stockopedia
My morning smallcap tweet: Never seen so many beats
Actual Experience (LON:ACT) Directa Plus (LON:DCTA) Sanderson Design (LON:SDG) Animalcare (LON:ANCR) Chamberlin (LON:CMH) ECO Animal Health (LON:EAH) Robinson (LON:RBN) Somero Enterprises Inc (LON:SOM) Cloudcall (LON:CALL) Panoply Holdings (LON:TPX) Newriver Reit (LON:NRR) Headlam (LON:HEAD) £ZFT eve Sleep (LON:EVE) Keystone Law (LON:KEYS) Luceco (LON:LUCE), Medica (LON:MGP), dotDigital (LON:DOTD)
Actual Experience (ACT) £10m placing at >=105p, a 14% discount, to xpand its sales and support, hire R&D staff and working cap. [SP=124 Cap=59m]
Directa Plus (DCTA) CFO scarpers, leaves March, "to pursue another business opportunity". [SP=92.5 Cap=57m]
Sanderson Design Group (SDG) guides FY(Jan) pretax at least £6.3m as rev beats mgmt exp. [SP=105.5 Cap=75m]
Animalcare (ANCR) guides FY(Dec) rev £70.5m down 1%, ahead of mkt exp. Earnings also ahead. [SP=190 Cap=114m]
Chamberlin (CMH) BorgWarner places orders through to March 2021 after saying in Dec it intended to cancel all contracts. "The Board is implementing further measures to reduce costs and is exploring options to strengthen the balance sheet, including investigating the possibility of new equity capital and alternative measures to ensure the Company's future." [SP=7.4 Cap=1m]
Eco Animal Health (EAH) guides FY(Mar) rev and EBITDA significantly ahead of market expectations. Vites strong CHina pig market and also USA sales. [SP=255 Cap=167m]
Robinson (RBN) guides FY(Dec) rev up 6% and pretax ahead of market expectations, and ahead of 2019. Intends to pay tot div 8.5p (2.5p). [SP=157 Cap=26m]
Somero Enterprises (SOM) guides FY(Dec) rec c. $88m and adj EBITDA c. $26m. F/C were $80m and $21m. Net cash $35m cf $26m guided. Expect a special div. Will hire more sales and support staff, hitting FY21 profit. [SP=360 Cap=201m]. I hold.
Cloudcall (CALL) guides FY(Dec) rev up 4%, the upper end of guided range. Loss broadly in-line with market expectations. "Remains confident in its ambition to now reach monthly EBITDA breakeven by mid-2023 and achieve a £50 million revenue run-rate during 2026." [SP=106 Cap=41m]
Panoply (TPX) guides FY(Mar) rev over £47.5m and adj EBITDA over £6.3m, significantly ahead of expectations. [SP=164 Cap=114m]
NewRiver REIT (NRR) rent collection improving. On corse for taget £80m disposals. Sold at 6% disc to March book. [SP=84.8 Cap=260m]. I hold.
Headlam (HEAD) guides FY(Dec) rev down 15% and U/L pretax towards the top of the range of guided £14-16m. Will resumes divs albeit with FY a nominal amount. [SP=380 Cap=323m]
Zotefoams (ZFT) guides FY(Dec) rev in line and adj pretax at the top end of market expectations. [SP=NA Cap=NA]
eve Sleep (EVE) 18% sales growth in H2, exceeded twice raised expectations for 2020. Guides FY(Dec) rev up 6%, EBITDA -£2m (-£10.7m). Will it ever make a profit though? [SP=5.78 Cap=16m]
Keystone Law (KEYS) guides FY(Jan) adj pretax materially ahead of market expectations of £5.1m after a busy Xmas period (normally quiet). [SP=520 Cap=163m]
Luceco (LUCE) expects FY(Dec) profits at the top end of the most recently guided range. [SP=275 Cap=442m]
In line: Medica (LON:MGP) dotDigital (LON:DOTD)
Headlam (LON:HEAD) strong trading in 2nd half and reinstating dividend
spotted too - surprised how muted the response from the market is
Ah it's starting the react to the good news now...
Very pleasing trading updates from Headlam (LON:HEAD) and Sanderson Design (LON:SDG), together with the announcement by £AVG of a further contract worth £2.9M for its subsidiary Booths Industries. Headlam (LON:HEAD) have committed to reinstating the dividend. I am fortunate to hold all three.
A good morning. It will be interesting to see how the market reacts.
Paul/Jack, your views would be appreciated on any of the above, time permitting.
Best wishes to all
Sanderson Design (LON:SDG) and Cloudcall (LON:CALL) posted trading updates today both look positive.
Eve Sleep - year end update. Emerging from near death under new management. Very strong H2, beating earlier raised sales guidance. Net cash of £8m and market cap of £15m, generating sales of over £25m. Interesting recovery story worth a look.
Paul
May I please ask you to comment on Somero’s update today?
It’s been on a good run recently and today’s figures should hopefully help continue that
With thanks as always
Encouraging update imv from Zotefoams (LON:ZTF) (I hold) , but as it was fairly clearly signalled in the November update, its not obvious to me that it should move the market too much.
Record 6 month sales - whilst these were boosted somewhat in Q3 by PPE contracts, these were smaller in Q4 and with the aviation market badly down and some other markets subdued, total revenues being up looks like a good result and gives good momentum for the future.
The revenue number was actually in line with expectations (presumably post the November update) and adjusted PBT to be at the top end of expectations (unhelpfully they don't tell us what the expectations were.)
Strong cash generation has returned the net debt to EBITDA ratio "closer to 2x"
GRR- in the past they have given us a number for net debt (£36m at the end of September) - so why do we get such a woolly statement on net debt now?
Plenty more detail in the release on how their individual markets are performing and it all looks promising to me looking forwards.
Not quite enough meat in the announcement however to give a proper view.
Full year results are slated for 23rd March (same as last year, which was later than usual).
At first glance, results from Close and Secure Trust Bank both look surprisingly sound. Somero too. Maybe there is still some value out there.......
Secure Trust Bank (LON:STB) - I'd say better than 'sound' to be honest -
"As the Group has made further positive progress since the Q3 trading update in October, the Group expects that the full financial year 2020 results will be materially ahead of the upper end of consensus profit before tax."
sounds excellent in my mind!
An interesting article on Saga https://www.bbc.co.uk/news/bus...
RE: Saga (LON:SAGA) and vaccines.
They're right to delay restarting cruises until people have been fully vaccinated. There've already been cases of people who've died after having had the first dose:
https://www.bbc.com/future/art...
Can you change your behaviour after receiving a single dose?
"I would behave exactly as if I hadn't had the vaccine yet," says Altmann. "I wouldn't drop my guard at all or do anything differently."
Deborah Dunn-Walters, professor of immunology at the University of Surrey, is just as unequivocal about how people should behave. "There's a couple of reasons for that," she says. "One is, you're not going to be fully protected. And another is there is no evidence as yet that having had the vaccine will stop you getting the virus and passing it on."
timarr
I agree they are right to delay. Their return to cruising needs to be a success.
However, there is a definite return to travel. That is good news for Saga and others.
RE: Saga (LON:SAGA) (I hold)
I agree they are right to delay. Their return to cruising needs to be a success.
I'm wondering what they do about staff. Presumably a CV-19 outbreak in the crew would lead to abandonment and further cancellations.
It's going to be tricky to manage, I suspect. As it stands the UK is looking at being fully vaccinated by the autumn, Europe by end of the year. Saga's only non-European cruise, to
South America, isn't scheduled until January 2022 - although I reckon that looks optimistic (especially given the overnight stay planned for Manaus).
Assuming the vaccines work at population scale then they're possibly back to normality by end Q1 2022. Everything in between looks like guesswork.
timarr
I wish Saga well but Manaus must be one of the worst places on Earth right now. I can’t imagine wanting to visit as a tourist for quite a few years.
I wish Saga (LON:SAGA) well but Manaus must be one of the worst places on Earth right now. I can’t imagine wanting to visit as a tourist for quite a few years.
Precisely.
Healthcare system has collapsed, people dying in hospital due to lack of oxygen ... There's zero chance of that cruise going ahead.
https://edition.cnn.com/2021/0...
timarr
Quick thought on Saga, I almost bought in a few weeks ago until I thought about the situation regarding cruises. Every few days the ship stops and mingles with the various populations, maybe not a good thing ? I'm sure cruises have thought of this and have procedures in place. Wish the investors here the best but haven't heard of this angle from what I've read(sorry for my pessimism).
RE: Saga (LON:SAGA)
Every few days the ship stops and mingles with the various populations, maybe not a good thing ? I'm sure cruises have thought of this and have procedures in place.
Hi Gary
Apart from their single South American cruise all Saga's are to European destinations. Populations may not be vaccinated this year, but they will be next. But, yes, I agree that there will have to be processes in place around going on shore.
My view is that Saga is cheap, that it can survive a prolonged shutdown and (for reasons that completely escape me) there will be demand for their cruises when they finally restart. In two years time they ought to be trading at a level significantly north of of where they are today.
As to how they get from today to two years hence I have no real idea and I don't think anyone else does either, no matter how confidently they pronounce on the issue. But this is the nature of investing - looking ahead it appears impossible, in the rear view mirror it's obvious and the best we can do is allow ourselves a margin of error while we transit from one to the other.
And, of course, it could all go badly wrong - so if you're invested it's important to match holding size to risk.
timarr
timarr
Re your “for reasons that completely escape me there will be demand for their cruises,” comment; that reads as though you’ve never been on a cruise. I thought the same until going on one. The quality is high and resembles a 5 star hotel.
Sailing across the Atlantic on the Queen Mary is far more luxurious now than when major celebrities, Royalty and politicians saw it as the luxury holiday it was.
That luxury applies to Saga’s cruise offering too. Food is excellent and so varied with various eating options and usually available all day; service is exceptional, and on top of that Saga have two brand new small state of the art , market leading (and in air quality) all balcony cruise ships too. Sit on your balcony on an evening with a glass or two of wine watching in awe as the ship glides through Norwegian fiords looking at their best! Saga even pick up their customers if living within 250 miles of the port. The ships are spacious too and entertainment often high quality.
There are negatives. We like to be independent in ports of call but that’s a minority view. Many like to be herded in all inclusive tours provided by Saga. Many cruise Companies have lower initial prices but then charge exorbitant rates for their tour offerings. That suits us better so we’ve only been with Saga on one of their previous old, but still very good, cruise ships once. Older customers often want the all in offering.
So imo once life returns to normal and when Saga can sail full instead of 80% capacity Saga’s cruise ships could provide significant profits with their general travel business and insurance business on top. So SAGA is less risky than a pure cruise Company like sector leader, Carnival.
I hold Saga and Carnival. Both have significant upside potential but Saga is less risky than Carnival should vaccines disappoint and lockdowns last even longer than currently expected.
Hi Ken
Re your “for reasons that completely escape me there will be demand for their cruises,” comment; that reads as though you’ve never been on a cruise.
I haven't and I don't want to. Sounds like my idea of purgatory. But clearly I accept that other people feel differently, otherwise I wouldn't have invested in Saga (LON:SAGA).
As a general point, though, if I only invested in things I liked doing myself it would be an eclectic portfolio :-)
timarr
I agree that Saga are right to slightly delay cruise restarts to enable for vaccination and with the general message that at this stage vaccines should not change behaviours.
However that BBC article is very poor and slightly misleading. They say he was vaccinated " less than three weeks" before being diagnosed with Covid-19. In fact piecing together the dates from the local paper it appears he will have contracted it two weeks or less after being vaccinated. Which is therefore not at a time when even the first dose of the vaccine would be fully effective.
The general message of caution is of course a good one, but it doesn't appear to me that this story tells us anything about the effectiveness of a first dose (and of course there is no claim that any of the vaccine regimes are 100% effective anyway).
Sorry - sloppy reporting is just one of my bugbears right now!
Hi Gromley
Sorry - sloppy reporting is just one of my bugbears right now!
Well yes, although I think the motivated reasoning of high profile Covid deniers in the media would be a better target of your ire. But focusing on the human interest story used to hook people into the article rather misses the fact that there are a number of important points being made:
In the context of Saga (LON:SAGA) it simply reinforces their decision to wait until people have had both doses before resuming cruises. Although with no clinical data on the effectiveness of a twelve week gap between doses even that is not certain.
timarr
In the context of Saga (LON:SAGA) it simply reinforces their decision to wait until people have had both doses before resuming cruises. Although with no clinical data on the effectiveness of a twelve week gap between doses even that is not certain.
And you need to remember that if you have 800 people who have had two shots of the Pfizer vaccine on a boat, 40 of them could still potentially get the disease even with 95% effectiveness. And no-one knows for sure yet whether vaccinated people can still carry and pass on the vaccine to others. What they don't want is a mini Diamond Princess...
All the best, Si
RE: Saga (LON:SAGA)
And you need to remember that if you have 800 people who have had two shots of the Pfizer vaccine on a boat, 40 of them could still potentially get the disease even with 95% effectiveness.
Yes, although that's just situation normal going forward. At 95% effectiveness (in fact, at about 70% effectiveness) herd immunity kicks in. You may get an isolated case but you won't get contagion because most people who are infected are, at least in theory, immune.
The problem in (say) May is that you'll have 600 passengers who are vaccinated and 150 staff who aren't and you're on the edge of herd immunity - and if the vaccines are less effective in older cohorts then you could get an outbreak. And, as you note, those numbers change if vaccinated people can still act to spread the disease (which is unlikely, but possible).
Of course, in the short term, even a single case could trigger a reputational issue. You'd imagine that people will still be extremely nervous and would react quite negatively and the press coverage would be dreadful.
timarr
Yes, although that's just situation normal going forward. At 95% effectiveness (in fact, at about 70% effectiveness) herd immunity kicks in. You may get an isolated case but you won't get contagion because most people who are infected are, at least in theory, immune.
Yes, but doesn't herd immunity assume that once vaccinated you cannot pass on the disease to those who are not protected? Hence the reason they will still be testing people before boarding even though they have already been vaccinated. I have to admit it would not create an environment in which I'd want to spend a relaxing holiday, particularly if people are coming and going from the boat en-masse when in port. However, I can understand there are lots of other people who are completely desperate for a holiday and have no understanding of such matters, or statistics, and will act like they are 100% immune from Covid!
All the best, Si
Yes, but doesn't herd immunity assume that once vaccinated you cannot pass on the disease to those who are not protected?
It does. But while I quite understand the caution, and the fact that study over a decent period of time (months probably) is going to be needed to confirm the impact on infectivity of the vaccinated, I find it very hard to believe that it is not going to prove to be the case that there is a major impact on transmission.
People are infectious because they a producing a lot of virus in the respiratory tract, which gets spread coughing, breathing, talking etc. Any normal mechanism of vaccine action is via the immune system reducing both circulating virus and replication of it. If you don't produce virus, or you produce much less, it's hard to see how that isn't going to reduce transmission significantly. And there's no reason at the moment to think that covid 19 is operating in an unexpected way.
Re Saga (LON:SAGA), this is a response to all the good points made so far, rather than a specific reply to the last poster. All passengers must be fully vaccinated is the statement from Saga (LON:SAGA), but when will that be? I cant see their cruises making significant business until the late summer if I do my maths correctly, with the 12 week 2nd dose, and the mixed age range of the potential Saga (LON:SAGA) customer. I accept that I am a very cautious person with an underlying condition, but my desire to ocean cruise would be to have a relaxing holiday including visiting a rage of different ports. I cant see me regarding ocean cruising coming on to my radar until 2022. Then I accept that the flood gates may open - but for ocean cruising generally, and especially further afield, given the wide range of numbers being vaccinated in different countries over the next 2 years, my geographical range will be quite limited. All IMHO of course. It does mean to me that quite a lot of companies dependent on ocean cruising are already ahead of the curve on valuations. Im on the sidelines for now. There are other ways of making money in this bull run.
ridavies
Saga aren’t “dependent on ocean cruising.” They also have an insurance business and a general travel business targeting the over 50s.
It does. But while I quite understand the caution, and the fact that study over a decent period of time (months probably) is going to be needed to confirm the impact on infectivity of the vaccinated, I find it very hard to believe that it is not going to prove to be the case that there is a major impact on transmission.
Just to quickly follow this up as it may be of interest to some. I listened to this weeks excellent "More or Less" program or R4 this PM on BBC Sounds. The Pfizer Phase three trial did not test for the level of protection from getting the virus of those that had received the vaccine, but the Oxford/AZN phase three trial did. The latter showed that 100 vaccinated people still tested positive with a PCR test without any signs of illness (i.e. asymptomatic) and overall the vaccine was only 46% effective at protecting against getting the virus. This means more than half of those who receive the Oxford vaccine can still carry and pass on the virus. Please don't go and hug your old folks even when they've had both doses!!
All the best, Si
"The latter showed that 100 vaccinated people still tested positive with a PCR test without any signs of illness (i.e. asymptomatic) and overall the vaccine was only 46% effective at protecting against getting the virus."
I don't understand Simoan, the first bit says, to me, that all 100 still got the virus but the second part says 54% of those vaccinated still got the virus.
Which is correct - or is it that everyone still gets the virus but 54% of them suffer symptoms?
Which is correct - or is it that everyone still gets the virus but 54% of them suffer symptoms?
Neither. In the vaccinated group about 100 people tested positive, compared to 190 people in the control group. None of those positive testing people in the vaccinated group became ill - but they were still able to transmit the disease.
You'd therefore assume that 90 people in the vaccinated group also caught the disease but didn't test positive, resulting in a 46% reduction in the group capable of transmitting the disease.
Basically - the Oxford data says that the vaccine stops people becoming ill but is less effective at stopping them catching the disease and spreading it.
You can give CV-19 to your vaccinated granny and she probably won't get ill - but she could infect someone else.
timarr
Without wishing to extend the virus/immunity discussion too far (though it is certainly relevant to investment strategy), I'd take a bit of issue with this:
Neither. In the vaccinated group about 100 people tested positive, compared to 190 people in the control group. None of those positive testing people in the vaccinated group became ill - but they were still able to transmit the disease.
We don't know they could still transmit the disease, or if so how well. We know they had antibodies, so tested positive. If they were asymptomatic then the viral load was probably low, and so they would be likely to be (a lot?) less infectious.
However, clearly, at this time we don't know the full picture, and I'd agree with simoan - be careful hugging vaccinated grannies!
Without wishing to extend the virus/immunity discussion too far (though it is certainly relevant to investment strategy), I'd take a bit of issue with this:
Well, we're off the main thread, so I don't think it matters much.
If they were asymptomatic then the viral load was probably low, and so they would be likely to be (a lot?) less infectious.
It's unclear how viral load connects to infectiousness but the general point is correct - that asymptomatic people are probably less infectious: https://www.bmj.com/content/37...
"While viral load seems to be similar in people with and without symptoms, the presence of RNA does not necessarily represent transmissible live virus. The duration of viral RNA shedding (interval between first and last positive PCR result for any sample) is shorter in people who remain asymptomatic, so they are probably less infectious than people who develop symptoms".
So I'd agree with your statement but I don't think, in practical terms, it makes any difference. We have to assume people who are asymptomatic, whether vaccinated or not, are infectious and wait for the research to tell us exactly how infectious they are.
timarr