Small Cap Value Report (Thu 22 Aug 2024) - COST, PPS, MACF, LTHM, HAS, BMK, NEXN, CLX, EBQ

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
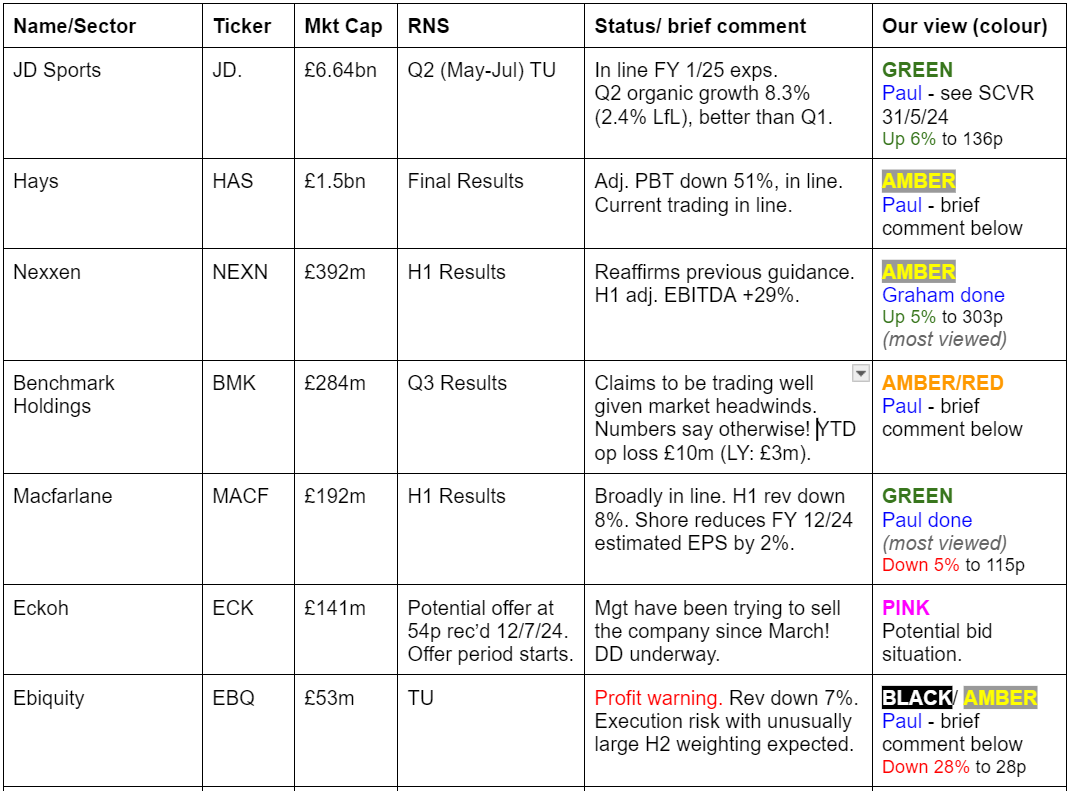
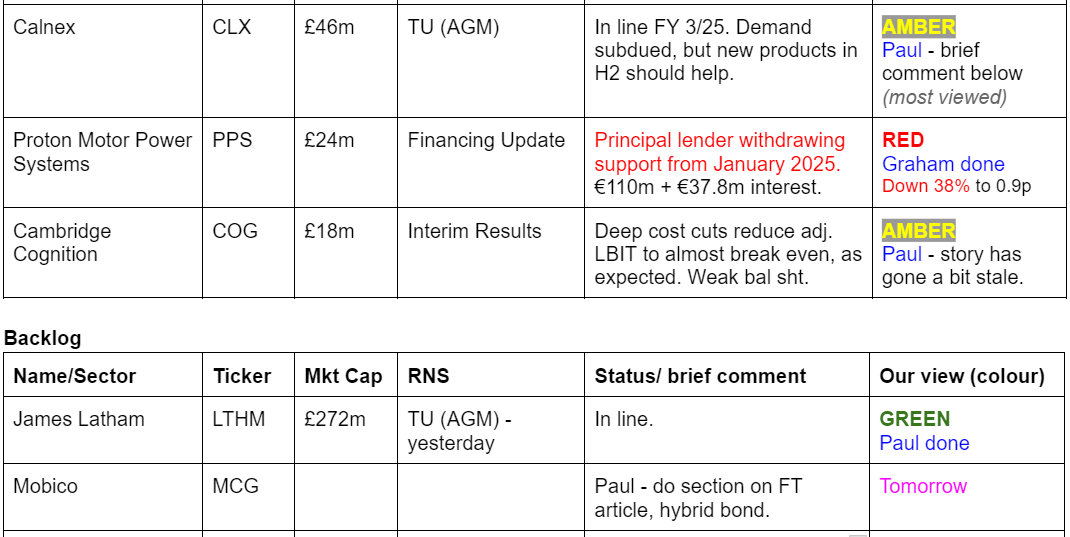
Summaries
Costain (LON:COST) - up 7% to 101p (£281m) - H1 Results - Paul - GREEN
From yesterday, I give a thumbs up again to this contracting group, which is planning on significantly increasing its operating margin from current low level of 2.5% to hopefully 5%+ over the next few years. It has a notably strong balance sheet with loads of cash. Don't forget the sector risk though! Webinar on IMC is 10am today.
Proton Motor Power Systems (LON:PPS) - 1.45p (pre-market) - Financing Update - Graham - RED
The lenders to this hydrogen energy company have indicated that they will no longer support the company’s working capital needs, from January 2025. Their loans are repayable in December 2025. Unfortunately the financial performance of this business has been abysmal and it is very likely to need more funds next year. Unless they can find someone new to throw good money after bad, the equity looks set to reach its terminal value in an accelerated manner.
Macfarlane (LON:MACF) - down 5% to 114p (£182m) - H1 Results - Paul - GREEN
Packaging distributor that reported soft trading back in May now says it's slightly behind FY 12/2024 expectations. Shore trims its estimated EPS by 2%, so no great shakes. I see this as a good business, reasonably priced, so remain positive.
James Latham (LON:LTHM) - 1,355p (£272m) - AGM Statement - Paul - GREEN
In line TU from yesterday, for this wood products distributor (eg fencing). A recap on the figures reminds me what a nice cash generative company this is, with an astonishing balance sheet groaning with surplus cash. Valuation looks reasonable, so I'm happy staying at GREEN.
Nexxen International (LON:NEXN) - up 5% to 302.8p (£411m / $539m) - Q2 and H1 2024 Results - Graham - AMBER
Full-year guidance has been maintained by this advertising platform. I’m taking an upgraded view of AMBER here, compared to Paul’s AMBER/RED, as I think that the company’s aggressive use of buybacks (including a $50m buyback announced earlier this year) could keep the positive share price momentum going. But fundamentally I don’t trust this company’s performance metrics and I wouldn’t want to hold it long-term.
Quick Comments
Hays (LON:HAS)
Up 2% to 96.7p (£1.54bn) - FY 6/2024 Results [in line] - Paul - AMBER
Staffing companies are really struggling. Poor FY 6/2024 results today, with adj PBT down 51% to £95m, adj EPS down 53% to 4.0p, but that’s as expected, after its profit warning on 9/1/2024. Fwd PER is high at 22.4x, as the market anticipates the still-elusive recovery in sector outlook. This is not just a UK problem, other large markets are also struggling, including Germany and Australia. More cost savings announced. Current trading sounds a little wobbly, with it saying Sept is key month, but “too early to assess trends”. Headcount down 18% in the year. OK balance sheet.
Paul’s view - trading should improve as a cyclical recovery begins, but I feel the share price is asking me to pay too much up-front for a recovery that hasn’t even started yet. I’m not convinced HAS deserves a premium over smaller staffing companies. Although Pagegroup (LON:PAGE) and Robert Walters (LON:RWA) are on fairly similar forward PERs. SThree (LON:STEM) appeals to me most in this sector, as it’s much less cyclical, and reasonably priced.
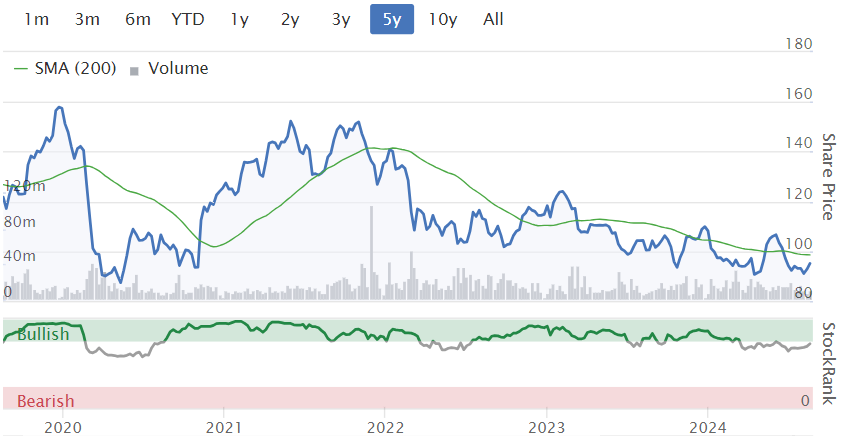
Benchmark Holdings (LON:BMK)
Unch 38p (£281m) - Q3 Results - Paul - AMBER/RED
Issues Q3 results, as required by its unsecured green bond. Another operating loss - £(6.5)m in Q3, worse than £(4.0)m op loss in Q3 LY.
Net debt (excl leases) has risen to £63.9m June 2024, was £56.8m just 3 months earlier, so cash burn looks an ongoing problem. Says it has plenty of liquidity though.
9 month YTD revenues down 17% to £111m. YTD operating loss of £(10.2m) worse than £(3.0)m LY comparative. Note the very large finance costs, so operating profit is not a reliable number. It made a £(17.3)m LBT in the 9 months to June 2024. Balance sheet looks OK overall, with NTAV £66m, but the debt £64m net debt worries me as it’s expensive. You would need to carefully check the terms - any covenants, repayments, etc?
Paul’s view - I remain utterly perplexed as to why BMK is so richly valued. It must have something special which is not yet apparent from its historical trading results, which have been consistently loss-making. It’s not even growing any more, with revenues going backwards. I’d say time is running out here, and personally wouldn’t touch it, so I’ll remain at AMBER/RED. Can any readers explain in the comments why this share commands a £281m market cap? What am I missing?
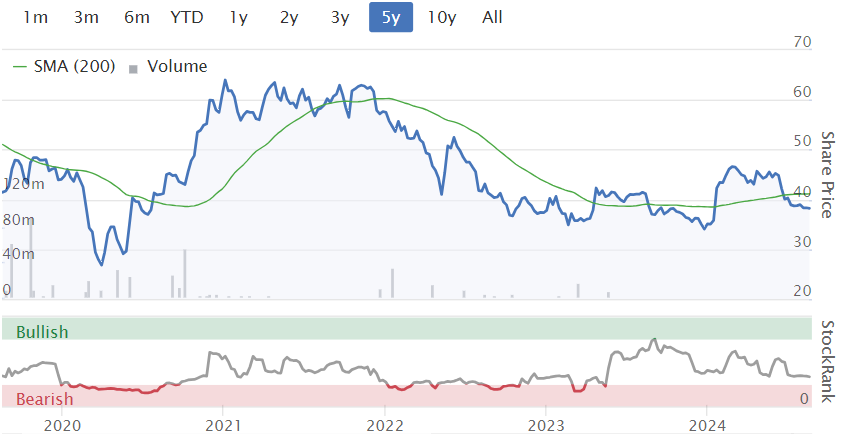
Calnex Solutions (LON:CLX)
Up 1% to 53p (£46m) - AGM Statement [in line] - Paul - AMBER
Calnex Solutions plc (AIM: CLX), a leading provider of test and measurement solutions for the global telecommunications and cloud computing markets…
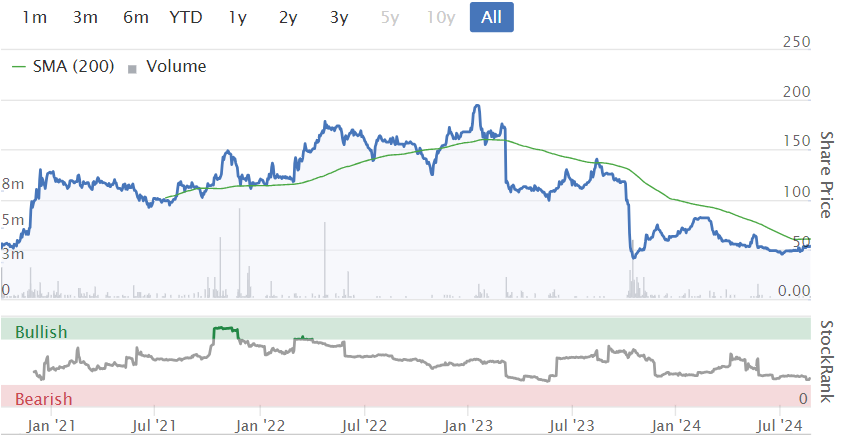
This warned on profits in Oct 2023. The chart seems to be bottoming out at around 50p. Graham and I were both AMBER when we previously looked at it. Calnex was previously a decently profitable growth company, but then performance crashed in FY 3/2024 to a small loss, vs a £7.2m profit in the previous year. So the question here is whether it can recover back to previous levels of profitability?
Outlook -
“As anticipated, the telecoms market has remained challenging throughout the first four months of FY25. While activity levels across the sector are generally expected to stay at subdued levels for the remainder of the year, the fundamental need for the Company's testing solutions remains strong. The Board is encouraged by the early successes of Calnex's new product launches, which are expected to underpin the Company's return to growth in H2 FY25.
Calnex continues to maintain tight cost control measures and benefit from a healthy balance sheet and the Board anticipates that the Company's performance in FY25 will be in line with market expectations.”
Cavendish leaves its forecasts unchanged today. This shows only a very slight recovery in profitability from £(0.4)m adj PBT actual in FY 3/2024, to £0.4m positive adj PBT in FY 3/2025. That doesn’t get me interested at all, especially as it seems to hinge on an H2 weighting from new products. Remember the market cap is £46m, which is a lot for a company that’s only now trading around breakeven.
The balance sheet is strong, with the 3/2024 situation being £13.2m NTAV, including net cash of £11.9m - although that fell considerably from £19.1m a year earlier, due to negative working capital movements and a large £(5.6)m of capitalised R&D (greater than the £4.1m amortisation charge, flattering profit by £1.5m compared with cashflow), so make sure you ignore the overstated EBITDA numbers.
Paul’s opinion - I wish them well, but there’s no sign yet of any significant trading recovery, and we’re being asked to pay too much for a company that’s only around breakeven on the P&L, and has negative cashflow. So for me it’s AMBER at best.
Ebiquity (LON:EBQ)
Down 30% to 26.5p (£36m) - Trading Update [profit warning] - Paul - BLACK / AMBER
Ebiquity plc ("Ebiquity" or the "Group"), a world leader in media investment analysis, announces a trading update for the first half year ended 30 June 2024 ahead of its interim results which will be issued on 26 September 2024.
H1 revenues down 7% to £37.9m, due to reduced demand from large customers. Fixed costs, so operational gearing is “acute”. Adj EBIT for H1 expected to be £2.3m, down 61% on H1 LY. Visibility over 80% of FY 12/2024 revenues. Depending on a big uplift in Q4. Net debt at 30 June was £15.3m, but plenty of liquidity - and year end net debt expected to be similar, peaking in Q3. Ample headroom on covenants. Expects “significant profits” in H2, underpinned by contractual visibility & pipeline. Acknowledges the execution risk. Warns that overall FY 12/2024 profit will be below previous expectations, but doesn’t say by how much. Sees Sept & Oct as “crucial months”. Panmures says likely FY 12/2024 outturn at EBIT level is £10-11m, vs previous £12.6m expectations, so not a disaster.
Paul’s view - looks an interesting business, worth doing some more research on it, for risk-tolerant investors. Everything hinges on whether you favour the heavily adjusted profits, or the statutory losses! Balance sheet looks stretched, with too much bank debt, and negative net tangible assets. The profit warning today and dependence on a big recovery in H2 makes this look like it might warn on profit again in H2, I worry. For those reasons I’m going to sit on the sidelines here with AMBER.
Paul’s Section:
James Latham (LON:LTHM)
1,355p (£272m) - AGM Statement - Paul - GREEN
This is a family-run distributor of timber products, fencing and such like.
It’s trading in line with expectations -
“Revenue for the first four months of the current financial year, namely 1 April to 31 July 2024 is £127m compared with £128m for the same period last year. Volumes are up 3.1% on the same period last year. Margins remain consistent with the second half of the previous year. Overheads and resulting profit are in line with market expectations.”
Outlook - sounds encouraging -
“Most of our customers remain busy and are more confident than at the same time last year.”
I was previously worried that the bumper profits made during the pandemic (when a boom in DIY collided with restricted supply chains) allowed Lathams to do a roaring trade temporarily, but would see profits return to normal. That’s pretty much what has happened, with EPS now looking more normal at c.100p -
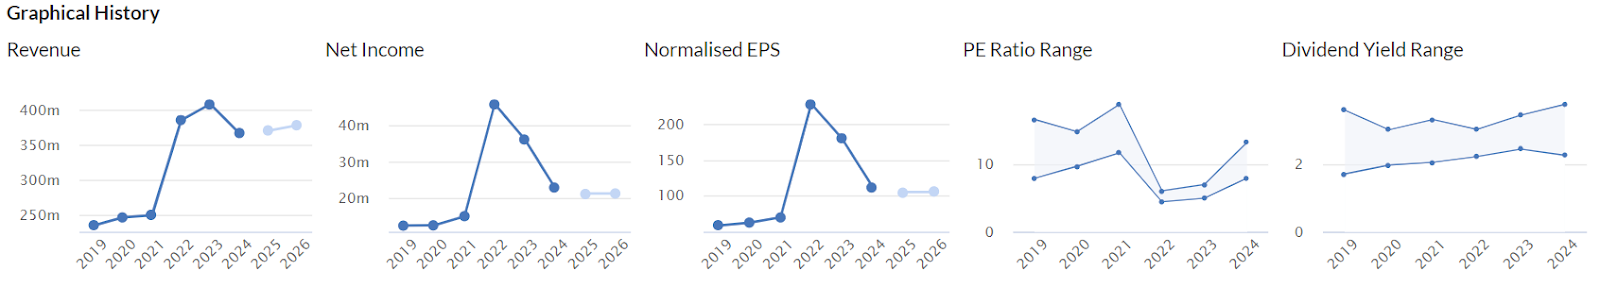
Stockopedia shows the forward PER as 12.8x, which looks reasonable to me.
Balance sheet - it says that “cash balances remain strong”. That’s something of an understatement! The last balance sheet at 31/3/2024 was astonishingly good. For example net current assets totaled £165m, including £76m cash!
Considering it operates from lots of depots, the lease liabilities struck me as modest, at only £8.7m. So it must have lots of freehold property, and it does. The last annual report shows £26m in freehold property, in the books at cost. Given that Lathams has been around for donkey’s years, what’s the betting that the market value of its freeholds is well above book value?
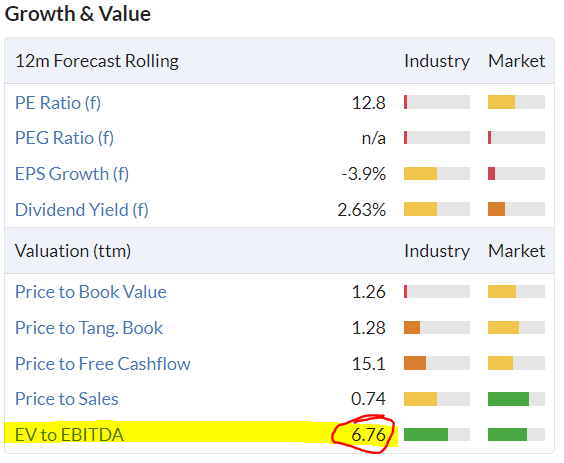
Calculating EV, the market cap is £272m, and net cash is £75m, so EV is £197m.
EBIT (FY 3/2024) was £26.1m, add back £4.3m depreciation & amortisation, giving EBITDA of £30.4m.
Hence EV/EBITDA is 6.5x (I could have just looked on the StockReport, which has a similar number!)
The cashflow statement shows that LTHM doesn’t spend a great deal on capex relative to its cash generation, so I would say this is quite high quality EBITDA, compared with say a software company capitalising a ton of its payroll costs, where EBITDA bears no relation to real world cash generation. Here at LTHM it does. So I think that’s quite an attractive valuation.
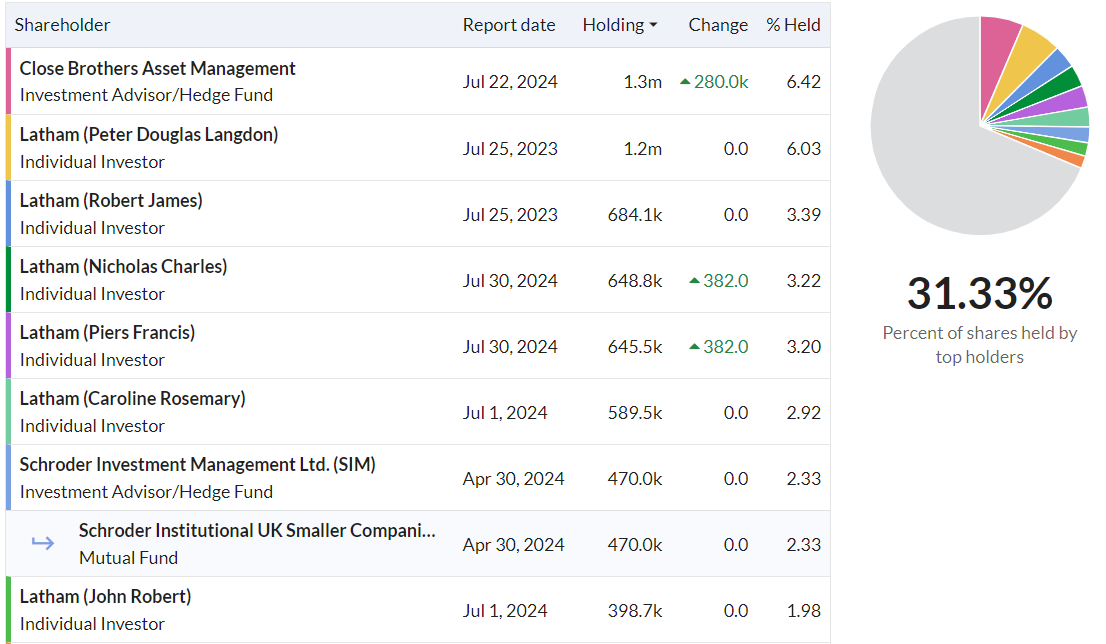
I imagine LTHM probably gets plenty of approaches from private equity, looking to strip out its cash and gear it up with debt, but the family probably tell them where to go I imagine, it’s that type of company. But you never know, at some stage maybe it might be sold, and the family shareholdings are not individually large, there could be more under 3% though -
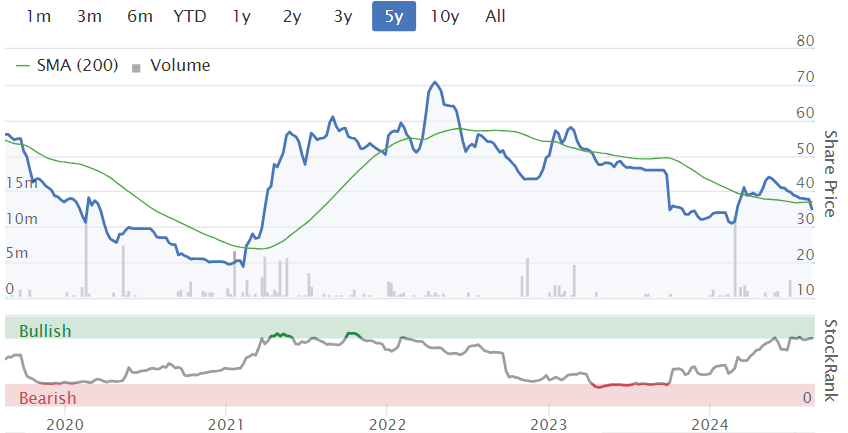
Paul’s opinion - I was green on 28/3/2024, and a fresh look at the numbers today reinforces my opinion.
It’s GREEN again.
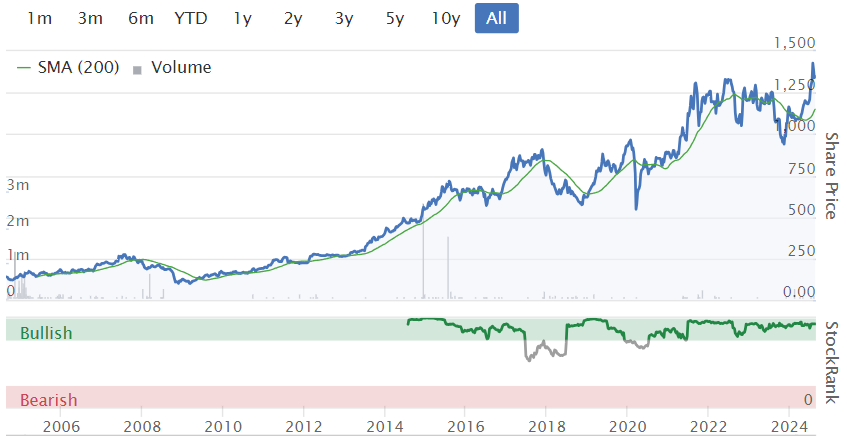
Zooming right out to 20 years, you can see what an excellent long-term investment Lathams has been (plus divis on top) -
Macfarlane (LON:MACF)
Down 5% to 114p (£182m) - H1 Results - Paul - GREEN
This Scottish-headquartered packaging group (mainly distribution, but also small amount of manufacturing) is one of our favourite value shares here, and it has a very good long-term track record if you zoom out on the chart - c.7-bagging in the last 12 years, whilst paying divis and self-funding bolt-on acquisitions.
It’s s struggled a little this year though. Checking my previous notes -
29/2/2024 - Paul - GREEN - 123p - Good FY 12/2023 results. Shares look good value.
7/5/2024 - Paul - GREEN - 131p - TU, weak Q1, expecting H2 recovery, so FY 12/2024 exps unch.
Today’s H1 results indicate a slight reduction in FY outlook -
“Resilient performance in the period; trading broadly in line for the full year”
The Chairman sounds sanguine -
“Aleen Gulvanessian, Chair of Macfarlane Group PLC, commented on the interim results: "As outlined in our AGM trading update in May, the challenging market conditions experienced in the latter part of 2023 have continued in 2024.
The management team has responded effectively through an improvement in new business growth, the management of price deflation and actions to control operating costs. In addition, the Group continues to execute its strategy, making two further high-quality acquisitions.
The strength of our balance sheet and the cash generative nature of our business underpins our ongoing investment in actions to grow sales both organically and through acquisition and increase the interim dividend.
Despite market headwinds, our operational and strategic performance is progressing, and the Group is well-positioned to benefit as the macroeconomic outlook improves."
Broker update - Shore Capital kindly gives us the detail, and it’s only slightly reduced FY 12/2024 estimated adj EPS by 2%, to 12.0p (down from 12.8p actual adj EPS achieved in FY 12/2023). Hence at 114p/share, the current year PER is 9.5x
H1 results - a little soft, but a 3% drop in adj PBT doesn’t unduly worry me -
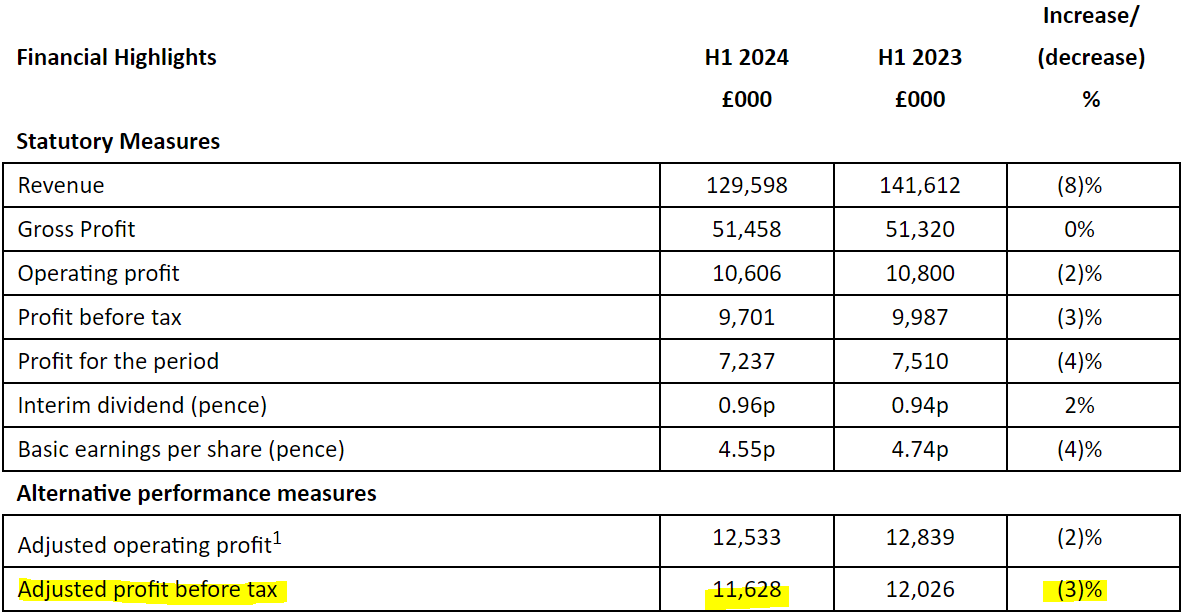
“Continued weak customer demand and price deflation have been partially offset by the benefit of the acquisitions of Gottlieb in April 2023 and Allpack Direct in March 2024.”
Outlook -
“The actions taken in H1 2024 and continuing through the remainder of the year should enable the performance of the Group to be broadly in line with market expectations for 2024.”
Balance sheet - NAV is £117m. Goodwill is £89m, so NTAV modest at £28m. That looks OK to me, as fixed assets at MACF are only £10m, so it doesn’t require much in the way of physical assets, being mainly a distributor. Inventories are also nice and low.
Note the £10m pension accounting surplus. It has 1 owned, and 52 leased sites, so possibly some inefficiency from so many depots, I wonder?
Bank debt is modest, and fully offset by cash, so it had net funds of £0.8m on 30 June 2024. The bank facility of £35m runs to 31/12/2025, and there’s ample liquidity.
Paul’s opinion - this looks fine to me, the fundamentals of the business remain good I think.
However, current trading is a little soft, but the 2% trim to estimated EPS today by Shore is not a concern to me. It’s such a small adjustment that I won’t flag it as a profit warning.
I think the value/GARP credentials here are good, and this is a fundamentally sound business. Therefore I’m inclined to see recent share price softness as more an opportunity for investors, rather than a threat.
I’m comfortable to stick at GREEN on the good long-term fundamentals. A slightly soft patch in current trading doesn’t alter the big picture that this is a good business, at a reasonable price.
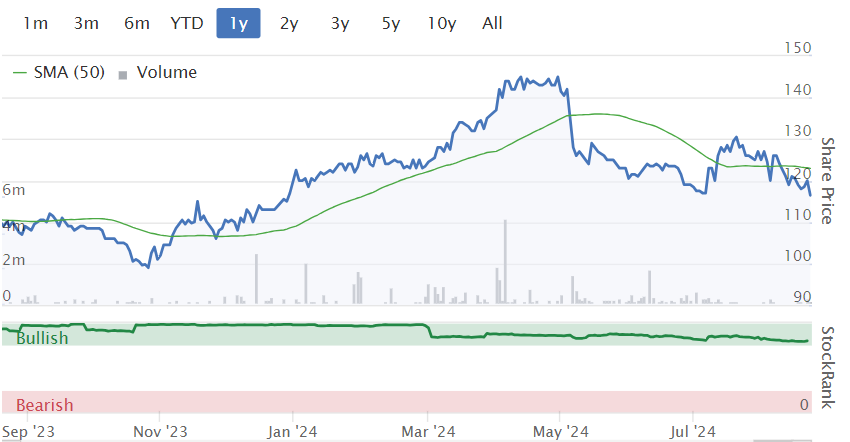
Good StockRank too, although it’s slipped a little as momentum declines -
Costain (LON:COST)
Up 7% to 101p (£281m) - H1 Results - Paul - GREEN
We like Costain here at the SCVR, a contracting group in several sectors (eg road, rail, energy, utilities). Our coverage this year being -
10/1/2024 - 67.8p - Paul - AMBER/GREEN - FY 12/2023 traded in line. Contract win in water. Y/e net cash above expectations at £164m. Quite interesting, PER only 5.4x. Note pension scheme. Paul doesn't like sector.
17/5/2024 - 81p - Paul - GREEN - In line TU. Very good cash position, and improving margins mean this looks to be headed for useful increases in EPS. Still looks cheap, providing nothing goes wrong, even after strong recent gains.
Now we’re up to 101p, is it still such good value? Let’s find out!
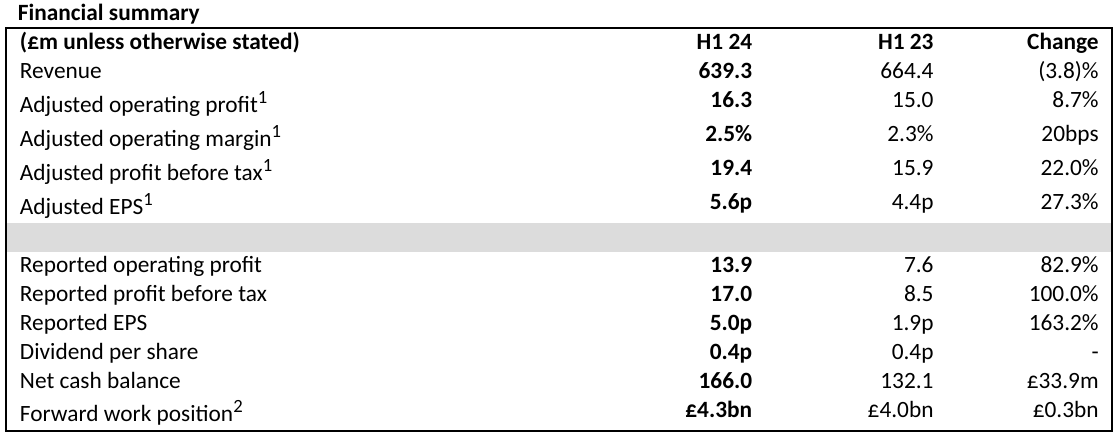
The wafer thin 2.5% operating margin above stands out as showing that COST is terribly busy doing a lot of work, for only a tiny scrap of profit.
However, this share is all about margin improvement, as mentioned here last time on 17/5/2024.
Note that PBT is above operating profit, due to interest received on the big cash balance.
This bit is key -
“On course to meet margin targets of 3.5% and 4.5% during FY 24 and FY 25 respectively. Adjusted operating margin1 increase of 20bps to 2.5% (H1 23: 2.3%), with margin growth in both divisions.”
Assuming that margin improvement is delivered, then it could result in operating profit almost doubling.
That doesn’t seem to be forecast in the FY 12/2025 broker consensus, which only shows a modest improvement on FY 12/2024 forecast, hence I’m thinking this share looks well set up to potentially beat the current forecast for 2025 -
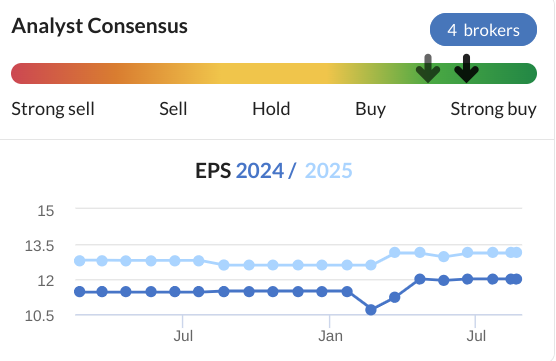
It did 5.6p actual in H1 2024, so 12.0p forecast EPS for FY 12/2024 sounds achievable.
Outlook excerpts -
“Having secured a significant volume of work in H1 24, our high-quality forward work position stood at £4.3 billion at the end of the first half, with at least a further £500 million of new work with Southern Water secured post period end and further wins expected in the second half. The quality and volume of our forward work gives us good visibility on future revenue and margin…
While we remain mindful of the macro-economic and geopolitical conditions and their importance for near-term government priorities and the timing of spending, we are well positioned for further cash generation and growth in profits [Paul: excellent clarity, and not the usual meaningless “profitable growth” we hear from other companies!]
We remain on track to deliver an adjusted operating margin run-rate of 3.5% during the course of FY 24 and 4.5% during the course of FY 25, in line with our ambition to deliver margins in excess of 5.0%.
Our expectations for FY 24 remain unchanged.”
Note that the higher margins it talks about are “run rate”, ie an improving trend, but the annual total will be lower.
On £1.2bn pa revenues, an operating margin of 5% in due course, maybe 2-3 years would imply operating profit of c.£60m, plus some interest income, hence maybe £6m, is £66m PBT, take off 25% corp tax, is £50m PAT, divided by 278m shares = 18.0 per share. Put that on a PER of 10, and I get to a valuation in several years time of 180p - nicely above the current price of 101p. Hence I see good further upside on this share, providing nothing goes wrong, and it is indeed able to achieve its target 5% margin. That may not be easy though, as presumably its contracts are won on competitive tenders, so if it keeps raising prices, the competition might undercut COST maybe?
Also as I always remind readers, in this low margin contracting sector, it’s only a matter of time before a contract goes wrong, with sometimes expensive cost over-runs, or remediation costs. Still, at least a 5% margin gives a better starting position for any future problems than the current 2.5%.
The share count is likely to fall, as a share buyback for £10m has just been announced, that’s about 3.6% of the existing shares.
Pension scheme - good news here -
“An assessment of the Scheme funding position was carried out on 31 March 2024 and, as the funding level (on a Technical Provisions basis) was more than 101%, contributions will stop from 1 July 2024 to 30 June 2025. These contributions would have amounted to £3.4m for the period if the Scheme funding level had been less than 101%.
In addition to contributions being stopped for a year, as the funding level is above 101%, "dividend parity" will be suspended for a year. Under the dividend parity arrangement, an additional matching contribution (the excess of the total dividend above the Scheme contribution) is paid to the Costain Pension Scheme when the total of the interim and final dividends (or other return of capital such as a buyback) is greater than the contributions paid into the Scheme in the previous Scheme financial year, which runs from 1 April to 31 March.”
Balance sheet - is excellent, as COST did a big equity raise during the pandemic. So it has surplus cash, which it is capable of returning to shareholders - hence the buyback, and also it means there’s substantial scope to increase divis, which are currently very stingy, for no apparent reason, at only 1.4% yield. I would work on the basis that divis are likely to substantially rise in the coming years, due to its strong, cash-rich balance sheet.
NAV is £230m. I’ll deduct £48m intangible assets and the £55m pension surplus, giving me NTAV of a nice healthy £127m.
H1 period end cash (and there’s no interest-bearing debt) was £166m.
I’d like all companies to disclose average daily cash. Although we can easily estimate it from the £3.5m H1 interest received on cash deposits shown in note 5. Annualise that to £7.0m, and I’ll estimate a 4% interest rate earned on cash, which implies average daily cash of c.£175m. That is very close to actual period end cash of £166m, so my reasonableness check suggests that the cash position is real, and not window-dressed to flatter the period end.
Cashflow statement - by the time you take into account lease costs and capex, there’s negligible remaining cash generated, only about £4m by my calculations, half of which was paid out in divis.
Paul’s opinion - I remain positive on Costain shares, and think there could be further upside if you’re patient and happy to wait a year or two.
I imagine broker forecasts are set low, and likely to be raised or beaten in 2025. Finances are very sound, with a really good, cash-rich balance sheet. Divis are mean, but with scope to be raised, and the share buyback of £10m announced today is equivalent to a one-off 3.6% dividend.
The downside risk is obvious sector risk of a contract going badly wrong, and being costly to remedy. I wouldn’t disregard that risk, no matter how good management are, these are large complex contracts and there will always be scope for human error either in the costings/bids, or execution.
Overall though I’m reassured by the numbers, and prospects, and remain positive, so it’s another GREEN from me!
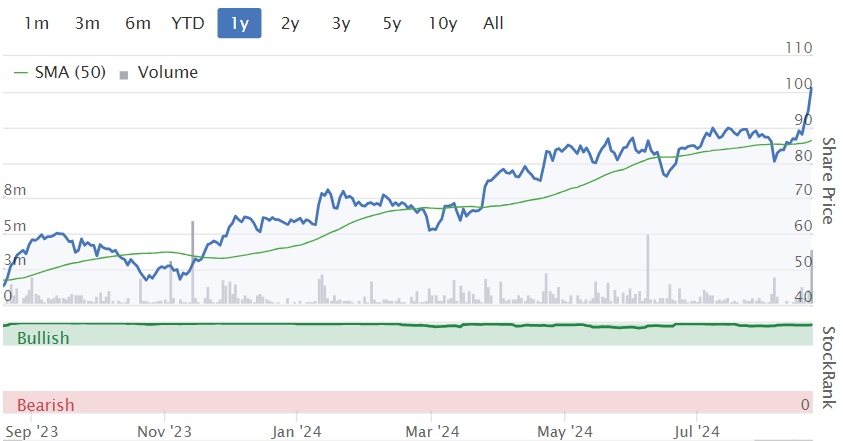
Excellent uptrend in the last year - and note the StockRank is jammed on maximum! -
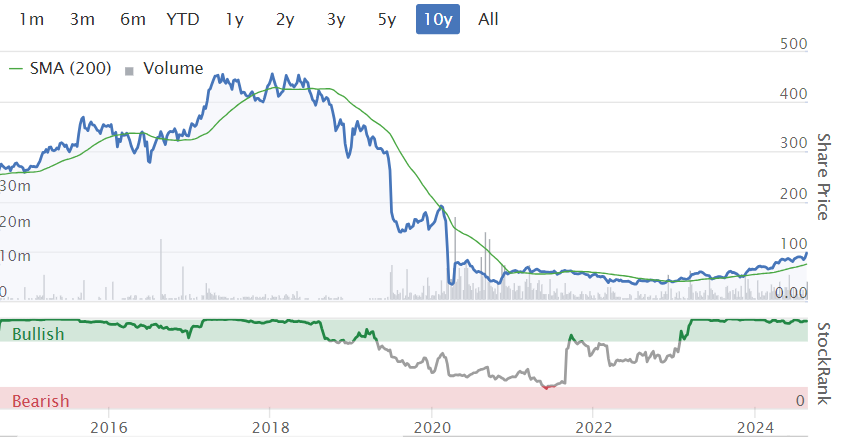
Although zoom out to 10 years, and COST has destroyed a lot of shareholder value, and the share count has more than doubled in the last few years, so 200p would be the new 400p in market cap terms -
Graham’s Section:
Nexxen International (LON:NEXN)
Up 5% to 302.8p (£411m / $539m) - Q2 and H1 2024 Results - Graham - AMBER
NEW YORK, August 22, 2024 -- Nexxen International Ltd. (AIM/NASDAQ: NEXN) ("Nexxen" or the "Company"), a global, flexible advertising technology platform with deep expertise in data and advanced TV, announced today its financial results for the three and six months ended June 30, 2024.
This company was previously known as “Tremor” with the ticker code TRMR.
Paul took a dim view of the company in August 2023 and was unimpressed by the announcement of a new $50m buyback in May.
It’s not a company that I’ve ever been too interested in: it’s an Israeli online tech/advertising company (in the same category as XL Media, for example) and rightly or wrongly I tend to assume that these will end badly for investors. But that’s just my bias - let’s see what Nexxen has to say in these results.
The first financial highlight today for H1 is:
Record H1 Contribution ex-TAC of $152.8 million, up 4% year-over-year
What does this mean? You’re welcome:
Contribution ex-TAC for Nexxen is defined as gross profit plus depreciation and amortization attributable to cost of revenues and cost of revenues (exclusive of depreciation and amortization) minus the Performance media cost (“traffic acquisition costs” or “TAC”). Performance media cost represents the costs of purchases of impressions from publishers on a cost-per-thousand impression basis in our non-core Performance activities.
First off, I don’t like the attempt to avoid counting depreciation and amortisation. What is special about Nexxen that means investors should ignore these?
Secondly, this definition strikes me as overly complicated. Is there not a simpler way to present gross profits or value-added than this?
Let’s continue. Other key points:
H1 adjusted EBITDA $38.7m, up 29% year-on-year. No other measure of profitability is given in the highlights.
$20m of shares repurchased, and new $50m buyback launched, as I mentioned above.
$100m of long-term debt repaid.
Net cash is $152m as of June 2024.
CEO comment:
"In the second quarter we generated record Q2 Contribution ex-TAC, programmatic revenue and CTV [GN note: Connected TV] revenue while increasing Adjusted EBITDA by 27% year-over-year, benefitting from increased momentum post-rebrand, better sales execution, scaling CTV partnerships and improved market conditions…
Our platform's differentiated products are enabling customers to maximize reach, returns and efficiency, while also generating growing multi-solution partnership traction with industry leaders. We are confident in our positioning to accelerate growth and long-term market share gains and are pleased to reaffirm our full year guidance."
Guidance is unchanged for the full-year:
“Contribution ex-TAC” of $340-345m (last year: $332m)
Adj. EBITDA c. $100m (last year: $83.2m).
These numbers imply a much stronger H2 than H1, which Nexxen says is anticipated thanks to “enhanced sales execution and recently launched partnerships scaling”.
Financial statements
I’m curious to see what numbers pass the accounting rules.
Firstly on the balance sheet: tangible equity is $173m.
There is a cash balance of $152m and a trade receivables balance of $189m.
That seems like quite a large amount of receivables - it’s more revenues than the company generated in the last six months.
On the income statement, the company makes an operating loss in H1, although it’s close to breakeven.
In H1 last year, it made an operating loss of $23m, despite very positive EBITDA.
In H1 this year and last year, finance expenses were higher than finance income, despite the company’s enormous cash balance.
On the cash flow statement, there is an impressive $59m income generated from operating activities. This was boosted to the tune of $23m by working capital movements, and boosted by $6m from the use of share-based compensation for employees.
Overall, I think these statements confirm that there are strange aspects to this company’s financial performance.
Graham’s view
I’m tempted to leave Paul’s AMBER/RED stance unchanged here. I could maybe be tempted to go for AMBER, on the basis that the numbers aren’t too bad. But I don’t fully trust what I’m reading from the company - it’s all too complicated and the questionable aspects of performance (e.g. the fact that it made an operating loss, and a pre-tax loss) are entirely glossed over.
The shares have performed strongly over the past year, and they have a StockRank of 97.
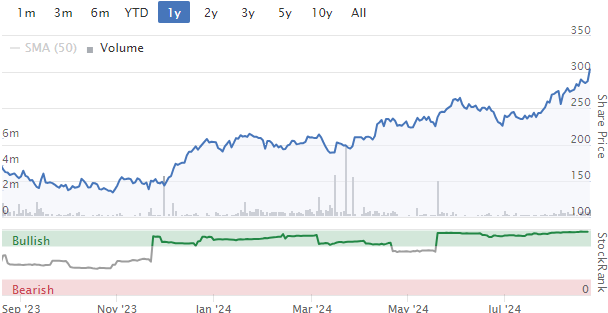
Since the share count is declining with the help of a buyback, I’m going to take an AMBER stance on this one today, as I think the buyback could help to propel this to even greater heights. But my instincts are that this stock is not a safe place to invest.
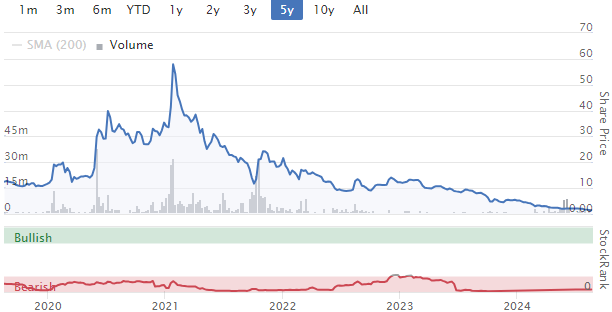
Proton Motor Power Systems (LON:PPS)
1.45p (pre-market) - Financing Update - Graham - RED
I’m sorry for anyone holding this hydrogen fuel cell company overnight, as it emerges that this company’s principal lender is no longer going to pour money into it.
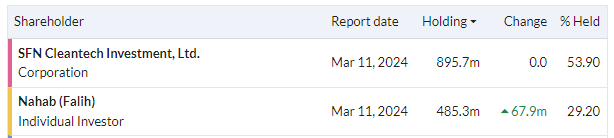
The principal lender is the second name on this list: a 29% shareholder who is the brother of the CEO.
The first name on this list is a company connected to the CEO that is also a major lender to PPS.
The two brothers therefore own or control over 80% of the company’s shares, are connected with the company’s debt financing, and one of them is the CEO.
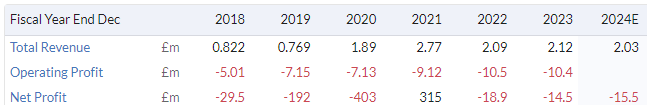
Financial results have been poor:
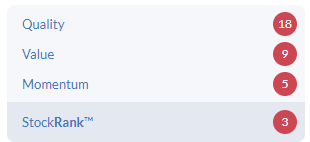
The company has a StockRank of 3:
The most recent annual report was replete with going concern warnings. For example:
Due to the continued losses incurred by the Group and lack of operational cash inflows, material uncertainty exists which may cast significant doubt upon the Group and the Company’s ability to continue as a going concern. The Directors firmly believe however that the Group and Company remain a going concern on the grounds that both SFN Cleantech Investment Ltd and Falih Nahab have continued to support both entities throughout recent years, as well as funding having been agreed by SFN Cleantech Investment Ltd and Falih Nahab for at least the next 12 months.
Paul briefly covered the stock in February this year, giving it a RED and observing that it had an “utterly bonkers balance sheet” and that “existing equity looks worthless to me”.
That is the context for today’s news:
Proton Motor Power Systems plc (AIM: PPS), the designer, developer and producer of electric hybrid systems with a zero-carbon footprint, announces that it has received notification from the Company's principal lender (the "Lender"), stating that the Company's working capital requirements will only be supported until 31 December 2024.
Amounts drawn from the Company’s principal lender were €110.4m as of the end of July, plus accrued interest of €37.8m.
Without any more money coming from the brothers, the company will need to find alternative sources of finance:
The Directors have been in discussions with other potential sources of finance and, in light of this new development, will accelerate those discussions in order that the business can continue as a going concern. Further announcements will be made in due course.
Graham’s view
I do not see why any other lender would want to get involved here.
PPS had an interest expense last year on its existing loans of over £6m, nearly three times its revenues.
And even if the existing lenders agreed not to receive any interest, I’m not convinced that PPS would be able to service any new loans in a sustainable manner.
So it will not be easy for the existing equity to survive here, even in the short-term. Do they have any chance of any equity fundraise?
In the long-term, the stock appears to be worthless due to the overhang of existing debt.
I can only hope that anyone holding this one was fully aware of the risk, and is prepared for their investment to become a zero.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Benchmark Holdings (LON:BMK) Q3 Results - Investor Presentation video (August 2024)
Trond Williksen, CEO, and Septima Maguire, CFO of Benchmark Holdings hosted an Investor Presentation following publication of their Q3 results for the three months ended 30 June 2024.
Watch the full presentation for more details on period highlights, which included a solid performance in Advanced Nutrition and Genetics, and the streamlining of Health towards Ectosan® Vet transition. Management provided a detailed update on operational performance per division, a Financial overview and an update on Outlook. Finally there was a Question & Answers session.
Abtan,
Macfarlane (LON:MACF)
“the latest acquisition (Polyformes Limited) took place in July
It's Operating Profit % over the last 2 years was 14% and 19% respectively based on the latest Annual Report (available on Companies House).”
The retired Chairman of Zotefoams (LON:ZTF) has just joined Macfarlane (LON:MACF) as a non executive director. Guess his experience with this type of packaging is what appealed to them? Maybe as it’s higher margin, it may be an area they might want to expand.
Somebody posted about this recently in a very good post. I think his name is illiswilligig or something like that.
Graham.
Edit!
Speak of the devil and he appears!!
See Marks comments below.
sorry I got your name wrong Mark :0
What is the matter with the Target Price data/%s on the Stocko individual company data sheets - if a thousand people haven't already mentioned this?
Thought it was my ipad!
Can someone tell me why the spanish lot who own 30% of PayPoint (LON:PAY) do not offer to buy the company? Or is this old news that I have missed
I hold
Can someone tell me why the spanish lot who own 30% of PayPoint (LON:PAY) do not offer to buy the company? Or is this old news that I have missed
The most compelling reason I have seen is that it is a blocking stake to prevent private equity swooping in and expanding PayPoint’s geographic reach. I would be interested to hear other theories.
PayPoint (LON:PAY) They are not obliged to as they only crossed the threshold by dint of the shares buy back so were deemed as innocent bystanders. See RNS on July 1st. I assume they don't want to buy the company.
The most compelling reason I have seen is that it is a blocking stake to prevent private equity swooping in and expanding PayPoint’s geographic reach
That doesn’t make sense to me when, if they are that impressed by the product, the far more profitable choice is to buy the whole company and enjoy the fruits of rolling its tech out across the globe
PayPoint (LON:PAY)
I understood that Asteriscos Patrimonial [the major shareholder of PayPoint] is a fund manager. Does someone have a different interpretation of the website? https://asteriscos.es/activos-financieros/
It is unusual for a fund manager to buy a whole company. I suppose they could be Private Equity but this is far from obvious.
N.B. The website is sparse and both Google Translate and I deal imperfectly with Spanish.
Astericos is a family office. The owner owns a business in Spain that does a similar product to PayPoint (LON:PAY) for convenience stores in Spain. Maybe other European countries too, I haven't dug that deep yet.
Hence the strategic "blocking" stake. Albeit that could also be have been achieved at 25%, without having to go to 30%...
BnB, BL,
I’m sure I saw a comment on ADVFN bulletin board (I know they’re not always reliable!) that said the Spanish holder is in the same sort of business as PayPoint (LON:PAY) and have bought the holding as a blocking move to protect their Spanish business, but don’t intend to take over PayPoint (LON:PAY) because they don’t have enough money/inclination to do that?
Graham.
When PayPoint (LON:PAY) first announced the buyback, they also said this:
"Following discussions between the Company and the Takeover Panel, the Takeover Panel has agreed that, under Rule 37.1 of the Takeover Code and the notes to that Rule, Asteriscos Patrimonial SL should be treated as an "innocent bystander" in relation to any increase in its holdings of Shares as a result of the buyback and will not therefore be required to make an offer under Rule 9 as a result of any increase in its holding caused by such a buyback."
I am completely with you on Benchmark Holdings (LON:BMK) , Paul. An unending stream of losses and excuses for years and yet they have been backed with additional funding by investors to make further acquisitions along the way. I think the market is seduced by the potential of genetics to improve livestock yields. There may possibly be some valuable ip within this business but I for one can't assess that very easily and certainly not with the confidence to put an enterprise value of 2x sales on such a serial lossmaker.
Watkin Jones (LON:WJG)
(I hold)
Following the various discussions in yesterday's SCVR, I note that there has been a further fall of 5.57% in the SP so far today, following on from what ended up as a 33% fall yesterday. I also note that Alan Giddins, none executive Chair has bought 157,000 shares today at 32.5p. Make of this what you will - but probably a meaningless gesture?
Late yesterday I put a few comments on yesterday's SCVR, but I doubt anyone here saw them, so I am posting them again below. Hopefully they could provoke anyone interested to dig further. In the meantime I am just holding, because they are either worth more than the current SP - or if not, then they might be history soon, although I am not suggesting that is the case!
**********************************************************************************************************
Unfortunately, the way this company has been communicating recently has (hopefully erroneously) reminded very much of Inland Homes, who went bust in Oct 2023. They always seemed to be winning contract after contract, but then went into liquidation in double quick time (all 20 group companies, I believe Secure Trust Bank had also lent them money,
----------------------------------------------------------------------------------------------
(In September 2023, Inland Homes, a property developer based in Bucks, appointed administrators and began selling off its assets. The company's collapse came after it admitted to breaching loan covenants with HSBC and Secure Bank Trust in February 2023, and said it expected to lose £90 million in 2022. Inland Homes also lost its CEO and the rest of its board in 2023. In October 2023, administrators FRP Advisory said they couldn't save any of the 20 companies in Inland Homes' group because there wasn't enough money to keep trading. They also said they had received expressions of interest in Inland Homes' assets, but couldn't predict when or how the assets would be sold. )
----------------------------------------------------------------------------------------------------
I have mistakenly held onto Watkin Jones through at least 3 profit warnings:
1)Fell 20% on 23/05/23.- bad trading report and big dividend cut - many orders delayed but not cancelled!
2) Fell 40% on 19/07/23.
3) THIS SHARE FELL ANOTHER 33% today (21/08/24) to 34,2P. Reduced profits forecast for Y/E 30/09/24 AND 30/09/25,
My note today : Too late to sell now - should fully recover eventually (famous last words),. Again buy no more until CERTAIN THE BOTTOM IS IN!
Good luck all here. Hopefully I am just paranoid,
-----------------------------------------------------------------------------------------------------------------------------------------------
Watkin Jones (LON:WJG)
I should have said I am a holder of both Watkin Jones (LON:WJG) and Secure Trust Bank (LON:STB) , and was a holder of Inland Homes (was INL).
------------------------------------------------------------------------------------------------------------------------------------------------
Yesterday 11:18 pm
Inland Homes website is still on the web, just as it was when it was wound up. IE promoting developments, extoling the virtues of the company etc etc, You would never know it isn't trading now!
YouGov (LON:YOU) did something similar lately the day after its big profit warning.I could have pretty much predicted the sell off today.Could be shorters, something tech nical, last stragglers selling, general sentiment and fear, not sure.
Same for me with the hold.Let's hope the management know what they're doing........! The non exec does have 880,000 shares now, which is still a fair whack of money, even if he might be worth millions (now idea just guessing..).If the sell off continues without further information and RNSs, i'm perhaps foolishly, buying more for a trade that will probably back fire!!Graham said there's a bunch of land assets backing up the marketcap.So unless they're not worth their true value?Valuation isn't exactly super stretched here either.I mean their forward guidance isn't exactly red hot either to be fair!
My feedback from students ( albeit local rather than national) is that Universities are currently under some pressure from a number of directions. ....
The effect is already being seen in a softening of demand.
If we then take for instance a a new PBSA such as 350 rooms there are multiple issues down the line. The first is the thorny issue of valuation. How do you value such a build. I would guess that it is valued as a multiple of income?
What happens therefore when say only 300 rooms are let to students? There is the loss of income and the valuation will probably also fall to reflect a more realistic rental.
All these risks are going forward and I can offer no reason Watkin Jones has apparently disappointed during the last few years when student demand has been robust. Investors need to ask some questions.
Watkin Jones (LON:WJG) Giddins has only been a buyer of shares as far as I can tell. This last purchase is ~ to his previous lowest buy, but so far it looks like he has made a loss on the total. Does sort of back-up Graham's view of AMBER/GREEN. I'm put off by the student side as universities are in trouble and struggling to get more high-paying foreign students so are lowering entrance requirements for this academic year.
Fm,
It was on national news today that the number of visas issued to overseas students is down. Can’t remember the figure but it may have been 25%. I immediately thought of Watkin Jones (LON:WJG) and their current problems and how this might compound those problems. I think overseas students have also been stoped from bringing family members over with them on visas (in order to reduce immigration) so this might also put international students off!
Graham.
You might not see this Mark Selby1 but I hope you do. Inland Homes was our biggest loss so far, I also found stupid reasons to hang on when it was clearly being mismanaged and will always regret that. We added to our mid size holding in WJG before the close at 31p, we now have an average holding price of 71p which will reduce to 63p when we buy more tomorrow. The non exec chair has 880,000 shares in WJG, I obviously hope it wasn't a meaningless gesture by him to buy the 157,000 this afternoon. We sold WJG shares at 240p several years ago for a good profit but bought back in far too soon at around 100p which I'm now hoping to make some sense of.
August UK Business Activity Grows
In August, UK private sector activity grew faster than expected, reaching its highest pace in four months. The S&P Global Flash UK PMI index rose to 53.4, indicating solid economic growth and helping the pound hit a 13-month high against the dollar. The report suggests stronger economic growth, improved job creation, and lower inflation, with the UK economy likely expanding at a rate of about 0.3% in the third quarter.
Input costs rose at their slowest rate since January 2021, and inflationary pressures in the services sector eased significantly. Official data showed services price growth fell from 5.7% in June to 5.2% in July, keeping headline inflation close to the Bank of England's 2% target. While this decline in inflation might not lead to another rate cut in September, economist Ashley Webb predicts that rates could drop from 5% to 4.5% by the end of the year.
August saw both the UK's manufacturing and services sectors grow strongly, with the services PMI hitting a 4-month high of 53.3 and manufacturing reaching a 26-month high of 52.5. Businesses reported better sales due to easing price pressures and lower borrowing costs, leading to the fastest job creation in 14 months. The UK's composite PMI of 53.4 outperformed the eurozone's 51.2, reflecting stronger economic growth in the UK during the first half of 2024. Economist Salomon Fiedler noted that the UK has been a "bright spot in Europe" this year.
Costain (LON:COST)
Paul points to the 10 year chart with the sp around 400p in 2018 pointing out that in terms of mcap now that is around 200p.
In May 2020 when the share count was 108m the company issued 167m new shares by way of a placing (80%) and p.o.o. (20%) at 60p. Had that been done as a rights issue the graph would have been adjusted retrospectively and 400p in 2018 would now show as 193.5p by my calculation.
[Compare International Consolidated Airlines SA (LON:IAG) who also raised money but via a rights issue in the Autumn of 2020. I sold my shares in Feb. 20 for 610p but the Stocko graph now shows them as 409p at that date. (Nostalgia - the second share I bought - early 1987!)]
MACF My own view, FWIW. I bought this in Nov 2021 at 139p, so I'm nursing a loss of around 17%.
ROE is around 15%, interest cover is good, the company has expanded well over the last few years, and its P/FCF is 6.1, EV/EBITDA is 6.4. It offers good value.
We've added to our holding of MACF several times Mark, we're on a small profit at today's price and it's now our 3rd most valuable holding. We're happy to hold, I hope we both find it a rewarding longer term investment.
I’ve been keeping an eye on MACF for a while now as I like that they are a specialist packaging business looking to operate in niche areas and therefore avoiding the volume commodity markets where price is everything.
I also like that they are also building the company by making not huge but useful bolt on acquisitions and appear to be ok at this, which to me is by no means easy.
Im a bit concerned by the size of the revenue reduction compared to last year and would be keen to understand what has driven this.
8 % strikes me as a pretty big number.They mention price deflation in the report quite a lot ( including in relation to new acquisitions) which suggests I might not be correct about my niche comment, in that it presumably means they do not have that much pricing power in competitive markets.
85% of the business is as a distributor , which will inevitably mean relatively low margins, and I guess this is what is putting me off investing for now.
Just my thoughts
Macfarlane (LON:MACF)
Hi Lochinver
The revenue decline was quite surprising for me as well.
I was, however, somewhat reassured that the £16m drop in revenue was accompanied by a decrease in PBT of only £0.3m.
I'm not going to fret over £0.3m in a weak economic environment, especially as PBT margins actually increased to 7.7% from 7.1% last year.
---
On a more positive note:
It's Operating Profit % over the last 2 years was 14% and 19% respectively based on the latest Annual Report (available on Companies House).
For context Macfarlane's OP% in the latest period was 8.4%.
i.e. this acquisition should be margin enhancing for the group and I'm expecting a boost in H2 to offset any organic weakness.
Very good points abtan, re MACF , many thanks for that
- it looks like they can effectively pass on price deflation to suppliers to maintain same pbt at lower revenue. A great strength.
- more margin enhancing acquisitions to gradually increase op margins , something they have a track record in delivering
I’m now more enthusiastic, thanks again !
Nice to see some good discussion of Macfarlane (LON:MACF) interims.
I think other companies have also reported soft conditions in the packaging industry? With worse numbers than Macfarlane?Revenue at -8% was better than the -9% flagged at the April AGM update. And the -2% operating profit, -3% PBT much better than I feared.
A quick look under the covers - or inside the packaging perhaps - at the numbers is revealing?
Despite the 11% fall in revenue to £111m distribution gross margin increased from 34.2% to 37.8%. And new business sales increased 10% yoy. Overall operating profit falls by a tiny 180k But selling bubblewrap is not much a receipe for price setting ability? Seems the product mix is shifting as management choose to exit lower margin business in favour of higher margin sales using their 'significant six' approach to improve value and service to customers. In the short term revenue growth suffers, Should prove to be a beneficial tailwind when market growth returns. Didn't I hear somewhere that the economy is about to start growing?
The smaller and higher margin manufacturing division has been growing both revenue and profits strongly. Not so much this period with revenue up 5.9% to £18.7m and gross margins flat at 50,5%. Rise in overheads by 700k more than cancels out the rise in gross profit - though the operating outcome is flat yoy - rescued by an adjustment to deferred consideration of 239k. Which does indicate a little fine tuning might be needed? I'd put my money on it being B&D -acquired in 2023 - the aerospace and defence sector can be quite lumpy from period to period - even though I think the trend will be strongly up in coming years. I also think there are likely to be useful synergies with the recently acquired Polyformes which I note was exhbibiting at Farnborough this year.
I'm reassured by these results. Management are usually cautious at the H1 stage. And Macfarlane (LON:MACF) has an established H2 weighting. At some point the market headwinds will reverse and become tailwinds. I just don't know when. In the meantime management is not waiting around and continuing to acquire quality businesses funded by the strong cashflow. For me the extremely capable management are the biggest attraction here. A rare ability to acquire businesses and create longterm organic growth. This has always been more about the journey than the destination for me, for the last couple of decades anyway. It remains one of my largest holdings and I'm looking forward to the next few years.
cheers
Mark
Bank of Georgia (LON:BGEO) nice set of results. Looks to me like they are capable of doing EPS of £12+ next year so not much more than a PER of 3. Given the extent of own funds, the buyback and dividend as well as the strong GDP growth in both Georgia and Armenia and despite the political unrest this just looks wrongly priced to me. Was surprised to see it down early doors but I see it has rebounded and is now up.
Talk about the value of compounding dividends - when I bought this it had a 3% yield and yet now pays me almost 30% on my original money.
Similar story for me and TBC Bank (LON:TBCG) which is of similar size to BGEO in Georgia and is pushing into Uzbekistan rather than Armenia...
Volex (LON:VLX) - not in the news today but another popular stock steaming back to its previous highs of over 400 achieved 3 years ago. Divi being paid next week. Those who chose the scrip divi rather than cash, doing well based on 351 against today's price of 370. Trouble is - not many platforms encourage taking scrip divi - too much trouble for them.
If it helps, I think the Halifax platform does this. Not sure if you can set each company differently, but maybe it will default for a single portfolio if you prefer reinvestment of divis. I know it does this for my ISA.
Dividend reinvestment - Hi Trident. I use Iweb, the low cost version of Halifax. They allow dividend reinvestment ie they use the dividends to buy you more shares, but I don't think they allow one to participate in a company run DRIP scheme.
Volex (LON:VLX)
I don't think that a PE of 15 is unreasonable in a stable market, provided of course that the company continues to trade in line with consensus. Forward earnings of 38.7 cents convert to around 29p. I think he FX $/£ will settle down, as both the Fed and Bank of England are likely to cut rates going forward. So a PE of 15 takes us to a fair price of 440p or thereabouts; far from unreasonable. Time will tell.
It is also somewhat reassuring that Nat Rothschild who holds over 25% of the company has never sold a share, although given his family's well I doubt that he needs to. An additional brownie point is that I have also found him and the management team to be shareholder friendly, especially towards retail investors.
Volex (LON:VLX) remains my largest position, hence a little crystal ball gazing.
Very pleased with volex over the last couple of years
They are now a pretty sizeable business with operations all round the world, which cannot be easy to manage, so they have done a very good job from what I can see.
Slightly concerned that Nat may be losing a bit of interest and focus on Volex though. I notice that he has taken on the chairmanship role at Tennor, an investment company with some big hitters involved. The FT quoted him as say something like he was going to devote all his time to this venture !
And he was previously being touted as a possible chairman at De La Rue
Volex (LON:VLX)
Instead of quoting the FT I suggest you listen to what Nat himself says about his role - the only Q at the AGM - hit the Q&A tab at:
https://www.investormeetcompan...
Fair comment sharw, but just to be clear, it wasnt myself who was quoting the FT. It was the FT quoting Nat at his unveiling dinner at Tennor on 25 July 2024 . Easy to google it.
Volex (LON:VLX)
Lochinver - yes, I wasn't criticising you (sorry if it came over that way). I realise it was quoting Nat and post your suggested google I find the article has him contradicting himself:
“I’m going to be devoting all of my time to this effort,” Rothschild told the gathered crowd.
11 paras later:
In Tennor’s statement, Rothschild said Volex, where he is also the largest shareholder, would remain his “primary focus”.
Ahh! Just realised Proton Motor Power Systems (LON:PPS) was Graham's write up. Apologies Graham for not adding you to my initial comments but equal praise to you!
No worries at all Kev. Thanks for the praise! G
Excellent write up of Proton Motor Power Systems (LON:PPS) Paul. Really useful to read a worked example of a share to avoid. Whilst we would all want to read about potential multibaggers all day long it is great to read the reasons behind the shares to avoid with one at the extreme end to highlight the points to look out for as well as how Stock ranks are a great starting point. Thank you for this, all of the other excellent analysis and of course, the entertaining and insightful podcasts - Brilliant!
Proton Motor Power Systems (LON:PPS) Seem to be involved in the same field as AFC Energy (LON:AFC) both should be avoided like the plague.
One way to outperform the market is to find the multibaggers.
Another way is to avoid the zeros (and -90%, -80%).
The latter looks easier to me than the former!
Chariot (LON:CHAR)
Once we are into late September, will fresh money come in for the anticpition of drill results? The share price is at one of its lowest points. When (and if) the fresh money comes, it's time to exit before the drill results. Market Makers seem to be onto this and opened the price at 7p today before it dropped again.
Timing is key with this play.
Why do you say, 'exit before the drill results' Chris? Do you know something about these already? I thought the prospects look pretty good here??
I suppose you've seen Malcy's wise words ? But is it worth a punt? ...
"These works will provide significant interest in the Anchois development and as the market seems to wait for proof of discovery and that Chariot are carried the chances are that the next few weeks are going to be as important in their history as anything I have ever seen anyway…"
Malcy?
Malcy's Blog About the Energy Market
Thanks
I have seen rumours that Malcy is paid by the companies he covers. Something he does not disclose, and which clearly impinges his impartiality.
The rumours may not be true, but it's something to consider.
Not at all. I just think there is a bit of money to be made for the anticipation of the drill results. I'm not a big gambler, so I'd like to be sold before the results with a bit of profit. But as I said, timing is key for this, and a bit of nerve.
In addition, as the share price is near its low, there can't be many people at all who intend to bail until (or if) it reaches 8p. Then the fun starts!
Those kind of o&g tend to attract folk who want a potential, quick profit on pre-drill hype or that's the hoped for trade for many.Helium One Global (LON:HE1) has already bagged and more again on drill hype for those who bought in post last placing.So i guess some might sell or go for a 'free ride' with their initial stake paid for by someone else and a risk free drill.I do remember Simon Thomson from IC mentioned Chariot (LON:CHAR) a couple of years ago i think..So i'm assuming it's not as risky as Helium One Global (LON:HE1).
interesting company, sadly gave up its interests in Namibia to early, if only
Ebiquity (LON:EBQ) - negative profits every year since 2018. It's a simple business: a people based agency/consultancy. Not quite sure why they can't properly price their services to cover costs.
Calnex Solutions (LON:CLX) still no improvement and the early mild sell-off is understandable in the light of recent strength. I was anticipating slightly better commentary given yesterday’s well-received TU from industry leader Keysight Technologies (NYQ:KEYS), in which I have a large stake. But that business is much better diversified, being well entrenched in data centre and semiconductor industries as well as telecoms, sectors that Calnex is only now trying to broach.
Nevertheless, I’m a buyer below 48p for the recovery potential so will be watching today with interest.
Thank you for your views on Costain (LON:COST) Paul. Having doubled in 12 months, I’m of the view it has scope to double again. While there is every chance a contract can go bad, the nature and diversity of the order book along with long term frameworks provides good mitigation and in a healthy infrastructure market, volume allows contractors to choose rather than desperately undercut each other. Once on a framework, competition is limited. AMP8 starts in April 2025 and runs for 5 years and Costain (LON:COST) are benefitting from their experience in the Water sector with I suspect more to come.
thanks Paul for the analysis on £COST. Re your comment on bombed out price if viewed over the past ten years - there must be an awful lot of such shares out there in this position - another reason perhaps why so many are being bought up
My morning smallcap tweet: Dance of the seven fails
Cambridge Cognition Holdings (LON:COG) Benchmark Holdings (LON:BMK) Macfarlane (LON:MACF) Proton Motor Power Systems (LON:PPS) Eckoh (LON:ECK) Neometals (LON:NMT) Bank of Georgia (LON:BGEO) Ebiquity (LON:EBQ) Mears (LON:MER), Calnex Solutions (LON:CLX)
◄Cambridge Cognition (COG)► H1-June rev down 7%. Pretax loss £1.1m (£3.4m). Outlook- "As a result of the actions taken during the year, combined with our clear growth strategy, we expect to deliver further success and value to our stakeholders". Further success? Last 2 years showed fall from profit to increasing losses! [SP=43.05 Cap=18m]
◄Benchmark (BMK)► Q3-June rev down 10%. YTD rev down 17%. Outlook - "Trading well against backdrop of market headwinds in Advanced Nutrition and the restructuring in Health which have an impact on short term performance but support near and long term prospects". Is this a warning? Throw me a frickin' fish bone here! [SP=38 Cap=281m]
◄Macfarlane (MACF)► guides FY-Dec only broadly in line with market expectations after H1 rev fell 8%. [SP=119.25 Cap=190m]
◄Proton Motor Power Systems (PPS)► principal lender will support co's working capital requirements only until 31 Dec. Will hasten its talks on other sources of finance. [SP=1.5 Cap=25m]
◄Eckoh (ECK)► response to recent SP rise: a highly conditional, non-binding revised indicative offer of 54p was received in July. [SP=48.53 Cap=141m]
◄Neometals (NMT)► strategy update: will sell non-core assets, shrink company and proritise the progression of Primobius. This is in response to falling battery materials prices and market sentiment. [SP=4.78 Cap=52m]
◄Bank of Georgia (BGEO)► share buyback. [SP=4320 Cap=1937m]
◄Ebiquity (EBQ)► warns FY-Dec profit below mgmt expectations after H1-June rev fell 7% pushing adj EBIT down 61% to £2.3m. [SP=37.5 Cap=52m]
◄Mears (MER)► £20m max share buyback. [SP=368.5 Cap=354m]
In line: CLX
Macfarlane (LON:MACF) disappointing update and a mild PW, full year to be only “broadly” in line. Recent weakness clearly justified. Memo to self: be patient.
Macfarlane (LON:MACF) I am a long term holder here and these figures are slightly disappointing. Just reviewed the Shore Capital note and they have £18.3m of FCF for FY24, which on a market cap of £192m is 9.5% - good enough for me. They seem canny operators and if they can continue to build the business by acquiring at low multiples, I'll continue to be patient here too.
Eckoh (LON:ECK) Eckoh PLC - Discussions with Private Equity Investor
Today the Board can confirm that, following a period of discussions and negotiations with multiple parties regarding a potential sale of the Company since May 2024, the Company received on 12th July 2024 a highly conditional, non-binding revised indicative offer from a private equity investor (the "Potential Offeror") of 54p per Eckoh share. Discussions with other parties remain ongoing.
It is important to note that while due diligence is progressing, there can be no certainty at this time whether any offer will be made, nor as to the terms of any such offer.
What are people’s thoughts on JD Sports Fashion (LON:JD.) numbers, starting to look like a bargain now?
What are people’s thoughts on JD Sports Fashion (LON:JD.)
As a holder, I tend to agree it looks good and I was content with today’s update. It’s priced as an ex-growth retailer, which, if you look at the last two complete years and this year’s forecast, is actually justifiable. But zoom out on the chart and look both at history and the medium range forecasts, and the multiple looks plain wrong. Nevertheless the market can react somewhat unpredictably to JD’s TUs so don’t assume the turning point has come yet, although I would load up on a big fall today if I hadn’t done previously already.
Like BnB I was pleasantly surprised by its results. JD Sports Fashion (LON:JD.) I see this as a longer-term holding, but was pleased with its improved numbers - whilst also highlighting the macro-risks. Maintaining its forecasts is a solid start and I would hope to see things continue in this vain over the next 6-12mths.
The Hibbett acquisition should open up further opportunities as well. Hopefully a positive reaction from the market. I hold.
JD Sports
Contrarian view
I dont rate it.
Falling tode industry as the generation realises the gloval sourcing of shiny stupidly priced trainers is a fugazzi of commercialism that is not fit for purpose .
Route 1 a chain of skate shops have taken a drastic nove in only selling 2nd life garmebts recycled and repurposed .
In kelham island alone within 1 mile of my warehouse teo credible , bold and driven brands havr popped up working on reworking 2nd llifd garments .
Billy Eiilidh didnt wear shiny nee trainers she eore a hat be Atelier (onr of those companies)
Im on holiday abd yesyerday my 17 year old son didbt ask to go to JD Sports but to the charity shop in markethill whete he bought a 1980s. Umbro track top .
Thiz is l happening , make no mistake and JD are going to be exposed to long term falling demand .
Its a decent company selling highly commecial chinese made branded items they market and sell to our youth for over inflated profits .
Its a fugazzi and the wind of change is coming slowly but surely .
Fat finger or time for a new keyboard? I think I might agree with some of what you are saying but I can’t be certain of what you said.
planetx language Lord Gnome, he took a brick to Ramsden's dirty window a few days ago and included H&T too, it's JD Sports turn today. I generally agree with him.
Agreed JASVFS about planetx's down-to-earthiness, also the reason why I won't buy a smartphone and have to stay close to my landline broadband desktop pc.
Holiday phone syndrome??
A combination of dyslexia., not got my glasses here, typing on a phone and half asleep .
Im sure you got the drift .
JD Sports (updated for those that cant read nonsense)
Contrarian view
I dont rate it.
Falling tide industry as the generation realises the global sourcing of shiny stupidly priced trainers is a fugazi of commercialism that is not fit for purpose .
Route 1 a chain of skate shops have taken a drastic nove in only selling 2nd life garmebts recycled and repurposed .
In kelham island alone within 1 mile of my warehouse two credible , bold and driven brands have popped up working on reworking 2nd life garments .
Billy Eilish did not wear shiny nee trainers she wore a hat made be Atelier (one of those companies) out of repurposed fabric .
Im on holiday and yesterday my 17 year old son did not ask to go to JD Sports but to the charity shop in Markethill where he bought a 1980s. Umbro track top .
This is l happening , make no mistake and JD are going to be exposed to long term falling demand .
Its a decent company selling highly commecial chinese made branded items they market and sell to our youth for over inflated profits .
Its a fugazzi and the wind of change is coming slowly but surely .
Interesting to hear the contrarian view. I live in a fairly gritty regional market town and a good proportion of the kids round here are still wearing the sort of tracksuits and trainers you'd get from JD. Go into Exeter and the students are dressing in baggier, more vintage looking stuff.
Reminds me a bit of grunge in the 90s, might this just be a product of no big rap stars on the level of an Eminem or 50 Cent? That was always the logic behind sportwear- rappers wear it, then suburban white kids copy the look. I suppose the tracksuit wearing kids in my town are still listening to Stormzy, Skepta and the like rather than Billie Eilish... what's coming out of their portable speakers sounds like grime to my relatively untrained ear.
Just look at how competition has finally caught up with Nike. Asics, Puma, Reebok (acquired I know) Brooks, Mizuno, New Balance, Salomon, Under Armour never quite tackled the Nike/Adidas global ubiquity head on despite success in certain niches....but the likes of Hoka and On do seem to be gaining mass market adoption.
There is no shortage of supply and the big brands are selling for $200 what they can make for $20.....I'm not sure flogging trainers and sports gear is much different to selling denim these days.
It becomes a branding exercise, and Burberry demonstrates that is a more difficult game than it may first appear.
IMO, as well as the likes of Hoka have done in making inroads into the running shoe market a lot of Nike's pain is self-inflicted. They've systematically gutted their channel network due to a myopic focus on their own (uninspiring) online platform- this is actually a good thing for JD Sports Fashion (LON:JD.) who are firmly "inside the tent", especially post-Hibbett acquisition (City Gear even has a joint branded app/loyalty program with Nike).
It's also been a while since their last memorable silhouette, and I'd speculate that now, for example, they have to sell to a demographic that wasn't even born when Michael Jordan won his last NBA championship the value of the brand is actually eroding with time.
Bill Ackman just took a position in Nike (NYQ:NKE) which moved the needle a few percentage points pre market.Here's hoping he does better than he did in his notorious Herbalife (NYQ:HLF) battle with Carl ICahn.Although admittedly he says he has firmly sworn off short selling now.And he has done rather well with burritos, Chipotle Mexican Grill (NYQ:CMG, buying during/soon after the EColi issues.It'll be interesting to see if/how/when they recover.I notice Lululemon Athletica (NSQ:LULU) 's share price, a big fashion winner over the last few years, has taken a bit of a hit recently too.I wonder if well off, younger urban women are wearing less super expensive workout gear as everyday leisure wear?Some of the trendy kids definitely are into the whole Friends 90's look and Abercrombie & Fitch Co (NYQ:ANF) smart new management, coupled with new digital initiaives, have really benefited the last couple of years.
I expect Ackman will agitate for a new CEO at Nike with more direct industry experience. Fundamentally still a decent business which has lost its way a bit and US investors have lost faith in management. Price dictating narrative a bit here, IMO- don't remember many critics when the p/e was up in the high 30s...
Similar story to Starbucks (another one Ackman has owned) where the shares popped by 20% on news that they'd brought the Chipotle guy on board.
I picked up a few shares in Lululemon Athletica (NSQ:LULU) at the end of last month- I'm not sure how durable the brand really is (not clear that they have the design IP that Nike does, for example) but a mid-teens forward p/e on a growing business with 20% operating margins and a couple of billion in cash on the balance sheet looks like a decent medium term idea.
Just look at how competition has finally caught up with Nike. Asics, Puma, Reebok (acquired I know) Brooks, Mizuno, New Balance, Salomon, Under Armour never quite tackled the Nike/Adidas global ubiquity head on despite success in certain niches....but the likes of Hoka and On do seem to be gaining mass market adoption.
That’s why I like JD Sports Fashion (LON:JD.) as an omni-brand door into athleisure. Acknowledging that the big 2 remain key suppliers.
Whilst I agree to some extent that this is a trend, this isn't the same crowd that would ever set foot in JD Sports anyway, whether it be 5 years ago or today. The acquisitions in the US are key imo to the growth story, there is still a very big thing around buying and collecting trainers which isn't as big thing as it is in the UK.
It’s a well established trend for middle class kids to be sporting vintage and second hand gear while the masses pile up new shinies from the big brands. My daughter chose to wear a ghastly second hand ski suit on her ski season instead of the more fashionable outfit, which I stress she chose, that I bought her as a “well done” on her A-levels. And that was 7 years ago. This trend has been going a while and I’m swimming in it here in Hebden Bridge!! But I see less evidence of it extending beyond the well-heeled woke set as yet.
Thats what i thought
But when I heard a fairly decent chain like Route 1 had changed policy I woke up.
The momentum is there and not sure “the masses” are as blind to this as you imply .(not my choice of word by the way).
It always takes a while for things to filter through.
Hebden bridge will be a fairly cutting edge melting pot due to its bohemian mix of eclectic individuals . And of course famed for being “trouser town” back in the day .
My friend Brant and old designer at on-one started Hebtro Co a few years ago.
They only use made in UK production and used the last factory in Hebden Bridge to make their first production (its now closed)
Retailers are doing surprisingly well and multiples are very stretched by historical comparisons in my view but because of the wider market and the fact they are holding or increasing guidance and beating expectations
TJX and Next are two other examples
At some point the growth will go but not seeing it yet
I think next are an exception
Brilliantly well run business offering lots of own brands with a clear commercial advantage and not a reseller of third party brands .
Next deserves its premium rating .
Planetx - I showed my daughter the Atelier site. She said that the designer should get in touch with a person called 'Yung Blud', a British musician who dresses in a similar fashion and their target audience might be similar.