Small Cap Value Report (Thu 23 April 2020) - LGRS, SDI, G4M

Good morning, it's Paul here with the SCVR for Thursday.
I finished off yesterday's report last night, with a new section on BooHoo, which is here. What a fantastic business that is. Although on current trading, the company should have just given the figures, instead of ambiguous narrative. Numbers in a table is always the best way of conveying information. If vague or ambiguous language is used, then my conclusion is that the PR is probably trying to hide something unfavourable from us.
Estimated timings - I should have a decent amount up by the 1pm email deadline, but intend continuing until about 3pm. Update at 15:09 - oh dear, I've only managed to get through 3 of the 9 companies I wanted to cover today. I'll keep going until whenever. Today's report is now finished. Most of the companies I didn't get round to looking at are now in tomorrow's report here.
Loungers (LON:LGRS)
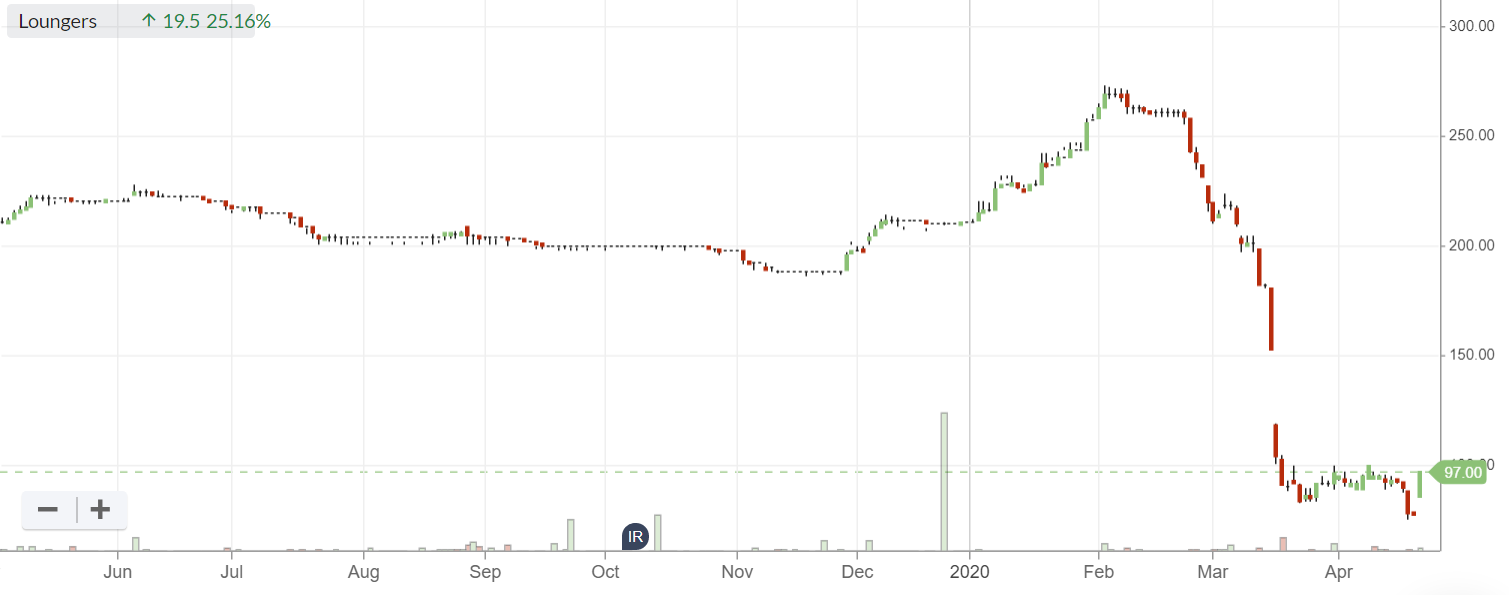
Share price: 95p (up 23% today)
No. shares: 92.5m + 9.25m new shares = 101.8m
Market cap: £96.7m
Extension of bank facilities and placing
Loungers - the operator of 167 café/bar/restaurants across England and Wales under the Lounge and Cosy Club brands - today provides an update on the actions it is taking in response to the Covid-19 crisis.
This RNS came out after market close last night. It joins the rapidly growing list of companies which need to refinance, because nobody thought of the possibility of a pandemic. The business models of entire sectors were completely wrong, for decades, with a huge risk lying dormant, we just didn't realise it. Once Covid-19 is over, I wonder how long it will be for this lesson to be forgotten again? 5-10 years, at a guess!
Loungers floated in April 2019. I reviewed the IPO document in quite a bit of detail in a video here. Although I made a mistake, in miscalculating the debt, therefore my main conclusion of it being over-geared, was (partially) wrong. Doh! Although the main purpose of the video was to demonstrate how you don't need to spend half a day wading through an admission document, but can actually skip a lot of it, and focus on the most important bits, in about an hour. Time well spent, if you're about to buy thousands of pounds-worth of shares in any company. Admission documents are usually on the investor relations section of AIM companies' websites, so I try to always have a look at them, even if they're a few years old. There could well be important disclosures in them, that shed light on the business, in a way which is never done again.
Actions taken - by Loungers, in response to Covid-19, sound very similar to what Revolution Bars (LON:RBG) (in which I have a long position) recently reported, namely;
- 99% of staff furloughed under Govt scheme
- All capex & "non-discretionary" spending paused. Surely they mean discretionary, not non-discretionary? That looks like a typo to me
- Negotiating with landlords & other creditors
- VAT & business rates deferral schemes being used
- Directors taking a 20% pay cut, and 30% pay deferral whilst sites are closed
Cash burn - weekly cash burn (on full rents) has reduced to only £480k. That is 20% more than Revolution Bars recently reported for its weekly cash burn of £0.4m. Loungers turnover is about 21% more than Rev Bars, so the cash burn figures are almost exactly in line with each other.
Bank facilities - increased bank borrowings are partially linked to an equity raise being undertaken - sensible risk-sharing to my mind;
As at 17 April 2020, the Company had £4.1m of cash on its balance sheet, undrawn facilities of £3.0m and net debt of £35.4m.
Loungers is pleased to announce that its current lending banks, Santander and Bank of Ireland, have agreed to provide an incremental £15.0m revolving credit facility for an 18 month period (the "New Facilities").
£10.0m of the New Facilities can be drawn immediately and a further £5.0m can be drawn conditional upon the Company raising equity funding of at least that amount.
Covenant tests at 12 July 2020 and 4 October 2020 have been waived and subsequent quarterly tests to 3 October 2021 have been re-set.
That sounds comprehensive, and should buy the company time to get through this lockdown.
I particularly like this very clear statement on how the company is now set up to survive even an extended lockdown. All companies need to issue this kind of statement, so that investors can correctly assess risk;
The Board believes that the net proceeds of the Placing, having utilised both of the above authorities, and when combined with the New Facilities, will provide the Company with sufficient capital to best manage through the Covid-19 crisis, particularly in the event of a protracted period before the Government allows hospitality businesses to re-open, and to subsequently recommence its roll-out.
Assuming completion of the Placing, the Board estimates that the Company will have available funds of approximately £31.0m which, if the Company's sites remained closed and including a forecast working capital unwind of £9.0m, would equate to approximately 46 weeks' liquidity at the cash burn rate set out above.
When will lockdown end? - this is the crucial question. Nobody knows, is the only answer right now. I see the Chief Medical Officer is talking about lockdown being required until the end of 2020. That's pie in the sky in my view, because the economic pain would be far too severe to tolerate such a draconian measure. Remember, the economy is people, not just numbers on a spreadsheet or on a bank statement. We're talking about extended lockdown ruining the lives of millions of people. It's just not an option.
The solution is obviously a vaccine, and/or drugs to treat the condition, and make it survivable for everyone. If such a breakthrough were to be announced, then shares like Loungers would probably double, or more, instantly, as business would return to normal quite quickly.
For what it's worth, which is not much because it's only one person's opinion (subject to change as the facts change), then my view is we're probably going to see lockdown eased in phases, quite soon (May/June maybe?). The reason being that the UK Govt seems to be bending with the wind, and just following what other European countries are doing. Macron is today reported to be mooting allowing France's cafe/bar/restaurants to re-open in May. That would be unusually early, and is very positive for UK cafe/bar/restaurants, which would probably be allowed to re-open once that is happening in other countries.
The nightmare scenario is that cafe/bar/restaurants are allowed to re-open, and a second wave of Covid-19 sweeps through the population all over again. Apparently that's what happened with Spanish Flu, a hundred years ago. In that case, I think many hospitality and retail sector businesses that survived the first wave, would close their doors for the last time.
It's all up in the air. If we don't get a vaccine or other effective drug treatment, then I think herd immunity (whilst protecting the vulnerable properly) would be the only viable option. Statistically, the risk to life from Covid-19 for fit & healthy, normal weight, working age people, is tiny. At some point, Govt policy will need to reflect that reality. Although every death is a tragedy for family & friends. We just had another death in my family last night, rest in peace Jack. He was 83, with dementia. Covid-19 has worked its way through his care home, and killed about half the clients there already. Nature/God is certainly demonstrating well its ruthless and brutal side, by mercilessly killing off the old and vulnerable.
Bottom line, is that investors in the hospitality sector are taking a considerable risk. If I'm wrong that lockdown could be eased for bars by this summer, then my largest position (in Revolution Bars) could go disastrously wrong. That's a risk I've weighed up, and accept, since I think the upside is much larger than the downside. Time will tell if buying a big stake there was a stroke of genius, or an act of madness!
Loungers has given itself more headroom than Rev Bars, because it's raised enough equity/debt to survive well into 2021. Whereas Rev Bars only increased bank facilities until Aug/Sept, so is on more of a tightrope.
Result of placing - another RNS out this morning.
Number of new shares: 9,250,000 (10% dilution of existing holders - perfectly reasonable in the circumstances)
Price: 90p (this is a very strong result -a premium of 16.1%)
Proceeds: £8.3m gross, £8.1m net of fees
Brokers: Peel Hunt & Liberum (who have done several other successful fundraises lately, they seem to be the dream team!)
Directors: are subscribing for 822,787 shares, a healthy 8.9% of the total being issued. Lion Capital (former VC owner) is subscribing for 3m shares. Therefore related parties in total are taking up about 41% of the new shares. Perhaps this is why they managed to get a premium price for the placing - because only a small amount of new shares are being issued to outsiders, and the insiders are motivated to protect the value of their existing shareholdings, hence going for a premium price for the placing. That's my theory anyway!
My opinion - the sector expert I consult on the hospitality sector, has always told me that Loungers are very good operators, better than most of the competition, hence worth backing.
Today's fundraising has dramatically reduced the risk for investors, hence I would certainly consider buying some shares in this company, if I didn't already have far too much exposure to the sector. I see this as a lower risk way of doubling or tripling our money, if Covid-19 is defeated, and normal business can resume. It now has headroom well into 2021, which I imagine should be sufficient. We can't hide away from this virus forever. At some point life has to return to normal, and we have to live with the risk.
The main problem with Loungers shares, is that liquidity is terrible. It barely trades anything most days. This is the problem with brokers that float companies shares to institutions - there's no after-market. The City needs to address this issue with new floats. There has to be some mechanism to distribute shares to private investors, thereby creating a liquid after-market. Otherwise, what's the point in acquiring a listing?
.
.
Sdi (LON:SDI)
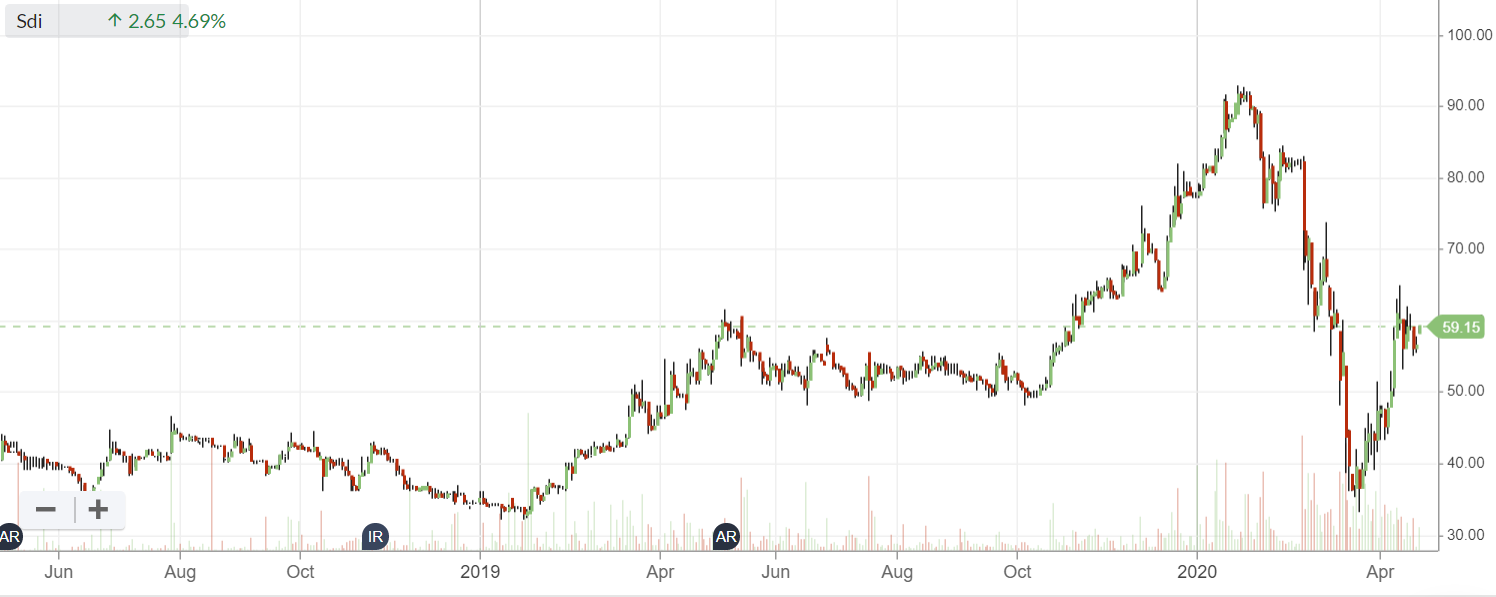
Share price: 60.5p (up 7% today)
No. shares: 97.5m
Market cap: £59.0m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing control applications, is pleased to announce an update on trading for the year ending 30 April 2020, and on the impact of COVID-19 on SDI's operations.
Summary of general points;
- Continuing to operate from its 8 UK sites
- Reduced costs & using Govt schemes where appropriate. 19% of staff furloughed - so they must be expecting a reduction in orders/output
- Conserving cash
.
Expected results for FY 04/2020 -
The Group continues to expect to meet market profit expectations for the year ending 30 April 2020, with sales of around £24 million.
A broker update note today gives EPS of 3.6p, for a PER of 16.8 - but that's likely to be peak earnings for some time, hence doesn't look cheap to me.
Cash & liquidity - this doesn't sound very safe to me, with bank facilities almost fully drawn down, hence not a lot of headroom if things turn really ugly -
SDI has a strong balance sheet with current cash in excess of £4.5m, unused debt facilities of £0.6m and bank debt of £8.9m. The Group has a good long-term relationship with its bank and has agreed, as a precautionary measure, a capital repayment holiday of three months of its revolving credit facility. The Group has also taken advantage of the UK Government's scheme allowing a temporary VAT payment deferral.
Current trading - not great, but not disastrous either at this stage -
...However due to COVID-19 SDI withdraws market guidance for the year to 30 April 2021. There has been some disruption to supply and some slow-down in orders, but SDI currently has all factories in operation and has so far remained both profitable and cash generative. At least four of our production units are providing their customers with components for medical and scientific products used in the fight against COVID-19.
Balance sheet - it's not strong, it's just OK.
When last reported as at 31 Oct 2019, NTAV was modest, at £1.7m.
In my view, management should take advantage of the share price strength, and do a placing of about 10% dilution, which probably wouldn't upset anyone, and would raise almost £6m to strengthen the balance sheet. That's simple, but sensible advice to the company. I don't charge any fees! Good quality companies like this, are not having any trouble raising fresh equity at the moment, and it could avert a future crisis if Covid-19 pans out worse than expected.
My opinion - given the uncertainty, withdrawal of guidance, and not much headroom in terms of liquidity, I'm quite surprised the share price has remained so resilient.
In the current, potentially dire circumstances, I think this looks over-priced for the time being. Am happy to look at it again, once the dust has settled. By looking through Covid-19 and pricing things for recovery, I think the market is possibly under-estimating the economic damage that is starting to occur. But everyone has their own opinion on that, and obviously alternative views are equally valid. I cannot see the sense in paying a fairly full price for a business at peak earnings, when a potentially very severe recession is just starting.
Don't get me wrong, it's a nice little group of businesses, and seems well managed. I'm just questioning the valuation, given how uncertain the outlook seems.
.
Gear4Music
Share price: 275p (up 10% today)
No. shares: 20.95m
Market cap: £57.6m
(at the time of writing, I hold a long position in this share)
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces a year-end trading update covering the 12 months to 31 March 2020.
As you can see below, G4M has fully recovered from the recent indiscriminate sell-off. Another reminder (after BOO yesterday) that some online businesses are coming into their own in the lockdown, with conventional competition stifled. Maybe Covid-19 might be accelerating previous trends, towards more commerce being done online, more people working from home, less travel, more video-conferencing, etc.? Or will things return to previous norms, once this crisis is over? Answers on a postcard please!
As you can see from the 2-year chart below, the company disappointed previously, as its operating margin fell to essentially nothing, as it chased market share. The strategy was more recently revised, to improve margins, and accept a lower growth rate. That now seems to be working.
.

.
We've been inundated with reassuring trading updates from G4M this year. Today's update gives us more data, for FY 03/2020.
Key points -
- Revenues up only 9% to £120.3m - much slower growth than in the past, but that's as planned, to chase margin, not revenues
- Gross margin improved by 310bps to 25.9% (FY19: 22.8%) - this is the stand out number. It's still a very low gross margin, but remember that the average transaction value is quite high, so gross margin in £ terms for each order is quite good
- EBITDA not less than £7.0m (FY19: £2.3m) - a whacking great increase in EBITDA. Before we get too excited, bear in mind that this £7.0m EBITDA only translates into adj PBT of £2.4m. It's still a cracking improvement though
Covid-19 - operational challenges. But, this bit sounds very encouraging;
I am extremely grateful for the extraordinary hard work and commitment our teams have demonstrated, which has allowed us to successfully satisfy the high demand we have encountered since late March, as an increasing number of people recognise the benefits that playing musical instruments can bring during these difficult times.
My opinion - things seem to be firmly back on track at G4M, very pleasing.
Sad though it is, I imagine that many independent music equipment retailers that were just about surviving, may not re-open once the lockdown is lifted. Therefore online is the beneficiary.
Overall, I think with forecasts beaten for FY 03/2020, and a strong outlook, given the current crisis, then G4M is starting to look appealing again. I'll probably be adding to my existing small position on down days. Management has renewed credibility, now that it has executed very well on the plan to increase margins.
I think this is likely to be a much bigger & more profitable business in 5-10 years' time. That's what investing is all about really isn't it?
That's it for today. Please see tomorrow's report for additional companies that I had originally planned to put in this report.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

113 comments
Why not use some of the Nightingale hospitals for Coronavirus and then start operations in hospitals? Some hospitals have plenty of capacity it seems now. Have you seen the fall in beds occupied today?
Bed occupancy isn't the issue - it's staff availability. The London Nightingale never had the staff to do much, even if other hospitals hadn't been able to cope; presumably there would have been staff redeployment if it had been absolutely necessary. The NHS only got through so far by calling up the recently retired (requalifying them even without recent training topups), deeming students as fully qualified, and having many staff work extra long hours.
Many will need to take their accumulated leave or holidays. Hospital managers will be trying to work out what resources they will have for the next wave. Some staff won't be able or willing to go through this again - there are already reports of mental health issues and they will mushroom once the pressure is off.
I'm sure they will look to use the Nightingales etc and local hospitals want to return to their normal work, but planning how to do it is a bit like planning to undo lockdown. Cardiology and Oncology are seen as priorities, but everything will depend on resources available.
And referrals. Most GPs are still in semi-lockdown, and most patients are understandably cautious about the prospect of mixing with sick people.
But if their are less patients then there should be enough staff this is why many hospitals chief executives are talking about starting cancer and routine operations in the next few weeks. One in Northumberland said they are only using about 30% of their ICU capacity at the moment and he said it was similar in the northeast region. If the govt. can test workers who are at home isolating then more staff could get back to work. Yes doctors have been very quiet I saw on an interview yesterday.
I can't see the public accepting that every pub, bar, restaurant, football match, sport event, concert, theatre, cinema etc etc is shut until dec (or 'for ever, lock em all down' if you are a scientist in your dark univercity office) or the conditions for attending are so miserable people don't want to go.
We constantly see the government say this or that, a scientist says this or that, but:
1. the lockdown is to allow the health service to cope, it now can and can continue preparing with unlimited money.
2. You are highly likely to get C19, the disease isn't going away, we'll have to live with it at a sustainable infection rate (a million infections a month..?)
Open them up for 2 or 3 days a week, have one of every three games of football with a crowd etc. There are more imaginative ways.
The fact is we have a disease thats not going away, there is a level of infection that is acceptable & they will have to-find that level. A puritan approach of stopping everything that social beings find pleasurable..... socialising, isn't going stick (we all still will work, those who still have jobs, shop, meet friends and family, ie pass the disease on).
We'll see, but they have not got a clue how to handle this other than 'lock em down', and I think they will constantly change their minds, test lots, and test the approach, such as 3 day openings etc. Invest in a pub or leisure group, still a bet though.
the lockdown is to allow the health service to cope, it now can and can continue preparing with unlimited money.
The health service isn't coping. Front line staff are dying and those who aren't ill are working unsustainable hours. Many are living away from their families to avoid infecting them. Everything non-urgent has been postponed.
That depends on the definition of coping. Not being able to treat patients because there are no staff, or beds, or equipment is how the government view not coping. Your points are highlighting the difficulties of the situation, which is of course very difficult, but not that they cannot cope.
Sounded as if you were giving your own opinion to justify opening everything up rather than explaining government policy.
In fact you said:
We constantly see the government say this or that, a scientist says this or that, but:
before expressing your opinion that the NHS is coping.
One hospital is now starting to do routine operations again as corona patients have dropped considerably in the last week or so. London corona beds have dropped even more than other areas, so it looks like they are coping and have some capacity. The fear is the second peak if we lift the lockdown.
Which hospital? I hadn't heard that one had restarted routine operations.
Hancock said yesterday that the NHS will restart as capacity becomes available, but there's quite a bit of high priority work to do before they get to routine. Some specialties can afford to start up because neither their staff nor their facilities are needed but they will still need PPE etc even when they didn't before.
There will certainly be a second peak in the absence of a successful treatment.
I think it was in Wales, it was on the news last night.
I think people are being too optimistic. I look at every scenario in my head and none of them are good. Let’s say we get a vaccine by September - rolling that out to 66 million people won’t happen overnight. It would probably take another 6 months.
Even If we do open some shops and retail and other businesses with a there will massively Reduced footfall regardless and level of spending regardless having huge knock ons. People are genuinely scared to go out.
This on top of huge PE ratios and large amounts of debt and very few ways of stimulating the economy (almost zero % interest rate)
I for one am avoiding recovery playS unless companies are looking to pivot. Any company that is holding on for dear life expecting business to return to normal is going to be in for a shock!
While it's not conclusive the Scottish government's approach to exiting lockdown clearly gives a taste of the type of thing we might expect from across the UK:
This is likely to be the shape of things to come for a while.
timarr
Public gatherings in groups or pubs are likely to be banned or restricted for some time to come.
Outlook doesn't look great for pubs, sport etc. Alcohol+people doesn't lead to distancing. Or tracking and tracing.
Yes, we should expect something similar for the rest of the UK. But this throws up a number of issues, including:
1. If they want to move in small increments while testing to ensure R<1, then this implies testing of a whole different order to that which exists today. So would they be prepared to start any easing before this is in place or does this imply a few more months under full lockdown? Being realistic about testing, if they are to do what they say, then they will be under lockdown for a quite a while yet. That would be difficult to say the least.
2. One implication of insufficient testing is that we have no real idea what R is really. Sturgeon said that best estimates were that it was about 3 before lockdown and currently between 0.6 and 1. That accords with other estimates I've seen. But, if that's true, that implies little room for manoeuvre in loosening restrictions. So, all the less likely that pubs will be open any time soon. But also, a similar story for gyms, restaurants, hairdressers, bowling alleys and everything else at that end of the risk spectrum.
In the real world, R is rarely more than a best guess. When evidence suggests that the number of cases is rising then it's over 1 and falling means the reverse. It's a worry that loosening in other countries has rapidly increased the number of cases, so it looks as if it will be very sensitive to the precise measures taken and everyone's behaviour.
The obvious first step is opening up employment and retail where distancing can be maintained and see how that goes. Allowing people out in condition they maintain distance is another option. Public transport seems iffy. If prevalence can be reduced sufficiently, then other things can be opened periodically so long as R doesn't rise too much above 1.
Assessment of the SARS-CoV-2 basic reproduction number, R0, based on the early phase of COVID-19 outbreak in Italy in Biosafety and Health, concludes:
"The findings of this study suggest that R0 values associated with the Italian out- break may range from 2.43 to 3.10, confirming previous evidence in the literature reporting similar R0 values for SARS-CoV-2."
FREng
LOL, of course it does! She attends the same cobra meetings. Seriously though, is there anything in this that we didn't know or haven't already been told at the UK press conferences? R must be kept under 1 - No sh*t Sherlock...
Seriously though, is there anything in this that we didn't know or haven't already been told at the UK press conferences? R must be kept under 1 - No sh*t Sherlock...
I don't think so. But if you read the comments here you might think otherwise, Watson ...
timarr
fair shout!
Tried to buy some G4M at around £2 but couldn't buy any in any decent amounts :/
Xlmedia (LON:XLM) FY19 results webcast just released. Given by (relatively) new CEO, Stuart Simms. Covers off results, de-ranking on Google, CV19, then the outlook and strategy going forward.
Hello Tamzin.
Thank you for posting the link to XL Media£XLM...I have a holding in the company but you know when it’s time to get out , when the CEO does not spend even a nano second explaining in detail the $80 m plus impairment loss and mind blowing net loss.
No amount of management speak can put a positive spin. on dire results..The words that come to mind are simple ‘ Bullshxt Baffles Brains ..the world is full of these characters and hopefully I will be wrong but I do not intend to stay around to find out..,I will deploy my capital in a better managed business...
Thank you again
I agree with your comments and management are continually and deliberately opaque about their future plans, however, you should be aware that Premier Investissement SAS is the investment vehicle of Moisse (Moses) Mitterand. He is the son of Olivier Miterrand who was the nephew of former French President Francois Mitterand. The family is estimated to be worth 550m euro primarily through their listed Les Nouveaux Constructeurs property business in France. His wife Melody, works for Google in Paris which is at the centre of a much lauded campaign by President Macron to make France a leader in AI technology. (Google - Meet the brain Macron tasked with turning France into an AI leader). His mother, Anne-Marie Hubin (Mitterand) was a strong supporter of the Jewish cause (hence the name Moses) I think as a result of her first marriage (Google Comment Anne-Marie Mitterrand a endossé la mémoire juive) and translate the article using Google translate. You may also want to look at the AI investments of Stuarts former employer Rakutenen. Make no mistake , AI is the future of affiliate marketing, in sports betting, in retail, in consumer finance. There is an excellent article here. https://www.visualcapitalist.com/visualizing-the-evolution-of-consumer-credit/ You may also want to look at what Rakuten did with Wells Fargo and, in addition, what Rakuten is currently doing in the US personal finance market. https://finance.yahoo.com/news/purple-selects-rakuten-marketing-affiliate-110500445.html
They have a plan here. Whether they can execute is another matter entirely.
purpleski
Maybe I am not having enough faith in modern medicine but it took decades to find treatment for HIV (and look at the money and resources that was thrown an that dreadful disease. Is it more likely that this time is different?
IMHO It has to be more likely that this time will be different
The amount of resources being used and the advances in technology mean we are starting form a different viewpoint than previously.
The comments coming from those at the coalface seem pretty optimistic , ok when Oxford university say 80% chance their attempt will work thats ridiculously biased speak - but even if they only have a 10% chance of quick success there will be another 20 similar institutions soon at a similar point of tesing i am guessing.
Bash on the door enough and it should break - i think they explaied the high level of confidence being due to the particular characteristics of this virus making it easier to pin down a fix for compared to hiv or the quickly changing annual flu.
Maybe i am having to much faith in modern medicine - but i would happily offer 5-1 up to a tenner with proceeds to charity on there being no proven (**) working vaccine by 31/12/20. **reasonable evidence.
Paul think you are being overly negative on SDI which has top quality management.
Judges Scientific is up 25x in the last 10 years. SDI is smaller than Judges so acquisitions will move then needle more. It has managed to grow earnings and revenues per share substantially since they started following the Judges model. Judges is trading at 25 times last year earnings so SDI is cheap in comparison.
I agree raising cash may be a good idea, especially because I expect a lot of nice acquisition opportunities for SDI going forward from this year and less competition from private equity too.
Why do you think there will be less competition from PE?
Hi pmytial,
I'm not negative on Sdi (LON:SDI) - if you re-read the article, you'll see that I think it's a good, well-managed company. My only query is the valuation, given current crisis conditions & lack of visibility.
On your prompting, I've just had a quick look at Judges Scientific (LON:JDG) and its valuation looks bizarre, way too high, given steep fall in forecasts. Similarly with Tristel (LON:TSTL) . Maybe investors think, oh they're something to do with healthcare, so they should be really highly rated in the current situation?
But I take your main point - that SDI doesn't necessarily look expensive compared with others! It all depends what earnings are like, and that's unknowable at the moment. Hence why personally I'm not paying a toppy price for anything at the moment.
Regards, Paul.
Opening up the economy has got to be about risk and reward. I know if it was my decision, I would see construction, housing, retail (with restrictions), offices (self governed) manufacturing and distribution all as relatively high reward for the risk being taken. Some opening up of education would be required too. I would see hospitality, professional sports events and anything with a crowd as the opposite - too high risk. I would also want to see what the effect was on R0 at each stage before going further (the govt have also started talking about this now). The more testing and tracing capacity we have, the more risks we can take.
On that basis, I can easily see hospitality being closed for (profitable) business well in to 2021 and maybe beyond. I don't see that as pie in the sky. As I've said before, I can see them being allowed to open partially, but I can't see bars and clubs making much money out of that.
Given the availabe data today, it seems that a full on opening of pubs etc would inevitably lead to R0 escalating beyond 1 again and so to another lockdown. The only reason that wouldn't happen is if herd immunity exists already and we don't have any strong evidence that is the case. Maybe the govt will change strategy again and go for herd immunity with an overwhelmed health service, but given what they've said over the last few days that is currently unlikely.
Just one person's view. I know a lot of people don't want to hear that, but what we want wont change the facts.
“Remember, the economy is people, not just numbers on a spreadsheet or on a bank statement. We're talking about extended lockdown ruining the lives of millions of people. It's just not an option.
The solution is obviously a vaccine, and/or drugs to treat the condition, and make it survivable for everyone. If such a breakthrough were to be announced, then shares like Loungers would probably double, or more, instantly, as business would return to normal quite quickly.”
I agree entirely with Paul’s first para above, I am just not sure the politicians realise this? Deaths etc from Covid 19 are reported daily on the news where as deaths from economic downturn over the next decade don’t make the headlines and therefore don’t necessarily lose elections.
I have nearly finished reading “The Great Influenza - The Story of the Deadliest Pandemic in History”. Times are of course different and the flu of 1917/1920 was far more scary and deathly, but there is definitely a case of history chiming.
That said it took years for scientists to find out what virus actually caused the flu let alone find a vaccine or a treatment. What eventually enabled the world to get over the pandemic was the mutation of the virus into a less deadly and less infectious form, which is what usually happens as I understand it (rather than the scary scenarios you sometimes find on twitter of the virus mutating in to a form that wipes out the entire human population). There were three main waves of the 1918/20 pandemic each one more benign than the last, though all far worse than what we are experiencing today. Maybe this is how Covid 19 will play out? What that means for lockdown I have no idea.
Maybe I am not having enough faith in modern medicine but it took decades to find treatment for HIV (and look at the money and resources that was thrown an that dreadful disease. Is it more likely that this time is different?
On the bright side remember after the Spanish Flu came the roaring 20’s and a bull market, where the Dow was up five fold, I won’t mention what came afterwards.
I totally agreed regarding the valuation that the market is putting on SDI and similar companies. None of us as yet know the damage that our badly damaged economy will reek. In normal circumstances we would not buy shares in a company where we do not know what is turnover and profits are likely to be?
It seems to me that there is a lot of this going on
Purpleski you need to think like a woman.....
For those of you interested Getbusy (LON:GETB) put out a brief statement yesterday re Covid 19. Business is currently on track, their existing revenues are sticky but it may hinder new business opportunities short term whilst it all plays out. The market lends itself to their product suite though. They also received a loan from the US govt for $ 515k. They are likely to keep all of this as they will continue to employ their staff. On my numbers they are like;y to still have close to £2m on the balance sheet at year end. Shares have been relatively firm,apart from a wobble at the beginning on tiny volume.
Thx for your review of Boohoo (LON:BOO) yesterday. I am of course kicking myself fo selling my last tranche of Boo on March 19.
I think I will dip my toe back in over the coming months just buying on a pound cost averaging basis as I simply don’t think it is possible to tell what will happen to stock prices over the next 12 to 18 months. I do find it difficult to believe we won’t have a another pull back though an outstanding company like Boo might not be so badly effected as it was in March?
The bear points for me are:
The bull case:
As I say I will be buying back in and while I have no idea where the price will be over the coming months I think one can safely say that in five years time I will be pleased to have bought back in.
In the bear case you are thinking too much like a sensible adult and not the teenage audience which Boohoo sells to. The world of influencers and Kim Kardashian keep teens buying clothes they may not even wear outside.
I used to have a stake in Boohoo but sold above 300 a while ago as it is very expensive but I do still think it will continue to grow and grow and grow.
I own some £boo and have done on and off for several years though unfortunately not as much as I owned pre Feb/ March as like you I sold off my holdings buying back only a c.third when it became pretty likely they wouldn't be closing their warehouse.
Your points on people spending a little on clothes certainly makes sense and I agree that is the last thing on my mind bar absolute necessary functional items. In addition thornabian's points the target customers for boo & PLT are prime users of the surging tik-tok which is seemingly an excellent way to show off new clothes. Also what fashion conscious zoom/ facetime user would be seen in the same top more than once or twice?
Also as credit is squeezed, debt is paid down and jobs are lost I can see the companies with the cheaper price points taking market share from their more expensive peers. See Primark in the GFC I remember queues being down the street in Liverpool for their grand opening in 08 for example.
The valuation certainly is tricky though as I the best I can deduce from the conference call Q&A yesterday is the growth to date in April has been 6-8% and the decline in LFL in March was somewhere better than -c.20% maybe even -10% or above. It's hard to extrapolate that with out a spreadsheet but anywhere from -5to+10% LFL seems like a fair guide for the June update. I'm surprised the share price is holding up so well and like many others shares on my watchlist I'm crossing my fingers for another buying opportunity but would be much happier if our lives returned back to normal instead.
I think Boohoo (LON:BOO) will be taking permanent market share from bricks and mortar sellers. Some customers will not go back to the High St. They will probably be able to add to their brand portfolio as distressed names fall into their hands. Even the disaster of coro lockdown provides opportunities to boost sales eg jogging/running wear and work tops suitable for smart appearance on zoom work stations.
I also think there is global potential here..the figures suggest their formula works in overseas markets as well as the UK.
I quite agree. I think we are likely to see a paradigm shift here. People will have spent months in the virtual world by the time this ends and will be far more familiar with ordering online. BooHoo may yet have a way to go.
Thursday piworld webinar with Leon Boros, discussing what he's been up to in the current turbulence, showing his top holdings, a new holding, and how to value accounting for debt.
Investing in an age of uncertainty.
At 1pm today, register here to attend: https://www.piworld.co.uk/events/
Thanks Tamzin for adding this to the bulletin board good to know Leon Boros is giving us his revered thoughts on where we are.
I see the Chief Medical Officer is talking about lockdown being required until the end of 2020. That's pie in the sky in my view, because the economic pain would be far too severe to tolerate such a draconian measure.
I think the mistake there is to see ending lockdown as all or nothing. There will certainly be some relaxation before the end of 2020, and significant parts of the economy will be able to at least begin to get moving again, but any part of the economy that is based around direct social interaction between many people is clearly going to be the last to have restrictions listed, and the first reimposed if needed.
It may well be possible to start lifting restrictions on some restaurants, and even pubs with tables (and food?) earlier, but until there are effective treatments or vaccines, it's going to be on the basis of limiting table numbers and numbers at tables. That's going to hit a lot of pubs and eating places very hard. Large sections of leisure related parts of the economy are going to have a very bad year, or longer.
The Government has also said that bars and restaurants are likely to be among the last to reopen and then only with social distancing for a while. So profitability could stay below previous levels for a year or more. Mark Brumby has also commented that trade sources say there will be a significant cost in reopening: cleaning, restocking, descaling equipment etc. I guess this will be treated as exceptional in the accounts.
I see the Chief Medical Officer is talking about lockdown being required until the end of 2020. That's pie in the sky in my view, because the economic pain would be far too severe to tolerate such a draconian measure.
Just to note - he didn't say that. He said some social distancing measures would be needed until we have effective treatments or a vaccine. If R goes above 1, the NHS is overwhelmed, lots more people start to die and the economic consequences are as bad, or worse, than the lockdown.
In the end it's a balancing act - keep R below 1 and open up the economy as much as possible. That means the future - at least for the next year - will look different from the past.
timarrThe New York Times has released an interesting report on excess mortality rates across countries - i.e. how many more people are dying than we would expect to see at this time of year. The average is around 30% - which is roughly where we are, Spain at 66%, Sweden, oft quoted, is at 12%.
However, New York is running 298% above normal. The story from the US will determine the way forward for the global economy, I'd imagine.
It's important to try to take into account the factors that can impact these results - population density and demographics are critical, but there will be others we don't yet know about. Clearly where health services are unable to cope more people will die. It's not simple to compare different countries and identify winners and losers.
As Chris Whitty said yesterday, some level of social distancing will be needed until we have therapeutic treatments or a vaccine. Keeping R under 1 is key but there's a trade off with the deaths that will occur due to an economic crisis, so there will some lifting of restrictions but public social gatherings involving drinking will probably be tightly controlled for some time to come.
Looking forward, assuming we have flattened the peak, the next big risk period comes early next year when the flu season strikes. I wouldn't be surprised to see measures tightened at that point, although hopefully we'll have better contact tracing and testing in place to reduce the possibility of another full lockdown.
Personally, I wouldn't want to be invested in any leisure or travel related businesses other than the very best and most deep pocketed, but some will survive and those that do will yield great returns. I just have no idea how to differentiate those between those that will survive over those that won't.
timarr
The more interesting point in that report IMHO is that excess deaths in Sweden are less than the number of people that have died having been found +ve for Covid-19, whereas in every other country covered by the report, excess deaths were well above the number found +ve for Covid-19.
AIUI, the FT in a frighteningly bad article argued that all the excess deaths in the UK were also due to (undiagnosed) Covid-19 feeding its narrative that the Government are doing a dreadful job.
A more logical conclusion IMHO is that a lot of people are dying, one way or another, because of the lockdown... ...whereas Sweden has no lockdown, so this is not an issue there
This fits in with the suggestion that the lockdown is achieving next to nothing provided hand washing and social distancing disciplines are maintained.
Obviously ending the lockdown (ASAP please) is no help whatsoever to any business that routinely puts vast numbers of people in close proximity to one another, but would get a lot of people back into work at little apparent risk to health.
Hi Paul, is it possible to have an insight on Sdi (LON:SDI) and Concurrent Technologies (LON:CNC) ?
Many thanks
I am really fed up. I think the whole capitalist approach has been corrupted to such an extent that it becomes a game of cheat. Today at the Avacta AGm the shares granted to Kumani and Zeus were passed. Days before an announcement that AVCT had signed an agreement with Cytiva and Zeus Capital were made joint brokers, we get told AVCT have raised £2m (£2m???) via two shareholders Kumani (why on earth was he involved anyway!) and Zeus' wife! at 18p. The share price is now 3.6 times that. Easy money. The authorities are sooooo weak its dismal. It may be that I am wrong and if so I apologise to all parties but it seems unlikely given the chain of events. Sickening and simply a reflection of the race to the bottom we are all on. Sorry to rant...
I agree..doesn't look good does it. I scanned the RNS quickly..does it not say at the bottom that Kamani has given the shares away to his son?
i see a lot here want pubs back open and are willing to take the risk of catching covid. Go have your pint but please don't ask some doctor or nurse to treat you and risk their lives so you could socialize again.I would rather go into a deep recession than see more lives lost
I understand the feeling behind this, but it's simply not how the world works (or, in my opinion) should work. Some think it feels cold-hearted to put a price on life, but in my opinion that's because people only consider one side of the equation and not what the "price" represents. Let's not forget that money is just a way of measuring economic value and economic value has a huge effect on the number of quality adjusted life years (QALY) of the whole population. So while it may seem overly mercantile to think that more people may die as a result of re-opening the economy, you have to at least ask how many QALY are gained as a result.
I am in the "we need to open soon" group. The higher risk group should be advised to stay at home although I doubt they all will. There is no guarantee a vaccine will be found soonish...flu has been around in some form since at least 412 BC apparently. The virus may need to just burn out as nasty as that sounds. Meanwhile domestic violence is soaring as is stress as people are worried about losing their jobs and business and homes. Personal debt was at crazy levels at the start of 2020 and will be much higher now... https://themoneycharity.org.uk/money-statistics/ All these schemes to suspend payment are helpful but are also just increasing the time and scale of debt. Meanwhile government debt is growing dramatically.
If it was a case of lockdown for another 6 to 8 weeks and the virus was gone then I could understand it. But virus are ancient in history and predate humans. We may just have to accept a much higher level of death....back to the 19th century levels perhaps. That life expectancy will reduce for a while and that our older population can no longer live to late 80's and 90's. We have had an amazing 75 years without major war or similar. Meanwhile look at the impact on our environment. Our air is so clean!
Unfortunately our UK politicians struggle to address this type of issue. For that we have to look to the German Chancellor, who has given brilliant and honest leadership. So too the New Zealand Prime Minister Jacinda Ardern who is accepted as being outstanding. "No paranoid rambling, no blame shifting - NZ PM hailed as world's most effective leader".
Unfortunately our UK politicians struggle to address this type of issue. For that we have to look to the German Chancellor, who has given brilliant and honest leadership.
Mmm. In Germany the actual lockdown decisions aren't taken by the federal government. And she has warned that the second wave will be harder to manage because there will be many infection points. The UK first wave had many points. The early single points were all identified and transmission stopped.
Jim Craig
i see a lot here want pubs back open and are willing to take the risk of catching covid. Go have your pint but please don't ask some doctor or nurse to treat you and risk their lives so you could socialize again.I would rather go into a deep recession than see more lives lost.
It's job of the government to make this decision on a risk adjusted basis - the facts are as others have said here today any form of social interaction carries risk in much the same , crossing the road or walking down the stairs in the morning after you wake up. If the authorities deem it safe enough for me to go drinking and i deem it safe enough to go drinking i will do so unfortunately whether you like it or not - thats the free society we have for better or for worse. Thankfully at present there is no immenent signs that the pubs will be opening within the next 6-8 weeks.
JC2 seems to think a Deep Recession does not have implications, after the social stress of the
depression of the 1920/30 the world entered a World War that resulted in the deaths of 55 million. The same stresses are starting to build now with a significant number of the population probably unable to cope with a recession let alone a deep one.
I will make a statement that we will remember the economic fall out as being way more
traumatic than the virus.
I would rather go into a deep recession than see more lives lost
Isn't this rather contradictory ? Would not a deep recession result in lives being lost because of that plus a lot of lives permanently blighted ?
There seems to be a general implied assumption in the media and in discourse that life should be saved at any cost. This is not reasonable, not how society can work and certainly not how an all embracing state medical institution works. Its about best endeavours and reasonable inputs and outcomes.
In the current situation, the lockdown is to spread out the number of cases over a longer period of time so that the medical facilities (which we all expect to have free and available at any time) can cope with severe cases. The number of infections will not be less but arise more slowly. By maintaining a functioning universal health system some extra (both infected and other ailments) lives should also be preserved which would otherwise not be. Throughout lock down the virus is still here; its not 'cured'. As its very infectious a level of continuing infection has to be assumed.
Typing as an at risk category, I am somewhat embarrassed that all this damage that is being done to my neighbours and our children and grandchildren's future largely on my behalf. I (partly) console myself that it is being done to protect the state medical services rather than pander to my natural narcissism. However the sooner the younger and economically more worthwhile cohorts get back to life the better all round so they can begin the long haul of damage repair.
Jim what is your stance on flu? I think something like 30,000 people in the UK die from flu each year, and I am sure the number would come down - maybe by half? - if we all went into lockdown every October for 5 months. I don't think many people would consider that sensible or worthwhile and it has never even been suggested. So if we all agree lockdown is not worth even being considered to save 15,000 deaths when is it worthwhile? - probably not to save 30,000 deaths either. I'd say a one month lockdown is probably worthwhile to save 100,000 deaths. I am sure everyone will have a different figure but few will say the figure is 1.
I think something like 30,000 people in the UK die from flu each year, and I am sure the number would come down - maybe by half? - if we all went into lockdown every October for 5 months.
Flu is quite different. Not really a mortality risk at all to healthy people. Covid19 is a significant risk for mortality and much greater for severe illness requiring hospital admission. In younger people, not just the old.
Some people would say that Covid-19 is not much risk to HEATHLY people
They don't know what they're talking about. There's a lot of that about.
There's a lot we don't know, and some we do, and that's evolving, which makes it even more important to be very clear about what we do.
Covid affects many healthy younger people, some severely, some fatally. Most have no or mild symptoms, but that is also true for most healthy older people.
Most flus aren't a death threat to healthy younger people at all. Though the Spanish flu apparently was.
Isn't it true that Covid does affect younger people but predominantly those with other health issues eg. Asthma, diabetes, obesity, etc. Therefore it could be argued that it isn't a major risk to healthy people. It depends on the definition of healthy you use.
No. Young people with no other health conditions can become severely ill and sometimes die. Having some other conditions massively increases that risk and age progressively so. But a risk is there for all. But risk for women is about half that for men at all ages.
Attributed deaths from flu in 17-18 were 26,408 and in 16-17 were 18,109 .
This is with a vaccine of course where the over 65s (most at riisk) have a take up rate of 72%. Without a vaccine the figure would be higher.
We dont have a vaccine for Covid 19 and in all probability wont have one for next winter. I would guess that over the full winter 2020-2021 the mortality rate for Covid 19 will be higher than 2019 -2020.
Could well be that the Nightingale Hospitals have been built with one eye on next winter - though I doubt that the Government would want to publicise such a possibility.
I think deep recession will come with or without pubs reopening. I favour Paul's comments , the pain will be too great if we don't relax the lockdown soon. I am over 60 so presumably my immune system is not as good as it could be ( if I was 20 ) but I will gladly take my chances generally ( I don't want to enter a pub ) but I do relish going back out to eat. The Swedish Method ! sounds good to me , tables spread out etc (but no lockdown) . I certainly don't fear going to the supermarket say as I try hard to stay 2 metres apart , turning my head if someone invades my space or quickly moving away etc. On the street its fairly easy to distance even in London. A virologist expert ( from Cambridge Uni I think ) has said after tests done in Italy that she believes it can be shown that we cant catch Covid-19 from BREATH only from coughs and sneezes. How great would this be if factual !!
I think also can be spread from speaking, so maybe everyone should wear a mask when out outside in public?
Hi Paul,
Could I make a request, do you have any insight or view, from you broker contacts of where the volume is coming from in the markets?
Like most I am looking at my Folios of held or prospective shares and they are up & down like a yoyo, be it micro or mega caps it's all up & down 5 - 10%. Is it retail, institutional. automated/algo flow. Are the volumes normal, are market makers acting normally. Nothing seems normal to me at the moment! I'd love to trade this market but thats not my style and it seems just too volitile.
I know a broker view is partly opinion, but it would be a more informed opinion than anything I can gather from website data at the moment.
Thankyou Paul.
The YouGov poll is interesting - doesn't it show that, in the event that lockdown is lifted across the board, the population is going to effectively accomplish that which the science deems necessary? Namely all establishments are going to be considerably less busy and those "riskier" should easily meet social distancing requirements.
Time, in any event, to start rolling out the lifting of restrictions.
Disclosure:- filling fell out over one week ago and impossible to find a dentist prepared to do anything about it.
Regarding dentists. They are under instructions from the General Dental Council and are not allowed to practice unless its an extreme case. I suggest ordering some DenTek to hold you.
If it is an emergency a dentist is available in my area at the local hospital.
May be better suited to Graham but there is a very positive update from Non-standard Finance (LON:NSF) today, highlighting significant cash balance (£38m), generation of £3m FCF in 3 weeks in April and decent collection rates. Management seem to have a grip on the situation and have access to £185m (arranged just before CV19 kicked off) to increase the loan book when the market improves (demand will surely be high once we are through lock down). NTA £56m vs. market cap of £32m. Looks far too cheap to me
Non-standard Finance (LON:NSF) were once my biggest position as I still believe in LT underlying strategy (specialist focus on poorly served non-standard credit market AND focus on face to face borrower evaluation to control impairment in conjunction with technology back credit scoring). I also bought into the counter-cyclical opportunity since I thought loan scorecards could quickly adjust to play extra volume at better margins vs extra impairments.
However, speed of downturn has been without precedent and NSF borrowers by definition are mostly those on fringes (casual workers, new graduates, immigrants) who will be fired first. Cash is only positive because lending (for revenue) has largely stopped.
Impairment rates will jump hugely and could exceed tangible equity. I think some form of re-capitalisation will be essential to avoid going bust before the benefits of fewer competitors/ higher margins can kick in (as I expect) as prime consumers drop into needing loans their banks won't give them.
My fear is I will be excluded and it will be a hugely dilutive private placing or a takeover vs an Open Offer Rights Issue and this will be announced at the time of the delayed results announcement. Some 29.99% % (ie max before takeover) are owned by Alchemy Special Situations who are specialists in distressed financial companies and effectively bought in as Woodford was forced to sell lout. They absolutely know what they are doing but may orchestrate a takeover at the low current place and refloat (maybe without Loans@Home) in 3 years time at great profit.........but I doubt this will play to my (long term holder) advantage.
Great post on NSF Zipmanpeter. Thanks.
There is a vast difference between going into a heaving London pub where you are jostling for a space at the bar, and going to a country pub where you can sit at a table in the garden (especially if waitress service could be enacted). I guess it is beyond the wit of the Govt to structure a diferentiated release from lockdown on this basis.
(As you might guess my locals fall into the latter category)!
Get those pubs open!
1- use a ticket dispenser like the ones at the supermarket deli counter to enable people to know when their time to be served whilst observing the social distancing measures.
2- Make sure that only pubs with sufficiently large beer gardens are allowed to open to ensure social distancing measures. POP UP pubs in large fields anyone ?
3- Give everyone a loud hailer so as to enable communication whilst observing social distancing rules.
4- Make sure everyone has a protective mask with a hole for a straw so
5 Sorted.
the problem with that logic,is assuming country pubs were the only ones allowed to open,you can be absolutely certain they would soon be rammed by urban drinkers
I can see the government guideline being that your journey time to the pub must be shorter than the drinking session :-)
Spoons have an app so you can order from your table.
£G4M; Simple fact is that when folk have time on their hands stuck at home they may decide to focus more on music, and upgrading existing instruments or starting to learn from scratch. One of the 'beneficiaries' in some ways from the coro/lockdown situation. Music/playing an instrument can provide comfort to many people, and using social media/zoom...you can share your new found skills with an audience!
£G4M Also with many shops being closed people switch to online buying. However that may change soon in some European countries.
I have bought a cheap guitar and started to learn from them. Seems to be a good service. Ancedotal I know!
Morning Paul, any comments on Xaar (LON:XAR) finals this morning would be greatly appreciated. Clearly had a terrible year with the cull of the Thin Film business and the subsequent write offs but a strong balance sheet to help tidy them over through COVID-19, Stratsys now owning a 45% stake in the 3D business and new management at the helm.
Unilever (LON:ULVR) not really for this thread but....
its an interesting window on the world...in Q1. For a branded business selling consumables, food and household products... the backdrop is flat... no revenue growth. This makes it difficult to manage your cost base and normally a negative earnings backdrop. However with unusual trading patterns triggered by Corona you have bottlenecks and some supply chain issues... that put some inflation in the system but with a weak consumer this is hard to pass on...
I think at best this is the new normal, flat to down revenue with cost pressure. If a 3.5% yield is enough for you then fill your boots.
I think as more companies report over the next few months rather than, recovery much more likely is price weakness, supply chain issues, and cost pressure... and in this environment, operationally geared suffer most ...
As we think more about 2021, rather than V or U.. etc maybe the way to think is, it will be difficult. A weak consumer and cost pressures with supply chain issues is not a favourable equity backdrop.
The company that likes to collaborate has issued another announcement about, you’ve guessed it, another collaboration. Hurrah! That should cheer us all up.
Yes, that champion of collaboration, Versarien (LON:VRS) , has issued an RCS about work that Rolls Royce are going to do with one of their subsidiaries to collaborate in development of graphene for use in wiring systems of the next generation of aero engines.
All sounds very blue sky, much like our weather, so no doubt it will be many years before anything comes of it. No wonder it’s an RCS announcement rather than RNS.
It’s about time this company actually sold something!
Credit Suisse published some numbers yesterday.
Fatality rate in under 40s 1%, population in that category 49.9%. 0.018% risk.
For under 60s the equivalent number was 0.08%.
Clearly this was not adjusted for pre existing conditions. It was not adjusted for flattening of the curve dynamics.
Majority of people have just realised that risk is a “thing” but the reality is we are living with risk on a daily basis. There is nothing that I would not go back to. The alternative is that you would never do anything until it was “safe”. No more crossing the road, no more driving a car etc
Taking sensible precautions is always wise but we are now in a heightened state of paranoia. Both my parents are locked up, my dad is high risk, so clearly they have to behave differently for longer but then their risk profile is different so it’s hardly rocket science.
It is always sad when people lose their lives but firstly it is a guaranteed outcome and secondly people are continuously dying and most people never gave it a seconds thought until recently. I have been confronted by death twice, once living through a war and also at Hillsborough. This level of risk is significantly lower for the same parts of the population for whom mortality is always lower risk.
The destruction of the economy will become self fulfilling unless the virus burns out(possible as with previous viruses) or a vaccine( ages away, Roche suggested end 2021 possibly yesterday). The path to recovery is going to be long because suddenly everyone thinks they are an expert in risk. Even the “experts” disagree. It is possible to be an expert in a certain area and have a huge body of knowledge, this does not make you an expert in interpretation which is why we have experts disagreeing.
It is very hard to see a V shaped recovery. The ramifications will be felt for a long time. There is also close to zero chance the government will “get it right”. In what way have their prior experiences or jobs( if they ever had one) prepared them for this?
This doesn’t mean there aren’t shares worth investing in because the market is a discounting mechanism and not everyone will be affected equally. However, I am worried about the long term real ramifications going forward.
Interesting chart from today's Daily Telegraph...
Interesting and certainly reflects my feelings - but I wonder where the data came from? If a survey of Telegraph reader I imagine the table would have looked similar a year ago.
There is a small tag at the bottom right-hand corner of the graph which gives the source as "YouGov"
My old mate used to say 'must do is a good master'. I like most am a little bit wary about going to all of the places on that list however when my barber re-opens I'll be the first one through the door.
:-) My barber sold his business on December 24th (what did he know) and I hadn’t had a haircut in about 3 months when the lockdown came here in France.
I ordered a Remington hair clippers and my wife (no training) cut my hair. I won’t ever be going to a barber again. So there is some money I have made out of the crisis!
Money saved? Hmm. I think you should defer judgement until your wife's bill has arrived.
To be honest you should really go to the source for this kind of thing. I'd rather stick pins in my eyes than visit the Daily Telegraph website:
https://docs.cdn.yougov.com/v54ts2llp1/Newsnight_Lockdown_200421_W.pdf
This gives much more detail of how the breakdown works. It seems men are more comfortable than women, and youngsters much more comfortable than older people as you expect.
Of course, you also have to bear in mind one of the main findings of behavioural economics - people often say one thing but in reality do something completely different, which makes these kinds of polls of dubious value. In particular, I find the level of comfort with going to the hairdressers probably just indicates a major concern of most women I've talked to - they don't want to end up looking like the wild women of Borneo! So it's more a case of perceived need than their being comfortable about visiting the hairdressers.
All the best, Si
I take the point about behavioral research e.g. many people say they will buy organic veg and milk in preference over non-organic, but don't at the point of sale. Many continue to buy what is cheaper. However, when it comes down to social distancing being MANDATORY for a very long period - as in if YOU dont as a bar owner say manage it appropriately, not the industry, you will be closed down - then that brings another very important factor into the mix. It is not just behavioral science alone that determines the behavior, it is the law that will determine it in the end.
What we really need is the attitudes of the bar flies and gym bunnies, which may be very different from the population in general. Or perhaps, better still, would be the attitudes of heavy users, medium users and light users of those venues. Then there’s the thorny issue of whether attitudes will be reflected in behaviour.
Interesting chart none the less.
.....and the issue of perception shift on the same issue over time. Data is from say 2 days ago (ie effectively full lock down, high fear, limited actual economic damage). When "easy" first steps have been navigated successfully and protocols established (eg as supermarkets have now normalised 2m spaced queueing and building capacity limits), the apparent risk from other steps will seem less but by then the economic damage (job loses, failed firms) will be clear.
So I also think the table (of comfort in re-opening in respect of CV-19) is very interesting - politicians will mesh this with scientific advice. But once the lockdown starts to lift at all, the pressure for fairly rapid wider and wider re-opening will be intense, especially from the young who are the key users and workers in gyms and pubs/bars/hotels/B&Bs etc. The later businesses especially in often low income tourist areas need at least some revenue from high summer sales and can manage social distancing in gardens, outdoor street seating etc. Otherwise it will be a long, long winter for them and thus the wider economy. (Similarly, this is why Boris fears any 2nd wave lockdown will be difficult even if it is tough to lockdown longer now ie through May).
Politics at the moment drives investment decisions. Effectively, I hold on to some F&B and consumer facing shares because I think the political cost of lockdown beyond a few more weeks will be insupportable. (Brutally, in 5 years at the next GE many of the >70s now will be dead/non-voting whilst the young ie <40, already Labour-leaning will remember being made redundant/locked down. ) I am a therefore "trading" an early re-opening without knowing if recovery is V, L, U or W shaped.
As we know,the young tend to vote for any other party,rather than the Tories,so suspect the Government will not be too bothered if the young are unhappy. Personally,(even though I am a part owner of a London restaurant and an investor in a few pubs,) don’t expect either to be opened before September at the very earliest . Our restaurant may well go bust, and no doubt many hundreds of others will too.
What we really need is the attitudes of the bar flies
I will be back in the pub at the earliest opportunity as long as someone i know is willing to drink with me. I do have no at risk people living in my household though so my decision is easier than most bods. Note in this regard Sweden is is probably a really useful yardstick - if they can show a measurable decline in cases or an ongoing level that the public can accept without imposing extra conditions i am guessing that this will give many confidence here to dip their toe in the water. It seems (albeit with very weak evidence) that pretty much every country is topping out with their increase in case numbers after a similar set 60-90 days period (or whatever) after exponential growth - despite the different controls being taken.
I would guess the stats with things like gyms and pubs in the graph above probably are probably not representative of the "main users" - i guess the high users will go back - will this impact gyms more than pubs ? - gyms are probably a bit funny in that they may make more from someone who uses them less whereas a pub needs bods to be in more to profit from them.
As an aside, I am rather tired of Sweden being quoted as H2 achieve the best of both worlds - low deaths/instances and low restrictions. Who the hell goes to Sweden, passes through Sweden, compared with the UK/Italy/Spain/France? Scandinavia is fringe. We are also hearing that the Swedish PM is saying that they did not act swiftly enough. I am much more likely to take heed of what happened in Germany although I read an interesting piece about how and which strain of C-19 reached various European countries from Asia - and in that analysis for what it was worth pointed to South Germans as major carriers though Italian ski resorts. Much more will come out in the wash and many books will be written on it in due course claiming in some cases to be one thing or the other - fact, fiction or a mix of both!
Who the hell goes to Sweden, passes through Sweden, compared with the UK/Italy/Spain/France? Scandinavia is fringe.
If we default to population density Stockholm hs 4,800 people per square kilometer ,and greater london has slightly less than that. I think per capita air tavel is higher in sweden than either the us or the uk. So i see any numbers coming out of sweden as at least being useful indicators of how a different method can work even if practicably speaking it may may not have as diverse a set of travellers showing up and the population density outside the main cities is lower than average. Note once the infection rate is high its the community spread that will be the primary spreader anyway and Stockholm seems similar enough to other major citites in that regard to be worthy of comaprison.
A lot of nonsense is spoken about Sweden. As their own Health Minister said, there are a lot of myths which misrepresent the situation.
The truth is that they started off with a lot of social distancing anyway (e.g. the most common household in Sweden is single person with no children) and they are now enacting a kind of voluntary lockdown rather than a mandated one. To take one data point, bus travel in Stockholm has declined by 60% as opposed to 80% in London. I've travelled on both forms of transport and I imagine that the effect on social distancing is similar.
This doesn't mean that if we lifted the rules, we would act the same way. I worked there briefly and I think it's true that they have a much stronger attitude of collective responsibility. Some people say that, as with other Nordic countries, it comes from their history of collective action being the only way to survive harsh winters. I couldn't say where it comes from, but I think there is a difference in social attitudes. Other countries have more of an attitiude of "what can I get away with". That will make a difference as to how guidelines versus mandatory rules are adhered to.
People should try and understand the differences before they draw firm conclusions from any other country.
People should try and understand the differences before they draw firm conclusions from any other country.
Absolutely.
There seems to be a general assumption that the differences between countries are predominantly down to government actions and the detail of infection and death rates are meaningful even though we know the numbers are wrong. People also seem to have bought into a lockdown/no lockdown future, which I think is the wrong way of thinking about it.
All countries appear to be aiming at transmission rates below 1. There appears to be a building consensus across countries in the West that there will be a second, possibly larger wave, come winter and the disease is now endemic; the presumption must be that everyone's models point to the same outcome. The large wave was a feared consequence of lockdown from the beginning. So far, easing regulations has produced higher infection rates in all countries where there was originally a substantial level of infection and the response has been to retighten.
Lockdown itself is not a key issue - it's only a means to an end. Distancing, hygiene and self-protection and self-isolating should easily be sufficient on their own. If people do it. The Swedes probably are better at it than we are.
Its the methods used not where Sweden is or who goes there that interests me. People go out but with great care.
Speaking as a regular pub-goer [10am Saturday and Sunday mornings as my Twitter followers know :-) ] I find that I miss that routine less than I thought I would. I find there is actually something quite pleasant about having a few beers at home while reading the paper and watching daytime TV in the comfort of my own flat. It's also a lot cheaper.
No doubt I'll get back into the pub routine when they re-open (which for what it's worth I don't expect to be anytime soon) but I'm not in any hurry. I certainly wouldn't expect them to be rammed full from day one.
Gostevie
Interesting interview on BBC last evening with an owner of a small group (30ish if I remember correctly) of bars and restaurants in Manchester area. Said continuation of social distancing just about makes sense to reopen restaurants - could break even with 3 max at a table - but no way for bars - said lose less keeping closed than opening.
I wouldn't be surprised if those most uncomfortable are not regular pub goers anyway. I would suspect many regulars are desperate to get back in. If you don't want to go to the pub, you're probably more uncomfortable going when you don't have to.
This is maybe true for the more discretionary venues, while things like hair services which most people use show higher levels of comfort. What people say, and what they do are often different anyway.
Regarding Gear 4 Music
I know that a fair number of commenters on here who know more than I do about musical instruments (not difficult as I know little) have stated that G4M would not be their vendor of choice if they were buying an instrument today. Others have pointed out that they are not as competitive on price as they might be. Others are concerned about Amazon.
However, their update does show good growth (not spectacular) in revenue coupled with improved margins. There is also strong confidence about their trading outlook. So, they are clearly doing many things right, or more than good enough despite the legitimate concerns that have been expressed in the past.
This is one I’m definitely holding on to through these turbulent times.
Lets hope Paul comments!
Concurrent Technologies (LON:CNC) results are also out today - any comments and views welcome.
A relative formerly worked at Concurrent Technologies (LON:CNC) , and I have formerly held shares. The inside assessment was always that it was an extremely well run company, that treated its staff very well. As for the announcement, it seems to say "business as usual" which in the current times is actually very unusual! I sold out on the announcement of the death of the Managing Director, who was a major driving force at every level. However that seems to have been a very poor decision. At the moment the company seems fairly priced to me: the PER is c24 and the yield c2.5%. I SHOULD have bought back in on the recent dip, but instead I opted for Aviva (LON:AV.) because of the dividend!!!!!!!!!
I cannot get my head around the valuation of Concurrent Technologies (LON:CNC) with a current PER of over 20. I am very sceptical as to what the £1,000,000 (a suspiciously round number) other income amount is for, which is not eluded to elsewhere in the results and artificially boosts the numbers beyond what would otherwise only be single-digit improved profits.
In a way it is a premium business: it has a great niche, with few/no competitors; it has no debt; their margin is over 50%; and the continual R&D spend minimises tax liabilities. That £1m is not to be worried about. I believe it stems back to a former export problem due to sanctions.
The £1m is a key man insurance claim. It is in full and final settlement and non-recurring. It was disclosed in the interim financials. If you go back on the RNSs, there was an announcement on 8 May 2019 about the death of their CEO.
Thanks Jack. An ill wind...
I bought for the Divi just like you , what a prat I feel now !!!
I sold recently because they paid the dividend and the results are exactly what they said they would be. Great little company. I am surprised for a tech it has not grown quicker. It has been prone to volatility, firstly when Naked Trade and following pushed it up to £1.20 in subsequent unilateral sell off it touched 60p. Then Lord Lee (ISA millionaire)announced in the Times he had bought in and here we are back at £1.00. Its is very good news and reassuring that their business is 'protected' from this lockdown by both UK and USA government . I wish there was a bit more about their recent Ai involvement because potentially that could be a big driver.
Beginner: Great to hear good things from the inside, thanks! (More positive than most Glassdoor reviews - which were bad enough that the new MD actually wrote a review, which I thought was a great sign of openness / willingness improve). I've never met the new MD but I have a positive impression so far - it looks like they are stepping on the gas.
Beginner/Andrea: For me the valuation seems fair when considering the £10m cash pile (i.e. look at EV rather than mcap, or deduct ca 3 from the PE ratio) and the quite high and recently accelerating revenue growth - is a slight re-rating fair? Also good operational cash flow and expanding production capacity with modest capex spend, and I like the upbeat comments on sales opportunities and the order book.
Simon: Lord Lee has held this one for years FYI. Yes, I am looking forward to reading the latest from NT very soon (tonight?) - I quite welcome the related share price volatility and choose to see it as Mr Market offering us opportunities to top up or slice a little.
My morning smallcap tweet: Gear4music strikes a chord
Non-Standard Finance (LON:NSF) £March Studio Retail (LON:STU) Devro (LON:DVO) SDI (LON:SDI) £G4M Trifast (LON:TRI) Dods (LON:DODS) Smartspace Software (LON:SMRT) Braemar Shipping Services (LON:BMS) Open Orphan (LON:ORPH) Synectics (LON:SNX) NMCN (LON:NMCN) DFS Furniture (LON:DFS)
Non-Standard Finance (NSF) to restart normal lending co is developing new scorecards and procedures, launched a remote lending solution for home credit business. Collections in April at ~90% of usual level but a large proportion of collections occur nearer to the end of the month. Group has become cash flow positive in April after all operating expenses.
Collagen Solutions COS) FY(March) rev down 3% due to covid which is hitting production, logistics and customers. Several late-stage agreements were delayed by customers beyond YE. Cash £2.1m.
Studio Retail (STU) guides FY(March) pretax in middle of forecasts. Studio division rev well ahead YoY during lockdown, especially in toys, games, electricals, fitness and garden. Cutting summer stock intake, particularly on clothing. Education div rev 20-30% of normal. Cash at hand £32m and has sufficient liquidity for its near-term requirements without requiring recourse to government funding schemes. No FY21 guidance. Expects sale of Education div to complete in Aug, before bad debt provision.
Devro (DVO) Q1 rev up 2%. Some raw material inflation due to shortages. Passs div but will pay same amt with interim div.
SDI Group (SDI) guides FY(April) in line with rev ~£24m. Current sales at reduced levels.
Gear4music (G4M) guides FY(March) rev up 9%, EBITDA not less than £7m (£2.3m). Gross margin up 310bps. High demand since late March.
Trifast (TRI) guides FY(March) U/L pretax broadly in line with market expectations despite covid hit to sales. Passes div. No FY21 guidance. Project Atlas rollout delayed to H2 FY21, optimistic on getting at least some of the deferral time back.
Dods Group (DODS) Merit workforce in India now working remotely with little disruption to the business. A third of UK workers furloughed but that's only 5% of Go. No guidance.
Smartspace Software (SMRT) enterprise software division has a small number of large multi-national customers and has seen no significant impact. AV equipment: material reduction in order intake. SwipedOn: new customer wins have slowed, but not stopped. Cash at hand £1.9m. No FY21 guidance.
Braemar Shipping Services (BMS) Q1 so far in line with new guidance. Passing div. Bank facilities should provide adequate liquidity and covenant headroom.
Open Orphan (ORPH) has commenced the testing of an anti-viral for treating COVID-19 on behalf of its client Nearmedic. Testing starts with flu, "normal" circulating betacoronavirus and ultimately COVID.
Synectics (SNX) significantly reduced levels of activity in every sector and geography. "Reasonable [?] levels of design and planning work are continuing for projects now expected to proceed later in the year than originally anticipated." Net cash £3.3m and £5m facilty unused.
NMCN (NMCN) FY(Dec) rev up 19%. Passes div. Workload 30% below normal. Co confident able to survive lockdown.
DFS (DFS) placing went throught at 150p, a 16% premium. I'm short.