Small Cap Value Report (Thu 23 July 2020) - CALL, G4M, DOTD, SBIZ, GETB, CHRT,

Good morning! It's Paul here with the SCVR for Thursday.
See the header above for the company updates that look interesting this morning. There might be room for more, depending on how I get on.
.
Cloudcall (LON:CALL)
(I'm long)
I really enjoyed the investor presentation yesterday afternoon - apparently the video isn't quite ready. I'll add the correct link here when it's ready. It's well worth watching if you're interested in the company, or not entirely sure what they do (which seems to be the case with a lot of people who comment on the company!).
What I particularly liked is that 4 Directors/senior staff spoke. Usually investor presentations are just the CEO & CFO. In this case, the CEO effectively interviewed his own team, including CFO, CMO & CRO. I asked what CRO means, and how it differs from a Sales Director, just to make the point that investors may not all be familiar with these abbreviations. All speakers struck me as straight-talking, which made the presentation useful, as opposed to just PR fluff.
Key points which I put an asterisk next to, in my notes;
- "Huge, painful, and rapid" drop-off in business due to covid, but recovering strongly now - the way they talked about this gave me more confidence, as it's clearly a one-off. Also, the company and its clients are better prepared, should a second wave hit.
- CRO indicated that his goal is to "triple or quadruple" sales, to a run rate of £50m p.a., and that he's done this before, at a startup that was subsequently sold.
- Product demos are key. CloudCall has a conversion rate of 43% from demo to sales. "Incredibly high". Therefore focus is on generating more sales leads & product demos, very simple! (Cleaver: "we need more sales, and quickly", CRO: "I hear you!")
- Shareholder register is now 40% American investors. Not intending to move listing to USA (where valuations on tech cos are so much higher), but "Never say never"
- Microsoft Teams integration (beta launch in August) is very important
- Interesting product developments in pipeline - e.g. "we have 10 billion minutes of client data". If we could use AI and machine learning to interpret that data, and provide new services for clients (e.g. instant transcripts, measuring tone & sentiment of calls, etc.), this could open up new revenue streams
- Cash burn remains high
There was lots more information, but those were for me the stand-out points.
My overall impression was very good. I think, with patience, this could be a good investment.
EDIT - I've just remembered another key point. CALL showed a chart between the UK (where revenues crashed in April, then began recovering), and USA (where revenues dipped much less). This was blamed on the UK's furlough policy - i.e. paying people to stay at home doing nothing. Whereas in the USA people continued working from home. More evidence that our furlough scheme looks to have been a serious mistake, and did unnecessary damage to businesses, in some cases anyway. Let's hope, if there is a second wave, that businesses are encouraged to keep people working (from home), and not made idle again. Or furlough could be reserved for specific sectors such as retail & hospitality only, where staff have to be physically present in order to work. All interesting to ponder anyway, and write to our MPs about these things, in the hope that it might influence future Govt policy. End of edit.
Another edit: there was some confusion over what LTV/CAC is (a key metric). I've asked the company to clarify, and they've just responded to say the correct figure is 7, and not 10 as a reader thought. End of another edit.
.
Gear4Music (G4M)
Share price: 490p (up 21%, at 08:07)
No. shares: 20.95m
Market cap: £102.7m
(I do not currently hold this share)
Am kicking myself for taking profits on this share recently, as it's put out a lovely trading update today.
Gear4music (Holdings) plc ("Gear4music" or "the Group"), the largest UK based online retailer of musical instruments and music equipment, today announces an update due to strong trading in the first quarter of the current year which is now expected to be ahead of the Board's expectations.
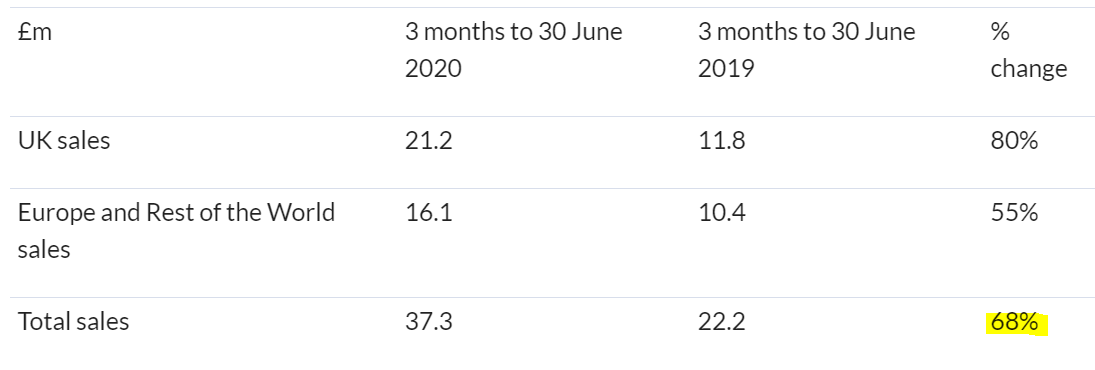
This is Q1, since the year end is 31 March 2021. Clearly there will have been a strong boost from lockdown, but even so these figure below are very impressive. Particularly as the company's strategy has been to focus more on growing the gross margin, as opposed to chasing sales growth. Hence there should be a double benefit to the P&L, from much higher sales, combined with a higher gross margin. All very impressive.
.
.
The CEO Andy Wass sums things up nicely, and this all sound positive;
"As previously reported, the COVID-19 lockdown created an exceptionally strong period of trading for the Group during April and May 2020, and further strong trading in June resulted in Q1 revenue growth of 68% compared with the same period last year.
The strong trading momentum has continued into July, and we continue to achieve higher gross margins and with a lower marketing cost than we would typically expect, alongside a controlled cost base.
As a result, and whilst still early in the current financial year, the Board is confident that a significant improvement in profits will be achieved for the full financial year, which are now expected to be meaningfully ahead of our previous expectations."
.
Valuation/forecasts - N+1 Singer previously (June) forecast 20.4p EPS for FY 03/2021. I can't find any update yet from them today, so have worked out the figures myself below. Equity Development has put out an update, but it only refers to EBITDA, which is largely useless because that excludes depreciation & amortisation (none of which is related to acquisitions, it's all capitalised development spend). Also, since IFRS 16 was introduced, finance costs now contain part of property rents, hence cannot just be ignored. Along with ignoring proper finance costs, and tax, all of which are cash costs. So how does EBITDA make any sense at all? It doesn't here, that's for sure.
Anyway, EBITDA forecast from ED is upped from £10.3m to £11.3m. I'll now adjust that to real world earnings, as follows;
EBITDA: £11.3m
Depreciation & amort: £(4.0m)
Finance exps: £(1.0m)
Profit before tax: £6.3m
Tax at 19%: £(1.2m)
Earnings: £5.1m, divided by 20.95m shares = 24.4p EPS
[NB. the above are my estimates, so may differ from broker forecasts]
At today's increased share price of 490p, the PER is currently about 20 - which doesn't look demanding at all, given the superb growth occurring.
My opinion - this company is performing brilliantly, and remember all the growth is organic too. The PER is now about 20, which still looks cheap for this rate of growth.
The only question is whether the growth might slow, or even reverse a bit, once we get into 2021, and (hopefully) lockdown is a thing of the past?
I'm absolutely kicking myself for selling my shares recently, which was clearly a mistake. I'll aim to buy back in, if the share price falls back once the excitement of today's positive trading recedes. Well done to holders, G4M is clearly on a roll. It's a very nice, well managed business, and still reasonably priced too.
.
Dotdigital (LON:DOTD)
Share price: 115.75p (up 4%, at 09:17)
No. shares: 297.9m
Market cap: £344.8m
dotdigital Group plc (AIM: DOTD), the leading 'SaaS' provider of an omnichannel marketing automation and customer engagement platform, is pleased to provide the following trading update ahead of the publication of its full year results for the year ended 30 June 2020 in November. The trading performance in this statement is based on unaudited management accounts.
(that leaves wiggle room for any audit adjustments)
I'd need to see the full year figures in November (ridiculously late), to get my head around what's going on here. As is often the case, cherry-picked numbers in a trading update don't give the full picture. In particular this is confusing;
Adjusted EBITDA1 from continuing operations is expected to be comfortably ahead of market expectations; | |
Adjusted operating profit2 from continuing operations is expected to be in line with market expectations; |
.
We have to remember that operating profit is not a relevant number any more, post IFRS 16. As mentioned above, some of the rental costs have now shifted (wrongly in my view) into finance costs, as a non-existent interest cost. Therefore quoting operating profit is wrong, because it ignores some of the rent costs. The figures we need are adjusted (if reasonable adjustments) EPS. That's the only measure which takes into account all costs, and strips out spurious (e.g. goodwill amortisation) and one-off/exceptional costs/income, to arrive at the most meaningful number. It's also the key number we need for valuation purposes. Yet many trading updates seem to withhold this key information, and just cherry pick whatever numbers they feel like showing us to mislead us into buying the shares! I do wish we had a standard format for trading updates, and not let the PRs get anywhere near the announcements. But we can draw our own conclusions about management, if they consistently put out misleading updates. Anyway. that's a general moan, not specific to DOTD.
Covid - DOTD says it had "minimal impact" in Q4 (Apr-Jun), which is encouraging. Whereas we saw yesterday that another high recurring revenues business Cloudcall (LON:CALL) saw a very big drop-off in revenues. It sounds as if not all recurring revenues are as recurring as they're supposed to be, so DOTD emerges here with credit.
Sorry for the delay, I'm getting a bit bogged down in this one, and can't decide if it's good or not. N+1 Singer to the rescue as its renowned tech analyst Kevin Ashton has published a brief update today (available on Research Tree) which nicely sums up the key points. He knows far more about the company than I do, so I'll just report the facts, and not give a personal view on it.
Forecast - consensus is for 4.0p adj EPS for FY 06/2020. That's a PER of 28.9 - normally I would consider that expensive, but bear in mind we're in a raging bull market for tech stocks, and DOTD has a nice cash pile, so it's far from outrageous in the current market.
Outlook -
We enter the new financial year with encouraging sales momentum, a robust pipeline, a strong balance sheet, a high proportion of recurring revenues and strong cash generation. Therefore it is our intention to invest as we look into 2021, to secure new business and grow revenue over future years.
"Invest" of course being used in the way popularised by Gordon Brown, as a cloak for spending more!
I'd be interested to find out what the key LTV/CAC (lifetime customer value, divided by cost of customer acquisition) is? Does anyone reading this know what that figure is?
Growth rate - this is my main concern with DOTD. Surely the growth rate should be booming in current conditions, and with the ongoing positive structural move towards online? Yet DOTD seems to be growing from milking existing customers, rather tan recruiting new customers. It says organic revenue growth is 12%, but also says ARPC is up 12%. This suggests that new customer wins are only replacing churn from exiting customers.
I'm therefore a bit concerned this company is looking ex-growth, in a booming sector.
Cash pile - very healthy, at £25.4m, which provides scope for ongoing payment of divis, and maybe an acquisition or two, to get the growth rate up?
My opinion - neutral, due to lacklustre growth. I can see the potential from Shopify & Magento integrations, but these seem modest so far.
I'll keep an eye on it, but would only be interested in buying if the growth rate significantly accelerates.
.
Simplybiz (LON:SBIZ)
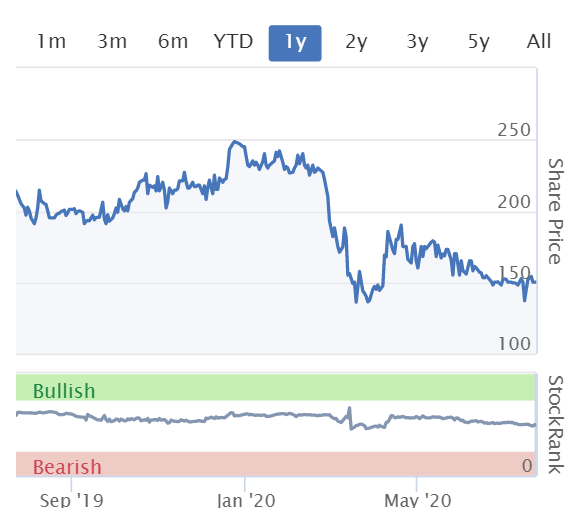
Share price: 151p (up 1%, at 12:57)
No. shares: 96.8m
Market cap: £146.2m
SimplyBiz (AIM: SBIZ), a leading independent provider of compliance, technology and business services to financial advisers and financial institutions in the UK, today issues a pre-close trading update for the six months ended 30 June 2020.
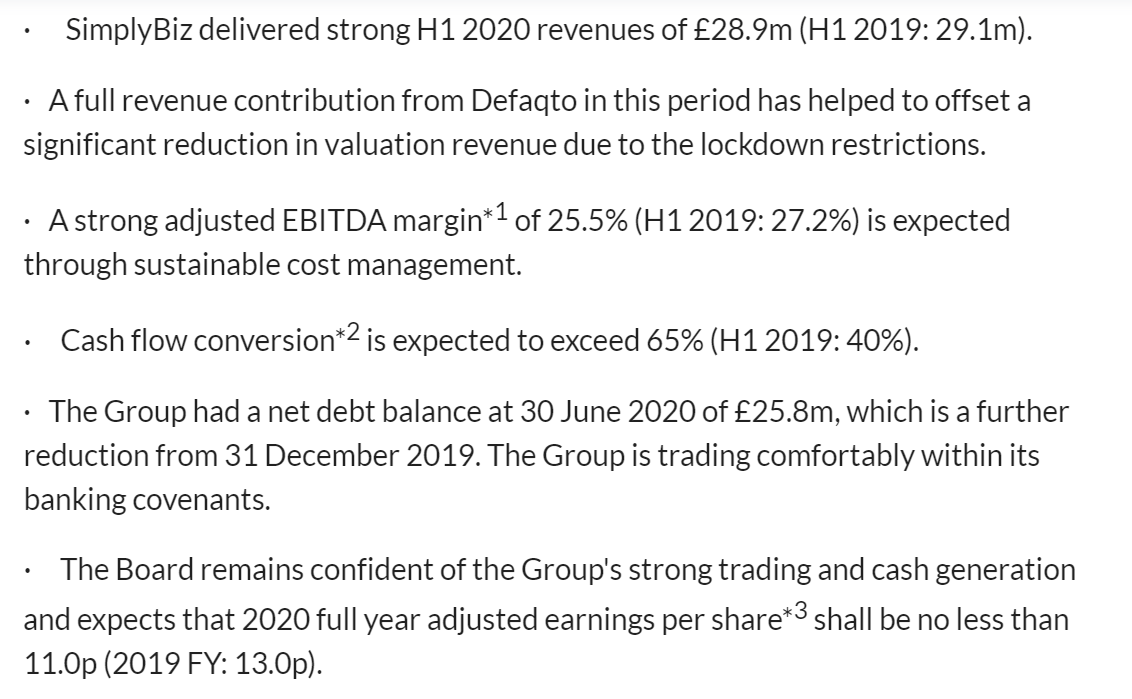
Here are the highlights they give us. It keeps saying "strong", but it's down on last year. I thought this type of subscription business should not be affected by lockdown?
.
.
The last point above is the most useful one - other companies please take note. Just tell us what you're expecting full year EPS to be, or if unsure then give a range of possible outcomes. So bravo to SBIZ for its clarity. At least I don't have to waste load of time trying to unpick reality from a load of cherry-picked statements and numbers, as so often happens with trading updates. Maybe I should introduce a scorecard system for trading updates, and put them in a league table from good to bad? Probably too much additional work, but it would be good to help steer things rather than tearing my hair out trying to interpret the variable quality output of the City,
That 11.0p estimate for FY 12/2020 makes things very easy. It's down from 13.0p last year, despite acquisition(s). Given the weak balance sheet, personally I wouldn't want to put it on a PER much above say 12. Therefore for me, the price should be about 132p for me to feel comfortable, and consider buying some. At 151p the current share price is not far away from my valuation.
Another way of looking at it, is to say that earnings might recover to say 13-15p next year, providing covid doesn't return with a vengeance. Even if it does, the mostly recurring revenues should be pretty robust, with IFAs working from home.
Balance sheet - I'm not keen at all - it borrowed too much, to fund acquisitions, in my view. But net debt is down, as you can see from the highlights.
My opinion - neutral. The weak balance sheet puts me off, but the lower share price makes it potentially interesting as a recovery stock.
.
Getbusy (LON:GETB)
Share price: 89p (up 9% today)
No. shares: 48.9m
Market cap: £43.5m
To get up to speed, I've re-read my notes here from 3 Mar 2020, favourably reviewing GETB's 2019 results.
My notes from the reassuring trading update on 5 May 2020 are here.
Half Year Report- out today;
GetBusy plc (AIM: GETB), a leading developer of document management and productivity software products, announces its unaudited results for the six months ended 30 June 2020 (the "Period", "H1" or "H1 2020").
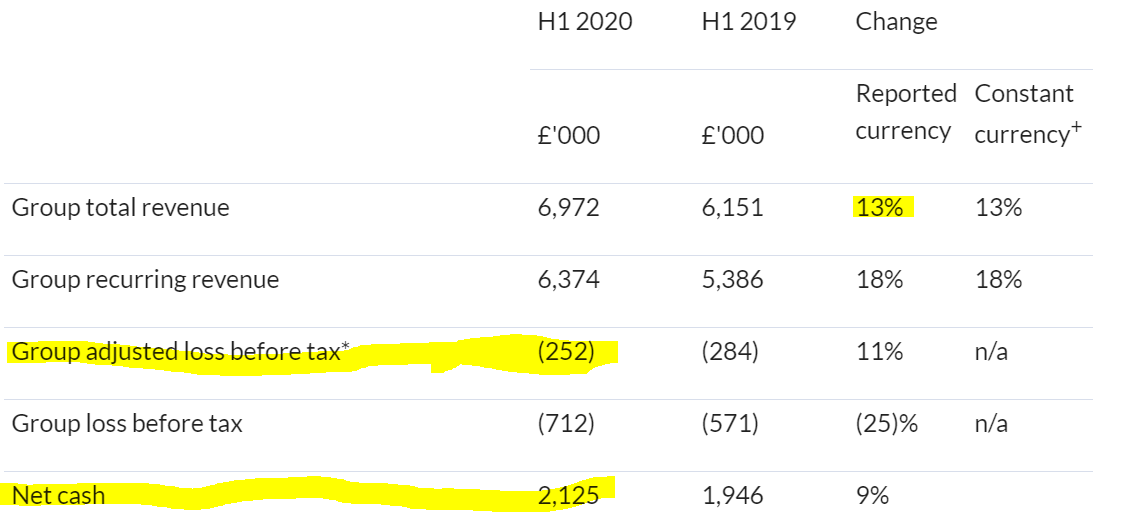
Considering that this includes the worst of the covid lockdown, these numbers look quite good to me. It reinforces the fact that recurring revenues, and work from home, have protected GETB from the covid impact, a very good thing;
.
It's running at a modest loss, which is not a particular concern, as the core business is nicely profitable, and subsidises the losses of the smaller, growth initiatives.
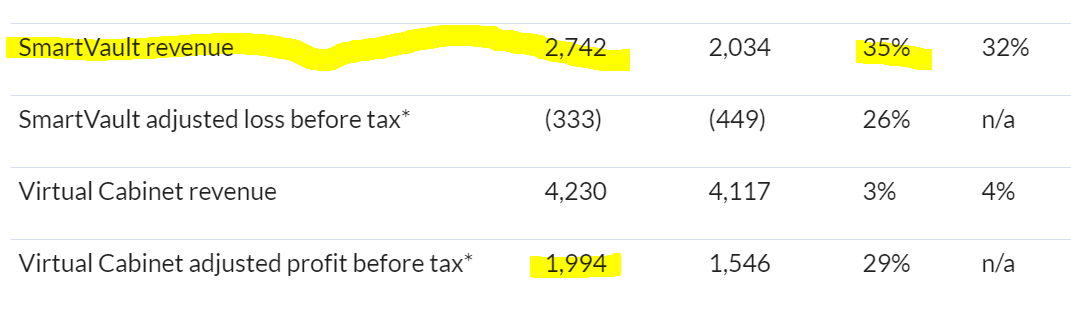
Looking at the divisional split, the core business has delivered increased profits, on a modest 3% rise in sales. The smaller division is growing nicely, so looks more interesting than before.
.
Note the extremely high 47% profit margin of Virtual Cabinet.
I've skimmed through the accounts, and here are my notes;
R&D tax refunds of £1.5m booked (4 years worth) - of which £682k cash received in the period, which covered more than the whole £547k cashflow used in operations.
Balance sheet is weak, with negative NAV of £(1.88m), less £565k intangibles, gives NTAV negative £(2.44m). Is that a deal-breaker? No, because customers generally pay up-front, i.e. the business is funded by deferred income. There is a risk that customers asking for monthly, in stead of annual fees, could squeeze GETB's cashflow. Note that deferred income fell by £429k in H1, probably for this reason. Therefore I feel that the balance sheet would benefit from another equity fundraise of say £4-5m, which would only be 10% dilution, so management should bite the bullet and get this done whilst the share price is high. My consultancy invoice is in the post!
Share options charge of £370k seems a bit steep relative to the other P&L figures, for a half year.
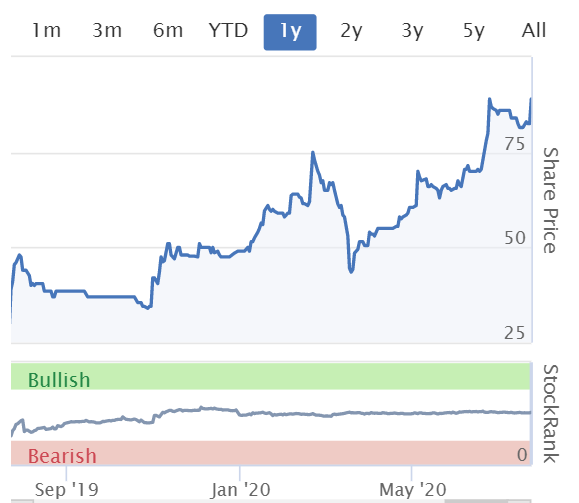
My opinion - as before, I like it. The recent rise in share price looks justified, and this is very much a topical share, which should benefit from the work from home (WFH) trends. Newer products look interesting, with SmartVault growing decently. GetBusy, the third division is not doing much at this stage.
Personally I don't want to chase up the share price any more, having missed my chance to buy at a keen price earlier this year.
.
.
Cohort (LON:CHRT)
Share price: 591p (up 3.5% today)
No. shares: 40.96m
Market cap: £242.1m
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
OPTI- to follow on from discussions on Monday
Some interesting articles below, for some balance and discussion, including a detailed contrast to Pauls review, one also being promoted via Shareprohets.
OptiBiotix Health plc (AIM: OPTI), a life sciences business developing compounds to tackle obesity, high cholesterol, diabetes and skin care announces it has extended the terms of its original manufacturing, supply and profit-sharing agreement with Agropur MSI, LLC (Agropur) as announced on 24 June 2019.....
https://lemminginvestors.blogspot.com/2020/07/optibiotix-health-wellbiome.html
On Monday 20th July Paul Scott put out another poorly researched hatchet job on OptiBiotix Health Plc (OPTI) and again today in what is nothing more than a rant at the company CEO. Stephen O'Hara - his crime? Having the brass neck to seek to assist Paul Scott in his understanding of the company and address non-factual errors by Paul Scott.
https://lemminginvestors.blogspot.com/2020/07/optibiotix-health-paul-scott-being-bitch.html
Believe Revolution Bars (LON:RBG) have just announced another 15m fund raising, or is this the previous one, fingers crossed but not hopeful
Believe Revolution Bars (LON:RBG) have just announced another 15m fund raising, or is this the previous one, fingers crossed but not hopeful
Well, if you'd spent 5 minutes checking before posting you'd realise it is the same £15m from the placing and open offer announced on 5th June. See:
https://www.investegate.co.uk/revolution-bars--rbg-/rns/fundraising--proposed-delisting--admission-to-aim/202006050700030558P/
Flipping 'eck... Si
This is the previous one. This involved a switch to AIM and this evening’s RNS is part of that. If you look back at the RNS from 5 June announcing the fund raise, you have the timetable there.
Big thanks Paul for drawing Gear 4 Music to our attention in march or april - bought then and taken excellent profit today. Hopefully price will fall back now and I will follow you back in. Cheers
Hi Paul
I think a checklist would be quite helpful given the ongoing tendency of companies not to mention whatever metric is going particularly badly for them in the latest period, be it revenue, profit, operating margin or whatever.
Not necessarily to share with us, but just so you don't miss anything important.... ....not that you normaly seem to anyway.
Best wishes and Kind Regards, Martin
Hi Paul,
Thank you for the commentary on Cloudcall (LON:CALL) - interesting growth share, though I don't hold. As I understand it, recruitment agencies are a major vertical for them, particularly in the UK - hence the sharp drop-off in revenues in the UK. The commentary in the TU goes into some depth on the increase in enquiries from the sector, as agencies have pivoted to homeworking, but need to upgrade their software to match. If true, possibly suggests employment prospects, at lease in in-demand skills, are not as bad as newspaper comment suggests. I worry about this stock that it has for some years been demonstrating profit-less growth - have they just been more honest than some in expensing customer acquisition sensibly?
Note : Cloudcall (LON:CALL) are rapidly diversifying from recruitment vertical. Can't remember the stats from the call offhand but they are now growing in a number of other verticals and the relative spread is much less recruitment weighted.
They pivoted strategy last year by raising money with a view of investing for a much bigger prize. Whether this is the right thing to do is a matter of personal opinion. I think it is the right thing to do but they are executing it on the wrong venue (ie AIM). The US market gives that strategy much more credence than the UK investors do. The difference is marked. We call it jam tomorrow and scoff at valuations and keep them low. The US are happy to pay for growth almost into perpetuity. I'm not saying that ultimately one is right and the other wrong but the US markets are up 400%+ since 2009 and the UK is down. It's a massive tech boom and Cloudcall (LON:CALL) are missing out. It frustrates me that the CEO doesn't seem to get this and has put a US type strategy in place whilst retaining a UK listing and exacerbated by the fact that they are integrating into Microsoft Teams and targeting sales growth in the US market. Just list there for heavens sake!! The new CRO clearly agrees with a US listing but the CEO appears to have his head in the sand. Which reminds me; as a shareholder I must write to him about it.
I suspect in the US this company would be trading at 4-5* its current UK value so I fear that a US investor will just buy it out at a fraction of what it could fetch. Possibly the saving grace against this is the tight insider and US institutional ownership.
No-one would bother floating a £30m cap company in the US. It would be privately funded until it was a much larger proposition. I would think it more likely that one of the US investors would take it private with a view to growing it to the stage it was worth listing.
LSE RNS delivery now working having inserted a screen asking you to confirm you are a private investor. As for the cookie confirmation I successfully negotiated the opt-out on Saleforce but Wistia just took me to a privacy policy page with no indication regarding cookies.
I can just hear Frazer in Dad's Army saying "Sheeeeer incompetence".
Morning sharw, I have had the private investor pop up since the hew look launch. Today I didn't get it, just went straight to the blank RNS. my phrase Dooohhh
The only other asterix I had was that the LTV:CAC ratio was now at 10x. So for every pound spent on adding a customer you get a lifetime value of 10. That´s a high number for SaaS (GETB 4.2 today for example) and seems to be a decent increase on the 7x they mentioned at year end
Hi MightyPedro,
I must have missed that. I noted down that LTV/CAC was 7, not 10. But I could have missed it, as I was multi-tasking. If you get time, I wonder if you could point out in the recording at what point they said it had risen to 10? Either way, both are fine statistics.
Regards, Paul.
Will do...unless my memory has failed me the CEO corrected himself and said it was 10...recording not yet available and it wd be nice to see the number in print at the half-year
Great, thanks.
I've edited this bit, as I've just spoken to the CEO, and he clarified that the correct LTV/CAC figure is indeed 7, and not 10 ("I wish!!" he quipped).
Also, the video is being edited, to take out the technical glitch at the start, so it will be available later. I've asked them to let me know when it's up, and I'll put the correct link back into the article above.
I like the IMC platform, but found the slides too small to read comfortably, as they're surrounded by a large black border on my screen. Enlarging the browser view percentage actually made the slides smaller, and the border larger!
Apart from that, I think the IMC platform is pretty good. Minor technical glitches (like Mr Cleaver accidentally logging himself out for a few minutes at the start!) don't really matter when it's online, because we can do other stuff on our computer whilst we wait.
I'm really enjoying all these online meetings, including the ones from others, such as ED, PIWorld, etc. It makes the day so much more productive, although I do miss the free sandwiches & the occasional glass of wine from city lunchtime meetings!
EDIT - I've just realised it would be easier for us if I ask the company directly, so I've just emailed Simon Cleaver to ask if the correct LTV/CAC figure is 7 or 10. I'll report back, he usually replies quite quickly.
Paul - your link still works! I found the slides OK to read if you go into full screen mode by pressing the symbol under the bar:
Brilliant, thanks for your help sharw!
I didn't see the full screen symbol, as was sitting outside in bright sunshine on my laptop. I'll use that feature in future. Thanks again :-)
Apologies my bad. minute 12...he corrects from 7.5 to what sounded to me like 10 but was 7. I´ll blame the broadband connection rather than admit to any incipient deafness ....though its quite hard to detect. Your multi-tasking better than my 100% focus.!
My morning smallcap tweet: Part 2/2
dotDigital (LON:DOTD) SimplyBiz (LON:SBIZ) £2019 Equals (LON:EQLS) Kin and Carta (LON:KCT) Personal Group (LON:PGH) Animalcare (LON:ANCR)
dotdigital (DOTD) guides FY(June) rev-organic up 12%. Adk EBITDA-cont comfortably ahead of market expectations, adj op profit in line.
SimplyBiz (SBIZ) guides H1(June) rev down 1%. FY Defaqto contribution offset lockdown. Adj EBITDA margin 25.5% (27.2%)
SBIZ guides FY EPS at least 11.0p (2019 FY: 13.0p).
Equals (EQLS) guides H1(June) rev up c. 1%. Excluding B2C Travel Money rev up 23%. Overall trading in line with management expectations.
Kin and Carta (KCT) bank relaxes leverage covenant. Net debt reduced through H2. Pension deficit repair contributions paused for 5 months from Apr, flattering debt position. Guides H2(July) organic net revenue down 20%, total rev down 10%. Expects tough H1.
Personal Group (PGH) guides H1(June) rev flat, EBITDA £5m, comfortably ahead of mgmt expectations at the start of the pandemic. Hopes to pay full Q3 div of 5.9p. Confident.
Animalcare (ANCR) guides H1(June) rev down 4.4%, at the higher end of range of scenario modelling. U/L EBITDA margin flat.
IG Group (LON:IGG)
Interesting piece in their update today
"The Group's differentiated business model of internalising, or netting, client flows and hedging the residual risk in each market remained unchanged during this period, as did the Board-approved market risk limits. The Group's revenue does not benefit from client trading losses, nor is it exposed to client trading profits. This model has been an essential part of IG since it was founded almost 50 years ago, and demonstrated its value throughout the unprecedented activity levels in Q4 FY20. Market and credit risk were closely managed and clients were able to continue to trade, for example, when the market experienced a 30% gap in the price of oil in March and a brief move to negative oil price futures in April 2020. The Group has not experienced any loss-making days since 2015."
So IG are not selectively taking the other side of clients' positions it seems. Good sign as a business in for the long run, rather than spec off client positions.
Any idea why their SP dropped? I thought their update was very good.
The same happened with The Mission Group and Halfords recently. I can only assume results were below expectations.
Basic EPS increased 52% to 65.3p. Dividend remained unchanged from last year at 43.2p. Maybe people were expecting a bigger dividend return.
I went into my local Halfords yesterday and there was hardly any stock in the shop and a long waiting list for bikes. If this is repeated across other stores they night be reliant on their online channel or are struggling to get hold of more stock
Graham has written about IG this morning on his Cube Investments website.
Did see a few message board comments regarding the lack of increase in Dividend
As an investor in IG Group (LON:IGG) for a number of years it is disappointing to see your comment of other (private) investors on message boards are complaining at a lack of increase in dividends. This has been well flagged by the company over the last year or so and was no surprise to me; before today I knew there would not be an increase in dividends.
From my point of view I think the results are excellent. Q1-Q3 showed good signs of growth yoy, whilst we all know Q4 was exceptional. I'm not sure of what market expectations were since I rarely read broker forecasts. This morning's price drop can be a combination of profit taking or maybe not meeting market expectations.
Personally I feel the company is well positioned for further growth (subject to regulation risk). They don't take unnecessary risk, unlike competitors as highlighted previously on SCVR. For me they are the quality choice and market leader in their field. Unless the wheels fall off I expect to remain a holder for a long time.
(Note that if private investors were expecting a dividend increase they clearly haven't "DYOR" very well!!!!)
I love IG Group (LON:IGG), my second best share +40% (even after today's 8% drop) with a 30p a share Dividend coming in October (equivalent for me of 5.3% yield in one go).
The Management are being (c)onservative in their expectation management.
As with everything, what will be key is what kind of market turbulence/surprises/horrors arise going forward.
So IGG, sensible results - shares down.
Meanwhile XLMedia (LON:XLM) 's trading update is full of waffle, lacking numbers, shy on surprises, down-playing the future, emphasising the on-going unresolved problems that the company continues to experience, no dividends, and the shares are still showing strength (on thin trading volume).
With regards Ig Group (LON:IGG) I think the fall relates to the fact that all of their recent updates (up to this one) have held a new and unexpected bumper bit of good news. This one didn't really have anything new.
In fact the way the results were presented almost minimised the year's good performance by highlighting the rather tepid performance in the first 3 quarters then adding in the exceptional fourth quarter as a bracketed extra. Don't know who thought that was a good idea!
There's a short comment on the Stocko IG Group share screen
"BUZZ - IG Group drops on stagnant outlook despite soaring profits"
but in a volatile and unpredictable market, I'm happy with that, possibly a good buying opportunity
My morning smallcap tweet: Part 1/2. Slow RNS feeds.
XLMedia (LON:XLM) Symphony Environmental Technologies (LON:SYM) Midatech Pharma (LON:MTPH) £G4M NAHL (LON:NAH) ATTRAQT (LON:ATQT) Immunodiagnostic Systems Holdings (LON:IDH)
XLMedia (XLM) guides H1 rev $27.5m ($42.5m), EBITDA c. $3.5m ($18.6m). Blames Google deranking, covid and ending media buying operations. Deranking around $1m pcm hit. Outllok "prioritising removing the penalties imposed by Google on some of its premium sites. Combined with recent encouraging signs of increased activity in Sports and Personal Finance, this would provide an increasing level of confidence in the Company's ability to grow revenue and profit in 2021 and beyond."
Symphony Environmental Technologies (SYM) positive in vitro antiviral test results for d2p antimicrobial masterbatch technology. Used Bovine Coronavirus - why not covid-19?
Midatech Pharma (MTPH) ends formal sale process after no proposals. Still exploring options for extracting value from its technologies and providing working capital. Evaluating early stage proposals including the potential acquisition of certain assets or an RTO.
Gear4Music (G4M) Q1 rev up 68%, ahead of mgmt exp.
NAHL Group (NAH) guides H1(June) rev down 21%. U/L earnings £1.0- 1.2m (£3.4m). Personal Injury enquiry volumes now recovered to 50-60% of prior year. Conveyancing recovered quickly during June. Noticeable slowing of new enquiries in Critical Care div. Not breached covenants and new covenants provide 'reasonable' levels of headroom. I hold.
Attraqt Group (ATQT) guides H1(June) broadly in line with the Board's expectations. Significant increase in usage volume but new bookings slowed.
Immunodiagnostic Systems (IDH) Q1(June) rev down 39% due to postponements of routine testing. July rev down <20%.
If possible in the time, a few words on KETL appreciated.
Hi Mesb
My position in £KETL stop-lossed a while back protecting a small profit and I had been quietly watching about buying back as it yo-yo'd.
The company is doing what it says on the tin, increasing it's products and it has now confirmed that the new factory should be online August(ISH) 2021, yes wish I had bought back in at £1.82 but today's update has reinforced just buy and hold and (almost) forget.
Reasonable PER and Dividend, never going to 10 bag in the short term but a solid player to hold as part of the portfolio.
The only question is longer term and whether and when they are going to pay down the existing debt, and how much do they have out there owing on various Government schemes too which will unwind over the coming year(s).
Tommy
I also own Strix (LON:KETL), believe Graham did a write up on them and a SHARES tip of 2020.
My only concern is will either the UK or US anti chinese stand have any affect on the company being able to operate out of China. Will the Chinese Govt do something untoward.
Other than that it appears to be all good news and delivering on their expectations.
Thanks for taking the time to comment, Tommy and Bob. I’m an investor in KETL but I confess to being really quite disappointed by the update. Not so much in the content of the update, but more how the communication flow has been managed since March. At no stage do I think they have signalled such a big (21%) drop in sales. They might think they have spelt it out but (for example) the most recent AGM statement about a ‘solid start’ for me is disconnected to a 21% sales drop. To rub salt in the wounds, I’ve just watched the CEO interview today with Equity Development, not the most dynamic discussion ever seen. I don’t see why kettle sales have dropped so much during the lockdown, by all accounts they will have been used a lot more than before. Maybe there is disruption in the supply chain and customers have reduced stock levels to preserve cash. Who knows. Will try to brush this off.
But Strix (LON:KETL) are not a B2C player but B2B. CEO explained that most kettles are manufactured in China, and said manufacturing was on hold at the peak of the crisis. Presumably with production lines halted the OEMs were not buying KETL's components. As manufacturing has resumed so have sales to OEMs. This has been the reality faced by most physical B2B component manufacturers during this crisis. The good news is that, as you say, B2C kettle demand has held up well, as opposed to big ticket items like planes. As an example just see today's update from Melrose for a much grimmer picture in automotive / aviation. Personally I think Strix (LON:KETL) has handled the crisis with aplomb. And despite the recent run-up the valuation remains compelling on a mid-term view.
Also suggest checking out the latest (free) research note on KETL at equitydevelopment.co.uk for their take
Oooh, Mr Contrarian has stiff competition! Thanks to both of you by the way.
Is it just me or have the LSE implemented another outstanding update to their RNS service - viz, making it impossible to view announcements?
Lots of interesting updates today - maybe Property Franchise (LON:TPFG) might be worth a look - really good results under the circumstances, revenue more or less flat and reporting:
As strong levels of demand returned in June the traditional brands' network revenue was up 5% on June 2019, of which lettings revenue was up 12%
Cash in the bank has increased since the start of the crisis.
And maybe Getbusy (LON:GETB) on the theme of small companies that ought to be riding the wave of home working? Still loss making, mind. I like the tone of their announcements which never seem to try to gild the lily - e.g.:
But, despite these efforts, we haven't yet proven its ability to scale. We don't yet have a sustained and consistent track record of cost-effective lead generation. We need to mature our pricing model to better reflect the value delivered. We don't yet have a well-defined, clearly addressable market in which GetBusy is proving indispensable.
Tons of other big cap stuff - Ig Group (LON:IGG) and Aj Bell (LON:AJB) for instance continuing to seem demand driven by volatility, but seeing volume drop from that seen earlier in the year.
timarr
Hi Timarr, Re LSE RNS Today - No you are not the only one. I got a complicated cookies accept or not cog icon in the corner today - Can't just set on what opens, you also need to go to 2 providers sites. I gave up after 5 mins and I am just looking up the RNS in Stockopedia for the companies I'm interested in - I'm just using LSE as a "refer list". How (not) to role out IT!
Re LSE RNS Today - No you are not the only one.
Thankfully the LSE isn't responsible for running any economically critical IT systems ...
timarr
I use www.investegate.co.uk for RNS. You can create a free login and follow companies and it will email you the RNS. You can search by date and keyword. It's easy and hasn't fallen over in the years I've used it.
Cheers Glen
Research Tree are also pretty good
https://www.research-tree.com/newsfeed?keyAnnouncement=true&resultsTradingUpdate=true
i used investigate until for some reason it never published an rns for (lon ibpo) in fact it was the final results and last time i looked it was not in the archive
I use them too but they typically arrive about 07:25 so if you are time conscious then just use the folio set up here and they come on the front page.
Then again just had some landed in my inbox after market close so that is why Unilever (LON:ULVR) and Sage (LON:SGE) were up so much,
Must find out whether it was the LSE, Russia, China, Iran Or North Korea who decided we shouldn't be able to see RNSes this morning. I suspect the usual LSE incompetence.