Small Cap Value Report (Thu 24 Oct 2024) - BMY, IPF, LUCE, APN, DNLM, ALU Briefs: ABDN, TPK, MER

Good morning from Paul & Graham!
All done for today!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
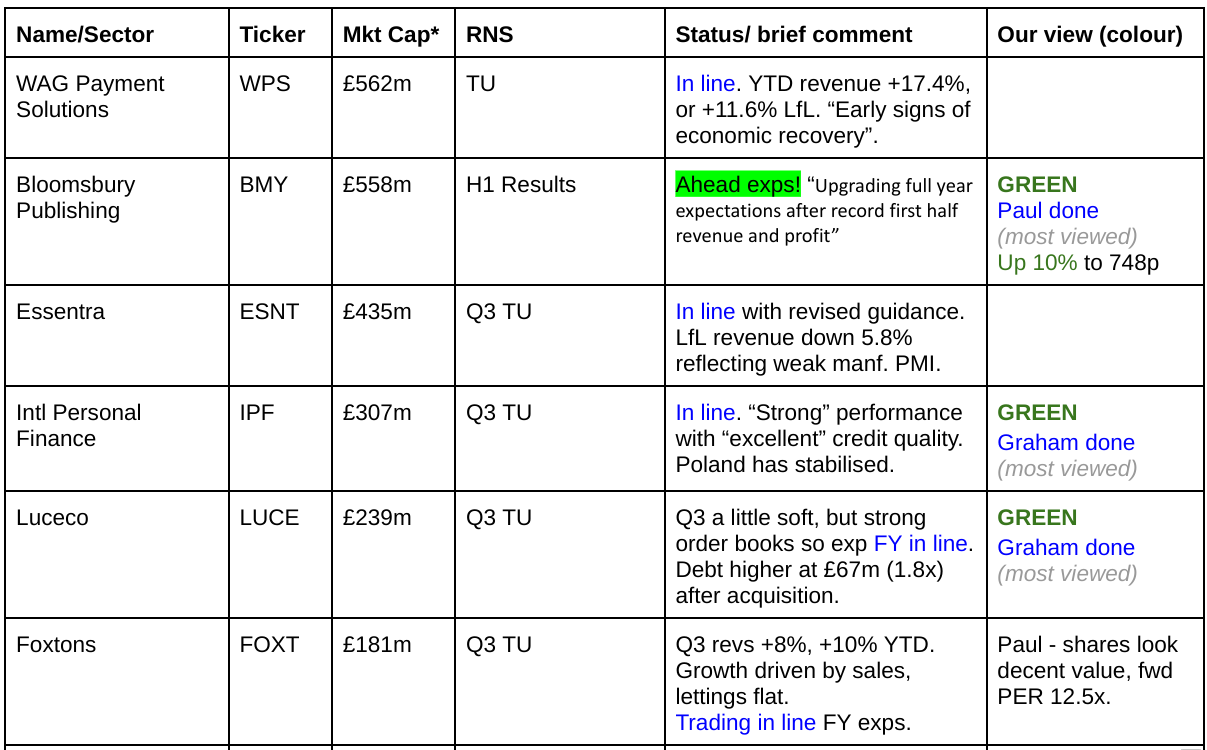
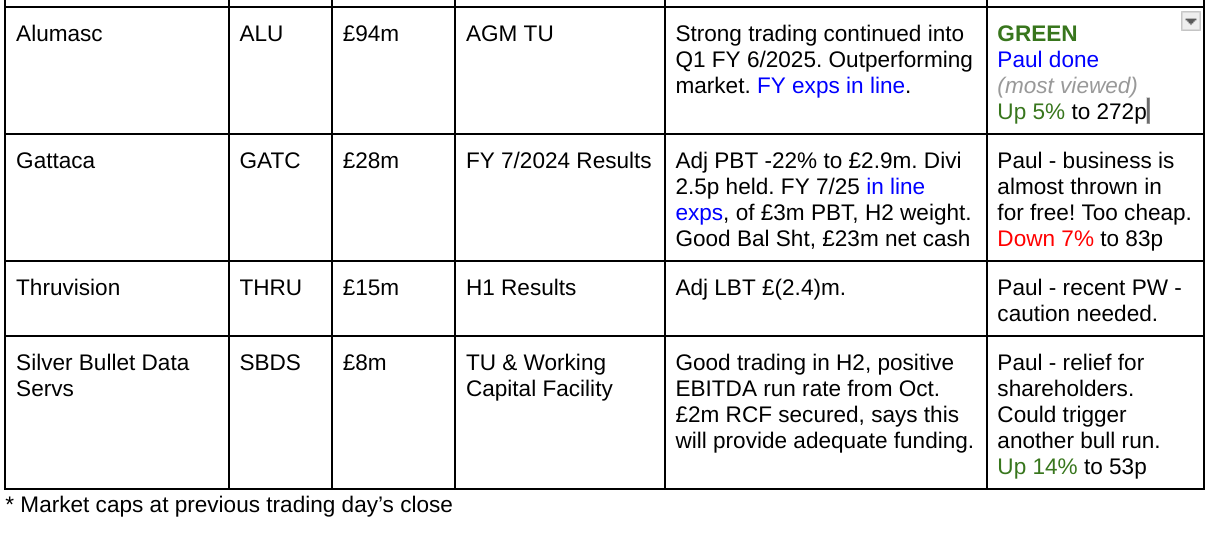
Other mid-morning movers (with news)
Abrdn (LON:ABDN) - down 8% to 151p (£2.78bn mkt cap) - Q3 Update - Paul - NO COLOUR
Adverse market reaction to this fund manager’s update.
Continuing fund outflows in Q3 from main business, partly offset by inflows at interactive investor.
In the process of deep cost cutting.
Assets under management and administration up slightly (<1%) to £507bn.
Shares stand out for discount to NTAV and remarkable 8.9% dividend yield. Large, complicated balance sheet.
Could be worth a closer look maybe?
Travis Perkins (LON:TPK) - down 6% to 870p (£1.85bn) - Q3 Update - Paul - NO COLOUR
Poor sales in its merchanting division, and only expects hesitant recovery - wider read-across? -
“Overall, the Group's key end markets are stabilising with some very early signs of recovery. Management expects to see positive growth in these underlying markets over the next twelve months, but that this growth will be slow and non-linear at the outset, with the benefit to financial performance starting to be realised in the second half of 2025.”
Second profit warning of late. Lowers adj operating profit guidance from £150m (Aug) to £135m (new).
New CEO is critical, saying business has been distracted & lost its focus.
Paul’s view - yet more evidence that recovery isn’t really happening yet in the building supplies sector generally.
Mears (LON:MER) - down 15% last 2 days (£300m) - Paul - AMBER/GREEN
I was wondering why Mears shares have fallen sharply this week on no RNSs.
The news tab on Stockopedia often contains useful news summaries from other providers, so is the first place to check what’s going on. In this case, a news digest post says that the FT has said -
“Britain ministers are keen to renegotiate terms or end the contracts for asylum accommodation with outsourcers including Serco SRP.L and Mears MERG.L as private companies made huge profits.”
Paul’s opinion - we’ve discussed this issue here before, it’s not a secret that Mears has been making bumper profits from contracts to house asylum seekers. The forecasts already show lower profits expected next year in this area. So it will be interesting to see if the company comments, and how robust its profits turn out to be, and if any changes are made to broker forecasts. The StockReport is now showing a forward PER of 9.9x, and 4.5% dividend yield.
See my review of its H1 results here on 8/8/2024.
Summaries
Bloomsbury Publishing (LON:BMY) - up 7% to 731p (at 09:23) £596m mkt cap - H1 Results & FY upgrade - Paul - GREEN
It's another ahead of expectations update from BMY, which has had a "stellar" H1 driven by two key authors. Forecasts are raised, hence my previous concerns about a stretched valuation have subsided. The cash pile has now largely gone, being spent on a large acquisition in the under-performing academic division. Profit concentration does worry me, but the figures are so good it has to be GREEN again.
International Personal Finance (LON:IPF) - down 5% to 135p (£293m) - Q3 2024 Trading Update - Graham - GREEN
An in-line Q3 update with IPF on track for adj. PBT of £78-82m. Poland has stabilised with business no longer shrinking there in terms of the receivables book or year-on-year lending numbers. All other geographies are performing fine and I continue to like this at a PER of only about 6x.
Luceco (LON:LUCE) - unch. at 148.2p (£238m) - Q3 2024 Trading Update - Graham - GREEN
An in-line update from this supplier of wiring accessories, EV chargers, etc. Q3 LfL revenue is down but with a strong order book, H2 as a whole is expected to show LfL growth. The recent £30m acquisition looks interesting and I’m happy to leave our GREEN stance unchanged for now.
Applied Nutrition (APN) - up 3% to 144p (£360m mkt cap) - First day of dealings - Paul - AMBER/GREEN
I don't touch IPOs normally, as they're nearly always overpriced and opportunistic. However this one look a decent business, highly profitable, and growing strongly. Valuation is about 18x PER, which also looks OK. Why are the founding Directors selling nearly half their positions though?
Dunelm (LON:DNLM) - up 1% to 1,202p (£2.4bn) - Q1 Trading Update - Paul - AMBER
Annoyingly vague update that doesn't say how it's traded vs expectations. So I'm guessing that it's probably in line - why not say so then? It's a good business, but with both growth and valuation seeming ordinary, I can't get excited about a PER of 15x. Divis are excellent though at 5.1% (EDIT: higher if we include regular special divis).
Alumasc (LON:ALU) - up 3% to 268p (£96m) - AGM Trading Update - Paul - GREEN
It's another encouraging-sounding, in line with expectations update. All looks good here. Valuation appears cheap, and with rising forecasts, this looks an interesting situation. I can't see anything wrong with it anyway. Is the recent pullback (AIM jitters?) a buying opportunity? It depends what happens in next week's budget!
Paul’s Section:
Alumasc (LON:ALU)
Up 3% to 268p (£96m) - AGM Trading Update - Paul - GREEN
As mentioned in the quick, early comments, this is a reassuring update which confirms trading is in line with full year expectations. So reassuring rather than particularly price sensitive - that’s why it sank down the list of priorities today.
Alumasc really stands out in this sector (building supplies) due to having an unusually strong operating margin (which it’s further increasing), and seemingly unaffected by the general sector downturn. We’ve covered it a lot in the SCVRs here.
Outlook comments are quite vague but sound positive -
“While demand headwinds in Alumasc's key markets are expected to persist for the rest of 2024, the quality of the Group's businesses and the execution of its well identified strategic priorities means the Board remains confident of delivering another year of growth, in line with its expectations.”
Broker forecasts have been rising nicely too -
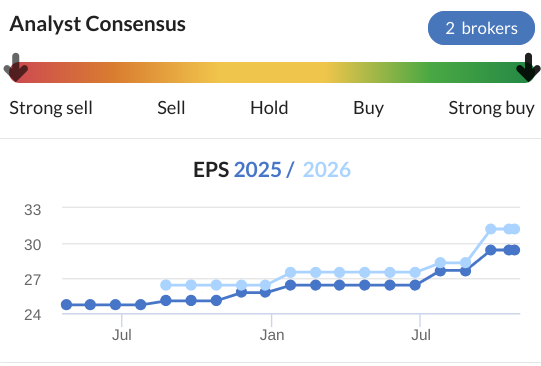
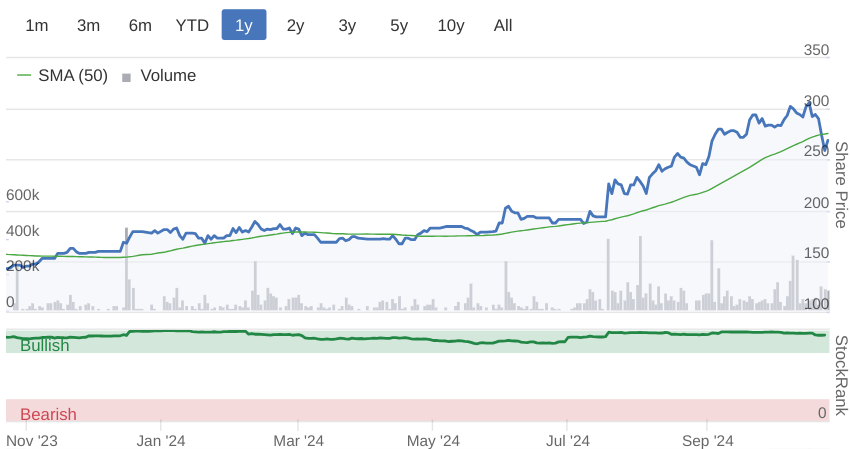
The valuation isn’t just reasonable, it still looks cheap -
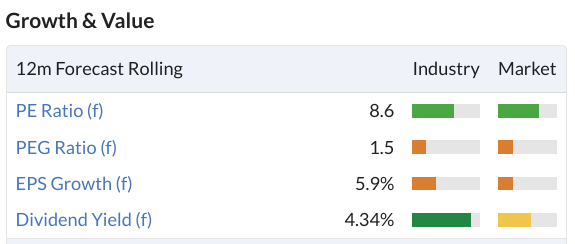
Paul’s opinion - I remain a fan, and there’s been a useful recent pullback too, so could be a buying opportunity maybe, providing nothing goes wrong?
It’s GREEN again.
Dunelm (LON:DNLM)
Up 1% to 1,202p (£2.4bn) - Q1 Trading Update - Paul - AMBER
Annoying “trading update” that doesn’t pull together the detail into a clear overall view. So they don’t tell us whether they’re behind, in line, or above market expectations.
We’re left to assume that it’s probably in line with expectations, due to -
Q1 revenues up 3.5% (total, not LfL) - “driven by increased volumes”.
“Digital” sales of 37% is meaningless, as it includes in-store sales done on a tablet.
Gross margin up slightly, 20 bps, guidance unchanged at 51-52% for FY 6/2025.
“Volatile trading conditions”, with no further explanation of what that means.
Claims to be increasing market share.
Vague outlook comments.
Paul’s view - as mentioned last time (here 13/9/2024), Dunelm is clearly a good business, making reliable profits on a good margin, from out of town sheds on retail parks (which are cost-efficient). The main attraction is the 5.1% dividend yield, which pays out most of its earnings. EPS growth looks fairly pedestrian now, and a PER of 15x looks about right. The rate of new site openings is slow now. I’m wary of all companies that get things manufactured cheaply in China, and sell them in the UK, because the Chinese are developing an appetite for selling direct, at remarkably low prices, to UK consumers. Overall then, DNLM looks OK, but not exciting either in terms of growth, or valuation.
EDIT: a friend has messaged to point out that DNLM also pays regular special divis in Feb/Mar each year, which are often enough to be considered normal. That's a good point, so I checked the StockReport's dividend data, which shows the historical yields of interim+final, but not the specials. Whereas the forecast yield shows about a 50% uplift, so that looks like it might include an allowance (maybe too low?) for possible special divis too. Anyway, it's worth checking this, as the yield could be more generous than I thought. On further digging, we think one broker might be forecasting a special dividend, but not the other, as the consensus seems to be about halfway between. Anyway, bottom line is that the forecast including special divis is about 6.5%, higher than the 5.1% forecast.
He also mentions that the pace of new site openings is accelerating, a good point.
Applied Nutrition (APN)
Up 3% to 144p (£360m mkt cap) - First day of dealings - Paul - AMBER/GREEN
Activities - sports protein drinks, sold internationally.
Dealings have started this morning for this IPO, key points -
Priced at 140p (£350m mkt cap) - lower end of 136-160p indicated ranged (in prospectus)
250m total shares in issue.
Selling shareholders sold 137.4m shares.
No new shares issued, this placing is entirely of existing shares to raise c.£198m for sellers.
Main 3 sellers are: CEO/Founder, drops from 53.5% to 30.0%, COO drops from 9.4% to 5.0%, and JD Sports, drops from 31% to 5%.
Main market listing.
Sponsor & bookrunner: Numis.
IPO documents are here.
Fast-growing, and high margin business -
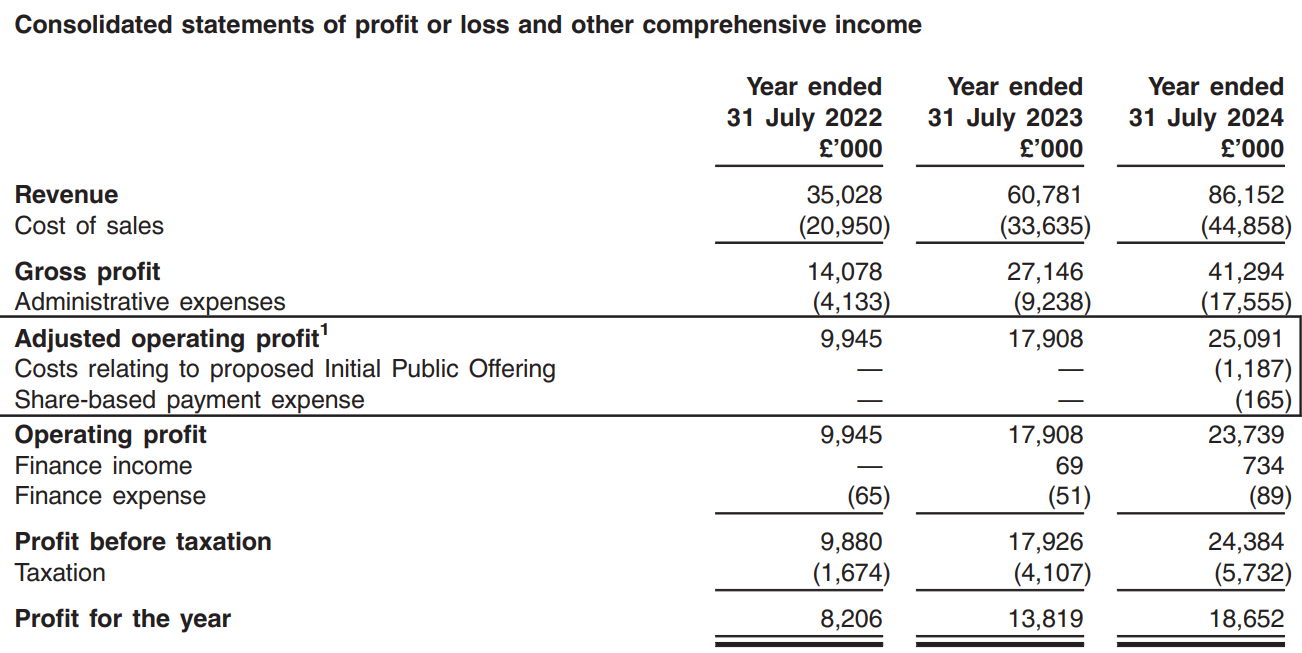
I make that 2024 earnings (assuming 25% tax), stripping out the IPO costs of about £19.3m. Divide by 250m shares = EPS c.7.7p, so the PER at 140p looks about 18.2x - that seems reasonably priced to me, assuming profit growth continues.
Guidance is for £100m revenues FY 7/2025.
Balance sheet at July 2024 looks strong. Very little fixed assets (is manufacturing outsourced?). Net cash of £18m. So it clearly didn’t need any fresh cash to be raised at IPO, financing looks more than adequate as is.
Paul’s view - this seems a reasonably-priced, well financed IPO. The big question is obviously why do the founder/CEO and COO want to cash in almost half their chips, if everything is so good?
Anyway, based on the figures provided, I think this looks moderately interesting, although I hardly ever touch IPOs, as they so frequently go wrong, often quite badly. On first impressions, I’ll give it AMBER/GREEN - worth a closer look.
Bloomsbury Publishing (LON:BMY)
Up 7% to 731p (at 09:23) £596m mkt cap - H1 Results & FY upgrade - Paul - GREEN
Bloomsbury Publishing Plc (LSE: BMY, "Bloomsbury" or "the Company"), the leading independent publisher, today announces unaudited results for the six months ended 31 August 2024.
Outlook -
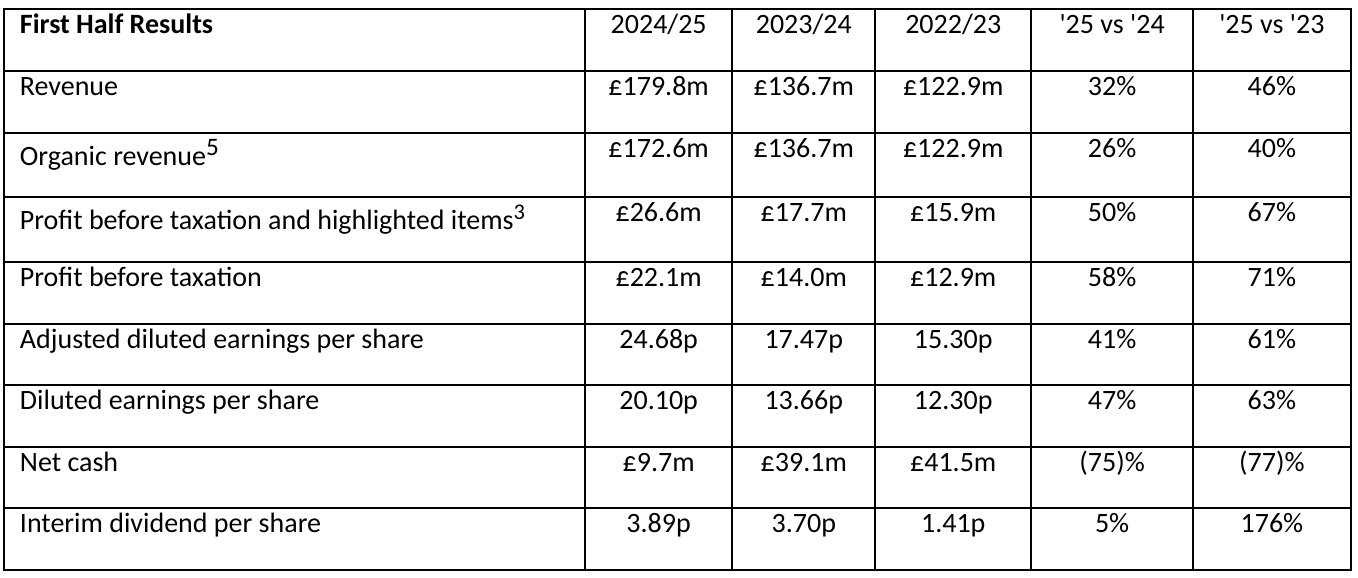
“Following our strong performance in the first half of this year and good trading in September and October, we now expect trading for full year 2024/25 to be ahead of the current consensus2 expectation."
2 The Board considers consensus market expectations (before this publication) for the year ending 28 February 2025 to be revenue of £319.3m and profit before taxation and highlighted items of £37.5m.
How much ahead? A note from Radnor has just come through, upping PBT expectations for FY 2/2025 by 6% to £39m, and 35.7p EPS.
This looks a low forecast, but as BMY has explained before, H2 this year doesn’t have any new releases from Sarah J Maas (best-selling fiction author), and they’re up against strong prior year comps. Even so, it looks to me as if there could be further upside on the new forecast. Last year’s result was higher, at 46.6p, due to the exceptional success of Sarah J Maas.
Note that BMY spent its cash pile on its largest acquisition to date (£65m), of Rowman & Littlefield’s academic publishing business. This seems to have been acquired in late May 2024 so would have contributed June-August, 3 months into the group’s H1 P&L. It contributed £7.2m revenue into the group’s H1 results, boosting organic revenue growth of +26%, to total revenue growth of +32%.
These headline numbers for H1 are undoubtedly superb -
The academic division is not performing well, with customers facing budgetary constraints. Its H1 profit fell by 12% to £5.2m, and even that was heavily adjusted up due to one-off costs incurred in the large acquisition.
The consumer division is the powerhouse of group profits, and seems to hinge heavily on Sarah J Maas and JK Rowling. No profit per author is given, but this statistic stands out -
“Bloomsbury has sold more than 55m of Sarah's books in English worldwide”
Should we be seeing BMY as essentially a two trick pony, having got lucky by signing 2 bestselling authors? Or should we admire its vision for having spotted these authors early, and securing what seems to be multi-year almost annuity type profits? (27 years so far for JK Rowling). It also mentions that new releases from Maas also tend to trigger increased sales in the back catalogue.
BMY calls its H1 results from the consumer division as “stellar”, rightly so -
“Profit before taxation increased to £21.2m (H1 2023/24: £11.0m).”
This makes the rest of the business look like a sideshow, so the profit concentration in just two authors does worry me somewhat. Hence why personally I wouldn’t want to chase up the earnings multiple too high.
Balance sheet - NAV is £203m, less intangible assets of £75m goodwill plus £63m other, gives NTAV of £65m. You could argue that the relationship with the two key authors are huge off balance sheet assets. I’d be interested to better understand the contractual relationships between key authors and BMY. Could they jump ship and move to a different publisher if offered better terms, once their exclusivity period ends? If so, that could be a serious hidden risk, so we need to know.
BMY has spent its large net cash pile on the latest acquisition of £65m. Note the appearance of £28.4m in long-term “borrowings”. This is more than offset by cash of £38.1m, so it’s a comfortable position of now modest net cash.
BMY has done a total of 34 acquisitions, so this company is best seen as a self-funding buy & build share. It’s difficult to determine if every acquisition has been a success or not, since newly acquired companies are absorbed within the whole group.
Nobody can argue with the overall results though! -
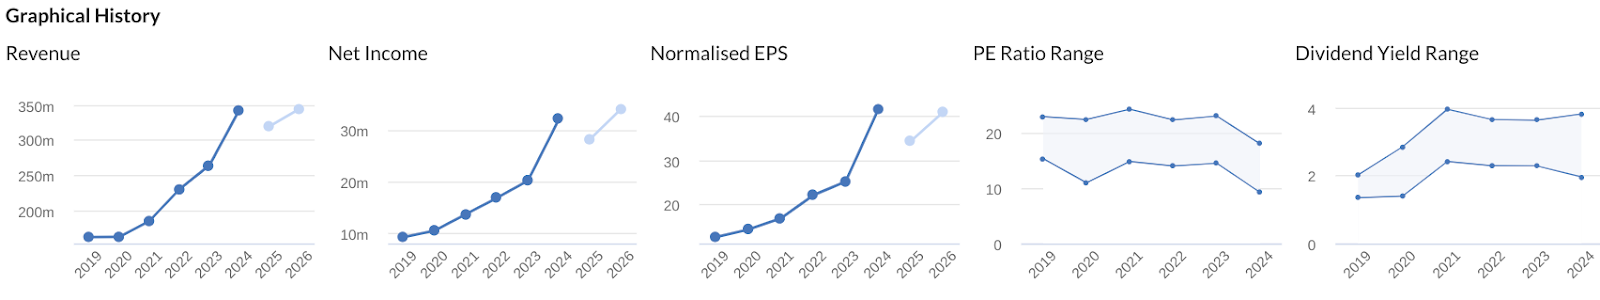
Paul’s opinion - we like BMY shares a lot here at the SCVR, and review it positively every time. I moderated from green to amber/green last time in July, since at 710p on the valuation starting to look stretched. I needn’t have worried though, as today’s ahead of expectations update has recovered all the recent slippage, and powered further up to 731p at the time of writing.
What might earnings be in future? Providing nothing goes wrong with the 2 key author relationships, then I think we could probably value BMY shares on roughly 40-50p possible future EPS. So at 731p/share I get a PER of between 14.6x and 18.3x. I think that looks a reasonable valuation.
I’m not convinced that the academic, and other areas are interesting. BMY shares are all about the stellar growth from two key fiction writers. All the evidence suggests that these are long-term winners, not a flash in the pan. Although some reviews for Maas do say that her plots and characters are very similar. I wonder how long she can keep churning them out? I mystery read one of her books, and couldn’t manage more than a chapter, so I have no idea what the appeal is, but the appeal is real - they’ve sold 55m of her books, which is all that matters.
AI is another interesting area. I wonder how long it will be before best-selling books are written by computers? It could already be happening for all we know! Could that be an opportunity for BMY? After all, not having to pay anything to best-selling authors could work wonders for its margins.
Overall, I’m tremendously impressed with how well BMY is performing, and its habit for beating expectations. With a valuation that looks reasonable again on forecasts that may be beatable, it’s best to shift back up to GREEN I think.
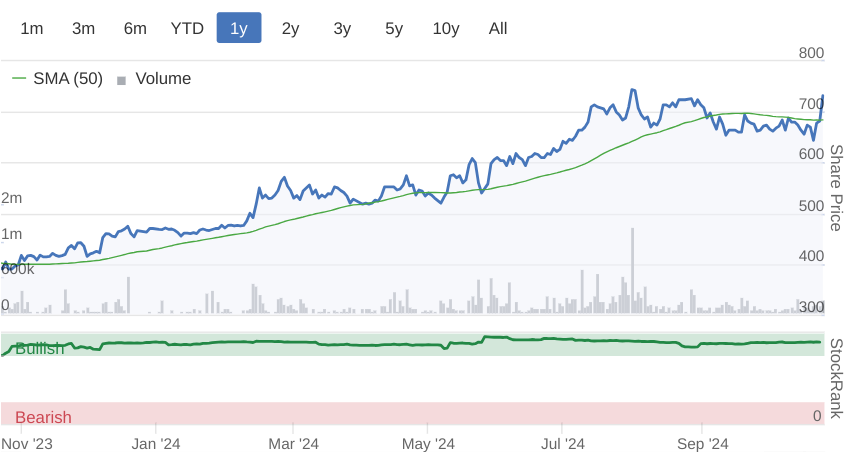
Powering ahead despite difficult market conditions this year -
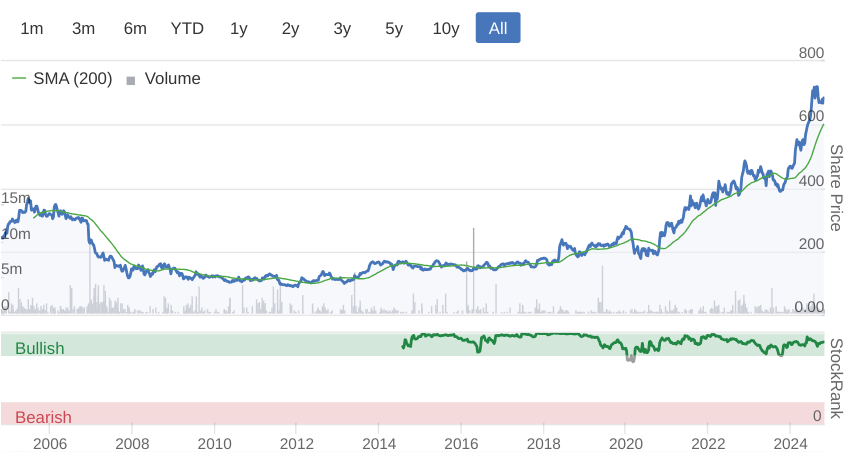
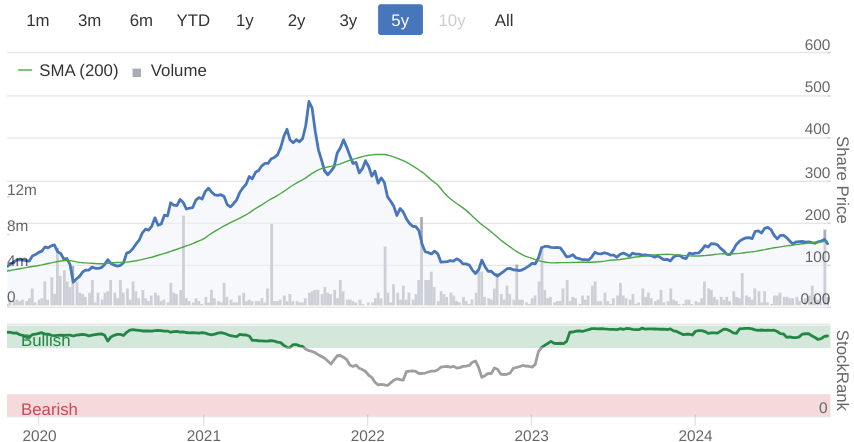
Long-term, note how BMY went nowhere for years, with all the share price appreciation starting in 2020 -
Graham’s Section:
Luceco (LON:LUCE)
Unch. at 148.2p (£238m) - Q3 2024 Trading Update - Graham - GREEN
Luceco plc…, the supplier of wiring accessories, EV chargers, LED lighting, and portable power products, is pleased to provide the following update for the three months ended 30 September 2024…
This update is in line with expectations.
Many thanks to Luceco for including the consensus in the update: adj. operating profit for 2024 is expected at £26.5m (analyst range: £26-27.2m).
Key bullet points for today:
Q3 revenue growth 3%, but on a like-for-like basis it’s down 3.6%.
Q4 order book “supports LfL revenue growth expectations for the second half”.
M&A: a £30m acquisition was announced on 30 Sep. Luceco bought CMD, a manufacturer of commercial wiring accessories, and “continues to review a healthy pipeline of M&A opportunities”.
Outlook: total revenue growth of 10% including positive LfL revenue growth in H2.
They are optimistic on residential RMI (repair, maintenance, improvement) given recent growth in UK property transactions, and are excited by new product launches in EV chargers.
CEO comment:
Luceco continues to deliver growth despite a challenging market backdrop and we are excited by the recent acquisition of CMD, a market-leading manufacturer of wiring accessories for the workplace. Improving market sentiment underpins our belief that 2025 will see a return to more normalised growth in our markets. The Group's diverse portfolio and channels have contributed to the good trading performance in the year to date and our profit expectations for the full year remain unchanged."
Leverage multiple is 1.8x, within the target range of 1-2x. By conventional wisdom, this is a reasonable amount of leverage and they expect it to fall towards the middle of their target range by the end of next year. Net debt is £67m.
Graham’s view
Roland covered this one recently but before the acquisition of CMD was announced.
I’ll have to ask him what he thinks of this deal.
At first, the price (£30m) seems a little high compared to CMD’s last-reported EBITDA (£4m). Because often, only a fraction of EBITDA converts into after-tax net income.
However, I’ve fished out CMD’s annual report for 2023 and found that it did convert almost all of that EBITDA into net income:
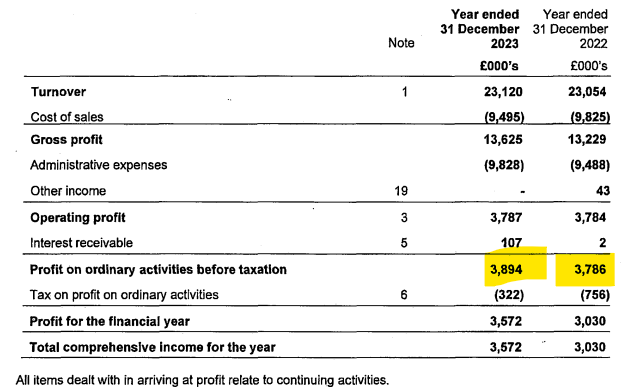
Having seen this, the price paid for CMD doesn’t worry me too much.
Overall, I don’t have a strong view on LUCE. Therefore, for the sake of continuity, I’ll leave Roland’s GREEN stance unchanged after today’s in-line update.
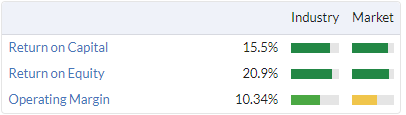
I must say that I’m impressed by the quality metrics for this company, given the sector in which it operates. Luceco has apparently cracked the code of how to manufacture in China, where they have a wholly foreign owned enterprise rather than a joint venture. Impressive!
International Personal Finance (LON:IPF)
Down 5% to 135p (£293m) - Q3 2024 Trading Update - Graham - GREEN
We have a solid Q3 update from this lender, and the outlook remains in line with full-year guidance.
Guidance is for full-year adj. PBT of £78-82m.
Excluding Poland, customer lending has grown 7% year-on-year.
Even better, the impairment rate continues to fall, reaching 9.2%, “well below our target of 14% to 16%”.
As explained by IPF management in July, their growth ambitions in Mexico and more broadly mean that they are happy to take on a significantly higher impairment rate. But so far, they have not needed to do so!
Poland: is now growing year-on-year after a big change in regulations that shrank the business. Q3 lending in Poland is up 4%, and Polish receivables have stabilised at £180m.
Latest annualised metrics (excluding Poland):
Revenue yield (revenue as a percentage of the amounts owed by customers) - is within the target range of 56% to 58%.
Cost-income ratio (costs excluding interest expense, dividend by revenue) - is too high at 55.1%, compared with a target range of 49% to 51%. I would like to read more about how they will address this, but I guess I’ll have to wait until the full-year results.
Leverage has increased slightly as the company recently carried out a £15m buyback and there has been some depreciation of the Mexican peso.
Regulatory update - no material impact expected from new cost of credit cap in Romania. Engaging with the regulator in Poland to issue more credit cards.
CEO comment excerpt:
"Our financial performance in the third quarter continued to be strong, with good growth in customer lending and receivables, as we implement our Next Gen strategy. The demand for our expanding portfolio of credit and insurance products is robust, and we continue to see very strong repayments and credit quality.”
Graham’s view
I’ve been banging the drum for this stock for some time now.
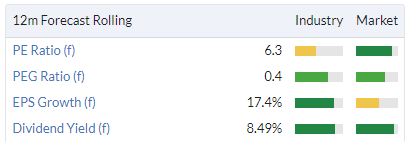
Yes, IPF carries quite a lot of risk for investors: consumer credit risk, foreign exchange risk, regulatory risk, and the company itself is leveraged (with an upgraded but nevertheless below-investment grade credit rating of BB).
In exchange for that, it offers a tempting valuation that includes a high dividend yield:
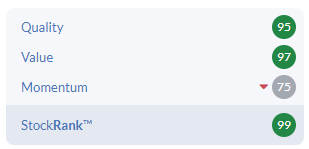
And a perfect StockRank:
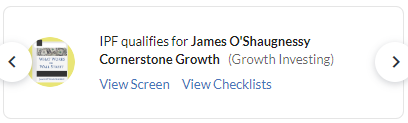
And it passes two bullish stock screens, including a Growth Investing checklist:
The trend in EPS expectations has been reasonably stable:
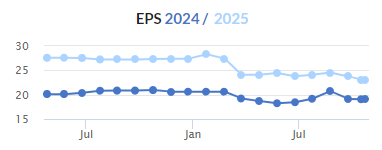
Obviously it won’t be for everyone and given the sector I don’t expect that it’s going to be a bulletin board favourite any time soon. But the risk:reward on offer continues to look attractive to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

110 comments
Gattaca (LON:GATC) - Investor Presentation video recording now available ***
Matthew Wragg (CEO) and Oliver Whittaker (CFO) of Gattaca plc hosted a live Investor Presentation with Q&A following the release of their Full Year Results for the period ended 31st July 2024. Management highlighted the key initiatives delivered in the period, including a cost rebalancing and the exit from loss-making US-based operations. The team provided a detailed Financial overview of results and insights on their outlook, before answering a range of questions submitted by viewers.
Having just moved house and needing lots of "things," I visited Dunelm for the first time and was very impressed with the cost, quality and choice that they have in store and online. I am watching their shares with interest.
Timarr if you see this wondered if you would mind giving an update on your latest thoughts re Abrdn (LON:ABDN) on the company thread you started a few months back.
Thanks
Andy
Definitely not SCV but well done any Tesla (NSQ:TSLA) holders, looks like 2025 will be transformational
30% profit margin for Tesla energy, affordable car H1 2025, FSD unsupervised H1 2025.. and they actually make money on the Cybertruck
What's not to like (don't mention Elon or politics)
+19% today
Applied Nutrition (LON:APN) anyone with any forecasts going forward?
Tried their products, all fine, lot of competition in this space. 18 x forward earnings bit rich for me, maybe!
Rockwood point .
One point that is being missed sand i had also missed .
If you held individual shares with a gain and sold CGT is payabke
Simikarly dividends are taxabke .
By holding the fund if a component company is sold / exited CGT is not paid
Richard Staveley did sone calculations showing this , its sort of compound interest effect as gains are hrld untaxed in the fund umbrella as opposed to taxed individually .
Im sure someone can explain better
But this applies to any collective investment, and tax free investment wrappers (ISA and SIPP) are available, at least for the time being... I’m sure he’s a very good salesmen as well as investment manager. Certainly sounds like it!
Personally, I never invest based on tax reasons and count CGT as a nice problem to have. I should imagine most small cap investors have plenty of losses to offset the gains, something a fund can’t do.
I think you are quite wromg
its a numerical calculation that is factual .
Bit harsh to say “very good salesperson” when its based on just the way compounding works .
I think you are quite wromg
its a numerical calculation that is factual .
Bit harsh to say “very good salesperson” when its based on just the way compounding works .
What is special about how this fund compounds then compared to similar funds? Rather than just accuse someone of being wrong back it up with facts. And if you don’t think he’s a salesperson, it’s you that is wrong. You were wrong to meet him IMHO. I can feel your biases from Cambridge!
Hollywood Bowl (LON:BOWL) have just released an RNS timed at 16.30 and 1 second about 2 considerable PMDR sales of 150,000 shares each. While i dont have a problem with directors cashing in I do object to a company trying to slip the info out in that fashion. Very poor form in my book.
Not a good look
Can't argue with that. On a similar note Elixirr International (LON:ELIX) announced a £25m secondary placing at 16:35 with the price being 650p (discounted from the current £7 level). It looks like pretty much all of the directors, NEDs and some partners are taking part in order to shift 8% of the company. Nice work if you can get it.
Coincidentally I sold my shares in Hollywood Bowl (LON:BOWL) this morning for a modest profit. The reason being the somewhat pedestrian growth and the view that more promising earnings are available elsewhere. Part of the proceeds were reinvested in Bloomsbury Publishing (LON:BMY) that has the potential to grow earnings at a greater clip.
Hopefully the acquisition of Rowman and Littlefield will in time be seen as a good buy and not a rush of blood to the head by Nigel Newton. Fingers X!
Update on smallcap IPO discussed yesterday:
"Applied Nutrition plc has successfully raised total gross proceeds of approximately GBP157.5 million. The offer was oversubscribed, meaning customers will receive 100% of the first GBP 250 invested plus approximately 56.794 % of any additional amount. The Issue Price was set at GBP1.40 per Ordinary Share."
To be more accurate, it should have said that the selling shareholders have raised £x millions, because it was seemingly a placing of entirely existing shares, with no cash raised for Applied Nutrition itself.
It seems a bit strange that the Abrdn (LON:ABDN) momentum rank is 94!
The share price has been very weak but I see that the Stockrank has been moving in the opposite direction and brokers have been upgrading forecasts.
Likely due to an increase in earnings forecasts.
Bloomsbury Publishing (LON:BMY)
Hi Paul
I really enjoyed reading your write-up here, thank you.
You mentioned that"the profit concentration in just two authors does worry me somewhat."
I agree.
Actually, I'd probably take it further and say that the entire company is reliant on just one author, Sarah J Maas.
----
Based on my own sleuthing I don't think that the Harry Potter books have made more than £7m of Operating Profit in any of the last 10 years, which isn't material now that the market cap is £600m.
As a side point I think that sales have probably declined in the last 2 years given that the company stopped mentioning YOY% revenue changes - they always mentioned this figure in the past when there was a positive change.
As a reminder the company only owns the UK Print rights for Harry Potter.
---
BDR is another area of focus, however, I mostly saw negatives here today:
I don't think I've seen this happen before.
----
3 other negatives that stood out for me today:
Given that Adult posted a -11% Operating Loss in FY24-H2 (-5% for the FY) I see this as a bad sign that things are not improving and the company wants to use SJM to mask weakness.
I wonder whether the recent acquisition made in this same sector will turn out to be ill-timed.
There are a lot of negative comments above, so for full disclosure I think it's important to highlight that I sold out of my LT position earlier this year. The market clearly liked today's results, but so far I have no regrets. There's just too much concentration on 1 author, I can't see where growth is going to come from and I personally think the valuation is about right.
On a more positive note I follow the Amazon Top 20 US Most Sold listings each week and it's remarkable that SJM still has 2 books in there at the moment.
https://www.amazon.com/charts/...
It will be interesting to see how things pan out over the next few years and if the company is able to find material growth from other areas.
A
Abtan, that is a brilliant overview of BMY, thank you for posting.
I have to agree abtan. Bloomsbury Publishing (LON:BMY) has done a great job finding two phenomenal authors that have consistently produced great profits and cash. However, the rest of the business has been pretty ordinary at best. The multiple acquisitions in Academic Publishing mask poor underlying performance. Special Interest hovers around zero profit and most of the Adult division authors are also unprofitable.
So, its congratulations on these results but I am not tempted to get back on board now (although like abtan, I admit I sold too early!).
Some nice detective work there and always good to get a better idea of the fuller picture behind the numbers.I'm guessing they invest in a wide range of 'early stage' authors.I guess they only need one or two to become future international bestsellers.I wonder what kind of algorithms/data science they use (speaking of 'ai') or whether it's more still a feel, experience, relationship sort of thing.And also wonder why they are in the academic book business?Seems like a tough business and with no fangirls/fanboys chasing after your product (and the sequels) if you do it right.
Re: Mears - asylum housing contracts
The FT article was mentioned yesterday. It suggests that the Government is considering applying a break clause to the 10 year contracts awarded in 2019. This break clause could be implemented in 2026.
Three companies were mentioned by the FT as being affected - Serco, Mears and what appears to be private company.
The FT says that the value of these contracts is 4.6 billion though it is not clear from the article if this is for the full term (10 years) or till the break clause.
These contracts would seem to be in addition to the hotel asylum bill which is reported as running at 8 million a day and likely to increase as it would seem that more hotel accommodation has recently been booked.
Whilst these contracts are very large it is difficult to see what the Government can do. There are a limited number of companies which run these schemes and the numbers of seekers increasing.
I looks to me like the Government has a rather weak hand here. I don't hold either Mears or Serco but thought the original FT article might be of interest for discussion
I looks to me like the Government has a rather weak hand here.
Without knowing detail i would agree it does seem plain wrong that the government can turn around and insert a break clause where non exists ? hey ho if its true probably nice compensation package due to some offshore entity in 4 years time that buys the legal rights to sue from administrators when these companies go pop after the contracts are stopped mid term - or it could be nefarious destabalising nonsense being spouted by the FT. comments kinda tongue in cheek i offer no proper informed commentary as to how solvent these contracting companies are. Perhaps mid term is enough notice for orderley closure and firms will benefit by getting other similar work?
In defence of the FT rmillaree, the article was well written and imo far from destabilising nefarious nonsense. As intuitive6191 wrote break clauses were written into the contracts for 2026 which is what the Government are thinking of using.
Thanks for the correction JASVFS
if the break clauses are already present then that does make much nore sense - as you say the FT probably shouldnt be put in the same bucket as the daily mail and their bretheren.
Hi, apologies for the non small caps question, however I have been struggling for an answer so hoping this knowledgeable community can help.
I am looking to find historical share price for companies in tabulated form. Anyone know if this is easily available?
Thanks
Re historic stock prices - Mr Microsoft says try this https://support.microsoft.com/...
Hello SouthernHighlander, I've used yahoo finance in the past for this. Search for the company, and then select 'Historical Data' on the left hand side. I'm sure you used to be able to export the data but I don't see that as an option now. Hope this helps you.
The best (free) I have found is googlesheets. The googlefinance function has more tickers than even paid services, and if you are feeling tasty you could write something to interact with the googlesheets API.
edit: this is much better than the microsoft offering (which you have to upgrade to an Office 365 licence in order to get the stock data type, which is a subscription based offering) - MS doesn't even offer index data
All of the prior suggestions are good.
However, if you don't want to even bother learning the spreadsheet formulae, and API is what you are after a beer, then I recommend investing.com
Look for a UK stock then click on the "Historical Data" tab and Bob is indeed your tabulated uncle.
Investing.com is also a useful source for historical data on total return indices - which are a glaring omission from Stocko.
ah come on now ! beers and programming dont have to be XOR, and anyway I thought that Monty Carlo was referring to the simulation rather than the cocktail :o)
Thanks everyone, appreciate the guidance and advise.
Bloomsbury Publishing (LON:BMY) Paul, I think you’ll find that Bloomsbury haven’t had a relationship with JKR since the last of the 7 original books was published at least 10 years ago. They have republished all the books many times with different covers and extracts but as far as I know, no more involvement from JK Rowling.
ABDN Fund managers in general have been having a right old time of it. Shares were 400p 10 years ago, now 150p. Not fun. It's not just ABDN either. JUP (Jupiter) down 75% over 5 years. MNG not as bad, down 10% over 5 years. Nick Train favourite SDR (Schroders) down 32% (5 years). N91 managed to be up 7% over that period.
What will staunch the flows, who knows? Perhaps we'd need to see strong rallies in UK markets for people to take interest again. Are we at the nadir.
TPK continues to struggle, I see. Shares down 37% over 5 years. It's odd when you compare it with a company like HWDN, which is up 50% over the same period. TPK has only managed a ROE of 5% over the last 6 years, whilst HWDN is in a completely different league at 32%. HWDN has an interest cover of 25, whilst TPK is uncovered (ouch).
Bloomsbury Publishing (LON:BMY) I hold
Yesterday on ADVFN a poster in the book business provided some data on BMY book sales which proved to be correct. Today the same person posted this:
"Just looking at the latest Nielsen Bookscan trade sales data for Bloomsbury’s current 6 month period (so Sept & Oct MTD) the total value of their UK physical sales is up by 36% (£6.7m v £4.9m PY). Last week they had a 4.7% share of the total UK market, compared with 3.8% this week last year. Looking like they have some good momentum going into the all important Christmas period."
I'm inclined to trust the accuracy of this information.
That was me. And info is 100% accurate
Hi Jean-Michel
Where can you get this Neilsen Bookscan info?
it's subscription only for the book trade, which any large publisher will have a subscriptions to in order to keep abreast of the market and competition. So not something that individuals can sign up to but available to people in the book business. And I'd imagine analysts too. It only tracks physical sales - so not digital audio/ebook sales which can be significant - but gives a clear view of sales through the tills each week. It doesn't capture US sales, which is a different subscription service.
A few negative views above, which I don't necessarily disagree with. But I don't think they're a 2 trick pony, as significant as those ponies are. Starry names aside, their educational publishing is very profitable indeed (low outlay; high margins) and I suspect the Rowman & Littlefield acquisition will be a smart one. Book publishing can be feast or famine but Bloomsbury has a v solid business, even when Sarah J. Maas starts to wane.
Nigel Newton (69) has no plans to retire any time soon, or so I hear, and seems super motivated to grow the business further before, presumably, selling up. I'd imagine KKR & Co (NYQ:KKR) who own Simon & Schuster, or Hachette/Lagardere SA (EPA:MMB) , or PRH, or HarperCollins/Rupert Murdoch, might all be eager suitors when that time comes.
BMY Should we be seeing BMY as essentially a two trick pony, having got lucky by signing 2 bestselling authors?
You raise a good point, Paul, and I think it's important not to get over-excited by what might turn out to be a one-off.
They've also got Katherine Rundell who seems to be doing some good numbers, too. They seem to have picked some really good female authors. Then there's "The Three-Body Problem"m written by Cixin Liu. That's sold millions of books. It's turned into a Netflix series. It first aired in March 2024 (source: Wikipedia). It turned out to be one of Netflix's most popular series. A second season is in the offing.
I heard in one of their presentations that audiobooks will provide them with another revenue stream. I think it's in the initial stages, but take-up was quite favourable.
I guess it's a little like Games Workshop. Just how much money can you make out of dumb tiny plastic monsters that you have to paint yourself anyway? As the Gen Z (or is it late-stage millenials?) Youtube influencers say, "The answer may surprise you."
With Boeings continuing woes you’ve got to think that Avation (LON:AVAP) are right and that new aircraft supply is going to be significantly constrained for many years to come. So their ATR options, leasing rates and aircraft values only look to be going one way. I would anticipate uplifts in NAV shortly (it usually lags performance by a few months) but seems the market is starting to appreciate this a bit more. Still probably a 40% discount to NAV though so I am hopeful of a double or more from here over next couple of years. Fingers crossed patience pays off :-D
Bloomsbury Publishing (LON:BMY) - Has anyone had the time to study this report out this morning - and who are H2Radnor ?
https://www.bloomsbury-ir.co.u...
I get h2Radnor’s emails & find they can add another layer of information to a company’s results- their note today on Bloomsbury Publishing (LON:BMY) ran to 5 pages so is quite comprehensive and they’ve upgraded their forecasts for the company by 5% on the back of todays Interim results
hi Bohenie
Bloomsbury Publishing (LON:BMY)
BMY became a recent new client of h2Radnor. The initial coverage note by h2Radnor was issued on 20th August and was a very comprehensive 62 page note. Todays broker note is their 2nd coverage of BMY.
They are a very useful addition on Research Tree. Apart from a very brief one off note by Edison on 27/10/23, BMY has had no coverage available to small private investors since 2018.
So who are they? For what it's worth here is an excerpt from the 'About Us' section their website :
h2Radnor is a new, leading advisory firm born out of the combination of Radnor Capital Partners and h2glenfern.
Established in 2004, we are a team of experienced professionals from across global equity capital markets with expertise that spans investor relations, equity research, fund management, sales, corporate finance and trading.
Snazzy
Bloomsbury Publishing (LON:BMY)
Thanks to those who have pointed to h2radnor. Note that you don't need to go through Research Tree - you can go straight in:
https://h2radnor.com/research/
for BMY:
https://h2radnor.com/wp-conten...
https://h2radnor.com/wp-conten...
Alumasc (LON:ALU) the headline is that trading is in line despite weak construction markets, but it's also worth noting the discussion of synergies from the ARP acquisition. On 25.7.23 they said “expected operating synergies” would reduce the ARP multiple to <5x assuming full payment of the earn out. Today they say “delivery of the initial synergy targets is well advanced.” Talking about “initial” synergies (I think for the first time) implies that management expects to find more synergies than were baked into the acquisition plan and that the ARP deal will turn out to better than planned. More bolt on acquisitions are planned looking at the slides from the recent CMD.
Nexergy is floating. Anybody know any info on them and whether it's likely to be a good investment. Any info would be appreciated as I can't find any info on them
Nexergy is floating. Anybody know any info on them and whether it's likely to be a good investment. Any info would be appreciated as I can't find any info on them
Being an investor in the UK is tough at the moment.
This is an excellent podcast with many helpful reminders:
?si=8pMzHMak9hkNqaGpBMY shares up 9% today based on interims. Company has been compounding its revenues per share at around 12.5%pa over the last decade. Stocko quality score is 99, which is great. It has net cash. It's on a fwd PE of 18 and a P/FCF of 18, which I reckon is not overvalued for a company of this quality.
The bulk of this is in their consumer division (Harry Potter, Sarah J. Maas, etc.), split £131m consumer and £49m non-consumer. Non-consumer revenue growth was 3%, compared to 47% for consumer. So be a little careful.
Its BDR (Bloomsbury Digital Resources) revenue grew 2% to £14m. They expect it to react £41m in 2027/28
I hold.
LON:IPF – International Personal Finance good numbers but market doesnt like seemingly and hasnt for the last few weeks with gradual selloff. Any thoughts Graham? I know your a fan
re International Personal Finance (LON:IPF) being in the duldrums, despite no bad news. I think it's just a symptom of the general malaise of the UK small cap market. If the budget brings bad news then I find it difficult to see what will turn the small cap market around. I'll probably give up with it at that point.
af20001,
Aberforth have been reducing their holdings in International Personal Finance (LON:IPF) they have sold at least two small tranches this week plus the share buyback has stopped. They may be the reasons it's unloved atm as well as the numbers not being as good as they could be?
I hold.
Graham.
"The darkest hour......" etc etc (Re International Personal Finance (LON:IPF) comment
Bloomsbury Publishing (LON:BMY)
I know the company well having been in and out of the shares several times over the last decade and always at a profit. However I should have stayed put, but that’s history. Anyway this morning I have bought back in at 736p. At that price I reckon the PE to February 25 is 18.5. The following year earnings will depend to a large extent on the next Sarah J Mass novel and progress at Rowman and Littlefield.
The shares are not optically cheap, but in the end one needs to pay for quality. As for the end game, who knows. It would make a good acquisition for one of the big American publishing houses who I am sure covet the enduring Harry Potter story, which is a children’s classic.
Rockwood Strategic (LON:RKW)
I agree with planetX regarding Richard Staveley. Having met him he has a passion for investing, which comes across in the many interviews I have watched. I am building a holding for my daughter in her ISA and think I should do the same for myself and my wife.
I am also of the view thatM&C Saatchi (LON:SAA) which I hold is undervalued being probably the most iconic global brand in advertising. For what its worth I also hold Restore (LON:RST) Funding Circle Holdings (LON:FCH) and Van Elle Holdings (LON:VANL) all held by the erudite Mr Staveley.
Bloomsbury Publishing (LON:BMY)
Annoyingly I typed a long (for me) piece on Bloomsbury's interim results announcement this morning and went to check another tab and when i returned to Stockopedia it had disappeared. I have not the inclination to start again but the gist was that the company is a serial under promiser and over deliverer. In July they issued an AGM trading update that was inline and 3 months later tell the market that HY25 revenue is plus 32% and pbt has grown 58%. I have no idea when the company or broker will release an update for expectations but the last lot were miles out at 392m for revenue and 37.5 for pbt, today they tell the market that the quieter first half produced 180m and 26.6m !!The first half is Bloomsbury's quieter half obviously with the Christmas gifting period falling into the second half of a year that ends in February. Sarah J Maas sales have more than doubled in this half without her releasing a new book in FY25 !!! With a new book due in both 25 and 26 ( ie BMY's FY26 and 27) and some more Christmas sales of her back catalogue expected for this year plus further growth for the BDR and from the recent acquisition of Rowman and Littlefield I can see eps in excess of 50p for both FY26 and 27. So I would say the shares still look cheap.
Silver Bullet Data Services (LON:SBDS)
Nice trading update - I think this is a really well run business. Good to see they are hitting EBITDA positive this month - that makes a difference, and with an RCF in place it seems there will be no raise that everyone seemed to think.
As I said I’ve watched these guys for quite a while (I do hold some) and management are tight with their equity. I like that - they don’t see the market as a cash machine, they genuinely want to create shareholder value (themselves included) is my impression. I want that characteristic in my management teams.
That doesn’t mean they will be successful mind but the odds are looking increasingly in their favour I’d say. Once they move from ebitda into cash profitability, which shouldn’t be particularly long then there should be something quite valuable there irrespective of Google dragging its feet on cookies.
Client base is good as well - probably batting above average so that shows that (a) they have something interesting and (b) management team are well respected.
Anyway up 10p today - couldn’t work out why it halved in the first place other than illiquidity but hey ho.
Silver Bullet Data Services (LON:SBDS) halved due to Spreadex selling their stake down. I took quite a few during the drift down. As you say they are punching above their weight with the quality of clients on their books.
Bloomsbury Publishing (LON:BMY) the "good trading in September and October" referred to in the update equates to UK gross sales of £6.7m v £4.9m for the same period last year. So that's up by 36%. That's the total value of physical sales through the tills (ex digital) as per the Nielsen Bookscan trade data. Gillian Anderson's erotic anthology is going well, as are others, so it's not just Sarah J. Maas. Looking like they're well set for a good run into Christmas.
Silver Bullet Data Services (LON:SBDS) The news today may change the statement in the last accounts: "We draw attention to the section headed Going Concern on note 1 of the financial
statements, which details the factors the Company and Group has considered when
assessing the going concern position. As detailed in note 1, the uncertainty surrounding the
availability of funds indicates the existence of a material uncertainty that may cast significant
doubt on the Company’s and Group’s ability to continue as a going concern. Our opinion is
not modified in respect of this matter". The revolving credit facility news should hopefully ensure the sp goes back to the 80s once the budget is out of the way.
Silver Bullet Data Services (LON:SBDS) have 2 convertible loans. the first due 31/5/25 for £2.1m and the other for £500k due a year later 1/6/26. The wording reference cash required was deliberately vague, I am not saying they will not be able to pay the £2.1m or refinance it, but that is why people are awaiting to see some real figures. Todays TU was hardly that. It said they had a good start to H2 and a record September but what does that mean?
I am pessimistic too and sold some holding this week, annoyingly some on the drift down with spreadex selling but it was looking like emergency raise was on the cards
I agree with your sentiment above, too much uncertainty in the statement that gives little confidence they won't have to tap for more money at some point. Not enough figures given I suspect there will be opportunity to get in lower again soon and it'll drift back now
My selling seems to have inspired a mini bull run confirming my timing of buying and selling is awful on some shares like this!
Thanks Zoo. That made be ponder. I was swayed because there had some time ago been a good deal of chatter on this one and I thought these people would jump back in again. That sort of statement from the company only works in a stronger market. Anyway, that was a very quick round trip! It also broke many of my rules, including being below the 200 day moving average line.
Mashley doing Mashley things - Mike Ashley requests an EGM for Boohoo (LON:BOO) so he can appoint himself as CEO.
Would probably be no bad thing Dan
Agreed - can’t be any worse than what the current management have done!
Mike Ashley is a brilliant retailer so this could completely change the trajectory of the company.
The Frasers letter isn't holding anything back
Https://frasers-cms.netlify.app/assets/files/financials/openletter.pdf
Kamani should've been buying back with all the cash he's taken out of the business - now left himself open to hostile action.
Gattaca (LON:GATC) - warning to Paul and readers. Shares look, and arguably are, too cheap. But this is a turnaround story, ie Gattaca is a loser, battling difficult market conditions and its own incompetence, not an established winner waiting for the return of demand. The company is making the right noises, but a churn rate still over 30% speaks of poorly trained and inexperienced resources, while a refocus into more attractive markets points to a poor current focus. Do you believe no one else is in those markets already, having established a solid reputation? Dislodging incumbents is hard.
All that said, the market will probably move the SP up in advance of the company having to prove itself during better trading conditions. So it could be a good trade. But why bother when Hays (LON:HAS) is going to nearly double without the same level of operational risk?
Hi BnB,
Given how Gattaca (LON:GATC) is supposedly such a bad business, I was quite taken with how relatively solid its figures are today. Some of the big name, quality staffing companies are only bumping along around breakeven, when they used to be seen as high quality cash machines. Yet GATC has managed to remain profitable.
GATC also has a strikingly good balance sheet, with net cash close to its own market cap. Poles apart from say EMR which Graham looked at recently.
So on relative valuation, I have to say GATC looks quite attractive to me, and am amazed its shares have fallen today.
Regards, Paul.
So on relative valuation, I have to say GATC looks quite attractive to me, and am amazed its shares have fallen today.
Hi Paul. Absolutely, GATC is on a better relative valuation than any other recruiter. But that discount reflects the operational difficulties that are causing it to go into turnaround mode, while other listed firms simply track time with some moderate headcount trimming, while they wait for the upturn.
In comparison to those companies, GATC
has a MUCH weaker brand
is poorly entrenched in its sectors
has almost no experienced consultants on account of momentous churn
has fledgling management
works off smaller margins - less than 1% operating margin
has been in operational decline for years
I believe the shares have fallen today because there is literally nothing in the update or the analyst coverage to point towards progress. The detail in the analyst report amounts to “we have hired a lot of staff with no experience and pointed them at better markets than we are operating in today, It can only be a matter of time before that works”. Hmmmm… I’ve said this before, with the same emphasis, recruitment is hard.
Now, if a turnaround can eventually be effected, this will be a very good investment, because the name offers a substantial risk premium today, over and above other listed equivalents. I’ve made that clear every time I’ve covered it. But any attraction that an accountant will see in the balance sheet is countered by the shudder the operating update induces in a sector specialist. Do I believe it will work out all right for investors? On balance, probably, yes, when a rising tide lifts all boats. Is this a Buffet-style hidden long term winner, laid low by circumstance. I’m absolutely certain it is not. The numbers and narrative all point towards long term decline. For traders only!
Live at 9.30am tomorrow (Friday 25th Oct) on Vox Markets Exchange, I will be interviewing accomplished fund manager Duncan MacInnes of Ruffer.
It's sure to be another fascinating conversation - including lots of investment ideas & topics such as:
1) Portfolio protection,
2) Delivering the best risk adjusted return, rather than owning the highest risk/reward assets,
3) Gold, bonds, derivatives & commodities,
4) #AMZN, #BABA, #ABX, #BP, #C, #MKS, #PFE, #ROG, #PRU, #RKT, #RIO, #MONY and #RR.
If you'd like to ask Duncan any questions, then please feel free join us here on Youtube. Everyone is welcome.
Pennant , Titon , Rockwood , Saatchi .Centaur .
Went down to London last week and had a quick meeting with Rockwood / Richard Staveley as Im probably going to let him be the custodian of my cash as clearly he knows his onions and im playing at it making some silly mistakes
And ive a few projects devouring my time now so need headspace
Lovely offices in a beautiful townhouse, spent the first 20 minutes talking about olive oil then tried to sell him a conference table after telling theirs is rubbish
Anyway
Hes trying to build Rockwood to a 250 million fund which gives him the ability to take more meaningful stakes in mid caps as opposed to being limited to the small caps . Hard to push for change when hes only got a few %
Went over how he got into it , “after watching wall street” in the 80s which is exactly same as me, was at newcastke (or was it durham) university and had to find his path into the stock market which was dominated by oxford / cambridge public school crowd. I wonder if thats why he loves being top of the investment charts as he still feels some sort of imposter syndrome or drive to show he is just as good despite not having a silver spoon.
Thats the psychoanalysis bit over . .
Funding circle and filtronic have been his runaways this yeat .
He clearly loves Saatchi and thinks the valuation is nuts and also still very keen on flowtech . Im not a huge fan of either .
We mentioned national world and I told him of my utter contempt and distaste for that weasel david montgomery and he was tight lipped but seemed to be somewhat in agreement which surprised me .
Pennant - we did discuss pennant and I thinknits a bit of a passion project for him with a 5-10 year timescale to build it up into some sort if defence group. But I think its heart over head .
Seems they have one of their buildings on the market for 3.2m NAV and i asked the ceo yesterday if when it is sold he is obliged to notify market which he confirmed . When that sells that 3 million cash hitting the bank which wipes out debt . I think its going to sell very easily .
Asked about CeO he saud very good and the chairman is clearly one of their guys .
Titon -
today they announced getting shut of their ball and chain south korean investment which is somewhat reminesscent of the Crestchic disposal of their australian division
I still think Titon is a long turnaround but today they inducate in line sales and increased margin so maybe they arent doing so rubbish.
Share price underpinned by freehold of their HQ which massively understated so lots of comfort there .
Centaur
Got the impression it was frustrating but. It was a couple days after the unexpected resignation of chairman apparently a total surprise .
New chairman is Rockwood stable so he then has to step down from the board as the other majot institution holders would be uncomfortable .
Finally
Bloomsbury - cracking results yet again a sleep at night banker class act .
Excellent insights thanks for posting planetx
Excellent PlanetX, I was wondering what happened to you last week. Missed your comments
Thank you for your appraisal, for me Rockwood is an excellent way of being invested in small caps their insights and active mgt make a huge difference.
Thank you for your appraisal, for me Rockwood is an excellent way of being invested in small caps their insights and active mgt make a huge difference.
I think we need to be careful with these types of funds. I appreciate performance has been good recently, but an illiquid IT trading in illiquid underlying investments is a recipe for disaster in a proper market downturn. And I’m sure the investment manager really thinks anyone investing in it at a premium is a complete idiot, but the marketing people will never let him say it.
Yes, you are right, being an individual stockholder provides more day to day control on buys/sells. For me it's creating a bit of portfolio diversity, appreciate your insight thanks
Re: Rockwood Strategic (LON:RKW) I don’t hold but I’ve thought about it quite a lot. Apart from the excellent performance, it is striking to me how there is zero crossover with my existing portfolio of 16 UK small/mid cap shares. Essentially, it would offer me exposure to a different style of investing (broadly, value/special sits versus quality) with an impressive fund manager. As simoan says though, the illiquidity and premium are a deterrent.
Essentially, it would offer me exposure to a different style of investing (broadly, value/special sits versus quality) with an impressive fund manager. As simoan says though, the illiquidity and premium are a deterrent.
What is important here though is that if you personally held the same shares, you’d have a decent chance of selling in a proper correction . The IT would have no chance.
I don’t hold Rockwood Strategic (LON:RKW) but wish I had.I wouldn’t be a buyer while it’s trading at a small premium to NAV but would if it goes to a discount. It’s the best performer in the UK SmallCompanies sector. At the end of this post are the highlights from their most recent trading update which speak for themselves.
Though it’s true that in a major downturn Rockwood Strategic (LON:RKW) wouldn’t easily be able to sell their holdings, there’s nothing to stop investors selling their Rockwood Strategic (LON:RKW) holding.
What happens in major downturns is Open Ended Funds/Unit Trusts sometimes ban their investor from selling, and that ban lasting while market share price falls are relentless. That doesn’t happen with Investment Trusts. Instead they just go to ever bigger discounts to NAV on a wave of heavy selling. And those are great buy opportunities for investors looking to buy that Investment Trust. I’ve bought Trusts at discounts as wide as 50% that have subsequently had the double plus of NAV rising again in due course, with the gains multiplied by a rapid narrowing of the discount.
e.g India Capital Growth Fund (LON:IGC) bought in the 2020 falls. I sold too early a long time ago after it tripled.
Highlights (Rockwood Strategic (LON:RKW) highlights:-
- NAV Total Return performance in the Period of 22.7% to 252.7p per share, which compares to a fall in the FTSE AIM All-Share of -0.4% and an increase in the FTSE Small Cap (ex-ITs) of 13%.
- Total Shareholder Return in the Period was 21.4%.
- NAV Total Return performance in the three years to 30th September 2024 of 48.3%, which compares to the FTSE Small Cap (ex-ITs) of -5.83% and the FTSE AIM All-Share of -40.5%. The Total Shareholder Return in this period was 67.6%.
- The Company's shares traded at an average premium to NAV of 4% in the Period and ended the Period at a 1% premium.
- Significant investor demand resulted in the issuance of 3,243,573 new shares in the Period, increasing the share count by 10% and, alongside performance, growing NAV to £87m. NAV has now grown 137% in the last two years, building scale. Net Cash at Period end was c.£3m, 3.4% of NAV.
- Twenty-one Period end holdings, with the top ten investments cumulatively representing 68% of NAV. Of these, nine are AIM listed, representing 33% of NAV.
I think the golden rule should be: never invest in a fund at a premium. Just ask holders of Scottish Mortgage Investment Trust (LON:SMT, Smithson Investment Trust (LON:SSON), Lindsell Train Investment Trust (LON:LTI) . I'm sure there are plenty of others.
They all have great run-ups when the style clicks. Alas, late-stage investors are sent into the tank when the style becomes out of favour.IIRC Nick Train did actually suggest people shouldn't be buying LTI at the price it was at a few years ago.
He was right.
Interesting comment "not having a silver spoon". Depends on whether one views the £15,993/term fees at Uppingham School he attended prior to Newcastle University as competing with the Cantab crowd or not I suppose. For my part, back in the day I worked at Spicer and Oppenheim and then Cazenove. All that from a dairy farm in Ayrshire, a working class state school and Glasgow University. It is a strange old world .....
I suspect Mr Staveley is not unfamiliar with mirroring*
*but also competent
Highly competent and I am an admirer and an investor. As you say, I think he has a good understanding of mirroring.
Hi James my son is looking to try and get into fund management I have a lot of contacts but would be interested in your route in if your happy to share, did you study economics at uni etc ?
Thanks.
Andy
Hi Phoenix
I have no formal expertise in economics and I have never worked as a fund manager.
I did a degree in Agricultural and Food Chemistry at Glasgow University and then joined S&O, who ended up being merged with Touche Ross after a series of incompetent audits which saw at least one partner removed from the CA register and several scandals including the Barlow Clowes gilts ponzi scheme which we signed off on. I worked in accountancy for several years, before returning to Scotland and doing a masters at Strathclyde Business School.
I then spent most of my career working in the agricultural and food sector supplying European and UK supermarkets up to CEO level. The strange thing is I took a marketing and business development route to the Board rather than a financial route. I am still a professional member of the Royal Society of Chemistry, but have long lost any professional interest in accountancy.
There are lots of retired fund managers on here who would be able to give you better advice than me. I will say I think it will prove to be a poor career choice as it is becoming increasingly difficult to add alpha as an active fund manager. When JPMorgan took over Cazenove (sold to us as a merger of equals ... the reality was survival in a post big-bang new world), the demand was for trading, stock analysis and corporate finance skills. I am now past 60, so this was a long time ago. I am told the demand is now for programming skills as the algos continue to take over, and I can see these guys ultimately being replaced with AI.
I am now a semi retired humble dilettante farmer, which is a good deal more fun than any time I spent in the City. The one bit of advice I can give which I think would be legitimate and timeless, would be to tell your son, if he is interested in business, to join one of the big accountancy firms and get his CA or ACCA. Accountancy is the language of business and he does not have to work as an accountant afterwards. I have lots of friends who qualified as accountants and work at senior level in a wide range of occupations other than audit and accountancy (which truth to tell, I found unutterably boring).
Thanks James I have a lot of contacts within the industry but most are London centric where I am based in Norfolk where there is some demand by large IFA firms to run in house models but not much else.
I will say I have learned more from the posters on here and the two chaps who run the portfolio matters podcast than I have in ten years of fund managers and fund house macro presenters.
I come into contact with a lot of reps punting cheap turn key off the shelf model portfolios the thing that amazes me is hardly any use things like gold bullion and dollar tracker etf's for the defensive parts of their portfolios.
One house prior to 2021 were heavily into long dated UK Gilts when rates were near zero so as we know now you were getting about 2% yield but were going to get obliterated on even a tiny nudge up in rates terrible positioning.
I think in their defense everyone myself included thought central banks would never get base rates above 2% as it would bring the whole system down with all the trillions owed but somehow they managed to pull it off.
Hi Andy ... what's the exact name of the portfolio matters podcast please? Many thanks indeed as ever...
Also Barlow Clowes christ I remember that , that is going back some years must be late 80's early 90's.
Something like that. I joined Spicer and Oppenheim in 1986. I think Barlow Clowes collapsed in 1988 or thereabouts.
Gattaca (LON:GATC) - just a reminder that we are hosting an Investor Presentation and Q&A with the management team at 11am this morning following their results announcement - the link to register is here: https://www.equitydevelopment....
Gattaca (LON:GATC) - ‘New’ Gattaca on track and well positioned - research report available here: https://www.equitydevelopment....
For Gattaca FY24 was predominantly about self-help, ensuring that the business was in good shape to take maximum advantage once the market turns and to improve market share in the short term. The good news is that the FY24 results were in-line with revised expectations and there are positive signs in terms of initial recovery in fee income.
Progress was made during what was a challenging year to meet many of the Board’s strategic goals. Progress was made in focusing staff numbers to align with the greatest opportunities, not least in Energy (renewables / transmission / distribution).
As regards to improving NFI, good momentum was witnessed during H2 whereby fee income rose 3.8% on a half-yearly sequential basis and was at the highest level in three half-yearly periods. In our note we cite examples to confirm our view that the UK and contract markets are in the process of bottoming out.
With no change to financial estimates and cash being 70% of market cap, we remain positive on Gattaca’s prospects and retain our 140p / share fair value.
Pinewood Technologies (LON:PINE) is worth looking at. Saw 10%ish upgrades on tues with new marshall motor contract and have announced west looks like a further 10-15% upgrade to Jan 2027 f/c at CMD today. Also suddenly an AI company, which is playing to the crowds a bit, but still.
They essentially have the only modern, cloud native motor dealership system. Most other competitors have built on older systems with apps and updates to the extent they are now creaking/need updating.
My big concern was the integration risk - felt akin to rolling out an ERP system over multiple, not yet integrated subsidiaries. However, news it has essentially happened over the UK lithia group is key. Plans to start US Lithia roll out early next year + marshals and some porsche japan/EU wins. There is def momentum and real potential.
Key is whether the OEMs see the same benefit and start mandating it. They need simplicity and dont want multiple systems to API into. Haven't seen or done full miners yet - was on 23xPE Jan 26, with some growth and today's upgrade would be sub 20x Jan 27 i.e. 2yrs fwd. If this works there should be good earnings + multiple upside.
I was sceptical before but they are answering most of the questions.
Silver Bullet Data Services (LON:SBDS) trading update:
Silverbullet has achieved record-breaking monthly revenue in September in line with management expectations, providing significant confidence of trading EBITDA positive from October.
Silverbullet has successfully secured a working capital facility allowing the Company to fully execute its growth strategy through FY25.
Renishaw (LON:RSW)
Solid, if not spectacular.
6% overall revenue growth in Q3 flattered by currency, underlying 4%. Manufacturing up, instruments down due to spectroscopy phasing. Additive manufacturing strong, cautious on future demand from semiconductors manufacturers.
+6% revenue results in +22% PBT.
Best bit is b/s with net cash up to £276m from £218m.
School run prevents further analysis at this juncture......
The shares have been through a subdued few years, the PER is now as low as I have ever seen it. I view it as a solid growth stock, but with limited opportunities outside its niche. AM is newsworthy, but will still take years to be significant. However, on a PER of under 20, it is on my list for a possible top-up.
A 2.6bm market cap puts it well outside Paul's remit.
My morning smallcap tweet: Mashley throwing his weight around at boohoo
Boohoo (LON:BOO) Titon Holdings (LON:TON) ADVFN (LON:AFN) Ra International (LON:RAI) Pressure Technologies (LON:PRES) Silver Bullet Data Services (LON:SBDS) Quantum Blockchain Technologies (LON:QBT) Bloomsbury Publishing (LON:BMY), Foxtons (LON:FOXT), Luceco (LON:LUCE), International Personal Finance (LON:IPF), Alumasc (LON:ALU)
◄boohoo (BOO)► Fight! Frasers seeks vote to remove CEO John Lyttle and make heavyweight Mike Ashley CEO. [SP=27.42 Cap=348m]
◄Titon (TON)► agrees to sell interests in South Korea ops for £750k due to losses. Guides FY rev (UK and Europe) in line and op loss slightly better than f/c. Awaits results from Korea. [SP=66.15 Cap=8m]
◄ADVFN (AFN)► warns Q1-Sept weak with no improvement in trading. [SP=17.91 Cap=8m]
◄RA International (RAI)► wins $60-70m UN contract over 3 years with 2 year option. Value includes the option. [SP=7.75 Cap=14m]
◄Pressure Technologies (PRES)► wins £2.8m five year contract to supply air pressure vessels to the Royal Canadian Navy. [SP=32.23 Cap=12m]
◄Silver Bullet Data Services (SBDS)► trading in line. New £2-4m working capital facility, ensuring support for its growth strategy through FY25. [SP=45.2 Cap=8m]
◄Quantum Blockchain Technologies (QBT)► predictive Bitcoin AI model mining tool, Method C showing good results in tests. Stockrank is zero. [SP=0.66 Cap=9m]
◄Bloomsbury Publishing (BMY)► guides FY-Feb ahead of exp of £319.3m rev and adj pretax £37.5m. [SP=682 Cap=557m]
In line: FOXT, LUCE, IPF, ALU
LSEG plz
London Stock Exchange (LON:LSEG) is an excellent business but it’s hardly a small cap. For what it’s worth, this holder was very satisfied with the TU and near double digit revenue growth. Particularly of note was the near 30% growth in electronic fixed income trading through its share of Tradeweb Markets (NSQ:TW) which I also hold independently. But all divisions reported good progress. Everything you need to know is in the RNS and I suggest you study that in detail. It’s not a complex set of numbers since the balance sheet is improving fast with the pay down of the Refinitiv acquisition-related debt. The movement at open will tell you what the market thinks of the update.
I think the acquisition announced by Ashtead Technology Holdings (LON:AT.) is much more likely to be of interest to the SCVR and an analysis would be widely appreciated. I’m glad to see some further progress at a holding that has been cruelly cut down of late by jittery investors.
Bloomsbury Publishing (LON:BMY) Interim Results look brilliant.
Headline is: *Upgrading full year expectations after record first half revenue and profit*
"The Board considers consensus market expectations (before this publication) for the year ending 28 February 2025 to be revenue of £319.3m and profit before taxation and highlighted items of £37.5m"
Given that half year results show £179.8m revenue and £26.6m profit, it is looking super impressive.
I'm surprised to see one of the most famous Spiderman quotes in the RNS
Bloomsbury Publishing (LON:BMY) wish I had taken a position at 400 per share when I had the chance. Oh dear never mind.
Bloomsbury Publishing (LON:BMY)
Maasvellous TU from Bloomsbury this morning
:-))
Indeed! Quite a maasterful performance. A maasive beat vs. forecast. Maybe I should potter on down to my broker to buy some more.
Luceco (LON:LUCE) reports an in-line update. Most importantly, freight costs have returned to norm. Hoping to open a position here once the budget us out if the way.
Well timed RNS from Alumasc to reassure investors. Thank you Paul Hooper.
The trading update doesn't provide any numbers, despite Q1 having completed, so it's impossible to tell whether they are on track to meet expectations of a 10% revenue increase.
I suspect it's a case where the brokers know more than the private investors do
Confident tone though
Alumasc (LON:ALU) Free on Research Tree is Cavendish new research note on: Alumasc Group plc, Antipa Minerals Limited, Pennant International Group plc.
LSEG plz