Small Cap Value Report (Thu 25 Jan 2024) - BBSN, WJG, ECEL, FOXT, SRC, MAB1, DOCS, YU., HFD

Good morning from Paul. Roland's with us again today!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Agenda
Crazily busy again today, but mostly "in line" -
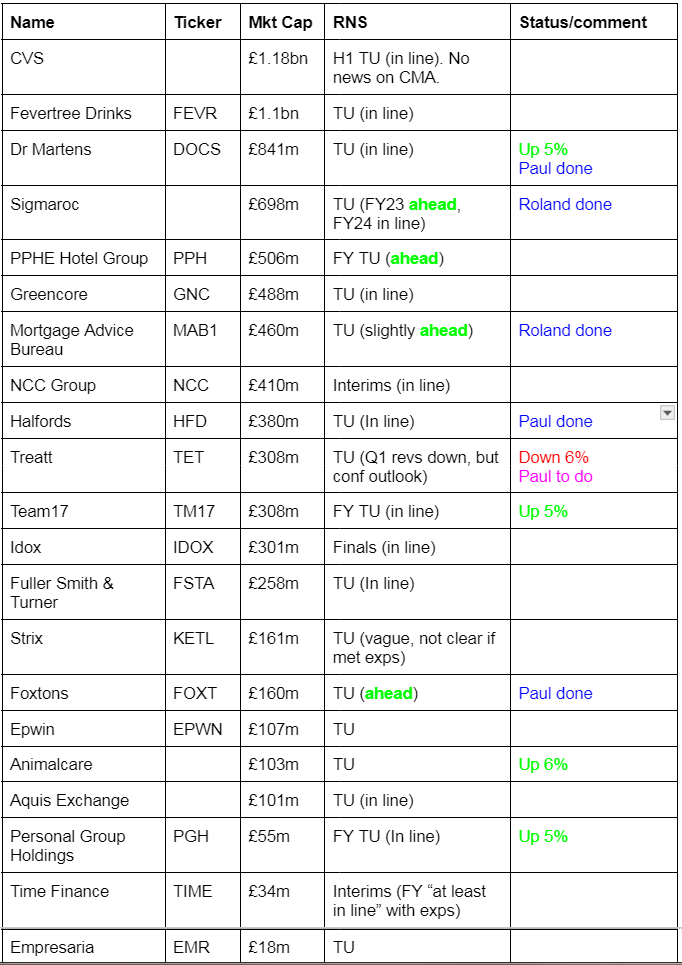
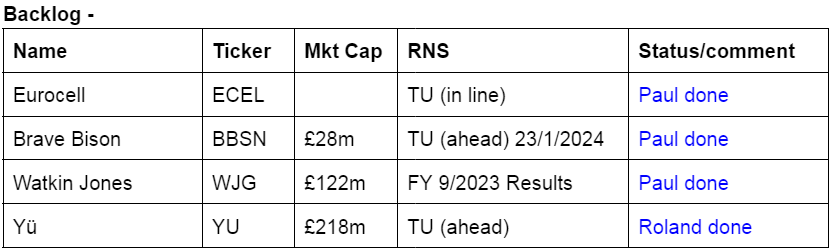
Other mid-morning movers with news
(excl resources & sub £10m m.caps usually) -
Titon Holdings (LON:TON) - down 11% to 80p (£10m) - FY 9/2023 Results: £(0.8)m LBT down -33%. Outlook weak. V good bal sht though.
St James's Place (LON:STJ) - down 9% to 616p (£3.7bn) - FuM update.
IG group (LON:IGG) - down 8% to 712p (£2.8bn) - H1 PBT down 21% despite big increase in interest income on client funds (regulatory risk?). £1bn NTAV.
Summaries
Brave Bison (LON:BBSN) - 2.15p (£28m) - Trading Update 23/1/2024 [ahead] - Paul - GREEN
I flagged this digital marketing company as interesting this time last year here 3/2/2023. My view remains positive, as it's profitable, has beaten market expectations for FY 12/2023 trading, has cash in the bank, and some impressive client wins under its belt. Looks worth a closer look, and the shares are almost 20% cheaper now than they were this time last year, despite a good performance in 2023.
Watkin Jones (LON:WJG) - 48p (£122m) - FY 9/2023 Results - Paul - AMBER
Shares have dropped 80% in the last two years for this build-to-rent property developer. At least there's no more bad news in these results not already known. Could it become a turnaround situation? Possibly, but legacy issues are still problematic & provisions will be a drain on cash. I'm leaning towards a positive view, and am reassured by the going concern analysis, and 97% NTAV support for the share price. Providing nothing else goes wrong, this could be good, but for now I will stick with AMBER until there's more evidence of a turnaround.
Eurocell (LON:ECEL) - 128p (£143m) - Trading Update (in line) 23/1/2024 - Paul - GREEN
In line trading update, following considerably lowered expectations in 2023. Strong balance sheet, starting £5m share buybacks, good divi yield. Looks attractively priced for a macro recovery. So thumbs up from me. Downside risk could be another profit warning before recovery begins?
Foxtons (LON:FOXT) - 52.6p (y’day close) £160m - Trading Update FY 12/2023 - Paul - AMBER/GREEN
An impressive 19% beat against market expectations is announced today. That's all the more impressive given how difficult the housing market has been. Foxtons has pivoted towards lettings in recent years, with acquisitions, so at 70% of revenues that makes it a lot less cyclical than before. I find the outlook comments reassuring, as it sounds as if a housing market recovery could now be underway, with mortgages below 4%. It's had a strong run recently, so not one I personally want to chase any higher for now.
Sigmaroc (LON:SRC) - unch. at 62p (£698m) - FY23 trading update - Roland - AMBER
A positive update from this European building materials group, which reports 2023 EBITDA ahead of expectations. However, a recent €1bn acquisition is still being digested. I think the valuation looks fair at the moment, but would like to see the 2023 accounts before taking a stronger view.
Mortgage Advice Bureau (Holdings) (LON:MAB1) - up 2% to 824p (£460m) - FY23 trading update - Roland - AMBER/GREEN
Q4 trading was better than expected at this mortgage broker. Trading so far in 2024 is said to have been encouraging and far stronger than January 2023. Although the valuation is up with events, I think the shares could remain attractive.
Dr Martens (LON:DOCS) - up 5% to 79p (£760m) - Q3 Trading Update [in line] - Paul - AMBER/RED
A poor update to Dec 2023, but as expected after a series of profit warnings in 2023. Peak period Q3 revenues down 21% says to me there are bigger problems than just macro. Balance sheet isn't great at £100m NTAV, with too much inventories & bank debt. Doesn't interest me at this stage, but it could be a turnaround potentially in future, who knows?
Yu (LON:YU.) - down 5% at 1,243p (£218m) - FY23 trading update (backlog) - Roland - AMBER
This business has delivered remarkable progress since 2022. This 2023 update suggests to me that momentum remained strong in H2 last year. The smart meter business could eventually become valuable, but I can see several financial risks to consider in the meantime. I suspect the shares are up with events, for now, at least pending the 2023 accounts.
Halfords (LON:HFD) - Down 3% to 169p (£374m) - Q3 Trading Update - Paul - AMBER/GREEN
Despite a tough Dec 2023, it seems to have made it up with decent Oct, Nov, and Jan, so reiterates within guided range of profit for FY 3/2024. Not seeing an immediate recovery in 2024, but I like the potential for an operationally geared profit recovery in time. Hence I'm leaning modestly positively towards this share, especially after the recent dip in price. Could it become a takeover target, as rumoured before?
Paul’s Section:
Brave Bison (LON:BBSN)
2.15p (£28m) - Trading Update 23/1/2024 [ahead] - Paul - GREEN
Brave Bison, the digital advertising and technology services company, is pleased to provide the following trading update for the year ending 31 December 2023 ("FY23").
Company headlines -
Results ahead of market expectations
Third consecutive year of growth in net revenue, EBITDA and EBITDA per share
I’m not interested in EBITDA, but it helpfully also tells us proper profit -
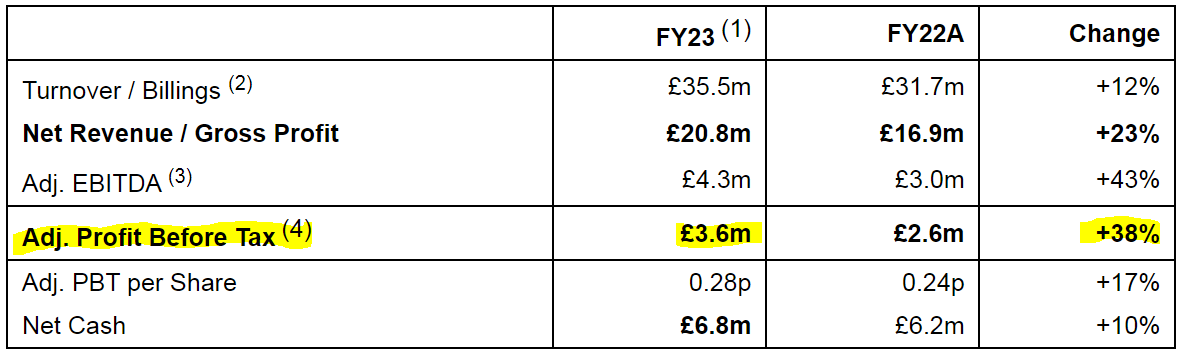
That’s pretty good for a £28m market cap company, I’m starting to get interested.
Net cash is also a big plus.
Nice client wins -
New clients won in 2023 include Pinterest, Purina, John Lewis Partnership, Holland & Barrett, ProCook, Monday.com, Patreon, The Army, Warner Bros., Aer Lingus, Markel Group, Asda, Team GB, Winparts , Fiskars and Molson Coors
Cavendish says adj PBT beat expectations by 13% (£3.6m actual vs £3.1m forecast). It did adj PBT of £1.5m in H1, so H2 is £2.1m, a nice progression. Note that the profit comes from adjusting out hefty restructuring & acquisition costs (in H1), so I'd like to see cleaner, non-adjusted profits in future.
Balance sheet - was only £2.1m NTAV on 30/6/2023, and note that intangible assets doubled in H1, due to an acquisition. So I’d say it’s an OK balance sheet, but not particularly strong. It doesn’t pay divis.
Paul’s opinion - this looks good. Interesting that a digital marketing company is trading ahead of expectations, when we recently heard a gloomy update from much larger S4 Capital (LON:SFOR) .
On the basis of these numbers, I think this share could be worth readers taking a closer look, with your own more detailed research. Hence I’m happy to stick with GREEN, same as this time last year. I’d want to learn more about how it’s achieving good profits, and whether that is sustainable? Whatever it's doing is clearly working!
Note there was some Director buying in late 2023.
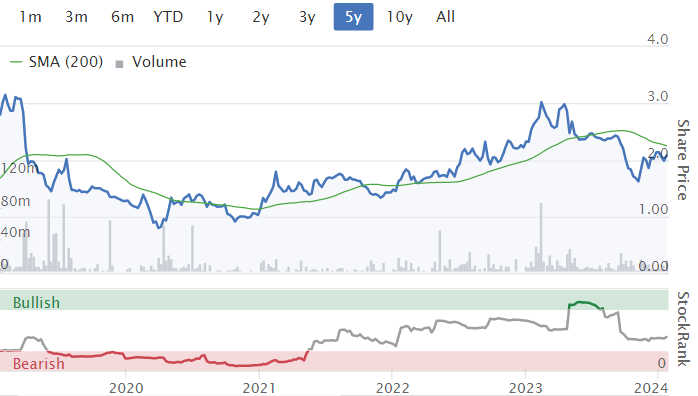
The stock market just doesn't seem interested -
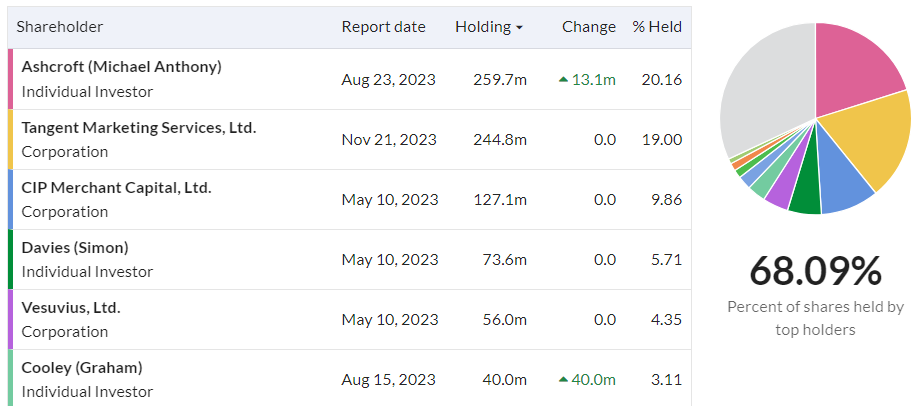
Rather concentrated shareholder list, with Lord Ashcroft being the biggest holder -
Watkin Jones (LON:WJG)
48p (£122m) - FY 9/2023 Results - Paul - AMBER
Watkin Jones is the UK's leading developer and manager of residential for rent, with a focus on the build to rent, student accommodation and affordable housing sectors. The Group has strong relationships with institutional investors, and a reputation for successful, on-time-delivery of high quality developments.
The Group announces its annual results for the year ended 30 September 2023 ('FY23')
Well positioned to capitalise on a market recovery
Shareholders have really suffered here, with previously fairly reliable financial performance (c.£50m pa profit) falling apart as the pandemic, but more importantly big interest rate hikes, not to mention operational mishaps and remediation of faulty projects, have wiped out profitability -
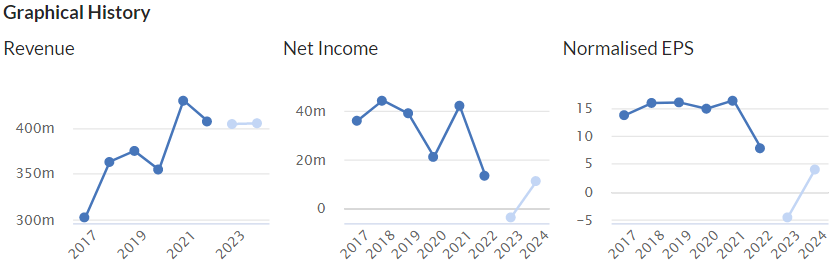
This is obviously why the shares have plummeted. Note that there has not been any dilution, with the shares in issue static at 256m over its time as a listed company - so could this be a recovery opportunity I wonder?
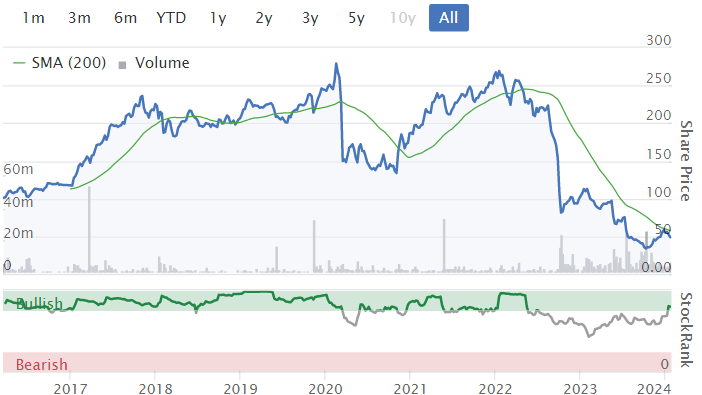
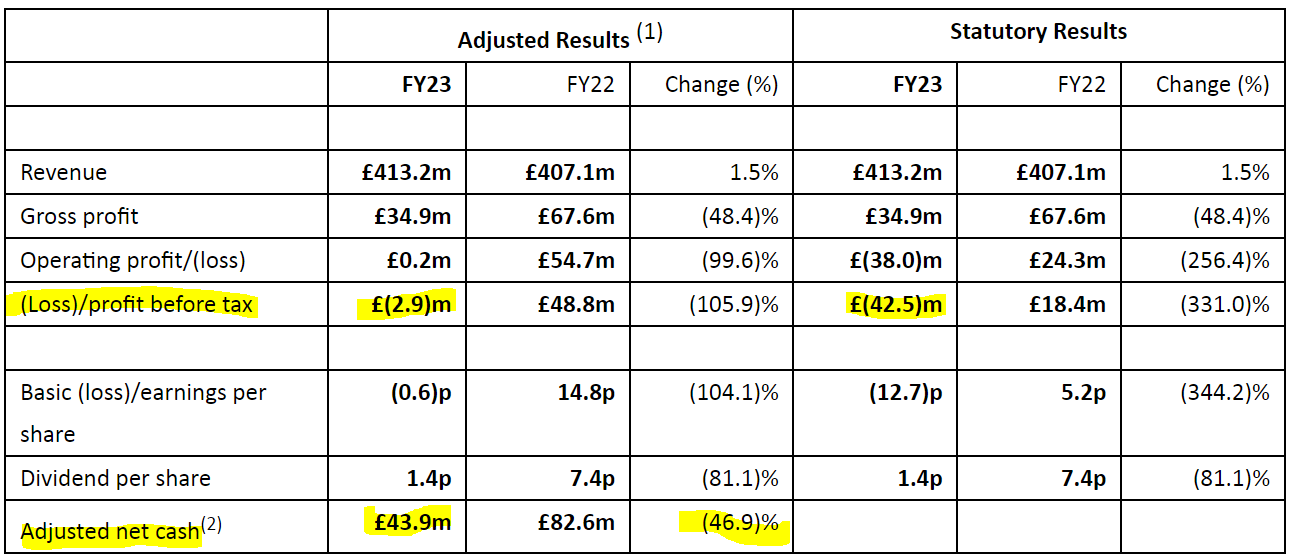
Poor results for FY 9/2023, and note the small adjusted loss is much worse in the statutory numbers (due to an additional £35m building safety remedial provision, to be spent over 5 years). Also the plunge in net cash worries me -
No divis for now.
Outlook - I particularly like point 1 saying forward revenues cover the cost base for FY 9/2024, which reassures -
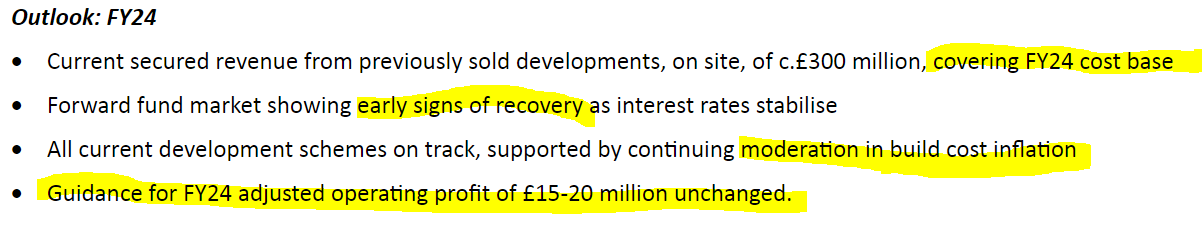
Any positive feelings from the above should be tempered by the company’s track record of being very unreliable with its forecasts previously for 2023, much too optimistic, with the bad news only slowly and belatedly released to the market -
Balance sheet - still looks fairly robust to me, especially the working capital (£311m current assets, less £134m current liabilities, giving £177m of net current assets).
Long-term debt is only £29m.
£118m NTAV overall is only a whisker below the £122m market cap.
Provisions do concern me, as they keep growing (this is for remediation work), so who knows if even more provisions will be needed? We've seen with other builders how the provisions tend to grow over time. There’s a £24m provision in current liabilities - which means £24m cash going out of the bank account this year, and another £41m in longer-term provisions. That could squeeze cash, and in the worst case scenario force a fundraise, although it does have £72m gross cash, so maybe I’m worrying too much?
Given that customers will be paying in large lumpy amounts I imagine, then the cashflow would need to be carefully managed here. It’s got additional headroom on the borrowing facilities though.
Going concern note - seems very thorough, and says bank facilities extended to Nov 2025, and that covenants have been met, and expected to be met through to 31 Jan 2025 (the going concern period, 12 months from now).
In a downside scenario, it says it could sell land assets, thus repaying the RCF and not needing covenant tests.
Overall, I think this is reassuring -
Based on the thorough review and robust downside forecasting undertaken, and having not identified any material uncertainties that may cast any significant doubt, the Board is satisfied that the Group will be able to continue to trade for the period to 31 January 2025 and has therefore adopted the going concern basis in preparing the financial statements.
Paul’s opinion - this is really tricky. We’ve seen a catalogue of problems with WJG in the last two years, which is why the share price has crashed about 80%. These latest results & outlook do at least not bring any fresh bad news. So should we be starting to think about a possible recovery? That would certainly be brave, but with the market cap now equal to NTAV, and a clean going concern statement with adequate funding it seems, then I could see a scenario where equity begins to recover, maybe quite strongly?
The downside risk is if the company is glossing over the negatives (as it has done before), only to deliver more bad news in future.
Institutional demand will probably be quite interest rate dependent, but there’s obvious end user demand for more rental property. If inflation and interest rates fall in 2024 and beyond, then it could conceivably start reporting more positive news. In the past WJG made £50m pa profit, which means any return to that level would be a share price maybe 3-5 times the current level. That’s obviously an optimistic view, but it’s nice potential upside.
Personally I’m leaning slightly towards a more positive view, but think it’s probably best if I sit on the fence for now with AMBER.
Eurocell (LON:ECEL)
128p (£143m) - Trading Update (in line) 23/1/2024 - Paul - GREEN
Eurocell plc, the market leading, vertically integrated UK manufacturer, recycler and distributor of innovative window, door and roofline PVC products, provides the following update for the year ended 31 December 2023.
ECEL had a profit warning on 5/9/2023, which didn’t unsettle the share price much at all. The strong balance sheet nicely underpins things, although timing of a recovery in trading is uncertain. Nevertheless, I like risk:reward here a lot, for a medium-term recovery, so ECEL was on my top 20 share ideas for 2024.
Share buybacks - £5m announced on 23/1/2024, began 24/1/2024 (28,456 shares)
Latest update for FY 12/2023 -
Year End Trading Update - Profits In Line with Expectations; Strong Cash Flow
Revenue £365m (down 4% on 2022)
Net cash £0.4m at 31/12/2023, improved from £14m a year earlier.
Reviewing strategy, will report in March 2024, with full year 2023 results.
Broker update - there’s nothing available to us plebs.
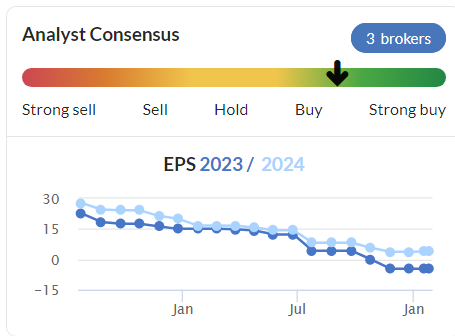
We have 11.8p EPS on the StockReport for broker consensus, which as you can see has been steadily lowered as the newsflow in 2023 got tougher due to macro trends -
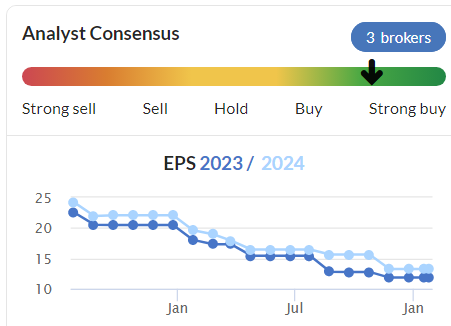
Pre-pandemic, ECEL did about 20p EPS, and there has been roughly a 10% enlargement of the share capital since then (although that will come down by about 4% with share buybacks just started). So I’m going to adjust pre-pandemic normal EPS to about 19p now, if trading recovers to pre-pandemic levels, which it should (hopefully) given time.
For this type of business, with a strong balance sheet, I think a PER of say 12x is justified, so I see upside to 228p. That’s 78% upside on the current share price of 128p, with nice divis whilst you wait.
Obviously we have to watch carefully to be sure that earnings can recover to pre-pandemic levels over the next year or two, which it might not, there are no guarantees.
Paul’s opinion - ECEL is only valued at 10.8x 2023’s rather depressed earnings, and 6.7x my target recovery earnings of 19p. I think that’s very attractive. There’s lots more detail in the announcement, I’m just focusing here on overview.
The balance sheet is really good, so investors don’t have to worry, even if trading were to deteriorate further. That would just mean having to wait a bit longer for a recovery I think.
Overall, I think this looks one of the safest ways to anticipate a gradual recovery in building products, at a reasonable price. So it’s GREEN from me.
Downside risk would be a profit warning from continuing depressed conditions in 2024, which is an obvious possibility, but given excellent financial strength, I don’t think that would come anywhere close to being a crisis, so would be something to just ride out (and top up my position if I have one at that point).
Foxtons (LON:FOXT)
52.6p (y’day close) £160m - Trading Update FY 12/2023 - Paul - AMBER/GREEN
25 January 2024 - Foxtons Group plc (LSE:FOXT), London's leading estate agency, has continued to deliver against its operational turnaround plan and outperform the market1. For the year ended December 2023, both revenue and adjusted operating profit2 are expected to be ahead of consensus market expectations3.
Footnote 2 below shows that there have been quite big adjustments, so I would need to get comfortable what these are, and how valid they seem. Why does it include £1.4m of amortisation of acquisition-related intangibles, when these non-cash costs are customarily excluded from adjusted numbers?
2 Adjusted operating profit is defined as profit before tax for the period before finance income, finance cost, other gains/(losses) and adjusted items. 2023 adjusted operating profit includes c.£1.4m of amortisation of acquired intangibles and excludes c.£4.4m of adjusted items.
3 2023 consensus market expectations being the average of forecasts provided by analysts covering the Group for the year ending 31 December 2023 (revenue: c.£144.5m; adjusted operating profit: c.£11.8m).
This is a useful 19% beat, at £14.0m vs £11.8m forecast -
2023 revenue of c.£147m (2022: £140.3m) and adjusted operating profit of c.£14m (2022: £13.9m), both ahead of consensus market expectations.
Although operating profit is not really a valid number, as it excludes finance costs, which may also include lease finance costs. Companies should be quoting adj (reasonable only) PBT as the key profit measure. Not operating profit or EBITDA! Or give all 3 if you like. It wastes our time having to check if they’ve cherry-picked a favourable metric when companies report EBITDA or operating profit. As a general point, we really need some standardisation of trading updates, as in many cases it’s a minefield of PR-driven deception (which is counter-productive and undermines trust & credibility) at the moment.
Broker update - many thanks to Singers for an update this morning. This converts £14.0 adj op profit into £13.5m adj PBT, so thankfully not much difference, which is all the more perplexing as to why FOXT uses op profit as a KPI?
This comes out at 3.3p EPS, so the PER (pre market open) is 15.9x - that’s a fairly punchy rating for a sector that doesn’t tend to attract big valuations.
Divi forecast of 0.9p gives a yield of a modest 1.7%.
Following a series of acquisitions, lettings is now the bulk of the business, or at least revenues, at 70%. I’m not sure what the profit split is between lettings & other estate agent activities?
EDIT: I forgot to include the cash/debt position - which looks fine to me, a recurring revenue business can afford to take on a bit of debt, this looks modest -
Net debt at 31 December 2023 was c.£7m, and reflects £13.9m of acquisition related spend, c.£11m of working capital investment in Lettings growth initiatives (expected to normalise across 2024), £2.7m of dividends paid and £1.1m of share buybacks.
Outlook - here it is in full, as all interesting & potential read-across -
Lettings is expected to remain resilient in 2024 with the business continuing to display strong recurring and non-cyclical characteristics. As lettings supply and demand dynamics have largely normalised, rents are expected to stabilise and remain at historically elevated levels, whilst improvement in the supply of available rental properties provides a good opportunity to deliver further market share growth.
In Sales, the Group entered 2024 with an under-offer pipeline significantly ahead of the prior year despite weaker market conditions, which should support a good level of year-on-year revenue growth in Q1. Furthermore, continuing to deliver the Sales market share levels achieved in H2 2023 is expected to drive further Sales revenue growth through 2024.
In addition, buyer demand has grown as mortgage rates have begun to normalise, with good levels of growth seen in recent weeks as the first mortgage products are released with rates below 4% since the September 2022 mini-budget. Any sustained reduction in interest rates is expected to spur significant further growth in buyer demand.
Through 2024, the Group will continue its focus on delivering operational enhancements to drive further growth and continue to decouple earnings from sales market cycles. By doing so, the Group is well positioned for its medium-term growth ambition to deliver £25m to £30m of adjusted operating profit.
That all sounds pretty encouraging, for a gradual recovery in housing markets in 2024, and presumably then housebuilders and building products too? Although FOXT is very London-focused, which in a way is even more encouraging for wider read-across, as London properties are the most expensive.
Restructuring - here we are, this is what caused the substantial £4.3m adjustment mentioned above -
Annualised cost savings of c.£3m will be realised in 2024 as the Group delivers synergies related to the November 2023 acquisition of Ludlow Thompson and consolidates certain branches within the Foxtons network by leveraging lease exit events. These savings have resulted in a one-off restructuring charge of c.£4.3m in 2023, of which c.£3.3m is cash related and c.£1.0m is non-cash. The cash charge relates to branch closure and vacancy costs, the majority of which will be incurred over a 3 year period.
Paul’s opinion - this is impressive I think. Although the recent strong rise in share price has probably factored in most of the immediate upside, in my opinion.
Well done to holders, but personally I’m not interested in buying at this stage, but possibly on a future pullback, as it looks as if Foxtons is going places, and I like that target of £25-30m operating profit.
Dr Martens (LON:DOCS)
Up 5% to 79p (£760m) - Q3 Trading Update - Paul - AMBER/RED
The famous utility/fashion bootmaker updates us on peak trading to Dec 2023, within FY 3/2024.
The numbers look very poor, in particular Q3 revenues down 21% on LY Q3.
YTD (9 months to Dec 2023) revenues are down 12%, so it’s a worsening trend in Q3.
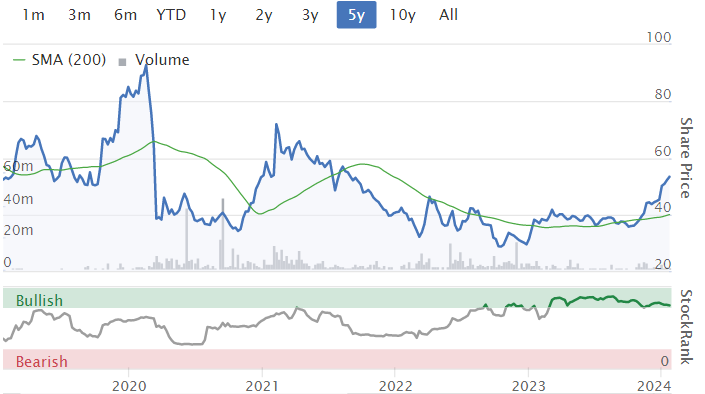
However the share price is up 5% today, so maybe the bad news was already in the bombed out share price, as it confirms Q3 as expected -
Our Q3 performance is in line with the updated full year guidance provided in November…
driven by a weak USA performance, as expected.
Note that the share price was 138p at the start of Oct 2023, now down to 79p, so a lot of bad news has already been taken into account.
They can’t blame macro for drops of this size in revenues. I recall there were logistics problems internally, but I think it must be more than that - clearly the product is not resonating as well with customers, why else would they be buying less?
Outlook - weasel words here perhaps, talking about product, not sales/profits? (like Dunkerton always does at SuperDry) -
We remain confident in our product pipeline for AW24 and beyond.
Other guidance is unchanged, so not getting any worse is a plus, although forex sounds unhelpful but not material overall -
The guidance provided at the time of our H1 results, for full year CC revenue decline of high single-digit percentage year-on-year, remains unchanged. All other guidance for FY24 also remains unchanged.
The appreciation of sterling since the end of H1 means that, if current FX rates persist, we anticipate a currency headwind to the P&L of approximately £5m, together with a non-cash Balance Sheet translation charge, also of approximately £5m.
Brokers notes - nothing for the plebs again!
Paul’s opinion - no strong view either way. Roland looked at its Nov 2023 profit warning, and decided to view DOCS shares as AMBER/RED.
I agree with that. Poor trading, and a weak overly indebted (and over-stocked) balance sheet with only £100m of NTAV, make me want to steer clear of this.
That said, it’s still profitable, and if it can return to growth, then there could be upside, who knows?
Can you tell it's a 2021 IPO?! -
Halfords (LON:HFD)
Down 3% to 169p (£374m) - Q3 Trading Update - Paul - AMBER/GREEN
Upbeat sounding headlines, but that’s the point of headlines of course! -
Continued share gains and focus on motoring services drove resilient performance in Q3, despite challenging market conditions.
Cost savings ahead of expectations.
Strong start to Q4 trading, FY24 profit guidance maintained.
Halfords Group plc (“Halfords” or the “Group”), the UK’s leading provider of Motoring and Cycling services and products, today announces its Q3 Trading update for the 13 weeks to 29 December 2023 (“the period”).
Oct & Nov 2023 were strong, but Dec “much weaker”.
Q3 LFL revenues overall up 2% on Q3 LY, hardly a disaster - with retail being flat, and autocentres up 5%
YTD LFL sales up a respectable 6%.
Including acquisitions, total sales up 9.5% YTD.
Given that the share price has been weak of late,the outlook actually strikes me as sounding resilient, and still in line (within range) -
Outlook
The Group continues to deliver revenue growth in a very challenging consumer environment, highlighting the benefit of our strategic shift to needs-based, service-related revenues, focussed on motoring. Whilst our cost and efficiency programme continues to perform well and we continue to take share across all four of our core markets, the Cycling and Consumer Tyres market are performing significantly worse than anticipated and have weakened in Q3.
Notwithstanding this and assuming that markets do not weaken further in Q4, we continue to expect PBT to fall within the previously communicated range of £48m to £53m. Whilst Q3 sales were below expectations, a strong start to Q4 trading, further cost action and resilient areas such as B2B performing well, mean that we are confident in the Q4 outlook.
But no improvement expected in FY 3/2025 at this stage -
We remain cautious on market recovery in the short-term and we are not currently planning for a material improvement in our key markets in FY25.
Looking beyond FY25, we remain confident in the mid- and long-term future of Halfords and believe the business will be exceptionally well positioned when markets recover. Our scale, brand recognition and market leadership provide us with a platform that has significant competitive advantage. Given volumes in the Cycling and Consumer Tyres markets are below pre-pandemic levels by c. 28% and c. 14% respectively, a market recovery alongside continued delivery of the strategy gives us confidence in our ability to grow profit significantly in the future.
Paul’s opinion - I think this looks quite interesting, for a recovery, and it’s still making decent enough profits in a depressed macro situation.
Attractive value metrics, although it does have a slight whiff of a possible profit warning maybe?
There was bid speculation around HFD recently, which looks a possibility.
Balance sheet is adequate, rather than strong.
Taking a medium-term view, I’m leaning positively towards this, as a value/recovery/takeover situation. So I’ll go with AMBER/GREEN.
Roland’s Section:
Sigmaroc (LON:SRC)
62p (pre-market)(£693m) - FY23 trading update - Roland - AMBER
“The Group is expecting to report underlying FY23 EBITDA and EPS ahead of current consensus expectations”
This construction materials group has been following a buy-and-build strategy, acquiring assets with a view to building a “specialist lime and industrial limestone group” across Europe.
The company recently moved the needle with a deal worth up to €1bn to buy the European lime operations of CRH (LON:CRH) (disc: Roland holds CRH).
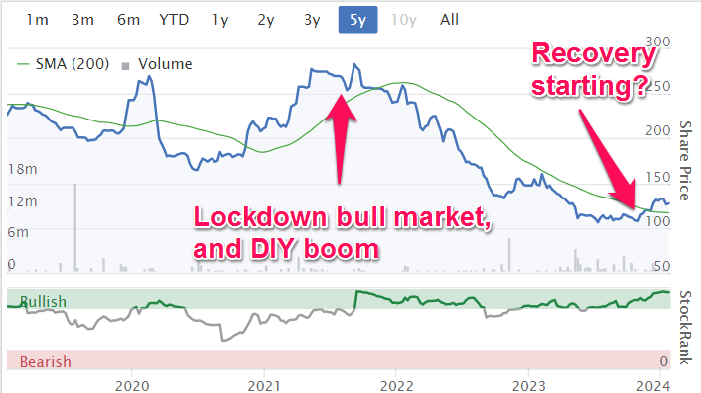
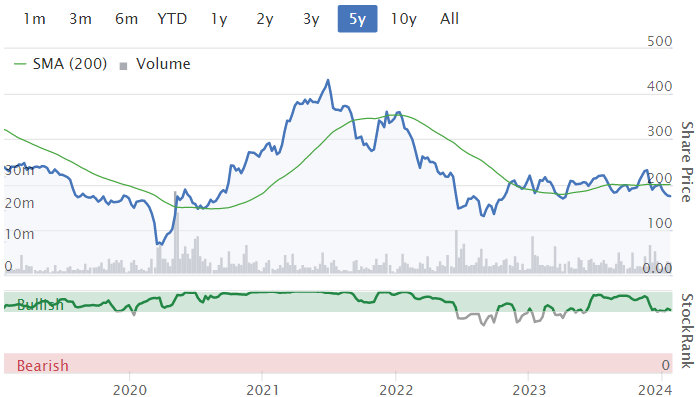
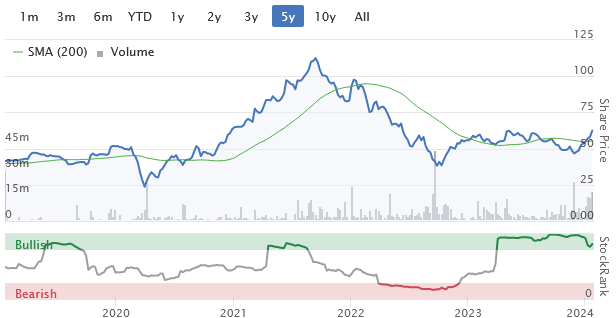
However, share price performance has been somewhat mixed and SigmaRoc has given up the gains it achieved during the pandemic:
Today’s RNS confirms that the first stage of the CRH acquisition was completed on 4 January. However, this update is mainly focused on performance in 2023, which has turned out to be ahead of expectations:
Revenue up 8% to c£580m (below consensus due to lower pass-through of energy costs)
Revenue up 2% LFL, despite 4% decline in volumes
Underlying EBITDA expected to exceed £116m, up 10% LFL
Underlying EBITDA margins improved to 20% (+1.1% year-on-year)
Underlying EPS “greater than 8p”, ahead of house broker Liberum’s estimates of 7.6p per share (updated note available on Research Tree)
Year-end leverage expected to close “below 1.6x” EBITDA, down from 1.7x at 30 June 2023
Trading: the company says it saw “good trading in most markets” during the second half of last year, although I note the 4% overall reduction in volumes.
Industrial minerals markets (43% of FY23 revenue): trading recovered from destocking earlier in the year. Sectors such as metals, environmental and agriculture are said to have remained “well supported”.
Construction markets (57% of FY23 revenue): Trading seems to have been supported by infrastructure markets, which represent over 60% of the group’s construction market revenues. This helped to offset the impact of softer residential markets.
Corporate: measures taken in the Nordics and UK should translate into annualised cost savings of c.£4m.
Newly acquired businesses are said to be “performing ahead of expectations” at the time of their acquisitions.
Outlook: SigmaRoc has left its FY24 guidance unchanged at this early stage in the year, perhaps sensibly.
An updated broker note from house broker Liberum confirms FY24 earnings estimates are unchanged at 8.2p per share, or 7.6p on a fully-diluted basis (many new shares are being issued as part of the CRH acquisition).
Roland’s view
SigmaRoc appears to be trading reasonably well and executing a successful buy-and-build growth model.
Trading on eight times forecast earnings, the shares do not seem too expensive, in my view.
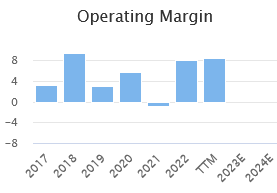
However, the profit measures referenced in today’s update are all adjusted, potentially quite heavily. Depreciation and amortisation cannot be ignored in real life and we don’t know what the actual operating margin was last year.
Margin performance in recent years has been mixed:
Similarly, the 1.6x leverage multiple cited doesn’t tell us all that much about actual debt levels or free cash flow.
I’d prefer to wait for the 2023 accounts before taking a more decisive view on SigmaRoc.
Even then, it’s worth noting that the completion of the first stage of the CRH acquisition on 4 January means that the 2023 year-end accounts will no longer be representative of the business, unless a pro forma set of figures are also provided.
More broadly, I think it’s fair to say that the success of the CRH acquisition is not yet proven. I think it’s worth considering why CRH – which I see as a good capital allocator – chose to sell.
What return on capital employed will SigmaRoc be able to achieve on this €1bn deal? We don’t yet know.
There are a lot of moving parts here and shareholders have experienced significant dilution as SigmaRoc has used its shares to fund regular acquisitions:
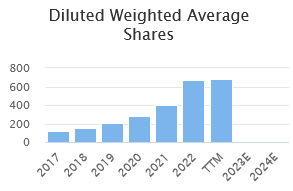
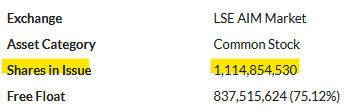
The share count has doubled again to 1.1bn since the interim results, due to the issue of shares to CRH.
I think it’s worth noting how FY24 earnings per share are expected to be broadly flat on a fully-diluted basis, despite underlying growth.
Despite the negative tone of these comments, I think SigmaRoc is probably in reasonable shape and fairly valued at the moment.
But I think management still has much to prove and I would prefer to wait for the full-year accounts before taking a higher conviction view. For now, I’m going to go AMBER on SigmaRoc.
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Up 2% to 824p (£460m) - FY23 trading update - Roland - AMBER/GREEN
“Actual trading was better than anticipated in Q4 2023 and the Board now expects the Group to report an adjusted profit before tax that is slightly ahead of the current market consensus.”
Graham last covered Mortgage Advice Bureau in July last year, noting “a gloomy update as far as the H2 outlook is concerned”.
He then went on to include this mortgage broker in his top 10 small cap ideas for 2024, earlier this month.
Today’s update suggests to me that Graham may have been right to stick with MAB in his 2024 choices, despite the increase in its valuation over the last 12 months:
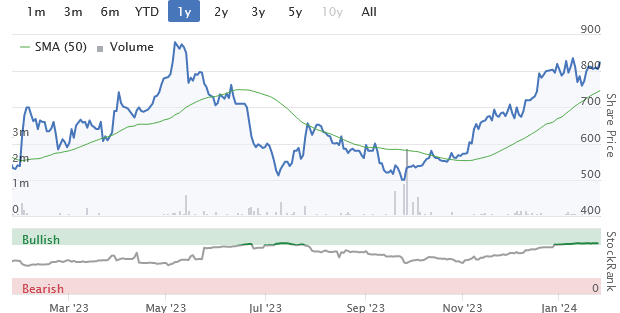
2023 trading update: the company says it took a “cautious view” in September on expected activity levels for Q4. Happily, actual trading was better than expected.
Although UK gross new mortgage lending is said to have fallen by 28% to £226bn last year, MAB’s full-year revenue rose by 4% to £239m. This suggests to me the company may have gained some market share, which should deliver benefits when activity levels recover.
As a result of this stronger trading, adjusted pre-tax profit is now expected to be slightly ahead of consensus.
I can’t find a recent broker note for MAB. But consensus earnings forecasts on Stockopedia suggest a figure of 28.7p per share, so perhaps we can plan for a figure of c.30p?
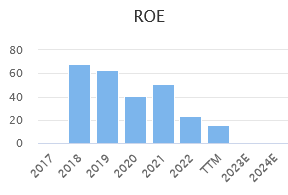
That would put the stock on a P/E of 27. That is still high when viewed in isolation, but this is a capital-light business that was able to generate 40%+ returns on equity before the housing market slowed:
Owner-management is another attraction, for me, with CEO Peter Bordnicki controlling 18% of the stock.
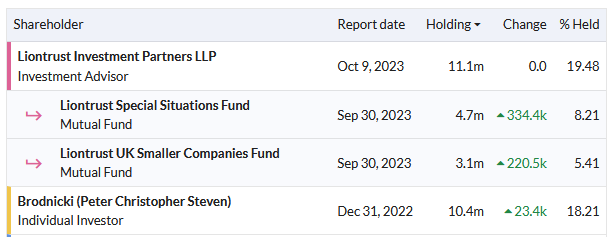
Let’s see what Mr Brodnicki has to say about 2024.
Current trading and outlook: the underlying demand for home ownership and home moves is said to remain strong.
As the cost of fixed-rate mortgages has eased, MAB says it has seen “early signs of increased purchase activity as well as refinancing”.
Written mortgage volumes in January are said to have been “substantially higher” than in January 2023.
After a 4% fall in the total number of mortgage advisors last year, MAB says it expects some of its Appointed Representative firms to restart recruitment “earlier than planned” if momentum continues.
The company also expects to sign up new firms this year.
As yet, there’s no upgrade to 2024 guidance, but if momentum continues then I would imagine an upgrade might be possible:
Current trading is encouraging and in line with expectations.
Roland’s view
I share Graham’s positive view on this business, which I think is well run with an attractive business model and a sound financial position.
MAB’s past performance was highly profitable and cash generative. I don’t see any reason why this shouldn’t remain the case in the future.
Although I think the share price is probably up with events for now, the stock continues to support a useful 3.5% yield.
On balance, I think the potential rewards comfortably outweigh the risks here, so I’m going to go AMBER/GREEN on this one.
Yu (LON:YU.)
Down 5% at 1,243p (£218m) - Year-end trading update - Roland - AMBER
The Group's strategy continues to deliver with all key financial metrics performing ahead of expectations, which were raised three times in 2023.
Utility reseller Yü issued an update on Wednesday including a(nother) significant upgrade to profit guidance.
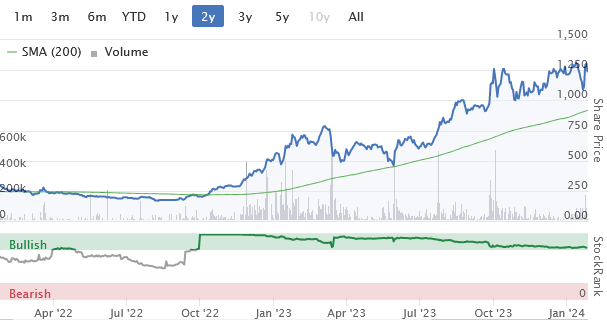
This stock has been a five-bagger since since 2022:
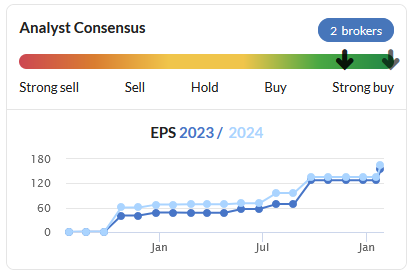
Profit forecasts have been upgraded repeatedly:
This isn’t a business I know well, so I’m keen to understand what I may have been missing so far.
Yü has two arms, energy supply and meter installation. The company focuses on corporate customers, rather than retail customers.
Upgraded 2023 guidance: full-year revenue expected to be around £450m (FY22: £279m), representing organic growth of over 60%.
EBITDA is expected to be “significantly ahead” of current expectations, although no numbers are provided.
Checking Research Tree – many thanks – I see that brokers SP Angel has increased its FY23 EBITDA forecast by 15% to £38m.
This is expected to drop through to give adjusted earnings of 166.6p per share, or 136.6p per share on a fully-diluted basis, including outstanding options.
This leaves Yü shares trading on around eight times forecast earnings:
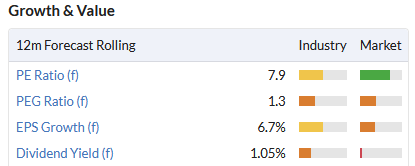
Trading summary: Yü says that average monthly bookings rose by over 120% to “above £55m” last year (FY22: £24.5m).
The group has secured contracted revenues of £519.7m for FY24, which represents a 11% increase on FY23. Total contracted forward revenue is now £825.8m.
The number of meter points under contract to the company – presumably a loose proxy for customer numbers – is said to have shown a “significant increase” in FY23, but I couldn’t find a specific number in the RNS.
However, an updated Liberum note on Research Tree says the number of meter points has “more than doubled” year-on-year.
The half-year results showed the number of meter points up by 52% to 39.7k, so doubling year-on-year would be consistent with a similar rate of growth in H2.
Yü says it's focusing on customers with better credit and more predictable consumption patterns. The company says that 98% of bills raised during the year have been received in cash.
This level of collection may sound reassuring at first glance, but I think bad credit is a significant risk in this business – with an operating margin of c.2%, a small percentage increase in bad debt (from the revenue line) could easily wipe out a big chunk of profit.
Net cash: the company says net cash at the year end was £31.9m, down from £36.6m at the half-year point.
However, management says that a further £49.8m of cash is currently held on deposit with its trading counterparty as collateral for hedging arrangements on energy prices.
Volatile energy prices can lead to sudden increases in collateral requirements, even if the hedging ultimately delivers a stable result. More stable energy markets mean that much of this cash is now expected to flow back to Yü.
However, this situation could easily reverse again in the future. Given the nature of this business, my feeling is that a substantial cash position is a prudent operating requirement and may not (ever) be surplus to requirements.
Dividend: in situations such as this where shares appear very cheap but may not be, I find that dividend cover and yield can be a useful guide to what I view as the true underlying valuation.
In this case, we see a sub-1% dividend yield and forecast dividend cover of c.10x, according to updated broker forecasts.
To me, this supports my view that the company needs to maintain a large cash balance and might not be as cheap as it seems, at least on a near-term view.
However, this could change over time, I think, if the company’s Smart Meter business can successfully achieve scale.
Yü Smart (smart meter business): this relatively new business reached 8,000 smart meters installed by the end of 2023, after beginning the rollout in H1.
This is somewhat behind the 10k target stated in its half-year results, but a new MD has been appointed to help scale up this business.
Owning smart meters is a potentially attractive business with the potential to provide high levels of recurring revenue, probably index linked. It’s clearly early days for Yü, but I think that if this business can scale, it could become quite valuable.
However, one characteristic of this business is that returns tend to be back-end loaded. The initial rollout is likely to require debt and will not immediately generate strong cash flows. But over time, this balance could reverse, with debt falling and distributable cash rising fast.
The risk for investors is that they may need to remain patient through a long – and potentially indebted – rollout period.
I guess the model of success for UK investors in this area is AIM-listed Smart Metering Systems (LON:SMS), which has c.2.5m smart meters and has just received a takeover offer.
Roland’s view
I’ve only taken a brief look at Yü today. I would want to dig much deeper and look back at the firm’s history before forming a more considered view. I think there have been some problems in the past.
For some starter reading, Paul has previously commented on Yü here and here (FY22 results).
One positive worth highlighting may be owner-management – CEO Bobby Kalar appears to control more than 50% of the stock.
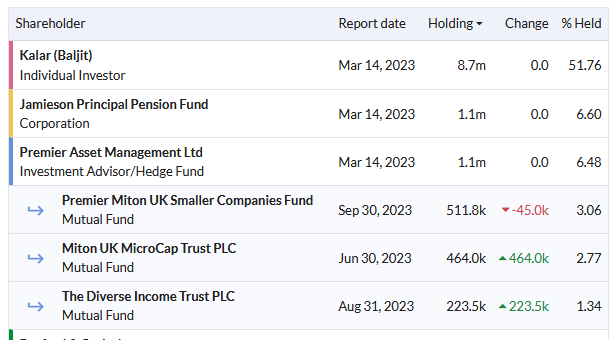
Although I’m encouraged by the theoretical potential of the smart meter business, it’s still very early days. Achieving a scale rollout won’t necessarily be easy.
Another potential concern for me is customer credit quality. Unlike households, businesses can go bust and disappear, making it difficult for unsecured creditors (which I assume includes energy suppliers) to recover outstanding debts.
On the positive side, there has been an exodus of competitors in the business energy market, as we’ve also seen in retail energy supply. In the half-year results, the CEO said he expected to see a “less competitive landscape” in the future, which should be a positive for Yü.
My initial view is that the Yü share price is up with events at current levels, at least pending a look at the 2023 accounts.
While I can see some interesting opportunities here, I also think the energy supply business carries significant risks that will always need careful management.
For now, I’m going to take an AMBER view on this business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

144 comments
Whenever you mention YU. you refer to risks which you appear to have found in the accounts but you never specify what these are. I am a long term holder and the metrics all seem good to me - although I am uneasy about the shareholder profile. Could you be a bit more specific?
Sky News reports "Saga is exploring ways to release money from its ocean cruises operation which could involve selling its two flagship vessels or offloading the entire business under a licensing arrangement."
Not sure what this means for the share price (I hold).
Link to news story
I also hold Saga (LON:SAGA) and thought the same. Considering the two vessels have a combined build cost of £560million and the market cap is only just over a third of that at £207million I would expect it to be viewed positively. Selling the cruise aspect of the business outright including the vessels would potentially clear the 600milion debt with a but of money left over. However, the cruises are what keep the company afloat... excuse the pun.
Gresham House Energy Storage Fund (LON:GRID)
I don't know if any fellow investors have any comments with regards to this stock or sector, however the share price has fallen from £1.10 to £.0.70 this month. There has been no RNS from the company which given the decline is in my opinion very worrying.
Gresham House Energy Storage Fund (LON:GRID) in the same sector as my holding in Gore Street Energy Storage Fund (LON:GSF) which is probably down more. It seems the market is not interested in the essential requirement of the much talked about energy transition. The bulk of electricity generation from wind and solar is unachievable without battery storage capability for when the sun doesn’t shine or the wind doesn’t blow.
RE: GRID and GSF
I dont hold but am watching the battery storage sector for a couple of reasons.
There seem to be ongoing issues with the National Grid which dont look to be fixed any time soon. It must be difficult to create a positive news flow when the key constraint is long term outside your control.
Worth watching - I try to catch up on Citywire Investment Trust Insider for any news.
LON:DOCS When I used to wear these when they were branded air wear 1980s. The Quality then was variable, the fitted insole used to decompose as soon as the sole had been penetrated and the sponge inside would suck the water in. I have no idea what they are like now but I believe they are now mostly made in China where I believe if you don't keep your eye on the process corners will be cut. Just wondering if that could be the case here. views welcome!
Yes, rubbish quality these days. My daughter bought a pair and they split between the uppers and the soles. Given a replacement pair but of the same low grade. The insoles of the second pair were worse that those in the first.
Petrotal (LON:PTAL)
I see Petrotal have taken a full page on the back cover of Investors Chronicle this week. Is that a fair way of generating interest or dies it smack of desperation? I recall Bluejay provided an advertising backdrop/surround for the News section on ADVFN for a few weeks sone years back - and that hasn't exactly turned out well. I'm happily farming the Divi on Ptal at the moment while waiting for continued output increases to be reflected in the sp in due course, hopefully!
Views?
Super business Petrotal (LON:PTAL) in my view. Extremely well managed particularly in terms of relationships built with indigenous communities and Government.
I've owned from 20p and the dividend at current prices is circa 13-17% depending on any liquidity sweep. Frankly that on it's own in a tax free ISA wrapper is a good return so it doesn't need to do much capital wise to give a nice 20% compounder.
Production reserves is set for decades and they can produce well over 20k bopd so really the constraint is barging which is being solved. Suspect they beat production targets this year.
Even with a $100m investment exercise in 2024 and an estimated $77 oil price they will generate $25m of FCF. Next year should be significantly better.
I think oil is currently too low and expect it to trade $85-95 range over next couple of years. Each $3 on oil price generates $10m of extra FCF so at over $80 they are already at $35m FCF this year and I anticipate that will end up close to $50m.
Elementis (LON:ELM)
As yiannos has said time for management to update the markets on the share price move and what appears to be behind the scenes 'bid' chat.
Goodwin (LON:GDWN) is a company that I have long admired but never found the right entry point/price for me. I would like to own it and have spent some time looking at it. It is off 20% since it's high at the 2023 year end. Technical analysis probably not of much use for this stock, very thinly traded and the family having a large holding.
Would anyone like to give me the current bull and bear cases please.
Goodwin (LON:GDWN) is my largest holding…I’m therefore an unreliable witness ..but I’d suggest it’s not a stock that rewards close scrutiny of the price action for some of the reasons you mention.
Its the epitome of a company that does the right long term things which pay off many years later ..as at today’s date they’re doing the following;
Building a new additional pumps facility in India
Acquiring a sizeable new site in Newcastle under Lyme to support their AVD lithium battery fire suppression range ..which is doubling in sales every year
putting the finishing touches to a foundry expansion/automation project that multiplies their capacity ..& adding machining capacity to suit
Launching a new poyimide product from a new purpose built facility that is going through final commissioning with sales commencing in the next few months
I could go on ..but I’ve never seen a more ambitious & expansionary set-up that’s been a decade or do in the making
I’ve no doubt it’ll do well
..the bear case isn’t quite as clear to me
rhomboid,
Thank you for your reply . I knew some of what you tell me but not all obviously.
More work for me to do I think.
Currently working on doing better research and buying only buy good quality value shares, and on developing a more patient time horizon for success.
"Time is the friend of the wonderful company, the enemy of the mediocre." Warren Buffet
Not always easy to be patient though. Currently being tested by Mercia Asset Management (LON:MERC) daily share buybacks, wondering whether I should just sell up.
deleted - meant to reply to a thread
Elementis (LON:ELM) board should make an announcement on recent events as soon as today; unless they do not respect their shareholders something that seems to be the case.
I hold.
Roland right to be cautious on Sigmaroc until the company demonstrate its successfully digested the big recent acquisition. Currently could be seen as a value trap but personally I see a strong future. Demand for a core commodity like lime should increase; operating margins should improve via group scale. One to hold for proof of recovery. Both Simply wall st & Guru focus value at double current price. If ( when) the residential housing sector picks up - likely under a labour government -better days ahead.
Hargreaves Services (LON:HSP)
A quick hat tip to planetx for bringing the above to my attention just over a year ago (thanks Dave)
The share price has not done much since I bought in 12/22, up around 10% plus some dividends.
I have just watched the H1 2024 report on Investor Meet HARGREAVES SERVICES PLC - Interim Results for the six months ended 30 November 2023 - InvestorMeetCompany
A lot to like here including a good mix of good old British accents and the straight talking Gordon Banham CEO. I would be interested in any other watchers opinion because the theme I got was that they were putting themselves up for sale. A lot of talk about the book value of the three parts of the business and what it would take to realise those values. (£6-£8 ps BTW).
With Harwood being a 28% shareholder, Nick Mills, Christopher's son I imagine, having a place on the board and Gordon himself 8% and maybe fancying retirement I would say this is very distinct possibility, and getting paid 8% while you wait for it happen represents a nice sleep at night part of anyone's portfolio IMHO.
I hold Hargreaves Services (LON:HSP) as well, had them for 18 months, 6/22, slightly down if excluding dividends. One for the patient investor.
Dr Martens (LON:DOCS) (I hold)
In case there are any holders out there, with today's update I've finally managed to work out the Q3/Q4 numbers (give or take) for the last 3 years:
Obviously the Q4 and FY figures for FY24 are my own guestimates, although the company mentioned in their call today that a chunk of the Q4 revenues are confirmed re-stocking orders, so the final figure shouldn't be too far off.
---
As a few of the negatives have already been mentioned today, here are some positives for balance:
APAC revenues, for example, declined 8% in Q3...but only -1% CCY
This continues a trend that's been evolving since 2014 when GM's were 46.3%.
For context GM's was 61.8% in FY23.
This has had a material impact on YTD revenues, a necessary short term hit in my opinion and which partly explains the poor year.
Who is Eldose Babu?
I am a holder in Saga (LON:SAGA) where an individual by the name of Eldose Babu has been buying a decent number of shares in the past few months. At current they hold 7% of the company, so about 15million quid. They first disclosed hitting a 3% stake on Oct 17th 2023, so quite recently.
They also hold a decent number of shares in Revolution Bars (LON:RBG), 16.2% of the company. An RNS on 21st December 2023 showing more shares being bought. Eldose hit the 3% threshold on 17th June 2021 (recorded as a move from 2.8% to 7%) following a 20p fundraise so has been invested here for a bit longer.
I have searched high and low online and this buyer is a ghost, I cannot find anything concrete about them, just that are based in Dubai and have holdings in these two companies. A name assessment on chat GTP suggests it is unlikely to be an Emirati name (making the chance of this being royal money unlikely), more likely South East Asian, where Babu is typically used as a title, similar to "Mr" or "Sir".
There is someone by this name who has been the MD of a company called EuroEmirates for 20years (according to LinkedIn), which is Dubai based and seems to own a number of smaller brands: https://www.euroemirates.com/c...
Nothing of the size of the two listed companies where a stake is being built. I cannot say for sure that the MD here is the investor, or if the correlated names are simply a coincidence.
The reason for my search is simple, does this person have the potential to bid for either of these two companies? Do they have the financial capability or desire to do so? If it was possible to know a little more about this person, then it would help to inform investment decisions regarding Saga (LON:SAGA) and Revolution Bars (LON:RBG)
I would be interested to know if anyone else can be more successful in finding out more about this person and their intentions. If there is another RNS from Revolution Bars (LON:RBG) stating he has upped his stake further I think I will be open a small position in case of a bid.
Someone on here mentioned this week that they made a bid for RBG a few years ago before the big fall in price, so perhaps not very astute investors ...
No - that was Stonegate that made a bid for Revolution Bars (LON:RBG)
This guy is nothing to do with Stonegate.
NCC (LON:NCC) Interims today. Generally in line. I watched the presentation - very excited about new Manila office and general reorganisation of methods and culture but this has left the mooted disposal of escrow - renamed Escode - on the back burner (expected by major shareholders including the Buffettology fund) . That probably accounts for a small drop this morning but still leaves the sp up just under 30% over the last 3 months.
One interesting note to the a/cs that will bring joy to the many on here who have moaned about adjusted figures removing such things as share based payments:
After reconsidering FRC best practice guidance around the disclosure of adjusting items and APM's, the Group have reduced the number of adjusted measures and items. The Group now only has one adjusted item 'Individual Significant Items'. Previous adjusted items of Amortisation of acquisition intangibles and Share based payments are no longer disclosed as an adjusted item. Accordingly, comparative numbers have been restated. For further detail, please refer to the Financial Review and Note 3 for an explanation of APMs and adjusting items, including a reconciliation to statutory information.
SDI (LON:SDI) Are there any holders here still?
After the interim results on Dec 7, Graham wrote "I’m going to stay neutral, and move my estimate of value territory down to sub-80p." Today's spread is 59-60p and there has been no significant news other than that the CEO has stepped down (he was thanked) and the COO has stepped up to CEO.
Is SDI now firmly in value territory? (I don't hold currently)
Is SDI now firmly in value territory? (I don't hold currently)
I’m inclined to the view that it is close. £0.50 is a good entry I think. I note shares are off 25% since the CEO jumped/was dumped. And have nearly halved since the Dec PW. Quite a reaction. The market for life science tools is in a protracted slump and that is both accounted for and compounded by the loss of Covid revenues across the sector. Large US caps are seeing some green shoots recently but downgrades have not ceased. Meanwhile I’m not up to speed with local events but the slow pace of recovery stateside suggests a final PW isn’t out of the question. Shares are cheap on a PER basis but debt is historically very high.
I was a massive fan of SDI having bought originally at 24p and rode the wave up (and somewhat down) but thankfully made a 10 bagger in total. I had another look at them yesterday and watched a useful presentation on Investor Meets Company which covers the H1-24 results - its well worth a watch and to me flagged a lot of issues around cash, the reliance of the group on large 1-off orders, and the reduced likelihood of the company being paid up front for these orders. So for me its a "no" for now.
Thanks BnB and Gimmers for these views on SDI (LON:SDI.
Hello Roland, Thank you for your "brief" (!) look at Yu (LON:YU.). I would welcome your 'more considered view'. I learn a lot from your Stock in Focus blogs.
I don't currently hold this stock, but have done.
I hold this stock and have a mixed view and would appreciate Roland to dive deeper. I have lost money and also made money at very high percentages but I feel the stock feels risky and needs a close eye. At the moment I can see the stock needs to be traded within a range.
Pensionbee (LON:PBEE) - "Growth still strong, adjusted EBITDA turns positive in Q4" (new research report: https://www.equitydevelopment....)
In March 22, our initiation note was titled A pensions fintech starting to look like a Rocketship. Since then, market, investor and consumer confidence have been rocked by geopolitical events and deteriorating economic conditions. But despite that, PensionBee has delivered. What’s more, it has moved into profitability on an adjusted EBITDA basis within the timeframe targeted at its Apr 21 IPO.
Over FY23 (to 31 Dec 23), 46k net new invested customers (ICs) were added (ICs + 25% to 229k), £1.3bn of AUA were added (AUA +44% to £4.4bn, net inflows +£857m, market movements +£464m), and revenue grew 35% to £23.8m. It was a continuation of an already-impressive growth story.
As scale benefits continue, adj. EBITDA improved from -£19.5m in FY22 to -£8.4m in FY23 and was positive in Q4 (>£0.5m). The business maintains a healthy cash position of £12.2m and does not envisage further equity raises. Our fundamental valuation remains 150p per share.
Pensionbee (LON:PBEE)
very useful info Equity Development - cheers
This company still looks like it has great potential - loeley to have up to date 2025 estimates as thats the breakthrough year ref profitability "potentially"
I say potentially as rather oddly there is great sales growth is expected in 2025 - but all the extra sales are consumed by extra expenses - oh dear.
So the question here is is why no operational gearing here in that year - perhaps they plan on ramping up the ad spend then to drive future growth - would be nice to know iif that is the case. Seems strange they wouldnt hold something back ref investment to book some profits if the extra spend is discretionary . Or is it the case of extra sales are being eaten up by extra non discretionary costs - if that is the case the question is why and is that one off that wont be repeated following year.
I was kinda hoping costs would grow much slower than sales when they reached critical mass.
apologies if info is all in broker note and i missed it.
Pensionbee (LON:PBEE)
The rocketship forecast by ED, when the sp was 140p in March 22, seems to have stalled somewhat as the SP today is only c90p, albeit up nicely from recent Oct low of 60p. Perhaps it is now gaining flight. Still significantly loss making though has the cash to cover that. On Stocko ranks has a good score for Momentum but lousy on everything else. Jury still out?
Pensionbee (LON:PBEE)
Still significantly loss making though has the cash to cover that. On Stocko ranks has a good score for Momentum but lousy on everything else. Jury still out?
thats why the broker note being posted here is really useful if you take the info linked today at face value - they expect losses of onl h £1.8 mill in 2024 (£1.4 mill following year). thats well down almost to teh point where you could argue they are near breakeven on the basis they will have material discretionary ad spending that they are only spending due to the fact they have the cash spare and that wil benefit long term
What i completely fail to get is why the extra £12 mill of sales in 2025 will be eaten up as expenses - thats fine if they have the extra cash the to push sales on again - if its extra necessary costs thats not so great.
The beauty here if my logic is correct that even on steady state active customer base - i wuld expend FUM and fees to grow materially over time for many years as more peps will be adding that drawing down (auto enrolment in its infancy)
the worry here would be customer churn and costs - is it like the wine companies where they have to keep paying to get customers due to churn - i would like to think not but dont know enough.
if this is a decent company i wil probably miss the boat waiting for the proof sigh
Dr Martens (LON:DOCS) - I cannot help but think that there is so much potential in the company. The brand is very strong. Not sure if its a case of expanding too quickly. Trying to run before you can walk.
If they can get the inventory sorted (maybe stick to a few lines) and start reducing the debt, then i can see it growing in the future. Naturally, that is a lot easier said than done.
I was surprised by a discussion on Twitter recently where Doc Martens were being discussed between Americans interested in buying them and British tweeters. The British tweeters told them straight that Doc Martens had totally changed, were now made in China, werent the quality they used to be and to buy another brand instead (who I understand have bought the old Doc Martens tools and machinery)
Sounds like Uggs, now mostly made in China and Vietnam, owned by a US company. However you would not know that from their marketting. I hrar tourists flock to the their shops in Australia probably unaware of where they are now made. Dr Martens (LON:DOCS) have been made in China for a long time now, 2003?
Interesting one. It was previously the classic advice to move production to China to cut cost, and possibly enable higher production. I have not heard any comments on social media or press re Uggs made in China being regarded as lower quality.
The question is if the new Doc Martens seem lower quality to previous owners. And whether actually being British made was an important part of the brand image.
Is the right man at the help. On calls he seems a classic brand bullsh*tter. They need a global operator who fixes the USA supply chain & understands distribution power better. Change here would reassure me as the brand is still strong as you say.
Titon Holdings (LON:TON) (I hold) - not going to go bust, cash flow positive, still being dragged down by South Korea. The directors report depressed me because there is no mention of the two key drivers of better performance, identified here by planetx and supported by the 27% holding by Rockwood capital. These are, first, an actual exit from S. Korea (where they own 51% of the production company and 49% of the distributor) - the report says only ' We do not expect that trading in South Korea will materially improve in 2024. However, we are working to streamline the corporate structure and operations which will reduce costs.' Not good enough, that won't cut the mustard, I think they need to just get out. Second, sale of the Colchester office and consolidation of operations at the Haverhill factory to release (one hopes) a lot of capital. Nothing in the report about consolidating on one site. I was showing a small profit on my holding yesterday, now it's a lossmaker and I am wondering just how long it's going to take Mr. Staveley to sort this one out.
Michael
Titon
I think it’s pretty ok
Firstly price to buy is 85p with not a lot of stock available , Sell price 78.3p
In short the market is trying to buy stock at a flushed out price .
The new CEO not in for a few months yet so things probably won’t get momentum till then .
His brief is certainly to get ride of the Korean drag hopefully with sone cash .
The positives are stock I’d getting better with FD and margin up slightly .
Looks pretty good , I was actually hoping for more of a profit warning so could increase.
I’ve been buying in the mid 80s past few weeks so the price is actually pretty. Unchanged .
Turnaround starts in April . Sideways for 6 months probably
Thanks planetx.
Have you been to Essex and seen the properties? Long way from Sheffield!
The AGM will be at Haverhill - I was hoping to get a look round the Colchester site and assess the practicalities of consolidating at Haverhill. As you pointed out this would have a non-trivial impact on the investment.
I live the other side of the country but have business in Cambridge and Ipswich this spring so may be able to fit all in together.
Michael
I was going to go and meet then chairman Keith Ritchie but as you say a long way .
At the time I was over 3%
After having had several conversations with him and Rockwood I came to the conclusion he was playing a “kingmaker” game of thrones style game and was a major negative for the business but he appeared to have control .
I needed cash for another project so binned the lot in one day which Rockwood picked up .
To their credit they got him out the door much quicker than expected .
I’m now building back up slowly won’t go anywhere near 3% though .
Anyway yes I’ll come with you / meet you there !
Why can't you put what stock you are talking about? I had to scroll al the way back to 'planetx to see. It has been mentioned on here so many times, please put which stock you are talking about.
cafcash49 - I didn't add the name, Titon Holdings (LON:TON), to all my comments because I put it in the first one in what became a thread. I always do that - put the name of the share in my first comment but not endlessly repeat it if there are replies which form a thread. If you view comments as "threaded", and not "unthreaded", you would see that. Do you really want everyone to add the topic of a discussion to every comment in a thread?
I notice you did not add the name to your comment.
Do you really want everyone to add the topic of a discussion to every comment in a thread?
it would be nice if people did ref ticker as not everyone uses threaded - note i am not asking here - just saying it would nice if it happened
But thread comments are all over the place, it is devil to find a post. There maybe 3 or 4 different threads running on the same stock. I can't get on with threaded. I'm not putting a ticker in here because it is a general about all stocks.
As it states in every SCVR: "include the company name/ticker"
Do you really want everyone to add the topic of a discussion to every comment in a thread?
Yes, why not?
"Do you really want everyone to add the topic of a discussion to every comment in a thread?"
Yes please - it is,after all what the header asks you to do every day. I suggest you spend the day reading unthreaded tomorrow and you will get the frustrating experience from the other side.
I wrote about this last Friday here and most people responded and named companies that day - much better for all.
not sure if it helps but I've found it easier to jump the thread by clicking on the 'in reply to' bit:
Eurocell (LON:ECEL) Stockopedia "Compare Stocks" function show Eurocell (LON:ECEL) 25/37 to Epwin (LON:EPWN) 12/37, so a clear win. I'm following Eurocell because the director deals are significantly higher and more frequent.
Eurocell (LON:ECEL)
Thanks Funnymoney (our var referee) - i took the wrong "net debt figure" from the update (last years total)- there is indeed no net debt.
var corrected score 1-1
We have also continued to focus on efficient inventory management to drive good cash flow performance. As a result, net cash on a pre-IFRS 16 basis was £0.4 million at 31 December 2023, compared to net debt of £14 million at 31 December 2022.
Since October Sylvania Platinum (LON:SLP) has fallen from 85p to 57p today a 33% fall.
I hold being 5% of my portfolio. I have been a long term holder. I know a good number of Subscribers hold this share and I would really welcome any opinions on the recent quite rapid fall in the SP.
I too am a long term holder and would value any wisdom - it seems to be related to the suppressed price of platinum with high supplies above ground and increased mining costs in South Africa - the dividends are good and PE only 5.1 with stock rank of 81 and value rank of 95 so one would think a long term good prospect when platinum group metal prices recover but paper losses have been immense in last few years from a peak price of near 150p to 57p now - I have a strong emotional attachment to it (maybe not a good idea - wish I had sold months ago) but am holding on currently - this helpful article came out yesterday https://investingnews.com/plat...
If the price of platinum is to recover a new application will be required. Clearly catalytic converters are on the road (sorry, I couldn't resist) to being obsolete. I know Sylvania Platinum (LON:SLP) have expanded their operation into non PGM metals but will it be enough?
It is the same story at Tharisa (LON:THS) - I hold and am also under water. The PGM basket price has been subdued - plus South Africa has not been an easy environment in which to run an industrial operation these past months. On the upside these companies are well financed, and certainly Tharisa is still making profit and generating cash, but it has had to push back its Zimbabwe project because of low prices. The hope must be that solid demand, plus reduced production from the less profitable operators will in time have an impact on prices. In the meantime there are worse places to be than a company awash with cash and paying a decent divi.
I also hold Sylvania Platinum (LON:SLP) , although it is my smallest position.
PGM prices are very weak and the situation in South Africa is clearly a mess, with elections coming up later this year - although that may not change things significantly.
Half year results are coming on Feb 19th.
The closest comparission is with Tharisa (LON:THS) which has been similarily weak over the past 12 months.
Agree with that. Sylvania Platinum (LON:SLP) and Tharisa (LON:THS) jettisoned from my PF too late to avoid much of the drop last year. With commodity prices not likely to recover til China launches stimulus and or the horrors of the Middle East, at least, subside and South Africa sorts out it's corruption why will they fly?
I sold my holding in Sylvania Platinum (LON:SLP) last week because the profit forecast didn't seem to be taking account of current prices of PGM and because the company is holding $127m of cash, without clearing identifying their plans for this cash. I understand the frictional (additional South Africa tax) cost of returning money to shareholders either via dividends or buy backs and recognise that they need some cash to cover potential short term losses while the PGM price is at these levels. But $127m just seems far too much for those needs, so assume they will "invest" in other assets, which is a risk from my perspective. Their financial calendar is saying there will be a Q2 report by the end of January, so I assume we will learn more then.
I also hold unfortunately and would like to know if there is news we do not see
Clearly linked to the PGM price weakness. But it’s cyclical & when it recovers this steady Eddie will recover. Rock solid balance sheet & decent dividend track record reassured me.
SLP. I, too, am a long term holder. I feel your pain. I bought in Mar 2018 at 18p and sold half in Jul 2021 at 98p, after its 10% drop in share price.
It's a low-cost producer, which has that in its favour. It is in South Africa, which is of course a risk. Is there any commodity producer that isn't a risk? Even petroleum production in the UK has its political side. SLP directors seemed OK with the risk (of course they would say that?), and even on the issues of power supply seemed OK, considering. Industrial users get more of a heads-up on power supply, and can mitigate at least some of the problems with power generation.
SLP has a tonne of cash and is trading below book. Rhodium is at 4550 USD/t oz. That's crept up from around 4000 in 2023. They are well above the period 2014-19, and way below the period 2020-2022.
SLP produce a lot of Rhodium, and automotive is a big user of it. I think people are overstating the threat imposed by the switch from ICE (Internal Combustion Engines) to EVs (Electric Vehicles).
If we have more inflation (there are both sides to the debate on that) and any global conflicts escalate, then this is likely to be good for commodities.
Those are the bull points. The bear point is that everything I said is just wishful thinking. It's certainly not a share to bet the farm on.
Ref Sylvania Platinum (LON:SLP) I have held for many years and though I have a strict 20% drop and your out of here, I have ignored it for this one share, how I regret that when it was 150p. However, over the last 5 years or so, it has returned 30% of my initial investment in dividends, so I hold it for those rather than the share price.
Should the dividend remain around 8-10% then I will continue to hold, however, if that drops, then I would sell on that announcement.
Let not forget they have a couple of exploratory exercise on the go that will report soon, and also the new Joint Venture with Limberg mining company, and none of that is factored in this new low price.
I am topping up at this price
Elementis (LON:ELM) Big jump this morning. Does anyone know what's going on here?
Ah just spotted, possible bid Airsoft
https://www.stockopedia.com/sh...
Empresaria (LON:EMR) is anyone close enough to this sector to validate this statement, below, from today’s update? Seems to me a very vulnerable sector in the current, will the landings be soft or hard environment.
Our Offshore Services operation continues to perform strongly. This business delivered year-on-year growth in net fee income despite the challenging market conditions and has grown at a compound annual rate of 32% since 2017. The Board believes that our share price does not reflect the value and potential of this business. Given M&A activity that has occurred in the sector in recent years, such as the acquisition of PSG Global by Teleperformance in late 2022, the Board is of the belief that our 72% investment in this operation is likely worth significantly more than the value attributed to the entire Group based on its share price over the last 12 months
Quite a claim to make -if it’s true!
Empresaria (LON:EMR) is anyone close enough to this sector to validate this statement, below, from today’s update? Seems to me a very vulnerable sector in the current, will the landings be soft or hard environment.
I know a thing or two about this sector and I’ve met the board at EMR - but that was back in 2016-ish. I take anything that any director of a listed company says about internal valuations with a huge pinch of salt. EMR is one of the least focused and most cyclical of recruitment firms, as the chart testifies. The sector is in a prolonged hiatus caused by the endless anticipation of the recession that has yet to materialise. It has lasted more than two years now, which is the longest in my memory of 40 years. The question is whether the market has fully discounted the slowdown. When confidence returns to the market, it will lift all boats, including EMR. The potential rebound in the most beaten up of stocks, is of course the greatest, but I prefer to own the quality operators.
Many thanks for that insight BnB. Much appreciated!
Eurocell (LON:ECEL)
I like this business too - lets do very quick top trumps (look it up on wiki young ones !) comparison of Eurocell (LON:ECEL) v Epwin (LON:EPWN)
if we look at profit expectations for 2024 per stocky
Eurocell market cap £142 mill expected net profit £14.1 million
Epwin market cap £107 mill expected net profit £14.4 mill
1 Nil eurocell
looking at net debt here which is probbaly next on the list
Euorcell £14 mill
Epwin £14.5 mill
lets call that a tie
Ok best out of two Epwin wins here 1-0 (perhaps slight biased refereeing can we have stocky version of var please)
Why does the Euorcell have the premium rating (strange calling cheap share premium rating but there ya go)
This looks like imho its probably to do with past glories - (are they they the man u of the building trade?) - Eurocell have previously posted higher profits that epwin so there its probably logical that profits will bounce back materially when the sector picks up. Epwin are the opposite they have historically had lower profits probably 50% of the level of Eurocell historically - does history mean anything here ? as a holder of epwin i am more than happy to hold the cheaper company htat is expected to make more profits this year (i would happily hold euorcell) - i dont presume that epwin will outperform Euorcell in then profit stakes but i like the trend of improving results here for epwin. Will be intersting to see which compani delivers better profits over the next 3 years - if you have one share in the sector idelaly you want to be on the right one - perhaps sensible peeps here would hold equal of both as they both seem solid companies.
Hi,
I might be mistaken but i think the latest update from Eurocell (LON:ECEL) shows they have cleared their debt and are now net cash.
But I agree with you Epwin (LON:EPWN) does look good value.
Foxtons (LON:FOXT) Thanks for the write up Paul. I take your point that the "recent strong rise in share price has probably factored in most of the immediate upside, in my opinion." But maybe there is more to come?
Guy Gittins, the dynamic CEO, has certainly had an impact since joining Foxtons (LON:FOXT) in September 2022 but he is incentivised in the form of LTIPs valued at £2.5m to get the share price upto 70p. This was noted in the 2022 Annual Report -"The vesting of the award is subject to a performance requirement for the Foxtons share price to be at least 70p for any 30 consecutive days during the vesting period. If this condition is not met, the award will lapse in full." The vesting period is 3 years from the award which was granted on 30/05/22 therefore they will lapse on 30/05/25.
I hope they do manage to get to 70p as I am a happy holder!
Regarding yesterday's discussion of easyJet (LON:EZJ) holidays by NewInvestor1972, I've just booked a getaway for next winter. After checking what I could do the package for myself and then comparing with Jet2 (LON:JET2) and On Beach group (LON:OTB) , I booked with easyJet (LON:EZJ) holidays for a substantial discount. I threw it out also to a conventional TA that I have used for more complex trips in the past, and he couldn't get close either.
The flight times were far better than offered by the others and the flexibility is incredible - I paid a tiny, nominal deposit and have nothing else to pay until a month before with complete flexibility to change up until that payment deadline.
With Easy Jet's extensive route network they will surely start to take a bite out of many competitors.
I would never invest in this sector, especially in the current geo-political climate but I think for those who are interested, it'd be well worth keeping an eye on easyJet (LON:EZJ)
I find easyJet is more expensive than On the beach
Having said that if customers are booking flights themselves, which is taking place a lot now according to trust pilot comments, what is the point of booking with OTB? Is it the hotel price is more attractive with them than the market or something else? with more insights? Anyone?
I would think On Beach group (LON:OTB) and others of their ilk have a wider range of destinations than Easyjet - Asia, Caribbean, USA etc.
On Beach group (LON:OTB) and TUI and the like offer that very reassuring ATOL guarantee. Booking flights etc separately leaves you vulnerable. I suspect we are also seeing polarisation into two camps here.
There are also those who just want the ease and convenience of having it all done for them. A bit like DIY becoming DIFM. Just an opinion from a holder of On Beach group (LON:OTB) !
The benefit of an OTA like On Beach group (LON:OTB) is fourfold:
(I hold in the Boon Fund)
This is where easyJet (LON:EZJ) are changing. They use to outsource holidays but that never worked. They have become a proper tour operator team now with a very experienced team running the holidays division and fantastic buying power. As John Smith said you can often find their prices untouchable as they give themselves preferential flight price and get exclusive rates from the hotels due to the volume they can produce. Hotels love working directly with airlines as it's often incremental sales. EZJ still make more on the actual sale, even when discounting as they get plenty of margin from the hotel. win win
As long as they keep an eye on the holidays divisions costs it will be a winner.
So in answer to your question Eesha if easyjet have a direct contract with the hotel it will often be 20% or more cheaper to book through easyjet holidays than DIY it.
I think this will eat into On Beach group (LON:OTB) market share as they can't compete on easyJet flight packages.
Disclaimer - I do hold easyjet and work in travel
Disclaimer, as someone else said On Beach group (LON:OTB) have plenty of other stuff to sell that is not on an EasyJet flight, won't make a huge difference.
As I said yesterday though this must be why Love holidays has signed a deal with the devil, ie Ryan Air as their sales will be dropping on easyjet routes
Is the race still on?
Is there a finish line?
Cause On Beach group (LON:OTB) climbed about 75% and easyJet (LON:EZJ) only 25%!
I do not hold On Beach group (LON:OTB) anymore.
Blimey, I backed the wrong horse....
Still, 25% is better than a slap in the face with a wet fish!
Keeping hold of easyJet (LON:EZJ)
Yes! But a 25% in such a short time is a great investment.
I see that one clever travel agent Kayak, offers the ability to choose trips NOT using Boeing 737 Max aircraft!
https://www.theguardian.com/bu...
Secure Trust Bank (LON:STB) : Anybody have any thoughts on this company? I hold . TU today looks promising & suggests that the recent issue of car loan interest rate concerns are only a small part of their historic loan book. I am conflicted though - the technicals look good and Stocko has a score of 81 ..but Terry Smith says "never own a bank" ( or airline for that matter!)..
Secure Trust Bank (LON:STB) is on my watchlist and looks quite good & cheap. But I've been held back by wondering what will drive the share price substantially higher? I think it will be a hard slog for them to double or quadruple their business, there are a lot of challenger banks about.
Secure Trust Bank (LON:STB) yes there is plenty of competition from other banks on the deposit side, but they do seem to have quite a strong niche on the lending side in retail finance. Not sure when it will rerate, but at least you collect a nice dividend while waiting. The incredibly cheap valuation (0.3x book value, 3x PE) is pricing in catastrophe, but I don't think this is right as they tend to take quite a prudent approach, for instance recently increasing the credit quality of their loan books.
I hold Secure Trust Bank (LON:STB) too as it looks "too cheap" with an EV of -128 million. Not the greatest quality, but makes a decent profit with little chance of dilution. If it doesn't go up at least I can enjoy the dividend.
Look like HE1 have found some helium
Trading updates in the small cap advertising / digital marketing sector seems to be bifurcating between winners and losers / strugglers:
Winners: Brave Bison (LON:BBSN) , System1 (LON:SYS1), Informa (LON:INF)
Losers / stabilising after profit warning: S4 Capital (LON:SFOR), Mission (LON:TMG), Dianomi (LON:DNM), Pebble (LON:PEBB)
Are we beginning to separate the reality from the hype around AI capability in the post cookie world?
Not particularly.
Brave Bison = riding the influencer marketing boom. But there is no moat, soon others will copy and do what they do better.
System1 = riding the measurement and data-driven wave (in upper funnel brand marketing).
S4 Capital = too exposed to Tech clients, pulling back on spending. Debt issues from too aggressive acquisition strategy.
Dianomi = part of the long-term downturn in display advertising, their subscale nature will doom them, they should just sell out to a bigger display network.
All these companies can not be put into the same bucket of "advertising/digital marketing" as it is now such a big, and diverse, sector.
(I hold System1 in the Boon Fund)
The Personal group (LON:PGH) trading update is positive, albeit in-line. The hospital plan insurance business is growing strongly again and now annual insurance premiums are back over £30m. I've held for a while, but just doubled my holding on the update. It looks like they are going to focus on their core business (insurance and the benefits platform in that order) which makes all the money with the new CEO, whereas the previous CEO was more focused on peripheral areas of reward consulting. Anyone else interested in this one?
Not sure what to make of IG group (LON:IGG) interim results. Bottom line is EPS down 27% to 33.4p against Stocko forecasts of 94.8p for FY2024. Unless there's a stellar 2nd half then this must surely be quite a big miss.
Also worth noting is that net interest income of £70.2 million (H1 FY23: £24.2 million) increased significantly, driven by higher interest rates across all markets.
Not sure how this might be affected by the recent announcements from the regulators.
I hold and still think it's the best of the sector and I'm keen to see what the new CEO, Breon Corcoran will do with it.
The interest income is impressive. Would remain so even though base rates are forecast to ease, we're unlikely to repeat the era of near zero rates.
Only worry on that front is if IG face regulatory pressure to pay higher interest amounts on client cash balances as has recently happened to stockbrokers.
Hi Mark L.,
we're unlikely to repeat the era of near zero rates.
How do we know that? It strikes me that Govt debt mountains mean that getting back to zero interest rates & QE might be a very attractive option for future politicians. They gave central banks independence, and could quite easily take it away again, overtly, or by stealth.
So nobody knows, but I think it's worthwhile to consider all possible outcomes.
Regards, Paul.
Hi Paul
Fair point, I don't know it's guesswork which is subject to my own biases (which we all have.)
I just see recent results showing a slow down in e.g. housebuilders and suppliers, but modest progress e.g. J D Wetherspoon (LON:JDW) . Suggest a slow economy not a recession and so leading to slightly reduced interest rates.
The world backdrop for inflation looks worse than say 20 years ago. For example end of ever freer trade, and a conscious uncoupling from China which has its own inflationary pressures. Anyway no one really knows.
BTW I read in the FT the government has another potential way of managing its interest bill from the vastly inflated QE debt. That would be to arrange/pressure the bank of England to pay less than the base rate on bank deposits it receives from commercial banks. (Apparently the ECB already does this.)
Anyway, I agree with your point that the overall debt level is a problem for central government and they're probably going to find a way to make this more bearable.
I acknowledge it's speculation, but it's just a though overall that we have had exceptionally low interest rates since 2007/2008. Assuming reversion to longer term average it's helpful to net cash companies and the opposite for indebted ones, and nvestors perhaps have not yet appreciated the new normal.
regards
Mark
Quite an interesting debate in FT Alphaville in an article over inflation in the US.
https://www.ft.com/content/864...
Basically there is a body of economist opinion that hikes in prices were transitory supply led issues and nothing to do with inflation. In their eyes this was proven because normally unemployment would drive down inflation, but despite full'ish employment the inflation rate has still fallen. Also higher interest rates have merely affect construction, and pushed people into renting, with the consequence this is one of the elements in in the inflation calculation that has risen, but only because of the Fed's actions.
Obviously there are some different dynamics in the UK and Europe. America is now a net exported of oil and gas (arguably eroding some of the swing pricing power of OPEC). The UK & Europe have a different profile (due possibly to their own goal tactics), but higher interest rates gave cover for a lot of supplier price rises (or reduced size of products), so I do wonder if a bit like the Covid enquiry circus, we will in a backward look think the BOE overthought and contorted the whole matter, and should have cut interest rates quicker.
so I do wonder if a bit like the Covid enquiry circus, we will in a backward look think the BOE overthought and contorted the whole matter, and should have cut interest rates quicker.
i would agree with the viewpoint inflation was mostly a blip. Seems me they did have rates too low for too long - if they had risen marginally earlier that would probably have helped. IMHO most of the latest rises above modest increase from low levels have actualladded to inflation as everyone when forced to pay extra on their mortgage will be trying to claw that back from their boss or from their tenant - or from their customers if they are a company. So as temporary issues i would have done nowt. What it really did do was screw over those with least barganing power who were struggling the most to start with. hey ho i aint an economist.
I don't think rates will get close to zero in the medium term (i.e. 5+ years). Firstly because I can't see inflation falling much below the 2% level due to de-globalisation, wars/conflict and the push to net-zero. Also, given the huge amount of governement debt, real rates (i.e. after inflation) will have to be significantly positive to avoid a buyer's strike and consequent debt crisis.
What people seem to miss on debt is that the central bank owns a decent percentage of the government debt. So in that regard interest is recycled and that debt can “disappear”. So whilst debt may be high don’t blindly believe the headline numbers as they paint a less than accurate picture.
But as you say Interest rates can go anywhere. I would say that the 4-6% range in the UK is the long term historic norm so on the basis of reverting to the mean current 10Y at 4% isn’t high at all. But as has been plainly evident rates can go much lower and much higher over the short/medium term.
Agreed Paul its all guesswork, but it is funny how most things spike back to long term averages 99% of the time as us humans certainly find ways to work round problems all be it normally takes a couple of years for things to normalise.
As an aside I do believe if covid hadn't of happended we would still be at near zero rates and my opinion is thats where we will head back to as the debt piles are so huge they need rates back down to afford the interest rate bill.
Also QE to infinity is doable with low rates. I went to a seminar with top three investment bank back end of last year and asked about the US debt pile from memory its increasing at $200 million dollars per hour, the bank had modelled that the US will run out of money within twenty five years and that model was at lower rates than we presently have.
Only part of the interest payments received is from the UK business. I was amazed they are sitting on billions of client cash it almost surprises me that the interest income isn’t much higher!
IG group (LON:IGG) don't pay any interest to clients on cash, think they get away with it because they don't charge any custody fees unlike Hargreaves Lansdown (LON:HL.).
IG group (LON:IGG) don't pay any interest to clients on cash, think they get away with it because they don't charge any custody fees unlike Hargreaves Lansdown (LON:HL.).
This is not true if you have an ISA or dealing account with IG. There is a custody fee of £96 per year.
https://www.ig.com/uk/help-and...
Our custody fee is a flat fee of £24 and is reduced by any trading commissions you pay during the quarter.
To be exempt from the fee you’ll need to place over three trades during the quarter, or have £15,000 invested in one of our IG Smart Portfolio managed funds.
That is only if you do very few trades. I have never paid anything. 3 trades a quarter, I suspect almost everyone does that.
That is only if you do very few trades. I have never paid anything. 3 trades a quarter, I suspect almost everyone does that.
You were factually wrong though. I apologise for pointing this out. If I responded to every post I read on this blog that was factually incorrect I'd not have time to do anytyhing else. And I have a life...
So why do IG group (LON:IGG) get away with paying nothing and Hargreaves Lansdown (LON:HL.) get criticised for not paying enough? HL charge a fee, no matter how many trades you do.
So why do IG group (LON:IGG) get away with paying nothing and Hargreaves Lansdown (LON:HL.) get criticised for not paying enough? HL charge a fee, no matter how many trades you do.
No they don't. There is no custody fee for a standard dealing account with HL and they still pay interest on cash held in it. And HL pay a reasonable amount of interest on all their accounts already - higher rates than AJ Bell, for instance. IMO they are not the prime target in the crosshairs of the FCA.
Well Hargreaves Lansdown (LON:HL.) do charge fees if you hold any funds and also on their share ISA.
So how do IG group (LON:IGG) get away with paying nothing?
So how do IG group (LON:IGG) get away with paying nothing?
The answer is, they won’t. The FCA is on their case and if you’d bothered reading the interims this week you would have seen this:
In the summer, starting in Singapore and the UK, we will be launching our next generation stock trading platform which will provide comprehensive coverage of ETFs, mutual funds, bonds, thousands of stocks and a cash management offering. Our existing stock trading and investments platform has over 90,000 customers, despite a more limited product range. Our next generation platform will be highly differentiated by providing unique products and features, risk management tools, flexible and competitive pricing and a highly tailored user experience.
So before the FCA get them they will be introducing a “cash management offering” that will no doubt pay reasonable levels of interest on cash held within investment accounts. We’ll see…
IG group (LON:IGG)
It's worth pointing out that 50% of net interest income currently derives from US-held balances.
Of the remaining 50% it's unclear how much of this is from Client Funds held on behalf of UK-based clients in UK banks. The only references I can see in the last Annual Report are of customer funds held in Swiss and Japanese banks for regulatory purposes.
The other data point worth noting here is that the UK makes up c30% of the Group's Net Trading Income, or 40% excluding the USA...so maybe 20% (50% *40%) of Total Interest Income could be at risk?
But I doubt it's even as high as this.
The below is stated in quite a few of the T&C agreements on the IGG website regarding interest on Client Money:
"It is not our policy to pay interest to you on any client money that we hold on your behalf and by entering into this Agreement you acknowledge that you therefore waive any entitlement to interest under the Client Money Rules or otherwise."
And an excerpt from the FCA handbook:
"Can a client opt out of client money rules?
The 'opt out' provisions provide a firm with the option of allowing a professional client to choose whether their money is subject to the client money rules"
I'm sure there is some risk to IGG's interest income, but I imagine it's minimal, unless of course I'm misunderstanding something.
A
Maybe it can be argued that the net interest income increase corresponds directly to the softer revenue being experienced, a bit like a seesaw, save we would obviously prefer the higher revenues.
Wonder if they will maintain the higher dividend if H2 is also soft?
IG group (LON:IGG)
I hold
Not sure what to make of this morning's interims. On initial reading they don't look overly impressive. Revenue and margins down. Interest income of £70m accounts for a significant proportion of PBT of £176m. The former will decline in the second half, assuming interest rates do likewise.
Observations and thoughts welcome.
PPHE Hotel (LON:PPH) expect to deliver full year results above previously upgraded expectations. Good to see room occupancy improving
Reported RevPAR was GBP120.7, up 25.5% vs 2022 (2022: GBP96.2), reflecting a sustained increase in occupancy throughout the year of 72.4% (2022: 60.0%) and an average room rate increase of 4.0% to GBP166.8 (2022: GBP160.4).
PPHE Hotel (LON:PPH) interesting this big director buy recently to get liquidity up to enter fste 250, cleared a seller, work events and meetings up in hotels again returning to pre covid levels, lots of promise/hotel opening for 2024. Last Trading statement mention capital returns and dividends, on their website the last webcast is a good watch Q&A
Skimming Team17 (LON:TM17) results this morning and it is a struggle to work out what it means. Why can't they tell us the FY sales figures? Instead just quoting EBITDA but with some adjustments. All seems needlessly vague and unhelpful.
I agree. Given the profit warning some weeks ago, tell us straight what you expect, rather than being 'all excited' about the future. I sold at a modest profit this morning; however, I wanted to stay in longer as there has been some issues with the company which appear to be straightening out and substantial buying by a new director. Will watch on the sidelines for a while.
My morning smallcap tweet: The three egg news omelette
Skinbiotherapeutics (LON:SBTX) Kromek (LON:KMK) Location Sciences (LON:LSAI) Team17 (LON:TM17) Petards (LON:PEG) PPHE Hotel (LON:PPH) Narf Industries (LON:NARF) Sigmaroc (LON:SRC) Foxtons (LON:FOXT) Strix (LON:KETL) Epwin (LON:EPWN) Tissue Regenix (LON:TRX) Mortgage Advice Bureau (Holdings) (LON:MAB1) Acuity RM (LON:ACRM), Fuller Smith & Turner (LON:FSTA), Personal group (LON:PGH), Animalcare (LON:ANCR), Empresaria (LON:EMR), Novacyt SA (LON:NCYT), Aquis Exchange (LON:AQX), Secure Trust Bank (LON:STB), Treatt (LON:TET)
◄SkinBioTherapeutics (SBTX)► borrows $5m convert from with Macquarie Bank and CLG Capital. 1% over SONIA. Come with warrants. Strike is 93% of prevailing price. Death spiral then? [SP=14.75 Cap=28m]
◄Kromek (KMK)► wins £1.4m+ order to supply D3M detectors and associated networkable solutions. Rev to be received this FY. [SP=5.25 Cap=31m]
◄Location Sciences (LSAI)► $3m max unsecured term loan facility at 1.5% per month = 20% PA. [SP=0.14 Cap=4m]
◄Team17 (TM17)► continues to expect FY-Dec adjusted EBITDA to be at least £28.5m. So in line. New CEO is ' extremely excited' about prospects. Steady on. [SP=211 Cap=308m]
◄Petards (PEG)► warns FY-Dec rev c.£9.4m down 14% and 3% lower than market expectations. Cost cuts of over £0.4m PA. [SP=4.14 Cap=2m]
◄PPHE Hotel Group (PPH)► guides FY-Dec above guidance with rev £413m+ and EBITDA £127m+. Guidance was £400m and £120m. RevPAR up 26%. Outlook - average room rate is now showing signs of stabilisation with occupancy gaining momentum. [SP=1195 Cap=506m]
◄Narf Industries (NARF)► guides 12m to Dec rev up 130% and EBITDA positive (-$2.6m). Loss $1.15m ($18.4m). In line? Note FY end moved to March. [SP=0.7 Cap=12m]
◄SigmaRoc (SRC)► more relief as the SP recovers from the slapping administered by the recent 47.5p placing to fund a massive acquisition. Guides FY-Dec rev up 8%. U/L EPS 8p, above mkt exp. FY24 exp unchanged. [SP=62.8 Cap=700m]. I hold.
◄Foxtons (FOXT)► guides FY-Dec rev and adj op profit ahead of consensus at c.£147m and c.£14m resp. F/C were for £144.5m and £11.8m. Outlook -"under-offer pipeline significantly ahead of the prior year despite weaker market conditions". [SP=53.28 Cap=161m]
◄Strix (KETL)► guides FY-Dec adj pretax £20.1m and £20.6m at const FX. "Demand in kettle controls in the key export regulated markets remains subdued...the recovery has been slower than anticipated....unregulated and China markets, which represents c.20% of Strix's kettle controls' gross profit has shown more positive signs." Sounds like a miss then. [SP=73.9 Cap=162m]
◄Epwin (EPWN)► guides FY-Dec U/L op profit towards upper end of market expectations. Consensus is £23.9m. FY24 trading in line. [SP=74 Cap=107m]
◄Tissue Regenix (TRX)► guides FY-Dec rev up 20.6% and an adj EBITDA profit. Both are ahead of expectations. Outlook positive. [SP=57.2 Cap=40m]
◄Mortgage Advice Bureau (MAB1)► guides FY-Dec rev up 4% and adj pretax slightly ahead of consensus. "Pick-up in mortgage volumes has continued into January, with written volumes substantially higher YoY." [SP=806 Cap=460m]
◄Acuity RM (ACRM)► wins £103k 3 yr order, its first contract with a North American state organisation. [SP=4.9 Cap=6m]
In line: FSTA, PGH, ANCR, EMR, NCYT, AQX, STB, TET
Wondered myself if I've got something wrong on BBSN.
Market has fawned over Sorrell yet the Green bothers who have bought plenty of stock, acquired and bedded in businesses successfully, and done what they said they were doing to do over years get ignored.
Think the problem is that it's tricky to work out what it actually does beyond digital marketing and so unless PIs are willing to read more at the start it gets put in the "too hard" bin.
I hold in family accounts.
Michael
I have recently bought back into Brave Bison (LON:BBSN) as I feel it had got hit too much in the sell off. I bought more again after this week's trading update.
What the Green brothers have shown they can do is buy a not very good business at a good price and cut out costs aggressively and turn it into a break-even or profitable business. My opinion is that future acquisitions will probably follow this playbook too. You can imagine there are a number of digital advertising businesses out there for sale with bloated cost bases. Indeed Brave Bison itself was just such a company before the Greens bought their strategic stake and injected themselves into the driving seat.
What I think the Greens have yet to prove is that once costs have been cut they can actually grow these businesses. If they can then the current multiples look terribly low. The stock price seems to imply that instead they will not grow the top line organically and the future holds just more cost cuts. If the company can demonstrate true organic growth, then I think the shares will rerate.
That's a fair observation. Yes, BBSN was a terrible business before the Greens came in.
They've already built a marketing business with Tangent so whilst not proven they can buy poor quality businesses they have proven they can grow it.
In any case, hopefully we're right and we're rewarded. Thank you for sharing.
Morning Paul. Thanks for looking at Brave Bison (LON:BBSN) and providing reassurance. Great output as ever perhaps you should suggest to management that they pay for your trip to Gozo as a reward.
perhaps you should suggest to management that they pay for your trip to Gozo as a reward.
Haha, but oh no, I wouldn't want to be beholden to anybody! (other than to you, the readers)
Epwin (LON:EPWN)
Building products supplier
Top banana year end update this morning , they are only on track here but year just finished is near top end of expectations so ahead of the midpoint. That’s the beauty of having a “range” clearly provided to the market 100% clarity ref the numbers. Note they updated as recently as 27/11 so one would hope they were hitting prior expectations.
Ok it’s all about the dreaded 2024 expectations here and they seem confident but mention short term headwinds - They seem quietly confident which is fine by me.
Confident outlook for FY 2024
These results indicate that the current drivers for the Group's range of low maintenance, energy efficient and recyclable building products are resilient and trading in the first weeks of 2024 has been in line with the Board's expectations.
The Board remains confident of executing the Group's strategy and in the strength of the medium and long-term drivers of its markets, despite the short‐term macro-economic outlook.
This company has now been delivered 4 years of really solid numbers and outlook for 2024 is good - with pe of 7.5 and no real negatives I can think of this company is totally unloved by the market.
Notes
Ok they sell building products no premium should be expected - however looking at what they supply it’s pretty specialised stuff so they they have their specific speciality.
There is debt but it’s 0.5 ebitda and their cashflow in generally great - note debt figure per stocky are nonsense (technically correct) as they include future rent obligations.
Recent annual results are better than numbers posted in stocky suggest look at the 2022 annual report and adding back goodwill adjust and fair one offs they had a good.
They have been making solid small add on acquisitions that are working well.
I am struggling to see why this company would trade on pe of under 10 - I have to presume the market expects trade to deteriorate medium term or short term - based on what the company has been delivering and is saying today I would say the company is very well placed even if the market is partly right and things get tougher in 2024.
Will it get a green mark today from stocky perhaps not but I do kinda get why others may think there is not enough to like here to take the plunge - personally I would happily add more at todays levels if I had funds particularly with their quiet confidence.
Epwin (LON:EPWN)
I’m with you on the update and a happy holder. Stocky likes Eurocell (LON:ECEL) but its performance is far more cyclical, recovery forecasts less confident and balance sheet not significantly superior. Epwin’s net debt is now below £15m and margins are improving. Feels like a higher quality business than many small cap peers yet valued alongside the weakest.
edited to add - looks like we both spent the last 15 mins doing the same comparison
Strix (LON:KETL) - Strong H2 cash flow (new report from Equity Development here: https://www.equitydevelopment....)
There are several encouraging messages which jump out from Strix’s trading update released today, led crucially by the strong cash generation during H2. This has enabled the Group to come in below the year end banking covenant test, thereby removing significant risk from the rating. In addition, the strong performance of Billi and LAICA has largely offset the slower than expected recovery within the regulated kettle controls market, resulting in FY23 numbers modestly below expectations at the adj. EPS level.
With significant scope for recovery in its key market and the focus switching to the most profitable areas, we expect a marked uplift in profitability and its share rating over the medium term.
Thanks Paul for Eurocell (LON:ECEL) & Watkin Jones (LON:WJG) - a phenomenal workload from you and the others for this week (and before) which I really appreciate.
I had held Watkin Jones (LON:WJG) for a while on the prospects of a recovery, but it was painful sitting on a largish loss. I probably got in too early and caught a falling knife.
I decided first thing on the morning of the update to sell out, based on a number of factors which you have highlighted - I am not confident of a speedy recovery, and with so many other companies now exhibiting a potential for an up-tick I felt there were better opportunities elsewhere.
The final nail in the coffin was the decision not to pay out a dividend - I understand this from the companies point of view (preserving cash), but it is just another signal for me to sell and move on. Being paid to wait is important for me, and cancellation of a dividend from any company is normally a red-flag as it is indicative of underlying issues with cash-flows and revenue.
I think there will be a solid recovery here, but it could take a while longer, so will keep it on my watch list.
I always also find it somewhat cathartic to get rid of a big red number our of my portfolio account at my brokers.
Best wishes. K
Hi Kevin1,
Interesting, thanks.
I always also find it somewhat cathartic to get rid of a big red number our of my portfolio account at my brokers.
That's why I don't have a P&L column on my portfolio spreadsheet, as it clouds my judgement for the reason you state.
Regards, Paul.
Time Finance (LON:TIME) a cheaper alternative to Cornerstone FS (LON:CSFS) worth a look. Continued growth, positive outlook, growing EPS
The two mentioned companies have nothing in common and Time Finance (LON:TIME) if you really research into it looks like a Subprime loan provider. Very risky and definitely not growing as fast as Cornerstone FS (LON:CSFS)
All the best
Time Finance (LON:TIME) v Cornerstone FS (LON:CSFS)
Agreed entirely different...but Time is the relatively 'quality' business as seen easily by its underlying high profitability, how it handled the potentially deadly covid escapade (staying profitable despite the blows) and the durability of the engine that drives its underlying growth and returns. Its not loved obvs and didn't help itself before current CEO so much (wasn't doing badly, just not 'strategically crisp').
Time is 'non-prime' not 'sub-prime'. Very different things. Time does not lend to stressed or 'low quality' businesses but seek to make a profit by charging extraordinarily high rates to cover for losses. It lends to small businesses that banks aren't interested in lending to and that credit data by default labels 'high risk' as they are not large businesses! Time exploit this structural gap by lending at good margin to businesses that are much better quality than data driven lending of big banks and credit reference agencies can see. Most of the loans made are also asset backed meaning that defaults have some cover (Time recognise such defaults and losses straightaway when happens but then historically do a great job of recovering value through security they have in place).
So Time is like an old fashioned local relationship bank in some respects. That's over simplistic/rosey but you get the analogy. They're exploiting a space that isn't well covered by 'big money' and where some of the competitors may not be as professional/cautious as they are. Not being a bank with deposits is on balance advantageous imo as it helps them maintain a high net interest margin that if they became a bank would likely come down and make them more not less cyclically vulnerable and lower quality business in terms of risk and return (as a bank they would have data/reg restrictions on 'credit risk' that would make their small company niche harder to exploit and they'd need to find 'higher quality' businesses ie larger not really higher quality...the sad story of PCF is significantly this).
By comparison Cornerstone is just another payments/processing firm chasing high volumes and transaction fees in race with all the others to become some significant or become irrelevant as someone else chases in behind. The broad non bank payment space can generate some high returns short term for a business but not many expand successfully over long period of times...ie they are low quality...this is as there is little protection from competition above and below. Cornerstone may be the exception...or not. Nice price moves obvs.
I don't know Cornerstone well as personally I have an aversion to all the minnow payment processors as I see them as always vulnerable businesses and outsiders will have little ability to assess the durability of revenues (based on some historic business experience with a startup business that had to work closely with players in the area). So my bias is clear :)
(What happens if Equals (LON:EQLS) goes messy or one of the other liked players...does it burst the bubble of enthusiasm for these sort of stocks?)
Be careful Time Finance (LON:TIME) it’s one of Simon Thompson loved stocks unless you changed your tune now!
And I stick to my point it’s just a factoring business
1) Unaware of Simon Thompson tips unless someone tells me! Clearly I am now selling ;) (...not really...Throw sh1t at the wall and some sticks etc)
2) Its more than just factoring with asset backed lending the biggest revenue...but factoring is part of biz...if it is 'just' that and does it well with a pricing opportunity driven by its positioning within the overall structure of things...well then that is a durable franchise and moat (much much more than a small fintech payments business aka grimtech)
Time Finance (LON:TIME) should present both earnings and valuation upside...particularly as we emerge into a less miserable economic situation (assuming we do)
As an aside. The biggest investor in Time Finance (LON:TIME) are these guys -> https://www.arenaco.com/ -> look up founder Dan Zwirn (interesting and hardcore investment guy). Time are like a mini version of Arena in may respects...them owning a big stake is an impressive vote of approval IMO.
I wrote about the stake from Arena here - https://www.stockopedia.com/co...
(I might have provided more info or updated in the Medium version of it)
I had some concerns about Arena's motivations and spoke to mgt about it. It seems those concerns didn't surface and Arena have been passive investors. Going forward there remains some potential for a form of collaboration between Arena and Time.
mojomogoz, I suspect there are already behind the scenes conversations between Arena and Time Finance (LON:TIME) on some sort of non-arms-length relationship. Time have mentioned several times in recent updates, that they will need more capital to grow their own-lending book. What easier (but maybe not the best for PIs) way than a commercial agreement with a 20% shareholder?
I wait and see... meanwhile, the increasing SP is pleasing, as more investors wake up to the good value on offer here. Not quite at my sell price yet, but if the momentum continues I might cash in.
(I hold in the Boon Fund)
TBH its still not obvious to me why Arena invest in Time Finance (LON:TIME) and it causes me a little bit of angst that I can't see the logic (for reasons laid out in my linked note). Maybe the Arena fund has evolved to taking 'unstructured' equity risk or maybe its an exception to invest in Time as its a business close to their MO. Hard to see how they can inject debt capital into Time and then both Time and Arena get enough return out of it...Time borrow prime rate and lend non-prime whereas Arena would want to provide funds that earn non-prime rates!
What could make sense: 1) an exit for gain by Arena or 2) a takeover by Arena and then Time becomes their a UK lending platform they scale up with their fund.
Its possible that Arena providing funding for growth. Perhaps a convertible gives mix of security and upside that Arena want and growth capital that Time want. Or some sort of JV expanding Time capability in new area. Dunno
As for price and value...there's potentially a long runway for Time structurally and cyclically. I invested thinking 100p was possible. May be too optimistic...and relies on Time doing any growth financing well
It is quite funny since you posted negatively on Cornerstone FS (LON:CSFS) it jumped from a seller of 28p to a buyer of 32p!
Obviously you haven’t properly researched the company , its prospects and growth potential.
Mojo
Someone else posted in the morning that Time Finance (LON:TIME) is a better alternative on growth and value than Cornerstone FS (LON:CSFS) -the latter grows about 100% pa its revenues. Estimates for this year are for revenues to grow about 15-20% ( if you catch my drift!).
All the best
Beautiful banalysis yiannos1! Bravo
Rather than a bit of macho posturing and waffle why not inform the ignorant like me why Cornerstone FS (LON:CSFS) is so super (I didn't really post negatively about CSFS...rather I posted positive about Time tbc). I've provided actual analysis rather than your...whatever it is you've provided
CSFS looks like just another 2021 opportunistic IPO mess down 50% from listing. Whereas 'high quality' Time is up about 1/3rd since despite all round trauma of 2022... so it WINS! Like CSFS it too swooned down in 2022 as we awaited the end of the world....but not as much as IPO flotsam ;)
Anyway, good luck with CSFS. Its got to keep moving really hard to grow into expectations and valuations...otherwise it will get cut in half. My dumb money is on the latter as more probable. But you are right in that I don't really know (and don't really care) as payments is just something I avoid knowing both my limitations and abilities. I'd wager that no-one promoting CSFS can articulate a 5+ year business evolution for it...and given its size and competitive positioning you need to do that as its more a company that should be be in VC land than public land.
Try not be so touchy in your next reposte. I am allowed to like and dislike companies. I'm not always right. I'm not touting Time to anyone.
I have provided all the information on Cornerstone FS (LON:CSFS) when it was 18p!
Haven’t got a clue what your post is offering other than abuse.
I don’t agree with you as well but i don’t bully you. I don’t call your analysis banalysis nor macho posturing and whatever else you mentioned there,
I have explained that Cornerstone FS (LON:CSFS) grows in revenues 100% pa but the analyst estimates have it for 15-20%. An experienced and successful investor understands quickly that the company will be beating the market in the next 2-3 years.
Paul Scott mentioned Cornerstone FS (LON:CSFS) and after I have realised that all analyst estimates were completely wrong I have shared this with the forum here.
If you have any other similar opportunities that you think the estimates are wrong please feel free to share this with us.
Billington Holdings (LON:BILN) Nanoco (LON:NANO) On Beach group (LON:OTB) McBride (LON:MCB) are others I have suggested they provided an opportunity for investment. We all know what happened.
And I have warned on many other stocks that almost all of them have collapsed.
I don’t get it always right as well. No one does and that’s why I diversify well enough.
All the best Mojo
yiannos1...you picked a 'fight' as I had in passing said something not positive about Cornerstone FS (LON:CSFS) when responding to something you said about Time Finance (LON:TIME)...seems pretty normal behaviour by me on a discussion platform (and I made clear my knowledge on CSFS was low partly as I have a well founded aversion to small payments space stocks) ...and now you are crying that I bully you. Get a grip and don't be such a drip! I don't follow you closely but it seems you like to dish it out...
Here's why I used 'bullying terms':
Macho posturing -> supposedly me saying something negative on CSFS caused the price to go up 10%. Maybe that's humour...but it feels a little bit like my ... is bigger than your .... ! And that's just silly playground level stuff when talking stocks. PS last time I looked Time is winning today! (yeah ridiculous to say it isn't it!?)
Banalysis -> I refer you to the above and talking about intra day prices as your (only at time) reposte. Also you called Time a subprime lender. For someone so informed and superior in there comments in here that is a shoddy mistake...the kind of thing you seem to beef about if others get it wrong on your precious (I learned that from our interaction).
I don't know or care what you've historically said on CSFS or other stocks. I don't follow your tips and I'm not keeping score. I'm not competing with anyone in here and I don't compare my returns to others. Park the ego and insecurity dude! If you are going to claim superiority and shut me down as you're an 'experienced analyst' or something then post up your credentials...we are all just spitballing here but its helpful to know when we are in the company of superior capability and should kowtow.
I learned from our exchange that you are probably over exposed to CSFS and are anxious about it daily. You've got an itchy trigger finger with it as you see the parabolic rise and worry it could come down a lot and you'd like to be smart enough to both sell and avoid...but stick and ride higher if it keeps going. Ahhh the (immature?) speculators dilemma...this conversation wont help you either as it will now play into your already fraught CSFS feelings - joy and ego at the payoff so far, angst about the future.
But hey...best wishes and all that. And I hope CSFS works out well for you and others...it may, and it may 100% pa as you say (as a natural sceptic I feel cautious of such claims in general sense)....I will miss that as I'm playing elsewhere I'm afraid and what I perceive as a structural inability for small players in payments to secure their franchises (its the nature of the space...I've been around it in a 'fintech' start up...maybe that's baggage on my part but we got to just live our own realities)
Your mojo, out
That’s nice!
God, you're up early like myself :)
Nah, he did them yesterday afternoon, and having a lie in....