Small Cap Value Report (Thu 26 Aug 2021) - VLX, WJG, BMS, D4T4, MACF, LTHM

Good morning, it's just Paul here today, with the SCVR for Thursday. Jack's off galivanting, and I'm dog sitting today, just to keep you in the loop! Today's report is now finished.
Agenda -
Paul's section:
Volex (LON:VLX) (I hold) - brief comment on another acquisition, looks an excellent deal.
Watkin Jones (LON:WJG) (I hold) - diary date for a Capital Markets Day (CMD) - 2 Nov 2021.
Braemar Shipping Services (LON:BMS) - a vague, but reassuring trading update. Looks potentially interesting, still modestly rated, in an interesting sector.
D4t4 Solutions (LON:D4T4) (I hold) - an in line AGM trading update. 2.0p final divi to be paid on 17 Sept. A difficult share to value, but I like the story.
Macfarlane (LON:MACF) (I hold) - very good interim results. The usual uncertainties & headwinds are mentioned, but despite that FY 12/2021 earnings expectations are raised. Broker upgrade. Looks good value to me.
James Latham (LON:LTHM) - a stunning trading update, with 4 months current year trading making the same profit as the whole of last year! Boom times won't last forever though. I crunch the numbers, and conclude that it looks priced reasonably.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Volex (LON:VLX) (I hold)
Another acquisition, of Irvine Electronics, in the USA, for $16.4m. Looks a cracking deal - low multiple of EBITDA (current run rate $3-4m pa). Good strategic fit, with most of Irvine's customers being in the defence sector.
Watkin Jones (LON:WJG) (I hold)
Capital Markets Day - 2-4pm, Tue 2 Nov 2021.
Trading update on same day, and presentation slides will be on website.
Braemar Shipping Services (LON:BMS)
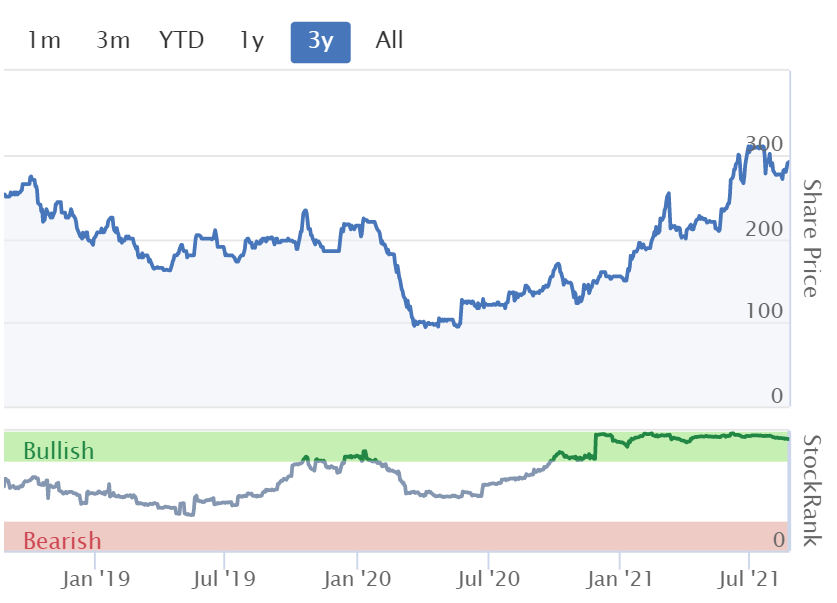
291p (pre market open) - mkt cap £93m
Braemar Shipping Services Plc (LSE: BMS), a leading international Shipbroker and provider of expert advice in shipping investment, chartering, risk management and logistics services...
We’re given a brief update today, ahead of its AGM -
'The board is pleased with the financial and operating performance of the Group for the first five months of the year.
Trading has been good across all three of the Group's divisions and the breadth of the Group's business model, the diversity of the broking operation and the markets in which the Group now operates, have insulated the business well from any ongoing pandemic weakness.
The board is united in seeking to develop further the Group's growth strategy and we look forward to the remainder of the financial year with confidence.'
There’s precious little useful information in that.
I assume it means the company is trading in line with expectations, or maybe a bit ahead?
Looking quickly at the StockReport for BMS, I can see some attractive metrics, especially the forward PER of only 11.5

.
My opinion - I’ve not properly looked at this share for a while. It could be worthy of further research, because the valuation looks cheap, and of course shipping is a very lucrative sector at the moment, due to sky high freight rates from the Far East. Hence it seems logical to expect BMS to be grabbing a slice of the action in its sector.
Today’s non-specific, but positive-sounding update, probably makes it more likely that the company would meet/beat profit expectations.
Overall then, this one looks quite interesting.
.
.
D4t4 Solutions (LON:D4T4) - I hold
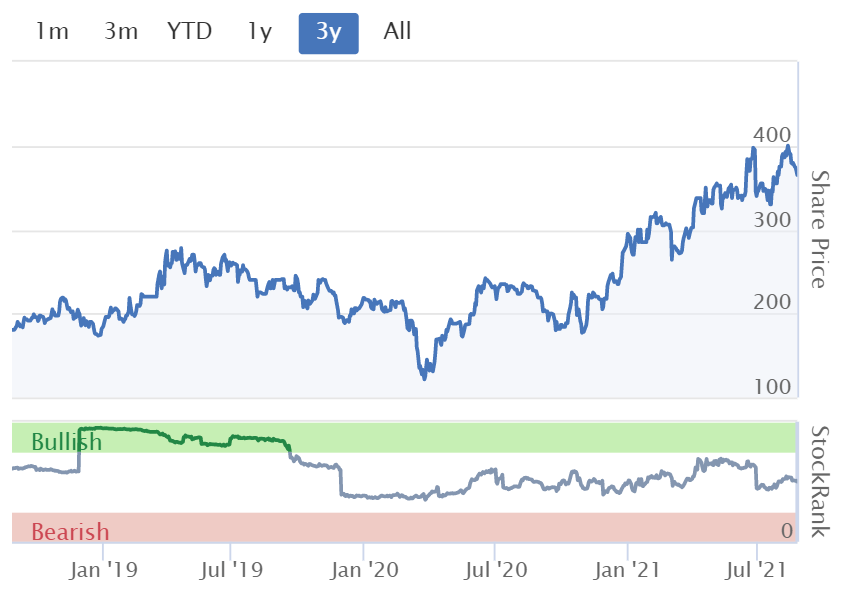
370p (unchanged) - mkt cap £149m
Trading Update (AGM)
D4t4 Solutions Plc (AIM: D4T4, "the Group", "D4t4"), whose software enables businesses to make smarter, informed decisions via Celebrus, its flagship first party product suite, gives the following update ahead of its Annual General Meeting being held today at 9am BST.
An in line update, nothing exciting -
The Group continues to trade in line with the Board's expectations; the business is delivering against its key KPIs and is well positioned in its core markets.
Other points -
- Roll out of new software continues
- Prickly Cactus acquisition is going well
- Marketing campaign in the USA
- Recruitment of specialist staff is going well
- Ash Mehta joining as CFO on 1 Sept (I recognise that name from a previous investment)
- Diary dates - H1 trading update in mid-Oct, Interims in Nov.
My opinion - sounds like costs are rising, which is fine by me, providing the money is being spent wisely.
This is a difficult share to value, but what appeals to me is that the products sound good, and highly relevant - with impressive clients internationally. So if it can build recurring revenues, then the business could scale up.
Looks expensive on a forward PER basis, so this is definitely not a value share. There was a bout of profit taking recently, as with so many shares, but it's recovered quite well since.
.
.
Macfarlane (LON:MACF) (I hold)
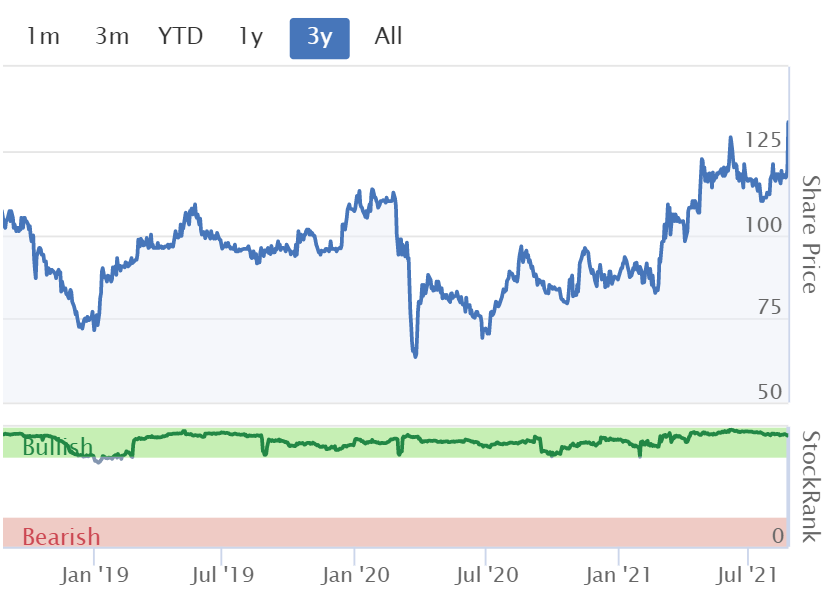
135p (up 13% at 08:29) - mkt cap £213m
This is a packaging manufacturer & distributor group.
As readers have noted in the comments below, the headline numbers for H1 (6 months to 30 June 2021) look superb (whilst bearing in mind that the 2020 comparators are soft due to covid). The commentary points out that profits have also doubled on the 2019 pre-pandemic numbers.
.

.
Also, thanks to martinck1 who points out in the comments that apparently for the first time, the company provides an adjusted profit figure, stripping out acquisition-related amortisation (which is standard practice at most companies).
This was an anomaly which I remember flagging up here before, in that previously MACF has hidden its light under a bushel, by reporting overly conservative EPS. That enabled us to buy the shares too cheaply (I got in at 95p a while back, after spotting the amortisation anomaly).
Acquisitions - 2 recent deals have boosted H1 sales by £8.1m, and operating profit by £1.9m, which is a good part of the £5.6m increase in operating profit.
That’s fine by me - buying up nicely profitable bolt-on acquisitions, using existing resources (no new shares seem to have been issued since 2018) is a very good strategy. We’re seeing a similar thing from Volex (LON:VLX) (I hold). Management that execute acquisitions well (i.e. buying good quality businesses at reasonable prices, with a good strategic fit & cost synergies, etc), can build significant shareholder value in that way, providing nothing goes wrong of course.
Outlook -
The Board expects that the Group's full year outlook for 2021 will be ahead of its previous expectations, despite the challenges we are expecting in H2 2021.
The challenges all sound generic, that we’re hearing from so many companies in many sectors, including -
- Inflationary cost pressures
- Raw materials supply constraints
- Staffing pressures
The key thing seems to be that some companies are navigating these problems better than others, and if demand is strong then that outweighs the problems, as seems to be the case here. Also it gives companies a reason to raise selling prices, if customers are struggling to find alternative supplies. Hence I’m beginning to see opportunities as well as threats from widespread supply chain difficulties.
Broker update - many thanks to Shore Capital for sharing its research update today, very helpful. Shore raises its profit forecast by 14%, a meaningful upgrade, to 10.2p adjusted EPS.
The commentary indicates that Shore sees this as a cautious forecast, so reading between the lines, we could see forecast raised again in H2, providing supply problems don’t get too bad.
Valuation - the broker consensus figures on the StockReport are now way too low, and should rise as new forecasts come through. Using the current share price of 135p, and the 10.2p latest adj EPS forecast from Shore, we get a PER of 13.2 - good value I think, for a decent quality business that’s now generating a decent operating margin, and growing.
Shore says that MACF looks unduly cheap compared with giant competitors Bunzl (LON:BNZL) and Ds Smith (LON:SMDS) . Being large caps, I don’t know anything about them! The StockReports here show BNZL on a fwd PER of 19, but DS Smith at 13.9, which looks similar to the rating of MACF. I prefer a smaller, growing company, as the growth rate could be much faster than the giants. At least they give us some idea of a valuation benchmark.
Manufacturing division - performed badly last year, but has since been turned around, back up to a decent level of profitability - £2.0m in H1 2021, vs just £168k H1 LY (that’s pre-amortisation operating profit). It’s encouraging to see this division back on track.
Net debt is modest, with plenty of headroom on bank facilities, this looks absolutely fine to me -
Net bank debt at 30 June 2021 was £8.7m, an increase of £8.1m from 31 December 2020 following £12.2m of investment in the acquisition of GWP and Carters. The Group is operating well within its existing bank facility of £30.0m which runs until 31 December 2025.
Balance sheet - is adequate, but not great, in my opinion.
NAV of £87.0m is mostly goodwill (of £77.0m). Strip that out, and NTAV is £10.0m, which requires some reliance on bank debt.
Working capital is not great, with a current ratio of 1.0 - personally I like to see a bit more of a balance sheet buffer, but it’s not a deal-breaker because the business is decently profitable, and cash generative - which naturally strengthens the balance sheet over time.
Lease asset/liabilities figures look quite high.
The pension scheme has moved into an accounting surplus, of £4.6m, but accounting numbers are often very different from the reality of actuarial figures, which is what drives cash payments, hence matters more.
The deficit recovery payments seem to be ongoing, at £1.2m in H1 (see cashflow statement), so I’m taking the pension surplus on the balance sheet with a pinch of salt. It’s cashflows that matter.
Cashflow statement - all looks fine to me. It’s a decently cash generative business. Last year benefited from working capital movements, which have gone the other way this year, as I would expect.
Acquisitions saw £12.2m paid out in H1.
Also note that due to big lease commitments, there’s £3.36m relating to rents paid, in the financing section near the bottom of the cashflow statement. Hence all the numbers above that line are over-stating real world cash generation. This is one of the many problems created by IFRS 16 that investors need to be aware of, and manually adjust the numbers if you want them to make sense!
My opinion - very good numbers, and no serious issues with the balance sheet or cashflows.
Valuation still looks modest, so I like this share, and am happy to continue holding.
If the company is able to make more acquisitions at reasonable prices, then it could be a long-term winner and see a re-rating onto a more aggressive PER perhaps? It’s not the type of share to shoot the lights out, but I do like to have some reasonably-priced, well run value shares like this in my portfolio.
MACF also seems to have some favourable tailwinds for its products, e.g. protective packaging for eCommerce, a structurally growing niche.
.
.
James Latham (LON:LTHM)
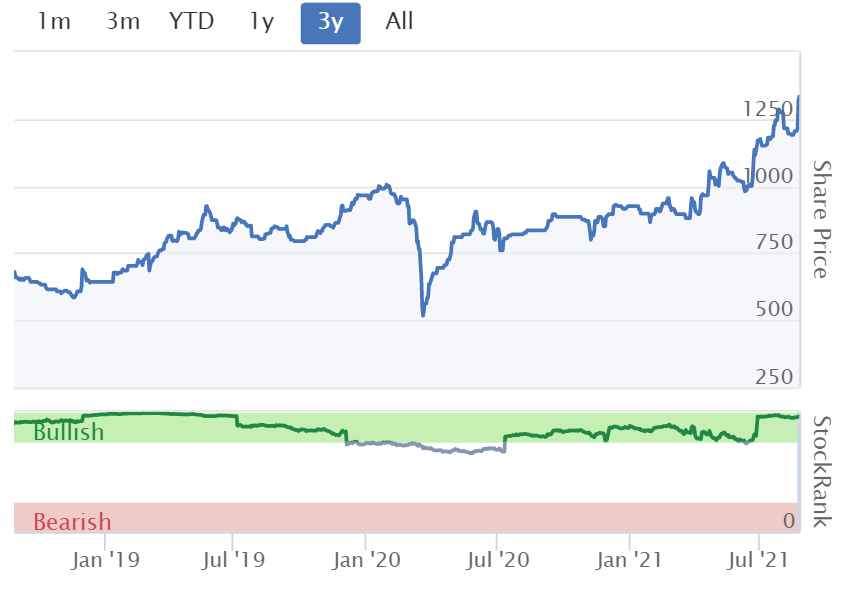
1320p - mkt cap £262m
Latham’s is a family company which sells timber products in the UK.
It’s a long-time favourite value share here at the SCVR, and its ludicrously strong balance sheet in particular is a joy to behold.
Many thanks to Discodave4 for flagging up a remarkable trading update from yesterday, which LTHM annoyingly issued during market hours at 12:24, which is a really bad thing to do, putting out price sensitive information when the market is open. I wish they would stop doing this. All trading updates should be issued at 07:00, especially planned updates, so that everyone has an equal opportunity to read & digest the news before the market opens at 08:00.
Unpacking the update, it looks as if Lathams is enjoying a trading bonanza at the moment.
Revenue for the first four months of the current financial year, namely 1 April to 31 July 2021 is £127m. This represents an increase in sales per working day of 34% compared with the three months ended 31 March 2021…
Volumes per working day are up 11% from the three months ended 31 March 2021
This sounds good, but I would expect a seasonal trading surge for timber products in April-July, compared with Jan-March. Therefore without any context, it’s not possible to say whether a 34% uplift is good, or as expected.
If my sums are correct, the above implies that selling prices have risen by 20.7%
Market conditions - striking comments here -
Global demand for timber remains high, which has resulted in increased prices and shortages that have not been seen in the industry before.
Sea freight - as we know, costs have shot up for everything imported from the Far East -
We continue to see large increases in container rates which have caused significant increases in the costs of our imported products.
No surprises there, everyone is saying the same thing. What matters is whether the increased costs can be passed on to end customers? Logic dictates that if there are shortages, then selling prices can be raised. Basic supply & demand.
Margins - have gone up, not down - this reminds me of the car dealerships, where supply constraints combined with high demand, have resulted in a stunning rise in short term profits. It looks as if the same thing is happening at Lathams -
Our ability to secure enough volume of products from our key suppliers and the unprecedented high demand has resulted in improved margins.
Overheads - “well controlled”, bad debts “very low”, and a shortage of haulage drivers “continues to be difficult”, but customer service levels are being maintained.
Profitability - a very striking statement here -
This revenue and margin increase together with our control of overheads has resulted in profit before tax for the first four months of this year being approximately the same as we achieved for the whole of the last financial year, namely a profit before tax of £18.6m.
That’s astonishing! Looking back at pre-pandemic trading, Lathams was making about £7m per half year, split fairly evenly between H1 and H2. So to have made about £18.6m just in the first 4 months of this year, shows that company is absolutely coining it in right now.
Higher inventories have been required to meet demand, and are taking longer to arrive in the UK.
Shortages of other building products could cause delays to Latham’s customer orders.
Outlook -
...at this stage we are cautiously optimistic that demand will be strong for the rest of the calendar year, but that margins will come under increasing pressure.
This is a reminder that current trading should be seen as a one-off. Generally speaking, shortages and higher prices eventually unwind, and can often reverse into a glut, and collapsing prices.
Diary date - 25 November, for interims to 30 September.
My opinion - a pretty stunning update! It seems to me that shareholders in companies like this, which are making hay whilst the sun shines, should be treating these one-off bonanza profits due to external problems, as a temporary aberration, and not valuing the shares based on the profits in a one-off boom year.
Booms often turn into busts, so this year’s party could be next year’s hangover. Who knows when the party is likely to end?
How to value it? Personally I would largely ignore this year’s bumper profits, and put it on a PER of say 15 times last year’s 75p EPS, which gives a valuation of 1,125. Plus an extra uplift of say 20% to reflect the strong balance sheet, cash pile, and bumper trading this year. That gets me to 1350p, compared with a current share price of 1320p - hence my conclusion is that this share looks reasonably priced.
Stockopedia loves it too, with a very high StockRank.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Nicktudor - please tell us which company you're talking about - see Explanatory notes at head.
Macfarlane (LON:MACF) - if only had spotted the volume rise a few days before results - duh.
I would agree with Paul's description of the update from James Latham as "stunning". The "one-off" COVID recovery effect is confirmed by the company in this update but I am also interested that the update mentions the global increase in the demand for timber (and this easily confirmed by a quick search on the internet). My impression is that sustainability has become more important during the period of the pandemic and the increased use of wood in building is one long term trend resulting from this. Technologies such as glue-laminated timber and acetlyated timber are also coming of age, making more engineered timber products possible. When the COVID fog disappears, I am hoping that it will become apparent that the growth prospects of James Latham are also more sustainable as a result of these trends as it was always a good company, but in the past has been a bit of a slow grower.
Speaking of acetylated timber, if this floats your boat, you might want to check out Accsys Technologies (LON:AXS)
I don't hold because I think the valuation is nuts and I don't know enough about the product, and I don't trust management to execute well (see how many delays they've had in construction of their plants over the years....)
Paul, how can you say something looks cheap, in this case BMS, by looking at a single metric such as EPS?
Paul, how can you say something looks cheap, in this case BMS, by looking at a single metric such as EPS?
As the article explained, I just had a quick look at the StockReport, and thought there was enough of interest there to make it possibly worth a closer look. But yes, I agree with you that I wouldn't make a low PER the single decision-making factor!
This was my full conclusion, which is a bit more nuanced than your version!
My opinion - I’ve not properly looked at this share for a while. It could be worthy of further research, because the valuation looks cheap, and of course shipping is a very lucrative sector at the moment, due to sky high freight rates from the Far East. Hence it seems logical to expect BMS to be grabbing a slice of the action in its sector.
Today’s non-specific, but positive-sounding update, probably makes it more likely that the company would meet/beat profit expectations.
Overall then, this one looks quite interesting.
Hi Paul, would appreciate your views on the trading update from James Latham (LON:LTHM) yesterday.
They’ve achieved the same PBT in the first 4 months of the current FY as they did for their last full financial year (and previous years too!).
Thanks
Hi Discodave4,
Thanks for flagging up James Latham (LON:LTHM) from yesterday, it looks a very interesting update.
I'll write up a section of it, hopefully up by 15:30 today.
Regards, Paul.
Thanks Paul for your analysis of £LTHM.
Agree it’s potentially a “bumper” start to the year, 75p eps is already in the bank so do think it’s worth more than a 20% uplift, but time will tell I guess.
Thanks again and all the best.
Any opinion/thoughts on the update from Eurasia Mining today? (LON: EUA):
26 August 2021
Eurasia Mining Plc
Nyud Progress Update
Eurasia Mining Plc ("Eurasia" or the "Company"), the palladium, platinum, rhodium, iridium and gold producing company, is pleased to announce progress update on the Nyud project.
As announced via RNS of 26 March 2021, Eurasia signed a binding agreement to create a joint venture with Rosgeo in which Eurasia will own a 75% equity stake in nine PGM and battery metals assets (four of which are post Russian Feasibility Study with state approved reserves) with a total of 104.6Moz of Platinum equivalent Russian Code reserves and resources in the immediate vicinity of the Company's Monchetundra Project in the Kola Peninsula.
As further announced on 15 June 2021, Monchegorskoe LLC was created to hold the licence for the Nyud open pit PGM and battery metals deposit ("Nyud"). Eurasia's 100% subsidiary Yuksporskaya Mining Company / Yuksporskaya Gornaya Kompaniya ("YGK") has signed a notarised agreement with Rosgeo group company pursuant to which YGK will become a 75% shareholder in Monchegorskoe LLC after the licence for Nyud is transferred from Rosgeo to Monchegorskoe LLC. Pursuant to the terms of this agreement Eurasia, through YGK, will also have a right to acquire Rosego's 25% shareholding in Monchegorskoe LLC upon the completion of a JORC Code compliant competent persons report ("CPR") on Nyud.
Additional drilling has recently been completed on Nyud at Rosgeo's cost and Eurasia has engaged Wardell Armstrong International in relation to Nyud to among other things:
Christian Schaffalitzky, Executive Chairman of Eurasia commented: " The Directors are delighted to see tangible progress on our JV with Rosgeo that is an integral part of our development strategy and a part of some of our strategic options that we are developing with our advisers: UBS and DLA Piper".
James Nieuwenhuys, CEO and Managing Director of Eurasia commented: " The Board is driving the concurrent development of both our Kola and our Urals assets, and we are looking forward to providing further updates in due course".
The acquisition by Volex (LON:VLX) does appear to be good value.
The market values Volex at circa 20 X EBITDA and they have acquired this business for just 4-5 X EBITDA from what Paul said above. This is value enhancing immediately.
UPDATE
I have just looked at another article which said Irvine made a pretax profit of $9.6m. This would make it astonishingly cheap. It needs to be approved in the US and is likely to complete in Q3 2022. How have they made this acquisition for less that 2 X net profit? Am I missing something?
https://www.marketwatch.com/st...
Your missing that Irvine has had a one off COVID windfall that won’t repeat. It’s explained in the RNS
Thank you. That explains it.
The Stocko Report shows EBITDA at £32m and a EV of 19.47 X EBITDA
Add on £2.9m of EBITDA ($4m) and you get to £35m of EBITDA
That gives an EV of £681m which is 10% above the current.
Eenergy (LON:EAAS) announces a contract win.
I really like the potential of this business.
The executive team they have put in place have lots of acquisition experience at a very high level. I think this could have enormous potentail.
Good Morning Paul
Is Macfarlane (LON:MACF) on your radar this morning?
Yes, sorry I got distracted but am looking at Macfarlane (LON:MACF) now. Section should be up by 1pm email deadline.
Thanks for the comprehensive write up on £MACF and I am happy to say I came to the same conclusion - continue to hold.
(Certainly no need to apologise - I'm still wondering how you manage to cram in as much as you do on a daily basis!)
Possible contender for the most vacuous Trading Update of the year award from Braemar Shipping Services (LON:BMS) this morning:-
« 'The board is pleased with the financial and operating performance of the Group for the first five months of the year. Trading has been good across all three of the Group's divisions and the breadth of the Group's business model, the diversity of the broking operation and the markets in which the Group now operates, have insulated the business well from any ongoing pandemic weakness. The board is united in seeking to develop further the Group's growth strategy and we look forward to the remainder of the financial year with confidence.' »
That’s it, in its entirety. Not a number in sight ….
Nice looking earnings enhancing acquisition by Volex (LON:VLX) in the US though:-
https://www.investegate.co.uk/...
Gus.
In my book Braemar Shipping Services (LON:BMS) has a long way to go before the Board earns my confidence. I hold.
Silver
Agreed on Braemar Shipping Services (LON:BMS)
Poor management and mediocre performance during the sluggish last few years. They just got lucky as the current shipping boom is lifting everyone in the sector.
Worth catching up on their news in the last 12 months. A new Chair and CEO are in place and there has been quite a significant shift in the Co's strategy & debt as a result. Worth reviewing imo.
I wonder if it is still a Lord Lee holding? He doesn't suffer fools gladly.
List of Lord Lee’s holdings.
https://members.parliament.uk/...
Doesn’t appear to include Braemar Shipping Services (LON:BMS) but some other names often seen in the SCVR.
Gus.
I'm surprised Lord Lee invests in palm oil.
Maybe it was the « MP » bit in the name of M P Evans (LON:MPE) ? Thought he’d get members’ privileges as a shareholder for being a Lord.
Gus.
“ I'm surprised Lord Lee invests in palm oil.”
Why is that Herbie? Is it because of environmental impact? We all need to be careful about that of course. So, perhaps he views it as encouraging the guys who are doing it in a sustainable way. M P Evans (LON:MPE) certainly appear to be committed to sustainable production. None of their production comes from land that has been deforested in the last 16 years or so from what I can see.
So, they are offering palm oil customers an alternative that’s going in the right direction. So, it removes the excuse from the customers who say they cannot find a suitable alternative to palm oil for their product. If they really cannot reformulate their product not to use palm oil then at least they can buy a more sustainable version of it. And the alternatives to palm oil tend to all have problems too.
Greenwash? Perhaps. I’m sure that some of the companies producing sustainable palm oil are possibly doing nothing of the sort and still causing deforestation. But Evans doesn’t appear to be one of those.
However, I’m leaping to conclusions that I’ve guessed the reason for your surprise correctly!
The price of palm oil is up 73% yoy, averaging $1,122/mt for the first six months to 30 June 2021, compared to same period in 2020 of $648/mt.
This looks to be behind today's stonking H1 results out from Anglo-eastern Plantations (LON:AEP) which reported H1 revenue of £200m compared to total 2019 revenue (ignore COVID year) of £219m.
Could be worth a punt on M P Evans (LON:MPE) with the expectation that their H1 results in two weeks show a similar jump.
Commodities getting hotter.
Looking into that, in their June trading update (below) it mentions an Indonesian export levy, so the price increase is a more modest 30%, still appreciable.
The average price of CPO (cif Rotterdam) for the first five months of the year was US$1,127 per tonne, substantially higher than the US$659 per tonne during the equivalent period in 2020. However, the introduction of an Indonesian export levy in December 2020 meant that this increase was only reflected to a limited extent in the price actually received by the Group at mill gate. Nonetheless, in the period to the end of May 2021, the Group realised an average price at mill gate of US$715 per tonne compared with US$550 per tonne in 2020, an increase of 30%. Prices for palm kernels have also strengthened, averaging US$487 per tonne (mill gate), 57% higher than the US$310 per tonne in 2020.
Re M P Evans (LON:MPE) , the group in June reported that the Indonesian government had capped their upside to rising Palm Oil prices:
"The average price of CPO (cif Rotterdam) for the first five months of the year was US$1,127 per tonne, substantially higher than the US$659 per tonne during the equivalent period in 2020. However, the introduction of an Indonesian export levy in December 2020 meant that this increase was only reflected to a limited extent in the price actually received by the Group at mill gate."
My understanding is that palm is the most productive oil in terms of tonnes per hectare. So if it were banned tomorrow far more land would need to be cultivated than is currently utilised. The bad press partly comes from the fact that overall oil usage is growing and palm oil is increasing market share.
I’m no strident environmentalist but having flown across the island of Borneo the scale of deforestation is truly shocking. From the air you can grasp the horror of what is happening to one of the most important tropical rainforests on the planet.
The problem relates to the type of land which is used for palm oil plantations. One of the very worst culprits in the destruction of rainforests.
Hello Herbie and other subsequent contributors commenting on M P Evans (LON:MPE) related to palm oil.
The ever increasing production of palm oil has been responsible for the deforestation of huge swathes of rain forest over a period of far far longer than 16 years so M P Evans (LON:MPE) cant easily cop out on that one,......and where did a figure as precise as 16 years come from?
If we are to take climate change seriously, then massive reforestation in such areas, plus off-the scale forestation / reforestation elsewhere on the planet has to be on the cards, and now.
I remember a recent example where Iceland replaced palm oil in all their products by a sustainable alternative but I must confess I don't know what that was. From the comments from others here, it seems that demand for palm oil is growing fast, and Iceland was clearly one small example with a positive approach.
We have to stop saying why we cannot do this and do that, and playing around the edges. On the other hand we can continue to say that our human society will find a last minute solution, as if it were as simple as a C19 vaccine !
This is not a criticism of contributors which is not appropriate for this site, just a statement of facts........ and personal opinions of course.
All the best to all the great contributors here which I read on a daily basis, and from time to time contribute to on a share by share basis as well as on general subjects of the day.
The other thing to point out is that many of the companies behind industrial scale palm oil farming are based in tax havens such as the Cayman Islands with licenses approved by high ranking Indonesian officials. Ordinary Indonesians see little of the wealth created.
I stopped knowingly buying anything with palm oil in about three years ago whilst shopping in Tesco with my daughter around the time of the orangutan advert from Iceland to see if we could do it. It meant reading the ingredients of more things than I care to remember but you quickly realise that it pretty much meant all processed food went out of the window apart from a 'bounty bar'! It does seem however that the tide is changing slightly and food producers are starting to move away from palm oil - baby steps now but there are a few more products becoming available by switching to rape/sunflower or coconut. Shampoo containing the surfactant sodium lauryl sulfate is usually palm oil (which is 95%). It's bloody everywhere but you can now quite easily get 'SLS' free shampoo too. Horrible bloody stuff and sustainable palm oil is a myth.
Do you hold many other shares where you do not have confidence in the board?
Spectacular H1 results from Macfarlane (LON:MACF) this morning. Revenue, PTP and dividend well ahead of my expectations which were already well ahead of broker expectations. I anticipate significant upgrades to this year's and next year's forecasts and believe that this share is still materially undervalued.
https://www.investegate.co.uk/...
Macfarlane (LON:MACF) yes excellent results - many highlights - no pension deficit now for example alongside all of the very positive numbers
The only suspicious element is the limited increase in cash balance - some is explained by the growth story (increased payables for materials, and increase in outstanding invoices. Also increases in overheads such as leases) but it seems less than we'd have expected given the very strong operating profit
I hold so hoping for an uplift in share price today
Macfarlane (LON:MACF) - (I hold)
' limited increase in cash balance'
Just started looking at the cashflow statement - I think the difference is mainly explained by the £12.2m in acqusitions in H1 versus the drawdown of loan facility £8.8m and increased dividends.
cheers
Mark
Macfarlane (LON:MACF) You are absolutely right - I somehow missed that earlier - so everything looks excellent and we are up c14% today which is nice
Nick,
Your post is thoroughly misleading. The £12.2m cash outflow on acquisitions explains the limited increase in cash.
Got to be looking at £1.50 in the near term, Shirley. Pension deficit is now a surplus, net debt pretty much all dealt with to the point the debt they have was used to fund the last acquisition and should get paid back fairly quickly. Lots to like here. I suspect a lot of people need to reappraise their thoughts on this company as it has been transformed over the last three or four years.
Shirley? Who he?
Leslie Nielsen, I'll get me coat
I'll be looking at the interim results from Macfarlane (LON:MACF) (I hold) next.
The figures do indeed look very good. Also, as I've mentioned here before, MACF does not present adjusted figures, unlike most other companies. So when you strip out its goodwill-related amortisation, then its comparable earnings would be a good bit higher. Hence it's actually quite cheap, which might not be immediately obvious from the reported numbers.
On Macfarlane (LON:MACF) (I hold), it's interesting to note that they have reported 'operating profit before amortisation and impairment', which they didn't last time. Just need the next step to 'underlying eps'.
Taylor Maritime Investments (LON:TMIP) in same sector as bms its a new listing it looks interesting
There was an article by David Stevenson under his Adventurous Investor emails a short while back on shipping and the various options and what the thought
http://www.adventurousinvestor...