Small Cap Value Report (Thu 26 May 2022) - PURP, BOOT, MORE, SUS, ADF, RAI, NWOR

Good morning, Paul & Jack here.
Agenda -
Paul's Section:
Purplebricks (LON:PURP) (I hold) - from yesterday. A gloomy trading update. Market cap isn't much above the company's own net cash, but it's loss-making, and instructions are down. Looks like some cost-cutting is necessary. Not really a regular investment, so this is only of interest as a special situation (possible takeover target?)
Hostmore (LON:MORE) (I hold) - a very predictable profit warning, which I've been expecting. It's not as bad as I feared, and the roll-out of new sites (on attractive rents) continues. Medium to long-term, I think this share should do very well. In the meantime, profits are down, but not horrendously by any means. Although sceptics point out that competitor RTN has recently issued a much more positive update - a fair point.
Facilities by ADF (LON:ADF) (I hold) - strong results for FY 12/2021. It floated at 50p in Jan 2022, and is currently 36% up on IPO price - remarkable in a bear market. I like this company a lot on fundamentals. It's in a lucrative niche, and raised £13m net at IPO to expand its fleet of TV/film production vehicles - a booming sector in the UK. Looks attractively priced too. Thumbs up from me.
National World (LON:NWOR) - I've previously liked the figures at this small newspaper group. Today's update is reassuring, in line with expectations. Valuation looks about right on a PER basis, but that ignores a substantial cash pile. Hence it's cheaper on an EV/EBITDA basis. Overall, I can't get excited about this share at the moment.
Jack's Section:
Henry Boot (LON:BOOT) - solid trading so far this year and the outlook is buoyant. Henry Boot is a good operator that has been around for a long time, and there is value in that kind of track record. But the shares have held up well amid a wider cyclical sell off, so I wonder if at some point we might be presented with a better entry point.
S&U (LON:SUS) - I hold - performance is ahead of budget here and, while issues such as the cost of living, low consumer confidence, and inflation could have an impact, the group is investing for sustainable profitable growth. The forecast PE ratio is less than 9x and the forecast yield is approaching 6%, so I think there’s good value here given the track record, management, and profitability.
Ra International (LON:RAI) - a big loss before tax as the group reports $31.5m of non-underlying charges related to its Mozambique project. The company helps deliver humanitarian projects in areas of need, so I wish the group well, but I think there is significant operational risk here as part of the business model.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Purplebricks (LON:PURP) (I hold)
17.8p (down 3% at 12:34)
Market cap £55m
This online estate agent is a special situation these days. The price is bombed out, and the cash pile is of key significance, supporting most of the valuation.
Although widely publicised legal cases, on employment status of staff, and a potentially expensive administrative problem re tenant deposits, are open sores, and likely to burn some of the cash to resolve.
Trading has been poor for a while, and the hopes for recovery on a change in pricing policy doesn’t seem to have worked. So is it a great business? Absolutely not, no arguments there! Although with such big brand recognition, and a still hefty cash pile, there could be value here. That’s why I picked up a tiny position a while ago, just as a cash-backed punt.
This is the latest -
Purplebricks Group plc, the leading UK tech-led estate agency business, today announces a trading update for the 12 months ended 30 April 2022, a year of significant transformation for the business.
Not much to celebrate here -
Since the announcement of our interim results in January, we have seen a continuation of lower volumes of new instructions coming to market1.
These market conditions have impacted the level of net2 instructions which for the full year ended 30 April 2022 were 40,141 (FY21: 58,043).
As a result, our revenue is expected to be approximately £70.0 million for the full year and Adjusted EBITDA3 is expected to be approximately £(8.8) million.
Our cash balance at 30 April 2022 was £43.2 million, reflecting the lower instruction volumes and exceptional costs in line with guidance.
Still plenty of cash left, and at least the exceptional costs are in line with guidance.
With demand reducing, cash also falls, as customers pay up-front, plus operational cash burn.
Clearly the business needs to cut costs, as running up heavy losses isn’t sustainable.
My opinion - it looks pretty bad. There’s still plenty of cash though, at £43m, versus £55m market cap. That’s the only reason that I’m holding a small position, and the high level of brand recognition from years of heavy advertising.
Maybe a private equity bidder might take a look?
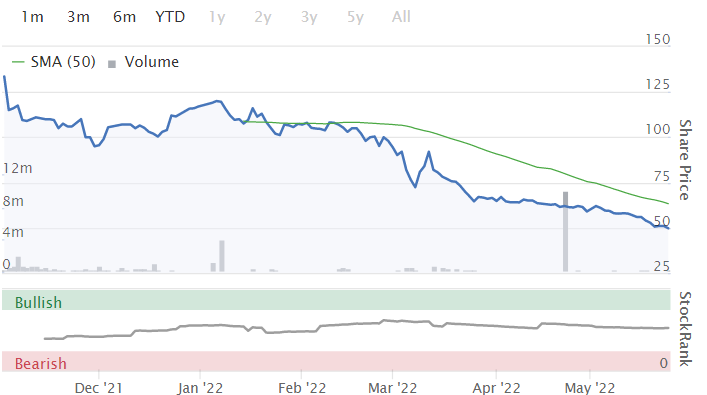
Note that the share count has remained at c.307m since about 2019 (the period of the 3 year chart below), which in theory leaves scope for a share price recovery. Although, as the comments section from yesterday showed, there's a lot of competition). Although with venture capital/ private equity funding possibly drying up, then I wonder if weaker competition might fizzle out, leaving cash-rich PURP in a last man standing situation? Who knows?!

.
Hostmore (LON:MORE)
50p (yesterday’s close)
Market cap £63m
I’ve been waiting for a profit warning here, due to all the news about people cutting back on discretionary spending. The relentless fall in share price has also been indicating that the market expects a profit warning. In fact it’s blindingly obvious, in current conditions.
Although competitor Restaurant (LON:RTN) recently surprised with an in line update, which did absolutely nothing for the share price (in the short term anyway). There’s clearly a buyers strike, as my broker is telling me.
The problem, and opportunity with hospitality businesses, is that they’re highly operationally geared (gross margins typically 70-80%). So when that works in reverse, then it can be brutal to profitability, but great on the upside, when sales are growing strongly in an economic recovery.
Obviously right now, with so much bad macro news building, then markets anticipate a plunge in profits in the shorter term.
PR headlines -
Trading update for the 20 weeks ended 22 May 2022 and revised guidance for FY22
A challenging consumer environment but well positioned with a strong and resilient balance sheet
I don’t like being told that companies think they have a strong balance sheet, as it’s often not true! So I've double-checked the FY 12/2021 balance sheet. It's adequate I would say, and dominated by intangibles and IFRS 16 lease figures. Stripping all those out, I get to adj NTAV of only £6.4m. Not much. There again, it has plenty of cash, almost offsetting the bank debt, so that looks fine. Overall then, I think the company's description of "strong and resilient balance sheet" is over-egging things! Although it's tons better than the heavily indebted Restaurant (LON:RTN) which has a worryingly weak balance sheet. So in comparison, MORE is the much stronger financed business vs RTN.
Revised guidance today sounds like a profit warning.
Remember this is not just TGI Fridays (in the UK), but also a new roll-out of 63rd+1st cocktail bars -
Hostmore plc (the "Company" and, together with its subsidiaries, being the "Group"), the hospitality business focused on American-themed casual dining brand, 'Fridays', the cocktail-led bar and restaurant brand, '63rd+1st', and the fast casual dining brand 'Fridays and Go' announces an update on trading for the 20 weeks ended 22 May 2022.
Revenue, on a like-for-like (LFL) basis is down c.6% on 2019 pre-pandemic.
It says dine-in revenue are in line with industry data.
“Limiting impact” on margins (due to price rises, and hedged utilities)
New sites - 2 “successful” openings done, and 3 more planned for FY 12/2022 - the Dundee site is key, as it’s a test site for a fast food takeaway concept branded as TGIs, with potential for a large number of smaller sites, if it works -
The new store openings in Dundee (Fridays & Go) in March and Chelmsford (Fridays) in May have both since traded ahead of expectations…
Subject to an improved trading environment our ambition is to almost double the number of site locations from the current 89 over the medium term. This growth will be self-funded and achieved through a combination of our core Fridays portfolio, further roll-out of 63rd+1st and, in particular, the development of the recently launched town centre concept Fridays and Go which allows low capital brand penetration into previously inaccessible but attractive geographies.
Growth - this is interesting, and I don’t think the stock market has priced-in the roll-out of new sites, which in more usual market/economic conditions would attract a premium PER. Also, there are many sites available on very attractive terms from landlords, hence this is an ideal time to be expanding, with so much competition biting the dust. An opportunity for a re-rating of the shares, in due course, I reckon. But obviously sentiment is currently very negative. We need to get ahead of the curve, that’s where the opportunities lie in the future, but clearly in the short term things remain tough.
Continued cash flow generation, balance sheet strength and liquidity headroom provides a base to almost double the estate in the medium term.
Inflation - costs are under control, which has been mentioned before, so nothing new here, but it does reassure -
Furthermore, early hedging of gas and electricity costs, both volume and pricing, and success in limiting food and beverage costs increases, has limited the impact on margins…
Food and beverage input cost inflation impacting the sector is currently approximately 10%. We have partially mitigated the impact of this cost inflation by fixed utility and supply contracts
Bear in mind that high gross margins means that higher food/drink input costs don’t make that much difference. For example, if your gross margin is 75%, then cost of sales is 25% (the raw materials, not including wages or overheads). Therefore a 10% rise in raw materials, would only reduce the gross margin to 72.5%. By my calculations, that would need only a 3.4% increase in selling prices to customers, to fully recoup the 10% higher cost of materials. There's also increased wages to consider of course.
Outlook - all important right now - this sounds sensible, guiding down expectations -
The challenging consumer environment means that we are taking a more prudent view on trading for the remainder of year, including the assumption that LFL dine-in volumes, as compared to FY19, may reduce by 8% for the rest of FY22.
Note it says volumes. With selective price rises, that could mean actual revenue might not fall as much as 8%. Indeed, next they confirm this, saying -
… appropriate pricing adjustments, in line with broader sector announcements, to mitigate approximately half of the impact of the lower volumes now anticipated.
Profit guidance - or rather I should say EBITDA guidance -
… the combination of cost increases and lower volume will result in an EBITDA margin (pre-IFRS) in low double digits (%) for the current year compared with our medium-term targeted level of mid-teens, which is retained.
To me, that’s actually fine, and I was expecting much worse. Note this is pre-IFRS 16, so it’s a realistic number, not the inflated EBITDA figure after IFRS 16.
Liquidity - I’m not keen on companies taking on debt right now, for obvious reasons. What if the consumer squeeze gets a lot worse, and sales plunge in a recession?
The Group is highly cash generative and maintains a strong and resilient balance sheet with significant liquidity headroom, providing the flexibility for disciplined expansion. This will be focused around our organic growth and new store openings from our existing stable of brands.
We now expect to be at the mid-point of our previously communicated target net debt to EBITDA range of between 0.75x and 1.5x EBITDA (pre-IFRS) at the end of FY22, taking into account the investment in new store openings.
My opinion - could easily be influenced with subconscious bias, because I hold this share personally, so do take that into account (that’s why we disclose if we hold shares personally).
However, for me this update is glass half full. I was half-expecting a disastrous update, due to consumers apparently drawing in their horns. However, I walk past my local TGIs several times per week, and it looks the same as normal, always doing steady, or busy trade in the evenings, because it's below a big Odeon cinema. Obviously it’s dangerous basing investments on just one site, because it may be atypical. Also many retail/hospitality businesses have a small number of super sites, which generate a high proportion of the profits. I seem to recall from the IPO slides that this is indeed the case with Hostmore. Most sites trade OK, but they’ve got some amazing top performers which generate multiples of the profit of regular sites. Also, hardly any loss-making sites, which is another key plus.
Overall, I’m pleased to see guidance for this year moved down to more sensible levels, and it’s a given that when some consumers struggle with disposable income, they’ll cut back on eating out. Or will they? Some data seems to be suggesting they’re cutting back on buying things like furniture, to prioritise spending on leisure experiences, like holidays & eating out, after several years of pandemic restrictions making such experiences that much more enjoyable. Another key point I'm hearing from sector newsletters, is that consumers are still happy to spend on hospitality, but value for money is key. I'm not convinced that TGIs offers value for money - the product seems expensive for what it is, in my personal opinion, so I rarely visit now. Although I think TGIs is more of a special occasion destination, as you often see families, and birthday parties in my local site. Plus, remember that many middle class households are achieving big pay rises, and so won't be feeling the pinch much, if at all. This bout of inflation is hurting mainly the poor, who spend so much % more on energy & food, the big contributors to inflation right now.
Ultimately it’s all about valuation, and at c.44p (down 11% today, which isn't bad at all on a profit warning) currently, I reckon MORE is an absolute steal, taking a long-term view. It’s a good business, and today’s update reinforces to me that management seem on top of the issues. It seems clear to me that the share price is almost certainly now nearer to the bottom than the top. Hence potential big future upside, if you can stomach current market conditions. I've been through a few bear markets, and it's bold buying decisions when sentiment is clapped out, and valuations on the floor, that are the big profits of the next few years.
Hence with patience, I reckon this share could double or triple from the current level, once consumer demand has returned to normal. It's a self-funding roll-out, which would usually excite investors in normal market conditions.
There again, I’ve been saying this share is cheap all the way down from 125p, so it may be best to ignore me, or do the opposite to what I do! That said, we just look at the fundamentals here, and it’s up to you to decide what price is attractive to you personally. Your money, your choice, as always. It might be too early to buy, I don't know where it will bottom out, as I can't predict the future. So traders might want to hang back, until it's formed a base, possibly?
.
.
Facilities by ADF (LON:ADF) (I hold)
68p (down c.2% at 09:26)
Market cap £51m
This is an interesting little company, hiring out TV production vehicles for outside broadcasting. Completely by accident, on a slow news day, I spotted ADF on the day it listed at 50p, reviewing it here on 5 Jan 2022, which is a good starting point for your research, even if I say so myself!
The 50p listing price looked a bargain, something that I rarely (if ever) say about new listings - which are more usually rubbish companies, or overpriced companies, and often both!
The main risk looks to be very high client concentration (IPO document said top 2 were 65% of revenues in covid-impacted FY 12/2020, with one being Netflix - so a risk of them retrenching maybe?). We might have seen peak streaming, who knows?
EDIT: I've done some more digging on client concentration, and am reliably informed that the top 2 clients are historically 35-40% of total revenues. So the spike up to 65% was a one-off in covid-impacted FY 12/2020. Netflix is still an important client, but growth from other streamers is reducing its % of ADF's total revenues). End of edit.
On to today’s news.
Final Results - for FY 12/2021 - it’s very late to be reporting 2021 figures at the end of May 2022! 5 months to produce results is ridiculous, especially for small caps, where the figures should be quite easy to produce. They’re not even audited yet!
Although to be fair, there was a trading update on 11 Feb 2022 which gave guidance -
The Board is pleased to confirm that following a strong close to 2021, and subject to audit, it currently expects the Group to report FY21 revenues of c.£27.8 million and adjusted EBITDA* of not less than c.£7.5 million, ahead of current market expectations.
Actual adj EBITDA figures today are £0.2m ahead of guidance, and as you can see below, 2021 was a fabulous year, with a very strong rebound from covid-impacted 2020, and way ahead of pre-covid 2019 -

.
Strong pipeline of films and TV shows “for the coming year” - does that mean calendar 2022, or a year from now? Not clear.
Outlook - this all sounds great, so I’m not sure why the share price has dipped today -

.At IPO, we were also able to demonstrate a substantially sold-out 2022 order book and a significant order book for 2023. This continues to progress and means our new trailers, which increase our capacity, can be booked out in advance. Around 100 additional vehicles will become part of the ADF fleet in 2022, bringing the total number of vehicles to 600, with similar volumes ordered for 2023.
…We have made significant progress in our first six months as a listed business which reflects the hard work and dedication of our staff across the Group. With an excellent customer base and a supportive market backdrop, I am confident this positive momentum will persist as we continue to deliver our growth strategy in the year ahead.
Visibility - this is a key strength of this business & sector -
Production companies are unlikely to change provider once they know the facilities and service levels meet their requirements, given the bespoke set of requirements for each production. The length of planning time has increased in recent years due to the rise in both demand for content and scale of productions. As a result, ADF is receiving some enquiries between 12 and 18 months before a production is filmed, with the average lead time of seven months, and its orderbook is mostly filled for 2022. This level of revenue visibility is rare in any business and allows the Group to accurately plan.
Industry expansion - the commentary contains a lot of very interesting stuff about how UK TV/film production is expanding, helped by large US corporations setting up facilities in the UK, e.g. -
… Major US streaming companies have now set up permanent bases in the UK, with the UK now being Netflix's third largest operation after the USA and Canada. Throughout the year there has also been unprecedented levels of investment in UK studio space and content, which bodes extremely well for our growth ambitions.
That doesn’t sound like a flash in pan to me.
Balance sheet - is pre-IPO, so doesn’t take into account the £13m (net of fees) raised in the IPO. So NTAV reported at £5.4m, should rise to £18.4m, plus retained profits generated since 31 Dec 2022. Therefore the current balance sheet as of today should look really strong, c.£20m I reckon.
Dilution - note that potential dilution looks unusually high, with share options potentially expanding the share count by c.6.5m shares -

.
The current share count (post IPO new shares issued) is 75.5m, so 6.5m options would be 8.6%, which is just within the generally accepted reasonable maximum of 10% dilution.
Valuation - many thanks to analyst Andrew Renton at Cenkos for making available an update note today on Research Tree, it's a massive help to me, and private investors generally. After all, if we can access decent research, then we're more likely to buy/hold the shares, something which some other brokers still don't seem to understand.
Forecast adj EPS is 4.6p (PER 14.8) for FY 12/2022.
Forecast adj EPS is 5.9p (PER 11.5) for FY 12/2023.
The increased revenues & profit look credible, as the substantial extra cash raised at IPO is enabling ADF to order a lot more new vehicles, and with strong demand, those new assets should be generating increasing revenues, at good margins, from day one.
My opinion - this looks excellent to me, ADF has clearly found a lucrative niche, in which it is the UK market leader. Operating in a sector that is experiencing strong growth & demand.
Valuation looks reasonable, hence I’m sitting tight on my ADF shares. With a bit of patience, I could see this share being at least 50% higher, once more normal stock market conditions return. That’s based on the forward PER being only 11.5 for FY 12/2023, whereas I’d say a PER of 15-20 would be more appropriate.
I wonder if demand might soften, as streaming giants feel the pinch? That’s probably the main risk. Also, competitors might see the margins being made, and also expand their fleets too?
Although positive outlook comments, and forward visibility of bookings being so good, there don’t seem any clouds on the horizon so far.
Nice balance sheet too, post IPO, so there’s a lot to like here.
Previously ADF has talked about expanding into Europe, via acquisitions. In a way, I would prefer them to stick to a lucrative niche in the UK, and not get distracted with overseas expansion. But that depends on management bandwidth, skills, and experience. Have they done acquisitions before? If not, then maybe best to stick to the UK, and organic growth?
.

.
National World (LON:NWOR)
22p (up 11% at 12:19)
Market cap £45m
National World plc issues the following trading update for the 21 week period to 28 May 2022 ("the period") ahead of its Annual General meeting on 26 May 2022.
This is a newspaper group, being mainly the assets from failed Johnston Press, later refloated without the baggage of debt or pension schemes, as NWOR.
I know a lot of readers like this value share, and I’ve previously reviewed it positively a couple of times here too.
Today it says -
We have had a robust start to 2022. Despite a more uncertain trading environment…
Pursuing acquisition opportunities.
Revenues YTD (year to date) up 4%, split +5% in Q1, falling to +1% in April & May - that doesn’t look right to me, so I tested it assuming equal weighting in each month, and I come out at +2.8% YTD. So there must be monthly differences to arrive at +4%.
Digital - much stronger growth, at +38% YTD (slower at +28% in April & May) - with stronger yields, and c.100% growth in video advertising. Sounds good, but with no numbers, I can’t assess the significance of this.
War in Ukraine has created volatility in audience numbers - eh? Why would that be?!
Print revenue (selling newspapers) down 2% - split +3% ad revenue, and -7% fall in circulation revenues.
Online-only newspapers are expanding into new regions, under Metro World brand.
Inflation - newspapers have been battling to reduce costs for many years now, as revenues fall. Today it says “careful cost management continues”, and “helps mitigate” increased cost of newsprint.
Cash of £25m at end May, very sizeable for a £45m market cap company. There is £1m of loan notes, and £2.5m deferred consideration to come off that, so still very healthy.
Outlook - sounds fine, being in line -
The trading environment is challenging with market expectations of a significant slowdown in the UK economy impacting consumer confidence, driven by rising inflation and interest rates. However, the Board remains confident that investment in and development of our digital business together with careful management of the cost base will support profits and cash flow. At this stage, the Board expects performance for the year to be in line with the Company's expectations
Valuation - many thanks to Dowgate for providing an update note today.
Unchanged forecasts are Adj EPS of 2.3p this year, rising to 2.4p next year.
At 22p per share, the PER is 9.6, falling to 9.2 - why would I want to pay more for a declining newspaper business? Answer - because about half the market cap is cash, and there could be growth potential in the digital business (shares in larger competitor Reach (LON:RCH) [I hold] went on a mad tear last year, when investors got over-excited about the digital side of the business, which subsequently unwound).
Hence the EV/EBITDA numbers look a lot more attractive, at about 4 times this year, dropping to 3 times in 2023.
Balance sheet - Is the cash real, surplus cash? Checking the 1 Jan 2022 balance sheet, I’d say mostly, yes. Current assets (including £23.0m cash) were £36.0m, and current liabilities were only £18.7m, giving a net current asset (ie. working capital position) of £17.3m - very healthy.
A strange feature is that inventories were only £0.1m. Is that because production is outsourced perhaps, I’m not sure, but that seems likely. Can any shareholders confirm this in the comments below please, if you know.
Overall then, it’s probably got up to about £15-20m available for acquisitions, which could be interesting, providing they don’t do a bad deal. Management is experienced though, so hopefully would not screw up.
My opinion - I can see some value here, but it hinges mostly on what they do with the cash pile. A good acquisition could add value. On a PER basis though, it’s not a particular bargain, probably priced about right.
Remember that this business is probably now up against headwinds on advertising revenue, as well as structurally declining circulation revenues.
I could do with more information about the digital side of the business.
Very recently, I have dipped my toe in the water with a small opening position in Reach (LON:RCH) which has a PER of only 3.6, and a divi yield of 6.4%. There is the huge pension fund to worry about, which NWOR doesn’t have of course. Higher bond yields do seem to be reducing pension deficits though, so maybe it’s less of a worry than previously at RCH?
I’m not massively drawn to either RCH or NWOR though.
There's not been much interest in NWOR since it floated. Why would that change, especially in this current bear market?

Jack's section
Henry Boot (LON:BOOT)
Share price: 327p (+1.24%)
Shares in issue: 133,384,574
Market cap: £436.2m
Henry Boot was established over 135 years ago and deals in property development, land promotion, and construction. It is based in Sheffield.
The group is trading in line with expectations after a ‘strong’ start to the year, with robust demand across its three key markets (Industrial & Logistics, Residential and Urban Development). As with most companies right now, the main challenges are supply constraints, cost inflation, and increasing economic uncertainty.
But Henry Boot has a good financial position and it says forward sales across all business lines are also strong (a word it uses multiple times in today’s announcement).
To date, the Group's performance has been supported by land disposals and property development completions, with all three key markets, Industrial & Logistics (I & L), Residential and Urban Development performing well. In addition, the Group continues to make good strategic progress towards the medium-term targets previously identified, leaving the business well placed to achieve its growth aspirations.
Hallam Land Management (HLM) has sold 3,477 plots, reflecting buoyant demand and competitive bidding for sites from housebuilders. The number of plots is stable at 92,569 plots (2021: 92,667). HBD remains on budget and on time and is currently 73% pre-let or pre-sold with continued high demand from industrial occupiers. Stonebridge Homes (SH) has now secured 93% of its 2022 delivery target of 200 units. The housing market continues to experience high demand, which has resulted in sales values offsetting cost inflation.
Both Banner Plant and Road Link (A69) are now trading ahead of budget.
Outlook
Boot notes ongoing buoyant demand that is allowing it to preserve margins against build cost inflation and supply constraints by passing through sales price increases.
There will be some first half weighting this year.
Due to a number of significant transactions, 2022 performance is expected to be weighted to the first half of the year and it is anticipated that whilst levels of activity will be high in the second half, this will primarily be contributing to the Group's performance for 2023 and beyond.
The group helpfully adds that market expectations are the average of current analyst consensus of £47.8m profit before tax. The share price has bucked the trend over the past year, outperforming by nearly 10% and retaining an 11.5x forecast rolling PER.

Operating margins of around 15% are better than a lot of competition and I think there’s a good company here an it’s reasonably valued, but there are a lot of outright cheap cyclical stocks around at the minute that might appeal more to contrarian investors on valuation grounds.
Solid results and the outlook seems encouraging. A safe pair of hands. But the macro concerns that have crushed some other stock prices are still there for this company, so I would be hoping for a single digit PE ratio - perhaps it won’t happen, but that seems to be the going rate right now for a lot of other cyclicals.
S&U (LON:SUS)
Share price: 2,350p (unchanged)
Shares in issue: 12,145,260
Market cap: £285.4m
I hold
This is a specialist motor finance and property bridging lender.
Profit before tax for the period was above budget for both Advantage Finance (motor division) and Aspen Bridging (property bridging division). Current net receivables stand at £340m, up year on year from £295m and are also above budget. Although there the well covered macro challenges, S&U is doing a good job of winning business.
… despite actual and anticipated pressure on household budgets due to cost of living and tax increases, credit quality remains very good.
Strong cash generation leads to current borrowings of £125m, well within medium term facilities of £180m.
Funding headroom for anticipated growth is fine - current borrowings stand at £125m against £180m of medium-term facilities, and group gearing stands at 59% against 60% on 19 May last year.
Advantage Finance - for the first time, Advantage's live collections have averaged over £13m per month in the quarter. Income, gross margin, cost control and profitability have all beaten budget.
The used-car market remains supply constrained and values are strong. Against this backdrop, Advantage has seen sales volumes growing steadily and current net receivables are now £268m (19 May 2021: £243m). Collection quality remains excellent at 93.7% of due. Payment arrears are below budget and falling, and progress has been made on the marketing strategy.
Nevertheless, prudence dictates that potential pressures on customer incomes are reflected in Advantage's historically conservative underwriting standards. Credit score cards are continually reviewed, and affordability buffers have been put in place to help ensure that new customers will continue to comfortably make the repayments.
Aspen Bridging - after a record FY22, this division continues to grow and current net receivables now stand at £72m against £64m as at 31 January 2022. Record fees and total income for the period.
Happily, reports of the demise of the residential property market in the UK are proving grossly exaggerated. Supply remains restricted, prices remain strong and, despite higher interest rates, re-financing remains readily available. In response to this and to service its record pipeline of new deals, Aspen has recruited additional staff who will prove themselves necessary in providing excellent customer service as the business grows.
Conclusion
With price inflation in the UK at around 9% per annum, consumer confidence at near 50 year lows, and geopolitical hostilities, the group says its progress ‘is inevitably marked by prudence and caution’. That’s fair, but it’s also fair to say the company is doing well regardless.
Demand for both housing and motor vehicles, and their resulting values, remains strong and with unemployment rates the lowest levels since 1975, rising prices, particularly for energy and interest rates, may persist. Hence, although we currently expect to meet growth targets for this year, S&U remains focused above all on maintaining the excellent quality of its own books and service to its customers. This will ensure a firm base for faster expansion when the macroeconomic skies brighten. That balance between quality and growth has always served S&U well.
I do think that both Advantage and Aspen could be affected by weaker consumer confidence and cost of living pressures. That’s a risk for many companies right now, and business is not always plain sailing. But S&U is a profitable, cheap stock focused on sustainable growth, one which pays out a near 6% in forecast dividends, so I’m quite happy to hold at these levels.

Ra International (LON:RAI)
Share price: 21.15p (-11.88%)
Shares in issue: 171,791,843
Market cap: £36.3m
Final results for the year to 31 December 2021
RA International provides remote site services to Humanitarian, Governmental and Commercial organisations globally. This is an interesting company on the face of it, but that doesn’t always equate to a good investment opportunity.
The group is clearly struggling to translate revenue into profit.

And it seems to be a very capital intensive business.

This quote from today, while good news insofar as it’s a business win, does back that up.
Maturity of the USD 10m MTN debt programme has recently been extended to 2024 and additional working capital facilities are available as required to support implementing material new project awards
It all translates into a rather bumpy ride so far for shareholders.

Results:
Revenue of $54.6m (2020: $64.4m) and underlying EBITDA of $6.7m (2020: $14.2m). Statutory loss before tax of $32.2m includes $31.5m in non-underlying charges relating to the Mozambique project, of which $5.9m relates to cash costs and $23.4m is a provision to impair the carrying value of assets.
We are pursuing opportunities to dispose of USD 7.2m of project related assets located in storage and remain confident that development works will restart in Mozambique, although timing is difficult to predict
Government and humanitarian clients represented 95% of 2021 revenue (2020: 92%), with government an increasing proportion of the mix (47% of 2021 revenue). These are stable, high-value clients that support our strategy to diversify geographically through customer-led growth.
Reflecting the Board's cautious view on the operating environment in the near-term, the Board is not recommending a dividend for the FY21 financial year
So that 7% dividend yield on the StockReport can be ignored.
Conclusion
Given the capex and geographies at play here, I’m not comfortable with the stock. It provides much needed services though, and I can see how the group might grow its operations. Covid has been a big hindrance but, as understandable as that is, it still points to a lack of earnings visibility and scope for significant operational disruption.
You’d never know what’s around the corner here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Ra International (LON:RAI) following up on from Roland's comments here yesterday (when I was at Mello). On Monday 30.5.22 at 11am, we have a presentation with management followed by a Q&A, if you'd like to attend register here: https://bit.ly/RAI_FY21_results_webinar
If I ever saw a bearish signal...
Three directors of On Beach group (LON:OTB) all with "Chief" in their titles, exercised their options and sold all. Total of £800k+ value.
The same trio sold similar amounts in Dec21, and also some in Jan22. Exercised options, sold all, kept no shares.
Re Hostmore (I Hold).
Does anyone know whether Hostmore service the TGI Fridays frozen food items which are exclusive to Iceland supermarkets? I can't see a reference to it anywhere.
Re £more (I hold) Good afternoon guys.
Mainly to say hello, as this is my first post, newbie here so please forgive me/correct me if I make a mistake. I agree that 7% revenue drop was expected and not so bad to explain a 16% share drop so I had to average down as I do believe that the co will survive this "crisis".
My question is about assets if anyone knows. According to stockopedia More has 351M£ of assets, does anybody know where/what they are? I don't think that they buy the land, right?
If Book Value per share is 99p then at a share price of 42p this must be a bargain.
Angelos
Hostmore (LON:MORE)
I agree that 7% revenue drop was expected and not so bad to explain a 16% share drop so I had to average down as I do believe that the co will survive this "crisis".
Welcome angelogr21
Always remember for high overhead business models small fluctuations in sales can materially affect the bottom line. 7% shortfall in sales could easily result in 50?% drop in porfits for some busines models. Hostmore who potentially have everything inplace to serve that "extra 7% custom" could be one of those hard hit businesses. - if they have the same overheads in place to serve 7% more customers than they get.
Angelos
Re Hostmore (LON:MORE) s asset backing.
If you look at the Balance Sheet of the last full year accounts, you'll see the largest assets are both intangible:
1. goodwill
2. right of use assets.
These are of questionable 'value'.
Yet if you remove these, there is no tangible asset backing at Hostmore (LON:MORE) .
Hi Epsilon,
Yes you're correct, there is no tangible asset backing to speak of at Hostmore (LON:MORE) (I hold). I covered this point in the main article. NTAV is negative if you write off all intangible assets. However there is also a deficit on the (meaningless) IFRS 16 entries. So if you also write off all the IFRS 16 stuff, it returns the balance sheet to a positive NTAV position.
Does that matter though? I'd say not, because if you look at the balance sheet again, it has little to nothing in both inventories, and receivables. Restaurants turn inventories very fast, because they're perishable, and get paid instantly in cash. Then suppliers get paid on maybe 45 days on average, which means the inventories are only paid for, after maybe 4 or 5 batches have already been used! that's a lovely working capital model.
Properties are leased, and with negative working capital, bars/restaurants simply don't need any NTAV at all, to function fine. Although the pandemic showed that, in an emergency, it's best to have plenty of cash reserves.
Also, as I mentioned in the main article, MORE's balance sheet is strong in comparison with debt-laden Restaurant (LON:RTN), which has a large negative NTAV position.
Regards, Paul.
Surprised no-one has commented or mentioned Yu (LON:YU.) yet
In the first four months of the new FY (Jan-Apr22), average monthly bookings was up 81% YoY.
This looks like a nice acceleration compared to +66% for FY21 (Jan-Dec21) YoY.
Pleasingly, revenues and profit margins have increased in the first four months. Normally you get one or the other, but they've managed to pull off both.
Disappointingly, management are still guiding towards "meeting" FY22 market expectations, rather than any outperformance. Hence why I think the shares have dropped a bit today.
The market isn't kind at the moment to high-growth and no proven profitability. But one could argue Yu is different; as a utility (albeit one trying to be digital first) we know they can be profitable, and therefore one just has to believe they can scale revenues up. As Yu does B2B energy and gas, this is not subject to the government price caps. In addition, most businesses would have fixed-term contracts; usually 1-2 years long. Therefore, the vast majority renewing this year were struck in 2020-2021 (at much lower rates). As a challenger brand, Yu is poised to gain most from this market dynamic, as increasing number of businesses look to switch providers to minimise the price shock.
(I continue to hold in the Boon Fund)
Hi Paul
Re Hostmore (LON:MORE) and Restaurant (LON:RTN)
“value for money is key”
I couldn’t agree with you more. People will expect greater value as things get tighter. Value can be provided at all price points in the market. The survivors will be the ones who beat the customer expectations time and time again.
I believe Wagamama is part of Restaurant (LON:RTN) and I won’t go back to the Cheltenham branch because I’ve had a really poor experience on 2 occasions (when you pay to dine in to expect to get better service than the raft of delivery drivers collecting takeaway meals.)
TGi Gloucester was loads of fun and less expensive (plus didn’t feel like a takeaway) so my limited survey says Hostmore (LON:MORE) will be ok in the long run. They just need to fix their dodgy Coke machines (not enough fizz)
If the margins are as good as you say then they have loads of room to offer special deals. They need to make sure the experience is awesome at a good price, so customers feel they’ve had a great deal.
My kitchen design Business survived the 2007/8 crisis by offering amazing value and when things turned around half our competitors had gone.
Facilities by ADF (LON:ADF) - "average lead time of seven months, and its orderbook is mostly filled for 2022. This level of revenue visibility is rare in any business and allows the Group to accurately plan."
Is this claim really justified? Doesn't your average building firm keep 6 - 12 months of jobs in reserve? Don't contract recruiters have 9-12 months visibility, that being the average future duration of the contracted orderbook? What about the huge number of industrials with a large element of service revenues? How about lenders with 25 year mortgages locked in? That's before we get into more highly valued SaaS and subscription models with multi-year visibility. I get that the forward insight is comforting. But there's no special sauce and, on any popular measure, ADF is more expensive than Ashtead (LON:AHT), whose business it closely resembles, for a MUCH shorter track record. That said, it looks a good business, while the good times persist.
Everyone here could be forgiven for believing that I am a great supporter of Angle (LON:AGL) and take up quite a bit of space here. Yet there seems to be little or no interest from other than 1 or 2 people. It is not as if life sciences are totally ignored, otherwise I would understand. 'too technical for me, etc etc'.
Yesterday something happened to this great BRITISH company which was HUGE - not just for investors, though there was some considerable benefit - a 50% SP rise from an OK base to start with is quite unusual in current market conditions.......but the potential for much, much more is massive so more to come.......and it is also associated with improving the life and especially illness experiences for tens of thousands of people.......and its a process which is CHEAPER than other diagnostic treatments.
What happened? Well this company and the uniquely superior process it holds was finally acknowledged by the FDA - the US gold standard appreciated throughout the world. I leave it to you all, including Paul S please, to read the statement from the company in the usual Announcements to appreciate the MAGNITUDE of a change which will be so big for so many.
Mello annual pass-holders will be able to go back to the presentation made by the CEO and FD, because the story from the company has not changed, other than with positive research developments for 4 long years. Covid 19 has a lot to answer for here too, putting back this approval by at least 2 years.
Naturally, we are all interested in today's news with companies like £HOST putting out the not unexpected profit warning, at considerable pain to many readers here......but lets get things in perceptive, can we.
Paul S has been for a long time a great supporter of the charity of ZANE in Africa, for which I applaud him and support it and his efforts. I suggest that in a way ZANE and Angle (LON:AGL) have some important things in common. They bring us back to the really important things at a time when lots of bad, bad things are happening. I hope this doesnt sound like preaching. It isnt meant to be. Thank you if you got this far without throwing something at the screen!
£AGL
Totally agree. Liquid biopsies will totally transform cancer treatment worldwide. I appreciate it’s not Paul’s field (and I agree about other failed startups) but I feel he’s way behind the curve on this one.
Update from Trinity Delta this morning.
FDA clearance of the Parsortix system in mBC has been a clear focus for many investors. Achievement of this gold standard validation could transform ANGLE, with a potential near-term acceleration in revenues from the Pharma Service business, in which we see significant value. Longer-term, this could also drive revenues in mBC. We continue to believe ANGLE is well positioned to capitalise on growing recognition of the utility of CTC analysis in investigating protein markers on cancer cells, without the limitations of ctDNA (circulating tumour DNA) liquid biopsy (inapplicable to proteins) or tissue biopsies (unsuitable for longitudinal monitoring). We value ANGLE at £506m ($658m), or 215p/share with significant upside once Parsortix’s positioning becomes clearer.
Full pdf download available via
https://www.trinitydelta.org/research-notes/parsortix-fda-clearance-marks-a-key-transition-point/
Re Angle (LON:AGL) - you are right on most counts, particularly on the future benefit to those in potential need of life-extending treatment. I'd just be wary on the speed of the commercialisation process. Shares now look very expensive next to liquid biopsy counterparts like GH and EXAS, with similar FDA approval but much higher revenues, which have been crushed under the boots of the US growth wreck. At the slightest delay relative to forecasts, contraction could be severe and my instinct here would to be to bank some or all the investment and wait for a pull-back. I wish I had followed my own advice in respect of multiple biotech names that once showed good gains yet ended up being sold much lower.
In the RNS yesterday "ANGLE believes this FDA classification is only the third liquid biopsy product clearance ever granted, with the other two being limited to a single gene in a single cancer using ctDNA (fragments of dead cells) and a system for counting cells that does not allow downstream analysis of the cells. ANGLE's clearance is the first and only FDA product clearance, considered the gold standard regulatory clearance worldwide, for a liquid biopsy solution to harvest intact cancer cells for subsequent analysis."
From my limited knowledge Angle (LON:AGL) has bigger potential than GH and EXAS, but as ever with biotech, it is difficult to really know until commercial deals are made.
I agree on the potential for the company and its technology. I’m only talking about the future of the share price. My experience in biotech investing is that you will get another look at a lower price. NTLA is a good example of a genuine and important medical breakthrough in July 21 which has not brought further gains. In fact quite the opposite, for which the reasons are well understood and to which Angle (LON:AGL) is very vulnerable at today’s valuation.
I agree it's great news, ridavies, and well done to holders. I thought I had some in a fund, but just found out no :(. I know it's been a huge journey and looks like it could be a big success. If it hadn't risen so much I'd have gone in. Will look at it thoughtfully at this level.
Raggedtp & BnB
My view, FWIW, is that there will significant progress in other areas Angle has already progressed and that the sp will be much higher in 2 years or the company will have been taken over at a significant premium. It's my biggest holding by far so I'm not at all biased. We're all hoping to buy various stocks at the lowest point of this market but we'll likely be too late.
I sincerely hope you are correct. Good luck and I'll be watching the name more closely in future.
Hello Jim McLad and also BnB. Jim and I have identical thoughts re Angle (LON:AGL) and our shareholdings in relation to our portfolio are identical.
BnB's thoughts are probably accurate and I will be ready to add my holding again on a pull back. I also agree with Jim that Paul (and generally Im his biggest fan and follower) has a blind spot on this one, though like BnB he may be able to say I told you so in a few weeks / months time.
Sometimes there is no doubt you can get too close to a share - and jim and I could certainly be considered guilty of that. For some time I was very concerned about the time the FDA was taking until I fully understood that this is what is called a De Novo** application and as such a separate category has to be created, despite the fact that many consider GH and EXAS to be in the same category. They most certainly are not, and their position is truly threatened by the Angle (LON:AGL) technology.
**NB in a De Novo application the case has to be proven by a much more detailed review of research etc than will now be required for repeat applications to the FDA for say the other areas where Angle (LON:AGL) has detailed positive research from acknowledged research institutes in the US, UK and Europe, especially in lung cancer, probably the next application.
In the case of ovarian cancer application, the latest research is expected in some months time, and a new study for the process application in prostate cancer is due to start very soon at Barts in London.
The principles of the effectiveness and superiority of the Angle (LON:AGL) process are truly applicable to many forms of cancer - saving money on the 80% of cancer treatments which are proven to be ineffective in retrospect; saving money on the biopsies which prove to be unnecessary; saving money by helping direct the right treatment to the right patients - and I mention only MONEY here on this investing website, because I accept that all the unnecessary associated pain and suffering are perhaps for consideration another place.
The point about speed of commercialization is always a valid one and was referred to in the broadcast yesterday pm, which is available on the Angle (LON:AGL) website.
The company has been waiting longer than expected, because of Covid 19. It has not stood still with its labs established in the US and UK, pursuing additional research opportunities with relevant institutions.
It will also have spent time on how best to commercialize and how long it will take. On the webcast, it was acknowledged that some areas will take longer - up t 2 years was mentioned, but also there were other routes discussed where staging payments etc would bring in revenue along the way. For example other organizations could develop labs of their own matching the current Angle (LON:AGL) ones, which would give revenue for usage of Angle (LON:AGL) technology.
A long way to go, I acknowledge, but of the outcome I am more confident than I have been about any share for a very long time. I agree with Jim that the SP will be much higher in 2 years or the company will have been taken over at a significant premium. I hope it is the former, as the management stated for very good reasons at the Mello presentation some months ago. The principal reason given for wanting to stay independent was a comparison with a similar company which was taken over, and then sold on effectively for many time more after a relatively short period of time. We will see. Certainly my holding important as it is to me will not influence events!
Replying to myself, and this is my final word on the matter (well probably!), I have been listening to the presentation which we finally got Angle (LON:AGL) management to give to Mello Monday, and guess when that was?
Yes, 1 year ago to the day to the announcement yesterday that FDA clearance had been granted - 25th May 20221 and 25th May 2022.. Do you believe in coincidence to indicate future success? At this point in time in this market and this world, I am looking for all the investor equivalents of rabbits feet and irish gypsy heather I can find! Just in case.
In the midst of all this gloom we all need something to cheer us on. Very luckily I own some £AGL..just decided to see what Stocko made of it. It is down as a Momentum Trap...made me chuckle anyway.
Hi hiyashi22,
Sure, every now and then, a blue sky type share comes good. But the vast majority destroy shareholder value!
I see Angle (LON:AGL) has received FDA clearance yesterday. I remember looking at this share a few years ago, and thinking it was an interesting story, but too speculative & impossible to value.
Market cap now up to £367m,
Share count has tripled in the last 6 years, which actually isn't bad for a negligible revenues, heavily loss-making blue sky share.
It looks a long way from being a viable business - they now have to get out there and actually sell something!
How do you value it? No idea!
The share price has nearly got back to where it was 17 years ago! So not exactly a rip-roaring success. Has risk:reward been worth it?
Paul - do not forget the property effect. Although many of Friday's consumer base are young(-ish), being rich enough to afford Friday's, they may well already be on the lower rungs of the property ladder and also still getting extra equity from that source. So they may be mortgaged to the eyes but must have good jobs/big deposits to get on the ladder at all. Assume a 400K property in a prosperous urban area (which is where Friday's typically reside), going up 5% pa, that equals 20K fresh "equity" pa plus typically 2 good salaries, with no experience of a bad bear property market - this supports a live for today approach. Drop the 2nd ski-ing holiday or long haul trip and that "saves" 4K for weekly nights out. Older Friday's consumers (who pay for family dining events in my experience!!) will have even more equity.
Only if property goes into reverse or white collar, middle-class unemployment jumps will this engine seize. (Politically, IMHO this is scandalously inequitous and we are heading to a permanent 2 tier society but we are focused on investing here.)
The poor and just-about-managing people do not have this long term cashflow perspective and are understandably fearful. It is they who feature on cost-of-living crisis stories bout foodbanks etc ......but they never went to Friday's anyway.
Net, a storm will blow but Friday's are likely to emerge the other side with more sites, less competition and their balance sheet largely intact. I may be wrong but I am likely to buy MORE in the the next few weeks.
An intereating take on the subject of Hostmore (LON:MORE) thank you Zipmanpeter. It may work if they are prepared to give up the assumed spend on that long haul flight or second ski holiday - a big if but a possibility, its true..
But do couples with 2 ski trips a year really eat at TGIF? I find that hard to believe. The food is more mainstream and for less pampered (or discerning, depending on your perspective) appetites.
Interested if anyone was present for the BASH last night and could let us know what the verdict was on Luceco (LON:LUCE) ?
Joshwood
I was at the BASH. Personally I find it interesting for the pros and cons put out on stocks rather than the “verdict”.
But as you asked for the verdict on Luceco (LON:LUCE) - the four other panelists were on the whole negative: “falling knife”, management credibility has suffered “. etc. The audience vote was also on the whole bearish.
I see the stock is up today.
Just my take on Luceco (LON:LUCE) (I hold). Personally I hold a lot of sway in Directors share dealings in these smaller caps. There have generally only been share sales over recent times in this company. Even the present price, down over 70% from highs last year, hasnt been enough to entice any of them to put their hand in their pockets.
The founder and CEO has made two very significant share sales in recent years. In November 2017, not too long after listing, his sales were swiftly followed by a 75% collapse in the share price after bad news subsequently was released a month or two later. . And in February 2022 they have been followed by a 60% fall in share price after the more recent profit warning.
Absolutely no suggestion of any wrongdoing at all, the team there seem very decent and honourable. But its really not a great look. So for me, investing further now is out of the question until certainty comes back, which they themselves have suggested may be quite some way away.
re Hostmore (LON:MORE) thanks for your thoughts Paul. I agree that this isn't a surprise and isn't that bad. In fact I think the co are getting it all out there because the shares are down 50%+ and have nothing to lose. When the co listed Numis had bear base bull case EBITDA for 2022 of £25.5m, £29.4m and £33.9m.
Bear case had Rev -6% margin 11.2% which sounds about right today. However brokers being brokers, they have actually moved to a 9.1% margin 2022 and pencilled in 10.4% for 2023... 2023 EBITDA £25.6m. Whilst its a decent downgrade its only 10% from base case when the company was listed. Yet the shares have fallen 70%. So most of the fall reflects sentiment which is poor.
Sentiment is fickle and can improve quickly. My guess is these numbers reflect all of the bad news and none of the good. Trading can still improve over the summer ... price increases come through...new openings contribute. Obviously it would be nice to wait for better trading numbers but by then the shares will have bounced. It is sentiment that is very poor here, and an improvement will see the shares recover.
Re Hostmore (LON:MORE) - clearly a profit warning but no meaningful quantification ! It is lovely that EBITDA will still be double digit, and genuinely encouraging that they remain positive on Friday's & Go albeit very early days. Plus I guess I am happy that inferred price increases and other actions will reclaim half of the impact of the now expected 8% volume reduction vs 2019 etc (although I do worry about them being overpriced) and that they are still generating cash and talking about a self funded rollout "if conditions permit".
But what I really want to know today is : where do they expect to end the year (esp vs previous forecasts) at 20 weeks in, on revenue at least if not profit. On that, much less clear.
My worries are increased by the recent appointment of a second broker, often the precurser to a fund raise.
I (still) hold as I have now bought into the resilience and plans for revival of the brand, with the opportunities it has for expansion but I am less happy than I was and that isn't due to the falling share price.
I had high hopes for the Mgt Team but as operators of a standalone, listed company with this trading update, they have yet to convince me.
I just get the feeling that the beatings will continue until morale improves. Macro events are driving consumer discretionary buying. I sold my Fulham Shore yesterday simply because of the general drag down. I like the sector and believe good companies will recover strongly, but out for now.
Hi Raleigh4343. I also own Fulham Shore (LON:FUL) and have been undecided on whether to exit. I have decided to stay in, and will top up, as their proposition is value oriented menus and a cheap night out/ night in with a takeout. Strong management team who have been around several blocks, and they will be taking advantage of a load of landlord discounts/ CAPEX funded premises. If it does drop below 11p and stabilizes at a new base I will increase to a full holding on a 3-5 year view. Then only time will tell.....
Hi BritishExpat70,
I think take-out, delivery is very important now, as a lot of people have switched permanently to using deliveries - I have become super-lazy and use JustEat multiple times each week!
Fulham Shore (LON:FUL) is notable for its take-out offer. the Bournemouth store is doing £5 (for pizzas 1-6 on menu) take out offer on Mon-Thurs, a compelling offer, as FUL pizzas really are delicious, and getting one piping hot straight out of the oven for a fiver, is terrific, and will still be high margin, for basically a lump of dough, with a little cheese & tomato on top!
Whilst I wait only about 5-10 mins tops for my pizza, I notice a steady stream of delivery riders coming & going too.
Tortilla Mexican Grill (LON:MEX) said something similar too, that delivery is now very important. I noticed Tortilla have just bought Chilango, who make by far the best burritos in London, but went bust from (as always) signing expensive leases. Interestingly, Chilango & others are opening dark kitchens, sites dedicated entirely to servicing delivery customers. That's also becoming an important new growth area.
As always, tough conditions drive innovation!
There was another interesting thing in today's "Propel" industry newsletter for hospitality. A restaurateur in South London has just lowered his prices by 10-15%, to give compelling value, and its attracting customers. He's done this by bringing in a "zero waste" policy, so chefs have to find a use for everything, thus lowering costs, enabling lower prices, and attracting new business, hence revenues actually go up, and staff time is better utilised, as they're not standing around doing nothing at quieter times. Also he's changing the menu weekly, using whatever ingredients they can source cheaply that week.
Regards, Paul.
Thanks for that Paul. All that is really interesting. As you say 'needs must' and its also an appealing story to hear by what must be an increasing number of people watching what they spend and looking for best value for money. Interested to hear about Tortilla Mexican Grill (LON:MEX) too. Have put them forward to Mello team several times recently. Would be interesting to see what they have to say and to put questions directly to them.
Hello Zipmanpeter and others. Re Hostmore (LON:MORE) at their last Mello presentation, one of the things that impressed me was that they had foreseen the power issues, and that they had bought forward for the next 18 months (at the time of the presentation). Of course they may have paid a lot, but if cost increases are generating these poor figures, then power price issues - a big factor for many other companies - shouldn't be one of them. Im just concerned that their market positioning and pricing coupled with their likely consumer base will not stack up in a tough economic environment for so many households and people. Fortunately, this is one company I did not invest in, though I have several others giving me pain!
Facilities by ADF (LON:ADF) Another vote for your opinion on ADF. Maiden results as a listed company have taken a long time to produce, but look good. Market background is currently buoyant, but Netflix a big customer. Most vehicles seem to be leased rather than purchased. I hold modest stake.
OK, I'll look at ADF next. I also like it, and own a few.
I have been impressed by Facilities by ADF (LON:ADF) and the market they are in which seems to be ok at the moment. However, as stuartb58 implies - for how long? Netflix - and Amazon - and others like them, are big spenders. They are suffering as the Netflix SP performance is a clear indicator. So........my conclusion is, good company but likely market issues will affect them too in the next couple of years. Was tempted when they were an unexpected Small Company Sharewatch NAP for 2022 but held back. Glad I did.
Paul,
I was wondering if you are going to give a brief synopsis on what happened on day 2 at Mello please.
Being in Guernsey I have been unable to attend this event.
Thanks
Mark
Hi Mark,
No, afraid not. There's so much news today, that I'm not sure I'll be able to get into London for Mello, from Bou'mth. We'll see how we go.
Maybe readers could put up something, who attend? I've got my plate full with company updates.
Regards, Paul.
Thanks Paul for the update and appreciate your work load-some great stuff from you and Jack.
Welcome any feedback from other attendees.
just digesting Facilities by ADF (LON:ADF) inaugural results as a listed company. Had to go to the company's website to find them. Seem very positive, but still number crunching. Will catch Sanderson Design (LON:SDG) today at Mello. I hold both. Paul/Jack any thoughts on Facilities by ADF (LON:ADF) ?
My only concern with Facilities by ADF (LON:ADF) (I hold) is the PE in the current climate.
2.2% down ATM and the niggle that is stopping me averaging up.
Hi Paul S,
Facilities by ADF (LON:ADF) With an adjusted EPS forecast for FY'23, a forward PE of around 12 doesn't strike me excessive?!
I would say it's cheap.
Regards.
John Doe stocko has it on a 22E P.E of 24.8...is that down for 2023 (12ish)? I don't have access to further broker notes.
Cheers
Paul
Hi Paul,
Cenkos has 5.9p EPS for FY'23.
Regards.
Cheers John Doe...good info
Hello jonno and others. Facilities by ADF (LON:ADF) was one of the Small Company Sharewatch NAPs for 2022. The NAPs are currently down around 12%, with a range of a big winner - £MNZ - and big losers - Joules (LON:JOUL) and Reach (LON:RCH) and Superdry (LON:SDRY) balanced up by more ok performers. I have an analysis going of £5k into each which gives the 12%. Others may have balanced their investment in a different way and probably come out with a bigger loss to date!
Hostmore Hostmore (LON:MORE) (I hold) has issued a profit warning in its trading update this morning. Appears to be a result of general macro environment including higher input prices. Would appreciate your coverage if possible today chaps. Will definitely have a negative influence on share price and I'm wondering whether to take the opportunity to average down as I believe in the model long term. All the best, Bristol.
I was a believer in the Hostmore (LON:MORE) brand and long-term story, but as the risk of economic impacts from the various inflation/war/shortages issues took hold I sold out (approx 50% down - probably my biggest ever loss). I will keep an eye on them though as I do think they have a good management team and at some point once things settle down I may consider them a recovery play. But I think it's too early currently and I'll watch from the sidelines. Good luck to all holders.
Holding long-term through thick & thin is very difficult once certain trigger points are reached and personally I felt that there was more bad news/losses to come at the point I sold out. Some may criticise and say sell at a say 20% loss (preserving capital) others will hang on and happily await a recovery and others will double-down. I will employ a mix dependent upon the likelihood of a fast recovery, what the stock is, past history and a variety of other factors.
I would normally jump ship at the first sign of trouble but given that there is less left to lose than the loss already incurred, I'm inclined to stay in, or at least not rush to crystallise an already unpleasant loss. I can't say I'm ready to double down though, I'd be looking for signs of recovery first for fear of throwing good money after bad. After all who wants a pudding when the main course has been unpalatable? (I, perhaps obviously, Hold, still....)
I have been watching Hostmore (LON:MORE) all the way down, waiting for a dirt cheap entry price. I keep re-setting my Stocko alerts every 10p decline, and have resisted pulling the trigger every time. I have learned so much from this downturn, as inexperience has resulted in taking positions too early, before positive news and a new stable base merits it. It has cost me dearly.
I did notice that Christopher Mills of Harwood Capital invested in Hostmore in April. His returns over the years have been astonishing, and is a highly regarded small cap turnaround guy. He clearly sees an opportunity here. I’ve set an alert for 40p but might be resetting that alert again today! Down 12%.
Will be interesting to see market reaction to the trading update from Hostmore (LON:MORE) - a rather painful hold for me as I bought in soon after its debut. Is the muted outlook already built into the price and does the prospect of growth and possibly sunnier times ahead mean that it has bottomed out? New format openings seem to have been a success.
Don't know whether there's enough meat in the update for a considered view from Paul.
This follows a few decent RNS's from pub chains. I wonder if Hostmore is more of an 'event' venue, or the other pub chains are just behind the curve.
I thought hospitality was a good recovery play but now I wonder, and will this also knock onto travel which with OTB RNS yesterday seems to be viewing things a little more bearish.
Paul S, re Hostmore (LON:MORE) you have mentioned before that their prices are too high, if I remember your comment correctly. Value for money issue too therefore?
For me there was clearly a lack of numbers. I continue to hold as I believe in a few years time it should be much higher than it is today but the short term outlook doesn't seem to great.
Mr C, thank you. This morning you have exceeded yourself. And made my day. No mean feat.
'Singin' in the Pain'
That says it all for me. I'm still laughing. I think its probably hysteria :-)
Mark
Strong results from Paypoint (LON:PAY). My largest "small cap" holding. Seems to be totally off-the -radar of small investors.
Yes, would be interested if Paul or Jack could review. Strong dividend, relatively low gearing. Cash generative. Good margins. Sales mix is changing slowly. They don't seem to mention the McColls recent events as being an issue?
Hi kuronagi & Trident,
We've covered PayPoint (LON:PAY) before a few times. It always looks cheap, despite making high margins & paying a very generous divi. I think the issue might be that investors see it as old technology, with a limited lifespan from here? I'm having a look at today's results, and the figures & valuation are indeed impressive.
Although it refers to bill payments as "legacy" business. It looks like they're expanding through acquisitions. So I suppose your investment view would depend on -
How quickly is legacy business declining, and what % of current profits come from that?
Are acquisitions any good, and creating value?
Also, with energy prices rising so much, then I imagine card payment energy customers will be forced to pay more, thus raising revenue/profit for Paypoint.
Balance sheet - not great. NTAV is negative about £(10)m.
All in all, it's a bit complicated to assess I think, so will pass on this one, but thanks for flagging it!
Regards, Paul.
Hmm. Govt putting £400 credit on prepayment meters this Oct. Gonna hit PayPoint (LON:PAY) energy revenues for a month or two as no top ups will be done.
Morning all,
Strong set of maiden results from Facilities by ADF (LON:ADF) this morning.
Cenkos have upgraded numbers for FY'22 and FY'23.
I hold.
NWOR National World in line update today .
Share prices has been drifting continuously lower down to a remarkable 20p level valuing the company circa 40 million .
Deduct cash of 21.5 million gives 18.5 million .
In line profits of circa 8-9 million gives PE of a crazy 2 .
Unlike Reach no pension deficit, It is to quote my old FD “clean as a whistle” .
It has great titles and a strong team and is not a declining business .
Looks like an anomaly to me but I was saying that at 30p !
You wonder what the catalyst might be for a re-rating here. Maybe Montgomery needs to show that he can use his increasing cash pile to fund bolt-ons, fueling digital growth to offset print declines. Maybe the market will now present some cheap acquisition opportunities. One for the patient (I hold).
Hi planetx,
A lovely summary of National World (LON:NWOR) thank you - that has got me interested, so I'll look at NWOR next, after I've finished ADF.
Best wishes, Paul.
P.S. We love it when subscribers put up a synopsis of company updates here, as it helps us focus on the most interesting opportunities, and increases the coverage.
Sanderson Design (LON:SDG) another new collection announced today; their Morris & Co garden won a Gold at Chelsea on Monday; Lisa, CEO presents at Mello today. Oversold. I hold.
Cost of living crisis having an impact on luxury spending?
I bought into Sanderson Design recently, my view is the rich are getting richer, the older generation which appeal to this kind of brand seem to be the ones with the money. My feeling is they will be ok through this. Time will tell.
Paul.S - yes I agree with you re Sanderson Design (LON:SDG) (I hold). On a recent webinar, the excellent CEO said that they have good pricing power, and normally raise prices by 3-5% every February, but this year raised by 9%, and are considering doing 6-monthly price increases in future, to avoid scaring the customers with large hikes.
I imagine there's likely to be some softening of demand, but anyone who can afford SDG products definitely won't be worrying about their utility bills! It's high end stuff.
That said, stock market plunges have had a big negative wealth effect already, so maybe the rich might tighten their belts a bit, I don't know.
They were discussing this on CNBC yesterday, and apparently 2 mid-higher end brands (I forget the names, but they're well-known) have just put out surprisingly strong updates.
Regards, Paul.