Small Cap Value Report (Thu 26 Nov 2020) - EKF, CTO, BOO, TRCS

Good morning, it's Jack & Paul here with the SCVR for Thursday.
Agenda - many thanks to Jack for covering the morning shift, with;
Ekf Diagnostics Holdings (LON:EKF) - 2 announcements
Tclarke (LON:CTO) - Trading update
Paul is doing the afternoon shift, and will be looking at;
Boohoo (LON:BOO) - Update on supply chain action, including appointing KPMG & Lord Leveson
Tracsis (LON:TRCS) - Final results
Shoe Zone (LON:SHOE) - Update buried in a "Date of results" announcement
Newriver Reit (LON:NRR) - Half year results - sorry, ran out of time, see Friday's report.
Motorpoint (LON:MOTR) - Interim results - sorry, ran out of time, see Friday's report.
(and possibly circling back to De La Rue (LON:DLAR) from yesterday, or I might do that tomorrow, it depends on time)
Timing - estimated time of completion, c.7pm. (extended, because I want to watch the webinar from Intercede at 16:15 on IMC). Today's report is now finished.
Jack's section
EKF Diagnostics (LON:EKF)
Share price: 63.17p (+4.41%)
Shares in issue: 454,993,227
Market cap: £287.4m
We last talked about Ekf Diagnostics Holdings (LON:EKF) here, on the 9th of November - a ‘comfortably ahead’ trading update - but this was just before the first of the vaccine news.
Those stories seem to have sparked a fundamental rotation in market sentiment. This might last, or it might not, but it’s interesting to track EKF’s share price movements this month, up nearly 20% at one point before handing momentum over to the FTSE 100.

EKF is a global, integrated medical diagnostics business that designs and manufactures diagnostic equipment for use within Point-of-Care settings. Its portfolio includes small blood analysers used in testing patients for conditions including diabetes and anaemia.
As a transporter of Covid samples, its business has benefitted from recent conditions with the release of its PrimeStore MTM pathogenic sample collection product. Even now, the shares retain a punchy valuation of 29.8 times forecast earnings. This is based on FY21 numbers, though.
Brokers are forecasting a bumper FY20, with earnings set to come in at 3.41p, making for a more reasonable valuation of 18.8 times current year earnings.
As with other stocks, the question of whether EKF is expensive or not revolves around how long heightened trading lasts, how big the boom is, and what business looks like post-Covid.
On that last note, the group has more established revenues over the years and so is less likely to be a flash in the pan.

£m
COVID-SeroKlir - FDA Emergency Use Authorisation
EKF actually has two RNS statements out today - the first is its sale in shares of Renalytix, the developer of AI diagnostics for kidney disease, which it spun off a while back. It looks like a useful profit as ‘the sale has resulted in gross proceeds of £7.705m to EKF and generated a profit of over £5.6m after dealing expenses.’
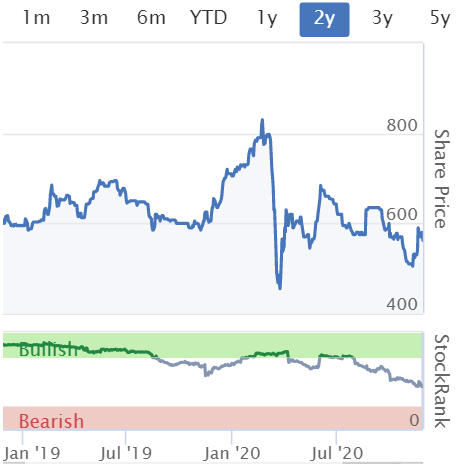
In fact, heading over to the Renalytix StockReport, the company is now worth more than EKF after going from 120p to 517p in just over two years, so a very successful spin off so far.
The other bit of news today from EKF is the FDA emergency use authorisation of COVID-SeroKlir, a quantitative SARS-CoV-2 IgG antibody test kit. EKF has exclusive rights to market and distribute this product in the UK and Germany and non-exclusive rights in Europe.
Its partner in this venture is Kantaro Biosciences. COVID-SeroKlir is a high-performance semi-quantitative antibody test kit (demonstrating 98.8% sensitivity and 99.6% specificity for detecting SARS-CoV-2 specific IgG antibodies against two virus antigens), ‘with a broad range of applications in the fight against COVID-19’.
The Kantaro test is being manufactured at scale and immediately available in the U.S, with a capacity of up to 10 million tests per month.
Conclusion
The Renalytix spin off shows that EKF is capable of creating substantial value. The company has established revenue, double digit operating margins, and is cash flow positive.
Of all the stocks with Covid-related business, this looks like one that is more certain to continue creating value long past the pandemic. What’s more, some of those Covid stocks trade on a similar market cap to EKF without that track record of established revenue generation.
But it’s not a company I know well, just a company I’d like to know well. With a market cap approaching £300m and a forecast £61.2m of FY20 revenue falling to £49.9m in FY21, the valuation raises questions. That said, expectations have been upgraded several times this year already so there is good operating momentum here.
Analysts have clearly struggled to appropriately incorporate EKF’s improving prospects in recent times, so there’s always the chance of further surprises.
T Clarke (LON:CTO)
Share price: 97.80p (+11.52%)
Shares in issue: 43,052,558
Market cap: £42.1m
Tclarke (LON:CTO) delivers electrical, mechanical, and IT services to buildings.
It’s a perennially cheap micro cap - note the stubbornly low PE ratio and high dividend yield juxtaposed against the rising revenue and income:

And then the StockRanks: good Value and decent Quality, but with poor Momentum. The kind of profile that, in a recovering market, could see it shoot up the StockRanks.

On the face of it then worth a closer look as a beaten up recovery play. Shares are up around 11% on this trading update so let’s take a look.
This is a ‘resilient performance’ and the group ‘continues to trade in line’ - so it’s not shooting the lights out, but neither is it in severe distress. On a forecast PE ratio of 5.9, I would argue that’s more than adequate.
The group anticipates turnover in 2020 of c£240m and underlying EBIT of around £6m against a market cap of c£40m. What’s more, it is assisting with the rapid delivery and maintenance of COVID-19 Testing Stations across the UK.
Margins are low though: ‘TClarke achieved its target 3% EBIT margin in Q1, broke even on much reduced volumes in Q2 and expects to deliver a 3% margin for H2.’
Meanwhile, the outlook sounds ok.
The group is winning new projects across a wide range of sectors and the forward order book has increased to £422m - that’s £61m (17%) higher than at the same point in 2019. Revenues of £257m for 2021 have already been secured, compared to £232m this time last year and up from £191m at the group's interim results in August.
TClarke says it is strong in the healthcare, education and data centre market sectors and sees ‘exciting opportunities across all of these market sectors, providing excellent opportunities for growth over the next few years.’
Conclusion
Is this just a low multiple business model? CTO has had a single-digit PE ratio for years now, so what is about to cause an expansion in that multiple? That said, the value on offer is striking.

Operationally the group looks to be making the most of a challenging period. And the outlook sounds quite healthy. Ideally, I’d like to see this backed up by some director buys but you can at least tell from the net cash balance sheet and lack of shareholder dilution that this appears to be a sensibly run business for shareholders.
There is a £26m pension fund deficit - quite big for a small company. From the most recent annual report we see that the group is contributing £1.5m per annum for 12 years (from 2018). That’s something to keep an eye on.
All in all though, given the cheap valuation and solid outlook there could be good value here.
.
Paul's Section
Boohoo (LON:BOO)
(I hold)
295p (up c.2%) - mkt cap £3.7bn
There's another step in the right direction to improve its supply chain, from this fast fashion business with 9 brands. It provides an update today on its “Agenda for Change”. To summarise;
- Sir Brian Leveson PC has been appointed to provide independent oversight into BOO’s supply chain changes - Leveson is a major figure in the legal profession. For anyone not familiar with his background, take a look at this article. Therefore this is quite a coup for BOO
- Leveson will report to BOO’s Board, and his reports will be published - top marks for transparency
- Leveson has appointed a legal, and independent enquiry & enforcement team - so this has teeth, it’s not just a window-dressing exercise
- The aim is to ensure that - "everyone associated with the Group's supply chain is treated fully in accordance with the law and the principles of ethical trading."
- KPMG also appointed to assist with improving the supply chain - working with 2 existing supply chain auditors, Bureau Veritas, and Verisio
- Chairman confirms he is onside with the Agenda for Change programme. It’s good that he’s stopped defending previous practices, and has moved with the times. I see this as part of the process of growing pains from a small family business, to a large global business.
My view - I think there’s a tremendous opportunity with this share. It’s a fantastic growth business, delivering superb financial performance. Yet the valuation is way below other similar growth companies. Look at $FTCH for example. Listed on the US market, it has similar revenues & growth to BOO, yet it loses money hand over fist! Whereas BOO is strongly profitable, but is only valued at a quarter of FarFetch. It’s a glaring anomaly. I’ve suggested to BOO that it lists in America, where the valuation would be so much higher than on AIM.
That’s one opportunity for a big re-rating. The other opportunity, is that the ESG fund managers who’ve been selling up over the supply chain issues, are likely, at some point (no idea when) to recognise that BOO is doing everything humanly possible to fix the problems, with total transparency, and considerable resources being used - I know KPMG are not cheap, and imagine that Lord Leveson’s hourly rate is not likely to be modest! Therefore, I can foresee all those forced sellers becoming keen to buy back in at some point, probably at a much higher price. Combine that with short sellers being forced buyers, and it's a recipe for a big & sustained move up in share price.
Hence this looks to me like a really terrific opportunity for private investors to get ahead of the curve. I’ve been buying more, and as mentioned before, it’s my largest personal holding.
The next trading update could be good, because we have Black Friday tomorrow, a major boost for online retailers in particular since their physical competitors on the High Street are currently shut.
It should be interesting to see what happens next. I think this is a seriously good risk:reward situation now. But obviously, DYOR as usual.
I wonder how long the UK press will keep trying to re-hash the supply chain problems? They’ve been dining out on this story for a couple of years now. Will any start reporting the fact that, actually the company has responded very positively, and extensively, to fixing these issues? I wouldn’t bet on it.
.
Tracsis (LON:TRCS)
Share price: 565p (down c.3%, at 14:32)
No. shares: 29.16m
Market cap: £164.8m
Tracsis, a leading provider of software, hardware and services for the rail, traffic data and wider transport industries, is pleased to announce its unaudited final results for the year ended 31 July 2020.
My report here on 19 Aug 2020 is worth revisiting, by way of background. In short, TRCS said that covid had a significant impact (£10m hit to pre-covid forecast, with guidance at revenues for FY 07/2020 of £48m), but that this was not as bad as originally feared. EBITDA forecast of £9.6m, down 8% down on LY, helped by cost-cutting. £18m cash at year end.
Let’s look at the actual results now, and see how they compare;
- Revenue £48.0m - tick, same as guided
- Adj EBITDA of £9.6m (excl IFRS 16) - tick, same as guided
- Cash £17.9m - just a smidge lower than £18.0m forecast, near enough
That’s fine then, the FY 07/2020 results are in line with expectations & previous guidance.
Valuation - fully diluted adj EPS is 23.7p (down 14% on LY) - which seems creditable, given the huge disruption covid/lockdown has caused. The PER is 23.8 - that looks about right to me, considering future performance should improve after covid, and factoring in the decent cash pile.
Balance sheet - TRCS has always been run on a conservative basis, with plenty of cash in the kitty. That, combined with plenty of recurring revenues, makes it a sleep soundly at night type of share.
Note that tangible fixed assets, and inventories, are low, which makes it a capital-light business model, a good thing.
Working capital looks fine, and includes £17.9m cash.
Note there is a total of £7.3m contingent consideration payable, which should probably be deducted from the cash pile, to arrive at a more conservative net cash position. Although the company would probably say that contingent consideration is paid out of future cashflows, which is a fair point.
NAV is £53.0m, less intangibles of £54.4m (goodwill from all the acquisitions I think), and NTAV is actually slightly negative at £(1.4)m. Maybe we should also ignore the £8.2m deferred tax liabilities? Doing so would turn NTAV positive again to £6.8m.
Overall, I’d say the balance sheet is OK.
Cashflow statement - often overlooked by investors, but in some ways this is more important than the P&L. In this case it clearly shows the business model - i.e. a strongly cash generative business, which uses that cashflow to acquire other businesses. Dividends are tiny, because the cash is being used for acquisitions.
Outlook - clear guidance here, which is helpful;
Q1 trading has been in line with the Board's expectations. As we look to the remainder of the financial year, we are aspiring to achieve modest revenue growth and EBITDA margin improvement despite the ongoing challenges of Covid-19, and we expect our cash position to remain equally as strong.
More detail is available in the RNS.
My opinion - I’ve always liked this share, but generally found it rather too expensive. I’d say the price now looks about right. Therefore anyone buying now, is not exactly getting a bargain, but it would be more of a long-term holding, if you believe the company will continue to grow, and generate a higher share price accordingly over time.
It’s got a good track record, seems well managed, and I imagine profits would be likely to rise, once covid is behind us.
I haven't read all the commentary, due to time constraints, remember I'm really only reviewing the numbers in these reports, not making predictions about what the future might hold. It's up to you to decide if you think the company's prospects make its shares attractive or not.
.

.
.
Shoe Zone (LON:SHOE)
Share price: 56p (down 9% at 16:03)
No. shares: 50.0m
Market cap: £28.0m
(I hold)
This RNS has really been given the wrong title. It contains much more than just the results date (which I would normally ignore, because I look at results every day, and use an email alert service to flag up companies of interest). It should have been entitled: trading update and results date.
It has a strange 5 October year end date;
Shoe Zone announces that, as a result of the impact of the second Government mandated lockdown in the UK, it will now announce its Final Results for the period ended 5 October 2020 on 8 March 2021.
That’s 2 months later than last year’s 8 Jan 2020 announcement of preliminary results, which strikes me as a rather excessive delay.
Lockdown 2 - will see at least £12m lost revenue vs FY 9/2020, which takes into account “good gains” in online sales.
SHOE continues to have a “material net cash position”
Sufficient liquidity, providing no further Govt restrictions above already known
Cannot give meaningful guidance due to economic uncertainty
My opinion - I don’t see anything unexpected in this update, so can only assume that today’s 9% price drop must be some punters deciding to bank some of the big recent gains (from a low base I should add).
I like this well-managed, owner-managed retailer of cheap shoes. Once retailing conditions are back to normal, then it should return to profitability. It looks as if SHOE has enough cash to tide it through. Personally, I’m holding for medium/longer term upside. If profits get back to anything like pre-covid levels, then we could conceivably see this share usefully higher than now. Remember that there has been no dilution, as it has not needed to raise fresh equity. Therefore in theory the share price could recover to previous levels.
.

.
See you tomorrow, for a big catch-up day.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

130 comments
Paul, or anyone else who was there - any impressions of the Intercede (LON:IGP) webinar?
I noted that they said they defended their IP if necessary, confirming they had some because unlike most software developers they have not capitalised R&D as a large intangible on the balance sheet.
It was difficult to follow because the sound quality was very poor. That made me want to buy shares in LoopUp (LON:LOOP) - their USP cf zoom and all the others is that the sound goes over a separate secure and quality network not VOIP.
Um, well, don't wish to be the pub pedant - but any transmission of voice over an internet channel is, technically, voip - voice over internet protocol ;)
OK - I was badly expressing this:
https://loopup.com/en/direct-routing/#
£:BOO (LON:Boohoo) Paul, I've been going through an interesting excercise of asking my nieces why they shop or don't at Boohoo, and immediately ASOS comes up as the counter argument. So with the principle of always questioning whether we become confirmation biassed in our decisions, I started having a look at ASOS on Stocko as a comparison and surprised that ASOS wins . Not dissimilar in many of the parameters. So can you remind me why Boohoo is such a favourite of yours? (I hold Boohoo)
@Paul - You mentioned about suggesting to Boohoo (LON:BOO) about transitioning from AIM to NYSE (or both I guess), do you see that as something that happens at all ?(Apologies I am still fairly new to this game).
Would it be costly for them, is it as simple as taking their share price and converting or is it a complex process ?
Very interested in your response if you get a chance
Thanks
Re Boohoo (LON:BOO) listing on NASDAQ
Is there a currency effect on that?
With the markets closed (final data still to come in)...
I hit my all time high at about Tuesday, lets call it an index value of 1.046, closed @ 1.009 today.
So that means we (assuming my holdings are similar-ish to other people's) have a small retraction of about -3.7% in the past 2 days.
I think Rishi Sunak and The US Thanksgiving Turkey-massacre, plus obviously traders booking profits explain this. I would expect more softness tomorrow as US bank holiday festivities continue.
Next week, we will probably hear if The UK gets an EU trade deal.
All my shares down about 2 to 4% today on disinterested low conviction volumes, accept for Boohoo (LON:BOO) up 1% closing 300p.
I bet we're going to see higher prices in 4 to 5 weeks time as funds adjust portfolios for year end, dividends start to come on-stream, and the annual Santa effect adds fuel and oxygen to the market hell-fire.
I hit all time high today. Previous high was March :)
superb summary Paul on Boohoo-totally agree on Levenson appointment. The Press will think long and hard before writing anything that cannot be backed-up now.
Hi Paul,
If you are covering Tracsis (LON:TRCS) could you take a look at the adjustments around the acquisitions (last note in the accounts).
In particular, I see they capitalise technology intangibles on acquisition (as opposed to Goodwill). On the call with PI World they talked about how they need to attribute the purchase price.
For me this makes them look a lot better as acquirers than they actually are (smaller goodwill means ROCE ex goodwill is similar to ROCE including Goodwill.
Further, these intangibles are impaired (so reduce equity / capital employed) but not included in adjusted profit which further flatters the ROCE metric.
Maybe I should be more tolerant of adjustments (everyone is doing it after all) but with the lack of director ownership (other than share options with a 0.4p exercise price (also excluded!)) and a change in CFO imminent, my spidy senses are tingling.
In a previous life I remember a client making an acquisition of some disruptive technology company. During the audit, we suggested it is more appropriate to attribute the purchase price to IP / Software. Goodwill couldn't be justified because the company hadn't built any.
Many thanks - whether you cover or not - appreciate you sterling work and efforts.
Vivek
Boohoo (LON:BOO) Paul, are you not concerned about the Almadani lawsuit in the US for $100m. They are demanding customer refunds because they claim, BooHoo's discounts were fake.
Hi Zoiberg, Paul has previously commented on this with the following statement:
'I've asked Boohoo (LON:BOO) about this US legal case, and they said it's not a concern at all'
Boohoo (LON:BOO) - have had to jump on board the Boohoo bandwagon. The cash generation, growth (at least historically) and the runway speak for themselves.
The governance with PLT minority interest which along with valuation was the main thing putting me off historically has been resolved.
Management have skin in game and from what I can tell the short reports are not especially compelling and at times sound like rant from someone who has lost the argument.
From a stock rank perspective and maybe I am completely wrong in thinking this but if I see earnings momentum rising and share price momentum falling, it suggests a buying opportunity (being a fuddy duddy fundamental random walk kind of guy)
As for ESG being a barrier to prospective purchasers (and one for the behavioral scientists perhaps) - Is it not a lot easier to avoid a sector/company on ESG grounds when the share price is falling?
Now that Royal Dutch Shell (LON:RDSB) is up 40% - is it necessary for the transition to a renewable future / look at all the investments they are making in that space (versus it being a dirty carbon emitter 6 weeks back)?
With regard to Boohoo (LON:BOO) the first thing that put me off was the following report.
"Solicitors acting for Mr Womack said he had spent two years developing the Boohoo website, choosing the company's logo and deciding the "look and feel" of the site.
When the website launched at the Clothes Show Live in December 2006, the IT consultant also designed Boohoo's stand and helped collect contact details of initial interested customers, JMW solicitors said.
Mr Womack says a meeting was held at the company's office shortly afterwards, in which he was promised a 10% share in Boohoo.
But he claims the promise was never honoured and he has received "zero recognition" and not "a single penny" for two years of work"
He would have lost his case because there would no doubt be nothing on paper but without any evidence whatsoever I had the feeling it could be true. We then had the performance with PLT. Forget about working conditions that was enough for me.
I don't doubt that it may end up at £10 but I don't care. Best of luck to Paul and all Stockopedia investors with whom I certainly have no issue.
The main man I understand is very difficult to deal with in business, am sure Carol Kane does far more but M gets the credit. Outside of BOO I have had friends deal with him in Property and as an Angel and neither would repeat the experience so I don't doubt your story. That does not mean to say that he is not bright and knows the industry he clearly does just that the way he does business is not the way that my friends do. I still bought back in as I think it is cheap but understand why you would not want to
Agree with PLT it was an own goal to agree a deal with the owners son for the sale of PLT and then when it did well give him back a lot of the stock. Would they have done if that was a non family related business. If the son was so important they could have bought the whole business for £ 5 million or whatever the figure was and given the son options on some Boo shares -would have looked a lot less like looking after family members for a PLC. Having said all the above I have bought back in as I agree with Paul's comments and think it could 3 bag from here
Many Thanks for further intel. Paul. I have just added Boohoo (LON:BOO) to the portfolio. I've been sitting on the fence waiting for a while.
Here are my heat maps for today (prices as at 1:20pm).
I have made a number of changes to the format and rendering of the images to try to address the comments about illegibility.
To me, they are now legible on my Mac, laptop PC, desktop PC, and iPad Mini. On my iPhone the only way I could get them easily legible was by reducing the number of items shown on each heatmap to the point where they were valueless. Although they were still legible by pinch-zooming. So my apologies to any smartphone only subscribers.
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than the 20d EMA of ATR):
Big movers today in the SCVR world (moving more than 20d ATR EMA against either yesterdays close, or today's open):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many as part of my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria ('T': profitable, low-debt, reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the individual instruments further using the Stockopedia Stock Report.
How (or indeed if) you use the heatmaps is up to you, I contribute them here in the hope that others may also find them interesting or useful.
My apologies for any frustration that the legibility of the heatmap images has caused.
greensiax
[Edit: Changed the 'big movers' heatmap to filter to just small caps - this is the SCVR after all!)
Sir Brian Leveson's appointment is an amazing step. He was an excpetionally distinguished judge. I am sure he would not have undertaken the role if he had not satisfied himself first of the essential probity of £BOO. It is a powerful endorsement of the ethics of the company though I daresay there may be scope for imrpovement. BTW he may become but I think is not yet Lord Leveson.
Fantastic step and biggest news to me in the past 3 months for £BOO.
He was the Head of Queen's Bench Division of the High Court in Royal Courts of Justice in London and Head of Criminal Justice for years.
I have added to my position at the back of this news today.
Yes - de-risks things dramatically in my opinion. Also, likely to be seen as favourable to the new audit pitch so wouldn't be surprised to see one or two re-enter the tender.
I originally bought at 40p and sold at 160p and bought back recently at 270p, though in med/low size due to risks around reputation and audit. Now considering adding more as well.
Paul, do you have any thoughts on Morse Ord (LON:MOR) recent rise and today's RNS and extension of results - I know you don't like these types of lenders?
did you mean to tag £MCL. Morses Club (LON:MCL) ?
I did, Antehelion, thank you.
Not sure there is much to say on Morse Ord (LON:MOR) catalogue. The share were marked down heavily and drifted on the previous news of a delay to accounts. Investors were fretting about why auditors were struggling to sign off the accounts and what it meant for write downs etc. I see the rise in last couple of days as a relief rally on the news that they are about to be published and that interims will follow within a month. Some investors will now be positioning for the potential of a large rise should the account show no gremlins.
Interestingly for Morse Ord (LON:MOR) the general read across from other sub prime lender collections hasn't been as bad as feared so I suspect that's why you have a more bullish tinge now the results have a date.
I am long from much higher but in a small low conviction position / income play. Actually had rather forgotten I'd kept them so marks down for me as I should have sold ages ago!! At current prices I am inclined to keep them tho
Re Morses Club (LON:MCL)
Interesting comments, David.
I'm over-over-over-weight on International Personal Finance (LON:IPF), who have also survived the crisis.
Morses Club (LON:MCL) seems quite similarly positioned, share price rise. I picked International Personal Finance (LON:IPF) purely because of it having good StockRank metrics. I'd say you have some upside to come.
Agreed that both are likely to do well in the near future - I prefer the debt, ROE(etc) and dividend levels showing in stockopedia for Morses Club (LON:MCL) (15% yield forecasted for next year, well covered - if we can believe the analysts) but International Personal Finance (LON:IPF) does seem to have retained higher momentum recently - I think perhaps due to the question marks over the late accounts at Morses Club (LON:MCL) as covered on here in other comments.
We'll see what happens with £MCL in the next couple of days I guess - fingers crossed for all holders.
Bull run is temporarily interrupted.
My temporary membership of the special club ;) is about to be revoked, with Security about to guide me through the kitchens door ;)
However, it was never going to be anything other thus.
I'm holding, no changes, because I think The Markets / Santa / company valuation / return to profits / Q.E. / Biden / Brexit / The 3 wise vaccines have more to give.
I have my eyes on Saga (LON:SAGA), falling back, and as dear Paul said, its going to be a one to two year journey.
Tracsis (LON:TRCS)
I have this share on my watchlist - results look ok - its the first time i have looked at the company in slighty more detail. It seems like a quality operator at what they do - so they do deserve a somewhat premium rating i think . Looking at the news today i can't see a trigger to make me press the buy button though.
As we look to the remainder of the financial year, we are aspiring to achieve modest revenue growth and EBITDA margin improvement despite the ongoing challenges of Covid-19, and we expect our cash position to remain equally as strong.
We are confident that the medium to long term growth prospects for all parts of the Group are unchanged and we therefore remain committed to our overall strategic growth and investment plans.
In defence of the company growth plans it looks like transactional volume related income has taken a hit for covid reasons - if we take the viewpoint these items will bounce back - it would seem there is a path back to growth quikcly perhaps? - i will default to the cautgious outlook at present though.
My one slight niggling worry is the prospect of semi nationalisation with regard to rail franchises - is it possible they could lose out here if customers hand back franchises to one single agency? It seems they are very rail centric = although thats probably their niche that they are good at but with such a single niche are they at risk due to curcumstances beyond their control.
Overall thumbs up ref what they do but possibly something below 500p would be my hoped for bargain entry point at present. Sometimes quality companies simply don;t come on the cheap though - hey ho.
Morning Paul and Jack,
If you have time to look into First Property (LON:FPO) I would greatly appreciate your views. Interesting little company and a possible recovery play. Cashed up and ready to make new investments, and current investments appear to be performing well. Strangely, no update on rent collection today in the interims
Cheers,
pkr1988
Hi pkr1988
I was looking at £FPO
However the level of remuneration that Mr Habib (CEO ) has been taking over the last 5 years has amounted to over £1million a year , to me this seems rather excessive for a company with a market cap of less than £50m (just over 2% of current market cap !!! )
During this time share price has not done much (I appreciate dividends have been paid ) to me this is looking increasing like a 'lifestyle' company .
Sorry was not able to make the First Property (LON:FPO) blue.
Tony
very true Tony. I think it looks exceptionally cheap so willing to look past the remuneration for now. Might rule it out as a long term holding though
May I also request Newriver Reit (LON:NRR) please? Resumption of dividend; historical yield is 19.6% on current price. As a reit it has to pay a certain amount;
"The Company is a member of the REIT regime whereby profits from its UK property rental business are tax exempt. The REIT regime only applies to certain property-related profits and has several criteria which have to be met, including that at least 90% of our profit from the property rental business must be paid as dividends. We intend to continue as a REIT for the foreseeable future".
Incidentally, Newriver Reit (LON:NRR) has had a good run recently but nothing compared to one of Paul's favs Revolution Bars (LON:RBG) ...this one has now trebled since the beginning of this month. Not such a disaster after all. Just shows the possibilities for hospitality stocks as and when the vaccines are actually distributed I think.
The issue for me is the REIT status. If it has to distribute all its income then how will it grow? Presumably only by borrowing money and building / buying more sites? Aren't you better off with Capital & Counties Properties (LON:CAPC) or other that does not have to distribute all its earnings - which can be tax inefficient if you are a higher rate taxpayer.
It can grow from recycling assets, capital purchases funded from debt/equity, rent increases or, in the case of its own pubs portfolio, growth of revenue/margins etc.
REITs are all about income so if you are a retail investor and higher tax payer and the REIT isn't sheltered in your ISA then yes, it's a drag on performance. Mine are sat in my ISA waiting for my 15-20% tax free income p/a once normality takes hold or a capital gain on uplift back towards NAV.
I was waiting for these results to see if management had done what they said they would in their investor presentations back in April and I'm pleased to see they have. This gives me a much increased confidence in the position and adds a layer of credibility to the mgmt rather than just my own take based on their presenting skills!!
David if revenue grows 90% of the resulting profit has to be distributed, Thats my point. I can see a REIT in an income portfolio but not a growth one.
NewRiver (NRR) half year results today show good cash position and headroom on covenants. LTV went up only slightly to 48%. Dividend likely for the full year despite the lockdowns. The affordability of their retail property remains the mainstay to more leasing activity and good occupancy.
Needs the market to give up the Broad Brush and use a Toothbrush!
"FDA emergency use authorisation of COVID-SeroKlir, a quantitative SARS-CoV-2 IgG antibody test kit. EKF has exclusive rights to market and distribute this product in the UK and Germany and non-exclusive rights in Europe.
Its partner in this venture is Kantaro Biosciences. COVID-SeroKlir is a high-performance semi-quantitative antibody test kit (demonstrating 98.8% sensitivity and 99.6% specificity for detecting SARS-CoV-2 specific IgG antibodies against two virus antigens), ‘with a broad range of applications in the fight against COVID-19’."
During the weekend I heard this excellent podcast - https://www.voxmarkets.co.uk/a... at 21min. 42 sec, Christopher Mills of Harwood Capital was discussing favourably regarding Ekf Diagnostics Holdings (LON:EKF) (he would do given that he is an investor!). Mr Mills mentions that regarding Covid-SeroKlir kit, this could potentially be a game changer given that it is the FIRST antibody test that actually gives you a measurement of the antibodies that you have remaining in your body. Thus, whilst you may have a vaccination - how do you know how long the antibodies will last for? The answer lies with Covid SeroKlir which can accurately measure them.
Now Kantaro is a JV between Mount Sinai Hospital of New York and Renalytix Ai (LON:RENX) (I hold) . Renalytix Ai (LON:RENX) is entitled to 10% royalties. So £RENX's hard work has literally been done, and any Covid SeroKlir sold gets them 10%.
Based on www.fool.com/amp/earnings/call-transcripts/2020/08/04/bio-techne-corp-tech-q4-2020-earnings-call-transcr/ Bio-Techne Corporation (NASDAQ: TECH), is the manufacturer of Covid SeroKlir wants to sell it more than $42 per kit. Assuming $40 per kit, Renalytix Ai (LON:RENX) 's royalty is $4 per kit. Per 1 million kits on mass roll out = $4 mn all bottom line for Renalytix Ai (LON:RENX) . I think you can do the maths if this ends up being a 10mn a month seller !
Covid SeroKlir can be used after vaccination and even before vaccination to determine whether you already have antibodies and if so how many you have.
As Jack mentioned in the write up of Ekf Diagnostics Holdings (LON:EKF) , Ekf Diagnostics Holdings (LON:EKF) who has been appointed the distributor of the Covid SeroKlir in certain jurisdictions, FDA Emergency Use Authorisation was granted for Covid SeroKlir. It claims to be best in its class.
Strange that the RNS went to Ekf Diagnostics Holdings (LON:EKF) and not to Renalytix Ai (LON:RENX) as well - https://www.investegate.co.uk/...
CNBC released - https://www.cnbc.com/2020/11/2...
Further info -https://www.dailymail.co.uk/he...
An extract below from the CNBC article shows why this could be the gold standard for quantifiable antibody test :
"Kantaro said the test has demonstrated 98.8% sensitivity and 99.6% specificity for detecting Covid-19 antibodies against two virus antigens, the full-length spike protein and its receptor-binding domain, two key elements of this virus. That means 98.8% of all positive diagnoses are accurate and 99.6% of all negative diagnoses are correct." Also, note that Covid SeroKlir was tested on 75,000 patients in Mt Sinai hospital.
I did not think too much about this kit previously until it dawned on me that even when we get a vaccination, we need some way of determining exactly when we will need another vaccination. Perhaps when we get the vaccination, our antibodies' level vary from person to person (?). Hence we will need a quantifiable and accurate way of measuring our antibodies. Here's is where Covid SeroKlir. Therefore,, post vaccine, there clearly is a significant part for Covid SeroKlir to play. This ultimately means Renalytix Ai (LON:RENX) is a beneficiary if Covid SeroKlir is selected by US states and national governments as the preferred antibody test due to its ability to measure accurately your antibodies.
In addition, for Renalytix Ai (LON:RENX) , the crux of their business is actually not covid kits but their brilliant AI platform KidneyIntelx . KidneyIntelx allows for early stage identification of Chronic Kidney Disease (CKD). Either in 2018 / 2019 , KidneyIntelx was already granted FDA breakthrough device designation. It is currently in the process of seeking for full FDA clearance (I believe recently applied). From my understanding, FDA clearance of a device is far more simpler than FDA approval of drugs. Thus, Covid SeroKlir was initially the icing on the cake, now, can be a very big piece of icing!
Renalytix Ai (LON:RENX) is one of those, not much revenue, but it's got $83mn (so loads of runway!!!) after this summer's NASDAQ listing. Absolutely fascinating company. If Covid SeroKlir takes off, I think its SP will fly.
Today, I noticed a lot of selling. I think these sellers are probably not aware of the hidden potential of Covid SeroKlir.
Usual caveats, Dyor
As I understand it, Antibodies are a fleeting indication of you ability to fight off C19. After 3-4 months they will be unmeasurable. While I can see a use for SeroKlir during development of vaccines, I doubt there is a long term use. Something that measures the long term T cells or B cells may be of more importance. Nobody measures the variable protection the flu vaccine provides despite is being an annual killer.
I am not a doctor, I rather rely on what doctors say. Per https://edition.cnn.com/2020/1...
In particular - Dr. Amesh Adalja, senior scholar at the Johns Hopkins University Center for Health Security says, "I also think that becomes important when we think about the vaccine, because we will often sometimes vaccinate someone and will want to know the levels of antibody that are generated and then follow those people over time to understand what the interval might be for boosting them," Adalja said. "So if the antibodies fall below a certain level after three years, then you can get a booster at three years."
Yes, me neither. Maybe vaccine antibodies are different to naturally acquired ones? Who knows?
"antibody levels rose to a peak at 24 days after the first positive PCR test, before beginning to fall. Those tested had lost their positive antibody result after an average of 137 days."
https://oxfordbrc.nihr.ac.uk/c...
Hence reinforcing the need/critical role for constant monitoring, from now until we find a genuine breakthrough that can provide long term immunity (if ever!). Meanwhile, this is the best that we have in respect of antibodies testing.
I have long speculated whether bio monitoring in something similar to a Smart Heart Rate Monitor watch could detect these bio-hazards?
Yes, me neither. Maybe vaccine antibodies are different to naturally acquired ones? Who knows?
Well, they're the same antibodies, the immune system doesn't differentiate between where the disease comes from. However, naturally acquired antibodies usually give better protection at the potential risk of giving you a much nastier does of the disease. A vaccine aims to trade off the minimum exposure to the disease for the maximum protection so dosages are usually lower. However, there are a few cases where vaccine provides a better immune response - HPV for instance.
The short-term need for testing is quite high, mass deployment of vaccines is still months away and we're quite a long way away from knowing how long immunity lasts and whether antibodies are a useful indicator. Longer term the need for mass antibody testing will probably drop, as we get into a pattern of vaccination.
But there will probably be a long term need for antigen testing - for instance, if you get flu like symptoms you'd want (need) to know whether you have flu or CV19. A lot will depend on the effectiveness of the vaccines in the field, the take up in the population and how long lasting immunity is.
timarr
Paul, if not much on today did you see Mothercare (LON:MTC) is emerging from another restructuring? Managing the brand for lots of overseas franchises and Boots in the UK. Perhaps Woolworths next?
On a fairly quiet day I have a question for Paul and the rest of the Stocko team. IFRS 16 (which is nonsense in my view) has completely messed up some of the Cashflow metrics on this site for many companies (Free Cash Flow in particular). Some companies now look ridiculously cheap on a Price / FCF basis but this simply reflects that Rent is not being captured as an expense within Free Cash Flow but instead is being treated like a form of debt lower down the Cash Flow Statement. So, the P/FCF metrics in my view are now off for many companies. Are the Stocko team able to do anything to address this? Many companies now have a huge jump up in FCF in the last 12 months or so simply because of this accounting nonsense.
where is the report on De La Rue (LON:DLAR)? We had the results yesterday but no report I can find?
Indeed I bought into what I had hoped would be a rise, I'm sure this will do well, this months Momentum Investor pick, its annoying that you loose out on a better buying price for the sake of a few days delay, don't buy and of course they rocket !
Give Paul a chance mort1980, he covers so much ground a day, it's a wonder how he consistently does it. I am more than happy if he misses the odd one he intended on doing at the start of the day, and I hold DLAR
I don't understand the reason for these many thumbs down. I asked where is the report because I couldnt find one despite the results yesterday. What did I say about Paul at all? I'm just shocked...
mort1980.
It was because of the way you (perhaps unintentionally) seemed to demand that Paul should update on De La Rue (LON:DLAR). It’s inevitable sometimes that he won’t be able to fit them all in.
Just look at the depth and quality of his reports. That research takes ages. Then the writing of each one takes a lot more time. It takes up much of his day and I don know how he manages to do it so well day after day, and to find time to add further comments in replies here too.
So if anyone seems to take his hard work for granted or gets angry with him for not updating on a share he hoped to, they are likely to get a lot of thumbs down.
Also it is worth checking posts here about DLAR. Had you done that you’ll have seen there have been at leat a couple of polite requests for a DLAR update. I’m hoping he will too as I hold DLAR but won’t be upset if he doesn’t find the time.
I think you will also have thumbs down because you didn't bother to read what Paul wrote yesterday:
" I'm going to print off the results for DLAR, and review them on the train home to Bou'mth.
I have to leave it there for now, but should be able to finish off the section on DLAR late afternoon (or worst case, tomorrow)".
(Edit - herbie47 beat me to it)
Possible it should be taken out of the title as it has not been covered.
It's quite frustrating to click on a link expecting to read something that is not there.
BSV
Paul did say yesterday "I have to leave it there for now, but should be able to finish off the section on DLAR late afternoon (or worst case, tomorrow)."
Paul,
you know I had nothing but to do with critising you (not even passed my mind!)
we are indeed friends!
i confess I hadn't read the full report yesterday. So that seems to be the problem, but I would suggest people could drop a line saying the last bit of yesterday's report instead of thumbs down, like one did below.
cheers.
Interesting narrative from The Times that the Government is in talks with De La Rue (LON:DLAR) over the supply of coronavirus "immunity certificates" and authenticating vaccines.
I think this was first mooted in the weekend press, so is slightly old news. (and doesn't seem to have done much for the SP sadly !).
DX (Group) (LON:DX.) gave a "materially better than .... expectations" update in the AGM Statement this morning.
https://www.investegate.co.uk/...
The current consensus forecast is 0.85p EPS. If, say, "materially better" is +20%, that takes it up to 1.02p. Consensus EPS for 2022 is currently 1.57p, say that now gets upgraded to 1.65p. At 23.5p per share, that would put the business on a forward PE ratio of 14 and a PEG ratio of 0.23.
The now not so new management team here is delivering rapidly and highly motivated to continue to do so, with their substantial share-based incentives maximising at 40p per share. In spite of already having meaningful equity commitments, management have continued to back themselves by buying in the market, with directors, NEDs and PDMRs having spent almost £600k in that way since May 2018.
So this was on a list of items to research and I got round to it yesterday and really liked what I saw, although with the adjustments and what not, it was pretty hard to get a handle on valuation (I prefer cash flow metrics to EPS). I dare say, had it not been up 6% yesterday, I would have initiated a starter position - as it turns out, I had to do it today a further 8% higher!
For me - operating momentum, substantial capacity expansion & efficiency investments. Seems a structural growth sector and the awkward sizes/ultra fast service have some moaty characteristics (assuming the oversize baggage at airport is separated for a reason).
Any holders of Paypoint (LON:PAY) - I would be interested in Paul's views on today's half year results.
Yes, Paypoint (LON:PAY) and also Newriver Reit (LON:NRR) .
Paypoint pls
Paypoint (LON:PAY) pls!
I sat in on the investor webcast.
I see this business having one of the most defensible moats around.
The PP terminal is a must have for UK c-store owners as it enables vital services that drive traffic to the shop including bill payments, parcel collections etc
They are successfully adding other services from their installed base of c. 80% of UK c-stores including card payments, ATMs, epos services etc
The c-store sector is thriving on the back of the trend to more local shopping and covid has accelerated this
Margins and ROCE, ROE are exceptional
They are solid dividend payers
The issue is growth and the vulnerabilty of the cash payments business which is a big chunk (there are still millions of people who pay for certain services in cash eg gas/electricity and rely on PP to do this but the segment is in decline. The loss of the British Gas contract knocked a big chunk of profits and that has depressed the share price. I'm not sure if they are vulnerable to others doing the same.
If they could protect this profit stream or manage a careful decline, the other services are all on high growth and so there would be growth plus very high cash conversion into profits/dividends
Anyone got any views on this ?
Great summary Steve
I don't hold but like Paypoint (LON:PAY) great business, solid, great moat as you say.
Who says cash is dead, if you listen to De La Rue (LON:DLAR) they will tell you cash is alive and kicking.
Personally (my opinion), I think PAY's end users... i.e. the punters in c stores are of the poorer variety and unfortunately this strata of society isn't going to disappear any time soon. And, with people going to be around home more, of course convenience is going to play an increasing role in the retail sector.
I really like their two acquisitions of card processors... payments is an area which is consolidating. I think the sale of the Romanian assets was a shrewd move, consolidate and diversify more into payments which counterbalances the short term dip in cash processing.
Although profits are down due to the loss of a major contract, they are still generating lots of cash, cash is up and debt is down.
I think the recent acquisitions will be cash generative.
Great div payers as well, which will attract buyers.
I disagree about cash, I have hardly any used this year, think I have been to the ATM once since March and still not spend that money, now virtually everything I buy is by contactless credit cards. I think many others will be doing the same. Once you get into the habit I don't see people switching back to cash to pay shops and pubs etc. Before the lockdown I rarely used contactless cards.
But PayPoint (LON:PAY) does a lot of electronic payments, unless I have misunderstood what they do?
Herbie, I like you have hardly touched an ATM for months, but Greenhat wasn't talking about the likes of you or I. He was referring to the LON:PAY customer base and I don't think that is going away any time soon. I also hold - current loss but am not selling
This is dependent on income, Herbie. When lockdown started, I went entirely cashless with little effect on my day to day life (the only merchant in my personal life who continues to only accept cash is my barber who obviously has solid ahmm ahmm "tax reasons" for doing so - I ended up switching after going there for 10 years). I expected this would be universal but when I looked at the figures from convenience stores in September it was really stark - those in the richer areas showed a change from about 60% cash to around 20% cash, those in poorer areas went from around 80% cash to around 75% cash - almost no change.
The reality is that Paypoint (LON:PAY) customers are lower income and cash will remain important here for foreseeable future
I understand your points but Paypoint are not just in poor areas, I checked out their locations in my area, so it follows that their use will fall? I just feel the trend to cashless payments will continue. I also got stuck once, behind someone in the queue, paying a bill, it took ages, I don't know why people would choose to pay in that way.
those in the richer areas showed a change from about 60% cash to around 20% cash, those in poorer areas went from around 80% cash to around 75% cash - almost no change.
I guess those that get paid cash in hand or receive cash from illegal gains are forced to pay with cash wherever posible :)
More or less anyone who goes into a c-store touches PayPoint in some way. Affluent folk are more likely to pay by card or collect a parcel, poorer folk without a bank account or credit card have to use PayPoint to pay for gasy/electricity and other stuff including TV licence etc . PayPoint make a margin on all of those transactions whereas the former are all in high growth, the latter are in decline, albeit not disappearing any time soon.
Another issue for Paypoint (LON:PAY) is they are under investigation by Ofgem for alleged breaches of the Competition Act between 2009 and 2018. I hold at a current loss, but I'm not selling.
When this investigation clears the sp might get a bounce - that’s why I’m watching closely
Renalytix Ai (LON:RENX) had great news yesterday afternoon regarding FDA EUA antibody diagnostic kit that actually gives a measurement of the antibodies - which could be a gamechanger. Renalytix Ai (LON:RENX) is listed on both NASDAQ and on AIM. Does anyone know why Nasdaq's SP jumped 31% circa whilst on AIM it jumped circa 11%. Then this morning on AIM the SP was still the same price as the close price yesterday (of AIM). Is this not an arbitrage opp? I'm a bit perplexed!
Re Renalytix Ai (LON:RENX) - RNLX (Nasdaq) closed at $14.08 (which using a $1.335 fx rate) equates to £5.27 per ord. The ord is trading below this at £5 - but since the NY close, the stock has had to absorb the placing by EKF at £4.60. So I don’t see any obvious mispricing.
Thanks.
Hi Wimble. Hoping you aren't a maths teacher as $14.08 using $1.335 fx rate = £10.54. or have I missed something?
Gari
Two ords = 1 ADR for Renalytix Ai (LON:RENX) - so you need to divide the £10.54 by 2.
Generally there will never be an arbitrage opportunity (for a human) between an ord and an ADR (assuming there is full convertibility), as the computers will exploit any minimal mispricing there is (at least in overlapping hours). ADRs on UK stocks will generally trade between parity and a 1.5% premium (because of the SDRT tax needed to be paid to convert an ord into an ADR).
The long standing exception to this rule for many years was Ryanair - where the ADR could trade for long periods at a 20-30% premium to the ord in Dublin or London. The reason for this was that the ord was not convertible into the ADR, as otherwise Ryanair risked breaching the non-European ownership limits for a European airline.
thanks.
As a Goco (LON:GOCO) holder it would be interesting to get your thoughts on yesterday's seemingly odd bid for Goco (LON:GOCO) by Future (LON:FUTR)
By chance - there was a webinar just yesterday with Mark Slater talking about his UK Growth fund - with Future being the largest holding - he extolled the virtues of this company but at that time knew nothing of this deal...!
can you share the link to the webinar?
Its here. : Future are discussed in the last minute or so
Thanks behenie, hadnt heard this interview.
Hi Becks - Dont think this is the one - its a Sept Money Week interview - but I am referring to a webinar he gave just yesterday afternoon - for investors in the Fund - and I'm afraid I cannot find a link ....
Just obtained it from slater
https://drive.google.com/file/d/10Z3BubPB7f2mGD8fV1nySloclSaeqC3q/view?usp=sharing
Tracsis (LON:TRCS) FY20 results today, here's an overview by the CEO & CFO video and podcast. Rail Technology & Services division outperformed, unaffected by CV19, offset by Traffic & Data Services which was hit by CV19. Q1 inline with board's expectations, with two major rail contracts in latter stages of negotiation. Renewal and extension of several large multi-year agreements for Traffic Data & Events contracts, and all software licence renewals secured. Outlook Rail and Technology & Services division very strong demand and lots of opportunities. In the Traffic and Data Services Division, with Events and Traffic Data businesses they are closely monitoring. As soon as the latter comes back on stream, they should be motoring.
There's a Tracsis (LON:TRCS) presentation by Chris Barnes, CEO & Max Cawthra, CFO at 1pm today (26.11.20). Register here.
Other results presentations forthcoming over the next couple of weeks:
Panoply Holdings (LON:TPX) H1 20 results: Monday 30th November, 12 noon. Register here.
Sosandar (LON:SOS) H1 results webinar: Tuesday 1st December, 12 noon Register here.
Creightons (LON:CRL) H1 results webinar: Wednesday 9th December, 2pm. Register here.
Hi Tamzin - I think your PI World series is excellent and gives a lot of insight to PIs like myself. Don't know if you do took requests, but if you do, would you mind perhaps looking to interview someone from Loopup (LON:LOOP) as I think there's considerable interest on these boards (Paul's invested too from what I remember).
Totally understand if this isn't how it works and you can't! :)
Many thanks,
PJ
I assume there's an element of ''pay to play'' in these - often interesting - podcasts. Can anyone confirm or otherwise please?
Good morning all. I notice that we didn't get your thoughts on DLAR yesterday, Paul. Will you be playing catch-up today, please? They are on my 'next to buy' list so I would welcome your views.
Of interest today is NRR which, I hold. This looks bombed out but there are signs of life and I reckon this could be a very profitable recovery stock from here. I have been adding at these distressed levels.
I know Aviva is well outside your brief, but the announcement today of a resumption of dividends and the confirmation of the business plan going forward looks positive for investors. FWIW I think the market will like it, especially the promise of a return of surplus capital. The new management is certainly getting to grips with things by the looks of it.
I have Newriver Reit (LON:NRR) as a significant holding in my portfolio and I posted elsewhere after the full year results with my rationale which at the time was very much a minority view. My takeaways from todays analyst call are:
- Positive cash position driven by disposals ahead of target (£82m 31/3 > £140m 30/9)
- Disposals FY21 now at top end of previous guidance
- Pubs profitable within 8 weeks of end of national lockdown 1 and good performance against sector
- Leasing activity well up on FY20
- Helpful segmentation of the portfolio aiding understanding of alternate use valuations (slide 25 and 30) which are reassuring
- No additional information on basis of FY21 covered dividend in Q&A but clearly underpins the management’s confidence and I sensed they are ready for ongoing Covid disruption
The shares have recovered from the lows I believe as the likelihood of a rights issue or cash call are receding and LTV target 40% seems to be realistic. I remain bullish.
With regard to Aviva 7p int divi to be paid Jan, 14p final in June and at least 7p int to follow in Oct/Nov? That's 28p next year for £3.25 a pop at today's price. 8.5% isn't to be sniffed at all things being equal.
My morning smallcap tweet: Monkeys at typewriter at Gibbons?
Atlas Mara (LON:ATMA) Boohoo (LON:BOO) Remote Monitored Systems (LON:RMS) EKF Diagnostics Holdings (LON:EKF) Shoe Zone (LON:SHOE) Actual Experience (LON:ACT) Norman Broadbent (LON:NBB) Chrysalis VCT (LON:CYS) Tracsis (LON:TRCS) Stanley Gibbons (LON:SGI), Pebble (LON:PEBB), Tclarke (LON:CTO), XPS Pensions (LON:XPS)
Atlas Mara (ATMA) agrees sale of its banking assets in Rwanda and Tanzania for a price determined by a book value formula. [SP=0.33 Cap=62m]
boohoo (BOO) Sir Brian Leveson will oversee Agenda for Change programme and will report directly to the Board and his reports will be published. [SP=291 Cap=3670m]. I hold.
Remote Monitored Systems (RMS) delivery and installation of its new anti-viral mask production line delayed. Commercial production and shipment of product is now expected to begin in Jan. [SP=2.6 Cap=41m]
EKF Diagnostics (EKF) sale of shares in Renalytix AI for £7.705m and a profit of over £5.6m. [SP=60.5 Cap=275m]
Shoe Zone (SHOE) delays finals to 8 Mar. Guides £12m hit from England lockdown. "The very late lockdown in certain areas of Scotland and all of Northern Ireland has further exacerbated the impact on our pre-Christmas trading...It is very difficult at this stage to provide any further meaningful guidance on the future outlook, given the material uncertainty in the wider economy." [SP=61.5 Cap=31m]
Actual Experience (ACT) wins order for recently launched Human Experience Management offering. It will analyse the digital experience of 10,000 home and office-based employees for one month. No £££. [SP=72.28 Cap=34m]
Norman Broadbent (NBB) seems almost boastful to get a few scraps of funding: £250k CBILS and extra £1.5m invoice financing. "he new invoice discounting facility will greatly improve liquidity and help fuel further growth." [SP=4 Cap=2m]
Chrysalis VCT (CYS) suspended pending shareholder vote on winding up. [SP=22 Cap=6m]
Tracsis (TRCS) FY(July) rev as per trading stmt. Pretax £4.1m (£6.6m). Q1 trading in line. [SP=580 Cap=169m]
Stanley Gibbons (SGI) H1(Sep) rev-cont down 26%, pretax-cont -£2.2m (-£0.66m). Vague essay of an outlook. "There are encouraging signs recently that will hopefully allow me to report that our rebuilding plans are back on track next year...This would be the first time in several years where we would [can?] be able to say that we had neither increased borrowing or heavily discounted some of our best inventory, while also continuing to invest in the future rather than diminishing our long-term prospects." [SP=4.05 Cap=17m]
In line: Pebble (LON:PEBB) Tclarke (LON:CTO) XPS Pensions (LON:XPS)
If anyone interested in Atlas Mara, I published this in July. https://brucepackard.com/remor...
Another great announcement from EKF. Just doubled my holdings
It seems you were correct that it was too soon to go with the 90% effectiveness number for the Astra Zeneca vaccine Mr C. Not good that they seem to have announced those preliminary results based on a small sample size.
Some additional complexities - there were two groups, one given two regular doses and another one half dose then a full dose. Also the second group was limited to age < 55.
So not sure AZ vaccine will get fast tracked then.
Yes JW, I noticed that. How strange and underwhelming that AZ and Oxford chose to not test on those aged 55+. Doesn’t look good for fast tracking, doesn’t look good for Matt Hancock personally pushing U.K. to buy so much of it.
What is crazy about Astrazeneca (LON:AZN) is the lack of profit motive. I hold!
Yes, I find that weird.
It seems the profit motive has helped AZ’s two competitors produce more effective vaccines with better proof of efficacy and safety.
What ‘better’ proof of safety? What is the evidence that the profit motive has effected the outcome rather than other factors?
Martin am surprised you got thumbs down. For me the profit motive is what would drive companies to find a vaccine.
It was done by accident was it not? If so, it wasn’t a choice.
Has Hancock ‘personally’ pushed for this particular vaccine? Is there a reference for that? And even if he did advocate for this vaccine is there a reference that demonstrates that he did so knowing about the error in dose level?
There seems to be nothing to suggest the vaccine will not be as successful as reported, just that further trials are required.
"In a statement on Wednesday, Oxford University said that some of the vials did not have the right vaccine concentration, which led to a few of the volunteers receiving a half dose. The university also said it had spoken to regulators, and decided to complete the late-stage trial with two groups. The manufacturing was corrected, AP reported, citing a statement.
“The reason we had the half-dose is serendipity,” said the head of AstraZeneca’s non-oncology research and development, Mene Pangalos"
So a few received a half dose and there is a comment that this was serendipity presumably because they think they have found the initial half dose has likely advantages. I like to be positive rather than negative. I expect this to be successful just as I do with all of my investments and everything else I do in life even if my anticipated win on the lottery hasn't quite happened yet!
Indeed - I believe the overconfidence bias is one of the most prevalent in investing. Not once have I bought a stock thinking - aah this may work, it may not!!
Did he not arrange to buy it many months ago along with various other vaccines being developed.
Exactly, the government, having taken advice from the scientists on the relevant advisory groups arranged to buy several different vaccines. That’s a long way from Hancock specifically pushing this particular vaccine as was stated in the earlier post.
I’m completely happy to adjust my view of what has happened if there is evidence to support that. What I am challenging is assertions that have been made that appear to be sweeping statements without supporting evidence.
Sorry I can’t remember where I read it, possibly Guido, but it was clearly stated that Hancock pushed for three times the amount of AZ advised by civil service/public health (presumably in an effort to spread risk evenly between potential vaccines).
Fair enough, Martin, but I expect that Guido is a somewhat biased commentator. Don’t read it myself.
It could be that the decision was made partly on the basis of, if all the vaccines look equally promising, double up on the cheaper one. I don’t know and don’t really care. My feeling is that if the regulators examine all the data and say it is both safe and effective then that’s great. If it turns out there is enough evidence to go with a lower dose that’s great too.
So not sure AZ vaccine will get fast tracked then.
From memory the original threshold for success was set at something around the 60% mark - so although the overall results are disappointing compared to other competing products if they have proved 70% success (+) and were originally aiming to exceed 60% then it is still job done as far as meeting goal of proving it is up to the 60% level necessary to be rolled out - it does raise additional complex questions though as to whether its better to wait a while and provide something that works to 90%+ of the time or dish out something now that works 70-90% of the time - i guess they may have to make a judgment call which may not turn out to be the best solution when they review the data in a year or two's time - as its all guesswork really anyway i don't see how we can avoid that issue. Not great that they have bungled the newsflow release but in the scheme of things at least it does appear to work and it may work better than 70% if we are lucky. Ref the disrepancy on doses success and talk of finding sweetspots - this does seem to be slightly strange - if they are now talking about finding right dose level and that does make a difference i would semi have expected they would have used different dose levels from the starts - so thats all still a bit unexplained whether it is the dose levels that matter or whether its more down to the lack of over 55's in the better performing group - i know which of the two reasons i would default to as being the reason for higher success in lower dose group and its not the dose level solution.
From memory the original threshold for success was set at something around the 60% mark
50%, in fact. If the Oxford vaccine is 90%+ effective in under 55's then the obvious thing to do is to give it to under 55's while reserving the other, more difficult to store, vaccines for the over 55's.
In the end vaccines serve two purposes - they decrease the probability of an individual catching the disease but they may also reduce the effective R rate of the disease because less people will get ill if infected. A 70% effective vaccine needs 75% population take-up to achieve herd immunity and the lower the efficiency the higher the take-up required. However, that assumes that someone who's been vaccinated is less infectious if they catch the disease - which is likely, given the way other vaccines work, but not yet guaranteed.
The problem here is that the announcement appears to have been deliberately skewed to put the best spin on the data, which isn't likely to impress the regulators, especially as they don't really understand why the lower dosage regime works. Given that's previously unseen Occam's Razor suggests the most likely answer is just that it works better in younger people. They really should have made that clear up front.
But until we have the long term results of mass vaccination programs we won't really know how effective the vaccines are. The critical points so far is that they are effective, to a good level, at blocking the disease and the side-effects are minimal. At this point that's exceeding expectations and is an extraordinary achievement.
timarr
The sample size was fine, it was not a representative sample of the whole age range. Abysmal that they didn't reveal this.
Some reports suggest that they discussed it with the regulators at the time, so, if true, it was revealed at that time. However, it should have been included in the information released to the press as well.
Overall, it probably would have been much better to put much more emphasis on the two full dose results and play down the other result.
As an Oxford trial vaccine recipient, the sample age groups certainly cover the over 55s. My group is in the 55-70 year age group, and there is an over 70 year age group. I don’t know whether I’ve had the real vaccine or the placebo vaccine, but the trial is being run brilliantly and safely and across a range of age groups. I cannot praise them more highly.
Thanks Mr C - I find the description for Stanley Gibbons (LON:SGI) as ‘vague essay of an outlook’ very helpful on your part, and disappointing on theirs!
"Monkeys at typewriter at Gibbons?"
Absolutely brilliant! Thanks for cheering my morning up and thanks for the reports, as always.
Well that’s made my morning (easily pleased), £Boo have appointed Sir Brian Levenson to oversee their change programme and KPMG to support its work (along with their existing specialist supply chain auditors). His reports will be published.
This is excellent news because these very high profile appointments will help change the mood music for the institutional investors and MSM. More importantly, it demonstrates that the Board has realised, and committed to, the need to address these issues permanently.
So now, hopefully the focus will move to their excellent growth performance!
Good timing. Particularly good is this bit “will help us on our journey to lead the fashion e-commerce market globally''
The news of KPMG supporting the change programme at £boo is exceptional news.
For me this proves that KPMG stepping down as auditor is in fact a storm in a teacup - they can' t audit plus also be involved in advisory services -due to conflict of interest legal regs.
The fact that they are choosing to be part of the team that will ultimately be audited by another third party proves that they are happy there are no skeletons in the cupboard that may be uncovered at future audits.
We just need the market to catch on to this....
Re £BOO I guess I'm in a contrary mood today but needing a former President of the Queen's Bench and Head of Criminal Justice to sort out your supply chain isn't high on my usual checklist of positive reasons for investing in a company. I hope he does a beter job than he did in the Press Inquiry.
Doesn't it provide some pretty bullet proof protection from a lawsuit / audit - be a brave prosecutor / auditor who challenges the former President of the Queen's Bench and Head of Criminal Justice?
Would be highly appreciative if you could cast your expert eyes on Aviva (LON:AV.) third quarter results please.
Is Aviva a small cap now?
Aviva (LON:AV.)
I would say it is a well held share so will likely be of intererst to many lurkers here, i hold aviva having take the plunge on a mix of Aviva and L&G for the stonkingly good dividend yield flagged up some time back. Aviva being the runt of the two since purchase.
It's probably a stupid plan really buying for the yield - but the quoted pe was also cheap as chips so there was some other logic for buying.
I would confess to not having a clue how sound an investment Aviva may or may not be due to the black box nature of their operations - this is evidenced today by the £250 revalutaion (downwards (of course) i think thats what they are saying anyway) due to a computational error (oops).
Ref todays news i would say other than their inability to add up (should i be worried?) the news all seems fairly decent - trading ok disposals ok - dividend rebased - but if its 21p+ increasing going forward thats still 6.5% thats the kind of haircut i can live with - bit like trimming my bald bonce. There has been no real brucie bonuses ref ongoing disposals there was always the hope that they would receive top dollar for units they are disposing of but its seems the odds of this are "fine chance - ie not fine chance"
Not sure what the expected macro future for their core buisness is - solvency and potential banana skins always being the main issue. Does the change to ifnflation calcs announced impact Aviva at some stage - i know not.
I will continue to hold for now and trouser the dividends while paying off the personal loan i took out to buy these shares in the first place (somewhat comical non recommended route for buying shares generally - hey ho loan interest rate was way cheaper than dividend yield at the time of purchase - what could possibly go wrong)
RM, why not use IG to buy Aviva? Can use 20x leverage if you want, costs L +250bps for the "loan". Can exit anytime if you change your mind. No fees.
Not yet a small cap. I also hold a small amount of Aviva (LON:AV.) The trouble with insurance is that QE breaks the business model - pull in a lot of premiums, earn interest on the money, pay it out again some time later in claims. Pay your admin costs out of the difference. If interest rates are artificially low the amount left over as return on capital becomes minuscule, or negative. So holding insurance shares is a bit of a one way bet, downwards. Will there be any insurance companies left in ten years time? OTH, I suspect there is room for improvement short term, and I also suspect Aviva (LON:AV.) has more cost-cutting mileage to come than its competitors.
Re Insurance and Aviva. Certainly if interest rates fall then it is bad news for returns on the customer "deposits", but in this case insurance premiums just go up.
I don't think (don't know) that the original premise of insurance was about earning interest on deposits. Surely it is about pooling risk and charging a margin for service. So if you insure a risk that has a 5% chance of occurring, if you can charge 10% of the potential pay-out you should be printing money - so long as your pool is deep enough and you judged the odds correctly.
The real question for insurers I guess is how they differentiate and get a competitive edge.
There are probably several answers to that which I doubt many of us are particularly qualified to judge. Seems to me that probably the best one can do is to judge them on their past performance (and perhaps trends) and hope that the past is some guide to the future.
Thinking out loud now, but if I wanted exposure to insurance specifically - then I might be inclined to buy them all or a sector ETF, But I am sure other opinions are available ;-)
Groiders
Don’t be too put off by the down votes for your post. It’s likely to be because Aviva is not a small Company, and people sometimes just down tick instead of pointing that out to newer subscribers here that the focus in the SCVR updates is on smaller Companies.
Paul does occasionally update on larger Companies too. e.g Next.
I hold Aviva and fwiw thought their update today was reassuring. Also the restoration of the dividend with 7p to be paid in January and probably 14p in March and then low to single digit percentage increases after that was good news.
Unfortunately Aviva was a share I didn’t sell during the March crash and despite an average down at 220p am still 5% down. Anyone clever enough to have bought near the bottom has a dividend yield of 10% and growing to look forward to. And arguably it’s worth holding Aviva as a bid can’t be ruled out.
Hi Paul
Have you done a report on shi please
regards
Dave
Click on the Discussions button of Sig (LON:SHI) and you'll see what's available.
thanks