Small Cap Value Report (Thu 26 Oct 2017) - CNCT, COS, CTH, ALU

Good morning! It's Paul here.
This is initially just a placeholder article (created the night before), so readers can post your comments on the day's results & trading updates from 7 am. I will then update the article in the usual way, once I've digested some interesting news.
Good morning properly! It's a quiet day for small cap trading updates & results, but I will be reporting on 4 companies (as shown in the article header). This has to be early, due to other commitments today.
Connect (LON:CNCT)
Share price: 95.5p (up 5.2% today)
No. shares: 247.7m
Market cap: £236.6m
(at the time of writing, I hold a long position in this share)
Preliminary results - for the year ended 31 Aug 2017.
This group is;
a UK leading specialist distributor
By far the largest (in both revenues and profits) part of the business is Smiths News;
Smiths News is the UK's largest newspaper and magazine wholesaling business with an approximate 55 per cent. market share. It distributes newspapers and magazines on behalf of the major national and regional publishers, delivering to approximately 27,000 customers across England and Wales on a daily basis. The speed of turnaround and density of Smiths News' coverage is critical to one of the world's fastest physical supply chains.
This raises the obvious question whether this is a dying business? As we know, newspaper circulation is relentlessly falling, due to the popularity of smartphones, and online generally. Well, that doesn't seem to be the case just yet. The Smiths segment reports profits that are flat on last year (well, up 1%, on an adjusted basis). It's shown as the first item in the table below "News & Media - News Distribution";
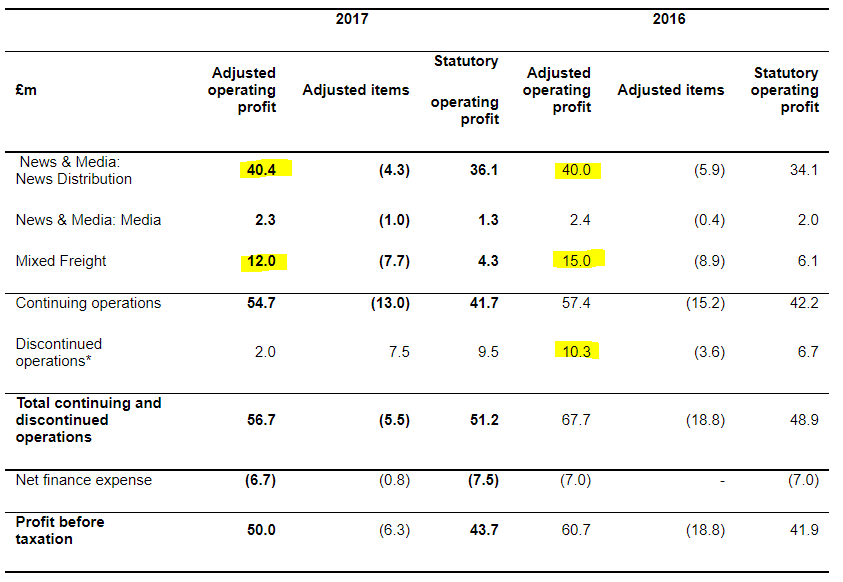
"Mixed Freight" is the other significant division, which is parcel delivery firm Tuffnells. Note that £15m cost savings are planned in the next 2 years, through integrating Smiths News and Tuffnells. So that should hopefully see profits cope with further likely falls in newspaper & magazine circulation. Price rises are offsetting some of the circulation falls.
The other thing to consider, is that if you have a sophisticated & fast network for delivering to newsagents & other shops, then you can distribute other things to them at the same time. So I suppose the challenge for this group is to generate sufficient new business to offset declines in the old.
Pass My Parcel - this is an interesting part of the group. It's one of several competing parcel services, which collect/deliver from 3,500 local shops in the UK. A great idea, but it's loss-making. So today's results include increased losses of £6.3m (PY: £4.0m). Mounting losses here do concern me, but I imagine it would be fairly simple to close down, if it fails to become viable. So there's an argument for ignoring the losses here, and increasing earnings accordingly. I'd like to see some forecasts, as to when this business is expected to reach critical mass and become profitable.
Doing a CTRL+F search for "Pass My Parcel" within the RNS, I've just found this comment, which reassures somewhat;
We aim for volumes to increase significantly in the current financial year and losses to reduce as a result.
There's strong growth in Pass My Parcel volumes, which is encouraging. The key differentiator from other delivery services seems to be rapid overnight delivery, hence enabling early morning next-day collection. So this looks quite interesting actually, and seems a nice way to leverage a delivery fleet which is already visiting those locations to drop off newspapers & magazines.
Adjusted profit of £48.0m is down by £2.4m on the previous year. So it would have been flat, if the increased losses at Pass My Parcel are stripped out. So it seems to me that the core business looks surprisingly robust.
Balance sheet & Disposals - my main concern with this company in the past has been its weak balance sheet (negative NTAV), over-burdened with debt, and a pension deficit.
However, on reading today's results, I'm pleasantly surprised. Net debt of £82.1m is a considerable reduction from £141.7m a year ago), and at 1.2x EBITDA it now looks much more reasonable. The main reduction in debt has been achieved by the sale of its Education & Care business for net proceeds of £58.2m.
The group's books division is also up for sale. This is expected to raise £15m, so that should further help reduce net debt.
A going concern note further reassures on bank debt - in particular with regard to covenants, and long expiry of the borrowing facility;
The Group meets its day-to-day working capital requirements through its new bank facilities of £175m, agreed in October 2017, with a term to January 2021.
The Group's forecasts, taking into account the Board's future expectations of the Group's performance, indicate that there is sufficient headroom within these bank facilities and the Group will continue to operate well within the covenants attaching to those facilities.
That looks fine to me. So I no longer have concerns about the net debt position.
NTAV is still negative at -£81.4m though, which is outside of my comfort zone. However, given that the bank facilities look secure, I'm (just about) prepared to make an exception in this case.
Pension deficit - on the balance sheet it's only small, but costs the company £5.2m p.a. in recovery payments & costs. However, this is small relative to the £24.0m paid in dividends to shareholders - giving a monster yield, which I'll cover below.
Dividends - this is the main reason that I've dipped my toe in the water with an initial small purchase of this share. Arguably I must be brave, stupid, or a bit of both to buy a share with a chart like this!
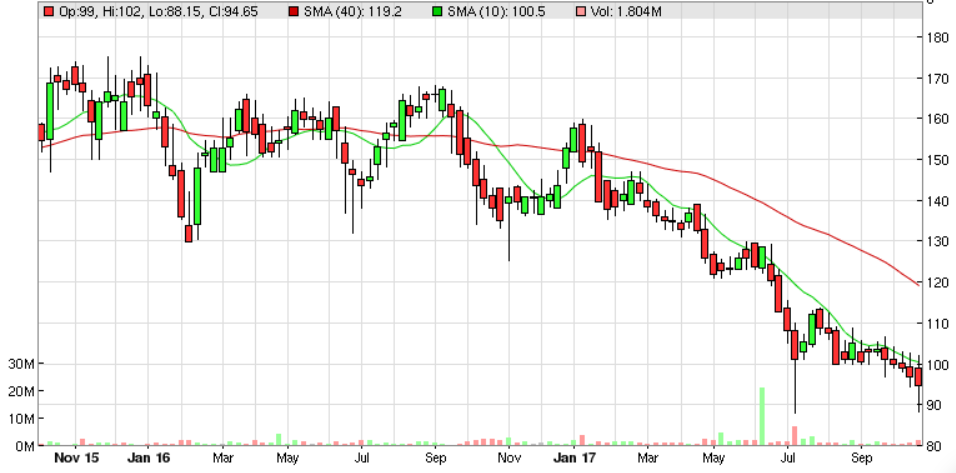
Looks terrible, doesn't it!
This chart suggests fairly obviously that there is relentless selling going on. I closely monitored the price movements this morning, and it seems to me that there's a risk of the share price falling some more. The initial flurry of buying seemed to conk out fairly quickly, and the price tried to break through 100p, but has since fallen back to 94p, on total reported volume of about 727k shares at the time of writing (10:00am).
However, for me, fundamentals trump the chart, and I don't really care if it carries on falling - I'll just buy more.
For me, the clincher is that the monster dividend yield of 10.4% actually looks sustainable. That's very unusual. Usually a dividend yield of that size, is a precursor to a profit warning and a dividend cut. Not in this case (for now anyway). Management has actually increased the divis too, up 3.2% to 9.8p. Again, this is very unusual - extremely high yielding shares don't usually increase the divis, as it's usually already too onerous a financial burden. In this case, the cashflow looks perfectly adequate to maintain this level of payout, in my opinion.
Therefore, I think the huge dividend yield could be the catalyst to trigger a positive re-rating of the share.
The proposed final divi of 6.7p is set to be paid on 9 Feb 2018, to shareholders on the register on 12 Jan 2018, subject to shareholder approval at the AGM on 23 Jan 2018. Something nice to look forward to.
Valuation - adjusted EPS is reported at 15.5p (down 4.3%), giving a PER of 6.2. I can understand why the PER is low - due to the risk of earnings falling from reduced print circulation in future. However, given that the balance sheet is no longer burdened by excessive debt, then this PER seems excessively mean to me.
Outlook - management sound pretty confident;
Despite a challenging year in FY17, significant underlying progress was made in refocusing our strategy and operating structure to support future growth. We are now moving at pace, and as we integrate the Group's core businesses we are confident of delivering the key targets that will underpin our future success. We expect a return to growth in FY18.
The Group expects to deliver solid financial returns throughout the period of transformation, maintaining strong cash flows that will allow for both investment and continued strong returns to shareholders.
My opinion - another point to consider is that the market is still going crazy for growth shares (which Connect isn't). This causes people to chase more sexy shares up in price, and dump their boring value shares. I remember that clearly in 1998-99, during the TMT boom. Many perfectly decent companies fell to extraordinarily cheap ratings (PERs as low as 4-6, for quite good companies, e.g. retailers & housebuilders especially). They turned out to be good entry points, as everything reversed in 2000-2002 - with many former sexy shares joining the minus 90% club, then eventually with many, the minus 99% club. Whilst a lot of value shares re-rated back up again.
To a certain extent, I think we're seeing a similar sector rotation effect now. Therefore I feel myself just starting to rotate a little bit back into value shares - but only where the price is right. A PER of just over 6, and a dividend yield of over 10% here at Connect, is good enough for me to start buying. It may get cheaper of course, who knows? People following a Minervini-style approach might wait for the share price to bottom out, and start making new highs. That might take some time, who knows? But they'll miss out on the divis of course, in the meantime.
If you tot up the dividends which the company has paid in recent years, then the total shareholder return hasn't been too bad, if you bought in 2009 or 2011. I wish we had a button to press, that would add dividends paid to the share price, and thereby give a total shareholder return. That would be quite useful.
Overall then, I like it for the massive & (I think) sustainable dividend yield. That said, I am worried about potential declines in the core business. Also, sentiment seems so bombed out that, I've only dipped my toe in the water to begin with. I'll hold back on buying any more until it's clear that the share price downtrend has ended.
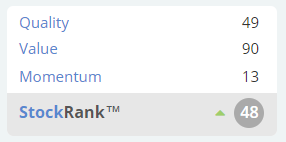
What do readers think? Is this a "Value trap", as suggested by the Stockopedia computers?
I like to not only look at the StockRank, but to think about what could change it. In this case, value is high, quality is medium, and momentum is low. So if the company gets a bit of earnings & price momentum behind it, then the StockRank could actually start to look a bit more attractive;
Collagen Solutions (LON:COS)
Share price: 3.9p (down 8.2% today)
No. shares: 324.3m
Market cap: £12.6m
Trading update - covering the 6 months to 30 Sep 2017.
Collagen Solutions plc (AIM: COS), the developer and manufacturer of medical grade collagen-based biomaterials for use in research, diagnostics, medical devices, and regenerative medicine
I'm not really sure why I'm writing this, as this share is not my sort of thing at all. I was distinctly unimpressed when last looking at it, in Jan & Dec 2016. The shares are down by about a third since then.
Today, it makes the usual excuses for why revenues have not risen in H1;
Revenue and other income is expected to be 1.86m, (H1 2016: 1.89m). Whilst the quality and scale of our sales pipeline are both at their highest levels to date, our first half revenues have been impacted by revenue recognition issues (150k) and anticipated orders which, for various reasons, have either not materialised or have been delayed by our customers' own internal issues (2016 equivalent 341k).
Those revenues affected by revenue recognition will flow through positively during the second-half of the financial year. As already highlighted in our August AGM statement, revenue growth this year is expected to occur in the second-half of the financial year and the Directors believe that the strength and quality of our sales pipeline continues to have the potential to deliver in line with these expectations.
I don't like the sound of that. There's no revenue growth at all in H1. Yet the forecasts shown on Stockopedia indicate full year revenue growth of 36% to £5.36m. That means H2 revenues will need to hit £3.5m, almost double H1 revenues. Is that achievable? I have no idea, but it sounds ambitious.
Even if the company does hit full year forecasts, it's still anticipated to generate a thumping great loss for the year. So what's the point of it all?
Cash - what is interesting, is that looking back at the last accounts, the company had £9.0m in cash sitting on its balance sheet. This was mostly raised in a Placing at 5p, but also it has some bonds + warrants from a venture capital outfit. So it would be worth checking out the terms of these.
My opinion - I like the big cash backing, which to a certain extent de-risks things. Presumably the financial backers see something interesting with this company, so it might be worth a bit more research, if you like small, loss-making companies. If they're decently cash-backed, then punting on them is probably less risky, as there shouldn't be any immediate dilution.
It's not my sort of thing at all.
Caretech Holdings (LON:CTH)
Share price: 428.6p (up 2.5% today)
No. shares: 75.5m
Market cap: £323.6m
Trading update - for the year ended 30 Sep 2017.
This is a provider of social care services.
The Board confirms that trading during the period was in line with market expectations.
Occupancy levels in mature sites look good, although the figures below suggest that newer sites are operating at lower occupancy levels;
Occupancy levels in the mature estate remain strong at 93% (2016: 93%) and the blended occupancy remains approximately 86%.
Fee increases - with this type of business, the absolutely crucial necessity is being able to increase fees, as costs rise;
Annual fee rate negotiations with local authorities have again led to a positive outcome this year.
The key to improving fee rates remains our work on reconfiguring services that we own and repositioning them for the needs of more complex service users in line with commissioner demand.
For me, this is the deal-breaker. I remember how Southern Cross Healthcase went bust, because it couldn't persuade Local Authorities to pay higher fees. So I wouldn't invest in anything that has large fixed costs, but needs to get fee increases from LAs.
There's plenty more detail in the RNS, if you're interested.
Alumasc (LON:ALU)
Share price: 166p (down 3.5% today)
No. shares: 36.1m
Market cap: £59.9m
AGM statement (trading update) - the key sentence is this;
...the group's financial performance is expected to have a greater weighting towards the second half than was the case last year.
and this...
Whilst we are mindful of the risks of ongoing economic uncertainty, we are confident that our strategy will enable the group to continue to outperform its underlying markets and the Board's expectations for full year results remain unchanged.
Normally I would be unhappy with this. However, the RNS contains considerably more detail, explaining why specific projects are going to be in the H2 figures. That gives some comfort that they're not just hoping to hit stronger H2 numbers, but that there's supporting evidence for this optimism.
Pension deficit - care is needed in valuing this company, as the pension fund recovery payments are substantial, relative to earnings. Graham covered this issue in his report here on 31 Jan 2017. He likens pension deficits to bond repayments, which is an excellent way of looking at things - i.e. treat a pension deficit as if it were debt repayment. Thus we would need to factor in this notional debt repayment within our Enterprise Value calculations.
Or, in short, we need to value this company on a much lower PER than if it didn't have a pension deficit. Although it also depends on how you imagine pension deficits might change. So that PER of 7.8 should probably be adjusted up to something like 10-11, to reflect the pension fund deficit.
There's quite a good dividend yield of 4.6%, I see. Although it;s worth noting that more cash is being paid into the pension scheme, than is being paid out in divis.
If you ignore the pension deficit, then the rest of the balance sheet looks fine to me, so I don't have any concerns over solvency.
My opinion - I don't have a strong view either way. It looks okay, and probably priced about right, once you adjust for the pension deficit. The share price seems to have oscillated between about 80p and 200p over the last 20 years. Surely our money would be better invested in something with a bit more upside than that?! Although adding in the divis would improve the overall return. I just can't get excited about this company.
I have to leave it there for now, due to travelling this afternoon.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Seems like Connect (LON:CNCT) has passed it resistance level today, passing 118p. according to some chart work a further break out into a higher price is possible now. I like to wait till something passes it resistance level before getting in.
Connect (LON:CNCT) is paying a great div, last date to get in is 11th Jan to get the div. I been looking to get into some value shares and this is now looking good to me, especially as the momentum is picking up. I hold after getting in today, and will be looking for further value shares this year.
Is there not a possibility of a merger/takeover of Connect (LON:CNCT) with/by John Menzies (LON:MNZS) as I am sure that there would be quite a lot of synergies to be had? This might give support to the share price in the future?
I would have thought that at some point in the not too distant future there will be only room for one company delivering newspapers and magazines.
Lastly I do think there will a floor, which will be reached, in the decline of newspapers and that maybe we should not extrapolate sales decline in to the future on a straight line basis? I could of course be completely wrong.
Anyway my interest is piqued by this and it has been on my watch list. Also I think Paul has a point about un-sexy “value” shares being forgotten and I feel recently there has a fair amount in the press about the end of value investing etc, which is surely a lead indicate that value is back? :-) Don’t get me wrong I have made good money from Boohoo.Com (LON:BOO), Fevertree Drinks (LON:FEVR), Treatt (LON:TET), Purplebricks (LON:PURP) and still hold all but the last but think that things may be start8ng to change.
Clearly, there IS SUCH a possibility, but is there a realistic prospect?
RE your last paragraph - maybe true but what is the relevance? The company has long since moved on and this is not the core mode;
I believe that our village shop accepts parcels for return to internet sellers , which seems to be a great convenience and could be a big growth area as customers become aware of the service.
I'm not currently a CNCT holder but the flexibility of almost every newsagent providing the service sounds good for the near future.
I will not be buying CNCT so DYOR|.
The difference between WH Smith and Connect Group share price is huge.
https://i.imgur.com/DaibCj5.png
I had been drip buying small amounts of Connect (LON:CNCT) since the July trading statement that basically said that things were ticking along acceptably. It was a little worrying therefore that the price had continued to flag over that period, so today's announcement was reassuring and the share price rise brings me back to about break-even :-(
My main worry though would be that the stocko computers description as a value trap may well be perfectly correct. On the metrics I'd probably be looking for a c. 50%+ upside here, but I'm just not sure what the trigger to deliver that upside will be. The 'fear' that it operates in an unattractive low margin business in a declining market can't really be dispelled in the near future, so there seems to me to be a strong chance that the benefits of the synergies between Tufnells and Smiths might not be fully rewarded in the share price.
Still the near 10% (apparently sustainable) dividend yield is a fairly decent compensation.
Incidentally, Paul, although it is not quite the magic button you were looking for, Yahoo provides a useful feature in it's share price history - "Adjusted Close" which states the historical share price effectively net of subsequent dividends. (So for example you can see that when the share price was around this level closing at 101.9 on 24-Jul-12 the "adjusted close" was 76.3p so whilst there has been virtually no capital appreciation over the last 5 years, the TSR has been about 36% (6% pa is clearly not that exciting , but you would have had the chance to cash out for over 100% return within about 18 months when the PE 'roared up to' about 11 and the yield fell to a 'paltry' 4.5% - such irrational exuberance must clearly be the hope of the value investor here ).
Anyone have any thoughts on what might trigger the breaking of the value trap here?
Many thanks Paul for your thoughts on Connect. The stocko window shows net gearing at over 300% and the acid tests at around 0.87. Things to worry about?
Think Paul must have pushed up the share price of Connect with his "small" purchase! Up 10.74% at the time of writing.
Paul Welsh said;
Our SCVR articles here are all about the company results & trading updates which have been issued on that day. So it's primarily that price-sensitive newsflow which is driving the share prices up or down, not our comments.
Regards, Paul.
Just a thought Paul - There are plenty of alternative communities for pointless useless posts like this.
Re CNCT
I don't think I place as much confidence in a management statement that they 'AIM for volumes to increase', as it seems some others do. What business doesn't aim for increased sales?
But I hope they can leverage the fast delivery service, this does seem to be the future.
No position at the moment, but pondering it.
In fact it is very worthwhile watching/listening to the results presentation available here (not sure for how long).
I gives much more richness to what the business is about and some of their key differentiation and the ability to drive some of the improvements outlined.
In relation though to the "aim" to grow the Pass my Parcel business, it makes it much clearer that the in year growth was very back ended so in fact much of this aimed for growth is in fact already delivered and in the run-rate. This though makes me a little disappointed that they are only targetting this business to be break-even in 2019 (rather than 2018).
I should have watched the presentation BEFORE making my initial post, because on the basis of seeing more of the detail I'm somewhat more comfortable that the "value trap" can be broken out of.
CNCT, so basically in a declining business, massive debts which are being used to fund a large dividend.... something in there says someone is going to pay!
Ref CNCT
My worry here is that there may be some adverse impact here with regard to the presumably relatively high fixed costs that must come with managing a national paper distribution network. They have presumably benefited from improved efficiences etc that have kept margins ok recently - but surely there must be some tipping point where the cost of delivering 27 papers per day sorting out admin and such means there is no margin left - the nasty operational gearing in reverse.
I guess the answer to this is diversification blah be blah - but it appears the news is still the vast majority of the sales - does anyone else see them hitting a brick wall at some stage in this regard? - the obvious Danger is that if profits drop to 10 mill a year and even if they are debt free - the current price would seem expensive. I do like a bargain though but this looks like there is a semi unknown nasty awaiting to happen here.
The rate of decline in news sales has been pretty steady & predictable - 4% decline last year. Management has proved pretty effective at taking cost out at a rate exceeding that rate of decline. Note that despite the decline in revenues, operating profit in news distribution has actually increased, as has been the case in past years.
Note also that news distribution is low margin, so whilst it forms 87% of revenues it only contributes 74% of operating profit. These figures are net of Pass my Parcel losses.
Thanks Marben100 very interesting and helpful
Having read the Connect release and read Paul's comments I've decided to buy some. I note the reference to strong free cash flow which is perhaps linked to the dividend. The ceo is called Mr Cashmore which is the clincher.
On that point the ex Provvies ceo is called Mr Crook.
I've never looked at Connect before, but a first glance at the Stock Report shows gearing of 1,430% and a price to book value ratio of 19.4. Interest cover is 6.09 which is not imminent danger territory but is not great for a low margin business particularly if there is a risk of earnings declines. Possibly there is more subtlety in the detail but at first glance the dividend doesn't look as if it is necessarily that safe. Am I missing something?
Bear in mind gearing shown only reflects interim results. Will be much lower once today's lower debt has been processed into the numbers. It also reflects a "capital light" business model, resulting in a low NTAV (book value) [and hence high debt:book]. Cashflow is the key for me, and this has always been a highly cash generative business. IMO the dividend is pretty safe. FCF yield is over 14% by my calculation at an SP of 96p.
A key factor in understanding cash generation is that it pays publishers on 30 day terms but collects from 000s of newsagents weekly. That's what leads to the large and persistent net negative working capital position*. I learnt that the company has made a big investment in IT systems, over the years, to support this and to collect and process masses of detailed sales data, which is valuable to its publisher clients.
ISTM that mgmt is seeking to transform the company into a pure logistics business,which is crucial to the future online economy, offsetting the slow but steady decline in its traditional news business. Its major network of "early" daily deliveries is a pretty unique moat. For the last few years the "Pass my Parcel" service has been lossmaking, but I note:
Pass My Parcel continues to grow volume and develop new services in response to emerging opportunities and growing demand for rapid overnight and early morning delivery. Total volume for the year was 1 million outbound and returns parcels (FY16: 500k), building in the second half, such that the annual run rate, prior to the seasonal peak, in October 2017 was circa 2 million units. The loss made in supporting the business was £6.3m (FY16: £4.0m) including investment in IT to support future service propositions. We aim for volumes to increase significantly in the current financial year and losses to reduce as a result.
That bodes well for 2018.
"My understanding of this benefits from my father owning a newsagents, supplied by Smiths, when I was a child. I remember that Smiths was a priority creditor from his POV (and that their terms were strictly enforced) - without newspaper deliveries his business was dead.
Mark
Hot Socks,
I think interest cover at Connect (LON:CNCT) should improve considerably, as it has de-geared greatly, from the disposals which I mention in the main article. So interest cost should reduce a lot in future. Hence interest cover should improve,
Regards, Paul.
Paul - thanks for explaining
Well, I own some Connect and have just bought some more. My average price was 120p before. I was nervous coming into this morning but am reassured that they are managing the magazine decline (more precipitous than newspapers) and believe if they focus on this ability to deliver early morning into towns and cities, then, of all the 'boring third-party delivery' companies, they are the one with a strategic advantage. Getting rid of Wordery makes sense too, so if they really follow up with their new focus, which it seems they are determined to do, they stand to be one of the few winners in this area. Pension seems ring-fenced enough, debt under control. I didn' t expect an actual increase in the divi, so I feel back to 150p with set of 'non-decline' is not unreasonable. Won't get people retiring maybe, but there aren't many shares with an apparently stable yield, offering 55% upside just to recover their SP of a few months ago.
I must be careful only to speak in generalities,here,but if a company has a substantially negative NTAV, and its book value is not rising as it pays an above-market dividend and disposes of assets;,then the logical conclusion is that the creditors had better get their skates on double-quick and put a stop to this if they can - before nearly all of its assets wind up being paid away in dividends and they get left with very little.
AlanJenkins said;
I must be careful only to speak in generalities,here,but if a company has a substantially negative NTAV, and its book value is not rising as it pays an above-market dividend and disposes of assets;,then the logical conclusion is that the creditors had better get their skates on double-quick and put a stop to this if they can - before nearly all of its assets wind up being paid away in dividends and they get left with very little.
I don't see what that has got to do with Connect (LON:CNCT). The key point with Connect is that it's paying divis from its own cashflow. Bank debt has been greatly reduced. See Marben's very interesting comments about how it has a negative working capital profile - i.e. it collects in cash from customers before it has to pay suppliers.
Regards, Paul.
Net debt has been creeping up despite an increase in shares.The z-score is negative.I am therefore not convinced that the market is wrong about the sustainability of the dividend.Unless of course those figures are out of date.
Marben's point about the company collecting from customers before having to pay suppliers is well made,but all it gives it is breathing space.
AlanJenkins2 said;
Net debt has been creeping up despite an increase in shares.The z-score is negative.I am therefore not convinced that the market is wrong about the sustainability of the dividend.Unless of course those figures are out of date.
Yes, those figures are out-of-date!!! That's the whole point of these SCVRs - we update you on the latest results, on the day they are published. As explained in the article, net debt at Connect (LON:CNCT) has reduced dramatically, due to a disposal.
Did you actually read the main article???
Paul.
I beg your pardon for my faulty memory - I had read the article.However,an asset disposal,while increasing the z-score,would only make the dividend more sustainable in the long term if the reduction in interest exceeded the return on the assets that were sold.Is that the case here ? Apologies for sounding like a boring bean-counter !
As it is a quiet day & if you are bored you could always revisit $CNCT ,which you have not covered recently, as they had results today. Might be interesting to dig into the detail as the Stockopedia rating has it down as a Value Trap - which is probably is on 5cx & a 10% yield, although they are talking of selling the books business which could change the story?
Seconded for Alumasc (LON:ALU) (I hold a bit). I know Graham likes it though I doubt many will find it exciting exactly. I note Sirius Minerals (LON:SXX) is out of the doldrums with a 750k ton polyhalite offtake agreement (sorry to mention a resource stock!)
Any chance of a look at Alumasc Paul Cheers
Re Alumasc (LON:ALU) , there are no figures in today's AGM statement, but there is 'a greater weighting towards the second half than was the case last year', and suggestions of declining exports and increased order books. The conclusion is an expectation of meeting board targets (if not the brokers').
The stats are:
PER = 7.9
PEG = 0.4
Yield = c4% (covered x2)
ROCE = c20%
The company has £6m in cash, but there is also a pension deficit.
Finn Cap, Peel Hunt and Canaccord all have it as a 'buy'.
Various divisions have been shed and acquired over the last three years to make the company more focused in the one sector. (Although it has neither boomed nor busted as the builders it serves has).
I have a tiny holding here, and have done for a while (worth seeing a doctor????) It seems to me to be a very well run company, with a potential upside of c10-15%. The yield is nice while you wait for that to happen.
Yes, I'll take a look at Alumasc (LON:ALU) later today. Leave it with me.
P.
Thanks Paul much appreciated
My morning smallcap tweet:
Very quiet day.
Ashley House (LON:ASH), Vitesse Media (LON:VIS)
Ashley House (ASH) PM's announcement that it is dropping plans to cap housing benefit in the supported living sector is good news. "This change should therefore enable the Company to unlock many schemes in its large Housing pipeline, predominantly in extra care." It rose 6% yesterday after PMQs.
Vitesse Media (VIS) H1 rev down 9%. Pretax - £213k (£3k). "We believe the change in mix in our media sales to a more visible revenue stream, plus the necessary investment in key staff should allow a return to profitability in the current financial year, albeit at a low level. We expect to see a more significant return to profitability in the financial year ending 31 March 2019."
Have you any views on Jarvis Securities Paul? No results tomorrow but noticed Graham had posted an update in Feb but nothing since. They had decent results in July and Stockopedia seems to like this SuperStock. Increasing revenue, profits, divided and cash in the bank ☺
Thanks
Hi bluetonto.
Jarvis Securities (LON:JIM) was mentioned as a recent buy in Robbie Burns's bi-weekly Naked Trader blog. As commented there and in various media (including here on Stocko) they may stand to pick up business from disgruntled private investors looking to move away from Barclays Stockbrokers following the recent revamp that seems to be having a fair few teething problems. Hargreaves Lansdown (LON:HL.) Also seems to have gained recent impetus, although of the two Jarvis Securities (LON:JIM) is smaller and may derive a bigger impact from the incremental business. Stock ranks are generally higher in a direct comparison too.
https://www.stockopedia.com/compare/?tickers=LON%3AHL.%2C+LON%3AJIM%2C+
Gus.