Small Cap Value Report (Thu 26 Sept 2024) - IGR, FLO, ABDP, SDI, VID

Good morning from Paul, Graham & Roland.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
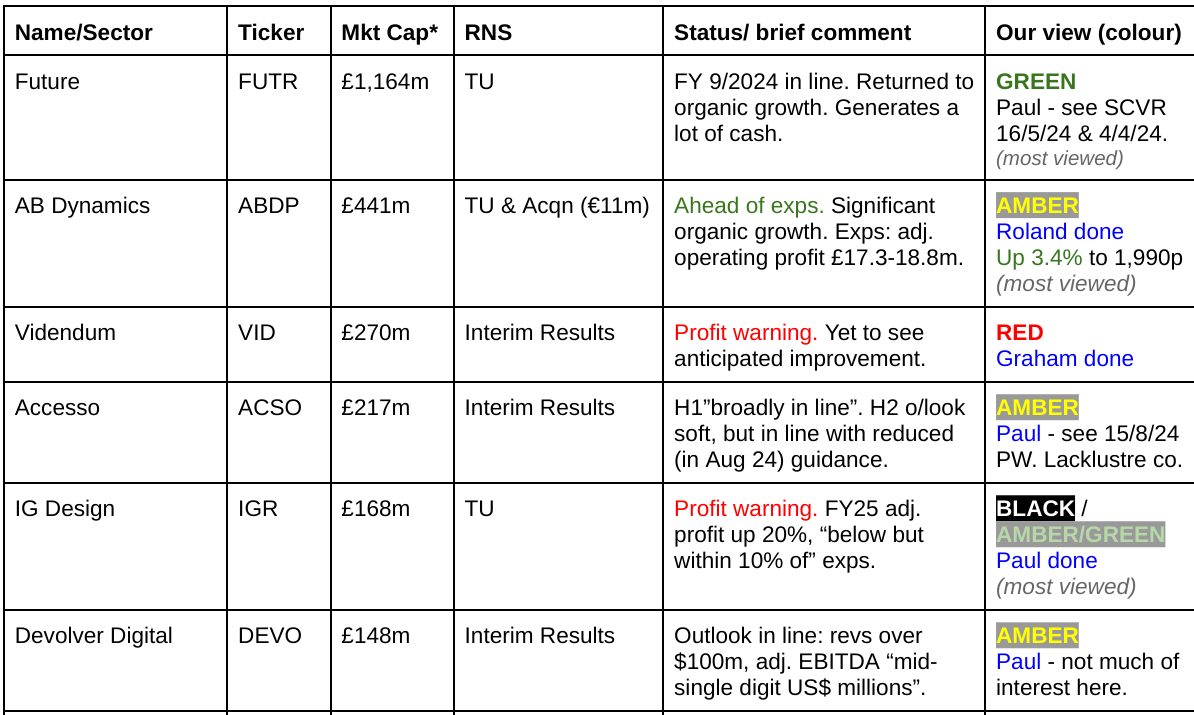
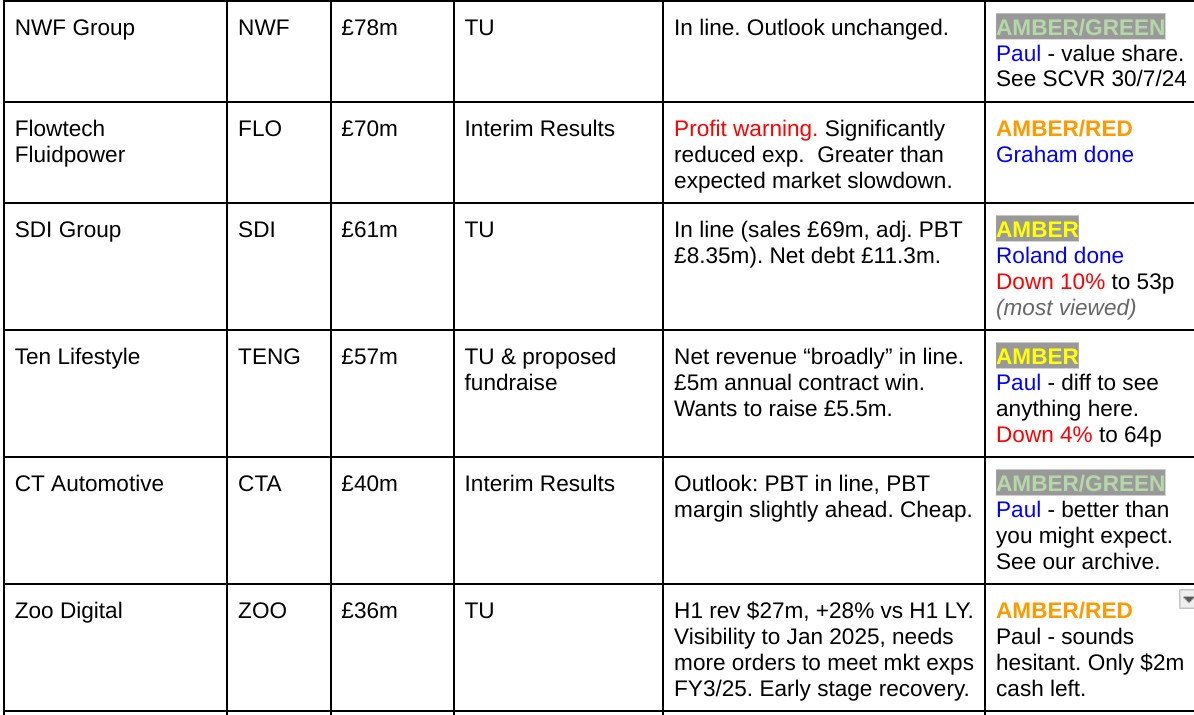
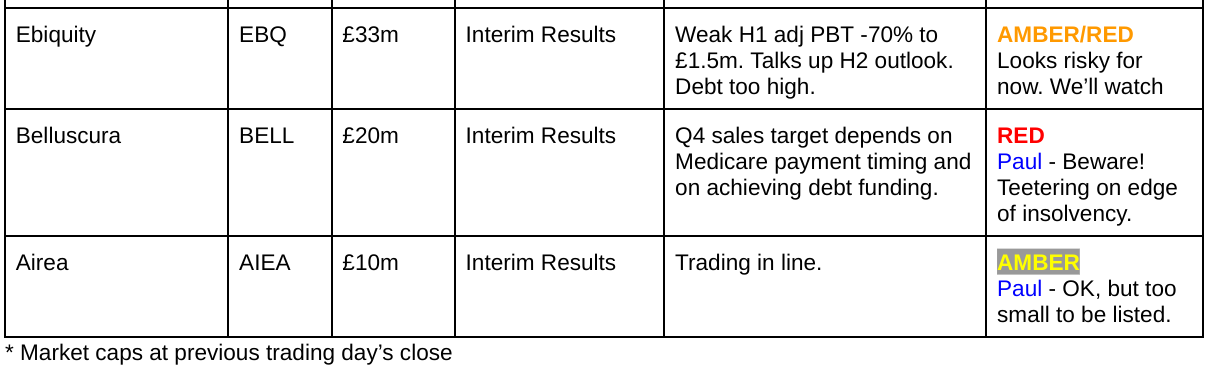
Summaries
IG Design (LON:IGR) - down c.21% to 136p (£130m) - AGM Trading Update [profit warning] - Paul - BLACK & AMBER/GREEN on fundamentals
Profit warning takes 9% off FY 3/2025 forecast profit, and 20% off subsequent years, so the -21% share price reaction seems about right. Sounds like there's still a fair bit of turning around to be done in its USA division, which lost its recent CEO. I suspect that trying to push up margins has caused some business to leak away to competitors. The price is now looking quite attractive on reduced forecasts, so I'm happy with AMBER/GREEN.
Flowtech Fluidpower (LON:FLO) - down 25% to 82p (£52m) - 2024 Half-year Report & TU - Graham - AMBER/RED
Bad news as EBITDA/PBT forecasts are both cut by £4m and the prospects for any meaningful profits in the current year take a big hit. Next year should be better as the recent Thorite acquisition should make a positive contribution and projects delayed in the current year will be delivered in 2025. I’ve been patiently neutral on this stock for some time but I feel obliged to take a mildly negative view on it now, after another disappointment.
Ab Dynamics (LON:ABDP) - up 3.4% to 1,990p (£456m) - FY update & Acquisition - Roland - AMBER
This automotive testing group seems to be making good progress and has upgraded guidance for the year just ended. A small acquisition announced today sounds sensible as well. However, the share price looks up with events to me, so I’m going to take a neutral view for now.
SDI (LON:SDI) - down 10% to 53p (£56m) - AGM Update - Roland - AMBER
This scientific instruments group has stopped short of a profit warning today, but has warned of a soft start to the year and greater H2 weighting than in FY24. I think the shares could be reasonably priced on 10 times FY25e earnings, but there’s clearly a risk of further problems. I’m taking a neutral view at this time.
Videndum (LON:VID) - down 18% to 229.5p (£216m) - Interim Results - Graham - RED
I didn’t expect to take a negative stance on Videndum today but shareholders have been warned at least twice that in a downside scenario, the going concern assumption is in doubt. The bank is still playing ball and the business can still plausibly turn around, but shareholders are at great risk.
Paul’s Section:
IG Design (LON:IGR)
Down c.21% to 136p (£130m) - AGM Trading Update [profit warning] - Paul - BLACK & AMBER/GREEN on fundamentals
Bad luck to holders here, some were wondering in the comments here whether bad news might be coming, due to the soft share price? It’s very tricky at the moment - do sellers know something, or are they selling for tax avoidance measures re the forthcoming budget? We don’t know.
In early trades this morning IGR is down c.20%, which looks about right to me, since Canaccord has helpfully updated us, with a 9% drop in forecast adj PBT from $36.0m to $32.7m for FY 3/2025. However, it’s also put through forecast drops of 19-20% for the following two years, which aligns with the 20% share price fall this morning.
Checking our previous notes here for context, I liked the turnaround at IGR at the start of 2024, and put it onto my top 20 share ideas for 2024, at a starting price of 148p. It had been a decent winner, but gone into a minus position today of -6%.
30/4/2024 - 157p GREEN (Paul) - Ahead exps TU after 5 months silence. Good value & strong balance sheet.
25/6/2024 - 225p AMBER/GREEN (Paul) - Good 3/2024 results. Plenty of net cash. Share price now up with events, so shift down from green to amber/green.
What’s gone wrong? Continuing revenue declines in USA, with 5-month sales (Apr-Aug 2024) down -14%. It talks about more cautious customer ordering, but I don’t believe that. No way are total industry sales down that much, so it says to me that shops are ordering products from IGR’s competitors instead. Maybe that’s a result of IGR focusing on raising profit margins - that some customers are finding better value elsewhere? IGR is only an intermediary after all, between Chinese factories, and Western retailers. Maybe it’s being squeezed out by some customers ordering direct from Chinese factories?
The US CEO left in July 2024 and they’re looking for a replacement.
International “performing well”, and in line with expectations. Europe good, offsetting UK & Australia “soft”.
Guidance & outlook - is nicely detailed and ties in with Canaccord’s update -
“Overall Group revenue has declined c13% in the period compared to prior year. Whilst the H1 versus H2 revenue split is expected to remain similar to the prior year, we anticipate an improvement in H2 profitability driven by the timing of benefits from strategic initiatives and mix improvements.”
“Outlook for the full year:
With the order book now c77% complete at this point (FY2024 equivalent: 77%), we anticipate Group revenue to decline c5% for the full year, mainly driven by the trends we are experiencing in DG Americas.
Notwithstanding the challenges in DG Americas, the Group's Operating Profit is expected to grow year-on-year, and the margin is still expected to return to above proforma pre-pandemic levels of at least 4.5%.
The Group expects to deliver in excess of 20% year-on-year adjusted profit growth, however, as a result of the lower expected revenue, the Group now expects results for the year to be below, but within 10% of, previous market profit expectations and towards the lower end of the Board's profit expectations… “
Turnaround of US operations - I’m quite surprised at these comments, which sound like there’s still some sorting out needed, and that the previous acquisition strategy wasn’t well executed -
“we continue with the turnaround of the DG Americas business, reducing the complexity that was built over successive acquisitions, and improving margins through more simplification and better leverage of its scale.”
Customer risk - this sounds as if IGR has turned away some business from poorly financed customers. This reassures me, as after all, sales are a gift until they’ve been paid for, and the impact of bad debts is large when you’re selling low margin product, as IGR does -
“In addition, we were carefully managing our credit risk exposure, which weighed on revenues, as some of our US retail customers gave us cause for concern.”
Valuation - Canaccord has now got 21 US cents (down from 24) for FY 3/2025, and similar 22 cents next year. Converting into sterling (unfavourable forex moves recently too) at £1 = $1.334 gets us to 15.7p and 16.5p next year. What PER to use? Growth seems to have conked out, and it’s a low margin business with little pricing power, so I think 10x looks about right. Hence I get 157-165p valuation.
Remember there’s also excellent balance sheet support, eg at 3/2025 it has net working capital of $195m, including $95m of net cash (which I think excludes lease liabilities), and average net cash of $28m during the last full year.
Paul’s opinion - today’s profit warning has certainly knocked my confidence in the turnaround, and it’s undoubtedly a setback that reinforces reality that this really isn’t a very good business. It’s always going to be low margin (although getting to c.5% is a good improvement in recent years). The pandemic showed that it’s very vulnerable to supply chain problems/delays, since a lot of its products are time sensitive to specific dates, eg Christmas, so can’t be delivered late, as they would be worthless and rejected by the customers.
That said, after today’s fall, shares now look attractively priced again, particularly with lots of balance sheet support.
So on fundamentals, I’m happy with AMBER/GREEN.
Overall, it’s a setback, but not a disaster, and the share price reaction (before, and today) has I think allowed for disappointing trading.
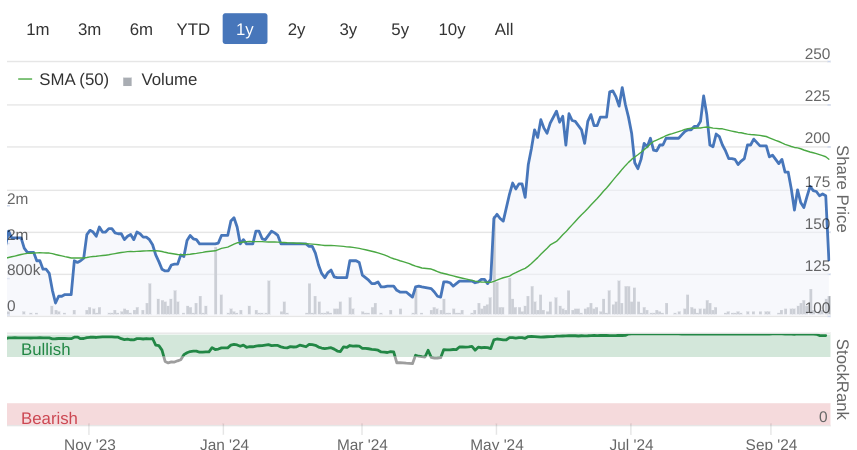
Will investors get a second slice of cake with a renewed bull run? Or has the cake been left out in the rain too long?
Graham’s Section:
Flowtech Fluidpower (LON:FLO)
Down 25% to 82p (£52m) - 2024 Half-year Report & TU - Graham - AMBER/RED
This share has been on the road to recovery for some time, but today we have news of another pothole.
Share price chart as of last night:
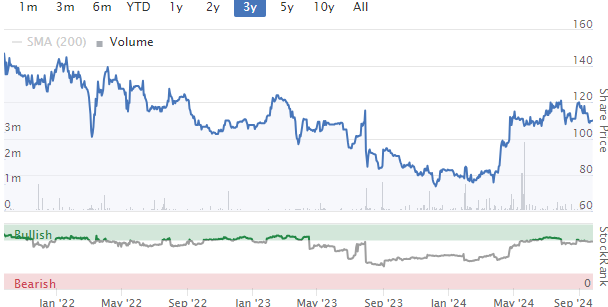
And the bad news today: revenues are under pressure so that even with better gross profit margins, net profits are going in the wrong direction. The outlook for 2024 is significantly below market expectations.
In the company’s words:
Persistent headwinds in our marketplace have continued to impact top line growth ambitions with revenue reducing 5.7% compared to H1 23…
Gross profit margin up 290bps against H1 23 and 160bps up on FY 2023; results in higher gross profit in H1 24 v H1 23 notwithstanding the reduction in revenue
Underlying EBITDA of £4.7m, reduction limited to £0.3m despite £3.4m reduction in revenue compared to H1 2
The “financial highlights” table reveals more bad news, including H1 operating profit of only £1.2m (H1 last year: £2.4m) and a pre-tax profit of only £0.3m (last year: £1.6m).
So the road to recovery is taking longer than anticipated.
The big picture is that Flowtech has already posted a loss for three out of the last four financial years. And so far this year, it’s only trading at around breakeven.
Customers have reduced orders, i.e. have down-traded:
Down-trading is largely external market related with our expectation being that more than 75% of these down-traders will increase orders as the market improves. Northern Ireland revenues have been specifically impacted due to a small number of long-standing large OEM customers with the crushing & screening industry output reducing by over 20% over the last two quarters. Specific larger, major turnkey projects Flowtech has won have been delayed or pushed out for delivery into 2025.
And there is pressure on pricing:
We have maintained a consistent underlying order frequency but with reduced basket size as customers curb general expenditure and burn off held inventories. Larger projects are being delayed which is reducing expected volumes. The market slowdown has increased price competitiveness as customers seek cost reduction. Our strong commercial discipline has protected our gross margin, and, in some cases, we have actively chosen to walk away from lower margin business.
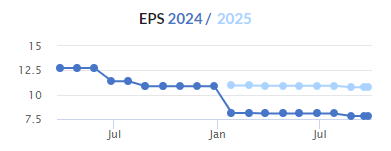
New estimates have been published by Panmure this morning (many thanks). They see an underlying sales decline this year of 5%, and cut their EBITDA forecast by £4m to £7m. Their new adj. PBT forecast also gets cut by £4m, to £1.7m.
Net debt has reduced slightly, despite difficult trading, to £13.5m. Debt reduction was boosted by a £4m reduction in inventories and the issuance of some new shares (an old warrant was exercised).
Outlook: the recent acquisition (we discussed it here in August) remains a source of positivity for 2025 and beyond, but it will negatively impact 2024. So while Flowtech is looking forward to a stronger performance in 2025 and 2026, the current year is trending “significantly below market expectations”.
Graham’s view
I’ve had a neutral stance on Flowtech in recent years.(e.g. August 2023). I have a lot of residual respect for the business, as I remember when it was profitable and seemed like a solid performer.
Unfortunately, events have disrupted this point of view and perhaps now I have to take a more negative stance?
One point which perhaps I haven’t emphasised enough is that when looking at Flowtech’s products and services, I do have to conclude that Flowtech probably struggles to generate pricing power: its own branded products have to compete against both generic products and 3rd party branded products (both of which it also supplies to customers).
In isolation, that fact wouldn’t force me to take a negative stance on the stock but after several years of struggle, maybe I have to accept that this just isn’t a very high-quality business? The revenue decline might not be Flowtech’s fault, but when it’s already struggling to generate any profits then maybe we have to accept that this just isn’t a very good investment?
I’m reluctantly downgrading my stance on this to AMBER/RED, as the recovery has now taken too long.
The trend in the EPS forecast tells the story:
Videndum (LON:VID)
Down 18% to 229.5p (£216m) - Interim Results - Graham - RED
Another profit warning to look at this morning. Videndum is “the international provider of premium branded hardware products and software solutions to the content creation market”.
Before getting into the trading update, let’s check out the interim results.
H1 revenue is “broadly in line” with expectations. Revenue down 7% vs. H1 2023. Recovery from cinema/TV strikes is “taking longer than anticipated”.
We covered Everyman Media (LON:EMAN) here yesterday and have also covered Facilities by ADF (LON:ADF) recently (here). These have also suffered from the cinema/TV strikes and their H1 results reflected that.
Videndum, in addition to the cinema/TV industries, serves the consumer and “independent content creator” segments. They say today that the “continued challenging macroeconomic environment” is affecting these categories.
Videndum’s H1 financial results from continuing operations:
Adj. operating profit £11m (H1 last year: £16.2m).
Adj. PBT £6.9m (H1 last year: £11.1m)
However, the statutory results are much worse than this. Without any adjustments and including the results of subsidiaries that Videndum intends to sell, there was an operating loss of £9m. The pre-tax loss was £13m.
Net debt has at least reduced over the six month period, from £128m (Dec 2023) to £117m (June 2024).
The leverage multiple is 3.3x and I consider anything over 3x to be a red flag.
On the lending facility:
The Group renegotiated its committed Revolving Credit Facility ("RCF") with its lending banks. The facility has been extended, reduced in quantum, and its lending covenants improved
Reading through the statement a little, I see that the new covenants include a leverage multiple of 4.25x and interest cover of only 1.5x. These are weak covenants so when Videndum says that covenants have been “improved”, they mean that the covenants have been relaxed.
This is standard procedure when a company is trading poorly but when the bank is happy to continue backing it, at least for the time being, in the hope that trading will improve.
Outlook excerpts:
Cine and scripted TV market shows continued signs of post-strike improvement with commissioning of new productions starting to ramp up. However, the recovery is taking longer than anticipated…
Despite signs of a pickup in cine and scripted TV productions, and growth in the premium camera market, the Group, along with other companies in our sectors, has yet to see the anticipated improvement in orders. As a result, we now expect FY 2024 to be below our previous expectations…
The Board expects the cine and scripted TV market to return to higher levels of demand during 2025, and for our ICC segment to start to benefit from the increase in premium camera sale
CEO comment: emphasises the company’s focus on managing costs, capex, and working capital during this challenging period. A cost-saving programming will deliver “at least £10m in additional permanent savings” from next year.
Graham’s view
This is another stock where we were neutral the last time we looked at it, and where it’s having difficulty meeting its targets.
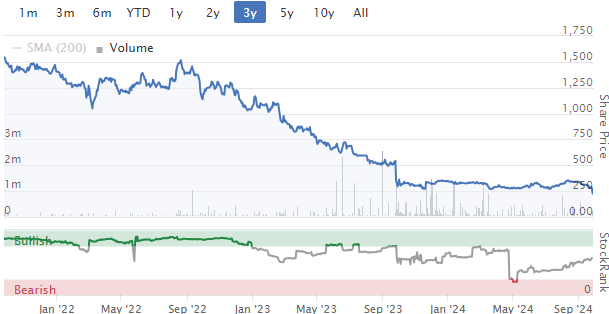
What’s truly devastating about this story is that Videndum already raised £125m in new equity last November (covered by Paul here). This was supposed to comprehensively deal with the company’s existing balance sheet problem.
Due to a very poor cash flow performance in 2023, the company still finished that year with net debt of £128m (down from £193m at the end of 2022).
Here we are looking at the results for June 2024 and there has been a modest reduction from that level, but it’s still not enough to enable the company to sit comfortably.
Again, this is not entirely the company’s fault: it could not have predicted the Hollywood strikes or the depressed conditions in the content creation segment. Although the company is to blame for getting itself over-leveraged in the first place, making it vulnerable to a downturn.
Going back to the Annual Report for 2023, I find an acknowledgment by the Directors of a “material uncertainty” when it comes to Videndum’s ability to continue as a going concern.
Today’s interim results contain a similar warning, so shareholders cannot say they weren’t warned:
…the Board has concluded that while the Group has a reasonable expectation of its ability to renegotiate the terms of the RCF if required, take other actions to avoid a breach of covenants or to obtain a waiver, these financial projections do indicate the existence of a material uncertainty which may cast significant doubt about the Group's ability to continue as a going concern.
In these circumstances, I have to go RED on Videndum. I hope it pulls through, but the position isn’t safe for current shareholders.
The share price has been saying this for a while:
Roland’s section
Ab Dynamics (LON:ABDP)
Up 3.4% to 1,990p (£456m) - Pre-Close Update & Acquisition - Roland - AMBER
full year adjusted operating profit is anticipated to be ahead of current market expectations
This high-tech engineering group specialises in testing, simulation and measurement products for the transport industry. It’s been a spectacular multibagger over the last decade, but progress (or at least market sentiment) has been more mixed in recent years:
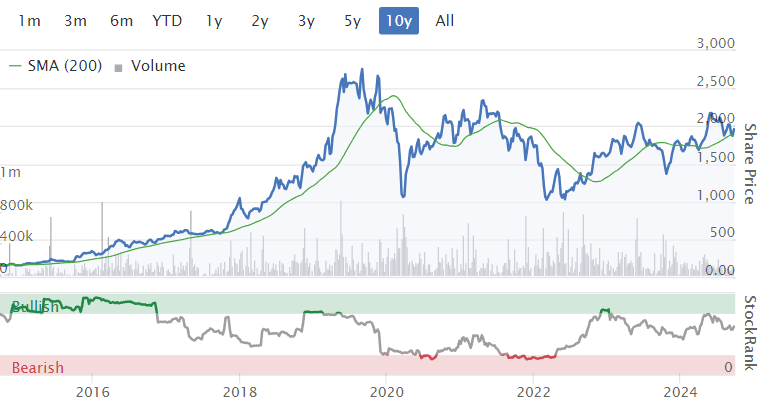
Today’s trading update includes details of an acquisition but leads with the news that adjusted profits for the year ended 31 August 2024 are now expected to be ahead of expectations.
Management says that demand for Testing products has been strong, driven by growth in driving robots and self-driving systems (ADAS).
The Testing Services business is said to have returned to growth as various headwinds have eased (vehicle shortages, China pandemic restrictions).
The company doesn’t provide any indication of how far ahead profits might be, but we do have some information to work with:
Revenue is expected to “exceed £110m”, which is the consensus figure shown on the StockReport
The previous consensus range for adjusted operating profit was £17.3m - £18.8m
ABDP enjoyed “robust margin performance” during the second half of the year
The company’s half-year results did indicate an H2 weighting, so it’s reassuring to see the business has delivered this result.
H1 adjusted operating margin was 17% and H1 revenue was £52.3m.
Assuming full-year revenue of perhaps £115m would imply H2 revenue of c.£63m. Applying an 18% margin to this gives a figure of £11.3m. Adding this to H1 adj operating profit of £8.9m suggests to me that the company might now be report an adjusted operating profit of c.£20m for the full year.
Unfortunately there are no updated broker notes available to us today.
Using £20m as my updated estimate gives AB Dynamics an EBIT/EV yield of just under 5%. In my view that’s not outrageous for a growth business, but not especially good value either.
One concern for me is that this company is quite a heavy adjuster. H1 adjusted operating profit of £8.9m only dropped out to a statutory operating profit of £5.5m. The majority of this is amortisation of acquired intangibles, so it’s up to individual investors to form a view on this.
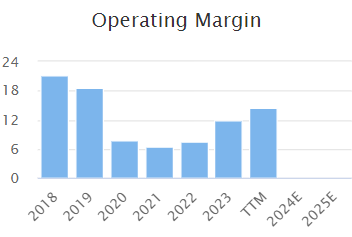
It may be worth noting that reported operating margins remain well below pre-pandemic levels:
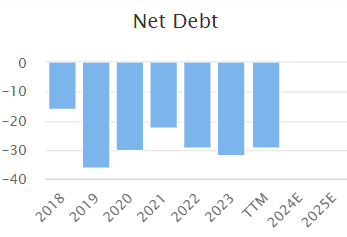
However, despite my reservations about profit adjustments, there don’t seem to be any problems with cash generation. Net cash was £28.6m at the end of August (FY23: £32.0m). This has been a consistent feature of the balance sheet in recent years and should hopefully prevent the need for any dilution:
Acquisition: the other piece of news in today’s update is the acquisition of German firm Bolab Systems for up to €11.0m (£9.3m), with an initial payment of €5.0m (£4.2m).
Bolab is said to be a niche automotive power electronics testing products business that was founded in 2012. AB Dynamics is acquiring Bolab from its founder, who will remain in the business.
Bolab is expected to report revenue of €4.0m and an adjusted operating profit of €0.8m for the current financial year, implying a 20% operating margin. It sounds a logical fit to me, and small enough to bolt on easily.
If ABDP pays the full €11.0m consideration, then the implied EBIT/EV yield is 7.3%, which doesn’t seem unreasonable to me. Based on these figures, I would expect the deal to provide a modest boost to AB Dynamic’s overall operating margin.
Roland’s view
AB Dynamics was trading on around 30 times forecast earnings ahead of today’s update, and the modest share price gain suggests to me that this multiple will remain broadly unchanged following today’s news.
I think this is probably a good quality business with attractive long-term growth opportunities, but the valuation seems up with events to me, with plenty of growth priced in.
The risk/reward balance doesn’t seem all that attractive to me at current levels, so I’m going to maintain our previous AMBER view on this business.
SDI (LON:SDI)
Down 10% to 53p (£56m) - AGM Update - Roland - AMBER
The Company expects to deliver full year results in line with market expectations
Shares in this buy-and-build scientific instrument group are down by 10% following today’s AGM update, less than two months after SDI published its full-year results.
Sure enough, while SDI has maintained its full-year guidance today, management now says that a slow start to the year means that results will be more heavily H2-weighted than last year:
Profit and revenue delivery in FY25 will be weighted more towards H2 than in FY24 due to the current financial year starting slowly, reflecting conditions in certain customer markets.
Checking back to July’s final results, management said then that as a result of “a conservative view on certain sales opportunities, adjusted EBIT guidance for FY25 has been revised”. So there were already signs of weakness.
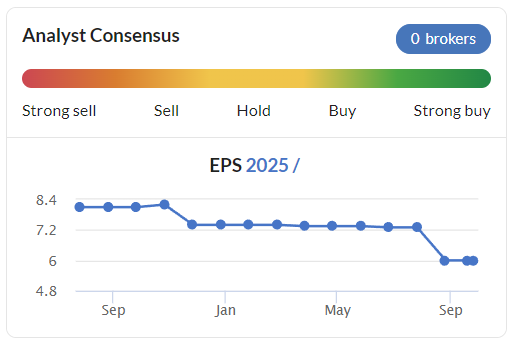
Stockopedia’s excellent analyst consensus trend chart shows how the company’s broker has cut its forecasts twice over the last year. FY25 eps estimates have fallen by more than 25% in total:
Debt reduction: the other item of interest in today’s update confirms that cash generation has remained positive. Net debt at the end of August was £11.3m, down from £13.2m at the end of April 2024.
This seems a comfortable enough level of debt to me, given this year’s expected net profit of c.£7m.
Roland’s view
SDI shares have now fallen by 75% from their pandemic highs, when the group benefited from exceptional sales of high-margin COVID-19 testing related products.
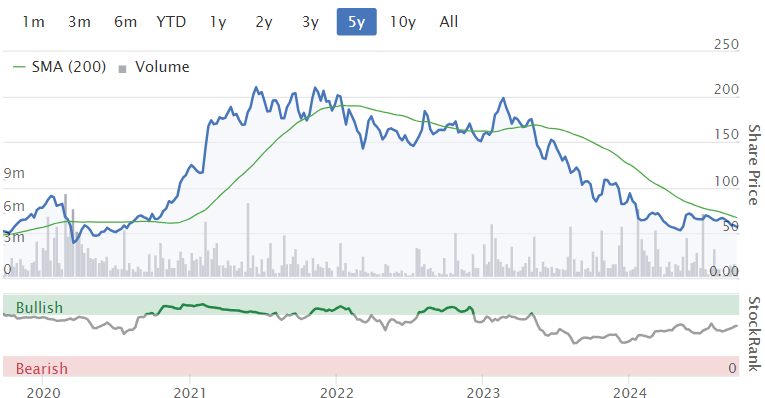
At its peak, SDI was trading on c.30 times forecast earnings and was being talked of by many investors as the next Judges Scientific (LON:JDG).
Where does that leave us today? SDI shares certainly look more reasonably priced, on less than 10 times FY25 forecast earnings.
However, I think it’s sensible to assume there’s some risk of a profit warning later this year, given the weak tone of today’s update.
In addition, I can’t help feeling that SDI may be struggling to replace its high-margin pandemic sales. House broker Cavendish (many thanks) has left its current year forecasts unchanged today, but has previously predicted that operating margins will weaken slightly this year.
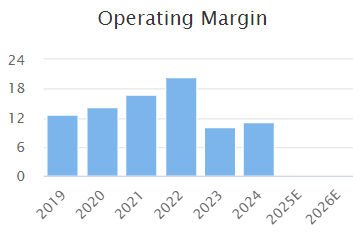
Creating a successful buy-and-build group like Judges – with high margins and high returns on capital employed – is not easy.
I’m not sure SDI has the durable quality that’s needed to justify a premium valuation, regardless of the risk of an H2 profit warning.
However, at current levels this business does look reasonably valued to me. I would probably share Stockopedia’s view that this could be an interesting Contrarian situation:
Overall, I’m going to take a neutral view. I can see risk and potential reward, but would need to do further research to form a stronger conviction.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

146 comments
Hi all
With all the recent chat about possible selling due to budget concerns re AIM shares and IHT exemptions, I thought some might find it helpful to see the top holdings for some of the larger ready-made IHT funds. This won't give any sense of non-fund individual investor holdings of course, but its an interesting read to skim over as these may perhaps be some of the names at risk of larger scale selling for IHT reasons if the budget is not kind (and/or to keep an eye on selling in the lead up to the budget).
Apologies for the scrappy formatting - don't have time to make it neat and tidy and hopefully it's legible.
BIACS
Octopus AIM IHT ISA (1.5 bn fund)
Top ten equity holdings :
Renew Holdings plc
Gamma Communications plc
Next 15 Group plc
Keywords Studios plc
Advanced Medical Solutions Group plc
Boku Inc
Johnson Service Group plc
GB Group plc
CVS Group plc
James Halstead plc
Downing AIM Estate Planning (150m):
Volex Plc 5.77
Cohort Plc 5.58
Team Internet Group Plc 5.23
Restore Plc 5.19
Hargreaves Services Plc 5.01
Kitwave Group Plc 4.90
Ashtead Technology Holdings Plc 4.78
Ramsdens Holdings Plc 4.73
Tatton Asset Mgmt Plc 4.60
Avingtrans Plc 4.03
Puma AIM ISA (240m fund):
Renew Holdings 8.37%
Judges Scientific 7.30%
Cerillion 6.34%
Property Franchise 6.34%
Vertu Motors 4.54%
Thorpe (F.W) 4.39%
Fintel 3.89%
Team Internet 3.75%
Craneware 3.57%
H&T Group 3.45%
Whitman AIM IHT Portfolio (75m fund)
Thanks. If you look at the list of largest holders of AIM100 companies you will find the other two main AIM IHT portfolio fund managers are Cannacord Genuity and Close Brothers. If you add their holdings to the Octopus holdings some of the companies listed in my post have > 20% held by the three companies together. At that level I agree it's a little worrying.
My only holdings in these lists are Volex and Gamma Comms. Gamma Communications (LON:GAMA) have already stated they will be moving from AIM to the main market, so I'm pretty relaxed about it.
All the best, Si
FWIW - Speaking as someone who is now (after 25 years in industry) a politician, a Cllr and now a Cabinet Member with a £75Mn budget in a unitary local authority, it is much easier to criticise politicians than be one. Frankly, working in the private sector was much easier, mostly nicer and more secure and yes, sooooooooo much better paid. (I'm on £20K pa, no pension but ask yourself of the public reaction if it were doubled!)
Running a business meant clear missions, simple metrics, relatively few key stakeholders to work with who mostly wanted the same as me (eg to sell more detergent/soft drink/whatever) plus the ability as a leader to make quick decisions that had to be carried out. This model exists in autocracies, dictatorship and in places where one party is overly dominant in a democracy but tends to lead to corruption and purges. In contrast, in politics, you very rarely have full control of the levers you need and often have multiple conflicting stakeholders to manage. In business, you can profitably and sustainably dominate a niche; in politics, to come second in a First-past-the post sytem is like being bankrupted overnight - and may have zero to do with your own performance.
So for every snout in the trough or weak manager - of whom I saw many in my business career, especially in safe corporate jobs where managers claimed to to be entrepreneurs - there are many people who do it well and because it is interesting.
So when people on here complain that many politicians do not understand business and lack relevant experience, they may be right - but it may also be true that they in turn do not really understand politics and lack relevant experience in the field.
There are elections most years if they want to show how its done!
Anyway, that's why I prefer it when this site sticks to company analysis and investment strategy.....
And there was I thinking that Politics was intended as entertainment provided by people too ugly for film and stage.
The challenge zipmanpeter - is that the politics affects the company analysis.
If, through naivety, a politician creates a massive void for investors by introducing clear uncertainty which, in turn leads to a large drop in consumer confidence, the beginnings of a brain drain and a flight to cash in on long standing pension understandings then that has a direct and potentially longer lasting effect on small caps and therefore forms an unfortunately large component of the company analysis.
That is not party political - if another politician through equal naivety creates huge economic uncertainty and rising/volatile interest rates by swinging the axe at taxes without an OBR assessment that also forms a large part of the company analysis.
Then we have the challenge that these previously rare events seem to be coming more common, so the question for investors, is why? Will that persist and we have to factor it into our company analysis or is it genuinely a one or two off.
So doesn’t matter to me whether it’s Labour or Conservative in power making the decisions but if they are creating a volatile small cap market then that should be discussed. Otherwise its a bit like assessing a company in a vacuum and that is unlikely to lead to strong results.
Zoo AGM today
Running out of cash I see.
Anpario (LON:ANP) ( I hold)
Watched the Investor Meets session from yesterday today. Their first one I believe and it went well, so good for them.
I definitely feel they have got something there - some interesting products and markets.
But I do wonder if the current strategy is the right one. The CEO frequently mentions the need to diversify to reduce risk - more products, more geographic markets, more species to support. My concern is that this is a very small business - only turns over £33m with only 100 employees. Not a lot to properly tackle all the markets they already operate in across the globe, to develop new winning products and to target new animal species to support.
Maybe an alternative would be to do the opposite : focus on less, target resources to the known winners, massively invest in quality worldwide sales teams and turbocharge growth in only the best products and markets. Leave the others for now, they can be picked up in the future when the business is really motoring.
Easy for an outsider to say, of course, sitting in front of a computer screen !
Its really unusual for top-rated shares on Stocko to have a proper shocker.
Often the 98% plus category go sideways or up, sometimes they go down, but very rarely do they get caned.
But in the last two days we have had two 98-99% Stocko ranked shares take a 20-25% beating - IG Design (LON:IGR) and Card Factory (LON:CARD) . I'm nursing my losses as I hold both but I'm intrigued too, suspecting that this also partly reflects the skittishness of the market in the build-up to the budget, as well as the slightly disappointing results.
dave
My thoughts also. There are no guarantees of course and I think the Stock Ranks are excellent but these two results are worrying and probably reflect the skittishness of the market given the Budget concerns.
Airea (LON:AIEA) Interims.
Tiny £10.5m mcap carpet tile maker based in Ossett, West Yorkshire.
In line. But in-line with expectations lowered by the August trading statement!
Trouble at t'mill?
Revenue falls 5.6% to £9.276m
Loss of £0.215m eps -0.56p down from profit of £0.490m eps 1.27p
Net cash falls from £5.728m at end of FY23 to £2.814m end of June, Cash outflow of £3m caused by £1.867m rise in inventories - new product launches and unanticpated fall in Q2 international sales - and £1.2m capex.
Not pretty at all. I fully expected a significant fall in share price.
Blow me down - the shares are up 7.5% at 26.3p!
Why? You tell me? AIM shares going up? On poor results? Unheard of? As you'd expect it's very illiquid. Normal shares traded around 8k daily - today over 700k shares so far.
Management talk on outlook is optimistic with improved trading in Q3, growth in order book and anticipating meeting revised management expectations for the full year with new product launches to come in H2. As there are no figures given for management expectations, no market forecasts and no broker coverage - then it's hard to put a value on the optimisim?
NTAV has actually risen slightly to 38p due to the pension deficit falling by £1.4m to £3.5m.
The remaining cash looks to be devoured by the £5m manufacturing investment due to complete in early 2025. Which, with the pension deficit of £3.5m, probably explains why the £4m investment property is being divested.
P/TBV of 0.68x - but I look at it more as a contrarian turnaround with a lot of upside potential and limited downside thanks to the NAV rather than a value play?
On the upside. Sales have risen strongly in the last couple of years and exceed pre-covid levels. New products include 'zero carbon' lines which wil should be attractive and command premium prices as Scope 3 carbon accounting becomes more normal in the commercial sector? While the £5m manufacturing investment lowers costs and increases efficiency and productivity through reduced labour, wastage and energy usage. Energy costs are also lowered by the 0.8m roof mounted solar power installation at the end of 2023 and the sustainability of the products increased.
Management is right to call it transformational? Though still a lot to go right? Success of the manufacturing investment is critical to the turnaround. In my view the next 12 months will either deliver long term success or doom the company to gradual decline? Seems that the interims have been interpreted as good progress. Today. Who knows tomorrow?
My target price to add would be 18p. Still hopeful!
cheers
Mark
illiswilgig This may be why: Airea (LON:AIEA) 26 September 2024, Conleth Campbell, Chief Financial Officer, purchased 60,000 ordinary shares of 25 pence each ("Ordinary Shares") at a price of 27.0 pence per Ordinary Share.
Thanks funnymoney I'd not yet seen that RNS. Good to know.
Still a remarkable amount of shares traded today. 310k were traded before the price hit 27p - on a share with a daily market average of 8k.Given the daily gloom surrounding AIM that does seem remarkable? Certainly makes me happy today :-)
cheers
Mark
Saga (LON:SAGA) results next week. Up 8% today. Leaky ship?
Saga (LON:SAGA) Goodness gracious - vertigo will set in at this rate :-D
Great news for IPO and CHRY as Featurespace takeover announced by VISA bigger impact for IPO but CHRY also announced buybacks
Chrysalis Investments (LON:CHRY) Yes they're looking to buy back around 8% of the company at current price - given they're on a 40% discount this looks a very good deal for shareholders.
Hunting (LON:HTG) Suprising price action downwards today though chart signalled this. Given the down action on so many small caps tecently with appatent sound fundamentals perhaps some ulterior motive at hand? Or just prilofot taking before the Budget unknowns.
Wanted to say a big thanks to the Yellowstone Advisory team (I think I've seen them pop up here once or twice?). They held a good investor evening meeting last night, with four companies.
Checkit (LON:CKT) , Safestay (LON:SSTY) , Light Science Technologies Holdings (LON:LST) , Transense Technologies (LON:TRT)
I've done a write-up of my notes from the event. A little criminal that each company only got 15 minutes to pitch the "why invest" story. I don't think any of them really nailed a polished compelling presentation, but there were some nuggets of interesting information. Enough to keep me holding one (SSTY) and the other three on my watchlist.
Hoping they hold more of these events to come! I thoroughly recommend attending if you're in London.
Artificial Intelligence - from today's AI Tool report
[Don't shoot the messenger, I'm just posting what someone else has said!]
Our Report: Israeli startup Bridgewise received regulatory approval to launch an AI-powered chatbot called Bridget that can provide stock-picking recommendations—a significant milestone in the use of generative AI for retail investing.
Key Points:
The Israel Securities Authority (ISA) has cleared Bridgewise to release Bridget later this month, partnering with Israel Disc. Bank, one of the country's largest banks, to roll out the product.
Bridget can give recommendations for which stocks to pick up and sell in response to user queries, with plans to expand to a second Israeli bank's platform in the coming months.
The approval comes with restrictions, including that the tool cannot provide advice "specific to the user" or have conversations that appear to be "personal advice".
Why you should care: While banks have long used AI for research and customer service, this shift to AI-powered stock advice marks a significant change, democratizing investing insights and bringing about all the risks and opportunities that go along with it.
.
Prepare for majpr price swings every 5 minutes?
Why is IHT getting everyone vexed and overexcited? How many people actually pay it? HMRC stats for 20/21 say just under 4% of estates were liable. A total of 27,000. The forecast is that by the early 2030s this will have risen to 7% , so c50,000 estates. Of course thresholds, etc could be changed.
More relevant to us as investors perhaps is how many estates do we think are using AIM exemption holdings to avoid being drawn into the net? And how substantial are their holdings if they have decent investment advice and hold balanced portfolios?
A bigger issue I suspect is a number of people cashing out their 25% tax free lump sums now in case the limit on that particular tax free opportunity is reduced to say £100k. Again though I would expect a relatively minor impact on AIM market if they have sensible portfolios.
Perhaps I just haven't a clue what is going on here but tend to agree with the poster that suggested this is a hurricane in a tea cup. Regardless we'll find out at the end of October so no point stressing for the next 5 or 6 weeks. It'll be what it'll be.
Well I am one who is bothered by the prospect of losing BPR. I don't remotely consider myself rich but I've spent lifetime working hard to accumulate assets that I wish to pass on to my offspring and theirs without the Government who taxed every penny I earned taking another handful. Over the years I have carefully identified companies like JDG, LTHM, ABDP, BVXP which afford relief from IHT. The total at invested in is six figures so it isn't a trivial issue.
One also needs to remember why BPR was created. When a family business suffers the loss of it's founder or their successor, in many cases the resulting IHT threatens the ongoing viability of that company and those who work for it, (and pay tax on their earnings).
It seems to me that many shareholders of AIM shares are asking themselves whether the loss of BPR would mean selling their shares and giving the money away now isn't a better tactic.
rwh3ue - problem with selling and giving the money away now (apart from the fact that you might need it) is that immediately you start the 7 year clock ticking and the previous BR planning was a waste of time. If BR is removed from AIM (and I can see why that's not such a bad idea) then why not consider rolling the investment across into other BR qualifying assets such as EIS (higher risk but compensated by 30% tax reducer) and or "lower risk" BR schemes such as offered by Time and Triple Point. I will be very surprised if these are axed in the budget because there's a very good reason why the govt wants us to invest our money in these things.
Well there was ~£2b invested in these AIM IHT ISA funds as of 30th June;
https://www.wealthclub.co.uk/a...
If they aren't going to qualify for IHT relief post say 2026 then why would you hold cash in an AIM IHT which has *significantly* underperformed a cash ISA over the last 5 years? I.e. Octopus's cumulative return is -19% since June 2019.
If investors are advised to relocate these funds then there will be significant headwinds in certain parts of the market. For example, the Octopus fund is the largest shareholder in Boku, 3rd largest in Midwich & based on TR1 disclosures, has bought up significant stakes in Hvivo, Fintel, Idox & Dotdigital over the last few months with cash from KEYW disposals.
Then there will be hundreds, if not several thousand individuals like rwh3ue below.
It's not a storm in a teacup in my opinion.
I just spent a while going through the AIM100 and checking for companies where Octopus hold more than 10% - shown below for those concerned about prices being affected by drawdown of Octopus IHT funds on budget concerns.
None of my holdings are present, I should add :-)
Thanks Aiming Higher that's really useful. And a great insight into letting the tax tail wag the investing dog, imo. Appreciate the impact it could have on Octopus holdings in particular though I'm sure this is not unique. If you're 'saving' 40% on the tax break it still looks like it makes some sense in the shortish term.
Let's see where RR and Sir Sausages take us.
I think part of the “vexation and excitement “ comes from the way the numbers on IHT are dangerously out of date and tend to be backward looking when the concern is among taxpayers forward planning. In February last year Savills estimated that there were more than 730,000 houses worth more than £1million, and it seems likely that eventually almost all of these owners will have IHT taxable assets under current rules even after recent changes. The number you quoted of 27,000 payers was for 2020/2021 and even now, over 3 years later the number has risen dramatically especially for some areas ( In London 23% of estates pay inheritance tax).
If you own a home now and can expect to live another couple of decades ,then I would suggest if that home is now worth £400k or more you are probably heading towards being caught in the net if the nil rates continue unchanged.
This forum is likely to be affected particularly, since we are talking about the choices of our savings, which for many are over and above a house paid off or with a smaller mortgage. (35% of all UK houses are owned outright).
Ramsdens Holdings (LON:RFX)
Another AIM share!
I have added a few more this morning. I don't invest in mining companies and Ramsdens Holdings (LON:RFX) is my preferred play on gold, although I appreciate this is one of its four revenue streams.
Anyway gold has just moved to over £2000 an ounce, plus the Watches of Switzerland (LON:WOSG) recent trading statement was positive for high end end watches and jewellery. This was also echoed by Ramsdens Holdings (LON:RFX), in addition to which the pawnbroking pledge book is growing.
FX revenue is reported as broadly in line, although I would anticipate any softness to be more than offset by precious metal buying.
Just my view.
Re: Stockrankings - On average the Stockranks perform well but Card Factory (LON:CARD) and IG Design (LON:IGR) seem to be recent glaring exceptions. Thoughts and lessons to be learnt?
I agree! IG Design (LON:IGR) caught me out. I thought this was a fairly safe investment. But I must remember that Stock ranks are a lagging indicator; sometimes by many months.
IG Design (LON:IGR)
You've also got to factor in the risk rating, which in the case of IG Design is
Highly Speculative
Indeed - and unfortunately I've taken a battering on both this week. As a general observation the markets are absolutely hammering anything that isn't a beat on results. What does this suggest - I don't think in 30 years of investing I've ever seen such massive price reactions even when companies report an in-line statement - Card Factory (LON:CARD) being a reasonable example (although gross margin contribution for FY risks noted)
Quick Edit - Add Future (LON:FUTR) to the list - down 6% on an "in-line" statement. Has investing gone bananas?!
Card, IGR, Future
All in retail sector. A tough environment which sadly may remain so for the next few months. The 30 October budget mayhem certainly has made it much worse.
Yes fair point Yadi. When talking to people all I hear about is their concerns over the budget and the fact that they've stopped spending until they understand what RR has to say. What a ridiculous "own goal" by the new government. Quite honestly beggars belief at how our own politicians actively put this country down for purely political reasons.
Holy understatement Yadi! I have been in retail for nearly 30 years now and I can tell you the word around high street retail trade this past few weeks is quite shocking!!
Gimmers,
What does this suggest?
Just my opinion but recently I have been noticing a rotation into more defensive stocks, so low quality earnings, consumer facing stocks like Card Factory (LON:CARD) or Shoe Zone (LON:SHOE) or IG Design (LON:IGR) are being oversold on the whiff of any bad news, just not wanted unless they are at give away prices again...
Having said that they have all had amazing runs over the last couple of years, plenty of money to be made out of them, but the old adage about running your winners does, in my opinion, only apply to higher quality stocks and not the above (note I am not a quality snob and I have owned all three at one time or another in the last 18 months).
Best of luck
Although not directly answering your question, last week I played around with Stocko's various factors. One thing I noticed was that for large caps, the results obtained weren't in decile order. Mid caps (£350m - £2.5b) performed better than large caps across all factors, and small caps (£50m-£350m) did uniformly better than the mid caps.
For example, top-decile SR (StockRanks) performed as follows over the last decade: large-caps +55%, mid-caps +83%, small caps +165%. If you want to do well, small caps is (or at least was) the place to be.
For companies like CARD, well, I guess stuff just happens. Remember it's a statistical process. There are no guarantees.
Possibly high momentum can be problematical. I bought MPE when it had a high SR score. What I hadn't picked up was that MPE is in a commodity business (palm oil), and the commodity price was high at the time.
So you have situations where both M and Q might appear high, but that might be due to some cyclical factor. I guess you just have to ask yourself the question as to whether you think a company is in a highly cyclical business and the price of the commodity in question is high.
Hover over the Operating Margin line on the stock report. If the margins are all over the place, then that's a sign of a cyclical business.
I don't think any of this would have helped in spotting red flags in CARD specifically, it's just something to watch out for.
The Q score is something that needs to be watched out for, too. Sometimes the Q score doesn't agree with my assessment of quality. I wrote about IGR elsewhere on this report. It has a Q score of 90. However, if you look at the "quality of earnings" that I talked about, you would have come away with the conclusion that that earnings had too many write-offs, and should be considered a red flag. Average ROE has been only 1.8%, a figure that I consider extraordinarily weak.
We can of course argue about the predictive value of something like ROE, but taking the number at face value, it is indicating it's a pretty weak business.
Good point, and thank you Mark. I will look more closely at all my holdings and be wary of this in future. I do tend to rely on Stockranks a little too much.
Again thanks for this thoughtful post. Makes the Comments section so interesting.
I've always struggled to see the appeal of IG Design (LON:IGR) - seems like a very commodity like product and difficult to see what their competitive advantage is. Profits have also been quite volatile over past few years and struggle to see why it should trade on a high multiple. Stock ranks generally very good, but certainly not infallible and you need to do your own research.
Stockranks work in aggregate and on average. There's no guarantee on any specific stock.
Exactly - stock ranks are a very good screening tool to identify companies that might be worth a closer look. Indeed I looked at IG Design (LON:IGR) only last week as spotted the 99 stock rank - decided pretty quickly that it wasn't for me for the reasons stated above (commoditised product, patchy track record, exposed to slowing US consumer...)
Spender71 - Stockranks don’t really account for the weighing machine effect. Right now particularly in the smaller cap space there is a lot of volatility on relatively light volume. People taking things off the table and it’s hitting many stocks.
Card Factory (LON:CARD) was in-line. Pretty much flagged in the outlook at y/e. But people forgot the H1 headwinds. Doesn’t really change anything for the investment case - if you look at the profit bridge the CFO charted for us between H1 and expected H2 you can clearly see the effect of normal seasonal revenue and the efficiencies they’ve identified (and these will be known) makes up the vast majority of the full year. So of course whilst we could see trading deteriorate over Christmas etc as it stands today you can see why the company expects to hit its targets. But investors bailed anyway, which with relatively low volatility causes an exaggerated effect. Now on a PER of less than 7 is too low for that business. None of this changes the medium term - it’s just cheaper as investors sit on the sidelines.
Fonix (LON:FNX) has really sticky revenues - these businesses trade on strong multiples. Nothing is baked into the forecasts for Portugal so we could see strong upgrades as it takes off but again in a poor market shares just get sold.
But you will always get a few highly rated stocks that suddenly warn like IG Design (LON:IGR) - without a crystal ball not much you can do about that. In today’s market even an in-line can push you 20%+ down and a profit warning at least 30%. It’s just a poor market largely created imo by this void the government have managed to create leading up to the budget.
Card Factory (LON:CARD) I sold when shares headed towards 130, a little early as it turned out and not for the first time, and bought back in around 110 this week, also somewhat precipitously it seems. Happy however as somewhere in between feels about right for now. Completely agree with your reasoning.
Card Factory (LON:CARD) was a bit of a crowded trade, before and after the large fund sells finished from forum posts i reckon.So i'm guessing quite a few dumped just as quickly as bought the momentum from £1/£1.10.I think Cockney Rebel still had a few i think.
For a moment I thought I had clicked on the Politics thread... :)
Flowtech Fluidpower (LON:FLO) I have reluctantly come to the view, to paraphrase Graham, that it is a fairly mundane business. Achieving good gross margins is not a lot of good if it fails to translate into improving operating margins. This may change but the can has been kicked further down the road and there are much better small cap companies on modest valuations competing for available funds.
I therefore sold my holding this morning taking a 20% loss.
IHT and Aim: I have no idea what will be in the budget and neither I would suggest does the BBC or any other soothsayer. I hold a number of AIM shares in what is now a 23 share portfolio, probably more AIM that main listed. I try to pick shares on their investment merits and not on tax related issues. Doing the latter insofar as I am concerned is like the tail wagging the dog. If the company performs and earnings rise, sooner or later the share price will follow. I have a couple of AIM shares on my potential buy list and hopefully the budgetary doom and gloom will push their prices lower.
As an aside Jonno I met a small cap UK fund manager yesterday who seems to have a good track record, I asked him how much of his portfolio was in aim and how he would play the bpr possible issue.
His comeback was nearly all the companies he held on aim could move to the main market listing if needed within six months, he would also view any plunge on his holdings as a buying opportunity.
He's obviously going to talk his book but I had a look through his holdings and most was sensible mid cap 250 holdings that we all like and discuss here fairly regularly.
The biggest issue as I see it is as I discussed with him is the UK is cheap as we all know, US is expensive again ditto but for the UK trade to work we still need the US to tread water worst case , if S&P drops 20% we will see mostly likely a similar plunge in the UK.
Jump in savers maxing out pension pots as budget rumours swirl
IGR One thing I've been considering lately is "quality of earnings". As a quick-and-dirty sanity check, sum up the reported EPS by the normalised EPS to gauge how much in the way of adjustments are being made. For IGR that ratio is a pretty minging 18% over the last 6 years. For comparison NXT has a ratio of 85%. ROE for IGR has averaged 1.8%, a very poor figure.
RTO (Rentokil) has been similarly introducing tonnes of adjustments. The ratio is 65%.
CPI (Crapita, as it is sometimes called) has a ratio of 27%.
All three of these companies has had poor 5-year performances. Caveat emptor.
Thought provoking Mark. Thanks.
Hi Mark, I do something similar in comparing reported eps and normalised eps. If the management are regularly making large adjustments which increase the reported eps to arrive at a much higher normalised eps then it means that I expect the same thing to happen with the forecasts. ie the reported figures will be much lower than the forecasts.
B.P. Marsh & Partners (LON:BPM) a good example where Reported and Normalised EPS are in alignment. A promising sign?
Lots of positive news this week but prices still slumping. Fonix (LON:FNX) Yu (LON:YU.) On Beach group (LON:OTB)
Well Fonix (LON:FNX) clearly a large seller at play
Well Fonix (LON:FNX) clearly a large seller at play
I think this is a very good niche company. So I have to ask myself, yet cannot answer, why are earnings and free cash falling behind revenue growth as we move into ‘25 and ‘26? This is a platform business with excellent operating leverage. It doesn’t make sense unless they are building out a new platform of which I’m not aware.
One reason may that they've scaled up headcount (not massively as they only have 49 employees) to support expansion into Portugal and adding functionality requested by customers (such as ApplePay). On the Portugal front they've been working on this for more than a year and even signing contracts won't deliver any revenues because they get paid on transactions. So there's a lag between investment and payback.
Probably large holders taking the opportunity of more trading volume on news day, to sell out at an OK price.
On Beach group (LON:OTB) criminally good value... <10x PE, double digit operating margins, possibility of +30% rev growth in coming FY Sep25, 40% of market cap in net cash.
UK consumers firmly prioritising holidays (life is too unbearable and gloomy in the UK - weather and politically). Planetx leading the way of more travel to olive oil elixir and grannies in Italian villages...
(I hold OTB in the Boon Fund)
Osb (LON:OSB) has been good value for some time. Perhaps the sense of seasonality just doesn’t make the share a viable investment.
IGR getting a pasting now after some early buying support. You'd have to assume they have caught a lot off guard after reporting ahead of expectations trading at the end of April only to then downgrade forecasts 5 months later. You have to question why management wasn't happy to guide to say 10% improvement in PBT this year and look to surprise to the upside, instead of pencilling in a 50% improvement? It's very poor management of expectations & has killed off momentum.
I wouldn't want to pay more than 7x forecast EPS as the risk of a second warning has to be high given there are 6 months of the financial year remaining, so not interested unless it falls to around the £1 mark.
Bad morning! I have been caught out with the profit warning from IG Design (LON:IGR) IGR . I wish I had sold some on the softening of the price. However, Paul's reference to Donna Summers Macathers park made me smile :). ".........., or has the cake been left out in the rain too long?"
Marcusb, you must be young, for many of us, I am sure Jimmy Webb's McArthur Park, can only be associated with the late great Richard Harris!
Thanks marcusb,
Glad you enjoyed my cake reference, on what might have been a painful profit warning morning.
Cheers, PP.
More great news from Ab Dynamics (LON:ABDP) (I hold). Beating market expectations for the year just ended and announcing another bolt on acquisition, typically sound strategically and sensibly priced, funded from cash generated from profits.
Amid all the negativity surrounding AIM, this is a shining example of how it can work for companies, shareholders and the economy. 2013 IPO at 86p, an already profitable and cash generative technology business, good links with nearby university, designing and manufacturing products to sell worldwide. Most of cash at IPO going to company to fund factory extension to support further growth. Apart from blip in covid period (outside their control, customers' operations forced to close), continuous growth in revenue, earnings and cash generation. At this rate, annual eps will soon surpass IPO price! Founder (already in his 70s at IPO) didn't rush to cash in and recruited professional CEO to take over. If memory serves me, the CEO is ex Diploma (LON:DPLM) which I've stuck with all the way from small cap in 2008 to FTSE100.
Perhaps it even deserves its 30x earnings multiple (lower now at £20 share price and raised forecasts).
More woes - BBC Breakfast this morning - talking about likely withdrawal of IHT on AIM shares - I just hope people will be sensible and invest for quality not purely for tax. Just looked at a couple of Stocko favourites - Bioventix and J Latham - both down today.
I’m getting a bit bored by all this speculation about the budget and yet there’s still a month to go. God help us all! Especially now it has even spread to the most brain dead of programs, BBC Breakfast. Who on earth watches that drivel?
I think the fears have been overdone about the whole thing but that’s what happens when you have a void into which you can inject bored people on social media and 24/7 news channels pumping out doom and gloom.
Also doesn’t help when the PM is full of woe and the Chancellor keeps making up a large black hole to score unnecessary political points and deflect away from the the spending they want to do but don’t want people to realise. Ie large public sector wage growth and pension with no efficiency strings attached. The void has unfortunately been created by a very naive set of politicians and unsurprisingly pounced on by the media where bad news sells better than good.
Sigh……
Also doesn’t help when the PM is full of woe and the Chancellor keeps making up a large black hole to score unnecessary political points and deflect away from the the spending they want to do but don’t want people to realise. Ie large public sector wage growth and pension with no efficiency strings attached. The void has unfortunately been created by a very naive set of politicians and unsurprisingly pounced on by the media where bad news sells better than good.
Yes. The messaging is particularly stupid. At least the Tories worked with Richard Thaler and started their “Nudge” unit under Cameron in 2010 to improve messaging and avoid such horrendous mistakes. My main worry is not so much the coming budget but much more the initial signs that the new government is every bit as stupid as the last one. Not that that surprises me!
Lammy, Milliband, Rayner... I have to say they may have outscored the Tories in some key area of ministerial dimness.
Unsurprising.
Can’t disagree - the general quality of our politicians dismays me. That’s not against one particular party or another it’s a general comment. For example Labour spent untold time attacking the Conservatives on sleaze, cronyism, accepting donations etc. and as soon as they come to power we find they’re basically the same.
The key problem in my view is (a) the political structure - we have this nonsense that MPs and cabinets are paid far too little so they top up with expenses, donations etc. They are supposed to be running the country but are paid like a middle manager at a corporation. That means the people you tend to get entering parliament are far too often just career politicians. Not enough of them have been exposed to the real economy in a position senior enough to justify leading the country or have any real gravity. (B) the level of media intrusion is insane - why would anyone actually want to be an MP in the current environment. In my view that means those attracted to politics are now a “certain type”.
So maybe we shouldn’t be surprised when the culture that has been fostered comes back to bite.
I am apolitical but couldn’t agree with your post more. It describes exactly how I feel about UK politics, so much so, I could have written myself,
I do think it's a bit more compilated than that. Labour had been attacking the Tories for not declaring services so declare absolutely everything. I mean who cares if Kier watches football from a box or his son borrows his rich mate's Flat.
Sorry I don't want a big debate on it, that's what twitter is for but I just feel the above is a big hurricane in a tea cup...
As you were...
Oh does anyone else think Cavendish Financial (LON:CAV) might be a new lifestyle company or is patience the key and I'm too needy? I mean it should be in a perfect position but just seems really dull and bored and solely looking after it's internal needs
I mean who cares if Kier watches football from a box or his son borrows his rich mate's Flat.
i care if the pm is lying to me - if he is lying to me why should i believe anything he says.
plus they called out the other party for doing exatly whatb they are doing
He says he rented flat for his son for gcse's when period he used flat for carried on well beyond date which gcse's stopped (if the tick-tock is correct) - so on face value he is lying here.
He said he accepted freebie to save taxpayers money ref arsenal tickets - that claim is at best dubious - i suspect arsenal would have been more than happy to charge him normal price then relocate for safety reasons
The only half honest reponse i have seen so far is the mp's who were honest enough to say it was treat for their kids - at least they didnt come up with some nonsensical back story or advoid answering the question.
apologies for going off topic
Hi David,
Although nothing to do with stocks but my father (in his 90’s now and his knows a thing or two about politics!) has exactly the same opinion on about media intrusion in politics and that people attracted to politics nowadays are mostly people of a certain type…….
As for media reporters-their moment of glory playing the star role asking stupid questions interfering every 10 seconds of an interview.
All the best
Hi Yiannos,
Good to see you. Yes, implications all a bit concerning.
Hey - at least Planetx cheered you up with memories of Messini :)
Best
David
I do not think you should go into politics for the good salary, you will attract the wrong people. Some of our MPs would not be able to hold down a well paid job by the looks of them. All MPs should have had some experience in the real world before they are even allowed to go anywhere near the house of commons.
Most daytime tv and Beeb Breakfast in particular qualify as opium for the masses. Not an original thought but can't remember who first used the phrase....
I think the quote you are paraphrasing is Karl Marx when he described religion as " the opium of the people."
Nowadays we can add social media and football to opiates of the masses, as well as much TV. (And, for me, Stockopedia).
Is strength of Sterling having an effect on Hunting (LON:HTG) ? Sharp retrace recently.
Oil price falling. Look at BP and Shell too.
Typically i bought 2 hunches earlier this week. Will wait a little until I buy some more, but does seems a good entry price now.
Same position Michael bought recently in starter size.. waiting for the price sentiment to change before topping up, ideally before the exdiv date on 3rd Oct.... as i think the figures( eps growth esp) are solid on Hunting (LON:HTG) . Realistically this could go down to the £3 mark thou... imo. DYOR
What’s happened with Watches of Switzerland (LON:WOSG) - seems to have had a big leap of some 20% over last 2 or 3 days on no news?
*DEUTSCHE BANK RAISES WATCHES OF SWITZERLAND TO 'BUY' (HOLD) - PRICE TARGET 490 PENCE
What’s happened with Watches of Switzerland (LON:WOSG) - seems to have had a big leap of some 20% over last 2 or 3 days on no news?
Some discussion over on the Technicals thread. I’d also point out that luxury stocks in general have been bid recently. And despite the doom and gloom, WOSG has put out two decent TUs in a row. I entered after the first and topped up after the second with the help of broader market volatility.
Hi BnB,
Where is the "Technicals" thread please?
C
Where is the "Technicals" thread please?
“Setting the scene for Stage 2’s” (sic)
Try not to cringe at the greengrocer’s apostrophe. CV’s - Aaaaaarghh!!
Thanks Both - yes, it does seem luxury stocks appear to be having a bit of a bid atm. I notice Burberry (LON:BRBY) also up 7% and Rolex 2nd hand prices have firmed a fair bit.
I was looking at Watches of Switzerland (LON:WOSG) around 370p as it bounced off the 340p lows but didn’t take action. Much less inclined at these levels though. Will see what happens at next trading update. The problem with acquisitions is you can’t quite tell how they will play out
Indeed. Chinese stimulus news has lifted a few luxury goods companies shares it seems.US Chinese previously hated adrs post Xi clampdown on edtech, chinese-us general relations etc... are all getting huge bids, many on no company specific news too.
Bottom Fishers?
I would imagine its the China stimulus noise over last 1-4 weeks David , in theory luxury goods buying should increase, even the share with one of the worst charts in living memory Burberry (LON:BRBY) is showing a tiny flicker of life today.
Hello. Any chance of your thoughts on Phoenix Copper (LON:PXC), Paul/Graham?
Donald Pond is the spokesman for this outfit and assume he will comment soon .
Yes, it would be nice if the Investor Relations director did some communicating - or explain why he can't. Has NIU got the money for further bond drawdowns or not?
For those interested, on 19th (when the SP was 19.5p) they published a PFS (pre feasability study) relating to their Empire Open Pit Mine in Idaho. They used a discount rate of 7.5% to come up with an NPV of $73.75m.
IMO there needs to be some explanation of why this discount rate was used, given that their cost of capital would appear to be far higher. They did also show the NPV's and IRR's at 5% and 10% ($90m, $61m).
The SP has somewhat tanked, 35% drop today alone. It is currently 10.4p. Tha't some value destruction. Comments I have seen about the discount rate range from surprise to incredulity.
Zeus note today suggests fair value at 64p and talks about its enviable position now the mine is financed with the "innovative" copper bonds. For info on the bonds see RNS of 15 May but briefly the interest rate is variable, linked to the copper price or the FED discout rate and subject to a minimum of 8.5% and max of 20% p.a. Hence the ??? re the discount rate. The longer the co remains silent on this, the greater the sceptisism?
Today's fall is not about the PFS. It's about the uncertainty that's become apparent about the staged payments from NUI, to fund the development. The first tranche was on time. The second was held up, for reasons still to be explained/resolved, and so is the 3rd. An interview/statement with the CFO is due to be released later today apparently.
This is not the sort of stock Paul is likely to comment on!
Hi HH,
Sorry no, we don't cover zero revenues junior resources shares.
Sorry about that.
Regards, Paul.
UK attitude and the olive tree investment strategy .
Just been to mainland Greece (Messina) on the hunt for high phenolic olive oil which is my latest rabbit hole .
Was real eye opening to see the contrast in attitude over there in an economy smashed to bits in recent years but a people who do not seem to complain despite a generational shift that has seen an entire region stripped of its youth .
I visited a small village that 50 years ago had 100 inhabitants and now has dwindled to three octogenarians all of whom still tend the land and live a simple life .
Not once did I hear anyone complain only talk of their hopes to bring life back to their valley .
So fascinating to compare the self interest and inward looking obsessions we are currently exhibiting as a nation with everyone so focussed on their issues and “situation” with that of peaceful driven by nature .
Lovely eye opening trip, olive trees have been tended by the same family for over 8 generations and need just a little support, direction and pruning each year and they reward you with dividends every year, a good year always follows a bad year .
Just rambling really but have to say not that keen on coming back to listening to the UK and its incessant obsession with self .
That’s Messini and not Messina but still brought tears to my eyes.
All the best
That’s Messini and not Messina but still brought tears to my eyes.
You old softy, you
I’m off to the outer Hebrides today, for some of the same.
Apologies yiannos
Are you from that area ?
Really great road surfaces too for bike riding .
Yiannos
Just for you -thought you might like this
”A year ago in 2022 it was early January, I was walking in my village, it was empty and cold. But I "saw" it very much alive, then I envisioned it bustling with life, as I described it to you in a previous message. You know from a long time ago, the villagers used to tell their children, urging them to leave the village and go either to the city of Athens or abroad because they were told that they could not live off the land, that their land and property could not support them. That's what I heard when I was a small child. My father recently repeated it to my son when he heard that he would return after his studies to work in the fields. He told him directly and without equivocation. "Don't come back, there is no future here" was his exact phrase.
This worked backwards in me . I thought it had to stop. That nature, trees, our village, etc., is a priceless treasure that we ought to cherish. To love ourselves first and stop behaving like slaves for a little money as employees of some bosses.
So Life in me worked a little backwards. First she brought me the "vision" and then she showed me the way. And that was what we always had. Olive oil. But now it wasn't just olive oil, it was olive oil of health, that elixir that generously offers health. The most precious commodity to man. What a noble thing!!!
Not sure what is your objective here: pursuit of 'high phenolic olive oil' for its intrinsic value of taste, health-giving properties and refuge in the Mediterranean lifestyle; or as a lucrative 'rabbit hole' investment opportunity now poor harvests have inflated prices out the reach of Joe Public, even in Aldi and Lidl.
(Sceptic with monocle, emoticon)
On Mediterranean lifestyles and blue zones. Read an article The secret of ‘Blue Zones’ where people reach 100? Fake data, says academic. Basically he says it is all down to incomplete records and pension fraud.
Thats a bit of a click bait story in my opinion .
There is no question a mediterranean diet is healthier than a typical processed western diet .
Well at least according to my mate Nigel who knows quite a lot about it .
Edmond
I could write a lot on the subject .
High phenolic oils are very different to the oils you buy in Aldi and Lidl.
The health benefits of polyphenols are really only just being discovered but basically massive anti inflamation properties .
I only got into it when i was just pissed off with feeling 6/10 in my early 50s.
It is possible to get super high levels of phenols using specific extraction techniques and you take it medicinally .
Its very bitter , the best oil should make you cough twice .
Because it comes from pressing very green underripe olives the yield is very low .
I only got into it cos its impossible fo buy over here .
Theres a high possibility im going to liquidate a chunk of my portfolio and invest it with the village to build a small mill and help them bring industry and life back to the valley.
Probably a much better thing to be involved with .
But look at the phenol levels when you are looking for the big health claims .
The lidl and also oils dont have any of note .
Think you might get a few customers from Stocko if you do!
Great post. An interesting and refreshing perspective.
Aligned with all you say. I am in Crete just now - and very impressed (as ever) with the attitude to life here.
What a great comment. I think we have news overload here, and there is still so much good here and yet we only seem to hear about the bad.
I certainly wouldn't hurry back, there is a lot to be said for the simple life, I often hanker back to life in the sixties it might have been financially poorer but it was happier and more fun than the current UK
And the music was different class.
CT Automotive (LON:CTA)
Looks interesting but to initiate a starting position of 20,000 shares one needs to go to 58.5p and the buyer is at 51!
No thanks.
One reason that this small cap market is not efficient!
All the best
Yes spread is over 10%. Who would buy these shares?
Zotefoams (LON:ZTF) Does anyone know why it has been dropping the last couple of weeks?
Zotefoams (LON:ZTF) was trading around this level before the big spike up when interest snowballed followed the big media launch of rezorce. A lot of traders jumped in thinking they could make significant gains in a short time frame following a successful launch. The latest investor meet really tempered expectations around the timeframes involved and a few traders hopped out. A few months of no news and those in for a quick win are still exiting and putting money elsewhere especially with it being Aim listed and the upcoming budget. It's low liquidity and spread doesn't help. Zotefoams (LON:ZTF) remains my largest holding and I strongly believe patience will be rewarded with this one.
BenHazz
I think it is worth pointing out that Zotefoams (LON:ZTF) is NOT on AIM, It is on the small cap index (SMXX).
Zotefoams (LON:ZTF) I'm very surprised to find that you are right Michael Tee. I was sure they were on AIM too. Details from LSE here
Sentiment is the same though, it's not because of the index, it's the capital gain that people may (or may not) be tucking away. If I was going to do this, wouldn't it make sense to bed and breakfast (or not) depending on the budget outcome? That would mean I would sell winners after Sept 30 and buy back (or not if there's no significant rule change) after Oct 30. Or am I missing something?
Now I think more, of course, just realising a gain now may also be valid (again on any index, not just AIM).
You are absolutely correct, I think I just got a little rambley there! Just as a reminder of the upside here, posted 2 hours ago:
#igr cash positive on top of previous balance will cover a lot of the share price after this -15% fall
Complete overreaction imo, yes some delays, CEO etc but cash generative and now likely makes up over 50% of the mc
Avation (LON:AVAP) been waiting for this, nothing remarkable at first glance. Especially when a lot of focus on debt reduction is plain to see; however, the weighted average cost of total debt rose from 6.1% to 6.4%. In a world of dropping rates, who sanctioned this (whilst over simplifying, I like to think what a decent CFO would be doing).
Similar - decline in other income dropped - I would have hoped that recent selling of aircraft would have seen some increased income of note.
I note that they draw note as a positive that the fleet is 100% operational, first time since 2020, although perhaps this is due to the fleet shrinking from 36 to 34?
Operational profit growth is up to be fair, although can't see much to sing about and was going to get cut and if the dog ever wants to go out for a walk in the rain, I'll think about it before, probably cutting.
Avation (LON:AVAP) is my biggest holding and was always expecting a steady as you go approach and I think they are still very much on track.
I was surprised equally at the cost of capital going up although my expectation is that they will look to refinance some of this debt after a few more base cuts. Income was indeed impacted by a reduced fleet although now fully utilized and unless they buy we won't see this increase until 2025 when they start getting delivery of the new aircrafts.
The results were impacted by the increased valuation of the aircraft which is probably warranted given the overall shortage in the world of available aircraft which will persist as long as demand remains strong.
Still a huge discount to NAV but requires patience and that might be still another year or two out but I do hope/expect over time the gap to NAV to come down. Happy to continue holding at these prices
Avation (LON:AVAP)
I was surprised equally at the cost of capital going up
I am surprised that people are surprised that borrowing rate paid would rise for any year end 30/06/2024 accounts ?
the average base rate for ye 30/06/2024 was much higher than for ye 30/06/2024 - base rates were still rising during the year.
the rate of increase the prior year was very quick so they started the prior year comparatives with very low base rates.
Surely rates paid are likely to be somewhat laging figure generally - i would expect they would have most of their debt at fixed rates or hedged partly into the future.
In some respects even though base rates have moderated now is it not possible that costs could rise again even with rartes say 1% lower than peak if they refinanced stuff with 2% based rates after 30/06/2023 - or if hedges end.
I dont know the detail so perhaps they haev announced some good refinancing deals that might have lead to lower expectations ?? - if tahts teh case its probaby the good stuff is sailing agianst te tide of much higher base rates plus lag ?
on basic principles i would still expect finance costs for many listed companies to be increaisng for tehn next 12 months on lfl basis even if rates start to drop - similar to current position with mortgages where many people are stlling coming off 2 year and 5 year fixed deals at much lower rates.
must admit my comments are probably of the quality of 5.30 pm saturday down the pub chat after 6 pints - i know zilch about the real detail here as top why lower rates may have been expected?
Hi Viz - weighted average cost of debt change for Avation (LON:AVAP) comes down to a couple of factors
1) debt on the bonds is relatively high and because of the repayment of other asset backed debt the overall debt is significantly lower but the average cost of remaining debt is higher.
2) when they take delivery of aircraft they tend to asset finance it at fixed rates. So you get an effect that long held cheap debt is replaced by debt at current interest rates.
But they also hedge almost all of their floating interest rate risk.
Recent selling of aircraft was post year end so that profit is booked in this year.
At some point I expect this to re-rate to NAV or above but unclear when - I take a 3-5 year view. Thus I expect c. 100% return at some point over 3-5 years. That meets my annual return target but I wouldn’t want to try and time it by trading in and out.
As debt continues to get paid down at $40-50m a year that value should all switch into equity. There is a lag between business growth and NAV increase, so also waiting for that to show through.
Thanks David for your analysis, I totally agree with.
My issue with Avation (LON:AVAP) is that whilst sitting and waiting patiently, you get no dividend. Other stocks that I hold for long term value realisation (Reach (LON:RCH, Smiths News (LON:SNWS) Abrdn (LON:ABDN) ) pay you near on 10% to wait, whilst still realistically being able to double in price.
I do also have a half position in Amedeo Air Four Plus (LON:AA4) which does need to be timed right for best gain, operates in the same space, but pays (to me) over a 20% div (thanks to Charles Mitchell for his investment trusts thread). AA4 offers significantly higher dividends, but Avation may provide more long-term growth potential as it reinvests more of its earnings into expanding its fleet.
I'm impatient, generally, its my ADHD, but I can temper that with money flows in, especially pertinent in a higher inflationary environment. Maybe I just need a longer cycle (and more cash) so I can ride these barren years out...
Yep - all depends on your investment strategy Viz
I have some stocks that I will sit on patiently because I don’t feel I will ever get timing the re-rate right but these need to be able to deliver an average 15% compound total return over whatever window I think the business should deliver on its strategy, Avation (LON:AVAP) is one, hVIVO (LON:HVO) and MPAC (LON:MPAC) are a couple of others. I see 100% upside on all 3 but I don’t want to trade in and out.
Then I have proxy bonds with some capital upside like Reach (LON:RCH), Smiths News (LON:SNWS) and the like where I get paid 10% income but consider the stock as having decent upside.
So I try and manage a mix of income and capital and look at it as an average total return
Avation (LON:AVAP) are appearing on Investor Meets Company today at 1pm.
Live tomorrow at 11.30am on Vox Markets Exchange (27th Sept), I will be interviewing accomplished UK smallcap fund manager Judith MacKenzie of Downing.
It's sure to be another fascinating conversation - including lots of compelling stock ideas such as #SPA, #AVG, #AT. #CHRT #EYE #EQLS #ADF #HAT #HVO #KITW #RST #SNX #TIG #TRCS and #VLX.
If you'd like to ask any questions, then please feel free join us here on Youtube. Everyone is welcome.
Thanks Paul, these interviews really are very informative and useful.
Many thanks Ox for the kind words.
cheers Paul
My morning smallcap tweet: Viscous fluid
Flowtech Fluidpower (LON:FLO) Hansard Global (LON:HSD) Netscientific (LON:NSCI) Aiq (LON:AIQ) £TENS Zinc Media (LON:ZIN) MTI Wireless Edge (LON:MWE) IG Design (LON:IGR) Downing Renewables & Infrastructure Trust (LON:DORE) Ab Dynamics (LON:ABDP) Touchstar (LON:TST) ValiRx (LON:VAL) Videndum (LON:VID) Arecor Therapeutics (LON:AREC), Frp Advisory (LON:FRP), Van Elle Holdings (LON:VANL), Zoo Digital (LON:ZOO), SDI (LON:SDI), NWF (LON:NWF), Colefax (LON:CFX), accesso Technology (LON:ACSO)
◄Flowtech Fluidpower (FLO)► H1-June. Warns FY significantly below market expectations of rev £113.0m and U/L EBIT £7.2m due to the market has deteriorated further. [SP=111.5 Cap=71m]
◄Hansard Global (HSD)► FY-June. Warns of short-term decline in the profitability (measured using IFRS) in FY2025, before recovering in 2026. [SP=50.04 Cap=69m]
◄NetScientific (NSCI)► becomes EMV Capital (EMVC). [SP=53.12 Cap=13m]
◄AIQ (AIQ)► gets $50k loan from director Li Chun Chung. [SP=4.1 Cap=3m]
◄Ten Lifestyle (TENS)► guides FY-Aug rev £62.9m, broadly in line with market expectations. Adj EBITDA £12.8m, in line. Wins £5m+ PA contract. Guides FY25 in line. £5.5m placing at 63p, a 5% discount, for working cap. [SP=NA Cap=NA]
◄Zinc Media (ZIN)► get recommissions worth £4m across FY24 and FY25. [SP=63 Cap=14m]
◄MTI Wireless Edge (MWE)► wins order worth $0.75m, to be delivered within 12 months.. [SP=52 Cap=45m]
◄IG Design (IGR)► warns FY-Mar adj profit up over 20% but up to 10% below market expectations ($36m). Blames continuation of trends in the Americas. [SP=167.55 Cap=165m]
◄Downing Renewables & Infrastructure (DORE)► potential sale of Swedish wind farm for small premium to book. [SP=79.6 Cap=139m]
◄AB Dynamics (ABDP)► guides FY-Aug rev over £110m and adj op profit ahead of current market expectations of £17.3m to £18.8m. [SP=1980 Cap=454m]
◄Touchstar (TST)► strategic review "to identify the optimal path for future growth and value creation". Options include sale of co or assets. [SP=104.9 Cap=9m]
◄ValiRx (VAL)► has decided to return the KRAS2 project to the university researchers for further development, with no further financial commitment from the VAL. [SP=1.83 Cap=2m]
◄Videndum (VID)► H1-June. Guides FY below mgmt expectation. Material uncertainty going concern stmt. [SP=280 Cap=264m]
◄Arecor Therapeutics (AREC)► H1-June. Guides FY rev in line. [SP=65.22 Cap=25m]
In line: FRP, VANL, ZOO, SDI, NWF, CFX, ACSO
Naked Wines (LON:WINE) Buyout rumour published on Betaville yesterday but behind the paywall.
CT Automotive (LON:CTA) H1 results today with an interim results webinar today at 11am.
Register here: Register here.
Full year 2024 is guided to be in line with market expectations. Beyond 2024, five contract wins have boosted the order book to 2027. There is an expanded business development team to drive further growth.
Flowtech Fluidpower
Long waffly statemebt with some notable wiffly waffly inotiatives .
Just cannot hide fhe fact that its only a distributor of third party products destined to work on 35-40% margin which evaporates in overhead .
Been there done that just dont rate this type if business .
Second issue is the recent acquisition which did look cheap and positive .
Very rarely l are these immediately “earnings enhancing” and everyone has a plan toll they punched in the face .
I know a lot of readers like it on here as do Rockwood but think its well, just an average business with a “turnaround” team full of of big words and even bigger incentives that cant hide the fact that as we say “you cant polish a turd but you can try “
Morning planetx,
I think that's a fair assessment of Flowtech Fluidpower (LON:FLO) - a distinctly unremarkable business. Did all these acquisitions, and then finds it all needs a big sort-out. I can't get even remotely excited about it either, and was surprised Rockwood got involved, but they do far deeper digging than I can do, so who knows?
Regards, Paul.
PS. I've just seen Graham is planning on doing a review, so apologies for jumping the gun!
“you cant polish a turd but you can try “
LOL.
But you can roll it in Glitter!
“you cant polish a turd but you can try “
LOL.
But you can roll it in Glitter
Morning Paul...SIMEC Atlantis Energy (LON:SAE) interims out any chance you can untangle
Morning Zorbatheleek (nice name LOL!)
I remember "untangling" (the right word!) SIMEC Atlantis Energy (LON:SAE) on 25/6/2024 SCVR here, and didn't much like it, so doubt I'll have time or inclination to cover it again today, as there are much more interesting companies reporting. Sorry about that.
Regards, Paul.
PS if you think it's good, then let us know, as I can always be tempted to look at anything if people present a convincing bull case! (After all, we're all trying to make money here)