Small Cap Value Report (Thu 27 Jan 2022) - SAGA, RBGP, WIL, COG, KETL, EYE, CALL

Good morning, Paul & Jack here. Today's report is now finished. I'm heading off to mystery dine Revs again, as it's the last day of their 50% off mains promotion.
Agenda -
Paul's Section:
Saga (LON:SAGA) (I hold) - quick summary (pre 8am) is in the comments section below. I've now written up a full section. It's a small miss against profit forecast for FY 1/2022, but that doesn't really matter, because covid has impacted travel operations so much, as you would expect. The forward bookings info for the 2 cruise ships looks excellent - high level of occupancy already booked for Feb-July 2022, at increased selling prices. So it's got that vital pricing power, needed in a higher inflation environment. I'm very bullish, with a long-term view - as you would expect for my largest personal position.
Cambridge Cognition Holdings (LON:COG) (I hold) - a positive trading update for FY 12/2021. I really like this turnaround under more commercial management, and things are panning out as I hoped. It moved into (small) profit in 2021, has plenty of cash in the bank, and a bulging order book provides good visibility. Valuation still looks reasonable to me, given very good sector tailwinds. Small and illiquid though - so it's one to buy between updates, when people get bored and the price drifts down.
Eagle Eye Solutions (LON:EYE) - another positive trading update, with strong, organic top line growth. EBITDA is shown as the key profit measure, but remember that last year all the £4.2m adj EBITDA disappeared once development spending, and share-based payments, were deducted. Profit after that? Almost nothing! There's no doubt about strong organic growth though, and impressive customer list & wins though. So I like the company. The only question is how to value it?
Cloudcall (CALL) - de-lists today, on completion of the 81.5p cash takeover bid. I rake over the coals, to ponder what I've learned from following and having bouts of owning shares in, this small growth company.
Jack's Section:
Rbg Holdings (LON:RBGP) - I hold - adjusted FY EBITDA to be 10% ahead of market expectations. Wage inflation is a concern, but an industry-wide one and RBG trades at a discount to a few of its peers, even before today’s upgrade. Another dividend takes the total payment to shareholders up to 5p, a c4.5% yield.
Wilmington (LON:WIL) - revenue, adjusted profit before tax, and net debt/cash all ahead of expectations. It looks like the company completed an organisational restructuring last June after a multi-year review of the business, refocusing on global Risk & Compliance markets. The past five years’ performance has been patchy, but no dilution and reduced net debt over the period, so a solid platform for future growth if the company has settled on an appropriate strategy.
Strix (LON:KETL) - Revenue up c30% at constant currency but FX headwinds, as well as ongoing supply chain issues and freight cost inflation. Net debt is higher than expected at £51m as the company invests in inventory. A mixed update unlikely to reverse market sentiment for now, in my view.
Thursday’s Market/General Comments from Paul
People seem to mostly like my early ramblings here, so I'll keep doing them if there's anything interesting to discuss. I'm not saying necessarily my views are right or wrong, but am more just pondering the current situation. As always, please feel free to add your views in the comments, we like discussions, and welcome all rational/polite opinions.
US markets were recovering well yesterday evening, then the Fed Chairman, Jerome Powell opened his mouth again. I listened to his commentary, and obviously I’m not an expert on any of this. However, the stand-out remark to me, was that he said inflation is now more persistent than expected, and has spread into other sectors, beyond the ones initially impacted (used cars have been a surprisingly large element of rising inflation, according to a recent article from the brilliant John Authers - if you don’t follow him, you should! I haven't got time to read all his articles, but when I do, they're most illuminating & interesting).
Yet the Fed is only talking about raising interest rates modestly, by about 0.75 to 1.0% in total this year. Powell doesn’t rule out more aggressive action though. I’m not sure why the market is getting so jittery about this? Last time he tried to raise rates, he backed off. Maybe this time it’s higher inflation that could force him to act? Even then, we’re still looking at historically extremely low interest rates, even after the 4 mooted increases of 0.25% each.
If we end up (UK similar to US) with perhaps 2-3% interest rates, and 6-7% inflation, then where is the best place to invest? I think it's the stock market, in reasonably priced shares, with a good yield.
E.g. a share on a PER of 20, paying a dividend yield of 3% wouldn’t quite do the job. I prefer earnings yield (the inverse of PER) to PERs, because you can compare a share’s earnings yield with other investments. Flipping the PER upside down, converts a PER of 20 into an earnings yield of 5% (1/20 * 100). That means our company with a PER of 20 is not generating enough after tax profit (earnings) to match inflation. Although it may be able to raise selling prices, increase profits, and thereby raise its earnings yield. So it could be worth paying a bit of a premium for companies which can grow earnings well.
To match inflation, we need a share with an earnings yield of 7%. Invert that to get to the PER, and it’s 14.3. Therefore I should be very happy buying a share on a PER of 14.3, providing those earnings are sustainable, because the company is earning the same as inflation at 7%. Some of that will get paid out in divis, and some will be retained by the company to fund growth, or build up a cash pile for acquisitions, or any other use (maybe debt reduction, special divis, buybacks), all of which should in theory add to shareholder value.
If I’ve chosen my PER of 14.3 share well, then it should also have pricing power, and hedge me against future inflation.
Hence in my eyes, value/GARP shares are now much more attractive in a higher inflation/low interest rates environment than the other options (cash, and bonds look terrible, with negative real returns, and some capital at risk with longer bonds too, as they re-price downwards when yields rise).
As mentioned yesterday, I do worry about pensioners sitting on cash piles in savings accounts, who are now lined up to lose maybe 15% of their savings purchasing power through inflation over 2022-23, potentially. That seems likely anyway.
The trouble is, how can an adviser tell them to protect themselves from inflation by investing in shares, when share prices are dropping heavily? They could incur a larger loss in the short term anyway, from buying into a falling market. They’ll be better off longer term, but if you’re very old, the time horizon is limited, and maybe erosion of 6-7% p.a. from inflation may not be quite as bad as the stress of volatile markets? Having money in good quality, reasonably priced IHT-qualifying AIM shares is an excellent way to boost returns for people in that situation though, providing they’re held for 2 years. Seek expert advice on that. Obviously, I’m not a tax specialist.
I still see property as attractive too, because interest rates of say 2-3% probably won’t be enough to dent property values much.
Is there a risk of interest rates ballooning to say 5-10%? Very little, in my opinion, because that would trigger an economic meltdown - households and indebted companies just couldn’t afford that level of interest rates, which central banks know. Given that central banks have discovered & used money printing on an almost unbelievable scale, that’s likely to be the tool they reach for in the next crisis - in fact Powell specifically said this in his testimony to Congress recently - “asset purchases” (i.e. buying up Govt bonds, funded by printing money) would be the main response to the next bog standard recession (not even an external crisis, like covid). That’s what Powell said, I noted it down at the time. Maybe we're now in a never-ending cycle of modest tightening & phasing out of QE, then a recession, with the response being interest rates immediately reduced back to zero again through another wave of QE? (that's what they did when covid hit, so it seems to be the go to response now).
US markets sold off heavily last night again, after Powell spoke, so I think he’s in danger of triggering an economic downturn. Shares are very widely held in the US, in people’s savings plans for retirement, which are sometimes self-managed. So there’s much wider interest in the stock market than in the UK. Hence as Americans see their shares tumble, they feel poorer (because on paper, they are), and maybe rein in big purchase decisions.
The destruction of wealth from plunging stock markets may already be scrubbing off the excesses of QE? So maybe it's a good thing to crash the speculative end of the stock market?
As mentioned yesterday, traders do their own thing, and try to profit from these market moves. Whereas long-term investors, which this column is aimed at, just accept market volatility and don’t try to predict, or react to it. Providing we’re in good quality, sensibly priced shares, then we should do fine long-term, even if interest rates do go up a bit.
I think we’re also maybe getting to a point where UK small caps have sold off such a lot since mid-2021, that anyone likely to panic sell has probably already gone. I suppose that if markets do continue falling, there’s likely to be a trickle of people who tip over their maximum pain point, and capitulate. Plus we have prices being constantly messed about with, by traders seeking to benefit from short term movements.
Looking at individual companies, I’m conscious of an ever-growing list of backlog items that I do want to look at, so will see if we can eat into those a bit today & tomorrow.
Anyway, my message remains the same. I’m a long-term investor, holding good quality, reasonably-priced shares, so I just ride out periods of volatility. It’s always worth reviewing portfolios though, and chucking out any speculative or over-priced stuff, which could still have a long way to fall, if these bearish conditions persist. Or wait for a powerful rebound day (common in falling markets), and sell stuff then.
In UK small caps, we’re seeing overwhelmingly positive, or in line trading updates so far. The economy is strong, with full employment (even labour shortages). Higher interest rates don’t seem likely to rise much, so I think that’s a bit of a red herring. That leaves inflation - which could be around for a while, but once supply chains ease, and we lap the tough comparatives, it’s perfectly reasonable to imagine it could begin to ease in 2023. That’s what happened before when we had inflation spikes in recent years.
I’m not mentioning Ukraine, because that’s political, and uncertain. To my mind, a major war between NATO and Russia looks highly improbable. But you never can tell, as the West rarely understands Russian thinking, and history shows Russia has a very high pain threshold. There could be a standoff there for a while, so I think we have to deal with the uncertainty. It could cause a spike down in markets, if war kicks off, but does it affect the value of Tescos in the long run? No. Or if the worst case plays out, the value of Tesco’s won’t matter.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Saga (LON:SAGA) (I hold)
286p (up 1.6% at 08:37) - mkt cap £401m
I should add that this is now my largest personal holding, so clearly I view this share very positively. That remains the case after today’s update. It’s a classic half full/ half empty update - sceptics might focus on the guidance for a small underlying loss for FY 1/2022.( forecast was for a small profit). Bulls like me, are focusing on the upside from travel restrictions lifting, and the indications there look good - with strong bookings for the new financial year starting imminently.
Summarising today’s update, with my opinions added -
Insurance division performing in line with expectations. I won't go into the detail, because everything sounds fine. This is the reliable cash cow of the group, and has proven a tremendous asset during the pandemic - generating the profit & cashflow to subsidise the losses from the travel division which was mothballed during most of the pandemic, although has restarted on a limited basis in H2 of 2021/22.
Cruise ships - remember SAGA owns 2 new ships, which have barely been used, as they were anchored in Tilbury Docks when covid restrictions prevented them operating. Then limited use (and higher costs) when travel restrictions eased. It surprised me how many over-50’s wanted to go on cruise ships at all, especially during omicron, but they did. Don’t under-estimate the huge pent-up demand for cruising that has built up during the pandemic. I think SAGA, and other cruise ship operators, look set for a multi-year bonanza, assuming no more travel restrictions.
SAGA targets the over-50s, who’ve got most of the money, so they don’t buy on price, they buy on service. Good cruise lines seem to generate amazing brand loyalty, so I think there’s hidden potential value in this brand/company/share, once things normalise. Like lots of other businesses, restructuring has taken place under newish management (including the former long-serving CEO Sir Roger de Haan [the founder’s son], who headed the rescue refinancing during the pandemic). The strategy is to run the business for customer service first. Whereas previous management teams (including a period of private equity ownership) just ran it as a cash cow - sowing the seeds of decline of course, as so often happens with private equity.
Cruise division - positive EBITDA in H2, but an underlying loss of £45-50m after the big costs of depreciation (non-cash) and finance charges on the hefty ship loans. It’s not clear from the RNS whether that loss is for H2, or FY? It's mopped up by insurance division profits anyway.
The load factor in H2 is called “strong”, but is only 68%. I suppose they mean strong in the circumstances of continued travel restrictions & covid anxiety/risk? You might think older customers would stay at home, but it seems they’re raring to go cruising again, and have to be triple vaxxed to get on the ship in the first place.
Cruise bookings - far more important, as this share (like the whole travel sector) is all about anticipating what recovery & eventual normality looks like, post covid.
Even if covid returns in some new form, we already know that SAGA can mothball operations, and won’t need any more cash, because the insurance division holds things up. So a very much better business model than all-or-nothing travel sector shares. I don’t think the market gives SAGA shares credit for this.
I’m really impressed with bookings info for H1 22/2023 (i.e. Feb-July 2022), which are 86% load factor - not far off fully booked then, given that more bookings are likely to happen in the coming months.
Pricing power - SAGA uses a silly term, per diem, which is just daily rate per customer. This was £299 in H2 of 21/22, but has risen 6.4% to £318 for forward bookings in H1 22/23. That demonstrates clear pricing power - almost fully booked, and prices up 6.4% - what’s not to like! So this is certainly one share where we don’t have to worry about the company’s ability to pass on costs to its affluent customers - SAGA is demonstrating that it can raise prices and still see strong demand - that's exactly what I'm looking for in my current investments.
Also remember SAGA faces fairly limited direct competition - its ships are over-50s adults only. Clearly then mainstream, larger cruise ships which dominate the cruise market, like Royal Caribbean, which target families & younger couples, are not competing directly anyway. I'm sure SAGA clients dearly love their grandchildren, but don't want to be on a cruise ship with other peoples' grandchildren screaming & darting about.
Hence a big tick in the box for not having to worry about higher costs - extra revenues are needed, and are being achieved, which should more than cover things like increased cost of fuel, food & drink, etc. Also hopefully some pay rises for the usually Filipino or similar geographies staff. I remember once feeling sorry for the immensely hard-working staff on a cruise ship, and asked several about their views. They told me they were very grateful for the job, which allowed them to support their families back home. It’s hard work, but they didn’t seem to mind. That was only a small sample of staff though. And of course customers can always tip the staff too, if they're feeling guilty. I’m only airing that to see if there’s any negative ESG type angle on cruise ships, but I don’t think there is, if the company is run ethically, which SAGA very much seems to be now.
Travel division - has been restructured, to make it more efficient. This is the bit where SAGA is a middleman for specialist holidays. Quite lucrative in the past, but the cruise ships should be the big money spinner (something like £80m EBITDA was talked about pre-pandemic for the 2 cruise ships combined - although it might take some time to get to that level, as they’re rebuilding the business from standstill).
Cash - plenty of it, following several refinancings. £151m (gross) cash pile, plus an undrawn £100m RCF, is clearly very healthy liquidity - more than adequate.
The way I see it, the £125m cash pile almost exactly nets off against the old bond (2024 I think from memory) which was £250m originally, then £100m was repaid when the new £250m bond was issued last year, 5 year duration I think.
Hence I would say the only structural net debt is the new £250m bond.
The ship loans are bigger, but they are asset-funding loans, so I just offset them against the value of the ships.
There’s no financial strain at all - the group looks fine to me, and has plenty of liquidity.
The plan is to reduce debt as a priority over divis in the coming years, so shareholders will need to be patient, but divis should recommence in future - fine, because I’m more interested in the share price quadrupling over a number of years (upside scenario, may not happen), than getting an income.
Overall profit guidance - small underlying loss for FY 1/2022 - that’s fine. It might be a small miss against broker consensus, but it really doesn’t matter in the exceptional circumstances of covid. It’s remarkable that SAGA has got through the pandemic with only modest losses, which shows the strength of its business model.
More important, is the future profitability. We’re not given any numbers (fair enough, it’s early days, and covid isn’t over yet) - the company says -
Although we are mindful that disruption from the pandemic could continue into the first half of 2022/23, we are well-positioned as customer confidence rebuilds and we move to a new Tour Operations proposition. This, paired with strong Cruise bookings and a strengthened Insurance business, place us in good stead for the future.
We will continue to take an agile, proactive approach to navigate any challenges but are confident that the strength of our proposition, management team and the brand will create sustainable long-term value for our stakeholders.
My opinion - very positive. I think SAGA now looks set up for a future where profits should come strongly back, providing travel can operate as normal. Even if restrictions return, we know SAGA can cope, and won’t need to dilute shareholders again, due to the cashflows from its successful insurance business covering any potential travel losses, as has been demonstrated in 2020-22.
What I like best about this share, is that the brand, and customer service are being rebuilt. That will take years, but everything they’re doing is music to my ears. I tested the customer service myself, and was delighted with it - a completely no quibble full cash refund was given, despite me cancelling my cruise on the morning of departure. That tells me this is a trusted brand again, and the upside on valuation from the brand value being restored, could be large. Remember this company was valued at something like £2bn when it was perceived more positively by investors.
On the downside, the shares are very volatile indeed, and nobody really seems sure how to value it. If you use EV/EBITDA then you won’t come up with such a bullish valuation as me (I use PER on future possible earnings of maybe 100p, possible upside to 1200-1500p per share, long-term).
Anyway, so far so good, things are panning out as I hoped. Just have to be patient now, and tuck it away for a couple of years.
.
.
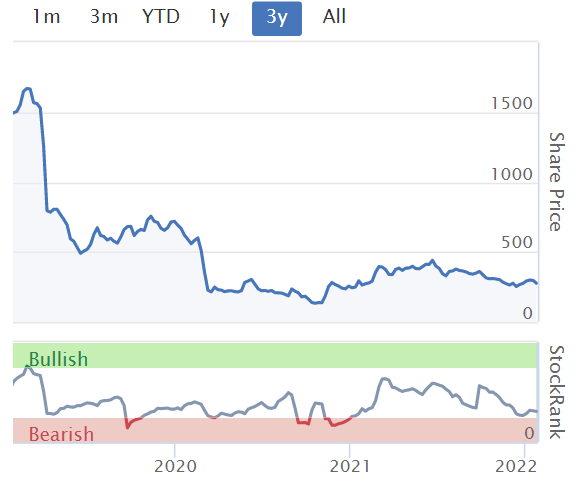
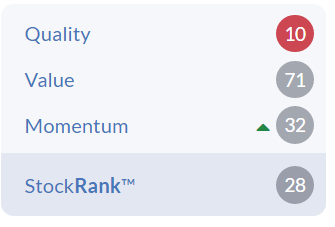
The StockRank system obviously doesn't know anything about covid, or travel restrictions easing, so it remains staunchly negative, as I would expect at this stage. It's a useful reminder that the upside hasn't yet happened.
.
Cambridge Cognition Holdings (LON:COG) (I hold)
131p (up 17% today, at 10:14) - mkt cap £41m
Many thanks to Michael Tee, who has posted in the comments below an excellent bull/bear review of COG’s trading update today, thanks Michael! I don’t really have a lot add, but here are my notes anyway -
Positive update for FY 12/2021
Revenues up a very impressive +50% to £10.1m (all organic growth too)
H1: £4.5m revenues (up 50% on LY H1), so H2: £5.6m (which must also be up 50% vs LY)
Gross margin was 80% in H1, so assuming that’s the same in future (it’s not mentioned today), COG has outstanding operational gearing.
Contracted order book up 51% to £17.0m, which gives excellent visibility, and proves that 2021 wasn’t just a one-off good year (which has happened before under old mgt).
Profitable now, PAT is £0.5m - nothing to write home about, but this is a breakthrough after years of losses. I’m not sure why the company references PAT, not PBT. Maybe it gets an R&D tax credit? Tax should be negligible in future anyway, due to brought forward losses.
Cash looks very healthy at £6.8m, no doubt helped by getting roughly 20% on contract signings. So I don’t think we need to worry about any more dilution.
My opinion - this looks excellent, and is playing out exactly as I hoped.
The 17% rise today looks justified, and bear in mind that’s only added about £6m to the market cap. It’s still cheap in my view, given the positive industry tailwinds, and COG’s expertise in a niche with barriers to entry.
Although we should remember that we’re in a much more sceptical stock market, that is reducing valuations on growth companies. Although COG never reached a lofty valuation in the first place, so that doesn’t worry me.
I regard COG as a classic turnaround, of a company with considerable expertise, now being enhanced from the introduction of a much more commercial CEO, Matthew Stork. That combined with lovely industry tailwinds. And a reasonable valuation still, I must top up when funds permit, and it remains a core long-term holding of mine. So far, so good!
Tailwinds - although partially offset by delays - could that be a longer term opportunity as delays reduce in future? Maybe, I don't know -
The pandemic has provided a catalyst for the growth in adoption of virtual clinical trials as pharmaceutical companies shift to measuring patients at home more1, which has been of benefit to the Company, but this has been offset to a certain extent by some delays to trials, mostly due to more cautious, slower patient recruitment. These trends are expected to continue in 2022.
The underlying market for the measurement of electronic outcomes in clinical trials was reported to be growing at 17% in 2021. The Company results were ahead of this underlying market growth. The 2021 performance provides a strong platform for further growth as the Company continues to develop and commercialise its innovative digital assessments, primarily for clinical trials.
.
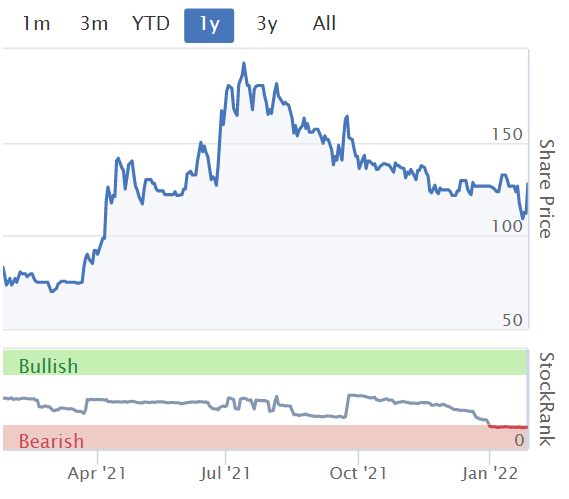
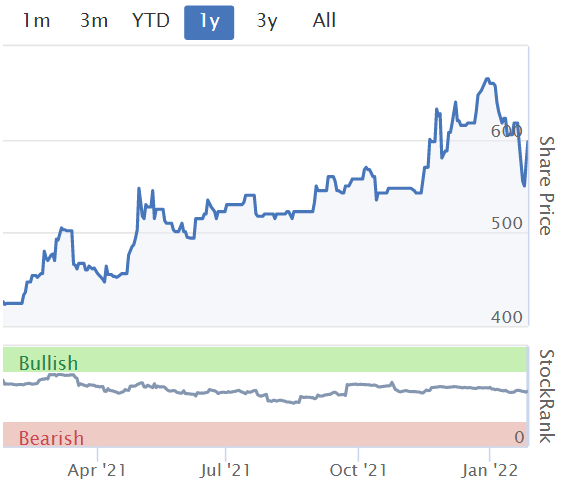
The 1-year chart shows a nice rebound from recent indiscriminate sell-off -
.
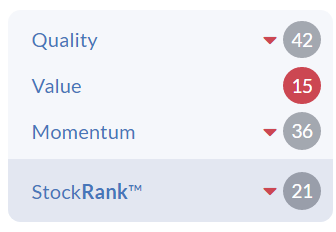
The StockRank is currently low, but I would expect this to improve. COG does look expensive on a PER basis though, so it's not well suited to the StockRank system!
.
Eagle Eye Solutions (LON:EYE)
Up 5% at 605p
H1 Trading Update (and US customer win)
Eagle Eye ( LSE: "EYE"), a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to provide an update on the Group's trading for the six months ended 31 December 2021 ("the Period") and announce the signing of its fourth U.S. customer, Giant Eagle.
“Continuing strong growth, high profile wins and customer expansions, plus record sales pipeline and growing recurring revenue, provide confidence for a successful year”
I like the very strong organic growth here, but not the focus on EBITDA - it’s not real profit here, because the company capitalises a lot of costs. For example, last year FY 6/2021, adj EBITDA of £4.2m turned into just £0.1m profit before tax! It wasn’t just the heavy amortisation charge of development spending, but also management swiped £877k last year in share-based payments. Leaving shareholders with no profits at all after tax.
Here’s the H1 trading update highlights -

.
Cash has been tight for a while, but is better than a year earlier.
Commentary - as always, this is upbeat. It mentions the growing new business pipeline. There’s a substantial new US client win, Giant Eagle.
Outlook - sounds positive -
Board confident in achieving results for the full financial year ahead of management expectations
My opinion - it’s a very interesting company, and has such an impressive, growing client list of large retailers, worldwide.
The only difficulty, is how to value the shares? Since valuation is detached from any traditional metrics (as it doesn’t really make any real profits yet), I’m completely at a loss as to how to value this share.
At around 600p currently, the market cap is about £156m. Is that too high, or too low? Nobody knows, because it ultimately depends on how the business develops in the next few years.
Speculative tech is exactly the area that’s de-rating the most in valuation at the moment, and has been in the US for almost a year now. So I’m worried about touching anything right now which relies on hopes of future growth to support pretty much the entire market cap, which seems to be the case here.
So I’m positive on the company & its prospects, but it looks far too expensive to get involved at this stage, for me personally. I know some investors will say that’s the wrong way to look at it, and I can see that point of view - if you find a company that is doing something special, sometimes ignoring valuation can be the right approach long-term. But sometimes it's a ruinous way to destroy your portfolio, chasing growth at any price, when euphoric conditions come to an end.
It's incredibly difficult to know what to do - run a winner, or bank the profits after a great run, reflecting deteriorating market conditions for growth shares. It's exactly this type of situation where I find that top-slicing a bit, and hold onto the rest, can be a nice compromise. That's for each individual investor to decide of course - your money, your choice. I like top-slicing, because then whatever happens, you can claim victory!
.
.
Cloudcall (CALL)
That’s it, the shares have now de-listed, due to the takeover bid from Xplorer Capital Growth I, LLC having completed. We get 81.5p in cash, in what is actually not a terrible outcome, considering how the company missed targets every year, and repeatedly raised & burned cash in its life as a listed company.
In the most recent update, no doubt in order to give us a kick to vote for the takeover, management said it would burn through the existing cash pile, and need more funding. As a fellow shareholder quipped to me on WhatsApp, “That’s the first time in its history the company has been honest about its cash burn!”
Looking back, I’m amazed to see that Cloudcall (previously called Synety) has been on AIM for almost 10 years! It might be helpful to post some thoughts on what I’ve learned from this experience since 2012.
Synety was little more than a startup when it reversed into a cash shell in 2012 (H1 revenues only £194k)
The product has always been quite good - web telephony integrated into CRM systems, I use it myself.
Cash burn has been unrelenting since day 1, and never declined as forecast - the fundamental flaw being that management kept adding to overheads, so the operational gearing from growth never fed through into profitability.
Growth was never fast enough to reach critical mass and become cash generative, constantly missing ambitious targets.
Ludicrously over-confident management, Simon Cleaver, repeatedly given the benefit of the doubt (and more money) by me & other investors, despite constantly missing targets.
Repeatedly (over years) claimed to have enough cash to reach breakeven. This was not true. A placing usually followed shortly after these reassurances, always justified by increased development spending - I see this as a big warning sign now.
I definitely got too close to management, so need to keep my distance in future.
Reporting focused on KPIs, which always told a good story, obscuring the reality of unrelenting losses & cash burn.
So if I see characteristics like the above again, I try to avoid small, loss-making companies. The only exceptions now, are those that are poised to reach profitability soon, and growing very strongly (e.g. Sosandar (LON:SOS) [I hold]).
Rather than buying the interesting-sounding small growth shares, I now just monitor a few of the most convincing-sounding, waiting for a realistic tipping point, where success looks assured. That avoids the horrendous losses that usually occur as these shares burn cash, disappointing, and repeatedly fundraising.
There are so many investment ideas that sound such good concepts, but actually scaling up a startup into a viable business, takes a long time, and is incredibly difficult. Entrepreneurs almost always under-estimate the costs & difficulty, and they never factor in enough overheads or support staff, to cope with a larger business. Hence why the early forecasts are almost always wildly inaccurate, especially on growth rates, and costs.
Having said all the above, if we look at the 10-year chart (below) for Cloudcall/Synety’s time on AIM, it’s certainly not been a disaster. Considering we’ve had 10 years of placings, dilution, and missed targets!
The share count is now 48m, which has risen 10-fold from the 4.9m shares shown in the interim results for FY 12/2013. Taken in that context, the share price below (current price shown as a dotted line) is actually not that shabby!
In conclusion then, I’ve learned a lot from this share over the last 10 years, and the final outcome is not a disaster by any means. So I’m happy to move on, with no hard feelings towards the company or management.
.

Jack’s section
Rbg Holdings (LON:RBGP)
Share price: 115p (+3.6%)
Shares in issue: 95,331,236
Market cap: £109.6m
(I hold)
Trading update for the year to 31 December 2021
The Board is pleased to announce that having completed a strong final quarter, it now expects adjusted EBITDA for 2021 to be approximately 10% ahead of current market expectations.
The board intends to pay a second interim dividend of 3p per share in respect of the six months to 31 December 2021 on 25 February 2022, bringing the total FY21 dividend to 5p (2020: 3p). That’s a 4.5% yield based on yesterday’s closing price of 111p.
Balance sheet ‘remains satisfactory’. Net debt of £14.2m (2020:net cash of £3.5m) following the acquisition of Memery Crystal in May 2021. RBG has paid back £1m of the £10m term loan used to fund the acquisition, with the remainder to be paid down over five years.
Furthermore, the Group has used £5.2m of the £15m revolving credit facility announced in April 2021.
RBG Legal Services - the group has combined the recently acquired Memery Crystal with its Rosenblatt law firm to create a new legal services entity (RBGLS). This entity now has two client-facing brands: Rosenblatt, which specialises in contentious legal services, and Memery Crystal, which focuses on non-contentious. RBGLS has performed well, benefitting from increased corporate and commercial transactions and greater breadth and depth of expertise.
The integration of the two support functions is largely complete and the business will now move to a new practice management software system. The move has so far resulted in a ‘sustained improvement in net margins of 29%, expected to rise towards 35% over the medium-term’.
Litigation Finance - there are two types of litigation assets here: RBGLS’s own client matters, and the third-party litigation matters funded by LionFish. Both have ‘significant return potential’.
In FY21, LionFish completed a further four investments bringing the total investments made by LionFish since its inception in May 2020 to 10, with a total capital commitment of £10.5m of which £3.6m has been deployed. Disposals since inception total £6.4m.
Convex Capital - the specialist sell-side corporate finance boutique has successfully rebuilt its transaction pipeline in 2021. A total of 14 deals generating revenue of £9.4m (2020: 2 deals, revenue of £1.6m) were completed in FY21, a strong recovery. This business can presumably be a bit feast and famine but the group says the pipeline remains strong, with 22 deals at various stages of completion.
Conclusion
I think the shares look quite cheap at these levels. RBG has performed well over Covid and is paying out nearly 5% in dividends in a period that has seen many payments to shareholders halted and equity significantly diluted.
The valuation remains modest - 10.1x forecast rolling earnings (pre-upgrades) compared to 15.9x for KGH and 14.5x for Gateley Holdings (LON:GTLY) . If you take the average of 15.2x and bring RBG in line with its peers, that suggests a share price of around 160p is achievable on a rerating alone.

There is a question of scalability, given that the acquisition strategy revolves around picking up companies whose quality is derived in part from the people that work there. It definitely has key person risk. Additionally, this part of the market may be more at risk than others from wage inflation.
Perhaps these concerns are weighing on the shares? Or perhaps the recent downturn in small caps presents an opportunity here. There’s an investormeetcompany presentation this morning, at 10am, which will be a good opportunity to hear from the CEO.
Wilmington (LON:WIL)
Share price: 238.65p ( +9.47%)
Shares in issue: 87,591,559
Market cap: £209m
Wilmington is a provider of data, information, education and training services in the global Governance, Risk and Compliance (GRC) markets.
Trading update for H1 to 31 December 2021
Wilmington ended the first half of the current financial year ahead of expectations for revenue, adjusted PBT and net cash/debt.
Double-digit organic revenue growth and adjusted PBT significantly up on the same period last year.
Net cash (excluding lease liabilities) was £11.0m with strong trading being augmented by the sale of the AMT Training business in December for £23.4m. All bank debt has been repaid.
Both divisions traded well in the first half, with events revenues returning to pre-pandemic levels. Strong first half trading and the return to face-to-face events means that profit for the financial year is expected to be comfortably ahead of expectations.
Diary date - full results for the six months to 31 December 2021 to be released on Monday 21 February 2022.
Mark Milner, Chief Executive Officer, commented:
Our divisions and teams are performing strongly. The resilient nature of our digital business delivery, the return of face-to-face events and our investment in new products and capabilities means we now expect profits to be materially higher this financial year.
Conclusion
The recovery to pre-Covid share price levels is complete, but it’s worth noting that the group appears to have disappointed the market pre-Covid, back in 2018.

Wilmington has been on a bit of a journey over the past few years and has restructured, with a clear focus now on regulatory and compliance markets that offer structural growth opportunities. The group structure was simplified into two main divisions back in June 2021: Information & Data and Education & Training.
Results have been choppy over the past five years but Wilmington has remained cash generative, with no equity dilution and falling levels of net debt. So if it has got its house in order then this could be an interesting opportunity. It seems like a decent business at a decent price, with signs of improving operational momentum.
There could be additional upgrades as the year progresses. The StockRanks are weighed down by previous results, but if the company has changed then so too have its prospects. The liquidity scores are poor though, and the balance sheet is not the strongest. On balance, it’s probably worth taking this one a bit further.
Strix (LON:KETL)
Share price: 248.25p (-1.49%)
Shares in issue: 206,671,946
Market cap: £513m
Strix is back in SCVR territory, having given up most of its 1Y share price gains over the past six months.

This is a leader in the design, manufacture and supply of kettle safety controls and other water temperature management components.
Trading update for the six months to 31 December 2021
The Group has achieved circa 30% revenue growth on a constant currency basis and profit after tax in line with market expectations for 2021.
Market expectations are for profit after tax of £31.4m according to FactSet. Well done to Strix for including this, it’s a small but important detail that many others gloss over for some reason. Clearly, it’s an important reference point to include.
The performance underpins management’s medium-term target of doubling revenue by the end of 2025, primarily through organic growth in its Water and Appliances categories. An important driver will be new product development initiatives. That’s something the newly appointed chief technology officer will no doubt help with.
An example of this new product development:
Strix also continues to work closely with its key partners and own brands to bring technological innovation to the markets delivering core benefits in usability and sustainability to the consumer. The launch of the Induction kettle in December 2021 was an example of that which also won a highly prestigious German award for excellent product design.
On managing well-known pressures:
Strix continues to proactively manage and mostly offset the impact of a number of headwinds which continue to persist including supply chain, freight cost inflation and adverse foreign exchange rates. This is being achieved effectively through price increases on some of its legacy products, implementing hedging strategies as well as a range of other efficiency measures and strategic initiatives. Additionally, the Company crystallised a tax benefit in relation to the factory opening which is expected to result in a lower effective tax rate in 2021.
Kettle Safety Controls, Water and Appliance Categories
Continued positive volume growth here as Strix increases the number of specifications using its latest platform ranges and regions.
With the combined contribution of LAICA and HaloPure technology, the Water category has made solid progress. The trading performance of LAICA has been particularly strong, while HaloPure has now secured 14 contracts.
Within the Appliance category, Aurora (Instant Flow Heater/Chiller) is starting to show signs of penetrating consumer markets across the world and is performing ahead of budget.
Corporate and Operational Review
The new manufacturing operations within Zengcheng district in Guangzhou, China are now fully operational.This has doubled the group's manufacturing capacity enabling it to grow the business, increase efficiencies and implement further in-sourcing opportunities which are expected to have a positive effect on margins over the medium-term.
Financial Position
Net debt (excluding the impact of IFRS 16 lease liabilities) as at 31 December 2021 was £51m which is higher than previous guidance as Strix has invested to minimise the future impact of continued commodity price inflation.
The group says it has enough to continue with its capital allocation priorities and pursue the purchase of niche companies or technologies. I would want to investigate the financial position a little further, personally. It’s not too much in the context of a £500m+ market cap, but given the backdrop more of a cash buffer would be reassuring.
Diary date - The group will be announcing its preliminary results for the year ended 31 December 2021 on Wednesday 30 March 2022. We should see the balance sheet then.
Conclusion
An interesting company with growth potential, but there’s not enough in today’s update to tempt me away from the sidelines. Sentiment is poor and the market currently unforgiving, so I’m minded to just keep tabs on the share price for now.
There have been some chunky director sales recently, as well as an increase in short interest.
The share price has suffered more than most over the past six months. There are headwinds, and I note that Zeus is taking the opportunity to trim its forecasts (which were at the top end of consensus) not just for FY21, but for FY22 and FY23 as well.
The group needs to prove to the market that it can grow. This is what analysts anticipate, and what the company itself is guiding to with its ‘doubling of revenue’ ambition.

I think you can take this update either way. Revenue is up by 30% at constant currency and the group has been able to mitigate some of the pressure with selective price increases. And the new factory is a major positive moving forward. Free cash flows should increase in the years ahead as related capex spend falls away.
Ultimately though, I don’t think there’s enough here to redirect market sentiment. There’s a bit too much for sellers to hold onto, namely net debt higher than expected (albeit as a result of increased inventories) and ongoing headwinds. So I’ll continue to watch from the sidelines for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

121 comments
Very interesting. I was an early holder of @KETL at around 130p I sold out at 300p a while back but it continued to grow to higher 300p territory. Price has been offset by pandemic; my concerns are also towards a slowing Chinese market, Strix does hold around 30% market in China but I can’t remember what proportion of revenues are generated overseas from the top of my head - one to keep abs eye on: gearing percentage and liquidity ratio is why I sold. That being said, if it has consistently raised its dividend, has good operating margins around 25% and a dominant market share. I would prefer it if the cash position was a little stronger; Also it’s very expensive from book value perspective. 30% drop over last 6 months is unwarranted, however, it wouldn’t surprise me if it fell another 10% or so before FY results are released - I’d wait for the results before buying back in as it may create further value.
Thanks,
GI
Hi Paul. I dont get chance to read the SCVR & subscriber comments until night due to work commitments so you probably wont see this…. But just wanted to say how much I enjoy them - and the recent “ramblings” have been a Brucey bonus. I am too contrarian to “copy” & never blame others if things don’t work out. It’s only me who can hit the buy button - I am also very LT- eg it might be fair enough for #BOO (I hold) to drop now but I am trying to guess the SP in 3 to 5 years not tomorrow. The SP movements in #SDG (I hold) are a great example of this. 3 upgrades; positive licensing etc. Yet the price today is same as 20/7/22 before those upgrades came. As an MD of a good sized business (qualified accountant & did Economics at Uni) I wouldn’t underestimate how useful your posts are (and Jacks & other posters - well most of them….). I think business leaders should spend more time looking at what investors deem to be Bull & bear. Finally for what its worth I think the reaction to interest rates increases is ridiculous. So what if we have 4 x 25 bps increases in the US this year. Yes if we are going to see base rates of 5%++ within 24 months thats a worry. FWIW I think inflation will be at the top end of ranges (7%+0); prices will “re rate”. Lots of people retiring early. Wage inflation. But then it will settle. I am an optimist but i think thats all positive in the long run. Wages rebase. Interest rates (say) 100bps higher. Inflation back to c3%. Property will continue to be a strong “currency”. Thanks again, your work is always top quality. Whether people agree or not is irrelevant. It’s takes 2 to make a market & at the end of the day its only money. Thanks!
Just catching up on taday's comments, and haven't read all, so this point may have already been made.
Re Saga (LON:SAGA) and other travel and hospitality shares, the bull case seems to assume that the pandemic is over as Omicron fades. But what happens if another COVID variant appears? That has been the pattern so far. It is not just a UK issue - cruise ships usually dock in ports in foreign countrie which may not accept them (has happened before). I am happy not to hold.
Richard
Saga (LON:SAGA)
I don't think the Bull case is totally reliant on Covid going away - they are broadly breakeven this year with covid issues. Would it be the end of the world if they were breakeven again next year with similar issues probably not although the debt does ned servicing. There is huge debt here so its not for widows and orphans - anyone investing should be doing so on the basis they know they could be wiped out . if a more mutant strain of covid re-appears and hangs around for a while it will be bad new for saga for sure.
Good afternoon Paul and Jack. Paul, I join with all the others in thanking you for your additional General Market comments. I am a regular here but I dont read every single comment by readers! Therefore my next comment may have been covered several times over. It is this.
The SP of many shares doubled, trebled in 2021. Therefore, given the considerable uncertainty that was building before Christmas and has certainly hit us since then about inflation, delivery issues, it would not be surprising if many people took some of their gains off the table.
Without any other effect facing a given stock, that could generate a sharp fall in the stock even if he fundamentals have not changed (and some have of course). I surmise that many investors will now be partly or significantly in cash and waiting for the bottom / near bottom to return to the market - in some cases, even to the same stock they sold out of earlier.
I wonder if you think my theory has any merit, and even more important should lead me not to ditch a stock where I may have paid too high a buy -price towards the year end? Thanks in anticipation.
Lookers (LON:LOOK) with some big late trades a takeover possible nice breakout
Watched that...was hovering at buy at 88...did not go through with it
I missed that one :(
I didn't look.
Picking up on the discussion two days ago:
As I said two days ago, seems like a distraction for the Russian people to take then away from covid than anything else.
2. Thg (LON:THG) up 15% in the past two days since the discussion on it. At least one broker has upgraded it to outperform on the basis of it being deeply undervalued - as I said two days ago, something funny has gone on with the whole libel Numis fake news situation.
3. And finally, Netflix, up over 7% today as Bill Ackman buys a big stake. - must have been reading my comments to buy the dip in it two days ago and got FOMO.... :))
Final 5p worth: With a very dovish Fed again and huge US Q4 GDP beat, there are reasons to be optimistic for shares if you search out the Quality that are now bargains.
Sure 'taper tantrum maybe and all that' but how long before that really happens and how much will be the compounded returns until it does? No one can say with certainty and waiting to buy an even bigger dip than this one historically doesn't have a good record against buying broad, diverse and consistently.
Many studies have been done on this. E.g.:
https://www.google.com/amp/s/w...
Many people talk of doom (like a broad large bear market) but I'm interested in how many actually think it is likely - especially from here.
Incredible how people can have such vastly different perspectives. But I'd say there are many more people that seem to believe there will never be a big bear market, and that the big indices, SP500, Nasdaq, are completely devoid of risk.
I've said it before but I think if you have another 10 years (the scope of time I am interested in as an investor, not a trader) of returns like the last 10 in these indices then you are really stretching all historical precedence. What causes Amazon to grow another say 5-10x over the next decade for example, where do you find all the additional revenue required, never mind profits? Same applies to Apple, Google, Microsoft etc etc, all the huge stocks that need to perform to drive the market higher. A lot of this seems fanciful to me. GDP growth just won't support it. They would need to cannabalise huge volumes of revenue from other companies.
That is the age old argument people have been making for decades.
The world economy is $88 trillion. $88 trillion increasing each year at a compounded rate.
Apple surely can double again.
I think the answer to that is that the growth comes from areas that you do not expect. You have listed the current big players like Apple and Google, the future stars will be companies you have never heard of. There are massive gains to be made, for example, in two very easily understood areas: healthcare and energy. In the next 10 years I can say with a very high level of certainty that there will be $10bn+ market cap companies who as yet you have never heard of.
I don't remember seeing such a discrepancy between index's before, FTSE100 up 1.3% and aim down 1%
Totally agree it's seems like a complete stich up but it can't be. 250 also hammered, I don't get it. We don't follow the US up but we sure follow the down.
Just a brief note of admiration for a bumper selection of market and company analyses and comments in the postings section from Paul and Jack. I don’t know how you do it.
I am slightly disappointed at the take over of Air Partner as I hoped to hold it for what looked to be a rosy future with regular dividends, but at least the profit can be recycled into some shares at reasonable ratings.
I know the MD he is very happy !
US economy grows at fastest pace in decades
"Official figures from the Commerce Department showed the economy grew at
an annual rate of 6.9% in the last three months of 2021."
Highest YonY since 1984.
Re Morses Club (LON:MCL) - no trading update but down 25% in last 2 weeks & vs the level it had been roughly trading at for last 3months. Trading volume up significantly in last 3 days but so far as I am aware, no significant news on regulatory or company specific front. It is now at a level of unbelievable bargain for income or about to be engulfed by a disaster! Stock rank 77 (Q90, V90, M23).
I have been following (and owning) for years and thought it about to come good as loss making digital lending division should be moving into profitability this half year and the market conditions for lending to people with poor credit scores seems good to me (market growing, competitors exiting, govt spending up, regulations stable).
Have I missed something?
Zipmanpeter
Morses Club (LON:MCL)
like yourself I was hoping for a quarterly update. I get comfort from their December statement that
"Further funding arrangements for the Group have now been confirmed until 31 March 2023, and the business is trading in line with expectations, with continued strong customer demand for credit products in both trading divisions"
I'm also glad that they stopped wasting money on rearranging their business. In my experience this just leads to obfuscation in comparing results with prior years (hopefully not like deckchairs on thr Titanic
Ever hopeful
Paul,
I would like to echo the sentiments on your market commentary. In uncertain times i feel it helps a novice investor like myself stay sane. Please make sure it doesn’t cause you to be overworked and burnout though.
The below made me laugh and brought a sense of reality to my day.
“It could cause a spike down in markets, if war kicks off, but does it affect the value of Tescos in the long run? No. Or if the worst case plays out, the value of Tesco’s won’t matter.”
Saga (LON:SAGA)
Numis - which has a 'buy' rating on the stock - called the trading statement "solid".
"Overall we think this update shows Saga’s business is going to plan, underpinning our thesis that a recovery in cash flow will drive deleveraging and transfer value from debt to equity, with the current enterprise value of £1.1bn (£747m debt, £393m equity).
"We reiterate our bullish stance, with upside of 63% to our target price of 460p."
https://www.google.com/amp/s/www.sharecast.com/amp/news/news-and-announcements/saga-upbeat-for-future-growth-despite-covid-hit--9104250.html
I discuss company specifics here pretty well every day, probably as much as any other subscriber!
Well, that's very welcome, keep it up. Some of us understand your tangible surplus approach but don't agree it's the only way of finding good companies for long-term investment and making above average risk-adjusted returns. I just get bored hearing about your performance (must be 3 or 4 times on different threads I've read about it) and how great companies like Microsoft are all crocks. That's just nonsense. I bet you would have said the same thing 18 years ago when I was hoovering it up for $27. And yet it's on exactly the same PER etc. as it was then. Never underestimate the power of compounding...
Haha, he told the intern reporter on the Daily Telegraph she’d overpaid for Microsoft at ~$150 less than two years ago.
Great summary as ever.
One comment though - £WIL. Jack writes the "The liquidity scores are poor though, and the balance sheet is not the strongest".
If I am reading your summary correctly and the company's trading update, it says there is Net cash (exc lease liabilities) of £11.0m and NO debt. I would argue that is very strong?
i dont hold Colefax (LON:CFX) so have only just seen this mornings release of their half year numbers to 31/10/21 but on the surface they look very good, hopefully a positive read across to Sanderson Design (LON:SDG) which i do hold .
Oddly Colefax (LON:CFX) are up,Sanderson Design (LON:SDG) are off a tad.
Having commented on Strix (LON:KETL) earlier today I read Jack's report with interest .This has been one of my more successful investments over the last 2/3 years with the share price rising from around 140/150 in 2018 to around 250 now - the share peaked at around 300 in September and like many small/mid cap companies it has been going south since then . This does not mean that the fundamentals have changed -a PE of 15.7 is not demanding - you mentioned that the company needs to show that it can grow but the TS indicated that revenue was up by 30 % - how much more growth do you want !! What has changed in the last 6/9 months is supply chain issues , inflation and exchange rates . I have been waiting for the TS with some trepidation because these 3 "factors" could easily have impacted the bottom line .This has not happened because the strength of their intellectual property and new product development has meant that they have mitigated these factors as I commented in my earlier note.
Equity Development have just published a research note and I enclose their summary ( to counter the Zeus one )
Valuation
Strix remains confident of its strong positioning, but we prudently shave our FY21 adj. EPS
estimate by 3% to reflect the headwinds discussed. Our fair value / share adjusts to 350p, still
more than a third above current levels.
On balance I think that this bodes well for the future and some of the spare cash that I have may well be invested in Strix
Strix (LON:KETL) revenues are growing nicely, but the all important EPS seems to have been flat for years and looking at broker forecasts not expected to grow much in the coming years either. Not quite sure what is going on there?
I have held Strix (LON:KETL) in the past , uncertainty over China could possibly be a reason for underperformance.
Three points to note re Strix (LON:KETL) discussion above.
1. 30% revenue growth mostly due to Laica acquisition, not organic (also part share funded, hence disappointing eps outlook)
2. Price earnings ratio is distorted by low tax charge due to Isle of Man base. Arguably a permanent feature but does affect comparisons with other shares, eg on EV/EBIT ratios.
3. Forecasts met for profit AFTER tax but update mentions tax benefit crystallising re new Chinese factory, implying pre tax profit expectations may not have been met (unless expectations incorporated that tax benefit).
So still a cracking core business in terms of operating margins and ROCE but jury out on growth: core business too dominant to grow, acquisitions and product diversification initiatives yet to prove they can make up for that.
I'm not keen on Strix. I don't like the connection with China, and the numbers have always struck me as a bit weird. The business model doesn't make sense to me. So not one I would touch.
P.
Not sure I agree with you but that is investing for you . The same time I got in to Strix I also invested in Boohoo and of the two and hopefully you will agree that the former has been more rewarding
RE Headlam (LON:HEAD) – Pre-close trading update is very clear and IMHO excellent.
Headline “Profit slightly ahead of expectations, with strong cash generation” (Not in headline is a slight revenue miss but I know which I prefer.)
Market expectations³ helpfully shown as “2021 revenue, underlying, profit before tax, 2021 total ordinary dividend and net funds at year-end, are £680.7 million, £35.0 million, 14.4 pence and £51.3 million
respectively (on a mean and post IFRS 16 adoption basis, where appropriate)”
So a 3.2% historic yield on current price. More excitingly, due to
the Company is considering a potential surplus return – details in March.
So, dull but rewarding. (Disc. I hold – very happily)
As a previous holder of Headlam (LON:HEAD) the trouble I see is this….
The residential carpet market has had a huge boost from (a) the frenzy of house moves caused by the stamp duty holiday and people re-evaluating where they want to live as a result of COVID, and (b) the huge amount of spending on home improvements caused by working from home and holidays and eating out being off the menu.
Those two factors are largely one offs that will not repeat to anything like the same extent. So, market conditions in the residential market are I expect going to be significantly less benign in the future. Additionally, all that activity will have brought forward sales from the next couple of years into 2020 and 2021.
This suggests top line growth will be much harder to achieve for Headlam and they will have to rely on internal efficiency savings to offset cost inflation.
So, I see the future for them being stagnant at best and with a significant possibility of profit warnings in the future.
If this thesis is true then could be difficult year for a few other companies linked to the home improvement market , Norcros (LON:NXR) and Wickes (LON:WIX) both spring to mind and regularly feature on here. Definitely something to bear in mind.
Paul: "If we end up (UK similar to US) with perhaps 2-3% interest rates, and 6-7% inflation, then where is the best place to invest?"
I think the point is we wont end up with that situation. We might have it temporarily but we wont end up there. Why? Because we cant have real interest rates at -4% for the long or medium term. That is one thing that certainly would generate demand led inflation. Real rates dip down this low very rarely and soon reverse. Looking at the US figures, the last time real rates fell below -4% was in 1980 due to the oil crisis at the time. That lasted for 1 month.
The reason the Fed (same for BoE) are allowing real rates to persist this low for now is because they still believe that supply will come back on tap and that will cause inflation to fall without them having to do much. They have shifted this position slightly (mainly because they now see the shortage of labour as a longer term issue) but the fundamental view is the same.
This is extremely rare in history. The only real equivalents are after major wars. It is much more common for inflation to be due to overheating which central banks duly respond to. That is why holding shares at a time of high inflation has such a poor record. The record shows that in these periods it has been a much better idea to hold cash and other non equity assets.
If supply adjusts and inflation falls then stocks have a fighting chance. But if supply adjusts too slowly and inflation becomes embedded, then central banks will act (they have mandates after all). In that situation, history says that holding 100% equities will be a very poor strategy.
“holding 100% equities will be a very poor strategy.”
Much of the point of this board is to pick equities that do not conform to an overall statement, so yes, companies with a lot of debt will get a shellacking as rates rise, but there are plenty with net cash who will get an extra boost. Similar points around foreign exchange impacts.
Markets can be large enough for a good small cap to grow strongly without being constrained by the macro outlook. Stock picking of course has risk but there many who have reaped more than commensurate reward.
My bias is that at pretty much all times there are companies to be found that are building their value above the rate of inflation, we should keep on trying to find them.
Paul, Re Saga (LON:SAGA) and the comment I’m only airing that to see if there’s any negative ESG type angle on cruise ships, but I don’t think there is, if the company is run ethically, which SAGA very much seems to be now.
Cruise ships in general are dreadful polluters. You might expect that Saga's newer ships are less bad than average but I'm not seeing much detail on that in the ESG section of their annual report. Their ESG piece on people is very thorough, but the environmental bit is around company cars and buying green electricity for their offices - I don't think that's been much of a focus for the new management yet, especially when their emissions were low due to the ships being stuck in port.
I don't suppose that will stop them finding customers to fill the ships though.
https://earthfirst.org.uk/envi...
Hi John,
I thought that cruise ships were less damaging than planes? Maybe not. Surely it's the vast number of container ships bringing in cheap consumer goods from the Far East that must be far more damaging? Also people burning peat, charcoal, and wood, are massive polluters, but wrongly think they're somehow being eco & tree-huggy!
That's not to detract from you pointing out the pollution angle on cruise ships, I hadn't thought about that.
P.
There's a company registered on Aquis called Sulnox which claims to have a green bio degradeable fuel additive that can increase efficiency and reduce carbon emissions for various types of transport including diesel users. Sales are low at the moment, but could add something to improve the carbon footprint of shipping which are a significant producer of harmful emissions (far greater than planes, I believe). I think they have some shipping companies trialing the product.
It claims other fuel additives tend to be carbon based.
They have appointed a distributor, and are launching a release on the Amazon platform.
I don't hold, but was interested.
Hi Trident,
I seem to recall they had an appearance on a Mello Monday a couple of months back (or maybe it was on another You-Tube video).
It all sounded very good on the presentation with lots of potential, but the more I looked into it the more I saw that they didn't have a moat, and there were a lot of other similar products out there.
Seemed like a very high-risk proposition and the risk/reward ratio was not going to be heavily enough on my favour.
Best wishes. K
Re Saga (LON:SAGA) (I hold)
Thanks Paul for your excellent report. Just a couple of points.
I looked at design reports of the two new cruise ships when they were on the stocks. They were very much the latest in thinking with ESG considerations well up to date and beyond most of the competition. SAGA apparently specified running economy as imperative. Intriguingly I am told that they are possibly the first ships to have an independent fresh air supply to each cabin cutting out the dangers of recirculating (designed well before Covid struck!) though I have been unable to verify this. Equally I cannot find anything about dual fuel capability or otherwise which seems now to be gaining merit points from the box tickers.
Cabin prices are not cheap and sell at a premium to Fred Olsen who are arguably the number one competitor in the over 50s market. However I have a cruise booked for April and SAGA tell me that it is now fully booked so no last minute discounts reducing margins.
The call centre experience for both cruise and insurance matters is to my mind very good with friendly and well trained staff. Insurance marketing mail shots seem to me to be well managed. The cruise marketing operation however leaves much to be desired with masses of irritating mail shots. I have decided to write to the ceo with some comments….
Best
Mark
I think there are 2 different issues here. My reading is Planes are far worse for putting greenhouse gases in the air (largely because they are doing it at altitude) which is very bad in our current situation. I think cruise ships are more polluting for what they put in the water. Clearly both are bad but different bad. Ditto burning peat, charcoal and wood. In my view we have to get over which is less bad and think what is good. For example gas is less bad than coal but it is still a hydrocarbon and with carbon in the atmosphere at an all time high in man's history probably not a good idea to burn more than we have to. To completely confuse everyone I am a Saga holder but a very confused investor and many think far too much of an environmentalist!! Please don't make this into a shouting match we all have our own views.
Apologies to you both appears I am wrong.
Environmental Impact of Cruise Ships (earthfirst.org.uk)
No question then that ESG will be a drag for cruising industry and I suspect will become a bigger issue in time as the topic get ever more media and politico attention. Difficult to work out how to price this in.
Re Saga (LON:SAGA) and ESG issues....Saga cruiseships are basing themselves out of Portsmouth.
The appeal includes the fact that the Council run port is aiming to be the UK's first zero emissions port via a whole programme of practical green actions. This includes
The SAGA ships are also new and efficient. Net, until cruise liners get stopped, Saga are very well placed to handle ESG issues and indeed make them a positive PR point.
(For the 50+ Saga cruise customers (not always the greenest anyway!), Portsmouth is also the historic home of the Royal navy, the port goes straight onto the M275 but is also close to the historic sea front. )
(Disc. I own Saga (LON:SAGA) and live in Portsmouth so may be doubly biased!)
Portsmouth harbour only has shore-to-ship power for smaller cruise ships. For the rest they are having to develop their own solutions due to the lack of UK electrical generating and distribution capacity so Portsmouth residents will all be breathing in more pollution from the ships burning the most polluting fuels for some time as the harbour expands their cruise offerings. They are at the prototype stage: https://portsmouth-port.co.uk/...
JohnEustace, Agree that Portsmouth port is still aiming for zero net emissions, which may still leave some gross emissions (geddit!) in Portsmouth presently, plus there is a wider point that cruises are frankly not very green in any form IMHO but the response started around the investor ESG risk to Saga (LON:SAGA) .
I would argue that Portsmouth > Southampton for instance and thus that the overall ESG "story" Saga can tell on its new, "efficient" ships to its potential customers (likely to arrive in large gas guzzling cars, implicit judgement intended!), is actually quite good vs its competitor set ie other cruise lines and there is no serious sign of them being banned as a class. :)
For sure running cost will be foremost in the minds of the buyers, its margin gain after all
Hi Paul, many thanks as ever for your extremely insightful commentary, preambles and analysis, always the highlight of any early morning - measured, sensible clarity of mind is a bit of what we all need right now.
I recall from your Oct 21 SCVR that you held Luceco ( £LUCE ) - if you're going through a backlog I wonder if you wouldn't turn your attention to the Jan 20th TU:
Revenue +36% vs 2019 (and +32% vs 2020)
Stating that they're passing on price increases to customers without adversely affecting demand
Margins roughly maintained (OPM of 17% vs 18%)
with lower than expected net debt due to strong H2 cash generation
With the fall in SP sub 300p your thoughts on this would be very much appreciated by, I'm sure, a number of subscribers as well!
All the best
Ucemarn
Hi Ucemarn,
Sorry I didn't get round to looking at Luceco (LON:LUCE) - there are loads of things I'd like to look at, but we keep running out of time, as there are so many updates every day.
I'm a bit worried that, supplying things for consumer & trade DIY type things, LUCE might have seen a one-off pulling forward of demand, for people to make home improvements when they had nothing else to spend holiday/leisure money on.
That could be true for lots of companies that had a bonanza in the pandemic.
For that reason I'm a bit wary about LUCE, and also its profit margins almost look too good - which makes me worry it might be susceptible to competitive threats maybe?
I'll leave it for now, and revisit LUCE on its next update.
Regards, Paul.
Thank you Paul, very much appreciated, looking forward to it!
All the best
Ucemarn
“Flipping the PER upside down, converts a PER of 20 into an earnings yield of 5% (1/20 * 100). That means our company with a PER of 20 is not generating enough after tax profit (earnings) to match inflation.
To match inflation, we need a share with an earnings yield of 7%. Invert that to get to the PER, and it’s 14.3. Therefore I should be very happy buying a share on a PER of 14.3”.
I’m struggling to understand your logic here Paul – you appear to be suggesting that only those companies currently on a p/e rating of 14.3x are capable of generating shareholder returns of 7% or more?
Nothing could be further from the truth.
The key determinant of profit growth is of course the rate of return (ROCE) that a company is capable of achieving. If a company
then its profit growth will be equal to its post tax ROCE.
So a company earning a post tax ROCE of 8% will achieve profit growth of 8%.
A company earning a post tax ROCE of 17% will achieve profit growth of 17% etc
Hence for the investor, assessing the sustainability of ROCE (assessing the width of the moat) remains key.
Of course, larger companies tend to do a combination of retaining Net Income & returning some cash to shareholders in the form of dividends/buybacks. This reduces profit their growth potential, all else being equal.
Hi Epsilon,
Good reply thanks, although I think you've got the wrong end of the stick a bit, about what I was discussing! My fault for not being clearer.
I didn't explain my thing about earnings yield very well. I was just bouncing ideas around, and looking at things in standstill, to reasonbleness-check what PER might seem appropriate in a higher inflation environment.
So c.14 PER would be my base point for a value type share, where I'm expecting earnings to probably remain around static.
But as you say, for a higher quality, growth type share that is going to grow earnings more strongly, then you'd be justified to pay a higher PER, without going mad.
ROCE is a good measure, as you say, but a crowded trade, as so many people use that to select high quality companies, and end up over-paying sometimes, as we're seeing in the valuation reset going on at the moment.
Also BOTB (I hold) highlighted how great quality scores over many years, can instantly unravel if there's an uncontrollable cost that soars (online marketing). So I think we need to be very careful with ROCE and online businesses in particular.
All interesting to discuss, so thanks for your contribution.
Regards, Paul.
P.S. I think maybe "nothing could be further from the truth" in bold, was a bit heavy-handed!! - I'm only bouncing ideas around, not stridently dictating the only way to value shares! ;-)
A more simplistic way, and one that I use is - providing the company can grow earnings above inflation, and provided the multiple remains the same, then the share should deliver returns ahead of inflation. This would apply whether the share is on a cheap 10x multiple or expensive 25x multiple. The key thing is ability to grow earnings.
Thankyou as ever Paul. I find your preambles useful in that they generate a thought for the day which is helpful. I am reading Putin's People by Catherine Belton. A belter of a book very well researched. The potential level of corruption is in my opinion a serious threat to our capitalist structures.
Impressive Trading update this morning from Strix (LON:KETL) ( I hold) particularly in the context of the discussions on inflation and supply chain issues .
Strix has experienced continued positive momentum in H2 2021 and the Group has achieved circa 30% revenue growth on a constant currency basis and profit after tax in line with market expectations for 2021*
Strix continues to proactively manage and mostly offset the impact of a number
of headwinds which continue to persist including supply chain, freight cost
inflation and adverse foreign exchange rates. This is being achieved effectively through price increases on some of its legacy products, implementing hedging strategies as well as a range of other efficiency measures and strategic initiatives.
From my point of view an inline trading statement at this stage of the cycle is good news and I continue to hold
Been watching Cambridge Cognition Holdings (LON:COG) for a while and bought some this morning based on their reasonable trading update. I’m sure Paul will cover as I believe he owns some.
Hi Bullygig
Cambridge Cognition (LON:COG)
I am a holder so biased
Bear case
Highly illiquid
Losing a contract can have a meaningful impact but COG are growing, signing more and more contracts with existing and new clients. Not overly reliant on one client as IXI were (they had one client worth 60% of their revs). COG now have an Order book of £17m, £7.5 for this year and £10m for future years which is a massive change compared to 2 years ago
Bull case
I think the results are very good. Forecast revenue for the year was originally £8.5m and was upgraded to £10.1m which was achieved against FY20 Rev of £6.7m = growth of 50%
PAT was ahead at £0.5, forecast £0.1 and look very good against loss of £0.4m in 2020.
Cash £6.8m means they have plenty of money to fund their growth and looks good against £3m in 2020.
Order book looks good too. £17m of which £7.5m for 2022 against forecast of £10.8 so circa 70% of this year's rev already booked.
So 2021 v good progress after same in 2020.
Gross Margin 81% so most revenue drops to bottom line
Well placed to profit from industry wide trends
Excellent reputation
Impressive client base including many top pharma
Matthew Stork CEO has transformed a poorly managed loss making company likely to run our of money into a profitable, well managed one with excellent prospects and a decent balance sheet.
Michael
Thanks Michael. The cash figure was the thing that made me press the button this morning, looks very healthy!
Thanks Michael Tee, that's a superb review of Cambridge Cognition Holdings (LON:COG) (I hold), not sure I have anything to add to that! Might be easier to just direct readers of the main article to your comment :-) A SCVR first!!
Best wishes, Paul.
Paul Scott,
Thank you for your kind comments. I am honoured. Made my day!
It is also pleasing to get confirmation that you view the investment case of Cambridge Cognition similarly to me.
Let's hope the next 2 years of their growth is as good as the last 2 years.
Best wishes,
Michael
Cambridge Cognition (LON:COG)
Additional points:
The cash position does include some up front payments.
The £17m Order book is at end December 2021, so does not include the £700,000 contract win announced 10th January meaning the £7.5m rev booked for 2022 (70% of forecast for 2022) is actually already higher.
Cambridge Cognition Holdings (LON:COG) (no position)
Thanks for your comments here Michael.
Below is a small table with some brief notes I try to keep updated for anyone interested:
Hi Abtan,
Cambridge Cognition (LON:COG)
Thanks for this table.
Some delays in contracts are mentioned in the update. I think most companies lose some contracts but it is important to keep track of this. I actually view this positively as revenue targets were met in spite of the apparent loss of orders and would have been higher were the contracts not lost.
Micheal
Paul, I would really welcome your thoughts on Eenergy (LON:EAAS)
many thanks
CR
A lot of valuable intangible assets never appear on present day balance sheets so I think the growth in tangible assets thesis is flawed unless you want mainly to invest in property or manufacturing businesses.
I think what it scaring the market is explained in your well written preamble. (Thank you Paul).
Namely inflation that has already reached 6-7% & is now “now more persistent than expected, and has spread into other sectors,”
And
”Is there a risk of interest rates ballooning to say 5-10%? Very little, in my opinion, because that would trigger an economic meltdown - households and indebted companies just couldn’t afford that level of interest rates, ”
So what do they do ?
The traditional alternative is to put up taxes.
Actually, I'm not sure that the FED can put up taxes - but the US Government could. On the other hand they can control the amount of money in circulation, as well as its price.
The Fed policy seems to be to flex the rate at which they allow their bond purchases to run off. They are currently debating what proportion of the funds they get from the natural expiry of the bonds they own gets reinvested in new bond purchases. They are still some way from stopping new purchases altogether, let alone selling down their book more aggressively.
They also say that their response in the next crisis will be to ramp up their asset buying again.
Hi Paul, for the novices like me could you please explain what the cash offer of AIR Partner means? Air Partner (LON:AIR)
Air Partner (LON:AIR) - the questions are sell or buy more if think undervalues the co and a bid war about to start. I won’t buy more but a little glow in the darkness was welcomed.
Well Done to Air Partner holders and well done to Jack who is a holder.I bought a year ago and was getting frustrated at lack of movement.Buffet said "Impatient transfer profits to the patient" he's not wrong.Any takeover I sell straight away and move on.Yes there may be a bidding war but bird in the hand etc. - see Metro Banks recent debacle.I got it wrong with Countrywide as there was a bidding war but that's life.
Hi Wornoutmk, the cash offer for Air Partner (LON:AIR) means quite literally that Wheels Up UK Limited are offering to pay 125p per share to buy the entire company. The share price has reacted by shooting up to slightly below that figure (the reason it hasn't gone straight to 125p is that it's only a done deal when approved by shareholders). In the meantime, there is the possibility that another bidder may appear with a better offer so it's not immediately the best option to sell out at the new current price.
A prudent course of action depending on your situation, might be to sell half at the new price (in case the deal falls through) and keep half on the table (in case a higher bidder comes along).
Hope that helps.
Thanks John. I was planning on doing the sell 50% keep 50%. When the buyout concludes are the shares you still hold automatically sold?
Yes, once the deal concludes, your share-dealing account will be credited with the cash equivalent of your remaining holding at the time of the sale.
Good advice by others. FWIW I have decided to sell at 123.21 as happy with a more than 50% increase on price paid 6 months ago,and will use the funds to buy more £SAGA
Given that Air Partner (LON:AIR) was trading at 150p before the pandemic, and currently sits on a P/E of around 9, I'm optimistic that there may be other interest in this and wouldn't rule out another bidder coming in. It's a decent, diversified business which should fare well from the re-opening of travel and I see this bid as somewhat opportunistic because effectively they are front running the recovery in air travel. I hold and don't plan on selling any at this stage. Keeping my fingers crossed that Wheels Up aren't the only ones who have spotted the value here.
Given that Air Partner (LON:AIR) was trading at 150p before the pandemic, and currently sits on a P/E of around 9, I'm optimistic that there may be other interest in this and wouldn't rule out another bidder coming in. It's a decent, diversified business which should fare well from the re-opening of travel and I see this bid as somewhat opportunistic because effectively they are front running the recovery in air travel. I hold and don't plan on selling any at this stage. Keeping my fingers crossed that Wheels Up aren't the only ones who have spotted the value here.
Well, there's no doubt Wheels Up have the cash. They reversed into an acquisition vehicle to get a NYSE listing only last July and have over $500m in cash, so Air Partner (LON:AIR) is small potatoes for them. It looks a good strategic fit for Wheels Up and a good use of some of their cash whilst being at a nice premium for us Air Partner (LON:AIR) holders, so I would judge the likelihood of this not happening to be quite small. I've sold 40% as I would like to recycle the funds in the account they are held in given there are some proper bargains about. The rest in my SIPP will be held until completion.
All the best, Si
The market clearly does not think Air is likely to get a better offer as the price is below the offer (unlike Morrison) where the price stayed above the offer all along.
If you have a better place for your money sell half or all. otherwise stay put and you may get a few quids more!
"Keeping my fingers crossed that Wheels Up aren't the only ones who have spotted the value here".
Well, a competitor of Wheels Up is NetJets (Revenue $2bn) owned by Berkshire Hathaway. Anyone here able to have a word with Warren Buffett?
Re earnings yield. Given that earnings can so easily be exaggerated, why not assess the tangible surplus - average annual growth in net tangible assets over the past 4 years, added to the yield, the sum expressed as a % of the MCap.
This is a far more dependable as a way of assessing what the business actually generates for shareholders and what you are paying for those returns.
Obviously you also need to adjust for share issuing or share buy backs, but once you have done that, you really have pinned down what the business is creating for shareholders relative to what the investor is paying.
Doug2b
This is a far more dependable as a way of assessing what the business actually generates for shareholders and what you are paying for those returns.
Apologies for labouring the point but there is pretty much universal agreement that your chosen metric is only looking in the rear view mirror and is not perfact. Have you thought of adding IMHO after your comments in this regard. The facts are the future business prospects are waaaay more important that any past metrics (Please agree with this statement !) - i applaud your system but you run the risk of sounding like a broken record if you default to simply repeating the same line ad infinitim suggesting that thats the only way to value stocks - i cant even see that your comments are directed at a particular stock so sweeping statements of any sort really dont cut the mustard here on this board particularly if its the same statement for the 11th time in 11 days - sorry.
Note i am not knocking your system its a great system - what would be more useful would be if you created some useful comment by picking a stock being updated on crunching your numbers and saying stock x generated only 2% compared to my magic number of 10% so fails my test its a pants investment IMHO . Your recent comments on Somero were fantastic useful addition in such a manner.
rmillaree - I do apply the tangible surplus approach to individual stocks, frequently. Yesterday I was discussing Forterra, the day before Watkin Jones etc.
The use of the tangible surplus is not a fixed screening process where I buy based on this metric regardless, it is simply to bring to the fore the most important single valuation metric by far.
You mention the rear view mirror and future prospects. There is a balance here. The rear view mirror is a pretty good guide to the future, most business are highly upbeat about their future prospects, if they have failed to deliver in the past, their forward optimism must be viewed with suspicion.
Take Forterra. Fort has a tangible surplus of about 7, strong, but about the lowest of all my holdings, which average a tangible surplus of around 10% of MCap. But Fort is my largest holding now, why? Because Fort has been heavily investing in a new brick plant over recent years at Desford. The new brick plant begins production later this year, it will be Europe's largest I believe. The new plant will significantly improve Fort's operating margins and output volumes. And this is in a market where the UK has to import just under 20% of its bricks, mainly from Holland, at considerable cost, providing a strong price moat for UK producers.
There is no prospect of the UK's brick production shortfall closing for the foreseeable future, even with Fort's new plant, it is likely to widen in fact. Fort's tangible surplus is likely to rise into the teens in terms of % of MCap over the coming years.
So this is how I apply the tangible surplus and I do so all the time on this site, that is how you achieve 1,600% 12 year unleveraged SIPP returns as I have done - as verified by the DT to last April.
Hello Doug2b
You mention the rear view mirror and future prospects. There is a balance here. The rear view mirror is a pretty good guide to the future, most business are highly upbeat about their future prospects, if they have failed to deliver in the past, their forward optimism must be viewed with suspicion.
Agreed thats its a decent starting point - however we have specific known near term info - if you are looking at info from 3 years ago when current year is highly highly likely to be materially better not having some flexibility here may mean you miss out on decent stocks IMHO. For example i am reasonably confident 2021 and 2022 are liely to be decent years - that are materially better than 2018 and 2019 - so the picture has changed somewhat. I like your mechanical trawl it cancel out over enthusiastic directors pumping their company - but i am happy for Somero that 2021 and 2022 and more indictive of the near term future than 2018 and 2019 - albeit i am slightly worried their sales growth will liley to come to adn end sometime.
So this is how I apply the tangible surplus and I do so all the time on this site, that is how you achieve 1,600% 12 year unleveraged SIPP returns as I have done - as verified by the DT to last April.
Yep i applaud your system and i am not knocking it - its a great system that clearly works and makes complete sense by filtering out companies who are known to not have generated much tangible results for shareholders - however it aint a crystal ball magic wand for any particular stock as i am sure you admit so it does not mean that you are right and someone else is wrong when a stock fails you test and you are reverting to the past history when the future is clearly highly likely to be materially different.
rmillaree - I like Somero, as I said yesterday, the price is a little rich now for me, taking it from a compelling to only a reaonable buy, wish I had caught onto it a year ago, Somero would have been right in my strike zone at that point.
The medium term, 3 to 5 year returns are extremely important in predicting forward results. My approach does allow some flexibilty. Take Forterra above, the new plant plant this year is afactored in. ScS - had a rough 2020 and the business had been pretty mediocre prior to that. But from 2020 ScS invested heavily in upgrading its online offering and the business has transformed. Last year the tangible surplus was over 30% of the current MCap, the business is awash with cash. This year will not be quite like last year - last year there was a post lockdown bounce and this year there are supply chain issues. Nevertheless there is compelling evidence that ScS has significantly improved itself and the risk is low, such is the enormity of the cash build up.
CAML - major share issuing from 2017 to 2018 and a significant debt build up to fund a very large acquisition. The jury was out, would it work. clearly it has, the divi is huge, the debt has almost gone and the tangible equity build up is very strong.
My approach is all about flexibility, it is also all about the gross inadequacy of taking declared earnings at face value without assessing whether the so called retained earnings actually make it the balance sheet as growth in tangible equity. A significant proportion of declared earnigs across the UK (and other) indices fail this test - and are therfore not genuine earnings. My approach also monitors closely for shareholder dilution via share issuing, another extemely important consideration.
Take Forterra. Fort has a tangible surplus of about 7, strong, but about the lowest of all my holdings, which average a tangible surplus of around 10% of MCap.
Forgive me if I'm being thicker than the offspring of a village idiot and a TV weather girl, but what is tangible surplus?
I thought this might be referring to the free cash flow yield but the FCF yield I've calculated for Forterra for 2020 is around 4% (so not close to 7)
It’s basically shareholder return of physical things. Like cash, hard assets such as buildings and plant.
Doug thinks IP, brands, patents and software are worthless. He will tell you that Disney’s back catalogue has no value, but a brick factory is a wonderful asset to have on the books.
Wrong. I don’t see intangibles as worthless, but at the end of the day, the business must ultimately create tangible wealth for its shareholders.
Disney bought Marvel for $4bn.
Disney bought Lucasfilm for $4bn.
You would’ve told shareholders of those two companies that management weren’t generating anything for their shareholders because they hadn’t bought a factory.
He's off again!!! :-D
He's off again!!! :-D
Yep. It's getting very boring now!! I wish we could just stick to discussing companies rather than people coming on here to boast about their performance. Personally I find it in very poor taste and can't help picturing Harry Enfield shaking a large wad of cash in peoples faces :-)
If you make large returns some of it will be down to skill, some of it due to taking on high risk in a risk on environment, and you can add to that a bloody good dose of luck as us holders of Air Partner (LON:AIR) have found this AM. FWIW I have no bloody idea what the tangible surplus of Air Partner (LON:AIR) is, or was, but I would hazard a guess it was rubbish.
All the best, Si
I discuss company specifics here pretty well every day, probably as much as any other subscriber!
For anyone wanting to get John Authers daily email which comes into your inbox about 5am each morning simply go to Bloomberg and click the option to receive the email - on the link below it is the very bottom left option - there are about 30 things Bloomberg offer in the table.
https://www.bloomberg.com/acco...
His daily take on things is very informative and gives some useful insight into what is going on, plus he has a UK as well as a US point of view.
Decent update from Greencore (LON:GNC) this morning. Ahead of pre covid numbers with share price still lagging. Hopefully due some good performance ahead of their busy summer period.
Headlam (LON:HEAD) Trading update.
"In line with the November 2021 Trading Update, the Company anticipates announcing 2021 revenue¹ of £667.2 million (2020: £578.1 million) with underlying² profit before tax expected to be slightly ahead of market expectations³. Both the UK and Continental Europe performed well, up 16.5% and 15.1% respectively against 2020 on a like-for-like4 revenue basis."
"Early trading in 2022 has been encouraging, and the Company has continued to be able to largely mitigate the persisting industry wide supply issues and associated inflationary pressures."
Decent update, but no mention of how the commercial side of the business is going? This had been underperforming, would have been nice to get a handle on how this is performing...
After Jack's write up earlier in the month and doing a bit more investigation I bought some Air Partner (LON:AIR) . I think 20 days from initial purchase to takeover bid is a record for me. Jack, if you're ever in Devon I owe you a pint.
Maybe bung a bit over to ZANE?! ;-)
https://www.zane-zimbabweanati...
I normally send them a few quid when I get a takeover bid. Nice to think that a destitute pensioner will get a food parcel or some diabetes tablets, which also enhances the pleasure from the windfall!
Have made another donation although it’s a small pain that Zane do not appear to keep info on the people donating thus avoiding entering address , email etc etc info each time. I appreciate I could organise a monthly direct debit, but prefer larger donations periodically.
A very worthy charity though which is deserving of our support as of course we are indirectly thanking you Paul for the fine work you do for us.
Thanks Caper4, and others who I know help ZANE out, it's hugely appreciated!
Best wishes, Paul.
Thanks Paul, that's a great idea. Jack, you're buying your own pint but someone in Zimbabwe has benefitted.
I bought some Air Partner (LON:AIR) yesterday so thats definately a record for me. Id like to say it was skill and hours of detailed research but it was pure luck.
I'll have to take you up on that Branoc! Very well timed.
A good update from Eenergy (LON:EAAS) I like this business.
First glance at Saga (LON:SAGA) doesn’t look great. It remains jam tomorrow.
I am relatively new to the investing but I wonder why some companies (in this case SAGA) do not report the actual performance against the key metrics like revenue, profits, margins against what they say their biggest revenue earner - insurance? But they do say how much loss they are going to incur on cruises this year? It does not seem to make much sense unless they want to tank the share price further down? Any explanation would be greatly received. Thanks.
This is what they reported instead:
Highlights
· Insurance performance in line with expectations; second year of positive momentum across key metrics. Compared with the prior period:
o Motor and home policies in force are 1% ahead; customer retention increased 2ppts to 82%; margin per policy of c.£75 (vs. £74).
o Continued popularity of three-year fixed-price offer, representing 47% of the motor and home book (vs. 35%).
o Underwriting reserve releases expected to be slightly ahead; current year claims trends in line with pricing assumptions for the second half
Saga (LON:SAGA)
I am relatively new to the investing but I wonder why some companies (in this case SAGA) do not report the actual performance against the key metrics like revenue, profits, margins against what they say their biggest revenue earner - insurance?
Unfortunately as an investor you have to go looking to find the info you want. Page 37 of the interims gives the key metrics you will get similar at year end - other than that you need to find comments about expectations and keep track of that. Company may provide presentations. brokers notes are the gold dust we rarely see - for larger companies keep a close track of how the expectations trend behind the scenes are brokers will update on ongoing basis. Note there is some detail ref ye profits but its common unfortunately that "trading updates" dont drill to much into the detail other then simple refresh of where we are (hopefully against known expectations)
But they do say how much loss they are going to incur on cruises this year?
they did confirm the following
o After ship depreciation and financing costs, Cruise Underlying Loss Before Tax expected to be £45-50m.
Oh and hopefully with Saga Paul with give us some isnlightful commentary too.
Thanks rmillaree - it is a matter of presenting the results. I thought rather than talking about the detailed metrics one would want to show what matters and easy to compare without too much digging. Its like one person doing a powerpoint presentation with loads of text on a slide and another choosing absolutely minimum but what really matters.
I guess the good point of presenting it this way makes me work - find and analyse the data myself!)
The thing is the update today is not a results update - its an in period trading update - thats how it works generally speaking with "trading updates" unhelpful waffly commentary with bitty numbers - the finals will give you what you need similar to page 37 of the intermins. Note some companies (pretty much all us) do report 3 monthly figures - thats a much beter way of doing things IMHO , but we are where we are and me and you aint goona convince all companies that they should change to reporting 3 monthly numbers.
Many thanks for your explanation rmillaree!
First glance at Saga (LON:SAGA) doesn’t look great. It remains jam tomorrow.
Saga (LON:SAGA)
Not sure what your expectations were Camraid but saga pretty much on track. Did you not like the solid insurance performance , thats ongoing jam rolly polly with custard .Ref cruises we have had a pandemic you know but the jam tomorrow starts next week with semi solid bookings into the new year. Overall you are technically correct this is a loss making business now factoring in the exceptionals - but no reason not to believe they are not firmly on track to be making £71 million net profit (pe of 5.6) from the period starting next tuesday.
Hi CamRaid,
Yes, Saga (LON:SAGA) (I hold) is jam tomorrow! (like all travel businesses). That's because the travel division has been heavily disrupted by covid. So this share is all about recovery of profits once travel restrictions have ended.
Meanwhile the insurance business has covered the losses from the travel business, and is performing in line with exps. An ideal hybrid business model to my mind, much better than a pure play travel business.
I think it's the figures on cruise forward bookings for 22/23 that are most relevant - load factor rising from 68% in H2 21/22, to 86% for H1 22/23. That's a massive jump & should greatly boost profitability (largely fixed costs, so high occupancy is what it's all about for profit).
Also note the pricing power - so inflation shouldn't be a threat - daily rate ("per diem") was £299 in H2, and is up to £318 for H1 22/23 bookings, a rise of 6.4% - seems very encouraging I think.
Overall then, it looks fine to me, as a long-term holder looking for the upside from travel conditions normalising post covid.
In the short term though, it could drop today - everything is likely to!
Regards, Paul.
Yes, results more or less in-line with what I expected on Saga (LON:SAGA) (I hold). I had pencilled in b/e this year but a small loss is neither here nor there.
The forward outlook is much more important and as you say an 86% load factor with increasing per diems bodes well for a strong breakthrough in profitability. Also, not mentioned, but since travel businesses have seen a big uptick in demand the last week or so on removal of travel restrictions this also bodes well for the tour operator moving back into profitability.
I agree it looks like Saga (LON:SAGA) has underperformed, however I would not call it a 'jam tomorrow' company, to me these type of companies are without saleable products/services, in the development stage. It has a strong insurance arm and anyone can see that the future of travel is bright.
It is however disappointing that they are so vague with their reporting, meaning you have wade through past reports to find out what they were expecting! Also, the way they hide all the disappointment further down in the text!
I think that Saga (LON:SAGA) is a different kind of jam though. By jam tomorrow I think that we are usually referring to stocks with new, unproven products or services which are high growth companies that are loss making or barely profitable.
The difference with SAGA is that in normal times cruises are a very well established market loved by the demographic that they serve.
The big trouble I think is, as with much of hospitality and leisure, that a return to normal times is unpredictable.
Last summer many of us were happy to believe that because of the vaccines it was all over and jump into these types of stocks. I was not one of them because the progression of the virus and unpredictability of the response of government actions was still big red flags.
Omicron has clearly demonstrated that back in the summer many people were too confident too soon.
The outlook seems to clearly be better now, and I expect many will be able to point to various reasons why they are no longer concerned.
I don’t want to initiate yet another COVID debate. But all I will say is that having a large number of people from a vulnerable age group, only protected by vaccines that are effective against severe disease, in a confined space potentially is a recipe for a mass outbreak of heavy colds that would not make a pleasurable holiday at all.
No position!
First glance at Saga (LON:SAGA) doesn’t look great. It remains jam tomorrow.
Given current circumstances, covid in particular, I can't say I was really expecting a lot of jam today from Saga! What I'm interested in is the likelihood of more jam tomorrow - which seems on track to me - subject to possible future covid setbacks.
All cash offer for Air Partner (LON:AIR) at 125p a share. Happy days.