Small Cap Value Report (Thu 27 Oct 2022) - PURP, FOXT, CCR, SEE, SPEC, PCIP

Good morning from Paul & Graham!
Bonds podcast - I'm hoping to speak to Paul Hawkins, a very experienced professional in corporate bonds, later today. So that should be published on my website and on my podcast channel at about 15:00 today. Bonds are, for the first time since zero interest rates, starting to look an interesting alternative to equities, hence why it's cropped up on mine, and many other people's radars. I'm only a generalist, so I'm looking forward to talking to an expert in the field! Essential first listening is this superb interview with Tamzin at PIWorld from June 2020. I'm going to try to avoid replicating that interview, so will cover different aspects of corporate bonds in my interview, as much as possible, and current themes now that interest rates are rising. Should be interesting! My podcast is now live here. Let me know what you think!
Also, our Graham, did a cracking podcast this week about bonds, where Graham has had experience handling bonds, from his fund management days. That's well worth a listen too, I enjoyed it.
Agenda
Paul's Section:
Purplebricks (LON:PURP) [no section below] - brings in a new CFO, to join the newish (April 2022) CEO. As mentioned before here, this share is now a special situation, with a decent cash pile and well-known brand name (from large advertising spend in the past) being good assets, but poor performance, heavy losses, and multiple operational problems & legal issues presenting the downside case. There has been Director buying, and cost-cutting, so maybe some hope of a turnaround? Although I think there are better opportunities amongst conventional estate agents with big lettings income (stable), such as Foxtons (LON:FOXT) (more on that later today) or Belvoir (LON:BLV) [no section below]
Made.Com (LON:MADE) [no section below] - another update this morning, says that the Formal Sales Process (under the Takeover Code) has ended. No big surprise there, as it had already informed the market that nothing was forthcoming from the interested parties. As I've previously mentioned, I suspect interested parties probably wanted to go through the figures, and then wait to buy assets (such as the brand name, website, inventories) on the cheap from an administrator. Today it repeated this line -
The Board of MADE will continue to look to preserve value for its creditors and shareholders as part of the ongoing strategic review and a further update will be made as and when appropriate.
As I mentioned yesterday, shares in MADE are likely to be worthless, but there is an outside chance that some cash might remain at topco level, and the operating subsidiary only might be put into administration. Although that depends what other liabilities & guarantees topco might have. So it's a completely unknown, and not worth speculating over, in my opinion. The company really should have disclosed what the cash position is at topco, so they're not revealing the most important piece of information as things stand now. [no section below]
Foxtons (LON:FOXT) - surprisingly (given tough macro conditions) this London-centric estate/lettings agent reports that Q3 has been good, and it's now trading ahead of expectations for FY 12/2022. Singers raises the forecast by 12%. The new CEO thinks there's upside from his turnaround plan. Balance sheet is OK I think. Valuation now looks reasonable, so on balance I think it's a thumbs up from me as a long-term investment idea, but shorter term, the outlook is uncertain. [more detail below]
PCI- PAL (LON:PCIP) [no section below] - Reassurance from AGM Statement today. Confirms that it is trading in line with expectations for FY 6/2023. Q1 revenues were up 29% (slower growth than FY 6/2023 exceptional +62% revenue growth - see my notes here). But Finncap’s forecast only assumes +20% growth this year, so it’s ahead of that. Strong pipeline. Mgt said they’re excited about new product developments, which I haven’t had a chance to look into yet. It’s still loss-making though, and has the cloud of a patent infringement case. But assuming nothing too bad happens with the patent claim, then I reckon this share could re-rate nicely in the next bull market. [no section below].
Graham's Section:
C&C (LON:CCR) (£640m) - a cloudy outlook from this beer and cider producer, which also has major distribution assets. The cost-of-living crisis has impacted recent sales, and input cost inflation is hurting margins. Today’s interim results illustrate that the overall operating margin is still below pre-Covid levels. This share does clearly suffer from economic sensitivity. But as a former shareholder, I still see great merit in the business, particularly with its Bulmers/Magners and Tennent’s brand. I don’t know when margins are going to normalise but I can potentially see the stock’s PE multiple moving higher in tandem with higher earnings, i.e. two major forces for share price growth. The debt position has been normalised, albeit at the cost of some dilution. One to consider for those with a sunny outlook on the economy. [more detail below]
Seeing Machines (LON:SEE) (£290m) - revenues are up 15% but the company argues that “underlying revenues”, excluding a licence deal, have improved at a faster rate. More pressing is the fact that the company continues to burn through cash at a rapid rate, although its preference to capitalise its development spending saves that cash burn from hitting the income statement straight away. Equity was raised during FY June 2022 to keep it going, but more recently it chose to go down the route of a convertible bond offering. If the share price doesn’t increase significantly, and if the cash burn continues, then paying off the principal of this bond in 2026 is likely to involve yet another equity raise. This company might stop diluting its shareholders some day, but there is precious little evidence of that happening any time soon. [more detail below]
Inspecs (LON:SPEC) (£61m) (-47.6%) [no section below] - just a short note on this eyewear manufacturer. I covered it in August, when the market cap was £228m, arguing that it was unclear how it was going to be able to justify this valuation in the long-run. It was a 2020 IPO that had yet to fall far below its IPO price.
The share price rapidly drifted lower after that, and today it has capitulated with a fall of nearly 50%. Today’s Q3 update reports that year-to-date revenues are up 2.8%, or 9.8% at constant currency (currency movements have clearly been a headwind). Worse, the economic and consumer conditions in Europe have “deteriorated sharply since September 2022”, and order intake is “significantly down on the previous year”. The total group order book is down 13% year-on-year, as of the end of September. Growth plans with new and expanded factories have been delayed, the Chairman has decided to retire, and Inspecs expects to be impacted by economic conditions through the first half of 2023.
Unfortunately, there is still not much tangible balance sheet support at the current valuation, and it’s reasonable to expect significant losses on reduced revenues. I would not be a buyer here. [no section below]
Paul's Section:
Foxtons (LON:FOXT)
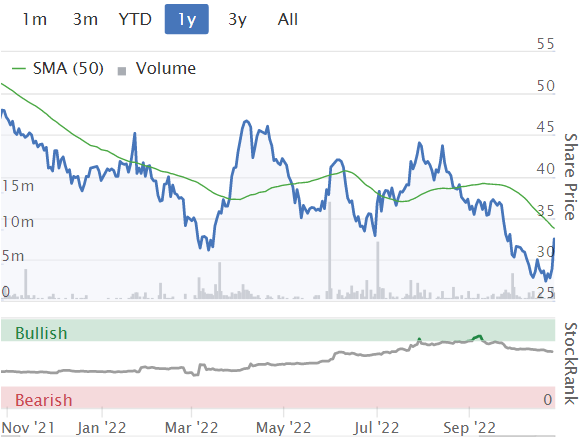
Price 31p (up 8% at 08:36)
Market cap £97m
The share price is volatile this morning - when I started writing this section, it was up 18%, but then fell to +8%, so I had to change the header above.
I reviewed the interim accounts for this London-centric estate agent/ lettings business here in July. My conclusion then was that the business looked interesting, with an increasing focus on lettings (steady, not cyclical income), and with cost savings being implemented. Although at 44p, the shares didn’t look particularly cheap on fundamentals at the time.
The good news is that the share price has dropped a lot, going below 30p recently, so this could be a more attractive buying opportunity now perhaps?
This is the latest update today -
Lettings continues to drive solid performance alongside strong sales revenue growth
Positive trading update, ahead of expectations (but not quantified) -
FY22 full year outlook
Whilst we are mindful of the ongoing macroeconomic and political uncertainty, the strength of our performance in the third quarter gives us confidence in the outlook for the full year. Accordingly, we now expect to deliver a result for the 2022 financial year ahead of our previous expectations.
Q3 revenues up 25% to £43.8m
9-month revenues for FY 9/2022 to date were £108.9m, up 11% on LY (last year).
New CEO Guy Gittins (a former employee) has returned recently (Sept), saying the business has “significant unfulfilled potential”.
Q3 performance seems surprisingly strong, especially in sales, although I suppose the time lag from negotiation to completion (extended due to bottlenecks in conveyancing & local authority searches) means that transactions in Q3 possibly pre-date the worst of recent economic & political turmoil -
This quarter has seen continued positive momentum with growth across all areas of the business. Our lettings business performed strongly as we delivered both organic and acquisitive growth. Our investment in sales negotiators, combined with strong buyer demand and a renewed focus on sales intensity has benefitted our sales business.
Q4 outlook is weaker, as I would expect, but I don’t hear any alarm bells ringing here -
We enter Q4 with a less certain sales market backdrop, but cost action taken in H1 and our resilient lettings and financial services businesses leave us positioned to weather further macroeconomic and political challenges."
More detail -
Lettings - this was 67% of total group revenue in Q3, so is highly significant. Most of the 18% growth is organic, with a bit from an acquisition.
Acquisitions performing well.
Higher rents, and longer tenancies, more than offset a fall in lettings volumes.
Demand strong, supply constrained.
Residential Sales -
Good growth, but remember that Q3 LY was unusually weak, distorted by Stamp Duty changes.
Q3 YTD sales revenues down 2% on LY.
“Early progress” in targeting higher value property transactions.
Pipeline at end Q3 is up 15% on LY - surprisingly good I’d say.
Uncertain outlook for Q4 due to macro factors.
Financial Services -
The smallest division, but committed to growing it.
Forecasts - an update from Singers has just come through, as I’m typing this, many thanks to them.
It’s upgraded FY 12/2022 from 2.37p EPS, to 2.66p, up 12%.
Next year FY 12/2023 is left unchanged at 3.18p - so that could be challenging if macro conditions worsen, which looks likely. Although offset by turnaround activity by the new CEO.
Valuation - the share price is still moving up and down, but at 32.5p currently (10:16), I make that PERs of 12.2 for 2022 (which should be locked on now that we’re near the end of the year), falling to 10.2 times for 2023 (assuming the forecasts are hit, which isn’t a given in current conditions).
I wanted to say that’s cheap, but given all the uncertainty, I’d say the valuation probably looks about right for now.
My opinion - as mentioned previously, I like this company, which has a good mix of business, with the lettings side very significant. Hence it’s not as cyclical or vulnerable as perhaps some investors might think.
Valuation now looks reasonable, after a fall in share price (partially reversing today), and better than expected earnings.
I went through the last balance sheet & cashflow statement here in some detail, but the short version is, they’re OK.
Overall, I’ll give this a thumbs up I think, for a long-term investment, but in the shorter term, I’m not sure. It depends on market conditions, and if the new CEO’s turnaround plans work - that could provide good upside if his measures do drive profit growth.
.
Graham’s Section:
C&C (LON:CCR)
Share price: 162.9p (-1.6%)
Market cap: £640m
This drinks company (in which I’m a former shareholder) has had a rough few years since the onset of Covid.
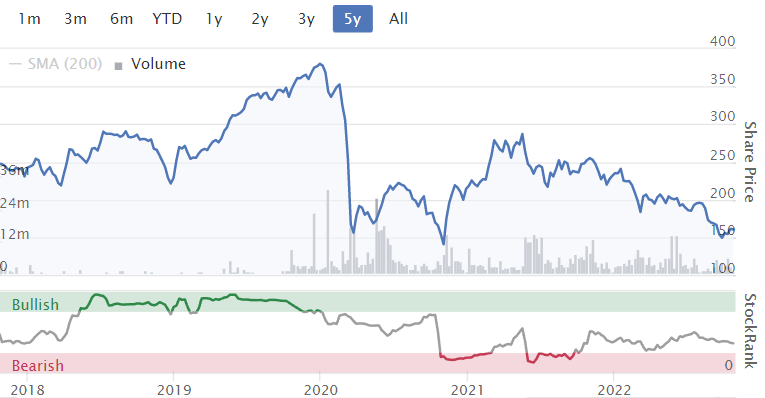
Let’s put the distant past behind us, and see how the company is doing more recently. This morning we have interim results for the period to August 2022.
Highlights:
- Net revenue +35.6% to €903m
- Adjusted EBITDA more than doubles to €70.9m
- Operating profit €54.9m (last year: €15.5m)
The operating margin has bounced from 2.3% to 6.1%, confirming that the company’s financial performance was ready to improve, as soon as sales improved.
The company’s balance sheet was a key concern during Covid. They saw fit to issue 81 million new shares at 186p, during FY February 2022. This raised £151m / €176m, money that was needed to pay down its debt.
The company also sold its interest in Admiral Taverns for £55m / €66m.
Thanks to these actions, and its underlying free cash flow conversion, it seems to have pulled through.
Net debt (excluding lease liabilities) is now €104.5m, so the net debt to adjusted EBITDA multiple is only 1.5x.
C&C “has now exited covenant waivers”, i.e. it has satisfied its bank lending group that it poses a normal credit risk and does not need to be given special treatment.
There’s no dividend yet, but the Board “intends to recommence a full and final year dividend following the release of the full year FY 2023 results”.
So on the face of it, things should be back to normal now for C&C.
However, profitability faces some serious immediate headwinds:
Group branded operating margins are broadly in line year-on-year, with volume, price/mix growth and price actions being offset by increased marketing investment, inflationary impact on cost base and manufacturing input costs.
Note that C&C is a collection of owned drinks brands, and also a major distributor. After the collapse of Conviviality, it picked up the distributors Matthew Clark and Bibendum for a song.
While the distribution businesses interest me somewhat less than the owned drinks brands do, the synergies between them are easy enough to understand.
It looks like inflationary input costs are going to hold back profitability in the branded drinks segment for the time being.
In the H1 results for 2019, which was the last pre-Covid year, C&C had an overall operating margin of 7.3%, versus 6.1% in the most recent period. Hopefully the pre-Covid margins can be seen again - surely margins will normalise at some point?
Outlook
The cost-of-living crisis is having an impact:
Macro-economic and consumer environment remains difficult with net revenues for September 2022 -5% compared to the same period in 2021.
More positively:
Our near-term trading focus is on ensuring the highest standards of service and stock availability to our customers and consumers as we prepare for the first unrestricted Christmas trading period for three years and the upcoming FIFA World Cup.
It will be worth remembering that the World Cup will impact full-year results this year (FY Feb 2023), with no similar boost available for FY Feb 2024.
My view
As a former shareholder, there were of course many things I liked about this business. I still do like it, just not with enough conviction to keep it in my currently quite concentrated portfolio.
Take the Bulmers/Magners cider drink, for example. This has very strong market share in its niche, and remains exceptionally well-positioned. In Ireland, Bulmers market share has grown:
The Bulmers Brand MAT off-trade cider volume share has grown year-on-year to 55.1%, a significant increase… compared to pre COVID-19 levels. Across the latest 13 weeks, share has increased to 57.2%...
In the on-trade, the latest Bulmers MAT cider volume share at 63.8% reflects growth in Bulmers market share ahead of last year… Bulmers continues to enjoy its position as the largest and most popular cider brand in Ireland.
In Britain, C&C sells more Tennent’s lager than the amount of cider it sells.
Tennent’s has lost beer market share to the trend for premiumisation, but remains a huge brand. Its volumes continue to “outsell the two closest competitors by 20%”, according to today’s update. In the on-trade, its volume share in beer is 35.8%.
So I still see huge brand assets at C&C.
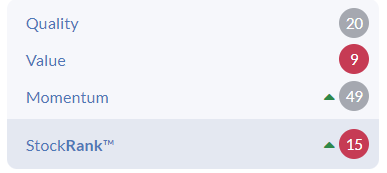
The StockRanks don’t like this share, but I view the company’s current results as being most likely temporarily depressed by our economic and inflationary problems.
I don’t know when those problems will be resolved, of course.
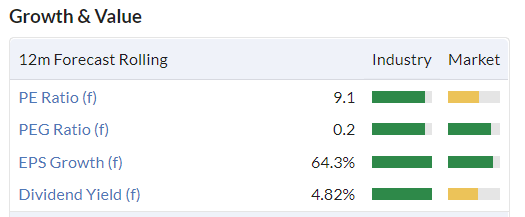
It seems to me that this share is well-positioned for an earnings recovery which could also be accompanied by a normalisation of its earnings multiple (e.g. to 12x or 15x). In that case, you’d get a double-whammy of share price growth:
However, let me repeat again that I don’t know when this will happen! Could input cost inflation and the cost-of-living crisis drag on for several years - who knows?
But if you’re willing to bet on economic normalisation, which I imagine that most equity investors are willing to do, then this share seems like a decent candidate to me.
Seeing Machines (LON:SEE)
Share price: 6.97p (-0.7%)
Market cap: £290m
Let’s skim the results from this Australian company that develops driver monitoring systems.
- Revenues +15% to AUD $54.4m
“Underlying revenue” is +22%, if you exclude a one-off licence from FY 2021.
Last year, there was a similar story: revenues were up 18%, but “underlying revenues” were up 30%.
I’m not sure I can accept this presentation of revenues.
In the results for FY 2021, it wasn’t clearly indicated that there was a one-off licence deal that should be excluded from underlying results. It looks like the licence deal revenues may have been included in last year’s underlying revenues.
I’ve gone back and downloaded the annual report for FY 2021, and still don’t have clarity on the calculation of underlying revenues. So I’m afraid I have a problem with the very first line of Seeing Machine’s income statement!
Let’s go to the cash flow statement instead, and see what is happening there.
Operating cash flows: AUD $15.8m outflow, not as bad as the $25m loss on the income statement.
Investing cash flows: $28m outflow, mostly due to capitalised development spending.
In total, there is a nearly $44m outflow from operating and investing activities, significantly worse than the prior year.
Seeing Machines dealt with that during the year by issuing shares.
Investment by Magna International: earlier this month, Seeing Machines entered into an exclusivity agreement with a car parts manufacturer.
Seeing Machines is receiving up to $17.5m in cash, and also sold a 4-year convertible note to Magna (maximum size $47.5m, i.e. one year of Seeing Machine’s cash burn at the current rate).
The note pays interest of 8% and is also convertible at 11p (latest share price: 6.97p), with dilution of up to almost 10% for existing shareholders in Seeing Machines.
My view
The convertible note looks like a risky move from Seeing Machines.
Remember that a convertible note should have a lower yield than an equivalent note without the conversion option (because the conversion option is a valuable bonus for the lender, so the lender is happy to accept a lower yield).
But Seeing Machines is happy to borrow at 8% and to potentially dilute its shareholders by nearly 10%, if its share price increases.
If the share price doesn’t increase, then it will need to pay off this convertible note with cold hard cash, most likely from a fresh equity raise (and who knows at what level the next raise will be at).
The cash burn remains awful and I must reiterate that I see no support for this company’s valuation in its financial statements.
It’s a mystery to me how this company has managed to sustain this valuation in a small-cap bear market. It must have quite a following!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
C&C (LON:CCR) - really the future is rubbish cider. Do feel for the brewers with rise in hops, energy etc. Tough times. We need to support their SP outside of our PL accounts.
Although viewed as some as low market J D Wetherspoon (LON:JDW) will be the nail in the coffin of trad pubs if we let it go. Sorry for the Bournemouth elites.
£SEE
Hi Paul,
I am going to disagree with a lot of what you said regarding seeing machines.
First with regards to the bonds. The yield is not 8% per annum it's 8% all in including fees. I think that works out to less than 2% per annum. Whilst potential dilution isn't great the conversion price is at a significant premium to the current share price. The deal also included $17.5 million in a license fee so all in all a fantastic deal in the current climate. Their main competitor Smarteye has less than 3 months of cash left and not sure what they're going to do.
Whils profits have been hard to come by their investment and currently won contracts put them in good stead as does the regulatory environment which mandates their technology in new car models from 2024 in Europe and in all European cars by 2026. It is also expected that USA will mandate it by 2026. That means that car makers have to make decisions on contracts that will last 6 years plus within the next year. I firmly believe as does the company they will win a significant portion of the pipeline. Their fleet (aftermarket) division is now profitable and there are significant tailwinds coming here, again mainly due to the fact the technology is being mandated by the EU.
The company recently did a meeting which explained the Magna deal and their general position in the market. You can watch it here. https://stream.brrmedia.co.uk/...
Hi boonboon, thanks very much for the comment. I'm struggling to find evidence that the 8% all-in yield equates to 2% per annum. Can you please help?
Graham
Occasionally Bidstack (LON:BIDS) has been discussed in here. I was a shareholder. Very high risk and high uncertainty so low position and an acceptance by me it may not work out. I believed they'd operationally turned the corner and have a shot at a large virgin market.
Anyway, I sold all today (I had partially sold some a while back too at higher price). I think the CEO has acted illegally. Below is an email he sent to a group of private investors (I believe to be private investors that took part in the recent placing)
"PRIVATE EMAIL TO INVESTORS
Azerion and Bidstack MSA discussion
From the Investor Presentation of Sept 2022, you will be aware of the existence of the Azerion Partnership, which is based around a contract which commenced on 1 March of this year (the “MSA”).
Following announcement of the placing, Bidstack received an email from Azerion requesting information under the MSA and reserving Azerion’s rights under the MSA, including taking steps to end the MSA.
Bidstack's response and legal position
Due to the timing of this email and the nature of the Group’s ongoing strong commercial relationship with Azerion, the Directors regard this email as a speculative and opportunistic attempt by Azerion to exploit a perceived weakness in Bidstack in an attempt to acquire Bidstack at a significant undervalue as part of Azerion’s buy and build strategy.
Bidstack has responded to Azerion with detailed information demonstrating compliance with all areas identified by Azerion and disputing the rights reserved by Azerion. Bidstack has taken appropriate external legal advice and has concluded that Azerion has no present entitlement to end the MSA.
Consistent with its strategy to review and improve demand side agreements, Bidstack will pursue discussions with Azerion in relation to the MSA, which may yet change in focus, scope or detail, and it is anticipated that these discussions may be on-going for some time.
The contract continues to be operated on a business as usual basis by both parties, with October already the highest grossing month, and with November and December anticipated to grow further month on month.
Forecast and outlook
Bidstack remains inline with 2022 and 2023 market expectations.
Bidstack notes that Azerion is primarily a European entity, with its sales-reach limited to these territories. The Company has invested in an experienced sales team with a proven track record in North America, as covered in the presentation, which has a robust pipeline for FY23.
Our Group Chief Revenue Officer is in active discussions on a number of significant global revenue opportunities, including additional resellers, licensors and media agreements, with anticipated contracts in FY23.
Kind regards,
James"
This very material information as Azerion are their visible revenue source through reseller agreements.
I believe this private email went out yesterday around the same time that this RNS was made public:
https://www.investegate.co.uk/...
Note that the last couple of days are also when recent placing shares come on to the market and I think the private email was sent to these placing participants.
I've contacted Bidstack's nomad and submit a complaint with the FCA. I think this is such flagrant abuse that it requires action.
TBH I did a lot of fundamental digging around BIDS and I have a positive outlook (always a bit sceptical of the Azerion deal achieving target tho)...but what just happened is just too murky for me. If you hold then you have your own view to make
Ciao
Wow - that is quite a different tone!
The FCA a bastion of our financial world. Nickel market, pensions market - sorry obvs work in progress.
SDI (LON:SDI) big sell by directors @165p causing a sell off. RNS out at 3.55.
Ford sold - £214,500
Creedon sold - £993,500
Not what we want to see, in these trigger happy times... I got out a little late for a small loss. Could have been a buying chance but to my mind they are already a little on the expensive side, so will wait it out.
Down 9.4% on the day
£SDI They didnt have a lot of skin in the game anyway but that sell has prompted me to call it a day and take profits. About another 570k sale went through at 165p in addition to RNS, so maybe more to follow.
New rule for me, any director sales around £1million+ I'm following them out the door no matter how bright prospects look.
Yes Gringo I agree, its just not a good signal from the directors in this present environment, and their previous sells at highs don't fill one with confidence...
That would have worked well at Kape Technologies (LON:KAPE) when directors sold at £4 in Jan - now ca £2.50
SDI (LON:SDI) - sorry boring chartist input influenced by the discussion.
155 - support. 183 - take a position (Mr Scotts 30% or your risk level).
Hi All
Since a capitulation moment, or just cutting losses, or following a tighter set of rules with a manual stop loss. I have obviously seen things that were sold across mine and mum's ISAs bounce back up again for a lot of the things sold, situation normal for me, and a what can I learn other than you cannot beat Mx Market.
Though some things have continued down, so actually maybe the rules do work and are just not perfect? Especially with ongoing volatility?
Within emotions there is a lot of FOMO, should have bought more, should have sold earlier, should have bought less, not bought at all, should not have sold, should have bought more and a lot of rear view mirror naval gazing.
But all portfolios still exist, I have not blown the bank in any account or worse gone into debt. Yes everything is down this financial year (sorry keep portfolios records on Tax year basis, as not everything is SIPP/ISA bound for everyone). But all the portfolios for all the family members are still there, I have not blown the lot, I have not done anything totally irrational or stupid, I don't think. And I keep trying to move forward and look after the wider family as well as myself.
I have been thinking about the rules, they are not wrong, just I have to be honest with myself, I am not a full time screen watcher, I am an interested person who fits this around other things. A key part is being able to live with myself, to learn and to sleep at night! They need a polish, they need a review, but they are not wrong for me. Keep going, and the biggest part keep a control of instinct and also the emotion that I need to do something, doing nothing today is not wrong, especially when you see something you have been watching down bounce back up and why did I not buy that particular day?
Yes I am not working currently, but I am applying and have two more interviews next week so that is good. The family home is secure, our next 12+ months is secure. So counting that there are a lot of positives in life, even if sometimes there are down days.
In the meantime, our loft has been reinsulated, the fences at the back will be finished tomorrow, a lot of the jobs at mum's and dad's houses have had progress made on them. And I have spent time with the family so life is good.
Sorry not a world of wisdom, but an honest thought for this afternoon.
The hardest part is keeping calm, to be rational, and to realise that there will be a tomorrow, and another opportunity which may well be a lot better, or maybe not as good, as the one that you feel got away.
Good Luck
Tommy
Hold tight is what I'd say to you Tommy, time could be on your side and don't make any rash moves meanwhile and forget the 80% down dogs, if you have any, as who knows one day they may rise like the phoenix and surprise.
Silver
In the coffee can.
I've seen a number of people say on various social media sites say that Made.Com (LON:MADE) are refusing refunds, cancellations, and returns. Is that legal given they are not yet in administration?
Hello Paul and Graham. Your material is compulsory reading / listening to me on a daily basis, but sometimes I am truly puzzled by your choice of companies for review - the ones in and the others left out. How could Seeing Machines (LON:SEE) be chosen over Franchise Brands (LON:FRAN) for example. One dead in the water, going nowhere despite what I regard are its really fine safety advantages (that few seem to appreciate, customers or investors) and a company like Franchise Brands (LON:FRAN) with real potential in the right places with quite a lot of the right credentials and safeguards in these tough times ahead. Perhaps you are going to cover them later on admittedly this busy day. I hope so. Kind regards though tinged with a little frustration.
Hi ridavies,
but sometimes I am truly puzzled by your choice of companies for review - the ones in and the others left out.
It's very difficult to choose, and I think most days we get it right.
However, I accept your point that it would have been better for us to look at Franchise Brands (LON:FRAN) instead of Seeing Machines (LON:SEE) - I don't know why Graham decided to look at SEE. Also, I ran out of time, because I had to prepare for my corporate bonds interview this afternoon.
This was our agenda today, as you can see, there are 3 backlog items I wanted to look at too. It's a permanent source of frustration to me too, as we can't cover everything we'd like to cover.
It doesn't really matter if we don't cover in line updates, as there's nothing price sensitive in them. But we do try to cover ahead, or behind statements, so it was a pity we didn't get round to FRAN. So I'll take that criticism on the chin - our apologies to you.
Regards, Paul.
Thank you very much for the response, Paul. As I indicated, it must be difficult early in the morning to make the choices Sincerely ridavies
Seeing machines has recently announced a deal and fundraising that was in effect a 100% premium to the share price at the time. That's exceptional in these market conditions. Magna who made the investment are one of the biggest suppliers to the automotive industry and will have visibility of what's coming in the way of contracts. Seeing machines has been in the investment phase for over 20 years, but it is now finally entering the growth phase as their technology is being mandated across the world. In fact seeing machines were instrumental in the wording and requirements for the EU regulations and as such have a real edge over their limited competition. They are also heavily involved with the transport authorities in the USA.
Their fleet division is profitable and on the cusp of massive growth as well. Close to 40,000 units installed and a further 10.000 ordered but not yet installed. That's 20% growth already this financial year. They're also seeing big demand from autonomous fleet companies who need a back up monitor and for truck and coach companies who have to provide DMS in every vehicle by 2024. You're talking about tens of thousands of units for each contract and in most cases they're the only ones bidding as they're the only ones with the technology.
Re Seeing Machines (LON:SEE) and your comments Boonboon, thank you for your in depth information. I have been following these for so long and faced disappointment after disappointment. I am delighted to hear they may be 'at a point of inflexion' and will arise from my stupor and watch with renewed vigour once again!
Thanks Ridavies,
I've been in these 10+ years myself and share your frustration at the time it's taken to get anywhere near profitability. Which should now be from FY2024.
However they're now facing the perfect storm. The technology is mandated but most oems seem to have left it really late to make a decision. That leaves the Rearview Mirror as the cheapest and easiest solution to facilitate this.
SEE are the only provider that has the technology and ip for this. They're also the only ones with the relevant technology for trucks and buses.
They are certainly getting more bullish themselves. They've always said their target was 30% of 70% of the market (they weren't bidding in China)
They're now targeting at least 50% of the total market as they're now bidding in China through partners.
rreally expect this to take off as the market catches on. From next month they will be doing quarterly updates on kpis including vehicles on road and fleet connections. Once the market sees the growth hopefully it will take off.
Hi ridavies,
Following up on this comment which Paul has already replied to.
It's always a judgement call re: which stocks to cover, and sometimes I get it wrong.
The primary reason I went for SEE is that it had issued its finals. When deciding between two companies, if one of them has issued results and the other has "only" issued a trading update, I prefer to attack the one with results, because the results are where you get the most information and the most complete picture of the company. I would expect us to cover FRAN when it issues its results.
Of course there are many other factors and reader interest is one of them. If there are three times as many readers interested in Stock A as Stock B, then I should probably cover Stock A! There does appear to be some reader interest in SEE (e.g. Boonboon's comment).
I hope this helps to explain,
Regards. G
Hi Paul. Please could you ask Paul Hawkins to identify a good website which allows retail investors to compare and sort bonds by key attributes (price, redemption date, coupon, yield to redemption, etc). I haven't been able to find a definitive single source, but I'm hopeful that it is out there... thanks.
Try this https://www.hl.co.uk/shares/co...
The spreads seem enormous.
Sharepad 561 corporate bonds (obviously for subscribers only). This is a screen shot of part of the default screen. I have no idea whether this is what you are after.
Regards
Michael.
Just a reminder to everyone that many of the companies featured in the SCVR are coming to MelloLondon to meet investors face2face and will do presentations (about 100 during the two days) We also feature many more in the panel sessions such as the BASH and there will be a Stockslam too. Katie Potts the star fund manager at Herald has just accepted our invitation to speak on the Wednesday.
There is all you need to know here https://www.stockopedia.com/co...
Regarding Asset Management companies (Rockwood Capital, North Atl Smaller co's.. Oakley etc).
Using HL account, charges generally look to be 6-8% p/a. those of you who may be more familiar with these co's- Is this based on a perfomance factor and will 'drop off' for a poor year? Is it a hangover figure from a strong couple of years in asset growth and the numbers need updated? Or is it just part and parcel of an asset managament co, and just needs factored in along with NAV etc?
Cheers!
Solid State (LON:SOLI) this is one of my few small caps holdings that has not faired too badly this year and they reported some solid results yesterday. “the Company expects to exceed the current revenue expectations(1) and be marginally ahead of the adjusted PBT consensus expectations(1) for FY23, despite the expected increase in interest charges.”. It seems to have benefitted from the increased military focus this year and also currency movements.
Unilever PLC Third Quarter 2022 Trading Statement - ADVFN
This is an interesting read .
In short, revenue up 10%, prices increased by 12%, so sales volume down by 1.5% .
Obviously Unilever brands are very strong and have huge pricing power but what happens when inflation subsides? I wouldnt expect Unilever to reduce prices much if at all.
Wages probably dont come down but packaging, transport and raw material costs probably do, so does this mean much higher margins and therefore future profits ?
As we have not had the current levels of inflation for a very long time can anyone remember what happens ?
Inflation is the rate at which prices go up. Even if inflation dropped to zero tonight, no costs/prices would come down - they'd just stay the same.
In fairness, to the extent that inflation is driven by supply side factors, there is also some scope for prices to fall back from current levels, so softening this ratchet effect. Nevertheless, by and large, I think what's gone up will not come back down.
Thats not what i said. Forget inflation, what happens if costs ACTUALLY come down.
ie Transport , both Nationally and Internationally will reduce, some raw materials will also reduce in ACTUAL cost ie . paper for packaging, some plastics etc I am assuming this will increase margins and profits .
Hi Paul. Great to hear that you are interviewing Paul Hawkins, who is a top bloke despite being an Everton fan. Can you ask him to explain like he is talking to an idiot (me) about what to look for when selecting a corporate bond. When I look at a list of corporate bonds quite a few are yielding (the coupon?) over 8% - If we buy now we are locking in a good income and when interest rates stabalise and lower, should get some capital growth - Seems like a low risk high reward investment strategy or am I being naïve !
The key measure is the yield to maturity rather than the coupon - this essentially gives you the annualised total return if you hold to maturity, which is a combination of all the coupon payments, plus any capital gain/loss when the bond repays at par. For example, if you buy a bond at 80p you will get a capital return when the bond matures and redeems at 100p, on top of the coupon payments. Many bonds now priced below par which explains why yields are so attractive, as you should get a combination of income and capital return.
And my own view - if you buy below or close to par and say 5 years ish maturity - u don’t have to worry too much about interest rates - u will get the YTM. The problem with buying a fund is you could do a lot worse if rates continue to rise. Possibly better should they fall but you have to manage the interest rate risk - it sell it as the bottom not wait for redemption. Just my own view.
Poor update from Inspecs (LON:SPEC) today. Think SVCR were right to have reservations on this. Unhelpfully no profit or debt guidance at all in the update which is crazy and the sales figures reported don't look as bad as the headline says except for the fact it seems to have fallen off a cliff since these figures with -13% expected in core market. Be good to know what this does to profitability hence the big markdown today I expect. Question is at what point is this value? Felt it was at £1.10 and vague possibility at some point of takeover perhaps (but I find buying shares hoping for that is always a bad idea!! Hardly ever happens).
Another update from Secure Trust Bank Secure Trust Bank (LON:STB) this am.
Secure Trust Bank (LON:STB) has a respectable record and is soundly managed, but the SP has declined relentlessly, and not just in the last 52 weeks, and now offers quite a yield.
Does anyone else follow this and perhaps might Paul or (more likely) Graham giving it a review at some stage?
Thanks
MJ GLEESON (LON:GLE) mkt cap has now fallen to £225m, Relentless decline since September results.
It goes ex-div today which explains the further slump in SP
Solid cash backing, price at 5 year lows, I have added. Could be a nice acquisition for one of the big players imo.
.
Re Purplebricks (LON:PURP) I've said it previously but I think their biggest problem remains that they are caught between cheaper online-only rivals like Strike (anecdotally I have noticed they have for sale boards on a lot more houses in SW London than Purplebricks) and those who can arguably better market less sellable homes like highstreet or specialist agents (as my personal view is online agents aren't as attractive for selling harder to sell or specialist properties). However, as a fellow reader pointed out last time, Strike's balance sheet looks awful so there is a potential investment case for Purplebricks (LON:PURP) being the 'last person standing' in the online agent space although I am not entirely confident it will survive the cash burn long enough.
I used Strike to sell my home - it was half the price of Purplebricks (LON:PURP) in SW London even with me paying for a professional photographer, premium Rightmove ad, and floor plan. Strike were pretty good at setting me up but pretty rubbish at customer service thereafter - although it didn't really matter as I managed the whole thing myself.
Where can i check strike's balance sheet?
Companies house
Also Purplebricks (LON:PURP) investment in Homeday might be trending to zero...
I note that Homeday, after aggressively hiring over 2020, 2021, and H1 2022... has now done a second round of layoffs (the first being this summer). As far as I can infer, they are were still loss-making and cash burning earlier this year, and will be in an even worse position now.
Most likely outcome is that they need extra cash; and only Axel Springer will be in a position to fund, and likely means PurpleBricks stake in the JV is probably close to zero.
Franchise Brands (LON:FRAN)
Morning Paul and Graham
I draw your attention to an ahead Q3 update from this franchise business.
I started investing in Franchise Brands after seeing them at Mello 2019. There were at least 5 directors present , all of whom have substantial holdings. The room was packed. I have yet to read a disappointing update and continue to be a happy holder. I think Franchise Brands are a quality growing company.
Q3 update:
Stephen Hemsley, Executive Chairman, commented:
"I am very pleased with our performance in Q3 and year-to-date which gives us confidence in exceeding current market expectations for the full year. This performance has been driven by an excellent performance from the transformational acquisition of Filta and the continued strong momentum at Metro Rod. It demonstrates the strength of our growth strategy and quality of our franchise networks.
"I am particularly pleased that the acquisition of Filta has given us a significant international presence in the large franchise-friendly North American market. This will considerably enhance our scope for both organic development and accretive B2B acquisitions.
"Our technology-enabled business is highly profitable and cash generative, with a strong ungeared £100m balance sheet. The Group is in a robust financial position to weather more challenging economic conditions and take advantage of future growth opportunities both in the UK and in the US. I, therefore, look forward to the future with considerable confidence".
Michael
Franchise Brands (LON:FRAN) good update expectations are exceeding. Benefiting from strong $
"Overall, the Board expects the Group's revenue, adjusted EBITDA, and adjusted EPS for the year ending 31 December 2022 to be ahead of current consensus market expectations* Consensus market expectations for the financial year ending 31 December 2022 are revenue of GBP92.9m, adjusted EBITDA of GBP14.3m and adjusted EPS of 7.31p"
Morning Paul,
A quick request - hopefully valuable to all subscribers. Can you highlight in the daily report title when you have your share of the week? Maybe with a * or similar?
e.g. SCVR (Date) - AAA, BBB, CCC*, DDD where CCC is the share of the week / mystery share.
I can't be the only one who will want to review these over time along with your comments on them. However scanning each article to find them isn't so easy.
Alternatively can you run an index of links back to the daily articles?
good idea
I guess the share of the week is not clear until the end of the week.
Yep - but once known the title could be updated or it could be added to an index?