Small Cap Value Report (Thu 28 Jan 2021) - PCIP, JOUL

Good morning, it's Paul here with the SCVR for Thursday.
Timing - I have to finish by about 2pm today. Update at 13:33 - sorry I'm completely bogged down in JOUL (I hold) results, so that (big!) section should be up by 2pm. Please bear with me.
Update at 14:35 - I spent absolutely ages on JOUL, so haven't got round to the other stuff, and have to go out now for an appointment. I'll catch up this evening, to go into tomorrow's report first thing. Apologies for any inconvenience. Hence, today's report is now finished.
Agenda - The first 3 companies I'll be looking at are all things that I either hold, or am considering buying, namely -
Pci- Pal (LON:PCIP) (I hold) - Trading update for 6m to 31 Dec 2020 - (done)
Joules (LON:JOUL) (I hold) - CFO leaving, and interim results 26 wks to 29 Nov 2020 - "Accelerating digital sales support delivery of profits ahead of expectations for the Period". At first glance this looks good. The key point is that Joules is more than recouping lost physical sales with online growth. That's very important, and not something I've seen with other similar companies. It mentions higher costs of export to the EU, something we've recently been discussing here. - (done)
De La Rue (LON:DLAR) - Trading Update - FY 03/2021 to date - guides ahead of expectations £36-37m adj op pr, vs £34m mkt exps) (to do)
Other things on my to do list, which I may or may not get round to covering, dependent on time, are these: BLV, ACSO, TRB, MMTO, Fonix, EMR - so please don't request them, as I'm already aware. Update - sorry these are going to have to wait until tomorrow.
As usual, I welcome readers giving your own opinions on companies reporting, in the comments, if backed up by facts & figures. Some of you know your companies inside-out, if so, do contribute your views here, it's a team sport after all.
Pci- Pal (LON:PCIP)
(I hold)
61p (up 4% at 09:05) - mkt cap £36m
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, announces a trading update for the six months to 31 December 2020.
This is niche software, which integrates into call centres, enabling operators to take credit card payments over the phone in a secure way, which means the operator doesn’t see or hear the credit card number, thus eliminating fraud. Apparently PCIP is a specialist in this area, and has very little competition. Hence its product is selling well (from a low base), especially in the USA, mainly through resellers.
.
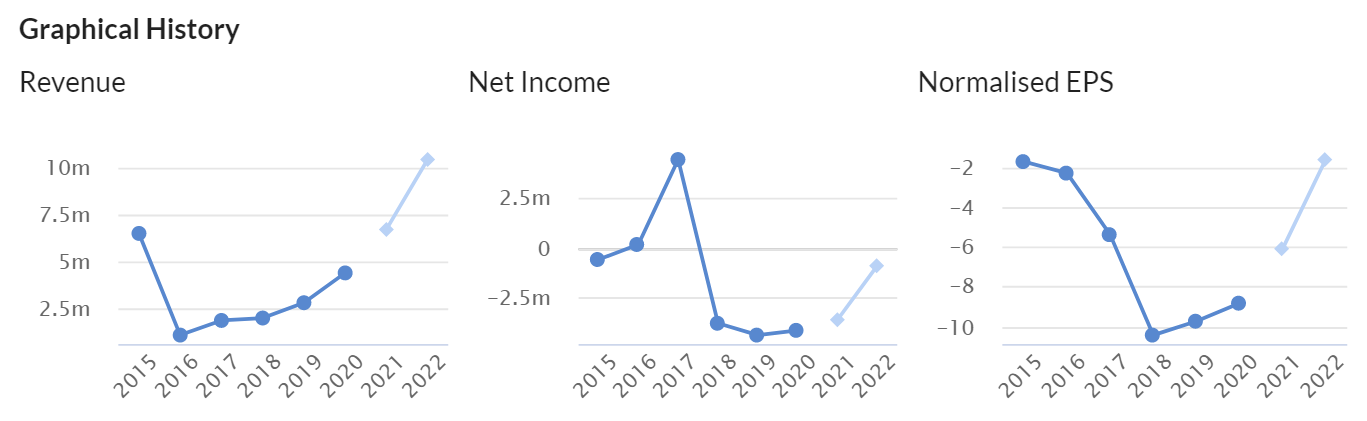
As you can see above, this share looks rubbish on the historic numbers, but you have to dig a little deeper, and look into the future, to see the opportunity (lighter coloured blobs are forecasts, darker colour actuals).
Fast growth is actually happening now, with each new sale bolting on high margin, sticky (low customer churn) monthly recurring revenues. On a mainly fixed cost base, that should deliver excellent operational gearing. It’s a lovely business model, and if revenue growth continues at high levels, then the company should move into sustainable profits in 2022.
The best briefing is here on InvestorMeetCompany, which I'm watching again now in the background to refresh my memory. The presentation is over an hour long, so a comprehensive explanation of the business, its results for FY 06/2020, and its prospects.
I consult a sector expert, who knows the contact centre space inside-out, and he tells me this share is the real deal. That adds to my conviction on the numbers. It’s important to talk to people who know individual sectors well, then monitor how well their ideas perform. Then talk more to the people who tend to get things right!
It’s important to do my own research properly as well as consulting experts. This is because I find drawing on other peoples’ conviction rarely works for me. I tend to sell too quickly, rather than riding out any short term price drops. Whereas if I’ve done my own research properly, then I’m more inclined to ride out any short term volatility, buy the dips, and make a good profit longer term.
Days like today are a good example - a few people get spooked by the US markets dropping 2-3%, and we can suddenly buy good quality UK companies that have reported strong trading recently, 5-10% cheaper! Also, I like down days because companies that report good trading tend to be ignored, allowing me to buy early, before a price rise that otherwise would have happened on a more normal day.
Anyway, moving on from the general points above, what does PCIP say today?
H1 trading update -
H1 revenues up 56% to £3.19m - which doesn’t sound much. However, it’s the strong rate of growth that matters most, because each new contract is adding monthly recurring SaaS revenues. Hence the more informative measure is:
Total Annual Contract Value (TACV) - this is the run rate of annual revenues from this point in time. Note that it includes existing contracts, plus deployments going live in the next year. So it’s forward-looking, giving us clear visibility for revenues to come. This is up a very impressive +59% to £8.28m.
New contract wins have accelerated: 93 customers (up from 51 in H1 LY), adding £1.68m of recurring annual revenues.
Customer churn is low
Cash - £4.22m gross, but there is some debt, so net cash is £2.1m, down about £1m in 6 months. I’m hoping it won’t do another placing, but we need to be alive to the possibility that there could be one. A (say) £3m equity raise would only dilute 10%, so I’m relaxed about this issue, as cash burn should now be fast reducing as monthly revenues build. Raising a little more cash would be a doddle given the superb growth rate. I worry about placings where companies are not generating enough growth, or burning cash at prodigious levels. That’s not the case here.
Outlook - sounds good to me -
"With a strong pipeline and growing ecosystem of partners, we are now growing this business at pace and we can look forward with confidence to the second half of the year, with strong revenue visibility against market forecasts for the full year."
Diary date - H1 results due out week commencing 8 March 2021.
My opinion - as you’ve probably gathered, I like this a lot.
The current valuation is probably fair, at this point in time. However, I’ve pencilled in a 2-3 bagger on the share price (up to c.£100m market cap) over the next 2-3 years, if strong growth continues, and assuming the current bull market (which values growth companies highly) also continues.
There’s a good update note today from Finncap, many thanks to them. It explains the business model & the opportunity better than I’ve managed above! Also it gives some forecasts, showing the move into breakeven should occur in FY 06/2022. Today’s update reassures that the growth is real, and not a pipe dream.
Therefore I’m happy to tuck away my existing holding for the next few years, and am fairly confident it should do well. Not sure I want to chase up the share price higher than 60p, I was happy buying up to about 50p, so hopefully we might see a pullback in price if the US markets continue selling off, to top up this position. It's quite illiquid, so not one to try and trade in & out of. My buy orders were normally scaled back a lot, and I had to repeatedly buy scraps a while back. Hence why I'm not planning on top-slicing if it goes up a lot, I'll just sit tight.
I appreciate this share won’t appeal to many readers, who prefer to buy companies which are profitable now, rather than ones which are aiming to be profitable in a couple of years’ time.
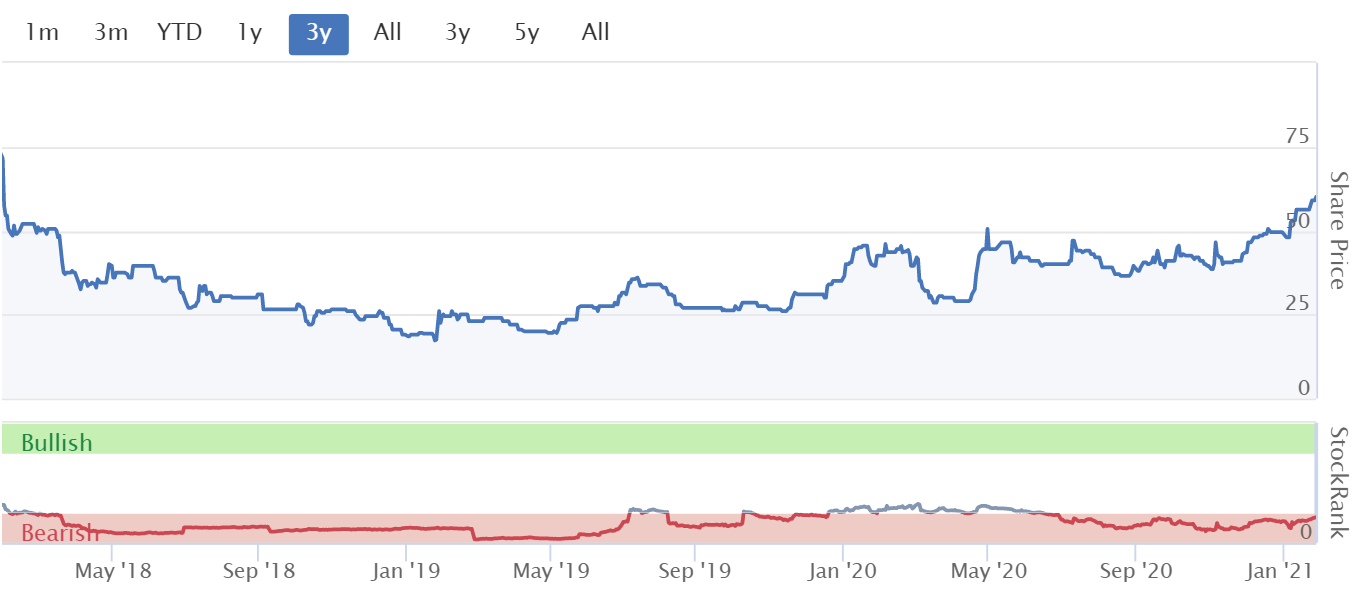
Stockopedia doesn't like it, with a StockRank of just 21, and it qualifies for 2 screens, both bearish! That's understand able though, as Stockopedia is designed to steer us away from more speculative stocks, since many of them don't work out as planned.
.
.
Joules (LON:JOUL)
(I hold)
151p (down c.3% at 11:18) - mkt cap £164m
I’m a bit surprised the share price has dipped a little this morning, as my initial skim of the interim results (as mentioned above) was positive. Let’s have a closer look, I might have missed something.
CFO leaving - after 5 years’ service, the CEO Marc Dench is leaving to join a private-equity backed growth company called HealthHero. He’s staying on until a successor is found, by end May at the latest, to allow for a smooth transition. Based on this information, it sounds like a reasonable and civilised departure for pastures new, rather than something which rings alarm bells, so I’m satisfied with this explanation.
Covering the 26 weeks to 29 Nov 2020, so that’s June-November inclusive. Most of the shops are likely to have been open, apart from a few weeks at the start, and the November lockdown. It says that of the 26 weeks, stores were closed for 10 of them. Hence a fairly badly disrupted half year.
Surprisingly perhaps, it’s remained profitable (ahead of expectations the company says), and there’s a big improvement in the cash pile vs a year earlier -
.

.
Compare this performance with say Superdry (LON:SDRY) or Ted Baker (LON:TED) - larger more well-known brands, but they’re performing very much worse than JOUL, fighting for survival arguably, whereas JOUL is romping along quite nicely.
JOUL will have benefited from Govt support schemes, in particular furlough when shops are closed, to cover a lot of the cost of retaining staff, and business rates relief. The cash pile may have been helped by creditor stretch too, re landlords & taxes. Hence future profits may not necessarily go up from this level, even if revenues do recover the 15.3% shortfall this year.
eCommerce sales - this is the thing to focus on, and it’s the main reason I’ve been building up a position in JOUL. Fashion brands have to crack the internet, if they want to thrive. JOUL is doing that. Gross digital sales are up 55%.
Look at how dominant eCommerce has become during the half year, remarkable stuff -

.
Therefore, we should be thinking about this share as a predominantly online business, with some physical showrooms as well. Mind you, I imagine physical stores are likely to bounce back once trading returns to normal.
The strong growth in eCommerce here is telling us something important - that customers want this product, and will seek out the brand, even when the stores are shut. That augurs very well for the long-term future, in my opinion. It also tells me that JOUL is good at digital marketing.
The usual fashion sector caveat applies, that product has to remain relevant, and not go off the boil. Brands can be quickly destroyed if the designers & buyers go haywire & lose sight of what their customers want. With the founder still active in the business, that’s not likely here. It’s not high fashion either, it’s traditional, country, preppy, influenced stuff - not rocket science, and the core look of JOUL doesn’t change much from one year to another. Hence the fashion risk is probably quite limited.
Current trading - 7 weeks to 3 Jan 2021 - strong eCommerce sales more than offset store closures. That’s really impressive, and greatly de-risks the shares. I think a key point here is that JOUL product, brand image, is very distinctive. It’s not just another me-too fashion brand, this is a product that I think customers seek out, and are prepared to pay a premium price for. I’ve been buying various items from JOUL website recently (in the end of season sale, as I wouldn’t pay their full prices!), and like the product very much - it’s good quality, with nice detailing. One cotton shirt was so good, I went back and bought 2 more of the same style! And 3 of the same light raincoats (well it’s so easy to lose them in pubs & trains, might as well stock up for future misplacements).
Active customers are up to 1.6m - that’s a lot.
Friends of Joules (“FoJ”) marketplace is interesting, going well. This is a curated selection of products from third party vendors. It says there are 10,000 products, which surprises me because my perusal of the site seemed to show quite a limited range of products. I bought a scarf, which arrived promptly, and is good quality, so it works. Joules earns a commission from FoJ - does anyone know what the fees are? Would be interesting to find out. I’m pretty sure the third party vendors look after everything, dispatch, returns, etc. So JOUL should just be earning a pure commission with no costs, lovely additional business. It’s reported within “other revenue”, which more than doubled, from £0.9m H1 LY, to H1 TY at £2.0m. This could become a lucrative business in the future. There’s also brand licensing income within that £2.0m.
Wholesale revenues down sharply (-44%) at £17.1m in H1, which sounds about right, given that customers would have seen store closures, and a need to de-stock.
New Head Office - in Market Harborough - has been a large capex project, which the company expects to move into between now and its 31 May 2021 year end. I wonder if they’ll be doing a shareholder site visit later in the year, to show off the new facilities? That would be a good idea, when possible. The warehouse has also been expanded. I seem to recall they were outsourcing logistics to Clipper Logistics (LON:CLG) as well, after distribution problems a while back?
Admin costs - the stand-out item for me here, as mentioned before, is that Joules spends very heavily on its Head office - £13.4m in the half year (down from £14.9m LY H1, helped by furlough funding). I know the design side of things is important, in making the brand & product distinctive, but an annualised HQ spend of £27m, which is probably mostly salaries, does seem rather excessive. The business needs to grow into that high central cost I think.
Property leases - good progress here, with the underlying cost reduced from £13.8m annualised, to £10.6m. Excludes one-offs, like rent waivers.
Dividends - nothing as yet, but will resume divis when appropriate. That’s fine, I don’t think it’s good for companies to be paying divis at the moment, whilst this covid situation. I’d rather see companies strengthening their balance sheets, and building up financial reserves for the future, in case something like this happens again. Covid has surely revealed that many companies were running too lean, in terms of balance sheet strength.
Bank facilities - I’m running out of time, so won’t cover this. Suffice it to say, that the facilities look ample, and are mostly undrawn. I can’t see any reason why the bank would not be co-operative when it comes to renewing the facilities, so not an issue in my opinion. Moving on.
Brexit - a very topical issue, this has read-across for other eCommerce retailers selling into the EU, so here it is in full -
BREXIT
The Group was well prepared for the additional operational and administrative requirements that came into effect at the end of the transitional arrangement with the EU on 1 January 2021. Notwithstanding this preparation the Group has experienced disruption and delays as well as higher costs on some of its exports from the UK into certain EU markets, with Germany being particularly impacted. The disruption is expected to reduce in time as the courier networks and supply chain intermediaries adapt to individual EU country import requirements.
The new trading arrangement will result in higher costs for certain of the Group's exports to the European Union as a result of higher duty charges, higher courier costs and increased administrative costs. The annual impact of these increased costs is estimated to be in the range of £0.8 to £1.0 million, which is broadly in line with the Board's expectations.
The Group will continue to evaluate and implement options to mitigate the adverse impact including a potential increase in selling prices and structural changes to the Group's logistics.
How interesting. It’s clearly an important issue, that is likely to hurt lots of businesses in the short term, but looks fixable to me. The obvious solution is to open a distribution centre within the EU, and have product sent there directly by the manufacturers, cutting out the UK completely for goods destined for the EU. It would clearly be a hassle to organise that, but once it’s set up, then it’s done, and wouldn’t necessarily be duplicating costs (2 smaller warehouses = 1 large warehouse?)
Looking at the last Annual Report, page 100 gives the geographic split of sales. It’s UK: £161.3m, International £29.5m. It’s not stated what element of international is the EU. At a complete guess, maybe half? That would be c.£15m revenues. So to be incurring almost £1m extra costs as noted above, is quite significant. That would require a rise in selling prices of about 7% in order to recoup it. So that’s the obvious way forwards for UK eCommerce businesses - raise prices for EU customers. Which in turn would be likely to knock back sales volumes, depending on the price elasticity of demand (yay, I managed to slip in some O-level economics there!)
Outlook -
Good - strong eCommerce sales, offsetting lost store sales. Better than expected H1 profits. Cost reductions at HQ, and rent reductions.
Bad - ongoing store closures & cancellation of country shows (but as expected there), higher costs re EU sales,
Overall -
… the Group's strong balance sheet, combined with the strength of its brand, product proposition and digital platform (reflected in the recent strong growth in active customers) will enable it to navigate the current climate and emerge in a strong position.
That’s fine by me, I don’t see anything worrisome in the outlook, all as expected. JOUL is a particularly strong proposition if covid continues to be a problem, as it’s now mostly selling online.
Going concern note - these are really useful, so I’m grateful to the rarely-praised (for good reasons!) auditing profession for requiring these disclosures. JOUL has traded, and continues to trade ahead of its original base case scenario last year.
Latest update -
The updated Base plan forecast indicates that the Group will remain within its available committed borrowing facilities and in compliance with covenants throughout the forthcoming 12-month period, and that the current national lockdown will not impact on the Group's ability to continue as a going concern.
That’s fine, I don’t have any going concern worries about Joules at all. It should be a safe investment.
Balance sheet - NAV is £40.6m. I normally adjust out all intangible assets, which are £18.7m here, giving NTAV of £21.9m - - adequate, but not particularly strong. Although it might include some property (the new HQ site)?
Cash (gross) is £28.6m, which looks flattered by creditor stretch, so I would expect to see cash come down a lot in the next year, as things normalise.
The current ratio is 1.10, which is OK for this type of business, but not what I would regard as strong. For example, special situation Quiz (LON:QUIZ) (I hold) which we looked at yesterday, has a much stronger current ratio! Not what people might expect, but that’s what the figures say.
Liabilities - trade & other payables have shot up from £41.7m a year earlier, to £56.7m at 29 Nov 2020. I can’t find a breakdown of the total, but it’s likely to be mostly trade creditors (i.e. garment manufacturers), tax, and rents owed. It’s probably safe to assume that the increase of £15m vs last year is probably creditor stretch (late payments) that would need to be caught up with at some point in the future. That would reduce gross cash from 28.6m to a more normalised £13.6m.
Overall, that looks OK to me, nothing to worry about here.
I reiterate my point above, that I’d like to see JOUL hold back divis, and instead build up its balance sheet strength, and clear all debt. Businesses of the future need to be stronger financially.
My opinion - I really like this company, that’s why I’ve bought a long-term position in it (medium-sized within my portfolio). My intended holding period here is open-ended, maybe 5+ years?
I don’t really know how we should be valuing this share right now. PER is not the right basis, in my view, as conditions are so abnormal, impacting sales, margins, costs, etc in unusual and hopefully one-off ways.
Thank you to Liberum, who have made a very useful note available by its analyst Wayne Brown, summarising the RNS better than I’ve done above! He’s not changed forecasts today, which are for 2.6p this year 05/2021, rising to 6.7p NY, and 9.2p in 05/2023. At about 150p per share now, the market is already pricing-in a full recovery 2 years ahead. I can see why that wouldn’t appeal to some investors.
For me, it’s not about PERs. I think there’s something special here, in terms of the brand, the online growth, and a bigger, longer-term opportunity for investors, looking years ahead. Hence why I’m happy to hold at what appears to be a high valuation in the short term.
.
I've run out of time for today, will catch up with the backlog tomorrow. Sorry about that, but I wanted to spend time on the most interesting company, with a deep dive into JOUL.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

104 comments
Thanks to greyster and Kouremenous for bringing Fonix Mobile (Fonix Mobile (LON:FNX)) to readers attention. Having never heard of this company, I have been doing some reading up and have come round to the view that Fonix Mobile (LON:FNX) is a decent and uncomplicated proposition which offers good value and potential for the investor. So I have taken a position for the medium to longer term in a bid to diversify my portfolio. Looking at the Fonix team, I was particularly struck how young they are, the client services manager must be about 15 years old!
Sky News have just said that Boohoo (LON:BOO) is in advanced talks to buy the Dorothy Perkins, Burton and Wallis brands for £25m and won’t retain any stores.
Sounds like a good bolt on brand for relatively cheap, especially a further push into men’s fashion with Burton.
Cash shell Ridgecrest (LON:RDGC) (formerly Nakama Group) has been suspended today "as a result of the deterioration in settlement performance". As Ridgecrest recently announced a placing of new shares due to be issued at 0.6p, and the SP has risen to many times that in recent trading, I expect that a Market Maker, or one of the instis earmarked to receive the new stock, has been selling the stock short, either hoping they can settle when the new stock is issued, or that the stock would quickly fall back to nearer the forthcoming placing price.
https://www.investegate.co.uk/...
This could end up being another Room Service fiasco, which some of you may remember involved Evolution Group selling short more than twice the entire issued share capital of the company, in anticipation of making a killing when heavily discounted new stock was due to be issued after a shareholder vote. Unfortunately for Evolution, shareholders voted against the new stock issue, leaving them with a rather large problem.
https://www.fca.org.uk/publica...
Just an observation on £JOUL (Joules) . I live on the West Coast of Wales. We have mostly independent shops here (shock horror) that cater for tourists during the summer. Up till a couple of years ago the go to clothes brands they stocked were SuperDry and Ted Baker. This changed in 2019 (so before the pandemic) when these seemed to go an Joules appeared.
Excellent analysis of Joules (LON:JOUL) Paul thank you. I have was hovering over buying this morning as it was a few percentage down, but thought I would wait until you had covered it. Had my lunch, and then saw your 'deep dive' into the company which is now over 6% up. A demonstration of the power of Paul? I could certainly not comment - just saying.
Anyone else having trouble with IG platform?
It was ok for about 5 minutes after the US market opened but now I can't get in at all.
Getting fed up with this, this is the second time in 2 days.
Had sporadic luck trading with their app the last ten minutes but the desktop is not working
Yes, it won’t give me a margin for Tesla.
Even FTSE 100 spreads are sporadic, occasionally it will work, often it won’t.
Joules (LON:JOUL) (no position)
Hi Paul
Thanks for your write-up on Joules (LON:JOUL) .
I must admit I was quite sceptical when I did my own analysis this morning, but you've made me think about a few things, which I did not fully take into account.
2 points to add if I may.
Gross Margins
The gross margin achieved on e-commerce sales appears to be materially lower than those achieved in store.
"Retail gross margin decreased by approximately 8%pt to 52.8% in the Period. This reduction was the result of the lower proportion of store sales in the Period - with store sales generating a higher gross margin than e-commerce sales"
That makes things tricky as any lost store sales need to be offset by much higher online sales to achieve the same gross profit.
International
Note that the German website is currently taking no orders:
https://www.tomjoule.de/
So that's £30m/£35m (FY19/FY20) of annualised sales that could be immediately lost if they decide to focus purely on the UK going forward.
It will be interesting to see what happens as the dust settles.
Cheers
A
Hi abtan,
Re gross margins at Joules (LON:JOUL) (I hold), I think this period has to be seen as an aberration, because they will have had all sorts of problems with stock intake, stock stranded in stores that are closed, etc. So I wonder if they've maybe used online to clear excess stock at discounts? Everything I've bought recently has been half price online. But it looks like they've cleared most of it now, as several things I liked are now sold out.
Also, wholesale dilutes the overall margin a bit.
I wouldn't worry about it, as once things are back to normal, then gross margin should go back to normal. Why wouldn't it?
Re international - good spot re JOUL German website being temporarily closed for new orders. Why would you imagine this means JOUL would pull out of selling in the EU altogether? As I pointed out in the main article above, the additional costs can be offset with a c.7% rise in selling prices. Logistical problems can be sorted out over time. So to my mind this looks a fixable problem. Time will tell!
Regards, Paul.
Joules (LON:JOUL)
Fair point on the gross margins normalising in time.
For reference I was comparing margins over the last few periods and whilst I can understand the 44.1% achieved in H2 FY20, I would have thought that things would be back to normal by now.
On the other point, I have no idea if Joules would pull out of selling within the EU, but for possibly less than 14%-17% of total group sales (assuming a chunk of this % is from the USA) it could be a huge distraction right now, especially with soaring UK e-commerce sales.
That aside, I'm quite surprised that they didn't mention a risk of lost international revenue in their update today. Or if they did, I must have missed it.
Belvoir (LON:BLV) (I hold)
(The EV of the company is c£62m, so it doesn't look overvalued.)
A nice hold to tuck away in the background as I spend more time on the risky stuff.
A
For £BLV Finncap upgraded broker expectations for FY20 that's now closed to 16.2p (was 15.2p). So this share is trading 11x p/e despite seeing off a pandemic and the lettings fees ban and yielding 4.3%. The share price looks a bit mean and didn't go anywhere on a day the markets went down. A p/e of 13-14x feels fairer value to me. Financial services are providing some additional growth and Belvoir (LON:BLV) has tended to make some decent acquisitions. It's also a company that's had 24 years uninterrupted profit growth.
It won't multi-bag but this has been one of my best little steady 20%+ a year earners in my portfolio for a number of years now.
Gamestop - Caveat Emptor - "Simples", as Sergei would say if he could speak Latin
Interestingly Robinhood are now reportedly stopping purchases of $GME, $AMC etc. on their platform. Users are apparently now only allowed to sell their position. I agree with "caveat emptor", seems extremely questionable to me to fix it as a one way street though...
This could make things interesting...!
Seems very odd, having shares that you can't buy but only sell. I bet the funds that have closed their short positions at heavy losses will be really happy.
These shares have been removed from the platform.
IG did suspend trading for a while I think it was on Monday in $GME.
I see $AAL is up 37% today, so that could be next one.
GME Resources (Australian miner) seem to be doing pretty well up 13% today and c. +80% since December.
Surely no connection????
Does anyone have a Reddit account? If so, I wonder if you could drum up some interest in a few of my minnows? I think they might like Bigdish (LON:DISH) (I hold) in particular LOL!! ;-)
Actually I did open one this morning to see what was going on.
Maybe they need to switch to some UK shares.
You might have enough acolytes to pull it off yourself Paul. J Sainsbury (LON:SBRY) has a 7.9% short. Why not think big
they have rules that only stocks over 1bn can be pumped, sorry I mean discussed.
A very nice update today from £rbgp. The law firm going from strength to strength and reinstatement of a useful dividend. It seems to offer a great deal of value. I hold
Unless I have misunderstood this morning's RNS, yesterday Paradice Investment Management LLC opened an 8.68% short position in Scapa (LON:SCPA) which I hold. I can make no sense of this and would be grateful if anyone can shed light on it. I also do not understand why £ followed by the ticker symbol never seems to work when I use it.
I also do not understand why £ followed by the ticker symbol never seems to work when I use it.
If you follow the ticker with punctuation it doesn't work.
So £SCPA. won't work.
While Scapa (LON:SCPA) will.
No idea about the short interest though, perhaps they expect the bid to fail?
timarr
timarr, thank you so much - edited in the light of your helpful advice.
I think you are probably right about the reason. Several institutions have opened short positions.
Well it does work for me.
Scapa (LON:SCPA).
Scapa (LON:SCPA),
£SCPA?
Depends which site and device you are using.
Paradice are shown as a major holder on Stoko, on Shortdata a company called Merian do have a short of 1.38% 19/01/21. I hold quite a chunk and would of liked a tad more as a longish term holder. I'm no expert PAUL thoughts ???????
Thanks, mikebianchi. I think I have misunderstood the whole thing. My brain is scrambled by the number of Form 8.3 and Form 8.5 notifications today.
Dear OSullivanB
I own shares in Scapa.
If you examine the Scapa statement from yesterday, you will see that three institutions, one of which is Paradice, have agreed to accept the 210p cash offer. Their combined holding is 16% which is insufficient to enable the offer to succeed although it is very early in the offer process. Perhaps of more interest is that today Water Island Capital, BennBridge and Samson Rock have each acquired a notifiable shareholding where they appear to have paid in excess of the proposed cash offer price amounting in total to nearly 5.5% of the issued share capital. This suggests that these institutions feel the agreed offer price is too low and may have to be increased.
Kind regards
Phillip
Scapa (LON:SCPA)
I do not believe that is what those announcements say at all.
Form 8.3 announcements (in relation to a bid offer) merely indicate who many shares are held on the given data , not when they were bought.
Under normal conditions the Water Island, BennBridge & Samson positions were not notifiable, but once a bid is in play anyone holding 1% or more of the issued share capital are obliged to confirm their holding.
Thank you, Gromley.
Thank you, Phillip.
if you read Bill Blain today and consider what is happening with GameStop inc ,you may not be surprised that the market is nervous,irrespective of Covid . Perhaps time to sell and wait for the inevitable market collapse ?
Pockets of mania doesn't necessarily mean that the rest of the market is going to crash though. Although I do think there are lots of warning signs out there in the USA especially - Bitcoin mania, Tesla's ludicrous valuation, many other growth/tech companies on daft valuations, IPOs soaring to large premiums, punters chasing anything that moves detached completely from fundamental values.
But if you then look at the mega caps in the USA, which drive the indices, they're fantastic companies not on particularly stretched valuations, eg. Microsoft, Facebook, etc, I think those look sensibly-priced, given their dominance & growth.
So overall, it's difficult isn't it. I don't see why we would get a widespread sell-off of everything, when only pockets of over-valuation exist.
As long as the zero interest rate, QE-fuelled stimulus continues, and companies earnings continue improving, then it's difficult to see a catalyst for a bear market. I am worried about a correction though, which is why personally I'm not interested in over-paying for things that have gone up a lot in the last 6 months, unless they're absolutely thrashing market expectations.
The Gamestop thing is very interesting & good entertainment. But I do worry that a lot of ordinary punters are likely to lose their shirts. Getting lucky once, is likely to suck people in deeper, who have no idea what they're doing. I wonder how many bounceback loans in the UK have ended up in Bitcoin? Most of the non-shares people I talk to are either punting on Bitcoin already, or have many family/friends who are also doing so. It won't end well, as financial bubbles never do. The only issue is timing of the crash for the worst excesses.
Regards, Paul.
Paul, I remember your comments a few years back about only shorting massive companies, so that you don't get killed by these types of events. Lots of small buyers can move prices drastically. Elon Musk has destroyed how many hedge funds in the past few days with a single tweet. I reckon this is to send out a warning to anyone thinking about shorting Tesla. Entertaining to watch, but lots of lessons in there.
I'm reading that shorts in $GME were over 100%. I don't think shorters will be doing that again.
Also funds are having to sell stock to cover their short positions but $GME is only about $10bn but the concern is these groups will grow and have even more influence on the markets.
$GME is not the only share to be targeted also $AMC, $BB and $BBBY are all heavily shorted shares but have seen large rises recently.
For me this exact issue serves to highlight the significant market dysfunction in the US. The idea that one tweet from a private individual can move countless of billions in capital flow simply speaks to the high risks of investments in US markets. I agree with Paul that some of the large cap valuations don't look completely ridiculous, Microsoft a good example, but we found out last March that when the liquidity gets tied up absolutely everything is sold, rational or not. Concepts such as efficient markets and price discovery seem to have gone missing for me in many cases. London listed stocks by comparison seem reasonably fairly valued in general, nevertheless the FTSE will no doubt (unjustly) get slaughtered again if there are large falls stateside. This inevitably leaves me holding significant amounts of cash presently, which i dislike having to do but it feels like i have no other choice.
its the new world, retail access has fundamentally changed how markets will operate so best get used to it
New paradigm? new world? fundamental change? Heard it all before i'm afraid. Tell that to the folks that waited nearly a decade to get their money back after buying the euphoria of the yr2000 boom and bust. Gd luck
From what I read from various sources and analysing different charts, the US main market is expensive on a P/E of 34 but it isn't in a bubble. Compare that to the UK stock market which is on a P/E of 16.
The things which appear to be in a bubble are certain US tech stocks and cryptocurrency.
At some point a correction will happen because that is the nature of stock markets but the markets will recover over time.
Yes but the companies in the US are different from the UK, compare our largest companies with the US, which has far more Tech. companies. Then compare the growth forecasts, in their top 100 companies with ours. There is hardly any growth in our FTSE100, no surprise that over the last 20 years the FTSE100 index has hardly gone up at all.
It is like comparing apples with lemons.
Hi MrM,
Another interesting angle on this fascinating development of shorters becoming the hunted, not the hunters, is that it calls into question the role of the shorting dossier.
Previously, shorters have typically prepared very detailed, extremely biased, and often inaccurate reports, in order to damage companies and panic shareholders into selling. Sometimes they get it right with frauds, and sometimes it's hot air (e.g. the rubbish published about Boohoo (LON:BOO) or Learning Technologies (LON:LTG) and others).
In the past, some shareholders panic sold, but I wonder if the tables might turn now? If someone puts out a shorting dossier on a company, what's to stop Reddit people (I know nothing about Reddit by the way, must have a look at it later), or advfn/Twitter people, to turn on the shorters, and start aggressively buying up the shares, forcing the shorters to panic buy, driving the price up further?
This is clearly all market manipulation, so is a dangerous area.
It would be quite nice to see unscrupulous shorters, attacking decent companies, getting whacked hard by other shareholders, who buy more, instead of panic selling.
Could publishing a shorting dossier become counter-productive, if it provokes buying, not selling?! It's possible I suppose.
Just a thought.
Paul.
I don't find the Gamestop thing remotely good entertainment Paul. It is a serious issue.
Fundamentally users on Reddit and other social media are targeting any heavily shorted company and driving its price up way beyond anything that could be considered a reasonable valuation for a company by creating mass micro investment hysteria. There appears to be an anarchist theme to this as well. People are talking about "sticking it to Wall Street", "not about the money" etc.
This leads to a couple of things. Firstly, whilst some shorting is the equivalent of ramping and deserves the investor ire it gets, much of it plays a valuable role in keeping the market in check and smoothing volatility. It also acts a natural circuit breaker when markets fall as shorts buy back stock. We should not forget that bubbles tend to get bigger and crash more spectacularly when shorting is not available.
The effect of this movement in Gamestop, AMC, Blackberry, iRobot and even Nokia over the last few days is having a profound impact on Funds that go short. In effect they are now looking to extricate themselves from short positions to manage risk. If this persists and is not tackled by regulators quickly then shorting will become too risky. At that point the market is imbalanced and structurally problematic.
So why do countries ban short selling if it is so good for the markets?
" The practice has been blamed for exacerbating volatility during times of stress."
Surely this recent action is just rebalancing what shorters have been doing to share prices and the markets?
Countries generally don't. They ban short selling on Financial Institutions rather than outright short selling bans, at least in developed markets. Largely this is politically driven and from a public confidence standpoint. The problem is that financial institutions depend on Joe public depositing savings with them. If said public get spooked that a bank may be weak then it leads to a run on that bank leading to its collapse. Shorting exposes the weakness of the bank and media will point to it creating mass hysteria. Hence the short selling ban was to make sure the illusion and confidence of the banking sector was maintained.
Shorts both keep markets in check and reduce volatility and help reduce the risk of asset bubbles. That is a good thing in my view. Financial stocks are not suited because they are systemic to the economy and mainly built on public confidence.
.
The Germans tried banning short selling an decided it didn't really have much effect. Why shoot the messenger? The questions I have is how much is it possible to deliberately manipulate a share price by groups of people clubbing together to attack shares, and do bot trades play a part in this manipulation, or do they simply correct prices over time? Why are they usually thousands of small trades?
I like Harry and Paul skit of the financial crash pretending to be entrepreneurs in the Dragons Den. Paul: 'you buy this blank bit of paper off me for 2 million.' Harry: 'gosh why is it worth 2 million Paul.?' Paul : 'Because I say it is.' Then they carry on swopping it for ever increasing amounts at which point Jones makes an offer and confesses to being Harry's brother.Pretty much sums up shorting in reverse.
Personally I think its good that average people can make such an impact. This is a statement on the markets to say the underlying way the markets trade is changing
It's market manipulation - it is far from good!
I'm all for the average guy getting the same tools as the professional investors (plug Research Tree as an example). I am not for organised manipulation. It will suck in a lot of other small retail investors at the top and burn them badly. Not pleasant.
It's been going on for a long time, the difference now is there are more people being influenced by tweets or social media comments, as more people have easy access to buying shares on such platforms as Robinhood.
I think this will be difficult to regulate, how will they do that?
Don't forget those shorting shares are only too happy to publicise their actions in the hope of getting more people on to their bandwagon. They are not shorting for the overall benefit of market participants, simply for their own profit motive. They are not likely to get much sympathy.
Yes and often a biased damning report to go with it.
As with anything Long or Short there are exceptions. I am similarly minded where there are certain funds who short a good growing company and then throw a sensationalist damning report out there for their own benefit. This is no different and no more acceptable than ramping a stock long in my opinion.
Those are the exceptions though and the headline grabbers. The short market is much much bigger than that globally and most participants behave responsibly and play an important role in the equilibrium of the market. Don't make the mistake of tarring the whole of the short market with the same brush.
It's market manipulation - it is far from good!
As there's no centre to this then regulators are lost, they can only go after individuals deliberately trying to manipulate share prices. This is hive mentality, you can't slap an injunction on an angry swarm.
If you read the reddit source material it's not about making money, it's about sticking it to Wall Street. It's driven by intergenerational anger about wealth dispersion and the way financial institutions have been privileged over other parties.
It is, if you like, a form of mob-led socialism using the tools of capitalism.
Like all rockets when it runs out of fuel, when there's no more money to invest, it'll fall to back to earth, but in the meantime good luck to them.
timarr
It will have started somewhere - there will be a core group. The regulators will look for it I'm sure, but whether it is traceable who knows. I do know it is dangerous mob mentality and I don't wish them any luck; it is downright dangerous and will most likely cost a lot of unsophisticated investors a lot of money. I don't see how you can wish someone luck in suckering a whole load of other retail investors in to lose their money!
But shorters sell shares they don't even own.
Shorters cause many investors to loose money, it is not just unsophisticated investors, some of my shares have suffered shorting attacks.
Would you be happy if say 50% of your shares were shorted and the prices went down 50% or more?
Maybe the rules need to change on both sides.
Hell yes, that would time to pick up a bargain!
I don't see how you can wish someone luck in suckering a whole load of other retail investors in to lose their money!
I spent a long time talking to my 20 year old about this last night. It's a completely different mentality to anything we've ever seen before. But I think the regulators will be very careful about moving without strong evidence of intent - to be seen to discrimate against retail investors in favour of institutions would be damaging for them and would likely provoke a different kind of backlash. People have the right to spend their money however they choose, even if that means setting fire to it.
And who are we to judge who's suckering who? Many of the reddit flash mob have already made enough money to retire on.
On a more practical note, institutions caught on the wrong side of this trade may well need to raise funds by selling their most liquid positions. We may see some interesting opportunities arising over the next few weeks.
timarr
The flash mob are irrelevant and to some degree so are the institutions.
The issue is that the flash mob through their behaviour encourage many other unsophisticated retail investors in to the shares often towards the top. Then the crash back to reality comes and who loses.............? the general retail investor buying at the top. That is who we should care about protecting.
That is who we should care about protecting.
Caveat emptor applies.
I'm all in favour of the nanny state, but if we start cossetting investors the last bastion of freedom has fallen.
timarr
"If we start cossetting investors"
I think the millenials on Reddit would very much like it if central banks stopped cossetting investors via endless QE.
I'm all in favour of the nanny state, but if we start cossetting investors the last bastion of freedom has fallen.
The problem is that the vast majority of the people taking part in this charade aren't `investors'. They're gamblers.
And they're only able to do so because iof sites like Robinhood, who offer free trading. But the only reason they can offer free trading is that they use the site to lure naive people into highly risky areas like options / CFD's / cryptos where they do make money out of them.
Such companies should be classed as gambling companies, and be subject to the same regulation as other gambling companies.
If I decide to start looking at Reddit (whatever that is) and see something that is going to be bid up would I be wrong in buying it? It would be at my own risk and up to me to try to get out before it collapsed. Incidentally, I believe that before this started 140% of the share capital of GameStop was shorted. Can that be right?
If I decide to start looking at Reddit (whatever that is) and see something that is going to be bid up would I be wrong in buying it? It would be at my own risk and up to me to try to get out before it collapsed.
I think there is a culture difference here - in the US they would say its your money your choice your risk you do what you want to do and as an adult deal with the consequence.
In the uk we would say as a potentially vulnerable person who can't make up their own mind you need to be protected from having the option to lose your own shirt or win 2 shirts.
Sensibility probably lies somewhere inbetween.
So 'collusion' and market manipulation is bad when small private investors do it and needs to be stopped by regulation, but when hedge funds engage in the same type on manipulation it's OK as it improves market efficiency? Not convinced.
The sudden calls for more regulation by the large institutions on the losing side of this trade strike me as hypocritical at best.
Saw a brilliant Facebook post yesterday saying that Citadel front run orders from Robin Hood - so in effect they get a tiny advantage in seeing orders before anyone else - so what not many realize is that Citadel are actually profiting from all this!
Investing has, and will probably always be, a game controlled by institutions who unfortunately operate in a different world to the rest of us private investors, and who have access to information that we simply don’t. Yes funds may be less nimble than a private investor, but then there are many bottom feeders who’ve set up shop in Mayfair with a couple of traders, a quant and a risk guy managing enough cash to make a decent return by targeting certain sectors / stocks, who can move very quickly. Or HFTs who have bought and sold in the time it takes you or me to take a sip of tea.
Robin Hood have undoubtedly been ‘leaned on’ by institutions moaning to the Fed about recent activity and how unfair it all is. I applaud the notion but fear for the novice investor who may well lose his or her shirt when all this unwinds.
Bubbles and rampant over / under valuations inevitably correct themselves, whether shorters are part of that correction or not. For example, the situation where Tesla is more valuable than many of the world’s largest auto makers combined and whose P&L is sustained by tax credits - eventually reality sets in and people realize it’s overpriced.
And I suspect the current situation is made worse by the fact that people are simply bored and can’t do the things they normally can...
I find it very amusing how little people understand why Tesla is so highly valued. Lots of people did this with Amazon too, when they didn't understand what Jeff Bezos was doing and were all 'well anyone can set up a website and run a shop can't they?' My day job is technology investment and it's really, really complicated. Even people who know technology and are experts in a field often struggle to say whether something is groundbreaking or not. But if you listen carefully you might understand why. Someone on this thread once said something about 'anyone can build an electric battery for a car' and it really made me laugh. No, they can't. They might be able to copy Tesla in time, MAYBE. The thing about Tesla is it's energy management system that manages the battery and that's software and probably a lot of other things that I don't understand and others don't too. It's going to take a long time for other companies to get even remotely close...and god knows where Tesla will be by then.
Tesla don’t make the battery. They buy them. They buy the same batteries as everyone else. See the recent news reports of Germans being extremely unhappy with the range of their Made In China Model 3s.
VW are already eating Tesla’s lunch, any market where the Model 3 and ID.3 go head to head the ID.3 is winning, as Deiss mocked Musk for in a tweet recently.
Real world tests by independents have stated the Mach-E goes further than the equivalent Model Y.
Ditto the Taycan versus the Model S. Porsche have just announced a “cheap” Taycan to directly compete with the Model S.
Tesla’s results last night were shambolic. Missed earnings, stretched creditors, huge accounts receivable, a load of costs stuffed in “other”.
Yeah, years ahead.
History is littered with first movers who no longer exist - I just apply logic: 1) Tesla was 1st to mkt with electric offerings that sold in any scale, 2) Demand and regulations dictate that electric car sales will increase, 3) The competition will catch up - because they know how to build cars - i.e. produce a vehicle in volume, reliably and turn a profit. Tesla does not know how to do this.
So I do not believe that Tesla will continue to dominate the sector - and if software or their charging network is their USP - both can be replicated.
So where will Tesla be? No-one knows but one guarantee is that they won’t have the market to themselves, and competitors will become faster & cheaper. Throw in the erratic behavior of the CEO and avoidance of jail time - yes people have gone to prison for far less - you have an interesting situation, one I’m just happy to watch from the sidelines.
History is littered with first movers who no longer exist
RE: $TSLA
Maybe so. But the first time judywil posted that she owned Tesla was December 25th (yes, really) 2019. Tesla's share price then was $63.95. It's now $845.71.
Where's fair value for Tesla now? No idea, but I wish I was so wrong.
It's important to remember that the competition has serious legacy drags on their business. The cost of winding down existing production - particularly diesel for the German car manufacturers - is a serious inhibitor of future growth.
Don't misunderstand me, I think Tesla's current share price is insane. But I thought that on December 25th 2019, in between basting the turkey.
timarr
I don’t understand the point about costs of winding down production. Cars / engines manufacturing plants get repurposed every few years. It’s nothing new for companies that have actual product development lifecycles, rather than ones who put a square steering wheel in car (Austin Allegro anyone?) and make out it’s something amazing.
I don’t understand the point about costs of winding down production
Well, there's plenty of research out there about the challenges facing car makers of winding down production of ICEs while also ramping up those of EVs, if you're interested. They can't just switch because the former are far more profitable and they need the cashflow to fund development of the latter.
The economics of ICEs v EVs is fascinating too, The main cost in the latter is the battery, which existing car makers don't control while EV manufacturing is a significantly different process, with far less parts to make, or things to break. That feeds into the post production process, potentially impacting the franchise model and the concept of after sales - which is more like a software update than a traditional service. Add in a lot of unneeded workers, their redundancy costs and pension liabilities and it's a real challenge to manage the transition.
Under the bonnet this leads to the question as to what extent ICEs and EVs are really the same type of thing. And from that you have to ask to what extent ICE manufacturing and EV manufacturing are the same sort of process. And, hence, to what extent legacy car makers have any kind of competitive advantage over the upstart EV makers.
It's all very interesting, if you like that sort of thing,
timarr
That rather reminded me of the period when the Labour government led by G. Brown was promoting diesel cars and everyone was buying them. The argument was that they had a better environmental footprint. Oh dear. What a clown he was.
Shame I couldn't give this one hundred upvotes!
Hi davidjhill,
Good point, well made!
I was listening to a podcast from the brilliant Grant Williams series, unfortunately cannot remember the interviewee, he was a care-worn sounding, hilariously funny and sometimes foul-mouthed, older American man, called Mark something, who's a shorter. He was bemoaning that (as you suggest) shorting has become too dangerous now, and that valuations in the US have in many companies become so divorced from reality, that many short sellers are withdrawing from the market altogether, as they can't make any money. Shorting focused hedge funds, are struggling or shutting up shop.
As you say then, a key brake on the market does appear to be disappearing for now.
Regards, Paul.
Paul
I don’t disagree with your comments but possibly because of my age (74) I’m not so sanguine about the current situation and the Gamestop caper is yet another flashing light to me. How many times with hindsight do we say ‘the approaching crash / correction was obvious’. This morning I started cashing in some of my profits and will largely sit on the side lines for a while – I can’t afford to wait n months / years for the market to recover IF it crashes. If my timing is wrong I’ll come back out of ‘partial’ hibernation – no doubt just as the next hedge fund crashes or a sovereign debt crisis erupts!
Good luck to the youngsters who stick with it !
Thanks for comments and sorry if I gate crashed the thread. On balance I tend to agree with you David and am worried that there could be an anarchist agenda to all this . Mind you I won’t be selling Boohoo,:) or indeed most of my long positions. May sell a few of the others though to have a bit of cash to buy more Boohoo if there is a major correction.
I agree with you Jim. Plenty of stocks are overhyped and overpriced and the market has rather ignored the pandemic, inevitable tax rises and the possibility of higher interest rates in my view. A lot of government cash has funded gambling in the markets; but when it stops and has to be paid back, what then? Corporation tax may increase in the March Budget and other tax increases may include capital gains. How many people are really out of work in the UK, discounting the furlough scheme?
"Individual investors attack hedge funds" scream the headlines. This is not investment; it is pure gambling. The smart ones will take their money too early but plenty will get badly burnt.
The thing that worries me about the gamestop thing is not the (obvious) bubble but what happens on the burst.
I would not be surprised if a lot of people with leveraged 'investments' in gamestop / BTC / your choice of tulip do not have significant assets.
When it goes wrong and there are heavy margin calls
1
There will be a lot of counterparty risks - if you had 1000 gamestop @180, you may be happy now, but less so if it reverts to 4.
2
there will be 'cascade risks' - closing the gamestop position that went wrong could trigger the closure of other (high risk) positions that are in the money.
This is what worries me.
There was a time in early feb 20 where i internally debated whether to cash in or perhaps it is a small correction. So I decided on a strategy of 'masterful inactivity', expecting a small dip. It was not comfortable but ended up ok.
I think we are heading towards the same need to decide time.
Fonix Mobile (LON:FNX) update today makes for interesting reading to me (I hold).
Pre IPO results for 2020 were Rev 113m, Gross profit of £9.99m, Op profit £7.2m (similar PBT)
Todays update gives a GP of £5.8m for the first 6 months. They state that "operating costs are at similar levels" (I'm assuming that excludes exceptional IPO costs) so on the assumption they post similar figures for H2 then the forward PE is in the region of 17-18
Looks v good value to me given the growth potential so be grateful if you could take a look Paul.
Thanks
Confirmation too that they expect to pay a dividend (expectation seems to be around 5p which is 3.5% yield).
They've previously mentioned there has been no churn from major customers in 6 years, and I think we can probably assume that's still the case from today's update (" We have significantly grown existing client revenues").
So decent growth and a dividend, with customers sticking around, it certainly feels like good value to me.
I also hold. Cash generative and revenue growth in the mid teens with operational gearing kicking in is a powerful combination. A 1y Fwd PE of 17 doesn't look bad value to me for a business that should be capable of that kind of growth on a 3 year view. A 3.5% approx dividend to boot. Unlikely to be spectacular riser (though I bought at 95p so its done quite well in just a few months) but can see it bringing steady returns of 20%+ p/a so fits nicely in the GARP section of my portfolio
Hi just a quick query on Fonix Mobile (LON:FNX) , is it not reliant on terrestrial TV audience going up? Is there much relevant programming on NetFlix etc?
Hi,
TV is just one application, their mobile carrier billing system can used for multiple mediums - web, tv, gaming..
Apologise this thread is not related to today's small-cap report. A quick question regarding £BALF.L (Balfour Beatty). Looks a solid stock but over past days they have continued to buy back shares. Looking to invest. Any observetaions
you should probably best go about this by adding a new "Post"
https://www.stockopedia.com/co...
this Post (series of) is intended for small cap stock discussions (with some exceptions for past winners that were in here from the start).
I was surprised to see that Jacqueline Daniell, who was today appointed as an independent NED at Crimson Tide (LON:TIDE) is eligible to be classified as “independent”. While I am sure the advisers have done their job correctly, if I were writing the rules I would not allow a director with such connections to be called “independent”.
As a reminder, Jacqueline Daniell is CEO of Wey Education (LON:WEY) - where Barrie Whipp is Chair. Barrie Whipp is also chair, founder and major shareholder of Crimson Tide.
Wimbledonsprinter, you are quite right. There must be a big question mark over how these two directors of Wey Education (LON:WEY) and Crimson Tide (LON:TIDE) can be considered to be independent. Such cosiness almost inevitably leads to a conflict of interest. I would have thought that an appointment such as this would have been scrutinised by those responsible for compliance.
If I held shares in either Wey Education (LON:WEY) or Crimson Tide (LON:TIDE) my finger would be on the sell button.
Re useless RNS, the multitudes of £boo updates on minuscule changes in ownership, back and forth, by Stanley Morgan are up there for me.
Has anyone else looked at the image in the Iq-ai (LON:IQAI) RNS this morning. The CEO says "...the images are so remarkable that "wow" is the only word that seems appropriate..." The image shows a few blobs - no context and no description of what they are doing. I think stocko should run a competition for the most useless RNS. I put forward this one and the one from Open Orphan (LON:ORPH) on Jan 21 that tells us someone has written an article.
Chris
A bit harsh.
From what I’m reading in the RNS from IQ-AI (LON:IQAI) they think they’ve achieved a breakthrough in producing brain scan images without using contrast agent.
Graham
Iq-ai (LON:IQAI) is one of those stocks that traders and rampers have jumped onto it seems. I am late to it and just bought a small position given that the price appears to be somewhat of a support level price .
I was put off with the company when it made a huge jump on Nov 3rd - when a "licensed" product which they have rights to sell obtained FDA clearance and the BB's were going ape stating "wow ...ooo THEIR product has FDA clearance etc". I was left extremely perplexed - the IP does not belong to them. Seems the rampers have left this stock now
Anyways - two key factors that make them legit (decided to jump in after some initial research and will do in-depth later:
- They have spent circa $20mn in the P and L - so likely on R and D,
- they have partnerships with some big US hospitals who are trialling out their products.
- Prima facie - their products appear to be legit and state of the art.
- A small shareholding by the Mayo Clinic Endowment Fund - surely some DD was done by the former -
AI in biotech is a hot theme e.g. Renalytix Ai (LON:RENX) (I hold) , don't like their cash position and Covid is impacting on them. Overall, let's see how this pans out.
And got to hand it to the CEO for his Wow comments - yay!
For the second time this week, there is a significant RNS from Getech (LON:GTC).
Earlier in the week, Getech announced "Two exclusive strategic partnerships that bring Getech, H2 Green and SGN together to advance a network of hydrogen hubs across the UK"
This is building on the company's core skills as a "provider of data, knowledge and software products to the energy industry".
Even this week's share price surge has barely pushed the market capitalisation over £10m. This is real tiddler of a stock.
Today, Getech announced major board changes including a new "big-hitter" Chairman.
When I bought the shares 2 years ago at around 29p, a key factor was a new CEO (Copus) with plans to leverage the firm's geospatial expertise to generate recurring income rather than one-off consulting fees.
Arguably, this is now happening. O n the other hand it may not.
Either way, this is an interesting situation worth watching.
Fevertree Drinks (LON:FEVR)
Year end update today
It's been a very tough year for fevertree with their on trade sales decimated by covid.
The future growth here lies mainly overseas and for the first time non UK has generated over 50% of revenue.
- UK sales went into reverse dropping 22% from 132 mill to 103 mill (Like Arnie they will be back when pubs reopen)
Thankfully the non uk sales clawed back more than half that shortfall increasing from £127 mill to £149 - leaving the company only £8 mill down on the prior year.
Note although on trade sales have been decimated the off trade has seen a spike in demand that will probably subside once the pubs reopen.
The company presvioulsy expected £235-£243 mill sales in septmeber so £252 is a decent beat - although i expect forecasts would have been ultra cautious so perhaps what they were hoping for but didnt tell us if i am being honest.
If we look at half year splits they were £13 mill behind last year at the H1 mark and only £8mill behind at the year end so they have shown growth in sales in the second half of the year compared to last which is impressive, well ahead of where i would have guessed when we were in first full lockdown. Slight caveat here they had german acquisition that generated £6.4 mill of incremental revenue so possibly more accurate to say h2 in line ish with h2 last year
US and ROW (non uk europe) alone should provide sufficient growth in 2021 to keep the numbers moving forward nicely if we ignore any temporary covid related hits they may take on the way.
The price premium to buy the shares is the same as the price premium to buy their mixers anything but cheap so that will put most bods off - but i feel for this company with the brand name , rock solid balance sheet (proper bullet proof) and worldwide marketplace the future still looks bright even if the uk growth prospects look slightly limited (probably closer to non existent).
With up to £143 mill cash in the bank now i wander if they might be making some acquisitions if something complimentary comes up for sale in the non uk marketplace.
Finally one note ref bottom line numbers - looks like margins will be down. I am very comfortable with the margins and bottom line profits being what they are with this business at present - they run it lean and mean outsourcing production and its really all about the sales numbers at present they can worry about pimping out the the botom line finer points when they are at a much more mature stage in their further to reach marketplaces. Note that's not to say they aren't doing a decent job in that regard at present.
Shifts in region and channel mix continued to impact the gross margin during the second half of the year. Our EBITDA margin is in-line with expectations, and while this is down on the prior year, due to the strong revenue performance, earnings are expected to be ahead of expectations.
For those who might be interested following Paul's review of Strix (LON:KETL) yesterday, Equity Development's interview with Mark Bartlett, CEO is here:
https://www.equitydevelopment....
Morning Paul
If you get a chance can you cast your eye over Fonix Mobile (LON:FNX) who announced a comfortably in line this morning in their initial trading update since IPO. Pre IPO metrics look good and seems to be a decent looking business.
Greyster
From Monday, the Sthree (LON:STEM) analyst presentation with Q&A. Always interesting to see how recruitment companies are doing, especially in STEM sectors (science, tech, electronics & maths). Of course, CV19 has taken a hit, but they still have their sites on becoming the #1 STEM talent provider. This is the last set of results with the CFO, Alex Smith, who will leave after an orderly handover. Video & podcast.
My morning smallcap tweet:
Belvoir (LON:BLV) Haydale Graphene Industries (LON:HAYD) M&C Saatchi (LON:SAA) Gresham House (LON:GHE) RBG Holdings (LON:RBGP) accesso Technology (LON:ACSO) De La Rue (LON:DLAR) IQ-AI (LON:IQAI) Avacta (LON:AVCT) Genedrive (LON:GDR) Fonix Mobile (LON:FNX) Biome Technologies (LON:BIOM) Parity (LON:PTY) PCI- PAL (LON:PCIP) Dillistone (LON:DSG), Tribal (LON:TRB), Epwin (LON:EPWN)
Belvoir (BLV) guides FY(Dec) rev up 12%, better than pre-covid mgmt exp. Expect pretax comfortably ahead of mgmt exp. [SP=170 Cap=60m]
Haydale Graphene Industries (HAYD) guides H1 broadly in line with mgmt exp. 2 year sales representation agreement in China with expected orders $300k min in year 1 and $500k in year 2. [SP=NA Cap=NA]
M&C Saatchi (SAA) FY20 expected to be ahead of Oct guidance. Net cash £33m, significantly ahead of expectations. [SP=NA Cap=NA]
Gresham House (GHE) guides FY(Dec) adj op profit ahead of market expectations. AuM up 42%, 35% organic. [SP=NA Cap=NA]
RBG Holdings (RBGP) guides FY(Dec) rev (including realised gains) and EBITDA ahead of mkt exp. No figs aside from net cash £3.5m. FY div 3p. "The Board expects to see an increase in M&A activity in 2021 driven by the economic conditions and the possible changes to the Capital Gains Tax regime. These trends will benefit both Convex Capital and RBL." [SP=NA Cap=NA]. I hold.
Accesso Technology (ACSO) guides FY20 rev at least £55m, ahead of mgmt exp. Net cash c. $30m. However trading will likely continue to be impacted by lower venue attendance over H1. [SP=NA Cap=NA]
De La Rue (DLAR) guides FY(Mar) adj op profit £36-37m cf F/C c. £34m. "As a result of the continued positive momentum of customers switching to De La Rue's SAFEGUARD® polymer substrate, and to create more possibilities in relation to future expansion, the Company now plans to spend approximately £20 million on its polymer strategy, an increase on the approximately £15 million previously indicated. Total aggregate 3-year investment for the Turnaround Plan remains unchanged at £79.8m." [SP=NA Cap=NA]
IQ-AI (IQAI) claims improvements in s/w mean 'simulated' images generated using the AI model now very closely mimic actual, with contrast, images. Will make further comparisons. [SP=NA Cap=NA]
Avacta (AVCT) collaboration agreement with USA co Bruker to evaluate the Affimer-based, bead assisted mass spectrometry covid assay. Bruker is one of the world's leading analytical instrumentation companies. [SP=NA Cap=NA]
Genedrive (GDR) US and Europe distribution agreement with Beckman Coulter Life Sciences for Genedrive 96 SARS-CoV-2 Kit. "We are very pleased to now take our initial collaboration and development agreement to the commercial stage." [SP=NA Cap=NA]
Fonix Mobile (FNX) guides H1(Dec) rev and profit comfortably in line with mgmt exp. Total Payment Volume £123m up 18%. Gross profit up 21%. Expect maiden interim div. [SP=NA Cap=NA]. I hold.
Biome Technologies (BIOM) guides FY(Dec) rev broadly in line with market expectations at £5.7m, down 17%. Guides adj pretax loss (before depreciation AND amortisation) in line. "Whilst the longer-term outlook for the [legacy] Stanelco RF Technologies division is slightly more encouraging than in 2020, the Board expects that headwinds will continue in the short term." Bioplastics mkt expected to grow. [SP=NA Cap=NA]
Parity (PTY) guides FY(Dec) adj profit flat. "Recent new business performance and the benefits of a lower cost base as a result of the successful transformation programme, should allow us to grow both net revenue and profit before tax in the coming year." [SP=NA Cap=NA]
PCI-PAL (PCIP) guides H1(Dec) rev up 56%. Net cash of £2.1m. "Strong revenue visibility against market forecasts for the full year." [SP=NA Cap=NA]
Dillstone (DSG) guides FY(Dec) adj pre-tax loss flat or better than FY19. £1.5m cash at hand, does not expect to need to raise additional funds. [SP=NA Cap=NA]
In line: Tribal (LON:TRB) Epwin (LON:EPWN)
Fear & Greed Index
What emotion is driving the market now?
Last week 65 (greed) and now at 40 (fear).
That Fear and Greed index is quite a mixed bag of component measures currently -
Stock Price Strength at Extreme Greed
Put and Call Options, Stock Price Breadth and Market Momentum showing Greed
Junk Bond Demand, Safe Haven Demand and Market Volatility all showing Extreme Fear.
https://money.cnn.com/data/fea...
Morning All,
Property Franchise (LON:TPFG) announce a large acquisition of another listed business in Hunters Property (LON:HUNT), part cash and part shares. wonder if Jack may want to cover as Estate agents was a focus of Mello a few weeks back, would be interested to hear others thoughts too
Yes, its an interesting situation. The acquisition has a high P/E so its a bit of a challenge to see why they are making this acquisition when there would have been smaller private entity opportunities, presumably. It maybe that the sum of opportunities opened up by this acquisition is greater, and to some extent reduces competition in a similar space. Agree an overview from Jack would be helpful
I would’ve thought there would be significant cost savings by merging some of their centralised operations. Having a lessor number of Non-execs, as well as adding on the savings from Hunts AIM listing and it’s probably being bought for c.10x earnings.
Property Franchise (LON:TPFG) are experienced in buying other (granted smaller) franchisors and bringing them into the group, so I feel comfortable knowing that the price they have paid, whilst looks expensive from the outside, once reorganised may deliver terrific value.