Small Cap Value Report (Thu 30 April 2020) - SHOE, NANO, UPGS, CNKS

Good morning, it's Paul here with the SCVR for Thursday.
Estimated timings - I'm running late today, so will keep going until about 6pm. Apologies for any inconvenience. Edit at 20:05 - I'm wondering why I put in estimates for timings. Anyway, today's report is now finished.
De-listing risk
In the small caps world, we always have to be wary of the smallest companies, as they sometimes (often without warning) announce their intention to leave the stock market and become private companies (known as de-listing).
This usually does instant, and major (typically about -50%) damage to the share price. For this reason, it's vital to avoid buying micro/small cap shares where there's a risk of de-listing.
Off the top of my head, these are the main reasons (hence risk) of a micro cap de-listing;
- Running out of cash, and no appetite from the market to provide fresh equity funding
- Story stock that has gone stale - i.e. everyone's heard the story, and it's never worked, so impossible to get even gullible investors to back it again
- Little to no liquidity in the shares - hence there's no point in being listed
- Costs - often linked with the other points above - all the various costs of a listing can mount up to £100-200k, even for the smallest companies - e.g. broker/NOMAD, listing fees, PR, NEDs that probably wouldn't be employed at a private company, regulatory burden, wasted mgt time, etc. If there is no discernible benefit from being listed, then why continue with it?
It's worth checking our existing holdings, to see if any micro cap holdings display those traits. Covid-19 & the recession it's triggering, could well accelerate the de-listings of some micro caps. Hence why I mention it - this is an increased risk that could us money.
Getting rid of bad investments
It's tempting to allow bad investments to languish at the bottom of our broking account. I had one situation like that this week, Malvern International (LON:MLVN) which issued an update that sounds terminal. Without refinancing, it says cash will run out in May, i.e. imminently. I had previously bought quite a lot in a 4p placing during the bull market, but the turnaround plan didn't work. Thankfully I got much of my cost price back, by top-slicing when it initially rose to about 7p. However, the rest are now almost worthless compared with what I paid. It looks like Covid-19 could finish off the company. I had about 1m shares left, and had mentally written them off. Anyone refinancing the company probably wouldn't want their money wasted on listing costs.
Then yesterday, I worked out that even at a share price of barely over nil, my shares could still be sold for about £500 before commission. I thought to myself, that I wouldn't toss away £500 if it was cash, sitting in front of me! So why throw away £500-worth of shares, to a very likely £0 outcome? Or a refinancing that dilutes existing shareholders so much that my £500 became say £50, or £5? Therefore, after pondering this, I bit the bullet, and instructed my 2 brokers to both sell "at best" (i.e. for any price you can get), which recouped at least c.£500 from this failed investment.
The chances of such investments (a basket case) ever recovering, are minimal, therefore clinging on in the hope that it might recover, is nearly always the wrong strategy. It's actually stubbornness that stops us selling, not any real belief that the share would recover.
I can also recommend the therapeutic benefit of a horrible loss disappearing forever from the portfolio statement I see every day.
Shoe Zone (LON:SHOE)
Share price: 90p (down 1% today)
No. shares: 50.0m
Market cap: £45.0m
Result of GM and interim update
This is a chain of shoe shops, selling cheap, Chinese-made shoes on the High Street and from retail park "big box" stores - which are obviously all closed at the moment, due to lockdown restrictions.
My report here on 3 April 2020 reviewed the situation - with SHOE saying it had to cancel its proposed dividend, and secure a new bank loan, in order to survive (that's how I read it anyway). As mentioned at the time, I was tempted to buy some at 60p, but decided that risk:reward wasn't quite right for me personally. The share price has since risen 50% to 90p - which is fine, it has rewarded people who took the risk when things were uncertain. I don't regret not buying it, because I've had similar 50% gains over the same period, from other shares where there was probably less risk. It's remarkable how many share price charts look the same right now. So big winners in the last month have not really been down to good stock picking, it's more a general market move up. Which could easily reverse, so congratulations are premature.
Yesterday's update - contains good news. The special resolution to cancel the unaffordable final dividend, passed almost unanimously. Some idiot with 25,891 shares voted against, but 99.94% of shares voted in favour. This outcome was never really in doubt, but it's good to have confirmation.
The company has a FY 09/2020 year end, so details of the first 6 months are given. Since Covid-19 and store closures kicked it right at the end of H1, then the H1 figures are now irrelevant.
Liquidity - this is the all-important question of whether SHOE will survive?
As at close of business on 28 April 2020, the Company has a net cash balance of approximately £5.4m, having utilised the existing £3.0m bank facility.
That seems to be saying that it has £8.4m in cash on hand, and £3.0m bank debt.
A new bank/Govt loan has been agreed -
This morning, the Company received formal notice that its application for a £15.0m loan utilising the Coronavirus Large Business Interruption Loan Scheme, has received credit committee approval from its primary lender, Natwest. Shoe Zone welcomes this support from Natwest and the Government, however there is significantly more to be done to protect the Company's financial position.
The last line worries me. Surely £8.4m cash on hand, plus a new £15m loan should be ample to protect the company? If not, why not?
It does go on to reassure with this comment -
...the Board consider the Company's current level of funding will be sufficient to secure the future of the business, assuming that stores are allowed to open gradually during the summer months and return to a high proportion of previous sales over the next year.
That seems consistent with what we're seeing in other countries - i.e. shops starting to be allowed to re-open, subject to social distancing, mask wearing, etc. The question is whether it is worth retailers opening stores if they're only likely to achieve modest revenues? I think we might see retailers cherry-pick, and only re-open their most profitable sites. Many others, in loss-making or marginal sites, probably won't re-open whilst restrictions on footfall remain.
Dividends - always the main attraction of this share, are now off the table for some time, by the looks of it. Very sensibly, the company wants to not only re-build, but increase its future cash position -
Over the forthcoming financial periods, Shoe Zone will focus on rebuilding cash balances to a higher level than previously carried, repaying debt, and fulfilling other statutory obligations. The Board believes that this focus is necessary to ensure the long term viability of the business, and the Company will therefore only recommence the payment of dividends to shareholders once these objectives have been met.
The Group therefore cancels its previously announced dividend policy and a new policy will be announced when the board believes the Company is able to resume making dividend payments to shareholders.
This is of wider read-across. We now know that many companies were running far too lean on cash reserves (something I've been going on about for many years!). The risk from a virus, leading to shutdown, was out there, but ignored by practically everyone. Things have now changed, and companies generally will need to bolster their balance sheets, and have higher cash reserves, and lower debt.
For this reason previously high yielding shares such as SHOE may not pay any divis for several years to come - making things much harder for income-seeking investors, such as the retired.
My opinion - the company's survival now seems secure. However, with no divis likely for several years, I don't see any attraction to this share right now. It's rallied nicely from the lows, and is probably high enough for now, in my opinion.
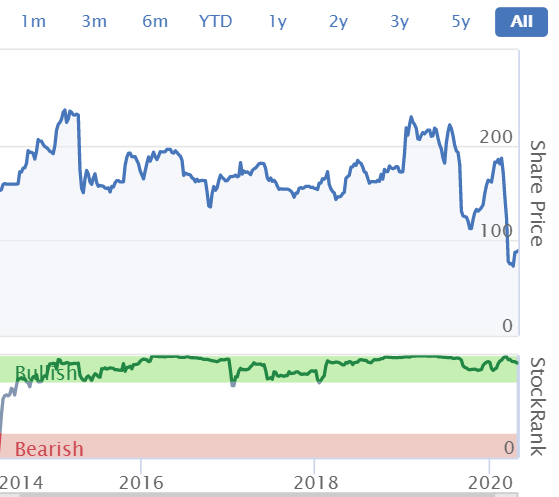
Looking at the long-term chart, and given the uncertainty surrounding High Street retailing (will it ever get back to how it was, and it's been in long-term decline for years, even before Covid-19), then I wonder how much upside there is now on this share? 50% perhaps, over several years, if we're lucky? Also, I wonder if income-seeking investors may decide to bail out, which could create an overhang of sellers in future, perhaps? I just don't see enough upside potential in this share right now, to get excited about.
.
Nanoco (LON:NANO)
Share price: 10p
No. shares: 286.2m
Market cap: £28.6m
(I currently hold a long position)
Termination of formal sale process
No offers have been forthcoming from interested parties. Onset of Covid-19 disruption means no attractive outcome likely, so talks have been terminated.
Patent infringement lawsuit against Samsung - in "advanced stages" of securing third-party funding to progress the case.
Commercial progress - no figures given, so not able to ascertain if this is significant or not -
Nanoco also continues to explore commercial opportunities, with purchase orders having been placed for existing and new materials for sensing applications and a new joint development for R&D services being currently documented with an existing customer.
Covid-19 & liquidity -
...management has taken action to reduce costs and maximise its cash resources while preserving its production and R&D capabilities. The Group's cash runway now extends to the second quarter of 2021.
The Board continues to review all the strategic options available to the Company, including possible sources of additional funding for the Company, with contingency plans in place if needed.
Given that we already knew the company is in poor shape financially, then having enough cash until Q2 2021 (subject to commercial agreements being signed) seems OK for now. That's an improvement from previous position of cash running out in July 2020.
Interim results - a second announcement.
First, I've refreshed my memory by re-reading a section I wrote about NANO here on 4 Mar 2020, where I concluded that it looks high risk, but possibly worth a fun money punt. I can't remember buying any, nor why, but as disclosed in the section header above, there's a small NANO long position in my spread betting account.
Nanoco Group plc (LSE: NANO), a world leader in the development and manufacture of cadmium-free quantum dots and other specific nanomaterials emanating from its technology platform, announces unaudited Interim Results for the half year ended 31 January 2020 ("the Period" or "H1 FY20").
As with most companies, at the moment the historic results are only of passing interest. It's what happens in this new, Covid-19 world, that matters in two ways - 1) will a company survive, and 2) will it be able to achieve commercial success at all, or again? All the evidence suggests that economic recovery from Covid-19 could take several years. This is what many CEOs are saying, when interviewed in the USA on CNBC.
With NANO, it looks much more specific: it has to win new business. In the past, it apparently only had one specific customer, in the USA. This is obviously therefore a special situation. If it wins the Samsung legal case, then that could provide upside, although I don't know what the size of the claim is - do any readers know?
For the record, 2019 looked like this:
- Revenues £2.9m
- LBITDA -£1.1m
- Cash £4.2m
- Loss after tax is -£1.9m (it looks as if NANO gets R&D tax credits, hence the after tax result is the most relevant)
Going concern - as you would expect, given that this is a special situation, the risk of insolvency is highlighted in a going concern note -
However, given that a degree of uncertainty exists in respect of future revenue and management's ability to implement the necessary cost savings in a timely fashion, there exists a material uncertainty in relation to the going concern basis adopted in the preparation of the financial statements.
Clearly then, this is not a share for widows or orphans.
My opinion - this is just a complete punt. Must admit, I'm wondering why it's valued at £28.6m, which seems quite high for a company that's not far away from the last chance saloon. But the technology does look interesting, and has generated some (albeit small & lumpy) sales. There could be speculative upside from a no-win-no-fee case against Samsung too.
Overall, I can't assess what the most likely outcome could be, hence it's just a total punt for me. I should probably sell them actually, but today's news (in particular extending cash into 2021) gives me some comfort that it won't be a 100% loss this year, probably.
Up Global Sourcing Holdings (LON:UPGS)
Share price: 50p (down 6% today)
No. shares: 82.2m
Market cap: £41.1m
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces its interim results for the six months ended 31 January 2020.
This company sources product from China, to sell to UK & European retailers.
I published an audio interview here with its Managing Director, Andy Gossage, on 20 Feb 2020. At that point Covid-19 was only a problem in China, and our main concern was China supply chains. Obviously everything has since changed, with 90% of UPGS's China suppliers now back to normal output, but demand now being the big issue, from UK/Europe retailers, many of whose shops are currently closed. However, UPGS also sells to supermarkets, and online, which have remained open.
Another worry, is whether customers are paying up for previous deliveries? There must be some withholding payment until they can re-open and get some revenues coming in again.
Incidentally, my occasional interviews are for our general interest, are not recommendations, and are independent because I don't charge companies anything - I just wouldn't feel comfortable charging anyone a fee. Have done so in the past, but it didn't work for me.
H1 results to 31 Jan 2020 clearly only tell us how the business was peforming before Covid-19 had an impact. The answer is, that it was trading fairly well -
H1 revenues up 2.8% to £67.7m
Underlying PBT up 4.8% to £6.2m - note the decent profit margin of 9.2% - which is around the level I like - a c.10% margin tells me the business is doing something well, but not so profitably that it's likely to attract competition or repel existing customers.
Covid-19 impact & outlook - this is the bit that matters, and UPGS confirms that it has been hit by a reduction in demand -
...the Group has seen customers defer and cancel existing orders and delay placing new orders since the lockdown started.
That's very obvious, so no surprises there. More detail is given further down today's statement -
We are continuing to make sales via online and to retailers that remain open, albeit at a reduced level. Total invoiced revenue for FY 20 as at Friday 24th April 2020 was £85.9 m (FY 19: £90.6 m) and there was an order book for the remainder of FY 20 of £18.1 m (FY 19: £27.0 m), although further deferrals and cancellations remain a risk.
Working through those numbers, H1 revenues of £67.7m, and YTD revs of £85.9m, means that H2 to date (Feb,Mar, and up to 24 Apr) was £18.2m,
The same figures for LY are: H1 £65.8m, YTD £90.6m, giving H2 to date LY of £24.8m. That's down 27%, but includes Feb and about half of March, which was before lockdown was imposed. Therefore, clearly the run rate in April must be far worse than -27%.
How might this impact the H2 results in due course? I reckon H2 revenues could be half H1, which would reduce gross profit from £16m to £8m (NB. See "EDIT" section further down, as this looks too optimistic!).
The big advantage UPGS has, is that operational gearing isn't such a problem, because it is selling on low gross margins (only 23.6% in H1). Therefore even if admin costs are unchanged in H2, at £9.4m, then a halving of turnover would only result in a move from an H1 profit of £6.5m, to an H2 loss of £-1.4m - not a disaster.
Actually, I might be under-stating the H2 loss, as it looks like there's some seasonality, with H1 being stronger than H2. There's an update out from Equity Development, which I've not looked at yet. I'll probably use their estimates as a base, but adjust them for myself to be more pessimistic. However, I've not taken into account cost-cutting in my figures, which goes the opposite way.
For this reason, I reckon UPGS should be able to survive this crisis. It depends how much its balance sheet is stretched by customers withholding payment? That worries me more than the downturn in sales.
Action taken -
Stopped capex (but it's light on fixed assets anyway, so probably not a big issue)
Deferring tax payments using Govt schemes
Short term tweaks to bank facilities (will this be enough, I wonder, if customers are not paying enough of the receivables?) -
Further to the renewal of bank facilities on 1 October 2019 with HSBC (see below), the Group has received credit approval for a £4.0 m increase in its RCF facility, amortising over the period to 31 January 2021. In addition, the Group has already effected an increase in the percentage of receivables advanced via the invoice discounting facility and an extension of the funding period of its import loan facility with HSBC from 120 days to 180 days.
Interim divi suspended
Purchase orders reduced
Upside - possibility of acquiring new brands, at attractive prices
Some employees put into furlough, but no figures given
Director pay cuts - CEO & MD have taken 100% pay cut until things return to normal (very impressive show of commitment), other Directors taken 20% pay cut
Profit warning - as I was expecting, but I wonder why the company has left it this late (2 months) to confirm it?
Until early March, the Group was trading well and in line with expectations, despite the supply chain challenges in China. However, the prevailing issues on the demand side mean that the Board is anticipating a significant drop in revenue in H2 FY 20 compared to previous expectations which will impact the overall profitability for FY 20. The overall picture remains volatile and unpredictable making it difficult to forecast.
The share price has only moved slightly today, so clearly the market had already worked this out! You would have to be living on the moon not to have worked out that H2 is likely to be poor.
Balance sheet - looks OK to me, but the company is clearly reliant on bank support.
There's a question mark over receivables - these could take longer to collect, and there might be some write-offs for customers who go bust.
My opinion - I don't see any immediate risk of insolvency, but I can foresee working capital getting tight.
It all depends on when lockdown is eased, and how much customers order & pay for,
For me, there's still too much uncertainty, so I'm happy to keep a watching brief on this one. Hence I'm neutral on this share for the time being, and the price looks about right given the current state of play.
EDIT: I've now had a look at the latest ED note, and they're even more cautious than me. Their updated figures for FY are;
Forecast revenue: £93.0m - this implies £67.7m H1 (actual), £25.3m H2 (forecast) - a huge fall in H2 of 56% vs prior year.
Forecast adj PBT: £3.6m. Given that it made £6.2m profit in H1, this implies a £-2.6m loss in H2 - not good, but not disastrous either.
End of edit
Cenkos Securities (LON:CNKS)
Share price: 49p (up 2% today)
No. shares: 56.7m
Market cap: £27.8m
Cenkos Securities plc (the "Company" or "Cenkos" or the "Firm") today announces its results for the year ended 31 December 2019. Cenkos is an independent, specialist institutional securities group, focused on small and mid-cap companies and investment funds. The Group's principal activity is institutional stockbroking.
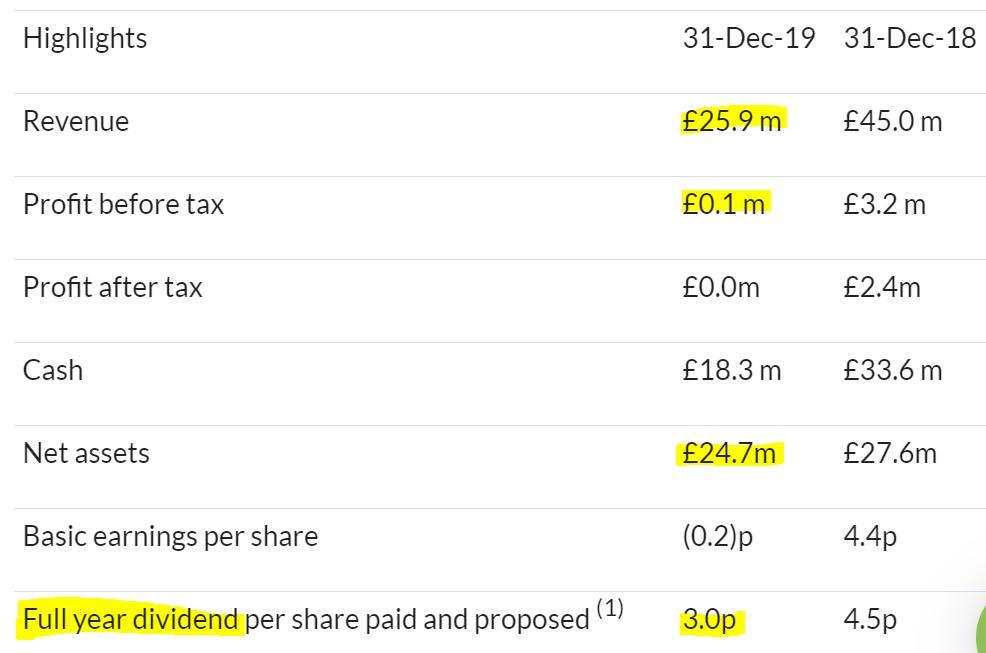
Here are the key financial highlights, as chosen by the company. For me the stand-out features are that despite a big fall in revenues (expected), it still managed to breakeven, not make a loss. I think a lot of that is down to flexible costs - i.e. staff get big bonuses in good years, but nothing in bad years. Also noteworthy is the 1.0p divi proposed - giving 3.0p in total - very significant for a 49p share, and at a time when many companies are pulling their divis due to Covid-19 uncertainty.
.
.
Another remarkable figure for a 49p share is this;
Since being admitted to trading on AIM in 2006, the Company has returned £114.1 million of cash to shareholders, equivalent to 176.3p per share, before the payment of the proposed 2019 final dividend of 1.0p per share.
Although a lot of that was down to a highly lucrative relationship with Neil Woodford, when he was flying high. Apparently, to get a big IPO away, signing up Woodford would then pretty much guarantee other fund managers would follow suit. That made bumper fees for Cenkos, which may never be repeated.
Management changes at Cenkos, could mean it has another period of success, who knows? Also bear in mind that huge numbers of listed companies are & will need to repair their balance sheets with equity fundraises. Not as lucrative as big IPOs, but still decent fees to be earned. I note that Peel Hunt & Liberum seem to be doing plenty of business in equity fundraisings right now.
Outlook comments are upbeat -
The outlook for 2020 is clouded by the, as yet unknown, economic impact of COVID-19. I am however, pleased to report that we have started the year well, completing the largest IPO on AIM so far this year and despite unprecedented market circumstances have also executed a number of secondary fund raisings.
We are continuing to work closely with our corporate clients to assess the impact of COVID-19 and the disruption that many of them are currently experiencing. We have a good pipeline, a cost base that is significantly below the 2019 level and a strong balance sheet, so I look forward to 2020 with tempered optimism. We are well placed to face the challenges ahead."
.
Balance sheet - bear in mind that the market cap is only £27.8m, you're pretty much getting the business for free. That's because net current assets (working capital), including £18.3m cash are £24.3m, or 87% of the market cap. I find that remarkable.
Note that a new, £5.2m longer term liability has appeared. This must be linked to the £4.5m right-of-use asset that has also popped up this year. Therefore these are IFRS16 figures, which I tend to look at with interest, and then cross out. Although in this sector IFRS 16 disclosures are more useful, because brokers may not need glitzy city offices in future, given how well things have continued in the mainly work at home situation currently.
City offices - talking to my friends who work in the City normally, I'm detecting a subtle change. Initially they loved working from home, seeing more of their kids, avoiding the hassle & wasted time of commuting, having to wear ironed shirts and trousers, shaving, etc. Now they're mainly telling me that the novelty is wearing off, and they're itching to get back into their City offices, not every day, but for 2-4 days per week. Providing the bars & restaurants are open, and it's safe to mingle again. Which sooner or later, it will be of course.
My opinion - I'm warming to the idea of buying back into Cenkos - I've held it before, for a recovery in share price that never really happened, although some nice divis popped into my accounts while I waited.
Many companies will need to raise fresh equity. Therefore fees are rolling in for brokers.
My main problem, is I don't trust this recent market bounce from the lows in March. So Cenkos remains on my watch list.
All done for today. As usual, apologies for the painful slowness of today's report. See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
You didn’t highlight this bit from SHOE which is key:
”assuming that stores are allowed to open gradually during the summer months and return to a high proportion of previous sales over the next year”
that is a big assumption! A return to a high proportion of the previous years sales? Given the reduction in jobs, salaries, footfall I can’t see it being a high proportion. Or maybe it’s cheap shoes will do well? If it’s online business improves it may stand a chance.
Good point, thanks for highlighting.
I did mean to emphasise the above point, but it slipped out of my mind whilst I was typing the report. So great that you flagged it! :-)
Paul writes in a way that shows he cares for his readers.He reminds me of Jeffrey Bernard who wrote in the Sporting Life in the seventies.He tells us about his ups and downs and his personal problems in a way we can relate to.I certainly can .Selling too soon ,hanging on too long are just a few of the things I have done.Holding on to Shell for the dividend being my latest error.
Thanks John, that's really nice. I'm an open book - it's just better that way - more interesting for readers, and often cathartic for me! :-)
I agree with Paul's comments about the feel-good factor that comes with clearing off a horrible, loss making position. It's pretty hard psychologically to crystalise a loss. ( I say this despite having read numerous investment books, years of experience and "knowing" the sunk costs fallacy.)
No problem for me psycholologically in dumping at the first sign of accounting scandal or even doubts. Or doubts about management oversight. Allied carpets (from years ago) springs to mind. More recently for me Avast - not accounting, but they'd been wrongfully harvesting user data. Avast have bounced back since that incident late last year.
I find cheap, large companies that go on to get cheaper very hard to cut loose. In fact I generally don't - to my cost. So after the COVID crash, I got rid of WPP at at very big loss and part sold ITV (ditto), but foolisly continue to hold Lloyds on its graceful descent.
Thanks Paul for the Cenkos update.
Bearing in mind that cash and other assets cover most of the market cap, a recovering business is in the share price almost for free. So it looks astonishingly cheap.
So though agreeing current market gains look unsustainable surely a good chance that Cenkos share price will hold up anyway. Indeed today the share was up 1p on a big down day.
Already they are getting a few more contracts and as long as that continues, or better still frequency and fees increase, surely a good chance the share price will at least double in time?
And they have always paid out a large chunk of profits in dividends. So could again become a great income share too. With business almost in for free, surely downside is limited as long as they do get a chunk of the many likely fundraisings ahead.
Yes I agree, I don't hold any Cenkos Securities (LON:CNKS) at the moment, but writing the above section did start my twitching buy finger moving! What puts me off, is that I think the overall stock market is crazy right now. Hence I don't want to buy anything, until there has been a cathartic general sell-off. Look how most charts look exactly the same right now. Stock-picking doesn't even come into it.
FWIW (nothing), I've re-opened my hedges, ie shorting the Dow. It's almost the only thing I've made money on this year, before people tell me how dumb that is!
I see that Warehouse and Oasis have gone into administration, following Debenhams, Laura Ashley and Cath Kidson. The chairman of John Lewis suggested this morning that some of its stores won't reopen after lockdown.
By the time this is over my local high street will be populated by estate agents and charity shops, and I'm not sure about the estate agents. Who's going to bother going there?
timarr
The newly unemployed and impoverished I am afraid.
Bonitabeach
The largest agent, CWD, put out an update statement today. "The Group manages approximately 86,000 properties in the UK on behalf of private and investor landlords and has a responsibility to keep our tenant community safe and compliant with legal standards through regulatory processes including: gas safety; essential maintenance; urgent repairs; and emergency rehousing. These are managed from our property management centres which remain operational, for this essential business only, supporting 100,000+ tenants who are reliant on us to manage their housing emergencies. The Group continues to facilitate lettings renewals through these centres and new lettings through remote working. Total renewals and new lettings together are running at 48% per week compared with the average for the first 12 weeks of the year". So they remain busy with 78 per cent on furlough.
Will all those staff come back? I doubt it. US unemployment; new claims up to 30 million. Just shows how many jobs in the UK must be under threat.
And I'm not sure about the charity shops.
Thanks for flagging, I hadn't spotted the news about Warehouse & Oasis.
I recall that Oasis got into trouble many years ago, and did a pre-pack administration to ditch its loss-making, problem leases. It then went on to trade very well indeed for years.
I wonder if the profitable stores might continue again, under a new pre-pack administration? Although given lockdown, even if it's partially eased, I wonder if any of their stores are likely to be profitable in the short term?
Maybe we'll see Boohoo (LON:BOO) pick up both the brands, and bolt them onto their online only juggernaut?
I had hoped that Boohoo (LON:BOO) might pick up Warehouse & Oasis but I see:
Hilco, a capital restructuring firm, have bought the brands and all the stock. for Oasis/Warehouse
Not sure what they intend doing with either.
Sounds like a pre-pack then - i.e. ditch the loss-making stores, and emerge a profitable business. I think Hilco tried that with Comet, but it didn't work?
I had Pv Crystalox Solar (LON:PVCS) which trades at massive discount to cash but with the prospect of only £2m being returned and the co delisting I cut my losses on what was left of this special sit.
On the subject of delisting, GAN is an interesting example. The company has decided to delist from London and move to the NASDAQ next week. Very difficult to buy these now albeit there are some huge trades going through. The share price has soared over the last month although it had done very well before. It will delist and relist on the same day. Why? Simply because a lot of its business is in the US, it is easier to raise money there and the US values growth companies like this much higher.
I hold GAN and I am very interested to see what price GAN opens up at. I will certainly be looking at other companies that make the similar journey. Our markets often value tech type companies very lowly..... more should make the switch.
I hold Gan (LON:GAN) barnetpeter which is due to list on NASDAQ next Wednesday 6th May.
Today it has been removed from the HL list of Shares but on Advfn its mid price is 237.5p up 15.5p on the day.
I am up 45% and it will be very interesting to see how the US investors value the share especially after the Road Show to promote the listing.
Portugull. Some were panic selling this at 60p just a month ago. Up 14% yesterday and 9% today at 250p offer.
Interested with your views on cleaning out dead wood from portfolio and getting some money back rather than potentially zeroing. I bought shares in a small diagnostics company 3 years ago and its shares dribbled consistently lower. I had all but forgotten about them until I noticed a tipster last autumn pointing out they had arranged financing which looked like the last gasp. So I sold them at 16p. Since February £Ncyt have done ok...
The exception that proves the rule maybe?! ;-)
To quote William Bernstein
"There are two kinds of investors, be they large or small: those who don't know where the market is headed, and those who don't know that they don't know."
I have absolutely no idea and have a lot of time for investors such as Terry Smith, Nick Train and Keith Ashworth-Lord to name but a few.
Yes, good link Simoan. Why is Sharw being voted down for saying so? Is it people who do know what is going to happen?
The more I look at Flowtech Fluidpower (LON:FLO) the more I become impressed by its management. Very lucid and open narrative in this mornings prelims, particularly the introduction by the chairman, Malcolm Diamond, who is unfortunately stepping down after 6 years. Despite the challenges and cyclicality of the industry I believe it will survive and emerge a stronger and better business.
I hold.
Keep well all.
Hi Jonno you've inspired me to look into Flowtech and on the surface it looks enticing. The shares look undervalued at 80.58p.
Do you have any knowledge of what their Goodwill figure (Y/e 2018) of 63m is based on? Goodwill and intangibles seem to make up a substantial part of the company's total equity.
Cheers
Flowtech Fluidpower (LON:FLO) has expanded through acquisition over the last five years; hence the large goodwill figure, and the debt level. From experience, I know they overpaid by some measure for two companies. This is a disaster waiting to happen. I would not touch this with an insulated, isolated, telescopic, shock-resistant, sound-proofed barge pole. (But I am probably wrong!)
Cheers Beginner.
Care to explain?
Flowtech Fluidpower (LON:FLO) bought out two companies I formerly dealt with. In both cases they were, more or less, family members working together from a big shed. They paid, in my opinion, way too much for both businesses. They have bought businesses in the good times, paid top dollar, and now have to run them through the bad times. They have issued at least three profit warnings in the last four years, and will probably do so again soon. The house broker cut its EPS forecast by 20% in January. This should be a good company, but it isn't. It moves up and down like a fiddler's elbow, so by all means trade it. But to me it does not seem to be a viable long term investment (said the man who stuck dosh into Intu Properties (LON:INTU) and Carillion (LON:CLLN) !)
I have been a holder of Flowtech Fluidpower (LON:FLO) for a while - and its not one I've been particularly tempted to add. I don't sell much but this one has always been on the block. I never quite pull the trigger but above £1 I'd let go. learned the somewhat painful lesson of how careful you need to be with acquisition-intent companies - over-paying for businesses being a cardinal sin. also their insistence on a absolutely daft dividend has left it a bit vulnerable on the debt side. I do think they'll make it through now and there are signs that they're a bit more serious about cashflow conversion and balance sheet. it may well end up being a decent steady-state business but the jury is still out.
Ditto Carillion, we live and learn...
(I hope)
Hi BullsnBears
Apologies for the lateness in getting back to you. As beginner has said the goodwill arises from the acquisitive strategy adopted by Flowtech Fluidpower (LON:FLO) when it first listed. The aim being to consolidate a fragmented industry. This left the company with too much debt for comfort much of which resulted from earn outs paid to acquired businesses compounded by an over generous and naive dividend policy. Both of these are now in the past
The penny started to drop about a year ago, when debt reduction became a primary focus. The acquisition driven strategy was primarily undertaken under the previous CEO, Sean Fennon, although in fairness Bryce Brooks, the current CEO was part of the management team at the time.
In some respects I perversely think that the current crisis, whilst a disaster both in human and economic terms has a silver lining for Flowtech Fluidpower (LON:FLO) in that it has further forced the company to focus on debt reduction and consolidation. Hopefully if it gets through the current crisis and I think it will, the company will hopefully emerge financially more prudent and chastened. Despite the obvious misgivings I believe that it is a half decent company capable of being a market leader in a niche area of the construction/engineering industries
I have been in and out of Flowtech Fluidpower (LON:FLO) on at least two occasions being fortunate to sell when the price ran ahead of itself. However I am about 25% down on my current holding.
Flowtech Fluidpower (LON:FLO) has in fairness been a bit of a marmite stock. I can see Beginner's point of view, although I think that his assessment is a little harsh. Also I agree with Jimbonambo41 regarding the historic generous dividend policy. I would have preferred the company to have been less generous and used cashflow to pay down debt.
On the plus side the company continues to trade profitably; net debt has reduced by £3.3m to £16.6m over the last months and is expected to reduce further during the current year. Gross margins are in excess of 35% and cash flow and cash conversion have increased significantly. The details are in latest broker research released to day by Finncap which can be downloaded for free, once you register, at
https://researchlibrary.finncap.com/
These are my views which as you can are markedly different from those expressed by Beginner, but it takes two to make a market and I may well be wrong, as I have been in the past. As always DYOR.
Best wishes.
Here's Proactis Holdings (LON:PHD) H1 2020, analyst presentation given yesterday, by Tim Sykes, CEO & Richard Hughes, CFO.
Final reminder to join today's piworld Thursday webinar, 1pm, where Financial pundit, David Buik will be giving his views on markets, money and the economy. And, you get the chance to ask your question(s). Register via this link.
Morning Paul interestingly your prediction about Nanoco (LON:NANO) has come true they are out of cash by second quarter 2021 but have obtained third party funding for the Samsung lawsuit. Guessing this must be a no win no fee type arrangement but for plc's.
Hi clarea,
Thanks for flagging, I hadn't noticed that announcement.
I'll look at Nanoco (LON:NANO) next this afternoon. I bought a few for my punting account a little while ago, but forgot to update my news alerts for the addition, so hadn't spotted today's results.
Regards, Paul.
No worries Paul maybe one of the directors saw your ramble a few months back and nicked the no win no fee idea. As you say utter punt one would have thought claim must be of reasonable value to go to the bother of putting in a claim in the first place.
On UP Global Sourcing Holdings (LON:UPGS) -> The most interesting thing to me is the lack of chat (here, Twitter, ADVFN) and very muted trading so far on results day.
I wonder whether a lot of PIs sold out over the recent covid linked hiatus? Or maybe everyone is nonplused
I have seen a few comments on Twitter regarding UP Global Sourcing Holdings (LON:UPGS) results... including from myself.
My own opinion is that the outlook until the virus fallout is over is rather dire, with product supply reasonably okay but demand from customers rather poor. The results to January 2020, even before the virus really showed itself, seem quite lacklustre, with only low-mid single digit increases in revenue and profit - supermarket and online growth was very good, but it looks like the majority of sales are to Discounters and these declined by over 16%.
FYI, Jarvis Securities (LON:JIM) issued an ahead of expectations trading update today and the share price has reacted accordingly (perhaps overreacted, although the quarterly dividend is still over 5% pa). I hold
According to Reuters, Royal Dutch Shell (LON:RDSB) has cut its dividend (by 66%!) - the first cut since World War 2.
ricardo
The ever depressing online FT has the Royal Dutch Shell (LON:RDSB) dividend cut as its main headline this morning. Some rumours that company received government funds from Netherlands government and quid pro quo was no dividend. Not sure how that squares with a reduction by 66% but perhaps something to do with dual listing in UK & Netherlands? The cut demonstrates the unprecedented times we are living through. Have to ask what is the point of holding many equities with limited growth potential (e.g. oil sector) if no dividend income!
Royal Dutch Shell (LON:RDSA)
"Have to ask what is the point of holding many equities with limited growth potential (e.g. oil sector) if no dividend income!"
Was there ever a point? Warren Buffett in one of his shareholders letters mentions this:
For the crux of Smith’s insight, I will quote an early reviewer of his book, none other than John Maynard Keynes: “I have kept until last what is perhaps Mr. Smith’s most important, and is certainly his most novel, point. Well-managed industrial companies do not, as a rule, distribute to the shareholders the whole of their earned profits. In good years, if not in all years, they retain a part of their profits and put them back into the business. Thus there is an element of compound interest operating in favour of a sound industrial investment. Over a period of years, the real value of the property of a sound industrial is increasing at compound interest, quite apart from the dividends paid out to the shareholders.”
Last downturn Shell actually raised debt to cover the dividend. This time they have gone into this downturn with higher debt levels. It's always bugged me about doing this, especially as tax is due on dividends (if not sitting in a SIPP/ISA). Imagine your own personal balance sheet - take out a loan from the bank with interest, then have to declare the cash received from the loan as income and pay tax on it.
Have to ask what is the point of holding many equities with limited growth potential (e.g. oil sector) if no dividend income!
And as if by magic, Terry Smith has the answer: https://www.fundsmith.co.uk/ne...
All the best, Si
simoan - many thanks for that link. Brilliant! "In my view, all of this speculation is useless. No one knows". Should be compulsory reading for all who post here.
I like to think that 90% of those who post here are smarter than the average investor (that especially applies to Paul and Graham).
Gosh, someone is very mean hereabouts.
Yes, the link was good reading. I often wish, particularly at times like this and with the benefit of hindsight, that I'd just put all my money with Terry Smith instead of thinking I could do better myself.
I see that he mentions "the 47 stocks in the Stoxx Europe 600 that are “family influenced”". Is there any simple way of identifying these stocks?
The statistic "47 stocks in the Stoxx Europe 600 that are family influenced" comes from research from AlphaValue.
The 47 companies are:
Adidas, Carlsberg, Pernod Ricard, Clariant, Fuchs Petrolub, Dassault Systemes, United Internet, BMW, Porsche Holding, Coloplast, Fresenius, Getinge, H&M, Ipsen, Kuehne & Nagel, Merck KGaA, Novo Nordisk, Novozymes, Roche, Sonova, Vifor, Investor AB, Kinnevik, Wendel, Pargesa, Bollore, Maersk, Securitas, SGS, Schindler, Sartorius, Ferrovial, HeidelbergCement, LafargeHolcim, Antofagasta, ArcelorMittal, Beiersdorf, Richemont, Henkel, LVMH, L’Oreal, Hermes, SEB SA, Swatch, Carrefour, Colruyt, Sodexo.
It's not clear what AlphaValue's definition of 'family influenced' is.
https://www.bloomberg.com/news/articles/2020-04-17/europe-s-big-and-hungry-family-investors-mean-safer-dividends?sref=wORX77mh
The missing three, which have cut dividends, are Adidas, H&M and Kuehne & Nagel.
timarr
Many thanks to you and Timarr for this information.
“....I'd just put all my money with Terry Smith instead of thinking I could do better myself.”
I bench mark myself against Fundsmith and this has crossed my mind as well but:
Whether it will be I am yet to find out.
Hello purpleski, I also bench mark against Terry Smith and can confirm that it is possible to produce exceptional returns by applying his methods to smaller companies as I have been doing this since shortly after he launched his flagship equity fund. I suggested to him that it would be good to start a smaller companies fund and he did indeed launch Smithson but I was actually thinking of companies which were smaller than those in the Smithson universe. I also treat Nick Train and Keith Ashworth-Lord as mentors and borrow their ideas heavily. I was pleased to learn recently that Mr. Ashworth-Lord has plans for a smaller companies fund in the pipeline as well as the previously announced Global Buffetology fund. My approach is to directly copy some of the investments selected by these managers as well as investing directly in their funds in order to get exposure to their foreign companies (excluding US) without the high currency conversion & witholding tax costs which I would incur as a private investor. This is in addition to using their ideas to invest directly in smaller companies like you do. This seems to work well. I use Small Cap Report to identify interesting companies and it is also very useful to see the perspectives of successful investors who use methods which are substantially different to mine.
Thank you for the link Si and interesting reading.
He asks a very important question:
“When will there be a vaccine (I suspect that question should be “Will there ever be an effective vaccine?”)
I think that there is a strong possibility that there will not be or not in time to matter. I think that it is likely that we will just live with this (like Africa lives with malaria 500k deaths in 2015).
And a statement which I think is also important to keep sight of:
This ignores the fact that what came before the crisis may not have been normal.”
But there are anti-malarials and treatments for malaria but it probably comes down to health care and money. Malarial deaths have almost disappeared in some Asian countries in the last 5 years, see Cambodia.
I would agree with purpleski's comment that there is a strong possibility that there will be no effective vaccine against SARS-CoV-2 within any of the widely suggested timescales. However, if I could inject a note of hope, it is worth reading about the work being done by Vaccitech (Oxford University spin-off) with international collaborators. This is arguably the front-runner vaccine. Most importantly, it is using the same type of approach which generated proven immune reponses against the coronavirus which causes MERS so the researchers already have experience with a coronavirus vaccine. Also, this SARS-CoV-2 potential vaccine has already proven to be immunogenic in monkeys. About now the researchers expect to start injecting just over 1000 healthy volunteers in the UK, with first read-outs in mid-June. Manufacturing arrangements are already in place, allegedly to produce a million doses by September if the vaccine is successful (that is a big if). It has been announced the Oxford BioMedica will be helping with manufacturing and this morning I notice that an agreement with AstraZeneca has been signed to manufacture and distribute the vaccine. This will be done on a non-proft basis (as I suggested might happen in an earlier post). I also notice that on the Vaccitech web site (partnerships page), the logo of Liontrust Asset Management appears. This arises from an earlier private equity investment in Vaccitech by Neptune Ventures which was subsequently acquired by Liontrust when it aquired the rest of Neptune but I haven't a clue how much this stake may now be worth. This vaccine is likely to offer the best chance of an early end to all the lockdown measures, albeit at quite long odds, so I think we all need to hope that it works!
First quarter results are on the website, don't know why they haven't made it to stocko yet:
https://www.shell.com/investor...
"
Chair of the Board of Royal Dutch Shell Chad Holliday commented: “Shareholder returns are a fundamental part of Shell’s financial framework. However, given the risk of a prolonged period of economic uncertainty, weaker commodity prices, higher volatility and uncertain demand outlook, the Board believes that maintaining the current level of shareholder distributions is not prudent. Following the announcement not to continue with the next tranche of the share buyback programme, the Board has also decided to reduce the first quarter 2020 dividend and reset to 16 US cents per share.
As conditions allow, the Board will continue to evaluate our capital allocation priorities between ongoing investment in our business, maintaining a strong balance sheet and increasing returns to shareholders which remains our ambition.”
"
what worries me about Shell is the huge debt. Far greater than their competitors . Obviously when the oil price recovers so will their shares but who knows how long that will be ? This for me is a stock to avoid .
The results today from Up Global Sourcing Holdings (LON:UPGS) look reasonably good to me. There’s lots of detail and finances seem OK. I’d welcome others’ views.
Hi FREng, (Up Global Sourcing Holdings (LON:UPGS)) as you say the results seemed fine rather than good and the numbers to date "Total invoiced revenue for FY 20 as at Friday 24th April 2020 was £85.9 m (FY 19: £90.6 m) and there was an order book for the remainder of FY 20 of £18.1 m (FY 19: £27.0 m), although further deferrals and cancellations remain a risk." look quite encouraging.
However I think the share price is all about the immediate future and I am personally quite bearish about people's purchasing in this area as lockdown is eased. The upside could come if they buy some good brands or licences at depressed prices but for that we shall wait and see. I am a holder and a fan of the management but have become somewhat less positive about the short term outlook as it becomes more apparent that the current CoVid situation is likely to be exited slowly and painfully. I have a smallish holding which I will keep at these levels.
Peter Wyatt says: However I think the share price is all about the immediate future and I am personally quite bearish about people's purchasing in this area as lockdown is eased.
Personally I have a nasty feeling that we are seeing the real dead cat bonce now and a dive rather than a dip is on its way if lockdown is not lifted pretty sharply.
Cenkos Securities (LON:CNKS)
Interesting they lead their results today with "Since being admitted to trading on AIM in 2006, the Company has returned GBP114.1 million of cash to shareholders, equivalent to 176.3p per share". Compare to their current market cap of £27m ! Hopefully the new CEO will continue like this. I thought his first update opening with governance affairs was a bit of a sidestep. In my experience CEOs who overly focus on internal matters lack commercial vision.
The cash flow statement shows a big drain out from Trade and other Payables. Is this customer deposits? They state surplus capital increased slightly to GBP13.5m. Under Going Concern disclosure they state after modelling... "Company has sufficient liquidity to meet its liabilities for the next 12 months". Funny this is at the end, shouldn't it be near the front? Dividend will be paid.
I have been buying at the lows, on a long term view activity will eventually recover and their track record of rewarding patient shareholders will continue.
Cenkos Securities (LON:CNKS) results announcements are extremely formulaic. They always include the "the Company has returned..." phrase, along with the usual "Highlights" table. They tend to be extremely succinct. The one today is a veritable "War and Peace"!
https://www.investegate.co.uk/cenkos-securities/rns/final-results/201803230700046829I/
https://www.investegate.co.uk/cenkos-securities/rns/annual-results-for-the-year-ended-31-december-2018/201903260700119521T/
I presume they have a template, and cut and paste. I like it!
So they do! Perhaps less is more in this case. More signs this is a patient capital stock rather than a story.
Re Cenkos Securities (LON:CNKS), I used to work with Jimmy Durkin (many moons ago). Unless he has changed his spots in the interim, one thing he does not lack is "Commercial Vision"! I own.
Cenkos Securities (LON:CNKS)
""Since being admitted to trading on AIM in 2006, the Company has returned GBP114.1 million of cash to shareholders, equivalent to 176.3p per share".
I'm slightly too lazy to look up the floatation price, but the chart shows the share price starting off at about 200p. So the shares have lost 151p per share, offset by 176.3p per share paid back to shareholders.
The "NEW" CEO was previously CEO from 2011 to 2017.
Reading between the lines, rather surprised that £INL cannot afford build materials and subcontractors without this placing. Cash sounds very tight as per
"The net proceeds of the Capital Raising will be used:"
...
"- where the Directors consider it appropriate, to enable the Company to structure payments to its sub-contractors and supply chain so as to facilitate their return to site and/or the provision of essential materials at the earliest opportunity"
Good Morning
Thanks for your all your analysis.Can you give your view on Lenergizer.
sady - what company is that? Do you mean iEnergizer (LON:IBPO) in which case comments here are mainly on companies with announcements and that one hasn't made one since November!
My morning smallcap tweet: No no for NANO as it pulls down For Sale sign.
Inland Homes (LON:INL) Water Intelligence (LON:WATR) Appreciate (LON:APP) International Personal Finance (LON:IPF) Batm Advanced Communications (LON:BVC) Fireangel Safety Technology (LON:FA.) SIG (LON:SHI) Getech (LON:GTC) Cenkos Securities (LON:CNKS) Live (LON:LVCG) Nanoco (LON:NANO)
Inland Homes (INL) H1(March) trading. Net debt £150.3m as a result of abortive land disposals (prev RNS). Agreed sale of 113 apartments for a gross value of £22.5m.
Water Intelligence (WATR) Q1 comfortably in-line with expectations.
Appreciate Group (APP) guides FY(March) broadly in line with expectations with rev £118m and adj pretax £11.5m. Has liquidity for at least until March 2021, covering a range of financial scenarios. Outlook - demand in Corporate and Other Consumer areas down 70%. Order book for our Christmas Savings down 10%. Int rate cut means int income hit of £1.5m annualised.
International Personal Finance (IPF) Q1 credit issued contracted by 15%. Group collections in Q1 at 95% of budget; 87% in March and 76% (estimate) in April. £217m of cash and headroom on debt facilities.
BATM Advanced Communications (BVC) repeats its recent covid test announcements. Networking & Cyber division: some customers temporarily postponing certain projects and some activities hampered by lockdown. No FY financial guidance.
FireAngel SafetyTech (FA.) Q1 revenue and gross profit slightly below budget, partly due to covid. Expects most significant effects of covid to be in Q2. The contract signing with a local authority for a large connected rollout is delayed. Withdraws guidance.
SIG (SHI) commenced re-opening selected sites across its Distribution and Roofing businesses. £142m cash at hand.
Getech Group (GTC) expects 2020 to be very challenging but no negative revisions to orderbook so far. Q1 2020 rev, forward sales and profitability all ahead YoY.
Cenkos Securities (CNKS) FY(Dec) rev 48%, pretax £0.1m (£3.2m). 1p final div. Has started the year well.
Live Company Group (LVCG) £250k covid loan. Half of staff now furloughed. Will issue shares to comp for lost pay.
Nanoco Group (NANO) H1. Cost cuts mean cash will last to Q2 2021, subject to new commercial agreements being completed. Ends formal sale process. I'm short.
I am a Diagnostic Radiologist by trade. Nanoco was a share I researched at the time I made my first serious killing with ARM. It claims to be a spinoff from Manchester University. Arguably all it was touting at the time was jam tomorrow "contracts being negotiated" etc etc.
I remain unconvinced the have a viable product
Pebble Beach have released some positive results this morning.
Headlines
· Key financial metrics all ahead of the previous year
· Gross margin improved to 74% (2018: 73%)
· Adjusted* EBITDA improved materially to £3.8 million (2018: £2.5 million)
· Net cash inflow from operating activities improved to £2.0 million (2018: £1.7 million)
· Extension to the bank credit facility until 30 November 2021, providing a stable capital base
· Net debt reduced from £9.4 million to £8.4 million during the year
Regarding Pebble Beach Systems (LON:PEB) yes, very positive indeed. Pebble Beach is all that remains from the implosion of the former Vislink, which came very close to administration. The group holding company took on the name of the remaining subsidiary. However good it was, it had to bear the inherited debt. Two years ago Stocko showed MCap £4.05m EV £15.1m so the best part of today's figures is that the debt continues to come under control.
Morning Paul,
Don't think you've reported on Harworth (LON:HWG) before, but given your interest (and mine !) in housebuilders and recovery in that sector would be interested in your views on today's RNS. Reads well to me, especially as rental incomes seem to be covering overheads and interest. I have bought two tranches during the current market turbulence, and may double up today as I believe that the North (God's own country) and Midlands will benefit from the impending kick-start of the economy and "levelling up" plans. Also doubled up yesterday on Redrow (LON:RDW) who are a bit more north/midlands focussed as a builder. Am hoping these two complement each other well. Appreciate any thoughts. Cheers.
Good morning. Hoping that you might have time to cast your eye over Harworth (LON:HWG) today...Stay safe, and thanks for the work you do.