Small Cap Value Report (Thu 30 June 2022) - UBG, WYN, HTG, MSI, CAR

Good morning from Paul & Graham! Today's report is now finished.
Agenda -
Paul's Section:
Unbound (LON:UBG) (I hold) (£11m) - this is the second "in line with expectations" trading update since Unbound became a separately listed company (using the former Electra PE listing). Change of NOMAD looks positive. Marketplace strategy for third party brands is launching imminently. After a lamentable start in terms of share price since listing, I now see probably more upside than downside, so am happy to stick with it. Sorry this share has been such a lousy idea so far, but it has potential I think.
Hunting (LON:HTG) - a trading update which sounds positive, but has caused an 18% share price fall. The problem seems to be that some broker forecasts (which we can't access) were too high. That doesn't come across at all in the positive-sounding commentary from the company, which seems a bit misleading. It seems a lot of company for the market cap, currently trading just above breakeven, but with good sector tailwinds meaning profit is set to increase. Looks interesting, for sector experts to check out maybe?
Carclo (LON:CAR) - results for FY 3/2022 look superficially good at the headlines, but digging into the detail shows that liabilities to the pension scheme, bank debt, and heavy capex, mean shareholders are very unlikely to see any income. The equity looks worthless to me, nothing more than an option on a big turnaround.
Graham's Section:
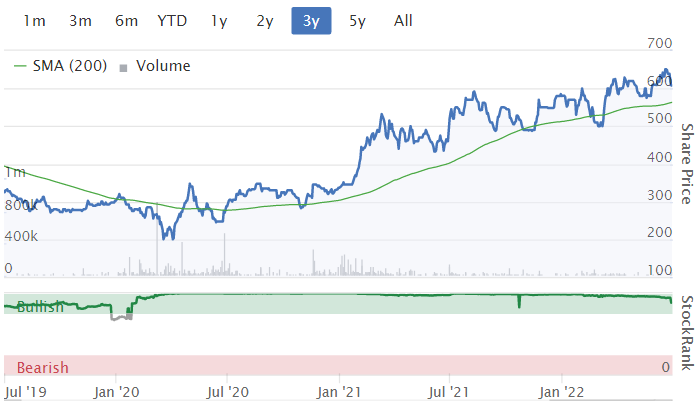
Wynnstay (LON:WYN) (124m) - this agricultural supplier confirms that it had an excellent H1. Revenues soared due to inflation, and the company made exceptional profits from selling its fertiliser stock, where the price had skyrocketed. Profits are expected to normalise in H2 and next year. This stock is a dividend hero where risk management has enabled it to trade profitably, nearly every year. While the valuation is increased, I would suggest that a multiple of c. 13x is not overly expensive for someone who wishes to build a long-term position.
MS International (LON:MSI) (£49m) - This company pays its directors very well, but external shareholders have also been rewarded handsomely as the share price is back near its all-time high, and a long stream of dividends have been paid out by this cash-rich company. The underlying businesses are involved in a range of heavy activities including gun cannons for ships, forgings and petrol station construction. MSI’s successful long-term track record speaks for itself and its lack of interest in investor relations is endearing.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Unbound (LON:UBG) (I hold)
29p (before market opens)
Market cap £11m
Trading Update & Change of NOMAD
This listing was previously Electra Private Equity, but was recycled to become Unbound Group from 1 Feb 2022, containing the last remaining investment of Electra, namely Hotter Shoes - comfy shoes for older women. It restructured in the pandemic, closing most of the stores, and is instead focusing online, and has a growth strategy to broaden its product range into other complementary products & services focused on affluent pensioners - arguably a big & underserved market.
There’s been hardly any interest in the shares so far, because the company and its advisers have largely ignored private investors, who are the market for the shares of an £11m market cap company - who else is going to buy the shares owned by Instis that don't want to own something this tiny? Although I did watch a webinar, which didn’t go down too well - too much corporate speak and trendy buzzwords, and not enough substance, in my opinion.
Still, it’s early days, and new companies that list need to be allowed time to find their feet. It’s a marathon, not a sprint, after all.
Its trading update on 12 May 2022 sounded encouraging, but nobody seems to be interested, with the share price continuing to be weak.
Trading Update today - this sounds OK, but no indication of what market expectations are, which is not helpful, particularly for a newly listed company, with very little research out there, and investors unfamiliar with it -
Following the Q1 trading update issued on 22 May 2022, the Company confirms that Hotter continues to trade in line with the Board's expectations for the year ending 5 February 2023.
Valuation - there’s a commissioned research note from Edison dated 16 May 2022, which pencils in these estimates for the current year FY 1/2023:
Revenue £59.5m
Adj PBT £2.0m
Adj EPS 3.8p (PER of 7.6, if achieved)
Divis: nil
So it’s a significant business, and profitable, with Hotter Shoes being a very well-known brand with the over 55s. I've mystery shopped it, and the shoes are nice enough, and quite comfy. Although mens' shoes are only a small proportion of sales, the main market is older ladies.
The trouble is, we haven’t seen any “clean” numbers yet. The last Annual Report shows all the figures from the previous investment business, Electra PE, so it’s difficult at this stage to see how Unbound will look as a standalone business. Maybe that's an opportunity at a market cap of just £11m? Once more investors are familiar with the story, then it could re-rate (once markets generally have found a base), possibly?
The Edison forecast shows a rather weak balance sheet, with NAV of £1.4m at 1/2023, and that is negative NTAV once £4.6m intangible assets are eliminated, NTAV: £(3.2)m. I'm worried that it might have been floated with too much debt, so that needs clarification.
Platform Launch - I’m a bit confused by this, as it doesn’t clearly spell out what this platform actually is? Is it a website? I think so, it sounds like a marketplace type website, which will host other brands, as well as Hotter Shoes.
Starting from 28th July 2022 through to October 2022, the Group will onboard 14 partner brands which will be sold on its new platform. These will be followed in due course by expansion into other areas including wellness and its own Unbound Group brands.
The Group is delighted to announce the following 14 brands, across apparel and specialist footwear categories:
· Apparel
- Rohan, Asquith of London, Boody, Noa Noa, Part Two, Kaffe, Soaked in Luxury, Cream, and Lakeland Leather
· Footwear
- Birkenstock, Muck Boots, Geox, Sketchers and Hush Puppies
It is therefore expected that the introduction of these brands to Unbound Group will benefit from greater engagement and an uplift in cross and up-sell opportunities.
Garden Centres - concessions (stores within a store) is called a “key channel as a low cost and flexible retail format”, with 2 more having been opened.
New NOMAD - out go Stifel (NOMAD) and HSBC (joint broker), who are completely inappropriate for a micro cap, and have been useless judging from the share price performance (and probably expensive too).
In comes Singer, as the new sole broker/NOMAD. Hopefully Singers will get some decent research up on Research Tree, and promote the shares to their clients, to clear any overhang.
The company also needs to get the word out, by appearing regularly on investor platforms such as Mello, PIWorld, InvestorMeetCompany, etc, explaining what they do (preferably without a lot of trendy buzzwords - plain English is so much better, and more credible), and running through the numbers.
My opinion - I’m sorry this has been such a lousy share idea so far. The jewel in the Electra crown was always TGI Fridays, but that’s been a dog too, with a consumer downturn smashing the whole hospitality sector. The demerger was completely botched, in my opinion - because the brokers failed to line up buyers for the shares in enough number to mop up the Instis who wanted/needed to sell. Anyway that's history now, it's the future that matters.
I saw Unbound as an interesting little business, and still do. Hotter Shoes is a strong brand name (ask some pensioners, they all know it!) who value the comfiness of its shoes, and the specialist fits & sizes, so there is a point of difference, which enable it to generate high gross margins.
The shoe components are made in China, then boxed up flat, and shipped over to be assembled in the UK, allowing it to proudly wear the Made In Britain flag, which is a nice selling point I reckon. This is also efficient for freight, as the parts are compact, as opposed to competitors importing finished shoes, where imports are bulky, with each pair of shoes being mainly “a box of air” to quote previous management at Electra.
Unbound now has two in line with expectations trading updates under its belt, and with the share price this bombed out, I reckon we’re probably over the worst now.
Valuation looks very low, and there could be decent upside from here. Hence I’m tempted to average down - because the very weak share price looks down to market sentiment, not the fundamentals.
At this stage, I’m not convinced by the multi-brand strategy, and want to see some results from that before adding anything into the valuation. Although it’s free upside, if it works. The multi-brand strategy has been set up to involve very little investment from Unbound, so risk:reward looks OK.
Overall - I see more upside than downside, if we’re patient.
At this stage, I would be sceptical of the StockRank, because we've not yet had clean numbers through for Unbound, hence the computers are using some of the defunct numbers relating to Electra, as it was the same listing.
EDIT: I've got a Q&A booked with the company this afternoon, so will update this article below with responses to some queries which have arisen in the reader comments, and from me. Watch this space!
Sorry, I was too tired to type up my notes, will do that tomorrow. But in a nutshell, I had a good chat with the company, and I was correct in my comments below. The new ventures are all drop-shipping, with no purchases of inventories, and limited marketing spend. End of Edit.
.
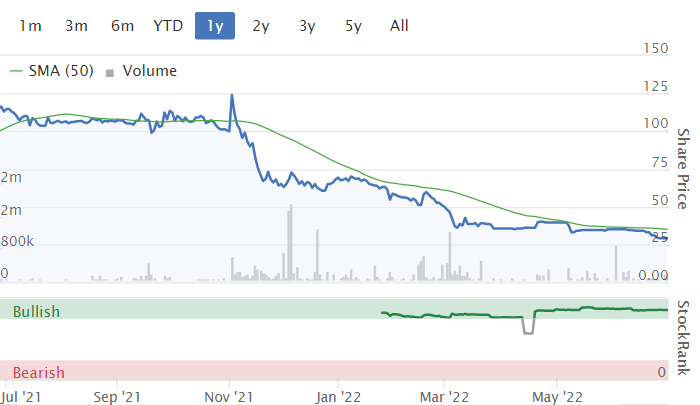
.
Hunting (LON:HTG)
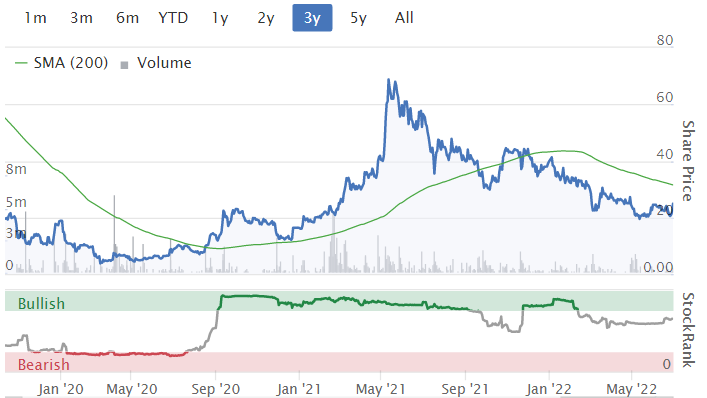
224p (down 18% at 10:18)
Market cap £370m
Trading Update (profit warning)
Hunting PLC (LSE:HTG), the international energy services group, today issues a pre-close trading update, ahead of its Half Year Results to be issued on Thursday 25 August 2022.
H1 is the 6 months ending 30 June 2022, within FY 12/2022.
This is perplexing to me, as the trading update seems to read positively, yet the share price is down 18%. Clearly I’ve missed something!
Arden helpfully update us today, also thinking the update is positive, and upgrading its forecasts. Although Arden notes that its $46.3m EBITDA forecast for FY 12/2022 is well below broker consensus of $60m, so it sounds as if other brokers might be dialling down their forecasts today. Obviously as we’re seen as pond life by many people in the city, we don’t have access to other broker notes.
Another problem seems to be that, as a capital-intensive business, Hunting has big depreciation charges. So $46.3m EBITDA forecast only turns into $6.8m PBT - barely above breakeven for revenues of $614m in FY 12/2022.
Lots of things look good for this company -
- Strong balance sheet, with net cash,
- Good order book,
- An improving trend of profitability.
Macro factors look to be moving in Hunting’s favour for now, especially an energy crisis where the price of oil has shot up and energy security is now the biggest issue facing Govts like Germany, which foolishly became dependent on energy supplies from a despotic, kleptocratic, corrupt, evil regime in Russia.
Fossil fuels look to be necessary for decades to come, as renewables take time to implement. Hence that could be good for oil services providers like Hunting?
My opinion - I think this share is for sector experts. Hunting could be entering interesting value territory, if you think the higher oil price is likely to stick, which would logically stimulate more drilling from producers, needing more services from Hunting.
I don’t have enough knowledge to determine whether today’s sell-off might be a buying opportunity or not, but it looks a lot of company for the money, and is benefiting from positive macro sector trends. Could be worth a closer look?
Divis long-term have been impressive, although patchy of late, as with many companies -
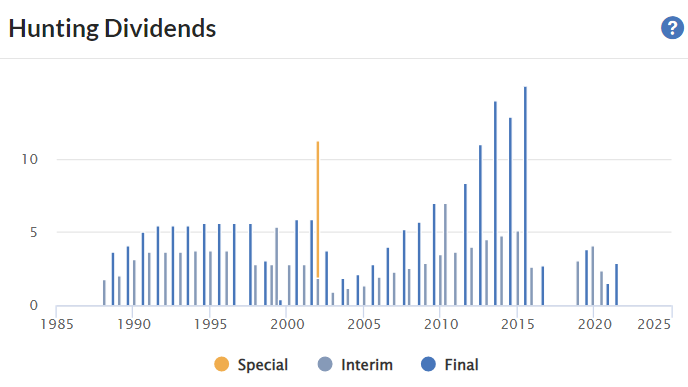
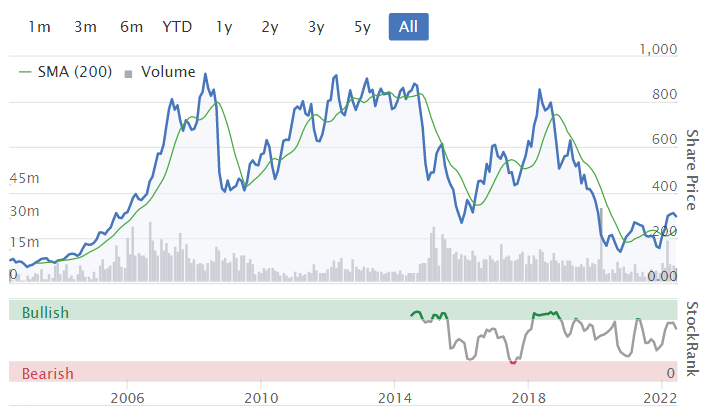
It's been volatile in the past, as I would expect for a company where profits are geared to the oil price -
.
Carclo (LON:CAR)
25p (up c.13% at 11:51)
Market cap £18m
This share looks superficially cheap, but as you dig into the numbers, it quickly becomes clear that it’s not cheap at all.
This table looks good for FY 3/2022 vs FY 3/2021 -

.
Trouble is, half the operating profit disappears in finance charges of £3m.
So adj PBT is only around £3m.
Here are the problems, and they’re big problems -
Pension deficit - Is shown on the balance sheet as £26.0m, down from £37.3m a year ago. Sounds not too bad? Think again! The actuarial deficit (which is the one that cash payments are calculated on) is estimated at £82.8m. Look at the scale & duration of the deficit recovery payments -
A schedule of contributions with the pension trustees is in place through to July 2023; beyond this a schedule of contributions for £3.5 million annually is in place until 31 October 2040.
Remember that deficit recovery payments do not go through the P&L. So this is a cash outflow that uses up more than all the annual profit.
Is Carclo going to be able to consistently generate £3.5m surplus cashflow every year, for the next 18 years, to fund this huge liability? I have my doubts. Investors must believe CAR can generate substantially higher profits & cashflows than it manages currently, to make the equity worth anything at all. And/or that the pension deficit melts away over time, which is possible in favourable conditions, with lots of variables to consider. As things stand, the business really only exists to service the pension scheme’s demands, and the next call on its cashflows after that would be bank debt reduction.
Hence little to no scope for meaningful divis, possibly ever.
Capital-intensive - note the balance sheet contains £47m of tangible fixed assets, and capex during FY 3/2022 was very high, at £9.7m (LY: £10.4m) - these figures taken from the commentary. Although the cashflow statement shows lower spend on capex, of £4.9m (LY: £7.3m), so that’s confusing.
Total fixed tangible assets are large at £47.0m. I’ve checked the last (FY 3/2021) Annual Report, and interestingly £23.6m of land & buildings are held at cost. So a key question to ask is, what are these properties, and how much are they worth now? This could explain why the bank & pension scheme are happy to let the situation roll, because this could be significant asset-backing, which in a downside scenario could be sold to pay off the bank & better fund the pension scheme?
More information is needed here. If anyone speaks to the company, then do ask about the market value of freehold property, as that could greatly improve risk:reward, if it’s a big asset.
Going concern note says the group has enough liquidity headroom, but of course that relies on the banks & pension trustees continuing to play ball. The severe but plausible scenario looks quite mild to me, modelling only a 5% fall in sales, and 1% fall in gross margin. In a recession, I would suggest the downside scenario could be worse than that, possibly?
Anyway, on the assumptions used, the going concern statement gets a tick in the box, which reassures somewhat.
Refinancing - is still pending. I’m amazed that the bank & pension scheme haven’t already required the company to raise more equity from shareholders. That’s still looking a high probability, so the dilution risk remains -
The Group, the bank and the pension scheme trustees are actively engaged in negotiations over the refinancing of the bank debt beyond the current expiry date of 31 July 2023 and over the updated schedule of contributions. The parties are committed to a plan to finalise these by 31 July 2022 and the Directors have an expectation that this will be achieved.
My opinion - as you can see, this is a complicated, special situation.
It’s not a bad business, and without any pension deficit or bank debt, it might be worth perhaps £40-50m market cap. The equity is actually worth £18m. So it’s a bargain surely? No, because the difference of £22-32m is actually far less than the net debt (£21.5m), and pension scheme (£26m accounting deficit, £83m actuarial deficit) combined.
Therefore I would argue the equity looks worthless as things stand now. It’s more an option, on the situation improving.
If trading improves, that would boost the enterprise value of the business, and its cash generation. It might then be able to reduce the bank debt, as well as servicing the pension deficit recovery payments of c.£3.5m p.a. for the next 18 years.
Another angle on things, might be that the pension deficit could reduce considerably. Higher interest rates tend to reduce pension liabilities, but higher inflation must push up liabilities the other way, depending on what the scheme rules are for index-linking pensions paid out.
It’s complicated.
Investors who just simplistically look at the low PER, and imagine that’s all there is to it, are completely missing the point here, and likely to be disappointed if they think it’s an overlooked multibagger waiting to happen. It's cheap for a reason.
The reality is that there’s unlikely to be any cashflow heading to shareholders any time soon, if ever, because it’s all needed to fund pension deficit recovery payments, reduce bank debt, and fund capex. Hence a thumbs down from me, as a serious investment.
Graham’s Section:
Wynnstay (LON:WYN)
- Share price: 608p (pre-market)
- Market cap: £124m
This agricultural supplier released interim on Tuesday. Readers have been mentioning it in the comments (thanks as always for the suggestions!), so I thought I’d circle back and have a look.
This company helps us to see where food inflation is coming from, because farmers will ultimately say that the prices they pay (to companies like Wynnstay) have gone up, too.
The company has two major divisions: agriculture and merchanting.
Let’s see what has happened at Wynnstay for H1 (six months to April 2022):
· Revenue +34% to £335.66m.
Wynnstay tells us how much of the revenue increase was driven by inflation, and it is well over 90%.
Some of the revenue increase also came from an acquisition which completed in March 2022. This acquisition brought a poultry supplier into the group.
· Pre-tax profit +78% to £9.56m.
· Net debt £7.6m after the acquisition (£9.5m cash paid upfront).
· Modest increase in dividend.
It’s crucial to know that a portion of the H1 profits can’t be repeated, as Jack wrote previously.
Fertiliser prices rocketed due to the shortage of natural gas, which meant that Wynnstay’s existing fertiliser stock became far more valuable. This helped profits at the agriculture division to almost treble.
At the smaller merchanting division, revenue was up by 5%, and adjusted operating profit up 26%. This is a more realistic and sustainable level of growth!
Outlook – “trading conditions remain positive – underpinned by firm farmgate prices”.
The exceptional gains are not expected to repeat, but the company says it is “well-placed to achieve growth prospects”, and continues to hunt for acquisitions.
Analysis
Wynnstay talks about strong sector sentiment: farmers are paying a lot more for fuel and energy, but are also benefiting from large price increases for beef, lamb and grain, with milk and egg prices also rising. There doesn’t appear to be any lack of confidence on that front.
I get the impression that Wynnstay is very focused on risk management, and is not interested in speculating on which way commodity prices will go.
It talked previously about having an “absolute unit margin model”. This means striving to collect a fixed margin on product sales to customers, regardless of the direction the product price has moved.
For example, Wynnstay’s grain trading division uses forward contracts to hedge itself against falls in the value of its grain stock. That resulted in “very significant margin calls” in H1. If it was merely betting on grain prices increasing, it would not have to bother with any of that!
The exceptional gain from fertiliser stock was clearly unhedged, and maybe that’s one product where the company will not be hedging (it would have to get involved with natural gas contracts, which may not be worth the effort).
My view
I’ve never written about this company before, because I’ve tended to avoid anything to do with agriculture – on the basis that I can’t predict the prices of most commodities!
Fortunately, I get the impression that Wynnstay is not attempting to predict commodity prices, either. When I comb through its financial history, I find a very long history of profitable trading, which suggests real expertise in risk management.
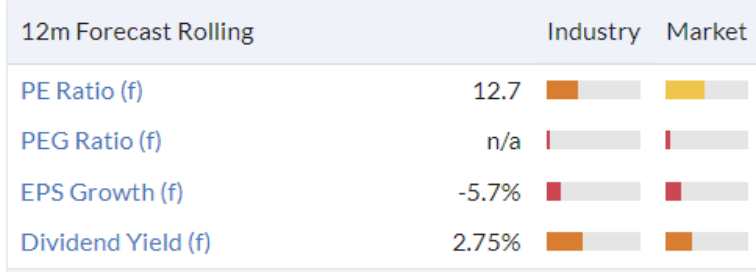
Analysts are forecasting adjusted EPS of 45.5p in FY October 2023 (a more “normal” year of profits than the current financial year). This gives an adjusted PE ratio of around 13x, the same results as Stockopedia’s calculation provides:
The stock is a dividend hero, with dividends being paid out during Covid and a dividend stream stretching back over 15 years.
When I spot a dividend hero on AIM, I always think that I must have found something special. This is the junior market after all, containing some of the most speculative and high-risk companies. But then occasionally you spot a company which has been faithfully sending its shareholders cheques, year in and year out, like a boring big-cap does!
The balance sheet does now have some RCF debt, and there is an element of trust involved in the company’s ability to manage working capital. Management report that there are now “significantly higher working capital requirements”, as a result of the inflation that has occurred.
A quick check of the balance sheet confirms that working capital needs are indeed very significant. For example, the company has over £100m in receivables. That’s not far off its market cap, and nearly a third of sales!
But financial debt is low, and tangible net assets are significant (c. £90m). Overall, the big picture view of the balance sheet is good. Hopefully, the dividends will continue to roll into shareholders’ accounts.
I’m inclined to have a positive view of this stock. It’s not cheap, but if I really liked it, I wouldn’t worry too much about the earnings multiple. The company will hopefully still be thriving in five or ten years, and paying a little bit more for it now would make a huge difference to returns.
Hopefully the company can bring us good news later this year, and tell us that food inflation has cooled down. But somehow I doubt that it will!
.
MS International (LON:MSI)
· Share price: 300p
· Market cap: £49m
The last time this was covered in the SCVR was by me, in 2018! Thank you again to readers for mentioning it in the comments and reminding us to cover it.
After a long track record of profitability, MSI did suffer a blip, in 2020, but has come roaring back and its shares are back near their all-time highs.
One of the first things you notice about this company is its barebones investor relations website. Despite being a listed company with a value of nearly £50m, it hasn’t wasted any money on web design. In my book, that’s a good thing!
Some people are turned off by a company that puts zero money into its investor relations efforts. But when a company acts this way, that’s often because it doesn’t need to raise funds and doesn’t care very much about its stock price. These are both indicators of a good investment!
Excluding the blip in 2020, MSI has been consistently profitable for twenty years. Dividends have been paid every year since 1993. And the number of shares outstanding has only fallen over time.
This history proves that it’s not a company that has needed to get the begging bowl out to investors. So why would it waste money on a flashy website? It doesn’t need to sell a story.
What it does - MSI designs, manufactures, and provides related services for heavy equipment in defence, fork-arms for forklift trucks, and petrol stations.
The stock might not ever find itself held by “ethical” portfolios, as its products include a range of gun systems.
Results - FY April 2022 was a brilliant year for the company. Revenues increase 21% to £74.5m, and pre-tax profits improve to £5.97m (from £1.59m).
This is not the best ever result for the company, but you have to scroll all the way back to 2012 to find a better bottom line.
Balance sheet equity improves to £38.6m, with zero financial debt and cash rises £18.1m.
For a review of divisional performance, I’m happy to point you to this comment from a reader (illiswilgig -Mark) on Wednesday.
In summary, the key points are:
· Defence. Working towards a major contract with the US Navy. “All trials are going to plan and positive progress is being made.” A new UK manufacturing facility is in the final stage of completion, and a new resource in the US is also being established, “to support our perceived growing defence opportunities in the United States”.
· Forgings. This Doncaster-based business has won many customers “that had previously procured product from China”.
· Petrol station superstructures. This construction business exceeded revenue forecasts, though was disrupted by material shortages and price inflation had a big impact.
Outlook summary:
We believe that we have placed each of our businesses in a strong and exciting position within the markets which we serve. Close monitoring of performance and further support in the development of new products and services will, no doubt, bring further rewards.
My view
This resembles a private company in the short annual results statement, the absence of investor relations efforts, and the heavy insider ownership.
Executive Chairman Michael Bell owns 17.5%, Ms. Adrienne Bell owns 13.6%, Finance Director Michael O’Connell owns 9.2%, and a former director own 10.6%.
Total director remuneration last year was c. £1.6m, about the same size as the pre-tax profit for last year and more than the amount paid out in dividends.
But this year, given the improved performance, there should be a much more favourable balance of profits vs. director pay.
Overall, I retain a positive view on MSI. It has a StockRank of 90, as the Stockopedia computers also find plenty to like:

The quality is a little low for my tastes, and predicting contract wins is difficult, to say the least. I wouldn’t bet the house on it, but I’d consider it as part of an AIM dividend portfolio:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
I always worry about a 'platform' so I checked out the board. I don't see anyone with a digital background or even an idea on what a platform might bring them, so it seems like the kind of idea thrown around in the board room 'we need to be tech enabled' I am skeptical £LON:UBG
I agree it is just ludicrous to they can create a platform at low cost to compete with the real hot brains and tech .
The owner of gymshark was asked if he feared the likes of Adidas or Nike coming after them, he said not a chance but he feared the next 15 year in a bedroom.
Hmmm. your sweeping statements yesterday turned out to be completely wrong, planetx. See tomorrow's report.
Maybe do some research in future, before publishing strident & factually wrong opinions?
Few strange happenings at National World (NWOR) my biggest, my most confident and my most ever declining underperforming investment .
Yesterday Non Exec resigns at end September and is thanked.
Today COO resigns and is not thanked.
A good chunk changed of 500k shares hands yesterday at 19p wonder if that was the COO of market.
Then today an RNS saying in line presumably to steady the ship.
Still looks bargains of the decade to me with market cap now 39 million, 23 is cash in the bank and circa 8-9m profits putting it on an EV/EBIT in the 2 region.
Maybe David Montgomery shouted at them or something and they took umbridge.
Incredibly low volume on this but if its gonna make 9 million quid a year I cant see any reason to sell .
Chrysalis Investments (LON:CHRY) posted their interims today, albeit the NAV has been known about for a few months for 31/03 so investors were well aware of the writedowns in Klarna, as well as the falls in listed investments Wise (LON:WISE) , Revolution Beauty (LON:REVB) and THG (LON:THG) . Using the latest share prices for the listed investments the share price is now at a c50% discount to the NAV which looks highly anomalous but symptomatic of the battering all companies holding PE investments are taking, despite a significant increase in the valuation of The BrandTech Group and a restatement of Starling Bank's valuation from April's funding round. Although some of these companies remain unprofitable, most are with significant growth (for example with Starling, they now have half of the share of the SME banking market of Barclays) I continue to hold and starting to look to add more to average down.
Would also highlight that TMT Investments (LON:TMT) - more of a VC investor - is now approaching a 60% discount to NAV using the latest £BLZE share price, meaning that at the current share price you are pretty much buying TMT's investment in Bolt (biggest holding) only and getting all other investments and cash pile for free. I continue to hold here also and looking to add.
WithIn the venture space Molten Ventures (LON:GROW) is on a similar discount but a much more established track record and better looking portfolio. I know with Chrysalis Investments (LON:CHRY) there are also serious question marks about how they took an absolutely massive performance fee for unrealised gains on several investments which have since collapsesd in value - of course they haven't returned any of the performance fee. This doesn't feel right.
Paul has been warning for a while about companies with funding issues. Shield Therapeutics (LON:STX) is today an example of this.
Shield raised £30m in 2021 at 30p (itself 70% below previously recent levels) to fund a launch of the product (Accrufer) in the US, after it failed to attract a US licensing partner.
Now the money has nearly run out. Shield admits it has tried to raise another $30m in equity - but so far unsuccessfully. Today, it has raised $10m as a loan (convertible into shares at a 10% discount to a look-back share price)! Unsurprisingly the shares are down another 40% today to be well in single digit territory.
it’s a real shame this is struggling as by all accounts the product is great and really benefits people in need.
A 100% increase in prescriptions Q1 vs Q4 and a change in strategy to really focus on womens health will hopefully help sales along, although a lot of damage done from dilution and the loan facility.
I rarely post as I am not as knowledgeable as the rest of you guys/gals, but I read this page every day, most many times a day.
I do not use it to inform me what to buy, I use the screens for that, but I certainly do use it to alert to what not to buy, that to me is easily worth the annual subs alone.
With regards to performance to date, my SIPP is 20% down YTD (34% from its ATH) against my work pension which is 8% down YTD, but over the years I have comfortably beaten the work pension.
I am moving my SIPP into 60% high yield stocks ( Rio Tinto (LON:RIO) Sylvania Platinum (LON:SLP) Persimmon (LON:PSN) £POLR ) with about 40% in small caps. My ISA is totally split between £SMT down 17% and FUNDSMITH down 4%.
I am still ploughing money in every month - cost pound averaging, and watching it sink, but hopefully the sowing of seeds during this storm will pay dividends once the sun comes out again.
Hi
Has anyone any thoughts on what as happened with Supermarket Income REIT (LON:SUPR) today, above average volume but not huge, just wondering if there has been anything I missed that means I should exit stage left?
Cheers
Tommy
Supermarket Income REIT (LON:SUPR) there was a pretty bearish note from Peel Hunt which reduced target price to 115p.
Thank you, picked that up this evening as usual after everyone else!
Crystal Amber Fund (LON:CRS) RNS today holds out the prospect of 70p payment per share later this year, as part of the closing down programme. Latest monthly NAV was 154.4p, against an sp of 117.9p, and whilst there is execution risk in selling the large shareholdings it has in companies there does appear upside in some of them such as Equals, Allied Mind (currently undertaking a strategic review), De La Rue, Hurricane and the unlisted GI Dynamics.
Thanks for your commentary on MS International (LON:MSI) Graham, much appreciated and hopefully it will generate some debate. Now a large holding for me having bought in last year initially around 150p and added on the way up.
The US Navy follow-on contracts (awards expected to start in 2023) will be transformational but we are not over the line just yet. In the interim they have contracts to supply Ukraine with mounts/guns for their Mk VI patrol boats through to 2026 and the likes of the Philippine Navy are renewing their fleet so there are lots of opportunities and a favourable tail wind re: defence spending globally now.
The Group also has some valuable freehold assets (now held as a separate subsidiary) which they could potentially do a sale and leaseback on which would massively boost ROCE which is otherwise excellent and depressed by this asset backing.
For mgt to have significantly enlarged their Norwich defence facility and also now be be looking to manufacture in the US (Rock Hill) they must be confident of a favourable outcome from the US Navy so it’s exciting times for the Group alongside a forks business that’s doing very well (and could be sold off as forklift manufacturers look to bring fork manufacturing in-house) and growth from petrol station forecourts as the likes of MFG and EG etc invest heavily into the sector to broaden forecourt offerings (groceries etc) as well as EV charging.
I’m quietly confident the 2012 record year will soon be broken!
Thank you for the informed comment on £MSI! Much appreciated. Graham
The existing Unbound (LON:UBG) website is very plain. I suppose I'm in their target demographic and I've never heard of them or their brand.
Targetting older people is certainly a niche but older people are creatures of habit and have fierce brand loyalty so I wonder how exactly they are going to build up a customer base. The Hotter brand isn't bargain priced and I also wonder why not pay a very similar price for a well known brand like Clarks?
The move towards brand expansion demonstrates that their own brand isn't successful enough and that they are now taking on other multi brand online retailers and people will simply do comparison shopping.
The elephant in the room here is returns and cost of returns. I have no idea of the scale of returns in online fashion retailing but judging by the activity at my nearest post office I would guess it is high, perhaps as many as 1 in 3 items gets sent back?
Not for me
Unbound (LON:UBG) Yes, where's the thermal underwear, and the 'woolies' that older people really buy?
Re Unbound (LON:UBG), I'm responding to Sheeza specifically, but I'm also responding to the other several comments referred to above, and I look forward to Paul Scott's conclusions later when he has had a chance to chat with the management, especially on the specific figures of reach, repeat purchase etc.
In the meantime, I will add a few personal and anecdotal comments. My wife and I are both Hotter users, and I think she was when they were in shops. She is currently late 60s, I am late 70s. We both go for comfort as No 1 and Hotter are strong on that IOHOs. At the same time, my wife regards some of their ladies shoes to be stylish. We are both repeat buyers.
As for the expansion of brands on the site, I would have guessed that they will be aiming to use their reach to attract buyers of other brands, and some of the ones quoted are strong for us. Again, admittedly a personal example, my wife is wedded to Rohan as a brand. However, it is a fair point that you can buy these and others like Hush Puppies (made famous by veteran politician Kenneth Clarke!) can be bought on their websites or on comparison sites.
I doubt that they will be stock holders, leaving it to the other brands to deliver.
One thing is clear. the management need to tidy up their communications for investors, especially more facts and less wordy / more punchy in terms of statements re direction and means to get there. I look forward to getting them to Mello for example.
Their target market is women aged over 55. My wife used to frequent the Horsham shop and I went in to complain why there was nothing available for men. I think their brand is successful and it is that which has enabled them to attract and get quality brands on board.
I don't know you sex (and obviously no need to tell) but if you are an over 55 lady then I am genuinely surprised you’re not aware of them. If you're male then you probably wouldn’t have heard of them unless your missus dragged you in!
I do hold as a result of holding Electra shares, admittedly mainly because of Fridays.
Am a chap and 2 of you have proved my point I think. You were introduced to the brand via retail outlets. Now there is only a website and it is one amongst many websites so how are they going to build up a present and future customer base who will make repeat purchases? There is a mens section but it seems somewhat, ahem, pedestrian.
Unbound (LON:UBG): Selling shoes to older women online? Hmmm. Surely shoes are an item that people are more likely to want to try on before buying? And surely this demographic is particularly unlikely to want to adapt.
Belvoir price has pulled back into the late 220s.
Seems tempting .
Anyone got a positive or negative on this ?
Im holding some already, actually sold a batch a couple weeks ago in the 250s and wasn't intending to buy back, so should probably sit on my hand or do some weeding .
Must resist .
Go do the weeding
Dont buy belvoir .
Can't help on Belvoir but I do find it quite helpful to take a look at the Bitcoin chart, as a proxy for speculative froth, to remind myself that there is still plenty of scope for the bouncy castle to deflate further.
It is a shame that delisted/acquired company share price charts are quite hard to get hold of. It would be fascinating to overlay bitcoin on British Biotech and see if there is any parallel. I've given up looking for parchment with plots of tulip prices.
I've initially lost quite a bit of money on some of my best investments over the years - you just have to take the 5/10yr view and buy something every month on the way down. Leave picking your bottom to the monkeys, as they say!
Belvoir (LON:BLV)
Hi planetx
Biased Belvoir shareholder here.
Last year the company generated c£8.3m of underlying free cash.
This year there will be a few adjustments to that figure, such as the annualised impact of acquisitions, but overall I imagine the company will probably produce a similar amount of cash.
The current market cap is £87m, so that gives me an FCF yield of just under 10%.
---
Sales revenue will undoubtedly start falling at some point and I'm prudently assuming revenues here drop 50% in H2 vs H1.
But 60% of Belvoir's gross profit comes from lettings, which are resilient and still on the rise throughout most regions:
https://homelet.co.uk/homelet-...
I think management recently said that lettings rates were up 4.4% vs last year, so presumably lettings revenue is up even more than this when accounting for acquisitions.
I've read several reports of the re-mortgaging market taking off this year, so hopefully there's additional upside in the Financial Services segment that I haven't accounted for.
---
As for FY23, which is of course harder to predict, I imagine that management will do what they've always done, and make some tasty acquisitions to keep the gravy train rolling. They certainly have the resources to keep growing.
The share price is rubbish right now, but I've no plans to sell whilst that FCF yield is so high and there's such a strong and recurring underlying business.
Good luck with those weeds and whatever you decide to do with Belvoir (LON:BLV) .
Cheers
A
Wynnstay (LON:WYN) just a heads up, I'm with Hargreaves Landsdown and wanted to sell some of these yesterday and they could not give me a live quote, I had to do a fill or kill and wasn't impressed with the fill they gave me at minimal 600p. There was a live price if I wanted to buy, the order size was a little over £4K.
I bought £WYN in October, 2020 at £3.34. It's a nice boring share and it's just the sort of company I love to have in my portfolio, increased dividends keep rolling in twice a year.
Cheers Graham. Thank you for the Wynnstay (LON:WYN) write up. Hopefully the market turmoil will present a buying opportunity.
You're welcome Jonno! Good luck. G
Where have all the punters gone.
Perhaps I am being cynical but this board is like a ghost town in The Badlands of Dakota.
Surely everyone has not sold up in this brutal market?.
What I don’t get is why everyone is bubbly and excited and eager to share and communicate when the market is booming but when idea, thoughts and analysts are needed like now, it’s gone quiet. Come on guys your valuable input, ideas and thoughts are needed now more than ever.
If it gets any quieter, I will have to cancel my subscription.
Every forum on every web site is the same Tony and it has always been that way. The 'post index' is a sure sign of market sentiment. Right now, it's rock bottom.
Where have all the punters gone.
Hi Tonysaparito
Well, your last comment was in January?
It's always like this in bear markets. The main thing is that the quality of comments tends to be better as there's less noise about, fewer people telling everyone how well they're doing and generally confusing a rising tide with skill. A lack of traffic on bulletin boards is a useful rule of thumb that tells you it's time to be looking for bargains.
I'd also add that the quality of commentary is as high as it's ever been, which is a tribute to Paul, Jack and Graham. Nearly all small caps get hammered in bear markets due to lack of liquidity, but picking the survivors is the trick - hence this is when the SCVR will really earn its keep. Although the benefit will only be seen in a couple of years time, when markets have turned.
timarr
It's always like this in bear markets. The main thing is that the quality of comments tends to be better as there's less noise about, fewer people telling everyone how well they're doing and generally confusing a rising tide with skill. A lack of traffic on bulletin boards is a useful rule of thumb that tells you it's time to be looking for bargains.
Couldn't agree more. So why don't we all say how badly we're doing? On a Total Return basis I've been saved by the large cash balance I entered the year with but I'm still down 7%.
I realise some are scared of having cash because of inflation, but I'm happy to hold cash in my investment accounts because of the exact opposite: share price deflation! Bargains for those who can see further than the end of their nose are now abundant. The problem for me is, why buy UK small caps when collective investment vehicles are on large discounts to NAV? As an example Smithson Investment Trust (LON:SSON) is currently on a discount to NAV >14% and it contains some real high quality US and UK companies including: Halma (LON:HLMA) Diploma (LON:DPLM) & Spirax-Sarco Engineering (LON:SPX)
All the best, Si
Si, and I much enjoyed your (and Timarr's) postings over the years.
On returns and losses, I prefer to look at real, inflation discounted numbers. Therefore at the half way point in this year you should be reducing the performance of your cash balance by 5%, and adjusting your equity gains and losses similarly. However if your equity porformance is worse than the cash performance you are still better of, relatively, holding cash.
My equity performance has been awful, just for the record, down 19% in nominal terms, about 25% in real terms.
On investment trusts, the traditional discount to NAV is about 15%, the argument being that e some of investments they hold are not shares that individuals would choose to hold. A further reason for discounting is if liquidity in the shares is poor (e.g. Woodcock's holdings). However discounts nicely above 15% may be worth looking at. I saw one at 34% a few days ago but have forgotten what it was, so that's not very helpful information.
Good luck
Richard
On returns and losses, I prefer to look at real, inflation discounted numbers. Therefore at the half way point in this year you should be reducing the performance of your cash balance by 5%, and adjusting your equity gains and losses similarly. However if your equity porformance is worse than the cash performance you are still better of, relatively, holding cash.
Maybe I should, but tbh I totally ignore CPI and its effect on cash awaiting investment. IMO the most important risk for investment cash is that of capital loss, not inflationary risk. CPI may be the best measure we have but it does not represent the change in price of products and services I buy with my cash. We all have our own individual inflation rates at the end of the day and CPI is a very general measure that bears no relation to my own cost of living. I think we need to remember that.
For mental accounting purposes I separate cash in investment accounts (for making new investments) from cash on deposit in bank and savings accounts for living expenses etc. It's maybe not the right approach if you view all cash as equally fungible but the reality is most of my cash is in SIPP accounts, so not that fungible! By viewing cash for investment this way, I am trying remove the pressure to invest in equities at any cost just because of inflation, when currently the greatest risk as I see it, is one of capital loss. However, I have been deploying the cash gradually over the course of the year and will continue to do so. So far only 30 out of 69 trades I've made this year are in positive territory.
I know others will not see it this way, but investment cash can now buy a lot more than it could at the start of the year i.e. most shares are much lower rated and on higher forward earnings, cashflow and dividend yields.
All the best, Si
I have to agree with your strategy Si, and just to add, for me its the phycology of holding big losers in my portfolio, and the effect that has on my decision making for future buys.
I cut at - max 15% (often happily after the initial disappointment) and yes you end up in cash (less) but your capital is preserved, to redeploy at lower market prices, which for me is absolutely key.
YTD I'm 7% down and 53% cash, but this last month I have seen less stopping out against more buys, so perhaps small/mid caps have seen the worst of it. Certainly some I think have.
As you say there seem to be some real bargains on down days. I am opening small positions at bombed out prices and averaging up if the momentum gets going.
This is a very good point, I noted down in 2020 what I should do in the next bear market.
"Buy ITs at a large discount" The problem is timing.
Currently considering £MTU which pays a dividend of 4% nav so about 6% currently. Although I'm not sure if the dividends are covered?
Anyone have any thoughts on North Atlantic Smaller Companies Investment Trust (LON:NAS) , Oryx International Growth Fund (LON:OIG) ?
Would be interested if anyone else has other trusts they think are worth a look.
Simoan, I agree on the point regarding importance of balancing Investment Trusts vs individual stocks (unless you have a ton of time to spend on research - which i don't). It's been mentioned before, but it is really such a shame that Stockopedia does not currently provide quality data on investment trusts. I really like the SCVR and the community comments, but I am sorely tempted to move my subscription over to Sharepad in the next couple of months due to the lack of quality data on investment trusts.
My portfolio is broadly 60% investment trusts / S&P 500 etf and 40% individual stocks. I currently rely on the AIC website for investment trust info.
Simoan, I agree on the point regarding importance of balancing Investment Trusts vs individual stocks (unless you have a ton of time to spend on research - which i don't). It's been mentioned before, but it is really such a shame that Stockopedia does not currently provide quality data on investment trusts. I really like the SCVR and the community comments, but I am sorely tempted to move my subscription over to Sharepad in the next couple of months due to the lack of quality data on investment trusts.
Don't get me wrong, I do not generally invest in IT's. However, I do drip some money in when the market sells off and they reach a very wide discount. I currently hold only 3 IT's. Tbh there is so much freely available on trusts (the AIC website, company website with monthly newsletters etc.) that I don't really see what value Stockopedia could add in that respect. I certainly wouldn't fork out £300 a year for a subscription just to get data on them.
All the best, Si
Thanks timarr, very much appreciated, and I agree.
Actually, I've been amazed at the quality of reader comments here recently, and that the SCVR readership & daily thumbs ups are similar to in the bull market. So we're very much retaining most of our readership, and having some terrific debates here in the comments section too. I read all the comments, as mostly they're very good. It's less interesting when people pointlessly post that they bought or sold today, who cares?! That stuff is best kept on advfn, along with all the mud-slinging, which rarely infects the boards here (and half the time it's my fault for over-doing the vino!), hence why they're worth reading. Not any more, we have to be serious & focused in a bear market.
It's the hard legwork we do now, that will set the foundations for when markets turn - I don't know when of course. I've been through 3 bad bear markets before, and the small cap bargains that people give up on, often become 5-10 baggers in the next few years, as things recover.
I'm trying not to worry about my % down YTD - currently 36%, very painful, but instead move my mind forwards to what happens when things recover. I've got no need to withdraw any money from my portfolio, so the current market prices don't actually matter long term. What does matter, is how the company fundamentals are panning out, and I've been very careful to only put money in companies that I think can ride out a recession (which is only 2 quarters+), and then strongly recover. If only we knew with certainty which ones they were! But we are getting some good indications, and finding interesting companies - look at Shoe Zone (LON:SHOE) yesterday, for example. Also plenty of other shares where I think we can see a fairly obvious 2-3 bagger, if we look beyond the impending recession, which now looks inevitable.
Overall, there's a change in ownership happening, with speculators giving up, and value investors buying their shares when the price is right (sufficiently low). Then the whole thing eventually washes through, and speculators come back, and begin chasing prices up again.
At times like this, I'm all for the hardcore of us remaining, swapping ideas, discussing anything, and being mutually supportive. Bear markets are a fact of life, and give us all vital experience. It's just a pity that bull markets always make me complacent, and I've largely forgotten all the lessons I learned in the last bear market, once the next one starts, which is exactly what has happened again this year! Never mind, sh#t happens, and life if still good. My nephew just got engaged, and I'm focusing on health & fitness, so there's more to life than just what our portfolios are worth.
Keep your spirits up everyone, this bear market won't last forever.
Regards, Paul.
I certainly hope not - it's been an absolutely brutal year. As I didn't have the foresight or conviction to sell up early I've just switched off. History tells me that selling when chins are on the floor isn't a great trade, though right now that offers only minimal comfort.
I've gone through my portfolio and I have multiple companies paying decent dividends with good net cash and trading in some cases on 2 or 3 times earnings. I have growth stocks trading ahead of expectations on sub 10* too. Then I have some good resource companies that have actually made me some money (a rarity) and a few others I bought that I think have great long term value with no big requirements for capital raises that have just gone down 40% for whatever reason. But the reality is that investors aren't interested so I need to basically just sit and wait it out and trust (or maybe hope) that I have picked good long term businesses and not too much dross.
You are right that comments posted goes down significantly in bear markets. That includes me, mainly because it feels a bit like banging my head against a brick wall. Market doesn't care right now. Doesn't matter what I think - if the buyers are on strike then even positive news rarely lifts the boat off the floor. We await a rising tide I suppose.
I have no idea what turns this market around - it's pretty schizophrenic at the moment. It will wilt as investors fret about inflation demanding rate rises and then fret a few days later that central banks are raising rates that will hurt growth. I think core inflation numbers need to tip over before we see any change in market behaviour. Certainly doesn't feel as though we have equilibrium at the moment. I would contend that so far little seems to have been done to temper the supply side. Recent Oil and base metal commodity falls should help a bit though. Consumer demand is falling so I actually don't think that, in the UK at least, rate rises are the right tool. The US is a bit different in that respect as the economy there is running a bit hot but consumer sentiment has significantly soured recently which makes me wonder if less rate rises will be needed there too.
True pearls Paul I wouldn't beat yourself up to much I remember you saying you were in a dark place in 08/09 well fast forward to now and you are doing a job you love (most of the time), living by the sea and hopefully enjoying life.
You may be down for the year but most importantly this time around you have capital to be still in the game rather than having to rebuild from scratch and also regain trading confidence to execute big calls when needed.
Maybe with to self notes put down next time i buy a nice expensive motor go 50% to cash :).
I'm mainly here for the bulletin board these days as I've given up trading small caps and fish in investments trusts and FTSE 100 stocks but the quality of the board especially now is top notch with a sprinkling of outstanding posters.
I've also been through three bear markets and actually was well positioned in cash going into each of them but where I was sh-t was getting back into the markets and missing probably half the rise off the bottom each time.
We won't recognise the low this time around until possibly 3-6 months past when it happens so like one other poster mentioned i am averaging into positions in stages on big down days then if we get a rally and a position goes to break even I sell 50% of the stake rinse and repeat the process to try and bring my average starting position price down.
One big learn for me at times like these is to start accumulating what will hopefully be long term core positions but without betting the farm to quickly and equally being way to slow to accumulate as previously has happened
If the stock drops by more than 10% I sell half and then look to try and average back in lower down at some point this process will stop working and prices won't keep falling back after every mini rally and that should hopefully signal things have turned.
I wouldn't risk averaging down to much in stocks but with decent investment trusts like Smithson, Black Rock World Mining etc the risk is much less as its unlikely the whole portfolio will fall over.
Regards Andy
Timarr, I know youre good on technology stocks, do you think former popular stocks like Teladoc or SoFi have reached bargin prices or their day in the sun has gone. Nasdaq has been so hard hit surely theres a bounce due
Timarr, I know youre good on technology stocks, do you think former popular stocks like Teladoc or SoFi have reached bargin prices or their day in the sun has gone. Nasdaq has been so hard hit surely theres a bounce due
I think BnB would provide a more informed view than I can, especially on overseas technology stocks. But generally I'd observe that the scale of a fall tells us very little about future prospects. Over the years I've noticed investors will tend to buy into former stockmarket darlings when they've fallen a lot because they've fallen a lot. Sadly, any stock can always fall another 100%. The past is history, all that matters is whether a stock offers value now.
A lot of stocks that aren't making any money and need more money in order to find a way to profitability are facing a very uncertain future even if they're a fundamentally good business. It's going to get more expensive to borrow and the pools of private money that have been funding a lot of earning-less growth will become harder to access.
Also remember indexes are like Trigger's broom - 17 new heads and 14 new handles - things that do badly fall out of them and are replaced by things that will probably do better. Nasdaq will rebound, but not all of its current constituents will come with it.
Anyway, I'm 14% down YTD and pound cost averaging into a bunch of reasonably priced midcap stocks at the moment. Stocks generally provide decent protection against inflation as long as you avoid those that need lots of capital investment, where input costs are a continual headwind. Also I want to avoid total wipeouts, so stocks that don't make a profit and require continued investment are not on my horizon.
So, personally, I wouldn't be chasing former Nasdaq darlings but, as history tells us, some of the most successful stocks of the next twenty years will be among the fallers there. Sadly, I've no idea how to figure out which ones they'll be.
timarr
Timarr, I know youre good on technology stocks, do you think former popular stocks like Teladoc or SoFi have reached bargin prices or their day in the sun has gone. Nasdaq has been so hard hit surely theres a bounce due
With a hat tip to Timarr for the name check, I would say that the potential within unprofitable tech for a bounce is less important than their potential to be left behind by strong free cash flow generators while the market remains uncertain about the course of rates. There are so many beaten-up tech stocks, why pick the unprofitable ones that rely on liquidity for price support? The Nasdaq is full of great semiconductor stocks on very low PERs anticipating an inventory glut/demand drop. And you can buy pricey but moaty/growthy ServiceNow, Palo Alto Networks or Veeva at pandemic bottom prices.
Meanwhile, I’m meeting my bank’s IT analyst on Monday so will have more thoughts to add but I know already that he is hiding in lower-rated legacy enterprise software like SAP, systems integrators and cheap games developers like EA which offer a combination of value and dividend. That reflects an abundance of caution (conservative Swiss bank) but perhaps it’s best to wait until he turns more bullish.
Hi BnB
I'm going to throw in a brief comment on SAP if that's okay.
I've used their software at a couple of companies in the past. It had such a horrible interface and I was shocked by its popularity. I was recently told that it hasn't really changed much in the last 20 years.
Sadly this all shows how deeply embedded it is in the financial ecosystem of the corporate world.
Revenues continue to rise each year, net profits have risen even faster, and they've done well with their expansion into cloud-based services. They buy back shares and have a small dividend.
Cash generation seems to have been c7b EUR over each of the last 2 years vs a market cap 107b EUR/EV of 115b EUR. I imagine that cash generation might come down this year with SAP pulling out of Russia, but overall the valuation doesn't seem overly expensive for such a quality company.
I should add that I only hold a small amount here as one of those safe, hidden away holdings that I don't ever really plan to do any work on.
Cheers
A
I agree with everything you say about SAP. Truly horrible software but a cussedly resilient company. I too have a small stake in my GARP contingent.
Hi Timarr..Thanks. I read this section and those from Paul, Jack etc but whilst I know many are running for the exits , I , probably like you am just getting on with the business as normal. The reason why I have not been posting as I have and still am very busy in my others businesses, which are making money, unlike my Sipp. ISA or other investments are like sinking ships. However, whilst many will be fretting about this bear market, at present I know from dire experience over the years, that there is little we can do when Mr Market has lost his focus.. I am just sitting this market out, as I know no matter what I do, my input has little effect. Overall, my total investments are down over 30%, and I have a mix of Fundsmith, Sipps, SASS, and ISA investments.. I am not even remotely thinking of selling, as I did that in January,Feb, as I anticipated a cold wind was going to blow in from the East...Whilst I do not profess to be an expert, WHO IS?. I think we all have much worse to come and fear what worse will mean for some newer to-market investors. best to all on hear
Yes, Tony, I agree with Lord Gnome, it is nothing more than market sentiment - or to put it another way, people hurting badly. Ideas? Well, nothing's new in this game, but I have begun a list of companies that I would like to buy if the price drops low enough. Please do not ask me where that bottom is. However, I took a look at Serco this morning (I do not hold) and suggest you do. Could not believe the chart. Momentum has gone up every quarter this year. No doubt though, it will go down now that I have found it.
It is very quiet, but that always happens. I have noticed a difference at work, the young lads have stopped bragging about how much money they have made, so they have a give up. Having lived through several of these blips I am trying to hold my nerve. I won't be cancelling, I am still getting a good insight into companies I may or may not have on my watchlist. I personally things these are the times to take more notice. I am not expert though, and learning every day.
This is the curse of the private investor. When I used to run employee share plans for a large FTSE100 company, we found the same thing. When the share price had gone up, everyone watched it and the participation rate in the (voluntary)share plans was high; when it went down, people lost interest and participation rates fell. That's exactly what Warren Buffett was referring to in his comment about the need to drive emotions out of making investment decisions - easier said than done.
I look forward to Graham's view on Wynnstay (LON:WYN) a nice 'boring' company. The type I like to own, if it is available at the right price.
Unbound update today shows a company in my opinion heading in the wrong direction.
In simplified terms they are expanding their range by stocking 14 other brands. The issue is they have zero competitive advantage on these products and are competing against every other retailer these brands have.
This will suck up cash and slow down the correct strategy of building their own brands which is where they create actual value and leverage and engage their claimed customer base in their journey.
You rarely see a strong brand confident in its itself listing other brands (could you imagine Apple doing this albeit a bad example).
There is a couple of benefits of course, one being it potentially gets new people to the website who then may buy Hotter shoes (own brand) and they will tell you it’s great for google rankings and SEO .
My point is it’s definitely not decisive it’s a middling to poor wiffly waffly move that will just drag down margin , absorb cash and actually the stock won’t sell because there is no reason to buy from Hotter compared to the hundreds or so retailers selling the same .
We used to list a lot of products alongside our own and I had a ranking system along the following lines that provided a benchmark of how committed we were and how much focus / effort to give
AA - own brand items , top sellers - most important , never run out of stock , commit cash
A - own brand products - focus your efforts on brands you own as ultimately you are building long term value.
B - exclusive products - products you don’t own the brand but you had negotiated a national or European exclusivity deal on so you have competitive advantage on. Nice to have and if successfully you can spend time building your own version and move to an A.
C - Clearance / blowout - big one hit deals where you have huge margin , great for driving traffic to your website / stores as everyone loves a deal .
No long term value apart from increased traffic , one hit profit deal. Trading businesses can do this brand led businesses don’t really , always debatable whether this was worth it and no scale. Pure trading .
Important note though these are very very time consuming and difficult to process so margin need to be very very high and you will end up with a lot of bad stock.
D - non exclusive products that compliment A .
There are sone itens needed that are must haves for own brand products, eg with bikes we needed shimano pedals , No competitive advantage but you need to offer em otherwise your customers are forced to buy something for your product from a competitor, dont let em go there ! .
E - products that you are non exclusive on , have no competitive advantage , and sell alongside others. Pretty pointless selling these as you create nothing of value and make no money , you might build up some matket knowledge on what sells or open up other channels but never quite goes to plan and these itens sit in your stock file until you get rid at cost .
The key is to DEFINE THE MISSION
I have read Unbound / Hotter's mission and I just think they are confused, clutching at straws and honestly a bit clueless and it is summed up by this -
Their target market and customer base where they claim to have 4 million ! customers (30% of the UK) is the over 55s .
Explain please why they are now stocking Sketcher shoes ?
After you define the mission every decision your company makes can refer back to that and you just ask DOES IT ADD TO THE MISSION.
Honestly this is not HOTTER it needs to be renamed HOTTAIR .
Essentially I agree planetx with you about Unbound. I am not that impressed (I am a holder) with the plan, which seems a bit desperate. However I am onboard because of the valuation which remains out of spec. So the question for me is how much value will the Management team destroy. In my view one of their biggest advantages is they make their product at home (or at least that is my understanding), at a time when that is going to become important. I think they should have been looking to add a couple of products sourced/made by themselves which are targetted specifically at the +55 age group who have more money than other demographics. There is no rush here but at the same time they need to protect their brand and balance sheet.
"Their target market and customer base where they claim to have 4 million ! customers (30% of the UK) is the over 55s .
Explain please why they are now stocking Sketcher shoes ? "
Maybe they are smarter than you think. My Mother and Father are in their 70s. Their absolute favourite shoe brand (that they simply do not stop talking about how wonderful they are)? Sketchers. I kid you not.
BIACS
Indeed, Sketchers is right for their target age group. Has someone been buying Sketchers who really should be too young for them?
I am in the same age group and also love Sketchers
Sorry - have to add this - I have a pair of Sketchers because they do a wider fit, but oh how the family laughed when my mother turned up in the exactly the same pair.....
Are you sure they will "stock" these brands? - I assumed the model was to harvest the customer base not invest in other brands stock. Clearly very different implications for margins ... since you are sourcing customers for others and charging a rent ... and they service the customer from their own stock.
Re £UBG - In summary, they have a nice little current business (Hotter shoes) which does seem to have a franchise with older, 50+ women, based on comfort and fit - it sold over £100Mn, a few years ago, including all the now (thankfully) closed retail shops. That's why Electra paid so much for it at the time - £84Mn from memory.
I watched all the webinars and read all the public reports issued and think the CEO has done a good job in the last 3 years in re-structuring the business within a PE world. However, whether he has the skills to survive on his own is as yet unproven and that is my concern. For all its sins, PE provides rigorous financial analysis and a support team: managers can focus simply of growth. Now the CEO has to worry about funding and many more operational details.
Nevertheless, it seems a relatively close & easy diversification from that to sell related 3rd party brands to the same demographic - they claim >1mn emails addresses - and to make some extra cash from that. It's a model that is serving Next well.
Is it going to become the next Next? No. Can it double turnover in 3-5 years? Yes. Will it build a new genuine "platform" as opposed to a nice, effective website including 3rd party brands - No. It is guff to pretend it will.....and that hubris is a risk.
Personally, I think it will grow a bit but might eventually be taken over by someone else wanting to accelerate building a bigger Seniors brand/platform and doing some serious cross-selling. Perhaps Saga in 3 years time when Cruising is cruising again!
What they need now is to let the market understand its proposition and standalone value now and to build trust and understanding. That's why they need to be exemplars about openness & communicating expectations. So today's RNS is a bit of a disappointment. Like this note, very few numbers!
FWIW - from the numbers (and strategy) it has released so far it looks hugely undervalued to me at the current price .....but until it has been on the market for a few more independent reporting periods, it remains high risk and a bit of a punt on the 'old & rich' still have money story.
On a high risk/high reward basis I hold.
Hi planetx,
I'm not sure you're right about that. Marketplace websites are where things seem to be going right now - Asos, Boohoo, Marks & Spencer, Next, are all going down that route. The idea being that consumers won't want to look at hundreds of individual websites, but instead are gravitating towards curated marketplace websites with multi-brands.
So I think it makes a lot of sense for Unbound, which has a strong relationship with older women from Hotter Shoes, to go down that route.
There are 2 ways of doing marketplace type website -
1. Buying the product wholesale from the brand owner, and fulfil the order & handle returns yourself, or
2. Drop ship model, where the marketplace is just a selling agent, takes a commission, then everything is handled by the owner of the product.
I think no.2 is by far the better model, and think I'm right in saying that's what Unbound is planning to do. It doesn't absorb any cash, and each order is pure profit.
But I'll ask the company later today, and come back to you.
I don't think we should condemn the business model, until we are sure of the facts!
Paul.
It seems to me Paul that the drop ship model relies on people coming to your website. I appreciate a strong brand like Hotter, this may well work for, but if for whatever reason consumers stop visiting that website the model would collapse. It seems another layer of risk to me.
Paul
Maybe your right.
But then again the fact the RNS is not clear and “we” are all guessing exactly what is the route to market just puts more water on the fire for me.
I just cannot see how these 14 brands names would agree to a drop ship model with no stock commitments - I certainly would not in their position.
I do stand to be corrected and if you can directly ask what is the stocking in requirement for the brands (cash down) and are they placing scheduled orders or simply pulling item by item as itens are sold and drop shipping (I just cannot see this being a working out for hotter)
I still only see real value these days in building your own brand and not being a reseller of third parties so that is my ultimate point.
But hey ho at least they are trying something .
dave
ps - This made me chuckle, if things seem to be going in a particular direction doesn't mean its the right direction ! ( the direction of travel this year of share prices Asos, Boohoo and Unbound is certainly the wrong one for investors)
"Marketplace websites are where things seem to be going right now - Asos, Boohoo,"
pps
Just looking at stats and the stated "4.6 million " database which sounds ridiculously high
107,000 Facebook followers - the older generation more likely to be Facebook literate, though a plenty of comments saying they want to be able to visit a shop .
30,000 Instagram - low numbers , but their target generation arguably not instagram , not exactly buzzing on there with comments.
Thats 137,000 who you might argue are active from a database of 4 million
I know my stats were roughly - a 500,000 database , 40,000 Facebook , but if the database probably 20,000 were active and real loyal customers .
4 million database I might expect to see 400,000 Facebook if the ratios are consistent ?
So Paul- a real good question for you to ask is "of the 4.6 million database " how many customers are active and have purchased within the last 12 months .
That database claim the more I think of it is ludicrous , "we have a database of 10% of the UK population" - come on guys .
Hi planetx,
So Paul- a real good question for you to ask is "of the 4.6 million database " how many customers are active and have purchased within the last 12 months .
Thanks, that's an excellent idea for a question, I will note that down & ask.
I've got a call booked with Unbound (LON:UBG) after lunch today, so I'll edit the article above, this afternoon, with any clarification on the issues raised.
Regards, Paul.
Revolution Beauty (LON:REVB) - have just appointed a new broker:
"Revolution Beauty Group Plc (AIM: REVB), the multi-channel mass beauty
innovator, is pleased to announce the appointment of Liberum Capital Limited
("Liberum") to act as joint corporate broker with immediate effect. Liberum
will act alongside Zeus, Revolution Beauty's existing corporate broker."
Does that mean there's likely to be a placing? Or is this normal activity? Thanks.