Small Cap Value Report (Thu 31 March 2022) - NWF, ELCO, XSG, PRES, GATC, BRW, POLX, BAR, IDP, ALT, MER, TMO

Good morning, it's Paul & Jack here with the SCVR for Thursday. Today's report is now finished.
Agenda -
Paul's Section:
Nwf (LON:NWF) - another positive trading update, significantly ahead of expectations. This follows on from a similar upgrade at the start of March. It's benefiting from a supply shortage of oil, so is clearly able to raise prices & profit margins. This looks a good company, with a noteworthy long-term track record of paying reliable, and rising divis. Boring, but sometimes boring is good!
Eleco (LON:ELCO) - final results are out, with profit flat, and EPS lower, due to increased tax charge. Balance sheet looks adequate. It's a nice company, but the valuation still looks too rich to me.
Xeros Technology (LON:XSG) - more bad news from this serial disappointer, jam tomorrow company. It won't now reach breakeven in 2023, and only has enough cash to last for another year. It's tempting to punt on things like this, but they rarely end well.
Pressure Technologies (LON:PRES) - I responded to a reader comment from Camtab and have copied it into the main report. Results look OK, but maybe the recent c.50% rebound in share price might be worth a top slice?
Gattaca (LON:GATC) - poor interim results, as previously flagged in a profit warning in mid-January. The shares have plunged so far, that I wonder if it might be a turnaround at some point, under new management? An apparently sound balance sheet, means that dilution/solvency risk seems low.
Quickies -
Brewin Dolphin Holdings (LON:BRW) - party time for shareholders, with a knockout 61% premium takeover bid from the Royal Bank of Canada. The valuation metrics on the StockReport for yesterday do look attractive: fwd PER of 12.6, and a divi yield of 5.4%, for an impressive business with a good long-term track record. Are there other bargains in this sector I wonder? It's a recommended, all cash deal.
Polarean Imaging (LON:POLX) - up 25% today, to 65p, on news of it resubmitting a regulatory application to the USA's FDA. Shares plummeted when the original application was declined. Shareholders now have a nail-biting 6 month wait, to hope that this time the application gets approved. This does look an interesting company, but all rather binary. It chewed me up, and spat me out - I sold right at the low, for about 42p.
Brand Architekts (LON:BAR) is acquiring Innovaderma (LON:IDP) for 7p cash + 0.3818 new BAR shares for each existing IDP share. Both share prices have moved significantly today, with BAR down 17%, and IDP up 24%, so it's clear what the market thinks of this deal (that IDP shareholders have done well). Although the water is muddied by BAR also issuing poor interim results today. The £17.3m cash pile at BAR is the main interesting thing. There must be a lot of duplicated costs, from both companies being listed, so the combined entity could make more sense than 2 tiny separately listed companies.
Altitude (LON:ALT) - a positive trading update. It's expecting adj operating profit of £1.0m for FY 3/2022. Cash looks tight at >£1.0m. A new $0.7m bank facility has been agreed. Market cap of £24m isn't cheap, given the poor track record. However, I think there might be something of interest here, longer term, it's not clear yet.
Mears (LON:MER) - not a sector that interests me, but the StockReport shows a forward PER of 10.5, and good yield of 4.1%. Final results today look OK - bouncing back into profit, but a wafer thin profit margin. Reports average daily cash, as well as period end cash/debt, which is excellent, all companies should do this. Current trading in line. Good visibility. Most contracts have annual uplift for inflation - an important point. Margins are too low to interest me.
Time Out (LON:TMO) - I've never liked the business model here, nor understood the high valuation. Interim results today show a reduced, but still large loss of £(10.5)m before tax, on £32.0m revenues. The balance sheet is reliant on debt, and the going concern statement flags a material uncertainty over debt expiring in Nov 2022 (but expected to be extended). Looks over-priced, and risky to me.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Nwf (LON:NWF)
223p (y’day’s close)
Market cap £110m
NWF Group plc ('NWF' or 'the Group'), the specialist distributor of fuel, food and feed across the UK, today announces a further trading update for the current year ending 31 May 2022.
I last looked at NWF here on 8 March, when it issued a “significantly ahead” trading update. I was also impressed that it said cost inflation had been “recovered”, whereas most companies are using the word “mitigated” (i.e. only partially recovered).
Today we get another positive trading update, although note that this seems one-off in nature, and due to “exceptional circumstances”, so is likely to only have limited benefit to the share price -
Following the positive trading update announced on 8 March 2022, which noted the Board's increased expectations for the full year, the Group has continued to outperform and as a result the Board now anticipates full year results will be significantly ahead of the revised expectations.
This has been led by the Fuels business as a result of exceptional circumstances, with the very significant short-term volatility in oil prices and a supply constrained UK fuel market.
Valuation - I can’t find any broker notes, but it looks as if the broker consensus chart has found some, because you can see below that FY 5/2022 EPS forecast rose from 17.7p to 21.2p when the last positive trading update was published.
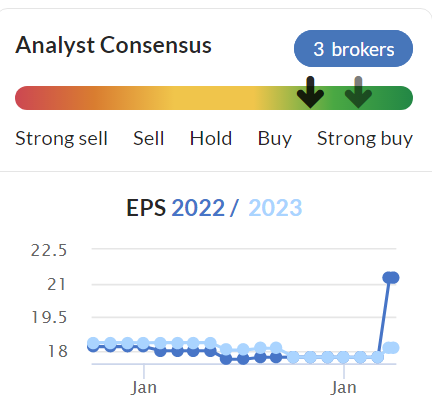
The same wording is used today, so I’m guessing that a similar sized upgrade of 3.5p might be on the cards. That would take EPS to 24.7p. That would give us a PER of 9.0 - with the caveat that the company is making one-off bumper profits due to a supply shortage. It might damage customer goodwill if NWF is seen as profiteering.
I would tend to value this share on next year’s EPS, of 18.1p - a PER of 12.3 - still quite cheap.
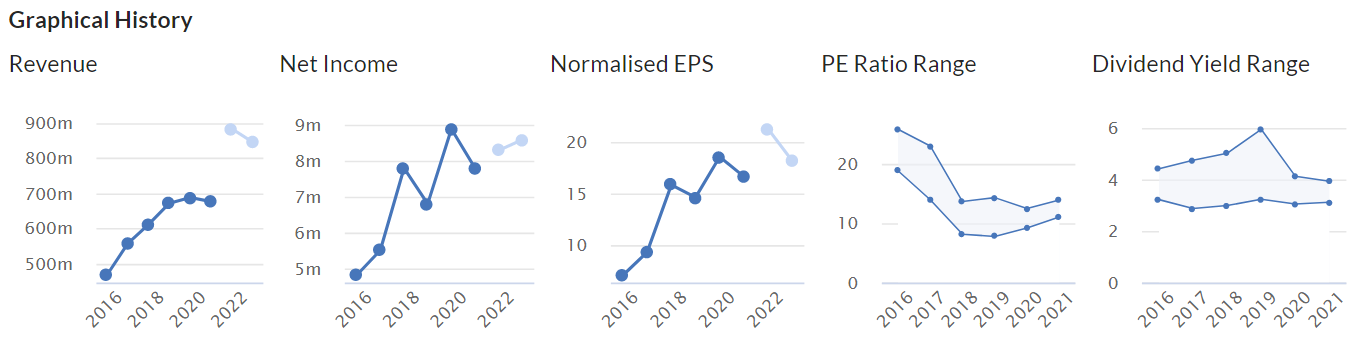
My opinion - even allowing for the likelihood that bumper profits for FY 5/2022 might not repeat, this share still looks modestly valued, given that its track record of growing profits and paying out decent divis looks strong over the last 6 years, as you can see -
.
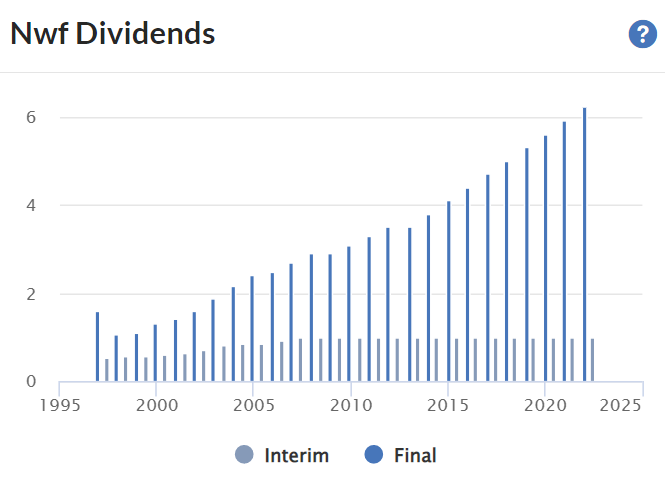
Overall, this share looks a good long-term hold to me. It’s the sort of share which might appeal to income seekers, how about this for a dividend track record! -
.
Eleco (LON:ELCO)
102p (up 2%, at 08:40)
Market cap £85m
Eleco is a provider of software to blue chip companies in the construction and built environment sectors
[from company website]
The Board of Eleco plc (AIM: ELCO) is pleased to announce its results for the year ended 31 December 2021.
Revenue for 2021 was £27.3m, up 8.4% (£15.4m is recurring revenue)
Gross margin is very high, as is usual at software companies. Gross profit rose 8.3% to £24.6m
All the benefit of the higher gross profit was consumed by increased administrative costs, so profit before tax only rose 1% to £3.9m
Tax - note that this considerably increased, so that PAT fell from £3.16m in 2020, to £2.73m in 2021. Hence why EPS fell from 3.9p to 3.3p - a PER of 30.9 times, which looks too expensive to me. Unless you think EPS could rise a lot in future, which might justify the rich rating.
Equity Development are showing (in a new note today) adj EPS of 4.0p for 2021. The company doesn’t seem to provide adj EPS in its results statement, which is an annoying mismatch. Using ED’s adjusted figure, the PER comes down to 25.5 - still quite high.
Strategy is to move more to SaaS rather than up-front licence fees. That tends to suppress performance for several years, as we’ve seen with lots of other software companies, so doesn’t fill me with joy.
Acquisitions - M&A is highlighted in the outlook section as something they want to do, so I would want to better understand what experience & track record management has in acquisitions, before investing in Eleco.
Outlook - general commentary, rather than anything specific, concluding -
With the foundations set in place, we are well positioned for continued growth, and increased market share through further product evolution and potential acquisition opportunities, supported by favourable market dynamics.
Balance sheet - not great actually, with only £1.7m in NTAV, but that looks adequate.
As mentioned before, software companies don’t need much capital, because they benefit from receiving cash up-front from customers. In this case, the £10.0m net cash is almost all offset by the accruals & deferred income creditor - i.e. it’s cash up-front from customers, for services not yet provided.
This means that I reckon ELCO would need to do a placing, if it wants to make any meaningful sized acquisitions.
Cashflow statement - this does look good. ELCO generated c.£7m in net cash inflow from operations, in both 2021 and 2020. About a quarter of this is spent on capitalised development spending, and the balance was mainly used to almost eliminate bank debt by £4.4m, to just £0.1m remaining bank debt at 2021 year end. There was also a trivial dividend paid, costing £493k.
My opinion - Eleco looks a decent business, with a good track record.
The trouble is that a shift to SaaS is likely to suppress performance and growth for a few years.
Personally, I’d only be interested in this share if it dropped considerably from the current level. Although software companies do attract bafflingly high takeover bids sometimes.
IT staff are expensive, and getting more expensive, so companies like ELCO need to generate decent growth just to stand still.
I see this share as in no man's land - it’s good, but not growing strongly enough to get me excited, and priced too high still, for only moderate growth. Then there’s the uncertainty of possible acquisitions, which increases execution risk, and possible dilution from a placing.
As always, I’m only reviewing the numbers, and don’t have a view of the company’s products, or the competitive landscape.
.
Xeros Technology (LON:XSG)
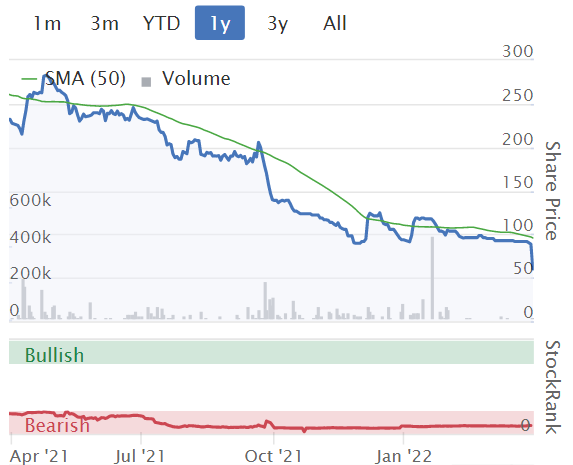
60p (down 32%, at 10:01)
Market cap £14m
Trading Update (profit warning)
This company is trying to commercialise a new type of washing machine, that uses little water.
It’s mostly blaming covid in China for under-performance, with the latest disappointment being -
Whilst the Board's view of the overall prospects of the Group remains unchanged, the Board has come to the view that the Group is no longer likely to reach month on month EBITDA profitability and cash breakeven in the first quarter of 2023, as previously guided. The Board now expects this to be reached in 2024.
I’d be surprised if it happens ever.
Is it going to run out of cash? Yes, but not until early 2023 - so it’s got about a year to pull something out of the hat, because I’d be surprised if investors would be keen to refinance it again, next year -
As at 28th February the Group's cash balance was £6.2m. These funds are sufficient to fund the delivery of major growth milestones through the remainder of 2022 and into the first quarter of 2023. The Board is actively evaluating several funding options to secure the remaining investment required.
That sounds like a highly dilutive equity fundraising might be on the cards. I can't see anyone being prepared to lend funds to the company.
There are also some upbeat comments about potential new business, which I won’t repeat here.
Outlook - the CEO remains upbeat, despite everything -
"Since our update in January, with the exception of China, the levels of activity by our existing partners have continued to be strong as has our engagement with prospective licensees. Our expectations are that multiple agreements will be signed this year with some fairly near term. This is against a background of increasing levels of interest from global brands in our ability to help them meet their major global environmental imperatives."
My opinion - Xeros has been a serial disappointer, and heavy consumer of investors cash, reflected in a plummeting share price.
It now looks to be in the last chance saloon, with a year of remaining cash, before it needs refinancing. In my experience, it’s very rare for situations like this to end well, but the odd one does, so we can’t rule anything out.
For people who like a gamble, the market cap of £14m isn’t outrageous, providing you’re prepared to lose the lot, for the off chance of a turnaround. Or as a trade, it might spike up on contract win announcements, which sounds imminent, possibly.
On balance though, I can’t see the point in taking on the risk here of dilution or insolvency.
Maybe this project was just too ambitious?
.
.
Pressure Technologies (LON:PRES)
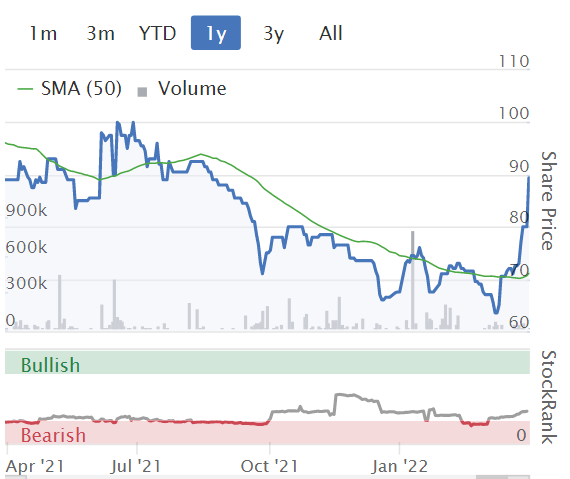
89p (up 12% at 10:10)
Market cap £28m
To save me re-typing it, this is a copy of a reader comment I replied to below.
Hi Camtab, Many thanks for that nice summary of Pressure Technologies (LON:PRES)
I've had a quick look at the its trading update today, and it all reads positively. So a little perplexing that the summary is only in line with expectations, not ahead of -
As a result of an increasing order book, notwithstanding the current economic climate and cost-inflationary pressures across the Group's operations and supply chains, the Board remains confident in meeting full-year market expectations.
They're half way through the current year, FY 9/2022. Maybe PRES is now set up to issue an out-perform update later in the year?
A Singers note out today only shows £0.9m adj PBT for this year, after 2 years of losses. Presumably as a holder, you're hoping for a beat against that?
Balance sheet - last reported at 2 Oct 2021, and as you say, it's been cleaned up with most of the bank debt paid off, and almost all the intangibles written off.
The share price has shot up recently, almost 50% from the lows, so I suppose the quandary now is whether to bank some profit? I'd be tempted to top slice on this vertical rise in price, but as always, it's your money, so your call.
.
Gattaca (LON:GATC)
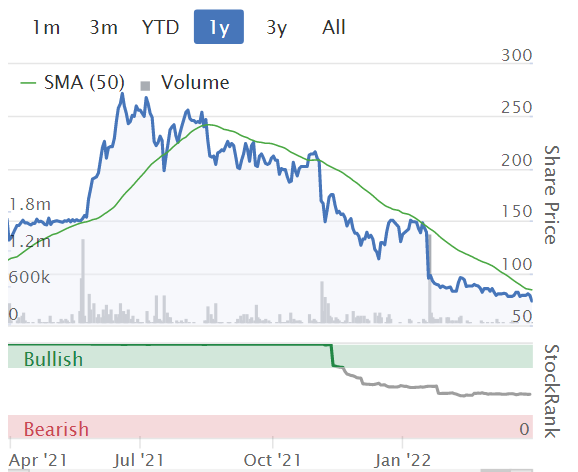
74p (down 6% at 11:30)
Market cap £24m
Gattaca plc ("Gattaca" or the "Group"), the specialist Engineering and Technology staffing solutions business, today announces its financial results for the six months ended 31 January 2022.
Management has made a right hash of things here, but the CEO & CFO are stepping down as Directors today (previously announced on 15 March), and leaving Gattaca at end April. Replacements have been appointed, so let’s hope they do a better job. The perplexing thing is that Gattaca operates in a sector that is booming, so how have they managed to perform so badly?
Poor results were expected, due to a profit warning, which I reviewed here on 18 Jan 2022.
It guided for breakeven in FY 7/2022. Lots more sales staff had been taken on, but were not yet contributing to increased sales.
Some key numbers for H1 -
- Net fee income £21.6m, up 5% vs H1 LY
- Loss-making in H1: £(3.1)m on a statutory basis, adjusted to £(0.2)m
- Balance sheet looks fine to me, quite good actually, with net cash of £4.8m - which should provide time for a turnaround, with little to no risk of dilution.
- No divis
Outlook - the key bit says this -
We are seeing encouraging trends across many of our sectors…
We expect continuing underlying profit before tax for its financial year ending 31 July 2022 to be around breakeven as announced in January 2022. Looking to 2023 and beyond, although the trajectory of the business has been slower than previously anticipated we expect to see the benefits of our investment in headcount and the technology platform begin to come through, delivering a return to profitable and sustainable long-term growth. This will continue to be supported by strong market demand for STEM talent, which we believe will remain scarce and in high demand.
My opinion - performance has been awful, and I’m not minded to put any reliance on forecasts. It would be easy to just slag off the company, given all the negatives.
However, everything has a price, and with the market cap now only £24m, this could be a base for a turnaround, if new management are good.
So the key issue for me, is to find out what track record new management have, and to see them present on one of the webinar platforms, so we can get a feel for who they are, what experience & track record they have? Also, how credible is their turnaround strategy?
Could there be anything nasty to come out of the woodwork when the new CFO checks all the numbers? It is a risk, and a £64m receivables book creates a lot of scope for burying some nasties in it.
NTAV is over £27m, so the risk of insolvency/dilution looks very low, unless it turns out that there’s been false or imprudent accounting.
Overall, I think you could see this either way -
Bull case -
- very low market cap,
- strong balance sheet,
- turnaround potential under new management.
Bear case -
- arguably, GATC might be viewed as a bad business, not making any profit, in buoyant market conditions.
For me, I’m on the fence right now, but will keep an eye on it, for more evidence of a potential turnaround (or not).
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
With regards to Brewin Dolphin Holdings (LON:BRW): there's loads of mergers and take overs in this area I think the attraction is your buying recurring revenue streams I'm looking at fund management companies for similar characteristics current favorite of mine is Polar Capital Holdings (LON:POLR): starting to tick back up negatives are they are heavily skewed to health care and tech which are two sectors that have been out of favor upside is they have cash on the balance sheet, capital light business and near 7% yield which is covered.
It seems to be wealth managers rather than fund managers that are attracting the interest. Makes sense as wealth managers tend to have very sticky clients (eg IFAs) and hence recurring revenue streams. Fund managers in contrast can be more subject to outflows, for example if a particular fund isn't performing well.
In my opinion both are attractive Jupiter snapped up Merian, Sanlam have took over Smith & Williamson and are in the process of taking over someone else at the moment who's name escapes me, River Mercantile were bid for I can't remember either if that one went through in the end but they were in play. Both have pluses and minus here what you are saying about IFA's but if you set a fund management business up once it has traction you don't really need much more staff whether your managing £10 million or £100,000 million.
Hi Paul
Re Gattaca (LON:GATC)
I remember you reviewing Gattaca (LON:GATC) at around 150p a year ago when it’s share price was rocking upwards on a wave of irrational exuberance (like many other shares). If I remember correctly, you puzzled why everyone was buying the share for no fundamental reason.
Turns out you were correct in your fundamental analysis. Maybe just underestimated how significant the momentum buying could be.
Now we have the opposite problem where good fundamentals aren’t producing corresponding share price gains. Clearly there is less money chasing small cap shares. Hard to see this situation changing soon.
Thanks for your insights on Eleco Paul. Equity Development have a more bullish report out on it today but they also pick up on some of the points you've made on slower performance for a while. My finger is no longer about to add to what we have at this time.
What are peoples views on £S4C announcement re postponement of results? The company states they are trading strongly within expectations. Tempted to buy.
S4 Capital (LON:SFOR) still looks over-valued to me, even after dropping by almost two thirds from last year's peak. I think people massively overpaid for Martin Sorrell's involvement. The figures have looked heavily adjusted in the past.
The inability to produce accounts, due to unspecified audit delays, introduces uncertainty, although as you said, it did say yesterday that trading was strong.
So personally, I'm wary of this one.
Regards, Paul.
Thanks Paul. I'm thinking out loud here but why would pwc delay at the last minute? Most of the planned work would be done otherwise it would have been flagged earlier. Did they uncover something that needed extra investigation perhaps? As you say it is unspecified hence being wary is sensible. S4 Capital (LON:SFOR)
S4 Capital (LON:SFOR)
Did they uncover something that needed extra investigation perhaps? As you say it is unspecified hence being wary is sensible.
Its fairly clear in the update from the company are still sticking to to their guns ref the profits being in the range previously specified. If there were "big questions to answer" i suspect the company would not have been so categorical if big questions had been asked? we are are all left speculating though.
What i dont know is what exactly the expectations are - so if expectations only referenced underlying profits that could leave room for exceptional w/offs not affecting the underlying figures - one would like to think year end expectations would go as far as mentioning bottom line profit figure - sometime though "like to think" may not cut the mustard. Not sure if anyone can confirm in that regsrd.
Obvious guess would be that covid outbreak could cause issues if it turned up at exactly the wrong time.
The Company believes that the results for 2021 remain within the range of market expectations and continued to trade strongly in the first two months of 2022.
£SFOR So personally, I'm wary of this one.
I think it’s right to be wary. The pertinent questions seem to be:
Assuming the auditors require some adjustment to either this years or previous years figures, which is my base case, are the corrections significant enough to warrant a near 40% drop in the share price overnight?
Following the sell-off, how does the valuation compare to other adtech firms of a similar growth profile?
I can’t answer the first question but I’m sure PWC will come through with a response in due course. On the second question, I’ve compared S4 to two of my holdings, Ironsource and Pubmatic*. They are not directly comparable in terms of product mix but they do occupy the same adtech segment. The former has a near identical forecast growth rate and is now 50% more expensive on an EV/EBITDA basis. The latter has a 10% higher valuation but for a forecast growth rate 30% (the inverse of 50%) lower.
Noted that you think S4 is still expensive, and you may well turn out to be correct, but that depends on your point of reference - but maybe not as much as it depends on PWC!!
* Yes, I know Tremor is cheaper but it’s run by a BoD who present like a bunch of gangsters and seem to care little for shareholders, other than themselves..
Hello BNB
S4 Capital (LON:SFOR)
“If this is all it turns out to be, then today's closing action will turn out to have been an excellent buying opportunity. I would not be surprised by a much higher open in the morning.”
What you expected did not happen. Your thoughts were understandable but a deeper awareness of how audits and announcements work suggested a deeper issue here.
I didn’t state that I had any expectations - only that I would not have been surprised by a rebound, which will still eventuate if the delay turns out to have been resource-driven. My base case, which I stated elsewhere, is that there is a disagreement to resolve. On that it seems we agree.
I did enjoy the patronising tone of your final sentence though.
I never held S4 Capital (LON:SFOR) but at the first sign of any accounting issues in any company I have held I'm out like the proverbial bat out of hell. Occasionally I've missed a rebound but on balance it works for me.
Eleco (LON:ELCO) (I Hold)
FY21 results seem less than sparkling for an award winning software business - but they are fairly much as flagged - due to the change-over from perpetual licence sales to SaaS. Also perhaps the after effects of initial licence sales in FY20 as the pendemic spurred working from home and ELCO introduced cloud based remote working options.
Despite the revenue increase the bottom line appears to be a slight decrease in eps to 3.3p (3.9p) but needs to take into account deferred tax change in preparation for FY23 tax rises (I'm seeing a lot of this in current results) and somewhat hidden a 0.6m provision against a product the board believes is no longer likely to achieve expected sales. Which seems a straightforward approach to be respected in my view. Taking these into account the results are much as anticipated.
Despite the share price falling from 140p highs to around 100p - the price still seems fully valued at around 33x eps against lacklustre growth. Except that looking a little deeper the amortisation charge considerably exceeds the current development spend (software development capitalisation) - given the significant cash conversion - adding 4m to the now 10m cash pile during the year. The ev/ebitda (if you believe in such things) of something like 14x (adding back in lease payments etc) looks a lot more appealing if you consider that the conversion to SaaS is improving future revenue growth and that the 12% spend on development is improving product competivity.
I sold about half my holding on the way down from 140p to 100p - and on these results I'd like to hold as I think ELCO is building a strong position - though it may take a couple of years before the fruits are delivered. I am struggling to find cash to buy some real bargains at the moment so it will be something of a battle in my head whether to fund shorter term opportunities or stay for the long term,
cheers
Mark
Be interested in your thoughts on Pressure Tech this morning Paul. It is a company I hold. They seem to sit in all the right places, Hydrogen, Defence although there is a trade off with oil, that said they mention interest is picking up there too. They make specialist cylinders through their CSC division which does seem to have a moat given the specialisation. These are for hydrogen, nuclear subs so not to be messed with. Problem is orders a bit lumpy. Had difficulties in recent past, and B/S restored with significant raise. 17 times p/e does seem demanding but coming off low base. Todays announcement says management will meet full year expectations. Only regret not many numbers to help us with so get it if not too interested. A real small cap £25m.
Hi Camtab,
Many thanks for that nice summary of Pressure Technologies (LON:PRES)
I've had a quick look at the its trading update today, and it all reads positively. So a little perplexing that the summary is only in line with expectations, not ahead of -
As a result of an increasing order book, notwithstanding the current economic climate and cost-inflationary pressures across the Group's operations and supply chains, the Board remains confident in meeting full-year market expectations.
They're half way through the current year, FY 9/2022. Maybe it's now set up to issue an out-perform update later in the year?
A Singers note out today only shows £0.9m adj PBT for this year, after 2 years of losses. Presumably as a holder, you're hoping for a beat against that?
Balance sheet - last reported at 2 Oct 2021, and as you say, it's been cleaned up with most of the bank debt paid off, and almost all the intangibles written off.
The share price has shot up recently, almost 50% from the lows, so I suppose the quandary now is whether to bank some profit? I'd be tempted to top slice on this vertical rise in price, but as always, it's your money, so your call.
Regards, Paul.
Many thanks Paul.
A comment from you on Eleco's results today (I hold) would be appreciated Paul and Jack.
Morning JASVFS,
Yes, we like Eleco (LON:ELCO) here at the SCVR, although the valuation strikes me as excessive, when reviewing it in the past. I might do this one next actually.
Regards, Paul.
P.S. We like it when readers give your view on a share, at the same time as asking me to review it!
Here is our Eleco (LON:ELCO) note (yes we are paid for as the disclaimer says, thanks for highlighting that johneustace).
Eleco delivered ‘in line’ results today, posting adjusted EBITDA & EPS of £7.2m & 4.0p respectively on record turnover up 8.4% to £27.3m (+7.7% vs FY19). This was further bolstered by 100% cash conversion (£4.75m, representing a 5.7% yield), whilst ending the period with a hefty £10m net cash balance (12p/share) – even after spending 12% of revenues on R&D.
Eleco’s award winning applications are being increasingly adopted by construction firms, asset/property managers, manufacturers and retailers everywhere.
Consequently given the strong industry tailwinds and positive start to 2022, we’ve held our FY22 forecasts (re adjusted PBT £2.9m & turnover £27.6m), and have a 150p/share valuation. Plus at 100p, Eleco trades on modest 2022 EV/sales & EV/EBITDA multiples of 2.7x and 11.8x respectively, equivalent to a wide discount vs BuildTech peers.
https://www.equitydevelopment.co.uk/research/grow-baby-grow-
Sharing some reading on Eleco (LON:ELCO) which gives a somewhat different spin that I came across previously thanks to Maynard Paton:
https://forum.quidisq.com/t/eleco
Innovaderma (LON:IDP) busy day for Innovaderma. First an interim results RNS followed by an RNS proposing a merger with Brank Architetekts £BAR.
for each innovadera share, shareholders get 7p in cash and 0.3818 brand architekts shares. Putting a value if 47.7p on jnnovaderma shares.
I'm holding the wrong side of that "merger" - Innovaderma (LON:IDP) get a great deal at Brand Architekts (LON:BAR) expense. If it was a merger then the deal wouldn't be such a premium for Innovaderma (LON:IDP)
Gattaca (LON:GATC) is the UK's largest specialist engineering/tech recruitment agency. Its shares have fallen >70% (vs c. -25% sector) from their 52 week high of 285p - principally due to January’s profit warning. There is work to be done, but even so we believe the scale of the sell-off looks totally disproportionate to the issues involved (Re temporary disruption from a major IT system implementation, staff turnover/culture, etc).
Following the recent appointment of Matthew Wragg as CEO - a highly capable & experienced industry professional with ‘sales’ running through his veins - the early signs of a successful turnaround are tentatively taking shape, with productivity levels inching up anecdotally MoM since January. Furthermore the company is “seeing encouraging trends across many of its sectors”.
We have pencilled in FY23 PBT of £2.5m on NFI of £49.1m with a 145p/share fair value, albeit these estimates are prudent, and we would ultimately hope to upgrade as key milestones are met. Similarly, we assume the FY22 dividend will be temporarily suspended, leaving net funds (pre IFRS16) of £5.0m as at Jul’22 (excluding £10.4m of non-recourse finance).
https://www.equitydevelopment....
I was a holder of £GATC. Am i right in thinking that Equity Development is paid for research, i.e. P.R.?
Yes, the disclaimer in the linked write-up includes:
Research produced and distributed by ED on its client companies is normally commissioned and paid for by those companies themselves (‘issuer financed research’) and as such is not deemed to be independent as defined by the FCA, but is ‘objective’ in that the authors are stating their own opinions.
The inverted commas around ‘objective’ are their own, not added by me!
Gattaca (LON:GATC) is the UK's largest specialist engineering/tech recruitment agency
Oh no it isn’t! If the analyst can’t get this basic fact right, what value their forecasts?
Gattaca (LON:GATC)
"but even so we believe the scale of the sell-off looks totally disproportionate to the issues involved"
Hmmmmm even they are admitting the company is gonna make no money this year and £2.5 mill profit next year.
Note sure how they think it is massively undervalued unless you factor in the "hope" that 2024 and 2025 will be much better.
Why will they make decent profits in 2024 and not 2023 - what is the issue that will take so long for them to turn things round and why will they be sat twiddling their thumbs in 2023 making half the profits they will make in 2024?
Hey ho the return to growth will be "sustainable" here if everything is to be believed
There's an excellent review of the pressures facing businesses at the moment in the James Halstead (LON:JHD) interim results . It's well worth reading the Chairman's commentary in full to get a feeling for the challenges both behind and ahead:
As a manufacturer we are experiencing levels of inflation not seen in a generation. The passing on of costs is a necessary consequence and whilst we do not know yet we are mindful that demand may be affected. The probable increases in interest rates through the coming months may exacerbate the issue. To date they have not.
https://www.londonstockexchang...
Price rises will start to bite now, with energy costs increasing and VAT and NI rises also kicking in.
The results are pretty decent, a small drop in profit and cash levels from a small rise in revenue. A proper coffee can stock.
timarr
Completely agree, have held these for many years through multiple 'bonus issues'.
A proper coffee can stock
A reliable company certainly, but surely only attractive if the 3% yield is all you anticipate. This name is flat since the summer of 2015 and in a narrow channel at that so not a trader’s stock either. Happy to be corrected of course.
RE: James Halstead (LON:JHD)
A reliable company certainly, but surely only attractive if the 3% yield is all you anticipate. This name is flat since the summer of 2015 and in a narrow channel at that so not a trader’s stock either. Happy to be corrected of course.
Over twenty years I'm content with the returns. Stocks can go sideways or even down for the best part of a decade and there are always better opportunities to be found, I'm just not smart enough (or interested enough) to find them. I imagine JHD will continue to go sideways until economic growth returns, but it'll manage its way through the issues and come out the other side OK while lots of competitors will fold. At that point growth will unfold again.
For me, personally, predicting share price movements has always been a second order guessing game that I'm terrible at. To take another coffee can stock, James Latham (LON:LTHM) went sideways from 2015 to 2020 and then nearly doubled. Who'd have guessed that a pandemic would hit lumber supply chains? Probably temporary, mind, but again I have no idea.
I hold plenty more exciting stuff, mind, but a lot of that has been sawtoothing down. If we get a proper recession - which is not certain, of course - there'll be plenty more of that to come. A company that knows its market inside out and can keep the lights on without requiring new capital while that transpires is fine by me.
timarr
A company that knows its market inside out and can keep the lights on without requiring new capital while that transpires is fine by me.
Amen to that and I hold “boring” stuff to balance my tech investments too. Was just interested in your perspective. Thanks
James Halstead (LON:JHD), James Latham (LON:LTHM) & Headlam (LON:HEAD) are what I would call 'Warren Buffet' stocks.