Small Cap Value Report (Thu 4 Feb 2021) - IDP, EVE, IGP, VLG, VTU

Good morning, it’s Paul here with the SCVR for Thursday.
Timing - today's report is now finished.
Agenda -
Innovaderma (LON:IDP) - bid approach by Creightons (LON:CRL)
Eve Sleep (LON:EVE) - trading update - still has plenty of cash, and losses reduced.
Intercede (LON:IGP) (I hold) - convertible loan notes dealt with - mostly converting into new equity.
Venture Life (LON:VLG) - Trading Update (from Monday this week)
.
Holiday bookings
I’m definitely getting old, because each passing week seems to fly by in a blur. Maybe it’s because every day is virtually identical at the moment? Get up, analyse shares, have a nap after lunch. Get up again, watch TV, listen to audiobooks/podcasts, go for a walk if it’s not tipping it down, analyse some more shares, go to bed. That’s it at the moment. At least I’m not having to home-school unruly/bored children, whilst trying to work from home, so I count my blessings in that way.
Something had to give, so I booked myself flights to spend 5 weeks in Malta in Sept/Oct, The cost was below £200, and it gives me something to look forward to. I’ll take the laptop and carry on writing the SCVRs here as before.
I wonder if other people are having similar thoughts? If any of you spot forward bookings information from travel companies, do post a comment here, as I’d be interested to find out if other people are booking up overseas trips like me, or are reluctant to do so due to the uncertainty, like some of my family for example. Opinions seem to be mixed.
Covid comments
Most people respect this, but please could those who don’t, take on board this gentle reminder - we’re discussing investment/markets/economics here. We’re not interested in anyone’s views on the pandemic more generally, or which politicians have been clever or stupid, etc. We need to keep focused on how covid is likely to affect the markets. Not the wider issue. Let’s try to keep the focus. There are plenty of other places on the ‘net for a wider discussion/rant.
I’m exercising restraint myself - there are plenty of things I’d like to say about the EU right now, but am keeping my personal opinions to myself, because (a) nobody’s interested, and (b) it’s boring, and (c) it has nothing to do with investment, which is what the SCVRs are all about.
Many thanks! Oh, and please don’t post comments about this comment, that just perpetuates the problem! Let’s draw a line under it, and move on.
.
Innovaderma (LON:IDP)
Bid approach by Creightons (LON:CRL)
This is an interesting, and topical issue.
Creightons issued a statement here at 07:00 on 2 Feb 2021, saying that it made a preliminary approach to Innovaderma (IDP) on 26 Jan 2021, regarding a possible all-share offer for IDP.
This approach was unequivocally rejected by the Innovaderma Board on 29 January 2021 without affording Creightons the benefit of any further discussion. The Board of Creightons continues to have a serious interest in the possibility of a combination of the two businesses, and is therefore publishing today, in the Appendix to this announcement, the text of its letter to the Board of Innovaderma ("Letter") in order that the shareholders of Innovaderma are directly aware of Creightons' interest.
The proposed deal is an all-share takeover/merger, buying out IDP shareholders with 2 new Creightons shares, for each 3 IDP shares held. That initially valued IDP at 44p (subject to change in line with whatever CRL’s share price now does). IDP shares have risen a little, and are now 48p.
IDP’s response - What’s interesting is that IDP rejected the offer, and only made a stock market announcement in response to CRL going public with its announcement.
At 11:41 on the same day, IDP issued this statement.
IDP confirms it received an approach from CRL, saying;
- IDP’s Board unanimously rejected the approach because it:
- Significantly undervalues IDP
My opinion - IDP is in the middle of a fundraising, so this could be seen as a distraction in the short term.
However, it does raise the topical issue of if/when companies should announce to the market any takeover approach(es). There don't seem to be any clear rules on this issue at the moment. Is it right that Boards can rebuff a bid approach, and not even tell its shareholders? The timescales here are very recent, so any criticism of IDP is premature. I’m just flagging it as another example (there have been others lately) where some shareholders feel that they’ve been kept in the dark about bid approaches - costing them money, if they sell out, not knowing that the company is potentially in play.
Sounding-out institutional shareholders in private is all very well, but the fact there has been a bid approach, is materially price sensitive (even if it’s at a modest premium, it still puts the company in play potentially, and it flags that the company is cheap, because bidders see value in it above the current price, otherwise they wouldn’t be interested).
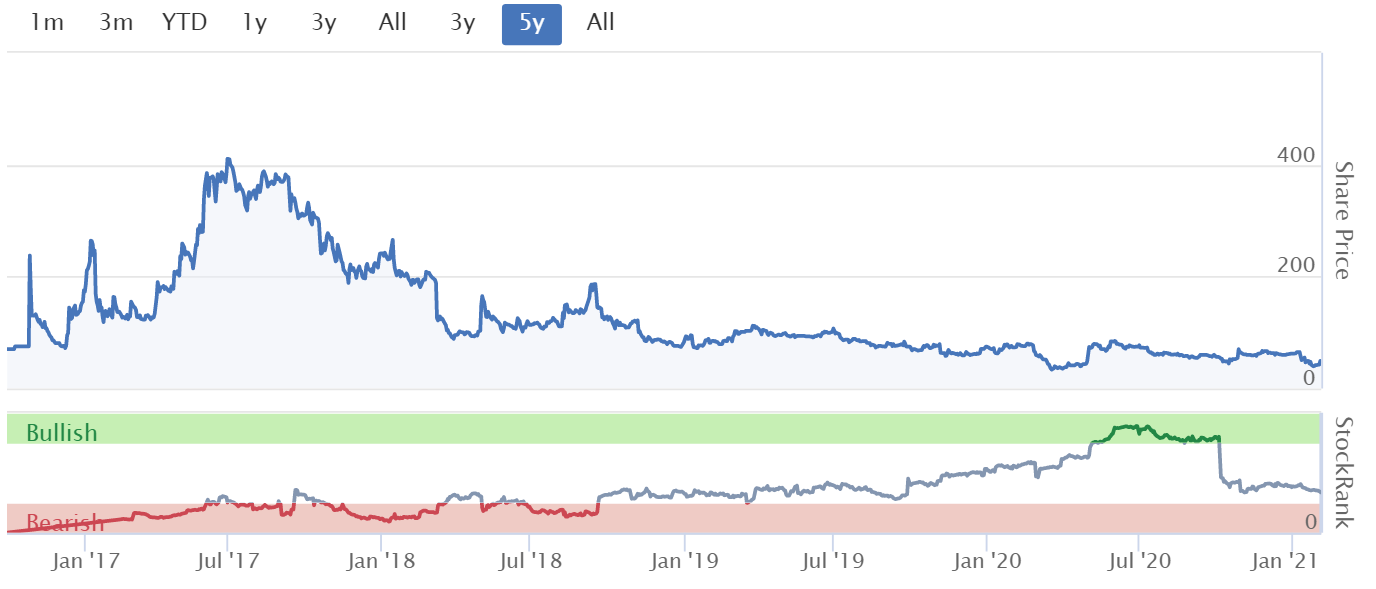
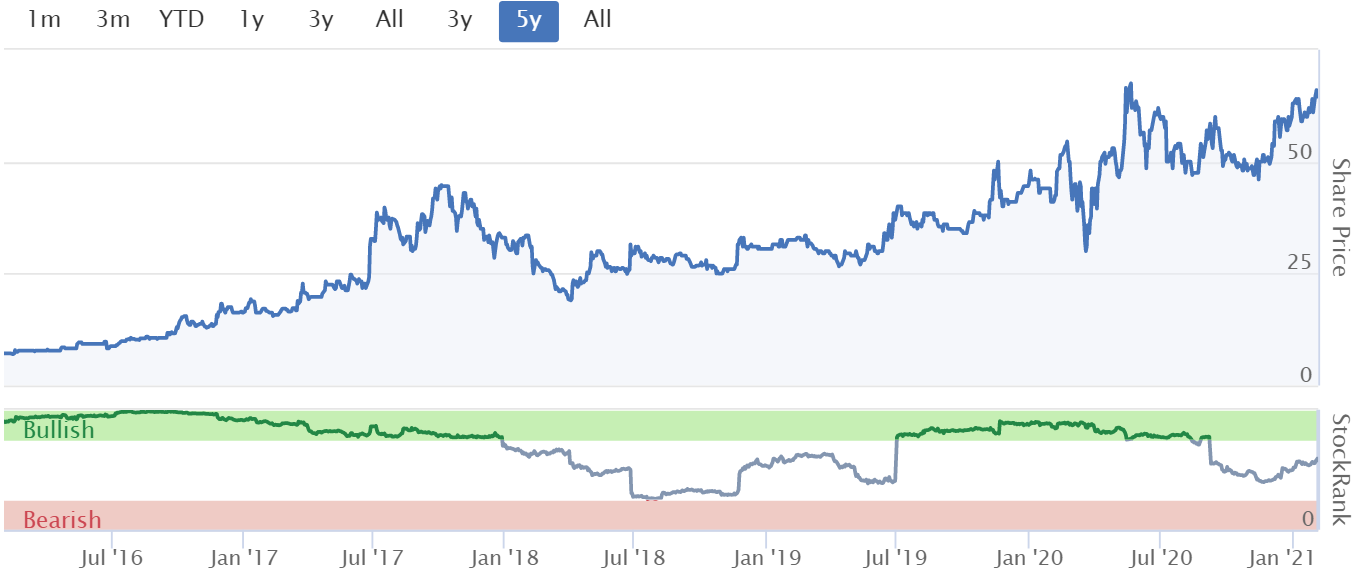
Surely shareholders have a right to choose between holding shares in a tiny illiquid £8.5m mkt cap company (IDP), or seeing their company absorbed into £42m mkt cap Creightons, by agreeing to swap IDP shares for CRL shares? That would improve liquidity, plus no doubt lead to some duplicated cost savings. It's pretty obvious which management has done a better job, so why would you want IDP to remain independent after such a poor track record? Compare the share prices -
Firstly IDP over 5 years:
.
Over the same period, this is Creightons:
.
Have IDP rejected the bid approach because management want to keep their jobs, or because they can genuinely do a better job than if they agree to CRL's takeover?
If you agree with me that we need tighter, clearer rules, on what companies must disclose to the market, then please do support Lord Lee’s & ShareSoc campaign on this issue by writing to the Takeover Panel with your views.
EDIT: See the comment below from davidjhill, who owns IDP shares, explaining well why he agrees with IDP's Board that it has better prospects as a standalone company. End of edit.
Review of Listing Rules
On the same topic of rules & regulations, I read that former UK EU Commissioner, Lord Hill (who? I hear you ask? He’s a mate of David Cameron), has been appointed to conduct a review of the UK stock market listing rules. Some have dubbed it “Big Bang 2.0”. The idea seems to be all about opening up, reducing regulation, to improve London’s international competitiveness, performance & opportunities.
This strikes me as a good idea, and a real opportunity to make things better, so we should get involved.
I might take a day off soon, to have a think about this, and draft some proposals to send to Lord Hill, about the many annoying & outdated ways the stock market works currently - e.g. just off the top of my head these include -
- Excessive costs for fundraisings,
- Leaving shares trading when a fundraising is going on supposedly in secret (yet hundreds of people know what’s going on, so it leaks out),
- Blatant insider dealing before bids,
- Trading statements that don’t include or obscure key information,
- Dis-application of pre-emption rights becoming routine when it should be an exception
- Slow & paper-based processes e.g. AGM/EGM votes which should have moved online 20 years ago!
- The ridiculous nominee system which disenfranchises smaller shareholders, removing proper shareholder oversight
- Excessive Director remuneration & bonus/shares schemes
- Remuneration committees & consultants that ratchet up pay
- Rewards for failure
- Brokers floating rubbish, speculative, blue sky companies, so many of which fail & hoodwink gullible investors
- Overseas frauds welcomed with open arms onto AIM (remember all the Chinese frauds like Naibu & Camkids?)
- Inadequate free floats on many small caps, leaving Directors free to do whatever they want
- No meaningful punishment for any kind of wrongdoing it seems.
- MiFiD 2 making it harder to access, and reduced the production of, company research
- Excessive compliance procedures & costs
- Improving liquidity in small caps, through encouraging a broader PI shareholder base, not just large lumpy institutional placings
- Giving better access to research & companies generally, for PIs
I could go on. There are clearly lots of issues and opportunities to make things better, creating a virtuous circle of more investment, and more listings.
My feeling is that we don’t necessarily need to de-regulate, I think we just need a thorough review, to make sure regulation is necessary, effective, and properly policed. Anything that isn’t, then just get rid of it.
Also, if there are new initiatives which could be introduced to make London a more attractive venue for companies to list, then let’s go for it. I want to see London as a vibrant market, leading the world with growth, tech companies that are maybe not quite big enough to list in New York.
It’s great to see the recent successful floats of Dr Martens (LON:DOCS) - Dr Martens boots, floated at 370p and it’s gone to a premium, currently 443p. Floats that go to a premium are good because they attract more companies to float, and attract more investors keen to get in on the act and make some money.
Moonpig (LON:MOON) - Moonpig - floated for £1.2bn, up from the mooted £1.0bn, and has gone to a premium also. All good for the market overall, even though neither share interests me personally, because they look expensive.
.
Eve Sleep (LON:EVE)
(I hold)
4.5p - mkt cap £12.3m
Just a quick note, as this share is high risk, illiquid, a total punt, with a very poor track record.
However, its recent trading update caught my eye as a possible special situation.
Look away now, as regulars here will know that my micro cap punts hardly ever work! I just can’t help myself sometimes.
eve Sleep ("eve", the "Company), the direct to consumer sleep wellness brand operating in the UK, Ireland (together "UK&I") and France announces a trading update for the full year ended 31 December 2020. All figures remain subject to audit.
The original business plan of spending huge amounts on marketing hasn’t worked. So this is version 2, with costs greatly reduced, and a focus on driving sales with online marketing.
Here’s the latest -
- Revenue increased 6% to £25.2m (2019: £23.8m), driven by 18% growth in H2
- Record trading over black Friday period and the first week of the Boxing day sales
- EBITDA losses cut by 81% to £2.0m (2019: EBITDA loss of £10.7m)
- Closing net cash at 31 December 2020 of £8.3m (2019: £8m), bolstered by £0.3m of tax payments deferred until after the year end
The way I look at the above, is it’s producing meaningful revenues, has slashed losses, and has plenty of cash in the bank, at about two thirds of the market cap.
My opinion - there’s a glimmer of hope here. It’s got enough cash to continue trading, and the massive prior years marketing spend has created good brand awareness.
2021 trading has “started well”. There’s a lot more info in the statement, which I won’t repeat here.
Highly speculative, but possibly interesting at 4.5p. Probably more of a trade, than a long-term investment.
.
Intercede (LON:IGP)
(I hold)
Share price: 83.5p
No. shares: 50.63m existing + 6.47m new shares = 57.1m
Market cap: £47.7m
Good news here, as this issue has been resolved earlier than expected.
As has been well documented here, IGP had £4.9m of outstanding loan notes, which were quite expensive, costing £400k p.a. in interest cost.
They were due for expiry at the end of 2021, but it turns out the company had the right to "Call" holders, to elect to either receive cash repayment, or convert into new IGP shares at a fixed price of 68.8125p.
The results are;
Convert into shares: £2,905,000 of loan notes, so 4,221,612 new shares to be issued.
Redemption in cash: £450,000 of loan notes
Intending to convert into shares: £1,550,000 of loan notes, so 2,252,498 shares to be issued.
Overall impact - there is dilution to existing holders, with the share count rising from 50.63m now, to 54.85m now, and another 2.25m shares to be issued, making 57.1m in total once all conversions have occurred. That's a 12.8% increase in the shares in issue.
My opinion - this is good news, as it means profits go up by £400k p.a. from now, due to eliminating expensive debt. Also the balance sheet will now be debt-free, with a big cash pile, so much stronger.
Note that Azalia Trust, connected to a NED, Jacque Tredoux, now holds 29.97% of the company.
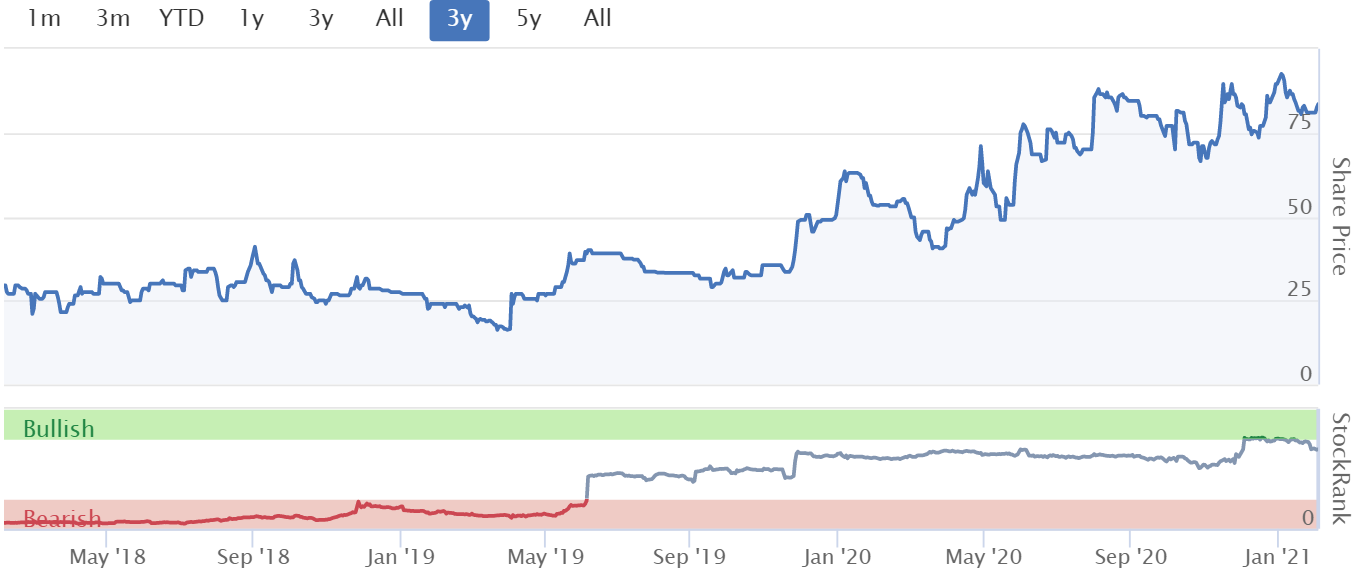
The company's making steady progress, and this eliminates the last legacy issue. So far it's been a decent turnaround, as the share price reflects.
.
.
Venture Life (LON:VLG)
82p - mkt cap £103m
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the self-care market, announces its unaudited trading update for the year ended 31st December 2020, ahead of the announcement of the Group's audited results on 25th March 2021.
Full year profit ahead of market expectations
The Company expects to report revenues for the year ended 31st December 2020 of £30.1 million, 49% higher than for 2019, and adjusted* EBITDA is expected to be not less than £6 million, more than double the 2019 adjusted EBITDA.
*Adjusted EBITDA is EBITDA before deduction of exceptional items and share based payments
There were no further shipments of product to our Chinese oral care partner in H2, but shipments are due to resume in H1 2021.
Directorspeak - the cash pile looks very impressive, post the big recent fundraising -
The placing and open offer completed in December 2020 has given us substantial funds, leaving us with net cash (excluding finance lease liabilities) of £35.5m as at the year end, with which we can now pursue our ambitious acquisition growth and, with an order book ahead of the same time last year, I look forward to updating the market further as we go through the year. "
Fundraising - why did it raise so much cash in Dec 2020, £36m at 90p (at the time, a 13.5% discount)? It says for working capital, and acquisitions. Maybe there's an acquisition deal in the pipeline?
Selling shareholders ditched 8.17m shares at the same time, a negative in my view.
Chinese order - if you recall, it previously announced a remarkable 15 year deal with a Chinese distributor for 168m Euros minimum. That orders dried up in H2 is a concern, as is everything related to China.
Forecasts - we have 2 fresh broker notes available on Research Tree, many thanks to the brokers for making those available.
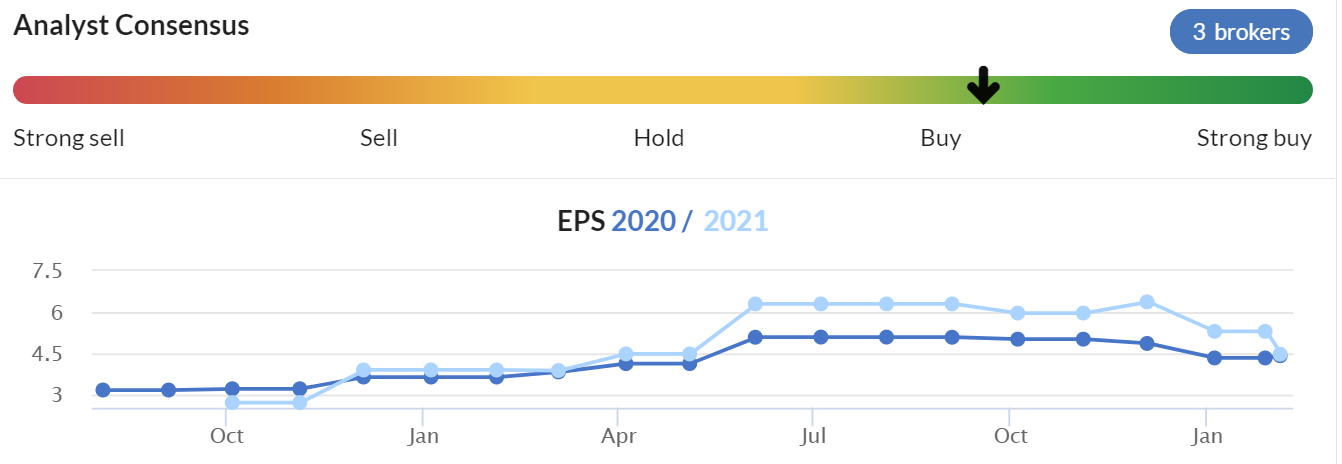
They have very different figures. N+1 Singer has FY 12/2020 forecast at 3.5p adj EPS, so a PER of 23.4 - whilst that looks expensive, bear in mind that the company has raised a ton of cash recently, so it will be able to deploy cash to make acquisitions, hence driving up EPS hopefully.
N+1 Singer has a forecast for FY 12/2021 of 3.2p, PER of 25.6. Note this is a reduction in EPS, despite a rise in forecast profit, because there are more shares in issue following the equity fundraising.
Cenkos has higher numbers forecast, at 5.0p for FY 12/2020, and 4.1p for FY 12/2021, PERs of 16.4 and 20.0, which look a more reasonable valuation.
Given the difference in broker forecasts, then investors need to drill into the detail, to satisfy yourself that you're locking into plausible forecasts & hence valuation. It's always a good idea to sense check forecasts, with your own simple spreadsheets. At the moment I find that many forecasts are too cautious, providing an opportunity. I particularly like it when companies report they're ahead of expectations, but brokers leave figures unchanged. That almost guarantees a beat when the next numbers are reported. The reverse happens when companies sound cautious about the future, but brokers leave forecasts unchanged - then you're risking a 30% hit from a profit warning. There's a lot to be said for selling at the first sign of trouble.
My opinion - checking back through my notes from June & July 2020, I was impressed with VLG’s progress last year. The market cap is over £100m now, so the company needs to continue growing earnings into that valuation. I’m a bit wary of the materiality of the lumpy Chinese orders.
A lot hinges on what it does with the freshly raised cash pile, which is about a third of the market cap. If a sensible, earnings accretive acquisition is made, then that could drive forecasts, and the share price higher.
Overall, I don’t know what is likely to happen here, so declare myself neutral on this share.
Note that forecasts have come down recently, probably to reflect the dilution from the issue of new shares. Although how much credence should we give to the "ahead of expectations" heading to the trading update, given that expectations had recently been lowered?!
As always, the darker coloured line is the current financial year, and the lighter coloured line & blobs are next year.
.
.
That's it for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

111 comments
post deleted
Apologies maxistaxis I was replying to the post by Simon7061 which he posted at 2.27pm re Hummingbird Resources.
Hi Paul,
That is a great list of proposals for Lord Hill's review. My top two priorities from your list would be:
Thank you as always for the excellent SCVRs.
Steve
Can anyone offer an explanation of the notifications for Boohoo (LON:BOO) - this morning they announced Morgan Stanley had reduced their holding by 0.03% (in one of those RNS that boo holders have come to know so well over the last few months...but then this evening announced that they had gone from almost 7% holding to under 3%! The thing is I can't see any significant volume on Stocko (ie this would be over 45m shares and this month Stocko is showing less than 20m in transactions to date.
What am I missing something?
Thanks in advance on anyone who can shed light on this (minor) mystery.
Martin
Continued spikes in
XLMedia (LON:XLM) +4.1% 700,000 shares traded
International Personal Finance (LON:IPF) +4% 269,000 shares traded
XLM Earnings Release somewhere at the end of March
IPF Earnings Release 24th Feb
Simon7061 Paul does not normally comment on Commodities.
I sold out today having held since early Sept last. SP has dropped25% in the last month.
Not a good sign.
Would be grateful if you would disclose the name of the company - tq
Anyone got thoughts on what’s happening with French Connection (LON:FCCN) the last couple of days?
Was wondering the same thing about French Connection (LON:FCCN) too, can't see any news anywhere but the price has shot up today
me neither. It went up yesterday before falling back later in the day...
Hey @Simmo1a. From the volume traded yesterday and today, I assume someone is building a position in French Connection (LON:FCCN) (I hold)
French Connection (LON:FCCN)
My guess is they will have to put out an RNS tomorrow. I saw last week Mike Ashley cut his stake below 25% - is this necessary to launch a formal takeover? Or did he do that to pave the way to invite a possible bid? Really not sure about the mechanics.
I’ve had a good look at the various message boards today but can’t see anything that looks like a credible rumor - just lots of random nonsense. This has been a small holding for me since Paul recommended last year but I’ve added to it on dips etc. and lovely to see a +106% beside it right now. Very tempted to just cash out but think I’ll wait around for a while.
Hi Phuntt,
Re French Connection (LON:FCCN)
This has been a small holding for me since Paul recommended last year but I’ve added to it on dips etc. and lovely to see a +106% beside it right now. Very tempted to just cash out but think I’ll wait around for a while.
Just to clarify, I don't recommend anything, am just giving my personal opinions on shares here, which are sometimes wrong, and sometimes right. Everyone needs to do their own research, and make up their own minds & take ownership of their own decisions. Please do bear that in mind.
I don't know what is behind the big share price rise in FCCN this week, just more buyers than sellers obviously!
My opinion - I'm in for the duration, so haven't sold any. Founder/CEO Stephen Marks is well into his 70's, and is inevitably going to retire & sell the company at some point. I've been told that Marks turned down a bid before covid, as being too low. So the only questions are the timing, and the price, of a sale of the brand. Now may not be the best time to sell, waiting a few months would probably make sense, as covid recedes.
Asos (LON:ASC) paid £330m for TopShop, TopMan, and Miss Selfridge brands, buying them out of insolvency. Whereas FCCN is solvent, and its market cap is only £15m now, even after the big recent rise in price. It also has a lucrative line in brand licensing, which is pure profit, for things like perfume, designer spectacle frames, and DFS sofas have sold well with FCCN branding apparently.
As someone else mentioned in the comments here, the FCUK branding is well known amongst younger people too. I was amazed a couple of years ago, seeing my 23 year old niece using a French Connection branded purse.
My personal price target is an agreed bid at 40-50p (there are c.97m shares in issue). I'd be happy with that.
Regards, Paul.
I agree Paul - sorry for that. I would say you pointed me towards looking at it seriously and gave me confidence I wasn’t crazy when I liked it.
Funny enough, you prompted me to have a look back through your comments on French Connection (LON:FCCN) in the SCVR. They were actually much less positive than I had remembered which was interesting. Can’t quite remember now why I chose to add again in September other than it was cheap....
If Frasers / Mike Ashley were going to make a takeover bid, the smarter thing to do is hoover up shares at the 10p price until they get to 29.9%, and then make a bid. That way, only paying a premium on as few shares as possible.
Could be just retail investors all jumping in when they saw 10%, 15%, and additional volume. If you look at a swath of small cap shares at the moment, 5% to 10% share price movements seem to be the norm over the last few days. Just too much bored money in shares that don't have deep liquidity.
Agree, dahoko. The share sale only registered with me because it was so random. Why would Frasers want to sell 1%/ £100k of shares in a company that they own a blocking share of? The money isn’t material and if the objective is to start divesting surely they would have sold a larger amount before having to report to the market.
I know the bid limit is 30% so it made me wonder if there was another relevance to being below 25% I wasn’t aware of? Then I thought maybe someone else was being enticed to bid. Then I wasted half an hour looking at company takeover law. Then I got back to work in my day job. Then I dismissed the whole thing because I was just randomly speculating at this point.
Then the shares went a little bananas this week with no credible reason (even a rumor) I can see. My guess is that someone (not Frasers) is accumulating a stake for a bid. But expect to find out more tomorrow/ next week from either company RNS/ rumour mill/ declaration of sizeable stake.
This has been a small holding for me since Paul recommended last year but I’ve added to it on dips etc. and lovely to see a +106% beside it right now.
It should perhaps be remembered amongst all this euphoria that the shares were trading at around 60p just a couple of years ago, so for longer term holders they have been a disaster.
Hi millbank71
In answer to your question I think the Acquisition by Nvidia of ARM will be blocked by the CMA. ARM was the jewel in the crown of British Technology and it was a sad day when it was sold to Softbank in 2016. I sincerely hope the deal does not go through.
I hold NVIDIA. Why do you think it will be blocked. I can see why the CMA feel obliged to look but CMA is about monopolies and as these companies are in different areas both with competition, I am not sure the monopoly question is valid? For NVIDIA this is a bolt on that they are buying for a steal it seems to me. I get the concerns about British Tech etc, but this is a change of ownership from Japan to USA. so not really sure what the noises about UK governement intervention are about other than perhaps aspiration that it will come back into UK ownership somehow. My hunch is that there will be reassurances about no asset strip, no relocation and the deal will go through.
As a former shareholder I wanted your take on the price. $40B feels cheap when Softbank paid £31BN for it. It reads like a forced sale to cover other losses.
The stock price has barely moved since August. It feels like it is waiting for a decision.
If NVIDIA don't or can't go for it, someone will. Is there a UK player out there that might take it on. ARM will need a home, unless it is refloated.
Sorry SCVR board.. Yes I know this is not a UK small cap.....but then neither is Boohoo. :)
Maybe Boohoo should bid for it. They seem to like diversifying.
Hi Paul
Do you or any of the readers have any opinion on Hummingbird Resources (LON:HUM) ( I hold a few ) market cap small co approx £95 M
Quarterly results were out yesterday and the price has fallen almost 20% I think due to lower production figures.
Nevertheless the F score is 9/9 , P/e is under 3 ! and it passes 4 long screens.
Is this a bargain or am I missing something else ( geo political risk maybe !)
This was tipped as a takeover target in the new year at a much higher price.
Thank you
@Simon7061
Is this a bargain or am I missing something else ( geo political risk maybe !)
My guess is you've answered your own question there. They are mining gold in southern Mali. There's ongoing conflict in the north of the country and a recent military coup.
Thank you . I wasn’t up to speed on the recent coup in Mali . Am more aware of the politics in Liberia re new mine
@Simon7061
On paper Hummingbird looks very cheap (and a quality stock) but there is negative sentiment for the senior management, questions about life of the Yanfolila mine and a relatively high AISC ($149*) in the latest update. Anything over $1100 is unattractive to me. (Some of the projects do look good though, Kouroussa is ramping up to production and the Dugbe project has promise and is very large.) I also think Hummingbird's transition from explorer to producer was well executed. Open pit is better than narrow vein, so another positive there. I imagine the coup will sort itself out in time, but it's a negative at the moment.
I've bought small tranches of Hummingbird over the years, but it has never worked out for me. I prefer to buy and hold growth stocks that invest in trading stocks, which is what I think Hummingbird is these days. It's quite likely to bounce strongly from the low twenties - it always has in the past. I imagine the trading range is something like 23p-35p I'm not interested in it despite the promise it has, I think trust in the management is the problem. I hope this helps, gold miner investments are tricky things.
@Spglet
Thank you for your observations. Since my posting I did find some similar comments on another thread relating to the management and the AISC.
I rarely buy many small cap companies preferring a small cap fund such as Blackrock Smaller Companies Trust (LON:BRSC) as I don’t tend to outperform indexes , and hummingbird does now seem a little high risk to top up , but then again it does look tempting.
I think what has spoked investors is the increase in AISC to $1496 per oz - it was $983 per oz in Q2 2020 so a substantial increase.
Gold price is also falling so a double whammy.
It looked cheap a few months ago - 100,000 oz per year for a Mkt Cap of £100m - but AISC is now very high. Compare Shanta Gold at an ASIC of $870 per oz.
It costs HUM twice as much to produce and sell an oz of gold.
@yellowdog
Thank you .I have just posted a reply to some similar observations
I did hold EVE a while back Paul but not overly impressed by the latest CEO - there's a few videos on the web of her talking about the business. Emma and Simba all throat cutting to get sales.
I'd say keep your cash under your matress imo :-)
Good wishes
Interesting...I'll sleep on it.
Any views on Eco Animal Health (LON:EAH) Paul?
.
Intrigued to know why my question got thumbs down? Eco Animal Health (LON:EAH) released final results and half year and has jumped up 40%. Would have thought that was worth a comment seeing he discussed it here last June.
Perhaps the way you worded your question? Always good to put a please or I would appreciate?
More likely (than Caper's answer) I suspect is that you did not offer a personal interpretation or insight into why ECO Animal Health (LON:EAH) might be worth looking at.
It's a subject that I don't want to poke to much for fear of disturbing wasps, but :
To be honest I no longer know where I even stand on this 'issue', except that I don't think I care and just accept that some people are going to find upset for the sake of it and my sanity is probably enhanced by avoiding such people and environments.
Paul,
Have you thought of doing your letter and attaching it to a petition. There are lots of places now that automate the process of collecting signatures to judge from the number of petitions I now get from charities, political parties and so forth. A petition digitally signed by 1000 small /independent investors would really make a regulatory body sit up and notice. I don't think that would be hard to reach if You/Stockopedia back it.
Does Ed have a campaigning for the public good bit in the Stockopedia mission statement. It did Martin Lewis no harm in terms of free media if that makes it sexier for him!
Here's a good place to start, I've done a search and there is nothing similar currently active.
Get 10k signatures and the government responds, for 100k signatures they consider debating in parliment.
https://petition.parliament.uk/
Bad karma - deleted
Hi Paul, on the matter of Rules and Regulations and the possibility of any future changes being dubbed Big Bang 2.0 , I would ask the question as to why RNSs are released at 7am, just one hour before the market opens??
Could the RNSs not be released the evening before so as to give PIs more time to read them. I understand (but I may be wrong) the big institutions get access to this news information the evening before.
Paul as suggested by you I have just posted my letter to The Takeover Panel with a copy to Lord Lee concerning the current takeover provisions
In my letter I cited the takeover of ARM Holdings by Softbank in 2016. The Institutions had the knowledge of takeover discussions but the Private Investors were in the dark. Had I not sold my shares on 23 June 2016 I would have been £10,500 better off as a result of the SP moving from £10 to £17 when the RNS came out on 16 July. Still bugs me!
Portogull, do you have a view on NVidia pitch for ARM. Looks like they are getting it on the cheap to me.
Venture Life (LON:VLG), somewhat of a conundrum. Having revisited last September's interim report and re-read the recent trading update, I have become a little more circumspect.
As mentioned in an earlier post, the use of EBITDA, rather than pre-tax profits does make me a little uncomfortable. Also reading through last September's interims it appears that the company benefited considerably from the sale of 'Disinplus' hand sanitising gel as the pandemic took hold, generating revenues of £3.2m, which represents 34% of the total revenue of Venture Life brands of £9.2m during the period. I recall watching Creighton's presentation of its interim results on PI World, last December when Pippa Clarke, the marketing director said that the market for hand gels had become saturated. In fairness Venture Life (LON:VLG) have said that it does not expect to replicate similar revenues from hand sanitising gel in the second half, although it does expect demand to continue. Nonetheless I prefer to take my lead from the management at Creightons.
I also remain a little wary of the contract to supply oral care products to China. Historically Chinese companies have not always been paragons of good corporate governance. Finally I note the large increase in 'Trade and other receivables' contained in current assets in the unaudited accounts to the interims. This is shown as just over £10m versus £6.3m for the prior year. At present I have not found an explanation for the significant increase. It is possible that I have missed something, which wouldn't be a surprise.
The upshot of the above is that I have decided to exit my investment in Venture Life (LON:VLG) at a modest profit. The company is in rude health financially and may well make some successful acquisitions. It may well be that I have thrown the baby out with the bath water.
However I personally feel more comfortable investing in companies where I believe I have a better understanding of the business and its finances and which update the market with greater clarity.
These are just my views and I wish those who continue to hold and invest in Venture Life (LON:VLG) the best of luck
Venture Life (LON:VLG) : announce a miracle covid killing mouthwash one day and the next dilute shareholders - burn't and wary. Good toothpaste though.
Quote Paul Scott as of today
Eve Sleep
(I hold)
4.5p - mkt cap £12.3m
Just a quick note, as this share is high risk, illiquid, a total punt, with a very poor track record.
However, its recent trading update caught my eye as a possible special situation.
Look away now, as regulars here will know that my micro cap punts hardly ever work! I just can’t help myself sometimes.
I have been reading your column for years now and yesterday I went against all your red lines - Micro Cap , a penny share , illiquid only 4.5% free float , not making any money and probably will need to raise more equity , weak balance sheet , resources - it should be an absolute no no . However I had been trying to find companies that were tapping in to the new age of batteries particularly the metals behind them and the way that electricity will need to be stored in the future . I came across £CRCL (formerly Regency Mines ) who tick all of those boxes with three legs - nickel and cobalt mining in Papua New Guinea , Vanadium in Canada and flexible energy storage In Cambridge ( Burwell to be precise ) . Progressive Equity had just issued a research note and the company did a Q & A session yesterday morning . It is obviously a complete punt but the world is changing and on balance I decided to give it a go .
Let's hope that your punt and my punt are both successful
J Sainsbury (LON:SBRY)
Been pondering this since Pauls comments on 8.1. I am tempted.
Moreover
It is sitting below consensus forecast but at the same time has a pretty chunky and increasing short on it of >7% They can't both be right. Is it time for a squeeze. :)
It isn't a gamestop clearly but as the share price has gained since September at some point the shorters will have to start closing down their short won't they?
Would the short position be a useful addition to the Stocko sheets? I always check before I buy and have to go elsewhere for the info. I think this would be a really useful feature tbh.
Is that just me? DYOR and all that but a short particularly an increasing short serves me an alarm bell to at least try to work out why.
Hi Millbank,Had a big long in my SIPP ,but binned them on Tuesday .Its unusual to see such large short positions on a big Mkt cap .Short squeeze would have been nice - but have only seen recently on smaller Cos.Was worried about Lidl and Aldi nicking their margin - which is what analysts will be looking at.Like idea about a short section on Stocko and also section on takeover targets and a rationale.
I was thinking more likely related to the working capital and the low Z score. I am not convinced that Lidl and Aldi will continue to eat more and more. My experience when trying them was that you shopped in Lidl, queued for ever, then had to go to the supermarket next door to finish off your shopping for all the things they didn't have. My view is that their market share will flatten......eventually. Bigger question to me is whether demand for food will go down post covid and on this I am not sure. We used to eat out regularly. Now more into home cooking. I assume a lot of others thinking the same. I am therefore less cautious that the entertainment sector will recover as strongly as others hope beyond an initial bounce.
https://www.statista.com/stati...
Lidl market share steady 5.9% 12 months and Aldi went down 8.1 to 7.9%. They should have been growing with their openings. I suspect because folks going for premium stuff to indulge in lockdown and for a perception of safety with wider aisles but this is a guess. Question then becomes whether they will revert back.
Looks like the Co-op and Iceland have gained, I can understand the Co-op as people shop more locally in lockdowns. Co-op up 0.5%
I do most of my shopping at Aldi now, can most things and some are much cheaper but same quality. Service is better more efficient as well. They have opened a store nearer to me now, so it's more convenient and close to Morrisons, BME and Screwfix.
Lidl have improved recently, well the one nearest me has, had a total revamp, looks good but I rarely go there as too far away and very little I want from there.
J Sainsbury (LON:SBRY) : remember they have Argos and a bank. Also feel happier in their larger less crowded stores - a dichotomy there.
I think I prefer the anonymity of the nominee account.....
Having your name and address on a publicly available shareholders list strikes me as opening up a risk of being targeted by scammers who think "they must have a few bob".
I can see the benefits of being on the shareholders register under some circumstances, so perhaps it could be optional.
"I think I prefer the anonymity of the nominee account....."
All company Directors in The UK are sitting targets with their details all over the Internet. Not exactly a safe thing to do in this day and age. One day, someone will do a "Day of The Jackal" type thing with this.
You don't have to disclose your personal addresses on Companies House forms. If you put down a business address instead, nothing happens. Nobody checks.
"You don't have to disclose your personal addresses on Companies House forms. If you put down a business address instead, nothing happens. Nobody checks."
For investing, Limited companies, and I think that includes investment clubs, have to use this bullshit "Legal Identifier" LEI code.
When they first came out with this, we had to pay about £100 in fees to get this number.
Mercifully, they have not expired the number, so so far it has been a one off tax and inconvenience.
As the writer of the comment about the lunacy of the Nominee system, I would now add that i completely agree with you that being registration of ownership could be optional.
I agree with your proposals, Paul. What annoys me is that there is never an open offer to existing shareholders or if there is, a paltry one at best. Take SCE's recent one for example - 1 share for every 38 held.. what's the point?
I also think that if there is going to be an 'analyst call' then private investors should be allowed on it too. To me, it seems grossly unfair that institutions get privileged information before we do. Naturally, the company argues nothing "price sensitive" is disclosed in these calls, but if those on the call don't like what they hear they have the option to dump before the rest of us.
I did ask EQLS PR as to why this was the case and the response was "because it was an analyst call".
Maybe I'm in the wrong but it doesn't seem fair to me.
I agree Michael. It's a bit easier for me, because writing the SCVRs means that companies & their advisers are often quite keen to speak to me, create a positive impression, and answer any queries I have.
Whenever I speak to companies, I urge them all to engage with InvestorMeetCompany or PIWorld, to do results webinars for private investors, as part of their results roadshow. Quite a few have followed up on that, and been happy with it. Companies that have done so, tell me that they found it useful, and enjoyable to engage with private investors. The questions submitted are always really impressive too, just as smart as the questions from institutions!
I think places like advfn's bulletin boards do immense harm. Company Directors read them, and get the impression that private shareholders are deranged muppets! Hence sometimes they are not keen to engage, having read the often malicious claptrap posted on those bulletin boards.
IMC and PIWorld (and others) give a much better impression, and once companies are engaged with their PIs, they seem to want to develop that communications route. Hence when any of you talk to company Directors, then I urge you to encourage them to engage with us more & tell them how useful it is.
There's no reason why PIs couldn't join in analyst calls, maybe in listen-only mode if they want to prioritise questions from research analysts who want numbers to plug into their forecasting spreadsheets.
Or hold a separate investor event. Plenty of companies are now holding results calls which anyone can dial into, which is best practice I think. Advisers who stand in the way of this process are not helping anyone, and should be ditched in favour of advisers who get the company out there in front of as many investors as possible! The message is slowly spreading I think, so things are moving in the right direction.
Best wishes, Paul.
REVIEW OF LISTING RULES. I completely agree with your comments that it is not so much de-regulation that needs to happen (though a measure is always good), but an improvement in existing systems. Amidst your list is a reform of the Nominee system. Dead right! If we want a proper shareholding democracy, this system is lunacy. Among other problems, it deters many potential shareholders, because they don't feel they fully own their shares, and wonder (sensibly) how long it will take for them to get their money back if their intermediary goes under.
Does anyone know if French Connection (LON:FCCN) has been tipped anywhere? Quite significant moves the last few days.
FCCN Bid rumours it appears
I seem to remember that Paul said he would be unbearable when his position on French Connection (LON:FCCN) was proved right!
I think Paul put a £50m value on it but that was with covid weighing on the economy. That's what Debenhams was sold for. Topshop brands were sold for £330m. French Connection (LON:FCCN) at £10m seems way undervalued at current market prices. I hold.
Hi FREng,
I seem to remember that Paul said he would be unbearable when his position on French Connection (LON:FCCN) was proved right!
I'm not saying anything, as I don't want to jinx things! But, yes I will be! ;-)
Best wishes, Paul.
Wonder what caused the jump up 30% at the moment - may almost be breakeven!
Don't forget to check r/wallstreetbets on Reddit if you're looking for causes of mysterious share price jumps! :)
A couple of points about Venture Life (LON:VLG)
This has a reputation for issuing what one poster called "rampy" RNSs. So on Monday we had at the top a headline picked out in colour proclaiming "Full year profit ahead of market expectations" but when you looked they said "expected to be not less than £6m" - ah! but Cenkos forecast £6m back in November so not likely to be the 5 or 10% that normally warrant such a headline.
Secondly there was no news on the acquisition programme - 'Project Vulcan, Target A, Target B' teased in the highly dilutive P,O,O. @90p in November. Without that the cash will just sit there getting minimal interest.
The market was not fooled by the headline - there aren't many companies that end 10% down on a day they say profit ahead of expectations.
On Eve Sleep, I agree its looking very interesting at these levels with a market cap of £12.5m and net cash of £8m. New senior management team, focused on UK / France, with a mattress that is top rated by Which. As well as Online direct sales, signed up with decent partners, inc Next in UK and Olivier Desforges in France. Current 2021 forecasts look ultra conservative. Company kept beating guidance over past 6 months and would hope for the same this year (I hold).
hi Paul
on Intercede (LON:IGP) a quick question as you are clearly well versed on the share and it has been on my radar for some time.
It's an illiquid share and my primary concern is that CLN holders who are converted will look to exit with a 20% extra profit thus causing a drag on share price. Bondholders taking 8/9/10% p/a type interest coupons will generally be quite pleased with an extra 15-20% capital bonus on top so I don't expect sticky holders. Do you know if there are any lock ins on the conversion or if the CLNs are held by strategic investors and unlikely to sell?
I'm biding my time on any purchase as I'd like to see it somewhere towards conversion price personally.
thks
David
Hi David,
I was pondering the same issue re Intercede (LON:IGP) (I hold) new shares - i.e. whether holders who convert their loans would be tempted to flip the new shares for an instant profit.
I've made some enquiries, and whilst nobody can know for sure, it isn't expected to be a problem. Some of the loan note holders are existing long-term shareholders (e.g. the NED who has converted his, and now holds a whisker under the 30% maximum). So they're expected to remain long-term committed holders.
Apparently there's growing institutional interest in Intercede (LON:IGP) because it's moved into profit, the balance sheet is sorted out, and the prospects look good. Therefore if anyone did want to sell a block of shares, it would probably get snapped up by an institution, rather than being dribbled out piecemeal into the market.
Put that all together, and I think there's probably not a problem with any overhang of shares.
If you do want to sell a big block of shares in something illiquid, you don't hit the market bid, you just ring up the house broker and get them to find a buyer. That way the block changes hands, without affecting the market share price at all. They often have a list of potential buyers who want shares, but are not interested in buying piecemeal in the market.
Overall, I think the share price of IGP is currently about right. The company needs to demonstrate accelerated top line growth to power it higher. I've held since 2018, and am happy with progress so far, so intend holding for the foreseeable future.
Regards, Paul.
I'd personally love to hear your views on wider things - it makes one understand your view on the markets too. So please do have your rants and views and everyone else refrain from responding on anything else but shares, companies and markets. would that be acceptable? Cheers and keep up your great work and insights
On Venture Life (LON:VLG) I've bored people enough. I think that bar a bit of a magic trick the share will disappoint heavily from here. Sub 50p and potentially meaningfully below that once the true state of business and opportunities post the covid miracle out themselves -> hand sanitiser sales booked as high margin sales growth in 'brands' and the YUGE £120m 10 year China deal settle down to reality (not the exact figures as can't remember but ballpark).
Its true a transformational and accretive deal may come along with all that money shareholders generously donated at the same time as allowing the mgt to cash in a nice big piece of their holding at a high price (....could it be that the need for an exit for management lead to the idea of raising for "imminent accretive deals" and that explains why imminent deals are still not imminent? I might be over cynical here obvs...but its rather a neat way given prevailing stock and market sentiment at the time to liberate nice chunk of wealth at inflated price)
I may just be very wrong...but I have read the reports in detail and tried to tie things up.
See sceptical counter comments made in these promotional posts:
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
I'm like you on this one. There is something about the numbers I don't quite trust. I was kicking myself all the way up from 50p for not buying it and missing out but every time I looked I couldn't quite get past the massive China deal and the historic propensity for those to end up illusory. I was also concerned in the recent update that no more shipments to China in H2 but should resume in H1 of next FY.....why?
I also didn't like that management raised so much money whilst taking large swathes off the table themselves. That told me they were happy to raise at what they considered very high prices. My guess is they sold as a kind of reset. Ie we've done very well so lets crystallise the wealth. Raise money, then issue options later so if we can make acquisitions and repeat the trick we can get more; though perhaps that is being unkind.
I would contend with your sub 50p target though. They have 25% of their market cap in cash now so you'd need the rest of the business to be trading on 5* current year ebitda for that to happen and I think that's unlikely.
Maybe I'm too conservative/negative.
Here's why I get to sub 50p:
£35m cash equates to approx 27p cash per share. I value that down as I think the mgt have proven themselves a bit slippery. You may choose to value that up as you may believe they will do something "accretive". I am being harsh...but this is how a cycle of disappointment goes which I think Venture Life (LON:VLG) seem to be in early innings of (obvs I cannot really know and this is speculation by me).
Pre dilution eps of c.1p per share in 2019 which now equates to roughly 0.75p per share post dilution. IMO 2020 results are very flattered by what seems to be very high margin gains on selling 'generic' hand sanitiser opportunistically. I think that VLG could be a lot more transparent on that and disclose better. H2 results were down meaningfully on H1 yet probably still had quite a hand sanitiser boost. How to price this? I don't think most of that gain should be wrapped into future discounted earnings path. Then there's the Chinese gain that is huge but drifted away in H2. Maybe it comes back strongly and that would confound my sceptical outlook for sure and make me wrong...I just think investors should acknowledge a lot of trust being placed in what mgt say here on China (I personally think its highly unusual and odd to report a long term massive revenue stream for mouthwash to China....I don't think the other side has really contracted in earnest for that even if they are happy to say that to VLG and have them promote it...I bet there is no comeback for VLG if the contract 'fails')....
...so how much over 0.75p per share is sustainable earnings? If VLG are lucky they will have strong hand sanitiser sales in 2021 with good margins. I'd guess they will be weaker both in volume and margin (just think of all that supply that's come on line...H2 2020 probably benefited from elevated margin due to people desperately contracting in H1 2020) -> so if hand sanitiser sustains in the meantime before acquisitions kick in then VLG probably doesn't hit 50p and I'm too sceptical.....but its probably still downside and a share price that goes nowhere for years until the prove themselves (once bitten etc)
0.75p plus sustained increment in eps supports at least 23p of share price (given max 27p attributed to cash). How much multiple should a moderate or even disappointing small scale consumer product business get? 20x seems rich to me. VLG don't have the brand generation and sustaining power of P&G...and experience tends to say that little brand companies have brands that die or regress (see Brand Architekts (LON:BAR) , Innovaderma (LON:IDP) etc). Its not obvious this is a high multiple area. That said some may point to Alliance Pharma (LON:APH) as a comparison ....I think VLG doesn't scrub up to it.
My belief is that management opportunistically checked out big chunk of their shareholdings in 2020 and raised cash with a view to making a bigger business in next 5 years. All okay...but their emphasis is on making the business bigger in future for them (not really a shareholder value thing) rather than current biz extrapolating. The current share price is extrapolating fairly heroic earnings growth.
So a sceptical perspective by me. I'd note that current eps expectations for VLG are rather heroic IMO. 2020 in stocko of 4.43p may be distorted by average share calcs in that the big issuance came at end of year so doesn't impact the average. Then the implied step up for 2021 is a lot of growth....which sits oddly coming off of H2 2020. I think my logic is correct here but may be faulty and in which case pls correct.
(I regret ever spending time looking at VLG and now getting caught talking about it....I think this is my last comment on it for a while, at least until we see how things go....DYOR everybody!)
mojo hand-sanitised of VLG and out!
PS I'm natural sceptic with stocks...and sometimes that is the wrong perspective
PPS a Chinese order could appear in 2021 for £Xm...will it be durable or one-off? Obvs this is going to boost sp regardless of whether sustainable or not and make my 50p at least wrong on timing etc
The links here are to my posts.
I wrote positively during 2020 about Venture Life.
But the 2nd link to my 9th December post explains why I sold my shares in #VLG.
As I had promoted the company I felt I should also say that I had sold out.
Paul, I really like your list of issues to send to the new review of regulations for the UK market. And it is great that you will be using your credibility to encourage some sense. Can I add a couple of extras:
1. Replacing the nominee system with something sensible (a CREST type approach) should be easy and effective. And it should apply to SIPPs and ISAs as well share dealing accounts
2. Just to amplify your points about holding people responsible for malfeasance
* someone who is caught shop lifting can get a serious punishment or even in some cases go to jail
* a company director, a NOMAD or a firm of accountants who tells lies in an RNS or a set of accounts pocket the money and go off to live comfortably in the sun
3. Slightly off your focus as this relates to off market investments - The new internet age has allowed seemingly unregulated advertisements for extremely dodgy investment schemes that usually make excessive promises and then divert most of the investment money into the hands of the directors / advertisers. Mark Taber is great on pressurising the authorities on this but so far it looks as if nobody is listening
Again thanks for taking your time to do good
1. Replacing the nominee system with something sensible (a CREST type approach) should be easy and effective. And it should apply to SIPPs and ISAs as well share dealing accounts
This would be my number one recommendation , not only because a credible shareholder capital market requires that shareholders have a direct voice, but also, and as importantly, without our names on the register we will get more Beaufort Securities style scandals.
When the Minister (or whoever) gets to summon his civil servants to start in on this it is not subject to “a thorough in-depth review”, “consultation with all parties”, “ these changes must be gradually introduced” or any other civil service pablum.
Here is how the instructions should be handed out to the LSE and relevant civil servants: -
1. This will be introduced no later than 31 December 2021. This is a career affecting deadline and all salary raises are deferred until this is complete.
2. Do not - read my lips here - do not invent a new system, there are several out there already, license one of those
We should expect that it will be resisted by all kinds of entrenched parties and will require a steely determination to implement
It is a measure of my pessimism that I do not expect anyone to lift a finger to do anything, but I can dream can’t I?
Replacing the nominee system with a CREST type system, including ISAs and SIPPs would be my number one change also. The current system is flawed and retail shareholders should have clear, direct ownership with automatic voting rights and the right to attend AGMs without having to request a letter of authorisation. Surely it is not beyond the wit of all these great minds in finance and politics to come up with a workable solution.
1. Replacing the nominee system with something sensible (a CREST type approach) should be easy and effective. And it should apply to SIPPs and ISAs as well share dealing accounts
That would be desirable, but I'm not sure it would be that simple, and it would almost certainly increase costs. At present, of course, you can't have an ISA in a personal Crest account, and it would need a fair bit of enthusiasm and work by HMRS, and probably extra checks, to implement.
Alternatives would be things like
-forcing all brokers to pass on all shareholder circulars from companies, ensure voting and AGM attendence are easy.
- named nominee accounts for each client, making sorting out ownership much more striaghfroward, and quicker, after any serious problems.
But this will all cost brokers money, and clients will have to be prepared to pay.
Your caution and concerns are those that are frequently raised but my holdings in Australia appear to work smoothly without any knowledge of these worries. Maybe we can just ask the ASX to takeover the LSE
Alumasc (LON:ALU) (I hold) interims arrived this morning and duly delivered (in spades?) on the recent TA, which Paul kindly commented on back on 20 Jan.
Market likes them (again).
FinnCap note this morning - still undervalued. Debt almost gone and divi's nicely increased. Even the pension deficit seems to have materially improved. They have adj EPS for 2022 of 22.2p, (that's a lot of 2's!) which at today's 149p is still only 6.7x: this seems awfully low for something that is growing and treating it shareholders to a nicely growing dividend. The only fly in the ointment I can see is poor historic ROCE.
Stocko's computers give it 94, and super stock (rockstar!) status and it's a "tiny titan".
Outlook pretty positive - subject to (inspite of?) Brexit (new frictions), covid and cessation of help to buy.
Can someone puncture my optimism here and point to concerns?
If I had to pick holes in the #ALU interims I’d say that they state that “ Timloc, our Housebuilding Products business, continues to perform well. It really benefitted from the introduction of several new products across the last year and also from its acclaimed 100% OTIF delivery performance.”
If that division performed so well, why was revenue static?
Hi fredericktug,
Regarding "Can someone puncture my optimism here and point to concerns?"
I would point to the fact that since 2001 the share has gone sideways for the last 20 years. Back on the 5th Feb 2001 the share price was 129p, Twenty years later the share price is 144p. That's a gain of 11.6% over 20 years. That is the equivalent of 0.58% growth per year!!!
Sorry to puncture your optimism!!
Agree, the question here is growth? They have a few interesting products but they need one/two to be the "go to" and be material to get rev >150m. Forward ROE (21 as 22 not updated) looks OK. Lots of thin trade days but recent momentum, positive albeit short term.
Venture Life (LON:VLG)
Excellent summary ref this share Paul. As you specifically mention nothing ever seem straightforward when China is involved . I made the decision to trawl back through the main thread on the other place to see what the resident commentators there think about the company and the general consensus was that board seems to have "positive spin" with regard to most of the stuff they say - i prefer warts and all presentation of numbers myself . I do have to admit being very tempted here and the price looks right if we factor in the future acquisitions bring in decent extra profits - not reflected in current numbers. To be fair to the board generally speaking things have turned out quite well so i can see why they would be enthusiastic about the future.
I think a specific example of the positive spin coming from the company here is with regard to Pauls comments today.
Chinese order - if you recall, it previously announced a remarkable 15 year deal with a Chinese distributor for 168m Euros minimum. That orders dried up in H2 is a concern, as is everything related to China.
Technically they havent said the orders have dried up - they sort of said the opposite when they did comment in september !!- but i would side with your caution here - if they havent been delivered (and paid for probably too !!!!) then as far as i am concerned unless they explicitly advise otherwise (they chose not to) then its probbaly best to presume the orders have dried up depsite the fcat their direct comments indicate otherwise (unless i have misread the september comments - that is possible!)
What they said on 24/9/2020 which is well into H2
Revenues of £2.3 million delivered via our oral care partner in China (H1 2019: £nil), with a strong order book for H2 2020
I read this as confirming they had the orders to china for h2?? - so if i have read this right is it the case that shipping has simply been delayed (surely they would have told us) or something else - i guess if orders had been cancelled they would also likely have told us? - so that leaves me with the impression that the Chinese have been delaying things after booking orders whilst not fully providing reasons to VLG?? - no idea if they need to pay upfront but it might be as simple as that if thye don't have funds to pay. They might simply be pimping VLG if they have unkown demand - order it just in case it may be needed whilst knowing practicably speaking your prior order will probably do till the new year.
Anyway i doubt any sensible person would place too much store on the future China contract - however as its a contract it may well be baked into broker forecasts - so i would be interested to know if brokers have factored in any material revenues in this regard.
Final thoughts - does anyone who knows this business well have any thoughts on whether sales may have been temporarily boosted by covid related stuff. That would be my other main slight doubt here.
Overall though i am more positive than negative here - but i do have the devil in my ear shouting stuff at me.
Pretty clear IMHO that Venture Life (LON:VLG) should have updated the market much more promptly that the strong China orders book for H2 had turned to nought.
But they were in the middle of bigging up the shares to support a large fundraising and sell a considerable number of their own shares. So that didn't happend
Maybe I should not be linking these events together as I have, but Venture Life (LON:VLG) have now been added to my list of companies where I no longer believe I will get a true and fair picture of the business. Ended up exiting at a small loss but at least I won't end up worrying about this any more.
Hi Paul
1) Innovaderma (LON:IDP) has new management so it's not really comparable to judge the share performance over several years of different management teams.
2) You're right it is very small but adequately funded post placing and strong product brand. The upside is far greater than pushing it into £CRL.
3) It was doing very well up to the point of the pandemic (looking at 8-11p EPS). It's actually done reasonably ok during the pandemic given it has a lot of product on the shelves of Boots and Superdrug. ie its DTC model is gaining traction. Once we return to more normality their retail should go back to doing well.
4) US sales are starting to take off - from a low base granted but is interesting.
I am a holder and would far prefer to stick with Innovaderma (LON:IDP) as a standalone entity for now. Putting into Creightons (LON:CRL) is like giving away 80% of the potential upside at the low point of the pandemic cycle......that would be nuts imo.
Note the same guy that bought 10% of Revolution Bars (LON:RBG) also now owns 15% of Innovaderma (LON:IDP) and has taken a directorship. He and the board obviously thinks similarly.
So a big no thank you to Creightons (LON:CRL) at that price. I prefer the risk / reward as a standalone entity.
Innovaderma (LON:IDP) - Thanks David, very interesting, and your points make a lot of sense! That deserves a name check in the main article! :-)
Thanks Paul - I am indeed honoured :)
I've done the most detailed research on Dr Martens...my teenage daughter says the products are very popular with her pals .The same daughter who predicted the demise of Superdry by telling me "its for old fatties for you "
Hi, could you do a review of Zytronic cash offer to buy back shares from Shareholders please?
I have made a circa 40% profit on these shares and am thinking of selling at least a portion of these, as the spread is about 8% (if I remember correctly). So thought this would be a cost effective way of taking some profits, but I'm not an experienced investor so would welcome some advice.
thanks
dennis
Hi dennis,
I can't give advice, you need to make a decision yourself on what to do re the Zytronic (LON:ZYT) tender offer.
See Monday's report here where I reviewed the tender offer & Zytronic's most recent trading update.
Regards, Paul.
I would also note that the directors in Zytronic will not be tendering their own shares.
In full, the directors' recommendation from page 9 of the Zytronic (LON:ZYT) circular:
"The Board considers that the Tender Offer is in the best interests of Shareholders as a whole. Accordingly, the Board recommends that Shareholders vote in favour of the Resolution, as they intend to do in respect of their own holdings of Ordinary Shares representing, in aggregate, approximately 1.5 per cent. of the issued share capital of the Company. The Directors shall not however be participating in the Tender Offer.
The Board is making no recommendation to individual Qualifying Shareholders in relation to participation in the Tender Offer. Whether or not Qualifying Shareholders decide to tender their Ordinary Shares will depend, amongst other things, on their own individual circumstances, including their own tax position. Qualifying Shareholders are recommended to consult an appropriately authorised independent adviser in determining whether or not to participate in the Tender Offer and the extent of any such participation."
Dennis, you might like to research the tender offer that Rockrose Energy made before making your decision.
Silver
Thanks guys I will have at look at both of those pieces of information.
dennus
With regard to holiday bookings, a survey on a well known money saving site indicates that 44% of 8300 respondents have already booked a holiday abroad with a further 19% hoping to book. Only 16% indicate they do not intend to book anything this summer.
And what will the rules be:
I would like to be able to travel abroad this year but certainly don't think we will be back to anything like normal until the latter part of the year at best. Perhaps just in time for Paul to go to Malta if we are lucky.
Malta is probably the exception. I live there and we'll have most people vaccinated by April.
hi thanks paul for all your work..B.A and Virgin were offering cheap flights to the USA until midnight 02/02/21 .We snapped up a bargain for August.Spoke with the lady on sales and lots of people booking
"Just a quick note, as this share is high risk, illiquid, a total punt, with a very poor track record." (I hold)!!! Paul that is what we love about you.
Paul, Yours is an impressive list. Would you mind if I sent your list on to my contacts in BEIS and the Treasury? They serve as a useful addendum to @ShareSocUK response to Lord Hill’s consultation. I agree that they would make the UK market more attractive to investors.
The ShareSoc response and our Press Release can be accessed here. https://www.sharesoc.org/share...
Maybe companies could be persuaded to announce results etc after market hours? So everyone (esp non professional investors) can absorb & consider at relative leisure - rather than a mad scramble between 7am & 8am?
Morning Cliff,
Paul, Yours is an impressive list. Would you mind if I sent your list on to my contacts in BEIS and the Treasury?
Yes absolutely, please do. Thanks!
Regards, Paul.
Paul, an impressive list of faults that Hill could examine from off the top of your head.
MIFID and research: my understanding is that pre-MIFID brokers were able to charge fund managers research fees via commissions on trades. This led to these research costs by-passing the fund managers' P&Ls and going straight through to costs within the funds borne by the underlying investors. These investors would reasonably be of the view that they were already paying for research in the fund managers' fees.
Obviously, with such an arrangement there is no incentive to control this cost as the payer is largely oblivious to its existence.
MIFID outlawed the practise and research dried up as fund managers didn't want to pay for it. So, subject to free market economics the value of third party research was found to be negligible.
In my view, I t would be egregious to revert back to the old practise.
Hi shipoffrogs,
Yes that's my understanding of MiFiD 2 too. But was it really such a problem beforehand? I think the regulators devoted a lot of time & effort (for the city as well as themselves) on a problem that was trivial.
Wouldn't it be ironic if the UK's parting gift to the EU was to tie them up in knots, with mountains of regulations which apparently largely originated from the UK, then we leave and abolish it all here!
Regards, Paul.
£PSDL released their valuation and business update with a recorded NAV of 475p they are still at a 33% discount. The company basically buy and rents out living accommodation in Berlin
There's currently a 5 year price fix on rents in Berlin which is being challenged in court. If its successfully overturned (which it has been in some other German cities) then there some uplift (not quantified) in rents and I think the discount could close quite a bit.
I am long on this waiting for a rerating which I believe will come. Its also a relatively safe yielding investment in todays uncertain times.
We discuss clothing retailers a lot on here and it’s probably not surprising as it’s a sector we can all relate to that has been undergoing accelerated change due to the lockdowns. So, although not a small cap I find the placing by JD Sports Fashion (LON:JD.) rather interesting and perhaps indicative that the smaller companies are going to struggle in this sector generally.
JD Sports Fashion (LON:JD.) have raised £464M from institutional shareholders at a very small discount. I hold JD Sports but their ever increasing forays into overseas markets, particularly the USA, makes me nervous. The USA has been a disaster zone in the past for some UK companies. Tesco comes to mind. Purple bricks was another. HSBC and M&S also messed up there further back if I recall correctly. But some successes. Fevertree doing ok so far. Boohoo successfully revived Nasty Gal.
That the instis are happy to invest in JD in this way at this time while various other retailers are falling into administration makes me wonder if we are about to see a fundamental change. Perhaps the large network type effects of multi-brand on line retailers like ASOS and Boohoo plus the sub segment specialists with large economies of scale like JD Sports Fashion (LON:JD.) are becoming dominant forces on a scale we hardly imagined before. If you want to compete against these guys it’s going to be like going up against Amazon, Rightmove or Autotrader. The chances of the little guy ever achieving great success are looking slimmer and slimmer in this sector.
My morning smallcap tweet: Roc solid, Vertu motors
Water Intelligence (LON:WATR) Argo Blockchain (LON:ARB) Vertu Motors (LON:VTU) Sigmaroc (LON:SRC) EPE Special Opportunities (LON:ESO) Christie (LON:CTG) Panoply Holdings (LON:TPX) Duke Royalty (LON:DUKE), Eenergy (LON:EAAS)
Water Intelligence (WATR) increases credit facility by $3.2m in order to further accelerate growth for 2021. [SP=510 Cap=79m]
Argo Blockchain (ARB) buys 25% of Pluto Digital Assets for £1m. "Pluto invests in, incubates and advises digital asset projects based on decentralised technologies (DeTech), decentralised finance (DeFi) and networks such as Ethereum and Polkadot." "Pluto shares the same ethos as Argo." What? Making money? [SP=94.12 Cap=338m]
Vertu Motors (VTU) guides FY(Feb) adj pretax above mkt forecasts of around £18m. [SP=33.2 Cap=123m]. I hold.
SigmaRoc (SRC) guides FY(Dec) rev c. £124m up 77% and EBITDA c. £23.8 up 64%, ahead of market expectations. Cites particularly strong demand for RMI and infrastructure products. [SP=64.2 Cap=179m]. I hold.
EPE Special Opportunities (ESO) Jan NAV/sh 437.63p up 38%. NAV end Aug was 345.7p. [SP=263 Cap=87m]
Christie (CTG) stronger trading leads to an op profit in H2(Dec). Agency & Advisory practice seeing increased demand insolvency practitioners whilst business buyer demand remains very strong. Expects FY21 to be H2 weighted. [SP=87.63 Cap=23m]
Panoply (TPX) wins contracts in partnership with Mastek worth over £7m over 2 years. [SP=161.75 Cap=112m]
Duke Royalty (DUKE) Q3 cash rev £2.5m plus cash gain from Wellyel equity sale £1.7m. Guides Q4 cash rev £2.5m . [SP=26.6 Cap=69m]
In line: Eenergy (LON:EAAS)
£vtu positive update. Confused by them saying exceeding analyst expectations of £18m, as according to stockreport. these are £14m. Maybe they mean £18m? Either way very impressed and I hold
February trading continues to be impacted by the national lockdown which restricts sales activity. Whilst uncertainties remain over the trading performance of the Group for February and into the next financial year because of the ongoing COVID restrictions, the Board now expect that the trading result for the year ending 28 February 2021, at an adjusted profit before tax level, will exceed the current Analysts' forecasts of around £18m.
The £18m they refer to is BEFORE tax, so probably ~ £14m post
you are correct Sir, my error
Thanks for this. The news feed in Stocko seems to omit some updates (eg Bushveld) so its great to have a back up! However Royal Dutch Shell (LON:RDSB) does not seem to be in either?
I think the earnings call is at 2pm GMT today