Small Cap Value Report (Thu 4 May 2023) - VINO, ZYT, MGNS, NXT, MTC, SNWS, AT.

Good morning from Paul & Graham!
Today's report is now finished, at 12:51.
We're planning on having a backlog clearing day today, so probably shorter sections in this report, to cover more ground.
I see US interest rates went up yet again yesterday. My view remains that this is reckless, and very damaging, plus there's no democratic accountability for this powerful role of central banker - and central banks are notoriously bad at setting rates anyway - far too low, for far too long, causing all sorts of distortions, and now overly rapid increases seemingly in a bid to crash the economy in order to remove inflation which is already falling. It doesn't make sense to a humble shares blogger here anyway, and isn't going to exactly help the pressures on the banking system either. Oh well, we'll just have to see what happens.
With "risk-free" interest of 5%, all of a sudden a 5% dividend yield from shares doesn't look enticing any more. So for the first time in c.15 years, equities are now competing for peoples' savings with decent returns on cash deposits (below inflation, but probably not for long, as US inflation is falling quite rapidly, and ours is set to follow suit from the summer, according to the Bank of England). This doesn't seem a positive backdrop for equities. Or, will this just be a short-lived spike in interest rates? If so, then equities could still be a good place to invest. It will be fascinating to see how all this pans out!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Summaries
(larger sections below)
Mothercare (LON:MTC) - down 20% to 7p (£39m) - Trading update - Graham - RED
Terrible news here as the company needs to once again seek revisions to its loan. This is just a £19.5m loan but it’s currently charging over 18%. It also needs to hope that pension deficit payments are revised lower. I view this as a bargepole stock in its current form.
Smiths News (LON:SNWS) - down 4% in 2 days to 51p (£122m) - Interim results - Paul - GREEN
Good numbers, and only 5x PER. Lovely 8% yield, that could rise further once bank restrictions are lifted. Balance sheet is adequate for a capital-light business. I ponder the various scenarios for the future, of this slowly declining business. Overall, the value/yield win through for me, but only just!
Ashtead Technology Holdings (LON:AT.) - 384p (£296m) - FY 12/2022 Results - AMBER
Excellent numbers for 2022, and a "materially ahead" outlook for 2023, no wonder the share price has been so strong of late. Although in the section below, I ask some questions about how it's possible to earn such large profits from an old, small hire fleet, and whether those profits are sustainable? Note it was a private equity float in late 2021 - but so far looks much better than its contemporaries from that sour vintage!
Quick Comments
(no additional detail below)
Virgin Wines UK (LON:VINO)
39p pre-market (£22m) - Profit Warning - Paul - AMBER/GREEN
Another profit warning today from this Virgin branded subscription wine service. The announcement mentions all the things that are being done to improve the position, and some signs of trading stabilising. Plus there are signs of inflationary pressures easing. But the bottom line, literally, is that u/l PBT profit guidance for FY 6/2023 is reduced again, to £0.5-1.0m range (Liberum previously forecast £1.7m PBT). It’s confidently expecting a return to double digit sales growth in FY 6/2024, and EBITDA also rising - which strikes me as optimistic. Although the current year has suffered from warehouse disruption after an IT project went wrong, impacting operations, and that should be a one-off.
A bearish view might be that with profitability having almost evaporated, and the pandemic boom long gone, maybe this is just a marginal business with little value to shareholders? A more bullish view might see potential for a recovery, and with a market cap of only £22m, that could provide nice upside for a say 50-100% bounce in this share at signs of things improving maybe? I reviewed its interims here in March. Note the strong balance sheet, so there’s no solvency or dilution risk in my view.
Paul’s opinion - it’s getting into buying range I think, so any further plunge from today might be an opportunity, for knife-catchers! The business is still profitable (just), and has sound finances. Note Gresham House owns 41%, and the CEO 8%, so unofficially the business might be up for sale to a bidder, perhaps? I’m viewing this as amber, but leaning towards green if it drops further, as a value/recovery trade.
Zytronic (LON:ZYT)
Down c.30% to 98p (£10m) - profit warning - Graham - AMBER
This touch-screen maker issues a trading update for the H1 period (ending in March) and for April. Unfortunately, the issues that have dogged it continue to do so and conditions are now apparently even worse, with “unpredicted significant turmoil in its Gaming market”.
One customer is said to have overstocked Zytronic’s curved touch sensors, and might not have any more orders until the next financial year (FY September 2024). Meanwhile, other customers are suppliers to a company called Aruze Gaming, which is in bankruptcy. An article on casino.org suggests that Aruze should be able to bounce back, but I’m not sure how long that might take. The hit to Zytronic includes the loss of expected orders in H2 and the loss of existing receivables/work-in-progress (£0.5m value). Hopefully the situation will go back to normal in FY 2024?
New expectations: revenues of £8 - 8.8m this financial year. That compares to £12.3m last year and expectations before today of £13.5m. There will almost surely be another loss on the income statement
It’s a huge slash to estimates and while the problems might just be temporary, I can’t help worrying that there could be more fundamental problems relating to competition or demand. With £5.4m of cash I can’t give this stock the thumbs down but I’m not entirely sure that the core business can support the enterprise value here so I stay neutral. As a punt on eventual recovery these shares could have merit.
Morgan Sindall (LON:MGNS)
Up 2% to 1733p (£821m) - trading update - Graham - GREEN
I don’t usually cover construction/regeneration companies, but this one popped up on a screen for me recently and I’m curious to see if it’s as good as its metrics suggest.
Today’s update is in line with expectations (for FY December 2023), with more of a first-half weighting (this is more reassuring than a second-half weighting!). General conditions have “continued to ease, with inflation falling in certain areas”.
Performance by division is generally good. I like the way management mentions how much capital is employed in some of the divisions - they could expand this.
Order book - the “secured workload” is £8.8 billion, up 4% since year-end, and up 2% versus the prior year.
Average daily net cash - as noted previously by Paul, Morgan Sindall is one of the companies that reports its cash balance according to best practices, instead of using a (potentially window-dressed) period-end balance. Average daily net cash for the first four months is £281m, very slightly higher than last year.
Management - the apparent quality of this construction group, if true, is likely related to the fact that it's run by a founder, John Morgan, who still has plenty of skin in the game with a 7% stake.
My view - I admit that I haven’t studied this stock in detail but I’m going to tentatively give it the thumbs up based on its quality metrics, the clarity of its reporting, stable management, and a solid track record. It’s cheap too, with a PER of 7.5x, contributing to a StockRank of 94.
Next (LON:NXT)
Up 2% to 6648p (£8.5bn) - Q1 TU - Paul - AMBER
We usually try to look at this fashion bellwether, for context when the smaller ones report - it's often striking how other companies in the sector blame all sorts of macro issues outside their control, which Next seems to cope with effortlessly!
Q1 saw full price sales (not the same as revenue, but this is how Next always reports) down -0.7% vs LY. Not good, when inflation is c.10%, and selling prices have risen, so this must be a significant drop in volumes of clothing sold. However, as always, Next guides expectations superbly, and this -0.7% is better than its expected -2%.
Profit guidance (PBT) for FY 1/2024 is maintained at £795m, 502p EPS, so a PER of 13.2, which looks about right to me.
Outlook is cautious at -5% drop guided for Q2 sales, due to tough prior year comps (which benefitted from pent-up demand after lockdowns ended).
Expected sales this full year are guided at up 18.7% vs pre-pandemic, which is good, but needs to be good, because a lot of costs have risen in the last 4 years.
Paul’s view - NEXT shares look priced about right to me. It’s good to hear nothing horrible is going on, and I imagine it might be nudging expectations upwards as this year progresses. It’s not really a growth share thought, with the trend of EPS being essentially flat over 8 years from 2018 to 2025 forecast. I think this is a very good share to trade - it always bounces back after large drops.
Paul’s Section:
Smiths News (LON:SNWS)
51p (down about 4% since results published yesterday morning)
Market cap £122m
The numbers from this newspaper/magazine distributor look pretty decent to me, in the context of what is a declining volume business (unless they find some other products to bolt on to this rapid overnight delivery network).
We’ve followed the turnaround story of SNWS here in the SCVRs for several years, and it’s worked very well - all the legacy issues (e.g. pension deficit, excessive bank debt, problem Tuffnells division) dealt with successfully. It’s now a financially stable business, paying bumper dividends. The only question is, how much longer can it keep this up, given the declining circulations of newspapers/magazines? It’s already surprised the sceptics though, with cover price increases offsetting volume declines for now, but not likely to repeat.
The bull argument is that this business could possibly continue for many years to come, and even get transformed if it identifies & exploits other product distribution niches.
H1 to 2/2023 numbers & my comments -
Clean profit figures, no adjustments this H1.
Revenue up slightly, to £550m for H1.
Very low gross margin of 6.9%, which keeps out competition, and means this business is all about efficiency and keeping overheads minimised.
H1 Profit before tax (PBT) is £17.1m, up 12% on LY (adj)
Diluted EPS is 5.3p, up from 4.8p H1 LY
There’s not much seasonality, so this means the 10p annualised EPS figure mentioned previously by management as being a reliable expectation, looks intact. PER is only 5x - very cheap, if earnings can be sustained at this level (a big “if”!)
Balance sheet - not the best, with negative NTAV of £(27)m. However, there’s very little in fixed assets, and low inventories (since product mostly comes in & goes straight out again to customers). Therefore it doesn’t actually need any net asset backing.
Working capital is a large debit (receivables from customers, which I can see approximates to about 1 months revenues if you add VAT), which is fine. That’s mostly offset by a large trade payables number. All as I would expect, nothing untoward about this balance sheet.
Net debt - great to see SNWS adopt best practice that I’m delighted to see slowly emerging in company reports generally, in providing the average net debt (I presume daily?) of £26.3m, down 55%. This is a much more reliable number than a one day snapshot at period end, which is £22.9m. Shareholders don’t need to worry about this modest level of bank debt, although I see the divis are still restricted to £10m pa under the current banking arrangements.
Outlook - looks fine -
On-track to meet market expectations for the full year
Good visibility from contracts renewed to 2029+
Dividends - broker forecast of 4.13p for the year equates to about £9.7m total cost, so they might pay a little more than that. The company indicates it intends to pay £10.0m in divis. This is about 2.5x covered by earnings, so this c.8% yield could rise considerably, once the bank has been paid down enough to remove the restriction. Is that yield sustainable long-term though? Possibly not.
Yield is therefore a big attraction, although less so now that we can earn a 4-5% risk-free return on cash.
Contractor model - I have misgivings with the business model SNWS uses - it doesn’t employ the drivers, they are self-employed contractors. So there is a risk, even if only small, that HMRC might take issue with this, and deem them to be employees - which of course would involve having to pay employers NICs, which could be a big number if it’s back-dated. It’s up to you to assess this risk, I’m just saying it’s another reason why some people might be a little wary of this share maybe?
M&A - interesting that the company spent £0.6m on a deal that did not proceed. Previous management made a disastrous mess of M&A, which almost brought the company down, and took years to fix. So I can understand that current management have been wary of any new deals. Although that’s got to be the way to turn this share from a cigar-butt with a few big puffs left, which could remain profitable for a few more years, into something with a more sustainable long-term future. Hence I think M&A could be key.
Product lines - this is helpful, but not a game-changer -
In addition, we continue to pursue our strategy of exploring and trialing new profit streams from a range of adjacent opportunities that complement our core operations. Notably, in the period, we have increased the supply of DVDs and books to leading supermarkets and will be reviewing the potential for similar offers across our customer base. Meanwhile, the additional rental income we secured in FY2022 from third party logistics suppliers has repeated and continues to make a small, but welcome, contribution to reducing overheads.
Cost-cutting - a lot of the costs are variable, so the business model does allow for gradually declining revenues. However, I remember asking previous management how long they can keep stripping out costs? The answer did ring alarm bells. They said that depots had been closed, amalgamated, thus driving out costs, but that process had almost reached its natural end point, with any further closures not being realistic due to having to cover an entire geography within a certain timeframe for overnight deliveries. So it will be increasingly difficult to drive out fixed costs. Hence I’m worried (and clearly the market is too) that 10p EPS might not last much longer.
Competition - with supermarkets, big retailers, and Amazon developing increasingly large & fast delivery networks, combined with gradual decline in volumes of newspapers & magazines, I wonder if SNWS will still be needed, or still even exist in 5-10 years’ time?
Paul’s opinion - I’m moderately positive, but it’s difficult to see much upside on the current share price of 51p, and the PER of 5x. Although there are catalysts - if the banking arrangements see the limit on divis removed, then the yield could go well into double digit %s. If management launch some other initiative, or make a good acquisition or two (without dilution), then this could morph into a bigger & better business. Possibly. Or they might gear up for an acquisition that goes horribly wrong, as previous management did.
Overall, I’ll give my opinion as still being GREEN, but only just!
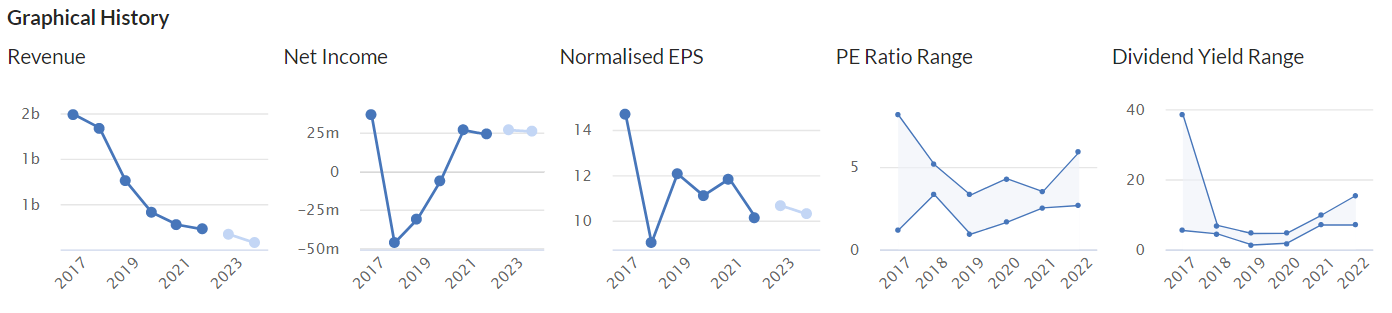
The Stockopedia graphs tell the story very well - structurally declining revenues, a painful turnaround succeeded over 4 years, EPS held up well thanks to cost-cutting, a permanently low PER, but divi yield returning and now very generous.
The algorithms love it - a StockRank of 99.
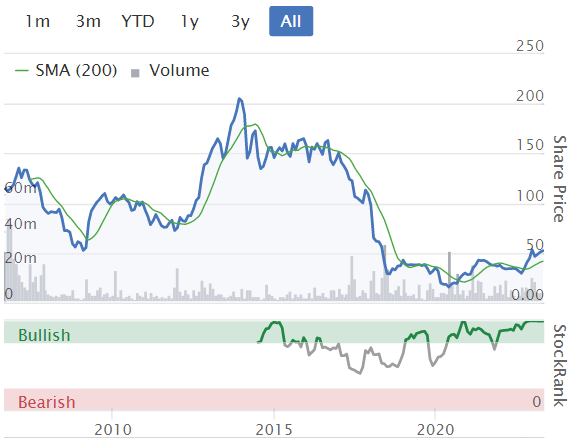
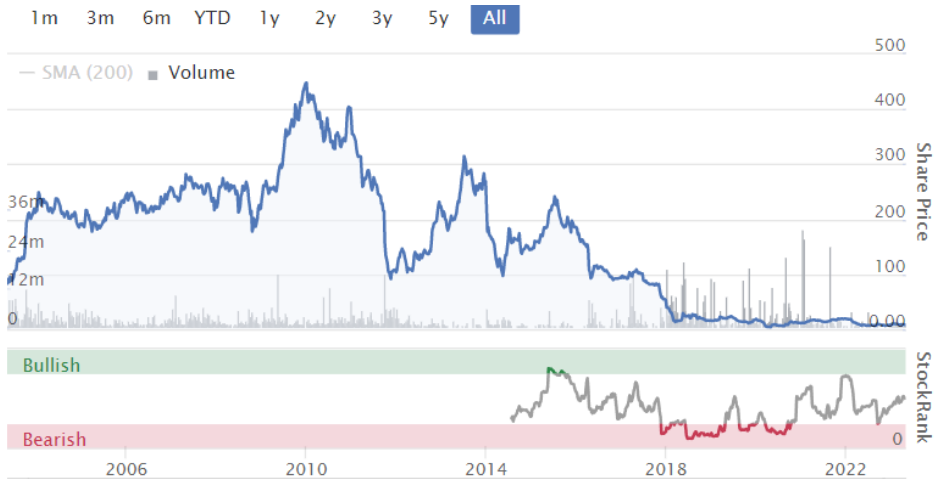
Long-term chart below looks nice, with a multi-year base put in. The share count hasn't changed much, so no dilution adjustments need to be made to the chart -
Ashtead Technology Holdings (LON:AT.)
384p (£296m) - FY 12/2022 Results (y’day) - Paul - COLOUR
Ashtead Technology Holdings plc (AIM: AT.), a leading subsea equipment rental and solutions provider for the global offshore energy sector, announces its full-year results for the period ended 31 December 2022…
This share has been doing very well, so I must take a look.
FY 12/2022 Results -
Good organic growth, powering most of the +31% revenues of £73.1m
Adj EPS up 48% to 19.6p = PER of 19.6x
Bank facility increased in April 2023 to £100m (+£50m accordion).
Outlook - all sounds good, with strong demand, pricing & utilisation up. Passing on inflation to customers.
“Materially ahead” of expectations for FY 12/2023 so far.
InvestorMeetCompany webinar is on 12 May, at 11:00 - so might be an interesting one, to find out more about the company.
Balance sheet - very little asset backing, NTAV is only £9.8m.
The figures look odd for an equipment rental business - there’s only £32m in fixed assets, and hardly anything in inventories. So how is it possible to generate £16.6m PBT from such a slim asset base? Wouldn’t competitors just buy some similar kit, and rent it out cheaper?
Note 11 shows that Ashtead’s assets were old in 2021: £105m original cost, but £86m depreciated, so NAV only £19m. That has been boosted in 2022 with £13m additions, so NBV of the hire fleet was £30m at end Dec 2022 - which still seems very small to be so highly profitable. Hence these figures look odd to me, and more digging would be needed on how a small, old fleet of equipment, makes so much profit, and is that sustainable?
It looks as if this company might be getting a bonanza from possibly offshore energy, wind farms, etc? Will that last, or will competitors move in?
The only company like this that I’ve seen before, is Gulf Marine Services (LON:GMS) which got into trouble with too much debt.
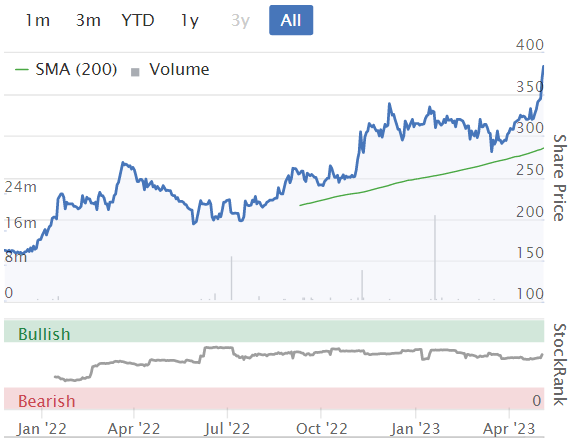
Broker consensus forecast has been rising, probably helped by a £24m acquisition made in 2022, and increased capex. I can’t find any broker notes.
Paul’s opinion - the numbers certainly look interesting, so I think this would be worth members here researching it in more detail, to properly understand the business model, and whether the spectacular returns currently being generated on a small, quite old fleet of equipment, are sustainable? As it’s not something I know much about, I’ll sit on the fence with an AMBER view for now.
Buckthorn Partners (private equity firm) owns a dominant 35%, and it looks like this float in Dec 2021 was selling shares to a variety of institutions. So that's a bit of a warning, as such floats often go wrong. In this case though, no sign of any trouble so far, quite the opposite actually, with this "materially ahead" trading update, and excellent numbers for 2022.
Graham’s Section:
Mothercare (LON:MTC)
Share price: 7p (down 20%)
Market cap: £39m
I can’t find detailed comments on this in the archive since Sep 2021 when Paul looked at it. Today we have a full-year update for FY March 2023.
Sales by franchisees are up 8%, excluding Russia. However, Russia was a very significant contributor in the previous year, responsible for nearly a quarter of franchisee sales and for £5.5m of adj. EBITDA, nearly half of the £12m total!
In FY 2023, without any contribution from Russia, franchisee sales are down 16% and adjusted EBITDA falls to just £6.5 - 7m, which the company describes as “ahead of analysts’ expectations”.
At least the deficit at the pension scheme has reduced from £78m to £39m, though net debt increased slightly to £12m.
The company continues to use the scientific phrase “steady state” to describe the profitability that they will experience “in more normal circumstances”. However, according to Paul’s article from 2021, their steady state at that time involved more than £15m of operating profit.
They are currently saying that this figure is only £10m. Maybe the steady state isn’t so steady after all?
Loan facility: the company has a £19.5m loan from Gordon Brothers at 13% over the overnight rate, plus another 1% that accrues and rolls into the principal. The rate is currently an eye-watering 18.2%.
I have checked the most recent annual report and found that the terms attached to this loan were already revised to take into account the loss of Russian business.
But with rising rates and slower post-Covid trading than anticipated, another revision/refinancing is in the works:
…the Group may require waivers to future periods’ covenant tests. We have therefore commenced refinancing discussions with our lender to vary, renegotiate or refinance this debt facility. Additionally we are looking at various financing alternatives (including equity and equity linked structures) to give us both additional flexibility and reduced cash financing costs. For the avoidance of doubt the Group does not require (and is not seeking through this refinancing) additional liquidity.
The reference to not needing additional liquidity is designed to reassure investors that they aren’t about to run out of cash. However, breaching covenants can have serious ramifications, typically including the possibility that loans get called in - I don’t know if that is likely in this case, but waivers to covenants are always a serious situation.
To help give you some broader context, there is a NED at Mothercare who was CEO of the company from 2014 to 2020 (a period of time which saw a near-total collapse of the equity value of the company). He is also currently a senior MD at Gordon Brothers, the lender to Mothercare. I wonder what he makes of the current situation?
Pension scheme - the Gordon Brothers loan would be bad enough, but there’s also the pension scheme to think about. The current plan involves deficit recovery contributions of £7m in 2025, £8m in 2026, and £9m p.a. after that.
Hopefully contributions of this size won’t be necessary, as the deficit appears to have fallen since they were agreed. However, if these contributions were necessary, I would have very little confidence in Mothercare’s ability to make them without an equity raise.
Chairman’s comments appear to have a level of positivity and optimism that is detached from reality:
“Once again our results demonstrate the resilience we have introduced to the business over recent years, where we continue to generate both profit and cash…
Although our immediate priority remains to support our franchise partners as they emerge from a period of suppressed demand, ultimately for the benefit of our own business, we have also redoubled our efforts to restore critical mass.
My view
This one is getting the thumbs down from me. It looks extremely risky with lenders and the pension fund circling nearby, ready to gobble up any cash flow generated by the slimmed-down business.
Depending on how negotiations go, an equity raise may be needed in the short-term, in order to satisfy the lenders (and perhaps to pay into the pension fund, too). Buying shares in an equity raise at a low, low price could make sense, but I would never want to buy in before that happens.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
US Regional Bank crisis seems to be getting worse and worse. PacWest Bancorp (NSQ:PACW) seems to be next. The US regulators need to come up with a better solution quickly. A temporary insurance of all deposits until a new insurance deposit scheme is put in place appears to be the only solution according to Bill Ackman.
Thanks Paul for your superb update on Smiths News (LON:SNWS) today. I won’t see analysis anywhere near as good anywhere else, and that applies across the board.
It’s the double digit dividend yield at my 40p buy price that probably makes it worth continuing to hold, though it’s a bit disappointing that it could be 2025 before the dividend can be increased unless debt reduces fast.
Ashtead Technology Holdings (LON:AT.) I think the stocko shareholder info is out of date. There have been two secondary placing and according to the company, Bidco (the PE vehicle) holds only 9.2%.
Ashtead Technology Holdings (LON:AT.) Yes there was a placing in January, 2023, but the Stockopedia info. has not been updated.
Keywords Studios (LON:KWS) any idea why the share price is down around 14% over the last 2 days, now down to 2300p? Can't see any news.
Keywords Studios (LON:KWS) any idea why the share price is down around 14% over the last 2 days, now down to 2300p? Can't see any news.
I'm surprised as well. One factor depressing prices in several areas this week is the threat of ChatGPT and other AIs to business models. I'm not sure how this would impact Keywords (quick and easy localisations, perhaps) but it's plausible that such fears are behind the falls in Relx (LON:REL) over the same period, and absolutely certain that it has hit sentiment on Pearson (LON:PSON).
Follow up to previous reply
Keywords Studios (LON:KWS) any idea why the share price is down around 14% over the last 2 days, now down to 2300p? Can't see any news
Yes, it’s the threat of AI to game developers in general and gaming services in particular that has investors worried. Covered in the FT today following analysis by Citi. The alternative, glass half full view is that, far from disrupting them, it might make it much easier for incumbents to develop new content.
Ive traded Ashtead Technology Holdings (LON:AT.) a couple of times. They have in the past used positive trading updates to place shares from selling shareholders. This can knock the share price and hold it back short term at least. I sold my shares this morning for just this reason, will wait to see if management sell any more this time.
Trading update 30th June 2022. ....4th July Placing of shares (BP Inv Newco/ Arab pet. sell 10m)
Trading update 10th Oct 2022.....8th Nov Placing of shares(Arab Pet. sell 6m)
Trading Update 16 Jan 2023......18th Jan Placing of shares (BP Inv2B sell 15.4m shares. Chief Executive Officer and Chief Financial Officer also sell shares)
This hasnt held the share price back longer term , and theyve sold at higher prices each time but something to bear in mind. Im always wary of large CEO sales especially after 2022
The private equity backers of Ashstead Technology (AT.) have sold down the vast bulk of their stake since the November 2021 IPO when they held over 50% of the group. According to the company’s website they still remain the single biggest shareholder with a 9.2% stake equal to 7.3m shares.
However, their importance on the share register has been greatly reduced by the arrival of 11 well known institutions, led by the likes of Fidelity, Aberdeen and Amati, which together now control 55% of Ashstead’s equity.
Many much bigger and more successful companies must envy the roll call of respected city names that have been recruited to Ashstead’s share register after such a short time as a public company. The company has clearly convinced many professional investors that its impressive early performance is not a temporary phenomenon. There could be some seriously red faces if this were to prove to be the case.
Since the IPO at 162p, when the private equity backers sold 22.25m shares and the company raised £15.5m in new money by selling 9.58m shares, there appear to have been three occasions when private equity backers and directors have placed shares at ever higher prices.
According to my rough calculations they were as follows:
July 4, 2022 10m shares @ 200p - 10% discount to the share price
November 9, 2022 4.8m shares @ 260p - 18.9% discount
January 19, 2023 15.5m shares @310p - 5.8% discount
The placings have often occurred shortly after a positive trading update, so it would not be a great surprise if Ashstead’s private equity backers used the current share price strength to dispose of their remaining stake at a modest discount to the current share price of around 375p.
For those of you who might be interested, I have received a response from the CEO of the company who has taken over Investegate after I expressed my deep dissatisfaction and frustration, and that's putting it mildly, at the botched upgrade that took place last weekend and this is his response.
Investegate Contact Form
Dear Noel,
Thank you for your contact form message.
I am genuinely apologetic for the experience you have had with the new version of Investegate this week.
Please be assured that we will soon have the elements that users expect to see up and running soon.
I am now able to share with you that the reason for the current change is that Investegate was scheduled to be decommissioned by its owners and we managed to acquire and therefore rescue the platform before a deadline for that. We did what we could given the pressure to decommission the site.
We only had a short time to try to understand and rebuild the very old legacy infrastructure and get a version of Investegate up and running before it was turned off for ever..!
Now we fully own Investegate and understand your needs better, we can rebuild Investegate with the new branding and the functionality you are more used to.
We can and will bring back the elements you would like reinstated whilst making some positive improvements along the way also.
It has been a hard and immense task for our team to do what we have done in a short space of time and we are all working as hard and fast as we can on updates happening over the coming days to bring back most of the features you know and love. The data feeds are working well now and the site is fast and stable and more improvements are on the way.
Thank you and please accept my personal apologies for the last few days experience. I was extremely frustrated at not being able to explain the reasoning for the change until now.
Things will only get better from now on, so please bear with us over the next few days.
Kind regards,
Paul Roberts
CEO
Read into that what you will. Fair play to Paul Roberts, at least he had the good manners and decency to respond personally. It's not everyday one receives communications from Company CEO's apologizing for things that have gone wrong and promising to improve and enhance the current customer experience, which lets face it isn't very good.
Er - really sorry but it wasn’t a personalised reply. That was the same text sent to all registered users today ☹️
Fair enough. At least some people who aren't registered users will have an opportunity to read it now, having shared it with a wider audience. So, I guess that's a good thing.
Morning Paul
Thanks for your macro outlook.
Your points all make good sense. I do not think it any surprise that the Fed increased by another 25 points. They signalled this. They are determined to reduce inflation substantially and the numbers coming out of the economy; especially the jobs figures haven't so far given them a reason to reconsider. Obviously the increase in interest rates takes some time to play out so only presents in the numbers quite some time later, which is clearly a concern. Hope the plane doesn't fly straight over the airport!
I agree income seekers getting 5% on deposit without risk is competition for investors looking for income, however it is not competition for most growth stocks which do not produce a dividend. I know the cost of money is higher when interest rates are higher but cash generative growth companies with cash on the balance sheet do not need to borrow or raise funds. Many of my investments fit into this category.
Hi Paul - please can we have your thoughts on Cambridge Cognition Holdings (LON:COG) results?
Sure, I'll try to comment on COG (I hold) tomorrow.
Hi Josh,
I hold also and am interested in Pauls thoughts. I think like some other high growth companies, Cambridge Cognition Holdings (LON:COG) has reported in line (even slightly better) and forecasts for the next few years are strong, but this is all expected news so it hasn't moved the SP. This lack of SP move is then causing some retail investors to get jittery and drip feed out of the stock on low volumes.
Personally I do not think there will be a significant move upward in the SP until evidence of the "several major deals" starts to come through on the RNS and investors get a feel for what value is attributed to them. I think until the first big contract announcement comes the SP will slowly continue to drift down, with a big pop up if and when the big contracts start to flow.
At least it looks unlikely to need to raise cash and a big SP drop due to a profit warning is very unlikely.
Cambridge Cognition (LON:COG)
Hi joshwood976.
There was a company webinar yesterday at 5,30.
Management were very excited about the progress they have made with acquisitions, partnerships and investment. They think there is considerable growth potential and they are having lots of conversations, tendering for contracts and have a strong verified pipeline of opportunities.
This is a period of transition integrating the acquisitions of Clinpal and Winterlight. Management say the additions mean they now have an end-to-end solution which they do not think any other company has and an excellent track record and reputation in the industry. Simultaneously, they have expanded their software development office in South Africa which I think is far cheaper than software development in the UK. Also the Luca Partnership which gives a stronger presence in China which they consider reasonably safe as it is operated through Amazon Web Services and APIs.
Results for 2022 were a 25% increase in revenue over 2021 but management hoped for more. There was a small amount of slippage and also a contract they were hoping to win has not yet been signed. Management thought it prudent to take one Winterlight contract off the Order book as the client is in a take-over situation, but the contract may yet be secured.
I have held shares since 2020 so have watched and experienced the progress made since then. Matthew Stork CEO has made transformative improvements to the company when other struggled. I have confidence that he has the ability and common sense to continue to take the company forward. The balance sheet is strong and COG have made 2 acquisitions and spent money of product development and expanding the sales team from their own resources which is a far cry from where they were 4 years ago. As with any company it is possible that the contracts to do come but I happy to continue to back Matthew and his team.
Michael
Hi Michael
Great summary. I have been feeling a bit 'cold' on COG having been underwhelmed by the Winterlight acquisition (a very small, early-stage company making a loss) but was buoyed by the call and now appreciate better how their speech-based assessments form an important piece of the puzzle which they can combine + scale.
Given the lack of profitability, it may take a bit of time for the market to appreciate what's happening, but I'm suitably reassured they're allocating capital in the right ways, and pleased they're not doing so to cause a massive loss like some software companies (rather focusing on building those puzzle pieces - eClinicalHealth also striking me as a well thought through acquisition.)
Finally, I noted down that they do not include potential big contract wins in their forecasts, so there is potential for upside.
Interesting to see Versarien trading at 1.15p bid and 1.2p offer. The placing at 1.25p looks likely to disappoint (according to the market at least). In better times there was real money to be made in these jam tomorrow stocks but those times have gone. I forgot that recently and bought a small holding in Plant Healthcare. I think the market is taking too long to adjust to the change in the risk/return ratio, because investors need time to change their mindset as shown by my purchase. But it is happening.
Had a reply from the Chairman of Plant Health Care (LON:PHC) having said I'd recently become a shareholder after seeing their presentations, iminent profitability etc which I share here for what it's worth:
"Many thanks for your email and for expressing your views very clearly.
We are now embarking on the process of consultation and will be communicating further with shareholders, as and when the Board is in a position to evaluate the options. We absolutely recognise our obligation to act in the interests of all shareholders. In the mean time, your input is noted and valued."
Thank you for the Zytronic comment Graham, my optimism for a recovery has been flattened by the TU. Our holding might have to go but I'll think about for a few days.
You're welcome, JASVFS, and good luck whatever your decision. G
I think the US reserve is broadly doing the right thing. Inflation is still high, and high inflation hurts almost everyone. I hope they are able to pause, which is their desire, in the next round. Then we will get to the low inflation target, set by government, soon and then they can start cutting interest rates so we get reasonable rates of both inflation and interest. All sorts of things can happen though - interesting times.
Inflation reignites in UK as economy powers further away from feared recession
https://www.cityam.com/inflati...
Mothercare (LON:MTC) update not gone down well today. High cost of servicing their debt may require covenants to be waived. Pension deficit down sharply. They talk of good future prospects. Directors have bought stock recently.
Any chance of covering this Paul/Graham? tia
Is there any chance of Mothercare returning to Russia should the hostilities stop or has the business been disposed for good?
hmm seems they've been disposed for good?
https://realnoevremya.com/arti...
Next (LON:NXT) has a deserved fan club here for clear comms and would appear to be saying, not too hot, not too cold today. Importantly though, they would also seem to be saying less cold than we thought ....but as is typical for them, clinging on to their cautious guidance. Another stock that is not expensive, may have some supply chain tailwinds but wouldn't be near my list of things to own in recession. Never the less I find myself thinking lots of bad news is in the price.
Paul - re Morgan Sindall (LON:MGNS) - and relating to comments below - the didv is nice too - near 6% !
Re the confusing Fed situation, continuing to increase rates into a recession.
My view would be it will be quite a shock if data releases now contradict their view that inflation is not low enough, unemployment is not an issue in the next month. Further out, does the pause result in better data ? It's possible... that confidence that the Fed is done means more stuff gets done. A higher nominal growth world is very different from the post credit crisis ZIRP decade but not necessarily bad....as Paul has highlighted UK housing would appear to be ticking along nicely enough, not dragging us into recession.
Seems to me the situation is best described as favourable. That is not one without issues but isn't it always thus. Higher for longer might not be so bad.
There is a webinar with Belvoir (LON:BLV) management today at 12.30pm. CEO Dorian Gonsalves and CFO Louise George will present the Belvoir Group PLC and discuss the exciting opportunities that lay ahead.
Register here
Virgin Wines UK (LON:VINO) I don't hold and I tried it once. I'm interested in wine enough to do some of the trade exams.
Anyway I just don't get the reason Virgin Wines exists...
If you want cheap - the supermarkets are pretty good - some of Lidl's are amazing for the price.
If you really like wine then The Wine Society has far better wines at great prices. (Co-op / member model).
If you want super good - then Berry Bros are excellent choice.
There are specialists in organic and biodynamic such as Vintage Roots, if that is your thing.
There are a host of specialist subscription services as well.
What is Virgin's USP? Classic falling between two stools? I suspect they will get swallowed up for the subscriber list by one of the others, or they need to do that to others who are struggling.
Hi wolfspirit,
Interesting comments on wine subscriptions, thanks.
I've largely gone off the two listed wine subscription services. Never liked Naked Wines (LON:WINE) - it seemed over-hyped, and it has a big problem with massive inventories, recently increasing the provision against those (tip of the iceberg maybe?). WINE doesn't make any profit, once you reverse the adjustments, and its poor payback period/cost shouts to me that it's just not a very good business model.
Virgin Wines UK (LON:VINO) is only of interest now as a bombed out value share, more of a trade for a bounce I would say.
Both these companies were presented to us as structural growth businesses, but it's now become clear neither is! They did well in the pandemic boom, and are now chasing their tails trying to constantly recruit new customers after others close their accounts (having taken advantage of the cheap special offer to open an account).
Also I recently sent a card through Moonpig, and noted that the wines are no longer Virgin Wines, so maybe they lost that contract, which I don't think has been disclosed to the market?
There's hardly any volume in VINO shares either, and with the growth story now finished, I can't see any reason as to why it would remain listed? Hopefully major s/h Gresham House might oversee a premium-priced bid for the company, as I assume they might have done at Medica (LON:MGP) ?
Anyway, thanks again for your interesting comments! We always like input here from people who know the sector concerned.
Regards, Paul.
I'd be betting on the takeover option - except I got stung badly on IBPO rip off and KAPE to a lesser degree.
Why would Gresham and the CEO pay a premium ? They could work with PE and soak up enough shares and find a few new "independent board directors" to join the vote to delist / go private. Then soak up the remaining at 20p in the £. That 49% control is a real put off.
Of course - whoever buys it has to see a really good reason to invest - and then we're back to what is the USP that drives growth?
The times when Virgin was a brand some people aspired to blindly buy into to like Apple or Nike have long gone. "Easy" empire tried the same.
With Branson disconnected a long time ago, I think it is just rent-a-name these days, and possibly a toxic one, with the bodged Galactic experience! I wonder if that will become as famous an example of PR/managers overruling engineering as the Space Shuttle was?
LON:BEG for those following Begbies, another small bolt-on announced today: expected to be immediately earnings enhancing, and fits with the Group strategy. New note out with retained FV, free access here: https://www.equitydevelopment....
Paul I know you have covered Trusts a fair bit, any thoughts on this as to what has been paid ? - Liontrust Asset Management (LON:LIO) Liontrust, the specialist fund management group, today announces that it has conditionally agreed to acquire the entire issued share capital of GAM Holding
AG ("GAM")
It's interesting to see that Liontrust Asset Management (LON:LIO) has purchased GAM Holding with it's undervalued shares. LIO's shares are down by about a third in the last few months. They have kept their cash level very high.
On this basis it looks like good business to me.
Anthony127. That's not quite right. Generally companies want to be using 'over valued' shares to make acquisitions. Using 'under valued' shares as opposed to cash dilutes future returns to their existing shareholders. Because they are exchanging an undervalued asset (their shares, including the rights to all future cash flows) in exchange for the target shares. In addition to the dilution to their existing shareholders from an expansion of NOSH, the newly issued shares will share in any future synergy upside (normally the main reason that justifies the strategic premium paid by the Buyer). Hence why using under valued shares as opposed to cash is not usually a great move. All this of course ignores the price being paid. Now in this case Liontrust are getting a huge amount of AUM relative to the purchase price. So one could argue that the fantastically low purchase price negates the dilution from using their 'undervalued' shares. That still doesn't change the fact that if they really believe they have a winner here, using cash (or at least a mix of cash and shares) would be more optimal. Presumably this is isn't an option as they want to keep a sizeable cash buffer on hand for integration costs / regulatory reasons / prudence. It's a bold acquisition for sure. Can they digest it is the million dollar question. They have a chequered track record in this regard. Will be interesting to see if they can pull it off...
Phil117 yes you are absolutely right I realised my mistake just now as I took a walk to vote in the local elections; it's better to pay with overvalued shares that way you don't pay so much.
Yes they're getting a huge amount of AUM, but not sure it's the best quality AUM (low margin wrappers, mediocre performance, etc). Liontrust have always been a bit too acquisitive for me, and fund managers not the easiest things to integrate (tend to have very different cultures with lots of big egos!).
Zytronic (LON:ZYT) (I hold) - Ooops! Nightmare trading update for H1. Combination of overstocking and a chapter 11 bankruptcy filing at Gaming customers, Zytronics largest sector, has led to a reduction in half-year revenue to £4.7m and full revenue from a forecast of £13.5 to managements current expectation of 8 - 8.8m as they currently don't see revenue from the gaming sector recovering before end of year. On top of that there is currently 0.3m of unpaid invoices to customers affected by the chapter 11 and a further 0.2m of stock for shipment.
That's quite a spanner through the touchscreen! I expect a rush for the fire exit this morning and a big fall. It may be that this is a cautious approach by management and that the disruption proves to be short-term but it doesn't feel like it at the moment.
The company remains stuffed with cash and property, and not in danger of going bust over this, so I may choose to wait it out. I'd like to see the H1 figures - particularly their order book for other growing sectors before I decide what to do as I don't tend to take quick decisions. But I do have a growing question over whether their new technology, patents and IP are actually proving attractive to customers,
cheers
Mark
Re your wider comments Paul, imo while Treasuries return over 4% (and rising) in America the leaching of deposits from regional banks in particular will continue. It's a game of who's next right now so feelings of optimism probably need controlling, what goes bang in America affects many markets.
TINA is dead…. Spot gold price hit an ATH in USD last night on the futures open!
Zytronic 'prudently' writing down £0.5m in this mornings T/U , on a debt of £0.3m and stock of £0.2. Reports net cash at £5.4m and forecasts £8 - 8.8m full year rev, any chance of a quick comment Paul or Graham -- we hold.
Good morning JASVFS,
Yes I'll try to have a look at Zytronic (LON:ZYT) - it appeals to me as a value share, given its very strong balance sheet, and recovery potential. But it's tiny, so we'll try to get some larger companies reported on first. Yes I know Virgin Wines UK (LON:VINO) is tiny too, but we have to start somewhere!!
Regards, Paul.
I completely agree, Paul. And now the UK government (ie the taxpayer), having blown an earlier windfall, is having to pay compensation to the Bank of England to cover their huge losses on purchased bonds of all types. Central Banks sowed this storm, and we are reaping it.
Help me understand what's happening with the BoE losses on QE and the cost to the Treasury.
The money to buy the bonds was just 'created' by the BoE. How does the loss arise?
Two possible losses. Mark to market, which is the current loss but may not eventually happen due to bonds being held to maturity (typically Gilts). Or a real loss which is what happens if you sell the bonds back into the market at a real loss.
You are right in principle; the BoE expanded it's balance sheet using funny money. But, the balance sheet is now being shrunk. That involves real losses in the circumstances above. The government has indemnified any loss and is now being asked to pony up the money.
Part of me just wants to park my capital in a 4% account until this bear market blows over. Of course, you miss divis and any potential bids!
and the capital increase! its still a possibility even if is getting slimmer and slimmer
Missing the bankruptcies, the de-listings and the hostile takeovers too.
Paul Volcker had to put up US rates to 20% to sort out the 1970's inflationary overhang. That recessionary pain meant we enjoyed several decades of low-inflation prosperity, quite whether circa 5% rates will bring it sustainably down or circa 5% is now ingrained as key people (including pensioners) get inflation-linked pay rises.
The problem is there is too much liquidity currently and many USA stocks are still trading at all time highs. You want names? Hershey Co, Chipotle, Carlsberg, Pepsico, McDonalds, Monster Beverage Corp, WingStop, Lamb Weston - consumer stocks have been basically jacking up prices to increase/retain their margins. Is this sustainable? What do you reckon will happen in the next few months? Meanwhile small regional banks which some thought would benefit from rate increases are on the brink.
The website Truflation is a far better measure of actual inflation compared to the lagged data the Fed uses. Truflation is showing the US inflation is down to 3.84% and falling fast. Inflation over there is almost beat. In the UK however Truflation has the current inflation rate at 15.55% and not falling as fast!
There is little reward in risk these days Paul, only more tax.
Don't forget even no risk is being taxed more heavily now, the next tax return will be sobering, but then of course the better off don't pay any tax do we, according to some. Just wait till Labour get their hands on CGT
I thought ZIRP pushed all the reward out of risk... and now rates are higher there is more reward not less ? ...that should encourage more Investment ( risk) .... a different landscape doesn't favour all but can be just fine.