Small Cap Value Report (Thu 5 Sept 2024) - CAR, FCH, CHH

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
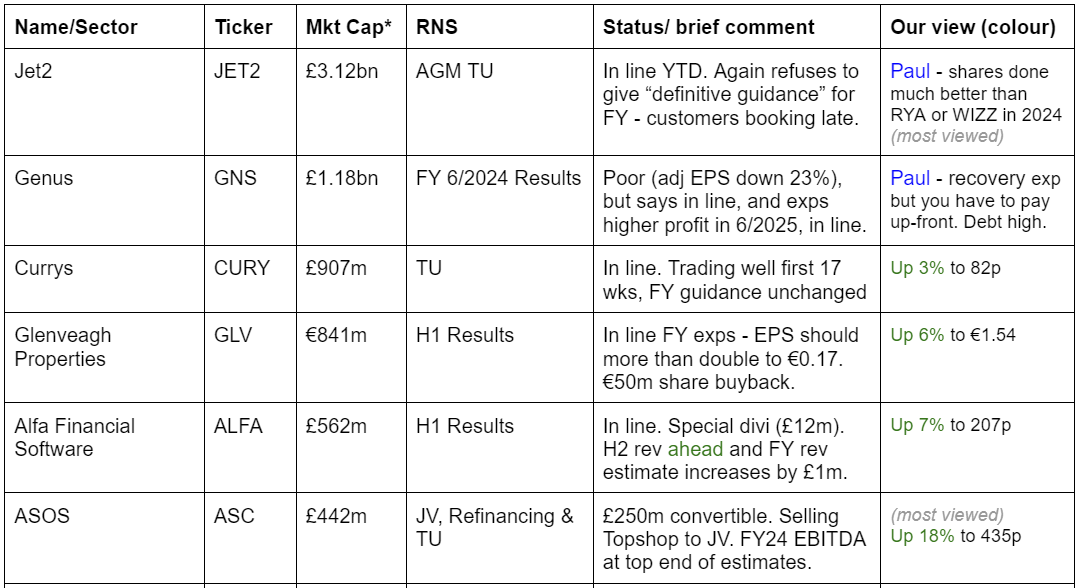
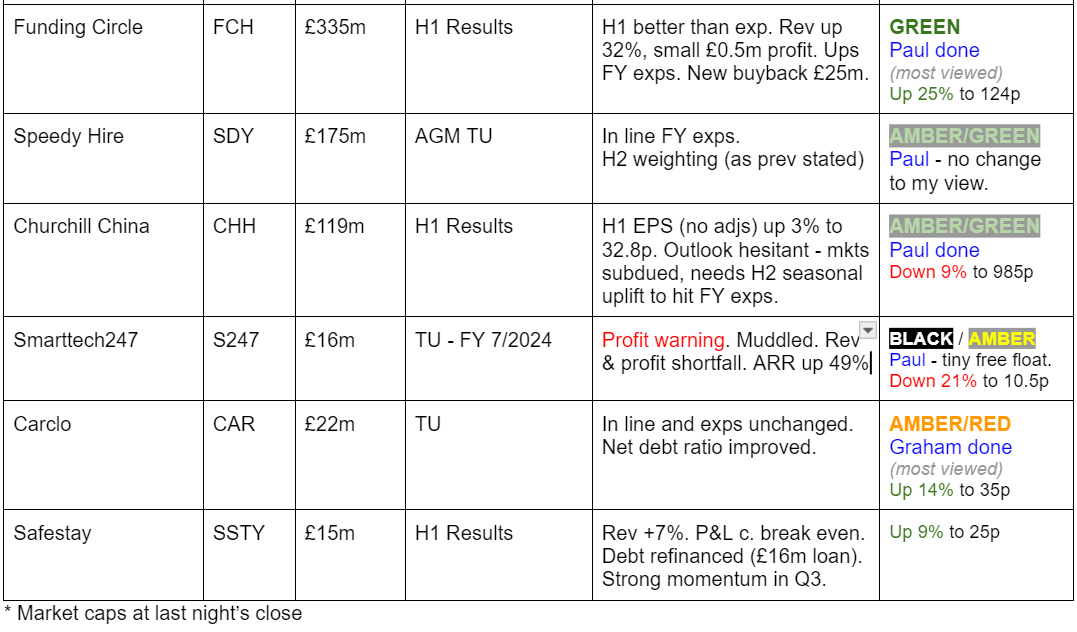
Summaries
Carclo (LON:CAR) - up 9% to 33.3p (£24m) - Trading Update - Graham - AMBER/RED
An encouraging update from this indebted manufacturer/engineer of high-precision components. It is trading in line and expectations are unchanged for this year and next year, as it returns to profitability. I’m upgrading from RED as renewed profitability should keep the lenders away in the short-term but the large overhang of liabilities, particularly the pension liability, requires me to stay cautious.
Funding Circle Holdings (LON:FCH) - up 25% to 114p (£419m) - H1 Results - Paul - GREEN
I'm late to the party here, but did tentatively like it on 25/6/2024. This has been an impressive turnaround, and moving into profit now (well, just above breakeven to be more accurate) is impressive - concept proven, and growing strongly, which is exactly the type of growth share I like. Is it reasonably priced though? Who knows, it's impossible to value at this stage. There's a big cash pile still, and buybacks are extended. Looks a good opportunity to me, but I have no idea how to value it.
Churchill China (LON:CHH) - down 9% to 985p (£108m) - H1 Results - Paul - AMBER/GREEN
Flat vs LY H1 numbers, with a slightly hesitant edge to the in line outlook comments. Hence a tinge of worry about a possible H2 profit warning, if the usual seasonal uplift doesn't happen. On the upside, it's a nice quality business doing >10% PBT margin, very well respected products & brand, with a lovely strong balance sheet. So I'll stick at AMBER/GREEN but with some reservations.
Paul’s Section:
Funding Circle Holdings (LON:FCH)
Up 25% to 114p (£419m) - H1 Results - Paul - GREEN
A strongly positive market reaction, that has just put £84m onto the market cap today (we manually recalculate the market caps in the line immediately above this one, to reflect the daily move at the time of writing, but we leave them at last night’s close, on the companies reporting list at the top).
The original business model of this lender to SMEs didn’t work, so I dropped coverage in 2019. However we’ve resumed coverage this year (here on 25/6/2024), as a remarkable turnaround seems to be underway. The loss-making US business was sold for £33m, and it’s focused on the UK business, which was stated (on 25/6/2024) to be -
“...on track to be profitable in H2, in line with our guidance. Over the medium term we expect net income growth of 15-20% CAGR with PBT margins of >15%.”
Further attractions are share buybacks this year, and a strong balance sheet with plenty of net cash.
I concluded in June that it was interesting, and worth a closer look - which corresponds with AMBER/GREEN, although I didn’t give it a colour at the time, due to not being confident I’d done enough work on it, due to time constraints.
H1 Results today (6 months to 30 June 2024).
I really like the format of this announcement, as it starts with a summary from the CEO, giving the main points - which are positive - ahead of exps, and upgrades to FY guidance -
“We are delivering on the plan I laid out in March to be simpler, leaner and profitable whilst continuing to show strong growth. In May, we simplified and streamlined the business to deliver £15m annualised savings in 2025 and in July we completed the sale of our US business for a gain of £10m.
The first half was stronger than our expectations with annual revenue growth of over 30%; 12% up on H2 2023. We were profitable a half earlier than we set out in our guidance in March and are today upgrading our guidance to be profitable for the full year (versus prior guidance of H2 profitable).
We are reaffirming our medium-term guidance of 15-20% revenue growth and PBT margins of more than 15% and continue to be excited about the long-term growth and profitability of the business as we execute against our plan.
We will commence a further share buyback of up to £25m following the conclusion of the existing £25m share buyback.”
This is a handy table, showing sequential 6 month periods -
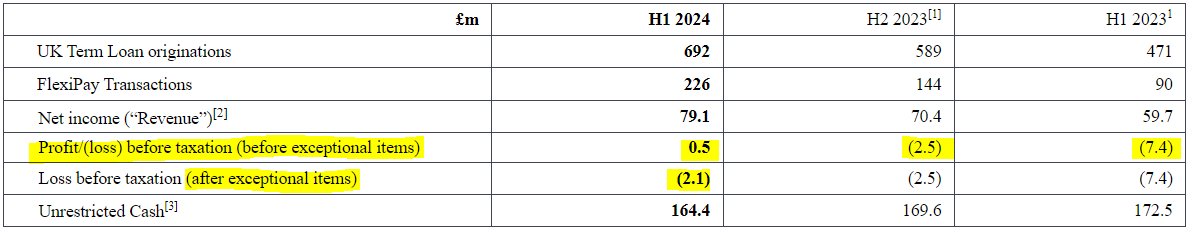
So it’s only really a slightly above breakeven result for H1 this year, nothing to get too excited about.
That’s decent top line growth, of +32% vs the year earlier comparator, so it’s not just cost-cutting that’s driving improved trading.
Cost-cutting has been big though -
“Progressed cost-efficiency actions, to deliver c.£15m of annualised benefit in 2025 and, together with the US sale, reduced total headcount to c.760 (Dec 2023: c.1,100).”
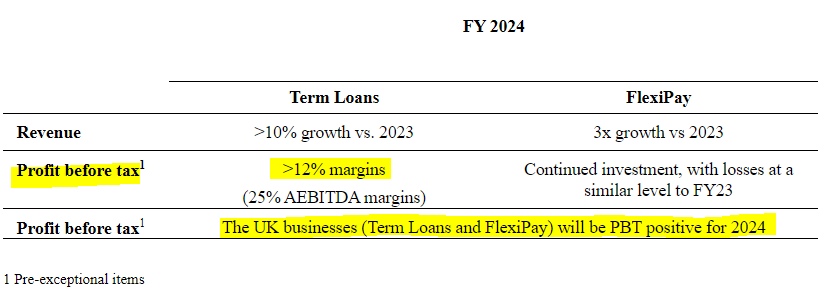
Another useful table here - the presentation of these results really is excellent, very clear - which shows us that the core business is making decent margins, but supporting a rapidly growing but still loss-making division (FlexiPay) -
CFO change - looks orderly, and previously announced, so probably not a concern.
Webinars/broker notes - I see FCH did an InvestorMeetCompany interims presentation this time last year, on 25/9/2023, so hopefully they might do an update this year too. There is an institutional/analyst meeting at 09:30 this morning, and the RNS says a recording will be available on FCH’s website, so I might listen to that later. Although analyst meetings can be a bit granular, asking obscure questions so they can fine tune their spreadsheets.
We’re in the dark already, with no broker notes available on Research Tree. Clearly FCH needs a better approach to communications with private investors. How can I buy the shares if I’ve not been able to read a broker note explaining the business, and all its moving parts, and providing forecasts? It’s a lot harder & time-consuming without that information.
The H1 slide deck is here on its website.
Business model - FCH seems to be mainly an arranger of loans, through its technology platform, with only a small lending book on its own balance sheet. That seems a decent and scalable proposition, especially now it’s moving into (modest) profit, and still has a ton of cash on the balance sheet - arguably not really needed now, if it’s only an intermediary, hence why using some of it for buybacks seems sensible.
Several shrewd fund managers and other commentators have talked bullishly about the potential for FCH to re-rate as a technology platform that is now taking off, having achieved at least breakeven, and targeting higher profit margins in future. I must admit, I find that argument quite compelling. I can’t stand loss-making start-ups, as so many fail, but FCH seems to have transitioned to an actual business that is now concept proven, growing strongly, and still sitting on plenty of cash.
Also, there was so much advertising done in the past, that most people will know the Funding Circle brand name - a real world intangible asset that would cost many millions, and time, to replicate.
Paul’s opinion - I’ve already spent half the morning digging into this, and don’t think it’s necessary to dig any further into or write about more detail, as the investing case is now obvious. It’s a growth share that's reached breakeven, with good reasons to expect that it should move into useful profits in the coming years. The brand is very well known, and it looks to be in the process of being re-rated as a technology platform, which as we know can command remarkably high valuations.
I have no idea how to value this share because you can’t use conventional value-style metrics at this stage with a growth company. Overall, I see an interesting situation here, as mentioned in June.
I need to do more research, but am happy to flag the opportunity positively with GREEN. Although I have no idea how to value FCH shares at this stage.
It's now a 5-bagger in just 6 months!
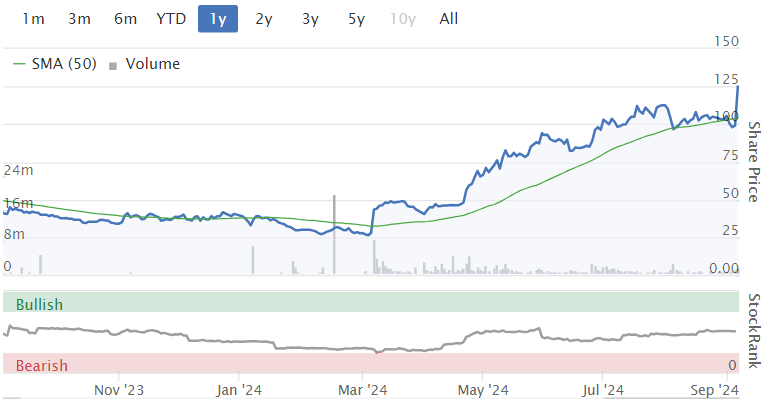
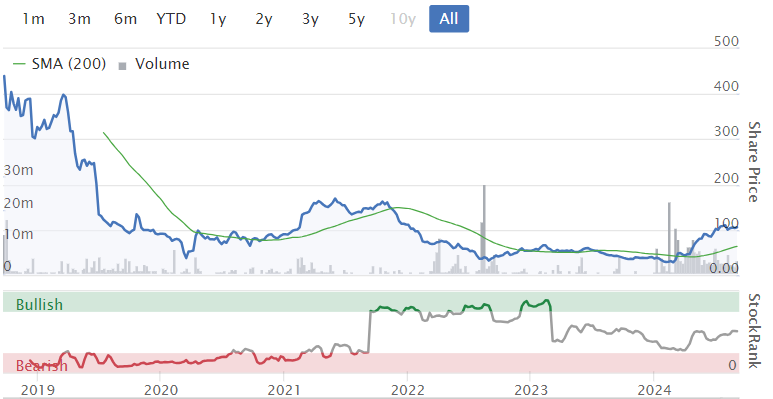
Although still a long way below the inflated IPO valuation, when it wasn't concept proven or profitable. There hasn't been a lot of dilution (and reducing with buybacks), so I would argue risk:reward now is far better than it was at IPO.
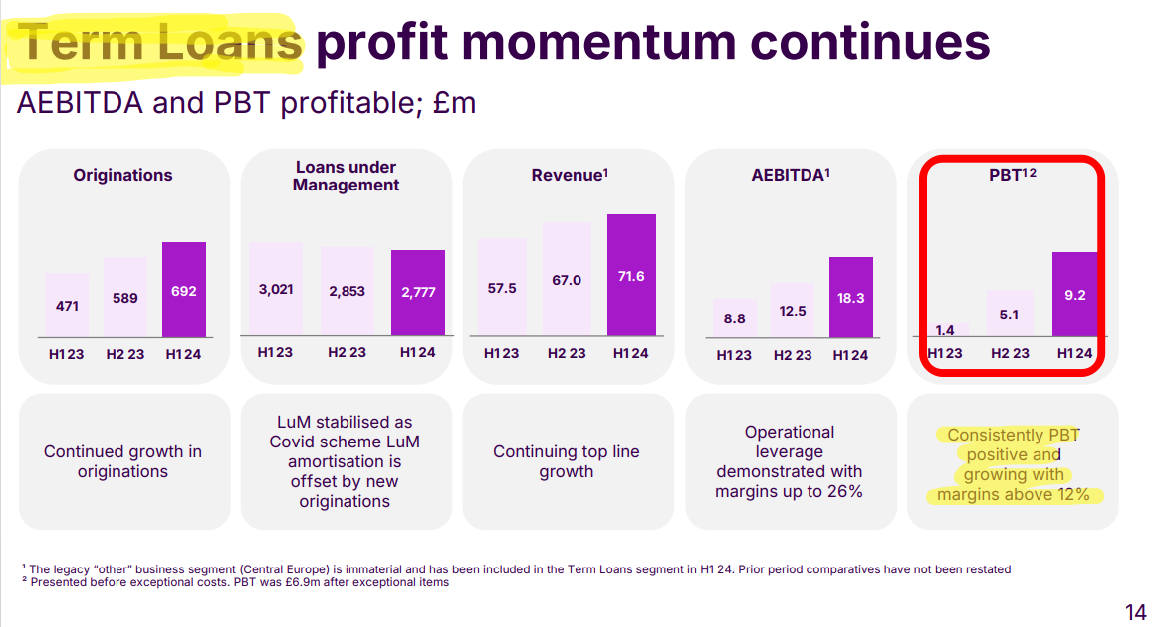
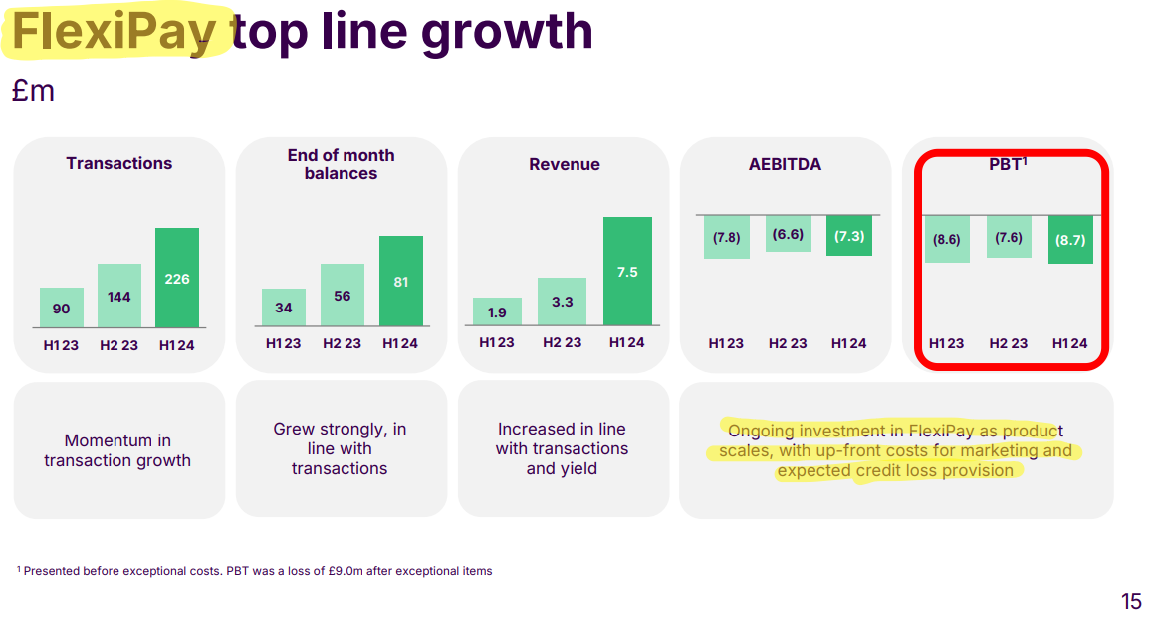
EDIT: another point which I didn't properly develop above, is that the Term Loan ("TL") division is actually nicely profitable, but this is obscured by losses in the developing FlexiPay ("FP") division. So there's a strong argument for using a sum-of-the-parts valuation, and giving TL a decent valuation, then say FP is worth nothing for now. Or give FP a speculative valuation if you think it could be come more profitable in future. Here are the slides that spell out this point nicely - and remember these are only half-year numbers -
Churchill China (LON:CHH)
Down 9% to 985p (£108m) - H1 Results - Paul - AMBER/GREEN
Churchill China plc (AIM:CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce its Interim Results for the six months ended 30 June, 2024.
Unremarkable results table below, and note the modest profit growth came from reinstating prior year numbers downwards -
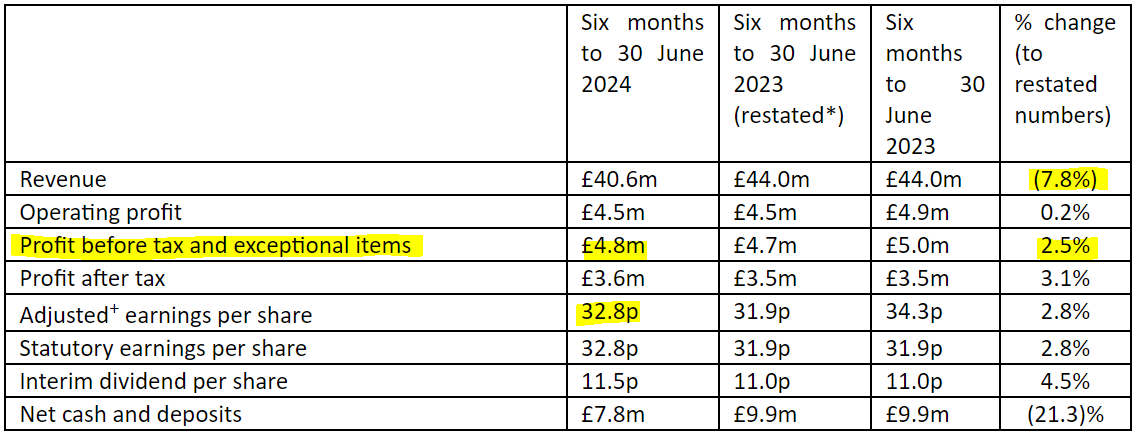
Margins are quite good, that PBT is over 10% of revenues.
“Factory cost of production was broadly static during the period with increased input costs from labour and raw materials being offset by the reducing costs for energy. The focus on improving efficiency and yields continues and as a result the overall profit margin slightly increased.”
Outlook - sounds a bit hesitant, with the possibility of a H2 profit warning maybe? - but as it says, seasonally it does usually see an upturn in H2, so could be nothing to worry about. Any qualification to the in line with expectations comments is bound to raise investor anxiety as a possible early sign of trouble ahead -
“The Board believes that the Company is well positioned to take advantage of a return to confidence in our markets when that happens but continues to see subdued activity in our key European markets. As such, we remain dependent on the stronger demand normally experienced in the final four months of the year to meet our full-year expectations.”
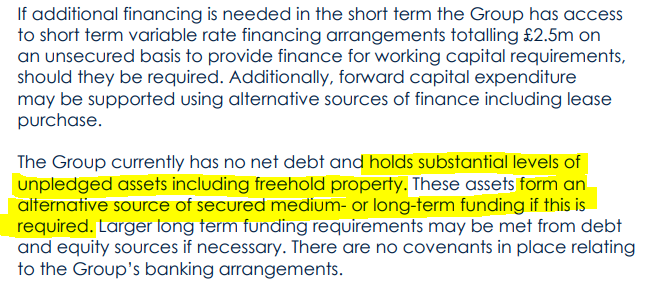
Balance sheet is very healthy, with £60m NTAV. There’s no bank debt, and it owns freehold property in the books at depreciated cost of £12m. I wonder what the market value of the land/buildings might be? Often that can be a hidden asset for elderly companies like this. Accounting standards should be changed to require freeholds to be shown at a prudent market value, in my view.
This snippet from the 2023 annual report is interesting in reinforcing why freeholds are such a nice thing for companies to own - greatly improving risk:reward for investors, although some investors see this as old-fashioned and “inefficient”, which is crazy in my opinion -
Cashflow - wasn’t good in H1, but seems to be because of working capital movements (that should unwind), with receivables up, and trade payables down in H1 vs 6 months earlier, which absorbs cash in the short term. That’s something to check at the next year-end, to hopefully see this factor reverse.
Broker updates - nothing available to us plebs. So we’ll need to keep an eye on the broker consensus data, to see if anyone slips through a downgrade, which wouldn’t surprise me given the hesitant sounding outlook comment.
To be on the safe side, I’d be happier taking say 10% off the existing 2024 EPS consensus of 79.6p, so let’s call it c.70p. At 985p/share that gives me 14.1x, which looks a fair price.
Paul’s opinion - looks priced about right. Lovely strong, ungeared balance sheet. You’re getting the upside in a possible sector cyclical recovery in for free.
I’d say that’s moderately interesting. I was AMBER/GREEN last time on 5/6/2024 at 1,115p, and here we are with shares 12% cheaper now at 985p, and not far above the covid lows. I am worried about a possible H2 profit warning, so probably won’t be diving in myself, but it is quite a nice business, making decent margins, with balance sheet safety, so it’s better than just vanilla amber. Hence I can (just about) stretch to AMBER/GREEN again.
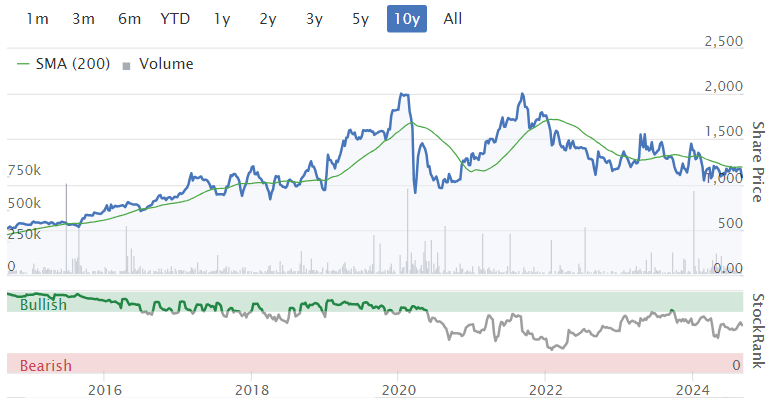
The 10-year chart below shows the current price is half the pre-covid, and post covid bounce peaks. There's been no dilution either, with still only 11m shares in issue, so maybe there's an opportunity here? That said, it's also looking ex-growth on earnings now, so maybe the de-rating onto lower PER is justified?
Graham’s Section:
Carclo (LON:CAR)
Up 9% to 33.3p (£24m) - Graham - AMBER/RED
Carclo describes itself as “the leading global provider of high-precision components, offering comprehensive services from mould design, automation and production to assembly and printing, serving the life sciences, aerospace, optics and tech sectors”.
Paul gave it a RED in April, noting high financial risk due to net debt of c. £19m, plus leases, plus a pension deficit. So as Paul said, it had the potential to be a zero, or a multi-bagger.
Fortunately, the company has delivered for its shareholders so far this year. Here are the key points from today’s AGM trading update.
Performance is in line with expectations.
The net debt to underlying EBITDA ratio has been “further improved” (numbers not given).
Expectations for FY25 and FY26 are unchanged, “with margin expansion anticipated to continue as the Group starts to see the full benefits of the operational optimisation process, continuing our journey toward our strategic goals of 10% return on sales and 25% return on capital employed”.
Let’s check some estimates.
In July, Panmure Liberum published forecasts for FY25 and FY26 as follows:
2025: revenues £133m, underlying PBT £2.4m
2026: revenues £146m, underlying PBT £5.2m
As you can see, this is a low-margin business - implying that small differences in the cost structure can have an outsized impact on the P&L. Carclo has been in restructuring mode since 2022, and its efforts are being rewarded with a return to profitability.
A reminder of the financial track record here:
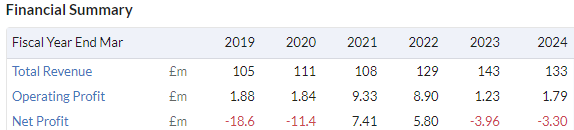
Other bits and pieces from today’s update:
US manufacturing restructuring is ahead of schedule, with new leadership teams driving the expected enhancement in margins.
EMEA manufacturing is now focused “on the next phase of operational improvement”.
Graham’s view
This has been a multi-bagger year-to-date, as the worst-case scenario of short-term insolvency/administration has become less likely:
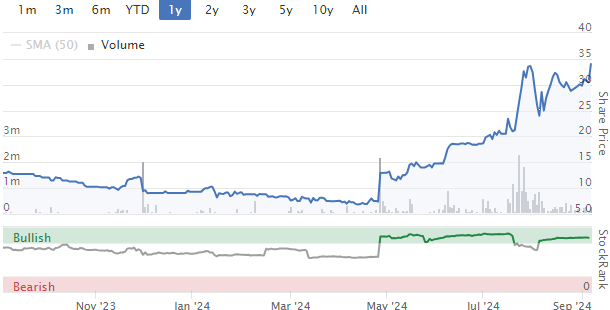
That’s the problem with these high-risk shares: RED might be justified on a risk basis, but if the company pulls through, the shares can perform fabulously! (This is also why shorting is so dangerous.)
So is Carclo out of the woods now?
I’m not a sector expert here, so I will look at the estimates and try to reach a reasonable conclusion.
The net debt estimates for March 2025 is £28m, falling to c. £26m by March 2026. This figure includes leases.
The annual interest bill is running at about £5m. That includes the interest on bank loans, notional lease interest, and interest on the pension liability.
The pension deficit was last recorded at £83m, with a new calculation due this year.
Given the size of these numbers, I don’t see how I can have a positive or even a neutral stance on these shares.
Adding the market cap, net debt estimate and pension deficit gives an enterprise value of £135m. This could and probably will come down with the new pension calculation, so let’s say the enterprise value is £120m.
That’s 12x the EBIT estimate for FY March 2026 (£10m).
Even for a manufacturing business that’s better-than-average and not overly leveraged, I’m not sure I could justify that valuation.
For a manufacturing business whose quality is uncertain and which is highly leveraged, I can’t justify it.
Therefore I’m going to go AMBER/RED on this. I’m upgrading from RED as the immediate risk of insolvency does appear to have reduced, thanks to improved profitability. But it remains much riskier than the typical stock we look at here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
I just thought of a positive upside of a CGT increase. With all the regs and tax changes forecast our portfolio gains will collapse, and there will be some lovely losses to offset in future years.
Glass half full as always :-)
RNS from Cairn Homes (LON:CRN) announcing an 8 million share secondary placing so the CEO can sell this number of shares. This is a big chunk, he has 3.5% of the voting rights and will have 2.3% after the placing
Wonder why he is selling ?
As you say, 1.2% of share capital is pretty significant
No criticism of him at all. Good for him to cash in a third of his holdings and realise the benefits of his hard work. Still heavily invested.
But there will be a reason why he sold at this price and he knows more than anyone about the prospects for the business.
Insider sales of this level definitely a red flag to me and remind me to “follow the money “ !
I hold Treatt (LON:TET) and Calnex Solutions (LON:CLX) . Both had senior execs sell a big chunk before the share price in both took a massive dive. Absolutely no thought of any wrong doing here . But these people know lots of stuff private investors do not, they are no fools and everything is in the timing. Personal wealth a massive motivator imo after a lifetime of hard work and stress.
If the CEO was living in UK I would guess the sell is intended to protect for any possible CGT increase but he is based in Ireland and I'm not familiar with the fiscal rules there. He's been there for a while so as you say he has a big position still and I wouldn't blame him for getting some hard earned profits! Another detail I've just realised is the slight downgrade on broker forecast for next year compared to the latest forecast available. Something to keep an eye on
Marmite but Tesla (NSQ:TSLA) have a clear route to full self driving now and it's not a long runway.. V13 is unsupervised FSD
People want to see a useful use of AI - this is it.
September 2024
- v12.5.2 with ~3x improved miles between necessary interventions
- v12.5.2 on AI3 computer (unified models for AI3 and AI4)
- Actually Smart Summon
- Cybertruck Autopark
October 2024
- Unpark, Park and Reverse in FSD
- v13 with ~6x improved miles between necessary interventions
Q1 2025
- FSD in Europe (pending regulatory approval)
- FSD in China (pending regulatory approval)
what no anti racoon update for the cybertruck - elon needs to up his game meethinks.
Hi NewInvestor1972 , IF that plays out it will be game changing. I'm presuming you have a Tesla or shares in them. The regulatory approval is likely to take a while.
Sorry JASVFS - I should have mentioned, Tesla (NSQ:TSLA) tsla is my biggest holding and biggest regret, always believed in the company but thought $25 billion was a crazy valuation in 2016 when I started investing so never invested. Oh well I've got a $160 average now so shouldn't complain, if they win the FSD race the sky's the limit
Interesting take on ISAs.
Reeves Should Kill All the ISAs — Except the British ISA
The new chancellor has a chance to reinvent how Britons invest while bolstering the dwindling stock market.
https://archive.ph/SiBnL
Good Afternoon
AJBell user query.
Has anyone any experience of their application to be classed as a Professional Investor? And how burdensome that it is.
Just trying to remove restrictions on what I am and am not allowed to buy within the account.
On a positive, two questions sent via secure messaging, both replied to within 24 hours with a clear response to the question asked. So tick on their customer services this week.
Thank you
Tommy
Hi Tommy
I did it- pretty straightforward. I think it asked what experience- I used to be a stockbroker back in the 19080's so that helped. Charles
Tommy,
The downside of being classed as a Professional Investor is that you become ineligible for FSCS compensation.
good update from Vistry (LON:VTY) this morning. the growth continues, the buybacks continue, the operating leverage is starting up
heh, as a funny note: i owned countryside partnerships as a merger-arbitrage before vistry chomped them up.
as part of the acquisition, you were offered vistry shares. i refused them because I didn't want to pay a penny more than £5 a share for vistry - the price at the time of the acquisition (oct 22) was £5.20....
i later did buy some vistry shortly after but in hindsight should not have been so picky over 20p more (or 4% more) a share!
I'm sure I'm not the only Vistry (LON:VTY) shareholder who would have welcomed a dividend announcement today, having watched some poorly timed buybacks at recent highs. It's all very well management managing numbers to fit their metrics; what about mine - Total Return.
well firstly: a share price at a recent high does not = an overvalued business!
secondly: Vistry (LON:VTY) already have committed to dividends! they announced last year that they are planning to issue special dividends alongside their share-buyback program; they have been very clear about this in all their reports and releases.
as an aside: British American Tobacco (LON:BATS) and International Personal Finance (LON:IPF) would be two other examples of companies whose share prices have hit or just did hit 52 week highs. and yet, they remain significantly undervalued vs their actual value and both companies are buying back shares hand over fist because of this (alongside their chunky dividends).
again, to reiterate: a recent share price high does not by default = overvalued. you need to look at it in context of where the business is and where the business is going to be (or where it isn't going to be, lol)
Vistry (LON:VTY) re share buybacks. I would much prefer divis (esp when tax free in an ISA or SIPP). Incidentally, I was shocked to see just how much the share count has INCREASED year by year, for a number of years, I always look at the share count shown near the bottom of each company page on Stocko. Other than this I am a happy holder and think the company has a profitable few years ahead.
I am firmly in the camp of buybacks here. Vistry (LON:VTY) is following the playbook of NVR (NYQ:NVR)...
Capita (LON:CPI) completes Capita One sale and receives £180m net cash.
"Adjusting for the disposal of Capita One, on a pro-forma pre-IFRS 16 basis as at 30 June 2024, Capita was in a net cash position."
https://newsfile.refinitiv.com...
Read across for Saga (LON:SAGA) from Direct Line results yesterday?
Fuel costs have come down too. Must help the cruise business which is already going well.
Saga (LON:SAGA)
unfortuantely nothing ever seems to read across well for Saga even when it should do - Hiscox have being providing reaonably positive updates for some time now - it only seems to be Saga that cant make any money and i have to presume thats more down to them than the market in genral who they seem to lay blame at. It may be more nuanced than that if Saga have set themselves up for unprofitible stuff thatb they near to suffer and will naturally sort itself out over time. They strike me as being hopeless though if others making good profits and they are not.
per the company 25/06 - not exactly great outlook ref insurance
Market conditions for Insurance remain challenging. We are taking action to stabilise our Broking business and are seeing early signs of the expected benefits in motor. Emerging net rate inflation in home means the actions are expected to have less of an impact overall.
Hey ho perhaps if others are doing well they will eventually get their mojo back - if theyt did get insurance mojo back and cruising holds up then long term shareholders nightmare might end ?
It sums up the company that despite them saying they were trading in line on 25th June forecasts are currently materailly below were they were at the end of may - so looks like expectations were lowered directly before they said evcerything was on track - go figure how transparent that situation is !!
Hi rmillaree
Agree that Saga (LON:SAGA) insurance situation has been poor. I suspect there were two reasons (1) the ill fated 3 year fixed deals that forgot about the possibility of inflation - poor mgmt there and (2) previous management (possibly also current mgmt but I will give them a bit more time).
I reckon they printed the 3 year deals at low prices - people come to renew and balk at the massive hike the renewals team have to put through, so turn to comparison sites and find something cheaper and then switch furious at Saga (LON:SAGA) cheek of such large raises. Saga (LON:SAGA) then have to compete harder to win back customers which impacts margins.
So in essence the 3 year deals were a complete own goal imo and very badly thought out. Nice one Mr Sutherland (not the first decision of his I’ve questioned).
So that division required an overhaul, let’s see how (if) that is improving - it will be a sign of the quality of current mgmt.
Osb (LON:OSB) £50m buyback kicks in tomorrow. Hopefully will stabilise the SP
A director bought 20k@381.66p on August 19.
Stocko 12mth fcst PE/PEG/DividendYield - 4.3/0.5/8.85%
Price to tangible book = 0.67
Funding Circle Holdings (LON:FCH)
Below are Rockwood Strategic (LON:RKW) top 10 holdings as of 30th June, taken from the company's Q2 fact sheet. Funding Circle Holdings (LON:FCH) has replaced RM (LON:RM.) as the largest holding. Rockwood Strategic (LON:RKW) last reported NAV on 2 September was 256.8p and the company issued equity on 3 September at 261.88p. I hold Funding Circle Holdings (LON:FCH) albeit a modest position; always the way when shares go up you wish you had bought more and vice versa.
Anyway my daughter holds Rockwood Strategic (LON:RKW) in her ISA which I manage and I have just added a few at 261p, slightly above NAV, but I suspect that the markets reaction to the interims from Funding Circle Holdings (LON:FCH) will likely result in the NAV climbing somewhat above my purchase price. On balance it is worth paying for the expertise of Richard Staveley and Christopher Mills in respect of UK small caps investing, not forgetting Stuart Widdowson at Odyssean Investment Trust (LON:OIT) , also part of the Harwood stable. Difficult to find anyone better.
For what its worth I also hold reasonable positions in Flowtech Fluidpower (LON:FLO) and M&C Saatchi (LON:SAA)
Top Ten Holdings as % of NAV
Company Sector %
All the best
Carclo (LON:CAR)
What is going on here? It's got a rocket up its proverbial, I don't understand....
And how does Cockney Rebel get it so right so often?
From my observations on his published comments he puts in a lot of work to understand what he is buying. By his own admission a success rate in the region of 70% is about achievable. Wish I could do that.
But also be careful - CR is quite promotional on twitter and in his weekly blog and has a lot of disciples. So once he starts crowing about something generally prices of the smaller companies start to move and you can get caught on spikes up.
That said I like his analysis and do pay attention to some of those ideas. His analysis on Marks and Spencer (LON:MKS) drew me to that stock but I had to be patient to get a good entry price which was in the early 200ps and I still hold.
So be careful he is talking his own book - hardly ever comments on things he isn’t holding from what I can see, so you need to work out when to be patient and not get sucked into the FOMO everyone else is feeling.
As you’ve seen from Graham there is a counter argument on Carclo (LON:CAR) : not one I hold
"Crow-ing" haha
Helvellyn
Joined 2020
592 posts
Yesterday 3:38 pm
Cairn Homes (LON:CRN)
Hopefully Graham, who normally takes a look at Cairn Homes numbers, will have time to do the same tomorrow with the H12024 figures that were released this morning. The growth looks impressive but I do not understand the very large H2 weighting that has been evident for a long time. Why would this be for a house builder? I have checked the UK equivalents and there is no obvious weighting either way, however Glenveagh Properties (LON:GLV) another large Irish home builder has an even more pronounced H2 bias.
Would it be the weather in Ireland possibly affecting construction or something more financial?
If anyone knows I would be very grateful for some insight.
I posted this rather late yesterday and wondered if Graham had time this morning he might be able to answer the question. It would be great if you could spare the time.
TIA
Hi Paul, Thank you are an excellent report on Funding circle. I have noticed Deutsche Bank target price was 170 pence - 'buy' on 16.8.24
SSP (LON:SSPG) has taken a tumble today. Is there a sell note out today? Recent numbers were quite good.
Morgan Stanley downgraded to equal weight.
Thanks. Where did you see this?
ADVFN Morning Market bulletin, a free mail out I have received for years, unsure if it's still free, I probably wouldn't pay for it but it's a good summary for larger stocks.
Insig Ai (LON:INSG)
Insig AI reports reduced losses for FY2024. Recognized by FCA for anti-greenwashing tech. New Transparency and Disclosure Index launched. In talks with Big Four firms and UK asset manager for potential partnerships.Company raised £1.71M through equity funding in 2023-2024.
Insig AI refocusing strategy to improve execution and sales approach. Long sales cycles and complex procurement processes remain challenges. Company sees opportunity in upcoming sustainability reporting regulations in EU, UK, and US. CEO Richard Bernstein: "the coming months are set to bear fruit from our substantial investment". Bernstein took over as CEO after last one was booted out at the end of May. Bernstein has 18%, Nat Rothschild 5%. Report card might say “failed so far” with little revenue, but you could argue that the CEO has skin in the game and the bit between his teeth and wants to win.
Have a look into the history of Ultimate Sports Group (USG), Catena, and Reverse Takeover Investments. It opened my eyes quite a bit regarding Insig Ai (LON:INSG)
Insig Ai (LON:INSG) Thanks for that cheeky_minnows, I'm aware of the share transactions etc., but if there is anything else that people allege, I would be interested in knowing.
All the history aside, looking at my notes, my guess is that John Wilson might be someone that Nat Rothschild has put on the board to keep an eye on his interests. This for me is the positive point.
From a business point of view, my understanding was that this is a business that wants to use AI to check if companies reports and statements show that they are genuine in their ESG aims. Maybe I am wrong in this interpretation - so please correct me if I have misunderstood. The problem for me is that I already guess that most companies' ESG policy is one of marketing and spin, and don't need AI to point it out to me. What ESG regulation are they basing the decision upon ? It sounds like a solution in search of a problem. This doesn't mean that it can't be very lucrative ! My very cynical view of ESG taints my opinion, but I am sure that regulators like the FCA are falling over themselves to find silver bullets so that they have some backup in criticising companies' ESG policy. It all sounds great doesn't it - we have found out that Shell isn't really as green as they are making out !
Another interesting point might be their acquisition of the Estonian company(looking at carbon impact of blockchain), but I had stopped my research at this point.
(Regarding ESG : Aswath Damodaran says it much better than me - Doing good or Sounding Good : A Skeptical Look at ESG)
edit: as a last thought ... maybe they can use AI to check the environmental impact of AI..
I wonder if it would be possible for Graham to look at Ashmore (LON:ASHM) whose final results were out this morning.
Net outflows of $8.5billion but the CEO is talking up the prospects of emerging markets in terms of valuation and superior growth.
It has a strong balance sheet and large dividend yield and personally I believe that momentum will turn as the interest rates in the US are reduced over the coming months.
Cheers.
If you look at the last few commentary from Ashmore (LON:ASHM) its been the same tune for a year or so now... "emerging markets are great value, they will turn at some point".
Who knows when.
However, I note that recently in the last 1-2 months, Bloomberg, FT, and other financial news have started to report numbers-backed commentary that investor flows into Emerging Market debt and equity is now positive. There's enough data points, across several sources of it, that seems to suggest that some sort of bottom has arrived and a reversal to positive inflows has started.
Whether this can be sustained... lets see.
Meanwhile, I hold as its a nice chunky dividend, lots of cash on the rock solid balance sheet, and I don't think the price can get any lower, so better to hold this than to hold cash IMO for the free option of a higher share price.
(I hold Ashmore in the Boon Fund)
Are transaction costs holding back UK equity markets?
"Small marginal gains are the differences between capital markets that prosper and those that fade. Excess friction on the transmission of capital through our market has held back our whole ecosystem."
In recent discussions about UK pension funds selling off equities, one group of buyers stands out: the companies themselves. Research from AJ Bell shows that mature UK companies return around £120bn to investors annually, mostly through dividends and share buybacks. In 2024, buybacks account for about a third of this capital.
While dividends transfer money to shareholders with minimal costs, buybacks are more complex. Transaction fees, taxes, and market timing can reduce the benefits to remaining shareholders. These implicit and explicit costs can diminish the potential returns from buybacks, with friction on capital flows adding up to substantial losses over time.
Current UK rules require companies to announce buyback plans upfront, which can inflate stock prices and increase the costs for remaining shareholders. In contrast, allowing delayed disclosure, as in the US, could help reduce these costs while still maintaining transparency.
Morgan Stanley research highlights that companies conducting buybacks tend to outperform their peers by 11%. However, much of this gain can be lost to rising share prices following buyback announcements. Reducing transaction costs by even 1% could save £600mn annually, a figure that compounds significantly over time, boosting investor returns and making the UK market more attractive.
By nurturing capital markets and reducing unnecessary friction, the UK could see improved returns, attract more investors, and strengthen its overall financial ecosystem.
(Based on todays FT article)
Learning Technologies (LON:LTG)
Just been running the slide rule over this one ahead of their results later this month.
Pros:
E-learning business with long term contracts with multi-nationals, part SAAS
Debt all but eliminated with recent sales which should add back circa £16m to cash flow in FY25
Earn outs from recent acquisitions falling away, again adding back to cash flow
Margins improving as integration of businesses are completed
Free cash flow yield could be 10%+ next year but a lot of forward guessing here ahead of results
CEO founder is very sharp and interests are aligned with a 10% holding
Bouncing along on multi year lows, no love for the stock at all
Cons:
It's more cyclical than initially realised
Currency headwind with the weaker $ v £
Regulatory issue with US government which they are trying to fix asap
Bouncing along on multi year lows, no love for the stock at all
Conclusion:
I'm attracted to the free cash flow here and the firepower it gives them going forward re capital allocation. I'm hoping the last of the negative newsflow will come out in these results leaving the slate clear for a big rebound in FY25. It's valued like a mid cap engineering business as oppose to a tech business but would welcome any insights from existing holders.
I've bought a starter position ahead of the numbers...
Great post Burnt Onions. Thanks
I don't suppose you know whether they have any other 'hidden' assets on the balance sheet that can be monetised - ie like the sale of VectorVMS to PIXID for $50 million in June?
Also any ideas what's caused the suspension in new contract awards with the US Government for its GP Strategies division? And how long it might take to remove their non-compliance (eg Structural vs simply procedural issue)?
Hi Paul,
I would love to give you a valuation of the individual businesses but all I have is what's in the public domain. After GP strategies I believe PeopleFluent is their most valuable business but I am digging deeper...
However I would say I was surprised to the upside by the prices achieved for the sales of Vector & Lorien $71m combined and as you know they have bought 17 businesses over the last few years so I have to assume there is substantial residual value and I would wager it is trading below its sum of parts.
The US Government thing is the news I am hoping to hear about in their forthcoming results, they say in terms of earnings it's not material which is fine but I think it is important in terms of credibility.
Would make sense for a US operator to own it given their mainly $ earnings and maybe that is the exit one day for the founders but plenty of runway here and they have the balance sheet strength to expand into it.
We shall see....
Thanks Burnt Onions
ATM I can't tell whether Learning Technologies (LON:LTG) is a value trap or value play?
That said its definitely an interesting unbundling story - which I'm sure is not lost on private equity.
No worries Paul
And yes I agree with you, there is plenty to unbundle here if someone wants to take it on.
I err on the side of value play, they've spent £600m on acquisitions since IPO and now have a business guiding £88m EBIT with strong cash conversion (currency headwinds not withstanding), no debt and a market cap of £530m ish?
The CEO is a pretty good operator in my opinion....but it is very hard to buy something like this when it is so unloved and with a miserable chart to boot.
Agreed Burnt Onions. The other possible elephant to consider, is whether Learning Technologies (LON:LTG) 's more commoditised training/consultancy services will ever be dis-intermediated by generative AI?
At the margin, this is probably inevitable - albeit migrated partly by how much the company can benefit (eg lower costs & improve quality) itself from deploying the technology.
The CEO of Learning Technologies (LON:LTG) is very close to the former executive chairman of RWS Holdings (LON:RWS) and in my view both companies currently suffer from the same problem, namely the perception, rightly or wrongly, that AI will indeed dis-intermediate their businesses substantially. Value traps or value plays...
The new AI driven RNS feed on Investor Meet Company is excellent. It summarises the key content of each RNS, including a good effort over trading updates and results. I just logged in this morning for the first time in a while and will be revisiting much more often now.
Are there plans for Stockopedia to offer a similar service in future?
I do like the IMC website. LSE has a similar effort called Sparklive, but I had to register to look at a past event even though I had registered for the site. IMC just gets things right.
Thanks for pointing that out. It certainly looks very impressive and is a free service. I'll have a look tomorrow to check what time the 07.00 RNS summaries come through. There surely must be a delay.
Just registered, looks pretty good. Think Stockopedia should consider something similar. Stockopedia are poor at notifying which stocks are reporting and often their information is incorrect.
Interesting …AI. my late husband was a vet so AI means artificial insemination in my vocabulary…However the outcome or input is oddly similar …Adding something to make something else ….
So conversation between 2 of our daughters the other week ….Daughter 1 PhD in organic chemistry and has written papers and publications …Daughter 2 works in high end online marketing (note …I don’t understand either) ….Anyway conclusion of quite heated debate….. AI is only as good as the information put in which (IMPORTANT NOTE) may NOT be totally accurate …(some GOOGLE searches will show that to be true if you know the correct answer )…. So AI as a basic search filter is OK to a point but should never be taken as the gospel truth….and ( from the scientific brained one) NOTHING can replace reading the original paper as there may be small comments or sentences that are NOT picked out by AI but which ,if followed up, can open up new pathways for evaluation ,interpretation and research.
My husband could see a situation with herds and rather than just go with current trends he could (if the clinical signs warranted it) remember reading a paper in a Veterinary journal years before..then find it and start a new line of investigation into why, when and how plus how to deal with it……There are parallels with that and relying on AI for info….
AI is a useful tool but not necessarily always correct for accurate information and much background but important content will probably be missed if the original isn’t read aswell ……That surely applied to RNSs as much as scientific papers
Just a thought but ………….
That made me chuckle, Penny.
As a dairy farmer's son, I always think of the other meaning of AI too!
I remember many years ago working for Genus who provided the straws for AI.
Penny, please stop writing comments like this. There are thousands of investors clinging to the idea AI is the answer to all and everything and all your comments do is undermine them!! As someone who works at a fairly senior level in IT I think your and yours observations are pretty spot on BTW.
I have recently reviewed three investments by Cos in AI. One is closing their "AI" section down. The other is "experimenting" to keep someone on the board "happy". The other is running a pilot to improve their searching for documents! None of which are world changing or going to provide the providers (Google Microsoft, Amazon) with anything like the return they need to justify their investments.
Old school IT system fundamentals with a shiny new wrapper - garbage in : garbage out.
Hi Penny,
I remember an interview with Google when the company was in its infancy. Larry & Sergey explained that Google was a 'Search Engine' and not a 'Truth Engine'.
David.
Looking forward to thoughts on ASOS now after this news...
Still not a sustainable business model yet at Asos (LON:ASC) . Looming debt cliff (2026 I think?) now a smaller cliff. And "IF" they can get the refinancing done (new convertible bonds) then its secure for another few years to 2028.
However, that debt will have much higher interest rates. And what price / concessions will the bonds have to convert to equity? Might make the current equity almost worthless.
The key still is whether they can stem the revenue declines, and generate enough of a profit margin here... to make this a viable business... and not breach the covenants of their new debt...
Good morning Paul and Graham, you might have missed my late afternoon polite request for a review of yesterday's Cairn Homes results. We hold and they made uplifting reading compared to UK builders performance this year. You covered them 29/2/24 Graham and I'd be interested in your fair value opinion now. I can see you have another busy schedule but I live in hope you might find time to comment.
Ditto for JASVFS comment to Paul/Graham please for Cairn Homes (LON:CRN) and also Glenveagh Properties (LON:GLV) which came in with their H1 results this morning.
Hi Paul,
If you get a chance can you have a look at Alfa Financial Software LON:ALFA. It's on your list so I suspect you will, having read the RNS it seems to have a rosy looking outlook statement.
Thanks for brining back the mystery share in your podcast (which I listen to in full every week). I have upped my contribution to Zane as your reward. I have to say I really like the style of it and even like the odd outburst of frustration at a subscriber who winds you up. I also love your odd foray of madness and then contrition as you ignore your own advice! The value of the mystery share for me is it translates into, "if I had the time this is what I would look into in more detail first" and helps me navigate the prodigious detail of Stocko. Keep up the good work.
Two portfolio companies reporting this morning.
Funding Circle Holdings (LON:FCH) As mentioned below the interims read very confidently on first reading. Still getting to grips with the numbers, but the future does look very promising.
Jet2 (LON:JET2) a super company with excellent management not given o hyperbole. Happy to remain invested.
Jet2 (LON:JET2)
Happy to remain invested.
i am very happy new holder here - i finds todays update mildly irritating - but thats not a biggie. My pet hate is companies that deliberately act sketchy to shareholders when they have know forecasts in place and the reality is that forecasts are being updated behind the scenes on nudge nudge wink wink basis - or there is a complete void so that there is likely to be wild swings if the nudge nudge wink wink aint happening and everyone is in the dark.
I dont think Next ever gloss of trading when they update the market (feel free to correct me if thats wrong) - and its a shame that most companies dont follow suit with very clear reference to current consensus.
In that regard Jet2 have passed the buck today so we are in the dark - there is narrative here ref current trading so we are left to make our own conclusions as to how this will affect forecasts thats a poor starting point if brokers start upping or lowering forecasts as that would tell us others are being told and we are not. Note at least then company is being clear that they are not providing guidance today so at least they have being semi transparent that they either havent worked it out or its as you were or they dont have enough information now to update - personally i wish they wouldnt act in sketchy manner and were bold enough to say as things stand we are on target or advise otherwise (eg boradly in line). The good news is this company seem on the ball - so i am hopeful that if anything perhaps they are simply leaving room for slight beat if things goi well - the reality is though as they arent updating clearly we simply dont know if they are still on track or not - other than its reasonably clear they are not materially offf track (unless they are screwing us over). Note they have said they will update 21st November so we have to kinda act like they didnt even give us an upodate today - albeit main good news is there is no bad news as i dont need the company to outpeform.
However, given the late booking profile, the remaining summer months of September and October not yet complete, plus the majority of Winter 2024/25 seat capacity still to sell, it remains premature to provide definitive guidance as to Group profitability for the financial year ending 31 March 2025. Consequently, we will provide a further update at the interim results on 21 November 2024.
Fair point; however I don't think the Jet2 (LON:JET2) are being coy. The management are, in my view above such shoddy behaviour.
Next (LON:NXT) is the gold standard in terms of reporting. A pity Simon Wolfson or should I say Lord Simon Wolfson isn't the PM at least we would have clarity on the country's finances and the outlook.
Jet2 (LON:JET2)
Fair point; however I don't think the Jet2 (LON:JET2) are being coy. The management are, in my view above such shoddy behaviour.
I would agree with you in that regard - there probably isnt any need to update now either if its like mid update period and they are on track - so not really a biggie - more important is whether management have control of projections taht do exist and plans are clear - in that regard unlike some other companies (saga) they clearly arent heading in an aimless direction.
Takeover boom seems to have evaporated ?
The start of year boom of takeovers seems to have evaporates ?
Remember the large number at start of year maybe
- valuations are higher ?
- USD rate is 1.3 ish now so not as good value for american buyers ?
- no one wants to invest in UK assets because we now have a government in charge clearly either anti business or more simply cant be trusted
Why bother buying a UK company when youll get taxed on the profits ?
Though if a company is c carrying tax losses that value has increased .
I nearly bought the brand hot tuna once out of administration and it cane with 3 million of tax losses which meant if you valued the tax losses they were paying you to buy it.
My FD advised me not to bank on valuing rhe tax losses as they were not cast iron so we ended up under bidder to. Mike ashley of all people .
I seem to remember transense have good tax losses so they wont be paying corporation tax for a while , but first they need to make the profits !
fiddling at the edges really but the hot money has left thre uk
Niox (LON:NIOX) is carrying huge tax losses. Christopher Mills has mentioned this several times and should make them an interesting target.
I hold a small position in Transense Technologies (LON:TRT), shouldn't have taken it really as I should be concentrating on dividends at my age but it was a fun and so far profitable thing to do. The shares are being shorted, can't think why, but I'm still going the other way.
How can you shares are being shorted ?
Good morning planetx, to clarify and remember that I'm still wet behind the ears, I'm going by Stockos stock report:
Seeing this creates greater volatility to the share price meaning I won't be surprised to see it drop, what say you?
Thats just a screen so unlikely to be any short selling .
Im pretty happy with transense, now my seccond biggest position following 50% gain.
Ryan Maughan impresses me as hes very commercial having learned by building and selling his own business .
The previous business was effectively a university spin off run by scientists who were commercially clueless and did not give a shit about the most basic business fundamentals , they were getting well paid with not a care in the world about orofits being higher than costs .
Chairman is good
Technology is good
Guaranteed revenue is good
The tyre monitoring division is a shoe in .
So still positive though i did trim 5% of my holding 2 weeks ago which caused spike down .
Illiquid
Thanks, your answer much appreciated. As ever, there is lots to be considered but I'll stick with it.
Hi Planets
If you look on LSE (londonsoutheast) then on the particular stock there is a separate tab for short positions
Hi
Notified short positions can also be found here: https://www.fca.org.uk/markets...
You know doubt remember Boris Johnson's infamous comment about business planetx? They did. Give the new team a chance, Rachel is going to give you a tax road map, all you got last time was potholes. Get your bike out tomorrow and enjoy a good early ride.
Not a chance Im giving labour a chance .
I dont mind pot holes and I liked Boris .
I work in the real world and if you have your feet in the trenches you ate the first to really know whats going on .
Ill be joining fhe exodus of entrepreneurs who see opportunity and enthusiasm in all areas of the glove and want a new challenge that is welcomed with open arms .
If you could build a business anywhere in the world why on earth (pun) would you choose the UK
Its timimg also aa my kids are almost gone, so one last roll of the dice in business, did 30 years here last 10 will be halfway across fhe world whete the sun shines and the people want to work and have fun in the process .
Good morning
Helpfully, someone set up a thread for discussing politics
Not sure commenting / raising the sudden drop in takeovers should be on a politics thread.
Could be as simple as exchange rate moves (i mentioned several possible causes)
A hell of a lot of takeovers happen at times of opportunistic exchange rates .
When we had several buyers circling at planet x I thought I would know all interested parties but KPMG pulled me to one side and basically said would likely be an American buyer simply because it was 1 usd equals 1 GBP and simply the americans knew the UK was cheap .
So , politics aside
- has anyone else noticed vastly reduced takeover of our “sitting ducks”
- what is the prime reasoning for the start of year surge and current fall in takeover activity
No need to mention politics
Valuations, at least for listed small companies haven't changed dramatically, so perhaps boards are rebuffing more opportunistic approaches. All the data is pointing to an improving economy in the UK, against the backdrop of falling inflation and interest rates so maybe the confidence is there to knock back initial approaches at a small premium . And of course our fantastic regulatory system would mean you'd never even know any approach had been made !
Planetx I'm of the view that the takeovers have only paused, probably for the summer. Not necessarily going to be all USA. As the economy in the UK is on the move again and there will be more interest rate cuts over the next 12 months I expect to see IPO market stirring too.
2 ITs announced Recommended Offers yesterday albeit one had been dragging through the whole summer.
Seems to depend which side of bed you've risen from as to what your view is. We're all guilty of that from time to time. Would suggest we may be in for 10 years of this crowd, whether good or bad, as Tories have a pretty sh**e list of candidates to haul them out of the mire. Any lurch towards Reform could see them face . So let's hope the new Govt moderate their actions if not their gloom and doom mongering.
Best of luck wherever you migrate to... The grass is always greener.
halfway round the world from Yorkshire is New Zealand - 6 months there and 6 months in Yorkshire and you'd have perpetual summer
I know we have global warming, allegedly, but 6 months summer in Yorkshire is stretching it a bit.
I liked Boris too, he'd have been great to enjoy a beer with but imo should never have been PM. My younger cycling pal is on crutches from a broken pelvis after hitting a pothole so good luck in avoiding them.
We're all capitalists on here, you'll have earned profit under Labour so why the blindfold now? There'll be winners and losers just as over the last 14 years, we're on here to have a better chance of backing winners. We're too old to emigrate now but I was sorely tempted in 2016 and I encourage our grandchildren to think about living elsewhere while selfishly hoping they stay here.
Our children have retired, three of them worked mainly in the Far and Middle East, I'd never been of the bus route until my 30's but our kids got me travelling, we've seen the work ethic in Singapore Vietnam and Hong Kong to name just three places. My guess is you're heading for Australia though. Good luck and I for one hope you stay on Stockopedia.
We might have only got potholes from the Tories and Reeves may well give us a road map except that the Tories' potholes will be turned into huge craters along the route.
Isn't it about time political opinions like this ceased? Whatever you might think personally of the current government, they haven't actually done much so far - until the budget, political views based on what might happen rather than what actually has are simply speculation.
Actually I dont agree .
The actual people that know whats going on 6- 12 months in advance of results etc and in advance of politicians is business owners.
So best to sit up and take notice and listen to the facts on what is actually happening .
Funding Circle Holdings (LON:FCH) look to have issued a smashing set of results. Another £25m going to buybacks, which should continue to support the share price and business moving ahead on all fronts. A big holding of Rockwood Strategic (LON:RKW) and worthy of research imo.
Funding Circle Holdings (LON:FCH) Agree - fingers crossed that the chances to keep accumulating under £1 are done. Markets still looking soggy though.
Live at 9.30am on tomorrow's Vox Markets Exchange (Friday 6th Sept), I will be interviewing super smart global investor Patrick Armstrong of Plurimi Capital .
It's sure to be another fascinating discussion - particularly after the recent market volatility & ahead of the important US jobs data in the afternoon.
Including not only lots of investment ideas such as the 'Mag 7' tech titans, #RR., #ABF, $AMD, #BA. #BA #BARC, #EZJ #IGG #WISE, $PYPL, $WMT, #SGE , Roche , Novo Nordisk & many more.
But also how to safely hedge one's portfolio in these uncertain times, and even invest on the short side.
If you'd like to ask any questions, then please feel free join us here on Youtube. Everyone is welcome.
These interviews you organise/present are invaluable Paul - thanks! - often revealing a range of professional investors perspectives on specific stocks, often when they are all holders or tracking them. The macro views useful too.
Great Paul. Will be tuning in. Also, do you have any plans to have Stephen English of Stella or Alexandra Jackson from Rathbones on again anytime soon?
Interesting podcast, Paul.
I always learn a little something, and occasionally pick up ideas for the style of investing that I'm trying to pursue.