Small Cap Value Report (Thu 6 April 2023) - G4M, MOTR, RWA, SOLI, XPD, FUL, ANX

Good morning from Graham and Roland!
This will be the final SCVR until Tuesday, as the UK market is closed for Easter bank holidays on Friday and Monday.
Today's report is now complete (10.15). Enjoy the long weekend!
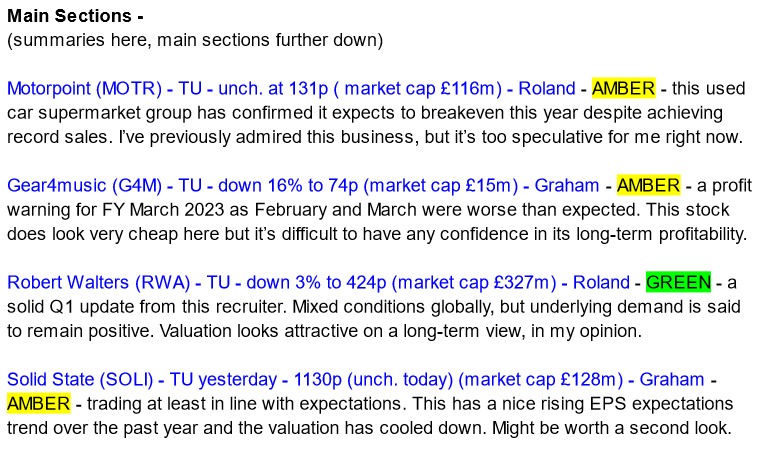
Quick comments -
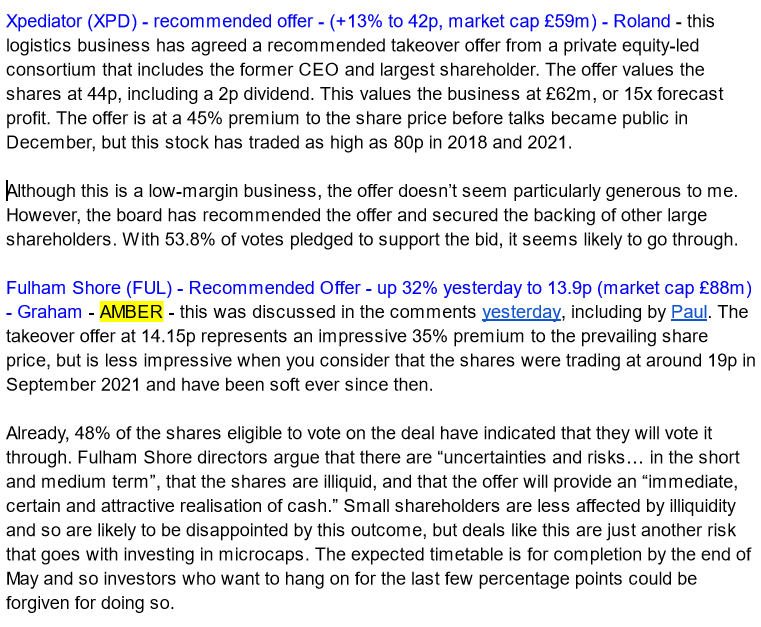
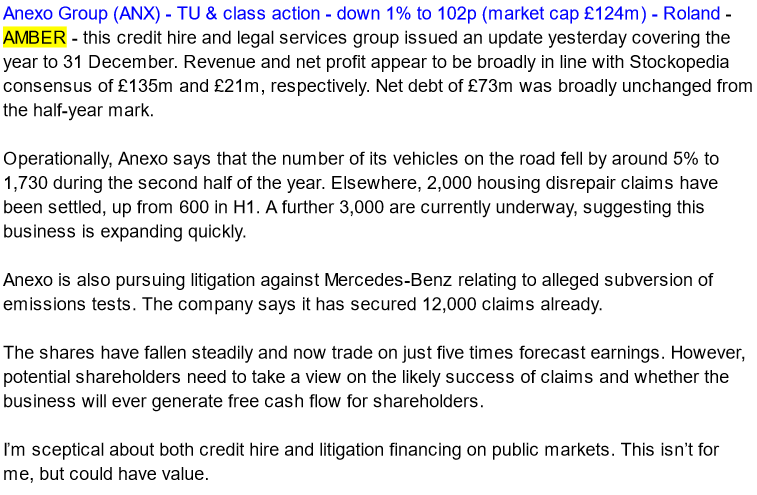
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's section
Gear4music (HOLDINGS) (LON:G4M)
- Share price: 74p (-16%)
- Market cap: £15m
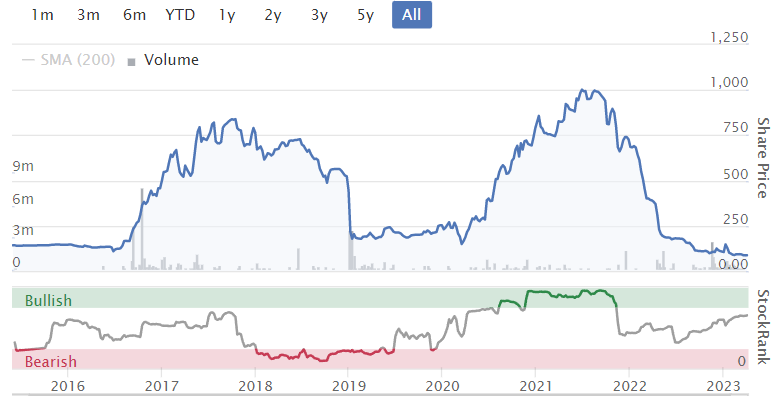
This is a stock that Paul usually covers, but here we are! Gear4Music is an eCommerce business that sells musical instruments. It has an amazingly volatile share price history:
Today we have a year-end update for FY March 2023.
These numbers are below expectations, as revenues and profits were “impacted by weaker consumer demand during February and March”.
Total sales £152m (expectations: £155.1m). The UK underperforms Europe and Rest of World.
Gross margin at 25.7% is weaker than last year, but perhaps this is the “normal” level for margins?
EBITDA £7.3 - £7.7m (expectations: £8.9m)
Net debt reduced by £10m during the year to £14.5m - that’s one bit of good news, as it was only expected to reduce to £17.5m.
Even if the numbers are disappointing on the whole, I greatly appreciate the transparency of this update. Most other companies require you to look up the broker notes to figure out prior expectations - thank you to Gear4Music for including this information in the update!
Looking ahead, there is “further reduction of net debt and a return to more profitable growth expected during FY24”.
I agree with Paul’s prior comments that the level of HSBC debt here was inappropriate. Fortunately, it appears to be heading in the right direction as inventory is reduced to the usual levels.
CEO comment: he reiterates the belief that FY 2024 will be better than FY 2023.
The further investment into our European distribution infrastructure during FY22 underpinned our progress in Europe during FY23, although high rates of inflation continue to squeeze consumer spending on discretionary items across all of our markets. In the UK, as previously announced, courier disruption impacted trading during our busiest period.
We are confident, however, of profitability recovering in FY24 as growth initiatives such as AV.com gain traction and the benefits of our continued focus on overhead cost efficiencies filter through.
The company is now offering second-hand products and trade-ins - an interesting idea! They will be competing with established operators in this space including eBay, Facebook Marketplace, Gumtree and Reverb.
My view
I’m sympathetic to the view that this stock offers investors a value opportunity.
Some reasons:
Great progress in debt reduction.
Exceptionally low price to sales multiple in the region of 0.1x
Shareholders have not been diluted yet, despite various acquisitions and extremely volatile trading. Management appear suitably reluctant to raise equity except as a last resort.
But we also need to be realistic about the stock:
Not very profitable in these conditions; needs a rejuvenated consumer to get it performing again.
Gross margin under some pressure. Pricing power remains questionable. Competitive market.
Unlikely to have the quality or resilience to justify holding any bank debt long-term; therefore should probably not pay any dividends until this is resolved.
I’m content to stay neutral at this level.
Solid State (LON:SOLI)
- Share price: 1130p (unch. today)
- Market cap: £128m
I checked out this company’s interim results in December, when it raised its expectations for the full-year. Yesterday, it produced a trading update for FY March 2023.
It describes itself as “the specialist value added component supplier and design-in manufacturer of computing, power, and communications products”.
Performance in H2 was strong and therefore FY March 2023 is again at least in line with consensus expectations
Revenues up 47% to £125m (expectations: £120.3m)
Organic revenue growth at constant FX is an impressive 20%
Adjusted PBT up 46% to at least £10.5m (expectations: £10.45m)
In August 2022, Solid State agreed to pay $45m for a California-based battery/energy company: Custom Power. It is performing in line with expectations, but is not going to achieve a full earn-out for the vendors, based on its revenue targets. So that will reduce the amount payable by up to $5m.
Contract wins: previously announced contract wins with NATO will “dilute the margin mix” but “contribute positively to the attainment of expectations for FY23/24”. I’ve remarked previously that Solid State puts a lot of focus on margins - but clearly they’re not going to say no to NATO contracts, even if these contracts hurt margins!
Order book: £120m extending over 18 months, up from £85.5m a year ago. There are still some supply chain challenges in the electronics industry, and this may be contributing to the bloated order book.
Solid State says it is navigating the situation:
…inconsistencies remain such that pro-active inventory management continues to provide competitive advantages to the Group and supply chain confidence for clients.
My view
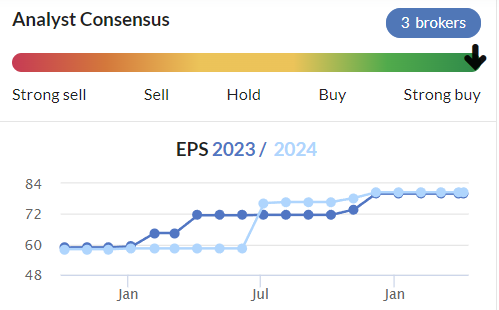
This one continues to strike me as a better-than-average manufacturer and distributor. I like management’s focus on margins, I’m impressed by the trend in earnings expectations over the past year, and returns are adequate.
EPS trend:
Returns:

The share price has retreated to where it was during late 2021/early 2022, so this could be worth digging into in more detail.
Roland's section
Motorpoint (LON:MOTR)
Share price: 131p (pre-market)
Market cap: £118m
The used car supermarket group has issued a year-end update today confirming it expects to breakeven this year at a pre-tax profit level on record sales of £1,437m.
It’s a dramatic comedown for a company that generated over £21m of pre-tax profit during its previous financial year (Motorpoint has a 31 March year end).
The share price has reflected this brutal decline, falling 65% from the record highs seen during the pandemic:
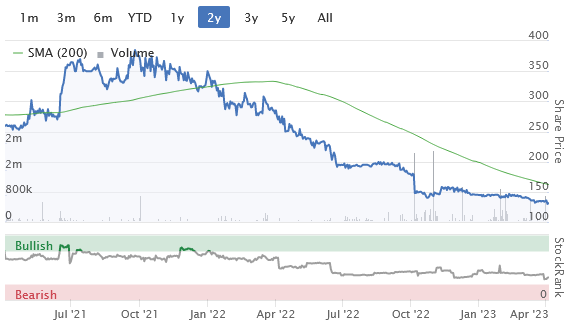
I’ll look at Motorpoint’s business model and the reasons for this slump in a moment, but let’s start with the main highlights from the year just ended:
Record revenue of c.£1,437m, up 9%
Pre-tax profit expected “to be broadly breakeven”
3.5% market share for vehicles under four years old (Dec ‘21: 2.7%)
£5m cash at year end and “significant borrowing headroom”
New Chief Technology Officer to drive digital growth
Net Promoter Score at “industry leading 84”
What’s gone wrong? In an update in January, management said that higher financing costs and falling prices on some electric cars had led to a reduction in gross profit per vehicle sold. Unfortunately, the company’s costs – staffing, energy, rent and stock financing – will not have fallen.
The wafer-thin margins on used cars leave no room for error, so Motorpoint’s historic profitability has evaporated.
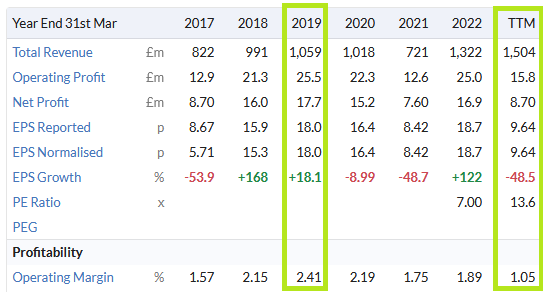
In my coverage of Lookers (LON:LOOK) yesterday I commented on the importance of aftersales income to car dealers. This is why.
Conventional car dealers also earn low margins on their car sales. But by owning freehold property and securing high-margin aftersales work, dealers can more easily absorb some variation in margins on car sales.
For Motorpoint, it’s much harder. This trend could reverse at some point, though, and profits could rebound very quickly. Chief executive and 10% shareholder Mark Carpenter believes we could be approaching such a turning point:
"Whilst the impact of higher interest rates and inflation will continue into FY24, new car registrations rose 18% in March, with the fleet market driving this eighth consecutive month of growth, which will in turn benefit used vehicle supply. This, coupled with continued market share gains and progress on our key initiatives, will enable Motorpoint to emerge from the current environment a highly profitable market leader."
My view
I’ve previously had a favourable impression of this business and have owned the share in the past. Motorpoint’s policy of specialising in high-quality, nearly-new cars in bulk at competitive prices has given it a significant share of the market and strong customer loyalty metrics.
I can’t deny the risks here, though. This business depends on earning a wafer-thin margin on high volumes of used cars. If volumes slow, financing costs rise, or used car prices fall, this model is disrupted.
If macro trends continue to go against Motorpoint, the group’s financial model could break down altogether. Unlike conventional dealers, it can’t backstop losses with aftersales revenue or property sales.
On the other hand, if market conditions stabilise and the company’s core strengths return, profits could bounce back quickly.
On balance, I am cautiously optimistic that Motorpoint will survive and return to profitability. I’m also encouraged by the presence of owner-management – CEO Mark Carpenter has also seen his net worth plummet with the share price.
However, the situation is too risky for me to take a positive stance at this point. There’s no way to be sure the group will outlast difficult conditions in used car markets.
Robert Walters (LON:RWA)
- Share price: 424p (-3% at 08.40)
- Market cap: £327m
Today’s update from recruiter Robert Walters covers the three months to 31 March. It highlights challenging macroeconomic conditions in global recruiting markets, but does not seem to flag up any new problems.
CEO Robert Walters seems to be confident that underlying recruitment demand will remain positive, when conditions stabilise:
"It is worth noting that recruitment market fundamentals such as vacancy levels and salary inflation remain relatively robust, which coupled with a systemic global shortage of qualified professionals gives cause for optimism that activity levels will bounce back when global market conditions become more benign.”
The group’s Q1 revenue figures highlight the geographic diversity of this business (all at constant currency):
Q1 revenue: £102.4m (unchanged)
Asia Pacific: £43.4m (-3%)
Europe: £34.3m (+10%)
UK: £16.3m (-9%)
Other international regions: £8.4m (+8%)
Other operational metrics suggest a stable position:
Headcount up 1% quarter-on-quarter to 4,403
Net cash: £70.5m (December 2022: £97.1m)
One potential positive factor is the re-opening of the Chinese economy. The company says that net fee income in Mainland China fell by 44% during the quarter. I’d imagine that a return to normal here could provide a useful boost.
The company’s commentary on the UK market suggests that financial services hiring is holding up well, but other sectors are more muted.
My view
This recruitment group is one of my top choices in this sector. It provides global exposure and has a solid history of shareholder returns.
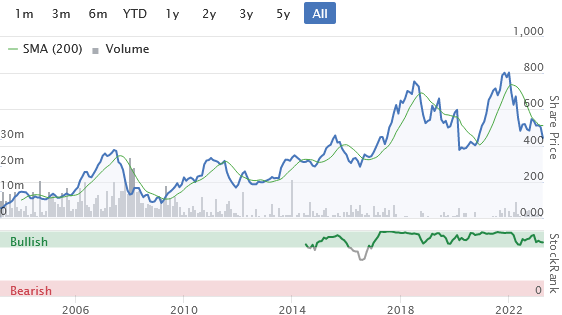
There’s also been no dilution for at least 10 years:
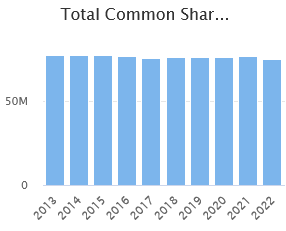
The shares look decent value to me on nine times 2023 forecast earnings. The dividend yield of 5.6% should be covered twice by earnings and backed by net cash, reducing the risk of a cut.
I’ve no idea what the short-term outlook will be for this business or the wider market. But taking a long-term view, the chart above and the company’s recent results suggest to me that now might be a good point in the cycle to begin building a long-term position.
Stockopedia’s algorithms reinforce this view, with a high StockRank and Contrarian rating:
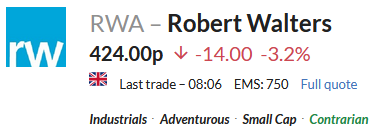
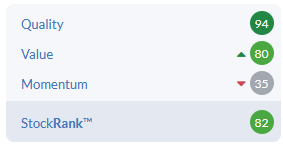
One possible risk is that founder-CEO Robert Walters will be retiring later this year after 37 years.
A successor has already been appointed who has been with the group since 1999, so I don’t expect massive change. But the departure of a long-serving leader is often an inflexion point, I’ve found. Founders often have good timing, too.
However, on balance I have no qualms about taking a positive view on Robert Walters. I think the shares look reasonably valued, with a solid balance sheet and excellent track record.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Arbuthnot Banking (LON:ARBB) I know a few interested folk in these. Couple of broker notes out and a bit of divergence between the two looking for somewhere between 180p adj EPS and 240p next year. Quite a spread! but puts it on a PE of just 4 and with a price to book of 0.6 share price looks anomalous to me. Particularly with divi at 5% for income.
Brokers appear to have 1600-2000p as 12M target valuation which would be 1.1 - 1.3 * book.
Very high liquidity ratio with immediately available cash of circa 50% of depositor base so little risk of a run. Balances held at BoE in central bank accounts - ie no mismatched duration to see here either!
Stockopedia have updated arbb forecast and stock ranks big jump into the green, when buying comes arbb will fly 1000p resistance. Half year results will look amazing v last year, agm soon. Value to win out.
RE Arbuthnot Banking (LON:ARBB) David do you have any issues finding what prices will be - bid and offer - because on Aquis?
Hi ridavies
Arbuthnot Banking (LON:ARBB) is AIM listed (not aquis) so should have no issues on bid/offer.
Do note though that there is a non voting share listed on Aquis, which from memory was a sort of dividend given to existing shareholders a year or so ago. I had forgotten I had these but they are only Aquis listed I think and trade around half the price of the ordinary.
Cracking SCVR today fellas! It's been really strange reading the report as a customer instead of a writer! But it's reinforced to me what a great format this is - a really quick way to read about company updates, to find new stock ideas, with useful background about the companies, written by experienced investors/analysts.
G4M looks a decent bet at these levels. I had an order in at 70p that got filled this morning. Never thought that order would get filled to be honest so very surprised we've come down to these levels.
Let's see what happens from here... has the worst been priced in or more downside to go I wonder? Interesting times for sure
Good morning!
Here are my brief thoughts on Gear4music (HOLDINGS) (LON:G4M) profit warning today.
Disclosure: I bought a small opening position earlier today, at 79p. I'll sit and wait, before deciding whether to buy any more, but no plans to do so for the time being.
My notes & comments -
Mild profit warning, as weaker demand in Feb & Mar.
Lower gross margin of 25.7% - remember this includes cost of P&P, so the clean margin on the product itself is in the low thirties. Still a low margin, but average transaction value is high, and returns are low. So it does still stack up, and the company makes a profit from the first purchase, ie. it's not dependent on repeat business.
Net debt nicely down, to £14.5m. This is the key point for me. I'm not worried about slightly softer trading currently, it was the bank debt that concerned me most. It's now come down a lot, driven by reducing excessive inventories, which was what the company said it was going to do, and it's worked. So for me, the much lower level of debt now makes me comfortable to buy - I've been sitting on the sidelines, waiting for an update, and in particular would not buy unless happy with debt, which I am now happy with.
Singers says G4M now comfortably within bank covenants. So again, this shouldn't now be a concern for investors. That removal of a serious concern is worth the share price going up, not down! Also it means with lower debt, and a lower share price, there's a double benefit to enterprise value (i.e. it's lower, so cheaper for investors buying the share now).
Expecting a further reduction in debt in FY 3/2024, is reassuring.
Only trading around breakeven, Singers new note says £(0.4)m LBT for FY 3/2023. I wish G4M would stop quoting nonsensical EBITDA numbers!
Confident profits should recover in FY 3/2024 - mgt has a good track record of being straight with investors about the outlook, so I'm encouraged by this. It's not mentioned today, but much lower freight costs from China should be a nice tailwind now. Other supply chain costs & disruption may also be normalising.
Secondhand trade-in marketplace, you can see this on G4M's website. This is a nice idea, and should be an incremental boost to profitability. It pays more for trade-ins (ie. money off new purchases) than cash sales. I suspect this is likely to be popular with customers, and comments today sound encouraging about it.
Overall - is it a great business and/or sector? No. But it's a well-managed growth company, going through a tough patch as the pandemic boom hangover works through the system. I think this year's results could be the base level, with future years building on it, and hence a re-rating of the shares likely in calendar 2023 & 2024 possibly? I've bought today with a 2-year timeframe for waiting to see what happens. I'm looking for a double or tripling of the current share price, as my upside case. Downside case is limited now, because debt is falling, and is no longer a problem to my mind. As a low margin business it doesn't have to worry too much about a decline in demand, as it can just cut costs if necessary, and on a c.26% gross margin, there's precious little leverage to the bottom line.
I now find the valuation attractive, so have dipped my toe in with a little purchase today, then I'll watch and see what happens, and buy more (hopefully) if it drops to say 50p, which would be the level I'd be inclined to up my position to a full size one.
There's also bid potential. The founder is loaded, after some lucrative share sales, and might just decide to take it private again. Although as we saw this week with Fulham Shore (LON:FUL) don't expect founder buybacks to be generous.
Above is obviously just my personal opinions, which might turn out to be wrong, or right, as the facts change constantly, and I'm not a clairvoyant.
Thanks for your thought ‘s Paul. Topped up my already fairly substantial position as I think it highly unlikely we will see levels as low as 70 again . Obviously, there is a risk of a bid but suspect this will not be lower than 120p so it’s a no brainer at these levels .
Gear4music (HOLDINGS) (LON:G4M)
Revised forecasts from Progressive now published:
https://progressive-research.c...
Robert Walters (LON:RWA)
I’m quite comfortable with prospects at this quality recruiter. Obviously a global recession, if it occurs, would send shares lower, but most of the business is exposed to markets that are not in imminent danger of recession, being continental Europe and the APAC region. The TU this morning specifically highlights China’s lockdown, still in progress or at least influential in its aftermath for the whole of the first quarter, as the primary drag on growth - but the brakes are coming off now. Meanwhile, big changes in Japanese employment trends point to an upturn in the company’s biggest single market. The secondary limiting factor has been the shake-out in tech recruitment, to which RWA is more exposed through its heavier emphasis on perm. But these hiatuses are usually fairly brief, lasting 2-4 quarters, before tech hiring goes full steam again. This will be a fairly flat year, in my opinion, with a small drop in earnings from record levels, but you are compensated by a historically low valuation and a superb, well covered dividend. Things could get worse and deliver an even lower price, or they might improve to reveal that this is the bottom. Over a reasonable investment period, this looks a good entry to me into a company of significant quality.
Hi
Gresham House Energy Storage Fund (LON:GRID) just about in SCVR range. Current Stocko PE 6.9, div. 4.54%.
Full year results to 31/12/22. Copy from top 2022 highlights ....
2022 performance highlights
· EBITDA of the underlying portfolio of £48.8mn, a like-for-like increase of 23.2%
· 155.51p NAV per share as of 31 December 2022, up 33.1% (31 December 2021: 116.86p)
· 7p per share dividend to be paid in respect of 2022, covered 1.28x
· NAV total return (TR) of 39.1%
· NAV TR since IPO increased to 93.2%; 17.2% on an annualised basis
· Performance mostly driven by revaluation of new projects and increases in third-party revenue forecasts
Full RNS here ...
https://www.investegate.co.uk/...
Copy of 2023 outlook .....
2023 outlook
· Q1 NAV per share expected to be driven by +3.3p from incremental project revaluations and +2.2p from newly awarded Capacity Market contracts. Other factors, including any changes to revenue curves or discount rates are still to be determined
· Operational capacity is expected to reach 1GW in 2023 and c.1.5GW in 2024; growth of 80% and 170% respectively vs year-end 2022 which is expected to drive NAV per share and EBITDA growth
· In light of growth in EBITDA from increased operational capacity in 2022 and expected in 2023, the Board intends to pay a dividend of 7.35p per share for 2023, a 5% increase over 2022. The Board will periodically review the dividend policy to maintain a competitive dividend yield while also ensuring that dividend cover is strong
· The Manager is trialling a new trading revenue opportunity on a small number of MW which has the potential to add a new income line to our revenue stack if the trial is successful
Share price has been in tight range recently but dipped over pas few days. It is up +0.88% as I type. This might tick up a bit further possibly?
In RNS there is link to live Webinar 6/6/23 11AM. If you are new to this sector, Gresham House Energy Storage Fund (LON:GRID) usually do a very informative presentation about their fund and the battery storage sector in general.
I hold a little.
Regards
Howard
Hi Graham and Roland, any chance of please looking at a backlog item CMC Markets (LON:CMCX)? Has good stocko metrics, but has taken big fall on a reduced outlook. P/E of just under 9, loads of cash in the bank, some new regions opening up. I'm a holder, but wondering if it's a falling knife.
The thing that bothers me is Jefferies downgrade last week and open questioning as to whether CMC Markets (LON:CMCX) [I hold] is losing market share in its core business. I see also the Stockopedia now ranks as a Contrarian (from Super Stock at the end of March), the value and momentum metrics are in the process of passing each other as the ranking switches rapidly from QM to QV.
Like you I've noted the Stock Rank has ticked up a little the last few days, and so have also sat on the fence wondering whether to stick or twist. Normally I'm out at the first sign of trouble but we weren't given the chance with the announcement made near the end of a trading day catching me out, (maybe that's an alarm bell in its own right).
Right on cue though I see there's a small bounce today, (showing signs of petering out before my coffee's brewed)...
The broker downgrades have stopped me jumping in as well. I do wonder whether the mistimed RNS has added to the fall.
The broker valuations are widely different: The 6 analysts offering 12 month price targets for CMC Markets Plc have a median target of 242.00, with a high estimate of 355.00 and a low estimate of 190.00 (Jefferies). The next trading update on the 14th should provide further clarity. I too hold but will decide whether to add or dump after the 14th.
Pretty poor takeover price for Xpediator (LON:XPD) I thought - 44p giving a forward p/e of 10x still too cheap. Any shareholders here happy with that ?
No! Xpediator (LON:XPD) gone for a song!
XPD - As Paul has expressed a low margin business, however I'm amazed that despite an offer of 42p on the table the share price has traded below this at around 37p for a considerable time since it was made despite a good set of recent results.
Xpediator (LON:XPD)
I'm 'inside' so can't go into detail but trust me, it's a fair deal and creates a good liquidity event for investors.
I'm not inside, but I agree with nocobos! Xpediator (LON:XPD) has always struck me as a poor quality business, eking out a tiny profit on ever-growing revenues. The shares have gone nowhere in almost 6 years on AIM. With all the interesting companies out there, why anyone saw anything attractive in this share, is completely beyond me.
Management told some cock & bull story a few years ago when I met the boss, about some exciting eCommerce new service, which came to nothing as far as I can tell.
The exit valuation looks attractive, so I would gratefully accept it, and move on. If you absolutely have to invest in a logistics company, Wincanton (LON:WIN) is a bargain right now, after a recent contract loss, and far better quality than XPD, yet on a similar PER. This deal looks a lucky escape for XPD shareholders.
My morning smallcap tweet: Geared for disappointment
Xpediator (LON:XPD) Rosslyn Data Technologies (LON:RDT) Real Good Food (LON:RGD) Gear4music (HOLDINGS) (LON:G4M) Lords Trading (LON:LORD) Helical (LON:HLCL) Sigmaroc (LON:SRC) Motorpoint (LON:MOTR) Robert Walters (LON:RWA), Fulcrum Utility Services (LON:FCRM)
◄Xpediator (XPD)► agrees 42p + 2p special div offer. That's 2p better than mooted. [SP=38 Cap=54m]
◄Rosslyn Data Technologies (RDT)► guides FY-Apr £2.9m and ARR £2.6m Adj EBITDA loss £2.4m (£3.9m loss). Cash at hand £0.8m. In line? [SP=0.71 Cap=2m]
◄Real Good Food (RGD)► another choker from this teetering tinpot. Q4 rev below exp. Significant price resets and cost savings having been achieved. Guides FY24 EBITDA £2-4m, and cashflow generative. £550,000 short-term loan from shareholders at 12% and 35% redemption premium. [SP=1.1 Cap=1m]
◄Gear4music (G4M)► warns FY-Mar rev £152m and EBITDA £7.3-7.7m cf f/c £155.1m and £8.9m. Blames economy. If only there had been some signs. "We are confident, however, of profitability recovering in FY24." [SP=86.2 Cap=18m]
◄Lords Group Trading (LORD)► refinanced £70m facilities with £95m on improved terms with material interest cost savings. [SP=69 Cap=112m]
◄Helical (HLCL)► positive sounding update. [SP=301 Cap=377m]
◄SigmaRoc (SRC)► Swedish state appeals case it lost. [SP=54.44 Cap=378m]
◄Motorpoint (MOTR)► guides FY-Mar rev up 9% and pretax broadly break even. In line? "Whilst the impact of higher interest rates and inflation will continue into FY24, new car registrations rose 18% in March, with the fleet market driving this eighth consecutive month of growth, which will in turn benefit used vehicle supply. This, coupled with continued market share gains and progress on our key initiatives, will enable Motorpoint to emerge from the current environment a highly profitable market leader." [SP=131 Cap=118m]
◄Robert Walters (RWA)► Q1 net fee income up 4% and flat at const FX. "Market uncertainty we experienced in the latter stages of last year has tipped over into the first quarter." Asia Pacific and the UK weak. "A return of confidence to the Chinese economy, a stabilisation of the technology sector and a continued decline in inflation should have a positive effect on the global outlook." [SP=438 Cap=329m]
In line: FCRM