Small Cap Value Report (Thu 6 Oct 2022) - MOTR, VIC, CMCX, ECK, FAN, STEM

Good morning from Paul & Graham!
Agenda -
Paul's Section:
SThree (LON:STEM) - I've lined up another of my CEO audio interviews today. These are only occasional, when I approach companies that I think look good, and are trading well, and reasonably priced. We've covered STEM positively here all this year, as it has issued repeated ahead of expectations updates. So I thought it would be interesting to talk to management and learn a bit more about the company. I'm recording it at 15:00, so it should be published here at about 16:00, and will come up automatically on my podcast channel. Here is my audio interview with STEM, I hope you find it interesting.
Motorpoint (LON:MOTR) - quite a nasty profit warning, with broker forecasts slashed by 50-60% this morning. The company tries to explain it as being about "investments" for growth, but I suspect the market is about to take a dim view of this update (am writing this just before the market opens). With profits now largely disappearing, and not much asset backing, it's a lot harder to feel bullish about this share in the short term.
Victorian Plumbing (LON:VIC) - one of many bombed out eCommerce shares. Today's update sounds encouraging, being ahead of (lowered) expectations. I like the balance sheet, with a cash pile of about a third of the market cap. Also a low PER. I do have some reservations, but this share now looks attractively priced, and fairly low risk due to its sound finances, in my view.
Graham's Section:
CMC Markets (LON:CMCX) (£624m) - a nice trading update from CMC. It’s looking to grow profits by 30% over the next three years, from the FY 2022 level. The FY 2021 results are considered a one-off event, boosted by Covid, and FY 2022 is considered to be more representative of normal performance from now on. The market apparently disagrees, however, and has put CMC on some very cheap valuation ratios. If volatility collapsed back to 2018 levels, then I agree that profitability would suffer but I don’t consider that to be very likely and I appreciate the counter-cyclical characteristics of these shares. I also welcome CMC’s move into traditional stockbroking. I like these shares - two thumbs up from me.
Eckoh (LON:ECK) (£128m) [no section below] - the “global provider of customer engagement security solutions” provides an H1 trading update. Orders are up >50% over last year at £17m, in line with expectations. The company provides payment technology, phone systems (“interactive voice response”) and other customer engagement services. According to a note published by Singer today, the revenue forecast for FY March 2023 is £40m, and then £43.2m in FY March 2024. The adjusted EPS forecast is 2p for both FY 2023 and FY 2024. This puts the shares on a current earnings multiple of >20x, which perhaps can be justified on the basis of the growth figures. However, Eckoh made an acquisition in December 2021 (Syntec - annual revenues c. £7m) and so the true level of underlying organic growth is unclear. I note that the company has a net cash position and has developed a good track record of dividend payments since 2016. I take a neutral stance on this share, pending better information on organic vs. acquisition-led growth. [no section below]
Volution (LON:FAN) (£678m) (+12%) [no section below] - this is a “leading international designer and manufacturer of energy efficient indoor air quality solutions”. FY July 2022 results are impressive: revenues up 12.9% to £308m, adjusted PBT up 14.5% to £61m, and actual PBT up 57% to £47m. The company clearly outlines where its revenue growth comes from: inorganic growth is higher than organic growth, and currency fluctuations have a negative impact. All regions are doing well: UK, Europe and Australasia, and with improved non-UK diversification. This is another company developing a nice dividend track record.
Comparing notes to when I last mentioned this stock a few years ago, there continue to be huge year-on-year differences in the “adjustments” applied to its earnings: sometimes they are enormous, while sometimes (like this year) they are less severe. Net debt rises to £85.8m after acquisition spending, but the outlook sounds fine: the new year has “started well, delivering revenue and profit ahead of the same period last year”. I haven’t got a strong view on this one but it’s superficially inexpensive relative to earnings and maybe deserves to recover a higher rating (it was trading as high as 550p in 2021, but has fallen in sympathy with the rest of the small-cap market). [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Motorpoint (LON:MOTR)
178p (pre market open)
Market cap £161m
Half Year Trading Update (profit warning)
Motorpoint Group PLC, the UK's leading independent omnichannel vehicle retailer, provides an update on its trading performance for the six months ended 30 September 2022 ("H1 FY23").
Strong revenue growth, up c.30% to £785m (due to new branch openings, higher spec cars being sold, and price inflation).
Sharp slowdown in volumes of cars sold in Sept, after positive growth over the summer.
Profit warning, which I suspect the market is likely to take a dim view of (am writing this at 07:36), despite the company trying to convince us that higher costs are “investments” -
Accordingly, as a result of the investments during H1 FY23, coupled with the costs of maintaining market leading finance rates at 8.9% (9.9% from 1 October 2022), Profit before Taxation ("PBT") for the period is c.£3m. This PBT is significantly lower than H1 FY22 (£13.5m) and reflects the increased strategic investment (c.£4m) and interest costs (c.£1m) in H1 FY23 and compares against record margins experienced in H1 FY22.
Outlook -
… macro factors will continue to challenge financial performance in FY23, the extent of which is difficult to predict. In this environment the Group will carefully manage its cost base, align its consumer financing rates with borrowing costs, and continue to build technology and digital capabilities which increase automation, data-led decision making and customer self-service, thereby enhancing the agility of the Group to proactively manage its cost base. Further, the Group will continue to invest in important strategic capabilities but only to the extent that it remains profitable and cash generative, and maintains a strong balance sheet…
As has been previously highlighted, the impact of rising inflation, interest rates, consumer uncertainty and worldwide vehicle supply chain challenges are significantly affecting the used car market. Whilst it is prudent to remain cautious given these short term headwinds, the Group will continue to invest now for the longer term in a weakening competitor landscape, whilst also delivering appropriate levels of profitability and cash generation.
Liquidity - sounds OK, but this will need a bit more scrutiny from me when the interim numbers are published -
The Company's balanced approach to investment, profit and cash is demonstrated by the Group growing cash balances during the first half and the absence of any structural debt. At period end, the Group had a net cash position of c.£4.5m (31 March 2022: £7.8m) and stocking finance headroom of c.£70m. The strength of the balance sheet will provide further firepower to continue the planned strategic investment.
Balance sheet - the business model for MOTR is different to conventional car dealerships. So it only sells secondhand (nearly new) cars, and doesn’t do the franchising selling (or servicing) for new cars.
Whereas conventional car dealers tend to have masses of freehold property and strong balance sheets, MOTR does not. Its last reported NTAV was only £38.8m, which is a fraction of Vertu Motors (LON:VTU) which we covered here yesterday. Therefore MOTR shares don’t have that bulletproof asset backing of VTU, making them higher risk.
My opinion - this is a big disappointment. Earnings forecasts for FY 3/2023 and FY 3/2024 have been heavily slashed, to just under 6p for both years, being 50-60% falls. This seriously undermines the investment case, and I’m sorry to say that a big drop in share price looks likely today.
The trouble seems to be that MOTR was egged on to grow more aggressively by American shareholders, but that’s now clobbered profitability. UK investors tend to focus on profit based valuation of shares, and don’t like it when profits are slashed to chase growth, especially in bear markets.
So unfortunately I think this share is likely to join the growing ranks of investments which have gone wrong in the short term, but which hopefully might recover long-term.
Solvency shouldn’t be a problem, providing the key lenders (there’s a lot of stocking loans for the inventories) remain co-operative.
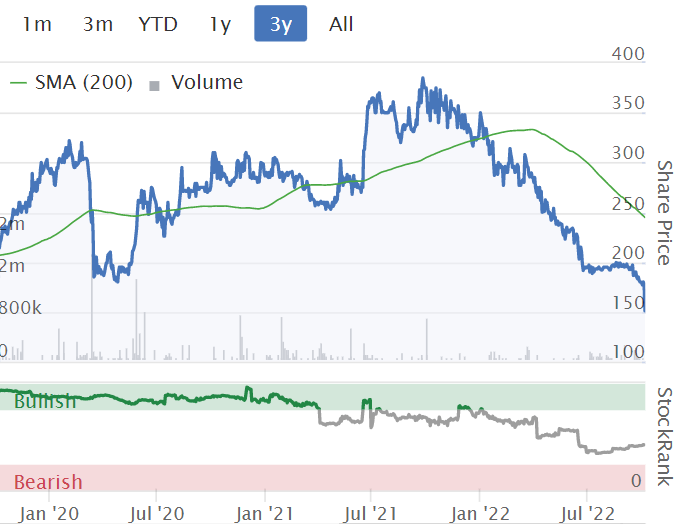
EDIT: I'm surprised it's only down c.12% in early trades to 156p. That strikes me as a selling opportunity, given the size of the downgrades.
.
Victorian Plumbing (LON:VIC)
37.8p (up 6% at 08:31)
Market cap £123m
Victorian Plumbing Group plc (AIM: VIC), the UK's leading online specialist bathroom retailer, today provides an update on trading for the year ended 30 September 2022 ("FY22").
The financial year finished positively with revenue, earnings, and cash flow all ahead of consensus market expectations.
Revenue for FY 9/2022 was flat vs last year, but showed an improving trend in H2.
Revenue up 78% on pre-covid year FY 9/2019.
It claims to be the no.1 bathroom retailer in the UK.
Gross margin improved in H2 vs H1 (but no figures provided).
Cash - this is impressive, considering the market cap is only £123m -
Victorian Plumbing continues to be highly cash generative and we will start the new financial year with in excess of £43m of net cash.
Outlook - fairly vague -
Whilst the operating and economic environment is challenging, as a highly cash generative business with a strong balance sheet and growing momentum through 2022 we enter the new financial year with confidence in our plans for further progress.
Is the balance sheet actually strong? (I always get suspicious when companies trumpet a strong balance sheet, because they’re often deluding themselves). In this case, actually yes it is. NTAV was last reported at £32m. Doesn’t sound that much, but bear in mind being an eCommerce business, it has hardly any fixed assets, and hardly any receivables. Therefore it doesn’t need much NTAV to be in a healthy position. There was no interest-bearing debt, and cash was £33.7m at end March 2022. Net cash is now £43m, so it’s in a very healthy position.
Is it really a “highly cash generative business”? It was during the pandemic, with £24.4m of operating cashflow (after tax) for FY 9/2021. However, the latest interim figures to Mar 2022 show that cashflow dried up to only £3.2m on the same basis in H1.
So the jury is out on whether it actually is highly cash generative any more - doesn’t look like it is, based on the interim numbers.
Marketing costs - management might be referring to cash generation before marketing spend - which is very high. VIC spends an extraordinary amount on marketing, £40.2m in the 6 months to end Mar 2022. That’s 30% of revenues, and it didn’t generate any revenue growth at all - revenues actually fell 5% on H1 LY.
This is my main concern with VIC - the business seems to have to spend colossal amounts on marketing, just to stand still. This implies poor customer lifetime value, and that many sales are just one-offs. Wouldn’t it make more sense to slash prices by say 10-20%, so that customers come back of their own accord, and spend less on marketing, because you wouldn’t need to - the lower prices would attract customers? Maybe that’s too simplistic?
Valuation - i can’t find any broker notes unfortunately, which hampers things.
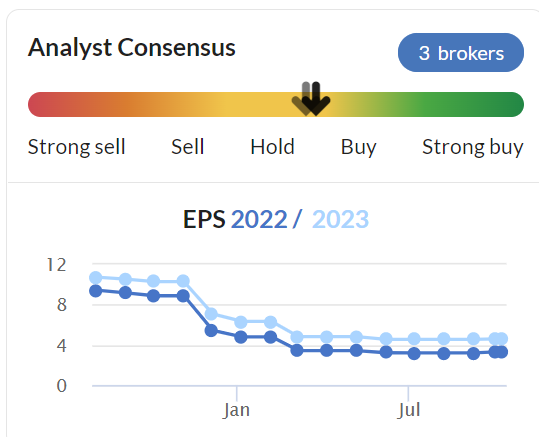
If we use the Stockopedia numbers - see below that forecast EPS has dropped a lot from original expectations, but it’s still profitable, and today we’re told that it’s beaten the market consensus numbers (but there’s no footnote to confirm what consensus figures actually are - a glaring omission, it really should be standard practice to always include a footnote, as many companies are now doing).
.
This graph from Stockopedia shows 3.3p EPS forecast for FY 9/2022, which would put us on a current year PER of 11.5, which looks good value, especially considering about a third of the market cap is represented by the company’s own cash pile.
My opinion - despite my reservations, this share is now looking cheap.
The upside potential for eCommerce shares, is that some structural growth might return at some stage, replacing the boom & bust cycle that we’ve seen in the last 2-3 years due to the pandemic. Also venture-capital backed new entrants are likely to be less of a competitive threat these days.
That could trigger a nice re-rating for some eCommerce shares.
VIC looks low risk (due to the cash pile), is still profitable, and looks modestly valued. That’s assuming the company is able to increase earnings in future - which can’t necessarily be taken for granted, hence why I've ignored forecasts for next year.
Overall though, it gets a thumbs up from me. It seems strange finding eCommerce businesses that are now priced as value shares, after so many years of them attracting sky high valuations as growth companies.
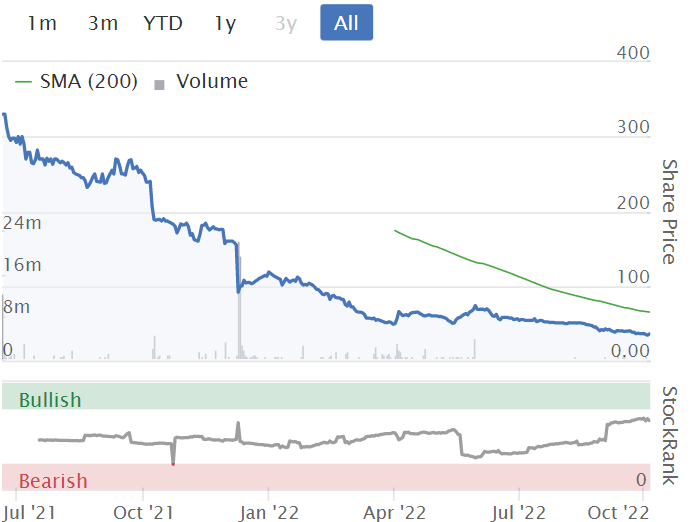
2021 certainly wasn't a vintage year for IPOs, was it?! Most have turned out to be corked, or just over-priced vinegar to begin with!
.
Graham’s Section:
CMC Markets (LON:CMCX)
Share price: 222.5p (pre-market)
Market cap: £624m
This trading platform provider was previously outside of our £700m market cap limit.
In April 2021, its share price reached a high around 540p:
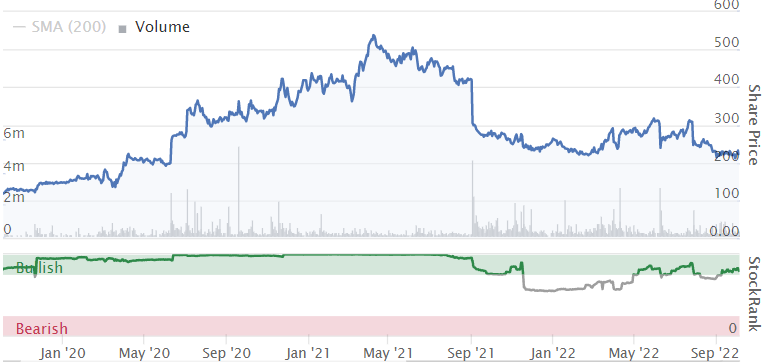
Maybe we need to adjust our market cap limit, depending on whether we are in a bull market or a bear market!
CMC is a competitor to IG group (LON:IGG) which is the third-largest holding in my personal portfolio. So I guess that makes me slightly biased against CMC.
Today we get an H1 2023 trading update. Key points:
- Net operating income +21% to £153m
- Leveraged net trading revenue +27% to £128m
- Non-leveraged net trading revenue minus 14% to £21m
They have launched a new platform for UK customers: CMC Invest, “with the aim of supporting customers throughout their entire investment journey”. They offer ISAs and SIPPs in addition to ordinary investment accounts.
They are a few years late to the party. IG’s share dealing has been around for a while now. I always thought it made sense that spread betting providers should provide investment services: they already have the apps, the trading technology and the customer service infrastructure. All they need to do is let clients access the physical shares (which the spread betting provider is already taking positions in, to hedge clients’ positions).
Even if they are a bit late with this product, compared to IG, I still think it’s the right move by CMC. Note that investment accounts are far less profitable than leveraged trading accounts, but they have more sticking power (leveraged traders have a tendency to lose money and give up within a few years).
Let’s dig into the specifics of this trading update:
- Client leveraged AUM finished H1 at £530m, slightly below the £560m record at which it started the period.
- Client numbers are “moderately lower”, but there is an “overall increase in activity”.
- Similarly, the Australian stockbroking business saw a “modest reduction” in assets under administration, but “activity remains elevated versus pre-pandemic levels”.
Medium-term plans: In FY 2022, net operating income was £282m. CMC is looking to grow this by 30% over the next three years.
(FY 2021’s net operating income was £410m. This was driven by the extreme Covid-related volatility and is not expected to repeat).
Currency exposures: GBP weakness will have the net effect of boosting results due to CMC’s non-GBP revenues.
CEO comment:
We closed the first six months with a pickup in market volatility and client trading volumes driving an improvement in operating income versus last year…
We are on a fast track to diversification, using our existing platform technology to win B2B and B2C non-leveraged business. Our strategic growth plans are on track and set to deliver significant new business expansion as we introduce new products across our retail, institutional and stockbroking businesses. We look forward to updating you more in our H1 results on 16 November 2022."
My view
I view this as a high-quality business that is likely to be undervalued at current levels:

However, please bear in mind that I feel the same way about IG group (LON:IGG) which is a large position for me. IG also appears to be “cheap”:

The market doesn’t seem particularly interested in either of these shares right now. Perhaps there is a feeling that Covid artificially boosted their profitability (which it did), and that activity levels are still artificially high.
Remember that these were much smaller businesses a few years ago. See the rapid progression in CMC’s revenues and operating profits:

So there appears to be sheer disbelief in the rapid gains in profitability, especially after the post-Covid drop in their performances. A suspicion that current profitability is unsustainable.
On top of that, investors in this sector have had to navigate some major regulatory issues in recent years, and that experience tends to have a lingering effect on sentiment.
Personally, I’m happy to own IGG and I’d consider adding CMC at current levels.
The major risk is perhaps that volatility dies down, and trading activity levels die down with it.
Here is a 5-year chart of the VIX (volatility index):

This chart helps to prove that volatility is still at much higher levels than it was pre-Covid. If it did go back to the low levels of 2018/2019, then yes, I would expect the profitability of the spread betting companies to suffer.
But personally, I don’t expect that to happen, and in any case I like to have a volatility hedge in my portfolio. Volatility tends to be highest when markets are going down and I like to own some companies that will thrive in that environment.
So while IGG and CMCX shares aren’t for everyone, they remain an important part of my personal investment strategy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
-
New lows for Sosandar (LON:SOS) today, with a 11% price drop to 14p. Have to go back to Feb 2021 when price was around this level. Half year earnings release is on 28th of Nov and can't see any news, so I guess its just the general bear market having an impact
It looks like things are going really bad at Sosandar (LON:SOS) - they've been doing a blanket 20% off everything sale for more than a month now.
Thanks for the udpate on CMC Markets (LON:CMCX) I agree the spreadbetters are worth holding as a hedge against ongoing market volatility. Also worth mentioning Plus500 (LON:PLUS) I know Graham was previously never keen on this one, but its growth has been phenomenal (something like a 30 fold shareholder return since IPO in 2013 if you include the generous dividends - blows both CMC and IG out of the park so they must be doing something right).
Plus500 (LON:PLUS) are very good at fleecing their customers which they readily admit. In terms of a % of customers who lose money. However, if a trade is going against them they just shut down trade on that instrument and then when it restarts customers can lose out badly as stop losses not implemented. Having said that being a shareholder would have been a much better option over the last few years!
Re SThree (LON:STEM)
I would take their recently announced outreach to investors (and Paul Scott) as bullish - they think their shares are worth more than the value ascribed to them by the market. But if I had the opportunity to quiz them, here are some of the questions I would ask:
What has been the average margin - or markup if you prefer it expressed as a higher %ge but do be clear which you mean - on contractor placements for the past x years, including current? What is the highest level that could be achieved on average across the group? And is this a target? - This is a measure of the trend in demand but it will also reveal where the company sits on the quality scale
What was the rate of wage acceleration across contractor and perm in the last FY? And what is it this year? - Another measure of demand but also a predictor of where we sit in the hiring cycle
What is the company targeting for annual organic growth in contractor numbers over the next 3 years? - This has been very strong these past two years and I consider it to be the most reliable measure of future growth potential
What is the highest rate of commission routinely paid to top billers? - The rewards for top performers reflect the balance between price/brand-led and service/quality-led market approaches. The higher the rewards, the higher the service quality and vice versa (usually). There should be a relationship between this measure and gross margins on contractor fees.
I would ask about attrition rates among established consultants. - High attrition in the experienced cohort is a significant limiter of expansion
I would ask about changes in the balance of experienced vs junior employees (existing, not new hires). - A shift towards more experience would point towards higher productivity in the future and vice versa
I would be asking about M&A intentions - This might reveal concerns about organic growth although I would not worry about good tuck-in acquisitions.
Don’t get steamrollered into believing SThree is leading the market in anything It”s the largest listed STEM recruiter with a global reach, yes, but it is a grain of sand on a beach of recruiters, some of whom are twice as profitable on an operating margin level with the same mix of perm/ctr.
I would not get hung up on IR35 changes in the budget. These are broadly positive for the sector but SThree is a bit part player in the UK.
I’ll post this now to get the ball rolling and add any other thoughts over the next hour while I can still edit.
Hi BnB,
Unfortunately that's come through too late for me to cover in this interview.
I'll ask them to do a webinar for PIs, where you can ask all this type of detailed questions yourselves.
My interview starts in 6 minutes, and I've planned more general questions on performance, and outlook. So it's intended as an introduction to the company, rather than a detailed thing. Maybe I could have them back for a more detailed interview at a later stage?
Regards, Paul.
Noted Paul
However, given your prominence relative to us lowly PIs, perhaps it would be worth asking Timo if you could submit my suggested questions in writing post-interview for their measured response. They ought to recognise these questions are the real deal and might even see benefit in thinking them through.
Apologies everyone - I’m surprised no one pulled me up - got my numbers all wrong yesterday - a £250k repayment mortgage at 1.25% is about the same as £175k at 5% over 25 years - in affordability. It’s not the only driver of house prices and more important for first time buyer. Anyway with a 50k deposit that would mean a drop from £300k to £225k - but it’s obviously more complicated than that. A lot of stock just doesn’t trade when prices are weak. If incomes are rising though and prices are falling - for the first time buyer - the investment will be a much better one. The magic of compounding unfolds thereafter.
In London prices make no conventional sense anyway. This flies in the face of the above analysis. Most of Londons rise in the last 10/ 15 years was down to interest rates. Rental returns make little sense in a higher interest rate environment.
On balance I agree with Paul that rates are looking toppy - but I’m less convinced they go back to zero. That would just bring back inflation. We will see.
I would say inflation is more a case of supply side problems caused by the lockdowns. As well as the high cost of fuel, which feeds into everything. In which case increasing the interest rate will just make things worse. To me it looks like the Bank of England is trying to crash the economy. Back in 2007/8 they increased the interest rate which made things worse until they reversed course.
The reason house prices have gone up (although not so much in London) is for the same reason, supply and demand. We are not building enough properties to keep up with the increase in the population.
House building interests me, largely because I don't believe this build build build mantra. I think a lot of the problem is big business moves around the place and their employees have to move hence increase in housing required. I also think property is an investment and a lot of people want more to increase their own investment opportunities. Finally I have a conspiracy theory (based on recent developments in Cambridge) - we sell a lot of housing to the Chinese. In a controlled society a lot of this housing is not being bought by individuals and by moving citizens into an open society at the same time applying pressure at the political level will in time pay dividends. The Chinese have seen efforts by Putin and Trump to play these games and they are much longer term. Weirdo i hear you say (and think it myself to be honest) but the influx of Chinese faces around me (Cambridge) has been startling.
SThree (LON:STEM) - Paul - Sthree announced the first in a series of briefings this morning, a webinar - Analysts & Institutional Investors only. Maybe your interview would be an opportunity to nudge them to include smaller investors too?
N Browns numbers are poor which probably has a read across to other Small Cap favourites e.g. Sosander. "As the period progressed weakening consumer confidence led to a more challenging online retail market, with the retail market down circa 7% for H1 23". I am not a holder but cannot help feeling there is plenty of room for deterioration with rising interest rates, deteriorating real time etc. But remember and it has caught me out several times in my life, when everything around you is looking terrible the market is looking through it. It is often at the worst times when the market starts to kick in. Everyone seems to have an informed view so I will give you mine, we aren't there yet.
Watching Sosandar (LON:SOS) but not doing anything until the November update. I think things will generally get worse in the coming months. Sitting on my hands and not buying my targets has served me well so far.
Snap
On Motorpoint (LON:MOTR) because they hold their used cars on their balance sheet, there is nasty margin shock if used car prices were to start dropping due to decreasing demand. I can't remember the margins (I think they were low as hundreds or low thousands is what comes to mind, I might be wrong).
Hi Boon,
I don't see secondhand car prices being an issue with MOTR, because they're shifting the cars quickly, rather than sitting on them for a long time. The model is rapid throughput of cars, with wafer thin margins, and priced very competitively. Trouble is, it's not now making any profit to speak of. I was very surprised that it sounded like they're subsidising customer finance deals, which seems a very strange decision, given there's so little margin to play with on the cars.
Regards, Paul.
Hi Paul,
MOTR (I hold), as a slightly different take as a holder of the business I was actually very pleased with the companies update this morning, as it continues to execute on its long term growth strategy.
The decision to hold their finance rates is in my view the best decision for the business, the company is taking the decision to invest in the customer at the expense of short term profits, this will only increase the companies market share gains further as well as extend its competitive advantage over its competitors as the lowest cost provider of used cars in the UK. In my view what drives its competitive advantage, as you mention above comes from 2 things, its industry leading sales volumes (as a comparison their inventory turn is on a similar level as Costco) and secondly their brand reputation and customer trust (both for service, 84 NPS score and reputation as the lowest price provider of used cars).
This will lead to a more loyal customer base with repeat purchasing continuing to increase consistently YOY & more consistent future revenues. within a business like the used car sales business, I would much prefer a company that prioritises its customers first above all else as opposed to taking profits today in an environment which allows them to (Which company do you think will likely win in the long term?)
the business has lots of other competitive advantages such as supply advantages, data advantages etc.. but ultimately for me it comes down to an extremely efficient low cost model, which obsesses about its customers and has the highest inventory turns in the business.
Add to that an almost 100% return on incremental capital and a owner managed business with 20% insider ownership, and a strong likelihood of major share buybacks in the next few years and I think you have a winning model.
I hope the share price keeps getting lower, as I plan to keep buying.
But would love to hear bear arguments as well.
I'm not Motorpoint (LON:MOTR) expert but this seems a good perspective IMO
My question is that people are sceptical of the MOTR outlook given its rather pure play used car market exposure then how can they be simultaneously bullish companies like Vertu Motors (LON:VTU) ? (this point is not directed at anyone...I don't follow comments or holdings closely for anyone)
When it comes down to it a lot of Vertu's outlook is driven by used car dynamics. New car sales and degree of general churn in car sales (new and old) are driven by used car prices and the extent to which they support the magical financing wheel whereby people feel they have cash to trade. Note that higher interest rates also impact this.
My drive by banalysis perspective is I don't want to buy any motor retailers at the moment as pain points are still to unfold. However, I'm interested in MOTR and will watch (I expect more pain) as ultimately it will win from the pain of others. Stocks like Vertu are value traps (the tangible value of property is a nothing burger as its so bitty and crappy...if it had value the company would work a lot harder to realise value from it rather than having it as a fetish that they like to own property)
I also agree with Bully 15's points abut Motorpoint mojomogoz, they were the sharpest used car sellers in the UK when I was involved in fleet car trading between dealer groups over 20 years ago and no doubt still are. I disagree about Vertu. You can aim your comments at me as I think the shares are excellent value, they have something Motorpoint doesn't have, i.e. New car sales and a constant supply of quality retail cars in p/ex against new, or a strong profitable and growing aftersales operation., you might also have found Vertu's success in their growing van sales highlighted in their webinar interesting. Motorpoint were and still are big enough to take advantage of manufacturers' weakness in scooping up pre reg cars but the big dealer groups get that advantage too although I agree with your observation about it winning from the pain of others. I do not expect that pain to come from Vertu although I accept the pain of recession might not be fully in any retail facing companies shares yet.
In my ignorance and lack of industry specific knowledge I will still take the other side on Vertu Motors (LON:VTU) - for years they have deployed capital poorly IMO. They acquired Bristol Street motors excellently back in 2006/7 (ish?) but since then they do a bad job allocating capital. Their folly of recent years is paying high valuations to acquire premium dealers (this leaves plenty room for goodwill write downs in future). The shift to premium juices results short term but increases the risk that high interest rates and lower resale prices and/or churn (so people own for longer) brings negative surprise. The tangible backing from property is not worth the sticker price as its value cannot be realised except in distress and at a discount (if they were good at allocating capital they would have realised much more value from it to date).
So I believe vertu is a value trap where the p/e goes up as earning go down
The bear case for Motorpoint (LON:MOTR) is the price. In the whole of 2022 its only closed twice above the 50 day MA.
Personally I wouldn't even look at it until this changes.
the Car a group had the same model a few years ago. Unfortunately when car prices fell the speed of stock turnover went down as well. It went bust.
On the other hand there is also the effect of much reduced new cars volumes in recent years to consider, which may mean the value of nearly new used cars will hold up for a year or two.
Paul,
Where/ what is the link for access to your podcast please
Hi Kanga, I think you are looking for this: http://qualitysmallcaps.co.uk/ you call also search for for the podcasts via your favourite streaming service. For example, I listen via Spotify (searching for "Small Caps UK" or "Paul Scott")