Small Cap Value Report (Thu 7 Mar 2024) - KIE, TYMN, TTG, RTO, DARK

Good morning from Paul & Graham!
A fairly uneventful budget yesterday, with all the main points already leaked to the media, as usual. Here's my brief summary -
Main measure, as expected another 2% cut in employee NI.
OBR forecast growth increased & expect inflation to fall to 2% target soon.
Plan for productivity gains in NHS & other public services.
Fuel & alcohol duties frozen again, as expected.
New British ISA - extra £5k allowance for investing in UK companies.
Non-dom being abolished, new regime for 4 years not 15.
As mentioned frequently in my podcasts, I think the macro outlook for the UK economy is now looking favourable, which I think should be bullish for equities. In particular, with inflation heading for 2%, and many households receiving 8-10% pay rises from April, plus another 2% NI cut, we could go from famine to feast. So I'm expecting the consumer to come roaring back this year, hence lots of opportunities for us to make money I think. Let's hope I'm right!
EDIT: I should have mentioned that others have commented the freezing of personal allowances for years means that the Govt is giving with one hand, and taking away with the other - a valid criticism. Increasing numbers of people are getting sucked into the 40% tax band for income tax. I feel the jump from 20% to 40% is far too great. Surely it would be more sensible to protect incentives to earn more if we had a 30% intermediate band? Some other countries have many more income tax bands, so that increases are much more gradual as salaries rise. There are also wild anomalies around £100k gross income, which deter people earning above that level, due to tapering of the personal allowance creating a c.60% marginal income tax rate. If you were to design a taxation system from scratch, you definitely wouldn't come up with anything like the system we currently have!
Keelan's thread on the budget is here, if you haven't already seen it.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
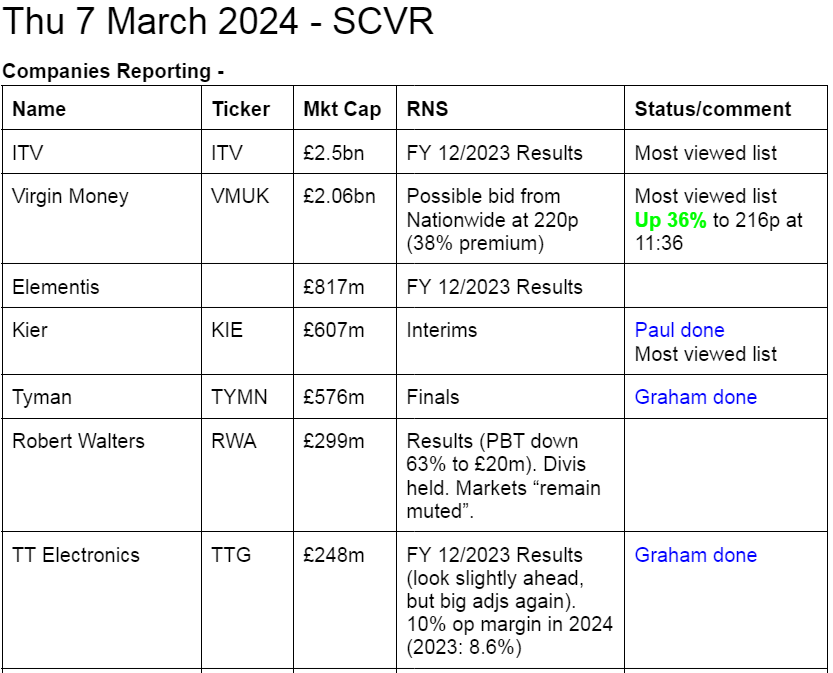
Other mid-morning movers (with news)
Rentokil Initial (LON:RTO) - up 15% to 495p (£12.6bn) - PAUL
Unusual to see a larger cap responding so well to Final Results figures & outlook. I’m surprised at how weak (or efficient?!) balance sheet is, with NTAV negative £(3)bn, and lots of debt. Adj PBT up 44% to £766m, but adj EPS only up 9% to 23.1p, due to dilution (shares in issue up from 2002m to 2516m in the year) - presumably for big acquisition of Terminix - going well with better cost synergies than originally planned. Outlook sounds confident for 2024.
Darktrace (LON:DARK) - up 15% to 403p (£2.84bn) - PAUL
Calls itself a “global leader in cyber security AI” - Interim Results well received today. Increases revenue (slightly) & margin expectations for FY 6/2024. H1 EBIT $46m vs £0.6m H1 LY! Negative tax charge on P&L looks odd. Balance sheet $252m NTAV. Big cash pile of $383m mainly comes from up-front customer payments, deferred revenue creditor totalling $317m. “Capitalised commission” on balance sheet of $41.8m + $43.2m is unusual. Cashflow statement - cash generated mainly used for share buybacks. Paul’s view - neutral, as I don’t know enough about the company. Large rise in profits, and raised guidance does look impressive though.
Summaries of main sections
Kier (LON:KIE) - up 2% to 139p (£619m) - Interim Results - Paul - AMBER
H1 results look as expected, and FY 6/2024 outlook remains in line (note that forecasts have been slightly reduced in the last 9 months). Balance sheet is large, complicated, and weak. Shares have had a great run, but look up with events to me, for a low quality, low margin contracting business. So I'm less keen that previously, and reduce my view to neutral - AMBER.
Tyman (LON:TYMN) - down 4% to 283p (£554m) - Final Results - Graham - AMBER
This supplier of products to the construction industry reports profits in line with expectations, but I think revenues have fallen short. Looking ahead, 2024 is expected to be another challenging year. Rate cuts might spur demand in North America. I’m neutral on this one.
TT electronics (LON:TTG) - up 5% to 146.7p (£260m) - Full Year Results - Graham - GREEN
These are decent results from a stock I’ve been bullish on. Financial net debt has reduced to £105m; perhaps the amount of leverage reduction I was hoping for was unrealistic. Another £20m of disposals have since been announced. I remain of the view that this stock is cheap.
Paul’s Section:
Kier (LON:KIE)
2% to 139p (£619m) - Interim Results - Paul - AMBER
Kier Group plc ("Kier", the "Company" or the "Group"), a leading UK infrastructure services, construction and property group, announces its results for the six months ended 31 December 2023 ("HY24" or the "period").
I’m starting with a favourable impression of Kier’s performance. Previously, I reviewed its AGM update here on 16/11/2023 - trading well, positive outlook, cheap at 104p, forecast 5% yield, GREEN.
On 19/11/2024 here I reviewed an in line trading update, moderating my view to AMBER/GREEN mainly due to the share price having risen to 125p. Also noting the weak balance sheet and low margins.
That sets the scene, on to today’s H1 figures - as you can see from the highlights table below, the very low PBT margin of only 2.6% is a reminder of why many investors avoid contracting groups with big, complicated projects that can easily go wrong, but no financial buffer to absorb problems given they win business through price (competitive tenders) -
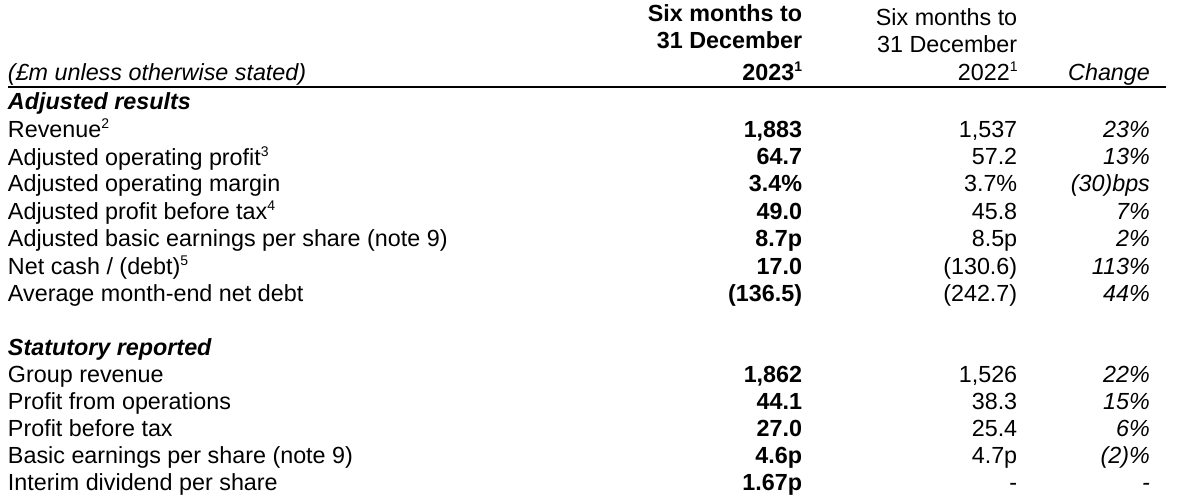
Also note a massive reduction in net bank debt (reported excl. leases), and the excellent additional disclosure of average month-end debt. Average daily net debt would be even better, but we’re not told that. Clearly this is a big business, with considerable working capital swings, so extra caution is needed when interpreting the cash/debt numbers, as they clearly fluctuate very considerably.
The net cash of £17m above looks an unusual peak, but the average month-end debt still shows a very considerable reduction in net debt.
Huge order book, up 6% to £10.7bn.
Strong visibility, with 97% of FY 6/2024 revenue secured.
Dividends have resumed, as expected, with 1.67p interim divi declared.
Financing sounds good -
Successful refinancing post period-end providing long-term debt facilities and a strengthened maturity profile
Outlook - in line -
The second half of the financial year has started well, and we are trading in-line with expectations. The Group is well positioned to continue benefiting from UK Government infrastructure spending commitments and we are confident in sustaining the strong cash generation achieved over the last 18 months, allowing us to continue to significantly deleverage the Group. We remain committed to delivering our medium-term value creation plan which will benefit all stakeholders."
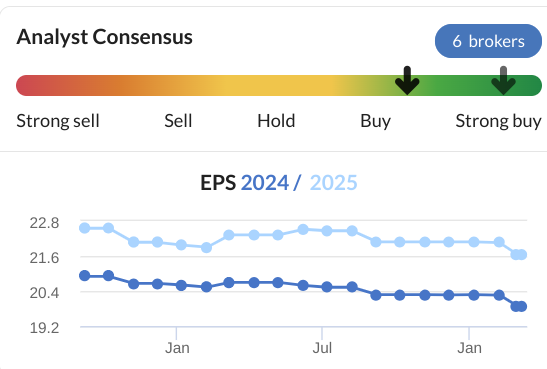
Valuation - no broker notes are available right now. Stockopedia has consensus of 19.9p (PER of 7.0x), and note that forecasts have been in a gentle decline -
Balance sheet - I’ve previously described as large, and complicated, which it remains. Writing off intangible assets gives negative NTAV of £(129)m. Gross debt strikes me as too high, and I note in the commentary it talks about deleveraging being part of the strategy.
Note that it has a pension deficit (costing £5m pa in cashflows) yet shows a pension scheme asset on the balance sheet of £125m - a reminder of how absurd pension scheme accounting rules are!
This bit is reassuring on the pension schemes, which looks a manageable, and declining problem -
In FY23, the Group agreed the triennial valuation for funding six of its seven defined benefit pension schemes. Given the Group's improved covenant and payments made under the existing schedule of contributions, the schemes are in a significantly improved position. Accordingly, deficit payments will decrease from £10m in FY23 to £9m in FY24, £8m in FY25, £5m in FY26, £4m in FY27 and £1m in FY28. Once the pension schemes are in actuarial surplus, they will cover their own administration expenses. In FY23, expenses amounted to £2.9m. The largest of the six schemes is already in surplus.
At the very least though, I would remove the £125m pension scheme asset from the balance sheet, which roughly doubles the negative NTAV to £(254)m - a poor overall position in my view. So balance sheet weakness is definitely an issue here - which could become a crisis if some major contracts go wrong in future, which tends to happen sooner or later with most big contracting businesses.
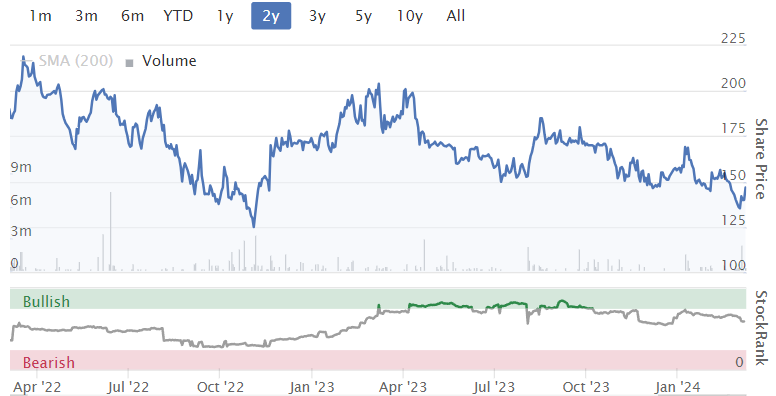
Paul’s opinion - KIE shares have been really good over the last year, and it’s established a nice up-trend -
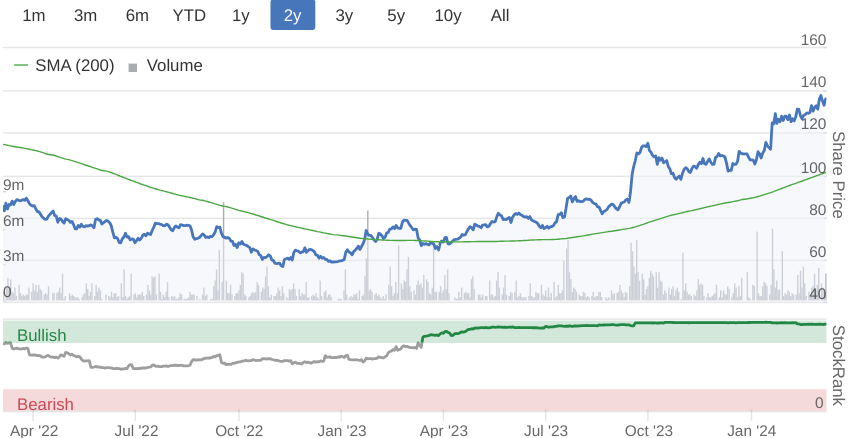
However, I can’t get excited about the valuation - why pay more than a PER of 7.0x for a low quality, low margin contracting business with a weak balance sheet?
I suspect the best part of this current bull run might now have already happened. It probably needed an ahead of expectations update to move it meaningfully higher, which hasn’t been forthcoming -a actually forecasts have been gently eased down in the last 9 months.
Overall then, I’ll ease back on the throttle to AMBER.
Graham's Section
Tyman (LON:TYMN)
- Share price: 283p (-4%)
- Market cap: £554m
Tyman is “a leading international supplier of engineered fenestration components and access solutions to the construction industry.”
Products supplied by the company include window and door hardware, window and door seals, niche products such as roof doors, and various related products (see more here).
Performance for 2023 is described as “robust”, and profits are in line with expectations.
However, the numbers don’t seem terribly robust at first glance, and revenues have fallen short of the figure indicated on the StockReport (£668m):
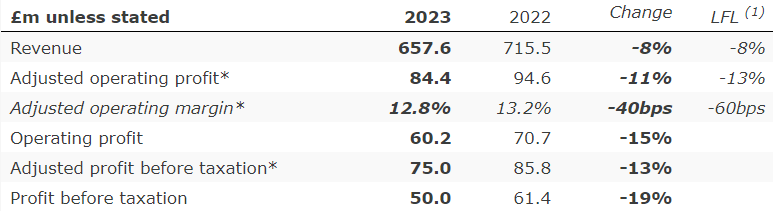
Everything has moved in the wrong direction, with signs of operating leverage working in reverse as profit figures shrink faster than revenues.
Explanation of performance? Weakness is due to “the impact of a significant reduction in volumes due to underlying demand softness and customer destocking, which more than offset the benefit from the carryover of pricing actions and share gains”.
Acquisition: in July 2023, Tyman made an acquisition in America for an initial cost of £44m ($57m). This deal was said to be “immediately earnings enhancing”, i.e. it will have boosted H2.
This is reflected in adjusted operating profits being down 11% in total (including the effect of the acquisition), but down 13% on a like-for-like basis.
Dividend is unchanged, “reflecting confidence in the Group’s future growth prospects”.
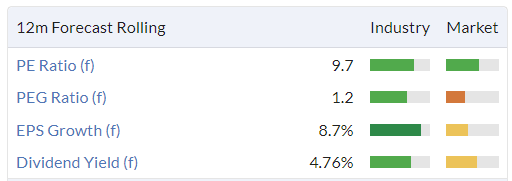
The yield at the current level isn’t to be sniffed at:
CEO comments: the company changed CEO on 2nd January 2024, so we get two CEO comments for the price of one.
The outgoing CEO says Tyman is “well-positioned to take advantage of the positive structural growth drivers when the housing market backdrop improves”.
The new CEO says:
The structural growth drivers for the Group remain attractive, although leading indicators for our major markets are currently signalling a challenging market outlook for 2024. However, given our self-help measures and a full-year contribution from Lawrence, the Board expects the Group to make progress in 2024."
“Make progress” is nebulous, but maybe it’s difficult to make predictions with any confidence at this early stage in the year?
The StockReport suggests revenues will grow to £688m in 2024. This could be overly ambitious, seeing as the 2023 forecast wasn’t met.
Geographic split - the majority of Tyman’s profits are in North America, and in that geography, adj. operating profit only fell by 5% (vs. a 17% fall in the UK and Ireland, and 31% fall in the “International Division”.
Therefore, the outlook for the North American market is worth focusing on:
The underlying fundamentals of the US housing market remain strong, with years of supply lagging demand creating a significant housing deficit. Economists are forecasting that the easing in inflation that began in 2023 will lead to interest rate reductions in the first half of 2024, which could alleviate the recent constraints on market demand and stimulate activity later in the year. The NAHB currently forecasts a 5.5% increase in single family housing starts, whilst LIRA (GN note: the Leading Indicator of Remodeling Activity) projects that the spend on repair and remodelling will decline by mid to high single digits.
In summary: there should be a bounce in building activity, assuming that interest rates start to fall, but RMI (repair, maintenance and improvement) of existing homes is expected to continue falling.
The outlooks for both the UK/Ireland and International markets are worse, with declines expected in both, but Tyman will try to gain market share.
Adjusting items of £10.6m include nearly £7m of “restructuring costs” and £1.3m of “CEO transition costs”.
Many different types of costs have been lumped into the restructuring category, and I note that there was over £6m of restructuring costs last year, too. I would therefore not treat these costs as exceptional. I’d also be reluctant to treat the CEO transition costs as exceptional - changing CEO is not exactly a rare and unusual event.
Net debt finished the year at £110m. Fortunately it seems that the company should be able to handle this amount of debt: the leverage multiple was only 1.1x for 2023, with interest cover of 13x.
Graham’s view
I don’t remember spending much time studying Tyman before, but my overall impressions this morning are positive. This looks to be a solid international business, apparently having 3,600 employees in 15 countries. It consistently earns a profit and pays a dividend, is modestly leveraged, and seems to take a thoughtful approach to the economic challenges it faces, such as input cost variability and volatile demand.
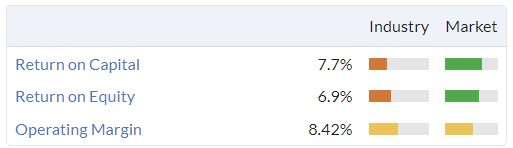
Against that, I don’t know if I’ve seen enough to get me too excited for the prospects here. Quality metrics, for example:
The level of adjustments to earnings is another factor to consider: there’s a really large gap between £84m of “adjusted” operating profit and the £60m of what I call the “actual” operating profit. The difference is made up of the adjusting items mentioned above, plus £13.6m of amortisation.
It’s not an unusual way to present results, but I much prefer when accounts are presented cleanly.
On balance, I’m going to take a neutral stance on Tyman. Paul has been slightly more positive on it - see his November coverage here.
TT electronics (LON:TTG)
Share price: 146.7p (+5%)
Market cap: £260m
TTG is “a global provider of engineered electronics for performance critical applications”.
I’ve been looking forward to this report:
Strong profit growth, margin enhancement and cash generation
Adjusted results:
Revenue £614m (up 1% at constant FX)
Operating profit £53m (up 16% at constant FX)
PBT £43m (up 11% at constant FX)
Return on invested capital 12% (up from 10.5%)
Statutory results:
Operating profit £8.7m (2022: operating loss £3.4m)
Pre-tax loss £1.1m (2022: pre-tax loss £10.1m)
Unfortunately this is another case of large adjustments.
In 2022, TTG used £50m of adjustments.
For 2023, it has used £44m of adjustments, so not much improvement.
However, investors might take some comfort from the fact that in both years, large amounts of the adjustments relate to non-cash write downs.
The write downs relate to the disposals announced by TTG a few days ago, which we commented on here. The assets are being sold for less than their balance sheet values, thereby requiring the company to take a hit to its P&L.
The disposals made good sense to me, from the point of view of deleveraging and selling businesses that weren’t helping TTG’s financial performance, and I won’t change my stance on this because of the resulting write-downs.
Taking a broader look at the adjustments, I don’t think I would adjust out certain items, such as “restructuring” (£2m) or “pension restructuring” (£2m). So I do think that TTG’s adjusted operating profit figure of £53m, allowing all of these adjustments, is too optimistic.
On the other hand, the £8.7m statutory figure is probably far too pessimistic, as it includes £32.5m of write-downs which I am glad the company is taking (instead of continuing to hold businesses that weren’t performing well enough).
The truth, as always, lies somewhere in the middle.
Net debt excluding leases falls from £115m down to £105m year-on-year.
Including leases, net debt falls from £138m down to £126m.
Perhaps naively, I was hoping for better than this. After all, the company generated an adjusted PBT of £43m. This translated to £24m of free cash flow and then after £11m of dividends, the net debt reduction was only £10m-£12m.
The year-end leverage multiple was 1.7x (previous year: 2.0x), within the target range of 1-2x. The CEO report says:
We are confident this downward trajectory will continue as EBITDA increases and as we deliver further strong free cash flow in 2024.
The disposals were announced after year-end. Perhaps net debt excluding leases is now approaching £80m? That would be getting into territory where just one more year of good free cash flow performance could bring it rapidly down to the bottom of the target range.
The Board seems to be confident at any rate, as the full-year dividend has grown by 8%.
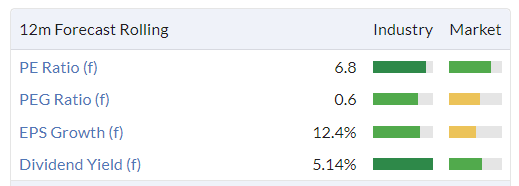
This is another stock that offers a useful yield:
Outlook excerpt:
There is considerable opportunity to unlock further value in the business by strengthening operational execution, expanding and optimising our routes to market and by enhancing product innovation. A first step in driving improved margins and simplifying the portfolio is the recently announced sale of our businesses in Cardiff, Hartlepool and Dongguan.
Based on the strength and level of visibility in our order book, current end market activity and operational improvement initiatives that are underway, while mindful of the wider macro environment, we are confident we are on track to deliver a 10% operating margin in 2024.
Adjusted operating margin was 8.6% in 2023 and 7.6% in 2022, so 10% would be a considerable improvement.
Nine months of 2024 revenues are already in the order book, implying good visibility (and it’s above pre-Covid visibility).
Graham’s view
Again I’m a little disappointed that we couldn’t get a cleaner set of accounts from TTG, but I think it makes sense to retain my positive stance on these shares.
The leverage multiple is at a reasonable level, far below the 3x number where lenders (and I) typically start to worry about financial distress.
Free cash flow performance was ok, but the cash position has been boosted since by the disposals.
In summary, I still think the market is pricing this one too cheaply at a modest single-digit earnings multiple.
Could 2024 be the year that we finally see a really big cash flow performance, clean accounts, and a reduction in the debt load down towards a leverage multiple of 1x? The closer we get to that level, the more ambitious the company could be, either in terms of growth or rewarding its shareholders.
In my view, based on the financials, there is a good case that TTG should be buying back its own shares at the current valuation. It might be difficult to convince shareholders of the merits of this, but think of it this way: if the company ploughed its entire free cash flow for 2023 into share repurchases, instead of paying down debt or paying dividends, it would reduce the share count by nearly 10% at the current share price.
That would be too aggressive - it’s good that TTG is paying down its debts - but I do think that some buybacks could make sense here, maybe instead of increasing dividends?
Either way, I’ll keep my positive stance on this stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
Kier
Back in the day my broker, along with many more at the time recommended Carillion based on the yield. Got badly burned. Your comments on low margin contracts with potential for SNAFU's ring very true. It's a sector I now avoid.
Kier (LON:KIE) Galliford Try Holdings (LON:GFRD) It's always useful to look back & check that things have really altered…I suspect these businesses are far better but I don’t know for sure
That must have been a very good broker suggesting a company Carillion as a buy to a client-it’s debt was increasing at a pace faster than Usain Bolt from £250m in 2012 to over a Billion+ in 6 years!
Kier (LON:KIE) is a totally different company with an experienced management and in a totally transformed sector that is not engaged anymore in many fixed costs contracts. I don’t understand the comparisons and an extensive research will do no harm to anyone. The low margin comments is something that needs to be addressed here as well. Many FTSE100 companies are a low margin businesses with great success.
I hold , added today and will add tomorrow for a minimum of a 3 year horizon.
After all Labour governments love the well much needed infrastructure!
Seplat Energy (LON:SEPL) "President Bola Tinubu on Wednesday signed executive orders introducing tax credits for some onshore and shallow-water locations and streamlining contract approvals, the government said in a statement."
The stock has jumped 10% on this news today. This further strengthens the chances of the transformational Exxon Mobil (NYQ:XOM) deal getting signed off. Tax credits a potential added bonus too.
-
?
Holding Darktrace (LON:DARK) is not that fun, although I am in quite a bit of profit, can't help to think it will crash soon with all the negativity that surrounds the company. The general trend has been good reports which has increased the share price, but then the share price starts trickling down again when there is another negative newspaper headlines.
Holding Darktrace (LON:DARK) is not that fun
I find it to be a better trading stock than buy and hold proposition. There are far better cybersecurity companies, with better products and better charts. But they are all listed on the US markets. Do you invest stateside as well?
That's true. It's very up and down so if you can time it right there is money to make. I've held it since before it was above 1000p so has been a bumpy ride!
I'm long Zscaler since 2018 after a friend in cybersecurity said their product was superior. It's been a bit more bumpy than other cybersecurity stocks lately though, so which I had sold off a bit and diversified into others in the sector.
What about you?
What about you?
Cybersecurity is about 6% of my portfolio with holdings in the usual suspects. I have very diversified portfolio so these are all outsized relative to the mean.
Crowdstrike
Cloudflare
Zscaler
Palo Alto Networks
Fortinet
Cyberark
The last is the highest rated by analysts. None are cheap and it’s been a roller coaster these last three years. And will be again, no doubt!
hi BnB
Sounds like you have a lot of stocks in your portfolio?
How do you manage to keep on top of them all?
I tend to hold 20-25 stocks (presently 21).
I'd find any more too difficult to manage. I guess I'm much older and slower so nowhere near as productive nowadays.
Snazzy
About 200. It’s easier than you’d expect as they’re mostly highly profitable international firms and well covered by the analyst community. I’m not trying to find something the market has missed. Outside UK cyclicals I just own the highest quality within each theme that I play. That makes for a coffee can type experience. Within the UK I had 4 this morning give updates, Robert Walters (LON:RWA) TT electronics (LON:TTG) Spirax-Sarco Engineering (LON:SPX) Rentokil Initial (LON:RTO) and it took about half an hour between 7 and 7:30 to satisfy myself that the results were either as expected, or better. It’s a little harder when there’s a PW and I have to get my thinking cap on.
All that said, I do devote a lot of time to monitoring my companies’ progress because I find it intellectually very satisfying. And it replaces the experience of running a conglomerate of companies which was once my day job. But without the firefighting!
That's very interesting BnB. You have a very wide spread of risk with minimal exposure to individual stocks. More like a quality tracker I guess.
I'm a bit of a micro manager so 200 stocks would be impossible for me to feel I was on top of things. Many ways to skin a cat.
I can now see why you were so relaxed about Headlam (LON:HEAD) the other day, given your exposure to Headlam (LON:HEAD) was likely less than 1%, whereas mine was almost 4%.
Snazzy
More like a quality tracker I guess.
Exactly that. Except I get to choose the industries and representative companies..
Darktrace (LON:DARK) Paul its very normal for SAAS companies to capitalize the commission over the life of the contract signed. Only risks are obviously if some reason the contracts are cancelled or negotiated down. Note I do not hold this share
Hi Brookeda,
Paul its very normal for SAAS companies to capitalize the commission over the life of the contract signed
It's not something I can recall seeing at any of the other (admittedly smaller) SAAS companies that we cover here. Hence I flagged it as something that looked a little unusual. Presumably they capitalise these costs to flatter profitability, and the numbers are quite material. I don't see this as an asset (it's more a cost that they are spreading over several years), so personally I would eliminate it from the balance sheet, although other people might view this differently, which is fine. Armed with the facts, we can interpret the numbers in a way which suits each individual investor :-)
Regards, Paul.
Darktrace (LON:DARK)
Paul
It's not something I can recall seeing at any of the other (admittedly smaller) SAAS companies
Reminds me of the company popular here that was capitalising the advertising costs connected with customer acquisitions - they soon changed their tune and went to more conservative accounting metrics - dont think they ever said what they were doing was wrong.
I am with you here Paul must admit i am struggling to recall any companies having capitalised commission expenses - sounds more like a prepayment to me if the money has been paid over up front (or accrued for) but relates to later provision of services.
not sure if this is them choosing an acounting option that is "available" as it looks better to have an asset rather than a prepayment? - damn acounting rules. Hate it if they are doing this because they can rather than "needing to". heyho perhaps the yanks love pimping up like this.
A good article on it is here https://www.airbase.com/blog/a...
A lot of US SAAS companies already do this, can understand the argument though
Thats a good article and basically covers IFRS 15 for those interested. Again a huge issue for rev rec in SAAS businesses.
cheers - interesting stuff (for me)
Note there is a practical expedient get out clause here.
If having to capitalise these sales commissions will cause excessive time and effort to account for short-term contracts, the standard allows for a practical expedient. If the practical expedient is taken, then these costs can be expensed in full when incurred so long as the amortisation period would be one year or less.
Being frank i am not 100% convinced this is anything other than a prepayment if i had been choosing the rules- not sure what the underlying logic is that dicates sales commission payable is ever capital . I get it with customer acquisition costs that are advertising - clearly something of value that could be sold on. Hey ho stupid i is and rules is rules.
Cant imagine any audit firm signing off on capitalising commissions. As a "long in the tooth" accountant I have never seen this, and have worked in several SAAS businesses. Reminds me of a former CEO arguing with me several years ago why we couldn't capitalise recruitment costs!!!
Indeed. Having been involved with finance in Aim listed tech businesses the pressure was always to frame agreements in such a way as to recognise as much revenue as possible up front and capitalise anything and everything. I'd draw the line at commission though.
Zotefoams (LON:ZTF) appears to be firming up with results on 19th with spread tightening.
Creightons (LON:CRL) (I hold) I am pleased to see Pippa Clark promoted to Group Managing Director - I have always found her extremely knowledgeable and her vision compelling in presentations. I do not that the CEO role is now vacant though; I wonder if this is left as a carrot for Pippa or that they anticipate making an outside appointment.
Do we know if the old MD is now selling down his shares, as know he had a big personal holding, or have they done some sort of deal with him?
Cheers Tommy
An ex-holder.
Really good report on TTG Graham. I agree with you I think they look cheap. Not a wild bull but feels like £1.80 to 1.90 would be a fairer valuation. Spoiler alert I hold, so on this years form probably heading for £1.
Thank you camtab! Atb. Graham
Treatt (LON:TET) Anyone interested in this one might like to take a look at the well-received results of Symrise AG (ETR:SY1), which has a good crossover with the UK company's beverages business. Not only is business improving for the sector after a prolonged destocking phase but Treatt looks incredibly cheap compared to industry counterparts - I mean, like half price!! The flavouring giants should be licking their lips at this opportunity to pounce.
My request is a little late but I'd appreciate an scvr and/or comments on HSS Hire (LON:HSS) when there is some spare time, they've sold 2 companies today for "enterprise value" of £23m, the actual figure is mentioned in the footnote as "cash consideration for the disposal is expected to be £20 million", so not exactly open & honest which has put me off investing for the moment. It does appear to have value but I also note the major shareholders holding a heavy chunk so always a chance of going private ? I also couldn't find out what the value of these 2 companies are on their books. Reading all this back suggests I'd be better of leaving well alone but I'd be interested for feedback nonetheless
Paul
Quick response to your comment: yes, it's a big jump from 20% to 40% income tax. But for those in work, national insurance contributions make the jump from 30% (used to be 32%; next year: 28%) to 42% - the real jump's getting bigger but not as large as looking at income tax alone .
If NI is abolished as some are predicting for later this year as part of the Tory scorched earth policy, it's to be applauded (since it's always been a quasi tax) - and it will make your concern very topical.
Thanks for the write up on Kier. Completely agree on the risk re: low margin. In the upside, inclusion in FTSE250 this month alongside a multi month price break out should provide some fuel medium term imo
Some stonking six monthly results from Darktrace (LON:DARK), I hold. I know its not everyone's cup of tea as there are major stakeholders "with History" but the business issue DARK addresses is not going away. We used them at the company I currently advise and the service was pretty effective and decent. Worth a relook IMO.
Know it's not a small cap but Paul has commented on it in the past.
$000
Six-months ended
31-Dec-23
Unaudited
Six-months ended
31-Dec-22
Unaudited
% Change
Revenue
330,303
259,259
27.4%
Gross margin (%)
89.3%
89.7%
n/a
Net profit
52,518
581
8,939.2%
Adjusted EBIT
70,977
32,430
118.9%
Adjusted EBITDA1
84,518
45,189
87.0%
Net cash inflow from operating activities
65,589
27,094
142.1%
Thank you Paul for a very informative note on Kier. I'm a holder having bought in with a personal target price of £1.50, which is very close. I would observe two things. The 1st is that Kier is not a low quality business in my opinion. I would opine they are highly respected in the sector. The 2nd is that I understand a fair proportion of their contracts are measured works which gives them some latitude in mitigating contract risk.
Does anyone know what the implication of moving to the ftse 250 is likely to be? I understand that kier are moving back in on/around the middle of the month. Is this priced in? I wonder if the inclusion of the share into the 250 triggers automated buying at volume? (notwithstanding the expectation is Kier will move up into the 250.)
Kier (LON:KIE)
The 1st is that Kier is not a low quality business in my opinion. I would opine they are highly respected in the sector.
the quality is everything to do with the financials and nothing to do with the trusted name - note many trusted well respected names in this sector have crashed and burned - so imho Pauyl is very much correc t that financially this is very much a low quality business due to balance sheet risk.
Facts are operating margin at 3.4% is wafer thin - the main issue here is the size of the numbers being so large - they have £500 mill owed in and the owe £1 billion out in payables. Any shortfall in collection or shorfall in provision for costs (quite often when these companies blow up they have under forecast what it costs to deliver agreed contracts) - could amount to sizeable sums.Just look at 2019 as an example when they kitchen sinked £340 millionm of exceptional costs - when these companies make decision to rejigg adjustments can be horrendous
The 2nd is that I understand a fair proportion of their contracts are measured works which gives them some latitude in mitigating contract risk.
are you sure? - judging your costs for large contracts has always been a skill - the main danger here is underproviding for future costs you are on then hook for (to contracturally deliver).
are you really saying that any unforseen costs (to deliver what they promise) will generally be picked up by the customer and not them? - note you could be right that sometimes customers may say simply biill us your costs plus 5% on time we trust you - i just wouldnt expect many customers to give them carte blanche to charge anything - for obvious reasons.
Note i would agre yiannos has a good point here that we are looking forward not in the rear view mirror - in theory these companies should have learned much from the past - its less likely they will be shooting for growth at any cost. So generic warnings such as mine are pretty useless - digging to tehn dsetail and knowing ten company is what is needed.
I think with companies like this you pay your money you take your chance - if they deliver - gains can be great - but when things go wrong there can be virtually no limit on the down side. Note if Kier have £300 cash in the bank and keep it - hopefully thats a nice little immediate protector against and future issues
If an ETF follows a particular index it has to buy.Some US data i heard talked about recently that there can be a potential arbitrage pre inclusion i think (although in the US i would imagine a lot of people are chasing that same arbitrage), like with Uber's inclusion fairly recently in the S&P500.Afterwards not so much.I'd think it'd depend on the size of the etf too vis a vis the amount they buy.Sorry i can't give anymore granular information as i just heard it from a reputable financial media source (ie.not CNBC and Jim Cramer!!).Some funds could well be more interested in the shares too if they have marketcap rules and index rules about their investments too.
Plexus Holdings (LON:POS) A new satellite that will track climate-heating methane emissions from oil and gas companies around the world launched this week from California's Vandenberg Space Force Base.
Found this very interesting on plexus website !
Committed to our ESG responsibilities, Plexus delivers the best possible engineering solutions for its customers and strives to be a champion for sustainability in the oil and gas sector.
With the impending Methane Emissions Reduction Act in the United States, which may mandate independent monitoring and seeks to introduce financial penalties for methane emissions, companies are being increasingly pressed into developing and using technologies to detect and reduce these harmful emissions.
Re LON:HAT, can anyone explain why Stocko assigns it as a 'Value trap', but is still qualifies for Benjamin Investment criterias - and also Paul gave it a favourable write up on SCVR
Hi Mark,
Just to clarify, the StockRank styles aren't based on any level of deeper qualitative analysis. They summarise how well a stock is 'exposed' to the share price drivers of Quality, Value, and Momentum. Using this, you can understand how - historically - stocks with the same fundamental characteristics have tended to perform over time.
I'd highly recommend reading our Academy post on this for some more detail: https://www.stockopedia.com/ac...
Best,
Lawrence
Big volume in GlobalData (LON:DATA) this morning. Its had a decent pullback since the Inflexion investment in December. Right on the 200d ma
@DATA ... have looked at GlobalData many times but no having any dealing with them personally its hard to get a feel whether they are a long term winner or a company that will be disrupted and need to work hard to stand still. Certainly the revenue growth appears alittle slow at 7% underlying and renewal rates at c. 80%.
Balance that with a platform company which seeing a high drop through in revenue to EBITDA on just a P/E 20 for the current year. Bargain?
Inflexion are paying £434m for 40% of the healthcare division, probably the largest of the divisions (38% of turnover), that will pay off all the debt, and have cash to invest, so will eliminate the interest charge (save for some non-cash charges, interest on leases and any facility exit costs) which will help the EPS despite now having a minority interest.
Any insights anyone?
I like GlobalData (LON:DATA) a lot. The read across is that the SoTP is worth considerably more than the current share price. If you talk to the founder he will point to multiple industry deals where that value can be realised.
Ordinarily I might “hmph” and say “he would say that” but the deal with Inflexion has part proven it and more than proven his ability to find and execute such deals. The fact he has a strong track record in building and selling high value businesses also gives me confidence.
BUT…..on the flip side is it all too complicated. I am afraid an old adage that is all too true when attracting investors is simplicity. A one stop simple story often tends to elicit higher multiples than a value play with multiple components, simply because people can understand one better than the other. I suspect that is the case here. It is on a reasonable PER because of the attractive end market but the Inflexion story and read across is just too complicated for people to bother with. That leads to inertia or stale bulls selling and you get a drift.
The other negative is that the CEO clearly has a plan to reduce stake over time at increasing price points. That’s good because he owns too much and (in this case) the liquidity is needed but not so good because it means institutions can wait and take directly off his hands at various points.
hi Markds28
GlobalData (LON:DATA)
It's not easy to pin down what this company is worth pre and post the partial sale to Inflexion. Judgement is clouded due to there being no historic breakdowns for Healthcare / Consumer / Technology divisions as this is a new Group set up from FY'24.
However there are two ways of looking at it, calculated on either share of revenue or share of EBITDA for TTM to 6/23, which was the period used for the Inflexion offer. Inflexion are buying 40% of the new Healthcare division for £446m, valuing the Healthcare division at £1115m.
The £1115m valuation was based on 22 x EBITDA which comes to £50.7m EBITDA for Healthcare. Group EBITDA for TTM to 6/23 was £100.9m hence combined EBITDA for the new Consumer and Technology divisions was £50.2m. Turnover for Healthcare was 36% (increased in FY'23 actuals to 38%) and 64% for the combined Consumer and Tecnology divisions.
A valuation based on the Healthcare sale at £1115m representing 36% turnover would suggest a valuation of £1982m for Consumer and Technology, assuming similar margins giving a total EV of £3097m less (say) £200m debt = M/Cap of £2897 and a share price of 340p.
However, margins were not the same in TTM to 6/23. Healthcare margin was 52.8% (36% turnover = £96m, EBITDA £50.7m) whilst Consumer and Technology was 29.4% (64% turnover = £171m, EBITDA £50.2m).
A valuation based on share of EBITDA x 22 values the Consumer and Technology divisions at £1104m plus Healthcare sale valued at £1115m giving a total EV of £2219m less £200m debt = M/Cap of 2019m and a share price of 239p.
This strongly suggests that DATA are selling 40% of the 'crown jewels' and to what extent higher margins can be achieved in Consumer and Technology is unclear. On the plus side is that overall margins have improved from 37.8% in TTM to 41% in FY'23 actuals recently released.
The exciting bit here is the growth story and previous successes of the founder / CEO so the bull case rests strongly on faith in the CEO.
Company brokers, Singer, produced a broker note in December at the time of the RNS announcing the partial sale. They increased their target price to 231p (from 178p) based on a reduced 20 x EBITDA multiple. If you use the sale multiple of 22 x then you would get a target price of 254p.
Clearly Singer are valuing the Group close to the lower 'share of EBITDA' valuation I outlined above. They will issue an updated valuation once the partial sale completes.
Guess it all comes down to success of the new Growth Transformation Plan 2024-26.
Good luck to holders (I hold).
Snazzy
Excellent work Snazzy, thank you
Kier (LON:KIE)
I have mentioned this as a golden opportunity when around 125p.
Half year results confirmed today the resumption of dividends. I have no doubt that soon buybacks will be announced as well enhancing EPS even more.
Recent entry in the FTSE250.
2024 Revenues already 97% secured: therefore obviously more upgrades.
This trades on an EV of £330m with FCF of £110m (2026 estimates). Very few listed companies trade on EV/FCF of 3!
The bonus is that the county needs infrastructure projects as soon as possible leaving plenty of room for increase in revenues.
In my opinion this is as green as it can be and I have no doubt that it will be a £1Billion+ market cap company.
I hold and added today.
All the best
hi yiannos1
Kier (LON:KIE)
All very good points making the bull case clear.
But it's hard to get away from the main bear points that this is a low margin business in an accident prone sector.
Not for me but good luck to holders.
Snazzy
Hi yiannos
I looked at Kier (LON:KIE) when it was trading at around 112p and was tempted, but as I already hold a large position in Galliford Try Holdings (LON:GFRD) and funds were limited I let the opportunity pass.
Anyway, providing management continue to effectively manage risk in bidding for contracts, the future looks bright. I wish you well with your investment.
All the best
Galliford Try are on the Mello show this Monday MelloMonday 11th March 2024 – Mello Events
TT electronics (LON:TTG)
I recently bought an opening position at 140p, on the basis that despite the lack lustre share price over the last couple of years and disconcerting level of debt, the shares were too cheap, given broker forecasts and the markets in which the company operates that focus on electrification and connectivity,
Having held the company previously with varying degrees of success I was pleased to see the change of CEO. Peter France has a good CV having previously been CEO at Rotork, where he enjoyed reasonable success, albeit he eventually left following a profit warning. Nonetheless his background appears to fit well with his appointment at TT electronics (LON:TTG)
Today's interim results read positively, albeit there are again a fair number of adjusting items, some £44m if I read the runes correctly. However £32.5m of that relates to the recently announced disposal of three business units.
The outlook statement is positive with several metrics heading in the right direction:
"Outlook
· Order book visibility remains above historic, pre-Covid levels - total order cover at December c.11 months revenues of which c. 9 months relates to 2024 revenues
· Focus on improved operational execution driving continued earnings growth
· Strong free cash flow generation and continued reduction in leverage expected
· On track to deliver 10% group operating margin in 2024
· Capital Markets event on 9 April to provide details of our actions and plans to accelerate the execution of a refreshed strategy, that will unlock value and deliver continued growth."
Hopefully Graham will find time to comment on the results
TT electronics (LON:TTG) as fellow holder I took comfort from the recovering performance of power and connectivity solutions - in stark contrast to the results at XPP.
Hopefully this is a kitchen sink job on the restructuring and further write offs. Typical of a new broom. I am positive on management ability to unlock the value. Hopefully the slide rules are out as well as net debt down to c £80m excluding lease liabilities and after proceeds of recent sales.
TT electronics (LON:TTG)
cheers jonno - dont no much about this company i specifically like the clear goal of 10% margins. that makes life simple for me as a potential sharholder - sales may rise and sales may fall but give 10% bottom line number and the investment is unlikley to be a disaster - as long as thats clean 10% - not ignoring material adjusts !
whether the operating margin number is clean is somewhat dubious as you say with chunky adjusting numbers in this year somewhat clouding that one.
Debt is chunky and finance costs/tax are deducted from the aspirational 10% pot that is left.
Overfall though if this company can churn out £35 mil pa profit and use that to pay down debt i could see potential nice rerating here - cherry on top would be geting £60 mill pa operating profit with no exceptionals and dwindling finance costs - not sure what their plans are ref prioritising debt reduction.
For anyone interested in Beeks Financial Cloud (LON:BKS) there is a Investor Meets Company H1 review this afternoon at 2.45pm.
https://www.investormeetcompan...
Prior to the seminar I did a little more Beeks desk research into what they consider any USP they may have and turned up this claim in a 2017 admission document…..
….Beeks’ connectivity has taken years to establish. The Directors consider that this is one of the Company’s core USPs and believe that establishing a similar offering would take a substantial amount of time.
Then more recently this USP is mentioned in a 2022 Progressive broker note…
….The (Infrastructure as a Service) suite offers an inherent security benefit vs. public cloud deployments – it runs on the client’s own infrastructure and operates under the care of their own IT team. This is a key USP, in our view, given the typically demanding security requirements of the target Tier 1 customer group.
I am unsure about the former claim, but I can understand that if you are an Algo hedge fund manager that having your own IT secure high speed line into a financial exchange vs. using public data line from a multi-national cloud provider, does have attractions. Maybe more colour this afternoon? I hold.
Funding Circle Holdings (LON:FCH) on such a busy RNS day it’s quite understandable that Funding Circle has slipped under the radar, but I was interested to read that they’re starting a £25m share buyback
Given that their market cap is £101m after todays +29% rise that’s a chunky proportion of shares being bought back & ultimately will be cancelled
In addition, their results today are inline with expectations “Over the next 3-4 years we expect net income growth of 15-20% CAGR with PBT margins of >15%”
Expressions of interest in their US business could provide a further boost
Usual disclaimers DYOR blah blah but may be of interest to small cap investors & I flag it up for discussion
FCH has great asset backing - this is from todays FY release.
They could easily double the £25m buy back they announced today and still have more than enough for their business which is very capital light
Looks like consolidation in the air with Nationwide bidding for Virgin money. Appears to be having a read across to other niche lenders that are very unloved/valued - my favourite Osb (LON:OSB) is up 8% today and I dont see any other reason for this than sector read across. Well apart from the tiny PER, large dividend and strong own funds /liquidity/CET……… ;-)
Agreed David, Been a favourite of mine for sometime and is a long term hold. Another stock to hold onto and collect the very attractive dividend and wait for the market to appreciate the quality of the company .
For anyone with an interest in the car retail sector, news came out yesterday that Cazoo (NYQ:CZOO) will be exiting the used car retail business, and instead trying to become a marketplace like autotrader, motorway, carwow etc..
This will take out a major competitor to the likes of Motorpoint (LON:MOTR) and other used car retailers who will step in to mop up their market share. And goes a long to proving the invisibility of the purely online used car retail model. Will be interesting to see what happens with cinch next, who are currently racking up annual losses of over £180 million, very similar results to Cazoo.
Isn't Cinch part of a larger (established/stable) group? I have foggy memories here, but wouldn't expect them to close as they probably leverage the scale opportunities of being part of larger group.
Cinch are part of constellation automotive group (owner of BCA the largest UK auction company for used cars, also own we buy any car & Marshall motors), who in turn are owned by private equity firm TDR Capital. TDR is the company which had a large stake in Pendragon and also recently bought a stake in Vertu motors.
- yes, the boys and girls at Motorpoint (LON:MOTR) (and Vertu Motors (LON:VTU) presumably) will be licking their lips that one of their rivals leaves their game entirely
- meanwhile the share price does nothing on this news, lol
More signs of recovery in housebuilding, with Nexus Infrastructure (LON:NEXS) reporting today a 24% increase in order book from Y/E 30 September to end of January. Paying a 2p dividend. Halifax also announcing today house prices rose in February by 0.4%.
Yesterday the UK Housebuilding PMI for February came out at 49.8, up from 44.2 in January. Although still less than 50 (just!) this is the highest level since November 2022.
Nexus Infrastructure (LON:NEXS)
Interesting company the market cap is extremely low here compared to sales cash and bok value. Heck Northern bear Northern Bear (LON:NTBR) could buy this company for 50% premium for cash and get £4 million improvement in their cash balances due to the £14 mill cash on the balance sheet.
Would be interetsing to se if there are new expectations ref 2024 - are profit number of £1 mill profits doable?
Everything here looks great other than the main business activities seem to be more a lifestyle business continuing operations £88 mill and cost of sales £83 mill - i know they are probably in extreme tickover mode but to me the test of a good buisness is that it can still eek out reasonable profits unless we are in the hight of a recession. Hey ho their plan may pay of perhaps if they retain skills and work picks up big time. I must say though even back in the day margins looked quite low. Perhaps its lingering effects of business sales and they will come out fighting lean and mean. Must say if you aint gonna make £5 mill profit all in on £87 mill sales should you be listed unless you have plans for decent growth ? - i would concede being listed might be good transparency ref their good solvency?
Looks an interesting oddity if nothing else - ripe for sale of activites that are left perhaps or delisting risk value trap?
Nexus Infrastructure (LON:NEXS) say their robust financial position helps them win business, and also allows them to bias towards better-margin projects. The cost cutting looks quite substantial and if they are winning decent margin business as well then so much the better. In part it depends on how the competitive landscape is washing out after the housebuilding recession, who is still standing, is competition tougher or weaker?
They are presenting on the Investor Meet Company platform tomorrow. Should be interesting.
Helium One Global (LON:HE1) this caught my eye this morning from the CEO.
The results from Itumbula can only be seen as transformational for the Company; flowing helium concentrations at these levels to surface would position Itumbula in the top section of major helium producing fields.
They have done 2 rounds of fundraising last year and I'm aware that helium prices are up recently, I don't know too much about the company, but will start digging around opening a small position if I can get in early.
"helium prices are up" Ballooning surely?
Now you are at risk of getting carried away Mr Contrarian
I refuse to be spoken to in that tone
hi Viz
Helium One Global (LON:HE1)
Not for widows and orphans!
Quality 17 Value 15 Momentum 13 StockRank 6
Snazzy
Hi Snazzy,
Yes, it's a short term trade, given I'm pumped via my punt in Superdry (LON:SDRY).
Obviously I have no idea what I'm doing, but having skin in the game makes me have to learn more.
I need some riskier stocks in my portfolio.
Viz - "Obviously I have no idea what I'm doing"
Welcome to the club!
I used to own Helium One back in the day but lost interest after a double. The chart looks awful, but zoom in on the past few months .... the stock has 10 bagged.
The thing that struck me about HE1 this morning were the 2 RNSs, interim results and outlook, separately. Why the need for 2? It's a small, hyped company with no firm future revenues in sight. Could they be trying to pump the profile a bit?
I'm not too sure about the viability of a first year in a UKISA, ii will charge me £4.99 a month for the £5000 invested in the account plus £3.99 per deal and I cannot see the slightest benefit in it.
Then use a provider that is cheaper than ii?
Plus you're assuming that ii will charge the same fees for the UKISA. That may not be the case when it launches.
Hello Boon, yes, I am assuming ii will apply a similar charge as it does to the ISA i hold with them and don't expect them to make an exception. Also, there could be a problem in opening the UKISA with a different provider in the same tax year as I intend to bed and ISA holdings out of my standard account with ii and into the ISA.
My sass was thrown out by ii after the abrdn takeover and is MUCH better at AJBell where it’s less clunky to use and better availability of investments for example I was able to buy Tritax EuroBox (LON:EBOX) instead of Tritax EuroBox (LON:BOXE) i.e. sterling instead of euros so the platform isn’t hosing me down on currency charges on the dividend ;)
I am in the same situation. However, for me, a considerable downside of AJ Bell is that you cannot set a stop loss for non-UK stocks. It seems very remiss of AJ Bell, given so many people have moved away from UK stocks.
hi Silver Moon
II will only charge £4.99 a month if it is a standalone new plan. If you are already a customer with an 'Investor' plan (the most popular plan) then you wont pay any additional monthly fee.
Snazzy
It sounds like a standalone plan to me Snazzytime, it's not the same as the Lifetime ISA which apparently was not additional to the ISA allowance, but what do I know?
Belvoir (LON:BLV) shares suspended the merger? Or something new?
Toad1957, yes.
From yesterday's announcement.
"The last day of dealings in, and for the registration and transfer of, and
disablement in CREST of, Belvoir Shares is expected to be today, 6 March 2024.
The Scheme Record Time is expected to be 6.00 p.m. today, 6 March 2024. An
application has been made for the suspension of trading in Belvoir Shares on
AIM and such suspension is expected to take effect from 7.30 a.m. tomorrow, 7
March 2024."
Belvoir (LON:BLV)
I suspect Louise George has her knickers in a twist re "The Scheme Record Time is expected to be 6.00 p.m. today, 6 March 2024."
This would mean with two day settlement you could sell the Belvoir shares yesterday but still be on record as the owner. I think as with share trading, if you bought them yesterday, the record will be updated on Friday hence no trading today.
If anyone wants to use the British ISA allowance without being forced to have more exposure to British stocks here's how:
1) Buy £5k of British shares in the British ISA
2) Now reduce £5k of British shares in your SIPP
3) You now have an extra £5k in tax benefits that isn't restricted
Or just buy ETFs listed on the LSE that has exposure to non-UK shares?
We don't know how they are going to define a "British" share for the purpose yet.
We don't know for sure, but the consultation paper gives us a pretty good idea:
https://www.gov.uk/government/...
"the approach could be to define eligible UK companies as ordinary shares in companies that are incorporated in the UK and are either listed on a UK recognised stock exchange or admitted to trading on a UK recognised stock exchange."
"The government could also replicate a previous approach for collective investment vehicles in PEP for the UK ISA. When introduced, PEPs allowed investments in authorised unit trusts and / or investment trusts if at least 75% of the value of the investments held by the fund were invested in eligible UK companies."
or just buy NVIDIA
The government are not that stupid unfortunately. The consultation document indicates it will be limited to funds/trusts that have at least 75% of the value of their underlying investments invested in UK listed companies.
In practice, it'll be much higher than 75% because you can't have a fund suddenly become ineligible for the UK ISA once you have already invested in it because of a shift in the markets.
Funds such as NinetyOne UK Special situations should do well out of this - but as already pointed out there's plenty of room with existing ISAs and SIPPs to invest in UK
probably works out well too bearing in mind i tend to hold all my us stocks in my sipp due to being able to hold dollar currency and the the tax benefit ref lack of the extra non reclaimable witholding tax that some stocks (Somero!) levy on isa dividends but not sipp dividends. Reet pain trading us stocks in an isa with my broker (think that is issues more with the rules than them)
Somero Enterprises (LON:SOM) rmillaree - do you perchance hold your Somero ISA shares via Iweb / Halifax? As they should be able to reclaim 15% - but refuse to do so. Unlike AJ Bell & II, where we also hold them and who do reclaim the 15%.
And, yes, in a SIPP, the full 30% should be able to be reclaimed.
Somero Enterprises (LON:SOM)
do you perchance hold your Somero ISA
i dont hold somero in an isa i hold in a sipp so i dont have the problem mentioned , thankfully - i get the full monty divi in my sipp with no deductions , was more flagging up the issues for others - always good to point out to peeps here they could be losing 15% or 30% of their divdend income here if they are not careful or if they have acrap broker.
My morning smallcap tweet: Pepper spray for promoters
Tribe Technology (LON:TRYB) HSS Hire (LON:HSS) BSF Enterprise (LON:BSFA) TT electronics (LON:TTG) Brooks Macdonald (LON:BRK) Robert Walters (LON:RWA), Nexus Infrastructure (LON:NEXS), Kier (LON:KIE)
◄Tribe Technology (TRYB)► startup aiming to revolutionise mine drilling has "switched on the engine of the autonomous Drill Rig prototype for the first time". Well, slap my thigh! Co also working on autonomous barrel scraper. [SP=6.07 Cap=13m]
◄HSS Hire (HSS)► sells power generation biz for £23.25m. Biz made £6m op profit in FY22. [SP=8.8 Cap=62m]
◄BSF Enterprise (BSFA)► working with the UK's leading cultivated meat production company, Ivy Farm Technologies, to help fundraise, launch and scale its cultivated meat plans in China. BSF will invest in Ivy Farm. [SP=7.75 Cap=8m]
◄TT Electronics (TTG)► FY-Dec. EPS -3.9 (-7.5) but adj EPS 19.2p up 5%. Difference mainly asset impairments and "measurement losses". Huh? Outlook - confident of 10% op margin in FY24, from 8.6%. [SP=139.8 Cap=248m]
◄Brooks Macdonald (BRK)► H1-Dec. Guides FY profit in line but now expect net FuM outflows for FY. [SP=1650 Cap=271m]
◄Robert Walters (RWA)► FY-Dec. Outlook - trading still muted. [SP=431 Cap=312m]
In line: NEXS, KIE
"Co also working on autonomous barrel scraper".
First Class!
Virgin Money UK (LON:VMUK)
Ok nationwide have bid for virgin - on the basis that merging banks is messy I suspect this deal is likely to go through. If anyone else wants this business they should probably show their hands quite quickly? Virgin is far from alone in being lowly rates do presuming this does go ahead should be plenty of options to recycle money into another bank.
Thank you for mentioning this, I have a small holding so beers will be on me in the pub tonight.
Virgin Money UK (LON:VMUK)
On the basis it’s Thursday I will be having my normal six tonite.However as my mates don’t buy me a beer when I get yet another profit warning I think i will take smooth with the rough and keep hands in my pockets. Bit spooky that I just predicted a few days ago on the other place that the price would be back at 225 by April the 1st - joke was on me with that one as that was meant to be an early April fool.
I sold my substantial holdings a months ago. I will let everyone know when I next sell any holdings!
All banks in UK are good value. and worth having a reasonable exposure to.