Small Cap Value Report (Thu 7 Nov 2019) - SDRY, PURP, WRKS, SYS1

Good morning, it's Paul here.
I'm making a guest appearance today, so that Graham can prepare his talks for Mello investor conference next week, in Chiswick. I'll also be pottering around at Mello, being generally affable to passers-by, but am not doing any talks this year, because I haven't really got anything new to say compared with last year. I'm still largely invested in the same shares, and my views on them have not changed much. The main change is that they've mostly gone down in price!
Estimated completion time - it's a bit complicated today, because I'm still on holiday in Gozo, the little sister island to Malta. My 50cc scooter has to go back to the hire shop by noon, but I'm itching to have a final whizz around the island on it. See moped-cam below, later! However, in order to not disappoint readers here, I'll write about half of today's report by about 10:00am today, then I'll come back and write the rest this afternoon. Apologies in advance for any inconvenience. So the full report should be complete by 3pm.
Update at 15:34 - it's taking longer than expected (due to technical problems updating the article), so I'll be finished by 6pm. Apologies for any inconvenience.
Update at 20:44 - I've been having technical difficulties updating this report this afternoon, hence the delay. I'll have one final attempt at getting the section on System1 up. Success! Today's report is now finished.
.
Kudos to Graham - for having the initiative to write to the Competition & Markets authority, asking them to put more detail in their RNSs. They have obliged, and instead of almost every RNS from them being titled "Merger Update", they are now including the company name(s) which the RNS refers to, in the title. This is a small, but very useful change, which will save lots of people some time and frustration, having to open numerous RNSs which won't be of any interest to them. So congratulations to Graham for prompting this improvement. It just shows that sometimes, a polite email with a good idea in it, can actually change things for the better. Also kudos to the CMA for listening, and responding positively to a sensible suggestion.
Today I'll be reviewing the following announcements;
Superdry (LON:SDRY) - Half year trading update
Purplebricks (LON:PURP) - Half year trading update
Works Co Uk (LON:WRKS) - Half year trading update
System1 - Interim results
Please bear in mind that reader requests mean less time for me to enjoy on holiday. Could you live with that guilt? ;-)
.
.
Superdry (LON:SDRY)
Share price: 445p (up 5% today, at 08:35)
No. shares: 82.0m
Market cap: £364.9m
Superdry today announces a trading update covering the 26 week period to 26 October 2019...
It's amazing to think that this previously high flying designer brand/retailer, is now a small cap. This is a potential turnaround, with the founder having turfed out previous, seemingly incompetent management. Although note that shareholders generally did not support his return - it was only his large personal shareholding which clinched it. That said, I'm positive about him re-taking the helm. If anyone can turn around a struggling business, it's usually the founder. Hence for me this share is a potential opportunity.
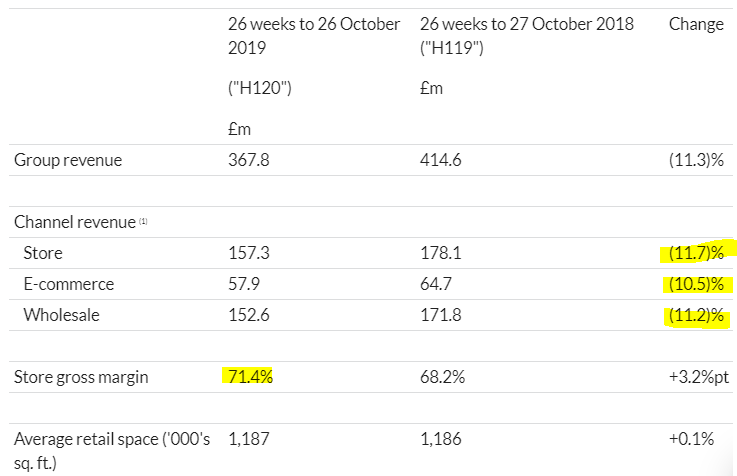
H1 revenue figures look grim;
.
Revenues - note the bottom row, showing that retail space has barely changed. Therefore, the store revenues will be almost the same as LFL store revenues. A fall of 11.7% in store revenues is bordering on catastrophic. The reason being that store costs are mainly fixed or rising, so any drop in revenues will feed through to an operationally geared (i.e. much larger %) drop in profit.
Improved gross margin - there is a notable improvement in store gross margin, from an already high 68.2%, to an extremely high 71.4%.
This partially offsets the reduction in sales. In fact, we can work out by how much, as follows;
Before - Notional revenue of 100. Gross margin of 68.2% = gross profit of 68.2
After - Revenue down 11.7% from 100 to 88.3. Gross margin up to 71.4% = gross profit of 63.0 (down 7.6% on previous level of 68.2)
Therefore, a revenue fall of 11.7%, combined with the higher gross margin, produces gross profit down by 7.6%. In other words, the improvement in gross margin has recouped about a third of the fall in revenues.
The above is a simple technique which I learned from my accountancy training. You always start with 100, and then put through the various % changes, and it gives you a useful result.
That said, a 7.6% fall in gross profit is still a big problem, given that store costs (rent, rates, utilities, etc) are fixed, and the other big cost of staff wages is rising due to increased minimum/living wage driving wage differentials up all the way up, as supervisors & managers push to maintain their differential above the lowest paid. Plus pension, and apprenticeship levies coming in. Employers are under a nasty squeeze with higher costs right now, which is proving ruinous for many retailers, as they're also losing sales & margin at the same time.
I reckon it's likely to be carnage in 2020, once Xmas is out of the way. Insolvencies in retail are often staved off until January, to get the peak Xmas trading & January sales in, to liquidate as much stock as possible. Expect many insolvencies in this sector in 2020, not just for smaller, independent retailers. I doubt whether Debenhams or House of Fraser are likely to last much longer, for starters. Although that will of course leave more market share for the survivors. Hence why I am not bearish on M&S. I think the short trade in MKS is lazy, over-crowded, and ignores some powerful positives.
E-commerce sales - down 10.5% - this is a serious concern too. Fashion businesses need to have a large (ideally half, or more) sales online, and growing strongly, to be of interest to me. This has been proven by the success of Next (LON:NXT) - where investors who spotted that it is successfully transitioning online, have done well.
Superdry's online sales are just over a third of its store sales, which is OK. But online sales should be rising by about 20%, not falling by over 10%. That worries me a lot.
Shop leases - It strikes me that Superdry is following the right strategy, using its stores for full price sales. The >70% gross margin should enable those stores to remain profitable, if sales volumes are also strong. SDRY has a problem in that it took on a lot of "flagship" stores, in prime sites, on big rents. This could drag down the whole company, if sales continue falling, due to exorbitant rents & leases which prevent them escaping from loss-making sites. This is my biggest concern about SDRY.
There's a lot to be said for SDRY selling only full price in-store, then sending unsold goods back to the warehouse, to be sold online only. The narrative seems to suggest this is what they're doing. As opposed to permanently discounting in-store. Therefore, reading through the narrative today, I agree with the revised strategy under Mr Dunkerton - namely focusing on getting the product design & quality right, then just selling at full price in-store. That way, enough gross profit should be generated to make the stores viable. Once consumers have been re-educated to not expect permanent discounting in-store. That is part of the reason why LFL sales are down - because the prior year comparative had a lot more discounting going on in the stores.
The problem is that, trying to sell more product at full price, could simply be deferring price discounting. Product that customers don't like has to be discounted in price, otherwise it just won't sell.
Outlook - cautious, challenging market. But makes optimistic noises about improving product designs.
My opinion - there are definite signs of life here, with improvements having been made. However, the trajectory of profits for H1 is likely to look pretty awful when the figures are published. Therefore, I won't be even considering buying this share without first seeing its interim results, due out on 12 Dec 2019. These are likely to look dreadful, given the 7.6% fall in gross profit at store level, combined with increased costs, plus big falls in online and wholesale revenues.
It's on my watchlist as a possible recovery share, but I wouldn't be surprised to see another lurch down in share price to go with the interim results in Dec.
The founder is obviously under pressure to report improvements, but that's not coming through in the numbers yet. Talk is cheap.
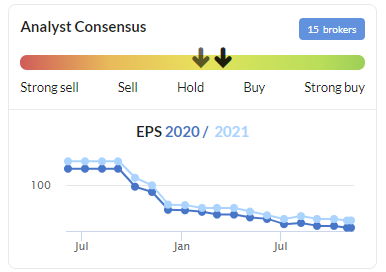
Profit forecasts have collapsed in the last year from 122p to 41p;
.
(incidentally, note that brokers are assuming an automatic improvement in 2021 figures, above 2020. Why? I would suggest that the 2021 forecasts line should be below the 2020 line! That applies to lots of companies right now. The risk of broker forecasts being wrong by a considerable margin, i.e. way too optimistic, looks very high at the moment. So buyer beware! We need to really question why forecasts for next year would be higher than this year? Unless there's a very good reason, then I'd be inclined to chop 20-30% off next year's forecasts, and then see if a purchase makes sense.
In order to drive EPS back upwards again, SDRY will need to start generating positive LFL sales growth from its stores, and positive E-commerce growth. It doesn't seem to be anywhere near that at the moment. Although remember that this year's poor figures become next year's soft comparators.
In conclusion, I think a turnaround might be starting, but it's very early days, and I wouldn't want to risk buying at this stage. I'll wait to see what the interim figures look like, and Xmas trading, then review it again in early 2020.
.
.
Purplebricks (LON:PURP)
Share price: 113.3p (up 4.3% today, at 10:07)
No. shares: 306.8m
Market cap: £347.6m
Purplebricks Group Plc (AIM: PURP), a leading estate agency business, announces a trading update for the six months ended 31 October 2019 (the "period" or "First Half") ahead of reporting interim results on 12 December 2019.
This is one of many growth companies whose share price soared in the boom of 2017, but has since come all the way back down again. This is because growth stalled, and some overseas expansion turned out to be an expensive mistake. Also, I think the bears were right (as I said at the time, and thankfully decided to sell my own shares in it) that the advertising by PURP claiming to be the same as a normal estate agent, simply isn't true. Its business model is leaving behind a long tail of dissatisfied customers with unsold properties, having paid the fees up-front. My family bought a property which was advertised by PURP, and found them largely useless. We managed the purchase with the seller, and PURP became irrelevant. In our experiece, the only purpose for PURP is to list properties on Rightmove, and enable prospective buyers & seller to connect through an app.
Trading update today - this sounds reasonably OK, in a tough market (where an online operator has considerable advantages, in having flexible, not fixed costs);
During the period, there was a weakening in the overall UK property market as political and economic uncertainty impacted confidence, reducing home sale volumes. This was particularly notable in the South East.
Against this backdrop, Purplebricks maintained its 4% overall market share and also expects to report an improvement in the marketing-to-revenue ratio as planned efficiencies are now being realised.
The Canadian business modestly outperformed expectations over the period.
At a Group level, pro forma revenue is expected to be broadly flat relative to the same period last year[1] and the significant losses incurred in the prior period have now been reversed and the Group enjoyed profitable trading in the First Half.
My opinion - the above sounds reasonable to me. I'd like to see the accounts when they come out on 12 Dec before commenting further, as trading updates really don't give the full picture.
PURP is the market leader in the UK, amongst online estate agents. Although conventional estate agents are not ignoring the online option. All that's needed is a very simple app, to handle enquiries. Another problem with PURP is that their supposed local property experts are nothing of the sort! They cover patches that are far too big to possibly understand local issues. Hence I think a traditional estate agent is far more likely to secure the best price.
Even though the share price went from £1 up to £4, and then back down to £1 again (rough figures), this doesn't necessarily make it a bargain. The market cap is almost £350m, which looks high for a business which may have had the best growth behind it now, perhaps? I'm not tempted to revisit for the time being, but reserve the right to change my mind at any time, if the facts change.
.
.
Works Co Uk (LON:WRKS)
Share price: 44.7p (down 42% today, at 15:39)
No. shares: 62.5m
Market cap: £27.9m
Half year trading update (profit warning)
TheWorks.co.uk plc, the multi-channel value retailer of gifts, arts, crafts, toys, books and stationery, announces today a trading update covering the 26-week period to 27 October 2019
Checking the archive, we've only looked at this July 2018 flotation, on a fully listed basis (not AIM) twice;
9 May 2019 - Graham reported on a profit warning, and urged "extreme caution"
3 July 2019 - I reported on the surprisingly good results, but wasn't convinced it had enough of a competitive advantage to continue growing profits.
What's happened today then? It's a profit warning, saying;
Whilst LFL sales have improved over recent weeks, as the impact of the prior year's Mega Trend eases, they were not at a level previously expected. Accordingly, the Company is taking a more cautious view on trading ahead of the Christmas trading period and, as such, the Board now expects full year profit before tax to be significantly below current market expectations.
I regard the "mega trend" comments & figures as a red herring. This is where the company has a temporary sales surge in a particular product. You can't adjust sales to exclude such surges. Therefore in my view, the only meaningful figure below is the -3.6% LFL figure;
Total revenue increased by 5.4% year-on-year, and when excluding the impact of the prior year Mega Trend[1], LFL sales[2] were -1.9%. This performance reflected the difficult consumer backdrop over the Period. When including the prior year Mega Trend LFL sales were -3.6%.
As we've seen with other retailers, the increased costs which the sector is exposed to, means that LFL sales need to be positive, just to stand still in terms of profit. With footfall dropping, and sales migrating online, it's very difficult for retailers to generate positive LFL sales.
New stores - this is a surprisingly large chain, with 525 shops. It's expanding at a helluva lick, with an intention of opening 50 new shops in total this financial year. What's interesting is that they're getting great deals from landlords apparently. The payback time is said to be only 1 year, which is phenomenally good. Although I would be interested in how that figure is worked out - in particular how they handle landlord contributions such as reverse premiums (cash contributions towards fit-out costs) and rent-free periods.
My opinion - the problem, as I mentioned back in July, is that it only ekes out a small profit from a lot of revenues. Therefore, if LFL revenues turn significantly negative, the company could easily tip into losses. What happens then? There's no sign of High Street trends (footfall) improving, or even stabilising. Some smaller towns are becoming ghost towns if they had an M&S which has, or will be shut.
For that reason, even though TheWorks looks tantalisingly cheap, I'm reluctant to get involved. With a £50m p.a. wages bill, and average wages currently rising by about 4% p.a., then that's a reduction in profit of £2m p.a.. Combine that with negative LFL sales, and probably pricing pressure too, and it's easy to see last year's £6.7m profit disappearing altogether in the not-too-distant future. That also means that divis may not be sustainable.
Therefore I think this one is probably best being given a wide berth.
.
.
System1 (LON:SYS1)
Share price: 180p (unchanged today, at market close)
No. shares: 12.6m
Market cap: £22.7m
System1, the marketing services group, today announces its results for the six-month period ended 30 September 2019 ("H1").
I went through the main issues here on 14 Oct 2019, reporting on its H1 trading update. The figures today look to be in line with what was previewed then, i.e. £2.4m adjusted profit. The main issue is that about half of that adjusted profit was spent on startup losses on a project called AdRatings.
All I need to do today, is a quick review of the interims, looking for funnies. Plus a review of the outlook comments.
Figures - look OK to me. I can't see anything untoward in the balance sheet or cashflow statements.
It looks financially sound, with a decent amount of cash on the balance sheet.
Divis - quite good, at a yield of 4.3%. Although with limited earnings visibility, the divis can't be seen as particularly safe.
Outlook - I'm not sure how to interpret this. Is it putting down a marker for a possible H2 warning? I admire management honesty in stating that there's little visibility. But would I want to invest in something with little visibility, especially at a time when the macro picture looks wobbly, hence marketing budgets can be one of the first thing that clients cut back on.
We continue to have limited short-term revenue visibility, so, as always, it is difficult to predict how the year will unfold. Nevertheless, we continue to believe that the business is making progress and in the longer term has high upside potential driven by its AdRatings asset and the more general digitisation of the business.
.
My opinion - I'm intrigued by this company, so will keep it on my watchlist.
.
.
That's me all done for today. It's been very frustrating battling with the technology today - several wasted hours. Never mind, these things happen from time to time. Thank you to the readers who were patient. To our 2-3 resident thumbs-downers, you can have a middle finger from me in response!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
Oh to see Brexit out of the way. Quite right to steer well clear of the high street.
Purplebricks (LON:PURP)
Interesting as £333m market cap making a loss with £62m cash in the bank.
Looking at the full year results reported last July, we can see the performance split by UK, Canada, Australia and USA. Noted USA and Aus will be closed down, which makes sense given the losses, leaving UK and Canada as the remaining business footprint.
To justify a £300+ market cap PURP needs, say, £30m in earnings or at least a trajectory towards that.
The UK grew revenues 15.7m yoy from 74.4m to 90.1m but Operating Profit only grew 3.1m from 2.2m to 5.3m. While Gross Profit Margin is high at 63%, admin and marketing cost growth held back profits. So, the translation of revenue growth into profits is not great at this stage.
Canada generated 23.7m in revenue and an operating loss of 3.2m. Again, good Gross Profit Margin at 53.2% but Admin and Marketing costs drove the loss position.
In the round, PURP is going to struggle I think. UK KPIs showed Instructions grew 8.6% yoy which is not that high. Also, Marketing as a % of sales was 29.6% which doesn’t imply a cheap, scalable internet growth model. These are not the kind of numbers demonstrating a disruptor effect to deliver the large revenue numbers required to overwhelm their costs to drive high profits. Also, some interesting, fairly negative, service experiences shared on this forum.
So not a buy for me, possibly even a short option, but I’ll wait for the detailed results on 12 December, as the lack of a debt burden gives them some runway yet.
Innovaderma (LON:IDP)
Interesting news today that the CEO has upped and left with immediate and he has also disposed of all (?) of his shares at well below the prevailing share price - he is off to pursue other interests - did he do a Joey Barton and take his coffee machine with him i wander ?- kind of sounds like he's had a strop and walked out for whatever reason.(Joey Barton when he left rangers went to the trouble of taking the fancy coffee machine he bought for the players canteen - now that's revenge no coffee)
PS Hope Paul hasn't come across any giant stray flags on his Gozo moped tour today - they like their flags in Gozo.
Share prices in Stocko seem to have stopped updating at @ 3pm.
I'm having lots of technical problems this afternoon, which is the main reason that updates are taking an age to publish. Sorry about that.
No problem waiting an extra couple of hours for your normal high quality work.
Enjoy the rest of your holiday
Thanks James, appreciated :-)
I had Purplebricks over when selling my flat. They sent their East London manager, who was bragging about how awesome they are, but he was completely useless. He didn't seem to know the market at all, and refused to advertise it for the price we wanted (which we eventually sold it for), but wanted to put it out for 7% less. We politely told him to bugger off. On the basis of this experience and from what I have heard from others I would never use them. Something is just considerable wrong with the way they run their business and I think the initial hype regarding Purplebricks is gone, so I can only see the company and the share price going one way...
PURPLEBRICK (LON:PURP)
The Purplebrick "expert" is rewarded for getting the property advertised so he has little incentive to ensure it is sold. That is a business model which does not appeal to me.
Thanks Paul for a superb write up on Superdry (LON:SDRY) I have no position but I'm from his home town where it all started so I'm rooting for him to succeed. I used to buyT-shirts from his very first Cult Clothing shop and regularly see him about town at one of his many business ventures (hotels, bars, restaurants and even a cider factory). I found your analysis to be pitch perfect. He'll need to be a magician to turn it around but as you say, if anyone can, then he can.
I'm surprised that they actually increased retail square footage (albeit fractionally). I would have thought a big part of the turnaround strategy would need to include a drastic reduction in bricks & mortar but perhaps lease lengths are too long for that.
Enjoy your time on Gozo - I visited a while back and really enjoyed seeing all of the old Morris Minors running about. They're all right hand drive so might be worth picking one up!
Watchstone (LON:WTG)
I understand everything is done. Bods are nothing to do with him.
Yes i have checked and its there from October RNS as settled cheers - note that's with regard to all "Existing" Legal proceedings - hopefully he doesn't find new grounds to sue them !
"I think the short trade in MKS is lazy, over-crowded, and ignores some powerful positives."
Probably true. But it's easy to get things wrong. For example, it looked like there was upside when the share price was >300p, too! :)
Also, the short trade is much less crowded than it was when the linked article was written. Disclosed short positions have reduced from 12% to 4.4% of the market cap. It's no longer in the top 30 most shorted UK stocks.
Good points Graham!
However, like a lot of people who are negative on Marks And Spencer (LON:MKS) you admitted that you haven't even properly looked at the numbers! If you go through the figures, you'll discover a business that is highly cash generative.
It's begun to close loss-making stores in earnest now, after years to ducking the issue. This should give a large boost to profits. Partly from eliminating the losses at closed stores. But also from an overlooked point that when a store closes, the nearest remaining MKS store receives a boost in revenues of as much as 20%, thus greatly boosting the profits of the remaining shop. A large, and double benefit to profits. Although it's disastrous for the towns that lose their MKS store, sadly. The future capex spend will also reduce, as the number of stores drops.
MKS food offering is the best out there. Indeed, MKS is still probably the strongest brand on the High Street. They've made a mess of the clothing ranges for years now, so there should be a fairly easy 10%+ gain in LFL sales to be head once the product is improved.
Then there is the JV with Ocado, to sell MKS food online. This could become a massive business, and highly profitable. MKS has high gross margins.
All in all, it's a supertanker, so will take a few years to turnaround. I think a lot of investors (including me) are taking the view that it's likely to take too long to be an attractive proposition now.
Longer term though, there's no risk of insolvency in my view. When Debs & HoF go bust, that's a ton more market share for MKS. Likewise as independents & other weak chains go bust, all the more for MKS.
Remember that 20% of retail sales are through the internet now, but the other 80% are in physical stores. So if retailers can downside their store portfolios, and deliver a decent online offering too, then they should be one of the survivors, enjoying a bigger market share.
I definitely wouldn't short MKS at this level (c.200p).
Regards, Paul.
Paul,
To be clear, I don't have a position in MKS, and never have. I merely identify it as the type of business which could make for an attractive short (carrying financial debt and lease liabilities in a hyper-competitive, low-margin sector), and therefore could be worth investigating for a short sale. I wouldn't short it without doing the necessary detailed work on it.
Most of the funds who correctly shorted it at 300p, when others thought it looked cheap, have since closed their positions. Presumably they would agree with you that it has some positive opportunities, which no longer make it an attractive short.
Best wishes
Graham
Fair points Graham, I think that's a fair summary.
I think what the shorts got right, was that it would take longer than expected to turn it around. But the fact they've now mainly closed their shorts, says to me that they did a good trade, but are now happy to bank the profits & move on.
Therefore, it's probably a good time to now be looking at it as a potential long.
The property side of things is that MKS owns a lot of its own freeholds. My worry is what happens to those freeholds once the store closes? There must be a big write-down on freeholds in the pipeline, but I'm not sure if they've been revalued upwards in the past? It seems to be something that MKS likes to hide.
We also need more information on the sites that are leasehold. The previous lease accounting standards at least gave us some info on onerous leases. The IFRS16 standard gives us no information whatsoever of commercial value in assessing the economic reality.
All that matters right now, for retailers, is if they can get out of leases where they are trading at a loss. The length of lease doesn't matter at all, if the site is trading profitably. IFRS16 is absolute rubbish, and simply does not give me the information I need assess retailers longevity (or not).
Regards, Paul.
Video: ZOO Digital H1 19 investor presentation by Stuart Green, CEO & Phil Blundell, CFO.
Won a major OTT provider in period, providing better revenue visibility going forward. Things panning out nicely.
https://www.piworld.co.uk/2019/11/07/zoo-digital-group-zoo-h1-19-investor-presentation/
I think that's the best SCVR you've written for a while (and I do not mean the recent ones aren't good).
Maybe you should holiday more often! It can't be easy writing reports day after day, even now it's shared between two of you. I think it's great that you have different priorities, interests and styles and I enjoy reading both of your articles.
Thanks Doug! It's only half-written too, so prepare to be astounded & delighted with part 2 after lunch ;-)
The pressure is on Paul!!
Watchstone (LON:WTG)
Has anyone else looked at the maths on this?
Cash in bank = £38m
Sale of PtHealth = £23m
Release of escrow funds = £39m
Thus we have actual hard cash of £100m versus a market cap of £66m. The lawsuits against founder and Slater & Gordon now resolved.
There is a residual ingenue business that is worth something and a potential lawsuit against a large accountancy firm.
So let's assume the remaining business value and lawsuit is just a bonus and exclude it. That leaves cash worth 225p that you can buy for 146p.
Management have already intimated they will return most of the cash when escrow released and sale proceeds received, so it strikes me that somewhere in the next 12 months we can expect to receive maybe 200p, a 40% return, leaving another 30-50p on the table for free in the residual business.
I bought some more on that hypothesis. Does anyone concur or think my maths is wrong?
Watchstone (LON:WTG)
Not really being serious but all they need now if for Rob Terry to sue saying it's all his money - hmmmm memory recall is he not already doing this?
Wouldn't put anything beyond the realms of possibility with this company.
Being serious it would be interesting to know where they are at as the discount does seem to high if everything is resolved and the current bods in charge have absolutely nil history of ever having liased with Terry in any shape or form.
Watchstone (LON:WTG)
hi rmillaree - if you check out the rns they sued and settled with Rob Terry prior to settling with S&G so I understand everything is done. Bods are nothing to do with him.
the only potential suit is that Watchstone (LON:WTG) appear to think they may have grounds with one of the big 4, can't remember which. I read one commentator who seems to think this could end up settled materially in their favour but I discount this to zero. I am only interested in the cash return, which I expect to be 200p, and a free ride on the rest.
David
Thanks for this. I had seen this capital surplus referenced somewhere elsewhere else, and it maybe that the market is deeply wary of Watchstone (LON:WTG) given its past history, and previous management.
I suppose one might see Director buying if they felt it was substantially undervalued, but they may feel tempered by past events on Director dealing, and also there may be a conflict with their cash distribution decision. I wonder also whether they would be nervous of undermining any options value they may have by distributing? It depends what constitutes the vesting terms, I guess.
Anyway following your post I have put a small punt into the stock. But win or lose I appreciate your flagging it up
Watchstone (LON:WTG)
Thank you for bringing this to my attention David.
I haven't previously looked at this company, but having been through the previous few RNS' I would agree with your numbers.
2 things I wasn't sure about:
Assuming that management does return excess cash and that £20m is considered a reasonable amount to not distribute, I would say that there is c20% upside to the current price with little risk.
Like you, I wonder whether I am missing anything.
Cheers
Abtan
ps as an aside I have just taken a look through Ingenie's 2018 financials, published a couple of weeks ago with Companies House. The numbers look terrible with a 50% drop in revenue and a clear indication that bigger players are beating them on price. I can't imagine the business lasting long at its current rate, so perhaps a final sale, or even a closing down, might be on the cards.
Abtan,
re Watchstone (LON:WTG)
The cash return has been part of management rhetoric ever since they sold the original business to S&G. Repeated on the sale of ptHealth with regards to that cash too. I'd be very surprised if they don't return almost all of it as some sort of capital return.
ingenie business sales as per latest report has now turned upwards again and the management of that business appear bullish that it has a decent future. It is losing about £2m to £2.5m a year currently. The BoD of the overall group have always appeared reluctant custodians. ie My guess is that they will retain £5-7m (2 years of liquidity), release the rest as capital distribution, most will resign from board and shareholders will be left with a "rightsized" ingenie business funded to breakeven.
Thus I expect a capital distribution of 200p (40% upside from here) and a listed business of 35p (25p cash and 10p hope/brand value), or at least that is my personal rationale for buying some more.
Thanks for flagging this David. I've not looked into the company before but I found this note from Evil Knivel on the mater investor website which I think you will find interesting as it matches your hypothesis. His note is below:
I have received a few congratulatory messages pursuant to Watchstone’s (LON:WTG) rise two days ago. This is an agreeable response. However, it is misguided in that the rise was down to Lady Luck rather than the application of my logic.
Events have moved on in that the share price stands at 150p. This is flat wrong. Cash now exceeds 200p and the sale proceeds of operations should clear a further 25p cash. Further, there is the joker in the pack in that, as readers will recall, the High Court in London cleared WTG to bring a counter claim against Slater and Gordon for £63m. This claim against Slater and Gordon was dropped as part of the settlement announced on Monday. But it seems to me that there must be a good chance that WTG will now sue PwC for their conduct since, or so WTG allege, it was PwC’s conduct in acting as a “back channel” to Slater and Gordon that allowed the original £63m claim.
As to what this putative action will yield, I decline to guess. But I have made no allowance for it in my assessment of the cash in WTG. So the outcome is in for free.
Yesterday I bought a further 70,000 WTG at 150p since it seems to me to be a virtually free of risk trade. Indeed, it is a gimme.
It emerged late yesterday that the seller of stock on Monday last was Prudential. This underlines my view that one should never allow one’s money to be managed by these investment behemoths. I grant you that in the world of “new improved” Prudential the managers may prefer not to be involved in a company capitalised at c. £75m. But that surely does not mean that the baby should be chucked out with the bath water.
Re Watchstone (LON:WTG) : From a quick glance looks like there are a few things to be deducted here - final legal costs for the settlement are likely to be substantial (and given there was no admission of fault on either side they will not recover any of this from S&G). I wouldn't be surprised to see this wipe out anything from 5m - 10m of the cash. Also, I think the proceeds from the sale of PtH were on a cash free debt free basis and there was a mention of paying out pref shares (presumably seen to be 'debt') of 2m+ so you need to take out 2m+ of the sale proceeds for that. There are a fair few provisions in the accounts that might also soak up some cash if we're looking at the whole business value on a net basis. Overall the numbers might still be fairly favourable but you might have to drop everything stated by ~10-15%? Just 10 mins. 'back of an envelope' stuff so I've probably missed items in each direction.
The dreaded £ and numeral clash taking us to Sysgroup instead of System1. Feel free to copy:
System1(LON:SYS1)
Moped-cam - love it!
Superdry (LON:SDRY)
woeful lfl comparatives but at least Dunkerton seems to have an action plan that seems sensible. slight positive that there are more sales are at full price.
They seem to be on track - so no further deterioration on expectations - subject to it all being up in the air. Expecting and delivering really poor numbers probably isn't anything to get excited about though i would say and there is still time for things to get worse.
Decisive action taken and positive indicators of future performance underpin full-year expectations.However, we remain cautious about the challenging market conditions over the peak trading period.
Note despite the poor numbers they are expected to churn out £34 mill profits this year so the company is still sound despite not being the money making machine it used to be.
Broker expectations of 20% plus growth in earnings next year (30/4/2021) seems waaaaaaaaaaay optimistic based on continued poor numbers being generated.
I continue to hold for some reason.
My morning smallcap tweet: TheWorks warns
Works co uk (LON:WRKS), Hansard Global (LON:HSD), Arsenal Holdings (OFEX:AFC), SysGroup (LON:SYS)1, TI Fluid Systems (LON:TIFS)
TheWorks.co.uk (WRKS) guides FY pretax significantly below current market expectations. H1 rev LFL down 3.6%.
Hansard Global (HSD) Q1 Present Value of New Business Premiums up 10%. Growth largely from new business in the UAE. In line?
AFC Energy (AFC) When 'disruptive' gets tired, wheel out 'truly disruptive'. Update on progress of the truly disruptive HydroX-Cell(S) fuel cell.
System1 (SYS1) H1 rev up 4%, pretax up 35%. Normalised pretax up 26%. "H1 sales growth is not yet on the trajectory we are aspiring to." Waffle for warning?
In line: TI Fluid Systems (LON:TIFS)