Small Cap Value Report (Thu 7 Sept 2023) - RST, CURY, DCTA, SYNT, CVSG, PAY, HFG, POLX, LORD

Good morning from Paul & Graham!
I hope you're coping alright with the heatwave. I'm fine with a desk fan blowing on me 24/7, and a siesta each afternoon! I wonder how many companies will blame the weather for the next batch of profit warnings?!
Right I've got to dash for another City lunch, so we'll leave it there for today. Graham has offered to help out tomorrow, so we can make a dent in the backlog.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
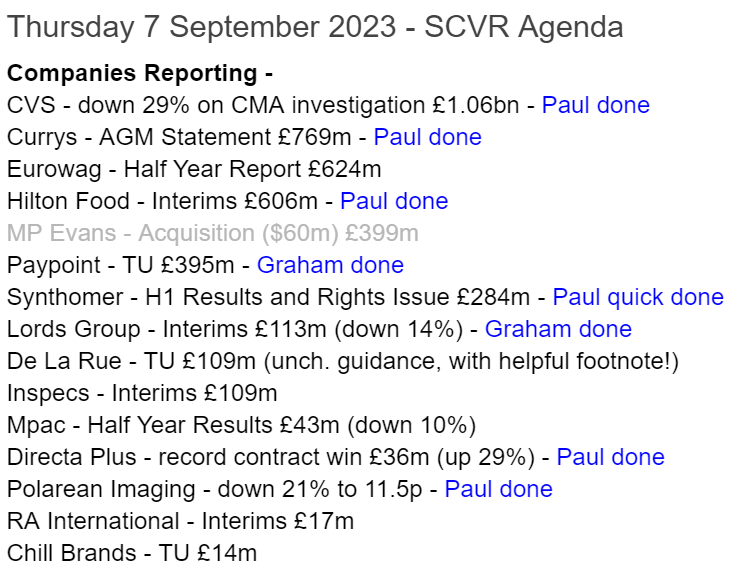
Busy again for reporting. So we'll probably do about half of these, trying to pick the more interesting, and price-sensitive ones as priorities -
Summaries -
Restore (LON:RST) - 205p (up 14% y’day) £281m - New CEO & big contract win - Paul - AMBER
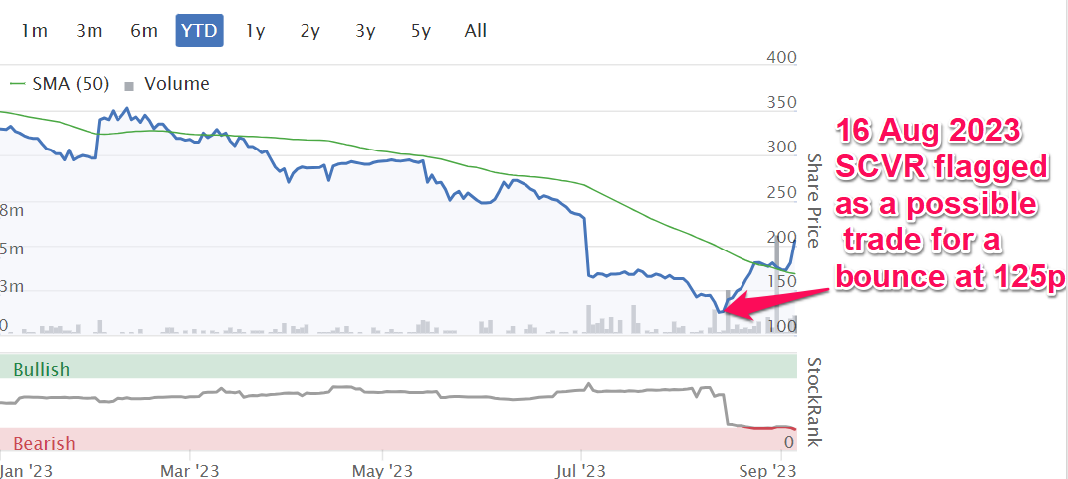
I'm pleased to say we spotted the turning point here in 16 August's SCVR (suggesting it as possible rebound trade at 125p), and RST shares have since bounced over 60% in just 3 weeks. Although the 14% surge yesterday was due to new information about a significant contract win with HMRC. Note that a long-serving (10 years) former CEO is rejoining as new CEO, so will be able to hit the ground running. Interesting, but I've shifted back to amber, due to the large recent bounce in share price.
Currys (LON:CURY) - 49p (pre market) £554m - AGM Trading Statement - Paul - RED
A reassuring trading update, with no change to guidance. Although LFL sales are down 2% in its largest market (UK & Ireland). I reiterate the extremely weak balance sheet risk, with the business entirely dependent on c.£2bn trade credit - this is why I continue to see the shares as high risk, hence RED.
Directa Plus (LON:DCTA) - up 29% to 56p (£37m) - Contract win - Paul - RED
An impressive-sounding contract win today has put a rocket under this graphene products company. Although the investment case quickly falls apart on some basic scrutiny. It's a big cash-burner, and I suspect will need more funding in 2024. Revenues are rising nicely, but losses remain stubbornly high. No evidence of any decent gross margin either, so I can't see the vitally needed operational gearing here. Thumbs down from me at this stage, but I'll keep an open mind if things improve in future.
Synthomer (LON:SYNT) - down 31% to 42p - Fundraising - Paul - RED
Quick comment - I’ll keep this brief. We flagged the dilution risk here on 13 Dec 2022, concluding with a RED view - “Risk of a dilutive fundraise strikes me as high. This share looks complicated & risky, so I’ll steer clear.” The problems were caused by a disastrous, large debt-fuelled acquisition, and then a deterioration in trading. It didn’t take any particular insights to spot this, just a quick look at the stretched balance sheet. Paul’s opinion - I can’t see any merit in spending time analysing the terms of today’s refinancing, we’ll take a fresh look at it once the dust has settled in future. H1 results are poor, and the right issue doesn't solve the debt problem, just mitigates it. Bank facilities dependent on rights issue. Looks a mess. [no section below]
CVS (LON:CVSG) - down 29% to 1484p (£1.06bn) - CMA investigation - Paul - RED
Quick comment - many thanks to readers below who flagged this issue. I was wondering why this chain of pets had plunged 29% this morning with no RNS news. Redice spotted a BBC article here which says the CMA is to investigate over-charging by vets, and how the market has consolidated with corporates gaining market share and driving up prices unreasonably. Long overdue I’d say, this sector is a disgrace in my opinion, in the way some vets exploit owners’ love for their animals through outrageously high charges. An example of capitalism working badly I’d say, so let’s hope the CMA gouges the gougers! I won’t be bottom-fishing here, at any price. Note that CVSG doesn’t have any balance sheet support either, with NTAV last reported around zero. I'd be worried about shorters getting involved. Update: CVS has published this brief response to the CMA announcement. It points out that there's a shortage of vets in the UK, and that wages (and other costs) are rising. [no section below].
PayPoint (LON:PAY) - up 3% to 558.9p (£406m) - Trading Update (in line) - Graham - GREEN
This provider of services to convenience stores and their customers gives an “in line” update. I’m enthused to read about their plans for the businesses acquired with Appreciate (“Love2shop” and Park). I view this as a quality fintech stock but it’s valued very cheaply.
Hilton Food (LON:HFG) - unch at 678p (£609m) - Interim Results (in line) - Paul - AMBER/RED
Quick comment - I’ve had a skim of today's interim results, and see nothing of interest here. In fact I’m struggling to understand why the market cap is anywhere near this level? Very low margin food producer, and finance costs have almost doubled, and now consumes about two-thirds of operating profits. Only £27m aPBT in H1, on £2.1bn revenues. Net debt of £217m is a lot, and given very small profits, I’m a bit concerned about this level of debt, and the cost of it. Paul’s opinion - the only bull case I can think up, is if investors believe margins can be strongly rebuilt. On over £4bn revenues, that could provide nice upside maybe? Outlook comments sound reassuring, with confidence in expectations for FY 12/2023. But why get involved, when we have so many other, better investing options?
Lords Trading (LON:LORD) - down 12% to 60.05p (£99m) - Interim Results (in line) - Graham - AMBER
These interim results contain a profit warning as macro conditions are unfavourable to this builders merchant/distributor. I note the fall in house prices announced this morning and see some sources of concern with this share. A cheap valuation may be fair in this case.
Polarean Imaging (LON:POLX) - down 21% to 11.5p (£25m) - Interim Results - Paul - RED
Quick comment - this has been a complete disaster unfortunately. I took a hit on it personally, buying when I thought it looked cheap, but ditching them at about 15p recently, as it just continuously fell, and confidence in the company seems to have completely collapsed. The cash runway is running out - this is the key sentence today -
The Company is funded until the end of Q2 2024, and the continued progress on the above initiatives will help support future financing at the appropriate time.
That’s now too soon for comfort, so it looks as if this share is now in a doom loop, a bit like we saw with Creo Medical (LON:CREO) earlier this year. There was a nice trade in that one, for a bounce, but only after it hit rock bottom with a discounted placing.
Paul’s opinion - it’s impossible to value Polarean shares right now. The tech sounds great, but with the clock now ticking re the next fundraise, in horrid market conditions, it’s unknowable what terms the next fundraise will be on. Whoever is putting in the next tranche of money can just name their terms. For that reason, I haven’t got any choice, this has to be RED I’m afraid, due to the big uncertainty over the next fundraise. I hope it works out OK for holders, but it’s just a gamble at this stage, with such high dilution risk.
Paul’s Section:
Restore (LON:RST)
205p (up 14% y’day) £281m - New CEO & big contract win - Paul - AMBER
New/old CEO - an interesting situation, announced 5 Sept, that a former CEO (2009-2019) has been reappointed as new CEO. They felt he was the best candidate, and will hit the ground running. It might be worth checking why he left. I see the share price took a big tumble in late 2018.
Significant contract win - this gave RST shares a 14% boost yesterday. This looks a decent contract win, providing digital services to HMRC. Up to £140m, over 5-7 years, starting this month. We don’t know what the profit margin is of course, and as yet I cannot find any broker forecast changes.
Paul’s opinion - I’m pleased to say we spotted the value, and timed it perfectly too (you see, we do get some things right occasionally!), in the SCVR here on 16 Aug suggesting that RST could be good for a bounce trade at 125p, based on a reassuring trading update that came at the end of a horrendous drop in share price. In 3 weeks, it’s risen 64%, demonstrating that there are some good opportunities out there right now, if we spot good or reassuring news from a share that’s been in freefall, such as this.
Personally I banked my profits at something like 160-170p from memory, but well done to anyone who is still holding.
If we spot any similar situations, you’ll be the first to know here!
I’ll move down from amber/green, to just amber, to reflect that the share price has shot up a lot recently, and there’s still some way to go to turn around this group. Although there’s also an argument for just running with the bull run, now that it’s looking established. Your money, your choice!
Currys (LON:CURY)
49p (pre market) £554m - AGM Trading Statement - Paul - RED
Trading update for 17 weeks ended 26 August 2023
Nothing much to say here, as the first bullet points says -
All guidance for the year remains unchanged
Interestingly, it says revenue trends in July & August improved from May & June.
Its largest market, UK & Ireland saw revenues down 2% for the first 17 weeks - so not a good performance I’d say, given that many costs (especially staff and energy) will probably be a good bit higher.
Paul’s opinion - see our archive for my previous comments on the balance sheet, which is absolutely horrendous. The whole business is financed by credit from suppliers, on a huge scale. So if confidence were to diminish, and suppliers (and trade credit insurers) start demanding cash up-front, then CURY would be bust.
So don’t let the low PER fool you. It’s cheap for a reason - because the finances are precarious.
Divis were cancelled in July, and it can’t afford to safely pay any divis for the foreseeable future, in my opinion. Hence I would ignore the forecast yield of c.4.2%.
That said, given how we’re constantly hearing about gloomy macro, today’s update that there’s no change to guidance might reassure some investors.
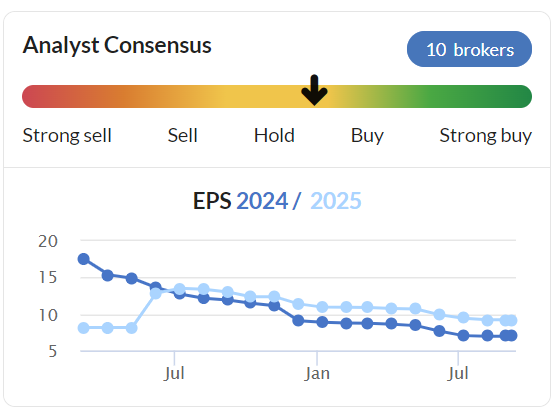
Also, look at how much, and frequently, expectations have been reduced -
Since I perceive balance sheet risk to be very high, I’ve got to continue viewing CURY negatively. Why take the risk, especially when consumer spending is under pressure? So it’s a RED opinion from me.
As always, I’ve no idea what the share price is likely to do, because many investors ignore balance sheet risk. That actually worked quite well when interest rates were zero, but it’s a completely different scenario now that debt is more expensive and macro conditions are tough. So high risk balance sheets are just best avoided in my opinion.
Directa Plus (LON:DCTA)
Up 29% to 56p (£37m) - Contract win - Paul - RED
This is a new one for me. Jack looked at it over 2 years ago, noting it was loss-making and speculative. That remains the case today. It came up on the top % risers list this morning, so I’ve had a quick look.
DCTA supplies patented graphene-based products for consumer & industrial use. The contract today is 5.5m Euros over 3 years, with potential to rise to 8.0 Euros. That’s nice, but nothing is said about the profitability of the contract. Since rising revenues in the past have not budged the annual 3-5m Euro losses, then I’d need more information about contract-level profitability, or at least a high gross margin to indicate it would be able to move into profit as contracts build.
Looking at the 2022 accounts, it’s not entirely clear what the gross margin is, but I see revenue is roughly equal to raw materials and staff costs put together, suggesting a not very good (if any) gross margin. Which raises the question, are they just busy fools, supplying products at or below cost?
It says the contract today was won in a public tender, suggesting that what it does is not unique.
More red meat is thrown to the bulls with an indication that the company is targeting a “new significant application” for its technology. Exciting!
Cash - nothing is said today, but I’ve checked the 2022 accounts, and it’s burning through cash at quite a rapid rate, and it seems obvious to me that another placing is likely to be necessary in the not-too-distant future.
Paul’s opinion - on the quickest of reviews, I can see that DCTA has exciting-sounding products, but I can’t see any evidence it’s commercially viable at this stage. Put that together with a clear need for more cash, probably in early 2024, and I wouldn’t be interested in speculating on this share myself.
The very concentrated shareholder base is another reason to steer clear in my view.
Bull market froth has mostly gone, but the market cap certainly isn't cheap, even now.
Note the Altman Z-score is flashing for potential insolvency risk.
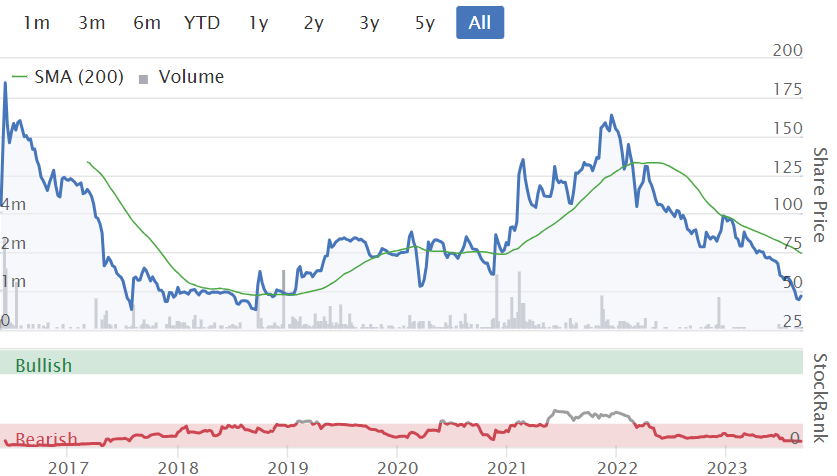
The Z-score can be a clumsy tool, but it's statistically proven over the long term, so ignoring it is foolish - especially when funding is much harder to come by, in a bear market -
Graham’s Section:
PayPoint (LON:PAY)
Share price: 558.9p (+3%)
Market cap: £406m
This share has crept up by 22% since Paul last covered it in July.
Six-month chart:

Full-year results, published at the end of July, showed revenues up nearly 12% to £129m and underlying PBT up almost 6% to £50.8m.
The takeover of Appreciate (another financial stock we used to cover in this report) completed only at the end of February, so those results hardly included any contribution from that deal.
Today brings a trading update for the new financial year: FY March 2024.
The key message is in the opening paragraph:
The Group has continued the positive momentum outlined in the Q1 FY24 trading update issued on 28 July 2023 and has made further progress in the execution of its strategic objectives across all four business divisions, giving the Board confidence in delivering further progress in the year and meeting expectations.
Shopping - I’m very interested to see mention of Appreciate’s gift cards, Love2Shop:
…a number of new proposition initiatives are now underway, including the rollout of physical Love2shop gift cards into circa 2,600 multiple retailers stores ahead of Christmas 2023, followed by the second phase of the rollout into our independent retailer estate in 2024.
Overall, the Shopping division has seen “a strong sales performance” with growth in their point of sale platform (“PayPoint One”) and new campaigns carried out for huge brands by “PayPoint Engage”.
E-commerce - “excellent volume growth” at Collect+.
Payments & Banking - two new bank clients go live this month (“Neo Banks”, i.e. online payment apps). Deposits and withdrawals for their customers will be available throughout the Paypoint retail network.
Further Appreciate update: 500 retailers have been recruited as “PayPoint Park Super Agents” to help people save for their Christmas shopping. This is the old Christmas savings product - it’s nice to see that the Park name lives on! And PayPoint is working hard to reinvigorate it:
…there are a number of initiatives in progress to open up further channels for Park Christmas Savings, with further details to be shared at our interim results in November.
PayPoint’s new Northern Hub is in Liverpool (Appreciate/Park’s home city).
New CFO - PayPoint has a new CFO. The retiring CFO gave over six years of service.
Graham’s view
I’m a long-term fan of this business so it’s hard for me to be anything other than positive on it.
The StockReport doesn’t provide much counter evidence with a StockRank of 98.
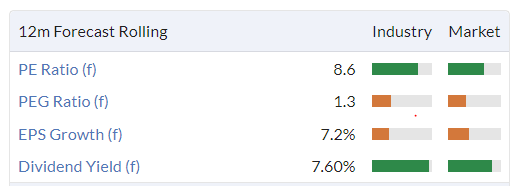
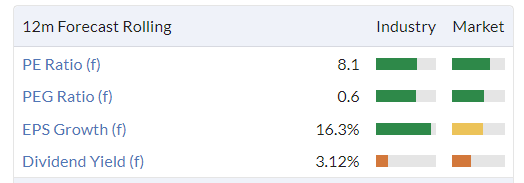
Valuation remains modest, with a chunky yield:
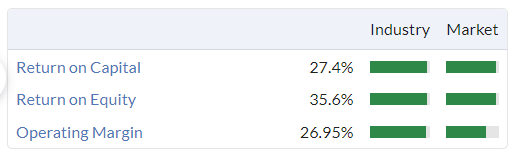
Quality metrics tend to be excellent, with amazing cash generation and margins:
What’s the catch, I hear you ask? In my view, the market simply views it as boring - a legacy business, without much growth prospects.
But when you look into its individual parts, I think you find that it’s not a business that’s sitting still.
It’s true that some activities - especially bill payments in cash - are likely to be in secular decline, as the unbanked population gradually declines. It is estimated that the unbanked population fell from 1.3 million in 2017 to 1.1 million in 2021.
But there are so many other parts to PayPoint, and it generates enough cash to reinvest in new, adjacent opportunities - Collect+ and Appreciate being prime examples of this.
I’m afraid I can’t provide much of a bear case on this stock, because I’ve been a believer in it for too long!
Lords Trading (LON:LORD)
Share price: 60.05p (-12%)
Market cap: £99m
Lords (AIM:LORD), a leading distributor of building materials in the UK, today announces its unaudited Interim Results for the six months ended 30 June 2023 ('H1 2023' or the 'Period').
These shares have taken a turn for the worse this morning, on the back of this profit warning.
But first, here are the H1 highlights:
Revenues of £223m are down 4.4% like-for-like, or up 3.9% in total.
Operating profit of £8.1m, up 11.6%.
Unchanged interim dividend of 0.67p.
It appears that the company’s key financial performance indicator is its adjusted EBITDA margin:
The Board remains confident of delivering our strategic targets of £500 million revenue by 2024 and improving EBITDA margins to 7.5% in the medium term.
In isolation, I view revenue and EBITDA targets as problematic - because they can signal that the company is willing to sacrifice its quality metrics in exchange for scale.
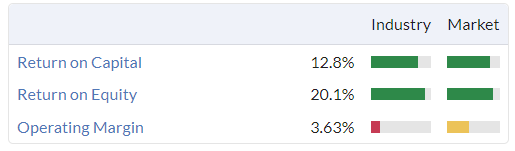
As a builders merchant/distributor, Lords has low profit margins but its return metrics have otherwise been quite good in recent years:
Let’s quickly review how Lords did in H1:
Merchanting is said to be “robust” but like-for-like sales were down 5.1%.
Plumbing and Heating is “solid”, down 3.8% like-for-like.
Two acquisitions (one of them was announced only last week, a small one mentioned by Paul here). “ Management remains focused on further opportunities that are complementary to Lords' strategy of product range and geographic expansion.”
Current trading/outlook
They believe they are outperforming the market, based on construction industry forecasts for double-digit declines in housing spending this year. But:
Since our last market update, persistent high levels of inflation, increasing interest rates and weaker consumer confidence have continued to reduce demand in the Group's key end markets of private repairs, maintenance and improvements (RMI) and new build housing, and consequently demand for the Group's products.
Given the continuing challenging backdrop, the Board now anticipates that demand will remain at current levels throughout the remainder of H2 2023. Accordingly, the Board expects the Group to deliver full year revenues of approximately 450 (LON:450) million and Adjusted EBITDA of approximately £27 million.
The previous forecast from Cenkos was for Revenues of £476m and adj. EBITDA of £31m.
With a cut to adj. EBITDA of c. 15%, we can see why the shares are down by a similar amount.
Net debt increases from £19m to £38m over six months. Additional working capital was needed due to “historical industry wide boiler supply issues”, but this is expected to unwind.
Here’s an excerpt from the CEO comment, talking about the medium-term strategy:
We have a substantial opportunity to grow the Group's current < 1% market share through attracting new customers, a greater share of existing customer wallet, product range extension, new geographies, digital capability and value added acquisitions. Our focus on the essential and resilient 'Repair' sector of RMI positions us more defensively during periods of volatility
Graham’s view
This one is also “cheap”, but perhaps for good reasons in this case?
This morning brought news that house prices have fallen by the most since 2009, according to the Halifax Index. It’s a 4.6% fall year-on-year, with a noteworthy 1.9% drop in August alone.
Of course it’s possible that interest rates will fall again soon, but does that mean we can expect house price movements to turn positive again? I don’t think so. We already knew that transaction numbers had stalled. We know that bank lending to first-time-buyers has collapsed. Perhaps sellers need to capitulate, and development needs to stall, before prices can stabilise?
Lords might offer decent value here but I would personally feel too uncertain about the macro backdrop to want to get involved here.
Other factors that make me wary: it’s a 2021 IPO, it operates in an extremely competitive market with low margins, and it uses KPIs (revenues/EBITDA) which I find to be problematic.
So this one is not for me. But I’ll maintain a neutral stance at this valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

108 comments
Why is SYNTH a superstock?
Nice £100k buy from the chair at Eurocell (LON:ECEL) - Nice to see
http://newsfile.refinitiv.com/...
I’m a very happy long-standing customer of our local independent vets…or at least our 2 dogs are…& I’ve never felt they’ve tried to do anything other than provide the best care at an appropriate price. Instinctively it feels a sector where it’s possibly inappropriate to have a corporate provider trying to intervene to set the tariff/approach but the numbers don’t indicate price gouging…in fact they look flat out average for CVS (LON:CVSG)
Shortage of vets seems more a question for the profession itself…as much like the GMC it seems keen to restrict the number of places at veterinary schools…& that inevitably has consequences
Shortage of vets seems more a question for the profession itself…as much like the GMC it seems keen to restrict the number of places at veterinary schools…& that inevitably has consequences
Sort of. Succesive governments saw no need to deal with this because there was an infinite supply of medics and vets from poorer regions of the EU to cover any shortfall.
Now that that supply has not just stopped, but reversed, it rather exposes the lack of any planning in this area. The issue of trade unions blocking expansion of training has only now become a problem, but even when addressed it'll take a decade or more to increase the supply of trained vets.
Of course, vets getting pay rises doesn't help the practices themselves - CVS have very average numbers, and giving more to their employees isn't going to improve their returns. But that'll get passed onto their clients, or practices will shut.
timarr
CVS (LON:CVSG)
CMA is to investigate over-charging by vets, and how the market has consolidated with corporates gaining market share and driving up prices unreasonably. Long overdue I’d say, this sector is a disgrace in my opinion, in the way some vets exploit owners’ love for their animals through outrageously high charges. An example of capitalism working badly I’d say, so let’s hope the CMA gouges the gougers! I won’t be bottom-fishing here, at any price. Note that CVSG doesn’t have any balance sheet support either, with NTAV last reported around zero. I'd be worried about shorters getting involved.
I do not currently hold but I will be soon.
Paul, I am a retired veterinary surgeon and have to say that your comments above are unnecessarily inflammatory, ill informed and in my view ill advised, and as an avid reader of your reports this is particularly distressing.
I am going to avoid going into rant mode and instead attempt to describe the situation as I see it at the moment .
1. I ran my business on an 18% profit margin (but this included mine and my codirectors notional salaries) which I do not feel excessive. When I subsequently went into a national role with the corporate we sold to, I found that virtually without exception every colleague I came across resisted fee rises, even when their sites were running at a loss with all adamant that they had the fees right. We surprisingly found very poor correlation between average transaction value and the local demographic. We also found a large number of vets with poor fee compliance, giving away free consults or undercharging for their work. The corporates have addressed this. The choice is stark, either charge properly or the site shuts. This has resulted in atvs going up and I am sure that there will be some clients that don't like it.
2. To put the manpower situation into relief, I used to employ 15 vets. The last time I spoke to the clinic director of my ex-practice, they were down to 6 vets. As this is over 6 sites, this is a challenge as the public expect a 6 day a week service. Salaries have rocketed to recruit and retain. What has caused this.. well a fair number have left the profession in exasperation at comments like yours, or because they have eye watering student debt, or because they can earn more doing something else, or because they are fed up with the long weeks, or because there is now no route to practice ownership because the corporates have hoovered up most of the practices, or because a huge number went back to Europe with that gift that keeps on giving, Brexshit. It is improving now, but as with the GP crisis there is a 10 year ish lag between wanting to increase the number of vet school places and churning out a good coal face competent vet.
3. Most practices I came across ran at a similar profit margin. We had funded our expansion with borrowing. Had I been in ownership still now, what with the manpower situation, the energy cost thing and the borrowing cost thing, I would think our fees would have gone up at least 25%.
4. Beyond that, as with human medicine, progress is relentless in terms of breadth and depth of service, tech advances and the like and upward pressure on fees is therefore inevitable. Overlaying this there is always the temptation to compare apples and pears. Even the most basic thing for example hospitalisation overnight can range from a practice checking an inpatient every 4 hours or every 15 minutes.
there will always be a few bad apples, but the number is tiny Paul. Most I came across were trying their best.
Your comment about NTAV is also poor. The reality is that CVS is made up of many local practices that throw off good cash, where the physical assets have been written down but are still there and still chugging away, beyond that the value is in the teams. Give me that any day over some of the dross that gets a thumbs up on here. I could mention Unbound (LON:UBG).
I expect better from you. If I want to read tittle tattle I'll read the daily mail.
I am sure Bog Dog ran an explemplary veterinary practice, but I am afraid I agree with Pauls comments. We run an upland farm, a riding school with 20 horses and a livery yard and have worked with our local vets for over 30 years. We are based in a national park in a very remote part of the UK meaning there is only one veterinary practice; not surprising, given the small size of the market. The practice was sold to a listed corporate chain a few years ago and that is when the fees starting going through the roof. Many farmers around here will shoot an animal rather than call the vet out because they just cannot afford the fees.
The other problem is undoubtedly staffing. The practice is 75% large animal and 25% small animal, yet despite the physically demanding nature of large animal work, out of 12 vets, only one is a man. The rest are ladies and I am told by the clinical director that 80% of veterinary students are women. The practice struggles to hold female staff in what is a predominantly large animal practice - they all want to work with small animals in more congenial surroundings and for better pay. I was very surprised to learn how little a veterinary surgeon is paid. I also know what stress a lot of vets are under as we had one young vet take her own life not so long ago, so I don't want this to sound like a rant. Neither do I want this to sound like an attack on our local practice who we have used for over 30 years and where many friends, including the clinical director, work.
Many of us in the farming community think the core problem is that veterinary medicine is ill suited to corporate ownership and we welcome the intervention of the competition authorities. Hopefully we will see an equitable outcome.
Improving liquidity ? Colefax , Titon
Not sure if anyone else has noticed but seems to be sone improving liquidity in small caps .
For example CFX Colefax which is usually very thinly traded can buy and sell over 20k worth both sides which is unusual .
Last week I cleared a big position on Titon holdings which was picked up by Rockwood .
Not sure taking examples is best practice but I’ve sold down a lot of holdings in past 2 weeks in others that have in the past year have had virtually no liquidity .
So I think that we are starting to see some progress which should filter through .
Also a few of mine bouncing near their highs showing some similar strength
Equals - trying to break pound barrier
Hargreaves - getting up to it’s 480 ceiling
Georgia capital - getting to £10 barrier
Mmmmm, not sure which way to call it I only sold down because I needed the cash for other projects, and ultimately to quote Warren buffer yet again
“The best investment you can make is yourself “
I’m supposed to be retired but I must admit I think a broad portfolio investment is pretty much doomed to sideways movement at best for at least 12 months so think my strategy is a very concentrated one
- reduced breadth of shares with maximum holdings (8) to give a concentrated portfolio of companies im very comfortable with (vertu , avingtrans , equals , Hargreaves , SDG / Colefax , Bloomsbury , Georgia capital , Filtronic (1/2) , Holders (experimental ) , Trifast (half)
- freed up cash to invest privately “backing myself” projects
Just ramblings really and talking out loud .
planetX
"Not sure if anyone else has noticed but seems to be some improving liquidity in small caps."
September should in theory have better liquidity than August (where this year liquidity seemed particularly poor0 - but not sure I see what you are seeing. I think it is very much hit and miss and depends which stocks you are talking about.
Colefax (LON:CFX) has the tender offer soon, which should help liquidity.
Titon Holdings (LON:TON) has had a buyer (Christopher Mills) for a while. I had held Titon for quite a few years and been looking to sell for the last 12 months at least. in June 2023, I suddenly managed to sell all my position. I am glad I am out of that - but the situation could get quite interesting as Harwood is now in a position to challenge the family whose holding is split up among a few members and I am not too sure how united the family is (not that I have any special insight). But I would be surprised if the management (or not) of the Korean situation has not caused a heated word or two.
In July I sold out of Brave Bison (LON:BBSN) I lot lot easier than I thought - as I buyer seemed to turn up just when I was looking to sell (as I was getting nervous about the advertising market - so far price has held up well). I had been trying to sell Trellus Health (LON:TRLS) since April - I got some off in April (worried about the length of the cash runway) but had to wait until early August until I could offload the rest.
I have a couple of other illiquid nano caps that I am trying to sell - but have found those even harder going.
Maybe use as sign of a trend is bad idea .
Titon - it was probably me that bought your shares and I’ve just sold to Harwood !
Harwood / Rockwood are viewing Titon as a 3 year turnaround and until they have the firepower to push through the changes they are at the mercy of the family members who clearly can’t run the company for shareholder benefit .
I am pretty certain Titon are going to earn on profits again so it’s going to go sideways / down for the next 12 months . If I had the same timescale as Harwood I would happily have held but I decided to bullet Titon and even made a few % in the process .
Colefax I think is very good , really don’t understand the discounted tender offer other than a group of well paid pensioner directors taking a slug of cash off the table without upsetting the market .
If add my SDG to Colefax the holding felt too high so I binned out sone Colefax today .
I sold today at 725
The tender offer is at 700 or maybe lower
So if I can sell 15% of my holding at 725 in the market why would you tender 15% at 700 ?
I may have missed something here ?
Anyway Colefax is a good hold bit the directors and overpaid past it pensioners with no ambition or plan . But it’s an ok one for my portfolio as it’s a sleep at night share
I also bought Colefax right at the lows so at 725 that’s a good 15%short term bump
Have to admit nothing is really rocking my boat in the market at the moment and think whilst there are bargains that will rise there are a lot of booby traps with companies going to have profit warnings and big drops .
Sone retail sectors are horrible right now and companies are going to have to report this .
Certainly online retail is super hard and the glory years are well behind us .
Good Morning Planetx
When you say Hargreaves ceiling of £4.80, just curious to know where that figure came from - is that your target price? I have held for 3 years and I reckon NTAV per share is around £6.50 and in April 22 the SP hit £6, albeit briefly.
PayPoint (LON:PAY) Thanks Graham for the review, and other contributor comments below also. What I like about Paypoint [I hold] as a business is that it's embedded in lots of other retailers' businesses. It provides services hard to replicate that it's retail client partners can't do, or don't want to do, or can't do as well as Paypoint does, so the business keeps doing what it does, adds value to it's B2B partners and they in turn are happy to let it continue while they focus on the mainstay of their own business. ME International (LON:MEGP) [I also hold] is not dissimilar in that regard.
If we were talking bear points then long term Paypoint in some areas is trying to hold back the tides of change, (thinking cash, savings clubs and that sort of thing), but conversely Collect+ is right on message serving a cashless society. I'd also say that there are a lot of parts to Paypoint and that investors have to buy into that and any upside or downside that might be perceived.
Hello all,
Silly comment but is anyone else just sick of this market now?!
My first experience of a bear market. I keep reminding myself this is a good time to prepare for the next bull market, but on days like this when your portfolio is mainly red its tough.
Around break even last couple of years so maybe doing better than I think. My own worst critic!
AIM100 has done very poor this year - down nearly 12% YTD.
FTSE250 is down YTD slightly, and FTSE100 is just about break-even it looks like.
I think it helps to focus on beating your chosen benchmark, rather than trying to ensure every year or time period is positive return on an absolute basis.
My argument goes this way
Yes - seeing red is no fun. But I console myself that I am usually less red than the index, and so when the bull markets come, I will be greener than green (having lost less in the bear markets and therefore have more capital to deploy in the bull markets).
This is, of course, if you have conviction you can beat the market by being an active stockpicker. If you don't have this conviction - it might be more sensible to go passive via Funds or ETF, and use that time saved for other enjoyments.
I feel your pain!
Often I ponder whether the mood might be different for those adding cash to invest vs. Investors working with/ recycling a lump sum. While being an investor might not have felt great in recent memory, if you are occasionally or regularly adding cash to your holding then this year might be looked back on as a positive period depending on when and how the cash is deployed.
Planetx Dental Services and Funeral Homes spring to mind as similar models.
Vets
Fully agree on the way corporate vampires are ripping off pet owners.
It’s a non competitive market that self serves and protects and detests competition .
Example metacam, every single time I go to the vets this is prescribed and sold to me at 70 quid a large bottle .
It is online at 25 quid for same size but you need a prescription .
So I ask the vet “how come yours is 70 quid but online it’s 25”
To be greeted with the ludicrous “we don’t make much money on prescribing and we can’t buy it for 25”
I said I’ve got an idea - ”you buy it for 25 online and sell it to me for 35, then we are both winners and I’m happy for you to have a margin of circa 30% for prescribed drugs . Especially as o have paid just paid 3500 pounds for a cruciate operation I don’t think it is fair practice to prescribe drugs at a premium on top of charging for a service “
Total rip off but they have it all sown up , long overdue regulatory change.
You can spot the rip off areas in the UK by the number of private equity owners such as care homes / vets .
It is a business now not a vocation and pet owners and regulatory bodies should be pushing back.
Agree, our dog is on Keppra Levetiracetam, we used to pay £100 for 100ml bottle from the vets, I get it non branded from Animed now for £20 for 300ml. Still have to pay the vet £17 to write the prescription, £17 for literally a piece of paper and 2 minutes typing.
Animed is part of CVS (LON:CVSG) btw.
Please see Liberum's look at some of the pricing of corporates vs independents. This was done across a very small sample size and with limited services analysed. It should perhaps therefore not be extrapolated. However, CVS, at least, found itself at the lower end of corporate pricing - 10% more expensive than the independents.
Obviously, the CMA investigation creates uncertainty; however, labour costs remain the main cost base. There has been a significant shortage of vets and nursing staff which has led to significant wage inflation.
I can understand why the industry is coming under review; however, I don't feel that CVS Group deserves the current share price reaction.
The cost to make a number of the drugs is pennies and the cost of a Vaet trip is now ludicrous.
Recently my dog vomited multiple times to the point the Vet said they should see her.
Of course by the time I got there she was perking up a little and I wondered whether it was really needed.
The Vet recommended an injection to stop her committing that is effective for 24 hours. Cost £60 on top of £100 appointment charge. He also wanted to do a blood test to check liver/pancreas etc. they charged £25 to administer the test as well as £200 for the test itself.
Total cost to me for that afternoon was a ridiculous £386!!!! Now it’s just as well I can afford that but imagine if you couldn’t and were faced with that rec from the Vet!
Anyway 10 days later I haven’t had any test results and my dog is back to her normal self. It is clear that Vet practices have become rip offs to me. Milk the consumer and/or insurers to an extent you aren’t allowed to do with human treatments. It’s no wonder pet insurance has almost doubled in last few years!
About time someone took action on it
I don't even have a dog. Our local set of vet practises were privately owned for many years and even featured on a BBC series about a vet practice starring Rolf Harris (can't remember the name of the programme). During Covid the set of vet practices has been taken over by Medivet. All the staff have changed and even our closest surgery seems less accessible for appointments. Whenever I take our rabbit in such as for eye drops, annual vaccination etc it is working out at around £100 per visit! Before being taken over I remember it being around £60. The rabbit only cost about £25.
I know a few friends have left the practice and gone elsewhere, however they have cats and dogs. If I had a long life, perceived expensive animal then I probably would too. However for a rabbit who may only have 2-3 years left I'm less keen to make the move. My fault I know and probably more expensive as a result.
We have strayed off investment and into a political discussion about vets here, so I will add a comment that it takes 7 years to qualify as a vet, the clinicians have to understand vastly more than human doctors because the anatomy and metabolism of a reptile or a bird is not the same as a mammal, and a lot of entrants are enticed by the "All Creatures Great and Small" myth but find themselves working in a corporate culture in unappealing premises in urban locations. Imagine working hard at school, and then at vetinary college, and then ending up in a Pets at Home clinic on a mezzanine in a shed on a retail estate, dealing with pet owners who blame you for charging what head office has told you to charge.
But it’s not really the labour and qualified status of a Vet that’s driving the problem price increases is it!
The problem is that each shot a pet gets costs pennies to make but is priced at £60-100 and then the proliferation of private vet practices that are not owned the vets you speak of but by private equity seeking to maximise returns.
Thus a Vet can get paid a very good salary commensurate of their training and total prices could still be much much lower. The key point being that the shortage of vets and their labour isn’t what’s driving the prices. It’s pure gouging.
Consumers are at a significant disadvantage when it comes to pet health as we have little reference point (ie not something we have experience of at a personal level being humans) and therefore are massively more susceptible to inflated pricing.
Margins are eye watering because private equity and diet drug companies have worked out demand is very inelastic but pets are treated like family. It’s a bonanza and nothing to do with vets themselves.
I'm sorry Michael, with respect that is utter tosh. Vets do not have to "understand vastly more than human doctors" although if you are suggesting that vets need to have a wider (but inevitably less in-depth) knowledge then perhaps you're correct. Medical doctors need to have a far deeper understanding of a human as both a person and object than any vet needs to have of a dog or lizard! And that's without considering the psychological & psychiatric element.
To become a fully qualified physician or surgeon takes at least 15 years - and that's working all hours of the day. To become a GP takes less time, around 12 years.
Veterinary medicine & surgery is very basic compared to modern human medicine & surgery and what can be achieved.
And a veterinary degree is 5 years (150 weeks) or 4 years for a postgrad. The basic medical degree is 5 years (192 weeks in total).
Maths make no sense whatsoever
My vet is awesome, can't praise her enough. She was the one who suggested I buy the dogs drugs elsewhere to save money once our insurance hit it's limit.
When you have a long term health issue with a pet a good vet is a godsend.
Ref Vets a hobby horse of mine, some brilliant others useless. - birds the average Vet does 1 hour's training in all those years! Those who want to specialize need to train on under a specialist avian Vet. I had shares in CVS many years ago until I saw the mistakes made on 2 horses I had in training = I moved immediately to real experts in their field and sold my shares
Ask the vet for a prescription, a couple of years ago I paid about 15 quid a time, then buy online and save a fortune.
planetx, just as an aside and hearing that you (presumably your dog) has just had a cruciate operation I can fully recommend canine hydrotherapy for the inevitable arthritis that comes with their old age, we just lost our 15 1/2 yr old Goldie recently as she eventually succumbed to a combination of degenerative myelopathy and arthritis but she had been doing weekly hydrotherapy sessions for around 2 years and in my opinion it gave her an extra year as well as the weekly swim which she loved. Both sisters had cruciate operations around the same time at about 9 yrs old (we lost the other sister in different circumstances at 13) and cost £2500 each and our vet did a fantastic job with both ops. Hope it helps and I know what you mean about the metacam it's a disgraceful price
Nice update on PayPoint (LON:PAY) , thanks Graham I share your enthusiasm. This is my second largest position now.
As for Polarean Imaging (LON:POLX) I hold and I can personally see it going to zero now, they have cash till Q2 2024. I somehow managed to end up 80% down on that one. It's a shame as the tech really is groundbreaking. It seems the management are more interested in lining their pockets and don't really have a commercial plan.
So do I sell and take £500 out and write of £2.6k, decisions decisions.
May as well keep it in, just in case..
New Invester in your position I'd sell the Polarean Imaging (LON:POLX) and treat yourself to a decent weekend away. Remove the negative from your portfolio and your life and let PayPoint (LON:PAY) keep looking after you. Too easy to hold these losing shares for too long and then feeling you may as well hold them to the death. Sadly I've done that too often. It feels so much better when you let them go. Naked Trader's book is worth a read on issues like this, IMO.
You are probably right Seven, I read Naked trader, that's why I'm here funnily enough, I never learn!
I just read Paul's update, pretty much what I made of it so maybe I am learning a bit! :)
Read this - really, I mean it: https://www.amazon.co.uk/Art-E... It's quite short, to the point, and you will almost certainly agree with everything in it. After you have read it you will wonder why on earth you haven't been investing according to these principles in the past.
and talking of Naked Trader Robbie Burns he hasn't done a blog for a few weeks now and normally sticks a date on his blog if the update isn't timely, I've been tempted to ask if he's ok (probably gone for an impromptu holiday) but if he doesn't submit a blog tonight I'll definitely be asking him of he's ok. He's a good lad and yeah his books are a great read and have really helped me.
Thanks threeputt I try and be a good lad (but I was quite naughty this morning). The website has just been updated (nakedtrader.co.uk) but really sorry to those of you on the mailing list, the company we use says email sendings are "delayed" but hope the mail will be with you all soon. ps. those of you with level 2 see the 450,000 buy order on Knights Group at 85p! My order is just above for 5,000 shares at 85.4. Be interesting to see if the big buy order re-appears tomorrow.
Classic .... lol
I second the recommendation of the Naked Trader's books. Particularly on the subject of stop losses. Sadly, I find it a hard discipline to adhere to and continue watching small daily losses add up to an 80% loss! There are just enough recoveries to make the decision to cut even harder!
Also badly stung to tune of 7k in sipp. Always fall into the same trsp on medical or biotech promising big things then running out of cash, if I'd leave these alone and stick to either good value investing or larger companies I'd do much better than the 'jam' tomorrow of these. We often find after some FDA approval or other similar positive noises they often fail to deliver for the original shareholders
I bought Polarean Imaging (LON:POLX) today on the dip. Hoping for a turnaround. That’s what makes a market! GLA!
Pittards (LON:PTD)
"Anyone holding this share here - I would hit the sell button & get out, as soon as you can".
Well said, Paul ( https://www.stockopedia.com/co... )
This leather company, founded in 1826, despite offshoring the tanning of leather used in its products to Ethiopia went into administration this week: https://www.bbc.co.uk/news/uk-...
Tradiing in shares was suspended at the beginning of July due to failure to publish 2022 results.
Hi sharw,
That's sad news, I'm really sorry to hear that Pittards (LON:PTD) has gone into administration. The writing was very clearly on the wall, but I was hoping it might be able to survive, as it employs lots of people. Let's hope it manages to find a buyer out of administration. Game over for shareholders though, I hope nobody here is impacted.
Regards, Paul.
MPAC (LON:MPAC) (I hold) have announced encouraging looking half year results to 30-6-23 today. However I am a little confused - it has reported three types of P&L; Statutory Profit, Underlying Profit and Basic Loss. Of these:
*Underlying results are stated before pension related credits of £0.3m (H1 2022: charges of £0.4m); amortisation of acquired intangible assets of £0.8m (H1 2022: £0.8m)..."
Removing pension adjustments looks sensible but why remove amortisation of acquired intangible assets? Are thy claiming those acquired intangibles will not lose value through time? I am not a fan of EBITDA but at least it states clearly what it is, to call any result a profit after removing the amortisation cost just looks wrong to me. Have I misunderstood what is happening?
I am bemused about the fall this morning. I anyone can shed light on this it would be much appreciated.
Judywil - I am bemused too - particularly on a FWD Stocko PE of 6.1 and a PEG rate of 0.2! I see Equity Development suggest a fair value of 485p against the current 188p! I think the answer may be that, with a market cap of around just £43M, the market treats any disappointment brutally, in common with most non dividend paying tiddlers. It does not generate the business volume to make it worthwhile doing a lot of analysis on the underlying fundamentals and perhaps, that is the opportunity. I certainly hope so because, in common with many small cap investors, that has been my core investing strategy for the last 40 years :-O
Having held the company for a while now I am as convinced as is possible currently that the business is sound, well run and has a great opportunity for growth. The recent addition of the FREYR business suggests there is a large potential new market to boost growth. If it can maintain current growth momentum it will have to be significantly re-rated soon enough, perhaps in line with ED's fair value of 485p.
From a different perspective (and apols for repeating a point made in an earlier post) it feels a lot like Equals (LON:EQLS) [I hold] which was hammered from Oct 18 (approx 145p) to Mar 20 (approx 24p) despite showing excellent quality growth KPIs during that period. The good underlying growth continued and dramatically improved the EPS and its rating. The share price has since improved from that 24p to 100p now, in a fairly straight line, with each 6 month report showing a gratifying (and confidence boosting) steady improvement in fundamentals.
Personally I am inclined to average down on MPAC (again!) but will wait until even the current market signals the price is low enough.
I share the confusion on (LON:MPAC) profit. However I topped up today on the outlook :
Order intake of £62.4m (2022: £32.8m) contributing to a closing order book of £77.5m (30 June 2022: £62.6m; 31 Dec 2022: £67.2m).
IMO we will see a bounce.
We have a great investor show lined up for Monday evening with Rosemary Banyard the very popular and successful fund manager as our guest speaker and two companies presenting plus more in the MelloBASH (Buy, avoid, sell or hold?) Do come and join us...
https://www.stockopedia.com/co...
Hi David
A polite suggestion, if I may? Were you to advertise which companies are in the BASH you might get more people attending? This, for me at least, is usually the most interesting/informative part of the show...Just a suggestion on what is otherwise a very enjoyable watch.
Many thanks
James
Jet2 (LON:JET2) I thought the shares offered excellent value when they traded around £12, which is when I made my initial purchase. I added a few more this morning in my wife's ISA. I had a small position in Lords Trading (LON:LORD) which I sold at a relatively small loss to do so.
Trading at Lords Trading (LON:LORD) continues to be challenging unsurprisingly, but for me it is more the issue of increasing net debt that has doubled to £38m and forthcoming deferred consideration, for example £4.1m is due to be paid by next July on the George Lines acquisition.
Conversely JJet2 (LON:JET2) is trading well and is cash rich.
Many thanks to Albertos , Tortoise Investor and Investingnewbie for their comments.
Golly! CVS (LON:CVSG) down 28% on no news today? Surely an error but also reflected on trading platforms such as AJB. Anyone know what’s going on?
https://www.bbc.co.uk/news/bus...
CVS (LON:CVSG) and Pets at Home (LON:PETS) both down significantly.
CMA review into vet pricing. Looks like an overreaction but CVS was looking especially toppy anyway.
I hold both :-(
timarr
Thank you so much Redice and timarr.
CVS has been an excellent investment for me over many years and something of a quality compounder so this feels like a bump in the road rather than a car crash, particularly since they have been driving overseas expansion opportunities of late.
Thanks for flagging the issue with CVS (LON:CVSG) (down 29%) and Pets at Home (LON:PETS) (down 11%), I was about to start googling to find out what's going on!
I'm really pleased the vets sector is to be investigated, as I think some of the corporate chains charge outrageous prices in the cynical knowledge that people adore our pets, so we just cough up. We've had some awful experiences with vets actually, they're mercenary, and jack up the prices once they know you've got insurance. (edited to tone it down a bit)
CVS (LON:CVSG)
I'm really pleased the vets sector is to be investigated, as I think some of the corporate chains are little better than thieves, charging outrageous prices in the cynical knowledge that people adore our pets, so we just cough up.
Totally true, but the review is unlikely to make much difference other than requiring more transparency around pricing. The main impact on CVS is that it may limit further expansion in the UK. They're now looking at expansion in Australia because they've already recognised they have limited opportunity to continue to grow in the UK.
The long-term trend is still positive for vets, because the wave of pets taken on during the pandemic are still young. As they age they'll need more treatments - and as part of the so-called "humanisation" of pets, they're increasingly treated as part of the family. Back in the day if Fido was a bit old and sick he'd be put down, now owners seem to be prepared to do everything they can to keep him going - which isn't always in the pet's interest of course.
But the market obviously views the threat to CVS seriously, as we can see by the price fall.
timarr
My experience is they ask whether you have insurance before advising of the cost, there being a higher price when the punter is insured.
The situation at CVS (LON:CVSG) and Pets at Home (LON:PETS) reminds me of Dignity which took a terrible tumble when it couldn't sustain high margins - this is what Ben Hobson said in a blog post about Dignity: 'So in reality, Dignity was what the analyst Pat Dorsey calls a ‘mistaken moat’. In The Little Book That Builds Wealth, he explains: “High returns will always be competed away eventually, and for most companies - and their investors - the regression is fast and painful… It’s easy to get caught up in fat profit margins and fast growth, but the duration of those fat profits is what really matters.”' https://www.stockopedia.com/co... I'd say that's one of the things which makes investment so difficult, far too difficult for me, and I have lost confidence in the investment approach. I am now a trader which seems to be going OK at the moment. FD: I have placed a buy order for CVS (LON:CVSG) at a price below that which applies at the time I am posting.
The situation at CVS (LON:CVSG) and Pets at Home (LON:PETS) reminds me of Dignity which took a terrible tumble when it couldn't sustain high margins
I think that's rather unfair. Dignity were raking in margins of nearly 50% at their peak, basically preying on people who weren't really able to shop around.
In contrast CVS (LON:CVSG) have margins under 10% and their customers aren't obliged to use their services. They operate about 10% of vet practices in the UK and nowhere do they have more than 25% of the market so it's not like there isn't choice if their customers are unhappy.
Of course, their overheads may be inflated, but on the face of it, it doesn't look like they're exploiting their customers. The largest driver of CVS's costs is vet wages, and we have a massive shortage of those in the UK, and a need for far more in future as we see the bow-wave of pandemic pets moving through the age range, and the need for more vets to handle post-Brexit border checks.
CVS looked expensive before this happened - it wasn't obvious why it was on such a high rating given the rather average growth metrics. However, it is hard to see how they won't keep on growing returns into the future, recession or no recession.
But part of the problem is that people just keep their pets going far longer than they used to. Just like people we can keep them alive for much longer, but the older they get the more expensive they get.
timarr
I have read your thoughts Paul and the subsequent views of others. I understand the from my standpoint largely emotive views expressed, and I should state that I am not nor have ever been a shareholder in either businesses mentioned.
However, what we all tend to forget when we assess health providers outside the NHS or equivalent for pets (there is none of course, which is the point!)is that the free at the point of supply feature of the NHS covers up any absolute cost information of actual service cost. We just take it for granted (apart from complaining bitterly about it all the time, and clapping during Covid). The nearest comparison is the cost of care homes of any quality which again many people regard as extortionate.
Is it not true that health care for us humans or our more loyal and caring non human companions is actually very expensive, extremely expensive. We only get a mere sniff of the cost through private health insurance costs, private prescription charges.
So many of us hide behind the often heard 'Ive paid for my healthcare all my life and so it is only fair to get that care now (in my old age, or in need of cancer or similar treatment / operations)'
Should I also add a lot of self inflicted diseases/conditions as a result of (relative) gluttony heavily dosed with unhealthy prepared food, drinks and snacks (versus third world countries), alcohol or tobacco or drug abuse (to name but a few).
I read with interest the unfair comparison with Dignity, and the seemingly not so high margins made by CVS and Pets at Home. Perhaps CVS has reduced competition too far, perhaps not. T
he fact is. and I repeat, that medical treatment is very, very costly to provide and we are still not paying medical staff enough for the service so many of us demand. If we were to receive an informational invoice for the cost of treatment which we undergo, we might appreciate it a little more. I say 'might' because I have so little faith in human nature in this respect.
Lots said about rip off vets my experience is the same as most. what I will also add is that the multiples set the price for the independents to follow and still be 10% cheaper
Pets at Home (LON:PETS) I own - not sure what all the fuss is about - having had a dog from 1989 - 2003 - I cant see prices have changed that much - I used to pay ~£60/yr for insurance which is about £150 in todays money and annual booster fee was about £30 which is about £75 today. They key for me is simple if people are happy to spend ~£2000 on a dog lets say then surely you can afford the costs that go with it.
I don't buy a Porsche then expect to pay Ford money to run it/service it.
Pets at Home (LON:PETS) I own - not sure what all the fuss is about
There are about 4,500 vet practices in the UK, about a third of them owned by corporates. Their job is to maximise revenue for their shareholders. The job of pet owners is to get the best treatment for their pets for the best price.
No one makes people use a particular practice for their pets, most of my friends have moved to local practices, where there's less of a hard sell and prices are a bit cheaper. But no one's saying prices are orders of magnitude less, and it seems to be the fact that they feel they're talking to someone who cares about their pet, rather than someone who's focused on making money, that matters.
Unless the CMA finds evidence of collusion among the chains its most likely remedy will be to demand clearer pricing so that people know what they're paying before treatment and to make it obvious which vet practices are parts of which chain.
I don't know really, sometimes capitalists are very contrarian.
timarr
Parallels with the funeral industry. Remember Dignity PLC?
Consolidation of small independant firms into a corporate structure, but each aquired businesss maintains the appearance of being independant. No wonder the CMA ended up investing!
In an MBA/business school way it all makes for a great idea but morally can leave a sour taste. Vets and funeral homes both serve people at a time of emotional vulnerability,
Ideally, as an investor you'd want a chair and board with some sort of wisdom and moral compass. (How often is that the case?). If nothing else that protects the investment from reputational risk and damage if the underlying business is caught out doing the 'wrong' thing.
My friend works in the funeral industry. He was with a local independent that got taken over by Dignity. They took over a lot of local firms but got so greedy that eventually new independents were able to undercut them and be viable. He now works for an independent that operates in a much better way, treating staff and customers ethically and well. He regularly visits care homes to collect bodies and notes how many of them show clear signs of significant dehyrdation and lack of care. That friend also grew up on a farm and notes how animals needed to earn their keep in the past. The farm cat or dog would be dispatched with a quick dose of medicine from the shotgun if they were no longer able to work. My friend has some views about Dignity, care homes, and vets which I will not repeat here.......
Interested to hear that WeWork is now in small cap territory at 85m us
From memory the peak was ~50billion
What amazes me is how long it took to fall rather than the magnitude of the fall.
Hi andrewdb,
That reminds me, I really enjoyed an audiobook about the boom & bust of WeWork, it's (rather harsh) title is "Billion Dollar Loser", by Reeves Wiedeman. A very entertaining listen, and it's astonishing how the charisma of WeWork's CEO fooled so many people, when the gaping flaws in the business model were so glaringly obvious! Always the way in tech booms isn't it, which we seem to now be having about every 20 years, with remarkable similarities in behaviour each time.
Regards, Paul.
Morning Paul, just read the figs for CRN, rather good with upgrades too. You had a look after I mentioned them a couple of months ago. The Irish financial situation seems one heck of a lot better than UK. As per UK need more houses, but Irish situation means the govt. are supporting new housing ,from strong financial situation. CRN seem to be well run, and in a strong position to take advantage . Stoko figs look good for next two years ,with growth,and income both meritous . Hope you have time to cover , with your accounting eye . Thanks Tony
Morning All,
I see Inspecs (LON:SPEC) is in the list today. Look forward to your views. FWIW the results appear solid if unspectacular (a win these days!) but with the SP well off the recent lows but miles below the unrealistic float highs, I'm seeiing some value here for the longer term if they can continue to deliver.
Now, on to the clustef*ck that is Synthomer (LON:SYNT) !
Agree Mark re Inspecs (LON:SPEC) - but its a cruel market out there - lucky the share price has only nudged down 1% today - Compare with Beazley (LON:BEZ) which has today plunged 7% for maintaining profits in a difficult market and the crazy over-reaction on the Vet companies today. Maybe I should take a holiday - with Jet2 (LON:JET2)
Hi Mark,
Sorry we didnt get round to looking at Inspecs (LON:SPEC) today.
Regards, Paul.
With apologies to Albertos who beat me to posting but I want to create a separate post just to spell out how good value the package holiday and airline company Jet2 (LON:JET2) looks. I also think worth a mention for the read across to other consumer stocks.
For balance, I have not found it to be recently transparent about its fuel hedging strategy so worth keeping an eye on that.
I hold and have topped up this morning. While the whole travel sector seems depressed in valuation, the valuation here with the large net cash particularly doesn't make sense to me.
As dad to two children under 5, we've abandoned organising our holidays independently and now book package trips only. We've used Jet2 (LON:JET2) five times now and I cannot fault them at all! The check in process is smooth and swift (night before drop off for morning flights and lots of staff on hand), friendly staff on flights, superb transfers and importantly, the hotels are 'as advertised'. The user experience on their website is second to none... and t & cs always clear so no sense that you're being taken advantage of. I hold and continue to buy. Currently, the price looks a bargain.
I agree with you on pretty much everything you have said and I hold for precisely the same reasons. A weakness as far as I can tell, is their reliance on Stansted in SE England. I would never again choose Ryanair/Easyjet/Wizz over Jet2.
We fly from Leeds Bradford (close to us) or Birmingham (close to maternal grandparents so no need to book hotel accommodation). I agree with you, mjfgs, about Stansted. It would need to be a substantial saving to consider using London's third airport.
Jet2 (LON:JET2) All good points on the bull case. I would add another important point - a lot of capacity has come out of the airline sector since the pandemic, with stretched balance sheets and supply bottlenecks. Analysts expect this to persist for couple of years. This in turn should support pricing (the airline sector has traditionally had too much capacity which has compressed margins). Jet2 should also benefit from some of the problems facing some of their peers.
Went for an interview once for Currys (LON:CURY) probably about 7 years ago in the finance department and came away very unimpressed with both the process and the management. Whilst they had a very nice share scheme given how things have panned out I was happy both them and I gave each other a wide berth. Thankfully I went to Amazon for a while and enjoyed their shares going from 400 to 3500 (before the split) and left there near the top.
A pleasing TU & AGM statement this morning from PayPoint (LON:PAY) prior to their AGM later today.
Things seem to be going well across all of their divisions and they are confident of at least meeting expectations.
One that I hold and with growing conviction - and offers a great dividend whilst we await the full turnaround.
After an 8 month wait the Curtis Banks (LON:CBP) SIPP provider deal with Nucleus Financial has finally been signed off by the PRA, the FCA, the SRA and the CMA. I invested after Harwood took a large stake. Not sure I've ever seen a UK small-cap company bid needing more regulatory approvals! Oh well, patience rewarded as it looked like it might not happen when the CMA referral was made. Common sense has prevailed. It is now expected to go unconditional a week before the long-stop date on 6 October with cash by 10 October. I hold. Was anyone else waiting for this to complete?
Yes, I've been patiently holding a position in my AIM portfolio that I run as an IHT planning vehicle. I bought on the view that CPB offered a reliable income stream as a low-growth, low-risk growth business, but with possible upside as a takeover candidate (not helpful from an IHT point of view I admit). So glad to be vindicated at last although the premium is very modest. Now face the problem of where to redeploy the cash in an unforgiving market.
At one stage, CBP was offered at around 300p so it would have been possible to take 10%-ish 'free' money assuming the deal went through. But I chickened out because of the long delay in getting regulatory approvalsand nervousness at the state of the market. C'est la vie!
Good morning Paul and Graham, I need to lay down again after reading Cairn's results today! I don't know where to start so I won't, it's all positive which for our portfolio is a first! Graham you gave it Green on the 5th July and we bought a starter position after reading mainly about the situation in Ireland which you'd picked up on. Note the extensive macroeconomic coverage after the results and weep for UK builders. We will add but if you get time today comments from you and Stockopedia subscribers would be appreciated.
MPAC (LON:MPAC) - just a reminder that we're hosting an investor presentation tomorrow at 11am with Mpac management following Interims published this morning - the registration link is here: https://www.equitydevelopment....
Might be considered too small but wanted to flag up Touchstar (LON:TST) who continue to make progress. Revenue up 25% and EPS up 65%. They have announced a small maiden dividend today and show having cash of around 30% of their market cap now. Trading sub 15 PE and less when cash is factored in. Very illiquid like most small caps
Morning Brookeda!
Thanks for flagging Touchstar (LON:TST) - we probably won't cover it today, as a little small (£9m mkt cap), but it's a share I've followed (and sometimes owned) for many years, and I see the shares seem to be in a decent up-trend, with positive newsflow.
Touchstar has always looked quite interesting, but never really achieved escape velocity in terms of revenues (usually in range £5-8m), and tiny profits each year.
I could certainly think of worse things to invest in, although the lack of liquidity could mean difficult to buy/sell in any size.
Can you see any catalyst for growth to accelerate? That's what I'd be looking for, to take a closer interest.
Probably won't have time to look at it today, as I have a hard stop around midday, to head into the city for lunch with a renowned fund manager, which I'm very much looking forward to!
Regards, Paul.
MPAC (LON:MPAC) - First half FY 23 results: orders continue to grow (new research report here: https://www.equitydevelopment....)
For the six months to 30 June 2023, Mpac Group reported revenue of £52.8m (+4%YoY) and a closing order book of £77.5m, compared to £67.2m at FY22 year end, with order intake of £62.4m (H1 22: £32.8m). The net debt position at December 2022 of £4.7m reverted to H1 net cash of £2.2m; we estimate c£2.5m net cash for the full year.
As the combination of order uptake cashflow progress demonstrates, the Group has re-established momentum; trading remains in line with management expectations. Reported H1 EPS was (2.2p)/share; on an adjusted basis 6.8p/share (H1 22: 3.6p).
Mpac reports progress on schedule in completing the Customer Qualification Plant (CQP) project for FREYR Battery in Norway, according to required specifications. Full commissioning is expected in H2.
At the January trading update, we raised our FY23 revenue outlook from £103.6m to £104.7m, and (adj.) EBITDA to £9.6m. After reviewing H1 performance, notably the strength of order inflow, we raise our FY 23 revenue outlook again to £106.6m (+2%). Our fair value for Mpac remains 485p/share, indicative of a FY24 EV/EBITDA multiple of 3.2x.
Excellent work Paul. Love this daily news, analysis and excellent podcasts. You are all essential! As you say, ‘Your choice.’ Exactly that.
Jet2 (LON:JET2)
Whilst not a small cap, a pleasing ahead of expectations AGM update today. The share price action recently has suggested the market expected the opposite.
http://newsfile.refinitiv.com/...
Does look like consumer spending on the annual holiday is holding up.
Since this share looks like a total valuation anomaly, I would be interested in others comments.
It seems cheap to me too, I can imagine that most peoples view would be that holiday spending is the first to be cut in tough times. I think also that the founder chairman is retiring soon, which may weigh slightly, although I think he is still involved in an advisory role. I hold - glad of the positive update.
Post pandemic, I think holidays are now a necessity, as opposed to a luxury. As an ex-teacher, the number of parents taking their children out of school for two weeks in the sun in her time was on the increase when I retired last year. The 'reason' was frequently cited as their childs' well-being. I suspect it was actually for the lower prices.
Synthomer (LON:SYNT) Poor half year results and a substantial rights issue announced, almost equal to current market cap, in order to reorganise the debt. Struggling to understand the right issue price, "6 New Ordinary Shares at 197 pence each for every 20 Existing Ordinary Shares" current share price 60p. Debt financed acquisition of Eastman looks terrible in hindsight. It might partly explain the share price drop in the last month but why raise money at the last moment when these issues have been know for a while.
So there is a share consolidation first of 1 in 20 before the rights issue. That's punchy. So rights issue is an 83.8 % discount to yesterdays closing price. Shambles
Couldn't agree with you more mickeyg14. It is a shambles and why raise the money now. Interestingly I work in the PE world and we have seen teasers for 4-5 different M&A processes for Synthomer businesses which will likely raise c.£250m. Clearly the bank wanted the cash sooner.
Just looking through the headlines of my various times I've dug into Synthomer (LON:SYNT) in the last year. Suffice to say, since Sep I was content to "sit and wait" for some signs of improvements, but....
Shocking that at various points (obviously with just information available at that point) I would have bought at 170p, 80p, and even 70p as late as just 6 months ago in Feb23. Luckily, the SP never got to those prices.
And I couldn't help but laugh at the newspaper quote from Oct22 from Berenberg analysts about their "shares could double" from 103p :) Must have read that on The Times when commuting, and added a note to update my investment doc on Synthomer.
Hi everyone,
This is piece I have written about HVivo, as a shareholder, but I would love to get some constructive thoughts on the below. I’m 24 years old and haven’t been investing for many years so still finding my feet in this space. I am also dyslexic, so if things don’t read very well please bear with me.
Many thanks
Olly
How is HVivo going to progress to the next level?
Hvivo is a really interesting stock in so many ways. I’m going to look into where they have come from, their situation today and where they are going. It is key player in the challenge trails and clinical services sector, niche part of the healthcare market. They are growing very well with contracted revenues for this year complete and have contracted 40% of 2024. However they haven’t been the easiest company to be a shareholder of. All of which will be explained later.
Hvivo is world leader in challenge trials, a significantly faster and more effective way of testing vaccines and anti viral drugs. Challenge trials are where volunteers are inoculated with a disease or virus to test the effectiveness of a particular drug or vaccine. Challenge trials can take the testing phase down from 2 years and 40,000 volunteers in the open world and all the complications that involved, to 6 weeks and under 100 volunteers. This was proven recently with the rapid testing of the Covid vaccines. More recent proof of this was shown earlier this year by SAB Biotherapeutics an American Bio-tech that has received fast track and break through therapy designations from the data collected in their phase 2 trial that was carried out by Hvivo. They are the answer to the worlds health care testing needs.
Today Hvivo is a fast growing cash rich company in a very interesting and profitable area of health care. They do not take any regulatory risks in developing drugs. They are simply a picks and shovels company suppling data and testing for those who are digging for gold. Hvivo is now running an end to end testing service for clients. From characterising the challenge agent to carrying out the trial, and then analysing the data. Offering this end to end service is what is setting them apart from their competition and is also what holds their high reputation. This year has been an impressive one for them with multiple large contract wins including 13.8 million to develop an Influenza B challenge trial, 6.8 million for RSV and 3.2 million Venn contract. All of these contracts plus others have led then to forecast another year of 20% growth, following the last 3 years prior. Hvivo is very well managed with Mo Khan the CEO with over 25 years of experience in healthcare. The chairman Cathil freil is the main man who oversaw the turning Hvivo into todays profitable business. The management are steady with cash and invest it well leading to it continued growth. Hvivo is well positioned going forward in terms of finances, sector headwinds or regulatory barriers. It has all the components of a really successful business.
Looking forward the future looks bright. There are so many opportunities open to them and they are also creating even more for themselves, such as the announcement of a completely new research and quarantine centre in Canary Wharf. To showcase the trust of big Pharma companies in Hvivo, and also the success of their testing, one of their clients has signed up to pay for a new testing centre. It will be fully fitted out and to even better standard as the last one in Whitechapel. It will hold 50 beds with the possibility to move it up to 70. This is clearest proof of how far the company has come and how valued they are by their clients, that they are now investing together in the company’s future.
Not only is Hvivo expanding the current business model but they have good progress on identifying and carrying out new directions the business could move in to. Recently, the CEO told investors that they have been working on a deal in which they can repurpose healthy volunteers that do not get used in their challenge trials, to another bio tech for use in there phase one trails. This would be for a small fee. Another way in which they are looking to the future is Hlabs and the new consultancy work they have now started doing for other companies on safety and running effective programmes. Hlabs is a CAP accredited stand alone lab services contracts team. It’s only a small and new team but it shows the way the management are looking to constantly expand the business in both in terms of revenue and breadth of activity.
The Continued work on new challenge trials, like Flu B and HMPV, is a nod to the future growth of the business. These new challenge trials, combined with the increased beds and end to end services, I think will serve very well for the long term growth of Hvivo. All of these are driving the core business forward and have led to increased margins and a higher barriers to entry over the past few years, cementing Hvivo as the world leader. Finally they do have a large cash pile and are cash generative, given this they do have some firepower if they did want to start making acquisitions or invest more heavily in the business. Considering that a client is paying for the new quarantine centre it seems they do not need to make immediate cash investments for growth. So this leads to the possibility that acquisitions could be another route of growth.
As with every company, there are risks. I have listed some of the main ones below and my thoughts on them:
Valuation is a hard one with HVivo, I have done a discounted cash flow analysis and came to a figure of 80 million for the current value of the company. This came from growth of 15% for net profits for the next 5 years and a discount rate of 10% (if anyone has any other figures please let me know I would love to see if have gone wrong anywhere). So currently Hvivo would be deemed as overvalued and to get to that point of buying it would need to be at a share price of around 13.8-14p. Which is drop of 30%. Hvivo has a higher then average PE ratio of 18 for full year 2023. This is definitely not in bargain territory but maybe with the contracted revenues and the visibility it brings, it could be considered growth at reasonable price or “growth and visibility at a reasonable price”.
To conclude on Hvivo I do really like the business, the long term visibility of revenues, the increasing margin and the growth cash pile are all characteristics that over the long term could be really promising for the company. They seems to have laid the ground work for some good growth drivers within the business going forward and for this we just credit the management who are very switched on and driving the business forward. As I’ve said it’s not cheap but in a market correction could be a long term opportunity with time horizons of 5 years plus.
Thank you for your time reading this. Please let me know what you all think as I’ve said I’m new to this and I’m looking for ways to improve my research and writing.
I think time is on your side, there's no doubt about that so good luck in the future.
Good write up Olly, as a holder I enjoyed reading it. Tell me, how did you identify HVivo in the first place as a company of interest?
Thanks for your comment, a friend said to me to have a look on them as he had heard about them on a podcast. I ran the numbers and went a bit more in-depth it wasn’t a screener but it does fit a lot of my screener criteria
There's been a fair bit of M&A activity in Hvivo's ballpark recently.So they seem to be in the right space.Ergomed having recently been bought out.
Great analysis of hVIVO (LON:HVO) – thank you. There’s been a lot (of good things) going on and I think this is a super summary.
Some thoughts:
Risks
Sustainable growth -Needs to keep winning large contracts. Fast growing market but how big (and lumpy) will it prove to be. Certainly doesn't appear to be an issue at the moment.
Volunteers - they have a few hundred thousand on the books and on recent calls management said they don't see this as a big risk.
Return and valuation (from Sharepad):
FY23 (31/12/23) Cash Flow Yield (f) = 5.0%
FY22 ROCE = 29%
FY23 EV/EBIT (f) = 14.9
PEG = 1.2
From Research Tree – Liberum – Price target 26.3p based on market EBITDA multiple
Analysts expected to update forecasts after results announcement next week.
Thank you for these comments and the valuations I will add it to my valuation in the future. It will be interesting to see the results next week as well .
I agree its an interesting business. Isn't the biggest risk something going horribly wrong in a trial? To avoid that risk, I would expect them to restrict trials to mild diseases. Actually, I was surprised they did a trial on Covid.
I would have thought most of the risk would be on whoever the pharmaceutical client is - chronic adverse reactions to any particular drug/treatment would be the responsibility of the drug company behind the product.
Obviously there is an implementation risk, e.g. giving the wrong people the wrong drug, or accidentally administering an overdose for example, but you would assume they would have very strict controls/procedures in place to mitigate against these risks.
Your analysis is good, so well done. Just a thought - something of this length might perhaps justify creating a Discussion post, which would possibly invite readership and comments from outside the SVCR, with a link posted here.
Thank you I’ll add it to there as well in future for more piece I write I’ll post it as a discussion as well.
I can’t see any forward numbers in your analysis except from your own DCF analysis.
For example you could have included your own revenues expectations (if any) and the expectations of Mr Market.
This is what matters (at least for me!).
I have to agree though, that it is very hard indeed to value this share.
Thanks