Small Cap Value Report (Thu 8 April 2021) - COG, ASC, ALT, MOTR, PMI, EQLS, WINK

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Timing - we're rattling through things this morning, so should be done by official finish time of 1pm. Today's report is now finished.
Agenda -
Paul's section -
Early snapshots - quick fire comments on stand out news items between 7-8am. Readers seem to like this innovation, so we'll keep doing it. Paul gives a quick view on:
- Cambridge Cognition Holdings (LON:COG) (I hold) - another contract win. Looks a very good, and reasonably-priced turnaround share.
- Asos (LON:ASC) - Not a small cap but .... strong interim results, could be worth a look.
- Altitude (LON:ALT) (I hold) - in line trading update. Seems to have enough cash to keep going. Recovery potential? I'm not sure on this one, it could go either way.
Motorpoint (LON:MOTR) - review of FY 03/2021 trading update. Interesting business model. Uncertain outlook. No guidance, so I can't form a view overall.
Tracsis (LON:TRCS) - Interim results are in line with the last trading update. A good quality group, I think.
Jack's section -
- Premier Miton (LON:PMI) - UK equity fund inflows but multi-asset outflows worth monitoring
- Equals (LON:EQLS) - cash break even and improving momentum into 2021 for this turnaround fintech company
- M Winkworth (LON:WINK) - resilient results from this high quality but illiquid real estate franchisor micro cap
.
Paul's Section
Early snapshots -
Cambridge Cognition Holdings (LON:COG)
(I hold) - another contract win, £0.5m, mostly for delivery in 2021 - with a new client, which has a pipeline of new drugs (implying there could be more contract wins in future). Gross margin last year was 80%, so each new contract layers on useful extra gross profit, onto a largely fixed cost base - that's the perfect business model to me, and very much what I look for.
Given the large growth in order book previously reported, I think a recent flurry of new contract wins (e.g. £1.3m announced 9 days ago) makes it increasingly likely that forecasts could be raised again - current forecasts look too low to me. I covered all the main points here on 23 March 2021, when it issued much improved 2020 results.
My opinion - COG is clearly on a roll, and I think the shares still look cheap - only £31m market cap, for a now-profitable company, with enough cash, that has seen its order book more than double. I’m very keen on this share - it’s a proper turnaround, that the market is slowly waking up to. Its cloud-based software is ideally placed for the emerging trend towards cognitive testing at home, driven by covid restrictions, but unlikely to reverse as it works just as well, and is cheaper & more convenient.
Asos (LON:ASC)
Not a small cap but… worth a look, with very strong H1 results out today. It has always disappointed on profitability in the past (very little of it!), but that seems to have changed. The adj EBITDA margin has gone up from 6.0% to 9.2%. Full year expectations raised. For the first time ever, the valuation actually looks reasonable now! I think this sector (online fashion) is very simple - the best ones are Boohoo (LON:BOO) (I hold) Asos (LON:ASC) Next (LON:NXT) and Joules (LON:JOUL) (I hold). I can’t see any point in wasting time looking at other fashion retailers and hoping for a turnaround. I’m very tempted to open a new position in Asos. Although I still chuckle about selling my initial Asos stake of 500k shares when I had an 80% profit - at the princely price of 9p per share! Everyone of my age and above has an Asos story. Better to laugh about it, than cry over spilt milk.
Altitude (LON:ALT)
(I hold) - in line with expectations update for FY 03/2021, but doesn’t say what those expectations are. Seems to be OK for cash for now, with £2.1m (up from £1.3m when last reported on 22 Jan 2021). Talks about being well positioned to benefit from unlocking.
My opinion - I think the jury is still out, on whether this company does have a workable business model, or if it’s all just hot air? Time will tell. I had a little punt on it, a small position size, because this story has attracted a lot of private investor excitement in the past, so there could be buying interest from a legion of previous fans coming back to it, possibly? Just a punt at this stage.
Motorpoint (LON:MOTR)
261p (up 1%, at 08:34) - mkt cap £236m
This car supermarket chain came up on a stock screen I did over the weekend, so I’m happy to look at it today
Motorpoint Group PLC, the UK's leading independent omni-channel vehicle retailer, provides the following update on its trading performance for the year ended 31 March 2021 ("FY21").
Accelerated digital investment drives strong online revenue growth through lockdown
I’m quite taken aback by how much business MOTR is doing online - e.g.
E-commerce investment prioritised, and results exceeded the Board's expectations
· 52% of retail sales were sold online, over 22,000 units, with 3,300 sold in March alone
Does this mean people are buying the cars without even seeing them? I can see why that might work though, as looking at a Motorpoint website (not for too long though, or I’ll end up buying something, I’m terrible for collecting cars!), the cars are nearly-new, and seem to be low mileage. You can reserve one for a £99 deposit online, and there’s a 14-day money back guarantee. It’s a good business model I think - with large plots of land, hundreds of cars, out of town, with low overheads. Volume prioritised over margins.
There’s plenty of competition though - not just from traditional car dealers, but also from new entrants - we’ve probably all seen the TV ads for online only car dealers, who deliver to your door, and if you don’t like the car you just send it back.
MOTR also has an auction site, Auction4Cars.com targeted at trade buyers.
All in all then, I think this looks an interesting company.
Its historical track record looks quite good, although margins are wafer thin, on a lot of revenues, and EPS seems to have stalled at around 15p in recent years:

.
Impact of lockdowns - quite severe at the revenues level - down 29% on LY. That’s not the company’s fault, all that matters is what damage has it done to the company’s finances? Very little it seems, with H2 said to be “broadly” breakeven at operating profit level - i.e. a small loss.
Re-opening - is on 12 April in England, and 26 April in Scotland.
Outlook - a mixed bag here -
… the Board anticipates pent-up consumer demand upon re-opening. The Board also expects growing momentum for its E-commerce, Home Delivery and Reserve and Collect services as consumer buying habits evolve. The accelerated expansion of our E-commerce offering, coupled with new sales and collection branches provides the Board with a high level of confidence in the Group's potential to gain further market share.
Nevertheless, the Board expects that the impact of COVID-19 will continue to influence events in the new financial year, and given this uncertainty, believes it prudent to refrain from offering future guidance at this time. The position is under constant review, and an update will be provided when appropriate to do so.
Surely they could have given a range of possible outcomes? Plenty of other companies have done so. I would argue that in times of uncertainty, investors need guidance more than ever. We need a change of mindset in the city, from the current attitude of just clamming up in times of uncertainty, to instead giving a broader range of guidance in times of uncertainty.
Guidance shouldn’t be a single number, it should be a base case, with upper, and lower alternatives, thereby giving a range of possible outcomes. Isn’t that just common sense? Most companies already have those scenarios in their internal forecasts. More openness is needed here, at all companies.
The gold standard is Next (LON:NXT) - all companies and advisers should be locked in a room, and forced to read NXT guidance, and then asked “Why aren’t you doing the same?!”. Clear, and detailed guidance is what builds investor confidence, and a higher rating for the shares in the long run.
Diary date - 16 June 2021 for FY 03/2021 preliminary results.
My opinion - I like this business model, and would consider buying MOTR shares if there was clearer guidance about future profitability & growth.
It’s all too vague, and therefore I can’t get comfortable with the valuation at this stage.
A Director sold a remarkable £50m of shares in 2018-19 at 200-225p, which makes me wonder why I would pay more now?
I’ve got a little exposure to this sector with a small position in Vertu Motors (LON:VTU) which I’m happy with, so will probably sit on the sidelines with MOTR for the time being. VTU is on a much lower PER, and has vastly better asset backing. It is also busy online, so on balance I think it’s probably a safer bet than MOTR.
There are plenty of other similar listed car dealers to chose from. I see that Lookers (LON:LOOK) has been the star performer of late (also reporting today), seemingly recovering from a problematic past.
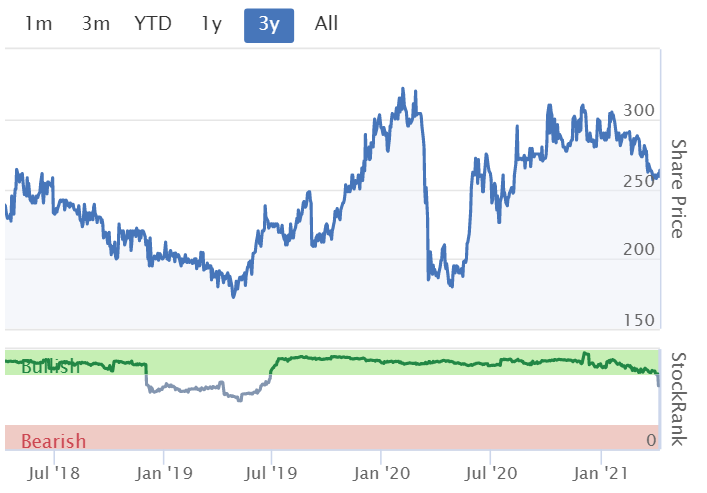
Over the last 3 years, MOTR shares have oscillated sideways, and divis have been nothing to write home about.
.
.
Tracsis (LON:TRCS)
720p (unchanged, at 11:28) - mkt cap £211m
There shouldn’t be any surprises here, as Tracsis issued an in line with expectations H1 (6 months to 31 Jan 2021) trading update in late February, which I commented on here.
Tracsys guided us to £22m revenues in H1, and EBITDA slightly down on last year’s £5.6m. Cash was guided at £21m, with no creditor stretch.
Actual H1 results today are as guided - revenue of £22.2m, and adj EBITDA of £5.4m. Cash is reported at £20.8m. That’s fine, it’s in line, near enough anyway. Covid had a big negative impact, but thankfully on the lower margin subsidiaries, so has barely affected profits. Good stuff. Not impacted by reduced passenger numbers on railways, because TRCS is part of key infrastructure, not dependent on passenger numbers - hence a resilient business model.
Current trading -
Encouraging start to Q3 trading with high activity levels across large parts of the Group
Outlook -
We have a significant pipeline of large multi-year opportunities across our Rail Technology and Services Division in both UK and international markets, and in our Data Analytics/GIS business unit. In addition, we are now starting to see an increase in new business enquiries across those businesses that have been hardest hit by the Covid pandemic and this is driving increased confidence around future growth prospects….
Results video - a summary from management is here, and an easily digestible 13 mins, I’ve just watched it - I do like these - video is a much easier way to absorb the key points, rather than ploughing through endless text documents.
Management sound upbeat about the order book & multi-year contract opportunities in the pipeline.
Share based charges - look a tad on the warm side, e.g. £665k in H1, which for context is 14.3% of adjusted profit (of £4.65m). In FY 07/2020 share based payments (i.e. free shares for management) was £1.05m, or 12.2% of adjusted profit - again that seems a tad warm, given that the share price has basically gone sideways for the last 3 years. Perhaps more challenging targets should be set in future?
Balance sheet - NAV is £54.4m, but that includes £52.3m intangibles, so NTAV only £2.1m.
There is a £7.8m long term creditor for deferred tax, which might be connected to the intangible assets, it sometimes is. So if I eliminate that too, then adjusted NTAV goes up to a more respectable £9.9m - not very much for a group capitalised at £211m.
The cash pile of £20.8m looks good, but bear in mind there’s a total of £7.9m contingent consideration creditors to take into account - this relates to acquisitions made, and is the expected payout related to performance targets for the acquired companies. I would treat this as debt, hence deduct it from the cash pile, to reduce cash to £12.9m.
Note 11 explains these creditors, and note there is scope for deferred consideration to increase further. Although from memory, I think the acquisitions were set up in such a way that if higher deferred consideration becomes due, it’s self-funding from the out-performance achieved.
Overall then, the balance sheet is OK, and does have some scope to fund some (small) further acquisitions. Anything over about £10m, and I think they would need to think about an equity raise, and/or debt. In the past Tracsis has been prudent about its balance sheet, avoiding debt. Given the proven resilience of the business through covid, maybe management could push the boat out a little, into shallow waters, and take on a small amount of debt for more acquisitions, if they’re decent, cash generative businesses?
My opinion - I do like Tracsis, it’s a nice group of businesses, well managed, conservatively financed, and management sounds positive about the outlook.
A slight annoyance is that it has just spiked up in price after a recent magazine tip.
In terms of valuation, it looks priced about right to me, at 720p. But we’re in a bull market, so share prices can go anywhere, I have no idea what level the share price might rise or fall to, that’s entirely down to market sentiment. It sounds like there’s a good chance of positive newsflow on new contract wins in the pipeline - which tends to trigger strong share price rises in a bull market like this. So it could be a good one to sit tight on, in expectation of contract wins. Maybe, who knows?!
.
It has a respectable StockRank of 75, and is classified positively as a “High Flyer”.
.

.
Jack’s section
Premier Miton (LON:PMI)
Share price: 152p (+1.33%)
Shares in issue: 157,913,035
Market cap: £240m
Although many asset managers such as Premier Miton (LON:PMI) are genuinely active and seek to provide added value, scale is still the name of the game here in many ways. That’s because the whole industry faces margin pressure from low cost passive funds.
This dynamic likely explains the merger between Premier and Miton (two mid-tier UK funds) back in 2019 that resulted in the £12.6bn fund we see today.
Asset management can still be a fantastically profitable business as long as assets are flowing the right way and investment performance is encouraging. In that sense, they can act almost as a geared play on the direction of the market and for that reason, some of the higher quality picks are probably worth considering in this environment.
This is a short Q2 update but, given the change in market conditions over the past six months or so, I’m curious to see how the professional managers are getting on.
Premier Miton announces its second consecutive quarter of positive net inflows, with AuM up to £12.6bn and net inflows of £193m for the quarter. That makes for £359m of net inflows year-to-date.
- Closing AuM of £12.6bn at 31 March 2021 (31 December 2020: £12.0bn)
- Net inflows of £193m during the Quarter
- Financial year to date net inflows of £359m
Mike O'Shea, Chief Executive Officer, commented:
For the first time in many months, and as we had expected at the time of our last update to shareholders, we saw increasing demand for our UK equity-focused strategies. This sector has been out of favour with investors for some time and it is one where we have a broad and strongly performing range of funds. Should this recent improvement in investor sentiment be maintained, we believe that the Group is well placed to benefit from increasing fund flows given our excellent track record in the area.
So that’s perhaps as we might have expected - it’s a bull market at the moment, and Premier Miton should be making hay while the sun shines.
There are some company-specific developments to note as well:
- A new Premier Miton Global Smaller Companies Fund was launched on 22 March 2021 and Premier Miton ‘continue[s] to believe that smaller companies represent an area where investors will be able to find value over the coming years.’
- Upcoming launch of the Premier Miton European Sustainable Leaders Fund on 10 May 2021, will focus on strong environmental, social and governance ('ESG') profiles.
- Cost reductions: of the £3.9bn multi-asset funds, some £2.2bn is managed on a multi-manager basis and £1.7bn is managed through direct investment in underlying securities.
In terms of year-to-date performance, the group’s Equity funds saw strong inflows and market performance, with AuM up 30% to £7.048bn (56% of total); Multi asset fund AuM down 4.4% to £3.937bn (31% of total); Fixed income up 7% to £520m (4.1% of total); Investment trusts up 22% to £731m (5.8% of total); and Segregated mandates up from nothing to £366m (2.9% of total AuM).
Conclusion
It looks like there’s decent value here with a c6% forecast yield and a forecast PE of 10.3.

Margins are the things to watch out for in this part of the market longer term. PMI’s operating margin of 12.33% does appear to lag its peers so perhaps we can expect more cost cutting initiatives moving forward.
There is good momentum in net fund flows, although the multi-asset strategy is currently going the wrong way and, as the second largest segment in terms of AuM, that could probably do with more of an explanation in the update.
There are a couple of high ranking fund managers on the market right now so there are a few alternatives worth checking out as well if you believe equity markets are in for a good year or two.

Equals (LON:EQLS)
Share price: 37.55p
Shares in issue: 178,602,918
Market cap: £67m
Equals (LON:EQLS) is a technology-led international payments group focused on the SME marketplace.
The group used to be called FairFX. Name changes often signify a break from the past and some sort of change in strategy. A quick look at the share price chart shows that shares began their fall before Covid and the price has yet to recover, so it does look like there are company-specific considerations here.

The group operates under an e-money licence, providing products including international payments, expense management, current accounts, credit facilities, multi-currency cards and travel cash.
Its subsidiary, Spectrum Payment Services (SPS), has access to real-time settlement accounts with the Bank of England and is a member of the UK Faster Payments Scheme, meaning customers can transfer and receive funds with immediate effect. SPS is also approved by the FCA to provide credit facilities acting as a broker.
But Equals does have a history of losses, cash outflows, and shareholder dilution. These are all flags I specifically watch out for, although it can mean you miss out on some of the higher risk, higher reward opportunities.
Companies do change and turnarounds can be very rewarding, but the risk is that everything just takes a little longer than expected - which often ends up being costly for shareholders.

Highlights:
- Group revenue -1.9% to £29m,
- Business-to-business (B2B) revenue +1.8% to £20.3m and business-to-consumer (B2C) revenue -3.7% to £8.7m,
- Gross profit -2.3% to £18.3m,
- Loss after tax -1.5% to £6.9m.
Equals is pivoting towards B2B and flags a further bolt-on acquisition of Effective FX in October 2020.
We’ve got Covid disruption to consider in these results and also the demise of Wirecard AG and its subsidiaries (the largest prepaid card issuer in the UK), whose cards Equals used for all its B2C and some of its B2B programmes.
So the fact the group achieved cash break even in Q4 2020 and says that the first quarter of 2021 has exceeded management expectations, with revenue of £8m and a free cash position of around £9m (5p per share), is creditable.
At these levels Equals is cheap in terms of revenue multiples compared to others in the fin-tech space but the track record of cash burn, shareholder dilution, and net losses do continue to weigh on my mind.
Commenting on the Final Results, Ian Strafford-Taylor, CEO of Equals Group plc, said:
As the UK payments sector becomes increasingly crowded with specialist operators, our unique proposition spanning banking services, international payments and card-based solutions is proving to be a major differentiator for our customers, driving loyalty and new customer acquisition. This, coupled with the benefits of our accelerated planned restructuring and right-sizing of operations, places us in a really strong position as we move past the challenges of 2020 and continue to focus on driving further B2B-led growth.
Conclusion
Top line growth has grown at an impressive CAGR of 41.4% over the past six years, but Equals is struggling to generate profits and cash flow.
Shares in issue have also increased considerably, diluting the upside for shareholders:

But the payments market overall is significant and Equals looks to be carving out a useful position spanning UK banking services and payments, international payments and card-based payments solutions. There could be a big prize at the end of the road.
The key question for me is how much it costs to get there and whether the company is at that inflection point where it can begin self-funding expansion, rather than coming to shareholders.
If cash breakeven in Q4 2020 really is that point then this could develop into a good growth company, but my concern is that Equals could continue to generate revenue growth and talk about big market opportunities while struggling to reach sustained profitability and cash generation.
I can see both sides of the argument here but caution keeps me on the sidelines for now. I’ll look out for future updates to see if the group can sustain this trading momentum.
M Winkworth (LON:WINK)
Share price: 160p (+4.92%)
Shares in issue: 12,733,238
Market cap: £20.4m
M Winkworth (LON:WINK) is one of three listed real estate franchisors that share similarly compelling quality, profitability, and cash flow metrics (the other two being TPFG and Belvoir). Winkworth is the smallest by some distance, with a market cap of £20.4m and an enterprise value of just £17.5m.

The updates from these companies have been surprisingly robust following the shock of initial lockdowns back in 2020, which I take to be the sign of a fundamentally strong business model.
There are two drawbacks to this stock though: its micro cap status and lack of meaningful liquidity, and the lack of real revenue and net income growth over time.
Highlights:
- Franchised office network revenue of £47.7m (2019: £48.3m)
- Revenues of £6.41m (2019: £6.42m)
- Profit before taxation £1.53m (2019: £1.63m)
- Year-end cash balance of £4.66m (2019: £3.57m)
- Rental income 50% of total revenues (2019: 51%)
- Two new franchises opened
- Dividends of 6.68p declared (2019: 7.8p)
Dominic Agace, CEO of the Company, commented:
Our business model was tested by extreme conditions in 2020 and proven to be very robust. The benefits of local expertise, highly motivated managers and a state-of-the-art digital platform meant that we were quick to emerge from lockdown and improve our market share. While challenges remain, we expect to see an increase in activity in 2021 and we are well positioned to further grow our network and respond to the evolving needs of our customers.
Given the events of 2020, broadly stable revenues and profits is a good result.
Management and lettings activity held up well although recent months have seen a reduction in interest in lettings. On the other hand, a stronger sales market is being driven by families seeking extra room for workspace and gardens, while still maintaining access to central London.
Winkworth expects this trend to continue, and is also experiencing an influx of new buyers at its country offices.
The group will be adding new franchises in 2021 and will continue to use its resources to attract and back entrepreneurial estate agents in key growth areas of Southern England and, after a rebound in sales activity in the second half, the group is experiencing strong momentum going into the first quarter of this year.
Conclusion
This is a small company and liquidity is an issue so it will be tricky to buy at scale.
But the commentary is useful as it shows that the property market is holding up perhaps better than many had feared. This is being helped by stamp duty, true - the government has extended the existing stamp duty holiday until June and on purchases up to £250,000 until September.
While the central London rental market is seeing some weakness, the overall demand picture looks surprisingly robust. Last year saw a resurgence of merger and acquisition activity in the sector and this environment could serve up growth opportunities for a niche, well-funded operator like Winkworth.
Affordability constraints in London will limit price growth but ultimately the capital should bounce back.
The only two things getting in the way with Winkworth are the combination of the group’s small size and liquidity constraints, and it’s lack of historical growth. If it can demonstrate revenue and earnings expansion, then it will become well worth considering.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Equals (LON:EQLS) Hosting Capital Markets Day next week for anyone interested.
https://www.equalsplc.com/capi...
On Asos (LON:ASC) margins might have jumped alot, driving a much better profit. But you have to take a call on whether returns rates will trend back to normal after lockdown, or not.
Two things that could drive increased returns: people going out and about, so able to drop off at the parcelshop or post office easier. And people buying more fancy, party wear instead of homewear, which drives more returns too.
eg even if you assume revenues are going to be same YoY, but margins returning back to where they were pre-COVID, you're looking at a 30% drop in operating profit YoY.
Hi Dahokolomoki
I recall receiving a response from an Investor Relations department in the last few months for an online retailer (sorry, I can't remember which company it was) and they confirmed that they didn't expect return rates to increase in the future.
Doing more in-depth research into Stitch Fix ($SFIX) (no position) revealed that they too didn't seem to be placing too much emphasis on a normalisation of return rates.
I don't really understand these positions, but it will certainly be interesting to see what happens.
Perhaps if people get used to personally ordering so much through a handful of online retailers (as they did in 2020) they already have an idea of what will and won't fit them, hence lower returns?
A
abtan - the only forecast for Tracsis (LON:TRCS) is from finnCap, one of the more PI friendly brokers, so you can register with them yourself and read it for free.
This morning they did a marginal trim and now have eps 25.8 this and 34.7 next on revenue 48.0 this and 60.5 next.
Tracsis (LON:TRCS)
Hi Sharw
Thanks very much for that.
I don't really read broker notes, but it's good to read that Finncap's revenue forecast this year is now £48m, that's much closer to what I have pencilled in too - thank you for sharing.
It looks like the £51m in the StockReport is therefore just out of date. I'm sure the updated Finncap number will feed through shortly.
Hopefully the £48m is management's view too, though I really wish they would just state this in their releases.
Cheers
A
A fascinating week:-
XLMedia (LON:XLM) closed @63.8 and is close to doubling from 35p on 26/02/2021.
For me, I've noticed XLMedia (LON:XLM) the share split has been applied on my HL Corporate Account but not on my HL ISA. I guess different back-office teams doing the admin.
My Corporate took the offer turning the 40p offering into the current 63.8p. Silly me for not taking my personal offering due to year end financial lockdown and window-dressing.
Here we may really find out the value of StockRank, Q and Magic formula. My money is on the algos being right. I bought XLMedia (LON:XLM) when it was No1 on the Magic Formula screen and threw everything at it in the crash.
International Personal Finance (LON:IPF) closes @110p.
Nice surge from the purveyor of self-destructive products to the dull-of-mind British American Tobacco (LON:BATS) +3%.
Centamin (LON:CEY) poking its head about 110p.
Plus500 (LON:PLUS) @1483p at last starting to chase its peers who have shot ahead.
IG Group (LON:IGG) @931p - all sins forgiven.
I'm up 8.6% this week and could be breaking two more milestones if nothing goes wrong.
Final fact of the day from a scientist on "Newsnight": You are more likely to die having a bath, coming down the stairs, eating breakfast or going for a walk than of a blood clot from the Astra Zeneca bug-jab.
Here are my SCVR heat maps for today (prices as at ~2:00pm).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
PS: My apologies for the slightly erratic nature of my contributions at the moment, school holidays and the day job are significantly impacting on my 'focus' time!
Special Divi is almost a certainty , Andrew Grant said as much in his last statement.
Which company are you referring to?
Jarvis Securities (LON:JIM)
Tracsis (LON:TRCS) (I hold)
To add to the commentary here I think it's worth highlighting:
NB: I assume the negative North America H2 revenue is FX-related, but it's so immaterial I'm not too concerned.
I am also hoping that Tracsis (LON:TRCS) become a beneficiary of the Biden Infrastructure plan.
Based on the commentary today I can't see how the company will exceed £47m.
In fact, achieving £51m would mean the company achieving it's best 6 month performance ever.
Are the forecasts we see the same as management's forecast?
I'm assuming this will double to at least £8m for the FY and, if things get back on track, £12m in 2021/22.
I apply a x20 multiple on this given the quality of the business = £240m valuation looking 1 year out.
The current valuation is c£200m.
---
As a believer in things returning to "normal" in the next few years, I'm happy to hold in anticipation of that material uplift next year and beyond.
Fingers crossed.
A
Thanks abtan, are you saying that forecasts are too high at the moment? Not often we find that situation in the current environment
Tracsis (LON:TRCS)
Hi Nanotrader
"are you saying that forecasts are too high at the moment?"
I'm asking which forecasts should I be looking at, because the ones in Stockopedia just don't seem right.
Cheers
A
Motorpoint (LON:MOTR) Hi Paul and many thanks for your daily reports. Very much appreciated. Shortly following the Director’s sale of a large tranche of shares in late 2019 I read that it was down to a combination of divorce/ retirement so I wasn’t concerned. Great business model but, like you, I am wary of the current influx of competitors.
I would also add that the competition is very high profile, can't switch on the TV without an Ad for them, Motorpoint seem conspicuous by their absence.
That's because competition (Cazoo, Carwow, etc) have VC money to burn and not concerned about turning a profit.
Cazoo is reversing into a SPAC, valued at US$7bn. In Q1, it did annualised sales of US$600m/yr. Used cars too. 100% of sales online.
Motorpoint (LON:MOTR) doing circa £800m in sales for FY Mar21. Market cap is £233m. But >50% of sales are online.
Presumably, the logical conclusion should be that if US$7bn is for "online car selling tech that can do $600m/yr sales", then Motorpoint (LON:MOTR) doing £400m+/yr (US$552m) sales online should be worth roughly the same US$7bn market cap?
Food for thought!
Maybe Motorpoint (LON:MOTR) management should just stop selling cars at retail completely. Therefore become a 100% online company. Doing £400m/yr sales (instead of £800m) but market cap will increase from £233m to US$7bn overnight.
To revert to Saga (LON:SAGA) (see yesterday’ SCVR) it is interesting how others see it. From today’s Guardian
“Saga hit by £61m loss as Covid takes toll on tours and cruises”
https://www.theguardian.com/bu...
The article is beyond superficial by the way. Paul’s post yesterday I think tells it the way it is.
I do not hold but am beginning to see the buy case if only I can decide what to sell.
Unfortunately am at the stage in life where I will have no new funds (apart from divis) to deploy, so something will have to be cut or sold.
Agreed Michael. Saga (LON:SAGA) HL mailed me last night with an update and if I had just read this alone then I'd have never gone near them. As it is I am very happy to hold them and look forward to the next couple of years with great expectations.
I am not sure the financial pages of the Guardian are worth the valueble time of Stocko members!
I am not sure the financial pages of the Guardian are worth the valueble time of Stocko members!
Definitely not, if all people want is to have their beliefs validated. Nils Pratley's comment on Saga (LON:SAGA) seems pretty much on the nose, mind:
“Customer demand remains strong, with evidence of significant pent-up demand from customers ready to travel,” says Saga, a statement that is clearly true because the first cruises this summer involve customers swapping their usual tour of the Mediterranean for all-British packages. Limited choice has not undermined demand.
Strictly speaking, one tour includes a look at a Norwegian fjord but the closest passengers will get to setting foot in Norway is the Orkneys and the Shetlands. The novelty of British tours might wear off if they became annual affairs. But, yes, the popularity of a cruise trip seems undimmed.
https://www.theguardian.com/bu...
timarr
Re Tracsis (LON:TRCS)
Thanks to Tamzin and theTracsis CEO and FD giving a video based summary of the Half Year report. Very much where it was suggested by an earlier Trading update.
A continuing teaser of a couple of new contracts currently being negotiated/finalised which I believe touch at least in part on the North American market (my guess).
This appears to be for their track analysis software. The size of these is as yet undetermined by the market, and they may be more strategic wins than super enhancing from an earnings perspective, perhaps? Any announcement should be considered imminent according to the CEO.
Very much in bounce back mode for the 2nd half, and with the usual marketing refresh that takes place with a new CEO. I like the idea of the new consultancy they are building up which will act a shop window for the several areas of activity that the Company specialize in. This could bring a more integrated approach to squeezing out more value from the disparate operating divisions.
I expect Govt's are a key focus for such an offering as they look for more integrated traffic management systems.
Hi, Would appreciate opinion on Jarvis Securities (LON:JIM) which raised equity via PrimaryBid last night to sell its treasury shares.
been with company for a number of years and i suspect we may see a special dividend coming our way
Positive BBC fashion coverage of Asos (LON:ASC) (I hold) just posted https://www.bbc.co.uk/news/bus... Makes a pleasant change from the three negative pieces in one week about a couple of pricing errors by 'you know who' (I also hold- shhhhh).
Are you in a hurry to sell then aknownmoose?
not in the slightest - quite the opposite, but some validation would be nice. It is especially annoying having held them at highs over 400 and NOT sold, now seeing them with much smaller gains
I am, at this point, on the brink of a full Python-esque breakdown trying to understand the Boohoo (LON:BOO) share price. The whole LSE market has risen with companies that have 5% annual profit growth climbing to new highs yet Boohoo remain at the same price they were 3 months ago, not even a nudge up in the past days
Come on moose, the market always looks through any current difficulties towards what the future offers...apart from when it doesn't.
2021-22 is an even bigger transition year for Boohoo (LON:BOO) as it still has much of its ESG work plan to complete and bed into the working and culture of the firm, and at the same time it is making the transition from awkward teenager with growing pains to become a more adult large scale multi £Bn cap firm that is comfortable with ESG, brand management, public relations and is also fully exploiting its new much wider range of brands and markets. if they can continue with their 25%+ pa revenue and profit growth, they will deliver great share price growth. When exactly? I haven't a clue...but there is potential for a lot of interesting news at their results presentation next month.
I hold.
Just points to the 100 bagger idea that you ignore the share price and just focus on the business. As long as the business is performing the share price will eventually catch-up (if not it will be taken over)
I hosted a ShareSoc webinar with Cambridge Cognition Holdings (LON:COG) a month or so ago and thought it looked a very interesting company that I should buy. Then I forgot to do so....silly me. But the webinar is on the ShareSoc site for members and is well worth a watch.
the key £COG quote during the webinar was that they were becoming more focused on selling products hence recruited more sales people. This seems to be helping the order traction.
Nothing to add but brilliant and worthwhile event, and I agree I could not attend the physical event so these are fantastic, a big thank you to everyone and well done Tamzin, Tim, Damian and all that goes on behind the scenes please keep it up!
Very happy with the GoDaddy bid for Minds Machines (LON:MMX) assets this morning. 8.8p per share is well ahead of my valuation of MMX as a stand-alone business and it is good to see a Board that is honest enough to conclude that their business is best taken forward as part of a bigger, better-resourced organisation.
I would have preferred a clean purchase of the whole listed entity, however, rather than selling the assets and transitioning to a cash shell. I guess the approach taken does give the opportunity to exploit the value of the listing but it also brings uncertainty as to the amount and timing of the distribution to shareholders and will leave me with a shareholding in a business that I likely would not have chosen to invest in (or cause me to sell out, probably at a significant discount to cash).
wrestling with what to do with Minds Machines (LON:MMX) . My current thoughts (SP at 7.5p as I write this) are to sell them all and move on or sell enough to cover my initial purchase costs and hold the remainder to see what happens. As I am unexperienced in this sort of situation I would welcome thoughts from wiser heads
Based on their past history I would quickly sell but don't blame me if they somehow do something useful and profitable with the cash!
Not advice and I don't hold but if it was me I would sell, I recently sold Arrow Global (LON:ARW) and Gamesys (LON:GYS) in the market before the takeovers went through. Bird in the hand and all that, in this market their are plenty of interesting opportunities or the cash can be ready for a purchase once the inevitable correction comes.
thanks for the thoughts on Minds Machines (LON:MMX) - I tend to agree and based on the fact I have other things I want to buy I have sold the lot for a nice 40% gain
Paul,
Many thanks for the early contract win Cambridge Cognition Holdings (LON:COG) commentary. I wasn't aware that Cambridge Cognition Holdings (LON:COG) was near profitability, nor of its 80% GM.
After a quick bit of desk research I brought a starter position 1st thing @ 103p. Company must be of its time and should be highly successful, if it can execute more sales.
Impellam (LON:IPEL) i think the results are quite understated and the shares offer good recovery potential.
obviously they are operating in a cyclical market, and were hit by the pandemic, but over 20 years the business has increased market share through the cycles and i think there are early signs that this time is no different. the shares in issue have increased modestly over 8 years meaning that it has been able to self-finance a doubling of turnover.
capex is c.10m per year, yet the amortisation is >£20m giving a £10m+ boost to annual CASH flows.
average margins over 10 years are 1.8% and sales last year were 2bn so i think it is modest to forecast profits in FY 2022 of 36m. debt is nearly zero so that is an EBITDA multiple of 4 times which seems way too low.
there is defd VAT to pay so maybe a more realistic current multiple is 5 times - still very low.
the mgt team have said that the pandemic allowed them to cut costs for future benefit , so realistically margins are likely to get above average, and similalry i have used 2020 revenues when there is likely to be increases for the next 2 years.
CHART: now that the downtrend has been broken, there is the possibility they retrace back to 800p in the next couple of years
i hold
Brilliant early snapshots!
Loving the early snapshots chaps, a helpful springboard into further research & much appreciated. Great to see you on the Stockslam last night too Jack, really enjoyed your pitch.
Seconded - it was good to see you on screen, Jack, I enjoyed both the pitch and your lockdown haircut! I thought the StockSlam as a whole was really well-run, big thanks to all involved especially Tamzin and Damian.
Thanks Whitbourne and Mike! The old mane is getting a bit wild again, that's for sure.
The event's great fun so if anybody's got a good stock idea I can thoroughly recommend getting involved for the next one.
And I'd like to echo the thanks to Tamzin, Damian, Sam, and everyone else involved behind the scenes. Hopefully there are many more to come.
These early snap shots are much appreciated Paul - very useful stuff.
Look forward to your comments on Motorpoint (LON:MOTR) - think their move into E-commerce is progressing very well and puts them in a strong position going forward
A friend of mine got me watching Norbert Lou of Punch Card Capital. He has a very concentrated portfolio. One of his investments I followed into was Naked Wines (LON:WINE) which I bought at 220p. Another is £MOTR. He has a very good track record and obviously sees something in Motorpoint.
How did you access his holdings please, especially UK ones? Do you sign up for a regular email. Thank you for any help you can give.
Tracsis (LON:TRCS) interim results today, here's an interview by Chris Barnes, CEO and Andrew Kelly, new CFO. H1 in line with expectations. There is encouraging trading momentum going into Q33, with a significant pipeline of opportunities across both the Rail Technology and Services Division and the Data Analytics/GIS business. Further, a reassuring increase in enquiries across the businesses hardest hit by CV19. Video & podcast.
Tracsis (LON:TRCS) will be holding an online presentation for all investors on Tuesday 13th April at 1.30pm, as part of the results roadshow. Register here.
Separately, a HUGE thank you to the ten superb presenters, including Jack, who presented their stock pick in last night's Stockopedia/piworld StockSlam. It was a great evening hosted by Damian Cannon, full of fabulous ideas. The video/podcast of the event will be available on Friday. And, thank you to everyone who joined to make it such an inclusive event. If anyone wants to Slam at the next event on 19th May, 6-7pm, please contact me through piworld.co.uk.
...and thanks to you, Tamzin , for your part in organising the event.
What surprises me about stockslam is that Paul and Jack look about 20 years younger than their official Stocko photos!
Thanks Tamzin, it was a blast and you've built up an impressive operation over at PIWorld that continues to be invaluable to the PI community. We appreciate all the hard work.
Thanks Tamzin for help hosting, really enjoyed it (whilst having dinner with my 2yr old!) The pandemic has meant I can actually attend these events which would not have been possible if it was a physical setting.
My morning smallcap tweet: Renalytix misleading RNS title
Equals (LON:EQLS) Renalytix AI (LON:RENX) Minds Machines (LON:MMX) Water Intelligence (LON:WATR) Spectra Systems (LON:SPSY) Lookers (LON:LOOK) Motorpoint (LON:MOTR) Alpha Financial Markets Consulting (LON:AFM) Tavistock Investments (LON:TAVI) Cambridge Cognition Holdings (LON:COG) Hyve (LON:HYVE), Altitude (LON:ALT)
Equals (EQLS) FY(Dec) rev down 6% and adj EBITDA £1.2m, ahead of market expectations. Q1 2021 exceeded management expectations. [SP=39.5 Cap=71m]
Renalytix AI (RENX) Study shows that KidneyIntelX "may be widely adopted by primary care physicians". This somehow became 'highly likely' in the RNS title. [SP=930 Cap=897m]
Minds + Machine (MMX) to sell the majority of its assets for $120m adj for working capital. Implied value of approximately 10p/sh and 8.8p after costs and taxes. A review concluded "the business has strong recurring cash flows but expects limited opportunity for material organic growth beyond the Company's AdultBlock services without fundamental changes." GM to approve. [SP=4.5 Cap=40m]
Water Intelligence (WATR) has reacquired its Central Florida franchise for $0.66m (1x rev) "as it provides greater scale to corporate operations in eastern Florida, a geography with high demand for water infrastructure solutions". [SP=710 Cap=111m]
Spectra Systems (SPSY) will be granted US patent for its technology for disinfecting banknotes from SARS-2 and other biohazards. Patent applications have been filed in other regions. Uses nitrogen and heat. [SP=188.3 Cap=86m]
Lookers (LOOK) Q1 trading better than Board expectations with 44k (49k) vehicle sales. Guides FY(Dec) U/L pretax materially ahead of analyst consensus of £22.6m. [SP=62.6 Cap=244m]
Motorpoint (MOTR) guides FY(Mar) rev down 29%. H2 op profit broadly brake even. No fwd guidance. [SP=259 Cap=234m]
Alpha Financial Markets Consulting (AFM) guides FY(Mar) adj EBITDA toward the upper-end of the range of market expectations. [SP=261.8 Cap=267m]
Tavistock Investments (TAVI) guides FY(Mar) gross rev in advisory business and FuM flat. "The opportunistic approach made to the Company by TEAM plc, a newly listed AIM company supported by a small grouping of former employees and disaffected shareholders, has been an unwelcome distraction...Board has been exploring ways in which the inherent value of the Company's assets can be used to fund the Company's further development and to deliver significant value for shareholders." [SP=2.34 Cap=14m]
Cambridge Cognition (COG) wins £0.5m order with a new pharmaceutical client to provide cognitive assessments in an at-home clinical trial. [SP=100 Cap=31m]
Hyve (HYVE) guides H1(Mar) rev c. £10m, including rev from Groceryshop Spring Meetup (its first virtual Meetup event) which performed more than 10% ahead of expectations. £15.9m of further insurance claims approved. Co trading between tow scenarios. In both Hyve maintains its strong liquidity position [SP=130.1 Cap=345m]
In line: Altitude (LON:ALT)
My take on Renalytix AI (LON:RENX) challenged by a Tweeter: "98% of the sampled physicians would purchase if FDA cleared and reimbursable."
I countered that it's well known that just because people say in a survey that they are likely to buy XYZ the outcome is usually not so. The 'zero-pound' opinion.
Am I being unduly cynical?
Re Renalytix Ai (LON:RENX) Mr C, I think perhaps your cynicism is misdirected and it's the US medical system that you should target.
If it's FDA approved and reimbursable then of course the doctors will use it. It's another thing they can charge for - why would they not use it? It's not their money they are spending, it boosts their income. And if they don't keep up to date with the latest methods they risk a malpractice suit.
brake even - ha ha ha
Would you chaps be able to cover Equals (LON:EQLS) please? year end results and positive q1 update seem to indicate a strong growing business.