Small Cap Value Report (Thu 8 Dec 2022) - SUS, NUM, RCN, OTB, TUNE, VTU, ITS, PURP, MER

Good morning from Paul & Graham! Today's report is now finished.
I typed up last week's podcast summary, here it is.
Agenda
Paul's Section:
On Beach group (LON:OTB) - I take a favourable view of this share, as a well-financed, recovering travel business, with good flexibility from a low fixed cost base. Shares seem good value. Very vague outlook comments, and who knows how it's likely to be affected by the consumer slowdown? Overall though, for patient investors, I think this deserves a thumbs up.
Focusrite (LON:TUNE) - results for FY 8/2022 look pretty good - it's held on to most of the pandemic boom growth. Balance sheet is sound, outlook comments seem reasonable. There are a couple of points to note - heavy capitalisation of developments costs, and profit includes a one-off forex boost which should really be adjusted out. Overall, I see this as a quality business, with good pricing power. Shares look priced about right. Thumbs up overall.
Vertu Motors (LON:VTU) [quick comment] - a very large acquisition (Helston Garages) is announced, at a cost of £117m (VTU’s mkt cap is £169m), so shareholders need to scrutinise this deal carefully, as it’s so material. Interestingly, VTU is leveraging some of its large portfolio of freeholds, by taking out a 20-year commercial mortgage of £74.8m via BMW financial services. Zeus says this deal will increase forecast EPS for FY 2/2024 by 19%, then 25% the following year, as synergies kick in. Sounds exciting. VTU shares remain remarkably cheap in my view, and remember that forecasts already factor in a normalisation of car supply & residual values. (no section below)
In Style group (LON:ITS) [quick comment] - poor H1 results, loss-making. Over-stocked, like many retailers, with inventories having doubled, despite lower revenues. Still solvent. CEO throws in the towel, so the founder returns to the top job. Strategic review implies that being listed is a waste of time & money effectively (which it is, as there’s no liquidity, due to the way it was floated in large chunks to institutions, as with so many small caps). Has put itself up for sale, but no interested parties as yet. My view - it’s been a dead loss since day 1, so I’ll be glad to see this hopefully de-list. (no section below)
Purplebricks (LON:PURP) [quick comment] - H1 results look grim to me. FY 4/2023 guidance confirmed, at EBITDA loss of £(4.0)m to £(11.3)m range. It’s cutting costs. Cash pile is depleting fast. Can the new CEO turn it around before the cash runs out? Positive going concern statement says the £31m cash pile is enough. Management reckon it should become cash generative in early FY 4/2024 - which could be interesting, if it happens. Very well known brand name. Tough market to be attempting (another) turnaround. I’ll keep an eye on it, but at the moment, a turnaround seems a tall order. (no section below)
Mears (LON:MER) - many thanks to Samscvb, who flagged up a positive trading update from Mears, which we missed. I had a quick look, and posted my thoughts in the comments below here - it gets a thumbs up. Looks good, trading well, and cheap. Plus a generous divi yield. I like the look of this.
Graham's Section:
S&U (LON:SUS) (£255m) - the December trading statement from this family-owned lending group confirms that their receivables book continues to grow rapidly. Even more importantly, collections remain strong in the motor finance division and the level of defaults in the property bridging division is considered to be low (only 7 technically defaulted accounts). I can understand that investors will be very cautious towards this type of stock in a recession that includes both a cost-of-living crisis and falling property prices. But I believe that the Coombs family shares this cautious attitude, and have excellent alignment with other shareholders.
Numis (LON:NUM) (£202m) - this investment bank posts weak full-year numbers, as expected. The expectations from the summer weren’t met, as H2 saw weakness spread from the public markets over to the private markets. The share price is down by 30% since I covered it last and is now hovering around the value of the company’s balance sheet net assets. This company has a great track record of share buybacks and dividends and I expect that profits are going to recover nicely, although the timing is beyond their control.
Redcentric (LON:RCN) (£177m) (+5%) [no section below] - this managed IT business reports interim results for September 2022. It made three acquisitions during the H1 period, and more during the prior year, and accordingly reports a very large percentage increase in H1 revenue (to £61.5m). The company provides several measures of H1 profits but it’s more useful to look ahead into future periods: recently upgraded forecasts now anticipate that the company will make £18.7m of adjusted PBT in FY March 2024, on £150m of revenue. The acquisitions are bedding in with £10m of annualised savings so far, and another £7m planned. CEO Peter Brotherton says “the outlook for organic growth is also favourable, with positive net new business achieved in each of the last six months to 30 November 2022”.
As discussed in November, Redcentric’s net debt has risen to £39m. The company does enjoy substantial headroom on its RCF and net debt/EBITDA is only around 1.2x. Furthermore, net debt is forecast to reduce to £21m by March 2024. Given the rapid pace of change, it might be sensible for Redcentric to focus on hitting that target instead of making further acquisitions in FY 2024. I am cautious in this sector and so the moderate valuation multiples attached to these shares make sense to me, but if they demonstrate some organic growth during the year ahead then I’d be open to the argument they are undervalued. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
On Beach group (LON:OTB)
109p (down 13% at 10:18)
Market cap £181m
The founder/CEO is stepping down in the next year, and being replaced by the CFO. Although the outgoing CEO is staying on as “Founder Director”.
Preliminary Results - for FY 9/2022
About On the Beach
With over 20% share of online sales in the short haul beach holiday market, we are one of the UK's largest online beach holiday retailers…
A strong bounceback in performance, driven by re-opening after the pandemic.
Revenue for FY 9/2022 was £144.3m, up 373% on LY, and almost back to pre-pandemic £147.5m in FY 9/2019.
Pandemic disruption affected the first 4 months (omicron), so these are not completely normal trading figures, hopefully next year could be better.
Heavily adjusted PBT is £14.1m, well below pre-pandemic £34.5m
Adjustments - the share-based payments charge of £4.7m stands out as excessive, and is exactly a third of the adj PBT above of £14.1m - how can that be justified?
Statutory PBT is only £2.1m
Regulatory reform - this section is worth reading, as it explains how after the failure of Monarch & Thomas Cook, the heavy losses incurred by consumers & taxpayers, means reform is necessary (maybe ring-fencing of customer funds). That could have far-reaching effects on travel companies which use customer funds to finance their business. OTB seems to already segregate customer cash, as £69.4m “Trust account” appears as an asset on the balance sheet. So OTB looks well set up.
Balance sheet - NAV is £156.8m. I always deduct intangible assets, £74.3m in this case, giving NTAV of £82.5m. That’s 46% of the market cap, so a fairly decent level of asset-backing.
Note that £11.0m of website development costs were capitalised in the year, much larger than the £5.3m amortisation charge. That flatters profit by £5.7m, a significant amount.
Cash is £64.5m, with no interest-bearing debt. The negligible P&L charge for debt interest suggests that it rarely, if ever, utilises the available bank facility.
Higher interest rates could benefit OTB, as it presumably could earn interest now on its own cash, and the customer trust account? Maybe a couple of million profit opportunity there?
Bank facility - note 18 details this, it’s £60m with Lloyds & Nat West, expiring Dec 2025.
Overall then, balance sheet & liquidity look fine to me, no concerns. Insolvency/dilution risk look very low, although the obvious risk of another pandemic has to be factored in. Do we want to invest in the travel sector at all, now we know how vulnerable it is to lockdowns?
Going concern note - an interesting read. It says even in a “remote downside scenario” of a travel shutdown until March 2024, OTB wouldn’t need to use its bank facility. That’s impressive. As note 6(a) shows, the biggest expense is marketing (£38.7m), which is greater than staff costs of £28.0m. Since marketing spend is very flexible, and can be quickly shut down in an extreme scenario, I think this gives us considerable comfort that OTB could weather any future storm. That’s arguably a much better business model than travel companies with large, owned assets, that incur considerable costs whether they are in use or not (e.g. airlines, cruise ships).
Dividends - nothing. However, it did pay divis pre-pandemic, so I would expect these to resume in future.
Outlook - if there was an award for vagueness, this would be on the final shortlist -

Broker research - the StockReport says 9 brokers cover OTB, but none of it finds its way onto Research Tree, which seems a glaring omission. The company should do something about this, as private investors need research notes. We create the liquidity in the shares, and set the price effectively, so it’s surprising this aspect has been neglected by mgt.
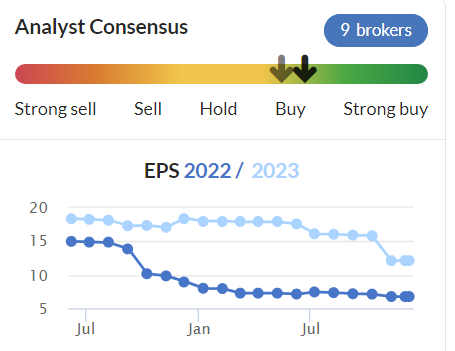
Actual (basic) EPS came in at 6.3p, which is close to the 6.7p consensus figure Stockopedia has below.
.
Is it reasonable to have higher forecasts for next year FY 9/2023? Given that FY 9/2022 was partially impacted by omicron, then it probably does make sense to assume the new year might perform better. Although we’ve now got the cost of living headwinds to deal with, and we don’t yet know to what extent consumers might cut back on holidays. Also, how much pent-up demand is there, after 2-3 years of disruption from the pandemic? For lots of people, holidays are sacrosanct, and they might make economies elsewhere, we’ll see in due course.
My opinion - I quite like OTB shares, as a good business on a reasonable valuation, so will give it a thumbs up.
Bull points are -
- Reasonable valuation
- Solid balance sheet with plenty of net cash
- Flexible business model, able to withstand another pandemic
- Prepared for regulatory reform, which might hamper competitors
- Should be further earnings recovery
- Well-known brand, and meaningful market share in a big niche.
Bear points that I can think of -
- Profits boosted by heavy capitalising of IT costs.
- Sector risk - maybe travel shares should be on permanently lower valuations, now we know how vulnerable they are to pandemics?
That doesn't seem enough, have I missed anything? If so, post a comment below!
Note the share count has gone up from 131m pre-pandemic, to 166m, up 27%.
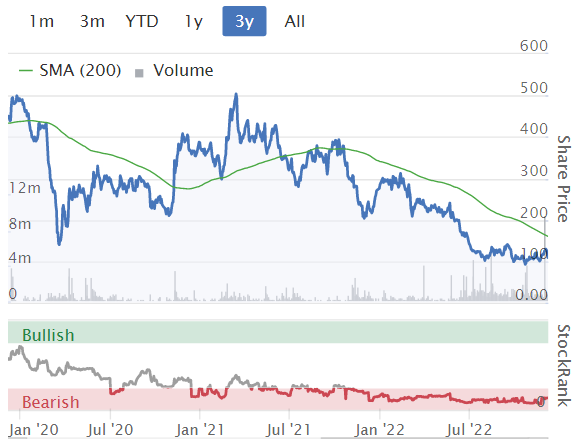
A share price similar to the bottom of the pandemic, seems surprisingly low.
Note the grim StockRank, but this should improve as post-pandemic numbers begin to feed into the data shortly.
.
Focusrite (LON:TUNE)
790p (down 9% at 12:15)
Market cap £464m
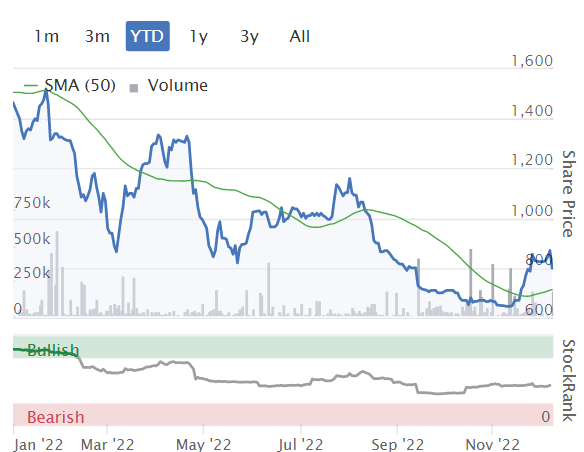
There’s a 9% drop in share price today, but this needs to be seen in the context of a strong recent rally. As long as shares are not making new lows, then this could be seen as reassuring.
.
Focusrite plc (AIM: TUNE), the global music and audio products company, announces its Final Results for the year ended 31 August 2022.
The financial highlights table below looks pretty good to me, in the circumstances - that Focusrite’s core business was a big beneficiary from the pandemic. So have held on to most of that growth is impressive I think.

.
52p adj EPS is ahead of the 47.0p broker consensus shown on the StockReport, assuming they’re calculated on the same basis.
Adjustments are explained in note 2, and look fine to me. The main difference is £5.1m amortisation relating to acquisitions, which it’s customary to ignore. Hence I’m happy to value this share on the adj EPS figure of 52p - giving a PER of 15.2 - which looks about right to me.
Finance income - I’ve spotted an anomaly here, which artificially boosts profit by £2.3m, so I think we should be adjusting this out, which isn’t done in the company’s adjustments.
Finance income of £2.3 million (FY21: £nil million) includes a large gain from retranslation of US dollar balances within the Group, which is not expected to re occur.
There’s no broker research available, maddeningly.
Declines in revenue have been more than offset by the benefit of acquisitions.
Outlook comments seem OK to me, and supply chains & freight costs easing could be nice tailwinds for this new year maybe -
For the current year, our first quarter trading has finished in line with our expectations.
Overall demand for the Group's portfolio of products has remained strong.
We remain mindful of the current significant global economic and political challenges, as well as the ongoing cost pressures in the supply chain, but we have worked hard to build back our inventory position. This provides greater resilience against supply chain volatility and ensures we are able to meet demand as we head into the key holiday season in FY23.
We have also introduced a number of measures to maintain margins, through pricing actions and ongoing review of our production costs. With new product launches across the product portfolio planned for FY23 and beyond we remain confident that the Group continues to have significant organic growth potential within our existing brands.
In tandem, the Group has proven that it has the capability to successfully execute on its proactive M&A strategy, carefully considering potential acquisitions that are not only earnings enhancing, but can also add to our market potential, expand our R&D footprint, and add scale and dynamism to our business.
All these factors combined leave us optimistic about our future prospects.
Balance Sheet - OK overall. NTAV is £29.6m, or £38.7m if we eliminate deferred tax (which is often related to intangible assets, so it makes sense to get rid of it).
Net debt is negligible, at £0.3m.
Working capital looks heavy - with both inventories and receivables having grown a lot, so these need to come down in future.
Note there is a large increase in capitalised development spend, at £8.4m (LY: £4.9m) which flatters profits, and renders EBITDA meaningless.
My opinion - this is an impressive company, which we like here at the SCVR.
My main worry was that the big pandemic boost might have unwound, as it has for many other companies. However in this case, TUNE has held on to most of that growth.
Overall, I think the shares look fairly priced right now. In the past it has commanded a premium valuation, so there could be upside from a re-rating, possibly?
I’ve been told by musicians that TUNE’s products are excellent, innovative, and they command good pricing power, as we can see from the good profit margins. So it looks a quality business, at what seems a reasonable valuation. I could see this share being a decent candidate for inclusion in a portfolio of high quality, long-term investments. Thumbs up from me.
Graham’s Section:
S&U (LON:SUS)
Share price: 2100p (pre-market)
Market cap: £255m
This is the motor finance and property lender managed by the Coombs family. We haven’t had an update since August.
Fortunately, trading has been good since then:
S&U continues to trade well despite a period of economic and political chaos unprecedented in most of our lifetimes. A change of government and of economic strategy, rising inflation, taxation and interest rates and an incipient recession is not exactly the ideal economic landscape for any business.
Nevertheless, trading is very good, focusing on the excellent quality of our customer relationships and the receivables which we derive from them.
Total group receivables continue to rise strongly and now stand at £404m, “with continued good collections and profitability during the period”.
At the most recent year-end (January 2022), total receivables were just £323m. So that’s a 25% increase, without making any acquisitions.
Motor Finance - profitability has been in line with expectations. Higher revenues are offset by “increased customer servicing and collection costs, designed both to protect customer collections quality and to retain staff as living costs rise”.
There has been no problem with customer defaults yet, as bad debts remain below budget. In light of the cost-of-living crisis, the loan underwriting criteria are constantly being revised.
Property Bridging (“Aspen”) - this newer business continues to grow at an impressive pace. Receivables are now at £108m (from £64m in January 2022). Given the volatility in the housing market, I was interested to read how Aspen might have been affected:
Credit quality at Aspen is strong, although refinance arrangements and legal processes are taking longer than usual. The extended beyond term list remains small and there are only 7 technically defaulted accounts as customer repayments during the period have been good.
Higher bank rate and interest costs mean that loan rate increases have been made to protect Aspen's margins.
Outlook - Anthony Coombs gives nothing away in today’s outlook statement.
My view
I have no reason to change my view on this stock. The property bridging division could be seen as a potential area of vulnerability, given that it lacks the track record of S&U’s motor finance division. So it may require some additional monitoring by investors.
And this property division, known as “Aspen”, is growing at a fierce rate. S&U has increased the use of its borrowing facilities and ploughed additional funding of £43m into it this year. It now accounts for a quarter of S&U’s entire receivables book: if it keeps going at this rate, it won’t be long before it matches the size of the motor finance division!
I would like to do a bit more digging into Aspen, to understand better how they are managing risk. But I believe that S&U as a whole is very well-capitalised, with a large equity cushion to allow for any mishaps.
So I continue to view these shares as offering good value. They trade at only a modest premium to book despite a remarkable track record which includes 30 years of dividends and an attractive return on equity.

Numis (LON:NUM)
Share price: 183p (-0.6%)
Market cap: £202m
This investment bank’s share price has weakened considerably since the last occasion that I covered it, in July. It has fallen back to Covid-era lows, which were a great buying opportunity:
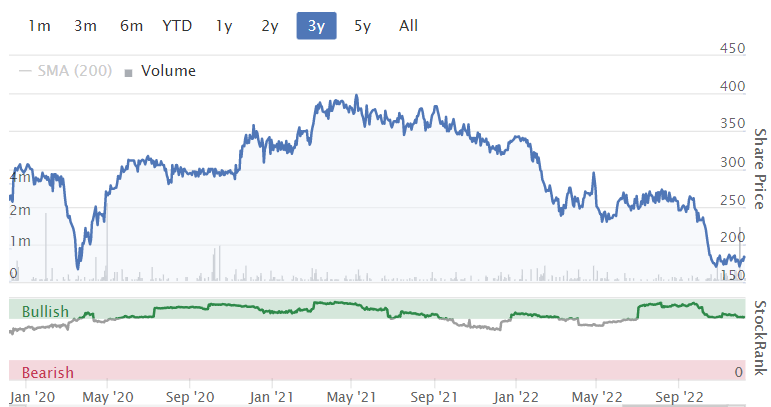
In July, I noted that Numis was still trading at a significant premium to book value. On balance I thought that was fair, given the strength of its name in the industry.
However, it has missed the expectations which prevailed then, for FY September 2022.
- Revenues: expectations were £145.8m. Actual: £144.2m.
- PBT: expectations were £25.1m. Actual: £20.9m.
Expectations for 2023 are now subdued, too (the light blue line):
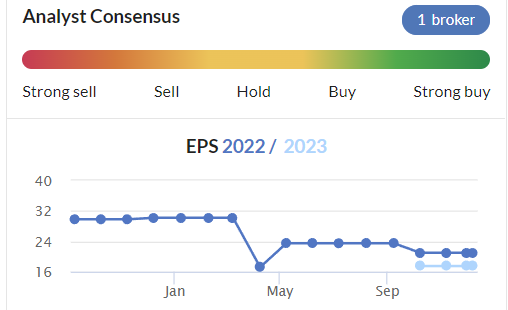
These full-year results contain some stark figures:
- Revenues down 33%, as “market conditions deteriorated from highly supportive levels”.
- PBT down 72%, “reflecting operational gearing in the business”.
UK equity trading volumes fell to a 10 year low (!).
Outlook
The capital markets outlook remains challenging with deal volumes remaining subdued and unfavourable conditions persisting as the market digests the impact of sustained inflation and higher interest rates. However, momentum in our M&A business has been maintained in FY23 with a strong near-term pipeline of transactions due to complete in the first half of the year. Our equities business has benefited from an improved financial performance in the first two months of FY23, driven by strong trading gains.
The last sentence offers some light at the end of the tunnel. Maybe, just maybe, bear market sentiment reached a low point below which it could not fall any further?
Balance sheet
Net assets are £185m and cash is £106m. We are fast approaching the territory where this becomes a “deep value” stock!
Strategy
Investment banking revenues were down 39% in FY 2022, as the UK IPO market ground to a halt. But the outcome would have been worse had Numis not developed businesses in M&A advisory and fundraising for private companies. These activities helped to pick up some of the slack although Numis says that even the private market slowed down in H2:
…the downturn in public markets, notably the de-rating in listed growth stocks, had a corresponding impact on private markets in the second half of the year. This resulted in deals taking longer to execute and some transactions being postponed or aborted which impacted second half revenues.
EU expansion - Numis now has an office in Dublin, from which it will look to grow its European institutional client base.
My view
I hold Numis in high regard and now that its market cap has fallen so close to book value, I can’t help but view this as a possible buying opportunity. The fact that it still earned PBT of over £20m, in some of the worst financial conditions imaginable for small-caps and mid-caps, demonstrates to me its resilience.
It’s a well-diversified business and in the good times, I expect it to make much more than £20m of annual PBT. So I have to rate these shares positively at a market cap of £200m and with very strong balance sheet support.
The stock already passes two of Stockopedia’s Ben Graham stock screens: The Ben Graham Enterprising Investor Screen and the Ben Graham Deep Value Checklist.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
I sure I read somewhere that bids in the run-up to Christmas were opportunistic. It might have been Robbie Burns that said that. I have TP (LON:TPG) Wentworth Resources (LON:WEN) and K3 Capital (LON:K3C) there maybe more to come.
So I realise this will be a minority view (perhaps of 1) but I don't like the Vertu Motors (LON:VTU) deal...
I think they've shown a great deal of strategy drift/incontinence in last few years. They started out deliberately targeting undervalued franchises and turning them around. So this took them away from the premium names. They were always looking to pick up some premium if they could at a decent price as they wanted to move themselves as close as they could to a representative snapshot of what averages sales are in UK (this took them into some Jag / Land Rover dealers a while back...I suspect as cheaper than Merc and BMW at time)...but value was supposed to be paramount and room for them to work their turnaround value creation magic that Forrester liked to boast about the group having*)
Then they started paying up for Merc dealers in the south...and now they've gone large on premium including supercars I believe with Ferrari part of the mix of marques coming in.
I'm no expert in the motor trade but I'd guess that these premium dealers are going to come with a lot of overheads and ongoing costs to meet the requirements of the marque. That could push on costs. Also, we don't really know what unfolds with EVs and how that impacts purchasing behaviour. A battery's a battery perhaps? I'm a bit of a sucker for kick ass ICG and the wrapper it comes with....I don't feel the same about EVs. I don't feel I'd pay up in the same way. Maybe I'm odd one out there**
I also feel that the servicing model operated by dealers will face some regulatory scrutiny. Its a bad deal for consumer and quite a bit of shenanigans going on with pricing and unnecessary work and expensive parts.
*IMO there was scant evidence of this...their value creating moment was being lucky enough to pick up used car dealer Bristol Motors for a snip back in 2008ish)
**I really worry about the idea of EV Ferraris...really!! What's the point?
Thought I would catch up on what has been happening been today as I have been busy since catching the RNS at 7am.
Well, I nearly fell off my chair, no bids on shares in my portfolio of 25 UK small caps since Air Partner in February and it appears two come along at once, K3 Capital (LON:K3C) and Crestchic (LON:LOAD) both top 5 holdings.
I hold them because they both operate in areas of demand and their potential for continuing growth. The bids if they come to fruition, are purely good fortune.
Having said that I think that the mooted 350p for K3 Capital (LON:K3C) and 400p for Crestchic (LON:LOAD) are not particularly generous. Hopefully it may stir interest from other potential bidders. As a small shareholder such matters are outside my control but failing a counter offer and subject to due diligence and the regulatory hoops, the bid for K3 Capital (LON:K3C) is likely to be a done deal, given the large holdings of John Rigby and Antony Ford.
As for Crestchic (LON:LOAD) Christopher Mills at Harwood who holds 24% of the equity will no doubt have a role to play.
It will be interesting to see what tomorrow brings.
I hold both also. I think the Crestchic (LON:LOAD) offer is far too low, I hope it is not accepted and I hope it does not get taken over.
A 400p offer for Crestchic plc looks imminent. Well done to Simon Thompson for analysing its potentials and recommending this when it was still at 130p.
Now Crestchic Crestchic (LON:LOAD) also under offer...
https://news.sky.com/story/agg...
Hi Graham
Not that I have read the H1 and FY results in any detail, but AIUI from the Stockopedia numbers, the Numis (LON:NUM) results are extremely H1 weighted. So the current profitability run rate is significantly lower than the forecast for the current year.
As you state, P/TBV and past performance coming out of weakness are both supportive but wonder if they will also miss this year’s forecasts giv8ng further SP weakness
Board at K3 Capital (LON:K3C) unanimously accept 350p offer is an utter p1ss take.
Clearly the deal is exit for Tony Ford and then the others get a stake and cash from PE partners to acquire and grow. Cam see the attraction...however the board is their to look after the interests of shareholders...and 350p is way short of upholding that interest.
TBC I'm not happy about any takeover as see this stock as a great long term compounding opp....but at, say, 450p I might grudgingly part and give respect to board AND institutional owners for extracting a good price.
40% ownership from institutions visible on shareholder register. I would hope they will fight on the price rather than be spineless gimps...
Offer for K3C @ £3.50, seems a bit cheap
Judging by the increase in daily volumes since the c 260p level, it's a very leaky ship!
Its been trying to break 300 for a while TBH...seems cheap to me
Low ball - think Shore cap issued 410p target recently
Derisory offer
Derisory offer
That was my first reaction. So why is the board of K3 Capital (LON:K3C) minded to accept?
I honestly don't know, not even the ATH share price! Would have thought 400p for starters...
K3 Capital (LON:K3C) Other parties have dropped out, so may not be any other offers.
Total stitch-up. No intention to negotiate best deal for shareholders. Upside to be retained by Rigby and Ford who will probably be kept on by Sun and incentivised to rinse and repeat. All we can do is refuse to invest in any companies brought to market by these two in future. Also worth considering whether PIs ever likely to benefit from any upside in £MTW
I agree, from the buyers perspective I think it's opportunistic given the exchange rate, the economic cycle and broker target price. Given the SP was 380p 18 months ago on much lower profits, it does beg the question as to why the board accepted.
I guess the easy value for private equity is to extract the £5m cash and leverage the stable cash flows by raising debt and pocketing the cash. I imagine this could help make employment at Sun Capital very lucrative for the executive board team.
I wonder what the non execs are up to....?
Agree - ridiculously low. There are a lot of institutional investors on board - Rigby and Ford only own 18%. So hopefully not a done deal. I thought they were good value at almost 400 last year.
Foxtons (LON:FOXT)
'New data shows demand for homes in the UK rental sector is continuing to rise, as home buyer activity drops off. According to findings from the Royal Institution of Chartered Surveyors, the rise in demand contributing to an upward pressure on rental prices, at a time when house prices have been falling month-on-month. Foxtons has recently been building up the lettings side of its business'.
Seems to be adding to a hunch I have about Foxtons (LON:FOXT)
Thank you for your quick comment on Vertu Paul, I've read the deal twice (we hold) and it looks like the Robert Forrester has crossed all the T's and dotted all the I's as usual. I like it, it's what he's promised to do but if you do get time later, or over the next few days I would appreciate your comments when you've looked under the bonnet.
Hi JASVFS,
I wasn't planning on doing anything additional on Vertu Motors (LON:VTU) - today's quick comment covers the main points I think.
The detail is covered well in a new note from Zeus that's on Research Tree, you've probably seen it.
I think Robert Forrester knows what he's doing, and will no doubt already know the business well, so we have to assume he's struck a good deal. It doesn't look amazingly cheap, especially if you assume the acquisition returns to pre-pandemic trading. Although it's mostly asset-backed. I particularly like the leveraging of freeholds, with long-term mortgages, that I think are covenant-free as they're commercial mortgages.
He did say in a previous webinar that sector consolidation would happen, so VTU would either gobble up smaller competitors, or get gobbled up itself. Or maybe both?
Regards, Paul.
Vertu Motors (LON:VTU), The market likes it, shares were up 25% before falling back a bit.
It didn't move much at all this morning for couple of hours, but just checked now and see it's surged - market very slow to react for some reason?
US market, I suspect. There was a surprising level of US investment in Cambria Auto, so Vertu Motors (LON:VTU) is perhaps similar.
Yes very slow reaction, I nearly sold recently, glad I held on.
Hi Paul and Graham,
I was looking at Petrofac plc and in particular its 9.75% 21/26 bond price trading at 62 cents. Surely another company that will definitely end up in the hands of the bond holders leaving current shareholders with almost nothing.
I will also appreciate a comment on today’s Vertu Motors acquisition. There is a hidden 2023 EBITDA results announcement from now in this RNS.
Allergy Therapeutics (LON:AGY) finally release some news. Looks promising on 2 game changing allergy solutions. I am quietly adding in regular blocks. My think is that 2024 will be a big year for AGY. A boring little tick along pharma is going to become exciting.
Give us some numbers not just stories or personal gut feelings , because the truth about Allergy Therapeutics is that is running out of cash and will need a big fundraise ( a much bigger than the recent one).
Have you looked at the recent £10m Loan Notes?
The truth?- A piece of your opinion. Are you sure?
Facility was from one of largest shareholders. That inspires confidence. New (interim) FCO in place, two Non Exec Directors just announced.
My feeling is that this looks good.
My opinion is based on numbers and nothing else. This company will be losing at least £20m for the next three years and by the end of 2024 will have a debt of over £52m.
Although you will need a miracle to make money on this one , good luck with it.
Mears (LON:MER) just an idea as no-one mentioned:
Trading Update and Board Changes - 07:00:02 08 Dec 2022 - MER News article | London Stock Exchange
Trading ahead of market expectations, do average daily net cash (which I think Paul likes), strong balance sheet, defensive sector.
Paul last time suggested it's boring. However, keep in mind it was mentioned by Betaville here: Spot Markets Live Transcript: 21/11/22 - The Blind Spot (the-blindspot.com) as a possible takeover target with some detail. The spike on the 11th is also I think because of takeover speculation. On the 7th they appointed Panmure and Numis as joint brokers. IIRC CFO has also bought about £150k of shares this year.
Hi Samscvb,
Thanks for flagging Mears (LON:MER)
I last looked at MER on 31 March 2022, concluding -
Mears (LON:MER) - not a sector that interests me, but the StockReport shows a forward PER of 10.5, and good yield of 4.1%. Final results today look OK - bouncing back into profit, but a wafer thin profit margin. Reports average daily cash, as well as period end cash/debt, which is excellent, all companies should do this. Current trading in line. Good visibility. Most contracts have annual uplift for inflation - an important point. Margins are too low to interest me.
Jack looked at MER on 17 May 2022, concluding -
Mears (LON:MER) - trading ahead of expectations thanks to improving margins and a strong cash performance. The valuation is modest and the yield is good, but this is an historically low-margin business and the share price has struggled to move over the years, which limits my interest.
I see from the StockReport that the value metrics are looking better - low PER, nice yield, and some asset backing, high StockRank of 97 - so this is starting to look more interesting.
.
Moving on to today's positive trading update, I think you covered this, but the main part looks good to me -
"Since the half year results which were announced on 4 August 2022, the Group has continued to experience strong trading. Based on the performance to date, and with good visibility through to the end of the year, the Board now expects that the Group will deliver revenues for the full financial year to 31 December 2022 of c.£950m and adjusted profit before tax of c.£33.5m, both above the current range of market expectations. This better-than-expected trading performance has been driven by the continued elevated volumes within the Group's Management-led contracts. Average daily net cash for the 11 months to 30 November 2022 of c.£40m is also ahead of previous guidance."
Outlook for 2023 also sounds positive -
"The Board is confident in the outlook for 2023 and is focused on continuing to improve the operating margin and delivering strong cash generation."
My opinion - this looks good, I like it! Thanks for flagging MER. On the quickest of skims, I'm happy to award it a thumbs up :-)
Re S&U (LON:SUS) write up and issues
1) Aspen bridging finance has average maximum gross loan to value at c.70%...so margin of safety on defaulted loans high (though will tie up capital a bit). Although 7 loans are reported to be in 'technical default' this is likely not an issue and the pattern is that these are made good and whole again. At c.£900k average these are significant loans and the incentive and ability of borrowers to make good the repayment is extremely high as the real estate is security.
2) Bridging finance is twice as capital intensive (net of bad debts) as car loans...so £1 of loan capital gets you approx 12p revenues per annum bridging (note the margin above base rates should be pretty steady as rate rises passed on), whereas its 26p of revenues on car loans.
3) Growth of bridging creates a growing pains issue for the business in that it will need to come up with a financing plan that is probably beyond extra debt finance at the entity level. S&U run with a high element of retained earnings that they use to underpin a lot of lending which boosts profitability as well as making the business higher quality from an investment perspective.
4) The potential for growth in their traditional non prime used car finance (cars typically over 3yrs old and think typical age is 7yrs) speciality is probably under appreciated imo as a) there's been a lot of competitive landscape and FCA related disturbance that structurally favours S&U and b) they have significantly improved their internal processes and sales channels with the arrival couple of years ago of guy that lead VW finance in UK
Overall, I really like
S&U (LON:SUS) Good points Graham and Mojomogoz. I would just add
1. I am a long time holder and have been impressed by the willingness of management to interact with shareholders.
2. The Aspen business has plenty of room for growth if/when the property market returns to any sort of normality. The high st banks have virtually withdrawn from this sort of lending. That despite opportunity for arrangement fees and good interest margins. Risk countered by taking freehold or long leasehold property as security with usually a big margin between valuations and lending.
3. Reduced competition in the used car loan market, or so I am told, due to the car manufacturer finance subsidiaries reducing exposure.
With a nice divi, what’s not to like?
Seraphine (Bump)
Looks ok seem to be doing the right things.
Pretty simple really, improve margin and reduce the overstock should improve profits and cash .
Just worry a little that the overhead might increase as they “build the senior team” ?
They need to keep it very lean not fat salary big ticket corporate types but lean and agile entrepreneurship .
Bizarre for an online retailer to have to recruit following two people ?
Hard to imagine they didn’t have these in place ? Maybe they had their own team and have recruited in people above the incumbents (sometimes a bad idea )
A good trading director definitely needed to work alongside the FD to sort that overstock out .
Appointment of Trading Director
Appointment of Performance Marketing Director
I hold a small position just for fun , pure gamble and probably the same odds Bump being a 10 bagger as England winning World Cup
.
Except England can win World Cup in a week or so...
Could you update (if only briefly) on £BUMP please Paul following their update today. Seems much as expected overall, and share has been showing signs of life recently.
This bit on the debt looks reassuring too,
“Net debt continues to be consistent with the position at H1, with the benefit of the stock unwind expected to reduce net debt during FY24. We have also agreed revised debt covenants with our lender, who continues to be supportive of the business.”
Hi ken,
Re Seraphine (LON:BUMP)
It's very high risk, so be careful with this one (I hold quite a big position, but I've gone into it with my eyes open, and accept that there could be a bad outcome. But if it works, this could be a multibagger, hence high risk, high possible reward).
H1 figures today are poor, but in line with most recent guidance.
Big positive for me is that bank covenants revised (but no figures provided), and bank supportive.
Net debt is only £3.6m, and it has cash on hand of £3.3m - that's not disastrous by any means.
Another big positive is the going concern statement, which says that it has sufficient funding for the next 12 months, and generating cash from de-stocking is key here.
Inventories - have gone crazily high, so yes de-stocking is very much a necessity. New CFO knows his stuff, so I'm sure will be prioritising inventories reduction, hence turning cashflow positive. 70%+ of lines are "continuity" - i.e. not subject to fashion risk, so this should be do-able.
Gross margins are very high, demonstrating strong pricing power, niche product.
High average basket size, so returns less of an issue than for cheap, fast fashion companies.
Balance sheet - clearly needs to be strengthened, so risk of an equity fundraise (on possibly poor terms) does look quite high. This could also open the door to Mayfair Capital & Christopher Mills turning the screw, and diluting smaller shareholders on unfavourable terms, so I hope mgt stand firm against anything like that, if it arose.
I'd like to see it move to AIM, as the costs of a full listing are far too high for a company of this size.
De-listing risk - looks high.
I think that's covered the main points.
Market cap only about £6m, so if they get things back on track, then this could be a 5-bagger. That's why I got involved. Historically it was profitable, but the soaring cost of online marketing has been the main headwind.
Do be careful with this one, it is unusually risky.
Regards, Paul.
EDIT: I forgot to add that outlook comments say improved H2 expected, which combined with de-stocking, should alleviate cashflow.
Many thanks Paul for updating on £BUMP. I’ve only got a small punt so neither here nor there if it doesn’t work out. Hope it’s a 5 bagger in time for you. My record with small risky fun punts over the years is poor, but maybe you having a stake will do the trick this time! . Your update today (especially so about the debt) was overall quite reassuring. Thanks again …especially so as you and Graham have had a lot to cover today. Good to see Vertu Motors (LON:VTU) at last justifying patience too.
Redcentric (LON:RCN) interims this morning. The period was 'transformational' with three acquisitions. finnC maintains its target price of 170 p "equivalent to 8.5x EV/EBITDA and still delivering a 6.5% free cash flow yield".
Graham - you covered here: https://www.stockopedia.com/co... - any further comments?
Redcentric (LON:RCN) - hi Sharw, added a brief update on this. G
Graham - thanks.
Another vote for Focusrite (LON:TUNE) please. While clearly still not cheap, it’s an opportunity to take a good look at what has been a very high quality share paying a visit to better value territory. Is it now a value trap or a great opportunity to bag a long-term winner?
The single most important investing lesson I've learnt (but still struggle to apply) is that of patience and for me, Focusrite (LON:TUNE) is a great example of a particular type of founder-led, fabulous business that will almost certainly reward patient investors. I'm staying my hand because I believe that patience will present me with a more attractive entry point even than today's reduction is offering. I interpreted today's update as signalling continuing headwinds for at least another year but also it demonstrated the underlying strength and quality of the business. If I am correct and manage to build a position at a more attractive multiple than is currently on offer, then I'm convinced that holding this one very patiently for a very long time will be seriously rewarding.
Re Focusrite (LON:TUNE)
I’m inclined to agree that things will get worse before they get better. Some 85% of Focusrite’s revenues come from creation (artist purchases) rather than reproduction (festivals and venues). B2B and/or long cycle is a better place to be than B2C and/or short cycle during a recession and it’s likely that personal budgets of impecunious musicians are going to be particularly stretched in the coming year.
On valuation, the company’s operating numbers and long-term growth track record suggest a mid-20s P/E multiple even today (see high quality US industrials and Halma/Spirax) but the current uncertainty undermines the case, leaving the name at best fair value IMO. Fair value would normally be enough for me to jump in as quality compounders are rarely available on the cheap. But I wonder if the calculation of fair value will have fallen another 10-20% by the next update.
I would also add that Phil Dudderidge is not a young man any more and his full retirement along with any attempts to dispose of his huge shareholding in the open market would be a significant weight on the shares. You could argue it might promote an attractive bid but that hasn’t worked out at Renishaw, for example. On the numbers themselves, it would be good to hear Paul or Graham’s view.
Focusrite (LON:TUNE)
Paul can you take a look please. Full year results this morning. Difficult to make meaningful comparisons with prior period owing to Covid effect and acquisitions. Market doesn't like judging by drop in share price.
On Beach group (LON:OTB) - results
Revenue £144.3m vs. £30.5m prior yr. PBT of £14.1m vs. £18.4m loss. EPS 6.3p vs. 9.7p loss
Paul/Graham, would be good if you can comment on the numbers. tia
Would second a request for £OTB. Dropping like a stone on apparently good results. CEO stepping down
Gross margins halved v 2019 I guess, so absorbing costs & with weak consumer spending outlook, not much room to cut prices to boost demand. Oil prices dropping back a bit now though which might help a bit.
Not too certain they are good results. Group gross profit was only 3% below 2019 but Group pbt was down 59%. Not had chance to find out where circa £17m of net pbt has gone.
Increased headcount and also performance marketing coet inflation (CPCs and cpms) would be my guess.
Vertu Motors (LON:VTU)
As I posted a couple of times recently, VTU have announced the acquisition of a substantial part of Helston Garages. The full statement is here
https://www.vertumotors.com/cu...
In particular , I note:
S&U (LON:SUS) - good trading update!
(Just saying something to be first on SCVR!)
Sorry to be an idiot, but can I just ask how that was flagged up to you? I'm relying on my Hargreaves Landsdown financial diary for updates and results and I suspect it isn't comprehensive.
Piling through morning RNS on https://www.investegate.co.uk/
thanks for that!
Badgersbrook - another source of RNS automatically sent to you is the LSE, registration is free and they generally arrive slightly before Investegate. Investegate has a limit of 50 tickers in your list so this could limit large portfolios. However, I find that Investegate is quicker if you are searching for an RNS you might have missed or want to check back on. When you put the ticker into their search box the RNS come up neatly listed in date order.
HTH
thanks!
You also get it on here Stocko first page if you have a folio with your shares noted or a folio of your watch items
It shows up on the opening Stocko screen for me of RNS's, as long as it is one of your holdings. If you do not hold, which I do not, it comes up if you have an "ideas" or "researching folder"