Small Cap Value Report (Thu 8 Sept 2022) - W7L, SFR, MPAC, SDY, PMs energy statement.

Good morning from Paul & Roland!
Liz Truss - Energy Statement (House of Commons today)
Here are my notes of the main points -
New energy price guarantee, will curb inflation.
Temporary suspension of green levies on energy bills.
Households - rate will be capped so that average household spends £2.5k (as expected).
Additional £400 support will continue, as previously announced, plus additional support for poorer households already announced.
This supersedes OFGEM price cap.
This deal has been agreed with energy suppliers.
Long-term measures being taken to secure more affordable supplies.
Fund will be set up to give equivalent help to households that are off-grid, e.g. using oil, and park homes.
Business - will get equivalent support for 6 months. Longer support for hospitality sector.
Emergency legislation will be introduced to push this through.
Chancellor of Exchequer will set out costs later this month.
Not doing another windfall tax, because we need to encourage home-grown supply, not stifle investment.
Our approach is pro-growth, pro-business, pro-investment.
Can’t tax our way to growth (intervention from John Redwood)
This is the moment to be bold (she obviously listens to my podcasts LOL!)
We’ll defray the cost of this intervention by ramping up supply.
Maddie McT?????? Is already negotiating new supply contracts.
Accelerating all domestic production - new licensing round (for oil/gas?) expected to agree over 100 new licences.
Accelerating renewables & nuclear - prices will move to CFDs, not based on gas price.
UK is already a global leader in offshore wind.
Generators will receive a fair price, bringing down the cost, under new contracts.
Question re Rolls-Royce small, modular nuclear reactors. Yes, these are important.
Substantial boost to the economy.
These measures expected to curb inflation by up to 5% bps - this will reduce cost of servicing Govt debt.
£40bn fund will be set up (by BoE I think she said?) to provide liquidity to the energy suppliers, to stop more going bust, and hence reduce costs.
Net zero - remain completely committed to this by 2050.
Why are we in this situation? Policy has not previously focused on energy supply.
We didn’t build any new nuclear in the last 25 years.
Regulatory framework has failed. Left us vulnerable to global factors & bad actors (Putin).
Putin has weaponised energy supply.
Question - we have 150 years supply of shale gas, why are we not using it?
Answer - we’re going to end the moratorium on shale gas (fracking). Production could start as soon as 6 months. Only where there is local support.
We must never get into this situation again.
2 reviews will be launched;
- Review of energy regulation, to fix underlying problems, address supply & affordability long-term.
- Review how to achieve net zero by 2050, that’s pro-business, pro-growth, led by member for Kingswood (Chris Skidmore)
Launching “Great British Nuclear”, with aim to achieve 25% of total electricity supply by 2050.
Question - Rough Gas storage facility closure was short-sighted wasn’t it?
Answer - she dodged the question.
UK will be a net energy exporter by 2040 - plan will be set out in next 2 months.
Secure energy supply has been ignored for too long. I will end short-term approach on energy security, once and for all.
Keir Starmer - put on mute, so I could type up the above!
Energy Crisis - latest thoughts
Probably like many of you, I was glued to the TV news yesterday, trying to pick up facts & views on the ongoing energy crisis. Just a few snippets worth repeating -
Big announcements are scheduled for today, on both the energy relief packages for households and businesses. Plus they're tackling the problem of inadequate supply, and the structure of the energy market too, apparently. The Speaker insisted these have to be announced to the House of Commons first, but a lot seems to have already been leaked to the press.
Looking at the TV schedule for today, "Live House of Commons" starts at 11:30 (EDIT: a friend says it might be slightly earlier at 11:15) on the BBC Parliament channel, so I'll have that on in the background, and will take notes to put up here. It's so important for corporate earnings, and market sentiment, hence this is the no.1 macro issue right now.
There was also some useful analysis from journalists. One reported that high prices have already dented demand i the UK, which is down 7% apparently (gas and electricity, presumably?) and that currently the UK is exporting energy to Europe, but that is expected to reverse later this year (if they have the capacity to supply us?).
Forecasters have already begun lowering their expectations for peak inflation, which is obviously very encouraging. Clearly it is obvious that inflation should peak much lower, if bills are capped at £2.5k, versus the previous expectation that they would soar to £6k in early 2023. Although we don't know what, if any, side effects there would be from a big rise in Govt borrowing. Anyway let's reserve judgement until we know the full facts, hopefully c. lunchtime today.
Markets tend to start moving up when there's a solution in sight to major problems, but before the actual solution has had a positive effect. We saw that from Oct 2008 when it became clear Govts would backstop the major banks. As mentioned yesterday, during the pandemic, the initial Govt measures (e.g. furlough, extensive loan schemes) stopped markets falling in Mar/Apr 2020, and began a decent rally. Then a huge bull run started when the news came through of the vaccines in autumn 2020. So it's key, game-changing news that tends to spark the big recoveries in share prices, I've observed. As mentioned yesterday, I think we're at that point again. I'm not saying everything is fine, and we're back to a bull market, but just that I think the blind panic we've been seeing of late, with people anticipating armageddon, now looks overdone, given that a huge package of support is being brought in, and fast. So a decent rally in bombed out small caps, is my current thinking. But nobody knows, it's just a hunch based on what I've seen happen in the past.
Also worth mentioning is that the reversal of the planned corporation tax rise from c.19% to c.25% (rough figures), is a big boost to future corporate earnings, and should mean that forecast EPS can be revised up, or at least mean fewer profit warnings, if companies leave forecasts unchanged with the now defunct higher corp tax rate. A significant tailwind, to help offset the many headwinds.
Agenda -
Paul's Section:
Warpaint London (LON:W7L) - another positive update, with profit guidance raised c.8% - not entirely unexpected, as we commented here in June that it looked set up to beat soft forecasts. This share ticks all the right boxes for me - trading well, modest PER of about 11, terrific balance sheet, and a dividend yield of 6.0%. Also it has entrepreneurial management, that I'd like to speak to at some stage. So an enthusiastic thumbs up from me. You see, it's not all doom & gloom is it?!
Roland's Section:
Severfield (LON:SFR) - a solid update from this steel group, with stable order books and an unchanged outlook for the full year. Severfield claims to be managing inflationary pressures and have good visibility for the remainder of the year. Exposure to industrial and infrastructure markets may provide some protection against cyclical pressures. With the shares close to their pandemic lows, there could be value on offer here.
MPAC (LON:MPAC) - today’s half-year results from this packaging and automation specialist give us a chance to learn more about the impact of July’s profit warning. The picture isn’t very appealing, in my view. Profitability has collapsed and underlying order intake is flat, at best. I’m not yet convinced that management has created much value for shareholders, post-Molins. However, I accept the group’s redevelopment is still ongoing. DYOR.
Speedy Hire (LON:SDY) - [no section below] - Today’s AGM update from this equipment hire firm continues the theme of robust trading in the infrastructure and industrial construction markets. Management says that “some recent weakening in market conditions” has been offset by new contract wins with “major customers” effective from October 2022.
Speedy is also continuing to invest in its retail and trade offering, through a partnership with B&Q. A new marketing campaign is underway to promote the business to consumers.
Net debt was £95m at the end of August. This looks reasonable to me, at under 30% of fixed assets.
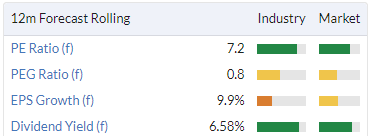
Outlook: overall trading is said to be in line with expectations. Consensus forecasts put the stock on seven times earnings, with a yield of 6.6%. As with Severfield, I think there could be some value here, if the UK economy can be stabilised without a major recession.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s section
Warpaint London (LON:W7L)
111p (pre market open) - mkt cap £85m
I last reviewed this makeup company here at end June, coming away with a positive impression. My inkling at the time was that full year forecasts looked beatable - that’s what we like, forecasts set lowish, which should then mean less risk of a profit warning clobbering the share price by 30-50%.
Today we get another positive update, as anticipated -
Strong trading performance continues and results for the year ending 31 December 2022 now expected to be ahead of market expectations
New guidance is at least £61m revenues for FY 12/2022.
Gross margin robust, and above 2021.
Adj PBT for FY 12/2022 now expected to be at least £9m.
Potential further benefit from forex hedging arrangements.
I’ve not seen any new broker notes yet today, but it’s easy enough to compare new guidance with the last note from Shore, which was £8.3m adj PBT (now raised to £9.0m, possibly more), and EPS of 8.8p, which I can raise by the same 8.4%, becoming 9.5p. What’s the betting they beat that in turn, and come out c.10p?
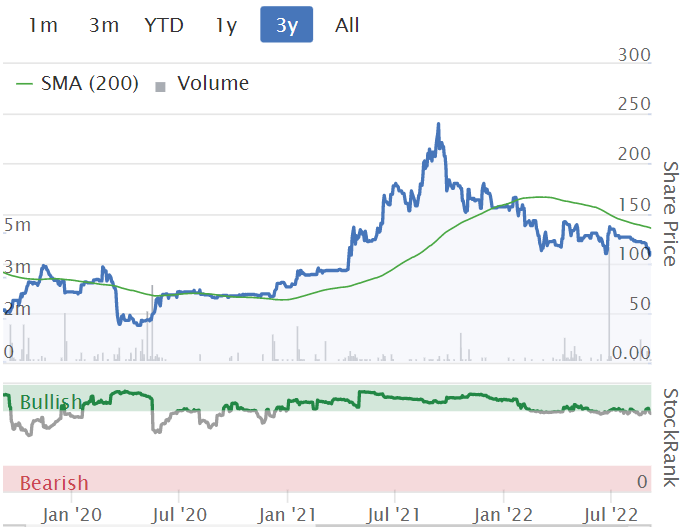
Valuation - The shares are 111p at close of play yesterday, so the PER looks to be only about 11. That’s too cheap I think, given that the company is performing well.
My opinion - thumbs up from me, I think this looks a good entry point at a modest PER, for a business that’s performing well despite all the macro headwinds.
The divis are really good too, with a forecast yield of 6.0%.
It has a cracking balance sheet too. Entrepreneurial management have big personal stakes.
So overall, this share is right up my street, and gets an enthusiastic thumbs up. If I had any spare cash, I would have bought on the opening bell today.
.
Roland’s section
Severfield (LON:SFR)
59p (+5% at 08.10)
Market cap £182m
When I last covered structural steel group Severfield in April, I commented on the obvious cyclical risks but suggested the shares could be good value.
Events have moved on since then and the market has priced in a further downturn, but once again today’s update reports solid trading and confirms full-year expectations.

“Performance in the first five months of the 2023 financial year has been strong and trading is in line with management’s expectations”
Operational highlights - The company says it’s managing inflationary pressures – it’s a big energy user – and expects several ongoing projects to deliver “significant profits in H2”.
Severfield’s operations are divided into two geographic segments:
UK and Europe: The order book stood at £483m on 1 September. This compares to £486m in June 2022, and £393m in November 2021. So the trend does appear to be positive, or at least stable.
I think that one reason for this may be the diversity of Severfield’s client base. The company supplies commercial and industrial construction projects, plus infrastructure and nuclear projects.
Management says they’re seeing “a good mix of projects” across the company’s key market sectors.
One other point worth mentioning is that 97% of the order book is for UK projects, so this is really a play on the UK economy. Europe is largely irrelevant at the moment. Although the company says it has a strong pipeline of bidding opportunities in Europe, its market share on the continent must be minimal.
India: Severfield is continuing to invest in this market as part of the JSSL joint venture. The order book is stable at £152m (June 2022: £158m) with “an improving pipeline of potential orders”.
Management says that the “ongoing conversion of the market from concrete to steel” should drive long-term growth and value in India.
However, as I’ve reported previously, profitability from JSSL has been minimal in the past, so I’m not sure how to value this part of the company.
Outlook: Management expects full year results to be in line with previous expectations. That prices Severfield shares on seven times forecast earnings with an attractive 5.7% yield.
Forecasts for the current year reflect expectations for a strong H2. Broker numbers suggest operating margins could hit 7%, with double-digit return on capital employed. That would be an improvement on last year’s performance:

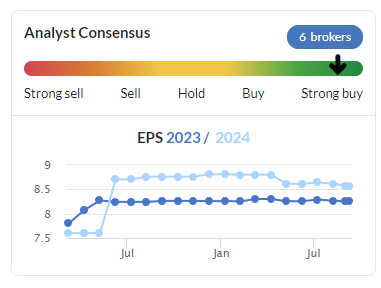
My view: Severfield appears to have resolved its historic problems and is operating with respectable profitability and a healthy balance sheet. Demand appears to be stable and broker forecasts remain positive:
Severfield could be a winner if the government’s planned energy bailout helps to create a soft landing for the UK economy.
Personally, I’m not completely convinced. But for investors who are more bullish and expect a stable outlook, I think Severfield could be worth a closer look at current levels, especially given the high dividend yield on offer.
MPAC (LON:MPAC)
231 (-8% at 08.30)
Market cap £47m
This consumer goods-focused “high speed packaging and automation solutions” group has been a successful turnaround investment in recent years. However, MPAC blotted its copybook in July with a big profit warning that caused the shares to collapse:
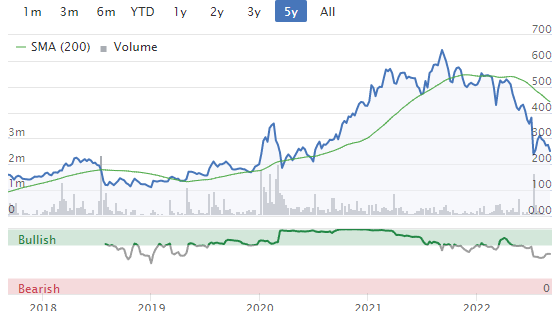
Graham covered the July profit warning here. Today’s half-year results give us a chance to see how the business is operating in more detail and gain an updated view on the outlook for the full year.
Financial highlights: The headline numbers do not look especially positive to me. New order intake has fallen and profitability has collapsed.
- Order intake of £32.8m (H1 2021: £51.7m)
- H1 closing order book of £62.6m (H1 2021: £62m, FY21: £78.4m)
- Revenue +14% to £50.6m
- Underlying pre-tax profit £1.1m (H1 2021: £4.7m)
- Statutory pre-tax loss of £0.4m (H1 2021: £2.8m profit)
- Net cash £9.5m (H1 2021: £11.2m, FY21: £14.5m)
Order book: MPAC says that the shortfall in orders during the first half was due to “a significant value of orders” that were brought forward from 2022 into Q4 2021 in order to secure lead times.
We can test this. The order book rose by £16m during the second half of last year. If I add this to the H1 2022 order intake, I get a figure of c.£49m, which is only slightly below the H1 2021 order intake of £51.7m.
However, there’s no escaping the lack of growth here. At best, I think we might say that MPAC’s underlying order intake has flatlined over the last year.
Revenue: sales growth appears to have been driven by the order backlog accumulated at the end of last year. Sales of original equipment were 17% higher, but service revenue only rose by 6%. The company says customer site activity was impacted by Covid restrictions.
Profitability: MPAC’s profit margins have collapsed. The company says this is due to higher costs, changing product mix and supply chain disruption, plus investment in new products.
MPAC’s gross profit margin fell to 21.1% (2021: 33.4%) due to “product and sector mix” as well as supply chain disruption.
The group’s underlying operating profit margin for the period fell to 2.4%, compared to more than 10% during H1 2021.
These figures suggest to me that MPAC has not been able to pass on higher costs to its customers. That’s a little disappointing. It calls into question the company’s competitive advantages, in my view.
Cash: Fortunately, MPAC is still well-endowed with cash from the £30m sale of its Molins tobacco machinery business in 2017. Unfortunately, MPAC is continuing to consume this cash:

Investing for long-term growth makes sense. But how much value is being created?
If we strip out the pension-related items from the balance sheet, MPAC’s net asset value today is just £23.2m.
The comparable NAV figure at the end of 2016, before the Molins disposal, was £37.6m.
Cash generation during the first half of the year was poor in my view, as it was last year:

I haven’t looked into this in detail, but I wonder if MPAC benefited from Covid-19 related contracts in 2020 which buoyed the firm’s results?
Outlook: MPAC’s management remains positive about the prospects for an agreement with FREYR Battery regarding battery cell automation lines. However, these discussions haven’t yet reached a contractual stage.
In terms of current business lines, the company says it’s seen “good acquisition” of new customers in healthcare and plant-based food.
A new Group Procurement Director has been appointed to manage the supply chain. Perhaps he or she will be able to improve cost control. The company continues to expect supply chain issues to ease in 2023.
The financial outlook is unchanged from the revised market expectations set out in July. According to broker consensus forecasts, these are for revenue of £95.2m and adjusted earnings of 14.6p per share.
Incidentally, this implies that H2 revenue will be c.£45m, which is below the H1 figure of £50.6m. This seems to support my conclusion that H1 revenue growth was due to the backlog of orders being cleared.
My view: I haven’t followed MPAC in any detail in recent years. I’d need to do more research to understand the company’s business lines and its prospects.
However, based on my reading of today’s results, I have reservations about how much shareholder value this business is creating. Profitability and cash generation seem poor and the company’s pricing power appears to be weak.
Another lingering concern for me is that the size of MPAC’s pension liabilities dwarf the value of its business. Today’s accounts show defined benefit obligations of £316.5m and assets of £376.5m. This compare to a market cap of c.£50m.
The scheme is in surplus and rising interest rates may mean that the company is able to reduce future payments into the scheme. However, as things stand the company has to make £1.9m deficit reduction payments each year until 2024. Administration charges are also material, at around £1m annually.
I’d need to do a lot more research to see if I could get comfortable with MPAC shares. But on balance, my feeling is that there are probably better opportunities elsewhere.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Sad the Queen died
I personally am spending some time to look at the investment in making my home financially energy independent via installing solar panels and battery. So far, if prices hold, my return looks to be under 5 years. This looks like a good investment. Obviously, things change and after the price freeze (2 years), the price for energy may go down a lot (obviously it could go up), but for me, any investment that gives you 100% of your initial outlay while still owning the initial investment within 8 years is good - at the moment it's 5 which gives me enough margin of safety to pull the trigger. I think opportunity.
"the investment in making my home financially energy independent via installing solar panels and battery. So far, if prices hold, my return looks to be under 5 years"
This so true for so many people if they did the Maths. Cost reduction on a certain expense is a brilliant low risk investment - at worst it takes a few more years to payout. The issue for most is however capital. However, a flexible, low cost loan (govt borrows at say 3%, lends at say 6%) say £5000, secured on property would make this feasible for millions at huge gain to the country's energy security and climate. Much more use than a second year of price freeze.
Best Of The Best (LON:BOTB) The founders have just sold a big chunk of their holdings to GIL for 400p.
"Following the signing of the LOI and as an indicator of
GIL's commitment to its long-term collaboration with BOTB, it today (or
as soon as possible) intends to acquire a 29.9% strategic shareholding
in BOTB. It is intended that these shares will be acquired from the
Company's currently largest and founding shareholders - William
Hindmarch (Chief Executive) and certain persons associated with William
Hindmarch, as well as Rupert Garton (Commercial Director)."
Best Of The Best (LON:BOTB)
Sounds interesting - and could potentially take them to the next level.
There are some who will have an issue with Teddy Sagi's involvement.
https://en.wikipedia.org/wiki/...
But he seems to be transforming £KAPE so I'll watch with interest.
Phil
(Edit: Exit route for Founders or smaller chunk of world domination? )
It doesn't really make clear what the commercial terms are, but it does sound like GIL will be taking a share of profits in UK so in the short term it will probably be bad for shareholders as it might depress.profitability? Albeit people might rate the shares on a higher multiple if there is a prospect of significant international growth.
A guide to prices in UK and EU on spot market per (MWh) does seem incredibly volatile
https://tradingeconomics.com/f...
We are actually exporting electricity to France at the moment
https://gridwatch.co.uk/
bottom right graph in dark blue http://www.gridwatch.templar.c...
shows uk have been exporting to france since late march, there is a clear correlation between uk export to france and the rising gas price, market concerns over the french plants.
On energy I find it strange there is little or no reporting that the French have switched of 20gw of nuclear power stations due to issues which is causes the gas spike also. 20gw is half of the uk output in the winter uk using more gas to make up this deficit
Davidallen77
My understanding was that France have been forced to lower nuclear output as the low level of river water, esp the Rhone, has meant it is too hot to cool the reactors.
Yes they where having that problem but also
In the link I posted above says 32 out of 56 reactors are down for maintenance for how long I’m not sure
yep but way before the weather french nuclear output has declined by >20gw since jan, they say they have found corrosion in plants seems done on purpose to me knowing full well that uk will use gas to fill in the gap. We have been an exported to France of electric since april hence high gas prices also. French punishment for brexit? What a perfect storm russia war and French nuclear offline.
Think Liz Truss has got off to a good start and think she got the balance of doing enough but not to much some people will find fault what ever she did
She resisted the more short sited envy driven call for a wind fall Tax
Long live the Queen
Paul - thanks for your notes on the energy announcement.
no details out on how the price freeze will work. doesn't seem right to subsidise Tesla drivers to charge their cars nor mansion owners to heat their draughty homes. The goal seems to be to keep the average household bill below 2500, this might imply that the subsidy may only apply upto typical average household energy usage. it can't be lost on the government that this crisis is a golden opportunity to incentivise energy efficiency measures amongst households and businesses .
Ashtead Technology Holdings (LON:AT.) (I hold) this morning announced they're hosting an interim results presentation for retail investors on Investor Meet Company on 13 September.
https://www.investormeetcompany.com/ashtead-technology-holdings-plc/register-investor
As a subsea rental and services business they're growing strongly but I think they'll also benefit from today's Government energy announcement with most assets located in the UK.
....meanwhile it look's like the French Govt (with 85% ownership) will largely be keeping EDF's windfall profits from its UK nuclear power generation business to themselves....
So I currently pay £250 a month on gas and electricity, so 3k a year. Does the announcement mean I will actaully be better off by £500 p.a.? Even before I turn the heaters on....maybe I'm just being ripped off at the moment by Octopus Energy
It depends on how much you use. The media don't help with reporting a cap of £XXXX a year. It's actually a unit price cap which works out at £2500 a year for an average household. Use more than the average household, you'll pay more, Use less, pay less etc
If you are on octopus then a variety of tools exist for you to examine your usage in minute detail and work out for yourself whether you are being "ripped off". They allow you to query your smart meter half hour data via a website and have an active development community that are making quite sophisticated tooling around this.
If you are interested have a look at:
https://energy.guylipman.com/s...
Hi Paul can you cover any views on Cenkos Securities (LON:CNKS) today? Been on SCVR previously but maybe market cap too low now to warrant a view. Not holding but still on watchlist, steep fall today on the interims.
O dear we still have the same borrow and spend government. It seem like we are borrowing to prop up Energy company profits.
This is only going trash the pound and stoke inflation and keep energy prices high.
What we really need is fossil fuel demand reduction is the short and long term.
BSV
Hi Paul, did you have a peek at £ORPH interims, if so what are your thoughts?
MPAC (LON:MPAC) in focus this morning after Interims - we have an investor presentation with the company on 19th September, you can sign up here: https://www.equitydevelopment....
Summary of our new note, published this morning (link to the full report & audio summary is here: https://www.equitydevelopment....)
First half FY 22 results mirrored the July trading update with revenue of £50.6m +14.5%YoY close to our revised estimate of £49.5m, and a closing order book at £62.6m (H1 21 £62.0m), which remained firm. Inflationary pressures and supply chain disruption remain features, however the Group continued to implement mitigating processes. We also note positive discussions with FREYR Battery towards a framework agreement for the installation of battery cell automation lines.
The underlying direction of travel for the markets Mpac targets remains unchanged. Spurred by the challenges of introducing environmentally friendly processes and packaging, and reducing plastic content and waste, Mpac’s target Healthcare and Food & Beverage verticals continue to require the innovative packaging and automation systems solutions in which the Group specialises. Mpac’s diversification into the new clean energy market provides a timely addition to the demand picture and offers the prospect of commercialised processes and solutions for wider application. Our outlook, revised at the time of the July trading update, remains unchanged: for the current year: revenue of £96.0m, and EBITDA (adj.) of £6.1m, indicative of an EV/EBITDA multiple of 6.6x.
Our fair value for Mpac remains 485p/share, indicative of a FY24 EV/EBITDA multiple of 6.7x.
Investor Presentation ***change of date*** - now 20th September (10.00am)
£Mpac, the specialist international business providing high speed packaging machines and complimentary services, will be conducting an Investor Presentation webinar covering their Interim Results to the period ending 30th June 2022. The online presentation will be hosted by Tony Steels, CEO, and Will Wilkins, Group Finance Director.
This event will now take place at 10.00am on Tuesday 20th September (note - was previously Monday 19th September - the date was moved in light of the Queen's funeral bank holiday).
The webinar is open to all existing and potential shareholders. Questions can be submitted during the presentation to be addressed at the end. You can sign up at this link: https://www.equitydevelopment....
Warpaint London (LON:W7L) - Only potential fly in the ointment is the fact that we've been here before with them, saying in Aug/Sep that they're ahead of expectations, sales didn't materialise and ended up with a profit warning which hammered the share price. Now, in their defence, that was when they had only just bought the gifting business (Retra from memory, could be wrong) and they didn't understand the way customer's ordered stock for the Christmas season with little to no follow up orders. So, I don't at all expect them to make the same mistake, but it is something to be cognizant of if you're new to the stock.
I'm long Warpaint for clarity.
Two things to watch which may give a tell re market enthusiasm for a change in sentiment towards the UK would be... ratio of FTSE 100 to FTSE 250 and Sterling Dollar.
Not much to say yet either way......
The Dollar trend is perhaps the more alarming and not confined to Sterling. For risk sentiment to improve this more than likely needs to reverse significantly. The correlation with the FTSE 250 is apparent... and more than likely small cap too. A reversal would be positive.
A range of macro events today, usefully listed by the Guardian:
The agenda
• 7.45am BST: French trade balance for July
• 11.30am BST: UK energy bill relief package announced
• 1.15pm BST: European Central Bank decision on interest rates
• 1.30pm BST: US weekly jobless figures
• 1.45pm BST: European Central Bank press conference
Very good and detailed report from Restaurant (LON:RTN) where they have spent an inordinate amount of time and space - and rightly so - on hedged energy policy and implications and forecast labour and food inflation. They are scaling back some expansion plans but they seem to have gained market share. IMHO, very impressive reporting.
Incidentally, in July, CEO and one other director made significant share buys - at the current price!
Much too big for consideration here, but always good read across from companies like Next (LON:NXT) and in this case Associated British Foods (LON:ABF) which Primark section has made the commercial decision NOT to raise consumer prices in 2023, and therefore will be running on a lower op profit margin. Obviously more interested in the longer term consumer approach to the brand. A brave but IMHO sensible approach that will be rewarded by higher sales and even higher consumer loyalty in the medium term. I trust they will be making their policy clear to the consumer in appropriate PR!
Hi ridavies,
Yes I had a look at ABF's update for the 52 weeks to 17 Sept 2022, out today. Here are my notes for the Primark section -
Revenues £7.7bn (up 40% vs LY)
Q4 LFLs close to pre-pandemic level (UK), lagging behind in Europe.
Click & collect trial for launch pre-Xmas - will this be a threat to the online-only competition?
Net cash £1.5bn, considering returning surplus cash to shareholders.
Operating profit margin declining: 9.6% for FY 9/2022, but H2 was lower at 8.0%
Outlook - obvious headwinds noted: strong dollar, higher energy costs, declining consumer disposable income.
Taken significant action to mitigate input cost inflation.
Limiting price rises next year, as a deliberate strategy (to drive market share, presumably, at the cost of reduced profit).
Next year's operating profit margin expected to continue declining, lower than the 8.0% in H2 this year.
Significant sales growth expected.
Adj EPS next year will be lower than this year.
My view - this sounds an aggressive strategy, designed to heap even more pressure on competitors. Primark has always been the price leader, and rather than passing on cost increases, it seems to be absorbing some costs in order to be super-competitive, and gain market share.
The shares look terrific value to me, if you take a long-term view that Primark is likely to continue its expansion, and drive more competitors out of business through maintaining super-low prices. I bet plenty of customers will trade down to Primark too, in a recession. Their products are stunning value, and I often wonder why buy things elsewhere, given that Primark quality is OK, and the prices are incredibly keen. I'm probably limbering up to buying some of these. As usual, the stock market is totally short termist, and has sold off the shares this morning on the short term reduced profit outlook, whilst seemingly oblivious to the longer-term strength and market share gains that this low price strategy should bring.
Pity there's a food business lumped in with Primark, I would much prefer they were separate shares.
Warpaint London (LON:W7L) thank you for flagging up that you’ll be covering W7L Paul
Todays TU reads well and they look to be navigating the challenges faced by UK beauty businesses (unlike REVB perhaps)
I recently bought a small amount after listening to Sam’s presentation at Mello and reading up on the Lipstick Effect (whereby consumers buy themselves small treats like lipsticks when times are tough as opposed to big ticket items).
With my equality hat on I do wish they’d appoint a suitable qualified woman to their Board but let’s hope this happens soon…
RE: Warpaint London (LON:W7L)
Details today were thin, but have to agree with Paul on this, it looks excellent value.
Cosmetics is an area that normally does very well in recessionary times - it's known as the Lipstick Effect, where woman spend small amounts on something that makes them feel good.
No idea what the male equivalent is ...
timarr
'No idea what the male equivalent is ...'
Beer?
Re Lipstick Effect
"No idea what the male equivalent is ..."
Another pint?
Richard
#DEST if anyone wants to read about Destiny Pharma results and update - new note from ED is here, with raised fair value : https://www.equitydevelopment....
Link to download wouldn’t post latest presentation is on there website and they are doing a video presentation on investor meet company at midday https://www.sylvaniaplatinum.c...
https://www.sylvaniaplatinum.c...
Nice results from Sylvania Platinum (LON:SLP) considering the back drop of weaker prices for PGM and inflation in production costs
They have doubled the final dividend to 8p maybe looking to increase payments from their cash pile which is around 50% of market cap
I do hold
Any thoughts Paul/Roland
I hold and like the dividend announcement this morning. They seem to be doing all the right things (buybacks, dividends, low debt), as usual though the SP is linked to the commodity price and I can't see that rising any time soon with the macro outlook. So patience might be needed here. I wonder if the lower production might push down the SP in the short term.
Testifying to the Treasury Select Committee, chief economist Huw Pill said that in the short-term, Government help with energy bills for households and businesses will likely result in lower inflation.
However, in the longer-term the multi-billion support package and tax cuts “will probably lead to slightly stronger inflation”, he said, adding that the impact of such policies would determine what the Bank decides to do with interest rates.
Energy prices: Bank of England warns Government bill freeze will add to UK inflation (msn.com)
Good morning both! At a market cap a shade under £700m may I respectfully request Oakley Capital Investments (LON:OCI) as a candidate for scrutiny today?
A positive trading update today with a line that stated 28% of their NAV growth is attributed to multiple expansion of their portfolio companies which I found remarkable in the current climate. Especially as it trades at a heavy discount to NAV.
Take care,
S.
Hi shamusj,
We don't tend to cover investment companies here, because they take too long to analyse, having to look at all the different investments they've made and then form a view on that. Plus as you allude to, investors also have to then scrutinise how the investments are valued, and whether NAV is fair or not.
Sorry about that, but by all means post your thoughts here, if you think it's a good share. Just because we don't write about something, readers are more than welcome to discuss it yourselves, especially if it's compelling value.
Regards, Paul.
According to RNS, Oakley Capital Investments (LON:OCI) has a NAV of 630p. Its current share price is 400p, representing a discount of 36%. Oakley Capital Investments (LON:OCI) often trades at a significant discount, though. Its average discount over the last year was 22%, according to Hargreaves Lansdown.
I've done rather well wit the share, and continue to hold.
My experience with investment trusts is that the stated NAV needs to be treated with a degree of caution, especially if it consists both quoted assets, where values can be easily checked, and unquoted assets where there is less clarity. For example, Crystal Amber (I hold) has a large stake in the quoted Hurricane Energy. Can that large stake be liquidated at the stated contribution to NAV? I doubt that a trade sale can be achieved at the stated NAV.
I had similar concerns in the listed PE space. However from what I have seen, Oakley Capital Investments (LON:OCI) has consistently exited from previous positions at a premium to their conservatively stated NAV which gives me confidence in their management and stated NAV.
I’m a substantial holder, and will continue to hold. Obviously exits will get harder, and revenue/profit growth will be less certain. However the directors have huge skin in the game, and the track record is good. To my mind the biggest risk is the very concentrated holdings.
Additional strengths of Oakley Capital Investments (LON:OCI) in my view: strong commitment to regular and thorough investor comms; relatively focused portfolio, leveraging their industry knowledge (ex the Time Out debacle, obvs). I hold.