Small Cap Value Report (Thu 9 Dec 2021) - CALL, COG, VTU, DWF, MADE, PRV, SUS, VIC

Good morning! Paul & Jack here with the SCVR. Today's report is now finished.
Agenda -
Paul's Section:
Cloudcall (LON:CALL) (I hold) - we're put out of our misery with a 81.5p cash recommended takeover bid, a 76% premium. What a relief!
Cambridge Cognition Holdings (LON:COG) (I hold) - £1m contract win is helpful.
Vertu Motors (LON:VTU) (I hold) - another profit upgrade! This is getting ridiculous!
Made.com (LON:MADE) - a profit warning, due to supply chain delays causing c.10% (£40m) of revenues to slip from FY 12/2021 into FY 12/2022. Does that really matter? I don't think so. The reason given is credible, as we know supply chain is problematic for everyone in the sector, and should sort itself out in time. A very interesting company, but personally I find the valuation too much of a leap of faith, as it's not yet reached profitability.
Victorian Plumbing (LON:VIC) - results for FY 9/2021 are excellent, but the sting in the tail comes with a negative outlook statement. Growth has stalled, and gross margins are falling hard, which I reckon could see profits fall 30-40%. That said, it looks good value now, at 99p. Tempting.
Jack's Section:
Dwf (LON:DWF) - legal and business services provider. Trading looks good, self-help initiatives have reduced the cost base and enhanced profitability, and the valuation appears modest. All in all, it looks interesting, although the financial health is borderline.
Porvair (LON:PRV) - looks like a sensible business in long term growth markets. The valuation is hard to justify right now, although the StockRank has recently improved (thanks to upgraded Quality and Momentum scores). For me, it’s one to watch in case the market ever presents a more attractive entry point.
S&u (LON:SUS) - I hold - confident update from family-run car and property lender. The valuation is reasonable, and the recent sell off does not tally with the group’s commentary. Long-term focused with a good dividend track record, and the stock is forecast to yield around 4.9%, so quite happy to hold.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Cloudcall (LON:CALL) (I hold)
47.5p (last night’s close) - mkt cap £23m
Recommended cash acquisition of Cloudcall
Hallelujah! We’re finally put out of our misery here, with a cash takeover bid at 81.5p, valuing the company at £39.9m - a 71.6% premium - not bad.
The buyer is Xplorer Capital LLC.
So far, shareholders with 23.9% have supported this deal - so it's not necessarily a done deal yet - I wonder if a higher competing offer might be a possibility? For this reason I’ll probably sit on my shares, rather than selling in the market.
My opinion - CALL has been a serial disappointer, missing forecasts repeatedly, and requiring never-ending cash raisings. That said, its product is quite good (I use it myself), and there’s always been potential here.
I don’t think loss-making minnows are suitable for the stock market. Returning to private ownership makes a lot more sense.
It’s so boring writing about this company, year after year, so I’m thrilled that it’s leaving the stock market. It’s only a small position for me, but a welcome little windfall anyway.
Cambridge Cognition Holdings (LON:COG) (I hold)
124p (last night’s close) - mkt cap £39m
£1.0m Schizophrenia clinical trial contract
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health…
I was only thinking yesterday that the flow of new contracts seemed to have dried up at COG, so this £1.0m contract (over 3 years) is welcome news.
It’s repeat business from an existing customer, which I like. The more COG’s testing becomes embedded in pharmaceutical companies as a standard part of drugs trials, then the more repeating revenues it could earn - at high margins remember (about 80%, from memory) - this is very specialised work, with little competition, and major barriers to entry.
This continues to be an exciting area for potential further growth for the Company in the future."
My opinion - I remain positive on this share. The order book has shot up in the last year, and performance appears to have turned a corner. Valuation still looks cheap to me, assuming that improved performance continues, as it's had a number of false dawns in the past under old management. There seems a much more commercial focus under CEO Matthew Stork, who comes across well on webinars.
The share price drift in recent months just looks par for the course with the general bearishness in small caps across the market, so doesn't concern me.
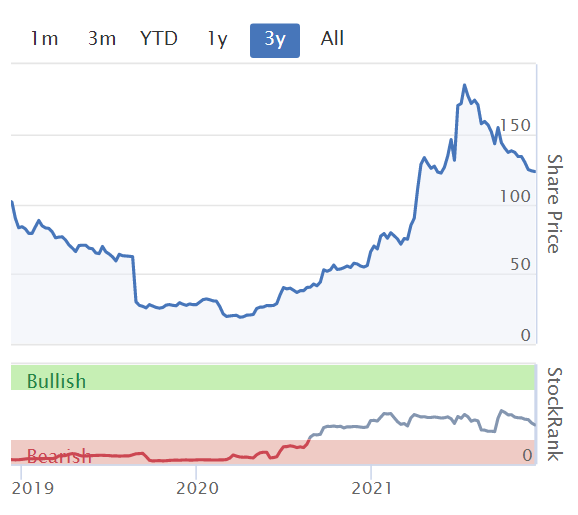
Vertu Motors (LON:VTU)
69p (last night’s close) - mkt cap £245m
Good grief, the car dealership sector is absolutely on fire at the moment. It’s yet another upgrade today -
Further upgrade of expected trading performance for FY22
My summary -
Oct & Nov 2021 trading ahead of plan (and prior year)
Shortage of new cars, but not as bad as expected, and sold at higher margins
Positive customer demand, with strong order book
Used car also supply constrained, values high, but have plateaued - “starting to follow more normalised seasonal trends”
Abnormally high margins in used cars continue
Staff being paid more, to address vacancies, reduced but still above historic levels
Cautious re outlook
Profit guidance raised -
the Board now anticipates that the Group's adjusted profit before tax for the year ending 28 February 2022 will be no less than £70m (previously not less than £65.0m).
My opinion - this bonanza won’t last, as everyone knows, but it will be filling the coffers with cash, and strengthening the balance sheet.
I continue to see VTU as a prime candidate for a takeover bid, due to its sector-leading balance sheet strength, including lots of freehold property, which could be leveraged by a buyer.
Marshall Motor Holdings (LON:MMH) received a takeover bid recently, so the sector looks in play.
.
Made.com (LON:MADE)
126p (down 6% at 08:50) - mkt cap £493m
MADE.com is an online furniture retailer, which listed in June 2021. We’ve discussed it here before, but I can’t locate my notes on it. There was an interesting results presentation below, which also shows some product & explains the business model (of using external designers, and continuously launching new product)
(complete with a glorious French accent from the CEO!)
It seems to be a popular brand with younger people, who seem happy buying furniture online.
MADE has been loss-making historically, but scraped into a £1.0m positive EBITDA in H1 FY 12/2021, although H2 is now expected to be a loss of £(13)m to £(16)m EBITDA.
The investment case is that strong growth, if it continues, should trigger a move into profit, through scaling up & operational gearing. I think this share looks potentially interesting.
The share price is quite volatile this morning, and I’ve had to change the price above 3 times already.
Obviously the sector is experiencing supply chain delays & freight cost pressures - temporary factors, but nobody knows when supply chains & freight are likely to normalise.
Trading Update (profit warning)
MADE reconfirms gross sales guidance of +40% year-on-year
Supply chain problems have worsened in recent months, delaying stock intake, and therefore revenue recognition.
I was puzzled as to how they reconfirm “gross sales”, whilst then telling us revenues will be deferred into next year? The answer seems to be that “gross sales” isn’t actually revenue, it seems to be order intake, so the headline above is rather misleading I feel. The company should change its terminology to "order intake", instead of the potentially misleading "gross sales".
Things are clarified in this table -

.
As you can see above, it’s a profit warning, due to £35-45m of revenues slipping into FY 12/2022, due to late deliveries.
Does this actually matter? Not really, in my opinion. There’s not a problem with demand, and we know the industry-wide supply chain delays are something that cannot be helped. So personally I’m inclined to look through this profit warning, as something external, and temporary, so it’s not a big deal in my view.
Remember that we’ve seen before (e.g. with Scs (LON:SCS) (I hold)) that one year’s delays and disappointing profits, are a bonanza of profits in the following year, as pent-up demand is fulfilled. I suspect we’ll see the same pattern again from SCS, which has already told the market it is struggling to deliver on the increasingly large order book.
Logically, investors shouldn’t worry, or react to this type of news. But as we know, markets are not always rational, and I’ve noticed that we seem to be in a market where people over-react to predictable, obvious news. That is creating some nice buying opportunities in my opinion.
Outlook - this is not the clearest of statements, but the general gist seems to be that they’re expecting supply chain to improve in 2022 -
MADE has continued to deliver significant progress on its key strategic priorities as set out at the time of the IPO.
On supply chain, the group has built stock positions to deliver significantly better lead times to consumers for 2022 and beyond as orders placed with suppliers are now in or close to our warehouses.
The progress is based on foundational work already undertaken over the last 12-18 months, focusing on warehousing and logistics. Additionally, supply of goods from Vietnam has now returned to close to normal levels, with all key suppliers now operational.
MADE has continued to make great progress on its homeware proposition and now has more than 100 designer makers, artisans and small brands onboarded to the curated marketplace.
My opinion - even after recent falls, I feel the nearly £500m market cap is too high for me to make a leap of faith that this will become a profitable company in future. I can see why that should be the case, if growth continues, but we don’t know at what level growth would fizzle out, as most companies have a natural ceiling in terms of size, and market share.
So how do we value it? It’s not possible to value it accurately at the moment, it’s guesswork, which is a problem.
The growth story seems intact, even though FY 12/2021 revenues are now being guided 10% less than previous guidance. The reason given of supply chain delays is credible, and should reverse over time, maybe in 2022, which would turbocharge the 2022 results.
Overall, it’s an interesting company, but for me the valuation is still too high.
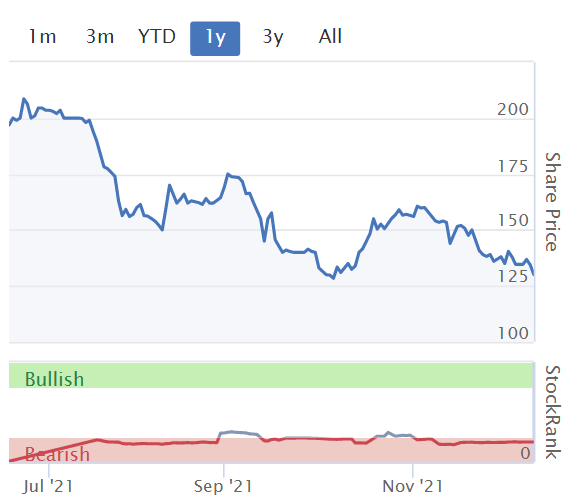
Another over-priced IPO -
.
Victorian Plumbing (LON:VIC)
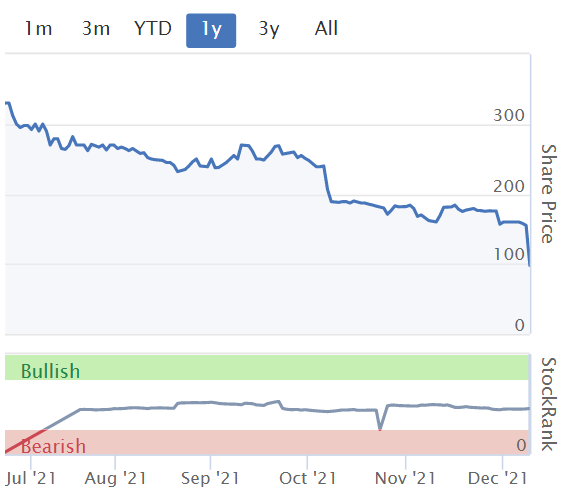
90.7p (down 42% at 09:36) - mkt cap £292m
Full Year Results (FY 9/2021)
This online (“digitally native”) bathroom retailer floated about the same time as MADE, and VIC has also been a flop, losing about two thirds of its value in just 6 months as a listed company. Institutions must be tiring of being stuffed with over-priced, opportunistic IPOs. A lovely gravy train for all the advisers, but are they killing the golden goose? I’d be surprised if there’s much appetite for any more IPOs given the poor performance of so many recent ones.
Here is the slide deck for the FY 9/2021 (which I refer to below) - easier to digest than ploughing through the RNS statement.
Results look really good, so why is the share price down 42%? It’s the wobbly outlook statement, which I’ll come on to, after some key figures for FY 9/2021 -
Revenue £268.8m up 29% on LY (last year)
Gross profit up 42% on LY, due to increased gross margin of 49% (44% LY)
Slide 11 shows massive marketing spend, of £69.7m (26% of revenue) - I like this, because it’s discretionary, although several online companies have recently warned about the sharply rising cost of online marketing, which could be a risk here maybe?
Adj EBITDA of £40.1m, up 53% on LY
Note exceptional costs of £9.4m (probably IPO costs), and £7.7m share based payments
Very good cash generation - see slide 14
Adj basic EPS is 11.0p (LY: 7.4p) - giving a PER of just 8.2 - a bargain?
Balance sheet - what strikes me first, is the very low level of fixed assets - PPE (property, plant & equipment) is only £1.7m, which makes me wonder if warehousing might be outsourced possibly?
Working capital looks OK, with a current ratio of 1.58, and includes a healthy cash pile of £32.7m
NAV is £30.8m, less intangible assets of £2.7m gives a healthy NTAV of £28.1m
Overall, a tick in the box here, with a sound balance sheet.
Cashflow statement - all looks fine, it seems a genuinely cash generative business.
Very little capex this year or last year, we like capital-light business models here at the SCVR, because it means there’s more cash available to pay divis.
Shares issued of £11.2m was primarily to pay £9.1m in exceptional costs of IPO.
Outlook - this has clearly spooked the market.
Slide 26 shows how the company is now struggling to achieve further revenue growth on the exceptional pandemic-fuelled growth of last year - something we’re hearing from many eCommerce businesses.
Investors have to decide whether it’s gone ex-growth, or the 2-year growth rate (bottom graph below) is likely to continue. That’s a tough call - nobody knows. I do worry that it looks as if VIC might now be running to stand still? There again, its massive 26% of revenues marketing spend, means that it might be able to crush the competition?
I’ve highlighted below the things that are a concern - growth has now stalled, gross margins are falling, and marketing spend sounds like it might be rising even more?
.
.

.
The issue with gross margin means that they’re saying it’s likely to drop from 49% back down to 44%. That means an annualised reduction in profits of £13.4m (5% of £268.8m revenues).
I make adj PBT £36.8m for FY 9/2021 (£40.1m adj EBITDA, less £3.0m depreciation & amort, and less £0.3m finance costs)
Therefore, the lower gross margin of 44% would reduce adj PBT from £36.8m to £23.4m - a future fall in profits of 36%
That could be exacerbated by increased marketing spend, which seems to be what they’re saying. The very low PER is now making more sense - because profitability is not sustainable at the reported level, and looks set to fall considerably, as gross margins fall.
The key question is, what is the long-term, sustainable level of gross margin?
Also, is all that marketing spend being spent wisely? Spending £69.7m on marketing, whilst seeing growth slow down to nothing (in the most recent 2 months) does call into question the wisdom of spending so much. It also seems likely that the business would be in steep decline, if it wasn’t spending huge amounts on marketing - not good.
My opinion - I need to caveat this by saying it’s the first time I’ve looked at Victoria Plumbing, and I haven’t read the Admission Document yet.
However, I’ve digested enough from today’s results to realise that the business was clearly floated opportunistically, when it was riding a wave of strong pandemic-related demand, and achieving unsustainably high margins. The selling shareholders are laughing all the way to the bank, having trousered £286m by selling 109.1m existing shares in the IPO, at a price of 262p. The share price is now 99p (down 62% on IPO), having recovered somewhat from this morning’s low.
On balance, I think this share is starting to look decent value, providing you realise that the next accounts are likely to show a sharp fall in profitability. It’s tempting to have a dabble at the current bombed out price of 99p. Although if fund managers are sellers, then the price could remain bombed out for a long time.
.
Jack’s section
Dwf (LON:DWF)
Share price: 110p
Shares in issue: 325,352,865
Market cap: £357.9m
DWF is a global provider of legal and business services. In May, the group moved from its previous five divisions (Commercial Services, Insurance Services, International, Connected Services and Managed Services) into a more simplified structure.
Now, operations are split into three groups:
- Legal Advisory - including restructuring, corporate, dispute resolution and more,
- Mindcrest - outsourced and process-led legal services, and
- Connected Services - a selection of other business services, including forensic accounting and auditing
Together, these support DWF's single ‘Integrated Legal Management’ approach, which combines the services to deliver bespoke solutions.
Shares have been treading water since its rerating after the Covid crash, and they look modestly valued on a forecast PER of 10.1x.

Highlights:
- Net revenue +3.4% to £173.3m,
- Gross profit +7.1% to £89m, gross margin up from 49.6% to 51.3%,
- Adjusted EBITDA up from £24.7m to £31.3m,
- Operating profit of £13.6m, up from a loss of £8.9m,
- Diluted earnings per share up to 2.8p from a loss of 4p,
Revenue growth comes from all three of the group’s businesses. The ‘integrated legal management approach’ of providing services from two or more divisions has gained further traction with a year-on-year increase in both the number of clients and percentage of fees generated. This sounds like a good way for DWF to differentiate itself in the marketplace.
Management is increasing its focus on growth in Mindcrest and Connected Services over the medium term, through a combination of organic growth opportunities and potential M&A. In Mindcrest, the focus is on investing in high quality scalable processes, technology and infrastructure.
The bolt-on acquisitions of BCA and Zing in HY22 have contributed to strong growth in Connected Services. Management has identified further M&A opportunities here.
Free cash flow in the period is down from £19.5m to £4.2m, but this is after the repayment of £5.4m of Covid deferrals, while the prior year was flattered by £10.4m of deferrals. Stripping those out suggests underlying free cash flows have risen slightly to £9.6m. There are still £6.3m of Covid deferrals remaining.
New business
In the period, we were appointed or reappointed to 13 legal panels or frameworks, including Hiscox and the Metropolitan Police. We also won new contracts with adidas and Capita Commercial Insurance Services, along with advising on high-profile cases such as the British Airways data breach litigation.
Outlook
The strong trading in HY22 is expected to continue in the second half of FY22 as the legal sector ‘enjoys sustained demand for services’, with the second half also expected to benefit from the normal marginally higher weighting of revenues.
The board has approved an interim dividend of 1.5p per share. The StockReport expects a total FY22 dividend per share of 6.34p, so either the company is not on course for that or is going to pay out much more in the H2 payment.
Balance sheet
Net debt is £77.2m (HY21: £58.5m). The increase is predominantly due to the repayment of the COVID deferrals, settlement of deferred consideration relating to previous acquisitions, and a one-off outflow for the restructuring of Australia (combined outflow of £24.8m). Net debt is expected to reduce by the end of FY22 to between £65m and £70m.
Aside from net debt, net tangible asset value is actually negative at -£7.2m. The current ratio of 1.46x looks ok, but cash of £24.2m is low relative to current liabilities of £142.6m. On balance, I’d want a stronger financial picture here, particularly given the M&A ambitions.
Conclusion
It has been more than six months since DWF introduced its new operating model, which has reduced costs and enhanced profits.
And the group’s shares seem quite cheap given the trading picture - like-for-like revenue is growing and gross margins have improved, leading to a ‘compelling step-change in profitability’. I’d like to see more substance to the balance sheet in the event that conditions take a turn for the worse, though. That might be what's weighing on the Quality Rank of 40.
Cash conversion also looks quite poor, and DWF does qualify for a short selling screen due to its borderline Z-Score. So the StockReport is flagging some areas to investigate further.

That said, the group does appear to trade at a discount to some of its listed peers and offers an attractive forecast yield of around 6.3%. All in all, it warrants a closer look given the management initiatives, improved profitability, and modest valuation.
A few legal services have come to the market recently: Gateley Holdings (LON:GTLY) , Rbg Holdings (LON:RBGP) , Keystone Law (LON:KEYS) - is that because there is a structural growth opportunity, or do insiders anticipate a market peak? There’s a debate to be had there.
Porvair (LON:PRV)
Shares price: 698p (unchanged)
Shares in issue: 46,169,175
Market cap: £322.3m
My immediate impression here is that Porvair is a quality company that is becoming a little expensive, so it will be interesting to see in the results today if there are reasons for justifying the 26.5x forecast PER and 2.6x forecast PEG.

Revenue and earnings per share have been steadily increasing, with the former up from £68.1m in 2011 to £145m in FY19 (the last non-Covid year, representing an annual growth rate of around 10%) and the latter up from 6.7p in 2011 to 23.9p in FY19 (CAGR of around 17%).
You can see below this has been a respectable longer term hold for patient investors.

The company itself develops specialist filtration, laboratory, and environmental technology businesses. Its divisions are Aerospace & Industrial, Laboratory, and Metal Melt Quality.
This is actually very short now I look at it.
Revenue for the year ended 30 November 2021 is expected to be 8% higher than 2020, with lower aerospace revenue offset by growth in laboratory, metal melt and general industrial segments.
Adjusted earnings per share are expected to be at the top end of market forecasts. Net cash at the year-end is expected to be £10.2 million (2020: £4.9 million) after capital investment, dividend payments and acquisition costs of approximately £9.5 million (2020 £6.5 million). Order books going into 2022 are healthy.
Preliminary results to be announced on Monday 31 January 2022.
Conclusion
The company itself sounds quite intriguing. Given the brevity of the update itself, it’s hard to comment on why the market is ascribing such a high earnings multiple to the stock though. That’s a shame, as it seems as though there’s quite a lot to like here on the face of it.
This is from the half-year results:
Looking ahead, the underlying drivers of growth for Porvair all remain in place: tightening environmental regulations; the need for clean water; expansion of analytical science; the drive for manufacturing efficiency; the replacement of steel and plastic with aluminium; and the development of carbon-efficient transport.
It all sounds positive, and the track record here over the years is encouraging. It’s just a shame that the stock looks so expensive - if I were to invest in such a company, I would want to do so at a point in time where it looks like you might benefit from a rerating as well as earnings growth.
Otherwise I suspect you’re looking to grow in line with earnings (and the 5y CAGR there is 3.86%), or less if there is a contraction in the valuation multiples.
S&u (LON:SUS)
Share price: 2,700p (+3.45%)
Shares in issue: 12,145,260
Market cap: £327.9m
(I hold)
This is a case in point concerning Porvair’s valuation: S&U has as good a long term track record as any small UK-listed company, but the forecast PER is just 10.9x compared to 26.5x for PRV.

FY21 earnings were knocked down a peg by quite conservative provisioning for bad loans. These could, in time, prove to be a tailwind for future earnings if S&U has been overly cautious here.
There are two businesses: Advantage Finance (sub-prime motor financing, by far the bulk of revenue), and Aspen Bridging (property bridging lender - new and growing).
Advantage Finance
Advantage is ‘rebounding vigorously both in profitability and in new business transactions’. There’s been an improvement on the record £38.3m of basic live collections in Q2, to £39.1m in Q3. This collections performance, along with ‘with continued associated lower than expected impairment provisions’, are the main drivers of improved profitability so far this year.
New business transactions have grown by over 30% year-on-year despite the lack of supply in the used car market. Advantage anticipates making increased net loan advances totalling over £140m in the financial year to 31st January 2022 (year to 31st January 2021: £102.6m).
Collection rates are better than ever, as the result of our tightened underwriting over the Covid period and industry-leading customer relations, which are reflected in Advantage's Trust Pilot rating of 4.7 out of 5. This means that customers are repaying at record levels. Those who never took a Covid related payment "holiday" are at 97% of due, whilst even those who did are now back to nearly 94% of due.
S&U is making a significant investment in digital marketing to drum up new business. It has also made customer journeys easier, with automated payments, open banking, and a self-service customer portal.
As a result, with the foundations of over 22 years of excellent profits and operational efficiency, Advantage is positioned for the great opportunities a fast-changing motor finance market presents.
Aspen Bridging
In less than five years, Aspen has grown its receivables book to over £60m. This is more than double last year, and transaction numbers to date are 38% up on a year ago.
S&U credits an ‘excellent profit increase in the period’ to maintaining margins in a competitive market and robust quality control. Levels of default are low and customers are settling within or just beyond the normal term of the loan.
Business volumes are increasing, and the group notes a significantly improved transaction to approval ratio. ‘This augurs well for the significant expansion planned over the next three years’.
Conclusion
I think the stock is mispriced at the moment and will likely rerate over the next three years, assuming stable market conditions. Earnings per share are set to fall slightly in FY23E, from 260p to 257p, but I suspect there is a better-than-average chance of realising long-term, sustainable earnings growth here. All in my opinion, of course.
The Coombs family runs S&U with a steady hand and prudent finances, which makes the growth prospects more enticing.
It’s also worth noting that the company is committed to paying out dividends, so this could be of interest to income investors at the current forecast yield of 4.91%.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Excellent FY results from Renew Holdings (LON:RNWH) this morning with all the important metrics well in advance. Braced by high public spending and accretive acquisitions this company could fly over the next 3-5 years. Not a sexy growth company but with a sound balance sheet and ROCE over 25% what's not to like.
I hold
Hi Steves cups,
I've got to pick you up on this bit about £RNWH -
... with a sound balance sheet...
RNWH actually has a weak balance sheet, with net tangible asset value (NTAV) negative at £(44.1)m
It might be that the group can function fine with a weak balance sheet, due to negative working capital. But that's not the same as having a "sound" balance sheet!
Impressive company though, and a major multibagging share over the long-term. I've done a short section on RNWH in tomorrow's report.
Regards, Paul.
Supreme (LON:SUP) ( I hold)
Apologies as not pertinent to today's news but i have just watched the Supreme (LON:SUP) investor webinar . I was very impressed with both CEO Sandy Chadha and CFO Suzanne Smith, both appear to be very smart and know the business inside out. I really like the business model, very simple and fairly easy to bolt on new products . I also liked the feeling that there was no Bulls##t and jargonese just a lot of common sense. I agree with some comments about preferring to see money reinvested rather than paid as dividends and Sandy's honest answer that this was possibly a mistake made at IPO with Income Funds showing interest. I only have a small holding but will look to increase now.
Richard
re Supreme (LON:SUP) - Paul said on Tuesday "The CEO Sandy Chadha comes across particularly well on webinars, in my view - an energetic, proven entrepreneur - which is what I look for".
I agree with him and you - excellent presentation void of 'management speak'. If only one or two of the initiatives talked about come off I think we could have what is known as 'surprises to the upside'. The recording is available here:
https://www.equitydevelopment....
Supreme (LON:SUP) - Shares magazine today:
The UK could soon be the first country in the world to licence e-cigarettes or vapes as a medicinal product available on prescription in an effort to help people stop smoking.
To get a licence, products would need to meet the MHRA (Medicines and Healthcare Products Regulatory Authority) standards of safety, quality and efficacy for medicinal products, following which doctors could decide on a case-by-case basis whether prescribing an e-cigarette to NHS patients would help them to quit smoking.
May be useful in delivering CBD products as well.
I have to say that I felt Sandy came across as a little bit flaky this time. The CFO comes across as really smart - you wouldn't be able to get anything past her! Perhaps the combination of a slightly dreamy (albeit full of good ideas) CEO and hard-nosed CFO is a good one! One thing I did notice was that without the acquisition, there would have been very little profit growth. I continue to hold but am slightly more sceptical than I was.
Porvair (LON:PRV) This share seems to have been expensive for a long time I first bought just after the”Financial Crash and have held ever since. I have topped up on several occasions but have always felt that it was expensive. It’s a company that has a clear moat with strong customer bonds. It ticks most of my boxes and is on my permanent watch list for topping up but it is expensive at the moment
Quiz getting hammered today ? Covid lockdown worries or some profit taking after good results .
Available to by 16.7p region - Couid be a decent dip to buy ?
Any thoughts
Quiz (LON:QUIZ)
I think the lack of specific clear guidance ref year end was unhelpful - if they are now back into profit exepcted ye 31/3/22 and next year i would like the company to be shouting that fact from the rooftops either directly or publically available broker forecasts. I wasn't really that impressed by the numbers they released - although i wansn't really expecting to be impressed for the reasons outlined by paul - ie not clean 6 months of trading. To make clear further progress ref shareprice increase i would like to think tgey should be delivering clean profits of 2.5 mill to 3 mil soon (ideally now) - i am on the fence as to whether that is acheivable. If price does shoot up to 24p again on no news i think i would sell what i have (very modest holding) - on no news i am not really expecting shareprice to do anything but drift aimlessly.
re Victorian Plumbing (LON:VIC) - seems to be the topic of the day. I have recently spent rather more of my life than I would wish trying to buy things like taps and tiles. so I thought I should comment. Victorian Plumbing (LON:VIC) have one of the better websites in this market, and it is impossible to do a google search for any sort of bathroom fitting without ending up on it, so they seem to be well set up for the online world. Secondly I didn''t actually buy anything from them. Thirdly, bathroom fittings is obviously a fiercely competitive market, so they will have to fight for any growth. Personally, I could see a PER of say 14 being justified, but not 20.
Like Paul I am getting up to speed on Victorian Plumbing (LON:VIC) having not looked at it before today. While it looks like earnings could take a bit of a hit in the short term due to lower margins and tough comparatives going forward, I do not think this is ex-growth. Plenty of charts in the presentation show long term track record of growth, in particular how they've grown market share from 3% to 14% since 2015, so with plenty more to go for. Sunny Trader is correct that this is a very competitive market, but I guess this is where scale advantages come in and as now one of the larger players they should be well placed to take market share and squeeze out smaller competitors. Definitely getting more interested at these levels.
The market share chart (slide 5) is interesting in that it reveals that the four largest plumbing have consolidated the market & control nearly 60% of market share (B&Q own Screwfix & Victorian Plumbing (LON:VIC) own VictoriaPlum.com).
This slide also reveals market maturity with anticipated growth of just 3% p.a.
Homebase is up for sale - it will be interesting to see if the purchaser disrupts this market.
Nice. Victorian Plumbing (LON:VIC) is only potentially good return-risk position once its had a period of fundamental (not just price) puke. Until that point its hard to know what you are buy in terms of future financial characteristics
Hi Paul, You commented on Seraphine Seraphine (LON:BUMP) after a profit warning in September (2 months post IPO). Half year results today. at first glance they look promising to me and the share price is well below where it fell after the September warning. And you did say you would have another look when there were some results .....
Hi Clementwether,
Sorry there were too many companies reporting today for me to cover all of them, so we picked the most interesting ones.
Regards, Paul.
Victorian Plumbing (LON:VIC) almost feels like the big fall was automatically triggered by some sort of algorithm due to the drops in profit. Closer inspection shows adjusted EPS (stripping out IPO costs) actually increased significantly from 7p to 11p.
Worth checking out the results presentation on the their website. Plenty of charts demonstrate this is a rapidly growing business with and long term track record and an increasingly dominant position in their field.
If you are happy with the adjustments being one off, then this now surely look very cheap (under 10 PE) for a growth business.
Anybody know the reason behind the declining SP of Revolution Bars (LON:RBG)?
I would suspect the prospect of further lockdowns / use of covid pass to enter premises
The market wants to offer us a better entry price for Revolution Bars (LON:RBG) .
I hold and I'll top up when I feel the selling has slowed
Vertu Motors (LON:VTU)
Very happy with the results here, been a great winner for me. Happy to exit my position this morning - There's a good chance the next update will be to confirm profits/margins beginning to normalise. We've had a fantastic run, was time for me to convert from paper to real profits!
Rather startled at the price fall in Victorian Plumbing (LON:VIC) which is down 40% as I write.
The trigger seems to be a pre-tax fall in profits of 17% but that masks a 49% adjusted eps rise where the adjustments are for the cost of the IPO and share related remuneration which appears to have been triggered by the IPO. Those look like genuine one-offs.
FY revenue up 29%, Gross Margin of 49%, supply chain issues under control, outlook appears to be fine. The founder's family still has over 50% of the shares so no issue with shareholder alignment.
https://www.investegate.co.uk/...
Dunno, maybe I'm missing something but I don't see how this update equates to a 40% fall.
timarr
totally agree timarr. More market madness!!
Victorian Plumbing (LON:VIC)
35% fall takes forward multiple down to 12ish which is not dissimilar from where other businesses are that have similar or better margin levels and growth forecasts? Immediate trading outlook is generally uncertain and probably acutely so for retailer to home improvements at the higher costs and work end of the market.
I'd guess that any growing sense of uncertainty and/or a cautious trading outlook early in 2022 could see price down more particularly as its a new listing. In addition, ownership is very tight and I'd guess quite PI orientated in free float which is bound to make for headwinds in current environment.
All that said, it looks like at least 'decent long term value' today...but decent isn't exciting enough for business this size and ownership structure. Why in your opinion is this a good long term prospect? They seem locked into UK centric world without risking significant capital in overseas adventure? They've had 20 years of good growth before listing...is this nearer the end of that trajectory as they saturate demand and the listing is to enable the next leg (ie raising capital or it)?
Drive by banalysis clearly from me.
Victorian Plumbing (LON:VIC)
Doh just lost a very long post here -ok lets cut to the chase
Looks obvious to me drop is solely due to subtle downgrade on sales , margins and profits for new year just started - i would expecxt broker updates from today will confirm this is a subtly worded stonking profit warning for year just started.
No excuse for this company not directly addressing the issues here - they should have updated the market in line with the approach taken by next in their year end financials (and every update next do)
this is how it should be done
In the first eight weeks of the year, Online sales have been stronger than expected and are
up more than +60% on two years ago. This overachievement plus the expected transfer of
sales from Retail during the additional two weeks of lockdown, are expected to add £30m of
profit. As a result, we are raising our central profit guidance by £30m from £670m to £700m.
my reading of the news today translated into as precise made up estimates as possible along the lines of how it should have bene done is as follows.
ref 2022 We now exepect sales to be in region of 260-290 mill from 300-330 previously expected consensus estimates. We now expect profits to be in region of 24-27 mill from 27.5 mill to 31.5 mill previously per consensus estimates.
You will have to replace my made up numbers above with the consensus of broker updates made dated today or later! guesing i wont be a million miles off though.
Based on my guesstimates thats a proper profit warning ref new year and that is the reason for the decline.
I don't get it - Victorian Plumbing (LON:VIC) - if you treat the adjustments as genuine one-offs (£17m in IPO costs and share based payments then the underlying EPS is 11p - so a current p/e of 9 (assuming a share price of a £1 which is about where it is now) ? No debt and well aligned management with credible growth ambitions. Even allowing for a bit of softening in the market that seems too cheap. Just taken a small opening position, which I had no plans to do.
Worth noting that it had already fallen 50% since listing before this morning's fall. Will definitely need to take a closer look now, as seems to be an interesting business.
Victorian Plumbing (LON:VIC) the fall to 85p, does look overdone, considering the shares were 340p not so long ago, that is a fall of around 75%. Shares are currently around 95p, I have opened a small position today. IPO expenses seem to masking the true figures.
Victorian Plumbing (LON:VIC)
Has anyone seen updated broker forecasts yet for 2022 ? in the absence of useful info from company until we see what the brokers are now saying i don't see how we can be certain that this is a bargain - must admit the price reduction does seem over harsh but should be rightly expected based on the useless update from the company themselves today. Would this really be cheap if pe is 15 at 90p and they are now ex growth with margin issues?
IPO expenses seem to masking the true figures.
They wont be masking the 2022 estimates though will they - so we are now into clean numbers ref new year i am presuming.??
RE: Victorian Plumbing (LON:VIC)
Would this really be cheap if pe is 15 at 90p and they are now ex growth with margin issues?
Well if Paul is right about the future profits then I think the forward eps is 7.2p which makes the PER about 13. Which would seem a little high. On the other hand if they can drive revenues then they could beat that.
Basically I don't think it looks cheap based on what we can see, but I haven't yet had time to do more than look at the headline numbers.
Of course, as Radcliffe and family still own over 50% of the stock there probably isn't a long term issue here, but who knows?
timarr
Made.com (LON:MADE)
Excellent stuff Paul , this company has appealing characteristics to me in that they seem to have a reasonably clear vision of where they want to be in 5 years time and they should be very profitible at that time if their plan is to be believed. So they seem to have their niche and certainly the rate of growth in their sales is not to shabby by any means. I also quite like the simple business name - lets hope they don't have a silly corporate idea of revesrsing the letters to make a different unique name that bears no relation to the name (old joke what is the only cheese made backwards?) I guess they would say at the time of float "we will dominate the planet" so its healthy to be skeptical
So to me on their clear niche , branding and decent sales growth and the numbers looking ok under the tin (high marketing at present explains losses). They have some of the characteristics franchise rollouts if most bods still don't know they exist at present (i have never heard of them till they listed which suggests the uk is reasonably untapped market at pressent for them). Once you get big enough then you do have the potential to sell yourself without paying for new customers..
I currently don't hold - it looks way cheap if we say they are on track to make nearly 100 million a year profit by 2026 self funded -(4 bagger potential from here) but they are so far off that level at present that its all guesswork as to whether they meet their long term ambitious plans. I think at present if one wants to protect ones capital sitting on the sidelines in not not sensible.
Will be interesting to see if brokers take a hatchet to future years growth expectations despite the company remaining fairly upbeat today. They really do need to keep the growth numbers above 25%+ each year to remain on track - no mean task as sales continue to grow.
Pretty subdued response to the Vertu Motors (LON:VTU) update so far after an initial gap up, wonder if this comment is making people think the bonanza is slowing down?
Used car also supply constrained, values high, but have plateaued - “starting to follow more normalised seasonal trends”
My working target has been 80p, but maybe price needs to consolidate for a while before getting there. Still looking strong.
Another profound thought from Paul Scott today: " most companies have a natural ceiling in terms of size, and market share", something well worth bearing in mind before buying a share near peak. Thanks Paul for this reminder.
Jack, regarding the quoted legal firms I think it has been a very slow and cautious response to the 2007 Legal Services Act that for the first time allowed non-lawyers to own or manage UK law firms.
Not entirely sure the market’s reaction to the update from Made.com (LON:MADE) is entirely warranted, any thoughts?
Made.com (LON:MADE)
Simmo1a
Not entirely sure the market’s reaction to the update from Made.com (LON:MADE) is entirely warranted, any thoughts?
It's tricky - they have such high expectations (necessity?) for growth to justify the prior/current pmarket cap that obviously the market will destroy them if they fail to deliver at any stage as their whole valution is based on high compounded growth for next few years.
Having said that the reasons for them being where they are at now seem genuine in that its circusmtances beyond their control that they could be forgiven for not having seen this coming 6 months ago. The story does also sem intact overall.
Facts are though if this is a profit warning passing the buck by making excuses that it will be alright on the night does take away from their credibility somewhat. I will sort of give them a pass here but i fully understand why the market does not - and at present ref next update is it more likely to be stonkingly good news or more ongoing issues hindering growth? - i always like companies to under promise and over deliver so that i am not left holding the can ref failed promises.
thanks. I have conviction in the business’s prospects and have bought more this morning thus averaging down on price. The market seems to be almost exclusively focussed on the here and now at the moment - pretty much all of my growth stocks continue to get battered. “Santa Rally?” Yes please!!, and I will certainly be raising a glass for a positive 2022!!
Made.com (LON:MADE) (no position)
Hi rmillaree
You said:
"Having said that the reasons for them being where they are at now seem genuine in that its circusmtances beyond their control that they could be forgiven for not having seen this coming 6 months ago. The story does also sem intact overall."
Whilst I agree that companies would have found it difficult to plan for the current issues 6 months ago, I certainly would expect companies updating in September to have provided more accurate guidance.
Made.com didn't really do a good job in this respect.
When I worked through their expectations at the time I couldn't understand how they were going to hit their revised targets. Or maybe I just got lucky with my workings, which I've included below for any interested.
Note the implied increase in returns/cancellation rates in H1.
H2 is of course just me guessing, though the £66m deferred revenue I'm now expecting for H2 does tie in with their updated guidance today.
In the long term, I'm sure they'll be fine - and I do have an intention to buy at some point - but I am put off by the poor communication from just a few months ago.
---
With regards to today's updated EBITDA guidance, there must be some serious cost increases in H2.
I imagine this is being driven by either even lower gross margins than the already depressed levels seen in Q2, or higher marketing spend.
Either way, I think there's going to be something unexpected when the market is updated in early January.
Cheers
A
Made.com (LON:MADE)
Cheers abtan - (for once) i pretty much agree with everything you say here - love your tables they really do put the companies that report waffle to shame - how hard would it be for them to knock up something with good bad and indifferent forecasts when they update shareholders.
With regards to today's updated EBITDA guidance, there must be some serious cost increases in H2.
I think thats highly likely i was speaking to someone who had delayed getting a mini extension after going to the touble of getting a quote and when they went back recently the original quote was revised up 50% higher so if they are keeping any semblance of margins that arent beyond awful short term that ensures sales are maxed out from cashflow they have available then i would expect them to make grim reading but be necessary evil.
I think you predictions about things getting tougher near term may prove to be spot on. -just look whats happened to victoria plumb today.
Thanks Jack for report on Dwf (LON:DWF) - reminds me - what happened to Ince not so many weeks ago...? Shame they had a brilliant reputation in the past......
Cloudcall (LON:CALL) Don't like ignoring a gift horse but I agree and will hold on for the moment. A lot of the major shareholders have obviously declined to make any undertaking. The bid is pitched at exactly the level they last raised capital in March this year which strikes me as a minimum rather than a maximum the long-suffering shareholders should expect.
Cloudcall (LON:CALL)
Nightmare decision to make here - if shareholders think current management can deliver more shareholder value than this offer i would suggest mr market will brutally take the exact opposite viewpoint if this offer is rejected. But now they are in play with decent product it does concentrate the mind of any other rivals who could really be improved by having this product in their armoury. I cut my losses here years ago thankfully - if i held now i might just wait long enough for another bidder to pop up quickly but not long enough for there to be sketchy close called vote to approve (or not approve) this deal that may fail - perhaps otehr shareholders will all quikcly fall in line to approve once they realise no other bids are coming in?
Re Vertu Motors (LON:VTU), Andy Brough refers to the motor retailers in his latest PIWORLD interview. Very candid interview by Andy giving his thoughts and insights on 2021. Video & podcast. Worth a watch, lots of stocks mentioned including Reach (LON:RCH) Future (LON:FUTR) Lookers (LON:LOOK) Inchcape (LON:INCH) Grainger (LON:GRI) Royal Mail (LON:RMG) Land Securities (LON:LAND) Litcomp Ord (LON:LIN) Frasers (LON:FRAS) Studio Retail (LON:STU) Tremor International (LON:TRMR) Indivior (LON:INDV) De La Rue (LON:DLAR) And, if you'd like to take part in Sell it to The City, listen to the end to get tips of what Andy and the team are looking for, and contact me via piworld.co.uk
Separately, a short Wh Ireland (LON:WHI) H1 results overview by CEO Phillip Wale. The key highlights showing the turnaround starting to yield results. Video & podcast.
Great interview Tamzin. Very informative. I was pleased to hear Andy’s comments on Indivior (LON:INDV) (I hold). I have a similar belief that their products could become more widely used to try to stop addicts leaving prison and going back to drug fuelled crime.
COG contract
Very welcome news indeed. I suspect Paul, that as well as the general falls in the market, part of COG's share price fall is down to the CFO leaving without explanation on 2nd Nov. Hopefully some positive news soon on a good replacement....
Simple inline trading update from £RM this morning. (I hold).
In theory £RM should be well placed to benefit from the catch up agenda in schools (which they do acknowledge is happening). Share price looks good value to me on several metrics and qualifies for the neglected firm screen.
Assuming schools remain open and exams happen then I believe £RM should return to its pre pandemic high.
There is a footnote to the Rm (LON:RM.) update saying:
"RM expects that certain costs that were previously being
capitalised relating to the Group's digital and automation investment
programme will no longer qualify for capitalisation and will instead be
expensed"
They expensed £7.9m of R&D last year and capitalised about £3m, and for context it was £13.4m unadjusted PBT.
Difficult to work out the impact, but even if the cashflow doesn't change it will dent the E side of the P/E ratio?
Agree that it’s hard to work out the impact of the accounting changes but they say that cash will not be affected. I assume that it just changes when they pay tax. I’m sure the accountants could give us chapter and verse.
£RM should be ideally placed to capitalise on increased spending in schools and the move towards using technology to enable teachers to do more with their time. However I agree with comments below that the share price seems stuck in a range and waiting for a change might represent a lost opportunity.
I’ll probably hold for now but sell if I feel the cash can be better deployed elsewhere.
Agree that all the Stockopedia metrics look good for Rm (LON:RM.) and have done so for quite a while. I have held Rm (LON:RM.) since July 2018 buying at 241.5p so even with the pretty meagre dividends I am still looking at negative return. Rm (LON:RM.) did touch over 300p in November 2019 but the 1st Covid lockdown inevitably crashed the price by 50%+. It has recovered from that but still seems unable to breakout from around the 190- 200p level. This mornings reference, as noted by Monty Carlo, to additional revenue expense due to a change in capitalisation policy didn't help sending the share price down by c. 5%. Despite the solid metrics I really can't see where any future potential is going to come from and Rm (LON:RM.) is likely to exit my portfolio. There must be better opportunities in the small caps world after the recent pull back for that segment of the market.
No bumpers for Clipper Logistics (LON:CLG) reporting a good set of results. I hold.
Tekcapital (LON:TEK) 'some news about crisps'... thank you for making me spill my coffee :)
Good results from Renew Holdings (LON:RNWH)
Strong organic revenue growth of 19 per cent, underpinned by
continued positive momentum in Rail business, along with framework wins and
operational progress across diverse Engineering Services business
Full year dividend of 16.0p per share reflects Group's strong
cash generation and positive outlook