Small Cap Value Report (Thu 9 Mar 2023) - WAND, TTG, GFRD, JIM, IQE, NWF

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
I'm still reeling from the bombshell announcement of fraud at WANdisco (LON:WAND) - that's about a 10% hit to my portfolio. Once I can gather myself together, we'll start working our way through this list.
Update at 12:40 - I think we'll leave it there for today.
Paul’s Section:
NWF (LON:NWF)
Up 7% to 275p
Market cap £136m
Trading Update (significantly ahead)
NWF Group plc ('NWF' the 'Company' or the 'Group'), the specialist distributor of fuel, food and feed across the UK , today provides a trading update for the current year ending 31 May 2023.
A lovely update today -
Whilst final quarter trading continues to be subject to seasonal factors, the strong year to date performance together with the supportive backdrop entering March means that the Board now anticipates the Group's full year result to be significantly ahead of market expectations1 with full year headline profit before tax2 not less than £17.5 million .
1. Company compiled consensus headline PBT of £12.3 million; information for investors including analyst consensus forecasts, can be found on the Group's website at www.nwf.co.uk
That’s a lovely, substantial beat against forecast.
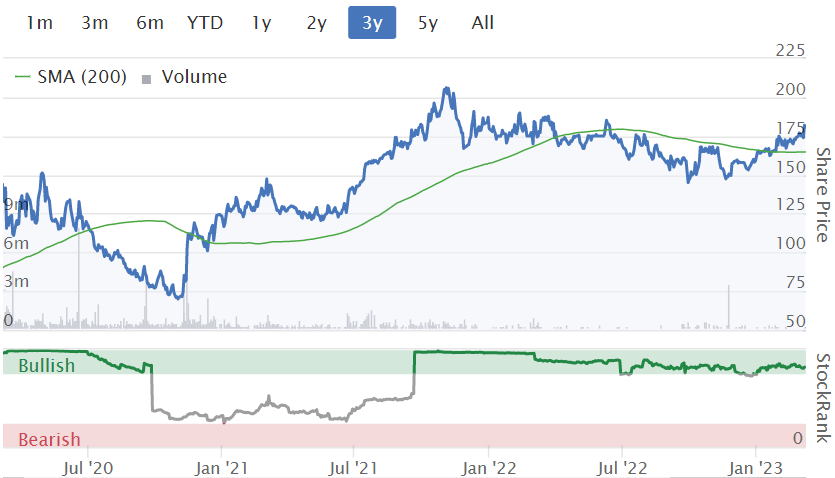
Looking at my SCVR summary spreadsheet, it says that on 1 Feb 2023 we flagged “NWF 225p - record H1 results to 11/2022. Outlook v confident - a beat coming?”, but annoyingly I cannot find the actual article here with that in it, which seems to have disappeared. I rated it green anyway. Previously Graham was only amber on 22 Dec 2022, despite H1 results being ahead of expectations, a bit stingy!
Today’s substantial beat against expectations should bring down the forward PER, once analysts have updated their models. The valuation looked reasonable beforehand, so the PER should now drop further, down to about 10 perhaps?
My opinion - remains positive. The shares have gone up a lot recently, which looks based on a firm foundation - providing of course that higher profits are sustainable, which they might not necessarily be - note that similar competitor Wynnstay (LON:WYN) recently posted superb figures, but emphasised that the big profit was one-off in nature. So that would need careful checking, to reassure yourself that you’re not buying into a spike.
We’ve discussed here before (writers, and reader comments) that NWF has a very solid long-term track record, and is a reliable dividend payer too. So it looks a decent value share, and more so after a lovely update today.
Stockopedia loves it, with a StockRank of 98.
£IQE
Down 31% to 32p (mkt cap £260m)
Trading Update (profit warning)
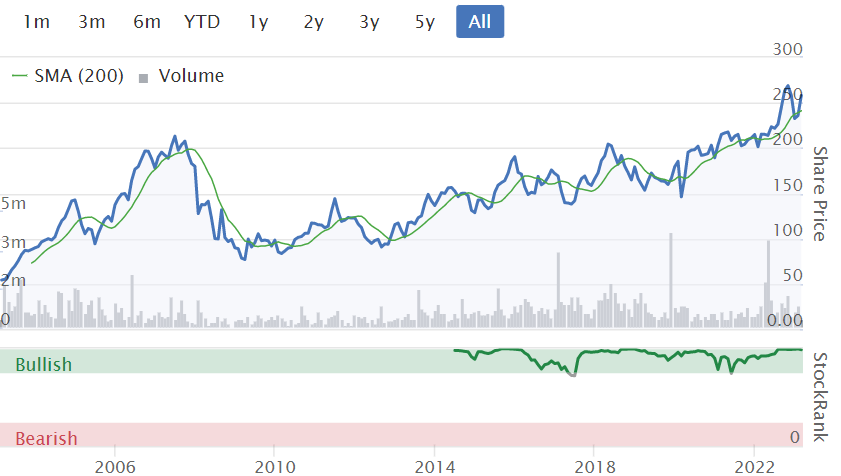
This company makes products for the semiconductor industry. Shares have now given up all the recent "everything rally" gains, and are back down to similar lows as last autumn.
Today it says that FY 12/2022 results are unchanged from the update on 16 Jan 2023.
The problem is with FY 12/2023 -
Weaker demand in H1 2023, with revenues expected to be £30m down on H1 LY (which was £86.2m revenues), implying a 35% drop to only £56.2m revenues in H1 2023. That’s awful, because it was loss-making in H1 2022, so apply a 35% revenues drop, and that suggests a hefty loss is likely this year.
This drop in demand (which it says is sector-wide) is temporary, and should return to growth in H2 2023 (based on talking to customers, and the pipeline).
Outlook - it says growth will come in 2024 from diversifying into new products, which to me implies that the existing products are a dead loss.
My opinion - I was negative (red) on this share previously on 16 Jan 2023, and today’s update just reinforces that negative view. I cannot see any attraction to this share whatsoever, and it still looks greatly overvalued. Is it a viable business at all, I wonder? Looking through the last accounts again, IQE strikes me as a capital-intensive business model, that doesn’t actually generate any returns from its assets. Shareholders get nothing in divis, as there’s no free cashflow being generated, over the long-term.
I cannot imagine any reason why anyone would want to hold this share. There's not even any jam tomorrow excitement that I can see.
WANdisco (LON:WAND) (I hold)
1310p (shares now suspended)
Market cap £906m
WANdisco (LSE: WAND), the data activation platform, provides the following revision to its anticipated trading performance and financial position.
An absolute nightmare announcement to wake up to here. The worst possible scenario has just been announced - that the growth in sales orders & revenues looks to have been fraudulently misstated, supposedly by a senior sales person -
Following investigations undertaken by the CFO and CEO, and as reported to the Board of Directors of the Company (the "Board"), significant, sophisticated and potentially fraudulent irregularities with regard to received purchase orders and related revenue and bookings, as represented by one senior sales employee, have been discovered. These irregularities give rise to a potential material mis-statement of the Company's financial position.
It gets worse -
The identification of these irregularities will significantly impact the Company's cash position and lead to a material uncertainty regarding its overall financial position and significant going concern issues.
The Board now expects that anticipated FY22 revenue could be as low as USD 9 million and not USD 24 million as previously reported.
In addition, the Company has no confidence in its announced FY22 bookings expectations.
As a result, the Company has requested that its shares be suspended from trading on AIM while it conducts an investigation with its external legal and professional advisers into the nature of this activity and its true financial position.
My opinion - Well that’s it. This is so bad, that it’s probably game over, or not far off, for this share. The £900m market cap was entirely based on the impressive bookings growth that I’ve been reporting on here since last summer. It never occurred to me that the contract wins could have been bogus, but that now appears to be the case.
The big question is whether it was really a salesman acting alone, and if so, how on earth was that not picked up earlier?
The CEO was in the City only last week, talking to investors, super-bullish, talking about a US listing, and expecting to achieve sales of c.$100m this year, rising to $500m fairly quickly. I mentioned here that he was incredibly bullish, but it now appears to have been hot air.
Unfortunately holders here will, I suspect, have to brace for a 90-100% loss on this share.
Sceptics were right to be sceptical. What a disaster.
Galliford Try Holdings (LON:GFRD)
182p
Market cap £196m
This is a building & infrastructure group, focused mainly on public sector projects - which is probably quite a good place to be, in times of uncertainty over private sector projects.
I ran through the H1 figures yesterday, here are my notes of the main points -
H1 revenue £679m (up 14%)
PBT is up 65%, but tiny as a percentage of revenue at just £11.7m
FY 6/2023 profit expected to be at top end of expectations.
Doing share buybacks.
Good divis of about 5% yield
Big order book of £3.5bn
Good visibility, with 95% of FY 6/2023 revenues secured, and 79% of next year.
Average month end cash of £154m, but this is an illusion, as it’s more than offset by huge creditors. So none of it is surplus cash, it’s all arisen due to timing differences (getting paid in advance by customers). So be careful attributing too much (if any) value to this cash pile of customers’ money!
There’s some value to PPP investments.
Balance sheet is quite good, with NTAV £127m.
A fair bit of dilution from options, total 8.0m shares (108m shares currently in issue).
Note 13 - I draw your attention to a large legal dispute with a customer, which introduces uncertainty. I don’t fully understand what risk:reward here is, but want to draw it to your attention anyway - companies are always confident about their own position, but courts don't always agree, so this would need careful scrutiny before buying any GFRD shares.
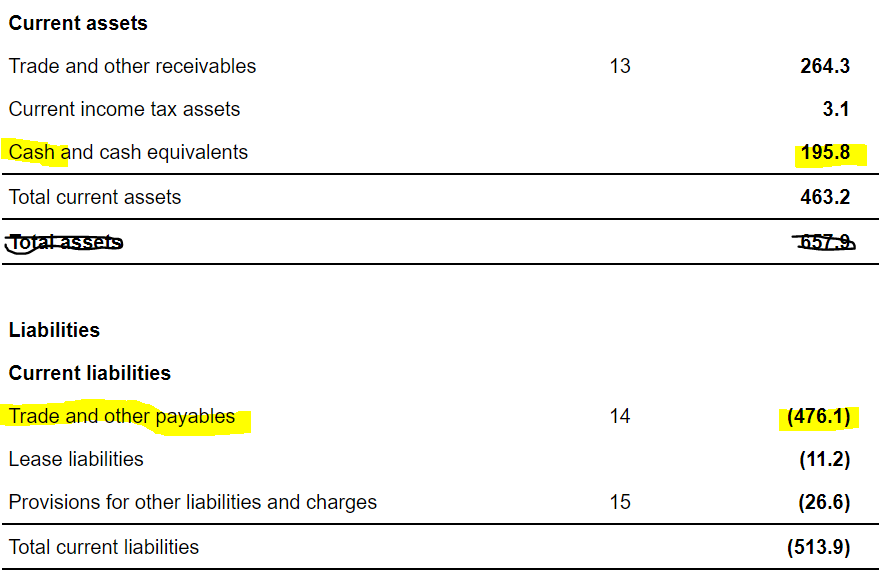
Working capital - to demonstrate how the cash pile is more than offset by trade creditors, here are the numbers -
.
It’s important to understand the above working capital position. As you can see, current assets total £463.2m, which is cash, and things (mainly receivables) that will turn into cash shortly.
But current liabilities (i.e. cash that will be going out) is higher, at £513.9m.
The net position on working capital is therefore actually a deficit, of £(50.7)m.
So the big £195.8m cash pile is not actually surplus cash, it’s just cash that GFRD is temporarily sitting on, due to the timing difference of money coming in before it goes out again.
That’s a nice position to be in, providing you can keep those plates spinning.
In a wind-down type of situation, if you imagine that the business suddenly stopped operating, then that working capital would all unwind into cash, leaving a £50.7m shortfall.
Now that’s not going to happen, but it does highlight the risk, if for example, new contracts do not involve such generous payment terms as previous contracts. It’s a risk, that the cash pile could melt away, if contract terms became less favourable in future anyway. For that reason, I would attribute little, if any, value to GFRD shares from the cash pile.
My opinion - on a positive view, GFRD seems to be trading well, and says that it wants to raise its tiny profit margin in future, which could trigger a re-rating if successful.
On a negative view, it’s taking on complex contracts, and only eking out a miniscule profit margin. So the risk of even one big contract going badly wrong, could easily wipe out profits.
Not many people invest in this type of low margin contractor, because so many of them have gone bust in the past. I don’t touch this sector personally, but there’s nothing obviously wrong with GFRD, and performance has been better than last year, so I’ll view it as neutral (amber).
Also, it could earn interest on the cash pile in future, which might boost profits.
Stockopedia's computers like it, with a high StockRank.
Graham’s Section:
TT electronics (LON:TTG)
Share price: 204p (+3% yesterday)
Market cap: £360m
This manufacturer of electronic components reported numbers for 2022 yesterday, which were ahead of expectations.
Unfortunately, there are no broker notes for TT on Research Tree. TT is a main market-listed company whose brokers are Numis (LON:NUM) and Barclays (LON:BARC) .
However, according to Stockopedia, the adjusted EPS estimate for 2022 was 16.5p. TT produced adjusted EPS of 18.2p yesterday.
Key points:
Revenues +22% at constant FX to £617m
Adjusted operating profit +19% at constant FX to £47.1m
Adjusted PBT +13% at constant FX to £40.4m (market expectations were previously £35.4m - £39.8m)
The growth percentages are all significantly higher if you don’t adjust for currency fluctuations, as the company benefited from its international exposure.
Unfortunately, there are some other major adjustments to these figures as certain costs were kept away from the headline numbers. These costs add up to over £50m and include:
“Restructuring and other” - £20m
“Asset impairments” - £23m
“Acquisition and disposal related costs” - £7m
The quickest way to check if the exceptional items are truly exceptional is to see what they added up to in the prior year.
In the case of TT, they added up to £15m last year.
If we go back one more year to 2020, they added up to £20m.
I would therefore be inclined to treat c. £20m as the baseline figure for the adjustments we should normally expect, until TT starts to produce cleaner results with fewer adjustments than that.
If we took the view that £20m of the exceptional items were therefore non-exceptional, then adjusted PBT becomes only £20m, not £40m. You don’t need me to tell you that’s an important difference!
The really unusual item was the impairment of the company’s Internet of Things Technology Products business:
This impairment is shown within the Power and Connectivity division and is linked to an increase in discount rates, coupled with revised forecasts for the business in the context of a weaker macro-economic environment and impact of the evolution of the COVID pandemic on the potential demand for COVID testing.
Looking further into the small print, the company warns that additional impairments of this business may be required in future. It still has £10m of goodwill on TT’s balance sheet.
Overall, TT has goodwill of £155m and other intangible assets of £54m on its balance sheet. After excluding them, tangible equity is £88m.
Let’s get back into these results and try to understand company performance a little better:
Book to bill ratio 118% - excellent order intake, replacing fulfilled orders.
Adjusted operating margin of 7.6%, up from 7.3% last year.
Organic revenue growth is 20%, most of which is driven by higher volumes rather than price increases.
Return on Invested Capital up 140 basis points to 10.5%.
Outlook sounds bullish:
“Continued order momentum through Q4 resulting in circa 90% of planned 2023 revenues covered at the end of December…
Strong free cash flows and a continued reduction in leverage expected in 2023
Disciplined approach to pricing of the order book, continued growth of the business and actions taken in 2022 underpin our confidence in further progress in 2023.”
The CEO comment mentions “unprecedented visibility” thanks to the strong order book.
Leverage reduced to 2.0x, as planned and as promised. It was 2.4x back in June 2022. The company’s target range is 1.0x-2.0x.
Net debt at year-end was £138m.
I suspect that excessive leverage was partly responsible for this stock’s sell-off last year - see my comments in November. TT is confident that leverage will remain on a “downward trajectory”, “as EBITDA increases and as we deliver a material step-up in free cash flow in 2023”.
My view
TT has done as I hoped it would. It has kept up its order momentum and succeeded in reducing its leverage multiple. It has thereby, in my view, proven that the sell-off in H2 last year was unjustified.
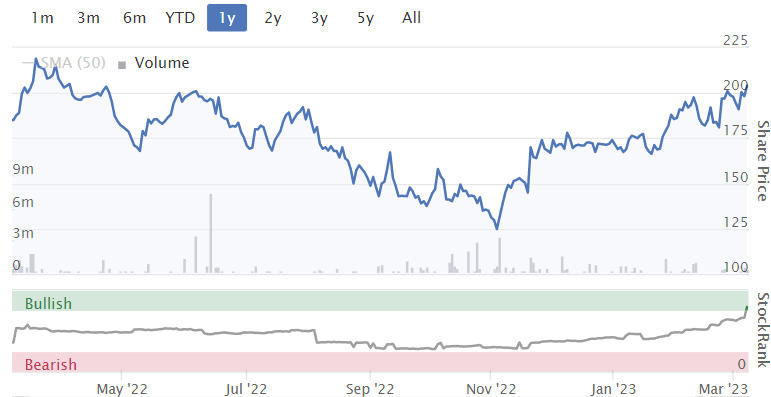
Does it still represent good value at this level? Well if you go by the earnings estimates, it’s still cheap:
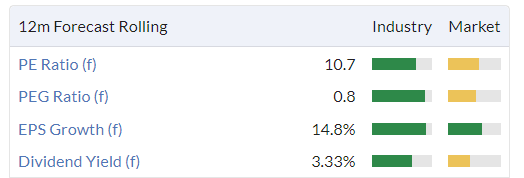
However, when you consider the significant adjustments involved in the earnings, the value is more questionable.
And the debt burden, while under control, is another factor that investors need to allow for.
I’m tempted to switch my rating from Green to Amber, on valuation grounds, but there is an old saying about letting your winners run. I can’t fault this company’s recent performance. So I will let it stay Green for now.
Jarvis Securities (LON:JIM)
Share price: 139.5p (-14%)
Market cap: £62m
Despite the share price fall today, Jarvis shares are still nearly 50% higher than they were when I covered them last September.
The market dumped JIM shares back then on news of an FCA intervention to review the company’s custody and settlement services. Among other things, Jarvis was forced to hire regulatory consultants and to stop taking on any new clients at this wing of the business.
Today’s results contain the following information regarding this matter:
We are severing ties with a number of our model B clients whose businesses do not meet the risk tolerance at Jarvis and fall outside of our more restricted outsourcing model. Whilst limiting the business activities in the short term, it was felt necessary to ensure that the business would thrive in the longer term. We have made and continue to make enhancements to our Model B and retail client onboarding procedures and monitoring to ensure that they are in line with market practice and meet that expected of us by the regulator.
This issue is far from resolved but based on the share price recovery since September, I guess the market agrees with my suspicions that it is not a fatal problem for the company.
The Chairman says: “This review is still ongoing and we expect to provide an update shortly.”
Let’s see how the company has performed in FY December 2022:
Revenues down 12% to £12.6m
PBT down 20% to £6.1m
These are some of the cleanest, simplest accounts you’ll find. No adjustments and nothing added to confuse investors.
Here is how the company makes money:
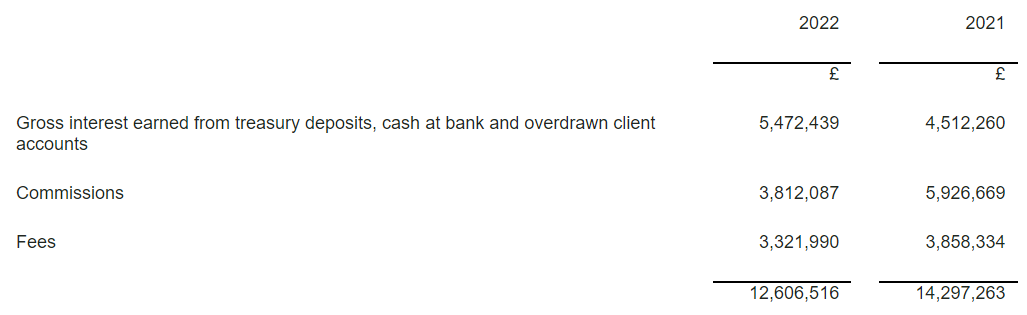
Note the enormous contribution of interest income, which exceeded commissions in 2022 as interest rates rose and as transaction volumes declined.
Jarvis is an example of a cash-rich business that can benefit from higher rates, as shown in the table above.
However, Jarvis itself only owns around £4m of cash. The interest shown above has been earned on client money. Or in the words of Jarvis itself: “The group derives a significant proportion of its revenue from interest earned on client cash deposits”.
The Chairman says “there are still further gains to come in the future” for interest income, as more funds mature.
One of the big imponderables at Jarvis is the identity and creditworthiness of its interest-earning investments. All we know for sure is that:
In accordance with FCA requirements, deposits are only placed with banks that have been approved by our compliance department.
Investors in Jarvis are, to some extent, trusting that management are investing client money prudently.
For what it’s worth, I do believe that management are extremely well-aligned: Andrew Grant is the founder and the largest shareholder (owning 37%), and he remains the Chairman today. If there was a problem, he would be the first to suffer. A lady who shares the same surname is the second-largest shareholder, owning 14%.
There has never, to my knowledge, been any loss associated with how client money has been invested in the past.
Let’s get back to Mr. Grant’s commentary to reflect on how the business has performed in 2022, and the likelihood of a recovery in 2023:
General share transaction volumes remain below average across the whole industry so we have seen a reduction in line with that. The Covid pandemic brought significant volatility to the market between 2020-21, and a flurry of corporate activity after lock down as IPO activity increased. This has largely died down and been replaced by a steadily declining market, which is not ideal for transaction volumes.... There are indications that the market may have now turned, as market indices have turned positive and central banks signalling that interest rates may now have peaked or the rate of increase will slow.
My view
I’m going to give this company the thumbs up. Although I may be suffering from bias as a former shareholder and customer.
I understand their retail proposition very well and I think there is still a place for them in the marketplace as an extremely cheap and simple broker. That being said, they probably could afford to modernise their offering a little more.
I also note that they earn exceptional margins and ROE. This is a long-running feature of the stock and makes it, in my view, one of the highest-quality performers in the UK micro-cap landscape:
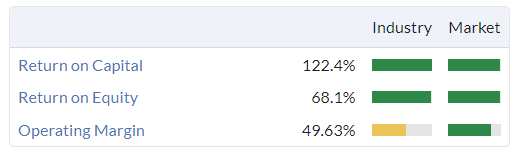
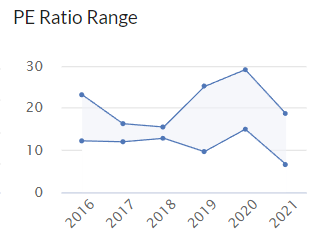
They have earned net income of £5m in a somewhat disappointing year, putting the shares on a PER today of only around 12x. It’s not often that such a high-quality business can be bought at that multiple, although Jarvis itself does trade at 12x from time to time:
There are two major risk factors, in my view.
Firstly, there is the risk that their retail offer eventually becomes uncompetitive, despite their low fees, due to the lack of modernisation and the entrance of new competitors in the landscape (think of the likes of IG group (LON:IGG) - in which I have a long position - who have entered the share dealing space in recent years).
There is also the risk that client funds have been invested in ways that would make investors uncomfortable, if full information around these investments was made public.
Despite this risk, I’m going to give Jarvis the benefit of the doubt (a dangerous thing to do, I know). They have been around for a long time and again, I think they are exceptionally well-aligned.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

203 comments
I recently came across an insult made to a celebrity who is prone to spout nonsense.I think it is also a good description of some of the CEOs of the companies that we investigate. “He is a clattering fanny”
Sorry to hear about WAND. What really stuck with me from Paul's podcast was when he spoke about the CEO, he said things like "if even half of what he says is true..." and called him "exuberant/energetic" (I may be paraphcasing here) vs. when he spoke about the Sanderson CEO for example, he called her "solid" and "impressive." There was clearly some doubt in Paul's mind all along so that and not understading the business at all helped me steer clear, but not to say I don't have other stocks with other issues:)
Hi Paul, thanks for producing these reports, despite what you have been through today. It shows your resilience, professionalism and commitment to us readers.
I'm sorry for anybody who has lost money with WANdisco (LON:WAND) today. I believe the lesson should be to harness the awesome power of the Stock ranking system for which we have all paid our hard earned subscription money to access. I would urge everybody to revisit the "Learn" section and watch any of Ed Croft's inspirational content as well as his recent excellent series of webinars.
Whilst the rankings would not have spotted this fraud, anybody with even the most passing interest or belief in the underpinnings of this website would not have invested in this company simply because it has been classified as a losing style at least as far back as September last year. People who argue that the Stockranks can be ignored for early stage, fast growing companies are really missing the powerful arguments that Ed repeats in every single webinar, article and video he produces. The first rule of investing must surely be to avoid losers and on average, investing in shares with such a poor ranking will damage your wealth.
I'm incredibly aware of the limitations of my own competence in all facets of investing from understanding what is truly going on inside businesses, in stock picking, in avoiding psychological bias, in analysing company reports and just about every other area of investing and yet, my portfolio continues to outperform after 6 years of using Stockopedia. The reason is that I trust the power of the rankings allied to good diversification to keep me out of trouble and keep my portfolio chugging along upwards and to the right.
I know that some people will argue that Patisserie Valerie had great rankings and that is of course true but it's purely a game of probability and there will always be more car crashes in the red rankings than the green.
Ed regularly debunks the myth that volatile, risky shares outperform "boring", balanced shares. It's worth repeating the Low Volatility Anomaly which states that low volatility stocks provide comparable returns to higher volatility stocks for less downside risk. Avoiding downside risk is the surest way to sustainably build wealth and Stockopedia charges us for access to such a simple and powerful framework for achieving it, that to pay the subscription and then invest in the Losing Styles is like paying a lawyer and then defending yourself in court.
With all the chat in today’s commentary, the guys at Stockopedia must be sitting on at least a couple of Petabyte’s of data. Congrats guys! You need to give that farmer bloke a call, you’re gonna be rich.
Paul,
Trusting you are recovering from the WANdisco (LON:WAND) shenanigans' - Its impossible to mitigate for fraudsters, so don't beat yourself up.
If you get chance could you circle back to the Franchise Brands (LON:FRAN) results tomorrow, who finished up +8.6% on a strong YE.
A question on WANdisco (LON:WAND) situation. Firstly so sorry for holders. I did take a look a few weeks back but I just couldn’t get my head around the valuation, EVEN if the projected sales were true! Thought of shorting it which I never normally do but didn’t given the risk.
So my question is:-
IF this share has been shorted, what happens in a scenario where the company doesn’t come back to market? Or, if it does come out of suspension with an actual share price, would the short still be valid? Thanks to anyone if they can answer this.
That Edison video is phenomenal. Pure Alan Partridge! I bet he drives a Lex-i….
That Edison video is phenomenal. Pure Alan Partridge! I bet he drives a Lex-i….
Actually, he mentioned he has two Tesla's. Apparently, they each generate 1 Petabyte of data per day and he charges Tesla $280k for the privilege...
Hahaha!!!
Take a look at the “Chief Scientist, Inventor and Co-Founder” on their Board of Directors. Looks obvious now doesn’t it!
Mr Cooper from Goodness Gracious Me!
Todays lesson is Know What You Own.
Well, today was a massive unknown for many including city boys. I was thinking that as long as the graph keep rising from left to right, the less questioning people become. Wand however was talking bs all the way.
Well f*ck me!! Just got back from holiday and seen the news r.e WAND! Have been holding this from around £5 and was sitting in a wonderful profit.
I suspect this will now turn into a mid 5 figure loss! FFS, what a nightmare...
How could all of this possibly gone under the radar? The top brass of this company are clearly crooks! How does this even happen???? What an absolute joke
I think the crooks reside in the sales department; the top table are just mere idiots.
Agreed
A bit of a random one, I hold a small position in Vanguard FTSE Dvlp Eurp exUK UCITS ETF EUR Dis (LON:VERX) which is showing a 7.8% drop on the day, having been going along slowly above the 50 dMA since breaking through last November.
Anyone any clue to something I have missed, as get the 2-3% moves in a good/bad day, but nearly 8% leaves me scratching my head
Thanks
Tommy
ps. I hold Vanguard FTSE Dvlp Eurp exUK UCITS ETF EUR Dis (LON:VERX)
And to updated it is now showing 0.76% drop, all calm maybe just stick with looking at 9pm at night!
JP Morgan Emerging Europe has fallen 14% today - this was after a big rise the last few days. Hedge funds? Trouble in Europe?
WANdisco (LON:WAND)
I’m sorry to hear about the losses suffered on WANDisco. I know little about the company and do not have a holding. In my search for red flags in an attempt to protect myself from similar catastrophes, I found the following.
I remember the Equities First scandal of several years ago. It was advertised as a way for directors to pledge shares as collateral for loans. Shares were signed over to Equities First and then sold with the proceeds loaned to directors. It became a way for directors to sell shares without technically selling their holding as there was an intention to redeem the transferred shares at the end of the loan period (which rarely or never happened). Directors could be listed as having a substantial shareholding in companies where they owned no shares. The deals were non-recourse, so directors could walk away and not buy the shares back. Equity First also had substantial protection. Rob Terry at Quindell was a user of this facility as were several other directors at now-defunct and/or fraudulent companies (Cloudbuy, Igas [still exists but down 99%], etc.). This was years ago (2014-2015ish) and I assumed (I really don’t know why…) that the regulator had shut this sort of thing down.
https://duckduckgo.com/?q=equity+first+holdings+scandal+wandisco&atb=v314-1&ia=web was the best web search I used to refresh my memory.
Hindsight is what it is, but involvement with Equity First is another red flag to notice.
RNS 9.xi.21
WANdisco (LSE: WAND), the LiveData company, announces that David Richards, Chairman and CEO of the Company, entered into a transfer and repurchase agreement with Equities First Holdings ("EFH") on 5 November 2021, a securities based capital provider of finance for private and institutional investors (the "Agreement"), in respect of 350,000 ordinary shares (the "Transferred Shares") of his total shareholding of 2,157,264 ordinary shares in the Company, as security for a loan.
Under the terms of the Agreement, Mr. Richards has transferred the Transferred Shares to EFH for consideration to be determined by the average of the last sale price of the ordinary shares as reported on Bloomberg over the three trading days upon and following receipt of the Transferred Shares by EFH.
Mr. Richards is required to redeem the Transferred Shares at maturity when the loan is repaid at the end of the three year term. Under the terms of the Agreement, EFH is prohibited from short selling or voting the shares during the term of the loan.
WANdisco (LON:WAND) is a real wake up call to all Private Investors.
What is so chilling is that on their Website they list Partners like Amazon Web Services, Microsoft Azure, Google Cloud Platform, and Customers like Daimler which makes for credibility.
I never looked seriously at Wandisco because I did not understand it. Warren Buffett famously said " Never invest in a business you cannot understand"
"It takes 20 years to build a reputation and five minutes to ruin it. If you think about that, you'll do things differently"
The Sage of Omaha is so often correct.
Commiserations to all holders including Paul.
That's a rule I've been following a couple of years now - stick with businesses that are easy to understand, predictable and with consistent long term track records. Of course this severely restricts what I can invest in and automatically rules out a lot of small caps, but can sleep a lot easier and pretty happy with my returns. Increasingly focused on mid & large caps and investment trusts these days.
I would never invest in a company with such a ridiculous name. I couldn’t, get past an image of glitter balls and John Travolta poses.
One I avoided - which looking at my portfolio is a nice change! However I've felt the pain.
IoT is not having a great time - I've been in it and I see companies folding - the data volumes aren't there. Growth is low. Ideas flop and or pivot. So I don't get the growth they "see". It reminds me of the Telco boom ca. yr 2000. All those growth stories - there were some - but most only existed in the pub. Then the price collapsed.
Also I don't get that moving data is something that they sell to Amazon, Microsoft, Google - because they can't do it - really? Amazon, Google, and Microsoft can't move data efficiently? Like they don't have well paid developers who could tackle this? Maybe as a utility service - but not a premium generator.
Finally I agree on the name - W.T.F is that about?
Can't believe this is one person. They will have feathered their nests and the money will be long gone. Maybe a directorship ban, maybe a small fine, but a nice reward awaits them.
Thank you Graham, your observations are very helpful on Jarvis Securities, I'm minded to modestly increase our holding, probably not today though as shrapnel from Wandisco spreads.
#WAND
Analyst commentary from John Hughman wrt WANdisco (LON:WAND)'s shock suspension of its shares this morning.
Thanks Paul. The only thing in that article I would question is it referring to a growing army of bulletin board investors. It was actually the opposite. The main shareholders in WAND are big, shrewd funds & investors (like Richard Griffith for example).
It was the very low level of bulletin board interest (hardly anything on advfn for example) that gave me comfort that this was unlikely to be a big ramp. Here's the major shareholders for example. It's quite astonishing that big, shrewd funds & family offices, that must have done far more due diligence on this than private investors, could have got it so badly wrong.
These WAND shareholders are not bulletin board muppets - and some were even increasing their stakes recently -
Yes there were obvious risks - awful historic numbers, as I flagged here repeatedly, for years. But you don't expect a whole series of contract win announcements to be bogus. Still that's what the entire £900m mkt cap was resting on, so everyone would have known that if those orders weren't real, then the shares could be worth very little. So I did consider that risk, but decided it was so far-fetched as to be able to completely discount it. What a mistake that turned out to be!
Think I'll go back to my knitting, and stick with profitable, cash generative companies paying divis again. The risk of those being total frauds is much lower, although Patisserie Valerie showed that even supposedly high quality companies paying divis, and with a big shrewd investor at the helm, might not be what they seem.
It's certainly a minefield isn't it.
Regards, Paul.
It's quite astonishing that big, shrewd funds & family offices, that must have done far more due diligence on this than private investors, could have got it so badly wrong.
These WAND shareholders are not bulletin board muppets - and some were even increasing their stakes recently -
It doesn't matter how clever or switched on you are, everyone loves a good story, and when they start seeing £££ signs they drop their guard and can end up looking a total muppet. A good story with the promise of riches is one of the most powerful influence techniques, used by dodgy salesmen the world over. Some of the shrewdest business people on the planet got taken in by Elisabeth Holmes and the gigantic fraud that was Theranos, even Rupert Murdoch.
I feel really genuinely sorry for anyone that got duped but I never invest where the CEO is also the Chairman, that's awful corporate governance. I also can't believe what I've just heard in the recent interview with Edison (linked to below) - Did the CEO really claim that a train operator would pay his company $140K a day to offload a Petabyte of data per train? I'm sorry, but that is just not credible.
All the best, Si
I never invest where the CEO is also the Chairman
Berkshire Hathaway? I think there are always exceptions. If the CEO has a long track record, then I think differently.
Berkshire Hathaway? I think there are always exceptions. If the CEO has a long track record, then I think differently.
Same problem, but you're lucky the person involved is trustworthy, that's all. Please don't tell me there's no chance of fraud taking place in such a huge and complex company. Still, it will be interesting to see how well the share price fares when the day inevitably arises that the joint Chairman and CEO is no longer around...
In every large company there will always be criminals - but at the top management level, I believe the current crop is top class. I also believe Greg Abel will make a fine CEO when Warren leaves. As for the share price, my guess is, it'll go down for a period while people panic. I hope to be a buyer, if it goes into my range, if that happens. However, I think Greg will steer the ship very well when he takes the reins and even if the shares tank, they'll come back as he will take care of the fundamentals. Greg isn't a business buyer like Warren and Charlie, but he is an excellent manager. Perhaps Ted and Todd will get a much larger budget to play with and buy larger stakes in public companies. Will they ever again buy private companies? Who knows, they may even start paying dividends. Either way, I'm almost certain I will be a holder for a long time to come. It is rare to find a CEO that is so trustworthy. Typically they're very old with stellar reputations earned over many years. When Greg takes over, one of Warrens sons will become the chairman. At 60 years old, Greg is too young in the tooth to be both CEO and Chairman. Perhaps then, Berkshire will no longer raise a red flag for you.
WANdisco (LON:WAND)
“ Unfortunately holders here will, I suspect, have to brace for a 90-100% loss on this share.”
Including the directors who owned about £15m+ worth of shares.
I don’t hold.
Regards
Michael
However, if I read Stockopedia director records correctly
£2m buy, £8.7m sell, £35m take/ex/gift
I dont hold (more by luck than judgement)
Pressure Technologies
Bought a chunk yesterday at below 40p
Just spiked up to 47p and still not much stock available to buy
Probably simply an example of price jumps in illiquid micro caps as opposed to anything significant .
Don’t normally jump in and out but might be tempting as I need to free up some cash .
The reason for the spike could be the Vox interview on Tuesday: https://www.voxmarkets.co.uk/a...
#PRES highlighted by Richard Staveley of Rockwood Strategic yesterday (starts 53:30)
&t=477sHi Paul Hill ,
I think it would be a great idea if you upload here all your interviews with Richard Staveley regarding Pressure Technologies plc.
For example the one in 2020 ( if I am not mistaken ) when the price was over a pound or at levels well above today’s price. He was saying exactly the same things.
This share offers no investment case and it is controlled by few major institutions. The price can go to anywhere they want. They have all recently supported the company in a new rights issue in order to keep it as a going concern. If they want they can take it again to the old levels as they control almost all the shares available.
I had a good look at Pressure Technologies (LON:PRES) in February and concluded that they are a jobbing engineer with some specialities (eg: as I said then, if you want perfectly spherical balls they will supply them). Every contract they get will be won on a combination of quality and price but I doubt they ever pitch for a contract where they are the only potential supplier. I'm happy to look at evidence to the contrary.
I tend to invest in companies based on the numbers I have in front of me. Pressure Technologies is too small for me ,it pays no dividends, generates no material free cash flows ( even on £35m revenues ) and last year was bailed out by its shareholders as it was about to break its banking covenants.
As I said in a previous comment, the price can go anywhere as it is controlled by few institutions. It only needs a couple of weekend newspaper tips or mentioned in monthly newsletter to take this over 60p.
Too speculative for me.
Thanks
I have a good few cigar butt stocks that are indeed highly speculative .
Richard Staveley and Gresham are on fire the past 24 months so I do take a lot of notice of their investing decisions that are always very well thought through and they have a very strong deep value investing approach that uncovers a lot of gems that the market has tossed aside .
With pressure tech being so local I like that too and I would say the real estate alone is worth market cap .
I’d be cautious on ascribing too much value to the site ..it’s not all freehold AIUI & has been downvalued in the last AR
An excellent comment and one that should be heeded whenever investing in illiquid small caps with dominant spivvy shareholders. Sometimes we get lucky and piggyback on irrational movements engineered by such players using other people’s money. But the risk is that the price is actually pure fantasy and although they can sometimes cover up the mistakes that they make by taking poor investments private, often they are just as likely to have their heads handed to them by the market
I think your being to pessimistic about Wandisco. Ok its going to take a kicking over this but its still in my opinion a good company with a brilliant future. No company can help rouge employees. Lets wait and see the full findings before condemning it.
Even the eminent Christopher Mills was duped.
Hi DavidCox,
There is a fraud here and this share will end up worthless. I do not think it will even be allowed to trade again.
Hi David,
on a gloomy day you made me laugh. (and I had to check myself)
Red employees, eh? Maybe a communist?
I don't think this is just one employee. Some frauds have finished the company, see Globo, Wirecard and Patisserie Valerie.
Likely irrelevant to what happened, but I noticed the global head of sales changed his linkedin profile photo and title from employed to "looking for work" at around 10:45am today.
The only unusual part in that is he has backdated his leaving date to Dec 2022.
I would have thought that he wiuld want to expunge all records of him ever being there.
Well yes, as if false sales were booked. The global head of sales was shaking the hand of those booking them.
WANdisco (LON:WAND) Worth reading the comment by iain1234 on Monday. Of course we are reading it now with the benefit of hindsight. https://www.stockopedia.com/co...
I am (was?) a WANdisco (LON:WAND) holder. I was treating it as a momentum trade and I was gonna be out at the first sign of trouble, or so I thought!
This was an exception to my usual rules of sticking to higher stock rank companies. Lesson learnt.
This stuff is all part of the game though and occasionally one is gonna land on the odd snake. I have reduced individual position sizes as my portfolio has grown and so luckily only had a 4% position. Diversification may somewhat reduce returns but it has saved me here. I don't need to shoot the lights out anymore.
I have already mentally written that down to zero which pretty much takes my YTD gain back to about 1%. So where I was about 2 months ago, not the end of the world. Stoicism is the key to being able to mentally navigate the stock market, in my opinion.
I hope anyone else in this position can keep their chin up. What seems a big deal now will probably be little more than a blip on the graph in a few years.
Shaken but not stirred ! - youve managed your risk well - and not taken a massive % hit
Anyone have insight into what's happening in Georgia? Sold all my holdings in Bank of Georgia (LON:BGEO) this morning, maybe a mistake but makes it easier to sleep at night!
Bank of Georgia (LON:BGEO) see link maybe this us connected, is on my research list, I am wary of investing in Georgia,
https://edition.cnn.com/2023/0...
The government had given support to something called a foreign agents bill which the opposition had pointed out was a limitation on free press and civi rights and increasingly authoritarian. It was modelled on a US legislation from 1930 and basically said that anyone engaged in political activity that received funding of more than 20% from foreign sources needed to register as a foreign agent. The EU said the draft legislation was incompatible with EU membership. There were public protests in the streets.
The Government has dropped their support for the bill and the President has said she will veto it if it comes up.
Yesterdays blip may have been due to the governments proposed Foreign Agents Bill
https://www.cnn.com/2023/03/07...
Bank of Georgia (LON:BGEO)
Anyone have insight into what's happening in Georgia?
can you outline what is happening ? ie whats your concern and why you sold.
i cant see any new news
It was on the news last night, lots of civil unrest, seem to be anti Russian protests. Here is BBC coverage: https://www.bbc.co.uk/news/wor...
Would be nice if balance sheet investigators gave some quick flags up on +1bn caps where noted on here. Not a deep dive, day job, just a quick squiz and insight into where Stocko algos may miss things. Current SR 95 so no red alerts. Forget DYOR don't have the time - rely on stocko.
Still holding Ferrexpo (LON:FXPO) so not divested East Europe just yet - hope lives eternal - said Warren Buffett, not.
Gutted for people who have invested in WANdisco (LON:WAND) , and hopefully they throw the book at the people involved. I don't think anyone should blame themselves for making the investment, you can not really prepare for things like this happening. I hope it doesn't put people off future investments, but I would understand if it did. Fingers crossed then next one you make is a ten bagger.
No chance of anyone being brought to book by SFO, FCA, the police or whatever regulatory body should be responsible for companies and their directors defrauding investors. Remember Patisserie Valerie! The directors (including Luke Johnson as chairman who claimed to know nothing of the fraud) cashed in some significantly in the money share options (£ millions+ worth) in advance of the fraud discovery. They have no doubt squirrelled the money away in some Swiss bank account but as far as I'm aware have not been charged with any fraud so no doubt will get away with it and live happily ever after on their ill-gotten gains. Grant Thornton the auditors got a fine of £2.3m but the directors kept their money and the investors got nothing. Fortunately it was only a small holding in my portfolio but very glad I wasn't holding WANdisco (LON:WAND) .
The Directors should be made bankrupt and stripped of all their global wealth including property in wives names + serve a short stay behind bars with proceeds returned to shareholders. This would send a strong message. I was savage by Pattisserie Valerie, the bar stewards just get away with it and so it goes on and on. A bit of public humiliation outside a court room would soon sort them out.
Have been thinking about hVIVO (LON:HVO) but looking at stocko summary it is 'highly speculative' compared to WANdisco (LON:WAND) only 'speculative'.
I recall scaling up and delivering orders would be a concern, but like Avon Protection (LON:AVON) may struggle.
I'm not quite sure what you are on about with hVIVO (LON:HVO) here?
They are the global (maybe only) challenge study game in town. Challenge studies massively de-risk pharma and bio-tech trials because it is much cheaper and more effective to do it in the wild. They are a service company with plenty of references from big pharma. They are nothing like WANdisco (LON:WAND) which has been doing low revenues and losses for many years. I believe the tech is good but they had never got it commercialised. Horrible situation for their shareholders but I have no idea why you are comparing them to hVIVO (LON:HVO) - its like comparing apples with eggs!
I'm not sure why you recall anything about scaling up and delivering orders either as that isn't factual. The company has diversified into various challenge study models which now means that volunteers who may not qualify for one study could qualify for a different one. The result is a much lowered cost of patient acquisition and thus improving margins. The current hub and spoke model provides capacity for £70m p/a of revenue versus expected revenue of £55-60m this coming year. Adding spokes to the hub is relatively inexpensive and doesn't take more than a few months so they have no need to commit to extra capacity ahead of orders coming in but have the capability to do so when they need.
Net cash exceeds £20m so no debt either. If they do £60m at margins of 15-16% (target 20% over coming years) they can be doing £9-10m ebitda. At an EV/Ebit valuation thats circa 10*
Whether that is cheap, about right or expensive is an individual choice of course but comparing those two companies with a view to investing in one would be odd.
Well said I was going to respond in a similar vein. I also think the f score on Stockopedia should be reevaluated as many of the criteria like profitability and cash are positive
I have, in the past , seen an apple that looked like an egg , or maybe it was a pear!
....or possibly a blackberry. Could've been an eggsbox.
Sorry....apologies to the Two Ronnies.
I agree with your assessment and calculations on hVIVO (LON:HVO. And well done if you got in near or below October lows. The problem for me is that today the growth/valuation matrix is no more attractive than the market leader’s, IQVIA mkt cap USD40bn, with far greater idiosyncratic risk.
Yes, hVIVO leads in the subsidiary field of human challenge studies, but look at what happened to IXICO (LON:IXI) when Roche pulled its Huntingdon’s disease study.
BnB - The thing about hVIVO (LON:HVO) is that it is not wedded to a study or trial and has low concentration risk. What is more is that the pharma pays a high upfront non refundable deposit of circa 20% so even if Pharma does not progress to the study hVIVO (LON:HVO) pocket the cash and can re-sell the slot.
IQVIA and Hvivo aren't really comparable in my view. They don't play in the same space. That's not to say IQVIA aren't attractive in their own right.
One of the main advantages of hVIVO is that has certainty of contracts right through to 2024 as Companies have to book many months ahead to book a space. They have to pay a non-refundable deposit as well. Paul went in a few weeks back so worth reading what he says plus a few broker notes. IMO it really looks like a solid little renowned company which also happens to be the market leader.
I am afraid that there are occasions where Stocko categories give the wrong impression and this one of them.
Speculative and highly speculative are (I believe) calculated on share price volatility. There's no direct read across to the underlying business.
Speculative and highly speculative are (I believe) calculated on share price volatility. There's no direct read across to the underlying business.
And as we should all know by now Richard, risk and volatility are not the same thing at all. A complete misnomer calling a measure of volatility the "Risk Rating".
Thanks Richard. That probably explains it. hVIVO is very much a sentiment stock at the moment and drifts when there is no news and wakes up when there is news. It's also been tipped a couple which gave the SP a spurt but I guess it is volatile, down 10.6% over the last 5 days.
WANdisco (LON:WAND), took a kicking this morning, I was up %104 had trimmed a bit of my position and debating trimming selling half of my position as I was at 8% of my portfolio, I was trying to practice running the winners, , whished I had sold some yesterday as intended but when I saw the announcement re listing on the US market I was swayed to stay with it a little longer, I knew the risks had done the research so only myself to blame, lesson learned, dont know how I could have seen this coming, thank god most of my wealth is invested property, at lease I Know whats going on.
I noticed this morning that stockopedia reports were coming up on Google finance news. Not sure if I can see this as I’m a member or if it’s open access for some reason. Thought I’d mention just in case.
Good point, how does that get into the news section? Any ideas Ed?
WANdisco (LON:WAND)
Would you trust this man?
https://www.google.com/search?...
Snazzy
Hindsight is a wonderful thing.....?
He looks more gentleman farmer than IT business leader
Well it's funny you say that because he is the spitting image of a farmer I know.....a perfect doppelganger in fact.
note at 2min 50 secs says "we changed the whole sales team 18 months ago"
Hi Snazzy
WANdisco (LON:WAND) . I'm not invested and have never really looked at them. Just watched the Edison video you linked to. Most of it sounded slick & pretty plausible to an uninformed listener.
But one thing leapt out at me as needing a reality check : the train @ 9.23. Richards stated that a high speed bullet train generates a petabyte of data per day "and that's $140k to us".
I don't know about bullet trains, but let's make a few guesses - based on UK long distance trains.
About 12 carriages, about 50 seats per carriage, about £100 per ticket and about 4 journeys per day - I'm sure all of those are wrong but, overall, not wildly unreasonable. And assuming 100% load factor.
So the train generates revenue of 12 x 50 x 100 x 4 = £240k v roughly.
So, his claim suggests that roughly 50% of gross revenue could end up in the pocket of the company moving the data about........... Sounds like complete b******s to me.
Interesting - from Google: How much data does a jet engine produce?
Aircraft engines such as in Boeing 787 generates about 1 Terabyte of sensor data every 24 hours.
1000 terabytes = 1 petabyte
(but somehow RR does it without wandisco)
I should also have looked up what a petabyte is......... On the basis that a RR Trent engine is an example of the highest level of mechanical & aeronautical engineering and a bullet train is (with rather a degree of exageration) a diesel engine on wheels, I suspect the jet engine produces rather more data than the train.
Just musing, I wonder if someone has got a decimal point in very much the wrong place? If the train was generating $140 per day for WAND, or even $0.14, the whole thing would be more credible....................
From the Edison video at 9:22 :"A train generates a petabyte of data a day which for us is $140,000 a day just for a single high-speed train." Multiply by 365 and multiply by a fleet size of, say, 50 HST trains and you get $2.5bn annual revenue coming to WANDisco from just one customer! David Richards probably needs to take a remedial maths class before he considers running a company again. It beggars belief how the financial PR firm and brokers let him make such outlandish claims about his company and its growth prospects.. every other phrase of his is peppered with unqualified superlatives . In a previous life as a journalist, I interviewed CEOs of IT companies and its a sector with a lot of big egos, preposterous claims and large quantities of smoke and mirrors, particularly when it comes to revenue recognition. But David Richards and the CFO seem to have screwed up big time by not having controls in place -- and believing their own PR . Does he really believe that (9:03) "in our pipeline we probably have 10 plus telcos and most of the top ten auto manufacturers" ringing up his sales team desperate to spend money with WANDisco?? As of today, I don't think the phone will be ringing so often. My sympathy to those invested.
WANdisco (LON:WAND) ChatGPT response to the question: How could a CEO and CFO not notice sales fraud?
ChatGPT: There are several reasons why a CEO and CFO might not notice sales fraud in their company:
It's important for companies to have strong internal controls, policies, and procedures in place to prevent and detect fraud. Regular audits and employee training can also help to identify potential fraud risks and prevent fraudulent activities from occurring.
Personal speculation: Like everyone has said... how could the managment not have took an interest in the salesperson and his perfomance?!!
I'm voting for option 3!
Chat GPT is miraculous! Def worth a look for all sorts of reasons.
Jim
Maybe one should ask it for advice on buying shares LOL?
Have a look at this https://app.mlq.ai/
I re-worded the question...
Q. How could one spot a companies sales person conducting sales fraud?
ChatGPT:
There are several signs that might indicate a company's salesperson is conducting sales fraud:
If you suspect a salesperson is engaging in sales fraud, it's important to report your concerns to the appropriate person in your organization, such as a supervisor, compliance officer, or fraud prevention team.
This from a poster on a chat forum
David Richards, CEO and co-founder of WANDisco in a recent interview
Richards, who calls the numbers “ridiculous,” is flabbergasted at the amount of business WANDisco is suddenly generating.
“It is bonkers what is going on right now with our company. I’ve never seen anything like it,” he says. “It was always sort of, this was what we said was going to happen. When it actually happens, you have to have the numbers to back it up.”
Companies with manic CEOs who know how to ramp but don't appear to understand the "numbers" and are "flabbergasted" by the growth in business are probably not the wisest companies to invest in IMO
Caduceus,
Thanks for that ChatGPT article. I'm really impressed with its answer.
As it's new to me, I tried out ChatGPT but didn't really understand what it can do, and what questions to ask it. So your posting an excellent example, is really helpful, and maybe other subscribers here could do likewise if you get decent stuff out of it.
Hopefully I won't have to enter early retirement just yet, but this does as if it could be an excellent tool for us to use in assisting our research.
Would be good if some investors could create a youtube video explaining how they use Chat GPT, to help other investors. I've been told it's not any good for analysing current news, because apparently it's using outdated data sources, but that could be wrong.
Anyway, looks very interesting!
Regards, Paul.
So, as an example I literally asked chatGPT to answer your query, here is the input and response:
I asked: Can you create an answer to Paul's following query:
Caduceus,
Thanks for that ChatGPT article. I'm really impressed with its answer.
As it's new to me, I tried out ChatGPT but didn't really understand what it can do, and what questions to ask it. So your posting an excellent example, is really helpful, and maybe other subscribers here could do likewise if you get decent stuff out of it.
Hopefully I won't have to enter early retirement just yet, but this does as if it could be an excellent tool for us to use in assisting our research.
Would be good if some investors could create a youtube video explaining how they use Chat GPT, to help other investors. I've been told it's not any good for analysing current news, because apparently it's using outdated data sources, but that could be wrong.
Anyway, looks very interesting!
Regards, Paul.
ChatGPT responded with:
Hello Paul,
I'm glad you found the ChatGPT article helpful! I'll do my best to answer your questions and provide some additional information.
ChatGPT is a language model developed by OpenAI that uses deep learning to generate natural language responses to prompts or questions. It can perform a wide range of tasks, from answering general knowledge questions to summarizing articles and generating creative writing. Some potential uses for ChatGPT include:
Regarding the use of ChatGPT for investing, it could be a useful tool for generating investment ideas or analyzing trends in the market. However, it's important to note that ChatGPT is only as good as the data it's trained on, and it may not always have access to the most up-to-date information. Additionally, investing decisions should always be made based on a variety of factors, including research, analysis, and consultation with financial experts.
As for investors creating YouTube videos explaining how they use ChatGPT, that's a great idea! It could be helpful for others who are interested in using ChatGPT for investing purposes. However, I would advise caution when taking investment advice from non-professionals, and always consult with a financial advisor before making any investment decisions.
I hope this information is helpful, and please let me know if you have any further questions!
Best regards, ChatGPT
Cad here again -
It's data it limited to 2021 and before, but it knows how to interpret language so it can read current things you paste in... like your scvr and you can ask it for things based in that input.
Basically you can ask it anything, you've just got to know how to ask the right questions in the right way!
Have a look at this Paul for machine learning investment insights https://app.mlq.ai/
Big commiserations to Paul and any WAND holders - been there few times - horribly painful. Traded briefly and took profit - sheer fluke . I usually diarise my comments as to reason I buy and reason I sell to understand my decision processes and what bias/prejudices may have entered .I made trade on " momentum and FOMO !?" after share had risen a lot. No entry made for selling but noted looking to re -enter on weakness !? Impossible to spot fraud at research stage
I had posted this as a reply to a brief JASVFS post from 07:30. On reflection, and as I feel able to contribute on Jarvis Securities (LON:JIM), I have deleted the reply and reposted my comments here, where its more likely to be seen...
...Unfortunately, I suspect Jarvis Securities (LON:JIM) have pulled their punches in quite an extreme manner...
IMHO the four key numbers to follow are:
As a shareholder until the 16-Sep-22 RNS re the FCA investigation, I have these going back to 2010, in a spreadsheet and tried to extrapolate them into the future. Compared to my forecasts prior to the 16-Sep-22 RNS:
Fees since 2016, have never gone down before and this drop presumably results from offboarding Model B clients since 16-Sep-22, plus other clients departing over concerns about a lack of financial controls. If I annualise the 13.9% drop, I am left wondering whether next year's fees will be say circa 50% of 2021.
This will then have a knock on effect on commissions and interest income, which I am finding more difficult to model, as I don't know the proportion of the commissions/cash balances they were providing.
Clearly, as stated, the interest margin on whatever the remaining cash balances, will be massively more attractive... ...I look forward to seeing the ""Cash under administration – annual average balance" number, to start trying to get a handle on that. Assuming its down somewhat, which would again be a first, we should probably extrapolate the current number to be down significantly from this.
As things stand, pending the 2022 "Cash under administration – annual average balance" number being released, I am expecting 2023 results to be considerably weaker than 2022
I used to like Jarvis Securities (LON:JIM) a lot as a boring growing business, paying a decent dividend, on a fairly low rating, so I am finding the current situation all a bit sad. All IMHO.
Thank you shanklin100, much appreciated re Jarvis Securities. It's on Graham's list now so I await his comments. I agree totally with your summing up in the final sentence.
Jarvis Securities (LON:JIM)
Hi Shanklin100
Thanks for your comment today.
I think I'm the only person who doesn't think that today's results were deserving of a 12% drop.
Some thoughts:
I would imagine that these will be provided for in the FY22 results.
I make the year end cash balance c.£330m, so roughly flat vs my H1 calculation.
"The model B’s being exited are typically characterised as corporate brokers to low market capitalisation companies. The companies they act as brokers to are highly speculative.
Their loss will have an impact on trading volumes, but the impact on cash under administration will not be significant as their clients do not hold large cash balances at Jarvis."
abtan
Its certainly useful to have a discussion about £JIM
In terms of "Cash under administration – annual average balance", Jarvis Securities (LON:JIM) don't state that the unit is £100m. What we can see from the relevant graph on page 3 is that from circa 3.6 units lin 2021, the average is down to circa 3.25 for 2022. One can also see, by going back through all the previous FY reports, that the average has never dropped previously, right back to 2009.
From the other graph of page 3, we can see that 2022 trade volumes were down 30% on 2021. This is a bigger percentage drop than any other year but on this occasion has not been mitigated by client wins.
So, its very difficult IMHO to know what's going on re "Cash under administration". Is the prime driver of this reduced trade volumes or the reduction in clients (Model B plus any who have moved because of reputational concerns).
They state "During 2022 cash under administration has decreased slightly, although balances remain close to their peak.". What I would really have liked is an idea of the average YoY figure for Q4 or for December, to better understand this.
If the year-end CuA is 3.25, and that is the average for 2023, I can certainly see 2023 interest income being twice that of 2022, at circa £11.5m. This would match the interest rate margins achieved in 2011, which is by far the best year in that respect since 2010. Given interest rates are much higher now than 2011, and probably interest rate margins also, your £13.2m - £14m, certainly seems very feasible.
Commisions being down circa 1/3 roughly fits in with trading volumes down 30%. What I don't understand is why fee income is down 14%; thoughts welcome on that?
And I agree, on the basis that they have lost few clients, and the outcome of the investigation is not onerous, that your £10m PBT figure would look very prudent.
Jarvis Securities (LON:JIM)
Hi Shanklin
I understand what you're saying about the Cash Under Administration Chart on page 3, which is here for anyone interested.
http://www.jarvissecurities.co...
I was initially sceptical to use the horizontal lines to denote increases of £100m.
However, doing so actually makes sense when we compare this with the interim period end cash balances.
I'm sure, or rather hope, that you'll agree that these come to £325m and £330m respectively for H1 2021 and H2 2022.
Based on the £353m average CUA for 2021 - taken from the graph mentioned above - we can work out that cash balances should = c.£382m at the end of 2021.
The movement in cash balances in this time period conforms to the trends seen at HL and AJB, which also recorded AUA peaking at the end of 2021, before coming down in 2022.
Using the logic above the Q4 2022 figure you're looking for must surely be close to c£330m.
It can't be that much lower unless there was a material increase in CAU in Q3 (Jul-Sep), which doesn't really make sense when we consider that HL actually saw a decrease in AUA from Jul-Sep 2022.
So it seems like quite a lot of cash has left the Jarvis ecosystem over 2022, but it still remains high enough to create over-sized returns in 2023, either through increased volumes, higher interest income or both.
Fingers crossed for that prudent £10m PBT figure.
A
Hi Abtan
Where does your table come from please?
Thank you, Martin
Hi Martin
Uuhh...I made it.
I calculated the interim cash balances by using the 2013 interim report and then extrapolating forward (the company has disclosed % changes at their interims every year since 2013.)
You might be interested in this comment from a few days ago:
https://www.stockopedia.com/co...
A
I know justice grinds exceeding slow, but I think Patisserie Valerie made their shock announcement in Oct 2018, and still we haven't heard anything about what happened there. Anyone heard anything
Seems they are still in business or the name is - saw a shop in Ealing.
No there has been no significant news. bad behaviour in the financial markets is seldom dealt with competently by the authorities in this country.
See my reply to a later comment. Only action is fine for Grant Thornton the auditors (£2.3m).
Franchise Brands (LON:FRAN)
Record organic growth at Metro Rod and transformational acquisition of Filta which has performed ahead of expectations
Excellent FY trading update demonstrating organic and inorganic growth following the acquisition of Filta Group last year giving FRAN a foothold in North America. B2B brands performing really well and Filta going from strength.
Revenue increased by 72% to £99.2m (2021: £57.7m) reflecting record organic growth from the B2B Division, complemented by the acquisition of Filta.
· Adjusted EBITDA* increased by 80% to £15.3m (2021: £8.5m).
· Adjusted profit** before tax increased by 98% to £12.8m (2021: £6.5m).
· Statutory profit before tax increased by 78% to £10.3m ( 2021 : £5.8m).
· Cash conversion (after adding back acquisition and reorganisation costs) of 79% (2021: 97%). The decline was due to additional trade debtors at Metro Rod on increased system sales.
· Net cash*** of £8.0m at 31 December 2022 (2021: £6.5m).
· Adjusted EPS** increased by 51% to 8.38p (2021: 5.55p).
· Basic EPS increased by 54% to 6.81p (2021: 4.42p).
· Final dividend of 1.1p per share proposed (2021: 0.9p per share), giving a 33% increase in the total dividend for the year to 2.0p per share (2021: 1.5p per share), 4.2 times covered by adjusted profit after tax (2021: 3.7 times).
Current trading and outlook
· Good momentum in the B2B businesses continued into 2023 to date, reflecting defensive growth opportunities for its essential services to resilient and diversified sectors.
· Filta International maintains excellent progress in North America.
· Strategic review has concluded there are greater opportunities for the Group for organic, acquisitive and international growth within the B2B franchise sector. The B2C Division is therefore being offered for sale.
The much smaller B2C division has struggled since Covid and will be sold - for approx £23m according to Dowgate note which also says FRAN made a failed bid for Pimlico Plumbers which sold for £130m.
The Dowgate note provides some interesting additional insight.
CEO Helmsley and Nigel Wray founders of Domino's Pizza are 20% shareholders and their franchise model has enjoyed great success to date. Very large and numerous director holdings aligns directors with shareholders.
I hold since 2019.
Meanwhile, amid this shock, two of my smallish holdings Forterra (LON:FORT) and Volution (LON:FAN) reported decent results, particularly the latter. If you can bring yourseves to cover any other updates on such a grim day, guys, please could you cast an eye over these? Thanks and commiserations Paul.
Hi BnB
I don't hold Forterra (LON:FORT) but I do hold Michelmersh Brick Holdings (LON:MBH) and I thought the read-across was excellent.
Here are some snippets from the former's results today that stood out for me:
"Total UK brick consumption in 2022 is estimated at 2.5bn bricks of which a record 570m (representing 23% of total market demand) were satisfied by imports due to a continuing shortfall in domestic production capacity...
...in the near term, the ability to displace imported bricks will insulate ourselves and other UK brick manufacturers from some of the fall in demand as our customers switch from imports to domestically manufactured products which are expected to become more freely available.
...We increased the majority of our brick prices by a cumulative 50% during the year."
I'm amazed by the 50% increase in prices (with apparently more to come) and that demand is only expected to fall by 20%.
Well, this has turned into my biggest disaster company lesson ever! I only bought into it 3 days ago after umm'ing and arr'ing for the last couple of weeks. Paul- would it be possible to do an 'emergency podcast' when you get a bit more info to detail events, explain whats gone on, potentially how and possible outcomes? My day has just flipped on a coin!
Did they not ask themselves why just "ONE senior sales employee" was winning all this business? Presumably the others were not winning business or the activities of "one" would not have had such an impact.
Literally unbelievable! More to come no doubt.
Fair point, I agree.
Some of the contract awards were incremental ie the same client increasing original orders
How many cancellations will they get now too? Untrustworthy service supplier red flags. I was looking at WAND chart yesterday and thinking I really missed all the growth spurt.
Paul is right to question how it could be that the fraud was perpetrated by one senior salesman acting alone. In small businesses like this you would expect the CEO and CFO to be taking part in all major sales negotiations (even add on sales). Big customers buying from small companies need to see the CEO and CFO to do due diligence on the viability of the business from whom they are buying. These fraudulent sales would have tripled WANdisco (LON:WAND)'s revenues. And the CFO didn't check the validity of the orders? Were the CFO and CEO asleep at the wheel? Are they major fantasists? Or were they complicit?
The 'fake it till you make it' approach of too many tech entrepreneurs has a lot to answer for.
Yep, I agree with all that.
Back in my days running a company with a turnover far in excess of WanDisco’s, if a big telco or auto OEM had given us a £6m deal, I’d have been all over the transaction and face to face with the buyer. It’s impossible for me to imagine the CEO it’s not culpable, whether for fraud or the most extreme incompetence.
BnB I completely agree. I would say the same in my own business and we would never count future revenue without either a signed contract, or we would take part of it if we were in contract negotiation. And no one person ever handled that. Senior people would be (nicely) interrogated not through any suspicion but just basic rigour. As an investor I am outraged at this today and the fact that I am not a holder is more by luck than judgement.
Seems the CEO was also the Chair for the last 7 years - not healthy.
Hi BnB,
Exactly right, I agree completely. If a small company like WANdisco (LON:WAND) suddenly started winning major contracts, then the CEO & CFO would have been all over those deals. To suggest that a lone salesman cooked up a load of phoney deals that constituted almost two thirds of 2022 revenues, is not even remotely credible.
Regards, Paul.
Agreed. In my working days as a consultant I worked on big software purchases for big clients. When buying from a much smaller supplier we always spoke to the CEO to assess the viability of the business as well as the quality of management. No chance a big customer would buy from WANdisco (LON:WAND) without seeing the CEO and CFO and agreeing the final purchase directly with them.
WANdisco (LON:WAND)
looks like even Stockopedia's fancy lights are a work of fiction. Commiserations to all holders. Never could get comfortable with WANdisco (LON:WAND) A painful reminder that we always get our fair share of frauds in the UK stockmarket
Not arguing with you but... can the stocko fancy lights really predict human deceit and evasion from truths? Although, I'm still not clear on how this could have been pulled off?
The fancy lights are only as good as the fancy numbers being entered into it.
This point was highlighted by Ed last night during the Screener Session which I have to say was very informative so many thanks to Ed and his team. Well worth a watch for those that missed it.
Hats off to Berksbee:
"spent my career in tech .... have been through the dotcom boom ... is this a good company yes, is this a viable product yes, would I be pumped if I was the CEO you bet!. But the stocko scores tell you all IMO. Value 2, Momentum 97. Market cap ~30x sales.
"Too many times I've seen the scenario where tech growth has been extrapolated forward into the future to support a story. IMO its a trade not an investment with lots of FOMO. That said if (when) it tumbles it might be worth a punt as someone big will buy it."
Stocko protected me from a bad investment and the contributors - thank you.
Hi TEIN
Perhaps a lesson to pay attention to the Stocko F-Score details (Z2-Score screen shot in next post)
Following previous post the Z2-Scores
I do not understand why Z2-Score is 49.7 when overall its 2/4 for the tests
Hi Howard,
I don't hold WANdisco (LON:WAND) and my post was just to start some conversation because when I went to the companies stock page this morning the F, Z and M scores were the first thing to look at, and immediately stood out to flag and discuss.
In response to your point, Ed Croft as recently as last night's webinar talked about looking for a minimum 6 on the F and I think the slides he presents usually talk about a 7+, but how many of us can say we don't hold some sub 6 F-Scores? I was just as interested in the Z and particularly the M score being so at odds with today's devastating news for holders, some of whom may have been reassured by green lights when making their investment.
Hi again TEIN
Thanks for the response.
I have not seen Eds webinar from last night yet, but recalled a quite recent previous one whereby Ed highlighted the tests behind the F, Z and M scores and since then I have begun to use them as guides to watch out for risk signals.
Luckily I sliced out 60% of WANdisco (LON:WAND) holding two days ago as I had quite a nice gain but was cautious about the speed of share price rise and the very optimistic 'stories' circulating.
Also luckily I had only averaged in in very small amounts so although still exposed quite a bit I am not that impacted within my overall invested portfolio.
I shall pay even more attention to the details behind the F, Z and M scores now (accepting that in the end they will only report what data has in fact been fed into them).
Regards
Howard
Not seen the webinar yet. Interesting about F and M scores. Yes I hold quite a few stocks with F scores below 7. I did just check the NAPS portfolio and quite a few stocks are below 7. Also all the ones that have 8-9 F scores have negative M scores. If you excluded all these it would be very difficult to fill 20
NAPs selections. NAPs has performed well until last year.
I see Prudential (LON:PRU) only has a F score of 1.
The guru screen based on high F scores has not performed that well.
Fair comment, I have no response to it, although I'm not sure how the metrics are composed, I'm sure there is an Ebook explaining it. Very confusing indeed!
From a bankruptcy point of view its clear the ticked items are waaaay more important and relevant than the ones that have x's.
ie if company has solid liquid assets and little liabilities - the fact it hasnt had great reinvested earnings or the assets do much doesnt really matter too much. Perhaps these only really come into play when the other flags put the company in the danger zone.
The reality is a company will £50 mill cash in the bank losing £2 mill a year on then cusp of breakeven is a pretty safe place ref solvency , that company woul;d probably have those 2 ticks and x's - note these quoted figures and made up and not what wandisco has !!
Hi Howard, I introduced Z scores to rate companies when I was a young partner at a London Accountancy Practice in the 1980 and it caught on so much that we rated all our clients, updated the data every year, and used it as part of our Going Concern reviews. There are, however, flaws and the WANDisco Z score I think highlights it.
From Stocko this is the Z Score criteria:
For public companies, the z-score is calculated as follows: 1.2*T1 + 1.4*T2 + 3.3*T3 + 0.6*T4 + 1.0*T5.
T4 I think is the problem. Using the 2021 accounts we get 906/7.76 = 116*0.6 =70.
If the z score was 49.7, that means T1, T2, T3 & T5 must have been negative 20. (I haven't tested those measures )
I guess the message is don't trust data without testing it AND if it looks too good to be true, it probably will be.
GLA
Barry
Hi Barry5
Wow thank you for those details and the back story.
Regards
Howard
Market cap pushes up the Z score. I think in cases like this it does lead to a bit of distortion.
Maybe if a company is up at a strong upper end level (light fully right) it should have a suspicious zone?
This may be a bad memory but around the time Chinese AIM stocks were going 'wrong' someone (Nick something?) looked into the Stock Ranks and noted that Value Rank was correlated with performance up to 94 and went into reverse 95-100.
WANdisco (LON:WAND)
Hi Paul, How many companies that you've analysed over the years have had receivables increasing by more than booked revenues in 2 consecutive HY periods?
I can't recall ever seeing that - their revenue recognition policy always appeared truly bizarre and now confirmed a fiction.
WANdisco (LON:WAND)
The CEO was in the City only last week, talking to investors, super-bullish, talking about a US listing, and expecting to achieve sales of c.$100m this year,
Presumably all the potential future contracts are linked to the activities of this one "rogue" salesman. Does the ceo have any clue whats going in their business? staggering incompetence all around not having suitable procedures in place. Would be interested to find out the facts of this "sophisticated" cover up to see how sophisticated it was in reality !! - we wont get the detail but a quick full and frank update for shareholders is the least they should be given here !
I do have a bit of sympathy for anyone who has been conned by others generally but strewth this is just plain crazy.
Rogue saleman. Bs. Rogue trader etc. More like rogue management.
Sounds like complicit fraud at the highest level to me.
comment deleted
WANdisco (LON:WAND)
Literally unbelievable announcement - even the announcment makes no sense
"The identification of these irregularities will significantly impact the Company's cash position"
Huh - how can one sales guy cause carnage to cash position of a £1 billion cap company - completley ludicrous - what is the sales guy doing posting sales receipts unchecked and why no checks. Surely the board should be reporting themselves for incompetence.
Thats without stating the obvious that how can you not have procedures in your company to enusre that 2/3 of your booked sales are not real.
Commiserations to all holders. Reminds me why I have a rule of no more than 5% in any one company. It means my gains in good times are nowhere near other but if something goes wrong I don't get heavily damaged. I guess it all depends what level of risk you need. Happy to bounce around 10% returns a year
Good advice - especially for small fry companies but the scale of fraud here has got to be mega, coming after they just talked up in the last few days a US joint listing and a new joint London broker. All the deals were of a large size and talked up by the CEO - no way is this down to one person tucked away in the corner of the office.
that is not necessarily true. I have more than 5% of my porto in Legal and General, Aviva, Shell, Apple and few others. They have been up and down but no disasters. Dividend on top too!
I have a couple of those myself but my personnel preference is to split up my large cap amongst more to avoid over exposure to one company. Lower risk probably means lower returns long run but depends what each person needs
Very sorry for anyone impacted by this mornings news. It seems reminiscent of Globo and Quindell where much noise was made about industry wide take up of a non existent product. I’m not deeply familiar with WANdisco (LON:WAND) but is there a product? Were they not stating that no large cloud migrations could happen without their software?
Who in the market is benefiting from this migration activity? Is it just the cloud providers themselves?
I agree. I often look at my returns and think "very average", but I've had a couple of stinkers over the last 18mths and just placate myself with the fact that whilst losing tens-of-thousands it could have been far worse.
I view my PF's as my own Investment Trust/Unit Trust and some may ask "well why don't you just invest in them instead", and my answer is I really enjoy the process and mental challenge, so whilst I hold large chunks of IT's I like to manage the other part of my PF's myself.
Feel sorry for you all in WANdisco (LON:WAND) , how on earth did one person create this without anyone above knowing??!!! Shocking!
TB_Investor - Same way Nick Leeson trashed Barings bank - one person who is not properly supervised can smash up even a very big old-established business. We still don't really know what happened at Patisserie Valerie but that looked like a fraud instigated by one person which the supposedly star CEO was too stupid or self-confident to notice. In any business, whether small or large, internal audit systems and management supervision are essential or there will be fraud. I have been on the boards of two reasonably substantial businesses during my career, and was chair of one of them for a while. I asked a lot of questions and always insisted on seeing a cash flow report every month, without fail, and the actual bank statements with the quarterly report. As an investor I do look at P&Ls and balance sheets but the cash flow statement tells me most of what I want to know.
Commiserations to all WANdisco (LON:WAND) holders. A shocking RNS and an awful start to the day for you all.
I know how it feels as I suffered 100% losses with frauds at both Marconi and Cafe Patisserie. Leaves a very unpleasant taste.
We can but hope that the fraudster(s) will be identified and punished.
Snazzy
Unfortunately, fraudsters rarely are punished in the UK, and never promptly. One of my first AIM investments was Silverdale which, albeit much smaller, went bust with similar suddenness. I've never heard anything about prosecutions.......
A few headline convictions would work wonders in "encourager les autres"
if the fraud happened in the US, and thus prosecuted in the US, you may see some justice served.
Hi Paul re LON:WAND what a disaster for investors indeed and sadly yourself included and there but for the grace of God it would have been me but thanks to your analysis and some analysis of my own peppered with cynicism of other commenters on here and other platforms I swerved the bullet. Please don’t blame yourself, you only reported what you were told by the CEO and indeed I picked up enough of your healthy skepticism about the strength of their orders ( and what might happen if they didn’t come to fruition) to make my own decision not to buy. Also part of my worries stemmed from the fund raising back in June at 270p a premium to the share price at the time!!! One of the funds was real estate investment fund which seemed an odd investor in LON:WAND to me. Hard to believe nearly a £1bn of shareholder funds have gone up in smoke. It’s a real crime.
Morning TheOx2906,
Thanks, appreciated. I always made it clear in posts here that WAND had a terrible track record, as a serial disappointer, with false dawns in the past. But naturally, I took the huge order intake, and explanations of it being due to 5G at face value. As did lots of shrewd investors - unusually for a fraud, the shareholder base is mainly big investors, eg shrewdie Richard Griffiths (a wealthy shrewd investor) holds about £60m-worth, and was buying more recently. That impressive shareholder list was one of the things that gave me comfort.
I suppose the sensible thing to have done, would be to wait until the April 2023 trading update, to confirm that the high year end receivables had turned into cash. When I directly asked the CEO this question a while back, he pretty much said yes, or a form of words which led me to think it was a yes. Then he later back-tracked on this, saying that some was not yet due, as on 30 to 90 day invoices.
After the recent meeting, I had lunch with 3 other investors, and we discussed it. I mentioned that I'd picked up multiple negative body language signals from the CEO, and another investor said he won't buy any more until he's met the CFO too (it was always just the CEO doing the promotional meetings). But none of these hunches were strong enough to make me bail out. I took the view that if even half what the CEO was saying was true, then we're onto a multibagger. We agreed that the worst case scenario was they miss targets due to delays, and it's a 30% loss. We all agreed that the idea of it being a fraud was so far-fetched, that it could be ignored.
Looking back, I should have waited to see the very high year end receivables actually turn into cash. There again, if a company is repeatedly lying about contract wins, they would probably also lie about the cash having come in!
Maybe Liberum were being lined up to do another placing? But the story was that they would only need a small placing, in advance of a US listing.
I can see why lots of people wouldn't have wanted to invest in WAND, which we discussed here plenty of times - it was speculative, and the valuation entirely based on the big new contract wins. Without that, it was just pure hope, and a very high valuation. But I never imagined the deals would turn out to be bogus.
A lot of the shareholders are American, and WAND operates in both the UK & USA. So let's hope the perpetrators (it has to be more than just 1 person) are taken to court, and end up in prison. There needs to be proper punishment for white collar crime.
You’re far from the only person misled here Paul…this guy Richards has some history, (there’s a Telegraph article out there from June 2016 about his behavior with the company available online)
Below is from a tech blog called Blocks & Files only 4 days ago!!The penultimate paragraph is just laughable if it wasn’t so terrible:
In general, he suggests that in the live data movement market WANdisco has no competition: “We have 100 percent market share.”
The analysis and ML environment can vary with vertical markets and WANdisco’s 10-person salesforce is organized by vertical market. It has just hired Thomas Wirtz away from Databricks to be its Director for Automotive and Manufacturing segments.
Richards said: “Ten enterprise sales guys pulled in $127 million in bookings. We think we can get to a billion dollars of bookings with 20 salespeople, and be the most profitable company the world has ever seen.”
With much of its sales activity taking place in the USA, it’s been rumored that WANdisco could be considering adding a US listing alongside its UK AIM market listing. The company has just put out a statement saying: “As a dual UK and US headquartered technology company, WANdisco has long stated its intention to consider an additional listing of its ordinary shares in the United States. The company can confirm that it is in the early stages of proactively exploring this option.”
hi The Ox 2906
WANdisco (LON:WAND)
The Telegraph article appears to be behind a paywall.
Snazzy
"Richards said: ...'be the most profitable company the world has ever seen.”
If this is true - it reminds me of a more high-profile individual who regularly makes such grandiose claims and the promise of never-to-be-delivered functionality and / or products, in EVs, autonomous driving etc.
And once you've looked through the smoke and mirrors you realize the reality is very different.
Never has caveat emptor been more relevant - especially in stocks!
Just wish I could follow my own advice and buy mostly boring, safe things - yep they won't set the world alight, but also they won't burn the house down...
I have not read the £WAN RNS but it is unusual for a fraud in booking sales to "significantly impact the cash position". Cash is cash, whatever a criminal sales manager says...
Hi grumpy5,
I have not read the £WAN RNS but it is unusual for a fraud in booking sales to "significantly impact the cash position". Cash is cash, whatever a criminal sales manager says...
It was all in receivables. I asked the CEO if the cash had come in, and he fudged it a bit, saying that the money which was due, had been collected. He was emphatic that there wouldn't be any more fundraisings. So clearly he wasn't telling the truth! Hence why I think this situation is probably worse than just a rogue salesman trying to hit his targets.
So it is the cash + net working capital position that is over-stated. Auditors BDO have a bit of explaining to do.
Hi grumpy5,
So it is the cash + net working capital position that is over-stated. Auditors BDO have a bit of explaining to do.
No, that's wrong. The FY 12/2022 figures are currently in the process of being audited and maybe this fraud came to light because the auditors found it? We don't know yet. The only numbers so far that have been published are just trading updates & contract announcements from WAND itself, neither of which are audited.
The fraud seems to have happened in 2022, so it doesn't relate to any historic numbers, as far as we know.
Regards, Paul.
As far as I can see the figures had yet to be audited - it was just a Y/E trading update. (11/1/23)
"Preliminary unaudited revenues of at least $24m
Strong Balance Sheet with $19m in net cash, $44m in Accounts
Receivable"
Phil
BDO are the ones that discovered this fraud and we should all be praising them as they have done this recently for many other listed companies. In fact I will go further and wish that all auditors act exactly like them.
This is what happens though when the accounts are just full of revenues and receivables. WANdisco cash position was $28m lower than last year and this should have been a big red flag for every knowledgeable investor.
There are other similar listed companies that inflate their revenues and hence their receivables (as there is no cash coming in) and perhaps Paul and Graham must examine these.
Hi yiannos1,
Yes I agree - a huge increase in receivables is indeed a warning flag. However, in WAND's case the story stacked up - they had announced a whole series of big contract wins in H2 of 2022, so I would expect some of that to be in receivables.
Although I do remember expressing surprise here at how low the revenues number was in one of its trading updates, and briefly went wobbly on WAND, going from green to amber. But then another big contract win announcement came out, and I was reassured.
There's no denying that WAND was high risk, and we've discussed all that extensively here, but I was just too gullible in believing the things the company told us. It always looked too good to be true. Turns out it was!
I'll collect my thoughts on this, and do a post mortem article and/or podcast, as I think this is the first time I've personally been hit with an outright fraud. In the past, I spotted and vigorously flagged up the obvious telltale signs at Quindell and Globo (29 negative articles on that one, for example!). The big lesson here with WAND is not to rely on just the contract win announcements, because they're so easy to fake.
I remember many years ago discovering that one small listed company was boosting its revenue growth (from almost zero) using circular deals - so it would entice a big customer to sign a sales contract by agreeing a side contract (not disclosed!) to buy some services (high margin) from the bigger company. I was told that by a disgruntled former employee who had been made redundant. There are so many ways that unscrupulous people can pull the wool over our eyes. Some investors argue that we should ignore everything management say, and instead privately investigate the company by talking to staff (especially ex staff), and customers. Not always easy to do though, but on the few occasions I have done so, it's been very revealing, with the companies I thought were great apparently being a complete shambles internally (eg Asos)
Regards, Paul.
In WAND's case, what is the benefit of this if it is an outright fraud though? CEO / MGMT have been buying and not sold heavily in to the rise, unlike GBO where the CEO was bailing out all the while.
Any thoughts how they benefit from this outcome?
One obvious answer is that if you have rich connected people who are short right now they could be potentially making a killing. Its not unheard of for directors to short on the basis they own shares and not declare that to the market.
I'll collect my thoughts on this, and do a post mortem article and/or podcast, as I think this is the first time I've personally been hit with an outright fraud.
Paul, I avoided this one using one of my golden rules. And it seems that you spotted the telltale yourself. You regularly described the CEO as “super-bullish” and I agree this is a fair description of his demeanour in presentations.
I don’t check the public persona of every CEO of my holdings. But when swithering over an investment I always take a look at the boss. And I just found Mr Richards’ rampy confidence off-putting - not to mention his agricultural interpretation of a tech bro’s gilet. I’m looking for quiet confidence and soothing competence, not over-reaching bullshit. He simply failed my sniff test, which I’ve found to be very helpful in avoiding trouble - I was given a hard time by some commentators here over my discomfort with the CEO of a certain Israeli adtech business whose shares have since collapsed. I wish holders well nevertheless.
So, if the CEO sounds too good to be true, or you just don’t like the cut of his jib, he’s either obfuscating or incompetent and he’s after your money.
I agree with you on that. Supper bullish CEO’s scare me. Some times you just get the feeling you don’t trust them and you should always pay attention to that. There is always another company to invest it. FOMO comes to mind.
One ceo I recently had this feeling with was Vic from Saietta (LON:SED) from watching one of Paul Hills interviews. I find it disgusting how Paul Hill promotes companies like Saietta (LON:SED) Revolution Beauty (LON:REVB) and Totally (LON:TLY) with such bullishness as if he owns them himself, when in fact he is just being paid to do it.
I do hope the bod of WANdisco (LON:WAND) get slaughtered for this as it is their responsibility in the end. They have caused a lot of pain to investors and I’m sorry for those that hold. It’s a horrible situation. The only positive will be if investors can learn something from this.
Dont think anyone will ever top the cheek of Rob Terry (Quindell) - hmmmm what is he up to nowadays - not sure he ever got any commeuppance at all. Im sure the ex globo guys are presumably having a ball in some nice sunny tax haven.
Yes. Rob Terry had previous form as well. He is probably onto his next scam.
I did look a few weeks ago into Globo and "4 Nov 2022 — The Financial Conduct Authority (FCA) has commenced civil proceedings against the former CEO and CFO of Globo Plc for alleged market abuse."
Only taken 7 years.
Globo - But no criminal proceedings........
RM
re Rob Terry
Yes, you are correct. Nothing ever came of the SFO investigation. He's a free man. Not quite sure how much a vineyard costs, but I suspect it is beyond the price range of most of us.
Estate & Hotel | Quob Park Estate
I don't have plans to visit anytime soon....
I'm really sorry Paul about WANdisco (LON:WAND) as I know you bought in. But you cannot predict fraud. I remember being done with the Patisserie Valerie fraud. Horrible.
Apparently, according to "The Signs Were There" the giveaway with Patisserie Valerie was that they had >180 days of freshly baked croissants in inventory. Not sure I'd ever have spotted it myself without hindsight, and the auditors didn't.
My morning smallcap tweet: Tragic WAND
WANdisco (LON:WAND) EnSilica (LON:ENSI) Global Ports Holding (LON:GPH) Alpha Financial Markets Consulting (LON:AFM) Verici Dx (LON:VRCI) Iqe (LON:IQE) Billington Holdings (LON:BILN) Xeros Technology (LON:XSG) AFC Energy (LON:AFC) Litigation Capital Management (LON:LIT) NWF (LON:NWF) Franchise Brands (LON:FRAN), Silver Bullet Data Services (LON:SBDS)
◄WANdisco (WAND)► huge fraud by sales employee. FY22 rev could be as low as $9m, not $24m plus no confidence in its announced FY22 bookings expectation. Significant going concern issues. Shares suspended. [SP=1324.41 Cap=905m]
◄EnSilica (ENSI)► £2m placing and £0.5m retail offer at 70p, a 5% discount, for working cap for "additional sector and contract momentum, which has exceeded original estimates". [SP=75.7 Cap=57m]
◄Global Ports (GPH)► wins 15-year cruise port c. oncession for Alicante Cruise Port following previously announced preferred bidder status. [SP=164.5 Cap=105m]
◄Alpha Financial Markets Consulting (AFM)► guides FY23 results significantly ahead of market expectations. Strong double-digit organic net fee income growth. [SP=432.5 Cap=494m]
◄Verici Dx (VRCI)► two key patents for Tutivia and Clarava granted in the US. [SP=8.65 Cap=15m]
◄IQE (IQE)► guides FY22 in line but expects H1'23 rev down c.£30m due to weak demand and inventory build-up. "This near-term market softness is expected [hoped?] to be temporary." [SP=46.78 Cap=376m]
◄Billington (BILN)► guides FY-Dec pretax ahead of market expectations. Also same for FY23 due to strong demand. [SP=359 Cap=46m]
◄Xeros Technology (XSG)► second global license for XFilter filtration technology. 5-year, non-exclusive agreement. [SP=4.5 Cap=7m]
◄AFC Energy (AFC)► general update on H-Power Tower deployment. [SP=23.09 Cap=171m]
◄Litigation Capital Management (LIT)► makes A$5.75m gross from settlement in an Australian class action. [SP=70 Cap=83m]
◄NWF (NWF)► guides FY-May adj pretax £17.5m+, significantly ahead of market expectations of £12.3m. [SP=257.27 Cap=127m]
◄Franchise Brands (FRAN)► FY-Dec. Outlook confident. B2C div to be sold because B2B franchise sector offers better opportunity for organic, acquisitive and international growth. [SP=208.5 Cap=272m]
Good morning Paul and Graham, if you fancy a challenge maybe Jarvis Securities results will attract your attention? The Chairman pulls no punches and presents it as it is PBT down 20%, Div down 15% and EPS down 20%. We hold and do not anticipate a good reaction this morning.
.
ugly RNS from WANdisco (LON:WAND) :
"WANdisco (LSE: WAND), the data activation platform, provides the following revision to its anticipated trading performance and financial position.
Following investigations undertaken by the CFO and CEO, and as reported to the Board of Directors of the Company (the "Board"), significant, sophisticated and potentially fraudulent irregularities with regard to received purchase orders and related revenue and bookings, as represented by one senior sales employee, have been discovered. These irregularities give rise to a potential material mis-statement of the Company's financial position.
The identification of these irregularities will significantly impact the Company's cash position and lead to a material uncertainty regarding its overall financial position and significant going concern issues. The Board now expects that anticipated FY22 revenue could be as low as USD 9 million and not USD 24 million as previously reported. In addition, the Company has no confidence in its announced FY22 bookings expectations.
As a result, the Company has requested that its shares be suspended from trading on AIM while it conducts an investigation with its external legal and professional advisers into the nature of this activity and its true financial position.
The Company will make further announcements in due course."
https://www.investegate.co.uk/...
WANdisco (LON:WAND) shocking RNS! Bubble burst
Wow. I mean wow.
I only bought into the share a couple of weeks ago. Thankfully, just a small starter position. Still, shocking news. Makes you wonder about their internal controls - or lack of.
I nearly bought in this week, so sorry for holders…
I took a small starter position yesterday - typical!
Lucky you practise risk management and didn't go 'All In'. Phew.... unlike me! Now I've just got to decide what to do regarding my stop loss that hasn't been activated yet as i fear this may be a huge gap down event possibly.
I dont think a stop loss will help you. if it resumes it will be gapping down much lower than the suspension price.
That's what I'm currently pondering, question is... to cancel it in hopes of a recovery... or take the kick in the knackers?! (Although there is the rule of never lowering or removing a SL). Ah, the ancient internal battle of head, heart and hope is strong today!
the difference is neither here nor there. if this resumes trading it will likely be at a price far below your stop loss, if you keep the stop in place it wont trigger anyhow as the open will gap down.
How can this be allowed to happen in 2023…? This is nothing other than pure theft of shareholder value with absolutely nothing you can do about it.
Thankfully I don’t hold however I feel extremely sorry for those that do.
There should be automatic and extensive bans for any BOD members who allow their companies to trash shareholder value to the extent of the quoted numbers in this mornings update.
WANdisco (LON:WAND) could be a wipe out for Global Frontier Investments as well as they only have seven holdings and their holding in this was their largest - the dangers of concentration
All done under the radar, no use crying over spilt milk. Just wait it out and then move on.
Shocking! Lesson: Don't own a concentrated portfolio of less than 20 stocks, ideally 50 (2% each).
If anyone doubts the value of a stop loss, I got stopped out of WAND yesterday afternoon. When I saw the RNS headline I thought it was going to be more contracts and an upgrade! Dodged a bullet, but a reminder to stick with original stop loss plan as always tempting to give it more room. I hope no private investors are too badly hurt by the fiasco but the culprits are caught and jailed.
Greyster
not really...if your stop was so tight your original plan was very aggressive trading and not suitable for position sizing. Fairly unusually for such a situation, there is nothing in the chart to suggest scepticism/distribution/short selling, so you basically got lucky imo. WANdisco (LON:WAND)
Morning Paul/Graham. Would it be possible to add you UK mid-Cap Value report like your small-cab one. It's really a struggle to find information about mid cap stocks. No one else is interested in them. You guys are absolutely fantastic in doing the small cap report. If someone like you can comment on the Mid-Cap, that will be amazing. Thanks
hi all
Following my comment on yesterday's SCVR (timed at 4.44) regarding the disappearing tags issues I have received a reply from Stocko as follows:
Thanks for raising and 'yes' we are aware of the issue and definitely appreciate how frustrating it is. If it is any consolation we are aware of this issue, however I am not in a position to provide any timing on fix. We thank you for your patience and for taking the time to let us know.
Not very satisfactory really as no idea on a timescale for a fix so all we can do meantime is to continue to message Paul if / when tags drop off so that they can be re-applied.
Snazzy