Small Cap Value Report (Thur 13 June 2024) - PAY, TRCS, CRST. Brief: HLMA, WISE

Good morning from Paul & Graham (Paul has been making some contributions from his travels!)
We are all done for today now!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Mid-Morning Movers
Halma (LON:HLMA) - up 10% to 2581p (£9.85bn) - not one we cover here due to its size, but I’m flagging it here in the movers section, with a +10% market reaction to publication of FY 3/2024 results today. Adj EPS is up 8% to 82.4p, so PER looks well into nosebleed territory at 31.3x. Balance sheet is totally dominated by intangibles from multiple acquisitions, so nothing in NTAV support - which doesn’t matter for such a highly profitable group with a remarkable long-term track record - shares have 10-20 bagged (depending on the starting point price) in the last 15 years. Profit margins are impressively high. It does specialist life-saving products & technology, clearly a lucrative niche, internationally. Outlook comments also sound positive.
Paul’s view - clearly a high quality share, priced accordingly highly, but I certainly wouldn’t bet against this one, given its superb track record.
Wise (LON:WISE) - down 15% to 716p (£10.2bn) - loses £1.8bn of its market cap today on a poor market reaction to FY 3/2024 results. This is the second lurch down, so this challenger bank (or international payments specialist) has now lost almost 30% of its recent peak valuation in April 2024 (although it did achieve a higher valuation temporarily in the first few months after floating in 2021). Quite a volatile share, doing big swings in valuation, suggesting investors haven’t yet quite decided how it should be valued.
I recall looking at the numbers a while back, and it’s demonstrated a large increase in profits, thanks to higher interest rates on customer deposits.
Interesting numbers, with PBT more than tripled to £481m, but it then presents “underlying” PBT up 226% to £242m, which strips out interest income above the first 1%, presumably as it will have to pay that to customers? I see readers are discussing this below.
There’s not much balance sheet support for a £10bn market cap, with only £980m NTAV. Unlike conventional banks, where you can often buy at, or below NTAV. Anyway, no view from me, as I’ve not researched it properly, just flagging the significant share price fall today. The newswire says that’s due to the outlook saying underlying profit growth will slow to 15-20% in FY 3/2025.
Summaries
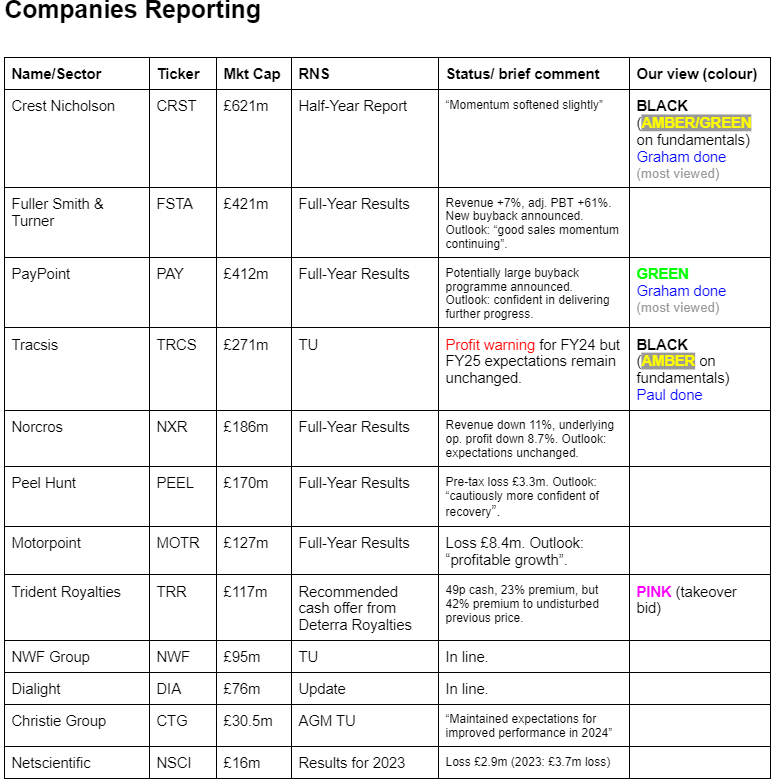
PayPoint (LON:PAY) - up 1% to 573.8p (£417m) - Final Results - Graham - GREEN
It’s a solid set of results but the real excitement for me is £20m of buybacks this year, with the potential for over £60m to be returned to shareholders over the next three years. With net debt currently at less than 1x adj. EBITDA, and the business trading well, it seems that the company can afford this commitment.
Tracsis (LON:TRCS) - down 9% to 815p (£247m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
Profit warning today sounds minor in the RNS, but is actually losing one third of the forecast FY 7/2024 EPS - quite serious, as it shows TRCS doesn’t have as much visibility as I assumed. UK election blamed, and slower contract signings in the US too. FY 7/2025 is unaffected, but now needs a 64% increase in EPS to hit unchanged forecast. This all makes me ponder the high valuation, which looks too aggressive now.
Crest Nicholson Holdings (LON:CRST) - down 8% to 220.8p (£567m) - Half-year Report [profit warning] - Graham - BLACK (AMBER/GREEN on fundamentals)
Another profit warning and a big cut in the interim dividend payment to go with it. These shares were already trading at a chunky discount to balance sheet numbers so pessimism was already priced in to some extent. Without having much conviction in this statement, I do still see some value here.
Paul's Section
Tracsis (LON:TRCS) - down 9% to 815p (£247m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
Tracsis (LSE: TRCS), a leading transport technology provider, provides the following trading update for the year ending 31 July 2024.
“Impact of UK General Election timing; FY25 expectations remain unchanged”
The PR headline is steering us towards seeing this as a one-off, hence not too important, and that seems to have worked, with only a 9% share price fall in early trades. TRCS shares seem quite tightly held by fund managers mainly, and surprisingly illiquid, so the price can do erratic moves on a few trades, e.g. this morning it’s been marked down 9% on just 16k shares trades printed so far.
What’s gone wrong?
It blames the UK general election -
The pre-election restrictions are temporarily impacting central government, local authority and Train Operating Company decision making and spending across the UK transportation sector. This action is resulting in the rescheduling of certain projects and a short-term contraction of new order activity, that was previously expected to occur in the Group's Q4 financial period.
However, there are also contract delays in the USA -
In the Group's April 2024 Interim Results statement, we highlighted risks in converting our North American pipeline before year end. While these opportunities continue to be pursued, the Board now expects that associated revenue will not be realised within this financial year.
Combined, these two factors have hit EBITDA -
“...strong operational gearing within the business, this will have a material effect on the Group's FY24 adjusted EBITDA margin.”
Mitigating actions - none, as it sees this as a short-term glitch.
Revised guidance -
“FY24 revenue is now expected to be in the range of £80.0m - £82.0m1
1 Analyst consensus range for FY24 revenue was £84.0m to £85.9m, with average analyst consensus being £85.2m, as at 12 June 2024.”
We are sent round the houses a bit with the profit impact -
“FY24 adjusted EBITDA* margin is expected to be slightly higher than the 15.5% delivered in H1 2024 but below analyst consensus market expectations
Broker update - as is often the case, whilst the PR can smooth over the issues in an RNS, the size of the problems only becomes apparent from the big reduction in broker forecast profits. And this is a surprisingly large miss, due to the delayed contracts containing high market licensing revenue.
For FY 7/2024 -
EBITDA forecast comes down from £17.4m to £13.1m
Adj PBT forecast down from 39.7p to 26.7p, making the PER now look much too high at 30.5x - why have a premium rating on a share that has now demonstrated no profit growth in the last 3 years?
FY 7/2025 forecast is unchanged at 43.8p EPS, which now requires a 64% rise vs revised FY 7/2024 numbers. Even if it achieves such a big jump in earnings for FY 7/2025, we’re being asked to pay up front for it, with a forward PER of 18.6x.
Paul’s opinion - whilst the UK election may be a one-off event, we knew it was coming, so the exact timing should not have made a difference to forecasts. Missing numbers by a lot, very near the end of the financial year worries me. It shows that Tracsis is still heavily dependent on lumpy contract wins, since these issues presented as relatively minor have just lopped off a third of the expected EPS. That shouldn’t happen at highly rated companies.
They should be budgeting more conservatively, with some slack to accommodate any unexpected delays.
Which makes me question the high valuation. I don’t want to invest in shares where I have to hope for, and pay up-front for, a 64% increase in profit.
After this significant mishap, I think TRCS shares are now looking much too expensive. There’s nothing actually wrong with the business, so I can’t mark it red or even amber/red just for being too expensive, but I definitely can’t go above our previous view of AMBER on fundamentals. Today’s profit warning does I think demonstrate that it’s not as good a business as people might think, given that profits are fairly unpredictable based on a few contract wins. It doesn’t give the split between the UK election impact, and the problem with US orders.
800p per share looks way too high. I’d be looking at more like 500-600p to even consider taking a position here. Highly rated companies have to hit or beat forecasts, missing them by a mile near the year end is a very bad look.
Graham's Section
PayPoint (LON:PAY)
Up 1% to 573.8p (£417m) - Final Results - Graham - GREEN
I added this one to my list of favourite ideas for 2024, so let’s see what the company has in store for shareholders today.
The main news appears to be a three-year share buyback programme. It’s unusual for companies to announce what they are going to do over a three-year period, but PayPoint have given themselves plenty of wiggle room.
They will return “at least £20m to shareholders over the next 12 months, with the potential to increase in years 2 and 3”. So while there is no absolute commitment to do this, there is a possibility that we are talking about a total buyback programme of more than £60m. That’s nearly 15% of last night’s market cap, so it is a substantial number.
As for the trading performance of the business, here are the highlights.
Net Revenue: up 3.3% in the existing PayPoint business, but up 40% in total if you include the new contribution from Love2shop (what used to be called “Appreciate”):

Underlying PBT: up 0.4% organically, or up 21.5% in total, to £61.7m.
Adjusting items: there are more intangibles being amortised now, so there are more adjusting items than before.
Actual PBT: up 13.1% in total to £48.2m.
Net debt: reduces from £72m to £67.5m.
The company is looking to have a leverage multiple (net debt/adj. EBITDA) of about 1x, i.e. for net debt and adj. EBITDA to be approximately the same.
With adj. EBITDA of £81m and net debt of only £67.5m,, we can understand why the company feels that it can afford to both increase its dividend and embark on a buyback programme.
CEO comment:
“This has been another year of progress for PayPoint where we have delivered a robust financial performance and made further progress towards delivering £100m EBITDA by the end of FY26. These results reflect both the resilience of our businesses and the transformation delivered over the past three years as we unlock further opportunities and growth across our four business divisions.
In the current year, consumer behaviour across a number of our businesses remains subdued, reflecting continued tighter family budgets and a generally flat economy. Our expectation is that the consumer outlook will improve during the course of the year.
Divisional highlights
Shopping - revenues up 3.9% to £64.6m. A mature business mostly serving independent retailers (70% of sites)..
Payments & Banking - revenues down 4.8% to £53.5m. Some parts of this division are in secular decline.
E-commerce - revenues up 61.6% to £11.8m. Super-fast growth at Collect+.
Love2shop - £51.3m of revenues. This business also declined in organic terms but as a newly-acquired division it has boosted PayPoint’s overall growth figure.
I’m still intrigued to see PayPoint’s plans for the Love2shop/Appreciate business, as that’s one that we commented on regularly when it was a standalone business. It includes both the gift voucher business and Park Christmas Savings.
In the commentary today, the company says that gift voucher billings were down “due to the broader caution from larger businesses, particularly with employee rewards”. The corporate sales team has been restructured and furthermore:
There is now a strong pipeline of new business building into the current financial year and much closer alignment with the business development team in PayPoint, driving revenue opportunities within both client bases.
An important synergy already being unlocked is the rollout of physical gift cards to retail locations. 2,600 locations were reached for Christmas 2023 (at multiple retailers), and independent retailers are being reached in the current year.
Other forms of progress have been made at Love2shop, too:
A number of major brands were also added in the year to Love2shop as redemption partners, including B&Q, Currys, Adidas, WH Smith, Matalan & Blackwell’s and a successful refresh of the Love2shop brand was delivered.
Graham’s view
Many investors see this as a business in terminal decline. I agree that’s true for some parts of PayPoint, but I view other parts as stable and others as quite exciting!
Its cash generation has always been excellent, and I’m pleased to see that it’s now directing some excess cash towards buybacks instead of dividends.
At this sort of valuation (modest single-digit PER), I much prefer to see cash being used to reduce the share count instead of being spent on dividends. The dividend yield here is already very large:

In summary: I have zero regrets about putting this on my top 10 list for 2024, and I have my fingers crossed that it continues to trade well for the rest of the year.

Crest Nicholson Holdings (LON:CRST)
Down 8% to 220.8p (£567m) - Half-year Report - Graham - AMBER/GREEN
Let’s investigate the key bullet points from this housebuilder’s interim report:
Revenues down 9% to £257.5m, “reflecting the low level of reservations at the beginning of the financial year”.
H1 completions 788 (H1 last year: 894).
Sales per outlet per week 0.47 (H1 last year: 0.54).
As flagged by Paul in March, the costs associated with previous work have increased. The one-off charge is £31.4m (previous estimate: $15m). “The increased charge is due to a wider scope of the review to cover all completed sites”.
Adj. operating profit £6.2m (H1 last year: £22.1m).
To get this figure, the company treats most of the £31.4m one-off charge as “exceptional”.
Even if we treated the entire one-off charge as exceptional, we would still only get an adjusted operating profit of £12m.
Actual loss after tax (including all costs considered “exceptional”) is £23.4m.
Interim dividend is slashed to only 1p (H1 last year: 5.5p).
Net debt £9m, and the company has a £250m undrawn RCF implying huge amounts of available liquidity.
Outlook
Points on inflation - build cost inflation is “flat year on year and we expect these conditions to continue in the remainder of FY24” (i.e. until October).
The outlook is mixed, with some unhelpful factors at play:
The spring selling season started well with positive housing indicators in an improving macro backdrop. Momentum has softened slightly since Easter, reflecting the volatility in mortgage rates and the expectation of a base rate reduction coming later in the year than previously expected. The imminent General Election is creating some short-term uncertainty, but this is anticipated to be alleviated in July once the outcome is known.
As a result, and including the one-off pre-exceptional charge for completed sites, the Group expects FY24 adjusted profit before tax (APBT) to be between £22m to £29m.
We get the following guidance table:

At the trading update in March, the company said it was looking for 1,800 to 2,000 completions, so this is a reduction of the top end of that range.
The previous consensus adj. PBT estimate was £38.9m, so this is a major profit warning.
And the adj. PBT estimated range is still very wide, making it difficult to treat any earning multiple here with much seriousness.
Note that even at the top end of the range, earnings and margins would still be far below previous levels:

Many of us prefer to focus on the balance sheet with this type of stock, so here are the key points from the latest balance sheet. Net assets are £803m, down from £856m six months previously (due to a combination of dividend payments and the after-tax loss).
Deducting intangibles from the total, we have a TNAV of £774m. The market cap is at a 27% discount to this figure. Or looking at it another way, the share price would need to increase by 36% for the company to trade at its TNAV.
Comment by the outgoing CEO:
We have made some important operational progress in the first half of the year against our strategic priorities. We are on track to achieve a five-star customer service rating, have a clear and comprehensive plan to resolve the legacy and operational issues, and continue to focus on maintaining a strong balance sheet.
"The Group is continuing to focus on completing its low margin sites, with FY23 and FY24 being the peak years of impact and the majority of the remainder expected to be traded through during FY25. Going forward the Group will benefit from its high-quality, higher margin land portfolio, and with an increased commitment to operational efficiency and control, is well-positioned to capture growth opportunities as market conditions improve."
Graham’s view
I tend to agree with Paul that AMBER/GREEN is the right stance for us to take on this share. It’s an attractive discount to NAV, but it’s difficult to have confidence given the provisions/one-off charges that the company has suffered, and of course the profit warnings!. That said, there is still a gap of over £200m between TNAV and the market cap, so there is still a large cushion to absorb future problems.
With the dividend getting cut dramatically, that removes in the short-term one way that value might have been delivered to shareholders. However, it’s understandable that the company might not want to see its net debt position grow much larger.
So how can this play out favourably for shareholders? First, I would almost completely ignore the short-term earnings multiple here. The big question is whether margins will recover to previous levels in future years - this seems plausible to me, based on commentary from the outgoing CEO.
Secondly, will there be more one-off charges? Unfortunately, I’m not able to answer this question, as it’s beyond my pay grade.
Thirdly, is there any other catalyst that might boost the share price? Dividends are out and I assume that buybacks are too, as the company needs to conserve cash in the short-term. The only other catalyst would be some form of takeover. There has been some activity in the sector.
There are too many possibilities here that are beyond my ability to predict, so I can’t be outright positive on this one. However, I do think that portfolios filled with bargain stocks (based on their balance sheet values) tend to do quite well overall. CRST does seem to be a bargain from this point of view.
Note that homes under construction and show homes are considered “inventories” under accounting rules, and are therefore “current” assets. On that basis, CRST is not just a TNAV bargain (based on tangible assets) but is also a “Net Current Asset Value” (or NCAV) bargain, under Ben Graham’s old rules.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
TRCS. I am puzzled. If orders have been been deferred from the current FY then why has the next year not seen a corresponding uplift rather than remaining in line?
Crest Nicholson Holdings (LON:CRST) Industry commentator bid story
https://reactnews.com/article/...
https://reactnews.com/article/...
Wise (LON:WISE) (I hold)
Hi Paul (or Graham...or both)
"PBT more than tripled to £481m, but it then presents “underlying” PBT up 226% to £242m, which strips out interest income above the first 1%, presumably as it will have to pay that to customers?"
What if they're never able to return the excess profit due to continued licensing restrictions?
What if interest rates drop below 1%?
----
As I'm here, these are my notes from today's update:
New Customers keeps going up.
% PY customers churning continuing to decrease
----
And on a final note, the Market Cap for Wise (LON:WISE) in Stockopedia is materially incorrect.
It should be c.£7.5b, not c£11b.
The difference relates to the types of share in issue and their nominal values.
Both Google Finance and the LSE are showing £7.5b
https://www.londonstockexchang...
https://www.google.com/finance...
Presumably Serica Energy (LON:SQZ) is down so much because of labours manifesto :/
Today's fall pushes the yield on the dividend going ex at the end of the month to over 9%. I hold and topped up two days ago on oil price recovery.
Serica Energy (LON:SQZ) produces 5% of UK gas and if using a 80:20 gas/hydrogen blend was to become a viable part of the green transition the valuation would be significantly higher.
Yes, I have been tracking Serica Energy (LON:SQZ) as it falls (remembering that there's a 14p dividend due if you are holding on 27 June) and wondering whether to buy. But I think the market is right - profits will be taxed heavily for years to come, leaving little for shareholders. So i am staying clear despite the temptation of a big discount to NAV and that chunky dividend. Commiserations to holders, the fall since the start of the year has been pretty brutal.
Serica Energy: tradition meets modernity (substack.com) - good read on Serica Energy. I hold and my largest holding.
Thanks Iceman - as you say, a good read.
Jersey Oil and Gas (LON:JOG), junior farm out partner, down 18% too after the relief rally.
https://labour.org.uk/change/m...
H & T (LON:HAT) Hi. Can anyone shed some light on the recent deterioration of the PEG & EPS growth numbers for HAT on the Stocko dashboard? The PEG was 0.4 in March when Graham reviewed (positively) the full year results. Now it is showing as n/a and a negative EPS growth. I am holder but not worried as I suspect this must be due to accounting standard changes (IFRS 9?) which was mentioned in the full year results by the CFO. Or else dodgy data. Broker estimates have not materially changed in the intervening time. If anyone has an explanation it would be much appreciated! Thanks
I see Marlowe (LON:MRL) is down over 23% but cant see RNS or news on open sources. Any ideas why the fall at the opening................
It went ex-divi on the special div
It went ex-div today, very large special dividend.
£1.55 per share, to be precise, so the share price is actually up a little on the day.
I wouldn’t worry too much about Marlowe (LON:MRL) - Mike Ashcroft, a non-executive director, bought £18m worth a few weeks ago.
Hi Paul, can you check (LON:SPSY) it is down 7% on no news that I can see ?
Thanks
Is today the ex dividend date please?
Yeah your right it is the ex divi date. Should have realised!
£HLMA What a superb business. Dividend raised by at least 5% in each of last 45 years. The compounding effect of that is wonderful - apart from capital gain (thankfully in ISA) yield on my purchase about 20 years ago now in double figures. Makes up for some of the dogs - a reminder that best to stick to quality.
On Halma (LON:HLMA)
They have perdormed well for more than 45y. I was briefly involved with their pension scheme in the late 1980s and they had top quality management who were in their 40s and 50s back then - and they had been there for some years.
They have arguably into their third generation of management. I do not know if their success is due to the market sector they are in or the management culture.
Every few years I would think of buying some and each time thought 'a bit pricey'. And still think that.
Halma (LON:HLMA) (I hold). Just finished watching the analyst presentation and listening to the questions. I have slowly increased my holding in this company over the last 6 years, so it is now my largest holding and was very pleased to see the new CEO (previously CFO) really growing into his job, with a confident and clear presentation.
It is an excellent business with that great combination of being an acquisitive company that focuses on growing organic revenue and creating the cashflow through the high operating margins to invest in acquisitions which grow the group without the need for additional equity.
I was also pleased to see the new CFO focus on cash, so that cash conversion for the year was 103%, which is one of my main criteria.
Incredible track record, which comes with a high p/e multiple. It reminds me of one of Terry Smith's Fundsmith letters where he goes back with some of his best investments to see at what p/e it would have be worth buying them. I think L'Oréal was over 100.
Georgia Capital (LON:CGEO)
Georgia Capital's stake in Bank of Georgia (LON:BGEO) currently worth slightly more than the entire Market Capitalisation of Georgia Capital (LON:CGEO) . So all the other investments are thrown in for free
Decided to buy a small starter stake.
Georgia's political situation a bit chaotic at the moment so not for widows and orphans.
A.
Georgia Capital (LON:CGEO) and Bank of Georgia (LON:BGEO)
There are good things to say about these, and I guess it is a question of where you are calling the bottom on the current retreat.
I am currently sat on the sidelines, but will reenter at somepoint.
Good Luck
Tommy
Re PayPoint (LON:PAY) , does a buyback programme always count as returning money to shareholders, or only if there is a commitment to cancel the shares rather than keeping them in treasury?
Hi FREng I've always wondered what the difference and benefits is between complete cancellation of shares and cancelling but then holding in treasury if anyone can educate me would be appreciated.
Regards
Andy
If held in Treasury, shares remain in issue and can be reissued again (i.e. to employee share schemes etc), but if Cancelled, they are cancelled and no longer in existence.
Many thanks that was my loose understanding it would appear to me the treasury route is the better option as you effectively can reissue the shares at a later date if needed I would imagine at a lower cost than if you had to organise a placing or rights issue.
I'd probably disagree on that. Share cancellation is probably the better route especially if dividends are healthy, as that becomes a virtuous circle for shareholders. At the level of the proposed purchases by PayPoint (LON:PAY) I would hate to think they all go into Treasury. Some maybe to hedge options, and preserve a bit of flexibility for acquisitions (share + cash offerings) but prefer not to see the the share buy back benefits to be deferred to some unknown date.
I have sold Tracsis (LON:TRCS) this morning based on the simple principle that I expect that the share price in 1 month will be lower than the price that I can sell for now.
Hi Graham. Thank you for the analysis of PayPoint (LON:PAY) . It’s very useful to me as it’s one of my largest holdings. I have been hoping that today’s update might be the trigger for PayPoint (LON:PAY) to breakout from its base. I suspect it will now contribute well to the returns of your top ten (which is already looking very impressive). Thanks again. Keep up the awesome work.
Hi Revs8, I appreciate the comment, thank you and good luck! G
Some general and stock specific thoughts.
The market, especially in small caps is currently pants, with liquidity equally so. I doubt there will be any improvement until after the election, unless Andrew Bailey and his acolytes find their philanthropic inner self and cut interests rates this month, which I very much doubt.
Regarding the election, all I will say is that in my view a change is needed, whether Labour will do any better that the Tories is another matter , but I doubt they can do any worse. Enough of politics and on to shares:
Bloomsbury Publishing (LON:BMY) and Property Franchise (LON:TPFG) I have no crystal ball, I am glad to say and the future will be what it will be, but having watched the recent webinars from both companies and read the RNS on the recent acquisitions, I am of the opinion that both will beat current market expectations.
Regarding the former, Nigel Newton said somewhat coyly in his summing up of the recent results, that Bloomsbury had a great March, a great April and a great May, hence the slight upgrade on the current year announced in the prelims. This was before the US acquisition of Rowman and Littlefield that will contribute to the current year.
Regarding Property Franchise (LON:TPFG) From the recent prelims
Q1 Trading and Outlook
·
Q1 has been ahead of management's expectations in terms of both revenue and profitability
·
Lettings market continues to grow at pace, with anticipated growth in sales revenue in 2024 amidst an improving sales market
From the AGM update on 7June:
" Notably, their lettings' revenues have continued to grow at similar rates to last year and the sales-agreed pipeline at 30 April 2024 was 20% up on the same period in FY23, signalling a much stronger sales market so far in FY24."
The merger with Belvoir has provided Property Franchise (LON:TPFG) with a significant financial services operation, which, will be a beneficiary from a fall in interest rates and the improving picture in house sales.
I also note that Louise George, the former CFO and Company Secretary of Belvoir has recently been appointed Company Secretary, added to which David Raggett, the current CFO of Property Franchise (LON:TPFG) has announced is intention to resign, I think at the end of FY25. The former's appointment may be a coincidence, but I would not be surprised if Louise George is eventually appointed CFO to replace David Raggett. Now that would be a good appointment in my view.
Finally infrastructure related companies have also come off with the rest of the market, Galliford Try Holdings (LON:GFRD) more than some. I have a lot of time for Bill Hocking, the CEO who has turned the company around. Galliford has continued to win contracts and has a significant presence in infrastructure, in particular the water industry, it is more highly rated than Costain and Kier , but is my preferred choice in the sector. Whoever wins the election is unlikely to curtail spending on hospitals, schools etc.
Also the forthcoming AMP8 (Asset Management Plan for the water industry) that starts next April will be significantly larger that its predecessors and I expect Galliford to win more than its fair share of the work.
I top sliced Bloomsbury Publishing (LON:BMY) after the results, but have started to add back post the acquisition of Rowman and Littlefield. I have also added to Property Franchise (LON:TPFG) and this morning added a few Galliford Try Holdings (LON:GFRD) at 234p.
I would add more but remain fully invested at present, but will wait for the dividends from PayPoint (LON:PAY) and tender offer from Palace Capital (LON:PCA) and see where the prices are at that time.
Just my views. Whether I have read the tea leaves correctly, time will tell.
All the best
Wise (LON:WISE) down today on revised forecasts of 'just' 15-20% income growth. Only 50 + times the growth rate of uk gov 2024. Vote WISE!
I'm surprised too about the big drop in Wise (LON:WISE) .
Headlines and bullets at the start of the results RNS looked good?
I think revenue was a big miss as well, but net profit beat.
Tracsis (LON:TRCS) - thanks for the comments Paul, I agree and have sold out this morning. Also don't understand why the revenue that has slipped from this year to next hasn't caused an upgrade to next years forecasts. Given it's not disappearing into thin air, has something else been lost from next year they haven't mentioned? Have less faith in the accuracy of next years forecasts in any case, hence why I sold out. Expect better from a co this highly rated as you say.
Hi Gary. Tracsis (LON:TRCS) . It's always a red flag for me if a company says that some revenue or profit has slipped from FY1 into FY2, and they decrease FY1 estimate but fail to make the corresponding increase in the FY2 estimate. It suggests to me that they are not being honest or do not want to reveal the full picture.
Looking forward to reading the Raspberry Pi write up.
Raspberry PI review is in the pipeline! Time diff in Washington DC is a problem. I was in the air yday & was about to type up my notes on plane, but Chromebook refused to work on plane. So pls bear with me!
There’s speculation that a Labour government might curtail or even entirely rescind the IHT relief that can accompany owning AIM-listed securities. What are other subscribers’ view? Would it simply be too damaging to the market for capital raising and the secondary market which already lacks liquidity for the smaller companies?
Hi Jayman - No, I can't realistically see any party doing this.
It would almost certainly reduce inflows into VCT and EIS funds which are the life blood for the UK economy wrt growing early stage businesses. Too negative for job creation & Britain's tech future.
Hi Paul
I don't think IHT Business Relief has ever been available on VCTs.
EIS investments do qualify for BR but as far as I am aware, very few AIM shares would qualify now for EIS relief.
Thanks Roger, although a significant number of AIM shares do qualify although there in us is on the investor to make its assessment and it only counts if it remains eligible for BPR at the time of death or transfer
More likely a hike in CBT by Labour? I expect the publication of their manifesto today MAY clarify their stance on the matter https://www.cityam.com/it-woul...
It would be the death of entrepreneurship’: City alarm over Labour capital gains hike
"It would be the death of entrepreneurship’: City alarm over Labour capital gains hike"
what nonsense - taxes get cut hiked and changed - life goes on .
If ones trade is to be an entrepreneur why should you pay half as much tax as someone who isnt ? the answer probably is you probably shouldnt be paying half the tax rate.
Hmmm, incentives...... because entrepreneurs often put their homes on the line and take huge risks , frequently losing and failing... an employee isn't under the same pressure....
Hmmm, incentives...... because entrepreneurs often put their homes on the line and take huge risks , frequently losing and failing... an employee isn't under the same pressure....
I am not against incentives and not against lower taxes as such - the facts are though it most certainly will not be "the death of entrepreneurship" just because taxes rise a bit so they get a bit less of a discount than others. This is clearly billshit nonsense of the highest order suggesting otherwise.
In many respects the tories have been quietly raising taxes the last 10 years that they would themselves have said "this will stiffle" had they been opposition - look at the recent hike in corporation tax rate to 25%.
an employee isn't under the same pressure....
for the pressure they get the reward of 5x 10x or 100x earnings - its pretty clear to me why people go into business mostly.
Note alot of big business - what you would call entrepreneur - probably makes more due to the fact they can more easily avoid taxes that smaller people who pay standard ish tax rates would need to pay.
I'm not going to engage in swearing or politics as this environment thankfully isn't the place for it... I think that you under estimate the risk reward calculations of incentives .... and the role that many small and mid sized businesses play in pro growth and employment creation...
I think that you under estimate the risk reward calculations of incentives
nope i dont - i deal with entrepreneur on a daily basis and their needs and wants - all i said was this will clearly not be be "the death of entrepreneurship" no more no less. Clearly anyone who thinks this with sound death bell for entrepreneurship in this country just becase taxes go up imho hasnt got the foggiest and are clearly spouting stuff thats their juandaced viewpoint - in the real world day to day activities that include tens of thousands of entrepreneurs will most certainy carry on pretty much as before whatever labout throw at them. Happy to provded wrong if that does not turn out to be the case.
Note there is a huge difference betyween saying something will die and something will be be materially affected.
We were questioning your unhappiness that entrepreneurs get incentivised tax treatment...
I would say the headline corporation tax is quite misleading given the large number of reliefs and allowances available which can substantially reduce liability for some companies
Hmmm, incentives...... because entrepreneurs often put their homes on the line and take huge risks , frequently losing and failing... an employee isn't under the same pressure....
Interesting. Do business owners (I dislike the term entrepreneur) often put their homes on the line?
Are employees not under pressure when the business they work for is failing? Is their home then at risk?
I have been involved in supporting and/or acquiring small businesses over the years and did not come across any business owners (those with the most equity) who had secured company loans against their house. Not saying it doesn't happen but in my world it didn't seem to be common. Generally the business could not get facilities from mainstream finance and used alternatives, factoring, convertible loans or mezzanine/pref equity at very high cost. Sad really because if they had had access to reasonable finance they would not have been in so much trouble.Conversely the employees were often under great pressure, sometime with equity or options, often with low pay and sometimes unpaid for periods.
After being an executive director I was subsequently a self-employed sole trader for many years - without the benefit of limited liability company protection - and placed all my assets at risk, albeit low risk, every day I traded.
It seems to me that the reality of being a successful business founder and owner is not to take high risks and to only take risks where the risk/reward is hugely in their favour? I find that its not so different from being a successful investor of my own capital?
cheers
Mark
Interesting. Do business owners (I dislike the term entrepreneur) often put their homes on the line?
If by that you mean enter into contracts (employment, deliverables, time and materials etc) that create obligations and expenditures which, if projects fail, would potentially ruin them. Then I would say this is more common than you imagine. I can think of multiple examples on a small scale in my home town and amongst my acquaintances. On a personal level, it exactly describes my first serious venture, when I put my accumulated savings and my house on the line. After that, the risks were never the same. But boy did it feel scary that first few months!
Business owner if you do it once. By the third time, you’re an entrepreneur!
Entrepreneurship often requires taking risks to your life that ordinary employees do not take (ask their partners and children!). I have no problem with helping such people get funding and thus tempting people into this - very necessary - part of the economy with tax breaks that are so far, I believe (but would like to know), of modest cost.
Because someone who isn’t is likely suckling the teats of the state and is being paid out the income tax receipts of said entrepreneur and his employees
I think we need to look more holistically at the taxation of investments and shares in particular - on income/dividends received, reliefs available, and on capital gains (noting the unfairness of taxing gains versus inflation adjusted gains).
For shares dividends are now very highly taxed versus other countries and gains modestly but we need to look at both in aggregate. Care need also to be taken to look at how the rate charge will influence when gains are actually crystallised. The smart money have been selling investment properties and businesses in the last 18 months assuming CGT would be going up.
Also relevant is that most investors are using tax free wrappers such as SIPPs or ISAs.
One abuse of the English language during this election campaign is the term “loop hole” when most often this refers to allowances and reliefs which have been explicitly granted with clear rationales (anything which disturbs the assumption that thrifty savers should really be a herd of compliant milch cows)
I think we need to look more holistically at the taxation of investments and shares in particular
For shares dividends are now very highly taxed versus other countries
100% agreed (for those paying 25% corp tax plus h rate tax on dividends that starts at 50% effective rate on earnings and goes up from their which is bleeding one dry somewhat) - i dont agree with many of the recent changes done by the current powers that be or many of the intended changes coming in from labour. In that regard though taxes have to come from somewhere - and i dont want to borrow out from future generations - so i do understand taxes may be imposed that arent particularly fair to some.
The smart money have been selling investment properties and businesses in the last 18 months assuming CGT would be going up.
the smart money probably planned for that possibilty probabilty 10-15 years ago.
It would certainly be stupid to cancel IHT relief on AIM shares as it would undermine investment in small cap companies, but with Labour where dogma tends to lead you cannot bet on it not happening.
But let's also remember that recently it was a Tory, a year before becoming Prime Minister, who said "Fu*k Business"
Here is an article I posted a few years ago on AIM and IHT relief. The sums involved are significant.
Inheritance Tax: The Exposure of AIM to Business Relief
Norcros (LON:NXR) i await the day keenly when this company elicits a green rating from the powers that be -same odds as scotland getting out of the group stages of a major footy tournament - no green ticks as of yet but always hope.
I always like to go to the pension detail in the year end/interms figures and annual report to see that everything is progressing nicely - this scheme still has decades to rin but is a super mature scheme. Its probably not straightline progress but the scheme liabilities have been in clear decline for a few years now - thats important for us investors as the lower the liabilities get the less the scheme assets have to perform each year to ensure shortfall does not increase (they drop in sympathy too) - same principle as life gets easier when one starts paying down teh capital on ones mortgage.
scheme surplus up a tad £16.5 mill
present value of scheme liabilities dropped £10 mill and scheme assets dropped by £8.4 mill
So another year of progress here in that the size of the pension scheme is smaller than prior year and that carries on the nicely reducing trend since peak "scheme liabilities" a few years back.
Still a decent sized scheme but nothing like the one it was 5 years ago when profits were also lower.
next up debt - norcros has generally had great clear transparent cashflow - building up debt when their are acquisitions with it dropping quickly normally when they are not splashing the cash - thats how it should be.Some companies seem etenrally mired in debt none of that here - albeit they spent £62 mill cash on the grant westfield acquisition in 2022 - underlying net debt down from £49.9 mill to £37.3 mill. (0.8x net debt to underlying EBITDA)
Ref results ticking over some headwinds this year - definite bounce up from the lows here and p/e showing as a heady 6.8. heady for them anyway.
ref outlook - this is how castings should most definately have updated the market yesterday - something along these lines is fine - give us some news please if things have changed - if things have not chaged confirmed that , thats exactly what they have done - no snakes in the grass needed here cheers.
Current trading
Group revenue in the two months to the end of May 2024 was encouragingly 2.2% ahead on a constant currency like for like basis, adjusting for Johnson Tiles UK and Norcros Adhesives (UK and Ireland +2.0%, SA +2.5%). Group revenue was 2.9% below the prior year comparator on a reported basis.
Although market conditions are likely to remain uncertain, the Group continues to make further strategic progress and the Board's expectations for FY25 remain unchanged.
the company always link some recent info (16th may) on their website that provides detailed info ref the future - on the investor dropdown tab they specifically link to the equity development research - so thanks to them for providing some meat on the bones that the company presumably are in agreement with - link to that research here.
https://www.equitydevelopment....
Just on the pension point at Norcros - also worth noting they are in the process of doing the triennial revaluation (results confirmed this is already underway). Result of this will almost certainly be positive for the scheme liabilities since the interest rate environment is so much higher now so discount rates applied will be more favourable. This makes the pension even less of an issue. Combined with your points above and also bearing in mind the company is getting larger with some growth and the acquisitions etc. so the pension is relatively smaller, all this starts to make this pensions ball and chain that has bound Norcros for so long much less of a concern. Hopefully this will be recognised in market perception of the company in due course.
To highlight the importance of this - they are currently draining 3.8m a year into the pension scheme (out of 27m profit) - so if this figure of 3.8 drops materially (or disappears if they manage to offload the pension scheme to a third party) this is a very material development and adds a ton of annual cashflow.
Norcros (LON:NXR)
This makes the pension even less of an issue.
I doubt very much the latest revaluation will change much - at present Norcros thankfully have reasonably modest annual payments that they make in relation to the size of the scheme. So in some respects the danger here might have been on the downside ref their prospects in that payments may have had to increase - you might be right that it might go the other way so that they are quids in - but i wouldnt presume that is the case bearing in mind modest amounts the are paying now. What i certainly dont is expect that gains on scheme assets alone does the job ref pension.
also i try to ignore any short term benefits ref change in interest rates lie assuptions etc - if we say this a positive what do we say in 9 months time when rate changes go the other way.
Personally i think debt is modest and pension is mature enough and earnings are consistent enough that it deserves a green mark - but i understand in that regard as a holder my viewpoint is a bit biased. I convenienty ignored sa bit there too !
Market Pull Back - If this were a proper bull market we would be buying this dip/retracement in the small caps but my gut feeling is we are all long and fully invested, net flows are still negative and so it becomes a very slow and frustrating market again. It's better than it was a year ago for sure but still feels like a sickly space, hopefully interest rate cuts will be the catalyst for a longer lasting shift in sentiment.
.
Live on VOX Markets at 9.30am tomorrow (14th June), I will be interviewing accomplished investor Leon Boros.
Here we're planning to cover lots of excellent stock ideas including: #HL. #AJB #ADVT #BARC #BVXP #JNEO #MNG #SPSY Novo Nordisk & many more.
Alongside trying to answer any questions you might have.
So please feel free join us here on Youtube.
Everyone is welcome. Lots to discuss
Hi Paul, I really appreciated the live conversation you had last week with Cockney Rebel, some interesting discussion beyond what might be read on his Substack column and it's good to be able to interact and for you to 'take questions from the floor'. I notice you kept smiling despite claiming his folio performance was wiping the floor with yours! Thanks very much, keep them coming.
Please advise where to watch/ listen this conversation
Paul Hill's twitter account has a link. PMH Capital
You can find it on YouTube by searching for Vox Markets. Best wishes.
Ultimate Products (LON:ULTP) - Beldray re-brand – Ultimate Products has “got this!” (link to note here: https://www.equitydevelopment....)
Ultimate Products hosted a Capital Markets presentation at the Exclusively Housewares Exhibition in London on Tuesday this week, where the company showcased its re-brand for Beldray®, having engaged in a similar process for Salter at the same event in 2023. Regarding trading, despite some sales and profit disruption so far in FY2024, we continue to expect above trend organic growth in FY2025. We retain our 200p fair value for the shares.
UP’s Brand Director Tracy Carroll presented key features of the Beldray (est 1872) re-brand. The overarching message was one of “collaboration” between UP and the product user with the simple tagline – “between us we’ve got this.” The company not only looks to have beautiful, affordable products for every home but also to inject humour into the experience of household chores such as laundry and cleaning. The Beldray – be beldray® - re-brand appears well positioned to achieve this.
As a company which owns increasingly powerful consumer brands, UP’s valuation relative to peers continues to look attractive. The company’s yield is above its peers and the prospect of ongoing share buybacks should also be supportive, in our view. We retain our view that fair value for the shares is 200p and base this on 1.2x EV/sales,10.2 EV/EBITDA and a 16.4x P/E. Moreover, the dividend yield at 3.1% would be superior to peers even with a 200p share price.
Destiny Pharma (LON:DEST) - "AGM statement and recent progress" - new note here: https://www.equitydevelopment....
Destiny’s AGM included clinical and business development updates which we summarise below. In addition, there has been an increasing tempo in broader market news that helps augment Destiny’s investment proposition. These include the UK Government and GSK’s pledge on antimicrobial resistance.
The group CMO also detailed the revised clinical program for XF-73 Nasal and what struck us most was the expected £25m cost. To most potential licensors of XF-73 Nasal, this level of cost (and any upfront payments) would be a ‘steal’ for a license that gets them to the other side of Phase 3, the rights to XF-73 Nasal in some jurisdictions, and a pathway to a regulatory submission.
In a recent, well-received announcement, Destiny said its product XF-73 had been awarded an IPD that provides entry into the UK’s Innovative Licensing and Access pathway (ILAP). After a similar award by the US FDA of Qualifying Infectious Disease Product (QIDP) status, this means endorsement by two transatlantic regulators, plus many tangible benefits from access to ILAP.
Our fair value for Destiny remains at £212.0m (or 234p / share) since our recent changes to reflect the longer times until Phase 3 studies start and revenues flow back. Ironically the recent IPD award may shorten some of these timelines, while QIDP status also extends exclusivity.
Destiny Pharma (LON:DEST) With current share price of 10.5p your fair value of 234p seems a fantasy figure! You should state on these releases that you are paid by DESTINY to release these in my opinion. DYOR.
Good morning Graham
I hope you can add PayPoint (LON:PAY) to your schedule as its a bit of a mixed bag with so many moving parts and an immense amount of detail. Love to Shop segment showing why the acquisition was made.
I suppose my big question is why engage in a massive share buyback when their debt is till so large. From a householder perspective this seems like the wrong choice when rates are still high and a cut is receding.
Dividend still good and rising
I hold
Re debt. Sound, financially managed companies, increase returns for shareholders by including debt as part of the overall capital structure.
Whilst the cost of debt reduces the absolute value of profit after tax, the percentage return for shareholders increases provided the cost of debt is below the cost of equity.
Trident Royalties (LON:TRR) - takeover bid at 49p. All cash offer from Deterra Royalties (ASX:DRR) . Can’t complain as only a fairly recent holding for me.
What is interesting here though is that apparently there was a previous bid in April at 44p, then a recent spike up to that level through May and early June. Clearly not a well kept secret in the city!
Trident Royalties (LON:TRR) - Reviewing their pitch from Mello Chiswick...the share price was about 40p then and they disclosed an approx 50% under valuation to NAV. Hence, this offer looks a little light in my view.
It would be good to get your thoughts on PayPoint (LON:PAY) today please. It looks like they are progressing well towards their £100m underlying EBITDA target moving from £61m to £81m this year. Chunky dividend and share buy-back.
Does anyone have an idea as to the potential liability relating to the two ongoing court cases. Noted that no provision has been made.
I've been a holder of PayPoint (LON:PAY) in the Boon Fund for a while. Have had a chance to go skim through the entire FY results now. I won't mention the obvious, but some more interesting bits:
I do think, however, that the outlook statement leaves the door open for a potential profit warning later this year, with the statement around "subdued consumer sentiment" currently.
However, the combination of single digit growth, c4% share buyback this year, c7% dividend yield, "moat" with its network effect, and multiple potential growth drivers...
My calc for a fair price here is at least 650p. I would probably sell my holdings at this, given I bought at 440p. But don't see why it can't get to 650p easily with this set of results.
(I hold in the Boon Fund)
Hi Boon. Do you not think that there is further upside from your £6.50 target - which we are within touching distance. I also hold from circa £4 but feel that they should get back to £8 at least in the mid term.
There probably is more upside above 650p for PayPoint (LON:PAY), but I think only with further good news, which of course is not certain.
I think at 650p it gets into the realm of fairly valued. For me, the easy money would have been made at that level. Going to 800p will require some new catalyst (ie new services, continued strong growth in the parcels business, etc) which is not clear to me yet from the company's commentary.
Good morning Graham, thank you for your comments on Castings yesterday, we're long term holders and might add if they fall much further. I noted and respect the comments other members made but we'll stay with them. I would welcome any observations on Crest Nicholson's results too, we sold on the assumption worse was to come although the shares continued to rally, today might be enlightening and we're hoping to buy in again.
You're very welcome JASVFS! Wishing you the very best of luck with CGS. Let's see if I can get round to CRST today - it will be a busy morning. Cheers! G
Crest Nicholson and other house builders.
Sometimes a call on a sector is easier and probably more profitable than individual companies.
I was bullish on the sector when Taylor Wimpey was under £1 and persimmon under £10.
All house builders were a strong buy then. They are still a good value but I stopped buying.
Banks and asset managers are sectors that i am currently adding to my holdings.
Agree that Castings is a great company. I too will add if they fall further.
My morning smallcap tweet: Election de-rails Tracsis
Tracsis (LON:TRCS) Physiomics (LON:PYC) Origin Enterprises (LON:OGN) Palace Capital (LON:PCA) Pensionbee (LON:PBEE) Galliford Try Holdings (LON:GFRD), Dialight (LON:DIA), NWF (LON:NWF), Christie (LON:CTG), Norcros (LON:NXR)
◄Tracsis (TRCS)► warns FY-July rev only £80-82m vs F/C £85.2m. Adj EBITDA also hit. Blames early election causing rescheduling of certain projects and a short-term contraction of new order activity. Also US orders have slipped into FY25. Expects FY25 in line. [SP=891.5 Cap=276m]
◄Physiomics (PYC)► wins £186k contract to be completed in cal 2024. [SP=1.23 Cap=2m]
◄Origin Enterprises (OGN)► warns FY-June adj EPS 45-48 cents. Blames wet weather. [SP=3.06 Cap=329m]
◄Palace Capital (PCA)► 250p tender offer. [SP=225 Cap=85m]
◄PensionBee (PBEE)► AuM hits £5bn. [SP=153.5 Cap=345m]
◄Galliford Try (GFRD)► wins £69m contract to build a school. [SP=234 Cap=240m]. I hold.
In line: DIA, NWF, CTG, NXR