Small Cap Value Report (Thur 14 June 2018) - RBG

Good morning all. I am writing to you from a secret location within Hever Hotel, in advance of presenting to the Mello conference. For obvious reasons, this report will be shorter than usual.
Revolution Bars (LON:RBG)
- Share price: 136.5p (-13%)
- No. of shares: 50 million
- Market cap: £68 million
More issues at Revolution. As MrContrarian puts it, "excuses ahead of expectations".
- "challenging and volatile trading conditions"
It's tough out there at the moment.
Total sales for the Group in the second half up to 9 June 2018 are up by 7.3%. However, like-for-like sales are down 1.7%. Adjusted EBITDA is now expected to be below market expectations and in line with last year.
Like-for-likes haven't been going far for Revolution. In H1, they improved by just 0.4%.
Full-year adjusted EBITDA, adjusted for pre-opening costs, is set to be around the same level as last year: £15.1 million.
Pre-tax profit was much lower: £3.6 million.
This company has a pattern of very complicated adjustments, forcing investors to make up their own mind about what the true level of profitability is.
The weather has been too hot and too cold, and we have a reference to 5 new venues this year, when 6 had been promised.
Bulls will find some hope in the reference to the new Food Director, hired "to drive a step change in Food sales and profitability".
I can't possibly agree with this, since the casual dining sector is widely acknowledged to be over-supplied.
Revolution doesn't appear to be differentiating itself particularly well as a drinks venue, so why should we expect it be able to differentiate itself in food?
There are no prizes for guessing that I'm not at all tempted to dabble in these shares.
On the positive side, net debt is likely to remain at a manageable level - last reported at £4.5 million in the interims - and the shares are superficially cheap against earnings. It's also conceivable that one of last year's suitors will come back with another offer, if they still believe that the EBITDA multiple is cheap.
The Price to adjusted EBITDA multiple is now about 4.5x (perhaps closer to 5x on an enterprise value basis), and that does seem to be at the cheaper end of the normal range.
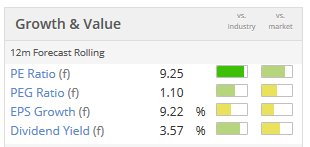
On the negative side, however, the company looks at the end of the day to be a somewhat ordinary bar chain, with weak like-for-like sales, a tail of underperforming sites and very heavily adjusted accounts. So I would humbly suggest that there are plenty of more compelling investment opportunities out there!
Ok, I'm out of time for now, and I'm unlikely to have any more time for writing today - exceptional circumstances. See you tomorrow!
Best,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
I think people will hold to see what happens. Stonegate coyld also come back to the table.
Plys a deal with deltic could make RBG and them a powerhouse. Have to learn what the proposal is...
Not sure what you mean by 'powerhouse' vik2001, but the problem for the pubs/restaurant industry is that's it's not really scaleable.
A Revolution Bars/Deltic combination would have 130 venues & £130million of revenue.
By contrast, J D Wetherspoon (LON:JDW) has 930+ venues & £1,700million of revenue.
Yet J D Wetherspoon (LON:JDW) earns net profit margins of less than 5%.
No doubt the price action will be crazy Monday am as people try to get in.
Im still not sure but think this must have been leaked early before the official rns release after 5pm today.
No doubt the price action will be crazy Monday am as people try to get in.
Surely people buying on the Betaville rumour today were expecting Deltic to make an offer for Revolution Bars (LON:RBG) and therefore to make a quick profit by selling their shares to Deltic. Instead they risk getting a potential big dilution or capital raise so Revolution Bars (LON:RBG) can buy Deltic - a company that Revolution Bars (LON:RBG) publicly disparaged during the stonegate offer don't forget - and a long recovery as they wait to see if the combined group can deliver synergies of operation.
I suspect that the Monday rush may be for the exit not the entrance.
I think given most shares are held by institutions then it won't be a stampede exit but RBG will have a big job on their hands to convince institutional support. If the stonergate offer was rejected how would this get voted through?
"RBG will have a big job on their hands to convince institutional support. If the stonergate offer was rejected how would this get voted through?"
Two different events, surely?
The Stonegate cash offer of 203p was rejected by institutions due to perceived undervaluation.
Whereas Revolution Bars (LON:RBG) aquiring Deltic draws attention to this perceived undervaluation only to the extent that Revolution Bars (LON:RBG) finance the acquisition with shares.
Morningstar quote " Revolution Bars Group PLC on Friday confirmed that it is in the "very preliminary stages" of considering an acquisition of nightclub owner the Deltic Group Ltd."
Start of something????
Paul,
FWIW my only operational thought from non-extensive site survey visits (but with a personal ex-P&G Marketing background, gone into General Management) is around product assortment & promotion and your comments around building day trade.
Evening audience target audience are already winning with a bias to an above ave. income/spend young female biased crowd - hence Sex in the city cocktail focus. Attracting them is a big success since men will naturally follow! However, I don't really know much about evening trade.
To build a premium day trade, in addition to better food they also need to be more inventive and distinctive in drinks they offer. Especially the big sites coming to town centres near to shopping need to provide attractive female friendly drinks. This means to promote i) non-alcoholic speciality teas both hot and cold to refresh and indulge you after shopping (mostly female) plus ii) and iii) I think there is also an opportunity to push alcoholic iced-teas and coffee+shot ideas (can be male/female/neutral executions) to attract the 'professional white collar crowd' in the middle/end of the working day with a quasi-business offer. These kind offers require differentiated A boards and offers of the day by time part - again making the fixed asset sweat harder and making the offer seem very fresh.
Thanks Paul, hope the holiday’s good.
Regards,
Andrew
Revolution Bars (LON:RBG) is also hampered by its poor liquidity , typically around 40-50K a day . That combined with its poor technicals made it a no-go for me. I increasingly observe the "nothing below a 200MA" maxim unless I am very deliberately in a reversal play with very fixed rules good (liquidity being one) or it is in an area where I have good expertise. We are late in a bull market so overreactions are becoming accelerated and more brutal as I suspect there is more crowding around the exits.
That said, today's price action in Revolution Bars (LON:RBG) is interesting and should give holders some cheer as it reversed rapidly off the decline. I note the big volume spike on 7 June was Artemis taking a much bigger stake. Instis now hold almost 80% of the free float so price dislocations can ironically be more severe if it is the loose hands (PIs and small traders) that are the dominant source of liquidity.
Today's reversal is oddly bullish despite the bad news.
I know Paul has deep sector expertise in this space and suspect this is one of his "special situations"
ricky 65
in April where you said that RBG was "bullet-proof".
Nice bit of selective posting there - Paul clearly was clearly referencing the balance sheet strength with that comment.
A Pretty astute comment really as despite the poor performance and the profit warning - the shareprice is actually above the level at the time the comment was made. So the "Bullet-Proof" balance sheet has done its job at minimising downside risk when things don't go as as planned.
There are no guarantees with stocks.
I think we would all agree with this comment :)
I think people have missed my point - Paul was implying that the risk with Revolution Bars (LON:RBG) was low because it has a "bullet-proof" balance sheet. Over the years I've seen plenty of stocks fall heavily with what many consider good balance sheets. A company doesn't have to go broke for it to cause damage to a portfolio. This Minervini quote comes to mind - "If analyzing balance sheets were the Holy Grail for stock investing, accountants would be the world’s greatest traders."
I think people have missed my point - Paul was implying that the risk with Revolution Bars (LON:RBG) was low because it has a "bullet-proof" balance sheet.
I did indeed miss your point low risk isn't nil risk - it's simply less risk than higher risk that might be present with no decent balance sheet backup. We all know shares are risky don't we :)
Balance sheet ability to back up shareprice IMHO is very individual to the circumstances of that share. Good point for discussion of facts.
ricky65,
I think we're talking at crossed purposes here.
A mild profit warning today from Revolution Bars (LON:RBG) doesn't affect my long term view of the company at all. Especially as it's not had a CEO for some time, so a soft patch of performance is not much of a surprise.
I still see it as bulletproof, in terms of the great balance sheet & excellent cashflow - providing the economy remains reasonably sound. Obviously if we entered a recession, then profits & cashflow would deteriorate, but would not threaten solvency, even if you model a hypothetical large drop in revenues.
A 5-10% share price move today on temporarily soft trading, doesn't really bother me - actually it's rather encouragingly small. Look at how recent profit warnings have clobbered share prices far more than this, with other companies. Today suggests to me that the RBG shareholder base is now pretty robust - not a jittery bunch of traders, but committed long-term shareholders, who buy on weakness.
There are lots of quick & easy ways I can see for the new CEO to improve operational performance. So it's now all about better execution.
My position size on this one is far too large to even consider trying to trade in & out, so I'm in it for the long haul. Nothing said today by the company has altered anything, as far as I'm concerned, taking a long-term view.
Anyone who thinks RBG bars are not differentiated, should visit one of their newer sites - those £1m fitouts are a very good differentiation, and that shows in the clientele, who are seemingly happy to spend freely.
I'll be proven right on this one eventually LOL! ;-)
Best wishes, Paul.
Hi Paul,
I note the points you made. As a long term holder I can see how a 7.4% drop isn't going to bother you. And I can see how a new CEO can inject some new life into the company. I can also see how new fitouts could make the bars more appealing.
The point I was making is that, sadly, a "bulletproof" balance sheet alone is not going to guarantee investment success.
As a Minervini trader there's not much to like here. The technicals don't satisfy Minervini's Trend Template and the chart is in a long term downtrend. It's got overhang of trapped investors stuck with a loss. That's the complete opposite of what I look for. I understand that your approach is different and of course there's more than one way to skin a cat!
As always, the market (or perhaps a bidder!) will decide if you are right!
Kind Regards
Rick
Bit late to party in responding (story of my life!) but I bought Revolution Bars (LON:RBG) over 2 years ago as a long term roll out ie as an investor not a trader and was expecting to hold for 5+ years to near national roll out. So also not particular disturbed by current trading weakness. Clearly the business isn't doing relatively great since other wet led / night time operators seem to be reporting better than it but equally not that bad.
Key phrase in RNS for me was:
I suspect the big, new bars in big urban centres are doing well whilst the old, small clubs are struggling (ie a continuation of trend requiring the provisions at interims). Understanding this is critical since my investment is based on the assumption that the new bars will be a bigger and bigger part of the estate and will be highly profitable. This is what they IPO'd to do and earlier mgt claimed a 38% ROCE employed on new bars from memory.
In your correspondence with them (much more likely to be listened to than mine!), can you ask them to improve reporting in this area ie break out pre - IPO vs post or ROCE per cohort. The (sensible) 5-6 outlet pa roll out plan makes this approach increasingly meaningful and would I think be positive. (Equally, I would like to understand the emerging 'tail' better. Personally, I would be more supportive if more drastic action is required ie closure /sale to avoid loss of focus and weakening of the brand).
FWIW, personally I expect this share to become increasingly dull but rewarding in the next couple of years as I don't expect any new offers for a while and the traders will gradually fade away. However, I remain happy to hold.
Paul,
FWIW my only operational thought from a non-extensive site survey (but with a personal ex-P&G Marketing background, gone into General Management) is around product assortment & promotion and your comments around building day trading.
Evening audience target audience are above ave. income/spend young female biased - hence premium Sex in the city cocktail focus. Attracting them is already a big success - since men will naturally follow! However, I don't really know much about evening/night time trade.
To build a premium day trade, in addition to better food they also need to be more inventive and distinctive in the drinks they offer. Especially in the big sites in to town centres near to shopping/offices, need to provide attractive, distinctive, female friendly drinks that fit the brand.
This means non-alcoholic speciality teas plus I think there is an opportunity to promote alcoholic iced teas (eg Long Island) to refresh you from shopping (mostly female) and coffee+shot ideas (can be done both male and female executions) to attract the 'professional white collar crowd with a quasi-business offer at lunchtime.
Critically, these offers require training staff to systematically put out daily, differentiated A boards on the street outside and on the tables with relevant offers of the day by time part - again making the fixed asset sweat harder. Mindset needs to move from nightclub to all day bar!!
Finally, to change perceptions they need to new customers through the doors. Old school on the day flyers and leafleting of office blocks would work wonders in my view.
Lets hope the CEO really gets the thing going as I believe the potential is very good indeed.
Re Revolution Bars (LON:RBG)
These types of businesses do have excellent cash-flow - usually it's possible to switch off roll-out quickly if there are problems and divert cash flow to re-investing in the current estate (a defensive move to protect existing profits) or enhancing shareholder returns in other ways.
As Buffet always alludes to - management should be expert capital allocators and if they are not generating a good return (20%+ ROCE in this sector required) from rollout, they need to find a more effective way of allocating capital to enhance shareholder returns. For example, if the shares are seen as 'undervalued', a share buy-back would enhance the EPS.
I would be weary though of describing any large leasehold business' balance sheet as 'bullet-proof' as the operational leverage inherent in servicing a large rent bill means that a small impact on LFL's can have a massive effect on profitability. It can also be difficult to exit sites that become loss-making.
Whilst the sector (wet-led) has held up well at the moment, you only have to look at what's happening with retailers (Carpetright, Mothercare, House of Fraser, Denbenhams, Dixons etc) and restaurants (Carluccios, Jamies, Byron, Restaurant Group) and the number of recent CVAs being issued to see the risks.
There other reasons why these Companies have struggled but you can see how if discretionary spending tightens the 'cheap' rating may no longer apply (if the E in P/E declines).
The sector and shares are generally unloved due to association with the Pubcos which have struggled in the past so there may be value, but in my mind they are potentially cyclical businesses which are at a discount for a reason.
The main catalyst I see for a re-rating is a takeover but with Stonegate the only consolidator (Deltic not credible bidder in my opinion) in the market (unless you own a craft beer microbrewery!) being rebuffed last year, I think that the 'value' could take a while to rise to the surface.
Nico
As the majority of BS captions are judgments and NOT facts, that quote is little more than a meaningless soundbite.
RBG.....made a stonking profit on these last time having first been short and then going long as the nosy buying was obvious. A bid was made two weeks later. Crazy it was not accepted.
This morning was a buying opp I thought. I agree though that a new bidder will not pay 200p. 180p perhaps?
A sell of the business is definitely the way forward here.
With respect to Revolution Bars (LON:RBG) I'm as cynical as Graham, having been stung by it already last year. A lot of companies are pure plays on commodities or forex, the direction of which I personally find impossible to predict. If the authors of today's update are to be believed, the fortunes of this company appear to be a play on the British weather, (not too cold, not too hot), which I find equally impossible to predict. Therefore how is this company any less speculative than those miners and oilies?
Good morning everyone,
My take on Revolution Bars (LON:RBG) is pretty relaxed. EBITDA being flat against last year is hardly a disaster. The cold weather reason given, would have affected trade in Feb-Mar for sure. I'm less convinced by the excuse given for hot weather depressing sales more recently.
I was half-expecting a temporary glitch, as there has been quite a long period with no CEO. The new chap, Rob Proctor, starts soon. There are some quick & easy wins to be had - primarily on the food, which currently is dire, and poor value for money too. The new CEO has a background in food, so I am hoping he should be able to dramatically improve sales/profits, if he brings in a top notch food offering at reasonable prices. Food is high margin, so adding additional sales on to a fixed cost base would be highly beneficial to profit, potentially. Also, what's the point in putting so much effort into premium drinks, if your food offering is probably not even up to the standard of the local Harvester? A massive blind spot from previous management.
It remains a highly cash generative business, on a dirt-cheap rating. Find me another self-funding roll-out which is also paying decent divis, anything like this cheap!
If the new CEO is any good, he should be able to turn LFLs positive again, and then we have probably an easy 50% upside on the current share price. Nice to see Instis hoovering up an overhang of shares - I think part of the problem here is that a lot of people bought stock in the hope of an improved bid from Stonegate, but liquidity has since been poor, leaving them high & dry.
I will shortly be writing to the new CEO, with my ideas for how they could greatly improve operations, after my own extensive research at 4 of their sites.
I think a 5-10% share price fall today is about right, given that recent trading has been a bit worse than expected. The long-term value in the company is however undiminished, as this profit warning firmly sits in the temporary/fixable problems bracket.
Regards, Paul.
"I will shortly be writing to the new CEO, with my ideas for how they could greatly improve operations, after my own extensive research at 4 of their sites."
You may want to leave at least 12 hours and several black coffees between your extensive research and pressing send on your missive to the CEO ;-)
I'll get my coat...
Is that the one at Audioboom Audioboom (LON:BOOM)
RNS Revolution Bars Group plc (the "Group" or the "Company") announces the appointment of Rob Pitcher, who will join the Board of Revolution Bars Group plc as its new Chief Executive Officer.
Hi Paul
I remember our Twitter disccusion on Revolution Bars (LON:RBG) in April where you said that RBG was "bullet-proof".
Link: https://webcache.googleusercontent.com/search?q=cache:5il-cnYyOKAJ:https://twitter.com/paulypilot/status/982611308548952065+&cd=1&hl=en&ct=clnk&gl=uk
Today's profit warning suggests otherwise! There are no guarantees with stocks.
Regards,
Rick
Hi Paul, re. RBG your suggestions to management- maybe a bit of Chaka Khan too on the hi-fi late in the evenings?
I think we’re lucky to have both Paul and Graham offering opinions and all the reader comments too- it gives us a lot to think on and help us make our minds up.
Best regards
Andrew
Hi Andrew,
I think we’re lucky to have both Paul and Graham offering opinions and all the reader comments too- it gives us a lot to think on and help us make our minds up.
Absolutely, I agree. Right from day 1, Graham and I agreed that we would never hold back on criticising shares which the other one owned. It's much better that way, and stimulates debate. Although I do sometimes get a bit cranky (temporarily!) when one of my shares falls out of bed, as inevitably happens quite often when you have 50-60 positions.
Regards, Paul.
I think RBG could be an opportunity here. Snow obviously must have had an impact, hot bank holidays not as obvious but makes some sense. No CEO for 6 months can't have helped. If new CEO and newish Food Director can make an impact this could recover strongly operationally. New CFO seems sensible. Don't think the World Cup will help, maybe modest negative. At 5.4x unadjusted EBITDA not paying up much for the chances of success.
RBG for me too please Graham. I can't read the report too negatively. Outside trade sites are up inside down. Weather has affected it, but not disastrously. They have good plans and more focus. Weakness is probably going to be picked up on if bidders are out there. Overall if I could have I would have added more when they were 20% down, but Hargreaves trading only seems to open up around 8.30am?
Revolution Bars (LON:RBG) some broker commentry this am:
-Numis now sees 2H softer than expected and co. “unusually” also underperformed in very hot weather, given only a third of its sites have outdoor space, Numis analyst Tim Barrett writes in a note PT lowered to 190p from 200p; buy rating maintained
-Separately, Canaccord sees takeover speculation reemerging after the stock falls, analyst Nigel Parson writes in a note; buy rating maintained
Re: Revolution Bars (LON:RBG)
Let's also not forget that in the last few weeks we have seen three large shareholders increase their stakes/open up a position:
Artemis: Up to 18.87%
Castlefield: Up to 10.33%
And new arrival, Axa: 5.04%
Morning All,
I second a look at Revolution Bars (LON:RBG), which I hold.
In answer to Abtan above, I have just recently read that their York license application was turned down, they appealed, but have just in the last few days withdrawn their appeal. it was due to be in a part of the former Debenhams but was rejected by licensing as it was in a Cumulative Impact Zone. Shame really, that shut Debenhams may now lie shuttered. I think it would be better to welcome new leisure uses and just police better at night (and enforce license conditions/compliance), than let city centres slowly stagnate.
I think the 118p price for Revolution Bars (LON:RBG) is a brutal reaction (I did very well the last time there was a spike down like this, ending up selling at around 225p when the takeover was at fever pitch. Whilst I doubt Stonegate will come back again, there is still interest from Deltic and who know,s someone else might take a bite. I am considering a top up as we're back in fundamental undervalue territory - that's why Stonegate came knocking last time.
I think £RGB is a long term survivor and will emerge stronger. Deals on new sites are also getting better by the day and the main offering is sound, if not perfectly executed at times. I have tested the product myself on a few occasions!
Still, takes all opinions to make a market.
Regards,
mark
Revolution Bars (LON:RBG)
I am considering a top up as we're back in fundamental undervalue territory - that's why Stonegate came knocking last time.
i did similarly well when the bid came along, however the company have doing nothing to convince me that the fundamentals are as good now as i thought they were at the time of the takeover. It seemed like they kitchen sinked everything last year reducing future depreciation charges etc) . So a late profit warnings along with the already present "large exceptionals" leave me wandering just quite how much the company are actually making.
New sites and they are struggling to add profit that should be the biggest worry , roll out format is only valid if they can show the extra sites are worth the cash invested.
Market cap now is £320 million right ? are they making 30 millon per year clean profits ? - i doubt it.
I kind of thought they were kitchen sinking to look good this year but expect they they may simply be struggling on all levels.
RBG market cap is £70m not £320m
Hi rmillaree,
I think you need another strong coffee, and recalculate your figures!
Market cap now is £320 million right ? are they making 30 millon per year clean profits ? - i doubt it.
RBG actually has 50m shares in issue. So at c.140p per share at the moment, the market cap is only £70m. It has negligible net debt - which could be paid off in full just by stopping new sites capex for less than a year.
I continue to be amazed at the overwhelmingly negative sentiment from investors, for such a good, cash generative self-funding roll-out. Investor sentiment doesn't make any sense at all to me. The bottom line is this - Stonegate offered 203p cash for the company a year ago. Since then profits have been flat, so that figure is still valid. If a competitor is willing to pay x pence per share, then usually they think the company is actually worth x + 30% or more, otherwise they wouldn't be interested in buying it!
We'll get a nice payday here, with patience, I reckon.
These bars are absolutely heaving in the evenings, especially at weekends. They need to make better use of the fixed overheads by getting punters in during the day, and early in the week. A fantastic, and good value food offering is the key to that. Also, I've noticed that the bar service is too slow - because staff are fiddling around making complicated cocktails, whilst dozens of people are waiting for 10-15 minutes, just to get a pint. So a quick win would be to separate the bar into 2 zones - fast service for pints, etc, and a separate area for cocktails. They should have an App whereby people can order the cocktails whilst sitting at a table, and have them brought over. Then just have certain staff concentrating solely on making the cocktails, whilst others are free to take the money & deliver. All pretty basic stuff, it amazes me that the company currently operates so inefficiently.
These relatively quick & easy upside actions are what make me positive on the upside potential. It just needs better management, so all eyes on the new CEO!
Regards, Paul.
Whilst I can see what Paul says on Revolution Bars (LON:RBG) makes sense, I am puzzled that the hot weather as referenced in the RNS affected sales in properties with no outside space, and cold weather when outside space was not required.
I would have thought cocktails would be favoured during hot weather, but not necessarily in cold.If it doesn't work either way, its a bit of a Goldilocks puzzle to know what is the right weather, or whether the estate is not entirely suitable to the market they are after.
Hopefully the new CEO can make sense of what is optimal, and tune their offering accordingly.
I am a Holder
I found the statement confusing when I first read it but it makes sense. In very warm weather people prefer a venue where they can either sit outside or have access to a terrace or similar space as crowded bars can get too warm. I would also add that bar venues tend benefit in World Cup years even if they aren't a primary viewing venue.
Revolution Bars (LON:RBG)
RBG actually has 50m shares in issue. So at c.140p per share at the moment, the market cap is only £70m
Thanks for that Paul that makes much more sense i - i had two screens open and was looking at the wrong one of the two when i noted the figure - Useful that Stokopedia has the info if you can check the right page !
My posts were as often all a bit rushed, £70 mill is much more scope for upside, i would still like the company to be on the up though rather than the down and as you say its the annoying things this company doesn't probably do that a well down company like JDW (hmmm they do also have queue's when busy). I did specifically when doing my company research notice the cocktail waiting time was an issue at Chester (only a basic 2 for one PC) so a simple system to avoid long queue at the bar should be found. Thankfully my local bar charges less than £2 a pint for beer and the main bar man dude is of the Ninja spiderman type who can pour 4 pints at once whilst not forgetting what you didn't even need to ask for.
Anyway
Would be great to hear thoughts on NWF (LON:NWF) following today's update. The news on debt being down below expectation was particularly welcome as I have always had a concern over this (some figures would have been nice though...). 5.5% up seems a little bit mean for a "significantly ahead of current market expectations and the prior year" update - perhaps room for some gradual gains in the coming days as market digests it? (no feed pun intended).
GYM (LON:GYM) placing last night at only a very small discount. Raising money for purchase of sites from easygym. Trading statement says membership growth of 31.8%. All very positive it seems. Their model appears to be working well and they are expanding at a time when it may be possible to obtain new sites at low rents due to the level of distress in retail sites.
Safestore Holdings (LON:SAFE) interims. Basic eps up 43.4% and further organic and acquisition expansion. They are now a mid-cap rather than a small cap but a possibly interesting play on the problem of people having to live in smaller properties with less storage than they really need because housing is so expensive.
GYM (LON:GYM)
Looks like the extra shares (10% ish) should be covered by the extra new members (10% ish) would have been nice had they said this would increase EPS all other things being equal (only quick look i might have missed something)
There should be good economies of scale be going on here though the more punters the more the fixed plc/IT/blah de blah costs are spreadabout more efficiently.
the shares are up 40% or so since i bought last summer, the company wasn't exactly cheap then so i do have to admit i am thinking of cashing in my chips. I am though trying to make an effort to hold onto shares where the company are delivering and the news is all good - in that regard i am not in any immediate hurry to do anything.
Very difficult to buy Revolution Bars (LON:RBG) despite its nominal big fall, or to open a spread bet. Seems like a false trapdoor..
Revolution Bars (LON:RBG) thoughts:
HI Graham,
Another request for Revolution Bars (LON:RBG) please. Also, I'm intrigued by Duke Royalty (LON:DUKE) who have two announcements today including the below.
It's an interesting long term lender to private firms with a business model reminiscent of medieval banking practices (in a good way). I'd be very interested in reading your expert financial opinion on them.
cheers
Francis
Hi Francis,
The Duke Royalty (LON:DUKE) model is well established in North America but I think unique in UK. I hold in my SIPP as although I believe there will be growth I expect a dividend of around 8% in 12-15 months when all the 'partners' interest payments hit the full annual run rate.
They will probably have another placing to raise funds but this is unlikely to be discounted, the last one wasn't. Most of the partners are long established private companies, often 50 years or more, with little or no other debt.
I see great potential for a little leverage but was somewhat dissapointed they have borrowed for this one at 9% albeit lending it out at 13%. I hope that in due course they can put a long term financing deal in place at a lower rate.
The company presentation is worth a read-
http://www.dukeroyalty.com/~/media/Files/D/Duke/documents/investor-presentation-may-2018.pdf?
Dave
Thanks Dave,
I worked with a hedge fund a few years ago who's business model was similar. However they ended up becoming a fully fledged bank three years ago so they could reduce their cost of lending by accessing wholesale rates and using depositor money for corporate lending. Perhaps that's the challenge Duke face?
cheers
Francis
If Revolution Bars (LON:RBG) get hammered today seems like it could be a decent entry point, EBTIDA only about x5 and some promised operational improvements in the pipeline
I am not really a person to follow charts blindly, but I was able to watch and pick up some around 121p today as the price moved down to the previous gap. Find it quite fascinating.
Interim results out for specialist care home provider Caretech Holdings (LON:CTH) this morning. Decent-ish progress being made although debt is up a fair bit due to acquisitions. Seems to be a good, well run company in a tough sector faced with the perennial problem of trying to provide a quality service (it rates well in various indices) against a back drop of fighting with its local authority customers to increase fees to cover rising fixed overhead and wage costs.
https://www.investegate.co.uk/caretech-holdings--cth-/rns/interim-results/201806140700043778R/
Long term growing market for decent residential healthcare that they seem well positioned to tap into.
Gus.
Morning Graham, here are a few for you or readers to think about:
Ultimate Products UP Global Sourcing Holdings (LON:UPGS) , the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, is pleased to announce that it has purchased the intellectual property rights of Kleeneze Limited ("Kleeneze").... for an undisclosed amount by the administrators of Kleeneze. The transaction does not include the employees [good news for them I suppose] or independent distribution network. Could this aid its ongoing recovery? I will be watching my £1 a point fun bet intently.
OptiBiotix Health plc (AIM: OptiBiotix Health (LON:OPTI) ), a life sciences business developing compounds to tackle obesity, high cholesterol, diabetes and skin care, has received a notification for the exercise of options over 1,461,408 ordinary shares in the Company at an exercise price of 8p per share providing the Company with proceeds of £116,912.64.
Don't know how long Tom Winnifrith(?)'s money (buy under 80p, 100p this time next year Rodney) will keep the lights on until their many collaborations actually start bringing in the anticipated megabucks from worldwide fatties but seems Paul was right to stay out until then (smallish position).
Revolution Bars (LON:RBG): 'Total sales for the Group in the second half to 9 June 2018 are up by 7.3%, however, like-for-like sales are down 1.7%.' They blame weather but acknowledge not having a CEO might have hurt a bit. Surely they must be taken over now? There is hope: 'Wet sales have performed better than food, particularly in the Revolution estate where little food development and innovation was undertaken in 2017. This development is now underway for delivery in Q1 next year.' About bloody time. Sweat those assets. I hold.
In news of other shares you were all too sage to get involved with, ValiRx (LON:VAL) 's 'VAL401 clinical trial and data collection is now complete and the regulatory process is moving towards completion with the Clinical Study Report on schedule' and will doubtless start up 3000% just after I sold out at a big percentage loss.
Bah humbug, RTJ
UP Global Sourcing Holdings (LON:UPGS) acquire established brands at zero to v low cost and then put it through the UPGS machine and see if they can make money from it. Near term impact from Kleeneze probably low and take a couple of years to work through.
They’re pushing a kitchenware brand George Wilkinson they acquired right now so interesting to see if that gets traction. I’ve seen a bit in some shops.
They have other brands that seem to be stagnating too and/or need some investment (Z-frame, Dreamtime, Constellation, etc). Russell Hobbs, Salter and Foreman are well known and they license these guys but their revenue ramp has come from own acquired brands Beldray and Intempo. Can they repeat? If they do them they are more than just cheap (IMO) goods trading house
Off to Mello South today so only had time for two.
My morning smallcap tweet:
Revolution Bars (LON:RBG), NWF (LON:NWF)
Revolution Bars Group (RBG) FY trading. H2 rev 7.3%. LFL down 1.7%. Adjusted EBITDA expected to be below market expectations and flat YoY. Excuses ahead of expectations. Blames cold weather, hot weather. Also "disruption caused by operational management change prompted by the unsettling effect of last year's takeover activity and the prolonged absence of a CEO has also played its part." Did the brokers not know about that before? I hold.
NWF Group (NWF) Guides FY trading significantly ahead of current market expectations and the prior year.
Excuses ahead of expectations
Brilliant :)
timarr
Revolution Bars (LON:RBG) please Graham - trading update this morning, not that great. Overall flat LFL blame on the weather, the takeover turmoil and change of CEO.
The positive is the Cuba bar concept where there is a glimmer of future growth with new rollouts and a better food offer. I’d welcome yours and wider boards view on this update.
All the best, CID