Small Cap Value Report (Thur 20 April 2023) - MUL, IGR, PAY, GBG, RNK, DNM

Good morning! Roland and Graham here to comment on this morning's releases.
10.20am: we're done! See you tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham's Section
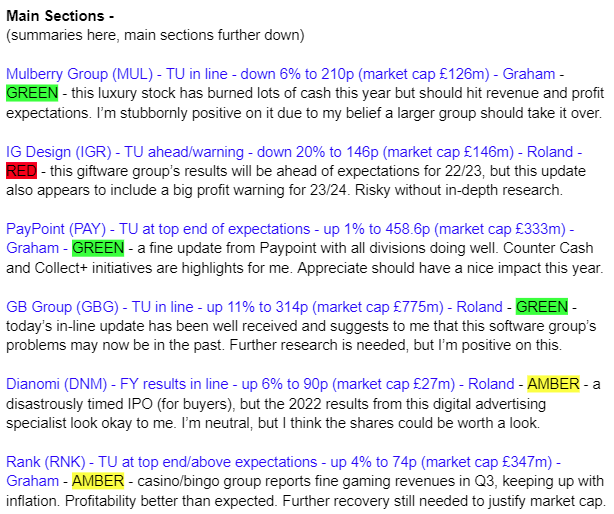
Mulberry (LON:MUL)
- Share price: 210p (-6%)
- Market cap: £126m
These shares rose 7% yesterday, in advance of today’s full-year trading update.
That might just be random white noise, however; the shares are illiquid as the company is 90% owned by the Ong family and by Mike Ashley’s Frasers (LON:FRAS) .
So there’s really only around £10m worth of Mulberry stock that is up for grabs for private investors.
This is a stock I like to follow as Burberry (LON:BRBY) is a core holding of mine, and the two companies share much in common.
Today we have a year-end trading update, informing us that FY March 2023 is in line with expectations.
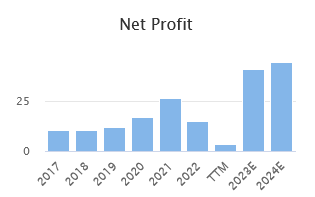
I note that the estimates for 2023 were cut about a year ago, and then stabilised:
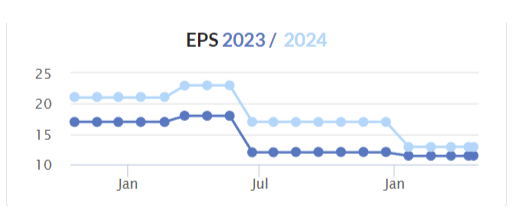
According to Stockopedia, the company is expected to generate revenues of £155m and net profit of £7m for 2023.
Key points:
H2 was better thanks to a good performance in the UK and an improvement in China. I reviewed the poor H1 numbers in November.
Gross margin has been maintained (the gross margin achieved by these luxury companies is one of my favourite things about them!)
As previously announced, they acquired franchisee-run stores in Australia (they previously did this in Sweden).
New collection launched.
Net cash finished the year at £0.8 million, as the company “continued to invest in its global brand awareness and the development of its business model during FY23 and remains focused on investing for future growth”.
It must be spending quite a lot, as net cash was £25.7m at the end of the previous financial year.
They previously said that they had a £15m RCF and a £4m overdraft, so they should not find themselves running out of headroom in the immediate future.
Graham’s view
The level of cash burn is a concern and it cannot be written off as seasonality as the burn continued in both H1 and H2.
However, I’m going to dangerously continue to rate this stock positively, for the simple reason that I think Burberry should offer to buy it. Or even LVMH.
Burberry trades at nearly 3x sales, while LVMH trades at 5.6x sales. Mulberry? Less than 1x!
This sort of discrepancy only makes sense, in my mind, because Mulberry as a company is sub-scale. However, I believe that the Mulberry brand is still a powerful one, and could be strengthened in a larger group. Remember that the gross margins here are currently around 71% - that’s as good as Burberry and even better than LVMH!
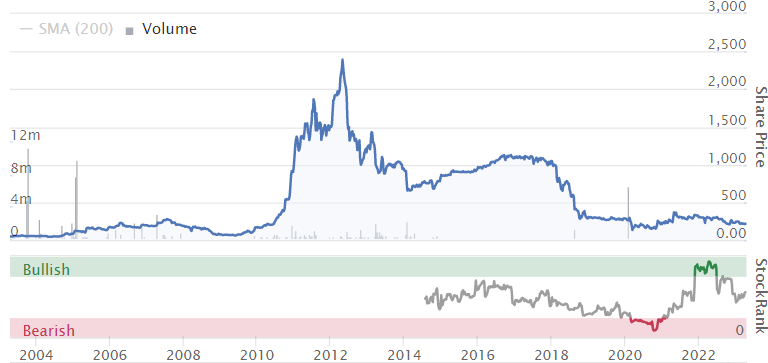
This stock is a long-term disappointment but I do like it at this valuation:
PayPoint (LON:PAY)
- Share price: 458.6p (+1%)
- Market cap: £333m
Another year-end update for FY March 2023.
I last mentioned PayPoint earlier this year, in relation to its takeover of Appreciate.
Let’s see how it is doing now.
Adjusted PBT for the year just finished, excluding any contribution from Appreciate, is “at top end of range of market expectations”.
Some highlights that stand out to me:
Net revenue £125m (last year: £115m), excluding Appreciate.
Counter Cash (a cash withdrawal facility) rolling out successfully to retailers.
“Excellent volumes” at e-commerce service Collect+.
Appreciate Group renamed as Love2Shop and trading in line with expectations.
The CEO comment uses just slightly too much corporate-speak for my liking, but it does convey the optimism that he is trying to get across:
We are entering the new financial year in a materially enhanced position across the Group: a full-strength sales team delivering high conversion rates; healthy pipelines for our FMCG and integrated payments propositions; a business-wide partnership philosophy yielding further revenue opportunities; and a dynamic platform of innovative technology and solutions enabling integrated payments and commerce for our extensive base of clients, retailer partners and SMEs.
Graham's view
I’m a long-term fan of PayPoint. At this stage, maybe it could be argued that I’m biased in its favour and unable to look at it objectively and with “fresh eyes”.
But just look at these quality metrics:
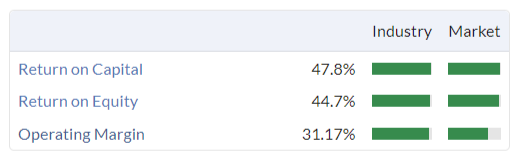
And look at these value metrics:
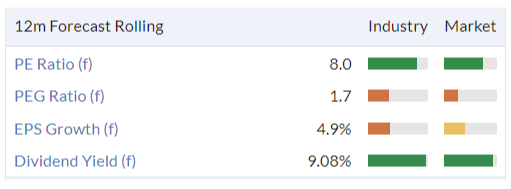
I liked it before it bought Appreciate, and then it bought Appreciate for what I thought was an attractive price.
And now it’s performing at the top end of expectations, and is firing on all cylinders in each of its trading divisions.
Admittedly its growth trajectory is quite limited, but I don’t think the point of it is to provide fast growth: the point of it is to generate high returns on capital and lots of cash, and pay this cash out to shareholders. As long as it keeps doing this, I’ll remain a fan.
Rank (LON:RNK)
- Share price: 74p (+4%)
- Market cap: £347m
This old name in gambling operates Grosvenor Casinos, Mecca bingo clubs, some Spanish casinos, and various gambling websites. See the list of assets here.
It had a miserable 2022 as its own operating costs ticked up and the cost-of-living crisis affected how much its customers were able to spend.
I see the share price hit a low in October. Could it have stabilised now, perhaps?
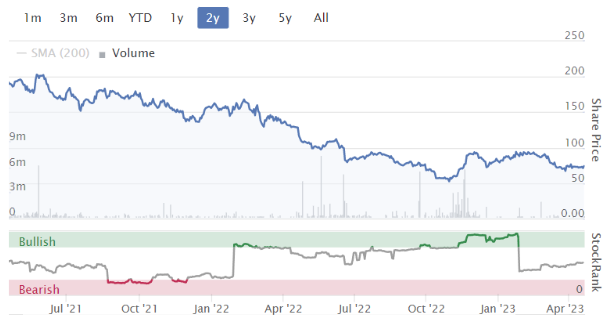
Today we have a Q3 update for January to March (year-end is June).
Key revenue points:
Like-for-like net gaming revenue +13% for the quarter
Like-for-like net gaming revenue +6% for the year-to-date
That’s a very nice improvement in Q3. The core business Grosvenor (responsible for nearly half of NGR) is up 15% for the quarter, “driven by growth in visitor numbers, with improved performance across London and the Rest of UK”.
The bingo clubs managed 9% growth while the websites managed 16%.
In the context of stubbornly high inflation that has only slightly reduced from its peak in October, and an ongoing cost of living crisis, these strike me as fine results.
To help explain them, the CEO points to “investments we have been making to improve the customer experience in our venues” and “the build out of enhancements to the customer experience on our prop
Outlook
As highlighted in previous years, the start of Q4 is traditionally a quieter period for our Grosvenor venues. However, due to the improved performance seen in Q3, the Board now expects the Group's underlying LFL operating profit for the full year to 30 June 2023 to be at the upper end or slightly ahead of the previously guided range of between £10m and £20m.
Graham's view
I’m going to hedge my bets and stay neutral on this one.
For an overview of some of the concerns people might have over this one, please see the archive - most recently, Roland’s thoughts in January.
The news that underlying LFL operating profit will come in at the upper end or even above the £10m - £20m range is extremely welcome, but actual net profits will be materially lower than that number and still not enough on their own to justify the current market cap.
In other words, the market cap is still pricing in a further recovery in trading as the cost of living crisis eventually recedes and profitability goes back to “normal”.
In boom periods, this company has indeed been highly profitable:
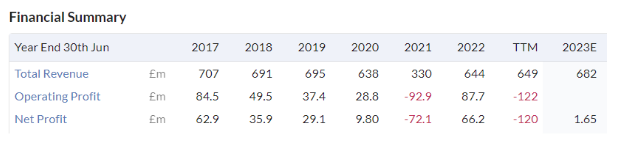
In my view, this stock has definite multi-bagging potential, but that potential rests to a large extent on macroeconomic factors that are difficult (impossible?) to predict.
In the meanwhile, the company reported cash of £90m offset by borrowings of nearly £80m in December, and it has substantial lease liabilities. In other words, its financial position is not as secure as it might be.
I’m a long-term fan of this business but the prospects here are cloudy and so I can’t take a more definitive view yet.
Roland's Section
IG Design (LON:IGR)
Share price: 145p (-20% at 08.10)
Market cap: £146m
an update on its financial performance for the year ended 31 March 2023, which is ahead of expectation.
This greeting card and giftware manufacturer is a former high flyer that’s lost its way somewhat since the pandemic. A turnaround is underway, with a new CEO, but today’s year-end trading update appears to be something of a mixed bag.
Today’s update covers the year ended 31 March 2023. Unlike a number of other companies we’ve covered here recently, IG Design has also included some guidance for the current year.
FY23 highlights:
Revenue of $890m expected for FY23 (-4% at constant currency).
International division revenue +10%, particular strength in continental Europe
US division revenue -10% due to lower volumes and exits from loss-making activities
Group operating margin 1.8% (+1.4% vs. last year)
Adjusted pre-tax profit of $9m - ahead of previous expectations
However, IG says that all of its businesses, except for those operating in continental Europe, experienced a year-on-year sales decline during the second half of the year (Sept ‘21 - Mar ‘22).
The company says that the macro and consumer environment was particularly challenging in the UK.
FY24 outlook:
Slim operating margins and high volumes mean that small changes in pricing and costs can have a big impact on profits.
IG does not expect the outlook to improve in the UK this year (my emphasis):
Due to the recently deteriorated trading, and very limited pricing expectations for Christmas 2023 in the United Kingdom, the Group is likely to incur a one-off, non-cash write-down to the historic goodwill value associated with certain businesses in that market. The Directors expect this to significantly impact the reported results for the year.
It looks like IG expects to struggle to deliver price increases this year to offset higher costs. Although this comment only refers to goodwill, a non-cash item, my reading of this is that it’s a significant profit warning for 2023/24.
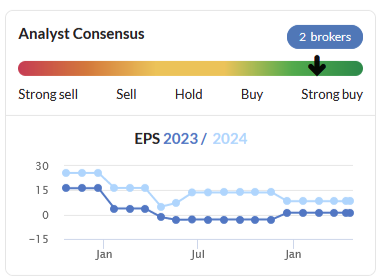
Broker forecasts were previously positive for the year ahead, but I expect these to be cut after today:
Financial position: IG Design is in the process of renewing its debt facilities. This is expected to be completed “in the near term”.
Although the company reports a year-end net cash position of $50m today, there are big seasonal swings in working capital as the group builds stock for the Christmas period each year.
Net debt was $74m at the end of September, so renewing its bank facilities on the best terms possible is a priority right now, I would say.
Roland’s view
I’m encouraged by November’s appointment of chief executive Paul Bal, who was previously CEO of former FTSE 250 firm Stock Spirits. As a former Stock shareholder, I think he was doing a good job before the group was taken over.
IG Design has been through boom-and-bust cycles before and may yet prove to be an attractive turnaround. However, I can see some significant risks for shareholders.
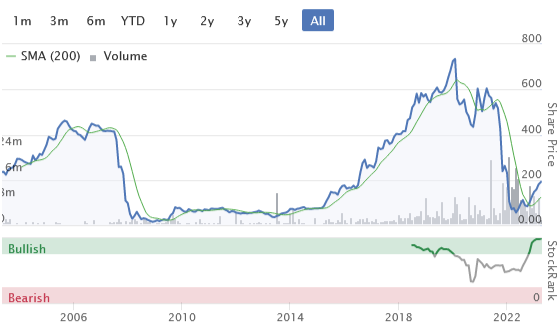
Although FY23 performance was ahead of expectations, today’s commentary suggests to me that margins will remain under pressure and could fall this year.
I think it’s possible, if not likely, that the group will report a loss for FY24.
The outlook for the UK market is clearly poor, while the US business is still in turnaround mode.
In addition, I think it’s safe to assume that IG Design’s new bank facilities will carry higher costs than its current facilities. This will add to pressure on the group’s margins and profits (if any).
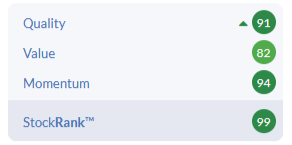
The StockRanks paint a strong picture here, but I suspect these numbers may fall after today’s update.
I’d need to do more research on IG Design to form a firm view on valuation or outlook. For now, I remain very cautious and would view this as a speculative turnaround.
GB (LON:GBG)
Share price: 314p (+11% at 09.30)
Market cap: £775m
Results in line with expectations
I’m a little surprised to see this identity protection and fraud prevention software group fall back into our remit at the SCVR.
Unfortunately, GB has become a textbook example of a falling star. But today’s year-end update is in line with expectations, so I’m keen to see whether the shares may be starting to look more attractive for a value-seeking investor like me.
Main highlights: today’s update covers the year ended 31 March 2023.
Results for the year are expected to be in line with expectations and the company has issued the following guidance numbers today:
Revenue: £278.8m (FY22: £242.5m)
Adjusted operating profit: £59.8m (FY22: £58.8m)
Adjusted operating margin: 21.5%
Net debt: £106m (FY22: £107m)
Revenue: the numbers above imply revenue growth of 15%, but this was boosted by acquisitions and some other one-time factors.
According to the company, “pro forma basis organic constant currency revenue growth” was 3.7% last year.
This fully adjusts for the impact of the two prior year acquisitions, including the associated FY23 deferred revenue haircut adjustment. It also adjusts for £4.2 million of revenue from US stimulus customers in the prior period and the full £15.4 million impact from the year-on-year decline in cryptocurrency customer revenues.
I’m not going to spend much time unpicking this as these factors all now appear to be in the past and unlikely to repeat.
Profits: GB’s adjusted profits are boosted by the exclusion of the amortisation charge on acquired intangibles. This is a standard (non-cash) adjustment, but because of GB’s acquisitive history, it’s also a very large adjustment.
Last year, the exclusion of the amortisation charge masked a fall in statutory operating profit:
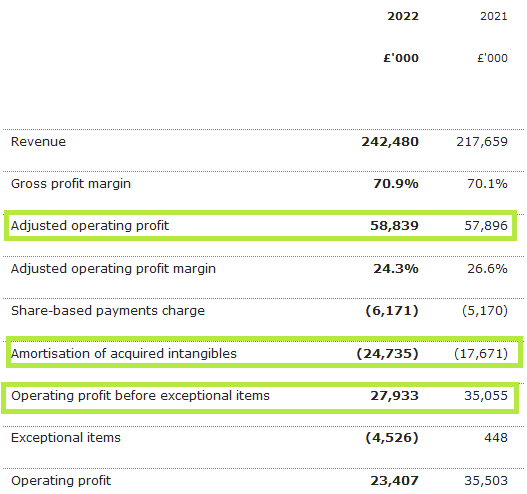
It’s up to individuals to decide which version of profit they find most useful – I think there are valid uses for both.
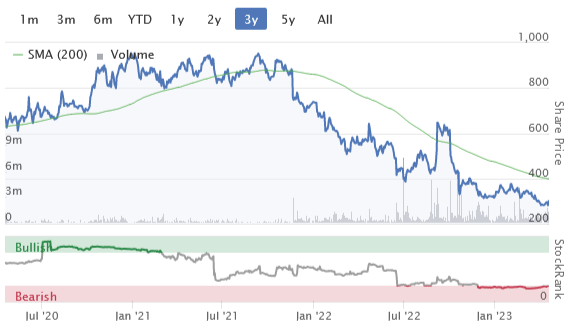
The question now is whether shareholders can expect a return to growth next year – and whether the shares offer value after falling by 70% in two years.
Outlook: today’s update does not include any commentary or guidance for the 2023/24 financial year. However, the company has previously said it expects headwinds in its US business to ease gradually this year.
In February, GB said it expected comparable revenue growth to rise gradually in FY24 to “high single digits” in the latter part of the year.
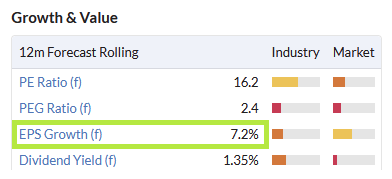
Given the absence of fresh guidance today, I’ll assume that consensus forecasts for FY24 will be largely unchanged after today. According to Stockopedia, a modest increase in earnings is expected this year:
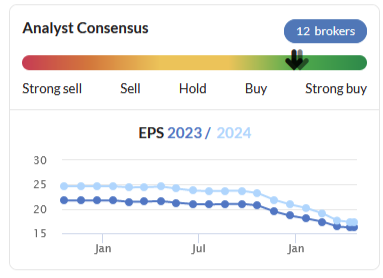
Broker forecasts have been trending downwards over the last six months, so I hope to see this trend stabilise after today’s in-line update:
Roland’s view
Chief executive Chris Clark says that the group’s Location and Fraud businesses delivered “double-digit growth” last year.
I’m not very familiar with the company’s products, but assuming they remain current and competitive, I would expect this business to benefit from structural demand growth for many years to come.
Historically, the group has delivered high levels of cash conversion each year and steady profit growth. If this trajectory can be resumed, as forecasts suggest, I think the stock could be starting to look attractive at current levels.
Forecasts I can see elsewhere suggest GB Group may have generated about £40m of free cash flow in FY23. That would equate to a 5% free cash flow yield – reasonably attractive for a growth business, I think.
I’d want to do further research on this, but today’s results do seem encouraging to me.
It may also be worth remembering that the group attracted a takeover bid at a significantly higher level in September last year. This didn’t succeed, but it’s clear that other investors see value in this business, too.
Dianomi (LON:DNM)
Share price: 90p (+6% at 09.30)
Market cap: £27m
2023 has started well and in line with management expectations. As we move through the year, we believe that we are well placed to capitalise on a return of confidence amongst advertisers.
This digital advertising business floated on AIM in May 2021. Like (almost) all IPOs, the timing appears to have been better for sellers than buyers.
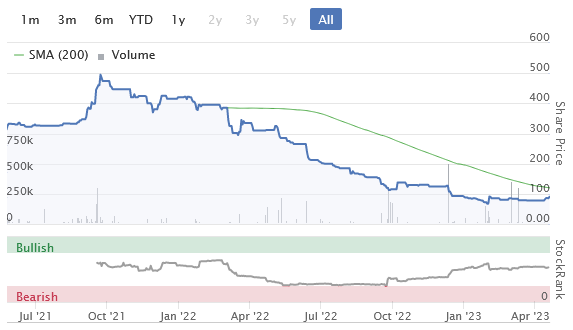
Nevertheless, the business appears to be cash generative, with a very solid balance sheet.
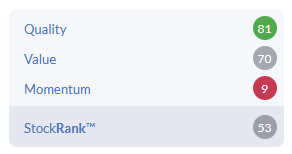
I’m also encouraged by Stocko’s Contrarian rating for this business, which indicates high quality and value scores and low momentum. A potential bargain?
Paul commented briefly on Dianomi in December, so I’ll follow up with a look at today’s results, so that we can start to build our record of coverage here – very useful for tracking the evolution of a business.
What it does: Dianomi provides contextual advertising for digital publishers, specialising in premium finance and lifestyle brands. The company lists Goldman Sachs, EY and Porsche among its new advertisers this last year.
An example of a publishing client is CNN Business.
Financial highlights
According to the company, advertising spend flattened out last year. This is evident from the results, which cover the year to 31 December 2022:
Revenue: £35.9m (2021: £35.8m)
Pre-tax profit: £1.2m (2021: (£0.6m))
Diluted eps: 1.46p per share (2021: (1.77p))
Net cash: £11.7m (2021: £10.3m)
I’ve bolded the net cash figure because this accounts for around 40% of Dianomi’s market cap at current levels. Very material, and provides a useful margin of safety.
It’s also reassuring to see the business appears to have converted its pre-tax profit into surplus cash last year.
Operating summary: Dianomi’s operating metrics show a decline in active advertisers last year:
Publishers at year end: 336 (2021: 326)
Active advertisers in 2022: 387 (2021: 427)
Advertiser churn: 5.5% (2021: 2.5%)
Publisher churn: 2.8% (2021: 4.1%)
My reading of this is that while advertisers cut their spending, Dianomi’s publisher clients remained happy and committed to using the service. That might bode well for a return to growth when the economic outlook improves.
Outlook: the company says it is the “contextual native advertising partner of choice in the business and finance sectors”.
Management believes this should position the group well to profit from an eventual return of confidence amongst advertisers.
In the meantime, Dianomi expects to continue investing and developing its programmatic (targeted) advertising offering.
The current year is said to have started in line with management expectations.
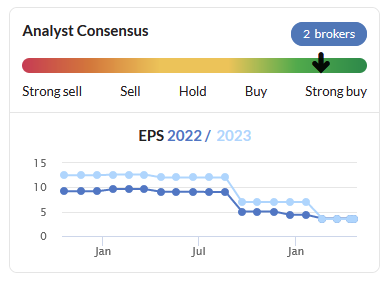
Stockopedia consensus forecasts suggest that a flat overall result is expected this year:
Roland’s view
I’ve been familiar with the Dianomi name for many years through other work, although I’ve never used the service.
While profitability was poor last year, with an operating margin of 3%, I can see potential for this business to perform much more strongly in favourable market conditions. There’s inevitably some cyclicality here, which I think was reflected in the timing of the IPO…
However, I’m encouraged to see that chief executive Rupert Hodson retains a 9%+ shareholding.
I haven’t had time to look through the AIM admission document to see how many shares (if any) Mr Hodson sold during the IPO, but it’s good to see that management retains some skin in the game.
At face value, Dianomi shares look fully priced on 25x forecast earnings for the current year. However, on a cash-adjusted basis the P/E falls to 16, which looks more reasonable.
I can see some potential in this business, but I’d need to do much more research to understand the company’s market share, competitive positioning and growth opportunities.
What does Dianomi offer for publishers and advertisers that Google doesn’t, for example?
I’d also want to study the company’s AIM admission document, in particular the risk section (always recommended reading).
For now, my view on Dianomi is neutral. But at current levels, I think the shares could be worth further research.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Eurocell (LON:ECEL)
This share was one of Paul's mystery shares in March, following release of FY'22 results on 16th March.
The SP today is down 8p but that simply reflects going XD today in respect of the final dividend of 7.2p.
In March the forecast EPS for FY'23 was 18p. It is currently shown on Stocko at a slightly reduced figure of 17.3p.
However, on the company website, consensus forecasts were updated in March as follows:
FY'23 EPS - Peel Hunt 15.5p, Berenberg 15.4p.
FY'24 EP - Peel Hunt 17.2p, Berenberg 17.4p.
The reduced FY'23 forecasts have not been updated on either Stocko or Sharepad. Seems rather strange (and unusual) that the revised figures have not filtered through to either.
Without these revised figures feeding through there is a heightened risk of a profit warning.
Paul's valuation was based around FY'23 EPS of 18p then reverting to a longer term reversion to at least a steady historic level of 20p. That might take a while longer than Paul expected in March.
I was doing some research with a view to opening a position but it looks like a downward revision of expectations is required. Not quite the slam dunk bargain it appeared so may pay to hold off for now.
This is the first time I have seen a company provide consensus forecasts on their website so credit to Eurocell for providing this information.
Snazzy
Thanks Snazzy - very informative. Eurocell (LON:ECEL) is on my watchlist, but am still a little undecided as to if it has reached its bottom yet, so appreciate your thoughts. I will hang on a while longer.
IGR . I think Roland is missing an important point . The company says it is making significant progress to achieving pre-covid margins of 6%.-see below . If they lose unprofitable business and re-set the cost base then that’s a positive surely and the price should replace the higher eps .
”The Board expects FY24 to present demand and pricing challenges given
widespread consumer caution. Nevertheless, it expects to make progress towards
its FY25 aspiration. With margin recovery underway, management is developing
a growth-focused strategy that will also better leverage the Group's scale and
capabilities to further underpin delivery.”
GB - I sold my GB ages ago at a fiver, much too early as it turned out, but at least I missed the collapse after it overpaid hugely for a US footprint and had the ToB interest disappear. There are a number of pertinent points in some comments above but basically I just could not see how a very high rating was accorded to a company with such pathetic returns (on capital). I can only assume thyey do not have much pricing power?
Castings (LON:CGS) (I hold) has exprienced unusally heavy buying this morning. It looks as though a buyer (or concert party) bought a total of 140,000 shares (cost about £475,000) around 11.30 a.m. Av daily volume is 21,000.
Does anyone have any insight on these transactions?
Have corrected the cost from £175k to £475k!
Kromek (LON:KMK) on a slowish day I'm drawn back to this topic which I think is an interesting case study and I'm trying to organise my thoughts around it as I find myself caught between two stools.
Interested to note the broker research post recent announcements. Two brokers went for a 26 to 27p price target (at the time 4* the share price). But then Equity Development showed the read across from the Redlen Technologies sale to Canon. That deal was done at $290m for a business producing around £8m of annual revenue. Apply similar metrics to Kromek (LON:KMK) medical imaging business and you get 57p a share (thats 8* the current price!).
Now I'm not for a moment saying that it will ever achieve 57p - we know the negatives, has been cash burning, only just turned break even etc. but there is a clearly massive gap between private and public valuation of this business. Ie the strategic value of Kromek (LON:KMK) medical technology is way in excess of its actual public market valuation.
So question is how do you unlock such value? If I'm a shareholder I want to maximise my value and at 8p (today - up 15%) I'm clearly not. But nor do I see a route to get there on the public market. The public market wants to apply a 10-15* PER type multiple to the business (nothing necessarily wrong with that) but the private market thinks the value is massively higher. Even at half the price Canon paid for Redlen (which was just the Medical imaging, not the Radiation detection) you'd have a share price north of 30p.
So should Kromek (LON:KMK) delist and then sell the business from a private vehicle? Maybe, but it is now the sole independent medical imaging business of this type globally so given OEMs reluctance to buy, or be offered, competitors tech, Kromek (LON:KMK) could clean in terms of market share and become increasingly valuable. But if no sale, then as a shareholder I wouldn't want it private and that then leads back to the public market being unwilling to give it a high rating, which in turn means it shouldn't use the public market to raise capital for expansion.
Any other thoughts out there?
The directors of Kromek (LON:KMK) have been buying (fairly small amounts but at higher prices than currently). Institutions seem to be buying rather than selling. Only David and Monique Newlands have sold (judging from the Stockopedia list). Newlands is a fairly large investor: his disclosed holdings are here. You might see what you think about his judgement by looking at his other investments.
Kromek's value depends on its financial returns or on its strategic significance to a trade purchaser. At the moment it seems that the market believes there are better returns elsewhare, and no trade purchaser is interested.
What might cause this to change? (No position currently).
I am really quite baffled by PayPoint (LON:PAY) . The quality metrics are excellent, they are growing (albeit slowly) and the dividend is excellent. And yet their total return over almost any time period is pretty poor. How can a business generating such excellent returns on Capital and Equity fail to reflect that in the return to investors? Any thoughts?
I share a similar view to you Julianh. I started building a position in PayPoint (LON:PAY) from 2016 onwards. I now sit on > 50% paper loss on share price. I think I bought in when the price was artifically too high so complete error on my part. It seems like a fairly pedestrian business. It is the quality metrics and dividend which are keeping me in here.
Purchased a starter position in PayPoint (LON:PAY) in 2014 with continued purchases until 29th March. Currently down 17% capital loss although more like 12.5% total loss after dividends to date. Currently my largest holding in an otherwise arguably over diversified portfolio.
The cash churned out in dividends hopefully backs up what appears to be is a fairly simple business with tailwinds from exposure to eCommerce and fintech whilst it's defensive inflation linked quasi monopolistic earnings benefit from a raising rate environment.
Mr Market is pricing it at a single digit PE equal to its dividend.
Sounds great!
On the other hand is the current price reflecting the recent letter before action which may challenge its market position? Was the recent acquisition of Appreciate a distraction to hide financial cockroaches?
Or is it just on sale right now and I should continue to back up the truck?
I've topped up my PayPoint (LON:PAY) holding today after their trading statement. Does anyone know anything about the largest holder: Asteriscos Patrimonial SL, which currently holds over 25%?
They've been gradually building a position in PayPoint (LON:PAY), however have yet to purchase in the market since the Appreciate acquisition. It is also worth thinking about the main shareholders of Appreciate and their intentions (Samson Rock aside).
Any recommendations ?
New tax year so pension funds available which means can consider main market shares
Nothing particularity standing out at the moment apart from the ones already holding .
Missed out on Portmerion few weeks back and that’s made it’s move .
Wynnstay looks ok and it’s at year lows but I’m pretty full on that .
Market has had a decent bounce so maybe due a May lull .
All a bit vanilla right now nothing much floating my boat .
Any inspired choices to look at ?
It is very sad to say that with the NSH declared bankrupt and failing patients and the public, demand for private healthcare will increase. SPI stands to benefit from this.
I have thought that for a number of a years, but SPI has persistently failed to deliver those profits and share price gains. Basically it struggles with wage inflation, rent increases etc. In addition to this the real profits are in the South East, particularly London, where HCA and more recently Cleveland operate. HCA dominates currently, Spire has no real presence in London. A lot of hospitals are leased etc, with inflation clauses etc. That makes it really difficult to make meaningful profits - if it can't make meaningful profits and progress now, when will these happen? A lot of its business likely comes from NHS overspill where margins will be very tight. It's the Cash buyers at hospitals like the Portland where the real profits are made - with no BUPA, WPA tariffs to stick to. Just my personal view, but somewhat reflected in the poor share price performance over the last 5 years or so. They also turned down an offer a while back at circa 300-315p from recollection - that looks like an error. Possibly management more interested in preserving their employment rather than shareholders interests there - just my personal view. Either way the shares have not performed well at all. Minimal free cashflow, virtually no dividend etc. Always jam tomorrow.
I agree with most points. However, the number of self paying patients are on the rise. The margin here is much better than the insured population. I keep an eye following my small purchase. It is the right business to be now. See how do they perform.
Generally, healthcare is a good sector to be in for the next few years. I also own PHP, GSK and Pfizer.
Spire is a minnow in comparison to HCA etc. It's a very capital intensive industry as well - think latest MRI machines etc. Most private hosptals for example (in the UK) don't have their own Cath lab - for cardiology procedures. HCA will have some - e.g. at LBH. Very costly / capital intensive - if you want to compete with the big boys it costs money. A lot of the provincial locations simply don't have the volumes etc. for such services. Of course there is self-pay and demand but even that self pay will be strained with higher rates / recession etc.
It was the shareholders who rejected the offer. Management recommended it!
As regards standing out, you could always look at Futura Medical which released their ED (erectile dysfunction) treatment on Monday. The shares have been quite perky since, although drooping a little the last hour. Every newspaper in the land covered the release. Boots sell the product (Eroxon).
Any recommendations
Robert Walters (LON:RWA) looks ridiculously good value today for a superbly run business with a great dividend. It’s priced for deep recession when it’s main markets in Asia are potentially about to go into overdrive, owing to a combination of a powerful bounce back in China affecting all satellites and structural changes in corporations and employment in Japan. I could be wrong about the entry price or the timing - I usually am - but I’m very confident about the company and the profit potential.
I think the 'easy money' has been made in Portmeirion (LON:PMP) but in my view the shares are still undervalued and have further to run. Given the recent update Volex (LON:VLX) also looks interesting.
I would also mention Jet2 (LON:JET2) . The following are my views/thoughts.
Forward thinking management lead by Executive Chairman and founder Phillip Meeson have run rings around the competition, notably TUI AG (LON:TUI). Jet2 (LON:JET2) has over 1 billion of cash (its own) and confirmed orders with Airbus. It has a very good record for customer service and treats its staff well.
"Following the trading update in late January 2023, the Board now expects to report a Group profit before foreign exchange revaluation and taxation for the year ended 31 March 2023 of between £387m and £392m. Total cash at 31 March 2023 was £2.62bn with an 'Own Cash' balance (excluding customer advance deposits) of £1.12bn."
It has also increased its control over handling operations at its major airports, in line with a proactive approach by management.
"Just as we did last year, we invested well ahead of the summer season to ensure we have adequate, fully trained resources to operate with our normal high standards of customer care. In addition, we have increased our operational resilience by taking control of handling operations at a further two of our UK bases - Bristol and Newcastle - meaning we now self-handle at seven of our ten UK bases and are therefore not reliant on third parties for these aspects of our operations."
Anecdotal evidence indicates that the holiday industry and airlines are experiencing significant tailwinds, if you look at announcements from easyJet (LON:EZJ) Ramsdens Holdings (LON:RFX) and the like.
Extract from easyJet (LON:EZJ) 18 April trading update:
"We see continued strong booking momentum into summer as customers prioritise spending on travel and choose airlines like easyJet offering the best value and destination mix, as well as easyJet holidays which is continuing its steep growth trajectory as the fastest growing holidays company in the UK. "
Jet2 (LON:JET2) is no longer as cheap as it was but trades on <10 PE. The company will to an extent be buffeted from time to time by macro events, but it has excellent management. I think that it is a very good company and may even in time turn out to be a great company. I have recently bought an opening position and will look to add depending on price and availabilty of funds.
Portmeirion (LON:PMP) and Volex (LON:VLX) are my 2nd and 3rd largest holdings. Avingtrans (LON:AVG) being number 1.
TU ?
Trading Update.
Question on "ex-dividend day" - is a dividend due to be paid to shareholders at the start or the end of the day? For example, according to Stocko, Ibstock (LON:IBST) , is ex-dividend today. If I buy the share today, do I get the dividend or not?
not!
I believe it's a not. You would have had to buy yesterday or earlier to receive the dividend payable on 12 May. I'm an investing noob but that's my understanding.
No, you won't get the dividend if you buy today. The dividend will be paid on 12th May.
Definately NOT. You should note in theory that the day it goes ex div the price falls by the dividend. In practice not always so.
It would be much appreciated if Stocko could list each Thursday those stocks going ex-divi - or a link to wherever..?
Here is a list: https://www.dividenddata.co.uk...
Far better to keep a page on your spreadsheet dedicated to these dates for the shares held on it. It's a no-brainer!
A bit surprised to read the confusion about dividends today.
There’s no need for Stockopedia to provide a list each Thursday which anyway is after a share has gone ex dividend! The ex dividend day is almost always a Thursday.
There is an excellent free site for dividends, so instead of asking Stockopedia to reinvent the wheel, make full use of an excellent free site already up and running!
This is the link for all forthcoming dividends, and this link is for ex dividend dates:-
https://www.dividenddata.co.uk...
Note that we are even supplied with the dividend yield for the next dividend too. It’s a superb site.
There are several other headings all well worth using.
e.g dividend pay dates, and the final “MORE” one which lists the quarterly and monthly dividend payers, and dividend cuts too.
Dividend Data site updates as soon as a dividend is announced and it’s very unlikely that Stockopedia could do that anywhere near as quickly. So it’s right up to date.
Just key in a any share on the ex dividend page to bring up both the next ex dividend date and pay day and yield for that dividend, if a dividend has been declared, and also the dividend history for that share.
Also, re the confusion about dividends. If we’re already holding the share on ex dividend day we get that dividend. If we buy on ex dividend day we don’t!
And the dividend is taken out of the share price first thing on x dividend day. But after that the share price as usual goes up , or down even more than the dividend taken out of the share price, for the usual reasons.
So sometimes the share price recovers ALL the early morning ex dividend fall almost at once. Or (e.g if a lot of holders sell once they know they will get the next dividend) the share can end the day lower than just that dividend taken out of the share price first thing.
You need to be on record as a holder on the Record Date which is usually the day after the ex-dividend date. To be certain of receiving the dividend buy the day before the ex-dividend date. Often the case, the value of the dividend is built into the share price which then drops when the share goes ex-dividend so there's not much to be gained. One may even want to sell just before the ex-dividend date if it's more beneficial to make a capital gain instead of having the dividend.
Ex is shorthand for excluding dividend. So as others have said buy the day before or earlier to get the dividend, This is because the exchange works to 2 day settlement and record day, the day that divi is assigned to a holder, is always Friday, allowing for the weekend just in case. If shares change hands on a wednesday, their new owner will be recorded two days later on the Friday. If you buy today, the previous owner gets the divi.
Thinking about the recent discussions on Sosandar (LON:SOS) and their reviews, I had a look at the John Lewis and M&S (and yes, even mumsnet.. no sniggering at the back please) websites - it is pretty positive, their products seem to get an majority thumbs up across the board. I think there will be better buying opportunities over the next few months, but it is definitely on the watchlist.
Unscheduled rns from PayPoint (LON:PAY) generally positive/top end of expectations although no mention of legal letter before action. Also I’m confused as it references turnover ahead at £125M vs £115M however I have last years turnover at £145M? I know Graham previously followed PayPoint (LON:PAY) and Appreciate so would welcome any thoughts. Ps I hold.
Apologies just realised £145M turnover at PayPoint (LON:PAY) last FY includes discontinued revenues after selling overseas business.
PayPoint (LON:PAY)
Hi Jamie, thanks for the comment,
Re: turnover, PayPoint did have net revenue from continuing operations at £115m last year.
Net revenue is an alternative performance measure that is not the same as statutory revenue. Here's the definition:
Revenue from continuing operations less commissions paid to retailers and the cost of top-ups and SIM cards where PayPoint is principal. This reflects the benefit attributable to PayPoint’s performance eliminating pass-through costs and is an important measure of the overall success of our strategy.
Best,
Graham
Thank you for your correction that net revenue is not statutory revenue and also for your thoughts above. PayPoint (LON:PAY) is now my largest holding so I would welcome any bear views from other subscribers as I no doubt also have positive ownership bias.
The objective of my holding is to generate cash for reinvestment into spicier growth stocks. I think the Appreciate acquisition will deliver a positive return on large cash holdings due to interest rate increases. I also believe it is embedded within small retailers and is also enabling banking type financial access to poorer communities and is embedded in government assistance including energy support etc.
Aside from the lack of significant growth prospects main uncertainty to me is whether the recent legal claim will threaten the quasi market monopoly PayPoint (LON:PAY) has. Therefore I would, er, Appreciate any negative views!
IGR update this morning is less than encouraging. The share price had clearly run well ahead of events and will almost certainly be in for a period of retrenchment. Down heavily already. Given the negligible profits for the next year or so, the share price is far to high and priced for perfection. The company is not in any danger and will recover, but life's too short. Good luck to all holders. I won't be buying back anytime soon.
I don't need a separate web site or chat room to post what I want to say. I will do it here. This is a timely and topical news and trading thread where we can post our opinions.
Are the final results of Dianomi (LON:DNM) worth a mention, or is the company too small with £40m turnover?
Hi Gerard88,
Thanks for flagging up Dianomi (LON:DNM), it somehow slipped through the net this morning. I've added it to the list for today, although we may not be able to t fit everything in.
Roland
Many thanks Roland. A very useful write up!
Anybody know what is going on with Melrose this morning? Up 122% (according to ADVFN) so far no news.
News just out 3 for 1 following GKN demerger.
Demerger into Melrose (aerospace bits) and Dowlais Group (automotive bits). Put simply, share consolidation of 3 for 1 of old MRO shareholding, then 1 new Dowlais share per consolidated MRO share. You should end up with an equal number of shares in each (i.e. both 1/3 of the previously held nominal).
Yes I second BnB re GB (LON:GBG) which I hold.It appears the US takeover of Accuant? last year was a very poor deal.
Recent departures of top executives suggests all is not well in the Group. Very disappointing as this has been a very successful Company for many years.
GB (LON:GBG), market seems to be relieved. Will GTCR table a new bid ? Previous one over £5 was rejected.
Thanks for the review of GB (LON:GBG) I was a long term holder until a few weeks ago, selling at a profit (cautionary measure since it was a multi-bagger for me then the decline in price nearly moved me into a loss.)
I found the company interesting but always felt they paid a very high premium for acquisitions in earlier years, yet somehow the acquisitions turned out well. I was also very impressed with their cash conversion, paying off debt quicker than I anticipated.
Reasons for my sell out were:
- avoid any further long term decline in the share price when I see other opportunities
- recent executive departures as mentioned by portugull
- in recent years they had a boost from crypto related business which has seen a downturn and I'm not sure that it will ever return to the same levels since crypto hype has died down (for the record I'm not a believer in crypto currency)
- high level of debt compared to historically. I've seen other previous holdings come crashing down when making exceptionally large acquisitions relative to the size of the company (i.e. Cineworld and 888 (which I exited profitably) and MicroFocus (which I took a big loss on). The most recent acquisition by GB was a massive multiple of earnings of the acquired company.
- Stockopedia reports show a declining margin over the years and with acquisition adjustments to operating profit I'd rather take a cautious approach in interpreting numbers (not saying anything untowards is going on, but my gut was telling me to get out)
Hopefully momentum is turning and this stock can regain past glories. I'm just not ready to dip my feet back in when I only recently exited.
Morning guys. If GB (LON:GBG) gets the full treatment today, I’d be grateful. Many thanks for your excellent work.
Thank you for the suggestion BnB... noted. G.
Hi BnB,
GB (LON:GBG) is next on my list!
Roland
My morning smallcap tweet: All's Well That Ends Well Up On The Day
Manolete Partners (LON:MANO) Filtronic (LON:FTC) Rank (LON:RNK) I (X) Net Zero (LON:IX.) Kape Technologies (LON:KAPE) WANdisco (LON:WAND) Trakm8 Holdings (LON:TRAK) IG Design (LON:IGR) Dekel Agri-Vision (LON:DKL) DG Innovate (LON:DGI) Ondo InsurTech (LON:ONDO) PayPoint (LON:PAY) ME International (LON:MEGP), Mulberry (LON:MUL), DP Poland (LON:DPP), Foxtons (LON:FOXT), Capital (LON:CAPD), Dianomi (LON:DNM)
◄Manolete (MANO)► guides FY-Mar pretax -£3.9m. H2 pretax £1.6m. UK insolvency market returned to more normal operating conditions following a two-year suppression. [SP=220 Cap=96m]. I hold.
◄Filtronic (FTC)► $1.1m order for Morpheus X2 high power modules. Will be shipped in FY24. [SP=11.57 Cap=25m]
◄Rank (RNK)► guides FY-June U/L op profit at the upper end or slightly ahead of the previously guidance of £10-20m. [SP=71.2 Cap=334m]
◄i(x)► Net Zero (IX.) strategic review concludes co should "execute profitable investment realisations from the existing investment companies in the short term". Will cut operating expenditure to 2% of NAV, less than half previous fig. $7.5m loan at 10.5%. [SP=9 Cap=7m]
◄Kape (KAPE)► final offer of 290p. [SP=286 Cap=1225m]
◄WANdisco (WAND)► FCA to investigate mis-statements. [SP=1310 Cap=877m]
◄Trakm8 (TRAK)► £6m+ 3 yr contract. [SP=17.53 Cap=9m]
◄IG Design (IGR)► guides FY-Mar rev c.$890m down 8%. Adj pretax c.$9m, ahead of market expectations, "Due to the recently deteriorated trading, and very limited pricing expectations for Christmas 2023 in the United Kingdom, the Group is likely to incur a one-off, non-cash write-down to the historic goodwill." Current trading ahead of exp. [SP=184 Cap=179m]
◄Dekel Agri-Vision (DKL)► Q1 production in line and cashew price slightly ahead of exp. [SP=2.4 Cap=13m]
◄DG Innovate (DGI)► re collaboration with BRIST Axle System and BASE Studio Arge - agree a detailed plan to develop a series of commercial offerings, incorporating co's technology. [SP=0.08 Cap=7m]
◄Ondo InsurTech (ONDO)► signs channel partnership with US's WNS to accelerate LeakBot deployment in North America and worldwide. [SP=6.69 Cap=5m]
◄PayPoint (PAY)► guides FY-Mar pretax at top end of range of market expectations. [SP=453.5 Cap=329m]
◄ME Group (MEGP)► 0.6p special div. [SP=134.33 Cap=508m]. I hold.
In line: MUL, DPP, FOXT, CAPD, DNM
Thanks for all your work on this daily news bulletin MrContrarian.
So just 6 weeks after suspending the shares, FCA decide to investigate WANdisco (LON:WAND) - guess thats progress for us!
sanjeeeeeettt .... couldn't resist ! :o)
FCA just turn up to count the bodies, they have yet to prevent or warn of any wrongdoing.
Hi MrC, I also hold ME International (LON:MEGP) and today’s special dividend announcement (on ex- div day) also seems to include an upgrade to guidance - very nice on both counts. Your daily efforts continue to be much appreciated, thank you.
0.6p?! I calculate that is £4.61 per £1000 of holding...