Small Cap Value Report (Thur 28 June 2018) - KOOV, TND, AUK, GOR, XPS, SPRP/FA.

Morning folks,
Quite a few announcements today.
I'm going to skip the trading statements that are "in line with expectations" - they aren't really news.
A few updates which did catch my eye, for one reason or another:
- Koovs (LON:KOOV) - "Customers love Koovs"!
- Tandem (LON:TND) - AGM statement
- Aukett Swanke (LON:AUK) - interim results
- Gordon Dadds (LON:GOR) - final results
- XPS Pensions (LON:XPS) - final results
- Sprue Aegis (LON:SPRP) -AGM statement
Koovs (LON:KOOV)
- Share price: 19.75p (+13%)
- No. of shares: 175 million
- Market cap: £35 million
This isn't a proper news announcement, either, but I just thought it was interesting!
Koovs, the online fashion retailer, has achieved a big net promoter score (NPS) among customers in a survey conducted by an "independent industry research company".
I'm not familiar with this research group - it is supposedly rather large in the Indian market.
Figures for Q1 2018 show Koovs with an NPS of 61%, 16 points ahead of its nearest rival and performing top in all six customer categories of Price, Product Variety, Product Quality, Ease of Navigation, Delivery and Post Delivery Experience.
I've just pulled out the interim results to confirm my suspicion the Koovs still had a negative gross margin, as of the most recent figures: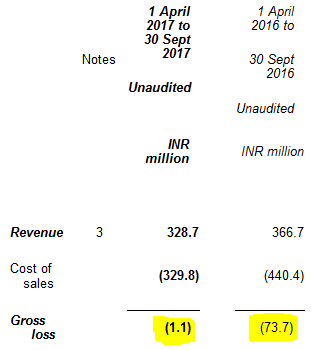
The company is moving in the right direction, certainly.
Sosandar (LON:SOS), another small online fashion play, should also see margin improve as it scales up, thanks to increased buying power.
But a negative gross margin is a major red flag in my book. It means the company is selling a dollar for 90 cents (or one rupee for 50 paise). No wonder customers love it so much!
It's easy to have very happy customers when you are selling things at a loss. What's more difficult is to keep your customers happy and make a profit at the same time.
The metrics have definitely been moving the right way for Koovs, but for me it still needs to get across that threshold of profitability at the gross margin level.
It had a much improved "Trading Margin" of 18% at the interims.
The definition of this is:
implied retail gross margin that would be reported in the companies accounts if Koovs India were able to ship products directly to the end consumer.
The trading margin excludes delivery, warehousing and customer care costs - these are important costs that nearly all of Koovs' competitors will have to bear, too. If they are all providing a more basic service to customers and/or at a much higher price (because they want to make money), then it's no surprise that Koovs would have the best NPS scores in the industry!
Koovs has a StockRank of 3 and is classified as a Sucker Stock, so the warnings are pretty clear. It could still succeed, but the odds don't look terribly favourable.
Tandem (LON:TND)
- Share price: 120p (-17%)
- No. of shares: 5 million
- Market cap: £6 million
Tandem is too small for us to typically cover in this report, but I feel compelled to mention it in light of this AGM statement. It is a bike and toy designer, owning and licensing some decent brands.
Sadly, this stock has been very costly to me. I may not be able to remain objective in my coverage of it!
Back in 2015, I was convinced that it was going to do very well for investors. I "backed up the truck" and made it my biggest position.
The profits that I imagined did not materialise. 2015 and 2016 results were uninspiring.
Bear in mind that this is a very old company. The share price chart goes back to 1994 and I can see RNS statements stretching back to 1999. Some of its bicycle brands are over 100 years old.
The most disappointing aspect of the performance, from my view, is the sense of wastefulness.
2014 had been a particularly good year for the company. Instead of increasing its dividend to an attractive level or creating some value within the existing business, it went on the acquisition trail. Over £4 million was ploughed into buying up other small businesses. That's more than half of the current market cap!
Directors paid themselves almost £800k last year, while distributing less than £200k in dividends to shareholders. I think that's sufficient to show where priorities lie. There are times when low dividends are appropriate, but that does not include mature (very old) companies, with limited growth prospects.
I held the stock for as long as I could, hoping for a rebound. Eventually, when I was trying to make a property purchase last year, I sold out and crystallised significant losses. But I still thought that the outlook for shareholders was quite good.
The 2017 results turned out to be amazingly positive. Revenue was down as the bicycles division was restructured to cut costs. As a consequence, net income rebounded to an all-time high of £1.7 million.
To give credit where credit is due, the company has almost never made a loss.
Additionally, the accumulated profits over the 2015-2017 period have left the balance sheet in decent shape.
The company has net debt of £1 million but net tangible assets are £5.5 million of which £3.5 million is freehold property.
I can't help thinking that if it hadn't been for its 2015-2016 acquisition spree, the balance sheet and shareholders would be so much richer again.
I strongly considered buying back in again, after the 2017 results announcement.
The following factors held me back:
- the bid-ask spread
- I had already got it wrong once before, so how confident could I be that I was going to get it right the second time? Was I acting on emotions, trying to recover prior losses, rather than thinking rationally?
- and the main reason: what was going to stop the entrenched management/directors from going on another acquisition spree or otherwise wasting their net income this time around?
Despite the above factors, it remained a tantalising proposition.
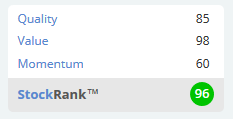
For a value hunter like me, a mid-single-digit P/E is hard to ignore.
And how often do you see a StockRank like this:
Anyway, let's take a look at today's AGM statement:
Trading in the first part of the year has been difficult, with revenue for the 25 week period to 24 June approximately 30% behind the prior year period for a number of reasons
Amazing, isn't it?
Just like after the 2014 results, Tandem has swung from a great performance to suddenly facing severe difficulties.
Toys and outdoor products have been overstocked. Again, to be fair to the company and management, there has been a well-documented bloodbath in the toys sector:
The well documented issues in a number of national retailers, most significantly Toys R Us who were one of our top five customers and an outdoor specialist, have also impacted on the sector.
It wouldn't be a proper profit warning without blaming the weather and consumer confidence, too:
Lengthy spells of cold weather and periods of heavy rain coupled with cautious national retailer buying and a lack of confidence in consumer spending was acutely reflected in toy industry data with a significant year to date decline in sales reported.
Bicycle sales have also been disappointing. No specific reason for this is given.
There is some good news on the horizon:
We are delighted to announce that we have reached agreement, subject to contract, with The Walt Disney Company to significantly expand our portfolio of licenses for 2019 and 2020 to incorporate their major properties, including Disney, Marvel and Lucasfilm.
So it's another mixed and mostly negative statement from Tandem.
I'm probably never going to buy shares in it again, since having been burnt by it once, and feeling sore about that, I don't want to revisit it.
But do I think the shares are too cheap? Yes, I do still think so. The brands owned by the company, its long-standing profitability, and its ability to win licenses from the likes of Disney deserve a bigger market cap, I think.
The problem is that £800k of remuneration for directors is so high, relative to the size of the business. And although they have by no means done a terrible job of managing the business, they have failed to take actions which would either a) generate strong compound returns for shareholders, through the effective reinvestment of profits, or b) produce a reasonable return for shareholders, relative to the riskiness of the stock, by offering buy-backs or dividends of an appropriate size.
If the directors could be motivated to improve shareholder returns, or replaced, I'm confident the value of the company could be significantly increased.
So perhaps in the absence of a shareholder campaign, and given that trading has deteriorated so much in the first half of the year, the prospects remain dim. At the end of the day, I'm just going to have to put this in the "too difficult" category.
These metrics are really fascinating, all the same:

Aukett Swanke (LON:AUK)
- Share price: 2.1p (-20%)
- No. of shares: 165 million
- Market cap: £3.5 million
Another tiddler of a company which I would normally never cover in this report, but it's another one that I have costly experience of, so it's close to my heart.
It's also a useful lesson in shareholder value destruction.
I made damaging losses here after I was hypnotised by a temporarily cheap P/E multiple.
The reasons to not invest were obvious enough.
An architectural practice has some of the most unattractive characteristics from an investment point of view:
- It's the perfect example of a "people business". No scalability. Always 100% dependent on employees.
- Large, lumpy, unpredictable transactions.
- Extreme cyclicality. Business dries up every few years.
Going back a couple of years ago, I was still willing to bet on a company like this, if it was cheap enough. A bit like my Tandem bet, I thought "it can't get any cheaper than this, surely?"
Having been burned, I am no longer willing to take that chance.
Aukett has another similarity with Tandem. After a couple of good years, from 2013-2015, it ploughed the best part of £2 million into acquisitions, including a poorly-timed Middle East purchase. Again, the amount spent on acquisitions now turns out to be roughly half of the current market cap.
If it had held on to that cash for a rainy day, or bought back its own shares or distributed the money as dividends, investors would now be in a better position.
Interim results today are as follows:
- Revenues down 18% at £7.41m
- Loss before tax of £1.22m (2017: £358k loss)
- Cash (net of overdraft) of £317k with net borrowings of £311k; representing 0.6% net gearing
That gearing ratio is not so bad, but the company is set for losses for at least another six months, and perhaps the base case assumption should be for at least another 18 months of losses.
The company does state that there were some "temporarily overdue" debts, and that it would have had a net funds position, if they had been paid on time.
That's another uncomfortable feature of the balance sheet: a very large receivables balance. Receivables were sitting at over £7 million at period-end, almost matching the revenue for the six months. Indeed, that receivables balance is twice the current market cap!
With revenues falling and losses ongoing, is there any hope for shareholders?
Its fortunes will be determined by the macro-economic winds:
Changes in the political climate and the subsequent timing of their impact on our markets is the key feature to the Group's recovery from the current losses. Whilst the focus on controlling costs will continue, this by itself will not resolve market issues and the Group's performance.
And this sounds worrying:
Progress has been slow on the recovery of our older debtors which has historically allowed the Group to operate within its own working capital and avoid further borrowing.
There are other investors who might be able to spot a company like this when it is coming out of a trough and is undervalued, but that's not something I've been able to do yet. I now appreciate how difficult that is.
Besides the difficulty of getting the timing right, there are also quality considerations. I now apply a filter to my stock selection which enables me to simply avoid companies like this. There are plenty of companies out there which are scalable, have more predictable sales, and aren't so cyclical. Perhaps it's a little bit more boring, but I think I prefer the stress-free life!
As for these shares, it's still possible that they are undervalued and could recover from the current level (assuming that the company can survive back to profitability and avoid massive dilution, of course). But they are going in my "too difficult"basket.
Stocko algorithms see it as having some value, with a ValueRank of 81.
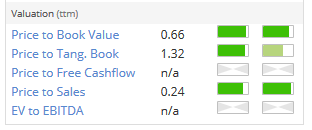
Quality and Momentum, as you might expect, do not rate quite so highly.
Gordon Dadds (LON:GOR)
- Share price: 172.5p (+6%)
- No. of shares: 29 million
- Market cap: £50 million
Gordon Dadds Group PLC (AIM: GOR), the acquisitive London-based international legal and professional services group, is pleased to announce its audited results for the year ended 31 March 2018.
I don't want to make too many specific comments on this company. I really just want to point out the proliferation of professional services companies who are choosing to list. This one listed a year ago.
Strategy is as follows:
The board's overall objective is profitably and rapidly to grow the business in professional services by acquiring additional revenue which can be efficiently processed through the group's bespoke administrative systems. As the traditional partnership model for solicitors breaks down the Group is ideally placed for growth in the legal services sector.
It's pretty much exactly the type of stock I am currently trying to avoid: professional services, and with an acquisitive strategy to boot.
Its idea is to have a unified, high-tech back office platform, allowing for the efficient integration of new revenue streams.
Back office is a cost centre and not a hugely important one to my mind. So I'm not sure how excited investors should be about this strategy.
Is there is a proper rationale for these legal/professional services to list on the public markets, or does it reflect an element of credulity by stock market investors, at the end of a long bull market?
What's next - a public listing for KPMG or Deloitte? Is Clifford Chance going to have an IPO?
There are important reasons why these companies have traditionally kept the partnership structure. And if that structure is good enough for the biggest and best professional services and legal firms, it should be good enough for the smaller ones as well, surely?
Let's see if my scepticism is justified.
XPS Pensions (LON:XPS)
- Share price: 183.25p (-5%)
- No. of shares: 204 million
- Market cap: £374 million
This previously traded as "Xafinity" (XAF).
I covered it ahead of its Punter Southall acquisition last December (link).
Revenues increase to £64 million and PBT increases to £4.2 million, with the following proviso:
This includes the operating results arising from the business acquired from the Punter Southall Group for the period 11 January 2018 to 31 March 2018 and amounts to revenue of £12.9m, and profit before tax of £3.4m as well as the operating results (Revenue of £2.0m and profit before tax of £0.8m) for the HR Trustees business up to 11 January 2018 when it was sold to the Punter Southall Group
I'm not entirely clear about this - does it mean that PS generated PBT of £3.4 in less than three months of ownership, while the rest of the business generated PBT of only £0.8 million?
The combined entity is now "the largest 'purely pensions' consulting and administration firm in the UK". It has 900 employees in 15 offices around the UK. It still trails the "Big 3" pensions consultancies (Willis Towers Watson, Mercer and Aon Hewitt).
Performance since year-end is in line with expectations.
Balance sheet shows equity of £154 million, eclipsed by £216 million of intangibles. The net tangible asset value has significantly deteriorated, compared to the last time I looked at it (prior to the PS acquisition).
Loans and borrowings are now £55 million, as some debt was needed, in additional to fresh equity, to fund the acquisition.
My opinion
There is precedent for companies in this space to list: see the US tickers $WLTW (Willis Towers Watson) and $AON (Aon).
I wish the company well, but I'm not personally going to get involved in terms of buying these shares. This is primarily due to the sector its in. I also think the balance sheet should weigh on the valuation.
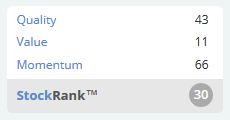
Stocko algorithms aren't seeing much value here yet, either:
Sprue Aegis (LON:SPRP)
- Share price: 77p (-1%)
- No. of shares: 46 million
- Market cap: £35 million
This accident-prone fire and smoke alarm company has changed its name.
Putting the past behind it, it will now be called:
FireAngel Safety Technology Group plc
and will have the ticker "FA."
Operationally, the company has a new outsourced manufacturing partner in Poland ("Flex").
The Chairman states:
As highlighted in our 2017 report and accounts, we anticipated that there would be some short term impact as a result of the final agreed settlement with BRK referred to above and the transition of manufacturing to Flex. However, I do expect the Company's operating results to improve significantly in 2019 and beyond, driven by greater efficiencies and margin control, alongside our ambition to expand our geographic footprint and broaden our product base.It's a strong statement. He is calling the bottom as far as the company's financial results are concerned.
I also quite like the way the company has unified its products under the "FireAngel" name - it's a memorable name, and it makes sense to develop a single, trusted brand for customers.
The statement continues with even more confidence:
We firmly believe that the Company is well-placed to capitalise on a number of exciting operational and strategic opportunities. We are now in full control of our manufacturing processes and see a strong pipeline of new business opportunities with our existing product set, along with increased interest and demand for connected home solutions.My view
This could make for an interesting turnaround stock.
There are probably a lot of stale bulls holding it, and the share price drifts around five-year lows. And it will take some time for any recovery to be fully reflected in the results.
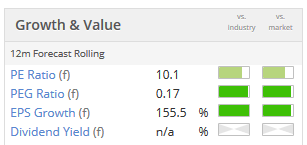
The StockRank is poor, with particularly poor momentum. It may be dipping into value territory, however:
That's it for today!
Enjoy the England vs Belgium match this evening.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Very surprised nobody has made the Sprue Aegis (LON:SPRP) is worth sweet FA comment.
(I meant to mention the other day a family member formerly worked for Mind Gym. When I mentioned they were to become a plc he laughed mightily! He valued it at about three pickled eggs and a tube of Smarties, but he could be wrong about the Smarties).
Redcentric (LON:RCN) prelims today. It looks as though they are struggling to win business. Revenue down but profit up and debt reduced. Maybe the new board can turn this round?
Well, hedge fund Coltrane obviously think so (or a takeover) as they have built up to over 19% of Redcentric (LON:RCN) .
The debt reduction is good - last year having £38m of the £40m revolving credit facility drawn was worrying.
Hi Graham
I don't totally agree with your analysis on Gordon Dadds. The legal industry is very fragmented. Many firms provide a similar service yet they all have their own support staff providing accounts, personnel, IT, marketing support etc. By consolidating there are huge savings to be made in these areas.
There are also opportunities to cross sell legal services in a larger firm which can increase revenue without necessarily having to increase fee earners.
At the moment GOR is not that profitable but it will be interesting to see how things develop in the current financial year. They need to make the right acquisitions and not pay too much for them. Also retaining key staff is important too.
Many made a similar augment to Graham when the investment banks went from partnerships to public companies. I guess the success of this is up for debate, Bear Sterns, Lehman Brothers vs. Goldman, Lazard, Evercore etc.
Arguably he also overlooks one of the better performing and well known professional service firms - Accenture (spun out of Arthur Andersen just before the Enron scandal occured) which is publicly listed and has outperformed the S&P 500 quite handily since it's listing.
Hi there, re: Gordon Dadds (LON:GOR)
As mentioned in my XPS Pensions (LON:XPS) comment, you also have WLTW and AON (and MHM, parent of Mercer) in the investment consulting industry. Some of these have performed well for investors.
Hi, re: Gordon Dadds (LON:GOR)
Thank you for putting forward an alternative point of view!
G
Ah Graham - you have made my day mentioning Aukett Swanke (LON:AUK) !
Graham and I have had a number of discussions over the last 12 months or so concerning Aukett and I have probably been buying his shares as he has been selling - the greater fool theory in play..!
As Graham has said, this is in cigar butt territory al la Mr Buffett and certainly before Mr Munger introduced him to the attractiveness of quality businesses at a fair price.
Whilst I agree with most of Graham's points (this is a lousy business) I am patient and happy to lock up a proportion of my portfolio on the simple thesis that on average over the last 10 years Aukett have produced around 3.6p of EPS and in 3 of the last 10 years they managed circa 1p EPS. Does the current SP make it good value - possibly.
Equally this sector is rife with M&A activity and I have lost count of the number of deals involving Engineering Consultants, Project Managers and Architectural firms. I would argue that a Price/Sales ratio of 0.25 is well below the sector average.
On the point of spending their cash on acquisitions - the rationale was that they were too UK centric and wanted to diversify their income stream. This has worked to an extend and their Middle East business is now a decent size and they are securing larger and better quality projects as a result.
By contrast one of my most successful investments Waterman (LON:WTM) moved out of Russia and the UAE in 2012/13 as they wanted to focus on their core market (UK) - this was a wise move given the notorious payment terms and bad debts that are part and parcel of doing business in the UAE.
The Aukett Board has recently being reshuffled and they are now looking to appoint a new Chairman and another NED, both of which are needed and may be a catalyst for better prospects.
Most of the Board and / or major shareholders are also around retirement age and have large shareholdings. The Board / staff own over 50% of the company. The CEO owns circa 10% of the company alone. At some point in the not too distant future they will want to realise their investment and I am banking on this being be means of some Corporate activity well in excess of the current valuation.
The patient investor should see a decent return on investment from current prices but this comes with opportunity costs and the shares are very thinly traded. Market timing is also key.
As Graham very sensibly notes - avoid if you want a stress-free life. Of course, I hold!
Re XPS Pensions (LON:XPS) - The interim dividend, paid in February 2018, was an "unlawful distribution"! But it seems this was just an admin cockup in that they forgot to file the interim accounts to 30 November 2017 (not to be confused with an interim announcement of results) which demonstrated the availability of sufficient distributable reserves. The payment will have to be ratified at the AGM in September. Not clever...
Graham,
Thanks for your candour regarding your involvements with Tandem (LON:TND) and Aukett Swanke (LON:AUK). I always find there is much to learn from an otherwise successful investor giving an honest appraisal of their occasional failures.
Really appreciate the report Graham, lots to think about and try and learn from, including managements’ ability to sensibly use cash because it can be so costly when you have to issue equity for it.
Regards
Andrew
Thanks Andrew, glad you like the report.
Management's ability/willingness to use cash well is so incredibly important.
There are plenty of "deep value" plays which don't work out, because management can't/won't use their resources properly.
On the other hand, management who do put money to use productively can generate fabulous compound returns for investors.
Best wishes
Graham
Hi Graham, As you've mentioned Sosandar (LON:SOS) I wondered if anyone here managed to make it to Mello Beckenham on Monday which included them making a presentation and if so what your readers made of it?
I saw Sosandar (LON:SOS) present at UKIS which was only a few months ago. Haven't got much to say about them that I haven't said already. If any new and interesting snippets of info were presented at Mello, I'd also be curious to know what they might be! Cheers
Hi Graham
Would it be possible for you to pick a few upbeat situations tomorrow?
I'm despairing of ever finding another good share after today - and all I've got to look forward to tonight is two teams trying to lose.
Slightly tongue in cheek
Phil
Phil.... This was possibly my most downbeat SCVR ever. I'm in quite a good mood, so it's not because I got out of the wrong side of the bed, etc. It's just the way the RNS announcements fell today - hopefully we have better luck tomorrow!
HI Graham, I think after a couple of torrid years Sprue Aegis looks interesting. A quick glance suggests no debt, positive tangible assets and an improving trading situation. Could it be great value now? Best, Peter.
Tremendous statement from SCISYS (LON:SSY) in my view. Very bullish commentary.
Order book up 10% so far this year - suggests annualised revenue growth exceeding 20% and around 2 years worth of forecast revenue
Cash generation of £4m since y/e is excellent so net debt now negligible
Trading on a next year PE of 10 feels too cheap for a business clearing growing with double digit EPS. Wouldn't surprise me to see them upgrade later in the year.
I wish I was at the Sprue Aegis (LON:SPRP) AGM. Fireworks galore, I'm sure!
Interested in your thoughts on ERGOMED Graham. Disappointing trading statement. Not one I own, I don't like buying lots of goodwill/intangibles. Seems to have good order backlog. Seems to me it is one of those companies you have to believe the growth will continue as trading on 20times.
Sorry I didn't get around to Ergomed (LON:ERGO) today, Camtab.
James Latham (LON:LTHM) . Underlying profits flat despite revenue growth due to cost pressures. 11.5% increase in dividend. Outlook is currently for a slightly better underlying profits next year, while the headline figure may be below due to one-off gain from land sales this year.
I'm going to concentrate on the pension shenanigans here. This the recent situation:
deficit
(during year before)
(during year before)
I am not an expert, but clearly in cash terms the pension costs will be higher than we have been used to in recent years due to some apparently unfortunate timing in the triennial valuation. I would imagine the pension trustees would want to see a significant surplus before renegotiating the pension recovery payments before the 6/7 years is up. This could conceivably constrain dividend payments at the margins.
In P/L terms I believe the finance cost of the IAS19 deficit is the important factor. In the past they have split the pension scheme finance costs out, for FY2018 I have made the assumption that it continues to be almost 100% of all finance costs. I'm not sure about the effect of the nominal finance costs on corporation tax. I would say the trend is downwards.
So, while I was initially rather shocked by the apparent sudden ballooning of the pension deficit and recovery payments, I do not believe the is a cause for undue concern. The revenue growth assures me that the company is still not ex-growth and there may yet be some exceptional gains from land sales in a few years.
I hold a small-medium position having sold down in 2016 and having bought back at lower levels earlier this year.
My morning smallcap tweet: Tandem buckles under weight of complacent mgmt.
Tandem (LON:TND), Vianet (LON:VNET), Toople (LON:TOOP), Walcom (LON:WALG), New Trend Lifestyle (LON:NTLG), Omega Diagnostics (LON:ODX), SCISYS (LON:SSY), Sprue Aegis (LON:SPRP)
Tandem (TND) AGM stmt. Apocalyptically bad 30% rev fall in first 25 weeks.In April (4 months into FY) said "The start of 2018 has been more challenging for the Group...but we remain confident that we have the resources and personnel to deliver profitability to our shareholders." And May as actualy better, so maybe worse than 30% down by April. Disgraceful lack of candour. Seems to be run as a lifestyle business. Cycle a mile from this one.
Vianet Group (VNET) AGM stmt. "Benefitting [sic] from solid momentum into the new financial year, the Group's trading in the first two months is broadly in line with the Board's expectations...In the Smart Zones division trading is marginally behind last year so far due to installation phasing although there is encouraging progress with revenue growth in our managed compliance service."
Toople (TOOP) Yet another CFO. "As the Company grows and we look to implement our plan to develop new revenue streams, both organically and through acquisition, it is important that we have the right Board with complementary skills, market knowledge and proven capability to execute on our strategy." On appointing the last one 8 months ago TOOP said "his experience in both SME and Telco will be a valuable addition to our Board." Obviously not. He is not even mentioned never mind thanked.
Walcom Group (WALG) Largest customer has defaulted on a payment of £230k but promises to pay next month after refinancing. A further £540k will fall due. I the cash is not received they are screwed, er "considering alternative financing arrangements, should any be considered necessary."
New Trend Lifestyle (NTLG) FY below the prior year, as expected. Q1 rev shows significant improvement.
Omega Diagnostics (ODX) sells infectious disease business, excluding the VISITECT CD4 test for £1.8m plus £0.375m contingent. Profit before central overheads was ~£0.3m. "This divestment is the first stage of a process following the strategic review as we seek to realise value for shareholders in the short-term from our other assets as well as building value through the more rapid exploitation of the opportunity in CD4 testing at the point of care."
Scisys (SSY) 'Impressive' start to year but say they expected H1/H2 less H2 weighted than previous year. Sounds like they are guiding in line.
Sprue Aegis (SPRP) AGM stmt. "we anticipated that there would be some short term impact as a result of the final agreed settlement with BRK referred to above and the transition of manufacturing to Flex. However, I do expect the Company's operating results to improve significantly in 2019 and beyond."
Just to build on your point about Tandem (LON:TND), these results included over 3 weeks of June, but they only mention that May showed "some improvement" - should I understand that things worsened again in June? I am always suspicious of blaming the weather, but to do so when May and June have had the best weather in (my) living memory seems disingenuous (or as you say, deluded). Clearly something is going very badly wrong.
I tried to short but was unable.
--
Talking about the weather in general, I hold a lot of clothing retailers. Is good weather unconditionally good, or does it get to the point where a long period of hot weather starts to reduce sales, even before the autumn season would normally start?
As a man who doesn't really understand fashion, it would seem to me that people need less clothes when it is hot and sooner or later what we need is some heavy rain to get people out buying raincoats etc. because the ones they used last year (or indeed, 3 months ago) have somehow got lost, fallen apart or gone out of fashion?