Small Cap Value Report (Fri 8 Dec 2017) - CER, XAF, PRV, PCF

Good morning,
This is the placeholder article, but I'd also like to draw your attention to my recent interview with Cerillion (LON:CER), which was originally published to subscribers on my mailing list but can now also be found on Stockopedia at this link.
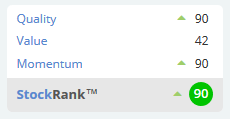
It's a software company which I had already covered a little bit in the SCVR, before realising that the opportunity to interview management would present itself. It's got a StockRank of 90 and a PE ratio of c. 14-15x. So I hope this interview might be of interest to some of you.
Regards,
Graham
Xafinity (LON:XAF)
- Share price: 183.6p (-1%)
- No. of shares: 137 million
- Market cap: £251 million
Proposed acquisition of Punter Southall
This is a mid-tier, domestically-focused pensions consultancy. It listed earlier this year, and this is the first time I've looked at it. Thank you for suggesting it in the comments.
Checking the shareholder register, there are some big names in the investment industry backing it up.
Yesterday it announced interim results and a very big (£153 million) acquisition.
The deal, assuming it goes ahead, will consist of £92 million in cash and up to 32 million shares, along with the sale of an HR trustees business worth £8.5 million.
To find £92 million in cash, Xafinity wants to raise £70 million in New Money and increase its debt facilities.
Its total (gross) debt at end-September was £29 million, offset by some cash. It is now seeking to increase debt facilities to provide a maximum of £80 million in borrowings.
Rationale
The target company is another mid-tier provider of institutional investment advice, so the rationale is as you would expect:
We believe that a successful combination of these two premier mid-tier providers would create the pre-eminent mid-tier firm in the pensions consultancy market, with significantly stronger growth prospects than each business would possess individually.
The "big 3" firms in the space are Willis Tower Watson, Aon Hewitt and Mercer. So the questions now are (1) will Xafinity be better-positioned to compete with them? (2) what about the XAF shares?
Current Trading at Xafinity is fine, with revenues up c. 2% to £26.6 million in H1. Operating profit reduced slightly to £5.3 million, but a much lower interest bill compared to the previous year enabled the final result to improve.
Outlook is positive:
The trading environment for Xafinity remains strong, with our new business performance during the period having undoubtedly been supported by our post-IPO profile. The Company expects strong growth in H2 2018, as the revenues gained from recent contract wins starts to feed through into the business and the pipeline of opportunities strengthens.
My opinion
After raising £50 million at its IPO, the Xafinity balance sheet is now significantly stronger, and the company boasts of its net asset position.
But if you dig into the balance sheet a little bit, you'll find that this includes £57 million in intangibles, so net tangible asset value is minus £25 million.
Intangibles will probably increase again after this deal, and gross debt will go to c. £50 million.
The outcome will be a large firm with something like 1,450 employees and maybe 1,000 pension scheme clients. It could be a serious contender versus the Big 3 in the domestic market.
But whether this translates into shareholder gains is another matter. Maybe I could have shortened this entire report by saying "it's a people business" and leaving it at that, but I wanted to dig into the numbers a little bit more.
Again checking the Xafinity financial statements, the £50 million which it received last year merely plugged the hole caused by its accumulated earnings deficit of £18 million.
But even after plugging that hole, it still had to carry a large net debt position thanks to the £57 million which it has spent on intangibles, as described above.
And the debt and the intangibles will be bigger again after this deal.
For customers and employees, these are successful firms. But from a shareholder point of view, it often seems to me like that there is a lot of money that goes in, and often very little to show for it. And to be honest, I'm not really surprised that this is so often the case.
Remember that there is no heavy equipment to be purchased, and there are no inventories of stock. There is a lot of technical innovation happening inside the firm, but there no copyrighted IP.
Ultimately, I think the shareholder position is too weak here in relation to the employees, to make it suitable for a long-term hold.
That's just my opinion, feel free to make the bullish case in the comments!
Porvair (LON:PRV)
- Share price: 482.5p (+7%)
- No. of shares: 45.3 million
- Market cap: £219 million
Pre-close trading update and acquisition
This company makes filters for industry. It consists of the following divisions:
- Metal Filtration: the filtration and handling of molten metal. Trading as Selee in the USA and China.
- Microfiltration: diverse filtration services. Operations in UK, USA, Germany, China. 500 employees.
Paul covered Porvair's Q3 trading update, which was ahead of expectations. Today's full-year update is also ahead of expectations. There is some nice earnings momentum here:
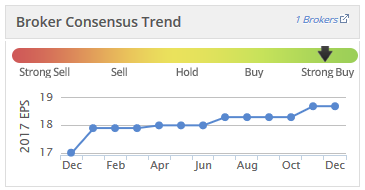
The good news is delivered like this
Revenue growth for the year ended 30 November 2017 was 6%. Underlying revenue(1) growth was 11% overall, with underlying revenue growth of 13% in the Microfiltration division and 1%in the Metals Filtration Division. Earnings for the year are forecast to be ahead of management expectations.
Underlying revenue is defined as: revenue at constant currency excluding the impact of large projects. There might be some discretion involved in the definition of large projects, but it's certainly helpful to see what the currency effect is.
My opinion
This looks like a good company with a niche offering. The historical performance is excellent, particularly when you consider that the growth over the years has been achieved with minimal dilution to shareholders. The share count has increased only marginally over the past ten years:
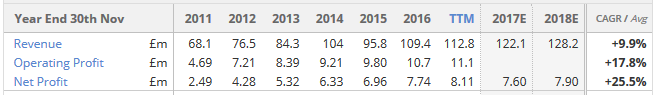
The dividend yield is small, barely 1%, but this makes it onto Stockopedia's dividend achievers screen thanks to growing it and consistently paying it, and enjoying a strong balance sheet.
Let's keep an eye on this, going forwards.
PCF (LON:PCF)
- Share price: 28p (-2%)
- No. of shares: 212.2 million
- Market cap: £59 million
Please note that I currently own shares in PCF.
This specialist bank was previously known as Private & Commercial Finance and produced annual results on Tuesday. The results were ahead of market expectations.
I last covered it exactly a year ago, the last time it produced annual results. Here is the link. It offers car finance to individuals, and vehicle and equipment finance to businesses.
Having reviewed the results, I've decided to get my feet wet and buy a few shares, taking a small, starter position for my portfolio.
Bear in mind that I like the financials sector, so was already biased in favour of investing here.
There are a couple of reasons I've invested.
As was flagged for some time, PCF became a bank earlier this year, enabling it to take retail deposits. These retail deposits are much cheaper than wholesale bank finance, enabling PCF to increase profitability and competitively expand its lending operations.
As they said on Tuesday:
The ability to raise significant amounts of retail deposits will support our growth strategy and allow us to scale the portfolio far beyond what could be achieved for a company of our size in the wholesale debt markets.
From initial banking operations in July through to the end of September, PCF took in £53 million in customer deposits. So it has started paying off the more expensive finance it was previously using.
The infrastructure to build a bank, and the process of being granted a license, are the difficult bits. I think PCF is ready now to grow from its existing base. The lending portfolio is £146 million, but the targets are for this to grow to £350 million by 2020 and £750 million by 2022. It probably won't be able to achieve all that growth organically, but hopefully the organic growth will be significant.
Valuation/Performance
PCF has net assets of £39 million, after raising £10 million at 25p earlier this year.
So the current market cap is just over a 50% premium to book value (and a slightly higher premium again to tangible book value).
I generally don't want to pay such a premium to book value for a financial stock, unless I'm confident that the company will generate an attractive return on equity for the foreseeable future.
PCF uses after-tax ROE as its major KPI. It achieved 12.9% last year, which is more than adequate in my book. It dropped to 8.7% in the current year, but that is to be expected since it raised fresh equity and was setting up new operations.
The target is for ROE to recover to 12.5% over the next three years.
Meanwhile, the cost-to-income ratio (administration expenses as a percentage of net interest income), also known as the efficiency ratio for a bank, increased to 59%. But if we exclude bank set-up costs, this ratio fell from 51% to 47%. As bank assets grow, the overall efficiency ratio should improve, too.
Business lending has been growing strongly. Retail car finance has been more difficult, as this is a highly competitive sector and PCF doesn't offer any PCP products. But with its lower cost of funds now from retail deposits, it will hopefully be able to compete a bit more strongly in this segment in the years ahead.
Outlook is great:
The potential for PCF Bank is substantial and our journey has only just begun. We have clear strategic objectives, have confidence in their execution and the growth prospects of the Group are exciting into the long-term.
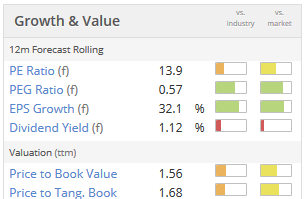
The StockRanks don't particularly like it, and I'm not expecting the share price to do anything very strong in the short-term. But I've seen enough to be comfortable with making a small investment and continuing to study it in the months ahead.
That might be it for today. Have a good weekend everyone!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Very quiet day today here.
So a final reminder that my report into how investors view the trading platforms is here https://www.stockopedia.com/content/quick-n-dirty-report-trading-platform-relative-satisfaction-249308/
Do 'like' it if or join in the extensive conversation there - there's 38 comments about investor experiences to read as well.
have a great weekend
Francis
Yes, also hope Paul is ok. Normally he checks in even if it’s late in the day.
Regards
Andrew
Thanks for the updates Graham, wishing you a great weekend.
I am sure someone has actually checked Paul is well?
He tweeted 13 hrs ago so I'm guessing he had a late night (well late for me, I'm normally in bed by 9pm).
Francis
Yes. Just on intangibles....I have started on this book about the shift in developed economies away from investing in tangible assets to intangible assets. Capitalism without Capital: The Rise of the Intangible Economy https://www.amazon.co.uk/dp/B071P3VGHQ/ref=cm_sw_r_cp_taa_S4NkAbE0BS2SX
Hi Graham
If you have time can you cast your eyes over the FY results from PCF (LON:PCF) released on Tue.
First benefits coming through of the cheap funding resulting from the banking licence.
Market appeared to expect more but underlying result was good and cost of funding much reduced.
Great suggestion aj, I've covered PCF (LON:PCF). Cheers
Morning Graham, as it's slow today I was wondering if you could have a look at £XAF's fundraising for an acquisition - I don't know much about the pensions sphere. Or did Paul cover it yesterday after hours? Can't see a link on the right to yesterday's SCVR. Thanks for Cerillion (LON:CER) interview, listening now.
Hi rtj, nice request re: Xafinity (LON:XAF). Covered it for you. You're welcome on Cerillion (LON:CER).
Thanks Graham. It did seem a bit ambitious for Xafinity (LON:XAF). Think I will stick with Personal Group (LON:PGH) in that financials sector, having bought the dip earlier this year. Nice regular div there.
Hi Graham - re. Cerillion (LON:CER) a very good constructive interview - thanks.
I took an initial holding the day the results were announced and following your review. One thing to mention which I am not sure you have covered. Around 30-40% of the shares are held by management and in particular the CEO (30% of shares). With a total market cap of only £40m, it means liquidity can be an issue. For example yesterday the sp dropped 6% on very little volume and no news.
An afterthought. Nowadays I prefer a podcast to reading text. So if you going to interview and write it up, there would be little additional overhead in recording your interviews and publishing them as well (or instead of?) . You can glean a lot more information from a podcast than you can from just reading the material.
Hi Ram, glad you enjoyed the Cerillion (LON:CER) interview. Good point re: liquidity.
We've tried audio and text versions before, if you prefer audio then I will pass on that feedback to the team behind the scenes.
Cheers
Graham
My morning smallcap tweet:
Porvair (LON:PRV), Angle (LON:AGL)
Porvair (PRV) trading - FY earnings will beat mgmt expectations.
Angle (AGL) University of Southern California has shown Parsortix liquid biopsy can detect metastatic breast cancer from a blood sample. "Angle is working towards an FDA clearance of the Parsortix system in metastatic breast cancer with the required analytical and clinical studies targeted for completion by 30 June 2018. ANGLE is seeking to become the first company ever to receive FDA clearance for a medical device to harvest cancer cells from patient blood for subsequent analysis."
I went to a presentation about two or three years ago where Angle's CEO said that FDA approval was expected shortly. They are very good at getting academic support. Commercial breakthrough seems much more elusive.
AGL will complete 2 major trials by mid 2018 which should lead to FDA approval later that year. For an update on the company see
https://www.sharesmagazine.co.uk/video/andrew-newland-chief-executive-of-angle-agl.
Thank you very much for the reference to the presentation by Angle (LON:AGL) management. However, and there were unfortunately no follow up questions on the subject, there was no reference as to how the revenue would come in - a licence basis or a licence basis plus royalties or a licence plus royalties and also sales of the patented cassettes. I hope I am making myself clear, because the revenue implications on the choice of the sales system will be huge. Colgate for their razors etc have built huge profitability on the sales of repeat blades. It would be reassuring if the senior management were clearer on how the revenue stream would be based. Thoughts anyone?
Always interested to hear your comments. Why do you think that £AGL's SP is not consistently driving ahead; it is up and down like a yoyo and that is on the basis of what is really a very small investment on a daily basis - may be £100k? I think that it is a grat story; it is fantastic that there may be a very accurate system of non invasive biopsy and seemingly now predictive directional recommendations for specific individual treatments. It is developing a good range of marketing associates, and as someone said recently, the latest - Philips - could buy it with pocket money. Why am I not filling my boots when I feel so positive about it? Its because I have bought 3 times at what I thought was going to be a reasonable price only to see the SP fall sharply, as I say often after only small volume sales. Any further thoughts, because I am poised to make another perhaps emotional into the shares which are currently sitting with me at a significant loss. i feel hurt as much as anything else! anything! I think there is a strong possibility of a takeover, but perhaps the restricted SP is based on the lack of information about how the revenue flow will pan out. Will it be sold on a system basis, or on a licence basis with future - and much more profitable - royalties per use? Do you have any further information on that, or where that information may be sourced. Perhaps a good target interview for Paul to have an interview with the CEO. After all, he has had them with companies with what I feel have far less potential than this one. What do you think Paul? Hopefully yours!
I could have written part of your post myself - I bought in 9/14, 2/15 and 3/15 before I read somewhere you don't buy the initial story but wait until you can see definite progress. FWIW I bought again 2 weeks ago because I feel the potential is now enormous. If you wish to find out the likely sales strategy (I don't know) I'd suggest you e-mail Andrew Newland the CEO. I've contacted him in the past re the FDA approval and received a fairly quick response.