Small Cap Value Report (Thur 6 July 2023) - CTO, RWA, PEEL, AO., CURY

Good morning from Graham and Paul! We are finished for today (11.30am).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Agenda:
Summaries
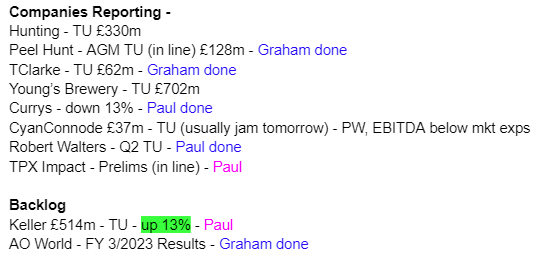
Tclarke (LON:CTO) - down 6% to 133p (£59m) - Trading Statement - Graham - AMBER
I am switching back to neutral here due to a placing that undermines my confidence in the cheapness of these shares. At a PER of less than 7x, printing shares should be a last resort. I have previous quibbles with CTO’s announcements and just can’t remain positive on it now.
Robert Walters (LON:RWA) - down 3% to 417p (£303m) - Q2 Trading Update - Paul - AMBER/GREEN
Reports a worsening revenues trend in Q2, but against tough prior year comps. Nothing said about performance vs full year expectations (which were lowered considerably in a profit warning in June). What’s the betting broker quietly lowers expectations again?! (we don’t have access to broker notes). I discuss the bull & bear points below. Short version - should be fine long-term. Short-term: uncertain.
Peel Hunt (LON:PEEL) - unchanged at 104p (£128m) - AGM Statement - Graham - GREEN
I remain interested in small investment bank shares. A depressed UK equity market, especially in small-caps, has left their enterprise values on the floor. If/when there is a recovery, perhaps valuations can be restored? This IPO’d at 228p two years ago.
AO World (LON:AO.) - up 1% today to 82.5p (£473m) - Final Results - Graham - AMBER
These results are much better than last year's, which isn’t saying much, but the company is now following a sensible, simple strategy and focusing on what it is good at. It’s not a company I’d ever want to own but it’s currently in the strongest position it’s ever been in.
Currys (LON:CURY) - Down 12% to 47p (£533m) - Audited Results FY 4/2023 - Paul - RED
Profit is down, due to a particularly sharp deterioration in the Nordics region. UK is OK. Big pension contributions, buybacks, and generous divis have proven too much, with only modest free cashflow inadequate for these burdens. So the dividend has now been passed. Balance sheet is weak, completely dependent on £2bn trade credit from suppliers. Risk:reward looks awful to me, so it’s a continued thumbs down.
Paul's Section
Robert Walters (LON:RWA)
- 417p (down 3%)
- £303m
Q2 Trading Update - AMBER/GREEN
The Robert Walters Group is a market-leading international specialist professional recruitment group. With over 4,200 staff spanning 31 countries, we deliver specialist recruitment consultancy, staffing, recruitment process outsourcing and managed services across the globe.
Checking our archive here, this is the story so far in 2023 -
16 Jan 2023: FY 12/2022 slightly below exps, tougher trading in Q4. Paul wonders if it might wobble in 2023? GREEN
6 Apr 2023: Solid Q1 . Mixed outlook. GREEN.
14 Jun 2023: Profit warning (significantly lower) for FY 12/2023. AMBER/GREEN.
The recent profit warning on 14th June caused a modest drop in share price, down 14% to 402p, since largely recovered - is share price bottoming out, with cyclical downturn now already in the price, I wonder?
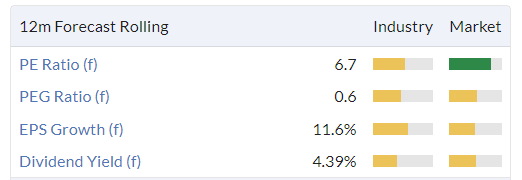
As you can see below, forecasts have been lowered a fair bit. Although remember that once economies return to normal, there’s every chance earnings could recover. So personally I would be pricing the shares on a mixture of the two, to reflect some uncertainty. So it’s currently priced at 11.9x reduced forecast of 35.8p EPS for FY 12/2023, which would drop to 8.5x if earnings subsequently recover to say 50p EPS.
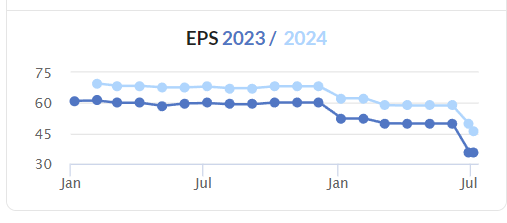
The strong balance sheet means that it still has strong dividend paying capacity, so the forecast yield looks attractive at 5.4%. Not much more than a cash deposit account, you might say. But owning a share gives longer-term inflation protection (with short-term volatility), as the business grows. Whereas cash earning interest below inflation is a depleting asset longer-term, but a safe port in a storm in the shorter term.
Obviously if you’re on Twitter, then you will tell everyone after the event that you switched from cash into equities right at the market low! ;-)
On to today’s Q2 (Apr-Jun 2023) update from RWA, the headline sounds downbeat, so things can’t be good, given that headlines are usually the PR firm’s best idea to put a positive spin on things -
CANDIDATE AND CLIENT CONFIDENCE YET TO SHOW SUSTAINED IMPROVEMENT
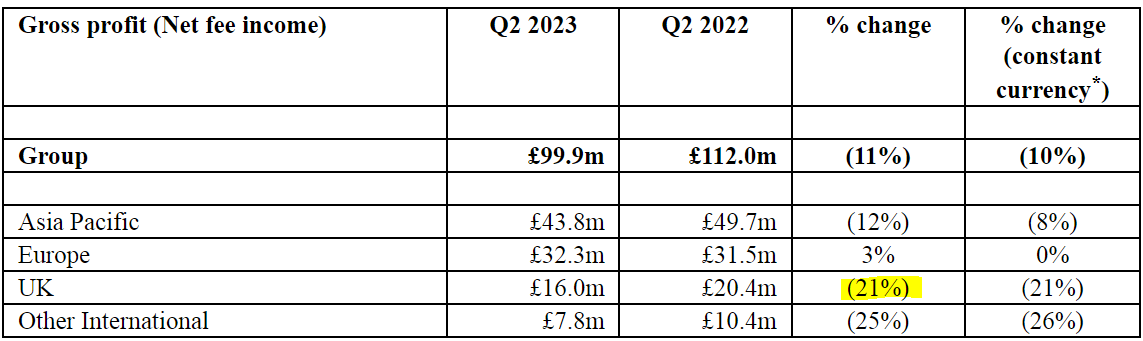
Net fee income of £100m is 10-11% down on Q2 LY
Note the geographic split has wide variations, with Europe doing best, with UK (only 16% of group total NFI) down a hefty 21% -
“Global market uncertainty”
Tough comparatives from a record Q2 in 2022
H1 NFI is down 5%, which implies a worsening trend of flat in Q1, and down 10% in Q2.
Internal headcount reduced 3%, so some cost-cutting there.
Net cash of £70m - balance sheet strength remains a key positive for this share.
UK market comments are of interest for potential read-across to other companies/sectors, assuming this is typical (which it might not necessarily be, as under-performing companies often blame macro factors) -
UK net fee income down 21% to £16.0m (2022: £20.4m).
o Recruitment confidence levels in the UK continued to be impacted by the knock-on macro-economic effects of a high inflation and high interest rate environment.
o Activity levels impacted by lay-offs across the technology sector and financial services volatility. Legal recruitment remained relatively robust.
CEO comments are effectively an outlook section -
"As reported in our June trading update, candidate confidence and time to hire are not yet showing the anticipated signs of sustained improvement. Structural recruitment market fundamentals including job vacancy levels, salary inflation and candidate shortages are still holding strong which continues to suggest that when market confidence recovers there will likely be an increase in demand and candidate movement across all areas of recruitment.
"The Group has a strong and experienced senior management team with a successful track record of navigating challenging macro-economic conditions and balancing short-term pressures with longer term growth. We have invested significantly in Group headcount and global infrastructure over the past two years and while we are taking a sensible approach to cost reduction, we intend to protect our strategic core to ensure we can move quickly to take advantage of opportunities when market confidence returns."
Paul’s opinion - I view this share as fundamentally sound, and probably a good long-term investment, albeit with surprisingly high volatility, as the chart below shows - timing has been everything for investors/traders here - so maybe a share to (try to) buy on the dips, and sell on the surges? Easier said than done of course!
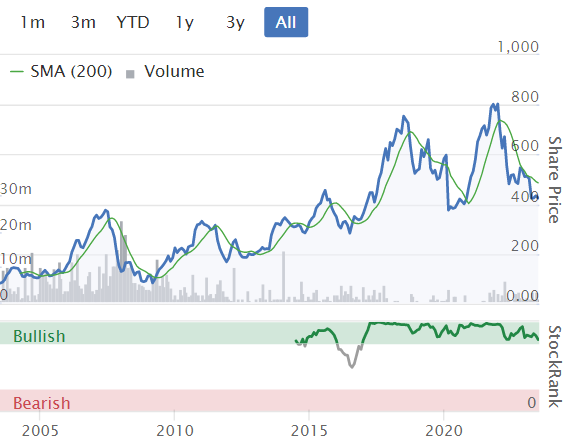
Although long-term holders could just ignore market volatility, and collect in the generous, and impressively growing divis -
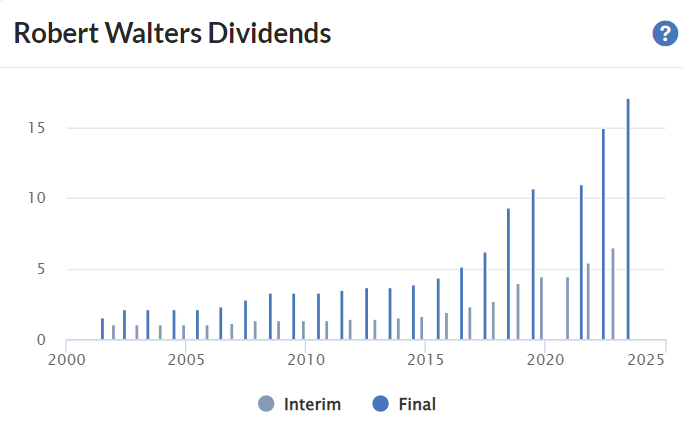
There doesn’t seem to have been any dilution in the last 6 years, with buybacks having more than mopped up share issuance, with the total in issue currently now 73m.
Ownership is the usual institutional names, with the top 5 owning over half, so a takeover bid would be fairly easy to agree, should any overseas operator decide they want to buy RWA, which I would say is a reasonably high probability in current circumstances, where lots of relatively cheap UK listed companies are being snapped up by overseas buyers.
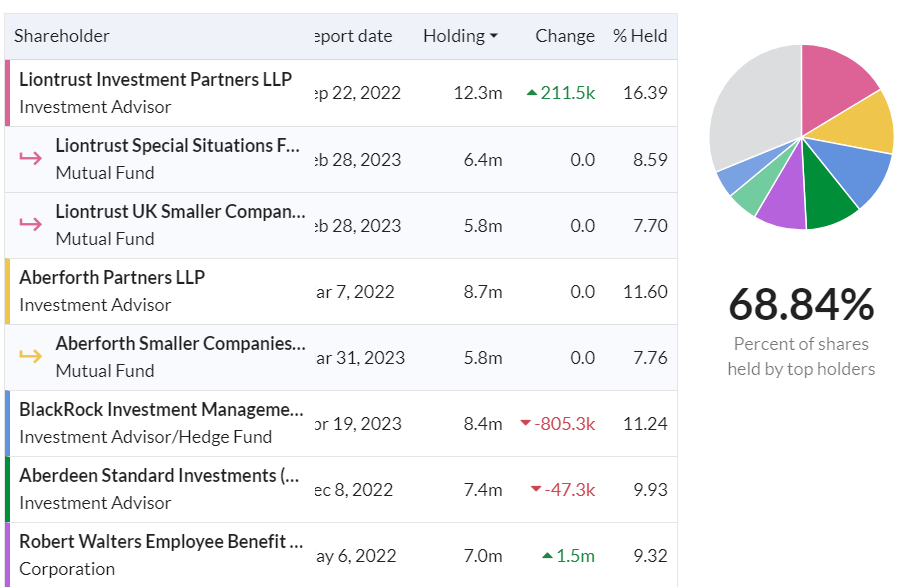
Note the employee benefit trust owns 9.3%, which reminds me that I flagged up the accounting treatment of this in a previous report, as something for investors to check before you buy the shares. I seem to recall the cash outflows for buying up employee shares were going through the cashflow statement, but were not obvious from anywhere else in the accounts. So it looked a bit like semi-hidden staff remuneration to me, but check it out for yourself, I’m just flagging a potential issue.
H1 results are due out on 1 August.
I’ll stick with my AMBER/GREEN view of this share - which means that there are short-term concerns over trading (due to soft macro), but I have confidence in the long-term fundamentals of the shares. Cyclical shares are obviously seeing some softness at the moment, which I generally see as potential buying opportunities longer term, maybe for starter-sized positions? They’ll obviously become more expensive, as signs of recovery appear, that’s what usually happens.
Currys (LON:CURY)
Down 12% to 47p (£533m) - Audited Results FY 4/2023 - Paul - RED
Many thanks to subscriber Mark Carter, and others, who flagged the results from this large electrical retailer today, which didn’t come up on my usual trawl of the RNS, because the RNS title was wrong.
Recapping on our recent previous comments here, to get up to speed -
15 Dec 2022: Profit warning - soft H1 results, FY guidance reduced. Weak balance sheet, huge trade creditors. Divis look unsustainable. RED (Paul).
19 Jan 2023: In line (with reduced forecasts). High risk - weak bal sht, dependent on huge trade creditors, hence the low PER. RED (Paul).
15 May 2023: Ahead of exps TU FY 4/2023. Key bank covenant relaxed. Paul & Roland both sceptical, over bal sht weakness. Cheap for good reasons! AMBER (Roland).
Today’s results for FY 4/2023 have not impressed the market, with shares down 12% mid-morning. A little surprising, as the first headline says -
Group full year profits at top end of guided range
Adj profit before tax (aPBT) £119m, top end of guidance, but down 38% on LY (last year)
UK performing well, adj operating profit up 45%
Nordics is the problem region, adj operating profit down 82% to £26m - taking action to improve performance.
Big goodwill write-off of £511m creates a £450m statutory loss.
Net cash of £44m LY has reversed into net debt of £(97)m - not good, but a business of this size will naturally have large working capital movements happening all the time, so year end snapshots are not necessarily reliable.
Outlook - I think the passing of the divi is probably what has hurt investor confidence today - but not a surprise to SCVR readers, as I flagged divis looking unsustainable in Dec 2022 -

It’s no good just looking at high dividend yields, and assuming they will continue. We also have to assess the dividend paying capacity. If it’s looking financially stretched, then divis are vulnerable, and they’re often cut altogether, rather than being trimmed, at financially distressed companies.
I continue to regard CURY as financially distressed, which is almost by definition the case where bank covenants need to be relaxed, and the balance sheet has a massively negative NTAV, as this does. All very simple things to check.
A special guffaw has to be awarded for the last bullet point above - whoever thought of that should win a PR industry award, here it is again -
“... well positioned if our market forecasts prove to be too prudent”
Classic!
Detailed guidance -
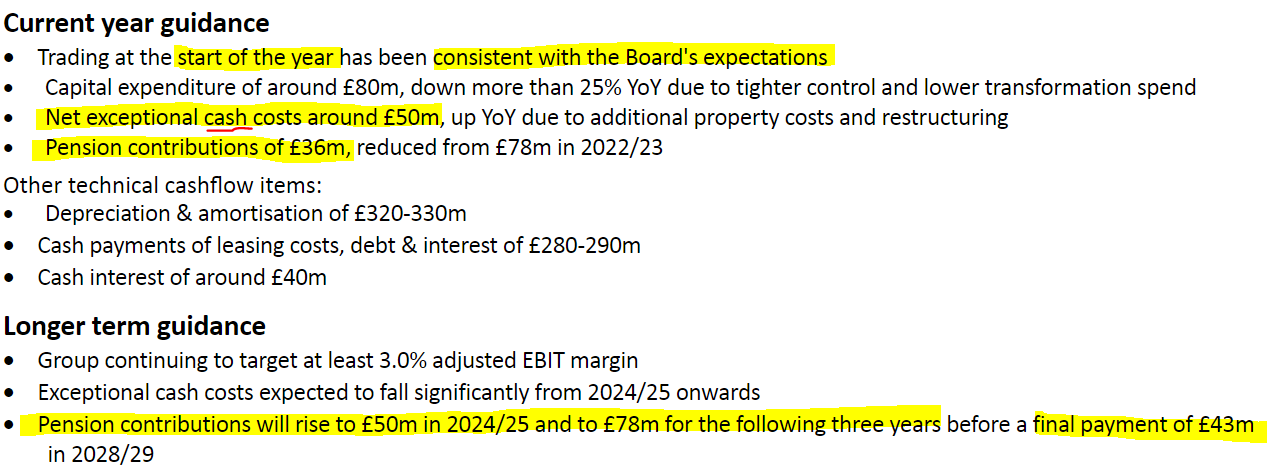
Some real nasties in there. The pension contributions total £363m over the next 6 years, a huge amount. Hence it’s difficult to see what cash, if any, will remain for divis.
Note that free cash flow was £72m, nowhere near enough to cover the combined outflows for divis £46m, buyback £32m, purchases of shares for the employee benefit trust £41m, and pension contributions £78m. That’s why net cash fell by £125m overall. The business is not generating the cash it needs. In fact, the free cashflow was only enough to fund the pension scheme and nothing else.
Balance sheet - is weak. NAV of £1,892m contains intangible assets of £2,620m, giving NTAV negative at £(728)m! Although the lease entries total a deficit of £(238)m (indicating plenty of loss-making stores), so if we eliminate all lease entries, NTAV improves somewhat, but still heavily negative, at £(490)m.
Does this matter? If it can keep all the plates spinning, then negative working capital doesn’t necessarily kill a business. But as I always mention, CURY is completely dependent on £2,067m of funding provided by its trade and other creditors. If the trade credit insurers (who are on the hook for a lot of this) get cold feet, and suppliers insist on cash up-front before delivering goods to CURY, then it’s game over - administration would be the only option, and shares would then be a zero.
Yet, surprisingly, this main risk to the business is not even mentioned in the list of 13 “risks and uncertainties” in today’s announcement.
So just to make everyone aware, if you ignore this precarious financial position, there is a very considerable risk. Why take that risk? Especially when there’s now no income in divis likely for the foreseeable future?
Going concern statement gives itself a clean bill of health, saying it should be able to operate within bank facilities. The severe downside scenario is only a 5% drop in sales, which doesn’t sound that severe to me. The auditors have signed off on this though.
My opinion - I’m happy to put it back to RED, after Roland’s tentative AMBER last time!
It’s fine buying well-financed cyclical companies that are bargains, in tough macro conditions, that’s often when the best investment buys are made. But buying something so obviously financially stretched, in tough macro conditions, seems reckless to me. Why take the risk when you don’t have to?
Institutions are stuck in many shares at the moment, but private investors can just press a button or make a phone call, and we’re out.
At this point in time, I think risk:reward looks very poor for CURY shares. As always though, the facts could change in future, so we’ll keep an open mind for all future updates.
Graham's Section
Tclarke (LON:CTO)
- Share price: 133p (-6%)
- Market cap: £59m
This engineering services company delivers two announcements today: a trading update and a placing announcement.
Firstly, the placing: the company raises £10.7m (gross) at 122p. That’s a 14% discount to last night’s closing price (141.5p).
The reasons given for the fundraise are as follows:
The net proceeds of the Placing will further strengthen the Group's balance sheet and will provide additional resources with which to capture and deliver identified short to medium term attractive contract opportunities in the London region - in doing so driving further growth and margin expansion.
I covered this company in May and also in March, when I noted their average month-end cash of £2.6m.
Now that they have a forward order book that’s pushing £800m, I can see the rationale for boosting the cash position: any significant amount of receivables on that work could push them into significant net debt.
However, it strikes me as less than ideal that a placing was necessary. TClarke has paid out c. £2m in dividends every year for the past five years. They’ve had clearly stated growth ambitions and I suspect could have foreseen that extra cash might be useful to support their growth strategy. But they carried on paying dividends anyway.
The placing will result in the share count growing from 44 million to nearly 53 million and will also involve broker fees that could have been avoided, if the company had used its own cash.
Let’s move on to the trading update:
Trading has continued to be strong, and the Board remains highly confident that the Group will successfully deliver its growth strategy such that the Group's revenues will exceed for the first time £500m in the current financial year, in doing so achieving the three-year revenue growth strategy set out by the Board in March 2021.
The order book continues to grow and has reached £781m.
Broker estimates are adjusted as the placing proceeds will help to support TClarke’s work on data centres, which has expanded at a blistering pace in recent years. According to Cenkos, the placing will support a “step change” in the growth of the business.
The net income forecast for next year (FY December 2024) increases from £10.5m to £12.8m, but the increased share count results in only a marginal increase to the EPS forecasts.
Graham’s view
I previously had quibbles with this company when it issued trading updates which sounded positive, but where the broker notes included profit downgrades.
Today, my quibble is different: the company is proposing to increase its share count by 20% to raise funds it would already have, if it wasn’t a dividend payer!
I’m sure there are many shareholders who don’t mind this sort of arrangement, but it always strikes me as wasteful (at best) or misleading (at worst). Why give to shareholders on the one hand, and take from them on the other?
20% dilution is material, whatever way you look at it. I can understand occasionally writing off dilution of 5-10% as being unimportant in the grand scheme of things, but 20% is another matter.
I also note that the EPS forecasts are barely changed, so it’s not clear that the placing will ultimately improve the position of shareholders very much at all.
In May, I “tentatively and cautiously” gave this stock the green light, against my better instincts, because of its growth prospects, cheap valuation, and cash on the balance sheet.
In light of today’s news, I’m going to switch back to neutral. Because if the company is willing to dilute shareholders at this cheap valuation, then maybe it’s not so cheap after all.
Peel Hunt (LON:PEEL)
- Share price: 104p (unch.)
- Market cap: £128m
Just a quick comment on a short AGM update from Peel Hunt. Performance for Q1 (April-June) is in line with expectations, with a second-half weighting expected.
...the macro-economic backdrop has continued to be challenging and investor sentiment has remained low. However, during the first quarter of FY24, we have supported our corporate clients in relation to a number of announced M&A and ECM transactions. This has included acting as named financial adviser on approximately a quarter of firm offers made for UK listed companies during the period, and as a bookrunner on the largest UK IPO so far this year.
Graham’s view
I was just looking at Paul’s comments from a few weeks ago, when he concluded with an “Amber/Green” view.
I remain intrigued by this sector; its most recent full-year results saw Peel Hunt report net assets of £93m, almost entirely tangible and very liquid. As Paul noted, net current assets were £100m.
In the end, consolidation might be the best way to crystallise value for shareholders of these companies. Remember that finnCap and Cenkos are planning to merge, and Numis is in the process of being acquired by Deutsche Bank. Peel Hunt is a recent entrant to the stock market and I would be surprised if it stayed here long-term in its current form, at this sort of valuation.
AO World (LON:AO.)
- Share price: 82.4p (+1%)
- Market cap: £473m
This electrical retailer published full-year results yesterday.
I was previously a bear on this stock, but I changed my tune last November (with a follow-up comment in January), after they changed their loss-making growth strategy and decided to start making some money! Paul has also covered it, most recently in June.
Let’s briefly review how they did in FY March 2023:
Revenue down 17% to £1.1 billion (good!)
Operating profit £13m (previous year: they made a loss)
Net funds: £4m (they eliminated their net debt by raising over £40m of fresh equity).
Their new strategy has been to “rationalise, simplify and refocus our operations”.
Cash headroom: £80m RCF provides plenty of liquidity.
Market share: 16% of domestic appliances, 30% of online.
Their latest net promoter score is 85. That is marginally lower than last year’s 86, but I don’t think that shareholders will mind. If the cost of getting a slightly higher NPS is that the company is unprofitable, I think the company should accept a lower NPS!
Outlook
Looking forward to FY24 we are confident in our ability to deliver on our 5% EBITDA ambition in the short term and returning to top line growth in the medium term. Our strategy now is to invest prudently in the business, seize the significant market opportunities that we see in front of us, leveraging our growing and loyal customer base.
A 5% EBITDA margin is nothing to write home about, but it’s a start. It’s hard to believe it but this strategy is much, much better than what AO was doing before.
CEO comment from the founder uses his distinctive terminology; the staff are “AOers” (although there are fewer of them now) and the company does things “the AO Way”. They treat customers “like our grans”.
Here is a revenue breakdown:
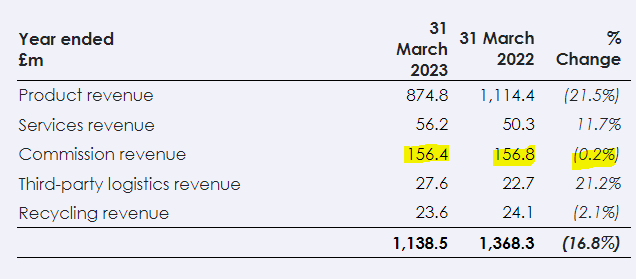
“Commission revenue” relates to network connections in the mobile phone business, and warranty sales in the appliance business. The company doesn’t publish a segmental breakdown of profits but I agree with Paul that a significant chunk of AO’s gross profits must come from this source, rather than from product revenue.
It is noteworthy that commission revenue didn’t fall, despite the general decline in revenues. This is due to higher rates paid to AO on an increasing number of mobile phone connections.
Warranties are mentioned a few times in the report, e.g.:
Our Financial Services business performed resiliently as our customers continue to recognise the value and peace of mind that our warranties offer. Our long-term successful partnership with Domestic & General (AO Care) and NewDay (AO Finance) helped us ensure high customer service levels, and we continue to work closely with both partners to enhance our customer proposition.
There has been no material impact to warranty cancellation rates as a result of the underlying macroeconomic conditions.
The cancellation rate is important as AO World carries receivables on its balance sheet from Domestic & General. The ultimate value of these receivables depends on warranty cancellation rates.
Here is the sensitivity of the value of AO’s receivables to changing warranty cancellation rates:
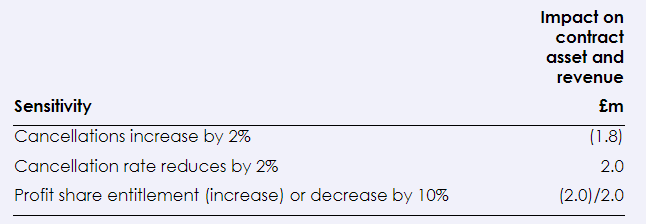
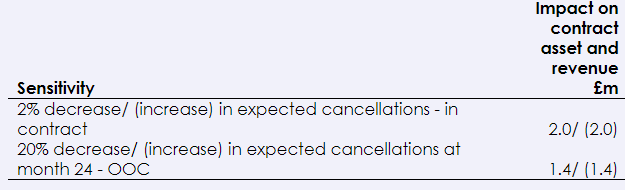
And here is the sensitivity to cancellation rates in the mobile phone business. The second line tells us that there is very little sensitivity to cancellation rates when the customer is out of contract (“OOC”).
Graham’s view
I’m going to stay neutral on this share. The quality of the business is clearly questionable but at the same time, they have fixed their balance sheet by eliminating net debt and they are now scraping a small profit.
The risks associated with warranty and mobile phone cancellation rates are real but have been quantified by the company. In circumstances that saw major changes in these rates, or in mis-selling claims, I don’t think AO World would be the only company to suffer. And I don’t have any particular view on how likely those circumstances are to arise - not very likely, perhaps? So I’m not inclined to criticise the company too much for having this exposure (of course it would be even better if they didn’t have this exposure!).
In summary - I wouldn’t want to own this, but I also wouldn’t dream of shorting it. So I’m neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
Robert Walters - In reply to Paul's analysis
Ownership is the usual institutional names, with the top 5 owning over half, so a takeover bid would be fairly easy to agree, should any overseas operator decide they want to buy RWA, which I would say is a reasonably high probability in current circumstances, where lots of relatively cheap UK listed companies are being snapped up by overseas buyers.
I wouldn't complain were this to transpire in the short term but I don't consider it particularly likely. The only recruiters large enough to swallow GBP 300m worth of counterpart/competitor are the big general staffing agencies like Hays, Adecco or Randstad. But their valuations are almost as low making it hard to achieve an accretive boost to earnings. And the days of Adecco buying Computer People seem to be long gone. It's much less risky to repeatedly pay 5x EBITDA for £10m worth of niche operator and slowly bring a small-ish workforce into the fold culturally, than it is to attempt to assimilate a company a fifth of your own size, especially one with strong culture and more successful consultants than your own!
Still, never say never. US-listed Robert Half would be a suitable acquirer and its valuation is, well, US-flavoured.
XP Factory (LON:XPF) announced on Lindedin they are opening up a site in Dubai next week!!!! H2 should be a good catalyst for the stock (hopefully!)
Just checking for any interesting companies rising, especially on volume, on a big down day. Slim pickings.
So far Hunting (LON:HTG) x 2 average volume. up 22%
XLMedia (LON:XLM) up 8% above av. volume last few days
Totally (LON:TLY) up 3%. 3x volume. Results Monday
Tekmar (LON:TGP) up 11%. 2x vol.
CentralNic (LON:CNIC) Flat. 10x vol.
Keller (LON:KLR) Flat. 4.5x vol.
Thanks Wolf of Small Street, we hold three of those.
Aim can't keep this up forever surely
Who knows where the bottom is? Dreadful chart anyway.
If US ever goes into a proper bear market (not had one for 15 years, but must be overdue given current valuations) then suspect AIM could go a lot lower...
That's the concern, isn't it? If US drops, so will we.
Everything seems to be going down, so many alerts going off, not just small caps, plenty of large caps also. Sell in May, maybe right again.
Yep, FTSE 100 below support at 7340. Very difficult market, even short targets have rallied. Some decent buying opps, maybe?
Maybe, I have been picking a few up, but probably too early.
"Gary Neville says interest rates are becoming a ‘big problem’ and causing construction projects to slow down"
Am I living in Narnia?
I've been saying that the classic 4-4-2 formation isn't really effective in the modern game for quite a while now.
40% stocks - 40% Bonds - 20% Scratch Cards?
Scratchies are my best winners at the mo.
Costco sells everything that Currys sell but much better price and excellent service.
It looks after the employees well. The share price has done well and share holders have benefited too.
Activeops (LON:AOM) FY23 analyst presentation. ARR +13% £22.6m GM 82% (22: 81%) Moved to positive EBITDA £0.7m which was ahead of expectations reflecting op leverage & fx gains. Cash and cash equivalents £15.4m (22: 13.8m). Outlook inline. Video & podcast.
Today at 1pm, Tpximpact Holdings (LON:TPX) FY23 online presentation by new management. Register here. The FY23 statement says these results are in line. The outlook for FY24 remains unchanged with like-for-like revenue +15-20% with an aEBITDA margins 5-6%.
Tomorrow at 1pm, Wynnstay (LON:WYN) H123 online results presentation. Register here.
Revenue £409.14m +22% Underlying PTP £5.25m EPS 17.2p
ShoreCap forecast FY23: Rev £729.1m adj PTP £10.7m aEPS 36.6p
Gives a PE 12.9x and divi yield 3.8%.
May fund retail sales data. Pretty much as expected, youd expect June to be poor also. Can see plenty of shares where the market makers look like they're walking the price down to fill sell orders.
https://www.theia.org/industry...
Retail sales
Retail sales by asset
Robert Walters (LON:RWA)
Regarding Paul's comment on the Employee Share Trust purchasing shares. I don't know if the management has issued options to staff, but if they have it is not unusual to use such a trust to buy in shares to minimise diluting shareholders by having available shares to provide for when/if the options are exercised. The options issue itself is recorded as effective remuneration in the p/l already. Depending on whether they are approved or unapproved options, they may have pay tax on exercise.
However, if the trust is buying in more shares than they have options, Paul makes a fair point that this is arguably additional remuneration, though legally employees they don't have any entitlement to that money at an an individual level.
The Company in effect loans the money to the Trust to purchase shares, so to the extent the Trust makes a loss on exercising the shares the Company may have to write down that element of the loan through the p&l, but that may not be reckoned up until all options are exercised and all shares are sold?
That's my non-accountant understanding, but I am sure someone will correct me. It all a bit messy.
Companies gift funds to Employee Benefit Trusts, not loan them. It's a one-way valve. The trust then buys shares in the market. They do this to hedge the share price. Regardless of the value of the shares when the employee receives them years later, the cash cost (and therefore, I'd argue) the true cost to the company is the cost of the shares at purchase.
True, if the price of the shares goes down, the company loses out on the hedge but there are no write-downs.
Share options that are funded by creating shares are a very different mechanism.
It might be worth discussing Currys (LON:CURY) from the macro/retail perspective.
Thanks Mark, well flagged - I see Currys (LON:CURY) is down 13% to 46.5p.
I've got big concerns about its financial stability, given that the weak balance sheet is totally reliant on massive trade credit from suppliers.
I'll check it out now.
I bought some Currys (LON:CURY) a few years ago, and did OK out of them. I sold when I realised that their best days were long since gone. Like a dinosaur stuck in a tarpit, their destiny is a slow pitiful death. Interestingly, 3i (LON:III) owns a large stake in a retailer called Action, which operates throughout Europe. It keeps going from strength to strength. Investing is a funny old game sometimes.
Well you certainly win today's prize for colourful language! "Like a dinosaur stuck in a tarpit, their destiny is a slow pitiful death." Great stuff!
Thank you. And the good news is that I have plenty more where that came from
Tweaking to takeover targets .
Was listening to the posh bloke Christopher Mills who I consider super savvy and talks pretty openly and more importantly is putting his own cash on the line as well as his clients .
His very valid point and one that is making me rebalance my positions is that clearly there are now some exceptionally cheap and undervalued companies the market is simply not functioning and not valuing these companies at a credible valuation .
It is now cheaper for a private equity to buy off the market or thus bids are coming through quite quickly buying the best stuff .
I’ve had Crestchic and Sureserve which Mills was in .
Mills is also fairly activist and I believe where they hold a big position they will be actively both pushing the board as well as actively finding the motivated buyers with cash to spare .
So I think repositioning a portfolio with more weighting toward the businesses that are going to be no brainer bid targets (eg Vertu) is a smart play .
I was checking my portfolio this morning, think I have Vertu and Sanderson as the two most likely and if I apply the “if I had 200 million quid would I buy it outright “ rule wonder what else comes up .
Going to make a hotlist today of great companies that are sitting ducks for private equity , starting with my current holdings
I’m also going to reduce a touch (25%) on my current positions that have zero chance of being bought even if they are good companies / strong holds .
I was checking my portfolio this morning, think I have Vertu and Sanderson as the two most likely and if I apply the “if I had 200 million quid would I buy it outright “ rule wonder what else comes up .
I can say with some confidence that if you had £200m (I don’t btw) you’d have a much more diversified portfolio!!
I do agree with your reasoning on looking out for bid targets - I’ve had Dechra Pharmaceuticals (LON:DPH) and Network International Holdings (LON:NETW) along with failed bids for the likes of GB (LON:GBG) which gave me good wins.
I’m interested why you would say this ?
“I can say with some confidence that if you had £200m (I don’t btw) you’d have a much more diversified portfolio!! “
I’d probably by definition be in some larger companies but not necessarily more .
I would always prefer to run a very tight portfolio, if it’s too many just dilutes and you simply start to follow the market and also as my brain has limited capacity I personally find anything above 10-20 is too many .
I run 8 full positions , and. 8. 30% positions and always have about 4. Starter positions plus 10 on a watch list
That’s 30 companies to follow which id quite a lot ??
I’m interested why you would say this ?
“I can say with some confidence that if you had £200m (I don’t btw) you’d have a much more diversified portfolio!! “
Obviously I don’t have a clear idea of your circumstances or risk tolerance. But my hunch is that, unless you were born with £200m, then having £10m in just one company, over which you have no control and no special insight, even if repeated 20 times, would feel like way too much exposure to idiosyncratic risk and management frailty. You would also find it next to impossible to invest in UK small caps at those volumes, so any information advantage you might gain by your research would be lost.
Things could get so bad you might even buy a tracker and some bonds to go with your individual exposures. I own neither, being extremely tolerant of risk. But I don’t have anything like £200m and yet have already run up against the psychological and capacity constraints mentioned above. I fully acknowledge your experience could be different.
Just for laughs I’ll play the 200 million debate out
Hypothetically if I had 200 million I would probably have the following
- 60 million in forestry / wind (30%)
- 40 million in Aim shares (20 % , 8 shares) with activist approach
- 20 million in business angel hands on entreiebeur support
- 10 million in cash
- I’d give 30 million to charity
- I’d give 20 million to you so your on your way to that 200 million
Actually having dibs the above it’sjust too much money don’t think I’d want that headache .
Actually having dibs the above it’sjust too much money don’t think I’d want that headache .
Wise words. And thanks for the bung. Just £180m to go now
No wine, women and song ?
No wine, women and song ?
Perhaps that would have been the £20m he’s giving me. So I’ll make sure to spend it appropriately.
Reality is that stupendously rich people have much more boring lives than the merely comfortably off. Who’d want to only spend time with other stupendously rich people? Give me a messy music festival over an exclusive hotel any day of the week. Well, six out of seven. A shower would be nice.
Morning planetX
I have a lot of time for Christopher Mills and his contemporaries at Harwood, Richard Staveley and Stuart Widdowson. I hold several shares that feature in their portfolios, Flowtech Fluidpower (LON:FLO) Elementis (LON:ELM) and M&C Saatchi (LON:SAA) to name some. I also hold Vertu Motors (LON:VTU) .
Elementis (LON:ELM) and M&C Saatchi (LON:SAA) have been subject to fairly recent unsuccessful bids, the former at 160p and latter at 207p (Vin Murria) and 247p (Next 15 cash and shares). The share register of Flowtech Fluidpower (LON:FLO) is a veritable who's who of savvy small cap investors, Harwood, Rockwood, Odyssean, and Downing, which I admit piqued my interest and prompted the purchase.
All are potential bid candidates, however I bought them on the basis of their investment metrics, they are all cheap and financially stable with operational upside and in the case of Flowtech Fluidpower (LON:FLO) and M&C Saatchi (LON:SAA) new management. They may of course get cheaper given the current market malaise. The bid potential to my mind is the possible cherry on the cake.
Anyway I digress I would be interested to know where you recently listened to Chris Mills. He did an interview with Paul Hill on Vox Markets on 6 June or is there something more recent?
Finally the presentation by Richard Staveley yesterday on Investor meet company is worth a listen.
All the best
Jonno
Think it might have been the Vox market interview .
I’m not a huge fan of Flowtech as it just seems to be a good distributor of third party brands which is not a business model I like even though looks a good company .
I spoke to Richard Staveley a few weeks ago at length about a company where Rockwood are building a game changing stake that I have a big holding in and he is impressive in getting down and dirty in quite complicated situations to unlock the hidden value on companies that at first glance are basket cases . Often knowing it’s 3-5 year turnaround with a lot of pushing / prodding that is needed and that’s an impressive skillset to have built .
Hi planetX
I completely agree regarding Richard Staveley and suspect that you are referring to Titon Holdings (LON:TON) . I haven't looked at the company and at present I am fully invested, having recently added to several existing holdings on weakness including Jet2 (LON:JET2) this morning.
Regarding Flowtech Fluidpower (LON:FLO) I have to an extent followed the money, but despite this, given the change of CEO and current financial metrics it continues to look a good medium term investment.
Not sure if you still hold Avingtrans (LON:AVG) but I expect a trading statement soon, perhaps tomorrow.
All the best
Yes still hold Avingtrans that’s a core holding . Strong hold no reason to sell and seems pretty recession proof .
Downing Strategic Micro-Cap Investment Trust (LON:DSM) will hold its AGM later this morning. Its second largest equity position has been Flowtech Fluidpower (LON:FLO) I agree that fund manager always appears quite savvy but the performance of the Investment Trust since inception (May 2017) has been very poor - with NAV (including dividends) down 20% over those 6 years. DSM have said that they will offer shareholders a 50% cash exit in May 2024. Does this mean that its holdings (like Flowtech) have an overhang over them - or are more likely to receive a bid?
Hi Wimbledonsprinter
I think you'll find that Downing Strategic Micro-Cap Investment Trust (LON:DSM) have quite a bit of cash, so Judith Mackenzie doesn't anticipate being a forced seller. I suggest watching her VOX interview with Paul Hill of 28 October last year, and looking through the recent prelims. As for the share price, yes it hasn't been great recently but again I think that you will find that it has outperformed its peer group, the likes of the much racier Blackrock small cap funds.
The poor performance of most small cap funds is to be expected given the hammering UK small and mid cap shares have taken over the last year or so.
The tide will turn at some point, patience is required but it is in bear markets that one lays the foundation for future profits.
Regarding Flowtech Fluidpower (LON:FLO) Mike England who was Chief Operating Officer at RS (LON:RS1) formerly known as Electrocomponents has just taken up the CEO position. RS (LON:RS1) has grown significantly in recent years. Its current market cap is £3.5 billion, although like most UK shares it has de-rated of late. It is an international distribution business, originally of electrical components. so Mike England's background and expertise in distribution fits very well with Flowtech Fluidpower (LON:FLO) .
Finally as a value style investor I would also mention Watkin Jones (LON:WJG) that I bought after the recent profit warnings. Gresham House recently took a 6.5% holding. Again despite all the challenges I just think it is too cheap, along with shares like PayPoint (LON:PAY) that I also bought sub £4. I could of course be wrong, time will tell.
There are many investment styles and mine is unlikely to find favour with many but it suits my temperament . To quote Howard Marks, its is not what you buy but what you pay that ultimately counts
All the best.
Interesting, thanks planetx.
One thing I've noticed is that takeover bids often come for structural growth companies, which seems to be what the private equity people are looking for, and not necessarily cheapness.
Bids for cheap companies seem to most usually come from trade, and/or overseas buyers.
I don't have any data to support that view, it's more my general impression, so could be wrong.
Regards, Paul.
Paul
Sorry I should have included trade and overseas .
A good company is a good company and if it’s perceived to be undervalued by a buyer can consolidate and improve those are also reasons to buy .
When I was looking to “exit” my last business KPMG were handling and at that time there was a huge influx of US money into the UK simply because the exchange rate was so favourable to US buyers that they perceived UK as the place to buy and deals were being done by seemingly random buyers who had just been told to go buy UK assets they actually knew little about, that was at the height of a frothy bull run with easy money being thrown around so different now .
Crestchic was a great purchase for Aggreko and that deal was great for them and ok for shareholders .
So yes I agree trade buyers are key players in the arena sorry I missed that out .
Persimmon under £10 and Taylor Wimpey under£1.
In five years time both are still in business.
If times get tougher they stop paying dividends but don’t need to raise cash.
Jet2 (LON:JET2) Market reaction seems daft to me. Having skim read the results I don't see any particular concerns. There are the unsurprising caveats relating to the uncertain economic outlook, also Phillip Meeson is stepping down, but his management team have effectively run the company of late with Mr Meeson very much in the background. Also he still owns 18% of the company or thereabouts.
Jet2 (LON:JET2) has in excess of £1 billion of its own cash, which is 30%ish of its market cap and was ahead of the game in procuring new aircraft. I hold and will continue to do so. It is a well managed company
Yes. I agree (and hold). I read the report this morning and was astounded to see the share price drop. I've added a small spread on it this morning in the expectation that it will return to yesterday's price within a few days/ weeks once this morning's results have been digested.
I used them only last week for a brief stay in Spain and I cannot fault them on their service at every stage of our engagement with them. Compared to other holiday websites, the booking process is clear, and speaking to an agent is never a problem. We had to make a change to the booking and we received calls every 48 hours until it had been resolved. Very impressive.
Another bizarre reaction on the UK market - similar to what happened yesterday with Redde Northgate (LON:REDD) - really not going to encourage companies to list here if this sort of thing continues. Seems to be due to a marginal fall in load factors versus last year, plus the executive chair leaving. Still a 12% drop on strong results and dirt cheap valuation looks a bit overdone!
The only thought I had, as my office is right in Redde Northgate (LON:REDD) central in Darlington, I probably should walk next door to the VanMonster site and see what the cars and vans are selling at for a survey of one.
There are obviously debates on values of the existing fleet and the direction of those over the coming months and years, having been a big peak in the last couple of years due to the lack of supply meaning they could negotiate a deal for what came onto the market and get rid of the old fleet as a premium to the rest of the market. Think what happens when Wincanton (LON:WIN) go to buy some new wagons for the next 5 years. Redde Northgate (LON:REDD) will be actively doing the same and are one of the biggest buyers in their market.
The other question is the longer term direction of the fleet, which is a mass of complex calculations on payload size/weight and delivery distance, versus overall £/km, versus longer term demand, versus short term hires, versus emission zones and all that is way beyond my ability with Excel!
But looking at the company I work for, yes we are going electric (very slowly) because we need payload (heavy and/or large) and longer distance. So we are looking at the inner city fleet (think London, Manchester, Glasgow) as options for electric with smaller vans and cars, as well as site plant. The rural projects (think waste water treatment plant somewhere in the north of Scotland) as diesel. The other challenge is obviously a lot of construction sites are not set up with charging points, yes we have power, but it is needed for the tower cranes. and many of these are run off generators as there is not enough capacity in the grid until the facility is completed and the supplier has upgraded their network to give the permanent building electric.
I can think of my last but one site and the challenges there to put two charging points for a site offices for 100+ people there for 5 years, and then statements from the supplier of there is not capacity unless you pay to upgrade the local substation.
There is also what are people factoring in for the post "Covid Delivery Van-itis" boom. Where everyone on my street seemed to be getting a parcel every five minutes and now you hardly even see the post person. Assuming these came from somewhere and probably are slowly going back as Amazon scale back on there £/delivery drivers.
Sorry not over analytical but food for thought.
Tommy
Ps. I hold Redde Northgate (LON:REDD)
Pps. Another Ouch of a Day
re Jet2 (LON:JET2) I fell for the chart, and an easily anticipated upbeat trading statement and went for a quick plunge ... instead getting exec ch exit and a 10% fall ouch! .... that's mkts, but this one should be fine IMO
( note to self - plunging into results ! please stop this )
I did exactly the same, if it's any consolation!
Jet2 (LON:JET2) - I don’t hold but observation from recent holiday - the jet2 check in counters were rammed with massive queues on both outbound and return flights, a noticeable difference from any other operator. Also my experience of them from several holidays has always been pretty faultless, all things being equal they would be my first choice for any package holiday.
I've just travelled to and from Croatia with Jet2 (LON:JET2) and previously Madeira and found them a class act when compared to Tui, Wizz, Easyjet, Ryanair etc - so much so that I bought their (Jet2's) shares last week .... In fact I now wouldn't travel with any of the aforementioned if Jet2 are an alternative. The Jet2 staff actually appear to give a sh*t, the flights are on time & seldom seem to be cancelled.
Probably the combination of these two outlook statements causing Jet2 (LON:JET2) plunge today:
"we are cognisant of how quickly the macro-economic environment is evolving and how this may affect consumers' future spending"
"On that basis, and with the peak summer months of July, August and September not yet complete plus the majority of Winter 2023/2024 seat capacity still to sell, it remains premature as is always the case at this time of year, to provide definitive guidance as to Group profitability for the financial year ending 31 March 2024"
--------
Reading between the lines, there's a strong worry/bias that consumer confidence is going to plummet very soon, and with the key Jul-Sep sales not all yet in the bag yet, this is a key concern.
They also have not given an indication of the amount of forward sales to date for Jul, Aug, Sep. Compared to last year. Is the forward sales doing better or worse? How much of key summer months is already locked in and in the bag?
And the summer season load factors (presume they mean June here) is lower YoY by 0.8pp. So not a great start. Especially if consumer confidence "quickly" changes.
-----------
I also note that FY24 EPS forecasts have risen steadily over the last few months on bullish analysts. Now expected +15% EPS YoY. Maybe the market thinks this is going to be trimmed now, given the outlook macro statement. Combined with continued bearish news on UK interest rates today.
-----------
Curiously, On Beach group (LON:OTB) slightly rising today, despite being in package holidays, like Jet2. Maybe rising because Jet2 stated that there is brisk growth in package holiday bums on seats. Some of which will be sold by third parties like OTB.
(I hold OTB in the Boon Fund)
Boon - In your Boon Fund blog you have been pretty consistent about there being a bumper summer season this year - do you still feel like that or are you, beginning to wonder if the early rush might slow down in the late summer? That's one way to read the Jet2 (LON:JET2) statement.
The UK Visitor Attraction which my wife and I built and still own a big stake is definitely seeing a slowdown.
My forward view for the rest of the summer is that travel demand is still very strong for USA and EU destinations. However, there seems to be some uncertainty on Autumn and Winter bookings. Consumer behaviour is changing. At the start of this year, there was a lot of "booking ahead", more than usual. That has reduced.
However, specifically looking at within the UK... specifically for domestic travelers.... my view is that there is softness.
I hold Jet2 (LON:JET2) and was tempted to double-up (went for Foresight Solar Fund (LON:FSFL) instead) and holding off as I am thinking that the cash the Chancellor wants to be spent within the UK economy is leaking out the sides through the desire to get away from it all. Hoping my balancing act stays vertical and in the right direction
Paul, I know you’re about to cover Robert Walters, but I don’t see much in this update that wasn’t already advised in the profit warning of last month. Demand for staff at the operational level remains high, but business confidence is low, leading to constraints on hiring activity. This is a potential stretched elastic band that will rebound very rapidly in the event of a return of confidence. On the other hand, a protracted downturn would delay that moment for another six months to a year and pull the shares down another leg. I don’t think there are any clues in the update as to what will happen. It’s simply a macro call and potential investors need to decide whether today’s valuation is attractive enough relative to the company’s fair value in more benign circumstances.
I started a position in the high 400s, I have been buying recently - which is a sure sign things will get worse - and I will buy more on another material fall, but I’m comfortable in the medium to long term.
On a fairly quiet day, may I be forgiven an off-topic question?
Over the next few years, interest rates smay fall significantly. When gilt yields fall their price rises. Is anyone here positioning their portfolio in anticipation of gilt/bond capital gains? If so, what products are you using and what durations do you expect to gain most?
Over the next few years, interest rates smay fall significantly. When gilt yields fall their price rises. Is anyone here positioning their portfolio in anticipation of gilt/bond capital gains? If so, what products are you using and what durations do you expect to gain most?
I have been buying gilts recently across the spectrum- from 2 years to 27, via 4, 8 and 12. I buy them directly, via HL for family members and e-trading in my wife’s case. I’ve bought the lowest coupon bonds to eliminate income tax exposure and focus on capital gains. I would hope that the longer duration bonds deliver good gains but the exposure to short durations is an expression of my caution that rates could rise yet higher in the short term.
Is there a website for retail investors to research and get data on gilts? I was browsing the other day, wondering about parking some cash in say a 2 year gilt. But (unlike shares) its hard to know where to look and research.
I've recently bought into CQS New City High Yield Bond Fund CQS New City High Yield Fund (LON:NCYF) which is one I liked the look of and is currently offering a 9% yield. Their website is quite good and provides a monthly fact-sheet.
I owned CQS for a while and was puzzled as to why it was not doing better. I asked for their full spreadsheet of all their investments and they kindly sent it to me. I was very disappointed when I studied this. Some of the bonds they have bought in recent times have gone to zero - far more than I would have expected from a professional bond investor. I sold on 05/04/23 at 48.3p - I would have done better to hold for another week but I wouldn't buy again except for a trade.
Also of the view that rates will start to fall as the economy slows and inflation comes down. Bonds looks very attractive at current yields - not only do they offer an attractive yield they also offer a lot of capital upside if yields come down. On top of that they offer a nice hedge - if there is a wider stock market crash I'd expect bonds to do very well.
The longer dated the bond, the more sensitive to yields - so if you want to maximise upside go for long duration bonds (although the flipside is they will fall the most if yields continue to rise).
I personally just use ETFs (ishares) for bond exposure - they have ETFs in pretty much every category (different regions and maturities, governments and corporates). One thing I would avoid is high yield/junk bonds - not necessarily bad, but they behave more like equities so won't give you that hedge.
I personally just use ETFs (ishares) for bond exposure
I’ve found it very difficult to get a definitive answer on this, but my understanding is that you only benefit from the exemption from CGT on Gilts when you own them directly. Very happy to be corrected on this.
I think you might be right on that, bond ETFs probably will be subject to capital gains - I hold nearly everything in an ISA or SIPP so not such an issue for me.
For long duration bonds, I hold SPDR Bloomberg 15+ Year Gilt UCITS ETF Dist (LON:GLTL). I'd prefer an accumulating one rather than distributing but I haven't found it.
Will interest rates fall? When will they fall?/ If only I had a Tardis I could comment on that one.
My take on regular income plus the possibility of good capital gains is high coupon cumulative irredeemable preference shares from stable reliable companies. At today's offer prices these will give you a 7%+ yield. And if / when interest rates fall capital gains should be decent too. General Accident (LON:GACA) e.g. was trading above 160p (mid price) in August 2021. The current offer price is 114p. I don't invest in banks (too much that we don't know) so avoid the bank prefs. The ones I hold (not recommendations, just for your info. are) General Accident (LON:GACA) GACA, General Accident (LON:GACB), Aviva (LON:AV.A), Northern Electric (LON:NTEA). Ecclesiastical Insurance Office (LON:ELLA) might be another good option and there are others on the market. Of course we still have to think about the safety of the issuing company. If Aviva went under the Aviva and General Accident prefs would be at risk. And of course capital gains will only materialise if / when interest rates start to fall
Anyone have thoughts on Jet2 (LON:JET2)? I thought the results seemed fine, but then i thought the same about Redde Northgate (LON:REDD) yesterday, so clearly in no good at this game!
Didn't see this one coming either. Was expecting lift off this morning and instead crash and burn. News of Meeson stepping down is the only conclusion I can come too.
Exactly like Carnival last week.
Shares dropped by 12% on the day for it to climb up 25% over the following days.
Don't beat yourself up, spit happens.
I guess I'll add that sometimes the market is in a punishing mood. Sometimes Mr. Market is in an unforgiving mood, and less than perfect results are punished. Mr. Market seems to be in a foul mood at the moment, where even reasonable results are punished.
The UK markets have plunged quite a bit recently. Down 2% today, which doesn't happen often. I just wonder whether a lot of it is down to technical factors of some sort. Liquidity drying up, perhaps? I'd be interested in others' thoughts.
It's been a trying year. Since April we've been getting lower highs and lower lows. Which is pretty bearish. We're at a low point for the year. A quick rebound is possible, though. For context, though, The All-Share was at around 2727 in March 2020. That was pretty bleak, mind, at it was inevitable that such a rapid drop would be followed by a rebound.
Who knows where the end will be, though?
Interesting reaction to Jet2 (LON:JET2) results this morning. Looked like a small beat to me but the market potentially focussing on Philip Meeson stepping down and the non provision of forward guidance (which isn't necessarily unusual looking back)
The ex own cash PER looks pretty compelling- have they ever been in such rude health, trading on such a low rating in their entire history ?
Market reaction in Jet2 (LON:JET2) seems very overdone. Meeson deserves a lot of credit for building a robust airline from (more or less) scratch, and these results show it is on rude health, with solid, sensible plans for the future. I have faith that CEO and CFO, who are both very sound, will carry this business forward. Way too cheap.
Also strikes me that they seem to be the best operator in the sector (fastest growing over the years?), the only one that is now cash rich (least damage done during the pandemic?) and they trade on the lowest rating- doesn't add up to me
I think everyone is very twitchy currently! If you have any extra cash, I'd be buying this one as I think it's growing at a reasonable rate! I hold.
Jet2 (LON:JET2)
to me the market reaction today is completely justified
straight to te outlok to see how they are faring compared to expectations.
On that basis, and with the peak summer months of July, August and September not yet complete plus the majority of Winter 2023/2024 seat capacity still to sell, it remains premature as is always the case at this time of year, to provide definitive guidance as to Group profitability for the financial yearending 31 March 2024.
To me any large cap that says we aint going to say the foggiest ref range of expectations deserves to be destroyed - imho completely unnaceptable copout. You wouldnt find next pulling this trick. We dont expect anything definitive at this stage in the year simply your best guess please with suitablly wide range.
Note brokers have forecasts and i would be 100% certain the company itself has forecasts - are we really saying that there is no additional information being made to brokers that would guide them as to what forecasts should be. If thats the case why not spell it out in your official update.
Any uncertainty like this is imho bound to adversley affect shareprice short term unless there are enough positives elsewhere to more than compensate.
Agreed. Jet2 (LON:JET2) now have nearly half their market cap in 'own' cash. That was a good set of results whatever the market's response. Today's analyst's report on Research Tree is interesting.
The most obvious risk is that the UK tips into a recession which means that fewer people book holidays. Set against that this does seem to be a high quality business at a very cheap price:
* high ROCE and ROE
* growing
* high net cash
* very positive customer feedback
I hold and will continue to hold or even add despite the market response
re Hunting (LON:HTG, they have upped guidance this year and next...for now are growing again .. their space appears attractive, valuation looks fine. John Wood (LON:WG.) came rattling back when the bid from Apollo evaporated. This was 240 so gets my interest....but we don't have decent proforma nos yet (post consultancy business sale) and need the H123 results. A positive was the recent contract win. Food for thought anyhow.
Agree, think Hunting (LON:HTG) would have went on a decent run after May update but being dropped from the FTSE250 with forced sellers created a nice opportunity.
Think I commented last week it looked to have bottomed when daily afternoon sells stopped. Unless that was another of my 2am share price dreams.!
Same thing happened to Goodwin (LON:GDWN) last year. Has nice earnings momentum now., just have to see if the rise sticks this time.
Zeus upgraded Hunting (LON:HTG) EPS + PBT by 8% and 37% for 2023 + 2024
Chance of a beat H2 in their opinion unless usual seasonal Q4 slowdown gets in the way.
Paul can you look at Currys (LON:CURY) results out today please hiden in their rns title. I would not touch the shares
Had a small holding, managed to dump it at open with tiny loss. Following comet is my opinion. Paul was right about this one...
Hi david,
Yes, I'm just about to start looking at Currys (LON:CURY)
Regards, Paul.
It is interesting to reflect on today being the anniversary of the US yield curve inversion (2 year versus 10 year). After 1 year, the yield curve inversion has generally increased and is now about 1.08%, meaning it costs 1.08% more to borrow for 2 years than 10 years. Such a yeld curve inversion has resulted in a recession following every time since WWII I believe. This is also the largest inversion of the yield curve since August 1981 from what I can see. In the UK 10-year gilts have now gone to 4.5% again, the same level as the fiasco budget last year.
UK stocks are cheap that's for sure and smallcap stocks even cheaper. However, what happens in the US ultimately drives global markets (including the UK) and I'm a bit concerned that global investors are torn between a shallow global recession and talk of "this time is different" (i.e. the yield curve inversion won't lead to a recession because the Fed have perfected their game). I am still very cautious about the impact of "toppy" US markets (with AI the latest bubble and the US having an 80s Japan style c60% share of the Global market) and that's leading me to hold back in the UK small cap space. I know its difficult / virtually impossible to time markets, but.....what do others think?
Something that has made me feel a little more confident in the small cap space (about 1/3 of my portfolio) is how it has compared with the FTSE over the past few days. I don't have the exact figures to hand but it seems to have dropped less on the down days and risen more on the flat/up days. This is the first week I can remember where this has been the case... could it be a turning point, a potential bottom? Who knows!
I would say it depends on the type of game you’re playing. I would argue that if your game is on timing the market and making an investment decision based on your forecast of macro dynamics in the near future you’re playing a very tough game which only a small handful of people in the world might play with any success (George Doris, Ray Dalio), because it’s unknowable it shouldn’t be a factor in your investment decisions.
In my opinion investment decisions should be squarely focussed on the business. And if it’s a business you plan to hold for the long term the most important factor is an assessment of its competitive advantage or moat and the durability of that moat, as well as its opportunity for reinvestment and the quality of its management and then the price it’s being offered for.
For me personally those are the most important things to focus on. If it’s a great business which I love and I think it’s great value on a long term view I would buy regardless of the short term macro. If you’re worried about the market going further south then perhaps dollar average into your position? That way you win either way, and even more so if the company is buying back there stock.
You highlight two important issues I think we all wrestle with...should we worry about recession and should we worry about a major US market turn.
For me, and obviously these issues are very personal....since ones investment horizon has a major bearing on the answer. Recessions tend to be short lived things so Im just not that concerned. The US market I have spent plenty of wasted hours worrying about. The relative valuation of the UK and its performance last year help. At the end of a period of drawdown, 2020, 2009, 2003 ....the market rallied significantly at the end of the weakness in a matter of days... reclaiming a good slug of the losses. So for me, I conclude I probably get bearish early, miss the top, and then miss the bottom....and therefore the chunk Im looking to capture is a relatively small 10-15%. To put that in perspective Jet2 (LON:JET2) announce strong results but the CEO leaves on the wrong day and the shares fall 12%! So I lean more towards the comment below, that we should worry less about markets and concentrate more on the companies. Especially now....I waited so long for the UK to be on 10x... unloved and offering fantastic future returns. I will resist the temptation to go all Jamie Dimon ... but safe to say the UK just isn't as bad as the media make out. IMO of course...
Agree with topvest. UK market has some cheap shares, but i think that the US market will fall this year which will affect the UK. In a way this is normal, good reasons for the market to rise balanced by good reasons for it to fall.
Stick to firms with decent profit margins and reasonable debt, the same recipe as normal.
Good morning Graham and Paul. I was going to ask if you'd do a quick comment on T Clarke Graham after your cautious Green on May 10th, I'm pleased to see it on your list (we hold). Also pleased to see Robert Walters there, I've been monitoring them as a possible buy since reading very favourable subscriber comments on Stockopedia. Like many other subscribers I appreciate the analysis you both do.
Hi JASVFS, how are you? Good news - I've just done CTO and Paul is working on RWA! Cheers.
We are fine thank you Graham, I'm an optimistic octogenarian about life in general and investing....often wrongly! Thank you for the T Clarke comments, their shares were kind to us in the past and I was hoping for a repeat in the next few years, your comments have given me serious pause for thought about the company and we may well take a small profit and exit.
Slightly off topic or is it? Always excellent daily Points of Return piece by John Authers (Bloomberg free sign up ) today - Drawing comparisons of turmoil and blood on the streets in various parts of the world
Just one snip in relation to markets "The array of policy changes that might follow a breakdown in social order doesn’t lend itself to modeling on a spreadsheet."
My morning smallcap tweet: Arguing the toss over quality and dross
Cyanconnode Holdings (LON:CYAN) Tclarke (LON:CTO) Gelion (LON:GELN) Distil (LON:DIS) Abingdon Health (LON:ABDX) Robert Walters (LON:RWA) Byotrol (LON:BYOT) Sabien Technology (LON:SNT), Peel Hunt (LON:PEEL), Next 15 (LON:NFG), Tpximpact Holdings (LON:TPX), Deltex Medical (LON:DEMG)
◄CyanConnode (CYAN)► guides FY-Mar rev broadly in line with market expectations but no figure. Three months guys! Guides adj EBITDA miss due to higher proportion of revenue from Middle East, on lower margin hardware. [SP=13.92 Cap=38m]
◄TClarke (CTO)► £10.7m placing at 122p, a 14% discount, for working cap. Trading still strong and highly confident that FY rev will be over £500m. [SP=142.5 Cap=63m]
◄Gelion (GELN)► update on its battery tech. [SP=26.99 Cap=29m]
◄Distil (DIS)► Q1 rev up 206% "lapping a suppressed Q1 in 2022 as a result of remodelling the business". [SP=0.31 Cap=2m]
◄Abingdon Health (ABDX)► guides FY-June rev up 42% and 125% higher ex covid revs. Cash at hand £3.2m, in line. [SP=12.15 Cap=15m]
◄Robert Walters (RWA)► Q2-June net fee income down 10%. "As reported in our June trading update, candidate confidence and time to hire are not yet showing the anticipated signs of sustained improvement." [SP=422.06 Cap=313m]
◄Byotrol (BYOT)► gets UK patent for anti-viral properties of certain enhanced extracts of commonly available brown seaweed. [SP=1.81 Cap=9m]
◄Sabien Technology (SNT)► FY-June trading. M2G rev up 62%. No rev fig for b.grn. [SP=12.49 Cap=3m]
◄Deltex Medical (DEMG)► guides H1-June rev £1.1m, down £100k. Waiting for an ambulance again with only £100k cash at hand. Considering another fundraise. [SP=1.1 Cap=9m]
In line: PEEL, NFG, TPX
Tclarke (LON:CTO) Disappointing that the issue of shares, at an appreciable discount to the latest closing price, is restricted to favoured investors and ignores private investors.
Re: Tclarke (LON:CTO) I also still have their Nov 22 trading update firmly in mind where £40m of revenues were conveniently delayed into 23 - which helped ensure they hit their sacred £500m revenue goal. Whenever someone says AIM companies can’t be trusted, it’s helpful to remember trust can also be lacking on the main market.
Maybe they need more cash to grow, the placing explanation is a bit vague, but it may also be true we’ve been reminded that reported period end cash balances by companies can be dressed up and might not reflect the true underlying cash position needed to run a business in a proper way.