Small Cap Value Report (Thur 9 May 2019) - DFCH, Swiss Watches, WTG, WATR, CCT, SDRY, CAY, WRKS

Good morning!
Quite a few things to look at today.
- Distribution Finance Capital Holdings (LON:DFCH)
- Watches of Switzerland (ticker unknown)
- Argo Blockchain (LON:ARB)
- Watchstone (LON:WTG)
- Water Intelligence (LON:WATR)
- Character (LON:CCT)
- Superdry (LON:SDRY)
- Charles Stanley (LON:CAY)
- Versarien (LON:VRS)
Financial Reporting Council
The FRC has imposed sanctions against Laura Ashley Holdings (LON:ALY) 's accountant in relation to its work on that company's accounts for FY June 2016. Fines were reduced to reflect "an exceptional level of co-operation" by the accountancy practice and its audit partner.
I've been criticising the authorities for taking up to a decade to resolve cases such as this. Bravo to the FRC for the quick turnaround on this investigation.
Distribution Finance Capital Holdings (LON:DFCH)
- Placing price: 90p
- No. of shares: 106.6 million
- Market cap on admission: £96 million
Admission to trading and first day of dealings
The share price has popped higher on the first day of dealings for this brand new financial stock.
Distribution Finance provides working capital for businesses, in partnership with major manufacturers. Its primary customers are the dealerships who sell equipment into business. The types of things it finances include mopeds, motorbikes, RVs, marine craft, industrial and agricultural equipment.
I was interested to check whether pricing might be attractive but the admission document tells me that the company's book value at December 2018 was just £54.6 million. I don't think that any of the IPO proceeds are going to the company.
The IPO is a demerger from TruFin (LON:TRU) that is designed to help DFCH in its application for a banking license, enabling it to offer retail and SME desposit facilities.
Long-term, it is hoping to achieve ROE of 25% with a £1.2 billion receivables book. It wants to develop a wide range of working capital solutions for business - invoice discounting, finished goods financing, etc. And it will accept leverage of up to 7x.
The plans are quite aggressive but I would still be open to investing in it. 25% ROE would be a terrific result, if it can be achieved.
Unfortunately the pricing isn't cheap, with a Price/Book Value ratio of 1.6x based on the placing price of 90p. And the share price has already rallied to 118p.
So I'll be keeping an eye on this while in no particular rush to buy into it at current levels. On the watchlist.
Watches of Switzerland
Intention to float on the London Stock Exchange
This is "the UK's leading luxury watch retailer".
It has also entered the "significant, but underdeveloped US market".
You can find its showrooms in prestigious shopping locations such as Regent Street, Oxford Street, the Royal Exchange and Heathrow Airport. Several of its stores trade simply as Rolex.
Rolex, Patek Philipe and Cartier are the headliners but it supplies over 40 brands in total.
Details of placing: it might raise £155 million (gross) in new money and give an exit to certain existing holders.
Raising these funds will reduce net debt to £120 million, or 1.56x adj. EBITDA.
My view: will need to see further details. I'm very selective when it comes to retailers but I do admire the luxury sector and would be happy to learn more about this one.
Argo Blockchain (LON:ARB)
- Share price: 3.36p (-4%)
- No. of shares: 294 million
- Market cap: £10 million
The major shareholder in Argo is on the warpath (see yesterday's report). It notes with palpable anger that Argo's executives have spent £3 million since the end of March on new crypto mining equipment.
The shareholder had requisitioned a general meeting on March 28th, with the hope of forcing the company to change strategy and save its cash from being wasted. So you can understand why it's not happy about this additional spending.
I can't agree more with this paragraph. EBITDA is irrelevant:
FIH also notes that management have set out that they expect Argo “operating cash breakeven during May” and “EBITDA break-even in the second half of this year”, which First Investments strongly believes are irrelevant metrics, given that the depreciation of the crypto hardware is not included, which is currently one of the major costs to the business and, as evidenced by the Argo Announcement yesterday, is draining Shareholders’ funds at what, in FIH’s view, is unsustainable on any level.
If I held any shares in Argo Blockchain, I would vote YES to the proposals at the General Meeting.
Watchstone (LON:WTG)
- Share price: 85.1p (-5%)
- No. of shares: 46 million
- Market cap: £39 million
This holding company is preparing for trial with Slater & Gordon over the botched deal it made in 2014/2015.
The "underlying" loss it reports for 2018 is £6 million, and the total loss is £20 million.
I don't think the businesses it owns are worth much. It says that it wants to generate as much value is it can from them. Why doesn't it sell them immediately? I'm not sure why it hasn't sold them already.
The S&G trial will take considerable time to resolve - and if Watchstone loses, then it can say goodbye to the £50 million that is held in an escrow account and will also have to pay significant legal fees. The legal expenses in 2018 alone were almost £6 million.
NAV has reduced from 144p in last year's accounts to just 101p in these accounts, and more operating losses and legal expenses are almost certain to drag it lower again this year.
There is a chance that £50 million from the escrow account could be recovered, if it wins the legal battle. Against that, you have to bear in mind that the rest of the group could turn out to be worthless, depending on expenses and on how quickly they shut down/sell off the remaining businesses. Not for me.
Water Intelligence (LON:WATR)
- Share price: 368.5p (-10%)
- No. of shares: 15.2 million
- Market cap: £59 million
This US-based, international group provides leak detection and remediation services. It has been sitting on a very high earnings multiple for a while, which it has been growing into.
Growth numbers are excellent for FY 2018, as expected:
- revenues +45% to $25.5 million
This is not the same thing as "system sales" (including sales made by its franchisees to customers). System sales are over $100 mllion.
- PBT +53% to $1.8 million
Evidence of operational leverage, with profits growing faster than sales.
- The UK unit crosses into profitability for the first time
- 2019 is on track to meet market expectations
Latest broker forecasts I can see are for Adj. EPS in 2019 of 15.3 cents, rising to 17.8 cents in 2020.
Given that we are heading for half-way through 2019 already, I think it's reasonable to focus on the 2020 numbers. The current share price is equivalent to 479 cents, putting this on a prospective 2020 P/E ratio of 27x.
The December 2018 cash balance ($5.2 million) equates to 33 cents per share, so the ex-cash P/E ratio is more like 25x.
I admire Water Intelligence's ambitions. As noted before, it wants to be a "world-class multinational growth company". While such ambition is often worthy of scorn from a small company, it is rarely backed up by strong, profitable growth.
Any negatives?
- it conducts close to zero R&D. So while it considers itself a technology company rather than a support services company, it is not currently developing any new technologies. And I don't know if it actually owns any proprietary technology. It's hard to imagine that someone has a monopoly on thermal imaging.
- Many franchises have been reacquired in 2019. This is bad news for me: I prefer the capital-light franchise model to the capital-intensive corporate-owned model.
Indeed, the company understands that royalty revenue is "especially valuable" in terms of having an "optimal capital formation", but seems to have a preference for having more corporate-owned stores, anyway:
Our operating plan for 2019 will be to keep pushing sales growth of corporate locations but continue to increase margins to levels closer to that of franchisees which are typically above 20%. Hence selective reacquisitions can be a driver of the share price reflecting an organic expansion of profits and equity multiple.
The paragraph above also worries me in that management seems to have a strong interest in the share price and P/E multiple.
I prefer when management is concerned primarily with metrics like ROCE and free cash flow per share, rather than share price and P/E multiple. If ROCE is consistently strong while a company reinvests its earnings, then strong profit growth is guaranteed.
But it sounds like Water Intelligence is choosing to boost earnings in the short-run, with half an eye on its share price, even at the possible expense of lower returns and lower growth in the long-run.
Or it might just be the case that it can't think of anything better to do with the cash flow it's generating, and that's why it is buying back so many franchises. It spent $1.8 million in 2018 doing this, and $2.3 million so far in 2019.
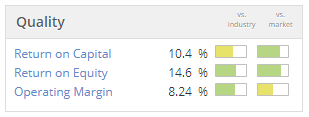
I was tempted to open a starter position in this share today but the historical quality metrics back up what I'm saying about low returns, and I'm a bit concerned that they might not rise very far from these levels.
Don't get me wrong: I still like the company and expect it to continue generating profitable growth. Time will tell whether my concerns are valid.
Character (LON:CCT)
- Share price: 582p (+1%)
- No. of shares: 21 million
- Market cap: £124 million
Designers, developers and international distributor of toys, games and giftware
We have covered this one plenty of times before - see the archives.
This update shows good progress. Trading is in line with expectations. An acquisition made last year has suffered a setback (a bankrupt distributor), but is expected to recover.
I like the fact that Character buys back its own shares sometimes - a good thing to do when you have excess cash, a cheap P/E multiple and are confident in your trading prospects. It hasn't bought many in recent times, but has the authority to buy up to 3 million this year. That could support the share price if sentiment weakened.
I haven't got anything else to add, as little has changed.
Superdry (LON:SDRY)
- Share price: 498p (+4%)
- No. of shares: 82 million
- Market cap: £408 million
Trading performance continues to be weak; initiatives to stabilise and improve performance underway
This is very interesting. Superdry says that full-year underlying PBT is likely to be below market expectations - and yet the share price is up!
- "Global brand revenue" (the amounts paid by customers for Superdry gear including taxes and from wholesale channels) is up 3.6% year-on-year.
- Superdry Plc revenue is flat year-on-year. Wholesale is up while store sales are down.
The range of market expectations for PBT is given as £54.1 million to £59.4 million. So the actual result will be lower than this.
Julian Dunkerton is back in the (Interim) CEO position, and has taken the following actions:
- More options for sale online
- Greater density of stock in flagship stores
- Less promotional activity, enhancing margins and strengthening the brand (this used to be a hallmark of Superdry's strategy)
- 500 new products planned for first six months
Mr. Dunkerton adds a positive comment: he is "more confident than ever that we can restore Superdry to being the design led business with strong brand identity that I know it can be".
My view: I think this has an excellent chance of succeeding under Dunkerton's leadership. He still owns 18% of the company and is highly incentivised and capable. This share is now primarily a bet on his vision. Tempted to open a long position here.
StockRanks rate it very highly in Quality and Value, though it currently lacks Momentum.
A few quick comments to finish off.
Charles Stanley (LON:CAY) - still working on its 15% net margin goal, launching a transformation project to achieve this. The jury is out.
Works co uk (LON:WRKS) - shares down 18% after guiding for adjusted PBT at the lower end of market expectations. Share price performance is minus 40% since IPO'ing less than a year ago. Might be getting into value territory but extreme caution needed.
Cambria Automobiles (LON:CAMB) - guiding ahead of expectations for the full-year. I still think that some of these dealership shares will turn out to be bargains. CAMB on a single-digit P/E.
Versarien (LON:VRS) - opens an office and a lab in North America. Announces four exciting agreements with partners to "explore" the use of graphene, "investigate" the use of graphene, "explore" combining graphene and carbon, and "establish graphene supply chain components".
And it's also taking part in a big graphene summit. And it says it's receiving a high number of enquiries.
It's little wonder that VRS is leading the way in the supply of RNS announcements.
Ok, I have to call it a day there. Paul will be back tomorrow.
See you in Mello, those of you attending!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
With Water Intelligence (LON:WATR) presenting at Mello next week, it sounds like there will be no shortage of questions.
So there we have it. Air Partner (LON:AIR) results issued at 17 45. If they had initially said that the results would be between market close today and open tomorrow there would not have been the panic with people making phone calls and ditching shares "in case it is bad". In the event underlying eps came in at 9.6p cf forecast 8.5p
Outlook - "I am pleased to be announcing a robust set of results, which I believe mark a turning point for the Group. We have taken the steps required of us to strengthen the business and made significant progress over the last year. As a result, we're reporting good organic growth, with a very strong performance in the US, strong Freight trading, a growing contribution from Consulting & Training and several new office openings. In addition, we have added excellent experience to our Board, invested in key management positions and appointed new auditors. This progress now leaves us well positioned to execute our stated strategy for growth."
So all they've got to do now then is sort out investor relations!
Graham, Versarien (LON:VRS) "It's little wonder that VRS is leading the way in the supply of RNS announcements" Brilliant and too true.
Separately, any views on the hostile originally nil premium Non-Standard Finance (LON:NSF) takeover of Provident Financial (LON:PFG) by anyone?
Much mud being expensively thrown by both parties. At the offered 8.88:1 ratio, NSF shares are now valuing PFG at around a <10% discount to the market yet >50% of shares (Invesco/WF/Marathon who hold BOTH NSF & PFG shares currently are (still) declared in favour of the takeover vs only 14% against (Schroders from Monday).
Industrial logic says NSF are right and they offer a better strategy (and possibly mgt) through bolting on Everyday Loans branch network and Guarantor lending brands GB / TrustTwo to Vanquis Bank whilst selling off Moneybarn/Satsuma and de-merging Loans@Home. But intervention from the Competition Authority a real risk. This may cause PFG shareowners to hold back support to avoid risk.
I hold (too much) NSF else I would be buying NSF now either for the very long term or as a cheap way to own some PFG (which I think is on the road to recovery).
Re £Superdry – great to hear some diversity of viewpoints. My take and concerns were different again.
Dunkerton’s desire for ‘more options online’ = more complexity in the supply chain - why is one of the strategy reasons why the MBA professional managers clashed with him (first pushing him out and then being ejected themselves). Personally, I think Dunkerton is right here (against my own classic FMCG experience & MBA training). The new online digital world demands variety that is supported by fast fashion cycles ….requiring flexible, near to home but more expensive suppliers vs lower cost Far East ones (another point of strategic difference).
However, IMHO, the real issue behind the poor £Superdry performance has been poor product. For the last 12 months this has got botched and occured when Dunkerton was ostensible involved but in reality exiting day to day involvement and rowing with the rest of the board. Quality of design suffered as energy was focused elsewhere.
Renovated product is due this summer (eg on-trend LBTQ+ ‘rainbow’ sweatshirts) and, critically, this autumn (eg transitional waterproof rain jackets to hedge bets on weather better). Jackets/Sweats were 56% of sales in 2018 in the key AW season. Hopefully, these innovations will be kept and be complemented with some ‘heritage’ designs now his old design partner is also being brought back.
But I also expect today’s profit warning will include considerable discounts offered to shift poor product and some prototype write-offs. Dunkerton will surely ditch planned Kidswear introduction and reduce deviation into ‘premium’ edits and women’s dresses etc (where Superdry has no real heritage) which is all to the good.
Another watchout is Europe. Majority of sales are now in Europe (UK <30%, US/China/ROW are still nascent development markets desite former mgt’s hubris). Lack of growth there if their economies struggle is going to hurt - especially in wholesale and franchise store sales.
Finally, again IMHO there is going to be a big write down of store assets and impairments in all mature geographies. Again Dunkerton had at least some input over these decisions over the last 3-4 years but can blame it on the old board.
In total, I think there may be up to £30-50Mn of bad news in the full year results being a combination of this year impacts of write-offs/discounts/exceptionals including the costs incurred in the Board war and the impairments that the property review will flag up. However, the balance sheet is very strong now with little debt so this can be managed.
So net, ne, 6months from now, Superdry will be selling renovated product from impaired stores and with extra online skus available - so LFL sales/profits are highly likely to go positive.
Personally, I did not want Dunkerton back but most importantly the management conflict and distraction is now gone and the business can move forward. Really good chance Superdry can recover its mojo to a large extent as I think the brand itself has been dented but not broken. So slow, steady but not spectacular share price recovery and good divis while we wait
I do not hold yet but will likely buy now or after the year end results are declared.
(Edit - need to learn to write faster as Graham has now also opined since I started my comment!)
Hi Graham,
Also very interested in Character (LON:CCT) if you can fit it in based on ISA’s comment:
‘There is some stuff in the middle of the report about problems with the new acquisition, looks like some re-capitalistion may be required to satisfy banking covenents, with a deadline of this Aug. Would like to see Grahams's take on this.’
Character (LON:CCT) management are often rightly criticised for excess pay, but they have been running the company for a long time, own a lot of shares ( I think) and steadily deliver, so far. They have very good customer relationships and are at risk of loosing a license when up for renewal, but so far haven’t. Solid balance sheet and good yield and good momentum.
Hi John, CCT says in relation to Proxy that there is "an element of under-capitalisation of its business and, that this will be required to be addressed".
I haven't looked into it in detail but I don't think Proxy is very big so it shouldn't be too expensive. G
Where are your comments on Water Intelligence?
Hi Peter,
I don't think Graham has finished the report yet so I am sure comments on Water Intelligence will arrive in due course, as planned.
Richard
Another vote for Character (LON:CCT) please, I have a small existing long position. A few observations based on a quick skim of the results:
The majority of the revenue increase came from the recent acquisition (6.2m of the 8.3m increase from 50.5m to 58.8m). This says sluggish organic topline growth to me.
Only a small part of the operating profit increase came from the acquisition, about 0.3m of the 1.3m increase (4.6m to 5.9m). This says good operational performance of the core business to me.
Excellent cash conversion, some very favourable working capital and inventory management.
Bombproof balance sheet, (Current assets + investment property) - (Total liabilities) approximately equals 25m, approx 1/5th of market cap.
There is some stuff in the middle of the report about problems with the new acquisition, looks like some re-capitalistion may be required to satisfy banking covenents, with a deadline of this Aug. Would like to see Grahams's take on this.
Cambria Automobiles (LON:CAMB) numbers out today if you could take a look - seems to be showing some top and bottom-line growth in contrast to peers after having made the shift to higher-margin brands. If they can sustain the growth then the stock can fly given its priced so meagerly as well as the strong asset coverage..
A bit concerned about Air Partner (LON:AIR) as they advised a week ago that results would be out today but no sign of them as yet. Does anyone know why not?
I hold
Air Partner (LON:AIR)
Reply from TB Cardew (PR) :-
"The results will be out this afternoon. "
Phil
Edit : There was no explanation
Phil,
Thanks for this information. Did you come by this information in response to a direct email to Air Partner or is there an RNS I have missed? It is strange that the shares have not dropped considering the information silence from Air Partner and no sign of the results.
Michael
Hi MBFP
Air Partner (LON:AIR)
I sent them an e-mail and they replied quite rapidly.
I'm surprised by the muted SP movement ( remember Staffline (LON:STAF) ) and my theory is that the "city" had been advised they were not coming out this morning FWIW.
Phil
Thanks Phil.
I hope your theory is right, and I think it probably is, but it is disappointing especially in light of last year's debacle. You would think they would do everything they could to get it right now.
Let's hope this afternoon doesn't mean 4.30!
I just sent another email to Kate Patrick at Air Partner as I am not impressed with the lack of results so far today (I hold):
It is now getting very close to the market close and still no results - an hour to go to the market close
Why, if the results were only intended to arrive this afternoon, were investors not informed? .
Results RNS are expected to appear at 7am.
It has not been fun to be an investor in Air Partner since April last year.
This is not the way to bring back investor confidence.
I would appreciate a reply to these questions from Air Partner.
Hi Ned,
I have also now contacted Air Partner directly.
Received the following reply:
'The results are due out this afternoon'. Again no explanation.
Michael
Morning Graham
A positive trading update from TT electronics (LON:TTG). Total revenue up 27% and organic revenue growth of 10%, excluding the impact of FX. Given the absence of of guidance on earnings it is reasonable to assume that the company is currently trading in line. Having said that it is continues to look inexpensive for a company that has recently been turned around by the CEO, Richard Tyson.
Views?
Regarding Water Intelligence; I bailed out on the run-up to todays results. I tend to agree the numbers are messy and where is the growth outside the USA? I can see this share slumping.
Another vote for Character (LON:CCT) please
Re Water Intelligence, this is one that tends to have a big run up prior to results and then drops back post results. Am expecting/hoping it will drop back to the 300 level having sold 80% of my holding yesterday. IMO anyone wanting to buy is better off sitting on their hands to wait and see where this settles.
Another vote for Character (LON:CCT) which looks cheap for its Quality metrics and strong YE outlook. Brought an initial position at the open.
It used to me the market's most shorted stock - but this is no longer the case.
Q1 results from Arrow Global (LON:ARW), which on first pass to be quite satisfactory, may be the reason for the gradual unwinding of what was significant short interest. The short unwind is slow but it appears to be one way at present.
It's not that the short thesis was wrong, more likely that it has just played out - and played out well for many involved. Arrow Global (LON:ARW) just seems to be delivering.
In my view, Arrow Global (LON:ARW) was probably overvalued, but now it appears undervalued. What seems to be missing is fraud, irregularities, deliberate hype, or over-leverage, which I also look for (as well as gross overvaluation) when going short!
If the short interest continues to reduce, that's a lot of stock that needs to e bought back. Borrowed stock that costs, as the dividends are large and growing.
Not for everyone (or many at all!). And (no surprise) I am long and getting a little longer each time I see a reduction in short positions.
Graham has commented before: "At a P/E ratio of 5x and dividend yield pushing 7%, it could be a value investment or a car crash waiting to happen. On top of the huge short position, the fact that the Stocko algorithms hate it is another red flag".
Stocko algo's NOW have it as:
Quality 41
Value 71
Momentum 40
StockRank™ 48
...so getting better, on all counts.
Edit - FYI the OLD (Sept '18) algo's were:
Conference call at 9: http://bit.ly/2IZomJo
Hello Frederick
I've got no opinion on Arrow Global (LON:ARW) positive or negative. I've been meaning to look at it and never got round to it.
My only view is that the "real" fundamental short sellers seem to have stuck against it and even increased their position and it is the run it by the numbers and hedge against long short sellers that have reduced (which they probably would with positive momentum)
Your thoughts on the Superdry (LON:SDRY) Trading statement would be appreciated Graham. Initial market reaction was negative but has now turned positive. I hold.
It's interesting this share passes 10 Stockopedia screens (all positive) - that's the most I've ever seen.
Superdry (LON:SDRY)
Could anything else have gone wrong - at least the company cat didn't pass away in the update period - so one has to presume it could have been worse.
Looks like this is a case of corporate mismanagement at its finest - hopefully some kitchen sinking to boot and i for one am delighted to have the old bod back - perhaps he should change his surname to Dinklage - put on the GOT gear get his "prepare for the final battle speech" ready and post it on you tube to motivate the troops (and generate some publicity) - Where they are now i think one person with clear vision and common sense leading the pack is what they need.
Anyway despite the fact the news today is a NEW profit warning - the shares are up today so the good news is that everything that has gone wrong is mostly fixable (ignoring the uk retail decline in general which is i do admit a mini fire breathing elephant) and hopefully they have the bod in charge to do it. I do think they will be unlikely to get back anywhere near where they were short term profits wise (uk retail decline) but there should still be a decent business here i "i tink". It's particularly disappointing wholesale and e-commerce has under performed as that is where the future lies.
Re Superdry (LON:SDRY) that was actually less bad than I was expecting. I think there's a decent chance of a short term turnround here as there do seem to be some quick wins for someone with retail nous. Why would they not have been offering the full range online before, surely that's the easiest channel to hold stock for? Ditto making sure the flagship stores have stock and stopping some of the incessant promotional offers that made them seem desperate.
Longer term it may be harder work to refresh the brand and cope with UK retail headwinds. But passsing ten Stocko screens makes me think I may take a small punt here.
Superdry (LON:SDRY)
But passsing ten Stocko screens makes me think I may take a small punt here.
wow that must be a stocky all time record i would guess ? - shame they have the old saying "when it looks to good to be true .....!" - if that's the case we need to invent the "sucker of suckers - to good to be true screen" which flags a shorting potential if 10 other screens are passed saying this share is a bargain.
Hmmmm just realised there is already a screen of screens setup doing the opposite - however that is set at a much more believable level of just 4 screens being passed.
All I will say is that Plus500 (LON:PLUS) passes 11 Stocko screens, has fallen 73.5% from its 52 week high and has a momentum score of 3!! Clearly meets your "sucker of suckers - to good to be true screen!
Just for interest on this subject ran a screen to filter shares with greater than 10 screens met. Top of the league were 4 housebuilders Barratt Developments (LON:BDEV), (13), Bellway (LON:BWY) (13), Redrow (LON:RDW) (15) and top of the league Persimmon (LON:PSN) (16). Only other entrants were Lonmin (LON:LMI) (11) and the aforementioned Plus500 (LON:PLUS) . Anyone for a housing market crash?
Any chance of looking at the final results from Water Intelligence (LON:WATR) .Revenue and profits growth look excellent. Am I missing out by being cautious about some of the red flags (discussed in this column previously) - related party transactions, US company listed in the UK, etc.?
Water Intelligence (LON:WATR)
Julianh
Am I missing out by being cautious about some of the red flags (discussed in this column previously) - related party transactions, US company listed in the UK, etc.?
I think the obvious "recent history" answer is yes based on the fact the shareprice was sub 240p not so long ago and is now up over 50% from that point and one could sell up and bank a decent profit - i too have remained on the sidelines due to exactly the same worries. I don't see anything specific to cause concern but its all just a little bit messy for my liking.
Looking at the accounts decent topline growth and very positive outlook, however its just all very messy numbers wise to the extent that the numbers are so complicated they are somewhat meaningless - looking at the growth in intangibles / level of salaries / share options / franchise ins and outs - i don't really have the foggiest with regard to where to start. To be fair thats probably to be expected and as long as the company continues topline growth i have to expect that the current shareholders will probably do ok - but i won't be chasing this shareprice up unless the forward looking p/e comes back into value territory which i am guessing is unlikely. So boat missed by me here.
Thanks rmillaree
Better to have the small pain of missing out on a successful investment than the much bigger pain of taking a loss if the red flags turn out to be justified.
julianh
Water Intelligence (LON:WATR) remains a puzzling company, for me. The excessive remuneration, Related Party transactions & absence of any corporate governance have been discussed on this board before.
But looking at today's numbers, there are other issues:
1. The company had net cash at year end & also at the interims, yet repeatedly pays a financing charge suggesting it has net debt, not net cash.
2. The company is valued as a growth company (p/e 35x) & reported today 45% revenue growth yet the underlying growth in royalty income is just 5.7% i.e. the organic growth is paltry, the reported growth is from the acquisition of franchisees.
3. The key subsidiary (ALD) was incorporated in 1974 - why has sales growth been implicity so low in the past 45 years to reach a level of just $25m today?
In summary, Water Intelligence (LON:WATR) has more red flags than a communist rally. It's akin to a game of Russian roulette - you have a 5/6 chance of survival, but why take the risk?
Hi julian,
I've covered Water Intelligence (LON:WATR) now.
I've not spotted all the red flags mentioned by others, but I still have a few concerns which are holding me back from opening a position in it.
Cheers
Graham
Water Intelligence (LON:WATR)
Graham
I've not spotted all the red flags mentioned by others, but I still have a few concerns which are holding me back from opening a position in it.
and
it conducts close to zero R&D. So while it considers itself a technology company rather than a support services company, it is not currently developing any new technologies. And I don't know if it actually owns any proprietary technology.
I don't know how material the sums involved are but there is the potential "conflicting interests" with regard to the agreements with PSS that may carry royalty payments once the relevant threshold is exceeded.
from prior year annual report
25 Related party transactions
PSS was a former owner of ALDHC and ALD until the reverse merger in 2010 that created Water Intelligence. PSS is now an affiliate of Water Intelligence and hence is a related party. PSS provides a technology license to Water Intelligence and ALD on terms favourable to Water Intelligence and ALD. The license is royalty-free for the first $5 million of sales for products developed with PSS technology.
*Patrick DeSouza and Michael Reisman are directors and shareholders in Plain Sight Systems, Inc. (PSS)
also
During the normal course of operations there are inter-Group transactions among PSS, Water Intelligence plc, Water Intelligence International, ALDHC and ALD. The financial results of these related party transactions are reviewed by an independent director of Water Intelligence plc, the parent of Water Intelligence International, ALDHC and ALD
I would feel a lot more comfortable if Patrick DeSouza only had his fingers in one of the two pies rather than both the company and PSS. Ok i am guessing this a non material historical remnant of a situation but it isn't ideal when bods have 2 fences they can sit on.
Yes rmillaree ,
You spotted the same thing that finally turned me off here.
If I understood the chain correctly Patrick DeSouza owns the IP on which Water Intelligence (LON:WATR) make their living.
Now of course this could just be a legacy of the way they came to market, or not.
I cannot help being reminded of Safestyle UK (LON:SFE) , where senior managers were able to leave whilst carrying with them much of the value, in that case it was illegal, in this case I think it could be entirely legitimate.
I have no wish to besmirch Mr DeSouza by saying that he would do anything underhand, but the suspicion that he could is quite enough for me.
As the growth now looks to be substantially lagging the valuation I don't even feel that I'm passing up a future bagger by being fussy - we shall see.
A positive trading update from Elecosoft this morning.
Please could you give your opinion Graham. (I hold)
Michael
As MrC points out, more collaborations for VRS
A collaboration being what you do when the organisation you’re talking to doesn’t want to be a customer!
My morning smallcap tweet: Frontier Smart trading smarts
Beeks Financial Cloud (LON:BKS), Velocity Composites (LON:VEL), Frontier Smart Technologies (LON:FST), Mirriad Advertising (LON:MIRI), Cambria Automobiles (LON:CAMB), Findel (LON:FDL), Versarien (LON:VRS), Watchstone (LON:WTG)
Beeks Financial Cloud Group (BKS) small acquisition. Commercial Network Services, a US-based online service provider, for $1.4m max. Co had rev of $1m and pretax $0.17m. Expected to be earnings enhancing within the first full year.
Velocity Composites (VEL) guides H1 ahead of Board expectations with rev up 5%. Adj pretax marginally ahead of breakeven and net cash flow effectively neutral.
Frontier Smart Technology (FST) warns FY rev only $36.6m and adj EBITDA loss of no worse than $0.9m. Blames competitive pressures in Digital Radio, continued weak sales in Smart Audio and slow start to new Smart Audio/IoT licensing business - 37% lower than market expectations.
Mirriad Advertising (MIRI) FY rev £416k, down 52%. Pretax -£14.3m (-£11m). EPS -14p (-19p). Newish CEO boasts that "The business is now getting into a far better position...I am very encouraged by the progress to date."
Cambria Automobiles (CAMB) H1 is ahead of management's expectations with rev up 4.5%, U/L EPS up 18% to 4.51p. Guides FY ahead of current market expectations.
Findel (FDL) guides FY pretax slightly above current market expectations of £27-£28m.
Versarien (VRS) is America the new China for VRS? A bunch of collaboration agreements follows the opening of its US office and laboratory facility.
Watchstone Group (WTG) FY rev £38m down 15%, EPS -12.6 (-41.1). Stockopedia F/C rev £41m but that's clearly wrong as WTG already guided £37.7m in Jan. Ingienie sales poor. I'm short.
Good morning Graham, i’d Appreciate your casting the slide rule over Character (LON:CCT) this am as it’s by on by profits seem up about 18% with exciting new toy ranges - I hold. Ta.