Small Cap Value Report (Thurs 27 April 2023) - SDG, TW., CREO, IPF, 4GBL, PPHE, HOTC, RWS, WINE, IBST

Good morning from Paul & Graham!
Today's report is now finished at 12:56.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
I'm happy with that, we covered lots today - with plenty left over for me to scrutinise tomorrow too.
Summaries
(more detail below, in main sections)
Sanderson Design (LON:SDG) - down 8% y’day to 134.5p - Paul - GREEN
FY 1/2023 results in line with expectations. FY 1/2024 outlook also in line. I review the numbers in detail below. SDG remains one of my favourite value/GARP shares.
International Personal Finance (LON:IPF) - up 3% to 98.9p (£221m) - Graham - GREEN
Q1 update is ahead as all divisions are performing at this international lender. Impairments ticking up but still below their pre-Covid levels. Good growth in lending and receivables and the company is ready for new Poland regs. A risky share but the value keeps me interested.
£PPHE - down 2% to 1120p (£474m) - Graham - AMBER
Solid trading in Q1 from this hotel group with summer bookings giving it confidence for the full-year revenue outlook. Occupancy is still lagging and needs to improve to pre-Covid levels before I can have any faith in the written-up valuation of its balance sheet.
Quick comments
Taylor Wimpey (LON:TW.) - 125.6p (pre-market) - £4.4bn - Paul - GREEN
Trading update (in line exps) today - interesting for read-across to small caps. Very similar to Persimmon yesterday - continued recovery in demand, FY 12/2023 guidance reiterated, good mortgage availability, toughest for first-time-buyers, house prices resilient, build cost inflation 9-10% but is/expected to moderate, bottlenecks in planning system.
Paul’s view - as mentioned yesterday, the whole sector looks interesting, because the bad news appears in the prices, and the next cycle could be recovery/upgrades. NTAV = market cap, and 7.2% fwd divi yield. Looks good, but TW. has already had a strong bounce.
Creo Medical (LON:CREO) - 24.75p (£87m) - FY 12/2022 Finals - Paul - RED
Revenue of £27m, and a £31m opertating loss for 2022! It was heading for insolvency, but shareholders saved the day with a £28.5m placing at 20p in Feb 2023. So it must have a strong story to have got away a big fundraise at a reasonable price. But there’s nothing here that I can value, as any value in the shares is entirely based on hopes for the future, with the past just being heavy losses. High risk yes, maybe high reward, who knows? Not really relevant for a value report, so let’s move on.
4Global (LON:4GBL) - down 4% to 51p (£13m) - FY 3/2023 TU - Paul - AMBER/RED
Just a quick comment on this tiny, obscure software company related to sports. I was expecting to dismiss it, but there might be something worthy of research here. Big improvement in revenues in H2, as previously indicated would happen, so FY 3/2023 is £5.6m revenues (H1: £1.4m). Adj EBITDA of £0.9m. Cash looks tight, at £1.1m (down from £2.1m at H1). Some impressive contract wins internationally, and it says the sales pipeline is large at £30m. Might be of interest to micro cap investors maybe? Although a red flag (given recent shenanigans at IBPO) - the CEO here owns 51% - which I think means I’ll have to go more towards red than amber.
Hotel Chocolat (LON:HOTC) - down 10% to 158p (£217m) - profit warning FY 6/2023 - Paul - RED
Poor recent trading means that forecast PBT of £5.5m previously, now becomes a negligible profit of £0.2m for FY6/2023. Yet this announcement reads like it’s a triumph! The only positive is £23m cash in the bank.
Remember the international expansion strategy has been an expensive failure, so they’re now trying to maximise the UK, with no sign of any progress at all so far. We’re told not to worry, this was just a “transitional year” and that magnificent profits are in the pipeline for the future.
Latest forecasts are profits soaring from nothing this year, to £18.5m next year, and £30.7m the year after, on little change in revenues. Will it really be possible to achieve such stellar increases in profit margins? Given the company’s poor track record (giving a good impression of a badly managed business, with terrible capital allocation in the past), I think you would need to be a tremendous optimist to believe the current forecasts.
Hence in my opinion, risk:reward still looks poor, although the share price has come down a lot. So if you believe the hype and the ambitious forecasts, then it could do well, who knows. Personally I would rather buy a business that is already nicely profitable, rather than buy one where I’m having to hope that it can become profitable.
Note also the ownership structure, with management having a controlling stake, so outside investors can't remove them. Hence high delisting risk I think, if the news continues to worsen.
RWS Holdings (LON:RWS) - up 5% to 266p (£1,028m) - H1 TU - Paul - GREEN
This share dropped sharply, from 286p to 239p earlier this week on publication of a poorly received H1 update. It’s bouncing now, and readers seem interested, so I’ll give it the once over.
It’s a mild profit warning with FY 9/2023 guidance indicated towards the lower end of analysts range of £128-137m, that’s for adj PBT, so real profits.
Reasons given are challenging market conditions, organic constant currency revenues down 6.8%, but helped by forex to overall 2.5% up. Softer client activity and slower decision-making are mentioned.
H1 is £54m adj PBT.
H2 weighting is still expected, and reasons given sound sensible.
Taking cost actions. Net cash position of £57.5m (end March 2023). I’ve reviewed the last balance sheet - it’s got massive intangible assets of £1,080m, but even if we write those off, NTAV is still positive. So no issues with debt, it all looks OK to me.
Active acquisition pipeline, and it looks to have the firepower to acquire without dilution, I reckon.
Paul’s opinion - this is only based on a quick review, and little to no understanding of what the company actually does! I think this looks very interesting. The fwd PER is only 9.8, and there’s a nice 4.9% dividend yield. Plus it seems to be self-funding growth through acquisitions, and there’s no net debt to worry about.
Thumbs up from me! This looks like it could be a nice entry point for a long-term position. I would query how AI will affect it - this is talked about in the update, but I'm not clear if it will be a net positive, or negative? Will computers be able to replace people? Maybe that's why the shares are cheap?
Naked Wines (LON:WINE) - up 2% to 116p (£86m) - FY 3/2023 TU - Paul - RED
This sounds mixed -
Positives - revenue of £350m in line exps. Adj EBIT at top end or slightly above £15-18m range. Net cash £10m. Reducing inventories. Cost control actions.
Negatives - inventories provision gone up from £8m to £14m (tip of the iceberg maybe?). Poor payback on marketing at 1.6-1.8x over 5 years - is this a viable business model?
Paul’s opinion - sceptical still. I’d need to see the full numbers. In the past, the excessive inventories was enormous, and that alone puts me off, as massive inventories can often be a can of worms. I’m happy to look at the numbers with fresh eyes when they’re published, but it doesn’t interest me at this stage. Not really any evidence this is a viable business model, or a growth company.
Ibstock (LON:IBST) - 167p (flat) (£656m) - AGM TU FY 12/2023 - Paul - GREEN
We saw recently that brick distributor Brickability (LON:BRCK) put out another positive update. IBST says it's the UK's largest brick maker, and it also sounds quite upbeat - rather surprisingly maybe, given macro worries. It says Q1 saw subdued demand, but it still performed marginally ahead of expectations, which seems a little confusing. Forecasts have come down a fair bit though.
It says cost inflation is now slowing, and energy costs hedged (although at higher prices than last year).
Outlook is confident about achieving FY 12/2023 expectations. Expecting conditions to improve as 2023 progresses.
Paul's opinion - I think this whole sector looks interesting, with MBH, BRCK, FORT also worth considering & comparing. I'm not entirely sure how, but they don't seem to (yet?) be suffering from reduced housebuilding - although the upbeat statements from the builders indicate maybe we should be looking through the hiatus caused by the clumsy duo Truss & Kwarteng?
Stockopedia figures show a fwd PER of 11.5, a nice 5.0% yield, and good asset backing too. So I like IBST as a sensible value share.
I see from the long-term chart, it tends to trade in a 150-300p range. So given it's near the bottom of that, maybe it could be time to think about dipping our toes in here? BRCK looks cheaper on a PER basis, but doesn't have asset backing.
Paul’s Section:
Sanderson Design (LON:SDG)
134.5p (down 8% y’day)
Market cap £96m
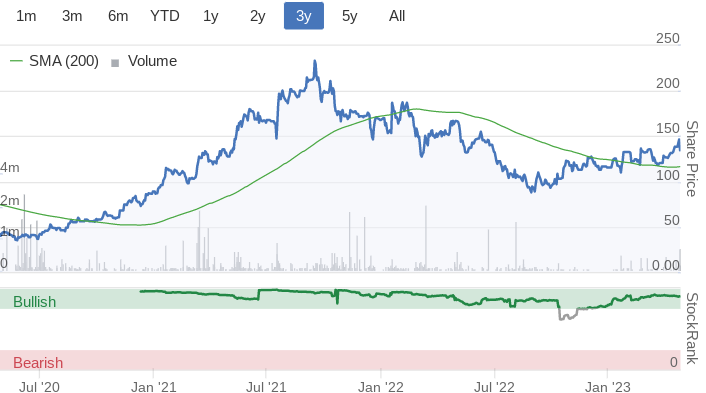
The figures/outlook didn’t seem to impress the market yesterday, down 8%, but the chart below shows this is little more than a blip.
The downtrend in share price from autumn 2021 to autumn 2022 was I think just the general market bearishness towards small caps, and nothing company-specific.
My overall view of SDG is positive, with Lisa Montague having demonstrated a strong turnaround since taking over in 2019, and guiding the group well through the pandemic.
I interviewed her here in Oct 2022, which got great feedback from listeners, and is still relevant as an overview of the business and the strategy.
On to the FY 1/2023 results -
Revenue flat at £112.0m, so given higher inflation, that’s effectively a real terms decline.
Profit matters more than revenue, and underlying PBT is up 1% at £12.6m, which I think is fine given the tough macro backdrop.
Underlying EPS is 14.2p (LY: 13.8p), giving a PER of 9.5 - a modest valuation in my view.
Licensing revenue (which is almost pure profit) is the star performer, up 25% to £6.5m
The other better performers were: Morris & Co brand, and USA region (a key focus for growth).
This EPS actual result is ahead of forecast (13.8p) but that’s due to a lower tax charge, so trading is effectively in line with expectations.
Dividends flat vs LY at 3.75p total - a yield of 2.8%
Balance sheet - is really excellent. NAV of £81.3m becomes NTAV of £54.9m, which is plenty for the size of business. This includes cash of £15.4m, and no bank debt.
Working capital is extremely strong, with £43.1m net current assets.
Pension scheme - has swung from an accounting surplus of £2.6m in Jan 2022, to a deficit of £2.5m at Jan 2023. There’s been a substantial drop in asset values as with many pension schemes over the last year. That does concern me a bit. Just because the method of valuing the liabilities has also resulted in a fall there, the actual liabilities haven’t fallen, the way I look at things. The cashflow statement seems to show £2.4m being paid into the pension schemes, so this looks to be an ongoing, and quite material cash outflow each year, so it can’t be ignored.
Overall though, an extremely robust balance sheet, so little to no risk of dilution or insolvency.
Cashflow statement - a stand out number is the increase in inventories, which look high now at £27.8m, which absorbed £4.9m cash. Singers expects this to reverse in the current financial year.
The main other uses of cashflow are increased capex, at £4.8m (incl. £0.7m intangibles), and payment of divis. Overall the cash pile reduced by £3.7m to £15.4m - not a concern, but the item I’d like to see reduced in future is that £27.8m inventories.
Current trading - input costs still increasing. USA doing well. Licensing strong. Hospitality contract orders “encouraging”. Excited about new product launches (the deal with Disney to revive archive designs sounds interesting).
Licensing - there’s an interesting section explaining this. NEXT is becoming increasingly important (I wonder if it might bid for SDG?)
Strategy is very clear - with a big focus on increasing licensing deals, more in the pipeline. Also continued growth in the USA, where SDG is hardly scratching the surface of a huge market.
Outlook - expectations for FY 1/2024 unchanged, but we’re not told what they are!
Brokers are obviously given a steer by all companies, so going by Singers update (many thanks for this, very helpful) expectations for FY 1/2024 look quite modest, with adj EPS expected to fall from 14.3p to 12.9p. That looks cautious to me, and I’d hope to see forecasts beaten.
Paul’s opinion - this is one of my favourite value/GARP stocks for 2023 (and beyond), which made it onto my top 20 watchlist here, and is a strong performer so far, up 24% YTD. Obviously it’s early days though, and given the tough macro backdrop, we have to be realistic and expect a few profit warnings in any portfolio. If SDG does warn on profits from any macro-related setbacks later this year, I’d just treat it as a blip, and if anything would probably see it as a buying opportunity, depending on the circumstances.
The fundamental strategy is good I think, and it has demonstrated pricing power, with profitability undented despite cost increases, and softer demand. That’s pretty impressive I’d say. Also I see SDG as a potential bid target, from the USA maybe, or NEXT?
Overall then, it gets a thumbs up from me, as a very nice business, at a reasonable price, that I think should do well long-term. There could be turbulence on the way, due to macro factors, and timing of licensing deals, so we don’t know exactly how things will pan out.
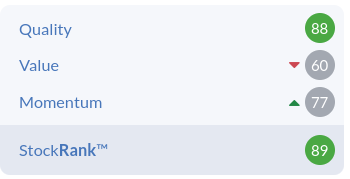
Stockopedia also likes SDG, with a strong StockRank -
Looking for similar shares? Check out this screen which includes SDG. I like a lot of the shares on this list (click on link in picture below) -
Graham’s Section:
International Personal Finance (LON:IPF)
Share price: 98.9p (+3%)
Market cap: £221m
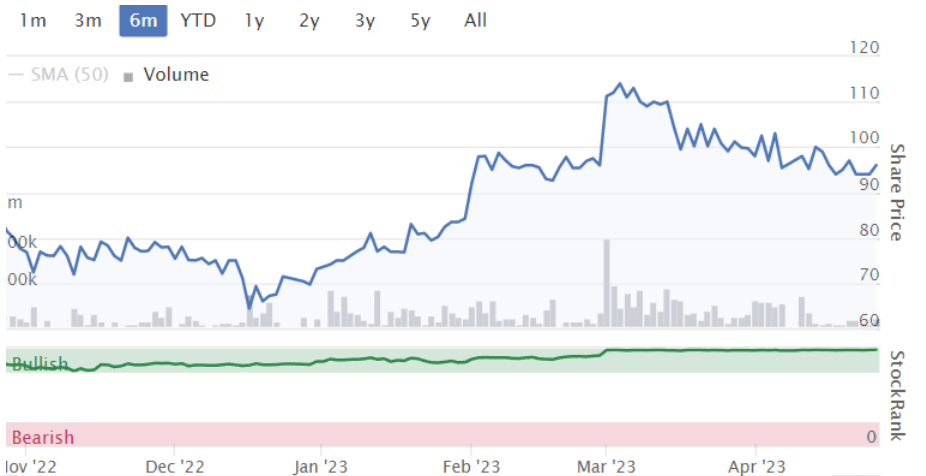
I’ve been taking an interest in this lender since last Autumn, when its value characteristics really started standing out to me! The last six months have seen the share price recovering to a higher level:
For an overview of the company and my thoughts on it, see the SCVR from March 1st .
Now let’s see what is new with today’s Q1 update:
Trading is ahead of internal plans
Customer lending is up 15% year-on-year
Customer receivables are also up 15% year-on-year.
Net receivables now £883m.
Revenue yield (the yield earned by IPF) is up from 48.5% to 53.4% year-on-year. It’s important that IPF is able to pass on higher interest rates to its customers.
Impairments: when it comes to fears around impairments, how is this for reassurance:
There has been no discernible impact from the cost-of-living crisis on customer repayment behaviour and our portfolio quality remains good.
The annualised impairment rate has doubled year-on-year to 10.5% but this is still good in comparison to pre-Covid impairment rates (see the impairments rates in 2019 for example).
If I check the unemployment rate in an economy like Poland where IPF operates, I find that it’s 5.4%. Maybe the cost-of-living crisis (caused by high inflation) doesn’t matter that much in comparison to the importance of low unemployment? So long as people still have jobs, I guess they will continue to make their debt payments?
Poland strategy: IPF has now issued 20,000 credit cards in Poland as it adjusts to new regulations which prevent it from charging non-interest fees on home credit loans like it used to.
All divisions are performing well: European home credit, Mexico home credit, and IPF Digital.
Excerpt from the CEO comment:
Whilst we remain mindful of the economic backdrop and continue to take a conservative approach to maintain credit quality, we now expect to deliver a result ahead of our original plans for the year as a whole.
Balance sheet: their bank lending facility continues to have about £80m of undrawn headroom and as I’ve said before, they may wish to increase their headroom sooner or later. But they still say their funding requirements are met until 2024.
My view
I was already positive on this stock, due to its cheap rating and performance which appeared to be solid despite economic concerns.
After today’s ahead of expectations update, I’m clearly going to remain positive on it!
So that I don’t get too enthusiastic, allow me to remind you of the bear points:
Investing in Eastern Europe and Mexico is risky without local knowledge.
IPF’s borrowing costs are 13% and its bonds are rated junk by the ratings agencies.
The bad debt allowances are huge and the impairment rate could still produce a nasty surprise if the economies in which it operates deteriorate.
Regulatory risk won’t go away.
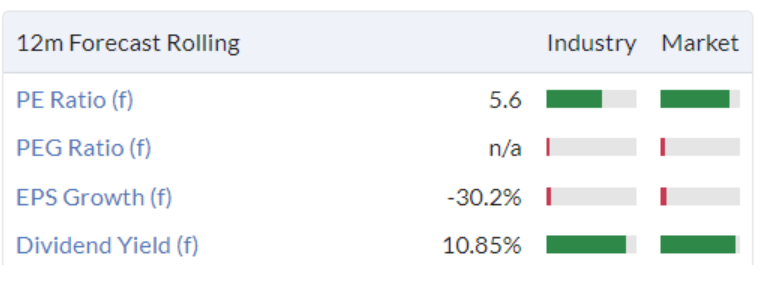
In exchange for taking on these risks, investors can get value metrics like these:
A high-risk, high-reward play in my book.
PPHE Hotel (LON:PPH)
Share price: 1120p (-2%)
Market cap: £474m
This group operates most of its hotels under the Park Plaza brand (owned by Radisson) and the “art’otel” brand.
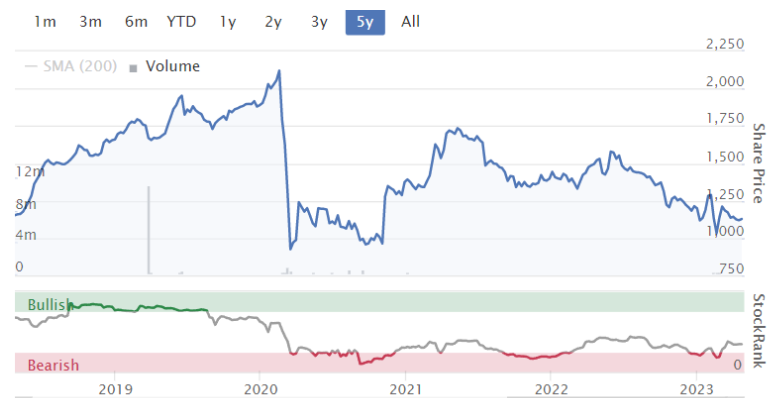
Its post-Covid share price bounce appears to have fizzled out. It’s languishing far below pre-Covid levels:
Let’s check out their Q1 2023 trading update:
Q1 revenues of £69m have more than doubled compared to last year. I think I’ll just ignore comparisons with last year as they are irrelevant. Let’s use the Q1 2019 comparisons instead.
Against 2019, revenues are up 10%, “driven by higher rates”.
Input cost inflation for hotels since 2019 is a lot more than 10%, so revenues have failed to keep up with inflation.
The problem seems to be with occupancy rates, rather than pricing:
Pricing - room rates are up 24.5% vs. 2019. This seems fine.
Occupancy - despite improved pricing, the RevPAR (revenue generated per available room) is only up 9% since 2019.
A table at the bottom of today’s RNS shows that occupancy in Q1 was 66.9%, vs. 76.4% in 2019. So there’s still a lot of room for improvement on that front.
Strategic highlights: PPHE has been busy with a range of projects in Zagreb, Rome, London and Budapest.
Fund launch: the company is launching a new fund, whose name currently is the European Hospitality Real Estate Fund. It will be 51% owned by PPHE, who will “buy” this stake by contributing their Rome hotel. The other investor, an insurance company, will contribute €28m to buy a 49% stake in the fund
The fund wants to deploy up to €500m, using €250m of bank leverage and €250m of investor funds.
This seems like very exciting news to me! PPHE will earn fees from long-term hotel management contracts with all of the fund’s hotels, and will also earn incentives from achieving various targets with the fund (e.g. internal rate of return).
Current trading / outlook
Strong trends in Q1 have continued into Q2.
Forward bookings for summer underpin confidence for 2023, so the company is “on track to deliver further growth in revenue and EBITDA in line with recently upgraded market consensus”.
The company helpfully discloses that expectations are for revenue of £368 - 376m and EBITDA of £108 - 111m. However, I would throw out the EBITDA number as being irrelevant for a hotel group.
Graham’s view
It has been a while since I’ve looked at this one, but I’m open to the idea that it could be a value investment at current levels.
According to the most recent full-year results for 2022 (published in March), their assets were independently valued (using the “EPRA Net Reinstatement Value”) at £25.17 per share.
Even the more conservative EPRA measurements are at least £24 per share, i.e. more than double the current share price.
This is due to £750m of property revaluations (on top of the £315m in official balance sheet assets).
However, these revaluations assume that pre-Covid trends will be reached within a short timeframe. From the annual report:
The positive revaluation follows a significantly improved forward-looking cash flow profile, as the Company recovered from its COVID distorted trading sooner than expected. In their 2021 valuations, the independent valuers had assumed the Group's trading would be largely in line with 2019 from the 2024 financial year onwards; however, this has occurred sooner than they anticipated.
I’m concerned that these assumptions might be too optimistic, as the occupancy rates discussed earlier show that there is still a gap between current trading and pre-Covid occupancy rates.
Perhaps the summer bookings are so strong that the company is confident of a full post-Covid recovery in 2023, but I’d like to see it in black and white before betting on it.
So I won’t be able to give this share the thumbs up just yet, but I think it’s worth keeping an eye on. If they do get to pre-Covid levels of trading soon then it’s possible that their assets could be trading too cheaply.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Hotel Chocolat (LON:HOTC) I'm going to add another comment now that I've been through their March 2023 report. The takehome is that it should be trading at less than 1/2 its current price of 140p because (i) its has no real strategy for its chocolate! (ii) it cannot drive revenue and margin growth from its digital marketing base without constant innovation, but this costs money every time, so as a single-branded company, it's stuck (iii) it's focusing on Japan, instead of the USA and China. HOTC's overriding strategic moves are WRONG. Shame, as with the right ideas, it could make a lot more money but at this price and with this shareholding structure, it's a dog.
Hotel Chocolat (LON:HOTC) s an ugly share for all the reasons you've listed before. I wrote about this here a couple of years ago when the shares were 350-400p and tried to short them at IG Index but couldn't! I know the chocolate industry and HOTC is smoke and mirrors when it comes to production. Great brand..poor product if you know chocolate. Sales, but almost impossible to make a margin on which is odd as their price point is mid+ and they apparently have a huge mailing list, but something is going on with costs or with ARPC. This share starts to become value at 75p. No chocolate company makes money unless it's has growing volumes in the US, and China. You cannot make big money from mid market chocolate in the UK.
Re Ibstock (LON:IBST) - the balance on the demand side is covered in Paul's commentary but the big brick makers, led by market leader Ibstock, have also been investing big in CAPEX and R&D in recent to reduce the energy component of brick production on the supply side.
Ibstock have a major new factory equivalent to 5% of national demand is opening in the next year or so, FORT a year or so later. Together with expected falling energy input prices next year, this will generate improved margins. As the market is dominated by a triopoly, this should give a good tailwind. I hold some already but am considering buying more as there is also a decent dividend whilst we wait.
Hi Zipmanpeter
Ibstock (LON:IBST) capex spend this year is material, wiping out most of the cash generation as far as I can work out.
It's one of the reasons why I probably wouldn't buy today (just in case something does go wrong), but if all goes well it certainly looks like an excellent company for the long term.
Below is an extract from the Michelmersh Brick Holdings (LON:MBH) FY presentation, which might be of interest to you and other brick lovers.
I hold Michelmersh Brick Holdings (LON:MBH) and have my eye on Wienerberger AG (WBAG:WIE) .
Presentation Link:
https://www.mbhplc.co.uk/wp-co...
30% drop in Heiq (LON:HEIQ) today seems overdone? Just a few weeks delay in getting results published?
Albeit the announcement had red flags all over. Process chaos, new systems chaos. Maybe reflective of a terrible management? But the shares look really cheap now.....
Heiq (LON:HEIQ)
Hi Boon
I couldn't agree with you more and must admit that I've very tempted to take a very very small position here.
It's worth noting as well that HEIQ own most of a subsidiary that was only last year valued at $200m when Hugo Boss bought a 5% share in Feb 2022.
Even if this subsidiary was now worth 75% less (i.e. $50m), there's surely still a deep value play, especially given the net cash positive position (excluding leases), low cash burn and current market cap of only £25m.
A
Sanderson Design (LON:SDG) Let us not forget although it did not get a mention in the RNS, the electricity and heating costs for the factory should tumble providing they have not bought ahead too far, if they can hold pricing margin gains should be very helpful.
Mattioli Woods (LON:MTW) - new acquisition, new note - Mattioli Woods (MW) has acquired 50.1% of White Mortgages Limited (White) with an option to purchase the remaining 49.9% within 24 months. White is based in Lincoln and specialises in providing independent mortgage advice as well as protection insurance advice. In the year to 31 Mar 23 it generated revenues of £0.68m and PBT of £0.35m. White looks like a good fit: MW’s existing advice proposition is extended by adding a new in-house mortgages capability, and the White business is well-positioned to benefit from being fed more business from MW’s large adviser-base.
It looks like a low-risk deal for MW which has paid £0.425m on a cash-free debt-free basis for its first-tranche 50.1% stake of White (a pre-tax PER of just 2.4X). The second tranche of the deal for the remaining 49.9%, if exercised, will be for a consideration of up to £2.625m, dependent on the attainment of specified targets being met. We would expect the deal to be earnings enhancing and therefore, if the second tranche is exercised with a performance-linked payment in place, we would foresee the full deal PER as being less than 8.7x, an attractive proposition for MW shareholders.
We remind readers that acquisitive growth is a core part of MW’s strategy. It has a long track record of success with 34 acquisitions (excluding White) since its admission to AIM in 2005.
Link here: https://www.equitydevelopment....
Staffline (LON:STAF)
Staffline (AIM: STAF), the recruitment and training group, has been notified that on 26 April 2023, Henry Spain Investment Services Limited, a person closely associated ("PCA") with Thomas Spain, Non-Executive Director and Interim Chairman of the Company, purchased 152,517 shares of 10p each in the Company ("Ordinary Shares") at aprice of £0.3802 per Ordinary Share and purchased 42,762 Ordinary Shares at aprice of £0.386 per Ordinary Share.
Following the above transactions, Henry Spain Investment Services Limited has a resulting notifiable interest in 32,342,585 Ordinary Shares.
T. M. Spain has bought 3,071,168 since start of this year. Is he lining up a buyout? HR Net are a big shareholder here.
Stocko rank has increased by 25% over the last 30 days. I've followed the money here.
Likewise, big money getting spent here, the reason will be known soon I'm sure...
I'm confused. Above says Paul has done Naked Wines (LON:WINE) but it doesn't seem to be there - or at least I can't see it.
it's there!
it's between RWS Holdings (LON:RWS) & Ibstock (LON:IBST)
Paul & Naked wines - It's in the quick comments section
Thanks. Found it!
Paul & Naked Wines I thought it was a postcard from Gozo!
Cheers Ox 2906 - Classic comedy duo script, the straight guys lines just set up an easy laugh for the funny guy
Sanderson Design (LON:SDG)
Licensing revenue (which is almost pure profit) is the star performer, up 25% to £6.5m
My one gripe here (with the companies commentary not your comment) is that its clearly not almost 100% profit - their use of the term 100% margin is somewhat disingenuous IMHO - albeit it may be they they are forced to follow accounting dictats here (i suspect it suits their narative to pimp up the margins though)
Anyway ref the licencing revenue costs they say the following which somewhat confirms they are having to "earn their licence crust" with "direct costs" relating to licence income - presumably these "direct costs" are sitting in admin costs.
"Our strategy for licensing
"To support this strategy, we reorganised our design teams during the year so that we now have dedicated designers who work solely on licensing agreements, which are highly collaborative. From our side, we provide the design and the design expertise to transfer the design from a wallpaper or fabric, or from our own archives, to a multitude of different finished products of all sizes, materials and uses. In essence, we drive the design work, which is a key value we bring to the collaboration, and the partner drives the product production and marketing."
Not really a big issue to me as i concentrate on the overall bottom line anyway - i am aware that licensing can be a double edge sword particularly if they are confiming they are in a purple patch. There seems to be lack of any confidence that they expect to continue growing licence income - hey ho its all in the bottom line numbers though. It is always an easy excuse to downgrade expecataions late in the year if they ever say "licensing income was not as strong as last years outstanding results that included material accelerated income"
Overall happy though they are on track overall as things stand - i would also say Lisa has done a great job - they do seem to be a more focused/efficient company than they used to be - they probably need to be on point though to keep delivering as they have fingers in alot of pies (not necessarily a bad thing)
Seems that the missing tag problem is back. They were missing yesterday as well.
Thanks Smudge! I'll go back and check/replace all the tags later, have put it on my to do list.
Hi Paul,
Would you consider Volex (LON:VLX) or Sosandar (LON:SOS) for your next management meeting?
Volex (LON:VLX) in particular seems criminally undervalued despite going from strength to strength
definitely Volex
To endorse what has already been said, a very positive contract win for Volex (LON:VLX) in EV from a global US automotive company of £30M annualised revenue. Very pleasing as Volex (LON:VLX) is my 3rd largest holding having added recently.
Also an interesting update from Taylor Wimpey (LON:TW.) confirming the views recently expressed by Persimmon (LON:PSN) that the housing market tentatively appears to be turning a corner. This is to an extent echoed in the AGM trading update from brickmaker Ibstock (LON:IBST). I don't hold any housebuilders, but do hold several 'picks and shovel stocks' such Belvoir (LON:BLV) Forterra (LON:FORT) Howden Joinery (LON:HWDN) Headlam (LON:HEAD) .
A final comment on how market sentiment towards UK small and mid cap shares is abysmal, many of which offer significant value relatively to the share price. As Howard Marks has said the plan is to buy well, it isn't what you buy, it is what you pay. Good examples being in my view the above and I would also mention Watkin Jones (LON:WJG) and REITS, such as Real Estate Investors (LON:RLE) which yields 8% and trades at close to 50% discount to NAV and where management have recently bought a shed load of shares.
Moving up the market cap I would add in Jet2 (LON:JET2). It currently trades on a PE of less than 10 and has over£1 billion of its own cash, confirmed orders for additional aircraft from Airbus and has taken control of baggage handling at 7 of the 10 airports from which it flies. Holiday bookings and air travel have significant tailwinds you only have to look at recent announcements from the likes of easyJet (LON:EZJ) and Ramsdens Holdings (LON:RFX) (foreign currency). Jet2 (LON:JET2) has run rings around the likes of TUI AG (LON:TUI) which recently raised1.8 billion euros via a rights issue.
I rest my case 'Mi Lord'
Needless to say I am biased and excepting Taylor Wimpey (LON:TW.) and Ibstock (LON:IBST) I hold all of the above.
Hi
Holders of NextEnergy Solar Fund (LON:NESF) who have not seen this RNS might want to take a look (I hold) ...
https://www.investegate.co.uk/...
The headlines are .....
Capital Recycling Programme
NextEnergy Solar Fund, the specialist solar+ fund, has today launched a capital recycling programme (the "Programme") to accelerate the next phase of the Company's growth. Through the Programme, the Company aims to capture significant value from the divestment of a 236MW portfolio of subsidy-free UK solar assets, the proceeds from which will be used to:
· Reduce gearing: materially reduce current drawings of the Company's revolving credit facilities ("RCF");
· Invest in future long-term growth opportunities : provide flexibility to capture higher returning investment opportunities in the future, such as energy storage; and
· Buyback shares: establish a share buyback in the future if the share price continues to trade at a material discount to the Company's net asset value per share.
For those interested ....
Conference Call
There will be a short webcast this morning at 9.30am for both investors and analysts hosted by the investment adviser:
· Michael Bonte-Friedheim (CEO and Founding Partner of NextEnergy Group)
· Ross Grier (UK Managing Director, NextEnergy Capital)
· Stephen Rosser (Investment Director and UK Counsel, NextEnergy Capital)
To register for the webcast please use the following link:
https://www.investormeetcompany.com/nextenergy-solar-fund-limited/register-investor
I would welcome any thoughts on the pros/cons of this strategy.
Regards
Howard
Missed the presentation, the notice given being too short (received at 7.18 am today), but will find the recording on Investor Meet Company when it's available as I do hold.
Driver (LON:DRV) - Welcome news of progress (link to new research note with audio summary: https://www.equitydevelopment....)
The pre-close trading update from Driver Group was encouraging, with static revenues (signifying rising productivity), improving profitability and margins, and the move into the black for the first time in two years within the Middle East region. Cash levels continued to improve, highlighting the collection of doubtful debts and higher profitability. We expect the solid foundations put in place by the management team over the last 12-18 months will provide a strong base from which to grow meaningfully over the medium term.
Although our estimates remain suspended pending further visibility, we note the NAV (FY22 end: £16.4m or 30.3p / share) and net cash account for 35.1% of the market cap. DRV’s wider consultancy peer group, trades on an average prospective P/B ratio of 4.4x, suggesting that a re-rating of DRV shares looks overdue now that an inflection point has been passed. Our fair value/share remains 49p.
Isn't adding net cash to NAV double counting?
hi shipoffrogs
Driver (LON:DRV)
The post is poorly worded. They are talking about two different things.
1. ED note the level of NAV at £16.4m (which is actually in excess of the this morning's M/Cap of £14m hence shares are trading at a discount). M/Cap is now £15.7m following today's 3p SP rise to 30p.
and they separately note
2. The level of net cash at £4.9m represents 35% of this morning's M/Cap of £14m
Hope that helps.
Snazzy
Isn't adding net cash to NAV double counting?
I suspect they arent "strrictly speaking" double counting - ie there are two different statements one being nav is great and the other being net cash is great. It could be possible to have great nav without any cash - so i guess they are kinda saying the net cash is tyhe cherry on top. Or perhaps its their best atemptn at positive spin with the cards they have.
My morning smallcap tweet: HOTC fails to egg on profit
Literacy Capital (LON:BOOK) Hotel Chocolat (LON:HOTC) EnSilica (LON:ENSI) Naked Wines (LON:WINE) Yourgene Health (LON:YGEN) Volex (LON:VLX) International Personal Finance (LON:IPF) Driver (LON:DRV), Kerry (LON:KYGA), 4Global (LON:4GBL), Synectics (LON:SNX), ENGAGE XR Holdings (LON:EXR), Telecom Plus (LON:TEP), Quixant (LON:QXT), Byotrol (LON:BYOT)
◄Literacy Capital (BOOK)► NAV 467p/sh, up 11% in 3 months. [SP=NA Cap=NA]
◄Hotel Chocolat (HOTC)► guides FY-23 rev slightly lower than market expectations and U/L pretax breakeven. Blames "Easter period sales lower than expected due to some range gaps which could not be addressed this year due to transition year efficiency focus," [SP=NA Cap=NA]
◄EnSilica (ENSI)► guides FY-May rev in line and EBITDA significantly above current market expectations of £1.18m. [SP=NA Cap=NA]
◄Naked Wines (WINE)► guides FY-Apr rev in line and pretax £2-5m, in line. Adj EBIT £15-18m, at the top end or slightly above the guided range. [SP=NA Cap=NA]
◄Yourgene Health (YGEN)► guides FY-Mar rev £19m, above market expectations but in middle of Dec's guidance. Why is mkt exp below co's own guidance? Adj EBITDA loss in line. [SP=NA Cap=NA]
◄Volex (VLX)► wins $30m EV power product contract. Full production to commence during 2024. [SP=NA Cap=NA]. I hold.
◄International Personal Finance (IPF)► guides Q1 ahead of mgmt exp. "No discernible impact from the cost-of-living crisis on customer repayment behaviour." [SP=NA Cap=NA]
◄Driver (DRV)► guides H1-Mar rev £24.2m and U/L pretax over £0.65m. In line? [SP=NA Cap=NA]
In line: KYGA, 4GBL, SNX, EXR, TEP, QXT, BYOT
Yourgene Health (LON:YGEN)
"Why is mkt exp below co's own guidance?"
Maybe the market doesn't believe a word they say anymore.
Hotel Chocolat (LON:HOTC) "...due to some range gaps which could not be addressed this year due to transition year efficiency focus" ... I read this as they forgot to make the chocolate eggs in time for Easter ... ah well..
I write this to cheer others up as I look with admiration on other members holdings! This morning brings results and TU from the following. We hold Novacyt, Synairgen, (Pandemic buys, one might survive) Driver (long term hold -- getting there) and Volex (EV transition holding - positive announcement). Trifast was hopeful yesterday though! Paul, Doc Martens on?
Ahead of expectations results from Brave Bison (LON:BBSN) this morning, accompanied by a somewhat cautious outlook statement. (I hold).
Interesting on the cautious outlook for Brave Bison (LON:BBSN)
As the outlooks this week from the BIG players (Amazon, Google) have been decent.
However, Brave Bison operates at the somewhat discretionary end of marketing unlike Amazon and Google that are more performance driven marketing.
Morning All,
Seemingly nice contract win by Volex (LON:VLX) this morning, over $30M in 2024.
Volex (LON:VLX) wins a nice EV contract for its Mexico based factory worth north of @ $30m per year from a North American car company.
Dear Stocko - useful if can delete 'my' ill conceived post during the edit period.
Any chance of RWS Holdings (LON:RWS) which was in the running order for yesterday?
Re RWS Holdings (LON:RWS)
The 11 thumbs persuaded me that there was enough interest for me to respond. Quick section is now up. Short version - I like it! Looks good value despite a mild profit warning this week.
Regards, Paul.