Small Cap Value Report (Tue 11 Apr 2017) - NXT, VCP, RFX, SEPU, PAM, TST, XPP, CALL

Good morning! It's Paul here.
Both Graham and I will be working today. Graham will be emailing me his sections, which I'll include in this single report, marked clearly as being written by him.
Retail sales volumes
Over the weekend, I was looking at some data, showing that the latest retail sales volumes have apparently fallen about 2%. This seems to have cast a cloud over consumer spending related shares.
However, the way I see things, consumers only have a certain amount of money to spend. Therefore, when inflation starts rising, as it is now (due to the fall in sterling), then one would expect consumers to continue spending roughly the same amount. However, that amount will actually buy a smaller quantity of more expensive items.
From the retailer's point of view, this shouldn't really matter very much. In such a situation, LFL sales would simply be flat. Fewer items are being sold, but the prices have gone up, so the retailer ends up achieving the same overall sales figure. Moreover, with lower volumes of goods being sold (at higher prices), the retailer will actually achieve some cost savings - e.g. fewer plastic bags being used, savings on staff rotas, warehouse costs, etc.
Next (LON:NXT)
(at the time of writing, I hold a long position in this share)
Next puts out the most detailed forward guidance in the sector, and its guidance for 2017 is extraordinarily pessimistic. Its central guidance for LFL sales is minus 7%. Now bear in mind this is after the company will have raised selling prices by 4-5%, then this means that Next is forecasting a massive drop in sales volumes of something like 12%. That doesn't seem very likely to me.
At just over £40 per share, Next seems a remarkable value opportunity to me. The Directory business is now more profitable than the stores, so it's effectively a growing, internet-based business. Yet strangely, the market is ignoring this, and treating the entire business as if it's a declining, old economy business.
Including pre-announced special divis (covered by cashflow generation), the dividend yield is now approximately 7-8%. The forward PER is about 10, but that's based on really pessimistic forecasts. The company has a history of starting the year with very gloomy forecasts, and then pleasantly surprising later in the year.
It will be fascinating to see how this year pans out. To me though, the current bombed-out share price of Next, looks a marvellous value opportunity. There's a lot of future bad news baked into the valuation, and I suspect that could be laying the foundations for a decent share price recovery later this year. Time will tell - as always with shares, it's educated guesswork to a certain extent.
Victoria (LON:VCP)
Share price: 475p (up 4.4% today)
No. shares: 91.0m
Market cap: £432.3m
(at the time of writing, I hold a long position in this share)
Positive full year trading update - quite an interesting touch, to put the word "positive" into the actual title of the RNS. I wonder if other PR companies will pick up on that, and start copying it, I bet they will! No doubt, in the fullness of time, we'll find average updates being entitled as positive updates too.
In this case however, there's no need for cynicism, as the update does sound genuinely positive;
The Board is pleased to announce that the Group's underlying profits before tax will be comfortably ahead of current consensus market expectations for the financial year ending 1 April 2017.
Victoria is a very successful buy & build of carpet & underlay manufacturers. I was late to the party with this one, but picked up some stock personally a few days after an excellent meeting with the Chairman, Geoff Wilding. I reported back to Stockopedia readers the day after the meeting, here.
There seems to be a good rationale for this buy & build - good synergies (e.g. bulk purchasing of raw materials, and manufacturing efficiency, sharing of best practices within the group, etc).
Outlook comments sound excellent to me. This carries weight, because the group has successfully delivered on its previously upbeat comments;
Victoria remains focused on its strategy to create wealth for shareholders. Ongoing operational improvements are expected to continue to deliver very good organic earnings growth over the coming 12 months.
Additionally, Victoria has invested a significant amount of time and energy during the past year identifying further suitable acquisition opportunities within Victoria's existing markets and, importantly, Europe.
The Group's banks continue to be very supportive and there remains considerable headroom in existing facilities.
The Board is confident it will deliver another year of significant, earnings-accretive acquisition growth in addition to underlying organic growth.
So fairly heavy hints there that more acquisitions are on the way. The group doesn't seem to have put a foot wrong with previous acquisitions.
My opinion - my broker has helped me enormously with this one. Whenever I've sent him orders to top-slice my position in Victoria (when I needed money for something else, or for a margin call), he's replied suggesting that I might want to think again. This is because brokers can see additional orders which are not visible to even those of us who pay for level 2 market data.
It's one of those annoying foibles of what is really a rigged market in small caps - the quoted prices are often not the actual prices, with Market Maker stocks. Very often there can be orders hidden from view, which only brokers can see, that are well inside the spread. That was the case with Victoria, and thankfully my broker stopped me from selling. He pointed out that the stock was very well bid (with hidden orders), at prices only just below the offer price. That is usually a precursor to a more upwards in share price - as has indeed happened.
So it's always worth either using a proper telephone broker, or putting in a small dummy trade on an electronic broker website, to find out what the real prices are. In many cases, on making enquiries, I find that the real prices are actually on quite a tight spread. So the published spread between bid/offer is very often best ignored, as it doesn't reflect reality.
Overall then, it looks as if Victoria is likely to see broker forecasts raised again. With a positive outlook, and more acquisitions on the way, I'm inclined to sit tight here, anticipating further increases in the share price.
Debt might be seen as an issue, but the group seems to be very cash generative, so should be able to pay down debt in a reasonable timescale. The end game is a sale of the group, once it has attained sufficient scale to be attractive to a larger, international group. I continue to like this share, and intend sitting tight.
I've just seen a broker note, which suggests that we should expect about 26p EPS for FY2017.
The year that's just begun, FY2018 is forecast for just under 30p EPS, with the suggestion that this is probably likely to be revised upwards in future. Therefore a fwd PER of maybe 15-ish? That doesn't look outrageous, given the remarkable performance of this group in the last few years.
This share is one example of how companies which out-perform tend to keep on out-performing. Hence personally why I think it makes more sense to pay up for decent growth companies, as they often grow into an apparently high valuation.
Whereas the alternative strategy of buying cheap companies, in the hope of a turnaround, usually fails, in my experience.
Graham has just emailed me this section:
Ramsdens Holdings (LON:RFX)
Share price: 120.5p
(+8%)
No. shares: 30.8m
Market
cap: £37m
(NB. This section is written by Graham Neary)
A fantastic update from the pawnbroker Ramsdens, which is relevant to my (Graham's) personal portfolio due to my long position in H & T (LON:HAT).
Of course, pawnbrokers see themselves as a lot more than just pawnbrokers nowadays, as Ramsdens describes itself as a “diversified financial services provider and retailer”.
This echoes the H&T CEO’s comment that his company “is evolving into a provider of alternative credit services” (i.e. a lot more than just pawnbroking).
Anyway, everything is going well at Ramsdens. The shares have only been listed since February, but are now significantly up on the IPO price:
“Ramsdens' strong performance has continued across the Group resulting in further revenue growth and strengthening gross profit when compared to the prior year. As a result, the Board anticipates reporting adjusted* profit before tax for the Period comfortably ahead of management's previous expectations.”
(“Adjusted” PBT means before IPO costs.)
All four income streams are said to be growing: FX, pawnbroking, precious metals purchasing and jewellery retail.
That’s interesting – perhaps the pawnbroking market isn’t shrinking after all, or is growing in those parts of the UK where Ramsdens operates (Wales, Northern England and Scotland).
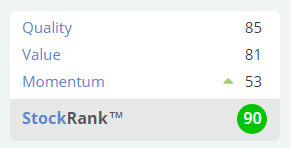
Anyway, the Stockopedia
computers love it and for selfish reasons, I will hope that it
continues to do well.
Sepura (LON:SEPU)
Share price: 12.1p (down 6.9% today)
No. shares: 370.1m
Market cap: £44.8m
(Paul Scott wrote this section)
UK Government public interest review - this is a fascinating situation. A Chinese bidder is trying to buy this maker of sophisticated radios for the emergency services. The agreed bid at 20p looks distinctly wobbly right now. The share price alone, is clearly signalling to us that the market has grave reservations about the bid going ahead.
If the bid doesn't go ahead, then I think there's a very real risk Sepura could go bust, or have to do another deeply discounted emergency fundraising.
The UK Department for Business, Energy & Industrial Strategy has decided to initiate a public interest review,
"as a result of Sepura's commercial arrangements with UK government entities"
Quite right too. Do we really want vital, emergency services communications equipment to be provided by a Chinese-owned company? On the other hand, if our Govt trusts China to help build nuclear reactors in the UK, then maybe it's splitting hairs to quibble over emergency services radios?
My opinion - I think this is a very high risk situation, and I'm keeping well away from it. To my mind there's a considerable risk of this ending in disaster for shareholders, so I'm not tempted to take the risk of buying at 12p in the hope of a 20p bid which may well not happen.
Graham has just emailed me another section, so this is from him:
Premier Asset Management (LON:PAM)
Share price: 133p (+0%)
No. shares: 105.8m
Market cap: £141m
(this section was written by Graham Neary)
A solid update from this growing, mid-tier asset manager, leaving the share price unchanged.
It’s yet another recent IPO. This one has been on the market since last October.
At the company’s final results for the year ending September, it reported assets under management (AuM) up 22% to £5 billion.
It was rather indebted at the time, with a lot of preference shares outstanding, but the IPO proceeds were used to redeem them all and clean up the balance sheet.
Strong AuM Growth
AuM are now up by another 11% in the six months since financial year-end, thanks to £310 million in net flows and £221 million in investment performance. So AuM are already at £5.5 billon.
Needless to say, this is a fantastic result. But of course the asset management industry moves in cycles, and when returns turn negative this is often compounded by outflows.
Performance is excellent. 95% and 96% of funds are above their sector median over three and five years, respectively.
Dividends are another attraction as quarterly divis are planned, and the yield looks set to be in the region of 5.6% versus the current share price.
My opinion (Graham)
This looks like it could be an attractive income stock. Active fund managers are under increased pressure to perform since the proliferation of passive alternatives, but those which prove their worth via good performance should continue to have a bright future, in my view.
In terms of valuation, Premier is trading at a market cap 2.5% of AuM, which I think is probably on the low side for an equity-oriented fund house with a good EBITDA/Revenue margin of 33% (according to the last Annual Report).
So I would be positive on the prospects here.
Touchstar (LON:TST)
Share price: 101.5p (up 9.7% today)
No. shares: 6.3m
Market cap: £6.4m
(at the time of writing, I [Paul] hold a long position in this share)
Results for y/e 31 Dec 2016 - this share is below my usual £10m market cap cut-off, so normally I wouldn't report on it. However, in this case, I think there seem to be some potentially interesting signs of better things ahead.
The actual results for 2016 are fairly unremarkable, as this is only a tiny company;
- Revenues £7.6m (down from £8.7m in 2015)
- Operating profit of £223k (vs £107k pre-exceptional in 2015, £6.5m loss post exceptional items, mainly goodwill impairment in prior year)
- Income tax credit, due to heavy R&D spend, so profit after tax was £475k
- Just over £1m spend on R&D
It's the product development, and R&D spend, which interests me. Reading the commentary, the new products sound potentially good. This includes a cloud-based software system for airlines to sell food, drinks, etc, whilst airborne.
On a recent flight, I noticed that BA are using a new, and very clunky system, based on an iPad, which seems extremely slow, and ended up with them only serving a few passengers, and then abandoning cabin service, as it was taking too long. So I hope very much this wasn't TouchStar's system, but I don't know.
Balance sheet - just about OK, but not strong.
My opinion (Paul) - this share is too illiquid for my liking, to I've not added to my existing position today, and am unlikely to do so in future.
However, I do think it might be an interesting one to keep an eye on, if the new products do lead to an improvement in sales & margins. I particularly like companies which spend heavily on R&D, as that can sow the seeds of future success, if spent wisely.
(going back to Graham now, for this section on XPP)
XP Power (LON:XPP)
Share price: 2432.5p
(+10%)
No. shares: 19.2m
Market
cap: £467m
(this section was written by Graham Neary)
I last covered XP Power at the final results last month, and today brings a Q1 update for the period ending 31 March.
It includes that beautiful word, “accelerated”:
Trading in the first quarter has been strong, as the positive momentum established in the second half of 2016 continued into the first quarter of 2017. Revenue growth, which had been building sequentially over the previous two quarters, accelerated once again in the first quarter of the new financial year.
Q1 revenues are up 40% versus the same period in 2016 (or up 23% at constant currency), reaching £40 million. And orders are up by even higher percentages:
Order intake in the quarter was also very encouraging at £47.0 million (2016: £30.3 million), up 55% on the same period in the prior year. In constant currency order intake was up 36%.
Dividends are quarterly at XP, and the Q1 dividend is increased by 7% to 15p.
Outlook is merely “in line” with expectations for 2017, so perhaps there was a disconnect between the positive expectations of the Board compared to the expectations of shareholders?
The Group has made a good start to its financial year, with continued growth in revenues and strong momentum in order intake. We are encouraged by the outlook and the Group remains on track to be in line with our expectations in 2017.
My opinion (Graham)
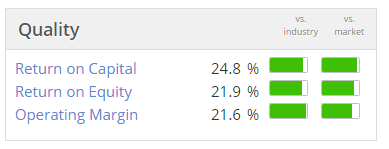
It’s a highly-rated
stock but this should be more than fully compensated for by excellent
growth, cash flow and quality metrics. Remember that they design most
of their own products: this is a lot more than just a distribution
network or customer support offering.
Cloudcall (LON:CALL) - a quick comment from Paul (I hold a long position in this share, at the time of writing) - the company has today announced new iPhone and Android apps for its cloud telephony product, with a key point of difference - that it integrates with customer CRM systems.
I've downloaded the app onto my iPhone, but can't get it to work yet, due to a configuration problem. With software companies, I always like to try out the product, and to become a paying customer. so I can personally verify that the product works.
Trying out products & services is a great way to test out your views about a share. This is a good thing to do, and Globo shareholders might have listened to the bear case a bit more, if they had bothered to try out its products - which were close to useless. As well as the accounts containing numerous red flags, as I reported on in 29 articles here.
Also, it enables you to experience customer support, for example. CloudCall are outstanding on customer support, in my experience. Very rapid response times, and problems usually get solved quickly & efficiently.
My opinion - I'll let you know what the App is like, once I've got it working.
As regards the company itself, I think it's getting there, gradually, despite a painful journey to date.
Will the cash last until breakeven? Probably not, is my hunch. The company has consistently failed to deliver breakeven in the past, despite promising to do so. However, I think it's making enough progress to mean that one final cash top-up probably won't be a problem.
You only have to look at LoopUp (LON:LOOP) to see how, once breakeven us reached, the valuation can go through the roof, when strong recurring revenues & decent organic growth are combined. CALL is maybe a couple of years behind LOOP, but its valuation is less than a third of LOOP's. So who knows, this one could yet surprise the doubters.
EDIT: I'm pleased to say that, within 3 hours of me logging a support request with CloudCall, then responded and activated my App. I've just tried it out, and it's great! Looks exactly like making a normal call, using your existing Contacts on iPhone, except the call goes via the CloudCall system, and gets tagged to the relevant CRM system contact. Seems to work fine. So a useful addition to the existing product, for sure.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
As a new investor, and ex electronics engineer, I was interested in Paul's comments on XP Power so checked them on Glassdoor (https://www.glassdoor.co.uk/Reviews/XP-Power-Reviews-E24805.htm). The comments suggest that it is not a well run company and could lose some of it's key workers and intellectual capital. How much weight should I give to this?
Hesitant to disagree with Paul on the subject of retail, BUT. I think you are being to relaxed on the impacts of inflation in this phase of the cycle. As consumer spending power is squeezed and increasing proportion is spent on essentials, leaving less yet for luxury / discretionary spend.
This is already being experienced but there's more legs to it yet as the inflationary impacts continue to feed through. Personally the Next (LON:NXT) downbeat revenue expectation seems pretty realistic to me, but Paul is not alone in not believing it. Hence I'm mostly staying well clear of "discretionary retailers" for the moment as I think there'll be an even bigger bargain opportunity in a few months time.
I seem to see a lot instances where the market reacts to an outlook warning, but reacts even further when the outturn matches the prediction.
I'm hoping to have more detailed delve into consumer spending over the next few weeks.
Hi paul, great article, really enjoy reading your articles. Just to be difficult i would disagree with this point you made.
"From the retailer's point of view, this shouldn't really matter very much. In such a situation, LFL sales would simply be flat. Fewer items are being sold, but the prices have gone up, so the retailer ends up achieving the same overall sales figure. Moreover, with lower volumes of goods being sold (at higher prices), the retailer will actually achieve some cost savings - e.g. fewer plastic bags being used, savings on staff rotas, warehouse costs, etc."
For retailers that sell bare neccessities i would agree but for other retailers i would argue lfl sales will decrease. Although consumers will still spend a similar amount, the ratios of where that money is spent will change and so the absolute values spent by consumers on certain products will change. All consumers need to purchase food, petrol, pay for rent etc... the bare neccessities so these will come out of their product first, they cant choose to spend less on these. If inflation is driving these up then consumers WILL have less to spend on things like eating out, clothes and other consumer products a lot of retailers provide. Hense LFL sale would logically decrease. I agree costs for retailers may decrease though as a result, cushioning this.
Let me know your thoughts
Reuben
There is a very good, albeit slightly outdated, guide to quote driven or market maker stocks and RSPs from pg 34 of The UK Trader's Bible: The Complete Guide to Trading the UK Stock Market
https://books.google.co.uk/books?id=c69WVkH6oHwC&pg=PA34&source=gbs_toc_r&cad=3#v=onepage&q&f=false
As Dominic Connolly puts it "The majority of trades are struck within the market spread on the screen; screen prices should only be regarded as indicative. I call them tourist rates."
RE Touchstar (LON:TST)
"On a recent flight, I noticed that BA are using a new, and very clunky system, based on an iPad, which seems extremely slow, and ended up with them only serving a few passengers, and then abandoning cabin service, as it was taking too long. So I hope very much this wasn't TouchStar's system, but I don't know."
I've also seen the problems with that system and have a nasty feeling it could be Touchstar. The whole thing has been very poorly received by crew and passengers. If you look at the Touchstar website, BA are listed as a customer, and there are many pictures of BA planes and crew on the relevant page.
http://www.onboard-retail.com/
Paul, you perked my curiosity when you stated that the quoted prices are often not the actual prices. I experience this myself, I often find with small caps I can buy and sell within the spread.
Am I right in saying that the stated Bid and Offer are the best Bid and Offer from at least one Market Maker? (i.e. other hidden (DMA?) orders are excluded) In that case I wonder why they don't take into account hidden orders when determining the best Bid and Offer. The current system seems disingenuous and cockeyed to me.
Any thoughts on Defenx (DFX) which reported excellent results today, confirming a growth trend and adding to this with the announcement of an acquisition?
All good, but can anyone explain the extraordinary accounts receivable which at €5.5mm are a large part of the €7.0mm sales figure.
I guess with Next the question is whether their offering is quite as popular as it was. A lot of younger people go to Zara which is very successful and there are, of course, businesses like Boohoo which Paul often mentions. At one time Jaeger was very popular but their ladies fashions got left behind. I understand that Next sells many brands so may carry on being successful although my wife who is 68 but likes very "with it" or unusual clothes never shops with them. At the cheaper end there are places like Primark and overall I suspect a lot more competition than there was at one time particularly on the internet.
Hi Graham or Paul,
As a matter of interest only I would be curious to know who charges the higher interest on poor punters Next on it's store card or Ramsdens on it's loans ?
Cheers again Graham.
Hi Paul,
Concerning your comments on bid and offer spreads in the market. I agree with you that market makers often do their best to trick punters,an example today was in QTX the bid and offer spread on level 2 was showing as 362 bid and 367 offered ,the bid size was 2500. I rang my broker and asked what the RSP was and he told me that there were 2500 offered at 362. (and in fact my guess was that the real offer was at 360 which is where it is offered now). I would say that the initial market price was false and designed to encourage punters (investors if you prefer) to overpay.
Cheers Graham.
Hi GrahamFraser,
Absolutely. I can also give another example today of the Market Maker quoted prices, and actual prices, being wildly misleading.
Altitude (LON:ALT) shares have been sliding, so I was considering a top-up (only a small, speculative position).
The quoted Bid-Offer price was 50p/56p. Anyway, I asked my broker for the real prices, and he said that Winterfloods were actually bidding 54.5p for 100k shares! Yet that bid was completely invisible to private investors.
Anyway, on that basis, I took out the MM who was on the Offer at 56p, and he then came back with a refreshed price at 59p, having been caught napping!
This is another example of where the published prices are totally misleading!
I think we ought to campaign to have more transparent pricing, as the published quotes are simply not the truthful, real prices, quite often in MM prices. We need to get the LSE to ensure that the RSP prices are published too, so that market participants can see what the genuine prices are. That would actually help improve market liquidity too.
Maybe it's something ShareSoc could look into?
Regards, Paul.
Hi Paul,
I completely agree,there should be much more transparency. I am sure market makers make the majority of their profit from individuals who pay or sell at manipulated prices. The institutions have their own dealers who can demand to be told the real price. I can think of many examples. Though you are right occasionally it is possible to benefit.
You must be lucky with your broker mine says that because of SFA rules he is not allowed to give me any advice and that includes telling me whether he thinks the market maker is telling porky pies or not.
I think it is something that should be looked into, it must be possible to enforce transparency.
Regards, Graham.
I have a small holding in Premier Asset Management (LON:PAM) for the income potential and spent a bit of time going through the admission document (https://www.premierfunds.co.uk/corporate/Content/documents/Admissions-Document-October-2016.pdf). A few snippets that seem to suggest that they, at least for the time being, are doing well in a popular segment:
1) "Additionally, multi-asset, equity income and absolute return strategies have proven most popular recently as the best-selling retail sectors in seven of the last 10 years." (p. 22)
2) "The IA has identified multi-asset and income funds as long term beneficiaries of changes in the UK
pensions and retirement market and AUM invested in the multi-asset market in the UK has grown by
a CAGR of 20.2 per cent. over the past 10 years." (p. 17) FYI, 1.202^10 - 1 is 529%
3) "As at 30 June 2016 PAM was ranked tenth by AUM in the multi-asset sectors and the Directors believe PAM ranked second in terms of net sales of multi manager funds over the six months ended 30 June 2016." (p. 16). They seem to be attracting more than their fair share based on AUM (though multi-asset and multi manager not equal)
4) "AUM invested in multi-asset sectors has grown by a CAGR of 12.5 per cent. over the Historic Period
and PAM’s AUM has grown by a CAGR of 25.6 per cent. over the same period." (p. 22) The Historic Period is the three years ended 30 Sep 2013/14/15 and 9 months ended 30 Jun 16 over which period they grew 2x the market rate.
They don't have any distribution direct to consumer and virtually everything is sold through IFAs. Approx 20% (15 of 85 from memory) of their staff are focused on maintaining IFA relationships. They referenced continued net fee margin compression as virtually all new sales are "clean" share classes with lower fees but no trail commission (net fee margin 82.2 bps y/e Sep 13 to 73.1 bps 9 mos to Jun 16). In the recent past at least, EBITDA margins have expanded as overall cost increases lagged fee growth from increased AUM (23% y/e Sep 13 and 31% 9 mos to Jun 16).
As an addendum, it looks like Electra have sold out their remaining holding at 125p. The admission doc says that Electra would hold 8,523,109 shares on Admission and that precise number of shares traded at 125p at 16:49. So, they sold half their holding at 132p in the IPO and the remainder at 125p. Queripel still hold 33% and are subject to orderly market arrangements for a further 6 months.
"Yes, a previously reported here, I've already bought back into Next (LON:NXT) in my real portfolio.
In fact, it's currently my biggest long position, as I've geared up heavily on it."
Apologies for missing your previous report. Glad to hear you've bought back in, as I have also shiveringly dipped my investor's toe back in.
I wish you the best of luck, but I do feel trying to call the bottom is a risky game. In my experience the stocks that have performed better, have been ones with relative strength and trending. My best performing stock has been Trifast, which netted an 84% gain, that had been trending upwards after several good trading updates and a positive outlook. Somero plc is another company with bright trading prospects and positive momentum for example. Though understand the appeal in Next, especially with its attractive dividend yield and cash flows, I would not buy the share at the moment because the company share price is in a negative trend downwards. The outlook is not great either for the retail sector with inflationary growth expected to outpace consumer wage growth. I think this is pretty much reflected in the Next plc outlook for sales going forward.
Though I can completely understand the appeal in buying Next at it's attractive valuation, for me it is the case of how much could the share price drop under negative momentum? With future trading prospects looking bleaker at the moment, I can't see any significant reversal any time soon. In which case, the risk is that you buy into a falling knife. However all IMO and over the long run you could profit. For me it's just a case of I think there are better shares out there with better prospects for the future at the moment.
Regards,
Roque22x
On Touchstar (LON:TST) you say "This includes a cloud-based software system for airlines to sell food, drinks, etc, whilst airborne." which is a somewhat startling image! Does that make it a blue sky stock?
Hi FREng
I'd have thought cloud & blue sky were mutually exclusive, but it could still be a high flyer.
I think it makes it an absolute nonsense stock. Unless they have a robot to deliver the food, they still need staff in the aisle. So it's just as easy to verbally order & pay the staff with cash or card.
Having the staff use touch screens will just slow the whole operation down. If slow service is the result, then it's another reason to avoid BA.
My guess is that Touchstar on BA etc is less a customer-service app, more a staff-control app – one that lets the company keep an eye on stock levels and ensure attendants don't hand out too many packets of peanuts. All of BA's moves recently have been like this – can't have the customers too much of a good deal, can we?
Display ordering is the kind of system that really only works with seat-back displays (Virgin America does this) - as it saves having the attendants roam the aisles.
But even then it's clunky. It can take an age for the staff to pull the stock item out and deliver it - possibly because the software lets them pack a lot of different goods into a small space with everything IDed by code - but they have to get to the right bit of the box first.
Regarding Victoria (LON:VCP)
I don't have a holding in this but I am long in Headlam (LON:HEAD) who are also in the floor coverings business. Both seem to be doing very well. Headlam are also growing by acquisition but are solely focused on distribution I think whereas Victoria seem to be more vertically integrated.
I'm not sure how many good acquisitions there are out there that these two can make. Surely growth from acquisitions must come to a halt at some point. But perhaps it is such a fragmented industry that this trend can continue for a while yet.
Hi Graham,
Re acquisitions, and Victoria (LON:VCP) - yes, I believe the market is quite fragmented.
The Chairman explained to me that the beauty of acquisitions in the carpet sector, is that businesses are often family-owned, and run very conservatively. What this means is that they often have considerable surplus working capital.
So Victoria can acquire such businesses, and then introduce measures to reduce excessive inventories, speed up production to sales cycles, reduce raw materials costs through group buying, make production more efficient, etc. So very real synergies, and acquisitions can be part-funded from releasing unnecessarily high working capital - e.g. tightening up on debtor collections, reducing inventories, etc.
It seems a remarkably effective strategy. I keep wondering what the catch is, but if there is a catch, I can't find it!
Regards, Paul.
Paul,
Given your very positive appraisal of Next, do you intend buying back in? Regards, Clive
Hi Clive,
Yes, a previously reported here, I've already bought back into Next (LON:NXT) in my real portfolio.
In fact, it's currently my biggest long position, as I've geared up heavily on it.
I can't use gearing in my fantasy portfolio, so for the time being have not put any into BMUS, because there's nothing in there that I want to sell.
Regards, Paul.
This is a good article on the pressures facing high street stores, even if it is about the U.S., as I can see the same forces at work here in the U.K. too: https://www.theatlantic.com/business/archive/2017/04/retail-meltdown-of-2017/522384/
In a nutshell investors might well be better off sticking with companies like Patisserie Holdings (LON:CAKE), Revolution Bars (LON:RBG) and Boohoo.Com (LON:BOO) rather than participate in the slow decline of bricks and mortar shopping.
Yet JD Sports Fashion (LON:JD.) profits are up over 80%. Reading that article it says clothes shopping is down and travel is up. I think there is a sift away from buying clothes etc and spending more on other activities.
Re Next (LON:NXT): The Directory business is now more profitable than the stores, so it's effectively a growing, internet-based business. Yet strangely, the market is ignoring this, and treating the entire business as if it's a declining, old economy business.
This reminds me very much of WH Smith (LON:SMWH) which has been successfully refocusing from the high street to travel outlets but all people seem to talk about is the declining high street.
Hi Paul, JD Sports Fashion (LON:JD.) final results are out today and maybe provide an interesting contrast to NXT's guidance. Sales, Gross Margin, EPS and like-for-likes all up significantly. Outlook statement is rosy despite there being no major summer sports tournament this FY. Seems to be displaying a 'Minervini' tendancy.
JD Sports Fashion (LON:JD.) results are excellent but the outlook did not sound so rosy, with inflation and currency headwinds: "The weakening of sterling against the US dollar after the Brexit vote will cause some headwinds on margin in 2017, he conceded, but the business is "in a reasonable position to mitigate against these" by working with its brand 'partners'."
Hello Mike,
Absolutely - JD Sports Fashion (LON:JD.) is a stock I've commented favourably about here a few months ago.
Smashing results out today from the company, as you point out. I won't cover the figures today though, but I agree it does look like a Minervini stock.
Regards, Paul.
Despite JD Sports Fashion (LON:JD.) doing extremely well, I do worry about its business model.
How sustainable is the demand for fashion sportswear? It's not really aspirational is it, to go around in a tracksuit & trainers, looking like a chav?! So sustainability of demand is one thing.
The other thing is sustainability of high margins from supply arrangements. As far as I'm aware, JD is mainly selling third party branded products. The problem with that, is you don't control the supply chain. There could come a point where, having maximised sales through JD, the brands then decide to squeeze on margins - i.e. take more of the profit for themselves. And/or sell direct to customers via the internet, and take all the profit for themselves. That's a potentially precarious situation to be in.
Personally I prefer anything fashion retail related to be own brands (e.g. Boohoo.Com (LON:BOO) ). That results in the highest possible margins, but most importantly no dependence on third party brands, who can cease supply arrangements on a whim.
So, amazing though it has been, I'm a bit wary of JD now.
Regards, Paul.
Hi Paul,
I guess most of us on here are more likely to be found shopping in Next than JD Sports. But to what extent, if any, should that impact our investment decisions? I wish I had overcome my prejudice and bought into JD sooner. When the charts looks like JD's and Next do, is it really better to buy Next?
I hope both are good investments - there's certainly a case for both but my money is staying with JD until I see signs of the sustained recovery in Next. Perhaps it's just a matter of timing as I'm never happy trying to call the bottom.
Hi Paul,
Though I understand your concerns over the business model, I think this company still has further to go. As many have already pointed out, this a classic Minnervini stock, with it's share price trading well above its 50, 150 and 200 day moving averages. This company also seems to consistently beat market expectations.
Though Brexit uncertainty and inflation is a concern for the company, I would point out that the company has grown revenues in Europe by 67.6% and The Rest of the World by 203.7% in this financial year. Add to that their latest acquisition of Go Outdoors business and strong net cash position of 213.6m, leaves the company well placed for future growth. IMO this a company that is a hugely attractive investment, that is a market leader in it's sector.
Regards,
Roque22x
Hi Mike
Regarding JD Sports Fashion (LON:JD.)
"Outlook statement is rosy despite there being no major summer sports tournament this FY"
There is the World Athletics Championships in London. Not an Olympics, Football or Rugby world cup I grant you but still a pretty important event I would think.
I stand corrected Graham, although might not have a major following among the 'Athleisure' brigade.
Best,
Mike.
JD is benefitting from the "athleisure" trend. I think of it as a fashion retailer as much as a sports shop.
Another happy holding that I only bought into as a result of this column!
Agreed on JD Sports Fashion (LON:JD.) being a Minervini stock. From what I can see, it also meets his Trend Template criteria (Above 50/150/200 day moving averages etc).
Anybody else here attending Minervini's webinar on the 18th?
Hi Ricky, can you post a link to the Minervini webinar you mention? Very interested to join that.
Many thanks,
Mike.
Hi Mike,
I found a link here for the Minervini webinar and have registered. It's at 16.30 Eastern US time on the 18th.
https://stocktwits.com/markminervini
Hi Mike
Here's the link for the webinar that is on Mark Minervini's twitter feed.
https://mpa.omnovia.com/registration/pid=32531490884595
Regards, Ricky
Many thanks Ricky, all signed up!
Best,
Mike.