Small Cap Value Report (Tue 11 June 2024) - BPM, OMG. Brief: RPI, OXIG, NCYT, GBG, IDOX, IOM, ECK, CBOX, VNET

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
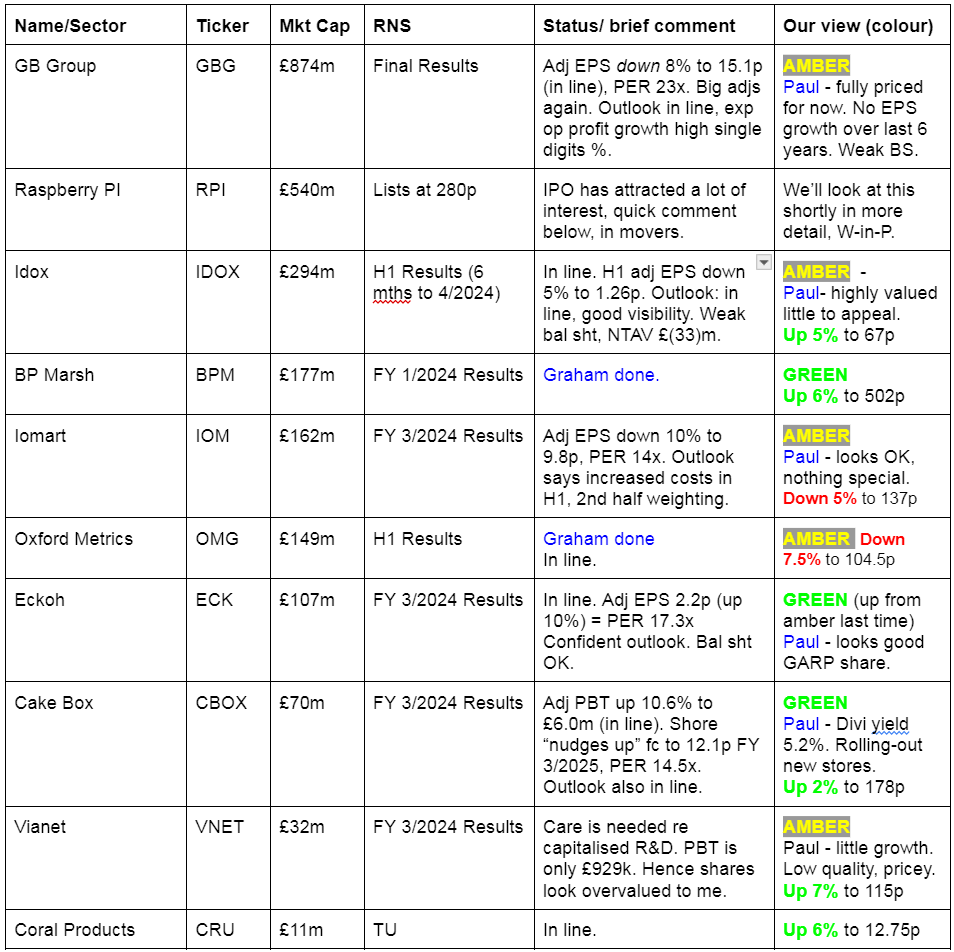
Companies Reporting
Other mid-morning movers (with news)
Raspberry PI (RPI) - up 34% to 375p (£724m) - IPO dealings commence -
It’s great to see an interesting company IPO on the London market. My view is that many of the problems in the London market have actually been caused by brokers floating overpriced junk, especially in 2021, killing off investor appetite for new issues. They killed the golden goose, chasing after fees, and it’s taken several years for that damage to be digested. Let’s hope RPI is the start of a new era of better quality, more credible UK floats. I started to review the prospectus last night, so we’ll get something up about it, maybe tomorrow.
In the meantime, in the first half hour of trading, RPI shares have gone to a lovely 34% premium - the float price was 280p, and it’s currently (08:35) at 375p. An excellent start! No colour yet, as I haven’t properly researched it yet.
Oxford Instruments (LON:OXIG) - up 9% to 2,685p (£1.55bn) - positive market reaction to FY 3/2024 results, which don’t look particularly exciting to me, with adj EPS down 3% to 109p (in line with expectations), a PER of nearly 25x, which looks a punchy rating. Outlook -
“Given our strong order book and pipeline, coupled with positive business improvement actions, we expect to make good constant currency progress in the full year ending March 2025."
Decent balance sheet, includes £84m net cash (excluding lease liabilities). A small acquisition is also announced.
Novacyt SA (LON:NCYT) - down 12% to 61.4p (£43m) - settles out of court its legal dispute with the Dept Health in UK (DHSC). NCYT will pay £5m to DHSC, without any admission of liability or wrongdoing. Strange, because on 21/4/2024 Novacyt told the market that DHSC’s case against it was weak, and it expected it to be thrown out.
Summaries
B.P. Marsh & Partners (LON:BPM) - Final Results - up 6% to 502p - Graham - GREEN
We already had a full-year update from BPM, but today’s announcement provides additional commentary on the excellent performance in FY Jan 2024. We also learn that this cash-rich company is launching a £1m share buyback and is willing to buy its shares at only a 15%+ discount to NAV (previously 20%+).
Oxford Metrics (LON:OMG) - Interim Results - down 8% to 104.2p (£137m) - Graham - AMBER
These are fine results in the sense that the company is on track to meet full-year expectations with a high degree of revenue visibility and excitement around its future plans. However, personally I’m disappointed with the fast rate of decline of the cash pile. Overall, the financial performance seems lacking to me.
Graham's Section
B.P. Marsh & Partners (LON:BPM)
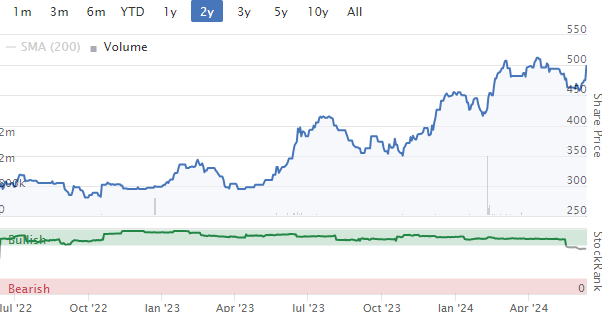
Final Results - up 6% to 502p - Graham - GREEN
B.P. Marsh & Partners Plc (AIM: BPM), the specialist private equity investor in early stage financial services businesses, announces its audited Group Final Results for the year ended 31 January 2024.
I’ve been positive on this one for some time, e.g. in February when they published their full-year trading update.
At the time of that update, I covered the full-year performance (to Jan 24) in some detail. Here are the key bullet points we need to know:
PBT £43.6m (previous year: £27.6m)
NAV £229m (previous year: £189.5m)
Three new equity investments made during the year.
Since the new financial year began, BPM has made one new investment (and two follow-on investments).
BPM’s main problem has been what to do with all the cash it has been receiving.
£51m was received for a major disposal last year.
Another major disposal was announced in December 2023 (“Paladin”). This deal completed in the new financial year for an upfront payment of £42m.
In January, BPM released an RNS titled “Use of Proceeds of Sale and Strategy Confirmation”, in which they announced that £4m would be paid in dividends to shareholders every year for the next three years. After setting aside money for this purpose, they would still have £74.5m (!) for use in developing their investment portfolio.
Let’s turn back to today’s full-year results statement and see what management has to say.
Chairman Brian Marsh is as enthusiastic as ever about investment prospects::
"From inception over 30 years ago our investment philosophy has been consistent and continues to deliver strong returns. This latest increase in NAV is testament to our strategy, enabling the Company to continue to invest in high quality management teams as well as rewarding shareholders.
"Looking across our portfolio and the new opportunities we see, I am confident that B.P. Marsh remains the partner of choice for exciting start-up insurance intermediaries, which will drive further growth in the future."
Buyback policy:
The Group remains committed to its Share Buy-Back Policy of being able to purchase shares when able to. Following the strong Share Price Performance the Group has agreed to amend its Share Buy-Back Policy to reduce the discount to Net Asset Value threshold from 20% to 15% and has allocated up to £1m in the aggregate for this purpose.
In a separate RNS today, the company does announce a £1m share buyback, “subject to Ordinary Shares being available to purchase at a price representing a discount of at least 15% to the most recently announced diluted NAV per share prevailing at the time of repurchase.”
The most recently announced NAV per share is 629p, and a 15% discount to this is 534.65p. Therefore even after this morning’s increase in the share price, the company will be able to buy back its shares.
Investment activity (since year-end)
March 2024: 30% stake in Devonshire UW Limited and loan funding.
May 2024: existing 25% stake increased with a further 7% in Pantheon Specialty
Comments by Chief Investment Officer:
The insurance market is consolidating, giving rise to opportunities: “Both the Group and its portfolio companies continue to be approached by entrepreneurial individuals and teams who do not wish to be part of this consolidation process.”
Insurance rates are rising more slowly (1%-3%), due to market capacity increasing: “Overall, whilst the market is softening, the Group does not see the market returning to the pricing of the last soft market in the short to medium term. Given the portfolio predominantly operates in specialist risk areas, rates tend to be less volatile and therefore we remain confident that our portfolio is suitably prepared to weather a softening market.”
Graham’s view
No reason to change my positive view on this one. Besides the long and enviable track record of investment success, the valuation here remains attractive to me.
The company clearly thinks the same as it embarks on further buybacks. Note that the shares aren’t too liquid: Brian Marsh himself owns 38% of the company:

Checking the very useful Director Dealings tool, I see that Mr. Marsh (age 81) sold over 900,000 shares in Feb 2024. However, checking the details, I see that it was his charitable trust that sold the shares, not he personally. So I wouldn't read too much into that.
With a stable management team, a fine track record of investment success, a discount to NAV, and a clear plan to buy back shares at a discount to that NAV, I feel obliged to keep giving this one the thumbs up.
Oxford Metrics (LON:OMG)
Interim Results - down 8% to 104.2p (£137m) - Graham - AMBER
Oxford Metrics plc (LSE: OMG), the smart sensing and software company, servicing life sciences, entertainment and engineering markets, announces unaudited interim results for the six months ended 31 March 2024.
The headline here is “on track first half revenues, driven by strong execution”.
Despite being “on track” in terms of revenues, profits have gone into reverse:

Estimates: checking the estimates from Progressive Research this morning, I find that they have made no change to forecasts, and indeed they say that OMG are “well set to meet expectations”.
These expectations include adj. PBT of £7.9m for the current year. It’s hard to argue against that with £4.0m already in the bag in H1.
Revenues are up 10.5% but with huge divergence in different business lines, e.g. Life Sciences revenues were up 38% (to £8m) while Entertainment revenues were down 22.8% (to £8.5m), due to “the global games industry contraction”.
Net cash falls by nearly £9m to £54.8m.This is thanks to £3.6m in dividend payments and a £6.2m acquisition.
Additionally, according to the commentary, cash was “deployed for working capital purposes to augment inventory and underpin second half performance”.
Checking the cash flow statement, I see that there was a £1.5m drag from increased inventories.
Against that, the positive net cash flow from operations was £2.2m. That’s a better figure than last year but it doesn’t inspire me, especially considering that the company had other factors pulling on its cash pile even beyond those I’ve already mentioned (£1m in capex and £1.4m of spending on intangibles - these alone would be sufficient to wipe out the operating cash flow).
So it seems like a poor cash flow performance to me. Checking briefly the figures from the previous financial year (FY Sep 2023), I must say I’m a bit concerned about OMG’s free cash flow numbers.
Stockopedia’s calculations will back up what I'm saying here:

Management - the company has a new CEO (since Oct 2023, previously at the company’s main operating business Vicon) and a CFO who begins next month.
CEO comment:
"Now over halfway into delivering our five-year plan, our teams are in full execution mode..
Our recent acquisition of Industrial Vision Systems has been a successful move, it's performing well and we are excited about the opportunity to drive yet more applications into the smart manufacturing space…
As Vicon works towards commercialising markerless, which enables 3D motion capture without the need to wear motion capture suits or markers, we are working with seven cornerstone customers to make the product the gold standard.
Looking ahead, Oxford Metrics enters the second half with >90% visibility of full year revenues and with a growing pipeline, the Board believes the Group is well placed to deliver results in line with current market expectations."
The outlook statement repeats many of the above points.
Graham’s view
I want to like this stock, as it’s a cash-rich scientific business with a long track record of profitability.
However, there are a few points holding me back:
Weak free cash flow performance after capex and development spending.
Moderate revenue growth and falling profits.
A completely new management team always brings some uncertainty.
For what it’s worth, the new CFO was a Finance Director at Sprue Aegis Safety Products from 2010 before becoming CFO of FireAngel (the new name for Sprue Aegis plc) in 2019. Sprue Aegis and FireAngel are names that investors are unlikely to remember fondly.
Above all, the answer to the question of what OMG plans to do with its cash pile seems to be: a) spend it on acquisitions, b) spend it on internal capex/development spending, c) drip out the rest of it in dividends.
I’m not seeing enough here to take a positive stance, so I’m staying neutral.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Vianet (LON:VNET) Prelims – Been out of digital reach in a meadow in Somerset (entirely by choice). Now catching up – and to be honest it takes me quite a while to ponder. So late to the party again! Not that there seems to have been much celebrating for Vianet (LON:VNET) recently?
The view in this place seems very downbeat? On that basis I’d see an amber rating as quite an achievement? Never mind, as a contrarian I’m entirely used to it. Indeed I’m continually searching for growth companies hiding in plain sight – and for that to happen there has to be a downbeat narrative?
I shan’t be arguing with Pauls excellent short summary. It sets out the history very well. I’m not so sure it sets out the future though, and there we are all entitled to our opinions, as none of us know what the future holds.
There are a few things in the results and the past year that point to there being quite a turnaround underway?
Revenue: £15.2m is still £1.1m below the FY20 (year to march pre-pandemic) £16.3
Profit: barely off the ground at £0.8m compared with £2.43m in FY20
So far, so nothing special, however
Gross margin: is high and at 69% in FY24 is 1% above FY20 at 68%
Operating cashflow (pre wc) at £3.929m is also above FY20 £3.722m
Higher gross margin and higher operating cashflow on lower revenue can be an indicator of a more profitable company with operating leverage will occur as revenues rise. If they do!
Recurring Revenue: 85% in FY24 is below both FY23 88% and FY20 92%
Is there a reason for this? I think so – the non-recurring sales relate to the installation of new connections to sites and machines after which they become recurring revenue. Provided that absolute recurring revenue is still rising – which it did marginally to £12.94m in FY24 – then the reduction in % recurring revenue indicates an increase in new connections feeding growth in FY25.
As well as increasing connections the profit per site and device grew in FY24 as customers make more use of the connections - particularly for contactless payment services.
The elephant in the room is the capitalisation of R&D costs. With FY24 amortisation at £2.164m it’s highly significant. Close to wiping out the statutory profit. The obvious concern is that the capitalised costs may be operational rather than capital costs. A way of propping up apparent performance at EBITDA level. The question does not arise if development costs are expensed as they arise. Though its not clear to me why this is a concern in this case and VNET may not have much choice in the matter. My understanding is that significant tax rebates and reliefs are available but only for R&D that is eligible. And only if capitalised. In FY24 HMRC paid a rebate of >900k and the company claimed R&D tax relief of >800k. The high level of rebates and reliefs indicate that HMRC is satisfied that the R&D is real and eligible – though thats not an indicator of future success unfortunately.
Recent products and trials underway include:
Management has stated that R&D spend has peaked – FY24 capitalisation of development is £1.24m significantly below the FY24 amortisation charge. Management indicates a likely eventual reduction to £1.5m (though to be frank with the recent acquisition of the inventory management platform - I see more development is likely in the short term)
Debt reduction: Despite development spend, cost of changing finance facility, costs of BMI acquisition and integrating the US teams, limited share buy-backs and paying a dividend there was enough cash to pay down net debt by around 50% or £1.78m (partly due to the HMRC rebated cash).
Valuation and FY25 outlook:
I agree that the shares are not cheap at 115p. They were a lot cheaper when I last bought, but arguably now they are backed by improving numbers there is less downside risk? The prelims are vague (as ever) on FY25 numbers, forecasts are for 13% increase in revenue to £17.1m and profit rising by 230% to 6.2p which puts the shares on 18.5x current year profits.
Not expensive if you view it as a software and service company with strong growth – but very expensive if you regard it as a cashcow in decline with the new products unlikely to generate real growth. Only the future will determine which it turns out to be?
Worth noting that the FY24 in-line results were softly upgraded by brokers Cavendish after the April24 update. Historically management have been too quick to promise growth and then underdelivered. Though in recent years they are hardly alone! Nevertheless we may have entered a soft-upgrade cycle in which management remains upbeat whilst brokers quietly raise forecasts on new contract announcement or after the interims?
According to management (on the recent IMC presentation) there is enough growth within existing customers (land and expand) to satisfy the FY25 forecasts – without new large contracts. The company aims to demonstrate that the Vianet platform recovers the cost of installation for customers within 3 – 6 months – through reducing wastage, stock leakage, increasing quality, improved service levels and stock availability across estates - and thereafter customers save more by adding further sites or machines to the system. Which means that large new contracts, specifically the forecourt car-wash rollout, and the US BMI platform are not included in current forecasts.
Management. Management is a big issue for me. I have to agree that I find it hard to warm to the longtime executive chairman/CEO (and largest shareholder) and the CFO. On the other hand I don’t have to like them but competence at managing their team with integrity is important. They appear to be straight talking – but not smooth or friendly. Maybe its a County Durham thing? They do appear to have recently put in place a complete senior management team (see https://vianetplc.com/about/ ), a good step in preparation for significant growth. In the past I have fallen for too many smooth-talking CEO’s – so I’m cautious and sceptical, don’t see any red flags and willing to give them a little rope.
Management Sharedealing: I like founder and owner managed businesses as long term investments. In addition to longterm buying by James Dickson (17.9%) the largest shareholder, Stella Panu, recently appointed NED with extensive tech experience, bought 310k shares at a cost of £216k over 18 months.
My opinion? After the recent strong shareprice performance I’m somewhat surprised to find Vianet (LON:VNET) is my second largest holding. The shareprice is up with current events – but at the moment I have no intention of selling. It seems to me that the company now has the right products in the right sectors with considerable market opportunities. Will they capture the growth? On current performance I think it’s very likely that they will meet forecasts for FY25 – but it’s the potential upside that I am after - more rapid expansion - now that the company is operating as an increasing SaaS business. In which case the current price will start to look cheap in 1 to 2 years. Nothing is guaranteed, but I do prefer a growth opportunity hiding in plain-sight, profitable, cashflow generative with operational leverage to those that have to come back to the market for more funds?
Analyst notes: Both Cavendish (house broker) and Capital Access have new notes out and freely available on Research Tree. The Cavendish note is particular thorough on the products, opportunities and new senior management team. Well worth a read if you are interested, or already invested.
Cheers
Mark
Novacyt SA (LON:NCYT) agree with Paul’s point re their statement regarding the legal case contradicting outcome, however think this is an issue for all plc’s on one hand you should report accrualty to the city but on the other you don’t want to show the people you are in a dispute with knowing the game plan of your court case./ action it must Be a bit of a conflict
i thought the saying was sell in may and go away
maybe it needs amending to June :(
Prune in June!
Paul, can I gently push back against your statement that “many of the problems in the London market have actually been caused by brokers floating overpriced junk, especially in 2021, killing off investor appetite for new issues”. I agree that plenty of overpriced junk was floated, but largely blame investors rather than brokers.
I’ll use a hypothetical to avoid upsetting anyone! Imagine I have a business with a concession to sell soft toys with Paris Olympics 2024 branding. Can I float that business? Yes. Certainly, it’s not illegal. I should flag in the risk section that demand for Olympics soft toys will almost certainly decline precipitously after the closing ceremony, that I have no other lines of business, and that I may well not be able to diversify into other lines of business. You might value my business at c. 1 x 2024 free cash flow to equity. But if investors want to pay 15 x 2024 earnings, that’s a matter for them. As long as the business is accurately described in the Prospectus, I don’t blame the broker for getting the best price for their client. Put another way, I don’t think a broker has a duty to calculate intrinsic value of a float and to pitch only on condition that the float price is at or not too much more than intrinsic value.
I’m delighted that Raspberry PI Holdings (LON:RPI) has floated successfully. I’m a customer and think the product is very good value, robust and reliable. I didn’t apply because trailing earnings seem to have been boosted by delays caused by component shortages and I’m cautious about the large increase in capitalised development spend (well ahead of amortisation) for what is a relatively mature platform. More fool me in the short term but if the SP subsequently falls for the reasons that put me off, that’s not the brokers’ fault because those points were obvious on the documents.
Impax Asset Management (LON:IPX) has slithered shy of 407p today - IMO bargain basement territory. Goes ex-div (4.7p) on 13th June too. 6%+ divie yield whilst you wait for int. rates to fall. I hold.
Impax Asset Management (LON:IPX) surprised this has fallen so much. Not sure it's all about interest rates though - enthusiasm for sustainable investments seems to have gone off the boil and they've seen weakening performance and large outflows recently.
CMC Markets (LON:CMCX) should have reported earnings today. How should it be interpreted that they didn't meet the set date?
"CMC is due to announce its FY 2024 results on 20 June 2024."
Yes after I posted I found that date in their previous results. Was confused as Stockopedia had the results as listed being published today.
I would suggest to follow the investors financial calendar of each company individually and on their own website in order to have a better and more precise view on particular events that may be of interest to you.
All the best
Tempting to open a spreadbet on Raspberry PI Holdings (LON:RPI) . Ride the momentum, though the sensible side of my brain is saying wait for any pull-back, as often happens with IPO's. Or maybe it won't...
History rhymes.
Plus this is not the only player in this space.
Paul,
Apologies if I have missed it, but did you post or can you post, a link to the spreadsheet of Phil Hansons' analysis of the various SCVR's?
Cheers
Hi Jeremy,
Sure the spreadsheet for measuring how the SCVR colour-coding has worked is here:
https://docs.google.com/spread...
It updates latest prices in real time, so the figures will change. Occasionally Google Sheets throws a wobbler and anomalies appear, so I can fix those manually if/when it happens again.
Regards, Paul.
Brilliant, thanks!
Flowtech Fluidpower (LON:FLO)
Just watched the AGM and admit to generally being impressed by the comments from CEO, Mike England on how the business is starting to come together. There was no update on trading but my impression is that the turn around is slowly starting to take shape. Whatever your views Mike England is certainly a man with a plan.
Just my view, but bear in mind that I have a reasonable holding and am not adverse to adding should the opportunity present itself.
Just to add that Flowtech Fluidpower (LON:FLO) streamed their AGM on IMC (as they did last year), included a CEO presentation and gave full answers to the investor questions. Other companies could usefully do the same.
Re Novacyt SA I'm hoping there's more to the agreed commercial settlement in Novacyt's favour than revealed in the RNS Paul.
Does anyone have any thoughts on why Bioventix continues to plummet? I can see that they missed their earnings forecast slightly but apart from that the business seems pretty steady and continues to grow. I don't currently hold but one of my triggers has gone off at <4000p. They clearly have R&D ongoing in some interesting spaces...
Bioventix (LON:BVXP) Well it's notched up a fraction this morning but share your concerns - especially as the CEO continues to sell down each year and of course Buffetology needs to also. Would help if they put out more news - the next scheduled is end October. On positive side - hope Stocko now upgrades Oxford Instruments (LON:OXIG) from its 'falling star' status. Hold both!
Does anyone have any thoughts on why Bioventix continues to plummet
Because it is, or at least was, overpriced. Companies with comparable margins and returns such as Auto Trader and Rightmove - with arguably clearer paths to continued growth and stronger moats - are, or at least have recently been, cheaper on FCF yield, which I find to be the best metric for comparison.
Comparing an on-line car trade website to a biotech diagnostic company with 10 year lead times on product development seems harsh. I would argue the moats for BVXP are MUCH higher. ONCE the antibody is fixed into a diagnostic you are not going to swap it out for a marginal saving. There are lots of new entrants vs Autotrader. I am curious though why Bioventix has risen so strongly and then fallen away in 6m on no news!
Comparing an on-line car trade website to a biotech diagnostic company with 10 year lead times on product development seems harsh
Not at all. It’s a compliment. Go through the numbers and you’ll see a striking resemblance.
RPI I'm interested in the prospectus. Anyone got a link?
OXIG Damn damn damn damn damn. I had that on my watchlist as an ISA top-up, but didn't buy. It did form part of my specimen portfolio that I put on Stocko at the end of March. OXIG itself is up 34% since I put it on. The portfolio overall is also exceeding my expectations.
Try this link for the Raspberry prospectus.
https://media-prod.ii.co.uk/s3...
OXIG Damn damn damn damn damn.
Well, the market seems to be waking up to the fact that this update wasn’t quite as strong as the response first thing seemed to indicate. I’ve been fortunate enough to have bought this one at the 2023 lows but I don’t see any value at all at today’s levels. A poor record of revenue growth and only 2ppts margin improvement in the medium term aspirations. FCF yield low and falling!
All that said, the products are first class and I’ll be first to admit I always find it challenging to understand the valuation on this stock. It’s not the high multiple that bothers me - I own plenty at double the PER - it’s the low growth. I think a potential bid premium always applies to this name. Still, I’ve made a good return, so hey-ho.
BnB if the Oxford Instruments (LON:OXIG) figures include writing off losses on repositioning their Far East business to allow for restrictions on what they can do in China perhaps there is a little more under the bonnet than first appears? Do we know the extent of any costs here?
Agree the PE always looks high here. Margins are good on one division. New CEO sounds like he's got a grip and will work on the other. And this seems like about the only company that has produced a 'Purpose' statement that really makes sense and inspires. IMO
Oxford Instruments (LON:OXIG) ( I hold). My initial reaction was the same as Paul's - results looked slightly disappointing to me. But having watched the results presentation, I was impressed by the new CEO, 20% strategy and 80% operational, which is my favoured split. He presented well and was ok too on the analyst questions. Already quite alot of change within the business.
I agree with BnB on the growth but it does tend to be somewhat uneven over the last few years and they did have to solve the China quantum computing export license problem. The inventory increases look ugly to me and could contain some future surprises, £27m increase on FY23, which in turn was an increase of £16m on FY22, which in turn was an increase of £7m on FY21. So inventory up 85% over 3 years while turnover is up just 48%. Each year the reason is presented as a one-off and turns out not to be a one-off. Of course with adjusted operating profit up by 41% over those 3 years, the return on capital is worsening dramatically, but still good.
That said, it's been a great investment for me, it is a very interesting area for the future, potential takeover target and with most of their earning overseas, it looks less exposed to a new government than some other businesses. So I will continue to hold and increase if the market falls.
Disappointed to get a miniscule allocation in Raspberry PI. Great to see strong support for the float though.
If you are happy with spread betting, I could open a long position earlier on CMC
Same with Spreadex
Yes, but you could only do this around 360p at the open and not 280p which was the float price.
Not a spread better but keep using CMC as I'm a holder of CMC Markets (LON:CMCX). Every Little Helps!
RPI
I admire your sang froid eParo, I’m livid, I got a 70th of my application and only found out when they’d been open for an hour . You can be sure as hell if they were down 30% I’d have got my full allotment! Heads you win, tails I lose!! When I applied HL said I’d be notified the day before and the shares would be showing in my a/c this am. But as you say a successful float, but then again that’s why I went for it!
I thought this was an interesting/worrying stat mentioned in a Deloitte blog yesterday:
'Schroders estimates that the number of companies listed on the main market of the London Stock Exchange fell by about 75% between the 1960s and 2022. Research by New Financial shows that since 2012 an average of 125 companies have left the UK stock market every year, mainly as a result of companies going private or acquisitions by overseas firms.'
Clearly there are multiple factors behind that. Perhaps higher interest rates increasing the cost of private debt might encourage a switch to more equity raises and listings especially as market conditions improve?
Here's the data from UK, US, Germany. UK obviously worst hit for multiple reasons as you say Tortoise. UK economy 2024 is completely different from 1960.
Private equity will no doubt look to offload many of the recent buy outs back onto the same fund managers who willingly accepted selling near the bottom. Probably for double or triple the price, when conditions are favourable.
It is part of a wider European malaise.
Theodor Weimer, who is the CEO of Deutsche Börse, said Germany is becoming a “developing country” and described its stock market as “a junk shop”. He blames the malaise on a “lack of leadership” from Chancellor Olaf Scholz’s coalition for deterring international investors. I think the emergence of the AfD as a major political force will not exactly encourage foreign investors,
The US market is held up by seven tech stocks, and increasing just NVDIA and the French stocks market is a war zone if you strip out the big French luxury stocks like LVMH and Hermès, and even they are suffering because so much of their business is in China.
The UK is actually doing quite well (relatively).
I was reading an article the other day (which alas I have deleted) that was lamenting the state of the US market, of all thing. Private equity had been gobbling up firms over there, too. Their RUT (Russell 2000) contains about 30-40% companies that don't make a profit. This figure has crept up over a 20 year period.
I personally am leery of Private Equity. They suck value out through fees, and have a nasty habit of loading companies up with debt.
I don't know what's to be done about it. I want quality solutions, not things proposed like split voting shares or Private Equity lobbing junk over the wall into the public markets.
I have worked in a firm taken over by PE. There is nothing good about PE for society broadly.
I agree. PE business model = strip assets; load the rump with debt; a few years later float and sell to mug retail investors. Rinse and repeat. This is why Buffett called it a fraud. It is.
That’s actually not really fair. To lump the entire PE industry together as one unscrupulous player is not a valid or scientific comparison.
There are definitely some unscrupulous firms out there who do exactly that but there are also a number of very responsible ones. You probably don’t hear about them because they are not the ones stripping assets and loading with debt.
You’d be surprised at how many PE sales as well as purchases are actually done privately. I know a number of PE firms who manage their portfolios very well and conscientiously and add long term value creation. And not to forget that they also offer a very valuable (and sometimes only) source of capital to market participants that would otherwise likely not exist, the absence of which would impact economic growth in the countries they operate in.
Right now PE firms will pay more for assets than the public market because they have a more sophisticated and long term view of value creation. They can ride out short term volatility that our public markets have proved incapable of doing.
David,
it would be interesting to hear about which PE firms you consider to be 'very responsible ones' I don't have a good opinion on PE too but am willing to research the ones you mention.
Many thanks
I have my eye on Literacy Capital (LON:BOOK) BO
Its really an investment trust taking a PE approach.
With PE I feel there is a general distinction between "financial engineers" and those providing capital to small companies.
BP Marsh is a good example and topical example.
KKR & Co (NYQ:KKR) has just joined the S&P 500 Index (SP:SPX) the other day and is on a tear.Apparently they're planning on running a part of their funds basically trying to copy Buffett's style niw, making use of their large insurance business float too, and running the better metric companies for longer trying to compound winners and even receiving regular dividends.Private credit's the hot market right now though and Apollo Global Management (NYQ:APO) is a big player there i think. stepping in with a large balance sheet where the banks only compete to do so when rates are low and money is cheap.Their ceo Marc Rowan turns up everywhere on financial media nowadays.
If you can, could you give us your views on Vianet ? It has been a strong performer and seems to be under most people's radar.
'Vianet Group PLC is a provider of actionable management information and business insight created by combining data from the smart Internet of Things solutions and external information sources. Smart Zones include Data insight and actionable data services as well as design, product development, sale and rental of fluid monitoring equipment. '
My view is that if they could explain what this lot means in English, they might attract more attention...The recent trading update reads as if they'd swallowed a dictionary. big words and jargon do not equal effective communication.........
But thank you for highlighting them
Vianet (LON:VNET) What I have recently seen described as a word salad. Sums it up perfectly.
Hi markmac,
I have a fairly low opinion of Vianet (LON:VNET) - it's a small group that I've followed for many years. It promises growth, and exciting-sounding tech, but in reality it's a rag-tag of ordinary businesses that they've given fancy names to, involving the internet of things, etc.
The main cash cow is Brulines, which has been in slow decline for years, as more pubs close.
The other businesses have never really got anywhere, despite upbeat commentary every year.
As regards valuation, it's too expensive I think. Why? Because the adjusted, and EBITDA numbers are nonsense. If you scrutinise the figures, you'll see that the large amortisation charge is not related to goodwill. It's actually amortisation of capitalised internal development spending. Hence we need to look at the PBT figures to include all cash costs, and this is only £929k. Hence the market cap of £32m is much too high for a very ordinary collection of lowish quality businesses.
The balance sheet has improved, and is OK now, with a little debt. Also note VNET used to pay generous divis every year, but these stopped in covid, and have only returned at little more than 10% of the old level. So the once attractive yield has now gone. I don't rate management at all, having met them a few years ago (assuming it's the same team now?)
So I'm being generous marking it AMBER!
Regards, Paul.
Paul, why does today’s SCVR tag Greencoat UK Wind (LON:UKW) ?
I think I understand the reason for the UKW tag. When I try to add RPI to a watchlist, using the @ sign, it generates UKW. I'll report it.
One relies on the real wind blowing, the other in a sentimental wind. With our British weather of late would not relay on either.
Card Factory (LON:CARD)
Nice to see the CEO, Darcy Rymer-Willson spending £89,500 of his money, buying shares in the company last week.
A reasonably size purchase, 92,371 shares at a smidgeon under 97p.
Teleios and a soggy market continue to keep a cap on the shares.
Card Factory (LON:CARD) the purchase looks like a requirement to spend one third of his bonus on shares so wouldn't get too excited. Lack of director buys is actually one of the things that is holding me back a here (failure to reach out to retail investors is another concern).
Indeed. Under the terms he had to buy them because his current shareholding is so small!
My local Card Factory (LON:CARD) shop never looks busy enough to cover its overheads. Has anyone here calculated the number of customers per shop, at the typical purchase per customer that would be required to cover the cost of the shops?
Card Factory (LON:CARD)
Cheers Bouden54, I will check out the annual report for confirmation regarding director remuneration etc.
Regarding FREng feedback, I suspect that it is a matter of timing as to whether a shop is busy or not. So on the run up to Christmas, Valentines day, Mothering Sunday etc I would expect to see the shops busy, whereas at other times they might well appear quiet.
Not sure if Clinton Cards is still trading, but without wishing its demise, particularly with regard to employees, its decline removes a potential rival, so must be a positive for Card Factory.
Card Factory (LON:CARD)
Not sure if Clinton Cards is still trading, but without wishing its demise, particularly with regard to employees, its decline removes a potential rival, so must be a positive for Card Factory.
perhaps - perhaps not - perhaps the demise of clintons could lead to it being replaced by card factory wanabee - somewhat strange that clintons never changed their (failed?) business model to try and replicate what card obviously do well. Either way competition comes and goes and the company hasnt been without competition so i wouldnt be worried what other parties do unless there is suggestion they were really targetting Cards core customer base. I dont own at present but whilst it stays around 90p is near the top of my shopping list for a small holding when cash permits - retail is always so difficult not sure i would want over sized position here.
I passed the one in Exeter on Saturday twice, and it was rammed. Same in Honiton. I would recommend you have a read of their annual report which is extremely detailed and helpful. Card run a very tight ship and are without doubt an extremely efficient operation.
Oxford Metrics (LON:OMG) results in line so down 8% !! Suppose that’s par for the course nowadays
Revenue up 10% but profit down 17% doesn't seem great? Order book down from £22m to £3m doesnt inspire confidence either.
Oxford Metrics (LON:OMG) results in line so down 8% !! Suppose that’s par for the course nowadays
I think you have to look deeper than this. The numbers are not great and the commentary uninspiring. It seems they are intent on spending the cash in a new business area based on the acquisition of IVS which is outside of the companies main core competency. It’s still not clear when the new markerless technology will start making sales, or even whether it will work. The new CEO is unproven and there is a new CFO too. It may be it works out but it all adds to risk. I was particularly put off by the large increase in operating costs that reduced a near 70% gross margin down to a sub 10% operating margin. I feel there are better places to be invested currently. Just MHO.
OK thanks . Good points
Pinewood Technologies (LON:PINE) As well as buying the mother company Pendragon's dealerships etc. and forming a strategic partnership with the resultant Pinewood, Lithia Motors (NYQ:LAD) continue to build a stake in Pinewood with their most recent purchase taking them to 22.76% (Harwood also have over 7%)
The valuation of Pinewood might look a bit rich but Lithia don't seem to mind. Holding and watching with interest.
Any views on GBG Finals out there? Looks like they will meet expectations going forward and the ship is on course following the excess paid for Acuant. No further goodwill writedowns so in FY25 the operating loss will become a profit. Net debt is also reducing.
I note the long list of Director purchases at Vertu Motors (LON:VTU) yesterday … does anyone have any insights?
They are all linked to their LTIP - all the same volume at the same price. No significance apart from interesting that they all have the same LTIP plan by the looks of it - normally you'd expect the CEO to have the most, then CFO and then everyone else.
It doesn't seem very generous unless there are further purchases and this is just a tranche of the overall amount.
The Vertu Motors (LON:VTU) announcement does not relate to an LTIP. It reflects the vesting of an employee share save scheme that will have Ben open to all employees, hence the low, flat awards.
Apologies - I stand corrected - too much rushing around to read it carefully. SIP not LTIP.
Although only just listed on Stocko - Are these not the interesting Director trades?
OK, yes, makes sense - thank you.
AFC Energy (LON:AFC) lives to fight another day.
I don't know how people stay enthusiastic about that one tbh, still no commercially viable product, even after all these years of promising.
Punters love exciting technology they don't fully understand but sounds good.
Tiny position in Centrus Energy (ASQ:LEU) pushing the realms of nuclear fission/fusion (don't even know the difference).
Guilty as charged your honour.
AFC Energy (LON:AFC) I think literally the worst company on the whole market. How people are dumb enough to subscribe for these shares is beyond me.
OVERSubscribe even!
B.P. Marsh & Partners (LON:BPM)
Chomping set of figures here , they have possibly delivered their best ever year here so practically speaking multiple years efforts probably only resulting in booked nav increases now. In summary one should not be expect such outperformance to be repeated here anytime soon - I have always had this down as being much more of a plodder type company with the discount to nav and long term reasonable results modest returns making this a fun little niche hold. With nav up to 625p per share and shareprice at 480p the shares actually look very reasonable value still with 29% plus discount from nav - in some respects with this discount to nav a higher than planned level of share buybacks would make sense perhaps to me - anyway easy choice here for me to keep this solid company just ticking away in the background.
B.P. Marsh & Partners (LON:BPM) all looks very good, although still very limited dividends or share buybacks, even after the recent increase. Given the high levels of cash and wide discount I'd like to see more in the way of shareholder returns.
Been watching this company - for a while - What concerns me is the near 80% held by founders/institutions leaving only 20% in the market - and the point Bounden has made - minimal shareholder returns. The Boss simply cashes in a 'few' shares each year to top up his salary . So will watch the investormeetcompany webinar tomorrow with interest.
To be fair to them - the discount wasn't that wide until today: it had mostly been closed. And given the ROI they have been achieving up to this point, I am comfortable with them holding some cash - I assume it is earning a good rate of interest. Shareholders can always top-slice if they want to take some funds out. (I hold)
Renew Holdings (LON:RNWH) interesting bolt on in the field of electricity transmission and distribution following my previous comment on National Grid (LON:NG.) investment programme and more widely across the network.
My morning smallcap tweet: Don't cry for me, Stockopedia
Directa Plus (LON:DCTA) Novacyt SA (LON:NCYT) Cordel (LON:CRDL) Raspberry PI Holdings (LON:RPI), Coral Products (LON:CRU), Idox (LON:IDOX), Oxford Metrics (LON:OMG)
◄Directa Plus (DCTA)► £6.8m placing at 18p, a 9% discount, for Setcar acquisition, capex and capital for growth. [SP=20 Cap=13m]
◄Novacyt (NCYT)► settles case with Gov't, pays £5m, a fraction of the claim for faulty tests. [SP=69.21 Cap=58m]
◄Cordel (CRDL)► gets its I-powered Gauging File Production certified by Network Rail. The tech captures data from trains running at full speed in passenger service. [SP=4.34 Cap=9m]
◄Raspberry Pi (RPI)► lists today after IPO at 280p, a £540m cap. [SP=NA Cap=NA]
In line: CRU, IDOX, OMG
Morning All,
Decent finals from Cake Box Holdings (LON:CBOX) this morning,.
Profit and revenue growth, margin expansion, net cash increased and a nice final divi of 6.1p.
Will you be covering please?
Thanks
Morning JohnDoe2378,
I've had a quick look at the numbers from Cake Box Holdings (LON:CBOX) - it's very straightforward, so I've just put a quick comment with the key points in the list of companies reporting above. I might expand on it, but it's self-explanatory really.
Looks quite good, so I've stuck with GREEN as before.
Regards, Paul.