Small Cap Value Report (Tue 12 April 2022) - CLX, COG, AGFX, HRN, W7L, SUP

Good morning! Paul & Jack here with the SCVR for Tuesday. Today's report is now finished.
Agenda -
Jack's section:
Calnex Solutions (LON:CLX) - I hold - acquisition of iTrinegy, which provides testing for gaming, military, tech, and financial organisations including JPMorgan and Ubisoft. Calnex has a plan for scaling the business up and expects this new addition to contribute significantly to profits in the years ahead. Beyond that, the group says FY22 results should be ahead of expectations. Arguably reflected in the price though, so the key thing to consider is whether you’re comfortable with the valuation.
Argentex (LON:AGFX) - shares down this morning despite full year revenue growth of 23%. Presumably the group has not matched expectations, but the valuation is now quite modest and it’s possible the fall is overdone. If management can begin to impress the market, then there’s a rerating opportunity as the valuation discount to peers is now quite wide.
Hornby (LON:HRN) - looks like solid Q4 results for the owner of Hornby Trains, with full year sales and margins in line with budget. There are supply chain challenges though and, while there are some positive developments (namely a return to profitability), I’m mindful that turnarounds can often take longer than expected but there is potential upside, so it stays on the watchlist.
Paul's section:
Cambridge Cognition Holdings (LON:COG) (I hold) - as expected, strong revenue growth of +50% (organic) has moved the company into profit. A much larger order book gives really good visibility for 2022. Forecasts are set low, so it should beat expectations as 2022 develops. Plenty of cash on the balance sheet, so no need for any more dilution. COG is benefiting from long-term sector tailwinds. Hence this looks an attractive growth share, and shouldn't be impacted by macro issues.
Warpaint London (LON:W7L) - a sparkling trading update, with very strong Q1 performance across all channels. Broker upgrades today look too cautious, so I think this company now looks set up to continue out-performing. This year's indiscriminate selling looks to have created a nice buying opportunity, and you get paid to wait, with an attractive divi.
Supreme (LON:SUP) - a strong performance for FY 3/2022 is reported. Shares are down 18% today on a mild profit warning for FY 3/2023, due to higher costs (hardly surprising). Broker forecastfor FY 3/2023 is reduced by 8%, and a lovely yield of 4.7% is forecast. This share looks good value now, so I give it a thumbs up.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Cambridge Cognition Holdings (LON:COG) (I hold)
175p (yesterday’s close)
Market cap £55m
Cambridge Cognition Holdings plc, a technology company which develops and markets patient-focused solutions to better assess brain health, is pleased to announce its unaudited preliminary results for the year ended 31 December 2021.
Revenue - up very strongly (+50%) to £10.1m - this is a step change, as revenue was previously always in the £5-7m range over the last 10 years.
It shouldn’t be a one-off either, as the contracted order book has been growing strongly, ending the year at £17.0m (up from £11.2m a year earlier)
Excellent visibility, with at least £7.5m of the order book expected to turn into revenue in 2022.
Moved into profit for FY 12//2021, of £0.5m after tax (versus £(0.4)m loss in FT 12/2020), reflecting R&D tax credits. PBT was £0.3m.
Ahead of expectations, says the commentary from COG, at 1.4p EPS (the StockReport shows consensus forecast of 1.28p).
Outlook - upbeat, but no figures provided on current trading -
We made excellent progress in 2021, delivering strong growth in orders, revenues and cash generation, together with moving into profitability and earnings ahead of market expectations. Furthermore, with a strong contracted order book providing excellent visibility of revenue through 2022 and well-beyond, we expect the company is well placed for further success. There does remain some uncertainty due to COVID-19 and the wider impact of the war in Eastern Europe, though these are considered limited at this time.
We have set out three growth strategies to expand market share in current markets, automate more assessments as demand increases for virtual clinical trials and seeking corporate business development opportunities. Each of these represents exciting growth opportunities for Cambridge Cognition.
With this clear growth strategy, together with a substantial pipeline of opportunities in an expanding market, leading market position and strong balance sheet, we believe Cambridge Cognition is positioned to deliver substantial, sustainable shareholder value in 2022 and beyond.
"We are delighted to have delivered above-market growth and a profitable year of trading. The demand for digital outcomes assessments for clinical trials is forecast to continue to grow. With these tailwinds, we have evolved our strategy and plan further investment in developing digital biomarkers and corporate business development, as well as continuing with a focus on commercial execution. We believe we are well placed for more success in 2022 and beyond."
Balance sheet - adequate, with NTAV of £259k. There’s hardly anything in fixed assets, as it’s a knowledge-based company. Cash pile of £6.8m is healthy, and up from £3.0m a year earlier.
Receivables look high at £5.1m.
Current liabilities offset nearly all current assets, so COG seems to have a favourable working capital position - i.e. collecting in some cash up-front from customers.
Cashflow statement - amazing, there’s hardly anything in it! Strong cash generation in 2021.
My opinion - good progress, and profitable now. There’s a big order book, providing strong visibility.
The main thing with COG, and why I like this share, is that it’s benefiting from an industry tailwind, accelerated by the pandemic, to do cognitive testing (for drug development) via the internet, which is what COG specialises in. There’s little competition, and big barriers to entry.
How to value it? As it’s only just broken into profit, PER doesn’t make any sense at the moment.
I think we can safely anticipate increased future profits, Dowgate has issued a new forecast this morning (many thanks) raising 2022 profit guidance by 10%. It’s only showing modest revenue growth though, and profitability flat at £0.3m for 2022 & 2023, which seems way too conservative to me, so I’m expecting COG to be able to beat those numbers, hence out-perform trading updates should some through later in 2022.
.
.
Warpaint London (LON:W7L)
141p (up 13%, at 08:35)
Market cap £108m
Markets are incredibly tough for UK small caps right now, so W7L being up 13% this morning in reasonable volume, then this trading update must be good.
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, is pleased to announce an update on current trading ahead of the release of the Company's results for the year ended 31 December 2021 on Tuesday 26 April 2022.
Strong trading performance continues into Q1 2022
We already knew FY 12/2021 trading was good, as announced on 1 Feb 2022, so no surprises there.
Q1 2022 continued positive momentum - sales up 60% vs 2021 (all brands up). I thought this might be due to soft prior year comparatives, but that’s incorrect - the 2021 trading update at this time last year was good, I’ve just checked. Last year’s update is so similar to this year’s update, that I had to double-check I wasn’t accidentally reading the wrong one! A notable difference is that last year gave the cash position, which this year’s does not.
Gross margin in Q1 2022 is up on the FY 12/2021 gross margin, despite higher input costs and freight costs. This seems to show that W7L has decent pricing power, and is able to pass on cost increases - absolutely key in this time of higher inflation.
Tesco shops - sales doing well, more shops being added.
Boots - performing in line with Boots & W7L’s expectations.
Significant new contract with another major grocer has been won.
USA - growth.
Online sales in Q1 up 29% on LY, helped by launch in China, which is expected to make a “meaningful contribution” in future.
Webinar is at 17:30 on 26 April - details in the RNS.
Broker upgrades - thanks to both Shore, and Singers for updated notes today. I’m struggling with poor wifi on a train at the moment, making my way to Malta for a break, given how miserable things have been this year I felt I would benefit from a change of scene, and some warmer weather. Anyway, I’ve managed to download Shore’s note, which is only forecasting a modest rise in EPS from 7.0p in 2021, to 8.0p in 2022. Revenue growth is assumed to only be 12% in 2022, which seems very cautious given that Q1 actual is +60%.
Hence I think we can probably assume that EPS is likely to come in well ahead of 8.0p for 2022, with further upgrades likely as 2022 progresses. That’s a nice setup.
My opinion - this looks really good, I’m impressed.
I reckon 2022 EPS is likely to come in a good bit higher than forecast, maybe 10p+?
At 141p, the share price therefore looks reasonable, maybe even cheap.
You get decent divis while you wait too, with a yield of c.4%
This looks an attractive share, at a reasonable price. It gets a thumbs up from me.
Even in poor macro conditions, companies selling attractive products at sensible prices, can still do well.
.
CHART
Supreme (LON:SUP)
155p (down 18% at 11:25)
Market cap £181m
Supreme (AIM:SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer products, provides a trading update for the twelve months ended 31 March 2022.
Here are my notes on today’s trading update -
FY 3/2022 guidance provided today is: revenue >£130m, and adj. EBITDA >£21m (up 9% on LY [last year]).
A note from Equity Development helpfully translates EBITDA into proper profit (before tax) of £17.8m.
Strong performance in FY 3/2022, the company says.
Core business (vaping products) doing well, with 10% revenue growth, expected to continue. Gross margin up, due to manufacturing improvements.
Batteries & lighting division is doing OK, modest growth, but improved gross margins.
Sports nutrition - this is small, but rapidly growing, revenue growth of over 100%. A key ingredient (whey) has sharply risen in price, thus denting profits.
Outlook for FY 3/2023 - cautioning on higher costs, as I would expect right now, because we’re in a period of elevated inflation.
Looking at FY23, the Group is expecting to deliver another year of profitable growth and increasing levels of cash generation, predominantly driven by Supreme's strong Vaping sales footprint. However, this performance will be tempered by commodity price inflation within Sports Nutrition & Wellness and the increases in the overhead base relating to wage and transport costs.
Management has already taken steps to mitigate the external factors, including buying forward whey, and will also be continually reviewing potential price increases and ongoing manufacturing and distribution rationalisation.
The Group remains fully focused on driving organic growth, closely balanced with strategic acquisitions, having agreed a new £25 million RCF facility with HSBC in March 2022.
The Board remains confident that the Group will continue to deliver both organic and acquisition led growth this financial year and beyond.
ED has trimmed its forecast EBITDA for FY 3/2023 by 8%, to £22m. Hardly a disaster, providing this is not the first in a series of downgrades.
Forecast EPS is 12.2p for FY 3/2022 (PER 12.7), and
13.3p EPS for FY 3/2023 (PER 11.7)
That strikes me as very good value.
Particularly as the forecast divis are set to rise from 2.1p, to 7.3p, giving a forecast 4.7% yield at 155p per share. That’s attractive, and when I’ve analysed Supreme before, I concluded that the cashflows look impressive, and are real, not accounting chicanery. It’s made some bolt on acquisitions from internal cashflow too.
The history of the company is very interesting, and the owner/manager, Sandeep Chadha still owns 57%. He seems to be a natural entrepreneur with real flair for spotting lucrative markets to enter.
My opinion - I think today’s fall looks a good buying opportunity, if you like this company.
It is dependent on vaping, which means potential risk, if for example it’s found to be dangerous, and gets banned.
A mild profit warning due to higher costs is fine in the current environment I think, and doesn’t undermine the fundamental attractions of this share - especially the decent ongoing growth from the core vaping product, plus explosive growth in sports nutrition. Yes, input costs are higher, but that’s likely to be passed on to customers in due course.
I’ve no idea what the short-term share price will do, your guess is as good as mine. In terms of fundamentals though, I think this share looks attractive at 155p. It’s going on my list of possible purchases, where typically at the moment I’m dipping my toe in with a small initial purchase, then adding more if it keeps falling. Some people like to wait for the price to start rising before buying, which is perfectly rational, as it shows improving investor sentiment. Everyone’s got their own strategy, so obviously that’s up to you to decide.
Overall though, SUP gets a thumbs up from me.
.
Jack’s section
Calnex Solutions (LON:CLX)
Share price: 157.5p (pre-open)
Shares in issue: 87,500,000
Market cap: £137.8m
(I hold)
Trading update and acquisition
This is a provider of test and measurement solutions for the global telecommunications sector. It’s been a rather rare successful IPO, with the shares now trading at multiples of the float price.

The group has acquired iTrinegy, which is a ‘developer of Software Defined Test Networks technology for the software application and digital transformation testing market’, for £2.5m in cash. A further £1m is payable dependent on meeting financial targets. This acquisition should be earnings enhancing in FY23 and will be ‘an important contributor to Calnex Group profit in subsequent years.’
iTrinegy was founded in 2006 and has its HQ in Stevenage, and its Network Emulation platforms provide tech, financial, military, and gaming organisations with the ability to recreate real-world network test environments. That means the company’s clients can verify the performance of applications before deployment, reducing the risk and improving the quality of their operations. The client list has some impressive names, including JPMorgan Chase, Ubisoft Games, and the UK and US government and military.
Calnex also notes that iTrinegy’s NE-ONE platform is also applicable to the ‘rapidly growing’ cloud-based and virtual development and testing environments sub-sector, meaning the company should benefit as more enterprises migrate from on-premise hosted solutions to cloud-based hosting.
Calnex plans to scale the business up by using its sales and marketing capabilities to support and grow a reseller network, which should accelerate sales (particularly in the US). In the year to 30 September 2021, around 60% of iTrinegy’s £1.4m revenue was from North American customers.
Trading update - Calnex continues to experience high demand for its solutions. The component availability shortages flagged in the update on 1 March have so far been successfully managed, with all planned orders shipped. Therefore, results for FY22 should be slightly ahead of expectations.
The order book is building and sits at record levels.
Conclusion
You’re paying up for a quality operator here. This is currently the most ‘expensive’ share I hold, but there are attractive long-term growth prospects to back it up.

That doesn’t entirely negate short term valuation risk, so I wouldn’t be surprised to see the shares come down should the market mood deteriorate. Calnex is also not afraid to sacrifice some short term profit in order to invest in the more significant longer term opportunity - that could at some point disappoint the market if shareholders are expecting a straight line upwards, forever. Which sometimes seems to be the case.
But this is a fundamentally attractive enterprise with good trading momentum. From a factor profile, it’s a classic ‘High Flyer’:

There’s no comment on the net income of iTrinegy, but the c80% gross margin is attractive and the price/sales of 2.5x is well below Calnex’s own punchy 7.06x. The group appears to have a solid strategy for growing the business, which has some notable customers already.
It’s all going well here, which is reflected in the valuation, so beyond that it comes down to whether or not you think Calnex can become a substantially larger enterprise over the medium to long term.
Argentex (LON:AGFX)
Share price: 72.81p (-7.6%)
Shares in issue: 113,207,547
Market cap: £82.4m
Trading update for the year to 31 March 2022
Argentex provides foreign exchange services to institutions, corporates and high net worth private individuals. There’s a growth opportunity in this market, but Argentex’s performance has recently lagged some of its peers by some margin.

Revenue growth for the year of 23% to £34.5m has been driven mainly by targeted investment in strengthening its team, broadening its geographic reach, and taking more market share. Corporate clients have grown from 1,385 to 1,624 and Argentex also continues to invest in its technology proposition.
That sounds positive to me, but the shares are down by around 5% this morning, so people must have been hoping for more. I can’t see any research for the company, so if anyone has access feel free to shed light in the comments, as I suspect this is a case of sub-optimal market expectations management.
Underlying profit margins are ‘broadly’ in line with last year at 30.9% (it would be good to have more detail here), the Netherlands office has grown half-on-half, and the Australian operation is set to launch in the current financial year. A new technology-enabled trading and client service platform has also been launched, ‘the first in a suite of upcoming developments underpinned by a new technology strategy’. So there’s plenty going on that might drive organic growth.
New appointments - David Christie appointed as Chief Operating Officer and David Winney as Global Chief Compliance and Risk Officer.
And a brief comment on exposure to the Russia-Ukraine conflict:
Our portfolio is matched with blue-chip institutional counterparties and remains heavily weighted to major currencies, with over 83% allocated to GBP, EUR and USD. The Group has no direct currency exposure to the Russian Rouble and continues to closely monitor the wider potential impacts of the Russia / Ukraine crisis.
Conclusion
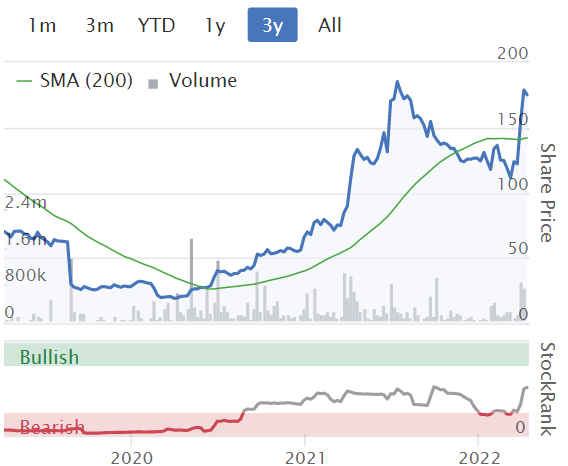
Argentex intends to grow its international operations, improve its technology, and invest in people. Revenue has been expanding, but the group’s share price chart shows a different story:

Relative performance lags that of Equals (LON:EQLS) and Alpha Fx (LON:AFX), but the shares also offer much better value. You can see the StockRank improving materially in the chart above as well, so from a purely quantitative perspective, there could be something worth digging into here.
If it can meet or surpass expectations and prove some momentum, then the shares could well rerate as there is a good growth opportunity facing these companies.

Setting and managing expectations is a peculiar confidence trick. More detail on profits, cash generation etc. would be welcome, but Argentex revenue is up 23% and the shares are down (and have now more than halved from the 2020 all-time high), with a single-digit forecast PER. That strikes me as harsh, but the company is not matching the kind of momentum shown by Alpha and Equals.
The Quality Rank of AGFX is 97, which is encouraging. There’s an interesting question here around which factor horse you’d rather back: Quality Value, or Quality Momentum?

Hornby (LON:HRN)
Share price: 34.99p (+6.03%)
Shares in issue: 166,927,838
Market cap: £58.4m
Trading update for Q4 to 31 March 2022
The share price has returned to a more realistic level after a brief spike upwards for this international models and collectibles group.

This is the owner of Scalextric and Hornby train sets, currently undergoing a deep turnaround with specialist investor Phoenix Asset Management on board as a majority shareholder. That means the free float is small and liquidity is poor, with a 606bps spread.

Group sales for the 4th quarter were very encouraging and ahead of the same period last year. As a result, cumulative group sales and margins for the financial year ended 31 March 2022 were in line with budget and ahead of the prior year. The Group will report a profit for the year having first returned to a position of profitability in the prior year.

However:
Managing supply chains continues to be challenging with extended shipping times from our partner factories and disruptions in UK deliveries into our warehouse due to a lack of drivers and fuel. Electronic components availability and lead times have also impacted our ability to increase sales further during the financial year ending 31 March 2022.
That’s an ongoing risk, but you could take it as a potential positive as well: if supply chains had been healthy, perhaps outperformance was on the cards.
Net cash of £3.9m, down from £4.7m in the previous quarter.
Conclusion
That’s it for now, more detail will be in the full year results announcement in June.
I’m genuinely curious about this situation, as there must be some value in leisure brands with such heritage, which appeal to hobbyists. There’s a surface comparison to be made with Games Workshop (LON:GAW) and its fantasy miniatures, although there is far less scope for world-building and intellectual property growth.
Previously, I’d considered the shares too expensive given where the group is in its turnaround, but now we’re back to nearly 1x sales. Turnarounds take time, so I continue to keep a watching brief here. There’s been a lot of equity dilution here, in order to finance the recovery. The hope is that these days are over now with a return to profitability.

Even now though, the share price factors in a degree of profit growth. And the world has moved on, in terms of toys and distractions. The group’s products don’t resonate with me personally, so I don’t have much of a feel for customer loyalty and stickiness. That’s important, because whether or not the shares represent good value depends on the potential scale of recovery.
One key point in the Games Workshop comparison is that Warhammer has a rich universe, virtually unparalleled, which can be licensed out to more modern media in order to retain relevance for younger generations.
I’ll stay on the sidelines for now, as other investors might have a far deeper understanding of this market and Hornby’s products than I do, so I doubt I have any kind of edge. The tightly held shares also suggest the price could move quite fast should the market’s perception change here, so it might never offer the kind of discount I would be looking for.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
For those interested Supreme (LON:SUP) are holding an investor presentation in respect of its recent trading update, next Friday 22 April at noon, hosted by Equity Development. It is free to register on the Equity Development website at:
News & Events - Equity Development
I suspect that the company was somewhat surprised by the market reaction to the update and wants to redress the balance. Anyway will shall see.
All the best
Cambridge Cognition (LON:COG).
Here is a link to a 5 minute interview today with Matthew Stork CEO.
It gives a quick idea of the present and future at COG.
Matthew demonstrates both the scientific knowledge and also commercial ability which is behind the company's recent success. Previous to his arrival the commercial acumen appeared to be lacking, as is the case in many such companies.
I hold
Traders Cafe with Zak Mir: Matthew Stork, CEO Cambridge Cognition - Vox Markets
Somero Enterprises Inc (LON:SOM) Looks cheap to me, so have bought some. Having previously worked in concrete laying and having been lucky enough to use Somero levelling machines in the past, I can't express enough the difference these machines make.
With health and safety playing more and more of a role in construction (construction still manages to kill a person, on average, each week, and kills more people than all of the UK armed forces put together in peace time!) this sort of kit will become the norm. I suspect that America is a key growth area for them, but just drive around and look at all these warehouses getting thrown up and gives you an idea of the scale of flooring going down.
As we move into robotic picking of goods, floor tolerances need to be that much tighter which again will point towards automated floor laying, and this type of kit.
I want to be careful with 'confirmation bias', but I have avoided to date as I have found them a bit pricey, but in my opinion looks good value now and wanted to give a personal view of the product to add to your own research.
Cheers
Paul.S
Hi Paul,
Thanks for that info, very useful.
I am also mulling buying some at this level...
Hello Paul,
I often think that the valuation of Somero is clouded by the thought of them using concrete whose production is a strong CO2 emitter. But think of the reduced emissions and health benefits which can be gained from using a flat floor.
It is a similar argument that miners face when they produce copper and battery metals, associated with lots of emissions, but which are then required for use in EV cars!
FWIW I topped up after the share price dropped to below £5.00 in anticipation of a big divi payout in June. Maybe then take take a small profit on a sale thereafter or hold on for more payouts!
SM
Does anyone know is there is an up to date resource for finding major company shareholdings? I know Stockopedia has this information but never sure where it is sourced & how up to date it is. Any pointers in the right direction very much appreciated! My interest was piqued by a few recent announcements.
Really looking for something that you can export (excel or .csv) and analyse, rather than going through each RNS individually!
I'm not aware of any reliable shortcut if you want 100% accuracy for corporate finance purposes where you can't afford to be wrong (or at least there wasn't a few years back, although some providers probably get close so I stand to be corrected) - even the Bloomberg register of major shareholders was often out of date or missed something.
Companys' website investor relations sections often also often lag behind. Only surefire method is to take the major shareholder list from the last set of published annual accounts and then modify for any RNS announcements since that date. Major shareholders >3% are obliged (by FCA handbook) to announce each time they cross a further integer 1% in either direction.
Again you need to differentiate between holders of voting shares and synthetic exposure via various derivatives such as total return swaps, not just CFDs. As Archegos demonstrated recently, it is possible to build up huge economic exposure without it being evident on the shareholder register.
Thanks a lot, that's helpful. Yes - I was struggling to find a clear/good source of information, was wondering if I had missed a trick. I ended up doing exactly what you recommended before even seeing you had commented!
Paul
Re Supreme (LON:SUP) , I am pretty certain the 2.1p dividend figure for the current year should be 6.1p. Supreme (LON:SUP) paid 2.2p for H1 and have committed to paying 50% of adjusted earnings in dividends, i.e. 6.1p of 12.2p.
I am just amazed Supreme (LON:SUP) don't talk more definitively about putting through price increases to maintain margins; they really should have done this already.
No I don't agree. Remember the board is playing with a number of operational units that are in varying degrees of maturity for the overall group. For example : The Sports science is growing very fast exceeding 100% YoY growth so management will need to consider whether they want to absorb any raw material cost increases in order to preserve growth or put through price rises that may have a slowing effect. They will inevitably need to work this through their medium term strategy in terms of sales, scale they want to achieve and margins.
The point being that management have a far better handle of price elasticity and the impacts on their growth strategy than we do, and it is clear from management commentary that it is not just as simple as increase prices and be damned.
Fair point David, well made. Always two sides to a debate.
Hi Shanklin
Good call on the dividend, Stockopedia and Sharepad show the dividend for the year to 31 March 2022 as 6.6p and 6.64p respectively, so 6.1p is in the ballpark, for a yield of about 4%. A consolation in the short term for today's share price battering. I also agree with your comments regarding price increases, still that and the market are outside my control. Just have to be patient, perhaps very, given the current sentiment, which is likely to prevail for sometime
Simoan, Please don't feel sorry for me, the small cap area is a small % of my portfolio 's & yes my expertise in small caps is limited which is one of the reasons i subscribe & respect Paul Scott & the teams views.I 've been investing for over30yrs now & have tilted to the more quality side of investments having read numerous Warren Buffett books & will give you one bit of advice if you are prepared to take your arrogant attitude to one side for a minute & say i don't need to know or have knowledge of individual stocks to be successful.Iwish you a successful future.
"Money does grow on trees"
They say eventually the golden lustre of parental knowledge disappears and this happened to me recently when I discovered after all these years discovered that my dad was totally full of shit .
When I was younger he repeatedly told me "listen sunshine money doesn't grow on trees" and with this advice in my ears I was set free into the world.
Gresham House (GHE) looking a super strong long term, buy even at record levels.
Today announced Net Asset Value (NAV) up 42.6% to £511.7mn (FY20: £358.9mn) against a market cap of 374m .
Unless I am missing something this looks a great prospect given its forestry and energy investments.
The forestry NAV I am pretty sure is massively understated even at the new NAV stated above.
I have some forestry investments personally so know the market quite well, Gresham are the alpha make of the UK forestry industry and prices have significantly rerated especially recently with the emergence of other less knowledgable funds entering the market.
The key point and one game changer in valuation is the proposed of wind farm development on their existing forestry. Forestry that gets wind farm development rises in value very significantly as the landowner derives around 7% of energy generation with zero risk and doesn't even have to sacrifice too much of the forestry ..
The numbers are quite startling, on a 200-300 hectare site with around 10 turbines forestry value currently might be 2-3 million (but Gresham would have bought way below this in the past ), development cost would be around 30 million (to the developer) and yearly income for ballpark 700k to 1 million . These are fag packet numbers but you get the drift.
I find it pretty hard to see a more solid company in these times, to be sat on 40% (I think) of UK commercial forestry is indeed a gold mine .
Seems money does indeed grow on trees .
I think it is GRID not GHE with the £511.7m NAV?
Grid/Ghe NAV correctamundo 2f1b
Knew I was missing something ! Doh .
Sill rate the share and it’s got great upside .
Agree plenty of upside on Gresham House (LON:GHE) I think you're best just valuing this off an earnings multiple, or rather where you expect earnings to go if they continue to see big inflows. Price/nav not really relevant for an asset manager as they are investing other people's money, not their own.
Fellow Supreme (LON:SUP) shareholder among other reporters today - markets and our interaction with them are a strange beast!
Trying to move with the times, trying to tilt to more value at least with new purchases (not very well as it turns out).
Moneysupermarket.com (LON:MONY) - Recent repurchase (glutton for punishment) read the report - am like this is not good, ex acquired revenues, revenues are down in a recovery. Value - why do I bother. Market expected cr4p - what else would they from this one - share price is up. Answering my question as to why bother with value (Underwater from initial purchase). FWIW I hold because it is too cheap - while it stays cheap I hold.
Calnex Solutions (LON:CLX) - I am like wow - one more time - ahead of when previous update market may have been reticent about this update. I think - nice, probably been a little too cautious with this one. Market goes MEH! I hold as a growth compounder holy grail stock - valuation is ridiculous, live with it!
Supreme (LON:SUP) - I see the update and think was not expecting one - finished my portfolio evaluation and this is a reduce (mainly illiqudity / where it should be compared to other holdings (upper tier 3 rank, lower tier 1 holding y'day). Read the update and am like - not going to be pretty - be ready for crash given illiquidity - valuation support should come in. Market taking care of the reduction for me. I hold as a long term - will be a bigger business over next few years & assess progress on that basis. This update suggests the revenue part of that is in tact but the profit part is in question. One might argue that not raising prices short term while building brand/market share to sacrifice an earnings target is the long term orientation that attracted shareholders. Alternatively, it is wishful thinking and I will sell on the 3rd profit warning!
Incidentally the rank does not move up today - value moves up, momentum/newsflow down & clearly my assessment of inflation risk was wrong so that also moves down, but the rank is independent of "reason owned"/"prospective future rank".
Pagegroup (LON:PAGE) - Don't hold - was thinking - WTF been wanting to get exposure to the sector, missed the boat, damn it. Market goes MEH!
Liontrust Asset Management (LON:LIO) - Don't hold - saw net redemptions - was like Oh that's new. Market was right in pulling back & now holders will realise. Market is like, the Lion does not sleep tonight!
not share related per se so apologies if not appropriate…
I’ve recently opened a Chase account - 1.5% interest on savings, 1% cash back on debit card payments and a round up feature offering 5% interest on your spare change.
Not a bad place to sit funds for the time being I think … ?
I read an interesting Bloomberg article as to why JP Morgan Chase are bothering with this in the UK. You're part of their their cloud banking trials. https://www.bloombergquint.com...
thanks for posting John - very interesting - I don’t mind being part of a trial guaranteed by JP Morgan, wouldn’t have opened an account with a new-starter for sure. Interestingly the 1.5% interest paid on savings is calculated AER and paid monthly so effectively (I believe) account holders are compounding each month… trial or not it beats the 0.65% per annum I’m currently receiving at Skipton Building Society so I’m shifting funds across to Chase.
Airea (LON:AIEA) FY 21 results out (Later than usual due to change of auditor).
(I hold)
sp 25.5p unchanged this morning -
Mcap £9.8m (10.5m diluted by shares held in EBT)
Many moons ago this used to be called Sirdar. Now as Airea its shorn of non-core operations and focused upon its Burmatex carpet tile manufacturing based in Yorkshire. The balance sheet it stuffed with assets. All tangible.
Word of warning - This is one of my collection of micro cap tin pot companies. Highly illiquid. The audited results are not yet up on the website though promised today – but here are my notes from the abbreviated results on the rns.
Rev £15.865m up 9% on FY20 but still well below (-17%) on FY19. You can either view this as a problem – or as more to come.
Profit 1.042m, or 2.7p eps (2.5p diluted) well up on FY20 – looks to me to be an increase in margin in H2 despite the end of furlough and well publicised sharp increases in costs particularly raw materials and energy.
Price to earnings of around 9.4x (10x diluted) which seems reasonable for a small manufacturer in a competitive business with rising costs.
Cashflow 1.7m (before movements in working capital) inventories up 0.3m to support new product launches
Cash of 5.7m (6.6m) after repaying £1m of loan and investing £1.2m in new machinery to support new product launches.
Net cash £2.1m on a market capital of 9.8m at 25.5p (10.5m diluted) an EV of £7.7m (8.4m diluted). Taking into account the investment property of £4m on the balance sheet the EV reduces to £3.7m (4.4m diluted) putting it on a very lowly 3.7x EV.
TNAV of £16.4m puts it on a price/TNAV of 0.6x
Points to note:
Longtime CEO Neil Rylance recently died aged 64 very shortly after taking leave of absence. Seems to have been well handled by the company. He is credited with turning the company around and investing for future growth of the business. The £1.2m spent during lockdown upon equipment to support new product launches is likely based upon his business plan. Puts the company in a good position to raise prices and maintain margins. Slight growth in margin during H2 seems to support this.
Rapid increase in UK revenue of 18% (H1 figure) based upon new products – is obscured by large decrease of around 50% in the small export business caused by lockdowns, shipping constraints and increases in export administrative costs and delays to Europe for small orders. This is not seen as likely to return very quickly – but the focus is upon the UK product launches and rapidly growing revenue.
Pension fund has been actively managed – and as a result of the recent actuarial valuation has moved into surplus. Pension contributions of 0.4m in FY21 will fall to zero in FY22 – a significant boost of 40% to profitability at current levels. Note that the surplus has not been included on the balance sheet (looks like input from the new auditors) as the company does not have an unconditional right to the funds – so the TNAV figures are not flattered by the pension surplus.
Outlook – the company is always conservative in outlook – but the reinstatement of a dividend, albeit at a small 0.4p – does imply that they see continued progress in revenue growth and profitability through the coming year.
My view – Now that the business is seen to be stable, profitable, cash generating and returning to growth despite the difficult environment for raw materials and inflation – looks to be seriously undervalued based upon EV and P/TNAV. Cashflow in H1 will keep driving these down – accelerated by the reduction in pension payments and finance costs. Revenue growth from new product launches will make this even cheaper.
I am presenting this as a value proposition and it is. But I see this as a well run and well invested business with growth opportunities. At some point the value will out – with a little growth on top – probably in the next 6 – 12months. I expect a 50 – 100% increase in share price. If the growth kicks into gear then it could go futher on a 24month basis. 2 or 3 bagger potential with the downside protected by the balance sheet and stable cash gernative business. Major negative is that these tiny microcaps have a habit of staying in deep value territory longer than you might expect - and thats where I expect the growth to play its part. Fully invested at the moment but currently looking for any spare cash down the back of the sofa to buy a few more.
cheers
Mark
Be wary with Warpaint London (LON:W7L) (I hold). A few years back they reported excellent sales early in the year (not this early admittedly) just after they'd bought the gifting business and were surprised when follow on orders didn't appear and they ended up releasing a profit warning. Yes sales are very strong Q1 - doesn't necessarily mean they're going to stay that strong throughout, indeed the update states on of the orders is for September (ie the run into Christmas and may well represent a hedge against inflation by retailers).
Don't count your chickens is all I am saying. I'm long and thinking of topping up.
Not at all surprised SUP have fallen so heavily,when every man & he's dog have been ramping them,when the bad news arrives the doors are not wide enough for all those that have been suckered in,me included.
Not at all surprised SUP have fallen so heavily,when every man & he's dog have been ramping them,when the bad news arrives the doors are not wide enough for all those that have been suckered in,me included.
I genuinely feel sorry for you. It's clear from what you have written you don't really know what you're doing and maybe you should stick to investing in ETFs and Investment Trusts for your equity exposure. At the very least you should stop blaming other people and look in the mirror. Only you are responsible for the research you do and the decisions you make based on it. I'd suggest reading the book on Influence by Robert Cialdini would be very useful if you genuinely believe you have been unduly influenced by others.
All the best, Si
Seems more than a bit harsh and condescending.
£SUP (I hold) as far as I can see it’s not a profit warning - just transient headwinds affecting margins, as a long term holder I’m not worried and certainly not panic selling
Given the comments I'm reading, my opinion on Supreme seems somewhat contrarian to the discussions here. I am interested to hear your views regarding my concerns. My conclusion is that their business is a lot weaker / vulnerable than many might think. It all seems to simple a business without any great IP or specialist complexities.
The sports nutrition products - the ceo has described this as a simple product to produce (whack a few ingredients into a pill press and whack them in a bottle!) - its a highly competitive market where I would expect margins to be squeezed in the future. There is no brand strength or competitive edge that I can see here.
Batteries - As far as I can see they are just a distributor. They own no IP or have any complex offering in this area. It is in perhaps a saturated industry that I would not expect to be growing very much (these types of batteries are not what the latest innovative products tend to use). I would fear that they are vulnerable to margin squeezes as all the power appears to be with the brands imo.
They have a discount warehouse type offering. From what I can see online - the products seem expensive to me. They don't seem to be selling them at a price that clearly shows there bulk buying power. I just don't see why I would shop with Supreme over Costco for example - the offering seems very small and random imo.
88 Vape product - personally I think this has very limited brand value. The customers buy it because its well priced and currently it dominates its space. However you would have to believe that Supreme have some kind of manufacturing super abilities that are rare or unique to believe that no one else will ever be able to produce similar product at similar price points. This is a super competitive industry and Supreme are up against multi billion $ players in the area. It would be safe to have a cautions growth assumptions in this area - personally I think they will struggle to maintain their market share. They also have some client risk in this area as I believe they have a contract with the prison system.
I am not an expert on Supreme (and obviously do not hold) - no offence to those that are bullish - just thought I would share a counter opinion as some may appreciate the view from the other side.
I genuinely think Supreme is a very well run company. They have grown the business in a very entrepreneurial way and perhaps I would be foolish to bet against their continued success. Imo as a private company you can easily go under the radar. People (usually correctly) assume your business must be complex and difficult. People don't just open up a salon or a restaurant with no experience believing it to be simple - they assume it will take hard work and a lot of know how. So when a company goes from private to public it becomes imo a lot more visible. It will get scrutinised closely. Imo this is one of the reasons investors place so much value on IP / brand / competitive edges etc - you could call this the complex engine under the bonnet - very hard to replicate. Supreme now as a public company will be closely looked at within its areas. And I think a lot of competitors will notice that there is nothing complex about the business - look under the bonnet and its a hamster on wheel. I don't mean that to sound offensive - its just a fact that their business by their own admittance is very simple. I am also wary of recent IPOs being near the top of the growth model - another reason why I would be cautious about future growth prospects.
None of my opinions are based on todays TU and I have not considered inflation / supply chains and all the current near term market conditions. This is just my view on Supreme as a business. As I've said I do not hold and not an expert so I apologies if I have made errors in my assessment.
Supreme (LON:SUP)
" bad news arrives the doors are not wide enough for all those that have been suckered in,me included."
Can I ask, who suckered you in?
the first in a suite of upcoming developments underpinned by a new technology strategy
This statement is tantamount to an admission by Argentex (LON:AGFX) that their original strategy, to provide an in-person, consultative approach to FX hedging, has not worked as hoped. As such, they are now chasing Alpha Fx (LON:AFX) with a far less differentiated proposition, and from a point several years behind the curve. I think we can all see the value proposition - but is the problem that Argentex is a bit crap?
Alpha Fx (LON:AFX) is rolling out internationally whereas Argentex (LON:AGFX) appear to need to fix their basic offering.
Argentex (LON:AGFX) are interesting. On the face of it they seem very good value but the market doesnt like them at all.
One of their main problems in my opinion is they think theyre bigger/better than they actually are. Management dont like talking to private shareholders and trading updates are quite often complete wibble as Blackadder might say.
I contacted IR a while back to politely suggest it pointless to have Numis as a broker if 90% of potential buyers cant see their forecasts, they didnt reply of course, but Im glad to see Singer has now been appointed.
There was no chance they were going to meet forecasts so the market has sold it down, but theyre slightly better than I anticipating tho they really need to start getting forecasts out there and meeting or beating them to gain some momentum.
Saying all that they do look cheap so Ive take a chunk at 71p. Not expecting any fireworks but new forecasts 2023 -9.3p 2024- 11.2p look achievable. Net cash and a nice divi. Decent chance of 100-120p this year if things go to plan.
Thanks for sharing the broker estimates. Do you know what they say about FY22 EPS?
Trading update basically covers this, year end March '22 so should be in the price now.
Off the top of my head they had 36.5m revenue and 7.9p eps. Both were too optimistic once 1st half numbers were known.
Singer will hopefully have a report out soon.
Supreme (LON:SUP)
As timarr says "Down 10%. Staggering really given that the issues are all external and all known about already" - well, it is down 17% now on forecast EBIDA trimmed by 8.2% this year and 6.6% next "taking a conservative view on the medium-term trends in energy and commodity prices which have already impacted a broad range of sectors" see https://www.equitydevelopment....
People are still going to buy batteries and light bulbs and there could be an increase in vape sales by people trading down. The company previously pointed out that Asda are happy to sell 88vape at 15% above the RRP of £1.
Down 10%. Staggering really given that the issues are all external and all known about already
In defence of the price reaction. Supreme (LON:SUP) has held up far better than other small caps until today, so some fall seems justified - not 19% though. I might have been a bit snooty about the name in my previous post but this looks a resilient, cash generative grower with a near 5% yield after today's adjustments.
However, Equity Development misquotes the company in a potentially misleading fashion:
"Despite FY22 growth in Sports Nutrition & Wellness revenue of over 130%YoY(E), profitability in this division was impacted by a combination of the increased price of whey and additional wage and transportation costs."
From the company:
"performance will be tempered by commodity price inflation within Sports Nutrition & Wellness and the increases in the overhead base relating to wage and transport costs"
That does not read as though it is confined to the 5% Sports Nutrition division, but rather across the whole company.
Supreme (LON:SUP)
Surely what matters most here is updated expectations ref 2023 year just staring - stocky was showing expectations of 15% profit growth for year starting now. All the company could say today was
"Looking at FY23, the Group is expecting to deliver another year of profitable
growth "
The lack of any benchmarking to current expectations provides uncertainty - on that basis alone can't blame anyone who reads this as being a potential profit warning or providing wriggle room for expectations to be downgraded . I guess broker updates needed to fill in the blanks.
Nil marks to the company here for creating the uncertainty by not refencing current expectations. If they are on track to grow profits 15% not confirming that to the market seems to be the reason for the drop for me.
Never thought i would say it but this company should be looking at Sosandar's update to see how it should be done so as not to spook the market. Perhaps though they are downgrading expectations here and just not coming out and sayingb it directly - broker notes will presumably fill in the blanks.
Any thoughts on interim results from MJ Hudson, which services the alternative investments industry? On paper, it appears well placed to exploit a growth sector of the financial services industry but its shares are still trading well below its 57p IPO price in late 2019.
Foolish or brave, I have added 25% to my holding in Supreme (LON:SUP) at 161p. I just feel that the market has over reacted and I am sure that the CEO, Sandy Chadha who owns 57% of the company will not be sitting on his hands. Equity Development have released revised forecasts for eps of 12.2 and 13.3 and FCF yield of 3.8% and 8.1% for 2022 and 2023.
My issue with Supreme (LON:SUP), attractive though the valuation might be, but also weighing up the product mix, is that it’s a bit like buying shares in your local convenience store, when the most powerful and cash-generative companies on the planet are also down between 15% and 30%.
Just bought a load more myself at 153p. A bargain long term .
I also thought about buying more this morning Supreme (LON:SUP) and after considering if I should up the holding in what is already my 2nd biggest holding in the PF felt that this opportunity was too big to pass by, so bought a few more at £1.55
I am in this for the long-run and have a lot of confidence in the owner (Sandy Chadha) and whilst things maybe a bit bumpy in the short-term with increased raw material costs, greater wage inflation & transport costs I cannot see Sandy just sitting around and doing nothing.
In the meantime, there is a decent dividend and whilst forecasts have been reduced I reckon there is a chance these maybe beaten.
Time will tell, but happy to hold for the long-term.
M Winkworth (LON:WINK) Fabulous figures...profit, eps dividend plus special dividend all more than doubled ! Interesting commentary.. expect London to improve and country to quieten, rental market strong.
Supreme (LON:SUP) good first year post IPO; trading in line. Not expensive and plenty of room for growth, despite that I suspect the share price will take a knock due to the inflationary pressures cited in its wellness and health division. Thoughts Paul/Jack?
I hold
Supreme (LON:SUP) good first year post IPO; trading in line. Not expensive and plenty of room for growth, despite that I suspect the share price will take a knock due to the inflationary pressures cited in its wellness and health division.
Down 10%. Staggering really given that the issues are all external and all known about already:
However, this performance will be tempered by commodity price inflation within Sports Nutrition & Wellness and the increases in the overhead base relating to wage and transport costs.
Well, no shit Sherlock.
Private investors are the market here and many don't seem to be adjusting their expectations, which leads to odd price movements. If they didn't expect this kind of statement what have they been doing for the past year?
You'd think that Supreme would be well placed to ride out the coming storm - they sell stuff that most users will regard as essential. But with wages rising less quickly than inflation pretty much anything mass market and discretionary must be at risk. Surely?
timarr
Private investors are the market here and many don't seem to be adjusting their expectations, which leads to odd price movements. If they didn't expect this kind of statement what have they been doing for the past year?
You'd think that Supreme would be well placed to ride out the coming storm - they sell stuff that most users will regard as essential. But with wages rising less quickly than inflation pretty much anything mass market and discretionary must be at risk. Surely?
Well, personally I’d like to thank all those selling. Just got a bunch at 156p. Nothing unexpected at all with the issues outlined in the trading update. Anyone in the same market will have the same problems re: cost push inflation. I would expect price increases across the board to help maintain margins.
All the best, Si
Supreme (LON:SUP) agree Timarr, Its a bad day to be putting out even good news! I agree seems a massive over reaction. I have taken a small stake at 19.5% down. Staggering really!
I think the market is very jittery...and perhaps even at tipping point...keeping my stop losses tight and hoping I'm wrong.
Its very difficult to watch small gains built over the last few months being wiped out in a morning. Two steps forwards and three back. But having said that, need to keep putting the hard yards in!
We should never forget the quote attributed to Warren Buffett: “The stock market is a device for transferring money from the impatient to the patient”
BTW very positive trading update from Diploma (LON:DPLM) this morning. It’s not all doom and gloom!
All the best, Si
Simoan Diploma (LON:DPLM) bit pricey for me, even more so today :-0
Given you put a question mark, I'm going to give you my answer ;)
You're assuming a very basic version of Efficient Market Hypothesis, for retail investors. You're assuming that all investors are investing on the basis of fundamentals, both macro and micro; knowledge of the product lines, the markets, the business model, the numbers, the ownership, the cost drivers in the business etc..
Whereas retail investors are invested in Supreme (and other companies) for all sorts of reasons; momentum, it was tipped somewhere, they buy the product, they work there, it has a good name, whatever.
Not to mention, as Simoan says, you're looking at the long term, whereas some investors will have wanted 10% in a month otherwise the share gets sold. Or they've took a sh*tload of losses elsewhere in their portfolio in the last year, and they can't handle another one this morning.
My two penn'orth.
Chris
Nice update from Warpaint London (LON:W7L) this morning. Margins increasing on 60% revenue growth sounds very encouraging. This looks a decent recovery play for the next few months now.
Warpaint London (LON:W7L) = agreed good update another small cap whose share price has been hammered for no apparent reason from £2.30 to £1.15 despite previous positive updsates and results. Partial recovery this morning on trading statement but still well below high. Appears to be a trend in small caps must be some bargains ot there at present, will be interesting to see Norcros (LON:NXR) update out on Thursday as again share price has taken a hit but on paper appears to be good value on very low PER.
Argentex (LON:AGFX) (I hold) is c.7% down while I type. It's undershot broker estimates and revenue in second half is up 11% by my calculations - compared to larger competitor Alpha FX's much stronger performance. 11% is still reasonable growth though and given the margin is the same as last year I think this will put them on a EPS of around 7p for the year. That means it's trading barely above 10x last year with net cash. The market's lost confidence but that seems harsh to me?
Excellent FY results & outlook from both:
Northbridge (LON: NBI)
Cambridge Cognition (LON:COG)
Happy holder
See for yourself:
Investegate |Northbridge Ind Serv Announcements | Northbridge Ind Serv: Audited results for the Year Ended 31 Dec 2021
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: Results for the year ended 31 December 2021
Agreed , Michael, and for LON:NBI there are raised forecasts and fair value by Equity Dev. Note here: https://www.equitydevelopment....
Another positive update from Gresham House (LON:GHE) with further strong inflows. As a specialist asset manager with a focus on sustainable/alternative assets, I really feel they are in a sweet spot, with very strong demand for things such as renewable energy (they manage Gresham House Energy Storage Fund (LON:GRID) which has been surging), forestry and VCTs. The fact that many of their assets are uncorrelated with wider markets is another attraction.
Gore Street Energy Storage Fund (LON:GSF) is another investment trust in the same space. In recent months it hasn't had the performance of GRID but as a consequence it is not at a big premium to NAV unlike Gresham House Energy Storage Fund (LON:GRID) . Also there are raising money through a share issue this week so as I am participating would be nice for some of Gresham House Energy Storage Fund (LON:GRID) share price/premium to read across to Gore Street Energy Storage Fund (LON:GSF) over the next few months!
Thanks, I became aware of Gore Street Energy Storage Fund (LON:GSF) after it was featured on the recent Stock Slam. Not the best pitch to be honest, but did encourage me to have a quick look and after a bit of research ended up buying some as there seems a big disconnect with Gresham House Energy Storage Fund (LON:GRID)
Gore Street Energy Storage Fund (LON:GSF) was in mail on sunday last week also
£PLUS another excellent Q1 update for this unloved CFD share. With the Ukraine volatility, Q1 results are 68% ahead QoQ causing Liberum to increase their 2022 forecast by 14%. With a P/E in single digits and a FCF yield of around 13%, it appears cheap to me but not without regulatory risk.
Plus500 (LON:PLUS) is unloved by me because I was one of the c 80% who lose money on their platform! Would have been better to invest in their shares and let other people lose their money! A few years back they did something similar to the LME and it recent Nickel trading fiasco though sadly they didn't reverse the trades. I had a short with a stop loss on Palladium but the price spiked (as it is doing now!) and they stopped trading - when trading reopened the price at which my short closed was way above my stop loss! Never again.
Plus500 (LON:PLUS) (no position)
Taking out Customer Trading Revenues (which show a $101.2m NET INCREASE year-on-year), there would actually have been a $30m decline in total revenues year-on-year.
I get the impression that Plus simply stop their customers from trading whenever it suits them to do so (as ACounsell possibly pointed out). To be honest, I'm amazed it's legal. Or perhaps I don't understand how their system works?
I continue to remain a bystander - those massive swings every quarter are enough to keep me out.
A
Abtan, You can get margin calls at anytime. Because of leverage you can effectively buy a huge amount of equity using their money. That's all ok until a downturn, and margin's get called in as losses build. If you can't add the money to cover the losses then you have to close out your positions. You cannot 'ride it out' without the money to cover the losses.
Makes a lot of sense when reading above but when using spread betting any gambling traits you may have are amplified.
Its not for everyone, but if you want to short for example, then its one of the only ways to do it, plus if your ISA is full then its a tax free way of keeping additional shares.
As ACounsell says, maybe 80 percent lose on spread betting, but then 70 percent lose on the stock market, with spread betting you get a lot of folks trading indices, forex and commodities...crazy risks.
Plus500 (LON:PLUS)
Hi Paul.S
Thanks for that. Yes, I'm aware how leveraging works with Plus et al.
What I was trying to explain was that at certain times Plus doesn't let you exit a position when you would like to.
I believe that this is what ACounsell was implying (happy to be corrected if I misunderstood!)
I think think some punters actually took Plus to court a few years ago when the company did not let them close a position and had made huge losses, although I'm not sure what happened with that.
A
AAhhh thanks for that A! That sounds bloody awful tbh!