Small Cap Value Report (Tue 13 Oct 2020) - FCCN, SCPA, OTMP, MMH

Good morning, it's Paul here with the SCVR for Tuesday.
Timings - I'm running late today, so finish time about 3pm. To avoid getting side-tracked & stressed out, I won't look at any reader comments until I've got my main work done.
Today's report is now finished.
Agenda - this is what has caught my eye in today's small cap results & trading updates;
French Connection (LON:FCCN) (I hold) - Interim results, 6m to 31 July 2020
Scapa (LON:SCPA) - Period end trading update
Onthemarket (LON:OTMP) (I hold) - Interim results, 6m to 31 July 2020
Marshall Motor Holdings (LON:MMH) - Trading update
.
French Connection (LON:FCCN)
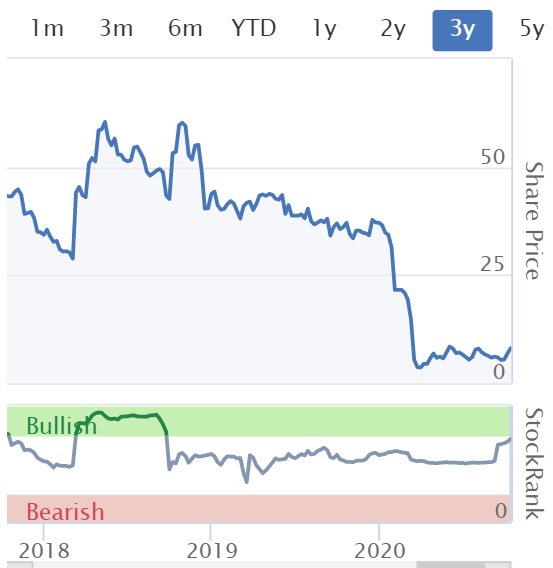
Share price: 7.8p (down 12%, at 11:11)
No. shares: 96.6m
Market cap: £7.5m
(I hold)
"Majority of Trading Period Impacted by COVID-19 Pandemic"
French Connection Group PLC ("French Connection" or "the Group") today announces results for the six month period ending 31 July 2020.
NB. This is a special situation. i.e. it should not be seen as a normal investment, but instead the loss-making retail stores are being wound down, which eventually should leave a profitable wholesale, and licensing business. The question is whether the balance sheet is strong enough to enable the company to get to that position without going bust. Obviously covid has made things orders of magnitude worse, which has been reflected in the bombed out share price. Therefore equity should really be seen as akin to a call option on the business surviving. Most investors will find this too risky to contemplate, which is a perfectly valid opinion!
The reason I still cover it here, and indeed have a reasonable size position in my personal portfolio (I've bought more since covid), is because I reckon the core (brand licensing & wholesale) business could ultimately be sold for about £50m, once the retail division has been reduced to breakeven, or closed altogether. This compares very favourably with the £7.5m market cap, and no threat of dilution to shareholders. So if I'm right, then this could be a fairly serious multibagger. That's why it's interesting. It's not as risky as people might imagine, because there's no immediate threat of insolvency;
Going concern - the last Annual Report contained a "material uncertainty" over going concern. However, this has now been withdrawn, because FCCN refinanced with a new £15m asset-backed lending facility from Hilco. This was arranged in July 2020, for 2 years, and is sufficient for the company's funding needs, hence going concern is now restored. That greatly de-risks things for shareholders, for the next 2 years anyway. For me, 2 years is long enough to see whether this is going to work out well, or badly, so I'm happy with the position.
CVA? - why management haven't done a CVA, I simply cannot fathom. Now that restructuring specialist Hilco is involved (providing a £15m working capital facility, that so far seems to be undrawn), then I hope they nudge FCCN towards ditching its loss-making retail sites in a CVA, once and for all. Rather than piecemeal disposals as leases expire.
.
.
Here are my notes of the key points, jotted down whilst reading the interim results;
- H1 is nearly always loss-making for FCCN, as it has a seasonal weighting towards profits in H2
- Due to covid closing its own & franchised stores, plus its wholesale customers' stores too, these figures for H1 are awful
- Revenues down 53% to £23.9m
- Underlying loss of £(12.2)m - this includes a £3.1m provision against inventories - clearly a lousy result, but did anyone expect better, considering the business was closed or limping along for much of this half year?
- Permanent closure of 9 stores in H1. It now only operates 72 stores/concessions, so good progress is being made on winding down retail, the problem part of the business. Total retail space (including partners) is down 23% to 124,300 sq. ft. - quite a rapid decline, which is good
Cash is king - there's still £5.2m in the kitty, and no debt. (down from £10.0m LY). Plus it has an undrawn (I think, though this is not explicitly stated) £15m borrowing facility from Hilco. Therefore liquidity is fine for now. No risk of insolvency, and no need for an equity fundraising
Current trading in line with expectations at time of the refinancing in July. NB ignore the broker forecasts, as they are out of date, which renders the StockRank unusable until fresh forecasts are provided by brokers
Online sales growing, but only at +8.1% in H1 (but this includes a slow period at the start)
Licensing income down, to £1.5m in H1 - still a useful amount. H2 should be higher, as licensing partners are retailers, hence have also been hit hard by covid in H1. DFS sofas branded French Connection doing particularly well. Licensing is where the brand value shows through, hence the hidden value in the shares
Gross margin has collapsed - this does concern me. Only £3.6m gross profit made in H1, vs £21.8m in H1 LY. This includes a stock provision for surplus stock, but also implies to me that the company had to heavily discount to clear excess stock. It might also have had to offer discounts to persuade wholesale customers to pay up?
The all-important balance sheet - can it ride out this storm without sinking? In a word, yes. NTAV still decent, at £16.0m. Current assets: £46.5m, current liabilities: £33.1m - that's a healthy position. No long term debt, other than lease liabilities, plus of course the undrawn £15m Hilco borrowing facility. This business is financially sound for the next 2 years.
Leases - a big reduction in liabilities, which is helpful. In this case, IFRS 16 is quite helpful, because I reckon it's safe to assume that almost all the stores are likely to be loss-making at the moment. Hence £7.1m lease liabilities in current liabilities should be the annual rent roll. That's down from £10.7m a year ago, suggesting that the company has got rid of some big, problem leases. I know that its Oxford Street store, on the opposite corner from Selfridges, is now gone, and that was a disaster, with rent of over £2m p.a. I believe. This is encouraging stuff.
The long term lease liabilities figure is now only £17.7m, which isn't that much of a problem any more. It suggests that put together, leases on average have about 3.5 years left to run, before the problem retail division is gone. Overall then, the end is in sight for the retail division losses, if we look forward a couple of years. Hopefully the company will see the sense in doing a CVA, to fix the problems sooner, in one go.
My opinion - at this point, ie. ignoring the past, I think risk:reward here is actually quite good. The market cap is miniscule at £7.5m, yet the business has plenty of liquidity, even holding cash of two thirds of the market cap. I'll have to go through the commentary in more detail, as I only have time to skim read it when writing up these reports.
A key thing will be how well the business recovers in H2. For the moment, Governments seem to be targeting hospitality, rather than retailers, for tighter lockdown measures. There's obviously a danger that covid could spiral out of control over autumn/winter, and lead to new national shutdowns, which would clearly be awful for FCCN and other fashion retailers. But even then, it's got enough liquidity to ride out such a scenario, by drawing down on the Hilco loan, and it might push the company into finally doing what it needs to, i.e. a CVA, to ditch the leases.
I look at every share with fresh eyes. I.e. my spreadsheet doesn't even include my original cost price, because that doesn't matter to good decision-making. All that matters, is whether the share is worth more than the current price, in the most likely scenario of how the future might unfold. It's difficult to be certain, but I reckon the odds with FCCN are actually quite favourable, at the current price. The founder is clearly very motivated to maximise the value of the business, as he's well into his 70s now, and owns something like 45% of the business. Situations like that can often be quite lucrative (remember Avesco a few years ago, when the retiring founder achieved a takeover bid of about 6 times what we paid for the shares?)
I always get reader comments, saying that it's a tired brand, etc. If so, why are DFS sofas branded French Connection selling so well? And why do consumers pay premium prices for French Connection branded glasses, perfume, purses, etc? It's actually still a very relevant brand, which is probably worth multiples of the £7.5m market cap. That's why it's an interesting special situation.
To summarise then;
Upside case - takeover bid, and/or return to profits once retail division wound down, giving multibagger potential.
Downside case - slow death over next c.3 years, and Hilco sell the brand to BooHoo, with probably nothing left for shareholders.
I had to laugh at some of the press headlines - e.g. French Connection plunges on results. It's actually just given back most of yesterday's gain!
.
Scapa (LON:SCPA)
Share price: 133p (up 8%, at 12:15)
No. shares: 187.8m
Market cap: £249.8m
Scapa Group plc (AIM: SCPA) is today providing an unaudited period end update for the six months ended 30 September 2020.
This share has really perplexed me in recent months. It did a refinancing, trading updates have looked OK, yet the share price remained stubbornly bombed out, at a seemingly attractively low valuation, yet nobody seemed to be interested. Then you inevitably start thinking, do the sellers know something I don't? Maybe there's something awful lurking under the surface? The only worry I have on that front, is the legal action underway with ConvaTec.
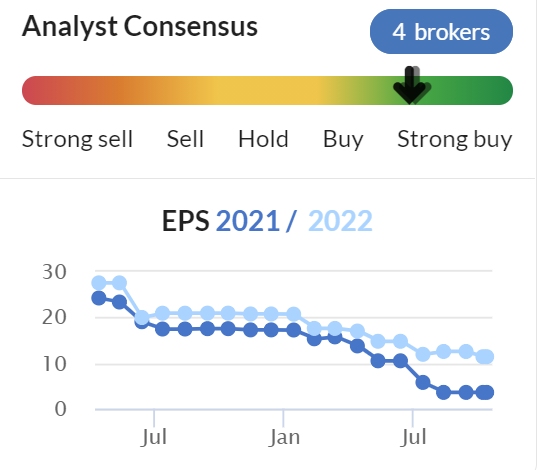
Also as you can see below, brokers have been steadily reducing forecasts, looking like bad news is coming out piecemeal;
.
.
Even so, if it gets back to say 10p EPS next year (forget this year, it's a one-off we hope), then the PER would only be about 13, which seems low for a decent quality business. Plus you've then got all the longer term upside, as hopefully again, earnings return to more normal historic levels much higher than 10p.
Today's update - sounds positive, but it only gives information on revenues. I want to know about profits! The bit below implies that profitability is doing better than expected;
Further to the AGM statement of August 2020, Scapa Group has continued to track ahead of its COVID plan.
Scapa now anticipates that FY21 H1 Group revenues will be ahead of the Board's expectations...
Broker updates - there's nothing available on Research Tree unfortunately. So we're in the dark - very frustrating, as this is a promising share that I want to own, but without proper information, how can we jump into it blindly? Companies and brokers really need to focus more on getting information out to retail investors. After all, its us lot that creates market liquidity, and therefore set the share price! To ignore that crucial part of the market is madness, yet it's a big oversight that many companies are guilty of, and some brokers actively pursue, for their own selfish interests.
Although on second thoughts, the broker consensus figures on Stocko do look up-to-date & credible.
There's a useful set of results slides on Scapa's website, which are worth a look. Hopefully the company can be persuaded to give a results webinar with future interim & final results, so that private investors get the same access as institutions, with Q&A, etc. I often find that the questions from private investors are just as clever as the ones from city analysts, at online webinars which I view. Remember also that many of us watch the webinar recordings later, so even though there might only be say 30 people live on the webinar, hundreds more will probably view it later. So these things are really useful - I'm very grateful to the sterling work being done by PIWorld, InvestorMeetCompany, and others such as Equity Development, to connect us with companies through online webinars. We need all companies to do these webinars. It's not expensive, and why should the institutions get favourable access, whilst retail investors are ignored?
H1 group revenues are about 24% down on last year. Is that good or bad? With no broker updates available, I'll check back to my previous notes here. Here are my notes from 7 Aug 2020 trading update. That update was much more useful. It said that full year trading profit was trending c.10% of market expectations. Today it doesn't say anything about trading profit. I find that confusing, to change the basis of what we're told, from one trading update to another. We'll have to wait about a month for a proper update;
Further details on expectations for the full year trading performance will be provided with the interim results on 17 November 2020.
Also, note the subtle change in tone. Today it says;
Further to the AGM statement of August 2020, Scapa Group has continued to track ahead of its COVID plan....
But in August it said a more positive;
Scapa has delivered FY21 Q1 revenues in the three months to 30 June 2020 well ahead of its COVID-19 scenario plan.
"ahead" instead of "well ahead" suggests maybe there's been a moderation in performance more recently? Or am I over-analysing it? Probably not, because a lot of work goes into the precise wording of trading updates, from companies and their advisers.
Net debt is £21.8m at 30 Sept 2020, compared with £18.4m at 30 June 2020, so slightly worse, albeit given the size of business, working capital fluctuations are to be expected, so I see this as being OK, in the same ballpark.
Last time I looked, the balance sheet was fine, because the company fixed the roof by doing an equity fundraising earlier this year.
Legal action - nothing is said about the ConvaTec case.
My opinion - I'm still kicking myself for selling this one through general anxiety about the share price being so soft. It's since recovered a fair bit, typical!
Brokers consensus is now 3.6p for FY 03/2021, rising to 11.4p FY 03/2022 next year. It still looks good value, if next year's figures are achieved, that's a PER of only about 12.
Providing there's nothing unsavoury lurking in the background, then this share does look good value. With a lot of business being in the USA, I wonder if it might attract bidding interest at some stage?
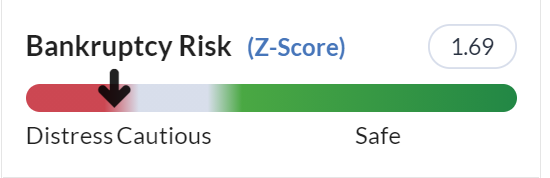
Note that the Altman bankruptcy score below is not great, however this will not yet have taken into account the equity fundraising that Scapa did earlier this year. For this reason, I think we can safely ignore this warning, but as always, it's good to check things out.
.
.
Onthemarket (LON:OTMP)
Share price: 97.5p (down 4%, at 15:33)
No. shares: 71.8m
Market cap: £70.0m
(I hold)
CONTINUED OPERATIONAL PROGRESS WITH CLEAR STRATEGY FOR GROWTH
OnTheMarket plc (AIM: OTMP), the majority agent-owned company which operates the OnTheMarket.com property portal, today announces its unaudited interim results for the six months ended 31 July 2020 ("H1 20/21").
This sector is obviously dominated by Rightmove (LON:RMV) (worth £5.8bn), then there's Zoopla, which was taken private at a staggeringly high price of £2.2bn by Silverlake Partners in 2018. Then we have OnTheMarket, valued at just £70m. This gives an idea of the potential upside, if OTMP manages to even half succeed in carving out a niche. Its key point of difference, is that estate agents own most of the shares, and free shares (with lockins) are used to entice estate agents to sign up from a free starter account, to a full price fee-paying arrangement. The concept is that estate agents are dissatisfied with the price-gouging market leader, Rightmove, hence would be receptive to helping kill it off by jumping ship to OTMP. That hasn't happened yet, because it's an all or nothing thing. Nobody can afford to leave Rightmove, because that's where the customers go. Although I reckon Rightmove is a highly risky share, as at some stage someone like Amazon, Facebook or Google, could set up a free property portal, do saturation advertising on their own platform, and kill Rightmove stone dead. Hence I would never be interested in owning Rightmove shares. Its grotesquely high profit margin looks too vulnerable to me.
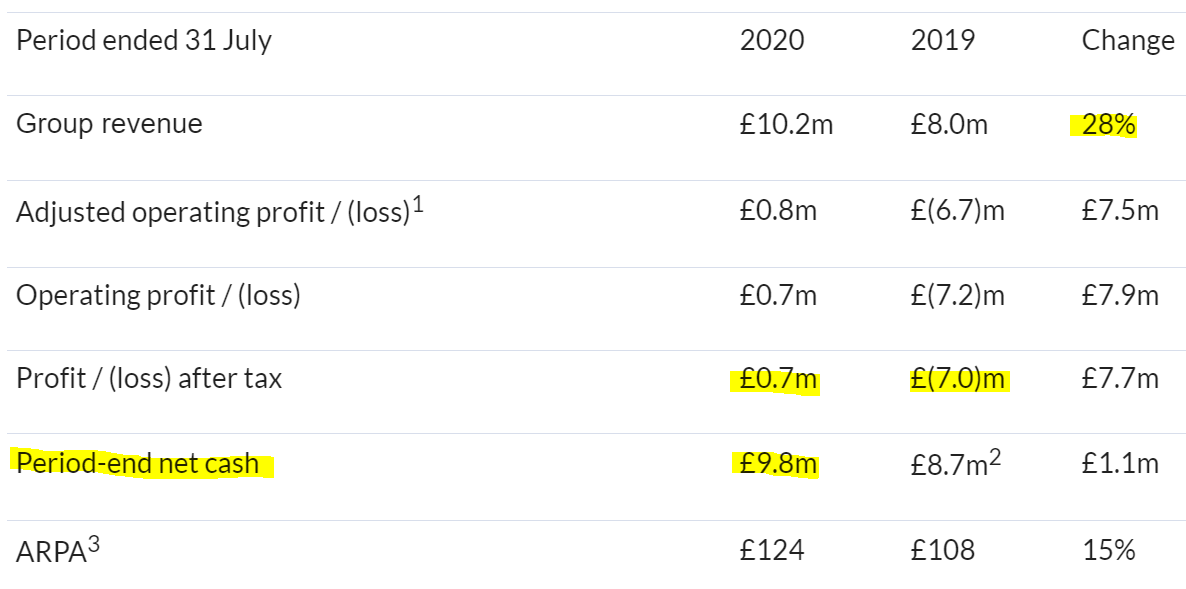
Is OTMP just a wild punt then? Not really. It's small, speculative, but has a high level of properties on it, not far behind Rightmove actually. And these results highlights look pretty solid, given this covers the covid lockdown period;
.
.
Revenue up 28% in H1 vs LY, is impressive, considering the property market paused during this period, and that like other property portals, OTMP gave discounts to estate agents, thus reducing revenues. This implies strong underlying revenue growth, if you take out those factors.
More strikingly, it's moved from heavy losses, into profit. As the commentary explains, this was mainly due to deep cost-cutting. This is what I love about online businesses - as we saw recently with Sosandar (LON:SOS) (I hold), in tough times they can slash spending, most of which is variable - people and marketing, and thereby conserve cash. Then re-start spending whenever they want. OTMP has demonstrated the same point. That both SOS and OTMP both managed to usefully grow revenues, despite slashing marketing spend, does make me wonder if the marketing pounds were being spent wisely in the first place? Maybe not.
Cash has risen a little, which demonstrates that the business can tread water without burning cash. That's important, as bears on stocks like this often claim that they could never reach breakeven. These results prove them wrong. Although to really hit the bigtime, then OTMP would probably need to have a marketing budget running into 9 figures (£100m+). Maybe that would be worth doing though, if it drove a huge increase in revenues & established OTMP as a serious competitor to Rightmove? A private equity buyer might see that opportunity, who knows?
Guidance - this is useful, and reassuring;
The Group expects to achieve a broadly breakeven adjusted operating profit position for the full financial year.
Profit & loss can be dialled up or down, depending on the marketing spend. So this is more a statement of intentions in that regard.
New CEO - appointed, joining on 14 Dec 2020. I'm interested in meeting him, Jason Tebbs, who has plenty of sector-specific experience. It's all about having someone on board who can take things on to the next level, or innovate in some convincing way. I actually thought the last CEO was pretty good, and made some good improvements.
The logical next step for the new CEO would be to do a review of the business, and come up with a revised strategic plan, and raise a load of fresh equity to really step on the gas, in terms of expansion. I'd like to see some mechanism to persuade & better incentivise the estate agents, which are both customers and majority shareholders in OTMP, to market the portal to the public themselves. In the past, I've seen lots of estate agents have that symbol of OTMP (like a marker symbol, or a darts board with an arrow on it) in their shop windows, but who knows what it means? It didn't have the company name on it, just a meaningless symbol! Imagine if all estate agents started saying to every customer, don't look at Rightmove.com any more, everyone's moving to OnTheMarket.com - that's surely the way to get some traction? Plus tons of social media ads. TV ads? Well maybe if they're impactful, but in the past OTMP's efforts have been dismal in this regard.
Because I reckon a big placing is likely, I don't want to commit much to this share unless/until that is done. Hence I currently only hold a small position here (less than 1% of my portfolio).
Overall - it probably won't work, but if it does, then this share could be a serious multibagger. As today's results show, the company can run at a profit, and still grow, in a global pandemic - not too shabby really, is it?
.
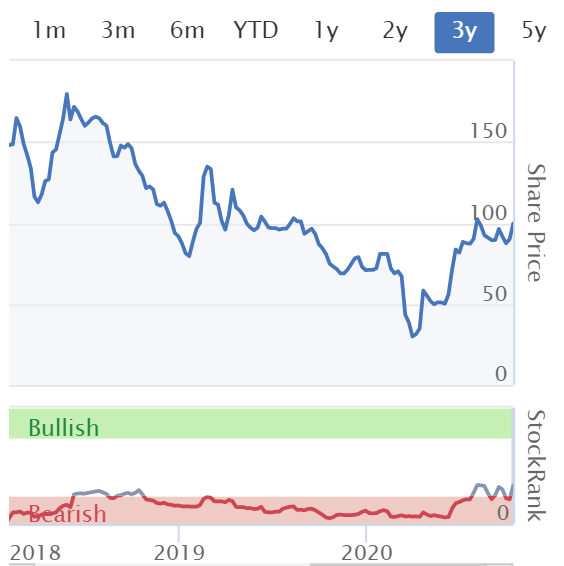
.
As you can see above, the share price hasn't been a complete disaster.
.
Marshall Motor Holdings (LON:MMH)
135p (up 12%) - mkt cap £105m
I've run out of time today, but just a very quick note to say this car dealers has issued a strong trading update today. This is particularly striking, a big increase in FY guidance;
Targeting underlying PBT for the Year of £15m; previously break-even
We had a good update recently from Vertu Motors (LON:VTU) - so it appears this sector is doing well at the moment, pent-up demand probably. It could be worth looking at other car dealerships too, as we might be able to find a laggard that is overdue a similar rise in share price.
That's it for today. Thanks for the comments today. I'm happy with interesting discussion & views of all kinds. Just don't be obnoxious, or disruptive, and then we're all happy & harmonious!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Scapa (LON:SCPA) is not normally one I follow, but I do have a small holding in £AMS. There seems to be a lot of similarities between these two, Advanced Medical Solutions (LON:AMS) is currently sitting on a mountain of cash and little debt, they could afford to take on some debt to fund this?
There could be some synergies to be gained here, even if they only made an offer for their healthcare division. It would be a huge aquisition for them but would make alot of sense.
There is a natural pent up demand from this health care market as many operations and procedures have been delayed until covid calms down, therefore I believe this market is quite low risk.
This is purely my own speculation, would be interested to hear some other views as well.
Spreadbetters directors selling. H&T price monitoring alert. Something afoot.
Superb updates yet again today Paul. Thanks. I was particularly looking forward to your latest on Onthemarket (LON:OTMP) as I’ve held for a while and the share has done well so far, and as usual your write up didn’t disappoint.
A bit surprised that share lost an early 10p gain today to finish 4.5p down. Maybe profit taking after recent good run including 11p gain pre results yesterday?
Is anyone else finding they don't get some RNS email alerts in the morning? I use the London stock exchange email alerts but I'm finding I don't receive about 1 a week for whatever reason. Does anyone have a view about whether this is a specific problem with LSE or is a general problem others are experiencing right now? It's a real pain. Apologies if this is a bit off topic or repeated elsewhere (I haven't been as active on the comment sections lately).
Hi Patrick - I have had zero success the last 2 mornings on an iPad with looking at the LSE nRNS page (Coffee in bed read!) - I think thy may have done another another roll out over the w/e? Anyway - I have resorted to other means including Stocko [TODAY/- NEWS /ALL ] Which has given me a better result even if I have to ignore all tree NAV reports ! Then I just wait for Mr C and HollandSmith
I have found the e-mail forwarding from the investegate.co.uk site has slowed down a lot. I now log on directly in the mornings to check my list.
It did occur to me to wonder if they are being slowed down by people using bots to scrape data automatically first thing.
Re French Connection (LON:FCCN) I remember Paul once putting £100m valuation on it but i cant remember the details of the calculation. £50m seems a more fair valuation.
Covid has happened. That's the main reason for thinking French Connection (LON:FCCN) (I hold) is worth less than before. I heard a market rumour that Marks had turned down a cash bid during the extended sale process, of between 50-60p per share, which is what I'm basing my current view on, of c.50p value for the business. (96m shares in issue)
Plus that ballpark valuation tallies with profits of £5-10m p.a. which I believe is possible from wholesaling/licensing, once the retail division has been ditched.
Situations are fluid, so we have to keep our views continuously under review, and adjust when necessary.
This is clearly not a good time to be selling a fashion business, so I'm perfectly happy for management to park the process until better times have returned. This covid stuff won't last forever. I'm amazed at how few UK small cap investors seem to be thinking about the investment opportunities once things get back to (even close to) normal, which could be 6-12 months, who knows? Medical progress is being made all the time, so in 6 months we should have much better testing, which could enable travel to return to reasonably normal, for example.
I think the mood of the public seems to be changing to. Lots of people I talk to, are now saying we need to live with this, get on with our lives, and protect the vulnerable.
Regards, Paul.
I bailed on French Connection (LON:FCCN) many moons ago. I don't remember at what price, but it was sure to be higher than now.
The problem with French Connection (LON:FCCN) is that it just keeps getting weaker and weaker, eroding its investment case. Who knows, French Connection (LON:FCCN) could make a dramatic turnaround; it's feasible, but the odds look distinctly against it. So Paul it right to say it's a call option on the business surviving.
I'm not especially keen on its new lending facility. What was "supposed" to happen was that the business would improve with a ton of cash on its balance sheet. Now we're seeing a company putting in place lending facilities. So what we've seen is a value play where value has been inexorably eroded and becoming distressed.Paul's a smart guy, so his views could well be vindicated as opposed to mine, and he'll be viewed as a genius. Still, tricky.
It's all about valuation though. You make good points, and I wouldn't be interested in FCCN shares (I hold) if the mkt cap were say £50m. Then the upside would be priced in, so the share would have no appeal to me whatsoever.
It's £7.5m market cap which appeals - for a business that is still in good financial health, as I explain in the article, with tons of liquidity available, a balance sheet that's better than many other retailers, and the underlying value of the licensing/wholesale businesses.
I do think we need to carefully distinguish between regular investments - i.e. companies that we think are great, and we want to hold forever, and special situations like FCCN where a one-off investment gain could be made, because the share price has oversold, and is ignoring breakup, sum of the parts, takeover bid, type of angles.
Most of the comments I read here about FCCN, whenever I write about it, don't seem to grasp the special situation angle on it, which is why I emphasised that above today. We all know it's a crap business! That's why the shares are dirt cheap. But it has 2 years to fix things, with no risk of dilution to shareholders, and within a 2 year timeframe I would say that covid is likely to have been tamed or even eradicated, which would present a range of new positive outcomes possible for FCCN. By that time, it should be a profitable business, with hardly any shops left losing money. That's what's potentially interesting.
Clearly not for widows & orphans although I'd say this micro cap with about £20m liquidity available to it (cash & undrawn loan) is lower risk than many much larger companies struggling with mountains of debt.
Regards, Paul.
I don't think Paul could have been clearer on FCCN. At about 7.5p to buy this is option money on some form of deal being agreed. It clearly is high risk and could be very volatile with a high spread. I don't hold at the moment although I have in the past. Punting money only I think.....and the low for the year is just over 3p. I personally would take a punt at about the 5p to 6p level looking at the charts; I don't see too much of a rush myself but who knows in these uncertain times?
it may be irrelevant to today's RNSs but given the popularity of Novacyt Sa (LON:NCYT) here, and being bought in to Stockopedia SIC club at 724p, I would welcome and certainly appreciate thoughts of readers whether or not the recent pullback was healthy and the weak handed holders are off now, hence, price rise will continue? Cheers.
Mort - I'm not an owner nor ever will be - too volatile. I am interested in valuation of shares generally. I read the weekend review and perhaps one alternative way of looking at it is to ask if this is a bubble. You could look at this model from Investopedia:
The first stage is displacement, meaning investors become enamored by a new innovation or development in fiscal policy, such as an extended period of low-interest rates. The second stage is a boom, as prices tiptoe higher at first but then pick up speed as more investors jump in out of fear of missing out. Stage three is euphoria in which cooler heads don't prevail and market momentum is driving the way. Stage four brings profit-taking, in which investors who believe the bubble will soon pop, start cashing out. The last stage is panic, as an event or series of events causes the bubble to burst and stocks to tumble fast.
There are some aspects of this present. I'll just get ready for the downticks!
Hi Mort,
I got stopped out yesterday at £8.67. Got overexcited when NHS contract was announced but the straight vertical line meant it had to burst at some point. It was just about getting the stops right for me.
All I can tell you is where I am - I have a rule about not buying back in until it drops at least 10% from my sellout point so that's £7.80ish but I don't think I would look at this share until it gets down to £7.00ish. My (admittedly very rough) calculation is a 1 year £9 valuation but there are so many variables (possible competition, possible vaccines, possible scaling difficulties to name a few) that it feels almost impossible to value this reliably - it could also announce another deal tomorrow worth even more than the NHS contract for example.
To answer your question, I'm not sure the recent pullback was the end of the decline - it just signaled the end of the insane growth period. There is likely to be some pain still to come.
Hi Paul,
Having read previously that you are invested in Saga (LON:SAGA), I saw there is webinar hosted by Eventbrite that you may well be interested in.
A little short notice; it's on tomorrow morning @ 8:30 - it will discuss the challenges of operating cruise chips during the pandemic.
https://www.eventbrite.co.uk/e/webinar-cruise-ships-and-covid-19-problem-tickets-118262266623?aff=ebdssbonlinesearch
Hope you find it of interest
Jabba
Directors Talk interview with Mike Allen, Head of Research at Zeus Capital about Vertu Motors (LON:VTU)
His valuation is 62p
https://www.directorstalk.net/vertu-motors-a-better-business-in-many-aspects-analyst-interview/
Directors Talk interview with Mike Allen, Head of Research at Zeus Capital about Vertu Motors (LON:VTU)
His valuation is 62p
https://www.directorstalk.net/vertu-motors-a-better-business-in-many-aspects-analyst-interview/
Thanks for the link. It just served to remind me how much I dislike broker analysts that are too closely associated with a company. Even then he mentions he's had no steer from the company and so knows no more than us going forwards. A pie in the sky valuation and not one single mention of any downside, including the effects of the FCA investigation that the company themselves recently described as "a future earnings risk".
All the best, Si
Si,
I love your posts. Sane and cynical - they keep me cautious, which is where I know I should be.
FREng,
Yes, as long as you keep cynicism in check it can be helpful. However, there are very large insider holdings at Jarvis Securities (LON:JIM) and only two executive directors. The largest shareholder Andrew Grant is Execuitve Chairman and CEO. The Finance director offloaded shares three times in July but his holding is pretty negligible. If they wanted to split the shares in order to improve liquidity for their own purposes, there's nothing really to stop them. If you hold the shares you really need to understand that the rest of us are investing on their coattails.
All the best, Si
I don't know about FCCN Paul. The argument about the old owner was proved wrong by recent events when he seemed to have interest but it disappeared or maybe he wanted too much for the business. Equally the argument about getting rid of the stores, he just hasn't done it, even opening the odd new store from time to time. There seems to be some ego in here. I am not sure if the problem isn't himself. But good luck I think in balance I will watch this ship sail by.
Hi Camtab,
Hmmm, I need to come back to you on those points, which are not quite right in my view.
Sale process - I agree with you that Marks probably wanted too much for the business (his life's work). But to be fair to him, why would he want to sell it, in the middle of a pandemic, when the valuation would be low? The argument about him retiring (he's well into his 70's) is therefore not wrong, it's completely correct! The only issue is on the timing. I'm happy to be patient with my investments, so waiting say 1-2 years for a potential multi-bagger to come good, is attractive to me. Probably not so to many trader/investors, who seem to have incredibly short timescales & nervousness about paper losses.
Store disposals - the company is getting rid of loss-making stores. 9 more have gone in H1 leaving only 72 remaining (some of which are concessions within Dept Stores, which can be exited any time). I covered the big reduction in retail space, and lease liabilities in the main article above. The problem is that leases are an impediment to disposals. Retailers can only exit from shops if the lease expires, or a break clause happens to be in place (often not the case for older leases, and they're usually every 5 years). I'm certain that FCCN has been trying very hard to exit from its loss-making stores. But it's a process that takes a long time. Landlords can see they've been cash rich (not so much now though), not at risk of going bust, so they refuse to compromise. It sounds like that is changing now though, as rent reductions are mentioned in today's report.
Can someone in management please explain the rationale for flagging "This post is under review" against what seem, to me, to be perfectly acceptable/normal posts?
Two of the preceding four posts have been so flagged - what's the problem with Fegger's question re French Connection (LON:FCCN) - he even gives some information from today's RNS and says that, to him, the position looks challenging. And then there's John Eustace's post where, I take it to mean, he can see the possibility of French Connection (LON:FCCN) being taken out by Boohoo (LON:BOO). Looks a definite possibility to me.
Such regular flagging runs the risk of disincentivising regular contributors from putting their heads above the parapet - not something most would want to see, I would have thought.
The flag just indicates that someone has reported the post and that Stocko have yet to review whether it breaks the rules. The flag is removed once review (& in the event that it has broken the rules the post is removed too.)
It looks like individual subscribers have been over-enthusiastic in reporting posts, so perhaps the management might want to instruct anyone who is inappropriately reporting posts.
Maybe the flags are just finger trouble. Or a newbie who thinks they are for something else.
Hi Laughton,
Unfortunately Bluesky Ventura is being deliberately disruptive and is flagging perfectly acceptable comments for moderation.
He’s on a final warning, so if this behaviour continues his subscription will be cancelled.
Hi Jack,
Not disruptive, experimental in understanding what is an acceptable or non-acceptable comment, having fallen foul myself so many times.
Can Stockpedia explain what are acceptable and unacceptable comments that would probably help everyone me especially?
Kind regards,
BSV
This might help posting-guidelines
Or just apply common sense and courtesy as everyone (well, most people!) do in everyday life :)
Hi Gromley,
I've read the guidelines and it does not really help, even the most benign comments seem to be red flag and moderated. But thanks for posting the guideline.
BSV
Hi BV
TBH if you cannot tell from they way others on here comment what is the preferred way to comment then maybe SCVR/Stockopedia is not the place for you?
I understand that there are boards (ADFN LSE?) where there is a lot of shall we say unpleasantness (I don’t know as I have never used) but fortunately here it is all much more civilised! :-)
Regards
Michael.
Correct ADVFN. It not too bad you should give it a go.
BSV
Thank god for that.
French Connection (LON:FCCN) I would be interested in Pauls thoughts on French Connections' interim results to 31 July. Wholesale has been badly impacted as well as retail being 49% down. Overall revenue was down 53% . This statement by Stephen Marks summarises his view 'Despite the unprecedented difficulties we continue to face alongside the rest of the High Street, having been able to secure the necessary financing we feel that we are well positioned to navigate an extended period of uncertain consumer demand but also ready to capitalise on any opportunities that may arise especially given the good performance of wholesale, while maintaining a very tight control of costs." The market doesnt like it very much down 18%. The market value is now £8.65 million and I think they sold Toast for £10 million if I remember. The overall enterprise value is now £30.65 million though including debt and the outlook to me seems extremely challenging
Perhaps Paul will continue to hold French Connection (LON:FCCN), but as part of his Boohoo (LON:BOO) holding?
Wow! - my small holding in Saga (LON:SAGA) is now worth an impressive (not) £13.44 and I just hope most of you were not persuaded by the jam tomorrow arguments - and now market data seems to be no longer available. Is the latter just an accounting pause while they build in the consolidation of the shares in circulation or something else ?
Well according to Stocko Portfolio screen, I am up over 1000%, but I have also lost more than I originally put in, hope they do the maths eventually
By my maths, the £100m that Roger de Haan put so recently into the capital increase is now only worth £52m (at market =142p).
Stockopedia can't handle share splits on portfolios, you will have to adjust it yourself.
Theoretically you can go back to the old version of Stockopedia to do share splits and consolidations, but there is a warning in the old version about possible problems, and I certainly found them when trying to account for the Apple share split. In the end, in my experience, you are quite correct herbie, and you are probably best doing the adjustments yourself manually.. However, this can be time consuming and I would suggest it should be basic feature of the new version of Stockopedia, that it can handle share splits and consolidations.
Thanks David, I don't use the new site, so you can't even adjust them on the new site?
That's correct. You are advised to use the old site but at the same time warned that using the old site for splits can cause problems when you return to the new site (and I can vouch for that). Somewhat of a Catch 22 situation!
I asked about the consolidation (I'm on the new site). The advice is to switch to the old site and run the consolidation tool on the Saga (LON:SAGA) transactions (just click on the settings button on the end of the SAGA line in your portfolio and choose the consolidation tool - it does all transactions in one go). You can then switch back to the new site. Of course, if you are on the old site anyway, then you just need to run the tool.
Huh! That nothing. My holding has accelerated to £58,850 making a +1050% return but I have apparently lost £4 800+/- in the last couple of hours. I await the correction with trepidation!!
Talking my own book, but I thought there were two interesting updates this morning from Capital (LON:CAPD) and £SCPA.
Capital (LON:CAPD) have confirmed that their performance is in-line and that they haven't been impacted by the safety measures required to be taken by Centamin (it had sold-off on the news from Centamin). There is a seller of the stock, a previous founder (Craig Burton), but I do think value will out eventually. A broker note today puts it at a 102p target. To me, it seems a fairly safe and somewhat diversified exposure to the gold play. I also think it seems quite possible that they will beat revenue expectations; for example, they just need to match Q3 figures in Q4 to meet the top-end of the 130-140m full year revenue range, which I would have thought likely in this favourable gold market. Plus it is no longer the wet season in West Africa so drilling and contracting will now proceed.
Scapa (LON:SCPA) have announced that revenues will be ahead again of the board's expectations, though it is unclear how this relates to the previous upgraded guidance of 10% ahead on full year trading profit (on 7 August). I assume it is a further upgrade but it'd be helpful if they quantified this, perhaps a broker note will in due course. I do think this has substantial upside be it a takeover/sale of its industrial business/or final resolution of its proceedings with ConvaTec. The risk I see is that the half year numbers will be a bit ugly and, even though they've been signposted, there may be a little sell-off when those come out. Do you have any views Paul as I know you have covered Scapa (LON:SCPA) previously?
Re. VAT and £BOO. "Retail Gazzette" website states that the full investigation" "All Sewn Up" is on File on 4: Tuesday 13 October 2000 BST on BBC Radio 4 and afterwards on BBC Sounds." Seems to involve several companies in the Leicester area. May see a further SP response on Weds am....or not.
Doug :
IMHO the latter - how can subdiving a share listed only at £7 or so be beneficial ? I”ve had this happen to a a few companies whose shares I owned including Air Partner (when £5) and Dart (then £2). Can only imagine they”ve listened to their broker rather uncritically.
Geoff
Subdividing/consolidation often seem to go hand in hand with a diluting event. It makes the dilution less obvious to the naked eye
Great point Richard, I hadn't thought of that!
Saga (LON:SAGA) being a case in point. Despite having just raised significant new equity at 12p (and 27p in the case of the largest shareholder) they continue to slide and closed today at the equivalent of below 10p (=150p in consolidated form). Why does a freshly supported share go to an immediate discount - people cannot surely have been stagging it sensing a premium?
Nanoco (LON:NANO): I hold some from years ago now a binary bet on the Samsung lawsuit, monthly operating costs halved, cash of 5.2 million , cash run way extended to Dec 2022 seem to remember Paul had a holding also.
Hi clarea,
I don't hold Nanoco (LON:NANO) any more. No particular reason, it was only ever a tiny holding in my trading account (not my main portfolio). So I probably cut it when I had a margin call. I don't have a view either way on it now.
Regards, Paul.
I'd be interested in Paul's (and others) opinion on the Jarvis Securities (LON:JIM) share split.
Is it worthwhile, or (as I think) a complete waste of time, effort and money.
It's not as if they're Next at £50 a share. If they get to that stage they'd be welcome to mess about, but until then I think they should concentrate on getting there.
Good company though.
Jarvis Securities (LON:JIM) I am also confused about this. Surely anyone investing in shares isn't going to baulk at a price of £7.40? Is there another possible explanation for the share split?
disclosure: I've held for years and it has done well for me.
Re £JIM I agree that share split seems a total waste of everyone's time. How does going from a share price of £7.40 to £1.85 make any difference at all?
I can only imagine some fool thinks it worked for Apple so it will work for them. Or maybe I'm the fool and it will?
Re Jarvis Securities (LON:JIM) I agree that share split seems a total waste of everyone's time. How does going from a share price of £7.40 to £1.85 make any difference at all?
I can only imagine some fool thinks it worked for Apple so it will work for them. Or maybe I'm the fool and it will?
I guess in theory it should increase liquidity and hence improve the bid-offer spread, but in practice these things often don't work out as intended. Of course, the cynic in me would suggest that improved liquidity would make it easier for insiders to offload shares at the recently heightened share price. I hold btw.
All the best, Si
I’m a happy holder but agree that the Jarvis Securities (LON:JIM) share split seems utterly pointless at £7 per share. If they were over £100 like, say Games Workshop (LON:GAW) then perhaps it would make more sense.
Yeah, if Games Workshop (LON:GAW) only split their shares there might be some momentum in the share price :-)
Regarding the share split at Jarvis Securities (LON:JIM) I agree that it is a waste for all except the company's lawyers and registrars who see some nice juicy fees coming their way.
Back in 2006 AVEVA (LON:AVV) were so advised and did a 3 for 1 split, closing at 680p on Friday, 14 July 2006 and closing at 228p the following Monday. They haven't bothered since and the shares trade at around £45 today.
I'm hoping this 'getting there' is on the cards.
Silver
Onthemarket (LON:OTMP) (no edit button on mobile.....c’mon Jack!)
I just noticed the CEO changed last month, i don’t remember seeing any commentary here on that, i might have missed it.
Steady as you go update from B.p. Marsh & Partners (LON:BPM) this morning. NAV continues to be significantly higher that the SP by over 50%. I think the only way this gap will close will be when some of the valuations they have start to get realized. Nexus is the obvious one for an IPO or equivalent and has been muted for a while now. I continue to hold and be long but this is not one for the impatient.
Onthemarket (LON:OTMP) please Paul, numbers look very good to me . Website traffic down (only KPI down) due to some shutdown or other but came storming back
· As lockdown restrictions were effectively lifted, year-on-year visits in July 2020 increased 173% to 27.5m and average leads per advertiser increased 56% to 148.
https://www.bbc.co.uk/news/uk-...
Boohoo (LON:BOO) Pitch forks out again on the BBC supplier VAT tax fraud link the new angle
Wow, so much for Paul’s original view that these stories blow over in a couple of weeks or so. Beeb, and others, are really working to keep this live as a Boohoo story.
Anyhow I was looking to top up....
Why would people red flag this comment? Are people allowed opinions anymore? Don't think Martin was having a pop at Paul, just exercising his opinion. The cancel culture is alive and licking with some people on Stockopedia it would appear unfortunately.
Thanks - Yes strange world. Anyhow, also an example of danger of reacting to a short comment. I was in no way denigrating Paul, in fact I completely agreed with Paul when he made those comments at Mello in the summer, and so bought on the strength of his commentary on Boohoo. My comment today was aimed at how the media is so desperately trying to keep this story on life support, no matter how tenuous the link!
Everyone should be making buying/selling decisions based on your own research, not blindly following me! Anyway, I couldn't care less about share price fluctuations. I'm not a trader, I'm an investor. So price weakness on BOO from constant re-hashing of an old story about dodgy Leicester suppliers, provides a favourable buying opportunity, as you suggest.
We're still massively up from when I flagged that I'd started buying recently, at c.209p (from memory, that kind of ballpark).
Re flagging - see Jack's comment about that. It's nothing to do with me, I hardly ever flag any comments.
Hmmn Paul, I don't think I was blindly following you :) - as you say, the business case for Boo was far too interesting when the price fell so much.
Sounds like the Beeb is gearing up for another go with its radio programme tonight (File on 4: All Sewn Up will be broadcast on BBC Radio 4 on 13 October at 20:00) - I will await decisions about topping up until that has aired and then been rehashed a bit(!).
Hi Martin,
Thanks for clarifying. I must have misunderstood what you meant when you said;
"...so bought on the strength of his commentary on Boohoo. " ;-)
As regards the latest attack on BOO (I hold), I find it utterly perplexing why anyone BOO shareholders would sell at this stage, given that the supply chain issues in Leicester have been so comprehensively aired already?
If suppliers are fiddling minimum wage, and poor working conditions, it's probably a given that they're likely to be fiddling their VAT and payroll tax returns too!
It is the job of HMRC and other agencies to police the tax rules. The article on the BBC website doesn't implicate BOO at all in VAT, or any kind of fraud. It's unthinkable, because BOO is a large, listed plc.
What the journalists seem to be trying to do, is to associate BOO with a generally dodgy garment manufacturing sector. I just think that's totally unfair. Why are all the other low price retailers getting away with no criticism at all, when they're nearly all buying from sweatshops? (abroad usually, well away from UK journalists, who can't fly there to check!)
Regards, Paul.
With Boohoo (LON:BOO) (I hold) I suspect that it is mainly down to the fact that the BBC and The Grauniad don’t particularly like success.
I am not sure why this is but I think you have to live with it.
I will unlikely to be topping up unless it falls substantially as it is already a 10%+ position. Obviously if the SP drops to £2 odd then it will no longer be a10% position and I will be adding.
Regards
Michael
I would assume that by sticking a popular well know brand name like boohoo into a headline for what would be for most people a dull story about vat fraud, that firstly they grab attention of more people especially with all the recent supply chain issues. But more importantly, how many times is Boohoo googled? They will get a tonne more traffic from boohoo searches than people looking for vat fraud stories. It's probably one of the best keyword for a search engine at he moment
Absolutely true. Additionally, keeping a story running for months (or years even) is so much easier than finding a brand new story.
So often these days, news is not that new!
Historical view is the operative word and as Paul has also said, anyone can change their mind about anything.
Silver
Agreed it’s another opportunity to top up but think I will wait till later today to see if the media run with this.
I agree, let’s see how the day goes for Boo
I think when you have a company with such poor governance and “shady” management there is a danger the co will always be mired in controversy. Plus there is clearly an agenda for whatever reason with BOO, maybe there’s another murky story in the background.
Well I know that is what the Guardian and Beeb think of £Boo, but I'm not sure that shady management is a fair comment. From what I have seen John Lyttle seems a first rank appointment as do the rest of the Board and senior management team. They appear to be making really positive moves to set the governance culture on a strong footing, as shown in their recent interim results presentation.
Their weak parts are 1. Governance has lagged the fantastic growth that has occurred, possibly almost inevitably given the industry, and will take some time to be demonstrably significantly improved. 2. The Chairman - he is clearly an entrepreneur of great talent...he is not really independent chairman material - he does not appear to care for the politics of it all, he does care about building the business into a great success. At some point £Boo may need a new chairman, on the other hand it really wouldn't be the first business to work around the (political) weakness of a chairman.
Wouldn’t this make Boohoo (LON:BOO) (and Select) a victim of the fraud, if they were being given artificially inflated, fraudulent invoices?
Or have I interpreted it incorrectly?
not necessarily the agreed price will be one thing, what this supplier does with his books another
I read the BBC article as saying the artificially inflated, fraudulent invoices were given to shell companies owned by associates of the fraudsters, rather than to Boohoo.
No. They charge VAT on their sales and reclaim it on their purchases. The balance goes to HMRC.
Interesting link, thanks.
I'm not surprised there's evidence of VAT fraud in the rag trade. I remember hearing rumours of bags of cash changing hands, when I worked in the sector.
Are the journalists now suggesting that its BOO's job to do VAT audits on its suppliers too?! It's ridiculous. The tax authorities are meant to police VAT fraud.
Like all businesses, BOO shops around for the best prices from a range of suppliers. Its the job of the suppliers to comply with the law of the land. If they can't meet the price required by retailers, then they should decline to bid for the work. That's the way business works, in most sectors. You can't blame the customer, if the supplier decides to break the law!
Nobody is suggesting that BOO is breaking the law in any way. That's what matters, and they've already announced extensive measures to deal with the Leicester supply chain.
This is just more background noise. It doesn't have any financial impact on the company at all - it's been reporting record performance, and broker upgrades, over the last 6 months. So the attempts by multiple journalists to taint the brand, is simply not working.
I bet if anyone looked closely at the supply chains of any company, they could find things made by child labour, in sweatshops, etc. That's not in any way to condone it, but that's reality. BOO is being unfairly singled out. It won't make the slightest difference to the share price in the long run, as we've seen before numerous times when big brands are exposed for buying from dodgy suppliers, or working their warehouse staff hard, etc.
Regards, Paul.
My morning smallcap tweet: Marshall up a gear
Palace Capital (LON:PCA) Scapa (LON:SCPA) Connect (LON:CNCT) Capital (LON:CAPD) French Connection (LON:FCCN) Marshall Motor Holdings (LON:MMH) Actual Experience (LON:ACT) Lidco (LON:LID) Essensys (LON:ESYS) B.P. Marsh & Partners (LON:BPM)
Palace Capital (PCA) H1 trading. 94% and 90% of rents collected for March Q and June Q. 70% of rents for Sept Q collected, higher than at the equivalent stage in the previous two quarters. Divs of 2.5p min restarted. [SP=190.08 Cap=88m]. I hold.
Scapa (SCPA) guides H1 rev ahead of mgmt expectations. Industrial division down c.22%, Healthcare down c.23%. [SP=123.4 Cap=232m]
Connect (CNCT) wins 5 year renewal from Associated Newspapers, publisher of the Daily Mail etc. Comples goal of renewing all major contracts. [SP=25 Cap=62m]
Capital (CAPD) Q3 rev up 20%. Guides FY in line. [SP=65 Cap=89m]
French Connection (FCCN) H1 rev down 53%. Wholesale rev down 50% which Marks thinks is 'good'! U/L loss £12.2m (£3.6m). Op cashflow £3.7m. Has sufficient cash "based on its current best worst case expectations". Is that the best phrasing they could devise? Why did SP jump 25% yesterday? [SP=8.92 Cap=9m]
Marshall Motor (MMH) FY(Dec) trading. Guides U/L pretax £15m, previously break-even. "Group continued to trade strongly through the remainder of August and, importantly, during the key plate-change month of September. The Group benefitted from the ongoing release of pent-up demand in both vehicle sales and aftersales." [SP=120 Cap=94m]
Actual Experience (ACT) 3-year extension of its framework agreement with Accenture. Co believes that Accenture has the potential to become a significant Channel Partner. [SP=97.5 Cap=46m]
Lidco (LID) H1. Outlook " too early to predict whether delayed purchasing decisions and postponed elective surgeries will catch up in time to benefit LiDCO's performance in H2. Although some opportunities are under discussion, the Board does not currently expect that H2 will benefit from a further significant boost to sales as a result of the pandemic." [SP=8.35 Cap=20m]
Essensys (ESYS) FY in line. [SP=132 Cap=70m]
B P Marsh & Partners (BPM) in line [SP=234 Cap=88m]
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Thank you!