Small Cap Value Report (Tue 14 Dec 2021) - JOUL, BEG, CHRT

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul's section:
Joules (LON:JOUL) (I hold) - supply chain issues deferred some sales, and increased costs in H1, particularly November. Despite that, the company is guiding £9-12m profit (up on last year's £6.1m). Broker forecast is reduced by about a third, from previously punchy forecasts. Valuation looks reasonable, given recent slide.
Begbies Traynor (LON:BEG) (I hold) - interim figures are in line with the last trading update, so no surprises. A series of good acquisitions are delivering strong profit growth. There's a tailwind coming for insolvency practitioners once taxpayer support measures are phased out. BEG has a sound balance sheet. Yet it's only priced on a PER of about 13.4 by my calculations. Looks excellent value to me.
Cohort (LON:CHRT) - profit warning for the full year accompanies lacklustre interim results (profit down 60%). Given its lumpy, unpredictable profit track record, it's impossible to accurately value this share. Looks expensive, given the uncertainty.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Joules (LON:JOUL) (I hold)
135p (down 29% at 08:07) - mkt cap £151m
Joules, the British lifestyle group, provides a Pre-Close Trading Update in respect of the 26-week period ended 28 November 2021 (the first half of the Group's financial year ending 29 May 2022, or the "Period").
The Group is providing its trading performance on both a year-on-year and two-year comparative basis, as FY21 H1 was characterised by boosted e-commerce demand reflecting Covid-19-related social restrictions and the enforced closure of stores (both Joules and its wholesale partners) for approximately two months.
The revenues table below strikes me as positive - key points being that store revenues have bounced back strongly (up 80% vs H12 LY) from last year’s enforced restrictions/closures, and are now almost back to pre-pandemic levels (helped by 5 new openings in Centre Parcs, which have “performed particularly well”)
Also note that eCommerce has continued growing, albeit at a slower growth rate (5%) versus a very strong +41% growth rate last year -

.
The acquisition of Garden Trading has boosted the total group performance columns.
Supply chain - a very well-known issue by now, which is causing temporary disruption, and additional costs, as I would expect. JOUL experienced problems in the period - which is obviously why the share price has been weak of late -
The well-documented global supply chain issues have resulted in some higher costs and stock delays during the Period. In addition, labour shortages in our third-party operated distribution centre (DC) have resulted in extended product delivery times to online customers, stores and wholesale partners. These factors were particularly acute in November, including the Black Friday period, which alongside weaker year on year online traffic contributed to performance during this month being below expectations.
These problems are expected to continue, but a better performance is expected in H2 -
Global supply chain challenges are expected to remain during at least the second half of the Group's financial year and there is increased consumer uncertainty as a result of the emergence of the Omicron coronavirus variant. Supported by a strong stock position and wholesale orderbook, actions that have been taken to improve productivity at the DC, and the ongoing strong customer demand for the Group's products, the Board is confident that the Group will achieve continued strong revenue growth in H2 and an improved profit performance.
Guidance - this is problematic, as the main issue with today’s update is that it omits to tell us what market expectations are, although Liberum has just come to the rescue with an updated note on Research Tree - many thanks for that.
H1 profit guidance - down a bit on last year’s H1 -
Considering these factors, Group profit before tax and adjusting items for the Period is anticipated to be in the range of £2.0m - £2.5m (FY21: £3.7m).
Full year guidance - down on (unknown) market expectations, but signalling a much better H2 than H1 -
… full year profit before tax and adjusting items is now expected to be below current market expectations and in the region of £9m to £12m notwithstanding any further significant covid restrictions.
Stockopedia’s broker consensus shows £6.0m net profit forecast for FY 5/2022, which grossing up for 19% corporation tax would be £7.4m pre-tax. Joules is saying it’s below expectations, but it’s actually well above the Stockopedia broker consensus figure, even after I’ve added back corporation tax.
So the company has scored an own goal here, by not explaining what its market expectation numbers are.
Is it a profit warning? The company says so, but on the numbers we’ve got, it’s a profit beat! Ridiculous, honestly why can’t companies just include a footnote to say what it thinks market expectations are, then there wouldn't be any confusion?
Broker update - new forecasts out this morning from Liberum have clarified things. It previously had very punchy forecasts, so with supply chain problems being so widespread, it shouldn't be a great surprise that they've been trimmed. It's easiest to work on EPS numbers, which are -
FY 5/2021 actual: 4.6p
FY 5/2022 latest forecast today: 8.7p
FY 5/2023: 11.7p (also reduced today)
Once supply chain problems have been resolved, then clearly there should be good upside on these figures.
My opinion - personally I’m pleased with £9-12m profit guidance, that seems a good outcome to me, in a year when there’s been massive disruption to supply chains, and additional costs. Once those temporary factors have been resolved, maybe in 2022, maybe later, who knows, then it’s reasonable to assume profits would rise.
There’s already early evidence that the UK shortage of truck drivers may be starting to ease - with recent press reports showing increased numbers of HGV licences being issued, and testing centres busy. As you should expect - higher wages attracts lapsed staff to return, or retrain from other sectors.
The share price has (like so many other small caps) drifted down a lot. I don’t know how the market is likely to react to this update. It strikes me as pretty good in the circumstances.
Last year FY 5/2021 JOUL delivered £6.1m PBT (before exceptionals), so the way I read today’s RNS, it’s heading for improved profitability at £9-12m. That seems positive to me in the circumstances of a year dominated by supply chain delays & costs that are affecting everyone moving physical goods, and continuing covid uncertainty.
The market seems to latch onto any excuse to panic sell at the moment, so short -term prices are a very unreliable indicator of fundamentals right now. For long-term investors, I think JOUL is an outstanding company. It’s a unique brand, executing very well (particularly online, which is 63% of its total retail sales). I also really like the online marketplace, Friends of Joules, which has a lot of potential in my opinion.
The market cap of £151m strikes me as undervaluing the potential here.
I see the price has opened down 29%, which seems crazy, given that supply chain issues are already known, have already been reflected in a lower share price, yet the market acts surprised when the obvious is announced! This is a cracking buying opportunity in my opinion at 135p per share.
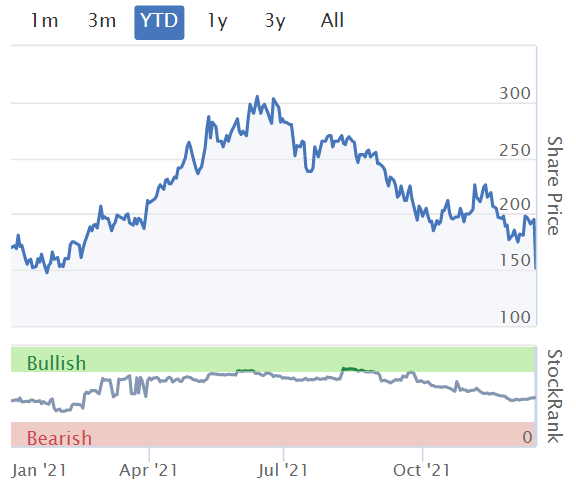
Note below that the share price has now given up all of 2021's gains - which doesn't make any sense to me, given that profitability has risen considerably, and the full year guidance is now usefully higher than last year's actual profits. Also of course, once supply chains are sorted out, then freight costs are likely to come down considerably, and delays disappear. This year's headwind is a future tailwind. At some point, it's like flicking a switch, the market suddenly turns from seeing only the downside, to focusing on the upside as temporary factors like supply chain, and covid, are perceived as lessening. These boom & bust cycles seem to be getting more intense at the moment, this feels like a market dominated by traders, rushing in & out of things. Quite unsettling for longer term investors, for sure. But that's what provides the buying opportunities, when Mr Market is having a deep depression.
.
.
Begbies Traynor (LON:BEG)
134p (roughly flat at 08:47) - mkt cap £203m
Begbies Traynor Group plc (the 'company' or the 'group'), the business recovery, financial advisory and property services consultancy, today announces its half year results for the six months ended 31 October 2021.
Acquisitions - insolvency practitioner BEG has made some chunky acquisitions, so it’s arguably more of a growth share, than the existing perception of a counter-cyclical, mature business. I wonder if it might re-rate in time, to reflect the excellent track record of management making decent acquisitions, and be viewed more like Sdi (LON:SDI) or Judges Scientific (LON:JDG) ? Who knows, it’s possible though.
In the past I always viewed acquisitive groups with suspicion, but having seen over the years examples of spectacular growth & shareholder value creation with SDI and JDG, acquisitive groups are an area that is worth looking at more closely I reckon. The key factor seems to be management competence and discipline, in only buying decent companies, and walking away from lousy deals. Management at BEG fit the bill there, with many years experience, and they don’t seem to have put a foot wrong with the acquisitions to date.
Today it says -
Following our recent acquisitions and organic development of the group, our broad range of complementary services provide a strong platform for growth. We continue to progress a pipeline of acquisition opportunities, which together with organic growth initiatives across the group, will enable us to build upon our track record and we remain confident in our outlook for the current year and beyond.
A minimalist financial overview table is provided, and these numbers tie in with the H1 trading update which I reviewed here on 18 Nov 2021 -

.
Note that adj PBT is +60%, but adj EPS is up a lesser amount, +32%, which either means there are more shares in issue, or the tax charge has risen a lot, or a combination of both.
The StockReport has a handy line which shows the average share count over a number of years, which I always check to see what dilution has occurred. In this case it’s not excessive, and the dilution has been used to fund good acquisitions -
.

.
Do remember to check the latest share count, which is near the bottom of the StockReport, as this will give the bang up-to-date figure, which may have increased further from the average numbers above, which it has here -
.

.
I thought it might be useful to flag this, for our newer subscribers.
Companies also often announce the total share count at the end of the month, so you can check the RNS as an alternative source for the latest share count figures.
Adjustments - note that statutory profit is much lower than adjusted profit, because the adjustments relate to acquisitions - transaction costs, and amortisation of goodwill. These are perfectly valid adjustments, because the adjusted numbers are intended to show the underlying performance of the business before one-off costs. So I don’t have any issue with that.
Balance sheet - the main danger with acquisitive groups is that goodwill becomes excessive at the top of the balance sheet, funded by excessive debt lower down.
BEG has avoided that pitfall. Whilst goodwill is a lot, at £77.3m intangible assets, NAV is higher at £83.1m. That leaves NTAV of £5.8m - not a lot, but as long as NTAV is positive, then I’m comfortable with the balance sheet for a profitable group like this.
There’s a £6.0m long term bank loan, but that’s more than offset by £7.2m cash. Maybe a bit flattered for the year end, but gross debt of £6m is negligible for the size & profitability of the business. Not a problem at all.
Valuation - many thanks to Shore Capital for providing us with an update note today on Research Tree. It’s forecasting 8.5p EPS for FY 4/2022, which looks undemanding.
As mentioned last time we looked at BEG, I see the forecasts as quite soft, so am happy to value BEG shares on 10.0p EPS which might be achieved next year.
At 134p per share, that gives a modest PER of only 13.4 - which I think is too cheap.
My opinion - all good - no surprises here, the figures are as expected.
BEG sees a wave of insolvencies on the horizon, as zombie companies relying on Govt support and the rent moratorium have to pull the plug in 2022 when such support ends.
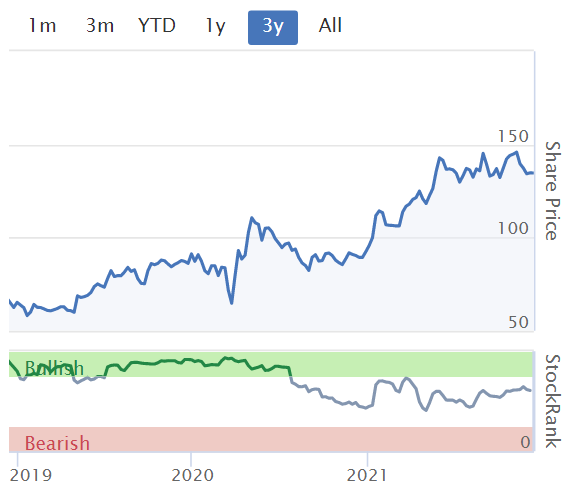
What seems strange to me, is that the stock market doesn’t seem to have priced in that upside, which is good news for shareholders at BEG - there seems fairly obvious upside on this share in the pipeline. Hence the fundamentals look good to me.
.
.
Cohort (LON:CHRT)
521p (down 13% at 10:20) - mkt cap £215m
Cohort plc, the independent technology group, today announces its half year results for the six months ended 31 October 2021
It’s immediately obvious why this share is down 13% today - despite positive figures on revenue, order intake, and order book, profitability has dropped 60% in H1 -

.
The commentary says H1 was disappointing, but that there’s good visibility for a better H2 -
"We anticipate a much stronger performance in the second half, but do not expect this to fully make up the shortfall. As a result, the Board now believes that Cohort's performance in 2021/22 will be materially below current market expectations.
Given the hideous market sentiment in small caps at the moment, I’m quite surprised the share price is only down 13%.
I can’t find any broker updates, so am not sure how much estimates are likely to be reduced.
Last year’s results showed a large H2 weighting to revenues and profitability (Adj operating profit - H1 LY: £4.3m, H2 LY: £14.3m), so it looks quite a lumpy business - which makes it difficult to forecast, and hence difficult to figure out what the shares are worth.
Balance sheet - intangible assets make up £63.5m, with £80.9m NAV. NTAV is therefore £17.4m - adequate, I would say.
Receivables strike me as high, at £54.2m. Given that H1 revenues were only £60.0m, then it looks as if customers may not be terribly keen to pay the company’s invoices. Hence this would need looking into before buying CHRT shares.
It holds a big cash pile of £35.5m, whilst also owing £29.5m in bank borrowings, which is unusual, and could suggest large swings in cash/debt during the year, perhaps?
My opinion - I can’t muster any enthusiasm for this share.
As you can see from the Stockopedia graphs below, historically CHRT has oscillated between about 10-20p EPS each year.
The lighter coloured forecast blobs will obviously be reduced by brokers, now the company has warned on profit today.

.
Graph 4 shows a re-rating onto high PERs over the last 5 years, which I’m struggling to justify based on performance.
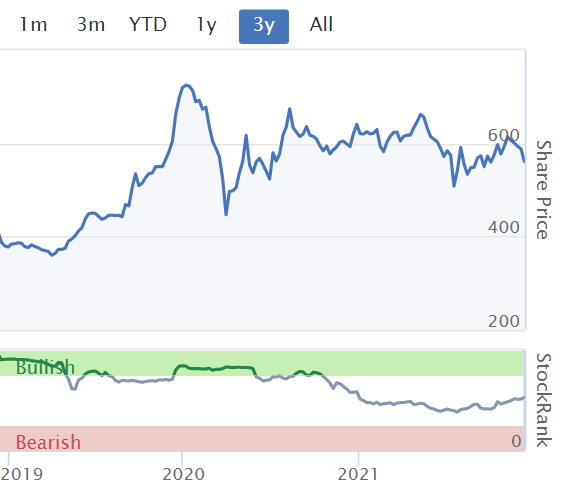
Overall then, it looks too difficult to value accurately, and expensive given the lack of earnings growth, and profit volatility. This strikes me as the type of share where you would need to get into all the detail of contracts, which probably wouldn’t be possible for outside investors, and still not have an accurate idea of what profit it’s likely to make in future. Hence I have to file this one in the “too uncertain, and looks expensive” tray.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Paul thought BEG at 134 a good value. Now it is 120 and probably a better value. Not much has changed since. Yesterday they issued 40,000 new shares for staff and in a day like today no one likes to think of insolvencies!
TUNG (TUNG) offer
The Board of Tungsten Corporation plc ("Tungsten" or the "Company") notes the speculation and confirms that on 19 November 2021 it received an unsolicited indicative proposal from Kofax, Inc. ("Kofax") relating to a possible cash offer for the entire issued and to be issued ordinary share capital of the Company for a price of 40 pence per share (the "Proposal").
The Company also confirms that, in addition to Kofax, it is in early-stage discussions with the following parties in relation to a possible offer for the entire issued and to be issued ordinary share capital of the Company:
-- Jaggaer, LLC
-- Accel-KKR
Whilst the Board believes that 40 pence per share significantly undervalues the Company, discussions are ongoing with each of the parties. It is important to note that discussions with each of the potential buyers set out in this announcement are at an early stage and as such there can be no certainty that any firm offer will be made nor as to the terms of any such firm offer. A further announcement will be made in due course if and when appropriate.
So Tungsten (LON:TUNG) kept invetsors in the dark for 4 weeks! Shocking. No position.
Somebody knew about the offer for Tungsten (LON:TUNG) . Look at the price chart. Starts to make a significant move on 19th Nov!
BBC are saying all 11 countries on red list to be removed tomorrow.
Paul.
Any chance of a review of Calnex Solutions (LON:CLX) (I hold). It has had a bad year and a disasterous month (-14%) This seems wrong for a growth company with a supposedly global reach and sound, cutting edge technology.
Any chance of a review of Calnex Solutions (LON:CLX) (I hold). It has had a bad year and a disasterous month (-14%) This seems wrong for a growth company with a supposedly global reach and sound, cutting edge technology.
Many of my growth names are back where they started the year, including Calnex, but on much lower multiples as they grow into the valuation - which gives some peace of mind. And remember this has been the year for value investors with growth stocks crushed at times - although no promises that this trend will end just because the calendar ticks on into '22.
This looks a very high quality business by any fundamental measure, with the only major risk being the reliance on the "accidental entrepreneur" at the head, whom I like very much. I would counsel patience, secure in the knowledge that the 5G roll-out is in its early stages. Compounding growth over long periods is the key and Calnex looks well placed.
Hi JASPERTHEDOG,
I can't see any results or trading update from Calnex Solutions (LON:CLX) today - which is what we report on here. But here's a quick review anyway.
I'm not familiar with the company, but have just had a quick look at the StockReport, and it looks a nice little business - high profit margin.
H1 results published on 23 November, and show adj PBT flat against H1 LY, at £2.3m.
H1 EPS is down due to increased no shares in issue & options granted.
Confident in meeting upgraded expectations for the full year.
Balance sheet looks fabulous - £13.6m net cash, and £11.0m NTAV - very strong for a small company with capital-light business model.
Cashflow statement - this looks a problem. Most of the cashflow in H1 seems to have been spent on what looks like capitalised development spend of £1.9m in H1. Although actually, the amortisation charge for R&D is £1.4m, so profit is only boosted by £0.5m in H1 through capitalisation exceeding amortisation on R&D. So not a big problem on reflection.
How to value it? I don't know, it depends on future growth.
Overall - looks quite interesting, thanks for flagging it.
Regards, Paul.
Hi Jasper, Calnex Solutions (LON:CLX) is normally one of Jack's shares - he did a lengthy update after their TU in Nov.
It's one I've held in the past, but it seems to get ahead of itself, although to be fair, if it is a play on tech then it still seems to be a reasonable valuation.
It is widely held within the PI world so there is plenty of commentary on it on the old stocko reports.
I would probably come back to take another look after any small downturn in the hope that it gets widely sold off.
Calnex Solutions (LON:CLX) my notes and holding in the SIPP through a coverage in Shares mag:
Raised £22m to join AIM 11.2020.
60% sales through Spirent (a competitor? and took me long time to get out of there when telecoms 5G was the thing).
Failed Luceco bid.
Market seems to hype sectors - 5G, platinum, iron ore, E in ESG and readers can list more for sure. Learning slowly and can make notes courtesy of Stocko system. I recall Ed article in trying to avoid ANY news once invested. Impossible and no fun, but sensible methinks.
hi Paul / Jack
Cohort (LON:CHRT) issued disappointing profit warning today with shares down 13%.
Would be great if you could have a look and let us have your thoughts.
hi Paul
Thanks for the update on Cohort (LON:CHRT) - perfect timing.
hi Paul
In the past I always viewed acquisitive groups with suspicion, but
having seen over the years examples of spectacular growth &
shareholder value creation with SDI and JDG, acquisitive groups are an
area that is worth looking at more closely I reckon. The key factor
seems to be management competence and discipline, in only buying decent
companies, and walking away from lousy deals
Would you place Marlowe (LON:MRL) in that category?
I hope Paul might have time to comment on Snazzytime's question comparing SDI, Judges Scientific and Marlowe as I have also wondered whether Marlowe matches up to the other two and another acquisitive grower, Halma. My admittedly oversimplistic approach would be to note that the latter 3 (SDI, Judges & Halma) reliably achieve a net profit margin of 10% or more (at least since 2018) and their business models seems to reliably generate a ROCE of over 15% which I find reassuring, particularly for a serial acquirer. Marlowe's net profit margin is under 10% and any ROCE is tiny so perhaps their business model is less mature and it is also less clear whether all the businesses they are acquiring have strong barriers to competition.
Good to see SUMO takeover hurdles now cleared. I hold and a big thanks to Stocko and (Dec 2020) Mello for providing me with a 50% return. ( know, you don't make recommendations, but I would never have found this without you!)
Begbies Traynor (LON:BEG) faces a potential opportunity in the next 12 months that they didn't really talk about in their HY results.
So far in the pandemic, the govt has financially supported businesses during covid restrictions. The latest ones for omicron, the govt has shifted stance and will not support hospitality businesses (and others) that will suffer this month and probably next two months.
Many will go to the wall and I wonder if we will finally see a wave of insolvencies feed through in early next year.
Otherwise their results today didn't really reveal anything new. Still on course for FY expectations, 15x PE looks cheap, but not overly so. It's the expectations for insolvencies next year that will move this share price.
(I hold)
Begbies Traynor (LON:BEG)
Not the most exciting share, but a very steady performer!
increased revenue, increased margins, increased dividend. outlook expects PBT to be 17.0m-GBP18.5m for the full year. although thats really heavily weighted to the second 6, i think its achievable given the insolvency situation for businesses.
good read-across for Frp Advisory (LON:FRP) who release their half year results on 16th December.
Very heavy H2 weighting with Begbies Traynor (LON:BEG) ... so there's that risk. If they miss it will be a big EPS miss and shares could be punished 20-30% with a disappointing FY trading update.
(I hold)
Mr Market hasn’t been pulling his punches of late has he? And definitely some below the belt blows going on. Not in the spirit of the season at all!
I know, tell me about it! Hideous at the moment, but when I see some really irrational movements & valuations occurring, I remind myself that this is where the seeds of future investing profits are sown.
The worst thing is to get despondent, and allow negative emotions to cloud judgement on the fundamentals, in my opinion.
I think the tricky bit, is to identify which companies are having temporary, fixable problems (e.g. with supply chains), and which ones are seeing something more fundamentally negative going on. We only know for sure on that front, with hindsight.
Regards, Paul.
Paul, I agree the market reaction does seem irrational in the last few months, even with in line updates, some stocks are getting hammered, yet Cohort (LON:CHRT) which looks quite a bad profit warning, shares are only down 13%. But Joules (LON:JOUL) down 30% today was IMO was a over reaction.
hi Rustbucket
Agree that Cohort (LON:CHRT) profit warning looked much worse than Joules (LON:JOUL) (I hold both so not a great day!). As Paul highlighted, Joules (LON:JOUL) was a bit of an own goal.
It could be argued that Cohort (LON:CHRT) was in reality a double profit warning as 1) The problems at EID are continuing and 2) Problems have now surfaced in the CHESS business. So in a Group comprising 6 independently run businesses there are 2 businesses with difficulties. This may calls into question the Group Management capability which may mean there could be further bad news down the line.
The usual conundrum. Are these temporay and fixable problems at £CHTG or are problems much deeper?
I'm always wary of the saying that profit warnings always come in threes. London buses syndrome.
Cohort (LON:CHRT)
Here is a reason why the profit warning has not done more damage at Cohort.
Cohort takes profits and buys other companies, sometimes taking several years to buy 100% of a company. Due to the nature of the sector, most of the acquisition value on the balance sheet is goodwill. This goodwill is written down each year which affects the reported EPS/PE/op profit/margin/return ratios/etc. The amounts involved are significant (e.g. 10.1mil amortization in FY21 compared to Op Profit of 7.8 mil). Consequently, and almost uniquely among the companies I follow, I feel that the EBITDA figure makes more sense as a valuation tool than the EPS or Operating Profit figures. Below is Sharepad’s EBITDA graph for Cohort (N.B. the interest figure has always been negligible). If today’s warning is seen as a short-term consequence of COVID, the EBITDA graph could flag up adequate underlying value at this level.
There are lots of reasons not to own Cohort—slow government payments/unable to judge the underlying contracts/uncomfortableness with the sector/this profit warning/the hours that it takes with a calculator to do a serious valuation/etc., but lumpiness of the underlying profit has not been a serious issue.
Disclosure- I’ve owned a few of these for c. a decade. I also trade them from time to time. I currently have both buy and sell orders in the market.
PS I don't remember reading thorough your analysis of Joules (LON:JOUL) whether you regard them as a buy at this price.
Joules (LON:JOUL)
You must have missed this bit:
"This is a cracking buying opportunity in my opinion at 135p per share."
The core problem appears to be liquidity. Apart from the US (and even then not across the board) there appears to be a big liquidity gap. What that means is that any buying/selling tends to have an over pronounced effect on the share price. One £800m market cap company today is down 7% on no news with about £1m worth of stock traded for example. You might expect that for a £50-100m market cap that isn't traded much but since mid year even quite well traded stocks are suffering similarly.
Fundamentally it strikes me that most of the trading in the UK since the re-opening is retail and retail are frankly just zig zagging across the pitch like a set of 5 year olds swarming around a ball at the moment. Very little by way of considered reaction.
So, as you say I think you have to try and look past what's happening in the next 5 minutes and back your own view on what you consider companies capable of being medium term winners. Inevitably in hindsight there will be a number of bargains out there.
Yes ; It is liquidity driven and we are not even close to the bottom.
Most of the stocks will bounce back from recent lows ( for a couple of days or even a couple of weeks ) but will then turn negative again and make new lows.
July 22 shares will start slowly bouncing back.
This is just my honest opinion .
Good luck to all.
CASH IS KING
It is very frustrating.
We all put a lot of time and effort into investing (or trading) - taking the time to research, analyse, plan, record... and in periods like this it can seem that the only result is to lose money.
But the markets are cyclical, and this current malaise will end, sooner or later.
Yes, one has to remind themselves that this will not last. Valuations are now looking very reasonable for a lot of equities!
This is usually the week that any Santa Rally may start, so we shall see...
Yet another down day today, pretty much across the board, that's both in the UK and the US.
I note several market commentators talking about the lack of 'breadth' in the US markets, as the S&P and NASDAQ are barely off their highs, but a high proportion of constituent stocks - including previous market leaders - are well down, by 50%, 60%, 70%.
It seems a final flush is needed, but we've been having that for months now it seems and heavy drops caused by the Omicron news.
Perhaps the turning point will be the Fed meeting which is due to conclude tomorrow and seems to be weighing heavy on the markets this week... but even if they provide a hawkish outlook, surely a certain amount of that has already been priced in?
In may prove the catalyst for a rally, but we'll see.
From IG, after the FED statement this evening:
U.s. Stocks Gyrate, Then Rise, After Fomc Statement
The Federal Reserve, signaling its inflation target has been met, said it would end its pandemic-era bond purchases in March, paving the way for three quarter-percentage-point interest rate increases by the end of 2022 as it exits from policies enacted at the start of the health crisis. ...
From the moments before the statement was released, until now, the main U.S. indexes have strengthened. Nearly all major S&P 500 sectors have gained. Tech is posting the biggest positive reaction, while financials are the only sector in the red.
FANGs , chips , and small caps are also among the outperformers since the statement was released.
Regarding the Fed, Ryan Detrick, Chief Market Strategist, LPL Financial, said “The Fed didn’t throw any curve balls. This is widely was as expected. One positive, is they see inflation at 2.6% next year, so the Fed sees inflation coming down. That could be because as much as three rate hikes next year could potentially put a lid on inflation.”
Anyone any thoughts on Chemring (LON:CHG): profits marginally better than last year, targeting dividend cover of 2.5 times underlying eps, they do quote that 84% of 2022 expected revenue is covered by the future order book so seems a good level of recurring revenue streams built into the core business.
The main plays in my opinion here is its a sector with a lot of takeover activity going on all be it most of the recent bids haven't yet been waived through and they also have a software security part of the business that some analysts think could be worth the current market cap of the whole business on its own.
On Joules (LON:JOUL) are the Stockopedia estimated EPS figures correct? E.g. for £FY22 it is suggesting £6m net profit but then this would translate to a 5.3p EPS figure wouldn't it? I'm assuming the 11.6p normalised EPS that it has includes some adjustments. Did the payment for Garden Trading fall into this financial year?
Victorian Plumbing (LON:VIC) heading towards a Boardroom Takeover so soon?
Victorian Plumbing (LON:VIC) heading towards a Boardroom Takeover so soon?
Well, the board sold high through the IPO so you'd imagine they reckon they're buying low now. On the other hand, £3 million for Mark Radcliffe is a drop in the ocean after the money he made before and after the IPO.
timarr
Agree totally with the folly of buying into an overpriced IPO, especially of a fairly ordinary business in times of peak frothiness. I did see some potential upside in £VIC following last week's price collapse, and bought a small holding at around the 93p mark. I have been using the same playbook on a few businesses immediately after a spanking for Supply Chain issues.....which one would assume are relatively short-term in nature for someone who holds for several years. Picked up some Joules today at the bottom of their cliff. The risk is that these things have further to fall in a tough market, like BOO, which is still heading south rapidly.
very cunny directors. selling shares at 262 and buying back at 94.
they can buy the whole company for free now.
avoid.
RE: Victorian Plumbing (LON:VIC)
very cunny directors. selling shares at 262 and buying back at 94.
Very stupid IPO investors.
timarr
Not sure stupid is fair.
The advisers and companies owners brought Victorian Plumbing (LON:VIC) (I do not hold) to market at a price they thought was justifiable at IPO time.
Investors bought on that prospectus. So one (or more) of these must be true:
a - Owners lied (reach for lawyers?)
b - Owners got it wrong (and so did the investors)
c - Events post IPO (joys of investing)
We have the benefit of hindsight here, in this place we know to avoid IPOs in the first 12-18m as a general rule, but a lot of people do not.
My point here is that you can be quite clever and still lose a lot of money
Not sure stupid is fair. The advisers and companies owners brought Victorian Plumbing (LON:VIC) (I do not hold) to market at a price they thought was justifiable at IPO time.
IPOs are a mechanism for transferring money from dumb outsiders to smart insiders. Of course the insiders don't always get it right and sometimes there are other reasons for IPO timing.
But really, we should always assume that the insiders think they're selling at a hgh price, so complaining about the price falling afterwards is just pointless.
timarr
Victorian Plumbing (LON:VIC) yet the share went up from IPO price so somebody must having buying, maybe some IPO investors sold for a quick profit. If it was so over valued then why did the price not plummet?
You have to remember at the time there were a lot of wildly overpriced IPOs, especially in the e-commerce space which was really on fire. Victorian Plumbing was not actually wildly overpriced if you compare it to the likes of the Hut Group. I think it looks very good value at these levels and took a position last week.
Yes that was true. I did not buy Victorian Plumbing (LON:VIC) at IPO but I did buy a small holding last week at around 95p. Looked good value.
I did the same last week too, the reason for my comment after seeing the Directors buying spree on the Friday.
Silver
Not many investors with an eye on this ball, lots of distractions, so it took Victorian Plumbing (LON:VIC) took 6 months to plummet slowly.
Re Headlam (LON:HEAD) - Headlam today appointed Peel Hunt LLP as joint broker alongside Panmure Gordon. Anyone any ideas why this has been done? No word of explanation in RNS.
I understood the received wisdom is that it is often a precursor to a fund raise but unless Headlam plan something massive then the balance sheet is very strong. If they are unhappy with the low share price of Headlam (I hold and I am !!), then why not fire Panmure Gordon.
Is it ever done as a defensive move when a takeover is rumoured? Or is it just something to ignore. Advice welcome!
Update from Sumo (LON:SUMO) with timetable:
Acquisition Timetable
The expected timetable of principal events is set out below. The Scheme is expected to become Effective on 17 January 2022.
Event
Expected time and/or date
Scheme Sanction Hearing
13 January 2022
Last day of dealings in, and for registration of transfers of,
and disablement of CREST for, Sumo Shares
14 January 2022
Scheme Record Time
6.00 p.m. on 14 January 2022
Suspension of dealings in Sumo Shares
7.30 a.m. on 17 January 2022
Effective Date of the Scheme(1)
17 January 2022
Cancellation of admission to trading of Sumo Shares on AIM(2)
8.00 a.m. on 18 January 2022
Despatch of cheques and crediting of CREST for Consideration due under the Scheme
By 31 January 2022
Long Stop Date
11.59 p.m. on 19 April 2022(3)
https://www.investegate.co.uk/...