Small Cap Value Report (Tue 14 July 2020) - BAR, SOM, VTU, CNCT

Good morning, it's Paul here. You have my undivided attention today. Many thanks to Jack for covering yesterday.
Here's the placeholder for Tuesday. Please see the header for the first batch of 4 companies that I'll be reviewing, which have all issued trading updates this morning.
Estimated time of completion - should all be done by 1pm, as I've started at 7am.
Update at 13:34 - most sections are done now, but I'll spend a bit more time on things, hence 3pm finish now.
Update at 14:51 - today's report is now finished.
.
Covid - as usual, I'm monitoring the media for latest developments, as I'm sure many of you are. Two recent reports in particular have concerned me;
1. A King's College London study has shown that immunity may only last a few months, for people who recover from covid. Specifically, antibodies peaked 3 weeks after symptoms appeared, then rapidly reduced in the following 3 months. This raises the horrible prospect of people possibly being re-infected. This study has not yet been peer reviewed. Researchers in Munich came to a similar conclusion apparently. If these studies are confirmed, then it sounds very bad news to me.
2. The rapid spread in some southern states in the USA led to some lockdown restrictions being re-imposed yesterday, and hospitality sector being closed down again. I feel US markets are being incredibly complacent about covid, and seem to think bringing in a vaccine and eradicating it is a given. Hence the V-shaped recovery in stock markets. Now that lockdowns are returning, at least in some states (e.g. Texas, Florida & California), then it raises the spectre that this thing could be around for some time and further disrupting the economy. That is not compatible with the huge stock market rebound, in my view.
Hence I'm leaning more towards the bearish side of things over the summer. We're overdue a correction I reckon - especially for the pockets of euphoria around tech in particular, and ludicrous momentum trades like Tesla (I'm short again, couldn't resist it).
.
Brand Architekts (LON:BAR)
Share price: 112.5p (before market open)
No. shares: 17.23m
Market cap: £19.4m
(I'm long)
Trading Update and Board Succession
Brand Architekts, the personal care and beauty products group with its own portfolio of brands, announces an update on trading for the 52 weeks to 27 June 2020 and board succession.
Sales in H2 - better than anticipated in last update in April, but still significantly down on LY.
Sales split - H1 down 15% to £10.6m, H2 down 21% to £5.7m - FY 06/2020 total sales down 17% to £16.3m
Covid impacted Q4. Supermarkets & online showed growth, but more than offset by declines in other High Street customers. International sales also down.
Profits are down as a result, but of course this is not a surprise, so should not be price sensitive;
Consequently, the board expect Group pre-tax profit for the full year will be significantly below last year.
Cash - this is the main attraction of this share - it sold off a division, and now has cash similar to its market cap;
Net cash position of £18.0m is a significant improvement when compared to the position reported at our interim results to January 11th of £15.1m and the £7.2m of net debt last year.
It doesn't say so, but there are likely to be some stretched creditors (e.g. taking advantage of deferral of VAT & payroll taxes) which have boosted that net cash figure. I think companies should disclose this effect, otherwise net cash or debt figures could be misleading.
Stock valuation - to review valuations. So that sound like an exceptional write-off is in the pipeline. Not good, and no indication of the likely size is given.
Market cap - this is a bit mixed. It doesn't give me enough information to value the share. Let's hope we get a broker update later today, as I'm in the dark at the moment. Why can't companies be more transparent? Not everyone has the time or inclination to make a spreadsheet model for hundreds of companies that we look at.
Why do I hold this share? It's a special situation, where you're paying nothing for the business, but get a cash pie instead. If the new CEO does something sensible with that cash pile, then if could create shareholder value. This stock is very illiquid, so it's anybody's guess what the share price is likely to do.
.
Somero Enterprises Inc (LON:SOM)
Share price: 229p (unch.)
No. shares: 56.4m
Market cap: £129.2m
This is a laser-guided concrete screeding company (it makes & supports the machines).
Somero is pleased to provide an update on trading ahead of its interim results announcement scheduled to be released on Wednesday, 9 September 2020.
This update today covers the 6-months to 30 June 2020.
This is self-explanatory, and very clear;
Trading for H1 2020 ended in line with the level detailed in the Company's announcement of 5 June 2020, approximately 25% below levels required to achieve the market expectation at the start of the year of US$ 90.0m in 2020 revenues.
Following the cost reduction actions implemented by Management, the Company remains profitable and cash generative at current volumes and the Board remains confident the Company would continue to be cash generative even in the scenario where revenues fall an additional 20% from current levels.
New product development is continuing well, not affected by cost-cutting.
Liquidity - looks ample;
The Company's financial position remains secure, highlighted by net cash as at 30 June 2020 of at least US$ 28.0m, exceeding the conservative US$ 24.0m net cash expectation outlined in the 5 June 2020 update. The strong operational cash flow performance reflects effective working capital management driven by healthy trade receivable collections to end the first half of the year.
Outlook - unclear, due to factors outside the company's control, re covid. Hence no guidance given. This seems a bit of a cop out. Surely the company could have given 3 possible scenarios for the full year? Base case, downside case, and upside case. They'll almost certainly have those figures in-house, so I don't see why such important information should be withheld from shareholders - the people who collectively own the company, after all!
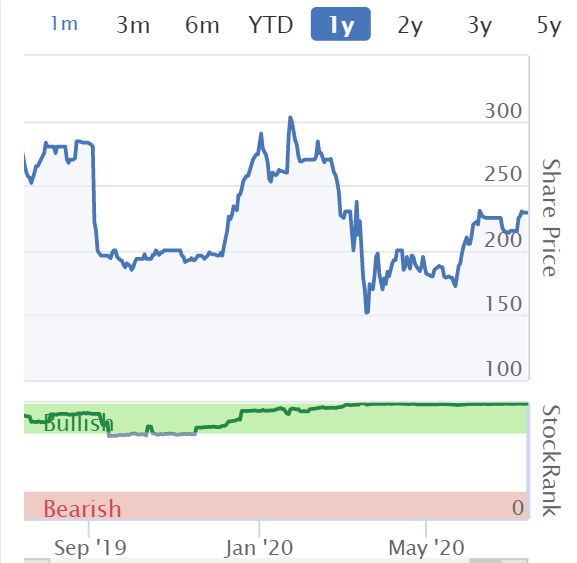
My opinion - clearly 2020 results are going to be poor, but it's a one-off bad year due to covid. There's nothing fundamentally wrong with the business. The only question mark is how quickly its markets recover? For the patient investor, prepared to sit back for a couple of years or more, this one should do well. And there's a bulletproof balance sheet to protect the downside. Therefore, it gets a thumbs up from me, as a long-term share. I've no idea what will happen in the short term.
Forecasts - NB, as with many companies at the moment, guidance has been withdrawn. Therefore the forward PER & dividend yields are based on old forecasts. So old forecasts should probably be seen as what the company might get back to, maybe next year, or being pessimistic, the year after that. I've checked with Finncap, and their latest note out today has no forecasts for 2020. Therefore our only option is to create our own spreadsheet forecasts.
.
.
Vertu Motors (LON:VTU)
Share price: 23.6p (up 4%)
No. shares: 369.2m
Market cap: £87.1m
This is a chain of car dealerships.
June trading was stronger than we had expected.
The Group's cash position was much stronger than we could have hoped
Cost-cutting - £10m of annualised cost savings identified, including reducing staff by 6%
Profitability - sounds like a decent bounce-back when its sites re-opened in June;
The Board is pleased to announce that the Group delivered an adjusted profit before tax of £9.0m in June, having incurred an adjusted loss before tax of £14.2m in the March to May period.
That strikes me as a reasonable performance, although it's difficult to be sure, without seeing the full numbers.
Demand - this sounds encouraging;
Overall, retail sales demand appears to have positively rebounded due to a number of factors.
Pent-up demand is evident with consumers having increased savings ratios during the lockdown.
Lack of plans to undertake foreign holidays and to stay in the UK may also be increasing demand as well as a potential aversion to the use of public transport.
These trends have continued into July.
Liquidity - surprisingly good, but again, likely to be distorted with one-offs;
Net cash (including used vehicle stocking loans) at 30 June was £9.7m which represents an improvement of £49.2m from the previously reported position at 22 May.
A partial unwind of the reduced working capital position which gave rise to this improvement in cash is expected as the Group moves towards more normalised trading. The Group is up to date with regards payments of external rent and amounts due to HMRC for employment taxes.
It only mentioned payroll taxes, but not VAT. So I assume the group might be sitting on cash relating to deferred VAT?
Outlook - full year guidance remains withdrawn. Hmmmm. Not good enough.
My opinion - the problem with trading updates right now is that it's quite easy to cherry pick items that look good, but may be unusually distorted. That said, I thought the comments on strong trading in June, and continuing into July, sounds positive.
I think this might be a good time to examine bombed-out car dealer shares, as it appears consumer demand is coming back. I can see why many people might want to get a car, instead of sitting on a bus or train, worrying about breathing in the virus.
.
Connect (LON:CNCT)
Share price: 18.25p (up c.3%)
No. shares: 247.7m
Market cap: £45.2m
Smiths News is the UK's largest newspaper and magazine wholesaling business with an approximate 55 per cent. market share. It distributes newspapers and magazines on behalf of the major national and regional publishers, delivering to approximately 25,000 customers across England and Wales on a daily basis...
The previous subsidiary, Tuffnells, was loss-making, but has since bee disposed of.
Background - It's worth re-reading my notes from the interim results here on 13 May 2020. The main issues are balance sheet related - NTAV is negative at £(91.0m), and the group is reliant on over-sized bank facilities of £175m, which expire on 31 Jan 2021. The interim results contained a "material uncertainty" going concern note, over renewal of the bank facilities. Therefore this has to be seen as a high risk share, with the possibility of dilution for shareholders, if the bank forces it into an equity fundraising, as the price for continued bank support.
Today's update -
Core trading remains resilient despite the considerable disruption to the UK economy at present....
Newspaper & magazine sales were down 25% in the 6 weeks to 27 April.
Bringing those numbers up-to-date today, in the 15 weeks to 4 July 2020, newspaper sales were down 12%, and magazine sales down 18%. It would have been better to present these numbers in a table, rather than confusingly in text. I would like to have seen the trends more clearly. But it's an improving trend anyway. But a C minus for clarity of presentation.
More cost-savings have been identified.
Bank facilities - this is the big issue;
As previously reported, the Company has a £175m committed bank facility, comprising a £50m term facility and a £125m revolving credit facility. Despite the impact of the Covid-19 lockdown on trading, the Company has continued to operate well within the headroom under its current banking facilities. The facility is due to expire on 31 January 2021 and we continue to expect to complete the refinancing during the autumn of 2020.
That's ambiguous wording at the end. I continue to expect "the refinancing" may well have to include a hefty equity fundraising, and probably reduced bank facilities. But I'm guessing there, based on what we've seen in recent months at other similarly overly indebted companies. It's perfectly reasonable for banks to require shareholders to share the risk, in my view. The trouble is, with a market cap of only £45m, will there be much investor appetite to refinance an old economy, declining business like this? Maybe, maybe not. Nothing is said about accessing Government loan schemes.
Full year guidance - this is great, at last a company that actually gives guidance, I'll upgrade the C- to a B+!
Given the performance of the business during lockdown and the improved performance as a result of the gradual easing of restrictions, the Board now expects full year Continuing Adjusted EBITDA of between £35m to £37.5m (pre-IFRS16 lease adjustments) and Continuing Adjusted Profit Before Tax of between £26m and £28m (pre-IFRS16 lease adjustments) for FY2020.
Financial guidance within this statement assumes no further material COVID-19 lockdown measures introduced in the UK prior to the Company's 52 week year end to 29 August 2020.
That combines the pre-covid period with the covid period. Splitting it out;
H1 (26 wks to 29 Feb 2020) actual results: £16.3m adj PBT
FY 08/2020 guidance: £26-28m
Balancing figure, H2: £9.7m to £11.7m range
Assuming my figures are correct, that actually looks quite good. But we'd have to look through the actual results, check that all the adjustments are reasonable, and that the figures contain no funnies.
My opinion - I've covered the risks, which are substantial - this is a good example of a company which paid out too much in divis in the good years, took on too much debt, leaving its balance sheet weak going into the financial crisis. This isn't being wise after the event, I've been going on about balance sheet strength for many years.
If it manages to refinance in the autumn without diluting shareholders too much, then it could be quite an interesting special situation.
I'm impressed with how resilient trading has been throughout the crisis.
For me, the balance sheet risk, and the relentless downward trend for newspapers/magazines, tips the balance towards me not wanting to get involved. I'll keep my fingers crossed for shareholders that the bank is supportive this autumn.
I'll leave it there for today.
See the comments section for a discussion about Boohoo (LON:BOO) and Quiz (LON:QUIZ) and possible unethical production from their suppliers.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Hello SCVRers...this Odd Lots episode on Angrynomics is great (and then segue into general economic circumstances). You may agree or disagree depending on your tribe but the whole melting pot of s.h.i.t. of our times is very well succinctly covered here....
https://open.spotify.com/episode/46YcO357H3dVvrF3L62XYR?si=BpDB-QVHQ76sDRxee7tsQg&context=spotify%3Ashow%3A1te7oSFyRVekxMBJUSethH
Enjoy (or not).
Oh no! I see we've gone angry ;)
Interesting RNS from Bigdish (LON:DISH) this evening - LAC Ventures Ltd have purchased a 9.87% stake in the business. https://www.stockopedia.com/sh...
Has anyone come across this venture capital firm before? The investment appears to show some confidence in BigDish's company/strategy. Although, it's difficult to know whether their inputs and expertise can help drive the company to success.
As a keen follower of BigDish thanks to the SCVR (but currently non-holder), I'm trying to find a case to buy in. Not quite there yet.
Bigdish (LON:DISH)
Actually looks like LAC Ventures are sellers - they had 39,000,000 shares at the time of the AR now down to 36,000,000
Don't know if anyone else here holds China New Energy Ltd (CNEL). They're de-listing from AIM today and moving to Hong Kong. I've just been notified by IG that I need to sell out by 4pm today. Currently spread is 3.5p-15p (124%), so rather than taking a 100%+ profit I'm forced to sell at a 50% loss. Leaves a bad taste.
Bill Miller’s view:
The biggest problem with those who believe the market is disconnected with economic reality because the economic numbers still to come will be dreadful (and they will be) is that those numbers report the past and the market looks forward. The market predicts the economy; the economy does not predict the market. Stocks went down in the first quarter of this year and the first quarter of this year was a quarter of growth. Stock prices typically lead the economy by 4 to 6 months so it is, or ought to be, no surprise they have been headed higher. Why should they not be: Things are getting better not worse, earnings are bottoming and should begin to recover in Q3, the Fed has said they do not expect to raise rates for years, inflation is non-existent, interest rates provide no impediment to higher stock prices, and even valuations are not demanding at around 20x 2021 earnings given levels of inflation and rates.
https://millervalue.com/bill-m...
https://www.technocracy.news/world-economic-forum-the-institution-behind-the-great-reset/
Brand Architekts (LON:BAR) really is sickly dross. See here...
https://www.stockopedia.com/content/just-put-brand-architekts-previously-swallowfields-out-of-its-misery-518486/
I looked in past as cash made it look interesting...but nothing else makes sense
Most bizarre is that the small brand biz has kept the pension deficit of the production business Swallowfields it sold in 2019....and given the fall in asset values and fall in bond yields since last year end the deficit will be up from £9.5m at interim.
The only way to make sense of this nonsense is to assume that another corporate play is coming....and I'd guess that will liberate little shareholders from any value they think they have in portfolio of brands or that distracting lump of cash
Good point about pension deficit, thanks.
Covid: We are moving from hysteria to coping. This is a positive thing. It wont go away and its a new disease we will need to cope with. Physical distancing is not a possible solution and will not be obeyed particularly by under 30s and parents with young children so is not workable at societal level for any meaningful benefit. Mask wearing is a simple mitigation.
Fear remains acute particularly among a minority of population (and some should be fearful!). There remains much emotional/societal/economic upside as we overcome/cope. Extant fear is just not durable....it is collectively too exhausting and boring...move along now.
Even the surge in infection in US is part of coping process (fingers crossed it sustains pattern of high infectivity but lower morbidity). In Italy, epicentre of European trauma, the medical view is that the virus is quite widespread but of markedly decreases potency (except that a strange potent cluster still remains in Bergamo area).
Our economic position is that we have had depression like economic activity but without depression like capital destruction....capital preservation has been good and govt/CBs seem willing to sacrifice themselves to fill in private sector holes.
I'm bored of covid stuff. Stoicism rather than hysteria is the only path. When we accept that (and we are moving that way inexorably) then along with the 'abundant' capital we will feel like we boom....probably later in 2020.
Of course, market watchers are impatient...they've see the price V and they now are getting anxious in the gap between (always!) market unreality and our lived reality (we do it in other ways too...like the ridiculous belief in FANG-ish things).
But to believe in the end of covid is a nonsense...check yourself before you wreck yourself...onwards to the new new (new?) normal...
mojotruth out
with regards to face masks my take on them is the grade. A P3 mask should be used to prevent infection, one with a HEPA filter. These 2 Bob masks you see everyone wear only prevent droplets really. Imagine a fly (being the virus) passing through a patio door (the pore of a cheap face mask material)...... that patio door is not the correct micron level to stop the fly getting through. Useless for prevention from airborne dust particles that the virus has latched onto. Only OK for droplets.
There is no scientific evidence that masks prevent you getting the virus. Surgeons wear them because they cut open bodies and do not want bacteria getting into open wounds while they are operating on the patient. They also prevent you getting enough oxygen into your lungs, which becomes detrimental if you wear the mask for long periods.
Masks do not reduce oxygen perfusion nor blood levels. Plenty of people have shown that recently, over and over again with oximeters. I have worn a mask in theatre for hours on end, as have all surgeons. It takes getting used to. There is plenty of evidence that wearing a mask does reduce the passage of viruses in both directions though it is far more useful controlling the spread from the carrier. Covid may be passes around by those who have no clue they have it, so waiting until you are ill to put one on is unhelpful. Let's care for each other a bit.
When I became a pathologist and performed daily autopsies, I wore a mask to protect me, not the corpse.
Finally, I survived Covid but am still short of breath four months later. How ill you become seems to depend on the dose of the virus you catch. Anything you can do to avoid it or at least avoid a big dose of it is worth doing. A cheap mask reducing your chances of death and long term disability by even a few percent is worth it
A thumbs up from me (have to do this by writing a comments as currently I don't seem to have any access to clicking on the thumbs up count to add my vote) :)
nonsense
The Lancet had a review of 170 studies that argued for a 80% reduction in risk with the use of masks. I’m a doctor and was impressed with the study
Covid is a droplet infection and therefore it makes sense that masks work
I spent six years in the Army and we were required to wear NBC suits with respirators for long periods including sleeping with them on and running with full kit and rifle. I don't remember not getting enough oxygen or waking up dead.
Nothing worse than waking up dead, that's a bad start to the day.
My recollection was that slightly unscrewing the respirator cannister aided breathing... reduced survivability of course.
Marigold it would be great if you could provide links to articles to back up what you assert. Additionally the wearing of masks is not about preventing the wearer from getting the Covid19. I read a lot around the subject, I have a fairly significant holding in Avacta (LON:AVCT) (smaller ones in £GNR and £NYCT) so it is in my interest to do so and the general consensus seems to be that a mask does help prevent the spread of the virus if your are an asymptomatic carrier (presumably if you are symptomatic you will stay at home and self isolate). It is not about preventing the wearer from catching it.
Here is one article from the University of California San Francisco, which pulls together some stuff and states:
“Both the Centers for Disease Control and Prevention(CDC) and the World Health Organization now recommend cloth masks for the general public, but earlier in the pandemic, both organizations recommended just the opposite. These shifting guidelines may have sowed confusion among the public about the utility of masks.
But health experts say the evidence is clear that masks can help prevent the spread of COVID-19 and that the more people wearing masks, the better.”
You can read here in more detail:
https://www.ucsf.edu/news/2020/06/417906/still-confused-about-masks-heres-science-behind-how-face-masks-prevent
Kind regards
Michael
Yes, quite agree with PDiddy about the need for more effective masks. Understandably, manufacturers are still prioritising the highest standard of disposable masks for healthcare workers but at the weekend I ordered a P3 respirator (has changeable filters) made by GVS from Toolstation for about £20. It comes with filters fitted and at the time of writing you can buy additional filters from eBay. These masks are primarily intended for DIY work involving dust or fumes but protection from bacteria and viruses is listed in the details of what they can be used for. GVS is a respectable UK company (but not listed). Incidentally I have also ordered subsidised tests for SARS-CoV-2 antibodies from Simply Health (formerly Hospital Savings Association) for £49 each, but this offer is only available to members. As part of the price, a healthcare professional from Square Health (a company which serves the insurance industry) comes to my house to take a venous blood sample for the test, and this is likely to be more accurate than the fingerprick tests. I can't help thinking that the UK government should be providing subsidised good quality masks and should make accurate antibody tests more widely available as my guess is that there would be great demand for them and it would help in all kinds of ways. Looking at what happened about PPE, perhaps they lack the degree of organisation needed to to do this on a nationwide basis.
Re Covid and retail:-
peterg - I really hope that you're right. Time will tell. Let us know if you start going as often as before after the 24th. Will shop staff not wearing masks influence your decision?
Local large Tesco now seems to have abandoned most of restrictions - today, no staff member at the door restricting numbers entering, no one way system in operation, no "keep your distance" stickers on the floor, no socially distanced queue waiting to be called forward to the next available checkout.
Funnily enough, the Post Office counter immediately adjacent to the shop counter in our local McColls has a sign up saying "please remove masks before approaching the counter".
Hi Laughton - My local Post Office says "Please hang up any mobile call before approaching the counter if you wish to be served"
Thanks for the update on Vertu Paul. I had already bought the shares back before reading it as I thought overall positive, and fortunately no negatives in your update to change that.
If there is a no deal Brexit outcome that could well mean tariffs on cars and hence significant price increases from early next year. The risk of that might see potential buyers making sure they buy this year and give a useful temporary boost to car sales generally.
With shares in the sector bombed out and Vertu perhaps looking the pick of them, it seems well worth checking out the sector.
Vertu Motors (LON:VTU) My wife and I went along to our local Ford dealership the other day and they reported a similar story i.e. since the relaxation of the lockdown the last couple of months had been their busiest ever. I think some of this is to do with the fact that a lot of people with Mobility cars haven't been able to change their vehicles so are now playing catch-up. I think I read somewhere that the Mobility scheme accounts for around 10% of all news cars sold in the UK every year.
Hi Paul,
Thanks for your report again with good comments.
Given the recent stories that have popped out re Boohoo (LON:BOO) especially the Guardian news, could you update us as with any comments you may have? I am personally in loss (I guess like many others) having missed to sell at the bounce back, but am unclear whether or not it is a time to buy more or just sell at some loss?
Your insightful and helpful ideas are appreciated.
Cheers.
Paul, regarding looking at bombed out car dealer shares, one thing I think anyone who does needs to bear in mind is any overhang from the FCA review of the ‘sales practices’ at Lookers. I can’t find anything in their announcements to say this review is finished, probably because they have too many other fraud/other issues to worry about, so my assumption is it’s ongoing (someone please correct me if there has been an announcement I missed to this effect). I don’t know but my assumption is this is to do with selling PCP financing deals and (based on my own experience buying a car at another dealer firm) questionable transparency around how much interest is paid. I do also remember reading something to suggest the lawyers and ambulance chaser community were moving their targets here now the banks PPI claim period is over. Probably there are some good eggs in this sector, but not sure I’d touch it until it’s clear everyone is doing as they should.
Audit Standards
And we spend hours poring over the numbers and I thought Britian led the World in bean counting!
Bonitabeach
In macro corner commodities are leaning more towards inflation with Copper now up a decent 7% and silver more speculatively, up 20%+. However Iron Ore still down. AND the bond market could not care less. The fintwit Fed watchers suggesting the Fed is not in the market supporting bonds so someone is because 10 year yields are not budging. Maybe that's to come? The dollar is still stuck in its a range but at the lower bound with DXY trading around 96. This lock, where the Dollar and Bond yields don't move too much have allowed equity speculation in certain sectors to run away. Be interesting to see if we get a change, not much happening yet.
"no one needs to go to a bar but we all do need to shop"
I'm not sure why but there does seem to be a cultural or other reason why UK people are so negative about wearing masks. With the high street already really struggling to get back on track, I see this as a definite negative.
On the one hand HMG tells us to get back to work (implying that things are now much safer) and on the other hand they tell us that we must start wearing masks (implying that things really aren't safe after all). And why does the rule not apply to shop staff, are they not a risk or at risk?
And then they have the cheek to say that the public are possibly a bit confused about the "guidance".
Yes, as you say, we do all need to shop. But this new "law" is going to be the death knell for the high street. We've shown for the past three months that we don't really need to visit small independent shops so this is going to kill whatever hopes small retailers had and lead to even more demand for Amazon and others that can/have geared up for home delivery. You might say, let the fittest survive but, long term, a dead high street is going to have major implications.
Apart from all the above, why wait for 10 days to implement?? Is that when the supplies of masks are expected to arrive from Turkey?
Whilst I'm here - school children must return in September. What will they do there when unions instruct their teacher members that they should not work? After all, Boris has just handed them proof that things are not under control and being in an enclosed space with others (classrooms) presents a health risk.
Sorry, rant for today this morning over.
Yes, as you say, we do all need to shop. But this new "law" is going to be the death knell for the high street.
Why? The only reason a requirement to wear a mask in shops will be a death knell is if people refuse to wear them. Why should they? It's clear we are going to have to live with covid for some time at least. That means we have to adapt and act in ways that minimise contagion while also minimising economic impact. Masks are an easy way to do both those at little cost - except to those so sensitive of their egos that they won't be seen wearing one!
I haven't been to a shop since March. I'm far more likely to start going again if I can be sure most or all of the other people there are going to be wearing one. Why would you want to take the risk if they don't?
Well peterg, I personally won't be visiting a shop, not because I have a moral objection to wearing a mask - it's just completely unnecessary to go to the inconvenience and discomfort when I can just order online.
Cheerio High St.
completely agree so much easier and less risk in this crazy world of covid to sit at home and order online, delivered hassle free next day. high street was already failing before this outbreak if anything this is the death nell.
Yes, as you say, we do all need to shop. But this new "law" is going to be the death knell for the high street.
John Lewis isn't reopening some of its stores, Halfords and Boots are both shutting 60, GS4 is cutting 1,000 jobs because they're not needed for cash handling any more - and that's just this week. Non-food internet sales rose 42% last month - compared to 3% in June of last year. Barclaycard's figures suggest that 50% of people are still avoiding shops.
This is all before the furlough scheme ends and the full impact of the recession hits. Meanwhile we'll be dealing with Covid-19 for months to come - the government's worst case "120,000 dead this winter" modelling today is a precursor to preparing for a second wave which means, at best, we should expect social distancing measures to continue into next Spring.
Face masks are an irrelevance - the High Street, as we knew it, is already dead - it just doesn't know it yet.
timarr
Paul
What do you think about today's rebuttal of the ShareProphets dossier on Manolete Partners (LON:MANO) ?
It looks tome like a solid refutation of the claims, which would make Manolete Partners (LON:MANO) a good buy at 390p.
I'm not a current holder but I tend to agree this looks like a buying opportunity. The main trouble with holding Manolete and Burford is that other shareholders are so easily scared into selling so I think it's best to either buy and tuck them away or actively trade if that's your thing.
I looked at the accounts. The issues with these companies is accounting for revenue and valuation of work in progress. I couldn’t see a reasonable basis for valuation so I passed.
Hi FREng,
Would be interested in your view as to why Manolete Partners (LON:MANO) is good value today despite being marked at 5x TNAV, whereas comps like Litigation Capital Management (LON:LIT) and Burford Capital (LON:BUR) are sitting at just above 1x? I'm no expert in the sector at all and have only had a brief look at this morning through results and clearly Manolete have a leading position in what could be a buoyant market over the coming years but that multiple looks high to me.
I've long felt Manolete Partners (LON:MANO) are overvalued compared to peers. I prefer Litigation Capital Management (LON:LIT) as they value investments in litigation at book. It shows up the lumpiness of the business, which I guess is why the others "fair value" their investments to smooth the curve, but at least I know I'm paying for assets that aren't inflated and should have a much higher forward value if management are any good at their job! I am happier to blend average annual IRR over a 5-10 year window than fair value the accounting. Not that this approach has helped my short term return any I may hasten to add so maybe I'm just wrong!!
In Manolete Partners (LON:MANO) defence they have a model that is geared towards volume of smaller cases with much shorter paybacks, so I guess that is their argument for fair value accounting even if I don't like it personally. However, paying 5* TNAV vs 1* TNAV (lower on a fair value basis) seems analogous to me.
what I would say is that beware liquidity. Manolete Partners (LON:MANO) seems to jump and fall a lot on relatively low volume so you probably have to take a long term view. Cynically one wonders whether liquidity forms some basis for publishing short dossiers.
I'm not interested in litigation funding companies.
Someone here persuaded me to look at Manolete Partners (LON:MANO) recently, and I couldn't fathom why it is valued at such a high multiple of NAV, when Burford isn't. They can't both be valued correctly, in my view.
A horrible sector, I wouldn't touch any of them.
anyone interested in litigation companies should check out juradicia it went bust about 3 years ago
any comments on DFS (LON:DFS) trading update if time permits. Revenue down £271m to June 2020 with £100m deferred to FY21. Opex cut by only £23m in response shows negative side of high operating leverage. Loss for the year £56m v £50m profit last year. Cautious on demand outlook.
Somero Enterprises Inc (LON:SOM) thoughts;
Agree with Paul, great little company and balance sheet strong this time which is a massive positive. However to illustrate how hard it is to come up with scenarios for next year I can add,
Revenue drop through to profit very high > 50%.
This is accentuated by significant shifts in demand for large boomed machines. Demand can fall to virtually zero. These machines can be 10x the value of small machines. Huge growth in online delivery warehouses has and still is driving demand. Old machines are recycled into China so you get a tech cycle which is positive for pricing persuading the US mkt to trade in and up. As/If this unwinds it could have significant short term profit impact. US market retains old machines... so falling sales in US and nothing to sell in China.
In 2019 sales of boomed screeds held up well at $38m but I would worry about the percent of sales, 43%. BUT they did bring in a mid price range during this cycle, bolstering this revenue line so I would not expect this revenue line to be as cyclical as last time. Losing a decent chunk of large screeds however could cost you $20m revenue and $10m+ profit.
This years trend of investment by Amazon - Ocado etc clearly has helped on the one hand... but potentially just brought forward investment that would have happened anyway. Only time will tell.
Forecasts are up in the air. 2021 holding up but the rating on the stock has fallen to around 7.5x. My guess is therefore the market is just running broadly with the company, so profits fall 25% not something more severe if you assume the long term rating is c10x which is probably a little harsh. Its interesting that the shares bottomed at 150 in March... as that would be about 10x a halving of profit.
Given todays statement I continue to expect a gloomy 12 months but the profit outlook in the short term may have been helped by large machine sales holding up. This is not the usual recession out turn. However should they subsequently fall the profit outturn will be severe. For me, below the 150 level they get interesting. Its obviously difficult for them to say much without worrying they are affecting the market so whilst frustrating for investors, I understand why they don't want to say too much.
The other complicating factor is whether the rise in online shopping will lead to the need for yet more large warehouses requiring flat floors, thus triggering a potential boom in sales. I'm with Somero Enterprises Inc (LON:SOM) on this one - if you haven't the faintest idea what the next year will bring, why dress it up with guesswork?
I originally bought Somero on the basis of more warehouse/distribution required for online distribution. That won't change and I am aware that management seem good and the company very well funded. But I was a bit concerned on the references to the uncertain outlook on the whole commercial building segement in the statement. Given what has happened in the past few months I wonder to what extent commercial office space demand may actually be in long-term trouble and am uncertain as to Somero's exposure to this segement.
I think that the key here is what the wider construction market is doing, yes there is a market for precision leveled floors for warehouse facilities, but there are a lot wider uses within the construction industry that draw in the rest of their machinery, such as what is going on with the high rise construction market, nuclear, manufacturing facilities?
More importantly you have to look at the wider construction industry status. Are the companies that buy their equipment in a position to be making purchases right now? Will the CFO really sign off on this when many of the jobs bid in the last five years will now be loss making due to the additional costs that Covid has introduced? When we are typically talking a 2% margin on a well bid and well run job...
Thoughts on a postcard.
I do not hold. I have been watching for about 12 months and was put off by the "wet summer" explanation last year, and Covid has moved my hand further away from the buy button right now...
Hi Paul, interested to hear you’re short Tesla. The overall short position is now at it’s lowest level since 2015. Good luck!
Interested to hear if there are any short term reasons, other than the crazy rise in the last few weeks!
Could some please explain what has happened to the share price for Mitie (LON:MTO) today, please? Apologies, if this is an obvious reaction to today’s statement but, I clearly missing something here... Thanks
Trading ex-rights today
@Chris 101.1 According to the prospectus for the Mitie (LON:MTO) rights issue, the shares went "ex rights" today, so anyone buying Mitie (LON:MTO) today does not have the right to buy a further 11 stares for every 5 they hold, at a price of 25p.
So Mitie (LON:MTO) shares are worth a lot less today than yesterday but if you are a holder then you can buy a lot more at 25p or you can sell your allocation of rights shares in the market as nil-paid shares.
The value of the company is broadly unaffected by this as there are now a lot more shares at the lower price.
Thanks @FREng - appreciate your response.
Fevertree Drinks (LON:FEVR)
Steady as you go trading update today, decent mitigation with regard to minimising the damage with regard to the on trade covid related near wipeout of pub and similar sales.
UK Off trade sales up 34% 12 weeks to mid june and 89% increase in US offtrade sales in same period - Us comparatives flattered as they have new improved distribution deal this year.
I wouldn't say there is much read through with regard to this decent growth as it will nearly all be replacing their customers who would normally drink in bars and restaurants but can't. I would say though i would hope us sales keep growing even when sales morph back to being higher % on trade.
Europe looks like a bit of damp squid overall - although off trade sales are robust..
They have advised they are sticking to pre covid marketing - so that will probably really affect the bottom line this year - makes sense though to keep pushing the brand "whatever". Profits will likely be down 50% + perhaps - my estimate as they have given none.
Shareprice has bounced back very strongly showing 50%+ gain since last trading update in mid April and higher gains from the March low point. I don't have any plans to offload here as i am still in the fanboy camp despite the fact core uk growth pre covid we very anemic - plenty of opportunities in the rest of the world to keep things interesting - sales this year or next at worst should be over 50% non uk related so worldwide brand presence improving nicely.
Hi Rmillaree
I too continue to hold Fevertree Drinks (LON:FEVR) though I am now wondering if the new strategy is sell the day before the trading announcement and buy back at 09:00 following the inevitable crash?
I am in profit still even with the downward spike, after buying and selling through this years rise, lesson to be learnt here about buy and hold maybe?
I personally take the off-trade as good growth, this has been a growing market for years in the UK with the gradual decline of pubs etcetera, and if we are honest about the summer (not much of one looking out the window this morning) it feels to me there is going to be a lot more hanging out in back gardens with friends then going out for an evening. Therefore I personally feel that a lot of the off-trade growth will be "sticky" as it is not driven by massive one off BOGOF at the supermarket type promotions. I am also encouraged by international growth as lets be honest whilst whatever you may currently feel about the UK, there are a lot of large markets out there and 0.1% of the Global market is how many times bigger than 50% of the UK market? Whilst I would like that growth to be NOW, I am happy for them to achieve with a sensible strategy which does not overstretch the company and takes advantages of opportunities that might, or might not, exist with issues with other companies right now.
I personally remain cautious about the on-trade over the summer, I have sold the last of my small holding of Revolution Bars (LON:RBG) at a loss a few days ago. I feel that on-trade will slowly start to grow back but there is going to be a lot depending on weather, news and local hot spots. Nice weather and no real news worthy outbreaks and I feel the market will grow quickly, poor weather and/or one front page story in the major press of "50 people catch Covid-19 after going to their local" then it will go back rapidly, and personally I will hold onto the cash that I have left right now rather than take a decision on factors which are not in my assessment capability. I will either turn out to be a genius, or a numpty and only time will tell. But right now I choose sleep at night as my investment strategy.
Thanks
Tommy
Interesting announcement from Rbg Holdings (LON:RBGP) regarding the launch of a financing solution for insolvency claims. The company also has a nascent litigation financing arm, but the main profit driver is the its legal practice, which to-date has performed well. It strikes me as a much better risk adjusted way to access litigation financing given the opacity surrounding Burford Capital (LON:BUR) and current controversy regarding £MANO.
I hold.
Surely if £RBGB build up their litigation financing business they will face the same fair value accounting issues that scare people away from Burford and Manolete?
They run a different model. There was a Mello presentation that is on Pi World site by Tamzin which gave a good account of how they operate, Hope this helps. Regards Roy
Morning Paul, could you cover Adept Technology (LON:ADT)? Final results out this morning, I hold. Thanks
Interesting share AdEPT Technology (LON:ADT). Over the past five years it has been better at growing revenue than eps, and the debt looks large. OTH, they look to be turning round to better earnings growth.
Zoo Digital (LON:ZOO) FY(Mar) rev up 3%, pretax -$0.1m (-$1.3m). Net cash $0.7m. Outlook "Whilst it is not usual for buyers in our industry to commit to significant volumes of work in advance, the multiple significant media companies and digital distributors that now regularly use our services give us reason to expect that growth will continue throughout the year ahead."
Q1 rev 'at least' 15% up. Is that enough with the covid headwind driving work to the cloud (their USP) and streaming services booming?
Paul, I think the V-shaped Recovery will be about as long as a piece of string, the only one I can agree with is the one passed, March 11th to March 27th. I apologise in advance to those who may think I'm being facetious.
Silver Moon
Bango (LON:BGO) A very upbeat H1 update from Bango this morning stating record revenue growth of more than 50%.
Deals announced previously are forecast to boost H2 End User Spent to £2bn. (needs EUS of £1.26bn in H2 to meet this, H1 £0.74bn) Broker retains price target of 225p. I would like to see the more detailed H1 figures due to be released on 15 September to understand how the joint venture with NHN works. End User Spend margin looks to be at 0.65% which has recovered from the last period.
Share price hit 61p in March and now at 170p (broker EPS forecast of 2.4p for this year) A punchy valuation but the story, yet to be delivered, has always been about the future with this company.
Paul, any comment on the update from QUIZ yesterday? SP surprisingly reslient. Thanks.
Yes, interesting to see that Quiz (LON:QUIZ) announced yesterday that its also been caught out apparently using a Leicester supplier that seems to be in breach of minimum wage regulations.
Quiz's mkt cap is so small, and the founding family own a lot, that I doubt any ethical funds hold any stock. So the market has just ignored the announcement. I think the problem (and the opportunity) with Boohoo (LON:BOO) is that ethical funds are selling up, which allows the rest of us to pick up cheap stock.
QUIZ and BOO may, or may not, know that some of their suppliers could be operating sweatshops. This is a long-standing problem with garment manufacturing. If sweatshops in the UK are shut down, then manufacturing would just shift to somewhere abroad where wages are much lower, but speed to market isn't so good.
There have been numerous incidents like this, over many years, often involving designer brands. Its just how the rag trade works, and it's impossible for retailers to police their supply chains, which involve thousands of factories all over the world.
This problem applies to other sectors too. Of the 20-30k components that go into a car, I bet plenty of them are made in sweatshops. Apparently a lot "Made in China" stuff is actually made in North Korea, then moved over the border.
Some people like to moralise over all of this, but they're only fooling themselves. Capitalism is based on cheap labour, and that's how poor countries develop & become rich - through trade, not aid. As they develop, wages go up, and sweatshops decline. Let's be realistic about it.
Regards, Paul.
My morning smallcap tweet: Part 2/2
Futura Medical (LON:FUM) Connect (LON:CNCT) DX (Group) (LON:DX.)
Futura Medical (FUM) submits MED3000 (erectile dysfunction treatment) product dossier for review to EU body. FDA however needs additional clinical efficacy data beyond the Company's three months' home use study. Holders have been waiting forever for this to come good.
Connect Group (CNCT) guides FY adj pretax-cont £26-28m (pre-IFRS16 lease adjustments). Newspaper sales in the 15 weeks to 4 July 12% lower than the equivalent period pre-lockdown. Mags 18% down.
DX (DX.) June rev 3% below pre-covid exp. Guides FY(June) revenue and adjusted EBITDA in line.
"Holders have been waiting forever for this to come good". Choice words indeed MrC.
hi Paul
I commented on Boohoo (LON:BOO) yesterday
https://www.stockopedia.com/co...
I don’t suppose you feel like adding your pennyworth this morning?
Thx
Kind regards
Michael
I brought into Boohoo for the 3rd time just over a week ago and saw nearly 35% profit in that time. I have just sold the entire holding for a 5% loss (and consider myself lucky!!) I just don’t see how they come back from this. It has the feeling of a story that’s going to get worse for them with more stones being turned over to reveal horrible cover ups and side stories. Every chance I could be wrong of course but this won’t be going away for them anytime soon.
I think isn't it similar to £PLUS? Management credibility has gone in the bin for now. Both of these companies (on financial figures) were fantastic businesses.
One different was that PLUS was cheap, BOO is expensive. Clearly there are other reasons explaining this.
The thing is, where does BOO's competitive advantage lie? Unlike other brands, it isn't in their clothes. I don't even think it's in the cost, ASOS can be just as cheap and of course Primark are cheaper.
Thus I would say it lies in some intersection between logistics and marketing. Personally I think they are perhaps the best operators of polishing a turd: get a celeb to wear a cheap rag and demand can be stimulated and of course users will buy other things while they are on the website.
I can't quite guess whether BOO are exceptional in their processes or ASOS are poor to produce that disparity in margins, I think it's a little bit of both, as well as that ASOS seemed to try to position themselves as (not so) tacky and at a slightly higher age group. But this means the moat is surmountable. If ASOS or any other company had the same social media game the results would be the same. Their users are not buying the clothes because of the brand.
What I can't quite understand is why bother using £3.50 labour in the UK when you could pay less abroad? On that kind of scale the extra logistics costs is completely offset by reduced wages. I do suspect as with the PLT deal some kind of unethical desire to help out.
Did look at it last time it dropped into this range but I was fairly neutral last week, still am now but I would be interested if there were further falls.
"...why bother using £3.50 labour in the UK when you could pay less abroad?"
Boohoo (LON:BOO) can get small runs made very quickly and also cheaply in UK, essential to its test-and-repeat model.
I'm staying clear of this for now. If strong links to BOO's founder or mgmt are proven BOO may not be able to keep a lid on this political pressure cooker.
Boohoo (LON:BOO) could well go lower from here but I think this is a great buying opportunity for Boohoo in the long run. My reasons:
1. This is a massive space, in a technological rather than industrial economy (which I feel we are moving towards), if Boohoo really do understand the market better than anyone else they could be one of the largest UK companies in 5-10 years time.
2. Boo are the only online clothing retailer that I personally feel have made the online clothing model work. Used Asos as a teen and it was rubbish. Never used Boohoo but the results suggest they have figured out how to turn online clothing into a scalable business. Even Amazon hasn't really bothered with clothes.
3. Half of their profits now come from outside of the UK with the fastest growth in America. Will these sales be affected by the current news? They probably won't even hear about it.
4. Diversification. Personally I think the BH, PLT and NG brands are pretty gross but I can't really judge as I don't understand the youth of today (and I'm only 30!). The concerning pace of change aside, it seems like these brands could fade with fashions. But Boo are picking up distressed clothing companies with more longevity, and are showing an eye for transitioning from a small disruptor to a industry powerhouse.
5. Death of the high street. We all know this one, but it's only just beginning. Maybe lower rents will save the day but I don't see how shops will ever be able to reduce their overheads to a level where they can compete with online.
"I don't see how shops will ever be able to reduce their overheads to a level where they can compete with online."
The answer is they can't - directly. They need to offer something other to justify and charge a bit higher price and have a differentiated product (when online actually enables a much wider choice! as £Next 's last results presentation showed clearly..
For example, some services are best enjoyed/must be enjoyed in a physical way. These will remain. Examples might be (I'm told) buying a dress with others before chatting about it over a wine or other personal services. More prosaically, buying really fresh stuff that cannot be sent via the post (less & less in this category) - flowers, some food like fresh bread. For others it may be more convenient than online when combined with other tasks eg as an adjunct to working in an office (but less and less of this?) In short many small reasons why a High St will remain but it will be just much, much smaller and more orientated to services vs goods, especially low price ones.
I already start to see some shops converting to little offices and houses in my area where they are in fringe residential areas. Govt will likely look to push this conversion strategy to mop up surplus retail /provide houses on brownfield sites once COVID setles down. Will be interesting to watch.
Some of the margin difference is due to BOO selling their own clothes, and ASOS selling brands they don't own.
And BOO are buying up the dying high-street brands and reinventing them online (Karen Millen, Coast, Oasis, Warehouse), so some of the cheap rags are getting more expensive. I took a wander around the Karen Millen site...no shortage of dresses at £100+
Hi Michael,
It's a huge storm in a teacup re Boohoo (LON:BOO)
The share price is low because ethical funds are selling out. Once they're gone, the price is likely to go back up again. So I see it as a lovely buying opp.
There's little impact on the business model. If Leicester factories are breaking the rules, then they should be shut down - that's the job of Govt & its agents. Production would then just move to a low wage factory somewhere else in the world. That's how the rag trade works. Scandals about sweatshops happen all the time, and I cannot think of a single instance of it doing any lasting damage.
The bottom line is that most consumers want cheap consumer goods, and don't really care, or think, about the wages of the person who made the product.
Regards, Paul.
Thank you Paul. Re-enforces my prejudices. :-).
Having sold 15,000 shares at the March 19th low, I am looking forward to buying back some of those next few days.
Boohoo (LON:BOO) is currently a 3.7% position and I would like to see that go 5%.
Kind regards
Michael.
This probably won't go down well with people on here but some truthful 2 cents and it backs up Paul's bearish comments in a way:- its also now mandatory to wear a mask in shops to isn't it or risk of £100 fine. But not bars or restaurants what on earth???? That wouldn't be appropriate would it. I went into a bar in Saturday, never again, well until COVID is gone anyway, reason being table was unwiped and dirty, alcohol gel had ran out and people obviously who have had 1 to many staggering around not maintaining distancing. Had to flap arms around to get a waiters attention to. The whole thing peeved me off and just isn't worth it to myself or risk of spreading it to others. They also take your phone number but imagine if I get a message saying I need to self isolate for 14 days due to a patron contracting it? It's just not worth it. Especially when 2 recent stories of the BA pilot in his early 40s who has finally recovered after months in hospital having only 10% lung capacity. Or the early 40s star Broadway actor who has just passed away from COVID leaving wife and child behind after an amputation and numerous strokes caused ultimately by the virus. Why shouldn't it be blanket masks everywhere indoors? Because that would be inappropriate to an industry & economy which requires hand to mouth publically for profit to be made & jobs and the economy would suffer. An economy previously fuelled on the fragile, precariat service sector. Bring back industry & engineering and other sectors pls. I am in Pharma, have been nearly all my working life, I am sure it is no surprise that the stats with regards to vaccines are something like: it takes on average 10yrs to get a vaccine to market. Out of the thousands that are touted only 10% make it to clinic trials, of those only 2% make it to market. It's more about big Pharma share prices than the vaccine I imagine, who can hand on heart say after numerous big Pharma scandals in decades gone by that that vaccine if it does get to market will be safe? There have been numerous scandals from the 10 year route drugs. Theres my glass half empty comments of the day. Personally I have pumped my hard earned into mining, litigation law companies and tech. Doing quite nicely thus far and soon even better with half year results not to far away.
I can't share this pessimism. Obviously you can't enjoy a meal while wearing a mask. Our choice is for places with outdoor tables as outdoors presents little risk. Our meals inside will initially be in higher quality restaurants where the tables are already generally further apart. We are in our 70's and we can't spend our lives hiding or we will run out of time! As regards finding a vaccine or medication I believe that with the incredible leaps in technology we see on a yearly basis we have the capability of achieving results that were not possible even in the recent past.
I've worked in Pharma or adjacent consulting for 15 years and I agree with PDiddy on all except the safety issue. The chances of us finding a one-shot, lifetime vaccine are small at best, growing ever-smaller with the discovery that COVID immunity lapses after mere months. I think the best we can hope for are seasonal jabs for high-risk patients and better acute management for the desperately ill.
That's the best I think we can hope for. To have that by the end of the year seems risible to anyone with industry experience.
Masks are crucial in halting the spread. Look at Japan, Korea as examples where masks are mandatory and infection rates are low. You cant argue with the evidence.
Can anyone share a link to any actual scientific evidence on mask wearing by the public?
I'm not anti. It's a small inconvenience and may well help, I would just like to see the actual evidence.
Have a look at this Edinburgh University study.
https://www.ed.ac.uk/covid-19-...
From the link:
Surgical masks and the tested hand-made masks were found to limit the forward flow of a breath out, but also generate far-reaching leakage jets to the side, behind, above and below. Heavy breathing and coughing, in particular, were shown to generate intense backward jets.
Only masks that form a tight seal with the face were found to prevent the escape of virus-laden fluid particles, the team says.
I wonder what this does for the viral load for someone suffering early stages of Covid-19 who is wearing a mask? Presumably the expelled virus gets trapped between the face and the mask and is then breathed in again and again and again.
And a large viral load leads to large problems for the patient.
Masks
My co sent me a 'snood' which had been sprayed with a magical substance which kills or nullifies the virus and is washable. I'll have to find it and see who makes it. A bit warm to wear at present but a definite in the winter and reduce the blow outs. May spray it with vodka, gin etc although risk getting bretalysed.
Pubs
On two experiences I feel hygiene will not be up to a good standard. Not staff fault, not trained in hygiene, may not be well motivated and perhaps don't see a problem (aka young). With a second wave so early and clearly still around and in my 60s its not something I will be repeating for a while and have bought £WINE.
Spraying
Someone told me they were spraying over London at night and it has affected their allotment yields. Not sure what to do with finance except find out who the German chemical companies are profiting. Live in London so my cancer risk has just risen along with heart and lung disease. Happy days.
“ Someone told me they were spraying over London at night and it has affected their allotment yields. Not sure what to do with finance except find out who the German chemical companies are profiting. Live in London so my cancer risk has just risen along with heart and lung disease. Happy days.”
Really?
https://fullfact.org/health/coronavirus-helicopters/
'spraying London a night ' ??I cannot believe that anyone really believes this sort of thing. It just seems so unlikely
I have not seen it referred to in any newspapers that I have read
"Someone told me they were spraying over London at night and it has affected their allotment yields. "
I think you can safely file whoever it was in the "barking mad" category!
Here
Links
From the top link (the lancet)
Our search identified 172 observational studies across 16 countries and six continents, with no randomised controlled trials and 44 relevant comparative studies in health-care and non-health-care settings (n=25 697 patients). Transmission of viruses was lower with physical distancing of 1 m or more, compared with a distance of less than 1 m (n=10 736, pooled adjusted odds ratio [aOR] 0·18, 95% CI 0·09 to 0·38; risk difference [RD] −10·2%, 95% CI −11·5 to −7·5; moderate certainty); protection was increased as distance was lengthened (change in relative risk [RR] 2·02 per m; pinteraction=0·041; moderate certainty). Face mask use could result in a large reduction in risk of infection (n=2647; aOR 0·15, 95% CI 0·07 to 0·34, RD −14·3%, −15·9 to −10·7; low certainty), with stronger associations with N95 or similar respirators compared with disposable surgical masks or similar (eg, reusable 12–16-layer cotton masks; pinteraction=0·090; posterior probability >95%, low certainty). Eye protection also was associated with less infection (n=3713; aOR 0·22, 95% CI 0·12 to 0·39, RD −10·6%, 95% CI −12·5 to −7·7; low certainty). Unadjusted studies and subgroup and sensitivity analyses showed similar findings.
From what I understand it reduces the chance of you catching it a bit and reduces the chance of you passing it on a lot.
Not sure scientific opinion is as much use as common sense when it comes to masks.
Why were most of us taught to cover our mouths when we sneeze?
Also figures from a Countries where masks are compulsory or in very widespread use are more use on this than scientific opinion. And there is clear evidence that those Countries had way lower infection and death rates.
And scientific opinion has been so wrong at times. e.g the advice given to the Government which the Government swallowed that care homes were at no risk from covid. Anyone with an ounce of common sense would know that if care workers and visitors were carriers then that care home was at risk.
Hi ken mitchell,
Agree your comments, save :
.."Anyone with an ounce of common sense would know that if care workers and visitors were carriers then that care home was at risk. .."
AIUI, it's a 'first' for a virus to exhibit the combination of a delayed, frequently asymptomatic response. So neither the scientists nor , apparently, the carriers themselves, would necessarily be aware of the risk.
ATB
Should have added my source : The Spectator, relevant extract , where writer Fraser Nelson
.."critiques the standard explanation: that older patients were discharged from hospitals in a panic, seeding the virus into care homes. In the past few weeks, I’ve been talking to those involved and found a different story. The order to clear hospitals was given on 17 March and 25,000 patients were discharged to care homes between then and 23 April. Is that proof of a panicked exodus? On the contrary: it’s business as usual for the NHS who sent 35,000 to care homes in the same period last year. Yes, some 30,000 beds were cleared and lay empty throughout the crisis, but that was achieved by stopping the inflow. Had this seeded the virus into homes, we would have seen an infection boom in care homes. Instead, it was a slow burn with the full horror taking some time to become apparent. The number one problem was our failure to realise early on just how many people are barely affected by Covid-19, spreading the virus asymptomatically..."
ATB
So :
Allegedly.
The quoted 37 day reporting period does not appear to be a standard reporting period for the health and social care sector, so I cannot validate the numbers.
Even if the stats are true it is worth noting first that, pre-covid, the winter had been pretty mild in terms of influenza and well below the five year average that is often used as a baseline.
Secondly FN appears to accept that an instruction for advance discharges was given and contemporaneously that is what I heard from within the system and also witnessed a number of discharges that earlier than we would have liked or expected.
However, I do accept that it was not known at that stage that Covid was capable of asymptomatic transmission, but that is not a novel concept in virology and it was certain not known that it was not!
By the same token I am not convinced that the Government were given (scientific) advice that "care homes were at no risk from covid". That does not sound like the way scientists work - I my very first science lesson I was taught (and it stuck) was that you cannot prove a hypothesis, only disprove it.
It may be true that the scientists under-estimated the risk to care homes or perhaps the decision makers failed to process correctly the information they were given - we may not ever know.
On the subject of masks, I do agree with ken that it is "common sense" that covering your face reduces the spread if you exhale (normally or violently) whilst infected. However, there is not strong evidence that this is a powerful effect in this case, There are other factors to consider.
One of the things I noticed going to the supermarket early in the lockdown was that whilst people were meticulously trying to keep their 2 metre distance, many of those that were not were those that were wearing masks. (Many seemed to think mask = immunity).
Unfortunately, I think the messaging now has been totally lost in a fog of blather.
I was originally broadly supportive of the UK response to covid, even though I am not fan of Boris or his boss, but I now find I'm tearing my hair out at how shambolic it has become.
Based on the early government responses I was quite confident of a V(ish) shaped recovery economically, now I am more inclined to think it my be a W with a last stoke that may either side of horizontal.
“ And scientific opinion has been so wrong at times. e.g the advice given to the Government which the Government swallowed that care homes were at no risk from covid.”
Were they given that advice? Could you cite your source for that please?
Graham
I’ve just seen your post. With luck someone else will post a source for that. If not I’ll see if I can find confirmation sometime tomorrow. There has been a lot of media coverage on this and Government Ministers including Matt Hancock have referred to the early scientific advice they were given that care homes were not at risk from coronavirus. I would be surprised if others reading this thread were not also aware of that advice.
Well hopefully you can find something to back it up.
And if that turns out to be the case that this not just the benefit of hindsight.
Graham
Will this do?
https://fullfact.org/health/co...
Ken
I’m afraid it won’t. That link is talking about advice from the government. It doesn’t mention advice from scientists which is your complaint.
But let’s assume for a moment that this was based on scientific advice. The number of cases was so low at the time this was issued that the risk was very low. So, it was a correct statement it seems at the time it was issued. However, the situation was moving very fast and that advice should have been withdrawn sooner. Easy to see with hindsight. Not so easy in the maelstrom of a fast changing pandemic from a completely new disease.
Graham
It’s not worth pursuing this further as we’re at cross purposes. I wasn’t complaining about anything, and just stating a fact. Namely that wrong advice had been given; namely that Care Homes were not at risk from covid. And it was Government Ministers and not me who said that advice was from scientists.
And it was Government Ministers and not me who said that advice was from scientists.
That probably reduces the confidence we should have in the statements, not increases it!
The thing is the statement as given was correct in its context.
“This guidance is intended for the current position in the UK where there is currently no transmission of Covid-19 in the community.
“It is therefore very unlikely that anyone receiving care in a care home or the community will become infected. This is the latest information and will be updated shortly.”
At that time there were I think 13 reported cases in the UK and the view was still these were imported & direct contacts.
However, I think it was clear that we were planning for the eventuality that community transmission would occur - although it is not apparent that there was a coherent forward plan for care homes at that time.
Namely that wrong advice had been given; namely that Care Homes were not at risk from covid
AFAIK there's no evidence that any advisor ever said that - but nor is there any evidence that they didn't. There was advice from PHE on February 24th that recommended that care homes be shut to new admissions in the event of a Covid outbreak. There's also a statement from Sage in late January that care homes should be subject to special measures.
The PHE advice changed in late March - the suggestion is that that was a political decision in order to make space in hospitals. Again there doesn't appear to be any evidence either way.
What is definitely true is that care homes didn't have access to testing until April and only this month have they had access to repeat testing. Nor did they have access to PPE on any scale until last month - and those aren't failures of advisors.
As yet we don't even know whether the main source of care home infections were patients being discharged from hospital. It's certainly the case that some infections were spread by agency staff moving between homes, that may have been the major issue. Again, not an advisory failure.
Broadly the evidence that the care home disaster was driven by scientific advice is at best unproven. And even if people with infections were discharged into care homes the overall impact could have been mitigated by proper testing, PPE availability and proper funding to ensure they were properly and permanently staffed.
Also, Sage's advice was driven by what they believed was possible to deliver given our state of preparedness. Both Patrick Vallance and Chris Whitty have been clear that had we been better prepared - and after Exercise Cygnus we should have been - then the advice would have been different.
But probably the biggest overall factor in the outsize number of deaths in the UK was the lack of testing. We were two weeks late locking down because it was believed we were three weeks behind Italy on the infection curve. We weren't.
timarr
Government Ministers will be very careful to be selective about which "scientific advice" they quote and refer to. Scientific advice that the government could not comply with because of inadequate PPE and testing facilities was discounted as undeliverable; despite being highly desirable.
The only thing that is clear to me is that the Government panicked and devoted and wasted enormous resources, energy and money in grand schemes (Nightingale Hospitals etc) when some basic sanitiser and face masks would have been far more effective.
We shall only ever know what they wish us to know.
Bonitabeach
No, that's what the govt said. We have no real idea what Sage were telling them.
Re: Covid-19 pandemic & lockdown
Then don't touch your face (or mask) with unsanitised hands; and wash or sanitise hands well before eating.
There has never been a vaccine for HIV because it mutates too quickly - could be similar for Covid-19 - I hope not and, given the unprecedented amount of effort and optimism from well-placed sources, I'm hopeful for a vaccine available by next spring. There are apparently multiple different strains of Covid in circulation, which seems to suggest it does mutate quite quickly, so that I think if vaccines are developed, new ones will need to be developed each year.
PDiddy
The thing with covid is that every little bit helps - with R0 close to 1 small changes in behaviour could be the difference between ongoing levels staying above 1 with continued growth in cases and a level below 1 in which case covid should dwindle away. It's not really asking too much for someone to wear a facemask in a shop - so this minor step might seem a drop the the ocean but it will help aiding the decline or limiting the growth. With regard to difference between shops and bars - this is a bit of a choice thing - no one needs to go to a bar but we all do need to shop unless we are lucky enough to have altenative arrangements in that regard.
The daily email from John Authers (Bloomberg Opinion:Stocks Bang Their Head on an Inefficient Ceiling) makes some interesting international comparisons today for the return to normal activity and the percentage death rates. On these comparisons he says that the UK is "an unmitigated disaster".
Yes. John Authers is almost always interesting and thoughtful. In today's article he shows how the UK has managed to get the worst of all possible worlds:
* among the highest death rates in the world (though Trump and Bolsanaro seem to be jealous of our ability to hit the top of the charts and are doing their best to overtake us)
* among the worst for economic activity
There are arguments for the Sweden model - keep the economy open, avoid the hidden damage caused by the lockdown (untreated cancer patients, domestic abuse, depression...)
There are arguments for the shut down fast and hard model (e.g. New Zealand, South Korea, China...).
We did neither. Instead we have been too slow on everything. I live part time in England and part time in Austria. The UK has sea borders so it should have been easier to keep the virus out and trace it when it arrived. But e.g.
* we are starting to introduce mandatory face masks in shops. Austria's outbreak is now so well controlled that they dropped the requirement for face masks in shops
My morning smallcap tweet: Part 1/2
EKF Diagnostics Holdings (LON:EKF) DFS Furniture (LON:DFS) Elecosoft (LON:ELCO) Somero Enterprises Inc (LON:SOM) City of London Investment (LON:CLIG) McBride (LON:MCB) Netcall (LON:NET) Mattioli Woods (LON:MTW) Brand Architekts (LON:BAR) Filta Group (LON:FLTA) Bango (LON:BGO) Manolete Partners (LON:MANO) IQGeo (LON:IQG) Clinigen (LON:CLIN) Vertu Motors (LON:VTU)
EKF Diagnostics (EKF) guides H1 rev £26.3m, adj EBITDA £9m, beating May guidance of of at least £25m and £7.5m resp. It's largely due to high demand for the PrimeStore MTM Device which is used for safe covid sample collection. Expects H2 to continue this momentum.
DFS Furniture (DFS) guides FY(june) rev down 27%, pretax -£56-58m excluding Sofa Workshop and Dwell restructuring costs. Order intake 1 June and 12 July up 69% but remains cautious for remainder of 2020 and into 2021, given likely lower consumer confidence and a potentially slower residential property market.
Elecosoft (ELCO) guides H1(June) rev down 4% but adj pretax up 14%.
Somero Enterprises (SOM) guides H1 rev in line. Net cash at least $28m cf pre guidance $24m. Outlook - too soon to say.
City of London Investment Group (CLIG) guides FY(June) FuM up 2% on $.
McBride (MCB) guides FY(June) adj pretax ahead of current market consensus of £21.6m.
Netcall (NET) guides FY(June) in line with market expectations: rev up 10% and adj EBITDA up c. 29%. Net cash ahead of exp. "Board anticipates that the disruptions caused by the pandemic will accelerate organisations' digital transformation initiatives."
Mattioli Woods (MTW) guides FY(May) profit in line with prev guidance. CFO resigns, becomes Chief Strategic Adviser.
Brand Architekts (BAR) guides FY(June) rev-cont down 17%, better than April's guidance. Outlook "there is still a great deal of uncertainty surrounding the impact of COVID-19 on the wider economy and consumer confidence, we expect this will continue into the first half of FY21, with some improvement in the second half."
Filta Group (FLTA) AGM stmt: June rev up 38% on May. Co has been cash generative Jan-June. Expects revenue trend seen in late Q2 to continue into Q3.
Bango (BGO) guides H1(June) rev up over 50%, adj EBITDA above whole of prev FY.
Manolete Partners (MANO) long refutation of bear note published on Friday since when SP has fallen 15%.
IQGeo (IQG) guides H1(June) rev up 11% and orders up over 100%. Outlook "IQGeo sees continued market demand reflecting the fact that both telecoms and utilities markets have been less affected than other sectors."
Clinigen (CLIN) guides FY(June) rev up at least 13% and 17% at const currency. Adj EBITDA up at least 29%. Outlook "We continue to see organic growth in line with our medium term guidance at this early stage of the new financial year, despite COVID-19 and expected competitive pressure to Foscavir. As we look beyond FY21, we see growth significantly accelerating as we onboard new asset Erwinase and we continue to gain share in the end-markets we serve."
Vertu Motors (VTU) June trading stronger than co expected with adj pretax £9.0m. Cash position was "much stronger than we could have hoped". Will make 6% of staff redundant. No FY guidance. I hold.
Ekf Diagnostics Holdings (LON:EKF) report:
Due to the continued demand for PrimeStore MTM, full year performance is likely to exceed and possibly significantly exceed previously revised management expectations.
If only we knew what their expectations were ... but the momentum here is all one way.
I'd also like to vote for the Fevertree Drinks (LON:FEVR) trading update as the worst ever produced by a near £3 billion company. Lots of happy waffle and figures about the rise in Off-Trade business but silence on the On-Trade other than an opaque comment on "gross margin headwinds". Utterly useless.
timarr
Completely agree with this re. £FEVR. Since they have deemed it unnecessary to mention on-trade revenue, do we assume this is near zero? That they think it is better to avoid disclosing altogether speaks volumes as far as i'm concerned. Also on the acquisition to "optimise route to market"; surely with a cash consideration of 2.6m, plus balances owed at 5m and settling debts at 1.8m it would appear the acquired co. was insolvent and Fevertree Drinks (LON:FEVR) were possibly forced to buy it out as the path of least resistance? The entire TU just smacks of treating shareholders like mushrooms i.e. kept in the dark!
Fevertree Drinks (LON:FEVR)
FedReverse
Since they have deemed it unnecessary to mention on-trade revenue, do we assume this is near zero? That they think it is better to avoid disclosing altogether speaks volumes as far as i'm concerned.
I think the comments today have to be read alongside the recent update of the 4th June and the update 22nd April - thats 3 updates in short space of time - no real need to repeat the same known bad news multiple times. I am well aware on trade is pretty close to being a complete wipeout so any numbers in that regard are mostly meaningless. So given the knowns based on the previous updates i will make do with the stats from off trade only which are at least ticking over nicely. I do share your annoyance that they can't just quote some consistent KPI's however crap they are just for some semblance of clarity. Perhaps an email of complaint or three to relevant bods is order - i am fine sending one with constructive criticism that rgeard - ditto with regard to lack of profit estimates.
Ref acquisition it's too small beer to relly worry about , many companies have negative retained reserves - if it gets them any "in" with regard to increasing or maintaining presence in the German market i will presume that's business - better to have control over an entity like that than no control whatsoever generally - unless all the key bods simply walk out which i guess is posisble.
Ekf Diagnostics Holdings (LON:EKF) definitely has strong momentum (I hold). The 15 May trading update said that full year expectations would be exceeded, perhaps considerably. This led broker upgrades for FY20 of 13% (revenues) and 26% (adj EBITDA). So far, I have not seen any broker upgrades this morning but given the similar wording in today's statement, I could imagine similar upgrades.
What is clear is that the PrimeStoreMTM boom is lasting longer than management previously assumed and now the order book looks full through to the end of Q3. I wonder if orders continue into Q4, will we see yet more upgrades.
What was noticeable from the broker notes in May was that although 2020 numbers were upgraded considerably, 2021 numbers were left unchanged (that is well below the upgraded 2020 levels). As the Covid saga drags on, it is more likely that the PrimeStoreMTM sales boost might continue into next year.
I also hold EKF Diagnostics Holdings (LON:EKF) (a starter position only). Is it not also feasible that all the cash being generated during the virus saga from PrimeStoreMTM will enable EKF to expand via acquisition...?
andrea34, Ekf Diagnostics Holdings (LON:EKF) will pay a maiden dividend by the end of the year of 1p/share, give a perspective yield of 2.2% and costing them £4.5m.
I may be wrong but don’t really see them doing any large acquisitions - maybe increased collaborations and JVs. Or more likely they might be acquired by someone else.
I think the acquisition binge some years back (Selah for example) hurt them greatly at the time, so now they are far more circumspect; and given the performance of the company, I don’t see any need for them to make one. More likely a special dividend next year if the current level of cash generation continues.
You may want to also take a look at Renalytix Ai (LON:RENX), which was spun out of Ekf Diagnostics Holdings (LON:EKF) in 2018 and is seeking a dual listing on Nasdaq (EKF still retain a significant shareholding). Currently loss making, but if you believe that AI will have a transformational impact on diagnostics and prevention in the next decade, then they might be worth tucking away.
Hi Timarr re Fevertree.
And their tonic is not as good a schweppes!!
My favourite is Nordic Ice but i can only get it in Spain
Morning Paul: could you have a quick look at Connect (LON:CNCT) please? A positive update this morning and the business seems quite resilient. It reads as though the expect to refinance the debt in the Autumn: something which will likely form a catalyst for a re-rate. I am long on this one.
Cheers
Andrew
Pre close statement out of CLIG, which I hold.
Revenues look fairly flat, dividend held, merger approved.
I will continue to hold.