Small Cap Value Report (Tue 14 Mar 2023) - ASC, NGHT, TUNE, PCIP, EYE, MIDW, ETP, VINO, SDRY

Good morning from Paul & Graham!
Today's report is now finished. We covered most of the things on the to do list.
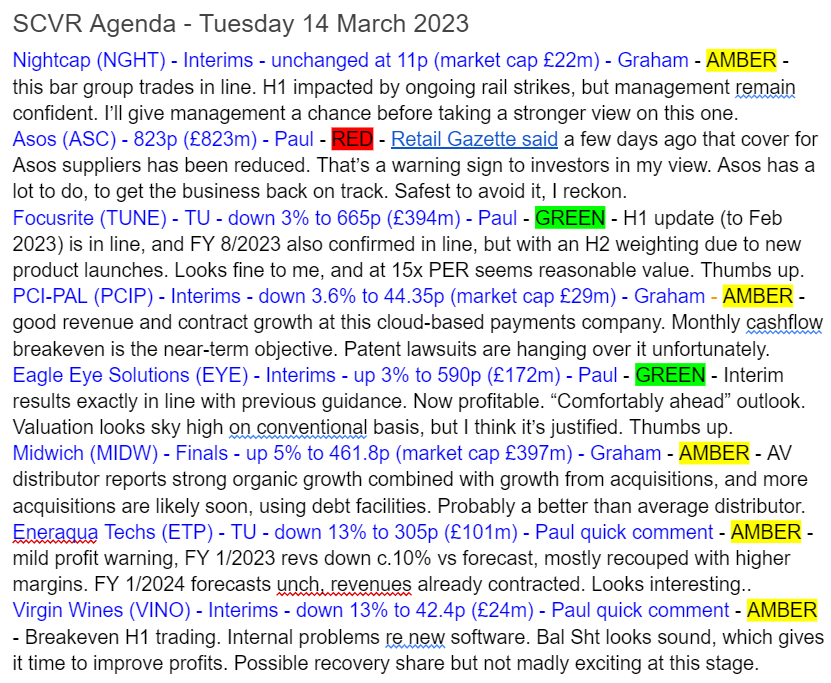
Superdry (LON:SDRY) - I forgot to mention this yesterday, but there are press reports that this fashion brand has called in Interpath Advisory, to help it restructure & cut costs. That doesn't sound good, does it? It suggests to me that the company must be seriously struggling, which f you strip back the presentational gloss put on its last poor interims results, was obvious from a little digging - see my report here on 27 Jan 2023, where I pointed out the problems. The way I look at it, if the business was trading well, then there would not need to be consultations with expensive advisers. The last update showed that there was some sign of improvement at the stores, but that wholesale orders had plummeted. I'm changing my view from amber, to red, at this latest worrying sign. Thumbs down from me, it's too risky right now.
Banking problems
We seem to be in something of a banking crisis, although not many people in the UK are aware, because our media is instead obsessing over something Gary Lineker said on Twitter.
It's difficult to know where this latest banking problem (mainly SVB) ends. On the upside, swift actions have been taken so far to contain the problems. On the downside, it strikes me that overly fast interest rate rises have put a big strain on the system, and the cracks are now appearing. What other strains are lurking below the surface at other organisations which held a lot of bonds (which are now worth less)? Might banks be more cautious in agreeing new lending from now on?
At the moment I cannot see any reason to panic sell any of my shares. Let's just hope it all blows over, and it might at least stop the central banks from continuing down their dangerous path of raising rates too far, too fast? You can't have zero rates for 14 years, and then flick a switch to return to normal, without it doing a lot of damage, as we're discovering.
Graham and I decided not to cover the flurry of RNSs yesterday relating to Silicon Valley Bank UK, because it was announced first thing that the bank had been saved, with HSBC buying it as a going concern. Hence any impact on customers should presumably have been resolved. Indeed, as an example, I see that Polarean Imaging (LON:POLX) suspended its shares yesterday over uncertainty re SVB, but has today said there has been no impact, and everything's back to normal, so wants to unsuspend its shares.
Storm in a teacup, or the tip of the iceberg? No idea, we'll just have to wait to find out.
P.S. Budget Day tomorrow, so it's being/been leaked to the media as usual. Apparently a big rise in the pension lifetime allowance is likely, because too many people are retiring early to avoid getting clobbered with punitive pension taxation.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Focusrite (LON:TUNE)
685p (pre market open)
Market cap £406m
Focusrite plc (AIM: TUNE), the global music and audio products group supplying hardware and software used by professional and amateur musicians and the entertainment industry, is pleased to give the following update on trading for the six months ended 28 February 2023 ("H1 2023").
H1 2023 Trading Update: Profits in line with expectations
H1 2023 profits for the Group are in line with Board expectations and remain unchanged for the full year supported by stronger gross margins.
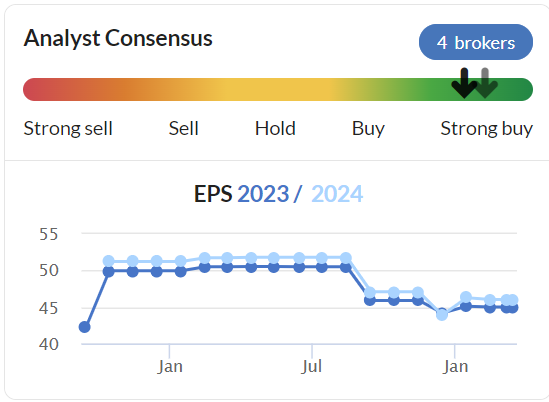
Broker forecasts - Note that broker forecasts stepped down in Sept 2022, but have remained almost flat since. So to be on track to meet the full year forecast seems fairly good to me. I can’t see any update notes available to us today.
What we’re seeing at lots of other companies, is an almost continuous lowering of forecasts every month. This looks more solid -
Other points in today’s trading update -
H1 revenues expected to be c.9% down on H1 LY, at £85m
H2 weighting expected this year due to new product launches, which rings a bell, so I think this has been previously flagged.
Weakness in Asian markets - again I think has previously been flagged.
Improved gross margin due to - lower freight costs, supply chain easing, and price rises to customers - all good.
Net debt has risen to £14m, but that’s not a concern to me, as it’s well within the facility limit, and easily affordable based on profitability. Not a concern. The increase is mainly due to £8.2m acquisition-related payments & inventory build for new products.
My opinion - this all sounds fine. Focusrite has always struck me as a decent company, with a really good track record. Although the valuation previously ran much too high for my liking. It’s now much more reasonable, and 15x forward earnings (confirmed today) strikes me as a nice entry point for long-term investors.
It would be worth deeper research to find out what the new products are, and how they compare to the competition. To some extent, TUNE has to keep innovating, as the products have a finite life. As I always mention, musicians I know tell me that TUNE’s core products are excellent, but tend to be one-off purchases. Hence why making new, improved versions is important to drive repeat purchases.
Overall, my view on TUNE shares is positive, so it gets a thumbs up. As always, that's just an opinion at this point in time, based on the information we currently have. I'm not Mystic Meg, so have no idea what the future holds, so our opinions might change in future, as the facts change.
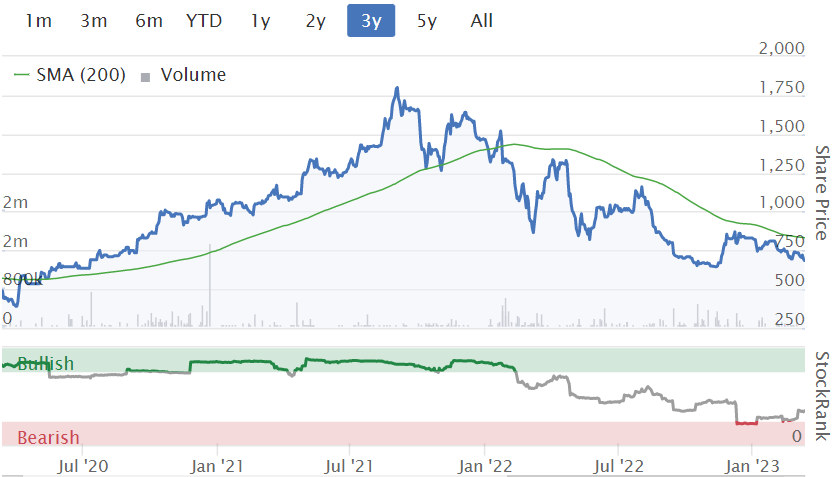
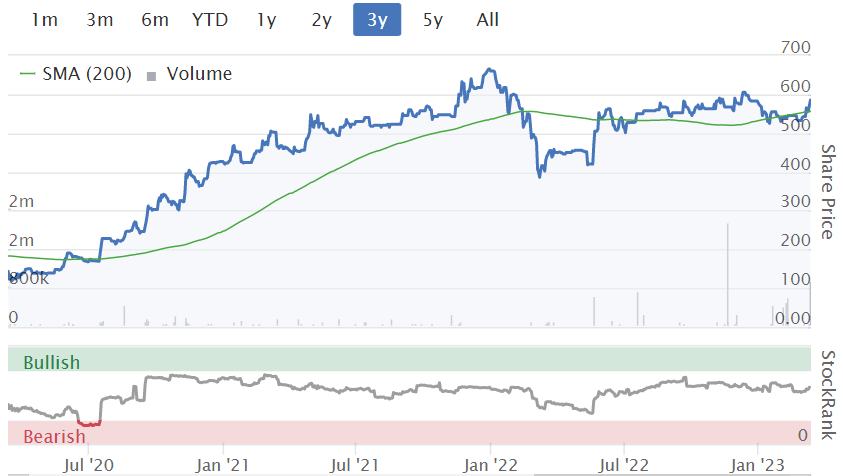
The StockRank seems strangely low, for a good quality business.
Eagle Eye Solutions (LON:EYE)
590p (up 3%)
Market cap £172m
Eagle Eye, a leading SaaS technology company that creates digital connections enabling personalised, real-time marketing through coupons, loyalty, apps, subscriptions and gift services, is pleased to announce its unaudited interim results for the six months ended 31 December 2022 (the "Period").
Strong organic growth and acquisition of Untie Nots supports continued expansion
Rummaging through the numbers, this is starting to look like a proper, viable business now, after years of jam tomorrow, cash burning. That’s really good to see, and is so rare in the UK market unfortunately. I wonder what percentage of speculative shares actually make it to profitability, without ruinous dilution? Sounds like a good question to ask ChatGPT. ChatPAUL’s hunch is that the number would be very small!
So congratulations to EYE for achieving success. There’s no doubt now that this is a good business, growing strongly, and now profitable. The only question is how to value it? That’s tricky because there’s no definitive way to value growth shares, and different investors use often wildly different methods. Higher interest rates also mean tech/growth shares are worth a lot less, as future profits are discounted to a lower number the further out in future they are.
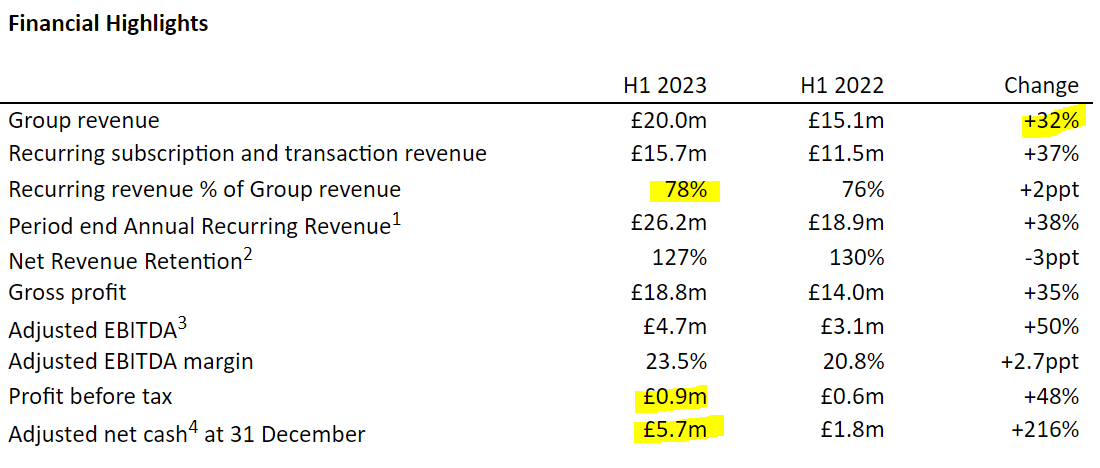
Some key numbers in the table below.
Strong growth - all organic I believe (an acquisition completed a few days after this period end, so won’t have contributed yet)
High proportion of recurring revenues is a good thing, that investors obviously like.
Very little profit before tax of £0.9m, but I’d be happy to add back acquisition-related costs (as one-offs) of £1,068k, and tax credit, which takes PAT to about £2.0m for H1 - not too shabby at all.
Note that the numbers below look exactly the same as the pre-announced numbers in its 18 Jan 2023 trading update. So no surprises in the numbers. Any share price movement today will be down to the commentary, rather than figures.
Balance Sheet - looks OK, with £17m NAV, including £6.8m intangible assets.
Note also that the £14.4m gross cash figure at Dec 2022 temporarily included the money to pay for an acquisition a few days later, so it has sensibly presented an adjusted net cash figure above, which looks adequate at £5.7m.
EYE got caught up in the Silicon Valley Bank crisis, but says today that it now has access to its funds again, so no great shakes there. It has a small drawdown on a loan facility with SVB, but that probably isn’t needed now anyway, and could probably be replaced fairly easily if required, from another bank - which tend to like companies with recurring revenues, and which are profitable, which EYE is now. So I’m not worried about the funding position. In any case, a £172m market cap means that EYE could probably raise a little cash very easily from equity investors.
The only number that looks a bit too high, is £12.9m receivables. So that would be worth questioning with management, if you get the chance on a webinar.
Outlook - ends with a flourish -
While conscious of the challenging wider economic backdrop, trading since the Period end has continued to be strong. The Board is confident in delivering another year of profitable growth, with revenue and Adjusted EBITDA for the year ended 30 June 2023 now expected to be comfortably ahead of current market expectations.
My opinion - checking my previous notes on 18 Jan 2023, I was positive on this share, commenting that a beat against modest forecasts looked likely. So it’s good to see that happen today.
I’m not sure how to value it, and even on upgraded numbers from Shore (many thanks) available today on Research Tree, the valuation looks scarily high on a PER basis. Remember that tech valuations generally have dropped a lot, so there's obvious risk now in paying up for growth. However, I’m still going to give it a thumbs up, because progress has been so good, that the big valuation & rating can be justified for this rare success story amongst UK small cap speculative tech shares. What a pity I didn’t put my speculative money into this one, instead of believing all the hot air from WAND. Never mind, lesson learned.
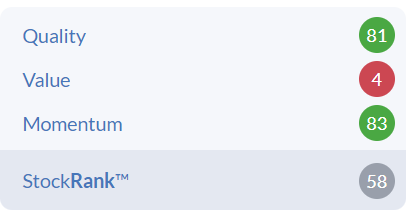
The StockRank neatly sums it up too - with a very low value rating, but great on quality & value - exactly how I see it too -
Graham’s Section:
Nightcap (LON:NGHT)
Share price: 11p (unchanged)
Market cap: £22m
We have H1 results from this bar owner with 36 sites, for the period ending 1st January 2023. It is led by Dragons’ Den star Sarah Willingham.
We also have a trading update - in line with expectations.
Results:
Revenue £23.5m
Like-for-like revenue decrease of 5.8%, attributed to the rail strikes.
Adjusted EBITDA: irrelevant to investors for a group that needs to do a lot of capex.
Operating loss: £0.1m, after-tax loss £0.8m.
But there is good news, too: the Christmas trading period “exceeded expectations with record amount of corporate Christmas parties, pre-sold events and New Year's Eve almost entirely sold out across all bars.”
Additionally, the new sites opened since November 2021 are on track to hit the company’s target (75% annual return on investment in their third year), and several of them may achieve this in their first year.
New subsidiaries have been integrated into the group with £1.4m of anticipated cost savings to follow annually.
Net debt is £4.1m (cash of £5.5m offset by debt of £9.6m), excluding lease liabilities.
The outlook sounds good:
Management continues to see extremely attractive opportunities within the property market and look forward to the ongoing roll-out of all of its key brands…
The millennial and Gen Z crowd remain resilient consumers, with high disposable income, as they continue to enjoy great nights out.
Trading has remained resilient since the start of 2023. The Group continues to trade in line with market expectations and the outlook is encouraging.
My view
I haven’t got a strong view on this particular share. The track record is still very limited and I have an open mind as to whether their roll-outs might succeed.
But I know that I don’t like this sector, especially when I’m looking at operators with lots of lease liabilities (no freeholds) and bank debt. One consequence of IFRS 16 is that we can see the present value of these liabilities directly on balance sheets: Nightcap has almost £40m of leases on top of its ordinary loans and borrowings. And the risk of something going wrong in this sector always seems very high, e.g. rail strikes in the most recent period.
I’ll keep an amber rating on it purely because the track record is short and I’d like to give management the chance to succeed before taking a particular view on the share.
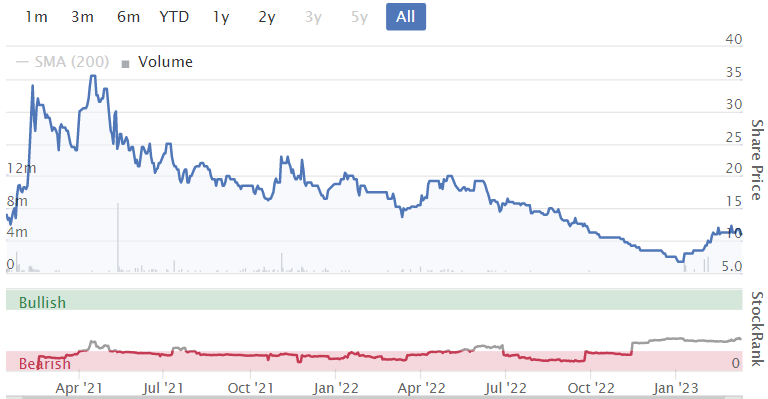
Remember that this is one of the 2021 IPOs:
PCI- PAL (LON:PCIP)
Share price: 44.35p (-3.6%)
Market cap: £29m
This share is involved in the Silicon Valley situation. It said yesterday:
SVB are the Company's principal bank and as at 9 March 2023, the Group had a total of £3.2 million of cash in accounts with SVB split between the US and the UK. The Group also has £0.33 million of cash held with other banks.
As we now know, the depositors at SVB are not going to suffer at all (the same cannot be said for investors in SVB).
So let’s move along swiftly to PCIP’s interim results for the period to December 2022, which have been released today.
As a reminder, this company describes itself as ”the global cloud provider of secure payment solutions for business communications”.
Key points:
Revenue +33% to £7.3m
Annual recurring revenue +33% to £11.9m
Annual recurring revenue of all signed contracts +30% to £14.7m (“a key indicator of future recurring revenues”)
Operating loss £1.9m (H1 last year: operating loss £1.1m)
Cash at the end of the period reduces to £1.9m (H1 last year: £5.5m).
Highlights section is bullish, outlining growth in customer numbers, upselling success, and customer retention levels.
Outlook: expectations for FY June 2023 are unchanged as trading is in line. Management are still seeking to achieve “monthly cashflow breakeven” in the current financial year.
CEO comment: emphasises the company’s “patented cloud technologies”.
This is where I need to scroll down and get an update on the patent claims surrounding PCIP. As I’ve said before, this strikes me as a potentially serious concern for the company and its investors.
Unfortunately, the wheels of patent law move slowly:
It is nearly 18 months since the Company became subject to unfounded claims of patent infringement in both the UK and US by one of its competitors, Semafone Ltd (now renamed Sycurio Ltd). The action was brought against PCI Pal shortly after Sycurio was acquired by the investment firm Livingbridge. It is our belief that the claims have been made in an attempt to disrupt our momentum and gain a commercial advantage given PCI Pal is the fastest growing provider in the space, with the most extensive partner eco-system, and the most mature public cloud offering.
The Directors continue to strongly refute the claims being made and as a result we have both defended our position on infringement, as well as made a number of counterclaims against Sycurio whose patents we believe to be invalid. We have worked closely with our legal advisors both in the UK and the US and remain confident in being successful across the breadth of our case. The court hearing in the UK is scheduled for mid-June 2023, with the US court dates yet to be set but expected late 2024.
The company adds that they have contingency plans for how they will operate in the “unlikely” scenario that they lose all of these cases, including “various options for product adjustments and enhancements”.
My view
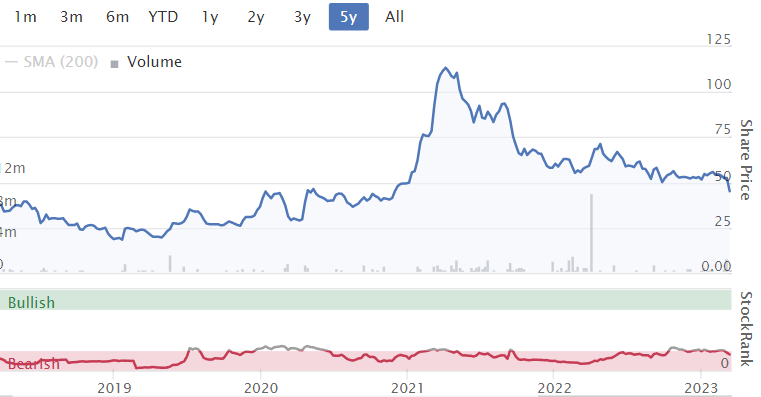
There is no change to my view on this. It’s an interesting company but the patent case seems very important to its eventual success or failure. And predicting the outcome of legal disputes is tricky, to say the least!
Some thoughts on valuation: annual recurring revenue is c. £12m - £15m, depending on which measure you’d like to use, so the price/ARR metric is in the region of 2x. It’s not a value stock by any means (ValueRank is only 9), but that price/revenue metric would be considered cheap by the standards of many tech investors. And if the company reaches cashflow breakeven as it anticipates, that will further strengthen the investment case.
Unfortunately, there are too many unknowns here for me to give it the thumbs up, but it may be worth studying further.
Midwich (LON:MIDW)
Share price: 461.8p (+5%)
Market cap: £410m
This is a distributor of audio visual equipment to the trade market. Paul looked at their trading update in January.
Today we have the results statement for the year, confirming enormous revenue growth of over 40% to £1.2 billion, including record organic growth of over 20%.
Operating profit is up 67% to £35m.
Or if we use the company’s adjusted numbers, then adjusted operating profit is up 46% (at constant currency) to £51m.
Either way, these are interesting numbers for a £400m market cap company.
As a distributor, profit margins are naturally on the thin side. Gross margin is unchanged at 15.3%.
CEO comment:
The impact of the pandemic reduced somewhat in the period, with product shortages easing (but not completely) and the cost of shipping containers reducing significantly during the year. We saw the resumption of a significant part of the live events and hospitality markets, and the corporate market strengthened during the year.
Although still early into the new financial year and mindful of the slower general economic conditions and higher interest rate environment, we remain confident that 2023 will see yet another year of growth in excess of the overall market."
Acquisitions / balance sheet
Midwich brought in c. £150m of annual revenue from two acquisitions early in 2022, and looks set to do some more soon.
The cost of purchasing these acquisitions resulted in a cash outflow of £22m, and Midwich’s net debt has increased from £58m (Dec 2021) to £96m (Dec 2022) (excluding leases).
The net debt to adjusted EBITDA multiple only increased from 1.4x to 1.6x, due to increased profitability, and Midwich says that this multiple is “well within the Board’s comfort range”.
Indeed, the multiple looks likely to increase further as the company has increased its bank facilities from £80m to £175m, “to support future delivery of our acquisition pipeline”.
My view
As distributors go, this looks pretty good. It claims to be “the sole or largest in-country distributor for a number of its vendors in their respective product sets”. I can believe that, given £1bn+ in revenues and its international scale.
If I was going to invest in a distributor, I’d probably choose something like this, instead of a marginal player. I’d want something with high market share in certain categories and products, like Midwich has.
It also has a praiseworthy track record of generating profits, and is recognised by the Stocko computers for having decent quality:
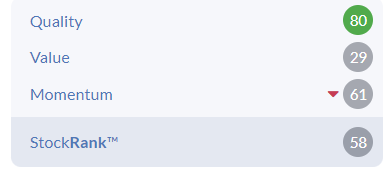
Against that, there are the usual financial risks that go with a debt-fuelled expansion in a low-margin industry. I don’t see how I can avoid taking a neutral stance here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Following up Paul's comments on Eagle Eye Solutions (LON:EYE) here's their H123 results presentation video & podcast. Maybe a bit of repetiion but a summary:
Rev +32% £20m
ARR £26.2m
Recurring Rev 78%
aEBITDA +23% £4.7m
PTP £0.9m
Churn 0%
Cash £5.7m
Untied Nots supports cont'd expansion. (Worth watching the UN teach-in published February 2023 here
As Paul says, not cheap but it looks interesting.
Listened to recent PI World podcast presentations on this one - Management are VERY positive and it interviews well. Sir Terry Leahy is on the board and the boards experience with Tesco Clubcard & similar schemes was mentioned a few times. The company and its recent acquisition seem to have particular expertise in assisting retailers with loyalty programmes along the lines of Clubcard.
Would say is very interesting as a high growth without needing much additional cash funds type proposition.
Any thoughts as to the drop on Yu (LON:YU.) today upon a relatively good TU?
Perhaps some aggressive profit taking after a momentous upward run Yu (LON:YU.) .
Strong trading udpate from Manolete Partners (LON:MANO) just came through, showing a significant pick up in new cases and settlements. A nice counter cyclical play and very cheap (based on where I think earnings will go in next couple of years, although none of this reflected in broker estimates).
Manolete Partners (LON:MANO) has issued a lunchtime trading update.
Celadon Pharmaceuticals (LON:CEL) Celadon Pharmaceuticals - Does anyone know of the reason for the tripling in price in the last week? If it keeps going at this rate I will be back in profit!!
They have just released an RNS at 15.01
Highlights
· Receipt of updated Home Office licence enables Celadon to commence the commercial supply of its GMP pharmaceutical cannabis product
· GMP registration is understood to be the first such registration of a UK pharmaceutical facility for high THC cannabis active pharmaceutical ingredient ("API") since the legalisation of medical cannabis in 2018
· GMP registration and a Home Office licence are required in order to sell high-THC medicinal cannabis in the UK
· Celadon becomes one of a small number of companies globally with the capability to produce an EU-GMP grade high-THC cannabinoid API
Just looking at the stock report on Secure Trust Bank. Does anyone know why the free cahsflow ps is so badly in the red? Just looking at some other similar banks and STB's cashflow section stands out as worse than most. I don't know much about this company, so if someone in the know could explain this that would be helpful.
I agree with Planetx re recession / bear market. Most people seem to be calling for falls in the S&P to mid 3000 range.... but even at the low end it's a fall of 20%. Whilst it will be deeply unpleasant the chances are it ends with some sort of rally.... normally high single digit ....which you miss if you sell. This to me suggests a lot of people spend too much time worrying about losing a low double digit % and not enough time concentrating on being in good stocks. The UK did. significantly better last year than the US and this may repeat. Many stocks in the UK are classically cheap. By this I mean... have a valuation approaching 10x PE ... a low multiple of revenue and grow. Look at shire foods... grows...low margin ... but trades at a fraction of annual revenues. I wouldn't want to encourage anyone to ignore risks of investing....but for me there seems plenty of scope to build a rather cheap portfolio of reasonable quality. You can also bolster this with decent yield in bonds....of shortish duration....and therefore expect a return of high single digits....
Recessions are positive for the stock picker because the go go stocks of the boom years lose favour. The inflation picture is interesting and far from simple. As we know it is an average number over time. It's true that supply chain and Ukraine have contributed. It's also true that fiscal policy has played a part. Fiscal solutions to problems hold more favour now than 10 years ago.... a fiscal solution to Ukraine and the rebuild will come in time. Fiscal investment in infrastructure will likely solve energy issues in Europe and fossil fuel transfer. So whilst I agree that inflation will fall.... to where im less sure. I like the idea that this investment will lead to an economy more balanced and better conditions for "old economy" stuff. But it's just an idea.... should it pan out though.... the recession may not be so bad for a lot of people. Especially if you work in the areas of future growth not past growth.
I would lean towards the view the Fed has done plenty enough. Probably already gone too far tbh.... no-one would have thought they could get this far though. I do think the republicans are somewhat encouraging the fed along because a poor economy favours them over the democrats and so the political cycle in the US also has a role to play.
Overall it is tempting to scale back equity exposure but I continue to resist and run my positioning. I hold 2 special sits, Sherborne Investors (Guernsey) C (LON:SIGC) and £VLE. I own Yellow Cake (LON:YCA), Fresnillo (LON:FRES) and £SQZ. Finally I own BT (LON:BT.A) and Gold. I consider it defensive and after a strong start I have drifted back a bit recently....mainly due to Serica Energy (LON:SQZ) and their unpopular acquisition. I have missed the action in Oil services but still like the idea of £weir or Rotork (LON:ROR) maybe. Any pull back and I will probably try and look at industrials which fit my view. In a separate portfolio I have a decent weighting to short duration bonds including UK Govt and IL.
Best of luck everyone and keep up the great work on here.
Is anyone here interested in Close brothers (CBG). Many use their service via Winterflood securities , the small cap market maker.
This bank used to be run conservatively but recently has run into troubles with one of its lending sections.
I am a long term holder but would love to hear from others. much appreciated.
I was an investor but sold a few months back, taking some profit.
My reasoning was:
Very poor diversification into an area and geography that it didn’t understand well, leading to horrendous losses in that sector. Fiddly to escape the decision, although it is doing so.
Winterfloods is a great business but it’s well known that small company liquidity has been exceptionally poor in recent UK history. This is hitting returns.
The low point of lending provisions has passed. Car loans in the UK are now prevalent. But the interest rate tends to be fixed while borrowing costs may be more variable.
Funding costs are rising sharply. A competitor, STB, has had to pay an astonishingly high interest rate on new debt, and this may yet go even higher.
EPS not growing.
There is a price at which I would buy back into Close, but it’s quite a bit lower than the current price. STB is way cheaper.
But I am an amateur investor, so may well be wrong. I’m a long term plodder, not a trader.
GreyInvestor - may I ask where the details of Secure Trust Bank (LON:STB) new debt at a high interest rate are? Is this it: https://www.research-tree.com/...? I don't have a paid sub to Research Tree so I can't get the details.
EDIT - found it, in an RNS. New issue of £90,000,000 13.00 per cent. Fixed Rate Reset Callable Subordinated Notes due 2033 (and buy back of£25,000,000 6.75 per cent. Fixed Rate Reset Callable Subordinated Notes due 2028.
Have you considered Osb (LON:OSB) as an alternative? Has been performing well and think looks much better than Close brothers on many metrics.
For anyone interested in the Silicon Valley Bank debacle, this very smart young lady will bring you up to date.
March 2023 Newsletter: A Look at Bank Solvency - Lyn Alden
Very informative. The paragraph that caught my eye was "If the Federal Reserve is unable to keep up the combination of interest rate increases and quantitative tightening for much longer due to hurting small banks too much, despite price inflation still being above-target, then a basket of anti-dollar positions such as gold, oil, commodities, emerging markets, and bitcoin would likely benefit"
Thanks for posting Camtab. Interesting piece explaining why we are where we are. Basically the law of unintended consequences combining with an extended period of ultra low interest rates has created a lot of landmines for policy makers. Hard to escape the conclusion that the latter will now pause / slow tightening. The result will be entrenched inflation, which will be seen as the lesser evil. Result: Stagflation. Truly the 1970s redux. As an aside this fact has caused me to tweak my investing style. I have never been a commodities investor, disliking their highly cyclical and uncertain nature. But in the face of this environment and the mismatch between mid/long-term supply and demand of metals, owing to the green transition, I have begun to selectively dip into metals & mining. Seems like a decent sector in which to diversify from a 100% allocation to GARP / Quality (my preferred style)
Thanks for sharing - great article, and watched an interview with her on youtube... seriously impressive lady. Able to explain macroeconomic complexities in a clear a concise manner, with no evident political bias. Excellent find.
If both the annual pension contributions and LTA are increased in tomorrows budget do we see this as a positive for equities?
Interesting but very complex question SC120. My take on balance is very hard to predict. More pension contributions will probably lead to increased equity purchases, obviously dependent on investors views of the markets. However an increased LTA will allow more investments to be sold without incurring a 55% tax charge. It obviously depends on whether pensioners are selecting to buy annuities or using drawdown or even uncrystallized lump sums. I think the answer may lie demographics and as the labour market is experiencing a lot of folks are starting to cash out.
Hi SCI20
I think that we need to firstly split this into the two requisite parts.
Public Sector Employees & those who have a pot which might or not be large enough to hold a half of mild at some uncertain point in the future.
The key part here is how the public sector employees pot is calculated - very happy to have my thoughts corrected if I am wrong as always - at the moment it is back calculated on an annuity basis that nobody in Joe Public can get for love nor money even with everything that has happened in the last year. When I last explained it to Mrs T she got 3x my annuity purchase for 1/3 of my years service and contributions, good old NHS 1995 scheme for you! The NHS 2015 scheme is not as good unfortunately.
Part of the government challenge is those at the higher end, where many are at the point where they are hitting the lifetime limit and they are walking away in their 50's. So hence the pension contribution limited was lifted away from £100k a few years back and now the pension lump sum is being lifted.
There are obviously those within private sector who have a good pension pot. I do know folks who can put away the £40k/year, but they are a lot less, and the impact is invisible to those in Whitehall.
But speculating out loud the impact of the loss of their "Sir Frank Gordon" for those old enough to remember, might have triggered some action.
#not so levelled up
Piffle over
Tommy
ps. I sold!
Morning everyone - I have been quiet for a while, mainly because im fully invested and doing very little. Volvere (LON:VLE) is meaningful for me... and has a trading update today. It's been a tricky few years with Indulgence and no new acquisitions... im hoping they do something new soon.... BUT if they don't then real value is opening up. Shire continues to grow strongly helped by price increases .....and profits are where I hoped they might get with Indulgence. £38m Revenue and £2.78m profit.... I think you are getting £20m + potential here. Nearly £21m cash.... so £40m plus valuation versus a Mkt cap of 2.36 * 1100 = £26m. At £40m the shares would be 1700..... which I believe explains why the co were happily buying stock at 1195 in December. My guess is they will return to buying as the shares are below the 1195 level...below book value...at 1382 .... and as they buy back more stock .... the economic value accruing to shareholders rises. Ofcourse there is a minority to adjust for which reduces the upside a little.
For me, either they buy something we can get excited about which I would prefer....or they exit Shire and wind the business up. Against a backdrop of uncertainty this seems a good bet.
Good to have you back RD!!!
Great results today from Midwich (LON:MIDW) are worth a look , with revenue up 40%.
Yes I keep seeing good results from Midwich but every time I get excited that my investment in them was right, they dive again. I am looking for opportunity to get out, I am wondering if traders just don’t like the share.
Recession
I do struggle with the drama surrounding “recession”
If the economy goes from 3.1% growth to 2.9% is contracted 0.2 % and everyone goes about their daily life
If it goes from 0.1% to -0.1% we’re in recession and it’s a total disaster and we’re going to implode .
I ran my company for 30 years and went through several so called recessions and at no point did it ever come onto our radar concerning building a trying to run a great business and a quarterly national growth rate is pretty irrelevant to a lot of businesses and to get quote my mate Sir Dave Brailsford you must “control the controllables” and not worry about what you can’t control .
If you invest in well run businesses then a national growth rate of 1% either way isn’t going to get noticed .
I don’t really get the obsession with the paranoia of falling below what is effectively a relatively random line in the sand .
Hi planetx,
I agree. That all sounds very sensible!
Another point that is often forgotten, is that GDP is measured in real terms, ie. stripping out inflation. So with inflation currently high, at around 10%, that means nominal GDP is actually growing at a stonking rate (also about 10%).
This point is confirmed in a recent Office for Budget Responsibility report here, which I'm having a look through, and note 8 says -
8. Public sector net debt (PSND) in January 2023 was 98.9 per cent of GDP, up 1.2 per cent of
GDP on a year earlier (but 1.0 per cent of GDP below our November 2022 monthly profile).
Cash debt increased by £143.4 billion (6.1 per cent) over the past 12 months due to the
continuing budget deficit, but the nominal GDP denominator was up 4.8 per cent over the
same period, thereby limiting the year-on-year rise in the debt-to-GDP ratio.
4.8% seems low for nominal GDP growth, even considering that this report is for April 2022-January 2023, so not a full year.
I should emphasise I'm not an expert on this stuff, but like to keep an eye on it, and understand the broad themes.
Wasnt it Tom Hunt who said I thought about recession and decided not to take part.
Re: Technical Recession
Doom-monger journalists love a recession - real or imagined - though don't they! - Think it sells newspapers/keeps them on air and in work. Perhaps it does, but it's always the same: by the time the economy actually meets the definition of a technical recession (until the data are later revised and it turns out we weren't actually in a recession after all!), journos have generally been draining their audience of the will to live, and helping to cause the very thing they bemoan, for at least the prior year.
Best to ration news consumption during a 'recession' methinks.
"We seem to be in something of a banking crisis"
I can recommend reading "This Time Is Different: Eight Centuries of Financial Folly Paperback – by Carmen M. Reinhart (Author), Kenneth Rogoff (Author).
Covers bank crisis and sovereign debt crisis with historical stats on cause, effect, duration, etc
Asset-stripper. Do you have any insights from the book that are useful today?
Summary by ChatGPT:
The book "This Time Is Different: Eight Centuries of Financial Folly" offers several key lessons that can be learned from the history of financial crises:
Overall, the lessons from the book highlight the importance of responsible borrowing and lending, prudent regulation, and effective crisis management in promoting economic stability and avoiding financial crises.
Is it fair to say central banks have raised rates too fast? They're stuck between a rock and hard place with inflation.
I don't see much alternative. If rates had risen more slowly, inflation would be worse and there would undoubtedly be calls for more aggressive rate hikes / monetary tightening.
Isn't it necessary to inflict some degree of economic 'damage' in order to get inflation under control?
Hi Breakout Trader,
I would agree if inflation was caused by an overheating economy with excessive demand. But that's not the case is it? In the UK and Europe anyway, we're teetering on the edge of a recession. The inflation spike was caused by supply chain problems, and the energy crisis from Russia invading Ukraine.
Forecasters are saying inflation should fall rapidly once those factors annualise.
Hence why do central banks feel the need to also dampen demand, when the cure for higher inflation is already well in progress? They've destroyed so much in asset values (shares, property, and bonds, all heavily down) by aggressive rate rises, that they're risking the whole system's stability, as we've just found out.
Regards, Paul.
If anything rate rises after a certain point must fuel inflation by adding one more reason (mortgages are going up) why workers want big pay rises. The whole system is nuts.
Too complicated for me Paul but too much QE for too long spilling into many asset classes, together with zero or negative rates had to end badly. Tin hats time again friends.
Hi Paul,
I would disagree with the assertion that inflation has been caused by the war in ukraine and supply chain issues.
In my opinion, the primary cause of inflation was the massive and rapid increase in the monetary supply during covid, at a time when productive output fell off a cliff. Inflation was already up and running in December '21, before Russia invaded... the invasion and supply chain issues certainly contributed, but I do believe excessive government spending is the main culprit. These charts show the increase in Money supply in both the UK and US, with a 1-year lag before inflation takes off. Correlation doesn't equal causation, but on the US chart you can even see a temporary pause in the Money supply, reflected by a temporary pause in inflation 1 year later.
Note: I don't want to open a political discussion here, but I think this is important to highlight.
You may be right, that inflation will sort itself out, but that's a risky strategy and will mean a longer process as Inflation fuels itself (workers in my company have had a 17% raise across the board) - I would contest that inflation is only coming down because of the interest rate rises and QT applied so far.
100% agreed. I was about to type the same thing.
Eneraqua Technologies (LON:ETP) trading update looks good to me, in the current climate. It's a shame they missed their revenue target, but revenue for vanity and profit for sanity as they say....
This market is incredibly unforgiving, 50% revenue increase yr on yr, with margins in line with expectations and it drops 15%....
See Yu (LON:YU.) for similar reaction this morning.
I've read through what I can get to on YU. Can someone brighter than me interpret please?
Despite great figures today the shares are down by 13%. Given the strong run over the last yer this seems like profit taking. Or perhaps the tree is being shaken to remove fragile holders making room for a major stakeholder.
Hello NewInvestor. Re Eneraqua Technologies (LON:ETP) vanity it may be but the revenue shortfall has hit the SP hard. Maybe it is the reference that although no contracts have been cancelled, the have been delayed into future years rather than into say, next financial year?
Creates risk of future profit warning. We saw something similar with Spirent Communications (LON:SPT). Tight budgets lead to customers putting off orders
Could be, Still looks good to me though, £110 million on the order book of which £79 million will be delivered this FY so the £80 million target is pretty much in the bag..
Whilst its comforting to know they have contracts signed/orders agreed and a regulatory tailwind, its worth noting that Eneraqua Technologies (LON:ETP) relies on multi year contracts with a relatively small number of customers (i.e. local housing associations, councils and building firms) and these sectors are facing a challenging environment.
Based on this I think the likelihood of further delays to contracts, tender processes etc is high. As I think the risks in the next 6 to 12 months are now skewed towards further profit downgrades I've being selling out of my position.
Its also worth being wary of management terminology here.
"The Order Book3 has grown and is now at a record level, with £110m in contracted and secured work, of which 72% is due to be delivered in FYJan24. This proportion represents 99% of the FYJan24 revenue target (previously 85% as announced in October 2022)."
Sounded good to me until I read that the order book is defined as:
3 Order Book defined as Contracted + Secured. Contracted = project contract issued and signed, with work started or ready to start. Secured = sum of a) tender process successful, awaiting project contract, and b) Directors' assumed win rate on Framework opportunities.
In other words, although there may be a framework agreement in place, the order book may include values for contracts that have not yet been put out to receive bids from framework suppliers - so by no means guaranteed work.
Costain $COST (LON:COST.) this morning
https://www.londonstockexchang...
Yu (LON:YU.) strong results. Revenue and PBT up significantly. Cash up too. Small divi introduced. Are you covering Paul/Graham? tia
https://www.investegate.co.uk/yu-group-plc--yu.-/rns/final-results/202303140700038065S/
Hello eParo. Hasn't done much for the £YU share price. Down 16% as I speak.
Clobbered is the term. Those accountants who spent all those hours putting the numbers together will be scratching their heads
Think the outlook statement maybe wasn't as strong as some had hoped, and the divi a lot lower than expected. Be interesting what EPS forecasts are next two years, anyone have any info on this?
Good morning Paul and Graham, you'll have bigger fish to fry as it were but any observations on these two however brief would be appreciated, Croma Security Solutions H1, last covered by Jack in July 2021 (possibly cheap at 81p but poor liquidity) and Tekmar (finals, 18 months) which got an Amber last month and in which we are further underwater than their cables. Banking crisis? Who needs one!
Morning guys
To me, the odds of a US hard landing just got a whole heap higher yesterdat.
What with short term Treasury yields plummeting and the 2s/10s curve becoming far less inverted.
My best guess is a US recession will officially start in Q3'23.
Paul, I think we’ve just swapped recession in ‘24 (Fed hikes too high and long to suppress an over-heated economy) for recession in ‘23 (Fed finds it broke something by raising too fast). Let’s just get the bloody recession over and done with and get back to growing economies and rising share prices. The good times just came nearer. Isn’t that a good way to look at the prospects?
In the meantime, traders can try to time the market and investors can own their companies through the turbulence. I didn’t try to sell my business during 9/11 or the GFC or the Euro debt crisis. I waited until 2017 when conditions were optimal. And I won’t sell my shares during the forthcoming recession.
Croma (CSSG)
Bit of a special situation arbitrage unfolding at CSSG
Divesting itself of its Vigikant security business which I think looks to be going ahead based on the management team changes (eg long standing chairman Sebastian Morley stepping down to concentrate on vigilant )
Reporting the two divisions seperately .
My fag packet for vigilant is 5 million .
Total market cap 7 million
Leaves residual Croma business in for 2 million , given it has cash, Inventory , and a lot of freeholds and it’s actually quite a nice simple easy to understand business that can keep adding on to its “empire” as mom and pop stores retire .
Granted it is definitely tiny and the divestment is not guaranteed, but even without the divestment it’s ok .
One of these tiny micro cap value traps that is below NAV so hats off at least to them for trying to unlock some value and sell off for a chunk of cash the vigilant division .
I don’t see it as particularly high risk due to the asset backing and it’s a heads you win tails you don’t lose special play .
My morning smallcap tweet: Eneraqua lukewarn.
Eneraqua Technologies (LON:ETP) Focusrite (LON:TUNE) Volvere (LON:VLE) Virgin Wines UK (LON:VINO) Literacy Capital (LON:BOOK) Polarean Imaging (LON:POLX) ITM Power (LON:ITM)
◄Eneraqua Technologies (ETP)► warns FY-Jan rev c. £55m, lower than previously targeted due to order delays. No contracts have been cancelled..However EBITDA within range of market expectations. Order book £110m. [SP=358 Cap=119m]. I hold.
◄Focusrite (TUNE)► guides H1-Feb in line with Board expectations. Rev £85m+ (down 9%). H2 weighting. [SP=695 Cap=412m]
◄Volvere (VLE)► guides FY-Dec rev-cont up 24% and pretax-cont £2.33m 9£1.07m). Overall pretax -££0.24m due to loss at the closed Indulgence Patisserie. NAV 1382p/sh (1349p). FY23 trading: "Since the year-end, labour market challenges and raw material price pressures have shown some signs of abating". [SP=994 Cap=24m]. I hold.
◄Virgin Wines (VINO)► H1-Dec in line. Jan-Feb trading broadly in line with expectations. Maintains FY guidance.. [SP=47 Cap=26m]
◄Literacy Capital (BOOK)► sells Kernel Global at a 48.9% premium to book. Hikes NAV by £9.4m. [SP=397.9 Cap=239m]
◄Polarean Imaging (POLX)► unsuspended following SVB depositor rescue. [SP=27.5 Cap=58m]. I hold.
◄ITM Power (ITM)► power supply at Bessemer Park to be hiked 300% to allow to significantly increase product testing. [SP=82.14 Cap=506m]
MrContrarian. I would like to thank you for your excellent smallcap tweets, which I always read closely. I notice that Midwich (LON:MIDW) was omitted from the list today, and I was wondering why this was the case?
I look at trading statements first and only read interim/FY RNSs if I have time.
You're still Superman (if Superman read & summarised trading statements), MrC!