Small Cap Value Report (Tue 15 Oct 2024) - DLAR, RCH, VCP, RWA

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
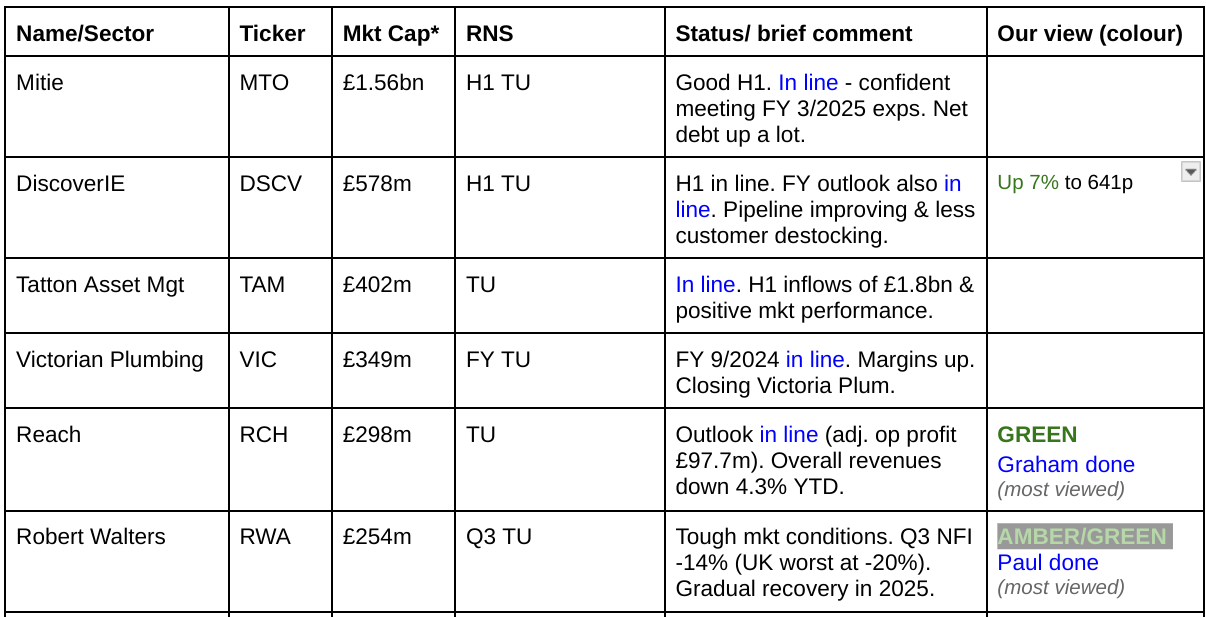
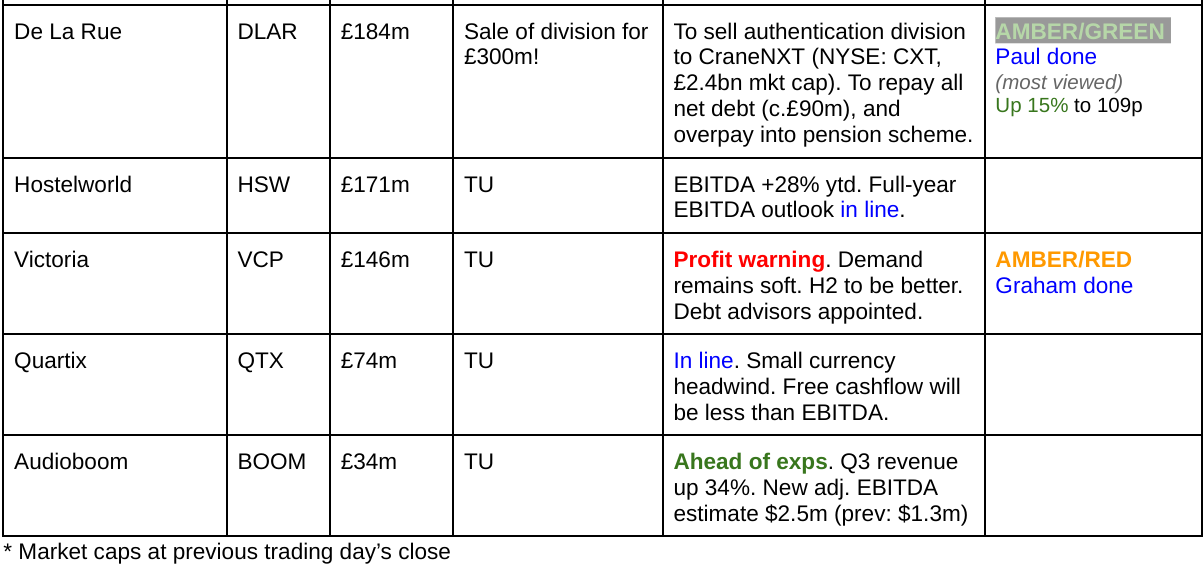
Summaries
Reach (LON:RCH) - up 3.5% to 97.1p (£309m) - Trading Update - Graham - GREEN
An in line update confirming full year expectations (adj. operating profit £97.7m consensus, slightly higher than 2023). This is despite a revenue decline in the region of 5%. Pension deficits and a shrinking core business continue to weigh on this, but I suspect the problems are more than fully priced in.
Victoria (LON:VCP) - down 7% to 118.4p (£135m) - Half-Year Trading Update - Graham - BLACK (PW) - AMBER/RED on fundamentals
This is a profit warning as VCP reveals ongoing soft demand for its flooring products. Debt advisors have been appointed to help with refinancing a large note that’s maturing in 2026. I am tempted to turn RED on this and would do so at the first sign of balance sheet trouble.
De La Rue (LON:DLAR) - Up 15% to 108p (£212m) - Proposed sale of authentication division for £300m - Paul - AMBER/GREEN
Achieves an impressive £300m deal to dispose of its authentication division. If it completes in H1 2025, then this deal would comfortably wipe out all net debt, allow DLAR to roughly halve its pension deficit (which isn't actually that large), and still have pots of net cash left over. Maybe I've missed something important, but my initial reaction was much more positive than Mr Market's.
Robert Walters (LON:RWA) - down 2% to 343p (£249m) - Q3 Trading Update - Paul - AMBER/GREEN
Another staffing company saying that revenues are still dropping, and it's only trading around breakeven. Recovery - no sign of it yet. Despite that, I mull over the recovery potential below, and think the strong cash position keeps it moderately positive looking through current dismal market conditions for a recovery in 2025 and beyond.
Paul’s Section:
Robert Walters (LON:RWA)
Down 2% to 343p (£249m) - Q3 Trading Update - Paul - AMBER/GREEN
“Trading update for the third quarter ended 30 September 2024”
“Continued focus on strengthening the business amidst challenging market conditions”
We had an excellent debate in yesterday’s report, with lots of interesting reader comments. Why is it that the expected recovery from staffing companies internationally, just isn’t happening?
We’ve had lacklustre reports from both Hays (LON:HAS) (late last week) and Pagegroup (LON:PAGE) (yesterday), both indicating no signs of recovery yet in their various regions.
As I would expect, RWA says very similar things today.
Q3 Net Fee Income (NFI) is down heavily vs LY at -14% - so it’s not even that this sector is bottoming out, it’s continuing to fall heavily.
The larger regions of Asia and Europe are both down -14%. The smaller UK operation is worse, down -19%.
Crumbs of comfort are the Q3 YTD is down -17%, so Q3 is a smaller reduction at -14%. There’s also the point that these weak 2024 figures should become 2025’s soft comparators. Also using constant currency reduces the -14% to -12%.
Company comments -
“Trading conditions were broadly unchanged from the first half, with client and candidate confidence levels yet to show signs of material improvement.”
RWA has slashed its own headcount by -17% compared with a year ago. It must be a horrible sector to work in at the moment, with the threat of redundancy & trying to meet targets being ever-present, I imagine.
Net cash is virtually unchanged at £50m. One of the reasons we’ve tended to view RWA positively is because of its strong, cash-rich balance sheet - meaning that there’s no solvency or dilution risk, and it is also adequately funded to scale up again once recovery gets underway (which can absorb cash when growth resumes).
Outlook - sounds rather hesitant on recovery, although as readers have mentioned here before, the staffing companies probably has little more idea than we do about what clients are going to do in future. Are things going to turn rapidly & strongly into recovery? It’s possible, but doesn’t sound imminent -
“As set out at our half-year results in August, our assumption continues to be that material improvement in client and candidate confidence levels will be gradual and not likely to commence until 2025.”
Setting the bar low here -
“Though market conditions mean second half fee income is unlikely to exceed that seen during the first half, the programme of actions underway mean we continue to aim for a profitable full-year outcome…”
I’m looking at its H1 numbers again (Graham reviewed here on 1/8/2024, concluding AMBER/GREEN), it generated a small PBT loss of £(2.3)m. It’s difficult to exaggerate how bad this sector is, the numbers are really quite dismal.
Forecasts are still falling too.
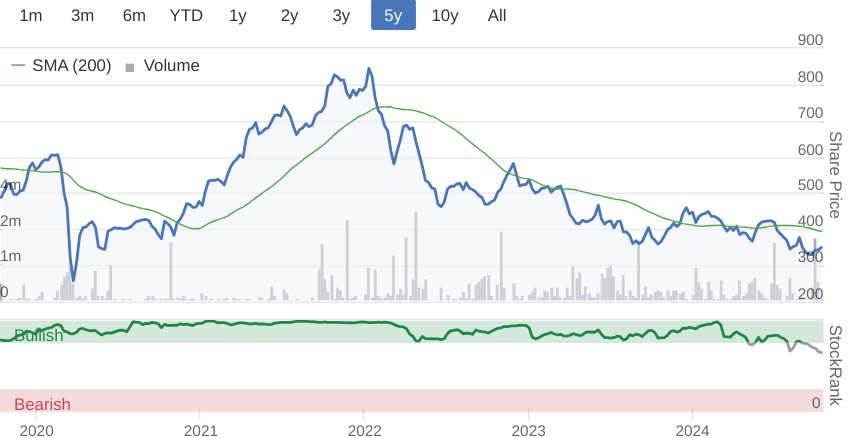
Paul’s opinion - I’m really torn here. It would be such a pity to give up on the sector right at the low point of earnings, when there could be a lovely recovery to come, even if it isn’t visible yet. We know that RWA is very strongly financed, so no issues there. RWA shares are quite near their 5-year, and pandemic lows, so is risk:reward now favourable enough to take the plunge? I honestly cannot decide. Buying at or near the bottom in any cyclical share tends to be deeply uncomfortable. I remain worried that something untoward may be happening with this whole sector, so am not convinced that a V-shaped recovery in earnings is necessarily going to happen. Who knows? Personally I’d be looking for a more distressed valuation, so I’ll sit this one out for now. Braver people could be rewarded in time though, but I think anyone buying this now just has to stick with it, and not panic if it keeps falling. Or maybe go in with a one-third standard size position, and keep buying if it continues falling? That’s the type of strategy I sometimes apply in situations like this.
Given that AIM in particular is throwing up some bizarre price moves at present, I’d rather keep some powder dry for better bargains elsewhere, then maybe revisit fully listed RWA later this year.
On balance I think Graham’s AMBER/GREEN from last time still looks reasonable.
De La Rue (LON:DLAR)
Up 15% to 108p (£212m) - Proposed sale of authentication division for £300m - Paul - AMBER/GREEN
As it stands, DLAR is 2 businesses (banknote printing, and authentication) on the asset side, with the liabilities side being c.£90m net debt, and a large pension scheme in deficit.
The group had big problems before, then was nearly finished off by the pandemic. It got a fundraise away though, and survived (although nearly doubling the share count), and has since achieved a somewhat hesitant & patchy turnaround.
It previously indicated that all parts of the business were up for sale, and that deal(s) would be concluded before its bank debt expires on 1/7/2025. It sounds as if the bank doesn’t want to extend the borrowings, so there could be deal risk here if the proposed sale of the authentication division falls through.
Key terms of the proposed disposal announced today -
Buyer: CraneNXT, which is clearly a credible buyer, NYSE listed (£2.4bn mkt cap, highly profitable).
Price: £300m on an enterprise value basis (presumably cash/debt neutral).
Escrow: 5% (£15m) to be held back for 18 months.
Subject to: regulatory approvals, and separating DLAR’s two divisions (cost £12m)
Timing: first half of 2025 (to allow time for the divisions to be separated).
Use of the £300m cash -
5% withheld for 18 months, so £15m.
Repayment of £89m net debt (at Mar 2024), so I’m assuming it’s likely to stay roughly the same.
Cash collateralisation of letters of credit & guarantees - not expected to exceed £10m.
Bankers fees £4.9m
Transaction costs £7.6m
Pension scheme overpayments £32.5m
Totalling that up, my best guess is that DLAR could have net cash of £141m (plus likely receipt later of the £15m escrow). That’s is clearly a very healthy position, and totally transformed & derisked its balance sheet & solvency.
Is the £300m price good?
I would say yes. It looks an attractive disposal price given these numbers (although the outlook for authentication division sounds good, so profits likely to increase) -
“The Authentication Division generated revenue of £102.9m in the year to 30 March 2024 (FY24), an increase of 16.9% on the prior year. Divisional adjusted operating profit for FY24 was £14.6m (FY23: £14.2m) after the allocation of enabling function overheads (at a margin of 14.2%).”
I’m surprised DLAR shares are only up 14% at the time of writing (09:28), I would have expected a larger increase, given the attractive valuation achieved for the disposal, and that it totally de-risks the remaining business - clearing all the debt, and largely sorting out the pension schemes too.
Will the pension scheme gobble up the rest of the cash?
The numbers for the pension deficit are much smaller than I was expecting, and much higher figures have been bandied around by investors.
According to the last accounts, the accounting deficit was £50m. This would be mostly paid off under the above terms.
The actuarial deficit was £78m at Sept 2023. So the above arrangements would repay about half of it, leaving a relatively small balance more than covered, several times over, by DLAR’s net cash post deal completion.
What’s the remaining business worth?
Difficult to say. DLAR will become just a banknote printer, which isn’t likely to excite investors, who will probably see this as in long-term decline. Although as Spectra Systems (LON:SPSY) (I hold) has shown, there’s a lot of interest in the switch to polymer notes. There are not many companies in the world that can do this, and have the necessary security credentials.
There’s also the intriguing possibility that DLAR might also announce a sale of this remaining division, as we know it’s been in talks for that.
Taxation - I don’t know what, if any taxes would be payable on today’s proposed disposal deal.
The currency division was about two-thirds of group revenue last year of £207m. It only made adj operating profit of £6.4m in FY 3/2024, down by more than half LY, although it says that the order book substantially increased, so I would expect it to make higher profits in future.
There’s also talk in today’s announcement about spending on capex to make it more efficient.
We’ll have to wait for broker notes to do the detailed analysis and estimate what the smaller, currency-focused business might achieve in profits. It will certainly be well-funded though, with plenty of net cash, and a largely resolved pension deficit.
Paul’s opinion - given that a bumper price has been agreed for the authentication division, I was expecting a higher share price rise today.
The pension scheme numbers are not frightening at all, the deficits are actually quite small now. So maybe that’s a point investors have been unduly worried about?
There’s still some uncertainty, but this deal looks transformational for DLAR’s financial stability - if this deal completes, it takes DLAR from a riskier investment, to something that would be rock solid. I think there could be an opportunity here, but I need more information and pro forma P&L and balance sheets ideally. I’m going with AMBER/GREEN.
Graham's Section
Reach (LON:RCH)
Up 3.5% to 97.1p (£309m) - Trading Update - Graham - GREEN
This is an in line update but when you have a stock trading at a PER of 4x, in line updates can be very exciting!
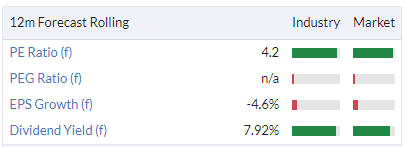
The adjusted. operating profit consensus number is £97.7m, vs. a market cap of only about £300m.
That’s about the same as the company achieved in 2023 (£96.5m).
However, we do need to bear in mind that these adjusted results are inflated; there were £50m of adjustments last year. Hopefully the adjustments will be lower this time around?
Getting back to today’s Q3 update:
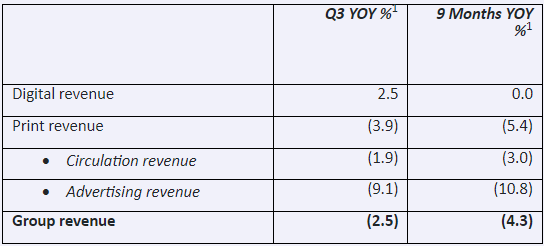
The market views this stock as a melting ice cube: the newspaper business is shrinking, perhaps towards total obsolescence, and digital revenues aren’t big enough to compensate for this.
The melting ice cube hypothesis does have some merit: year-to-date, we have another decline in total revenues.
Digital revenues, despite showing some year-on-year growth in Q3, are flat for the year as a whole.
In the print business, volumes are constantly declining: note that “circulation revenue” is down 3% despite the price of a printed publication going up. So volumes are certainly continuing on their downward trajectory.
But despite these challenges, the business is still being run for cash and profitability and I expect that we will get another decent full-year performance by these metrics. Revenues will be lower but adj. operating profit should be marginally higher.
Outlook: confident in delivering expectations for the year.
We continue to monitor the impact from the tech platforms' actions on referral volumes, and we expect further digital growth in Q4. We remain focused on costs and we are tracking slightly ahead of the 5-6% cost saving target we set at the start of the year.
CEO comment:
"Our Customer Value Strategy continues to drive revenue diversification and has helped us navigate the dynamic media backdrop. We continue to make good progress with our investments including our US expansion, the re-platforming of our websites and our in-house ad tech platform, Mantis.”
Graham’s view
I’ve been positive on this one, most recently at 105p in July, when the half-year report was published.
Today, at 97p, I see no reason to change my view.
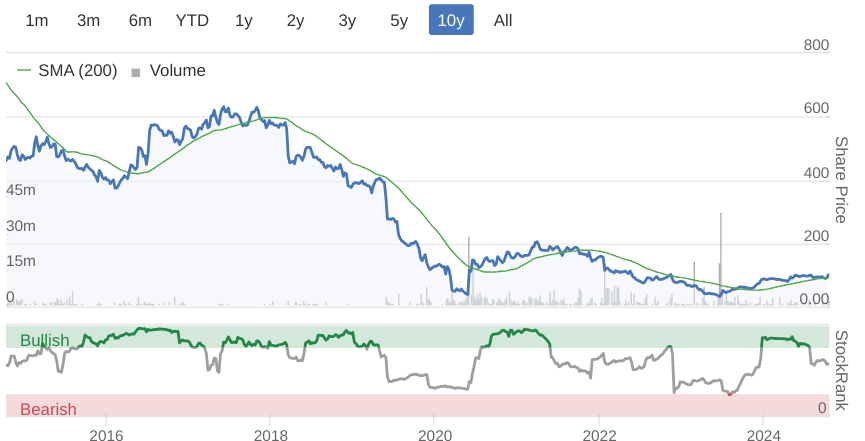
The stock has already made some progress from the lows around 60p at the start of the year:
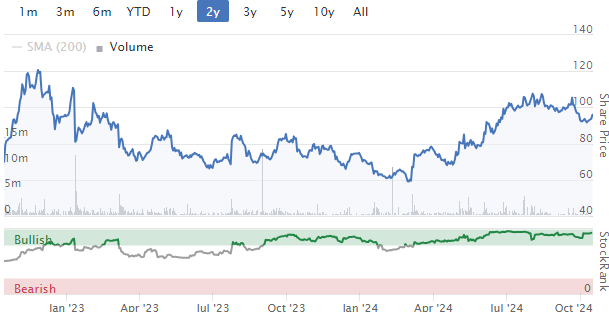
The big question is whether investors can start to get excited about what might happen after the company finishes making large pension fund contributions. That is scheduled for around the end of 2027. Will a valuable business remain at that time, or will it be shrinking even more rapidly by then?
The pension fund issue might not be fully resolved until 2028, at a cost of over £200m. So it’s understandable that the market would continue to treat this one cautiously.
However, I’ve been impressed by management’s ability to squeeze profits out of a declining business, and the year-on-year revenue decline is only about 4-5% currently. So I continue to think that this is an interesting investment idea.
Victoria (LON:VCP)
Down 7% to 118.4p (£135m) - Half-Year Trading Update - Graham - AMBER/RED
Victoria PLC, (LSE: VCP) the international designers, manufacturers, and distributors of innovative flooring, provides a trading update for the six-month period ended 1 October 2024…
This acquisitive carpet company has filled up much space in this report over the years.
The last few years have not been kind to it:
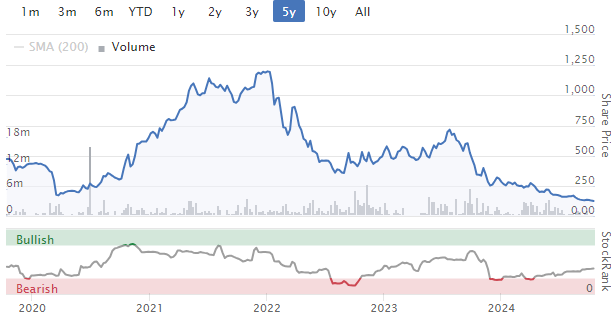
We have shown a healthy degree of scepticism towards this one. Paul has been RED or AMBER/RED in coverage over the past year (July 2024, June 2024, March 2024).
Victoria’s market cap is now less than three times the estimated market value of Chairman Geoff Wilding’s superyacht.
Let’s get into today’s update, which is a profit warning. Key points:
Revenue: demand remains soft and H1 revenue is expected at c. £580m (down 10% from H1 last year: £643m). VCP is thought to have “generally outperformed” the wider market.
Profitability: underlying EBITDA for H1 of c. £50m (H1 last year: £96m), with negative operational leverage caused by falling revenues.
On the bright side, “pricing remains stable and management is taking actions to optimise the cost base”. The Board have noticed some positive signs in their key markets relating to the housing market (mortgage approvals, rising house prices, and lower interest rates) which they believe will lead to increased demand for flooring.
Management actions: Various brands have been merged, and operations have been consolidated. Production has been relocated from Belgium to Turkey. There is now a Group-wide procurement team. And the production of tiles in Spain is also being reorganised, with benefits to be seen from late 2025.
These actions will support “EBITDA margin expansion back towards the Group's historical levels of mid-high teens”. The EBITDA margin in the latest H1 period was only 8.6%, so I guess the company will want to double this.
Refinancing: Victoria’s use of debt has been a source of controversy, and net debt as of March 2024 was a remarkable £633m, with EURO €739m of senior secured notes outstanding. The larger of VCP’s two notes matures in August 2026. This note is currently trading at 87.5 cents on the euro, at a yield of 11.6%, according to Borse Frankfurt:
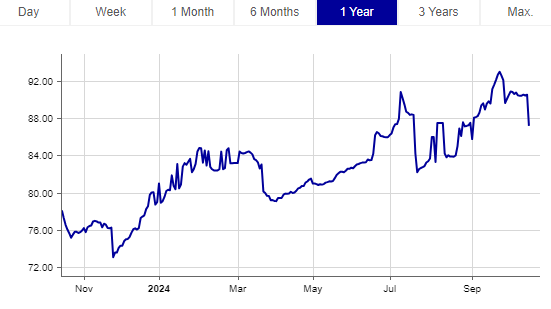
Fitch downgraded VCP’s credit rating to a lower grade of junk in March this year.
Today’s update lets us know that the company still has headroom of £200m and that Lazard have been appointed by the company as debt advisors, as the company makes plans to refinance this bond. The terms of this refinancing will be very interesting!
CEO comment:
"The flooring sector is experiencing the most severe and longest decline in demand in the last 30 years. During this period, we have focussed on optimising productivity and reducing operational costs whilst maintaining the same potential production capacity… Clearly the recovery continues to draw closer, although it is difficult to pinpoint precisely when it will begin. However, we remain prepared for growth when the time arrives, which will be delivered without any significant capex spend."
Graham’s view
This strikes me as a poor investment opportunity. A tough sector (flooring) cannot be made good with the use of leverage, and VCP has 22 months left before it must come up with an answer for its note holders.
Going RED on this might be a little premature, as the company is not currently distressed. But I see this as a high-risk play and it’s not a stock I’d want to own even if it was currently performing well. So AMBER/RED makes a lot of sense to me. But I would want to be RED on this at the first sign of any difficulty with the refinancing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Thank you to all that have replied to my post re taking the 25% tax free lump sum early but I was really just referring to a scenario where it has been done by someone who was previously happy to have left that sum invested in a SIPP . I was talking to a guy in the Pension Dept at Hargreaves Lansdown and he told me they have been totally taken by surprise by the amount of people selling down stocks in SIPPs to take their lump sum. To me I don’t see the advantage unless you now decide you want to do something other than invest this money.
"taken by surprise by the amount of people selling down stocks in SIPPs to take their lump sum"
It would/will be interesting to see the data around average lump sum withdrawals per year, vs this year (especially the period since the new gov issued their calming guidance post election!), i.e. has the recent uptick just been a 'bringing forward' of the next 5 (ish) years worth of withdrawals?
"To me I don’t see the advantage unless you now decide you want to do something other than invest this money."
As above, it is possible that many withdrawers are accelerating a plan they already have, in case the max lump sum is meddled with in the budget.
As per posts below, the cash is still partially 'investable' and can be nearly entirely sheltered from tax, eg 20k/year in to ISA, ~120k to cash savings, remainder in to low coupon short term gilts.
Also of course there will be some who are letting the tax tail wag the dog...
Thank you for the write up on Reach (LON:RCH) Graham. I hold and I concur.
Regards
Michael
My view is that it would be more optimal to have a lower dividend and more funds returned via more ambitious buy-backs, as might allow them to accelerate the pension deficit closure.
Like the ice cube analogy - classic industry in decline.
This post should probably be under the 'Discuss ALL Posts' section so i apologize in advance but it is not as busy as normal on here today so here goes.
Regarding the rumoured possible change to the ability to take 25% of ones SIPP as a tax free lump sum, would some one be kind enough to talk me through the rationale of taking the chance that this is going to be announced in the upcoming budget and triggering the withdrawal before October 30th please.
There will be a lot of variables in different peoples circumstances, however if one does take the 25% sum tax free what do you do with it? If you invest it elsewhere outside a tax efficient wrapper you will attract CGT, if you keep it in cash, interest rates are hopefully heading lower and you will still pay some tax on your interest and end up with bugger all. If you leave it in your SIPP it can still grow hopefully faster than base rate interest levels and if this growth compounds over a few years the tax that you pay on withdrawal will surely be lower than CGT. I feel that I must be missing something, Please someone tell me what it is.
EDIT - I imagine that unless one was planning to take the tax free 25% fairly soon anyone that has done it as a reaction to the rumour will have to have sold down their stock holdings. Having been investing for some time buying is the easy part, when to sell is hard but buying back a stock at a higher price than one reluctantly sold at must be the hardest call of all.
I'm with you, I don't see why you would risk it, if that 25% is part of your future retirement income, as it is with me. I can only assume that for some it isn't, and they have some other use for it, in that case it's probably worth taking it.
It's been the case that some people will always take the 25% regardless, as they see it as free money.
Dragon/Hellvellyn if one was planning to take the 25% tax free lump in the next 2 or 3 years taking it ahead of the budget might be a reasonable risk reduction measure, but only I'd suggest if it were significantly over £100k you received. I'd be amazed if they dropped the tax free element below £100k wouldn't you? And suspect it may not change at all. 50/50 call?
If you were able to take c £250k tax free what would one do with it? Here's my thoughts:
1 Put £20k per head for self and partner into ISA now and plan to do the same in April. (£80k used)
2 Pay off or pay down mortgage (c£100k used) unless paying less than 3% interest or so.
3 Update the car. (£20k?)
4 Give £25k to each of the Offspring and hope to live long enough and make it tax efficient! (£50k used)
Just my thoughts and as you say everyone has different circumstances. If you're fortunate enough to have a SIPP that has £1m + in it there's plenty left to keep growing and safeguarding your future income. Mine didn't get that far and most of the lump went to paying off the mortgage.
You forgot two things:
1. Recycle £2,880 back into a SIPP and get a £720 top up from HMRC whilst available.
2. If you have no other income in the current tax year you can earn up to £6000 in savings interest without paying tax thanks to the Starting Rate of Tax. At a 5% interest rate that’s up to £120k of unsheltered savings.
But you only get the 5k out of the 6k if you are not paying tax.
"If you don't earn enough to pay income tax, you get a starting rate for savings worth £5,000, meaning you have a £6,000 tax-free savings allowance. You can also earn anything up to the income tax threshold of £12,570 tax-free. This means your total tax-free earnings from savings interest could be as much as £18,750.2 Apr 2024" money.co.uk
But you only get the 5k out of the 6k if you are not paying tax.
That’s why I wrote: If you have no other income in the current tax year although what I strictly meant is: if you have an income of less than £12,760 in the current tax year.
There is a risk that we go back to being forced to buy an annuity with all or part of the SIPP pot, before taking a TFLS.
I certainly hope not, what a one way bet for the insurance companies that seems to be…
What I did was to withdraw the 25% in one lump then feed £20,000 a year into my ISA until the pot ran out. I did invest in shares in the meantime.
But why didn't you just take £20000 out each year and crystallize £80000 (4x the tax-free bit). It's called a flexible drawdown, where you leave the taxable part of the drawdown in the pension, assuming your provider allows it.
' why didn't you just take £20000 out each year'
I had retired by this stage and part of my 25% was used for my living expenses. The rationale for taking the full 25% in one go would be more urgent if, as the poster fears, the budget will restrict the amount of tax-free cash.
I took mine for the following reasons.
Its not just about what are you going to do with the money if you take it. Imagine the following scenario. You are entitled to 200K tax free. If they change this to only 100K. If you delay and they change the rules, there is 100K in your pot you cannot take as tax free, and will have to pay tax at your nominal rate on it. Even at 20% that 20K the Government are going to thank you for.
Fill yours and if available partners stocks and shares ISA, Premium bonds, splurge a little. If the doom and gloom happens then the stocks you had to sell may well be cheaper and you have a stash of cash to spend. It was the case of one in the hand was defo better than two in the bush for me.
25% of 200k = 50k but 20% of 300k in say five years time is 60k, i.e. your 200k grows to 300k and you get 10k extra tax free. Just another way to look at it, there are some many variables.
Why is Discoverie (LON:DSCV) a sucker stock on Stocko? Does anyone know?
Hi Chris re Discoverie (LON:DSCV) . Stock ranks explained - all 3 ranks are < 40. (Just click on the word Sucker Stock to view)
Galliford Try Holdings (LON:GFRD) are moving up nicely, some recent director buying and share buy backs...anyone know anything else? I hold
Hi Conistons - always love to see someone seeing positives in a share, makes me take a look (Smoke without fire and all that!). Quick question to your comment some recent director buying - Did you mean last Fridays announcement of the Award of shares under the directors bonus scheme, if so that ain't buying and putting skin in the game. They have been granted them now but they don't vest until Oct 2027.
Galliford Try Holdings (LON:GFRD) Yes, thanks, you're right, no director buys,
As for the positive comments, would that I had more to make! I'm just pleased that something I hold is going up as I seem to have a whole kennel full of dogs atm
But I'm still wondering why?
I’m also surprised at the muted share price response to the news from De La Rue (LON:DLAR) today. I had taken the profits after buying in the summer last year when the share price started to bounce from the extreme lows then,. Though having to pay 20p more than I sold for I jumped at that buy opportunity.
The currency division looks dull as so many have moved to alternative ways of paying these days. But just as recently has seen a surprise increase in popularity of town shopping centres and on physical shopping instead of online, so isn’t there the chance that the same could happen with cash payments too? After all scammers are catching out so many now, but they can’t scam our cash (except via fake notes and it’s now harder to fake notes).
Here’s the De La Rue (LON:DLAR) comment on their currency division in their latest Results:-
“Current trading environment
In the Currency division, market activity is returning to more normal levels after a protracted downturn and our order book has been maintained at the enhanced levels witnessed at the year end.
I think you have pasted too much of the 'current trading environment' text, Ken. Surely only the first two lines are relevant now as Authentication has gone? Nevertheless, currency markets are normalising which must be good news.
You’re right of course sparkler. Thanks for pointing out that I had pasted the lot. Luckily it was in time for me to edit the post to just the first 2 lines.
Amazing volume as well with more than two hours to closing.
Cash is more of a risk than online. Cash can be lost. Cash can be stolen. Some thefts risk physical violence for the victim as well, unlike white collar crime.
Cash is also useful for tax dodging and organised crime, along with bitcoin etc. I've never understood why high denomination notes are still being issued.
Trying to get rid of fifties though is a nightmare nobody wants them do to so many being fake.
Robert Walters (LON:RWA)
My view on recruitment is that there are two trends underway which are disrupting the whole sector. Firstly, the rise of the ‘Head of Talent’ role which in my experience results in a new senior exec’ becoming responsible for recruitment and HR, and employing an army of internal people to manage what used to be external agency/legal work.
Secondly, these people (or managers directly) are using LinkedIn as the ‘go to’ tool for recruiting. LinkedIn itself is also improving its capabilities in this area making it fairly indispensable. More and more frequently candidates do not present CVs, they just send their LinkedIn profiles. For this reason, and the fact it’s a highly cyclical sector, I don’t get involved. I think the exception is in executive search and very niche areas of recruitment where agencies can genuinely add value, and where trawling LinkedIn profiles is well below hiring managers / sponsors’ pay grades.
Below I have asked ChatGPT whether LinkedIn is taking market share from traditional recruiters. GPT obviously needs to be fact checked but this seems reasonable at least directionally to me.
As of my last knowledge update, LinkedIn held a significant share of the recruitment market in the U.K., often cited around 60-70% in some reports. Its growth has been bolstered by the increasing reliance on digital platforms for recruitment, with more companies using LinkedIn for talent acquisition.
Over recent years, LinkedIn has expanded its offerings with features like LinkedIn Recruiter and enhanced analytics, which have contributed to its growing dominance. The shift towards remote work and online networking during the COVID-19 pandemic further accelerated its use.
For the most current statistics and growth trends, checking recent industry reports or LinkedIn’s own publications would provide the latest insights.
Below I have asked ChatGPT whether LinkedIn is taking market share from traditional recruiters. GPT obviously needs to be fact checked but this seems reasonable at least directionally to me
As you hinted yourself, if you want accurate answers from ChatGPT, you have to ask the right question. Unfortunately, in this instance, ChatGPT’s answer is wayward. LinkedIn doesn’t compete with recruiters, except tangentially. Its competition is with Monster, Jobserve, Indeed etc. Recruiters are more normally potential clients where LinkedIn chases their advertising dollars.
See my three posts from yesterday if you’d like some industry colour. Particularly the first two, short ones, which dismiss the fairly widely-held view of outsiders that internal talent teams and new tech are what’s ailing recruiters today. There is literally no evidence for that.
Not strictly relevant to this thread but thought you would be more likely to view it on today's comments. Referring back to your list of Japan & Europe investments in your fund one of your high conviction holdings (my assumption from your highly positive write up) was ASML Holding NV (AMS:ASML). Today they somehow managed to get their results 'leaked' a day early and the market really didn't like it with a 15% fall in the share price. This seems to have focused on the Q3 net bookings figure of Euro 2.63bn vs a consensus estimate of Euro 5.6bn. This combined with a pretty cautious outlook for 2025 has hit the shares hard. Morningstar research remained very positive on the share as recently as last week but perhaps the situation has changed. Not sure if it is a great opportunity to top up on a great company or a warning that things in the short to medium term could get a lot worse before they get better!
Hi. And thanks for thinking of me. I saw the drop at 15:30 today and initially thought it must be an overreaction to the news that the US is thinking of restricting chip exports (again). I was puzzled why the apparent reaction came an hour later than the bulletin. Of course, all was revealed when I learnt of the early release from the company. I’m all over European chip stocks and this has had a big knock on effect there as well. I’ve seen this play out before however. ASML has very lumpy orders and the semiconductor market is inherently volatile. I’m happy to smile and carry on. Might be a good opportunity for others to do some research. This monopoly just got a lot cheaper.
Hi BnB,
Thanks, I went back and read your posts of yesterday which are indeed interesting and very informative. However, I cannot shake the feeling that this is an industry ripe for disintermediation. While you insist that there is no impact from LI I can’t see how this can be confirmed either way. It seems counterintuitive to assume that it’s solely the market and that LI is not leading to market share leakage. There may be market reports that can help but these would not be able to see the share of employees making direct introductions via the platforms. I guess the only way to know would be to survey a representative sample of employers for recruits by channel over x years. There’s no question that in the businesses I’ve worked in managers are increasingly incentivised to source candidates directly from LinkedIn, both from their own networks (which are more expansive due to the platform) and from using the recruiting functions, with or without help from an internal talent team.
You may well be right and you definitely know the industry far better than me, but I can’t help thinking of the proverb in John Piper’s book… ‘if you can keep your head while all around are losing theirs, perhaps you’ve misunderstood the situation’….
There’s no question that in the businesses I’ve worked in managers are increasingly incentivised to source candidates directly from LinkedIn, both from their own networks (which are more expansive due to the platform) and from using the recruiting functions, with or without help from an internal talent team
Absolutely, but you have to balance those trends with the extra productivity that LinkedIn and other tech has brought to recruitment firms. The internal matrix of every organisation is laid bare for every consultant to exploit. It’s a licence to headhunt!
And don’t forget, you are talking about perm recruitment, when the real money is in contract and temp, which are on the rise structurally as a proportion of employer spend. Virtually none of that is performed in-house because of the payroll complications and the reduced ROI.
Finally, I would point out that most internal “talent acquisition specialists” are former recruiters. The ones who didn’t make it. Is it really them you want them running your vital hiring program? Most line managers in specialist sectors understand this.
If people are using anything anyone posts on LINKEDIN then more fool them. I know a lot of people who put what they have done on that site, and it is a million miles away from reality.
Completely agree Bob
I have always found Linkedin to be a strange platform. Peopled by individuals craving attention and who all speak to each other in a kind of bizzare sub-language that they would never use face to face.
Having said that, I have occasionally found it of use as a starting point as a background information source on people/companies . And it is free.
Paul, thanks for the write up on DLAR. As an ex-holder did a fag packet sums regarding 300 million GBP
As per todays announcement:
Pension deficit contribution 30 mill
Additional deficit repair contribution 12.5 mil
Pension mess total of 42.5 mill
They mentioned few times of paying RCF, so numbers from their balance sheet as of Mar 2024
RCF drawdown: 118 mill
Secured (guaranteed): 41.8 mill
Total Debt 160 million
Thats circa 200 million (pension + debt)
Then other over heads as you mentioned fees of circa 13 mill
Leftover amount is 87 million, cash in bank 72 mill (+15 mill in escrow). Still not bad.
With debt paid fully, the Interest charges of 21 million as per Mar 2024 statement should flow to bottom line post tax. Could be roughly 10 p per share.
Hi Paul,
As Friday is typically quiet I had an idea for something you could do during your macro piece. The upcoming budget has investors spooked, but I was wondering if you could go into a bit more depth about which stocks would be hit hardest (or potentially benefit) from some of the rumoured proposals.
For example Burnt Onions mentioned in a another discussion that Card Factory (LON:CARD) could be adversely impacted by increases to employee NI if that goes ahead. There has also been discussion about the gambling tax being increased impacting Evoke (LON:EVOK) and Entain (LON:ENT), among others. On the flip side Made Tech (LON:MTEC) has jumped over 10% since he announced additional funding for government projects.
Cheers,
BenHazz
Not specifically for Paul to address but what level of impact do we think the potential increase in Employers NIC will actually have?
What is the likely increase? From current 13.8% tax on jobs to 15%? Or does it need to go to 17.5% or even 20% to raise the required money for them to waste on pet projects?
How much does the Employers part of the NIC tax actually raise now? Does anyone know? I believe total NI raises around £170bn which is around 15% of all Govt income. Haven't found the split anywhere. Are we worrying over something relatively incidental or actually substantial?
Certainly agree retail and hospitality likely to be hit hardest. Can hear Tim Martin revving up already. Difficult to square the growth agenda with further anti business measures, IMO.
'what level of impact do we think the potential increase in Employers NIC will actually have?'
This was covered on the Today programme this morning as well. The head of the CBI said that she was happy for employers' NI to go up if the proceeds were actually invested in economic growth. I'm not really sure how sincerely she believed this.
Please find IFS estimates re NI breakdown below:
https://ifs.org.uk/taxlab/taxl....
For more context, NI is a massive revenue source in the scheme of things:
Thanks Northender that's really helpful. So a 10% increase in Employers NI would raise c£11bn with the rate for businesses increasing from 13.8% to c15.2%. Hopefully not the end of the world for any business but it does seem intrinsically wrong to me to tax businesses for providing employment.
Let's see how much they are after.
What do we think on@ Mittie ?
EnSilica (LON:ENSI)
Announce a design and supply contract worth over $31m over 7 years but they haven't released results for the year to May 24 yet, which are now well overdue. It implies that financial processes are not a priority.
Further to that, looking at the H1 results, they now have £18.5m of development costs capitalised as intangible assets, a large number in relation to a £45m market cap, enough to make me very suspicious
Crystal Amber Fund (LON:CRS)
Rush of blood to the head perhaps?
I have just bought a position in the above for my daughter. The fund holds 17% of De La Rue (LON:DLAR) and trades at a significant discount to NAV of around 170p.
Its other largest position is in Morphic Medical, previously known as GI Dynamics, which is making significant progress in the development of a non invasive method for the treatment of obesity and diabetes known as ‘reset’. This is not a blue sky holding. For an overview on the regulatory progress of ‘reset’ see the announcement by Crystal Amber Fund (LON:CRS) of 31 July. It is reported that it is at a late stage of obtaining CE approval with sales anticipated in Germany this autumn. The risk reward appears positive. We shall see!
Are MM or GI listed independently?
Hi Daniel
Morphic Medical when known as GI Dynamic was listed in Australia, but delisted. I think that Criystal Amber had some involvement with the delisting.
Crystal Amber Fund (LON:CRS) which is in the process of winding down owns almost all of the equity.
Doesn"t the incredible success of Ozempic torpedo the idea of implanting a device to cure obesity/diabetes ?
Ozempic is a prescription medication only available to specific individuals, e.g. those who are severely obese. It is administered by weekly injection and as with any medication there are some potentially unpleasant side effects.
Details are available at:
https://www.diabetes.org.uk/
'Reset' is a medical device that is inserted into the small intestine via a gastroscope.
My understanding is that it forms a sleeve that lines part of small intestine and the food (the chyme from the stomach) passes through the sleeve avoiding contact with bile and other digestive secretions. It is removed after treatment. It doesn't depend on medication to achieve weight loss. This I suspect is somewhat simplistic explanation, but a video showing how reset works is available on the link below
RESET® Type 2 Diabetes Treatment - Morphic Medical
There was a short interview with the chief executive of Robert Walters (LON:RWA) on the Today programme at roughly 7.15. I was still dozing in bed so did not take it all in but his basic message was that due to economic uncertainty employers are reluctant to take on new workers and employees are less likely to accept job offers.
There was a short interview with the chief executive of Robert Walters(LON:RWA) on the Today programme at roughly 7.15. I was still dozing in bed so did not take it all in but his basic message was that due to economic uncertainty employers are reluctant to take on new workers and employees are less likely to accept job offers.
I took a lot longer to say the same thing in a long post yesterday morning!
Too modest. Your analysis left me disappointed in his despite his time constraint, poor chap!
'I took a lot longer to say the same thing in a long post yesterday morning!'
Oddly enough, he omitted to mention the exorbitant fees that agencies charge.
Reminiscent of Harold Wilson who brought in Selective Employment Tax in 1966 scuppering my new position with Norwich Union overnight. Also remember his £50 limit on money leaving the country, but only from a tourist perspective. Later, after joining the Army and finding myself attached to the UN troops, discovered that the additional pay most other country's servicemen received was withheld by him too. Jolly times.
YouGov (LON:YOU) has changed its joint corporate brokers from Numis + Berenberg to JP Morgan + Morgan Stanley + Berenberg.
There's always a danger in over-interpreting these things, but I'll take a wild guess that swapping out Numis for JP Morgan and Morgan Stanley is more costly.
Adding cost is, on its face, a surprising step for a business that is focused heavily on cost control following the PW. And signing up three illustrious names for a £480m market cap is, on its face, excessive if the real purpose is simply to promote the investment case.
On the other hand, YOU is an obvious private equity target as the founders have sold down their stakes over time.
YouGov (LON:YOU)
could it perhaps be that they are setting line in the sand to say the stonking profit warning this year will not be repeated (at any cost?) -the shareprice dropped nearly 50% in June. That might be a total over reaction based on events beyond their control - but does the market not expect slightly more realistic in year assumptions ? I perhaps have a bit of sympathy here as it looks like its gone from preimum growth rating to bog stand low digit p/e overnight and thats always going to have an huge effect on the shareprice. Is the business perhaps up for sale here ? - i know not.
De La Rue (LON:DLAR) that’s some deal!
Crane NXT to buy the authentication division for £300m
Could we see De la Rue transform from a large pension deficit with a business attached to a functioning business with a manageable pension scheme?- I’ll await Paul’s insight to find out
Franchise Brands (LON:FRAN) has launched a buy back of £5m to take advantage of pre-budget selling that's unrelated to FRAN's prospects. This looks like excellent capital allocation to me.
Should more companies be taking advantage of the share price volatility to opportunistically generate shareholder value?
There's no change to FRAN's targets for debt reduction for FY24 (2.0x) and the end of 2027 (bank debt eliminated) which implies that cash generation is ahead of plans.
Franchise Brands (LON:FRAN)
to take advantage of pre-budget selling that's unrelated to FRAN's prospects
errrrr could the reason for people selling up perhaps be related to the ongoing reductions in expected earnings per share this year and next perhaps?
Seems plain wrong to blame external factorsfor weak shareprice when company has been reducing earnings expectations ref this year and next - i am presuming figures on stock confirming this situation are factually correct - if stocky is wrong please ignore my comments.
Franchise Brands (LON:FRAN) put out interims on Tuesday 17 September that led brokers to reduce forecasts. The SP closed each day for the remainder of that week above 160p. The subsequent fall by 10% to 144p might have been a delayed response to the downgrade, but it seems more likely that all or most of the subsequent move was caused by budget issues since the market doesn't normally take >4 days to process new information and we have seen lots of budget related volatility in other stocks.
My morning smallcap tweet: Carpet bombing
Victoria (LON:VCP) De La Rue (LON:DLAR) Tern (LON:TERN) EnSilica (LON:ENSI) Active Energy (LON:AEG) Graft Polymer (UK) (LON:GPL) Abingdon Health (LON:ABDX) Robert Walters (LON:RWA) Audioboom (LON:BOOM) Franchise Brands (LON:FRAN) GSTechnologies (LON:GST) H C Slingsby (LON:SLNG), Reach (LON:RCH), Victorian Plumbing (LON:VIC), Tatton Asset Management (LON:TAM), Hostelworld (LON:HSW), Discoverie (LON:DSCV), Integrafin Holdings (LON:IHP), Quartix Technologies (LON:QTX)
◄Victoria (VCP)► guides H1-Oct rev £580m and U/L EBITDA c.£50m due to soft market. "The wider market is witnessing an estimated 20-25% decrease in demand versus 2019." Warns FY earnings miss likely. [SP=127.8 Cap=146m]
◄De La Rue (DLAR)► agrees sale of Authentication Division for £300m (EV). Expects sale to complete in H1 of 2025. Will repay debt and pay extra £30m to pension scheme. [SP=94 Cap=184m]. I hold.
◄Tern (TERN)► £625k placing at 1.25p, a 42% discount, to invest further in portfolio companies and for general corporate purposes. What a business model! [SP=2.21 Cap=10m]
◄EnSilica (ENSI)► wins $31m+ 7 year contract. [SP=46 Cap=44m]
◄Active Energy (AEG)► £125k convertible loan from Zen Ventures to fund FY23 audit and H1-24. Expects publication in Dec. [SP=0.06 Cap=m]
◄Graft Polymer (GPL)► research agreement with the University of Nottingham entered by its partner, Awakn Life Sciences Corp. Will evaluate the potential of aminoindane new chemical entity co-lead series to enhance social cognition and pro-social behaviors. [SP=0.16 Cap=4m]
◄Abingdon Health (ABDX)► opens US commercial office and laboratory. [SP=8.71 Cap=17m]
◄Robert Walters (RWA)► guides Q3 net fee income down 14% and 12% in const FX. "Though market conditions mean second half fee income is unlikely to exceed that seen during the first half, the programme of actions underway mean we continue to aim for a profitable full-year outcome." [SP=351 Cap=254m]
◄Audioboom (BOOM)► hikes FY-Dec EBITDA expectations to $2.5m from $1.3m after Q3 rev rose 34%. [SP=212.5 Cap=35m]
◄Franchise Brands (FRAN)► restarts share buyback. [SP=146 Cap=283m]
◄GSTechnologies (GST)► update on its businesses. [SP=0.65 Cap=13m]
◄HC Slingsby (SLNG)► Q3 rev down 11%, worse than H1's 8%. Blames customers reducing or deferring spending following cost increases. Q1-3 loss of £0.53m. Remains cautious regarding the FY outlook. [SP=251 Cap=3m]
In line: RCH, VIC, TAM, HSW, DSCV, IHP, QTX
Tatton Asset Management (LON:TAM) - "Bumper H1-25, AUM up 14% driven by inflows" - new research here: https://www.equitydevelopment....
Tatton has recorded an exceptionally strong start to the next leg of its growth journey: in June ’24 it set a target of reaching £30bn of Assets-Under-Management or Influence (AUI) by end-FY29, an 11% CAGR. But H1-25 (to 30 Sep 24) saw AUM jump 14% in just six months from £16.6bn to £18.9bn. Net inflows contributed £1,832m (22% p.a. inflow rate), and investment returns £534m (3.2% over 6m), in line with the MSCI PIMFA Private Investors Balanced Index. Including the AUM of 50%-owned 8AM Global, AUI totalled £19.9bn on 30 Sep 24.
With so much uncertainty around the UK budget (due 30 Oct 24), which could have implications for investors’ capital allocations and financial markets, we feel it prudent to wait a few weeks before updating forecasts, until Tatton’s interim results on 13 Nov. But we certainly see potential for a substantial upgrade if growth continues anywhere close to the current rate. Our June 24 note details our current valuation of 640p per share & Tatton’s growth opportunities in more detail.
Any good at trading? Well find out here.
You see in Elm Wealth’s "Crystal Ball" game, you'll be pitted against Wall Street’s best traders across US SP&500 & 30 year bond futures. However in order to rebalance the odds a little, each player is allowed to read the front page news from the Wall Street Journal one day in advance.
Meaning before ‘staking your bet’, you'll be told what actually happened in terms of key macro events, corporate results and economic data 24 hours earlier than everyone else. Which is the Crystal Ball part of Elm’s game.
From this, you’ll then be allowed to go either long or short across the equity & bond markets at prices prevailing the day before. Albeit anything that mentions what US stock/Treasury prices actually did have been redacted from the front pages. In terms of the rules, each player is given $1m of imaginary money at the start, and has 15 days’ headlines to trade – or 1 per year chosen randomly.
There are no transaction/financing fees and 1x leverage means that your position size is the same as your total capital value. Lastly you can also "skip" any day you don't feel like betting, and also "finish" at anytime – ie if you don’t wish to trade all 15 headlines.
As comparatives, please find below the Elm averages so far, alongside my own attempt. Very best of luck everyone. It's not quite as easy as you might think!!
Indeed up to last Thursday (10th Oct), 8,117 people have had a crack - losing on average -31.2% or $322k each after 15 rounds.
Where do I pick up the cheque Paul.
Pure luck going 50x leverage on jobs headlines, tho funnily enough my actual real life 'batting average' is almost identical