Small Cap Value Report (Tue 16 April 2024) - SDRY, DOCS, TAM, AWE, EQLS, AT., BOWL, CTO, PRV, SOS

Good morning from Paul & Graham!
Today's report is now finished.
The SNS (Sky News Service!) was saying last night that Superdry (LON:SDRY) is about to announce details of a CVA to reset its rents to an affordable level, so I'll keep my eyes peeled for that. EDIT: see details of restructuring & fundraise below.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Lots of companies reporting today, so please remember we can't cover everything. We focus on over/under expectations updates, top viewed (by subscribers here), shares on our top ideas lists for 2024, takeover bids, and anything else interesting that we have time left to look at.
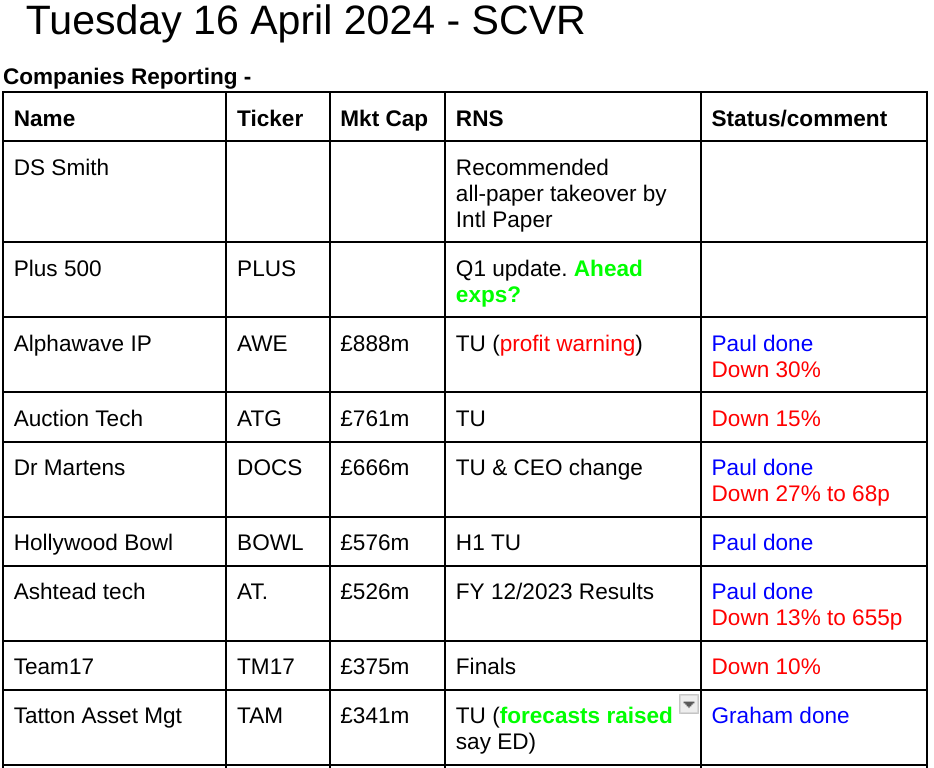
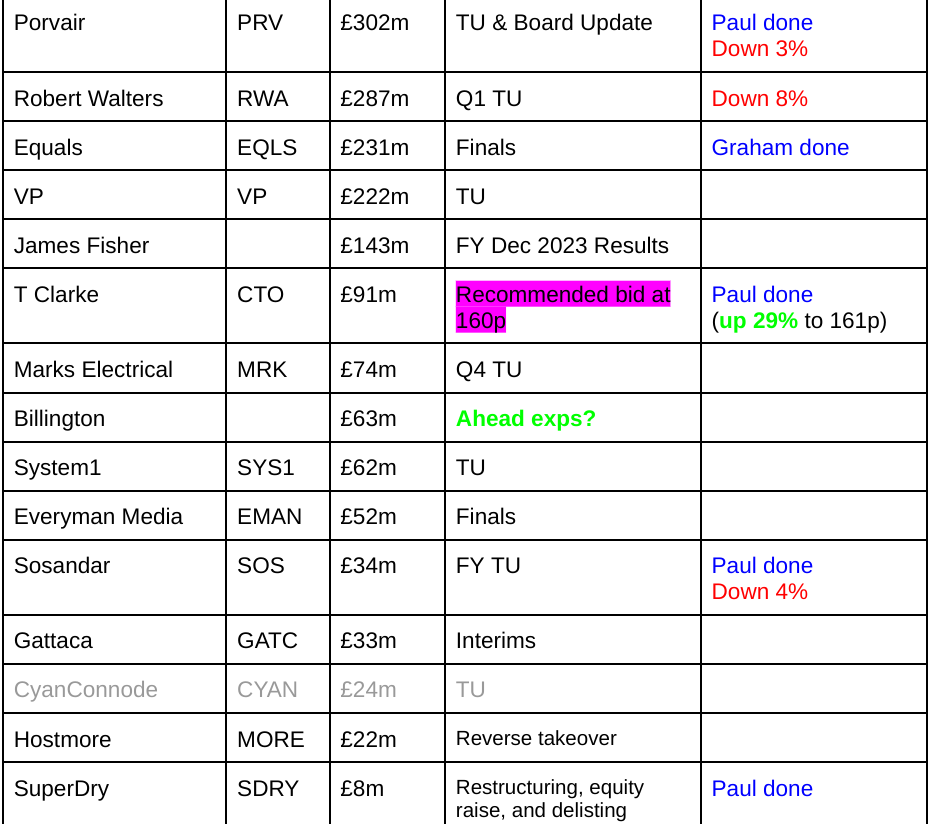
Summaries of main sections
Superdry (LON:SDRY) - Down 25% to 6.0p at 08:22 (£6m) - Restructuring & fundraise - Paul - RED
Confirms details of its expected restructuring. Equity fundraise at either 1p (open offer), or 5p placing (Dunkerton only). De-listing in June 2024. Equity probably worth nothing now, in my view, unless you want to hold shares in a struggling, highly indebted private company.
Dr Martens (LON:DOCS) - Down 27% to 68.5p (£666m) - Trading Update & CEO Change - Paul - BLACK (PW) (on fundamentals: RED)
Things go from bad to worse at this fashion boots brand. FY 3/2024 in line, but profit warning for FY 3/2025 says worst case scenario profits could be down by two thirds. It has balance sheet issues - too much debt, and excess inventories. Looks a mess, and it's not cheap even after today's plunge. A terrible over-priced, opportunistic 2021 float.
Tatton Asset Management (LON:TAM) - up 5% to 585p (£354m) - Trading update - Graham - GREEN
I try to justify a continued “GREEN” stance on this one: Tatton has performed amazingly well over the past year with significant net inflows and a 27% increase in AuM. Some investors may wish to take profits here, but I could see it continuing to run. PER is now over 20x.
Alphawave IP (LON:AWE) - down 28% to 119p (£871m) - Trading Update (PW) - Paul - BLACK, fundamentals: RED
Profit warning from this chip designer. I go through the numbers, and struggle to value this share, due to its poor cashflows, lack of broker notes available to us, and complicated accounts. As I mentioned last time in Jan 2024, until it establishes a proper track record of profitability & cash generation, it's impossible to value. An over-priced 2021 IPO. Tech experts might be able to shed some light on the company's products/markets & prospects, all I'm doing is reviewing the numbers, and I don't have any view on those other things.
Equals (LON:EQLS) - up 0.5% to 123.6p (£232m) - Final Results - Graham
Excellent results from this provider of payments services to businesses. Revenues have grown strongly (+37%) and converted to 70% growth in adj. EBITDA. Perhaps being overly cautious, I take a neutral stance as there are some aspects of the story which I find puzzling.
Hollywood Bowl (LON:BOWL) - down 1% to 333p (£570m) - H1 Trading Update - Paul - AMBER/GREEN
This update sounds OK, but they don't specifically confirm trading vs expectations, which raises questions. UK LFL revenue growth is only small. It's had a good share price move, and looks to be fairly priced I'd argue. That said, this is a high quality business, very cash generative, paying a nice 4.1% yield and self-funding modest expansion. So I still like it, but a little bit less now the price has gone up.
Porvair (LON:PRV) - down 1% to 647p (£298m) - AGM Trading Update - Paul - GREEN
Reassuring update. Nice quality group, with an excellent long-term track record, and still reasonably-priced I think. Thumbs up as a long-term share idea from me.
Sosandar (LON:SOS) - down 11% to 12.25p (£30m) - FY Trading Update - Paul - AMBER
It's trading around breakeven, not bad going in a very tough sector. Plenty of cash, and about to start its trial of physical stores. Maybe priced about right for the time being?
Paul’s Section:
Superdry (LON:SDRY)
Down 25% to 6.0p at 08:22 (£6m) - Restructuring & fundraise - Paul - RED
Restructuring announced. Confirms intention to delist (in June 2024), to save money and “heightened exposure of public markets”. Equity raise being underwritten by founder Julian Dunkerton. Landlords and local authorities (business rates) will be asked to reduce liabilities. Suppliers will not be affected. Expected completion June 2024. Alternative is insolvency (Administration) if this deal doesn’t go through.
Fundraise - shareholders are given 2 options to vote on: 1p fundraise through an open offer to existing shareholders to raise E8m. OR a placing at 5p to raise £10m but only for Julian Dunkerton! So in reality the fundraise price is irrelevant, as he will take full control under option 2. I'm not sure why option 1 is in euros, and option 2 in sterling?
Paul’s view - grim, as expected. I remain of the view that the existing equity is probably worth nothing now - unless you want to own shares in a heavily indebted, tired brand, which is about to de-list. I don’t believe that rent cuts will transmogrify this into a successful business, it's probably more a stay of execution - that's what normally happens with retailers that do this kind of restructuring - they go bust or do another restructuring a year or two later typically. This outcome (de-listing & deeply discounted fundraise) was indicated in the last update from the company, so shouldn’t come as a surprise to anyone.
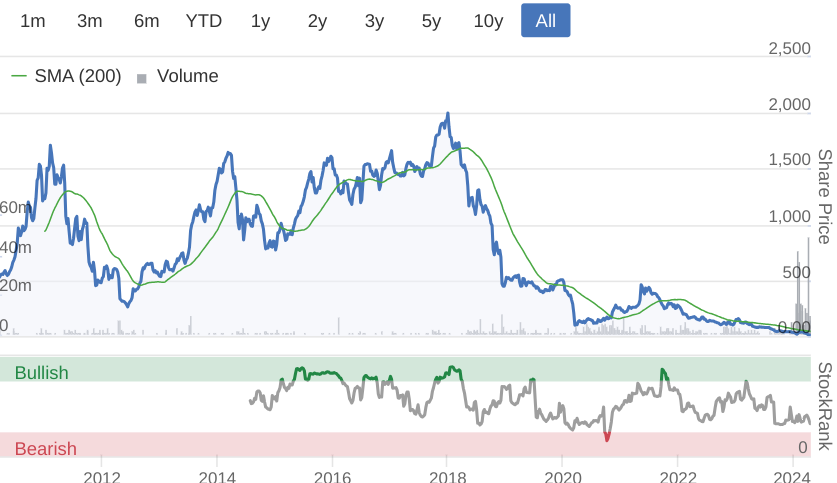
Dr Martens (LON:DOCS)
Down 27% to 68.5p (£666m) - Trading Update & CEO Change - Paul - BLACK (PW) (on fundamentals: RED)
FY 3/2024 sounds OK -
Dr. Martens Plc (the Company) will announce its FY24 results on 30th May, with results expected to be in line with guidance and consensus expectations.
Outlook for FY 3/2025 is what’s caused the 27% share price plunge today.
Key points -
USA wholesale orders down sharply, expected to hit profit by £20m.
Cost inflation will hit profit by £35m, and won’t be raising selling prices this year, so can’t mitigate it.
Extra costs of £15m to store (presumably excess) inventories in FY 3/2024 will repeat in FY 3/2025.
Overall - it’s heading for a serious fall in profit -
There is a wide range of potential outcomes for FY25 given that we have only recently started the year. However, we have assumed that revenue declines by single-digit percentage year-on-year and at the PBT level we could see a worst-case scenario of PBT of around one-third of the FY24 level. There are also scenarios where the profit outturn could be significantly better than this, with the key factor being if USA performance is stronger than our planning assumptions as we progress through the year. We will also look to drive cost savings wherever possible, whilst protecting our brand and future growth opportunities. Against this backdrop, we are focused on cash generation and have already significantly reduced purchases from the supply chain, which will underpin the strength of the balance sheet.
Our business is always second half weighted, however this year, given the phasing of USA wholesale and costs, this will particularly be the case…
"We have built an operating cost base in anticipation of a larger business, however with revenues weaker we are currently seeing significant deleverage through to earnings…
Paul’s opinion - this sounds grim, and I won’t be tempted to catch this particular falling knife. DOCS clearly has lots of problems.
Is it likely to go bust, or need an equity raise? The last (Sept 2023) balance sheet showed only about £99m NTAV, and hefty net bank debt of c.£275m. So investors need to look carefully at the terms & covenants of the bank debt. Banks don’t like funding excessive inventories that aren’t selling, and DOCS will have to figure out how to shift its excess inventories (that means discounting, which lowers profit margins of course).
The trouble with holding shares like this, is the temptation to average down because it seems cheap. However, at £666m market cap with little asset backing, and a big profit warning today (FY 3/2025 profit could be up to two thirds down on FY 3/2024), I’d say it’s actually not cheap. DOCS looks like an opportunistic float at an over-valuation during the pandemic boom.
The CEO says he will step down and hand over to the COO this year.
I think it could take a year or two to sort out this business.
Overall, it’s a mess, so it’s an avoid for me at the moment, RED.
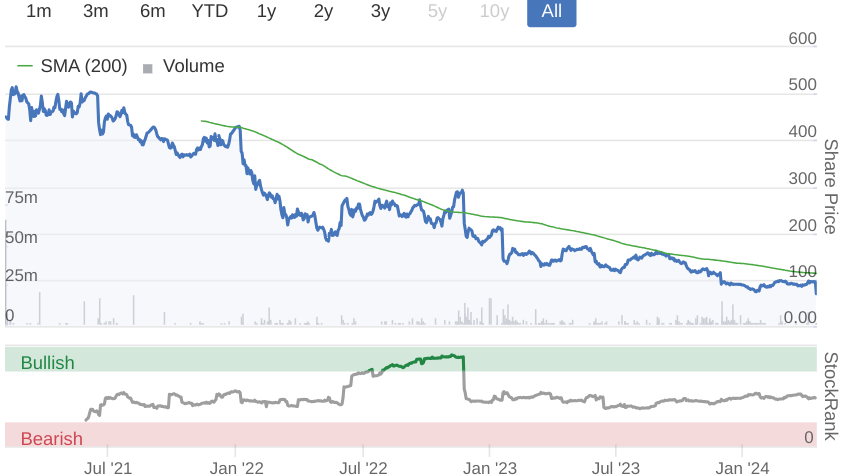
Alphawave IP (LON:AWE)
Down 28% to 119p (£871m) - Trading Update (PW) - Paul - BLACK, fundamentals: RED
This is another 2021 float. I’ve only looked at it once here on 23 Jan 2024, where I concluded negatively (RED at 134p) because of the lack of a profitable track record, and that EBITDA didn’t turn into positive cashflow in H1.
LONDON, United Kingdom and TORONTO, Ontario, Canada 16 April 2024 - Alphawave IP Group plc (LN: AWE, the "Company" or "Alphawave Semi"), a global leader in high-speed connectivity for the world's technology infrastructure, is publishing a trading update for the year ended 31 December 2023 and for the year-to-date 2024.
Revenue and EBITDA for 2023 are below expectations -
Based on the near completion of the audit process, the Company now expects FY 2023 revenue of approximately US$318m-323m which is below the original outlook for the year (US$340m to US$360m). This is mainly due to the accelerated transition away from China, and changes in expected revenue recognition of long-term contracts in advanced nodes.
As a result of the lower revenue and continuing investment in advanced R&D, the Company now also expects reduced adjusted EBITDA for FY2023.
Net debt is much worse than a year earlier at end 2022 -
At the end of 2023, the Company held US$101.3m in cash and cash equivalents and had borrowings of US$220.4m, comprising a revolving credit facility of US$125m, a term loan of US$94m and other long-term borrowings of US$2m. The net debt position was US$119m (FY 2022: US$24m)
Guidance for FY 12/2024 - it makes positive noises about this year, saying it’s had a “stronger than expected start to 2024…”
Alphawave Semi expects 2024 revenue of US$345m to US$365m and adjusted EBITDA of approximately US$70m or approximately 20% of revenue, which is at the mid-point of the revenue guidance range.
Guidance for 2025 is also provided (unusually) -
...the Company now expects 2025 revenue to be approximately US$450m and adjusted EBITDA margin to be between 20% to 25%. The new 2024 and 2025 guidance has been prepared on a bottom-up basis with projects that are currently being delivered across IP licensing, custom silicon and silicon products…
Paul’s opinion - I remain wary of this share. As I mentioned last time, it doesn’t have a track record of proper profits or cashflow. It spent a large cash pile on acquisitions, so the balance sheet is now full of intangibles.
We’re being asked to value it on EBITDA, but overall cashflow was negative in H1 for variety of reasons - negative working capital movements, heavy capitalised R&D, finance costs, etc.
It may be the best thing since sliced bread walked through the door, but the figures are telling me to keep a wide berth. So I’ll stick with RED for now. We need more proof that there’s a successful business here. The contract wins sound great, and it mentions AI of course, so who knows what the future holds? I think we’re being asked to pay far too much up-front for something without an established track record that backs up such a hefty valuation.
Ashtead Technology Holdings (LON:AT.)
Down 14% to 652p (£521m) - FY 12/2023 Results - Paul - AMBER/GREEN
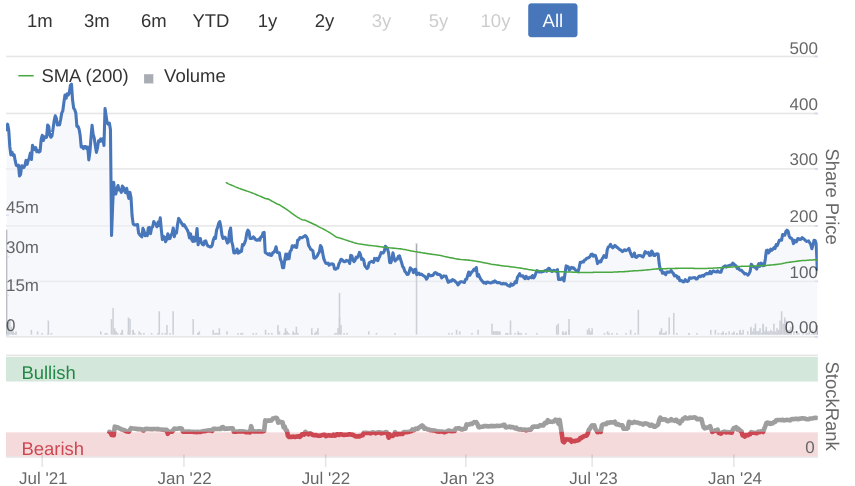
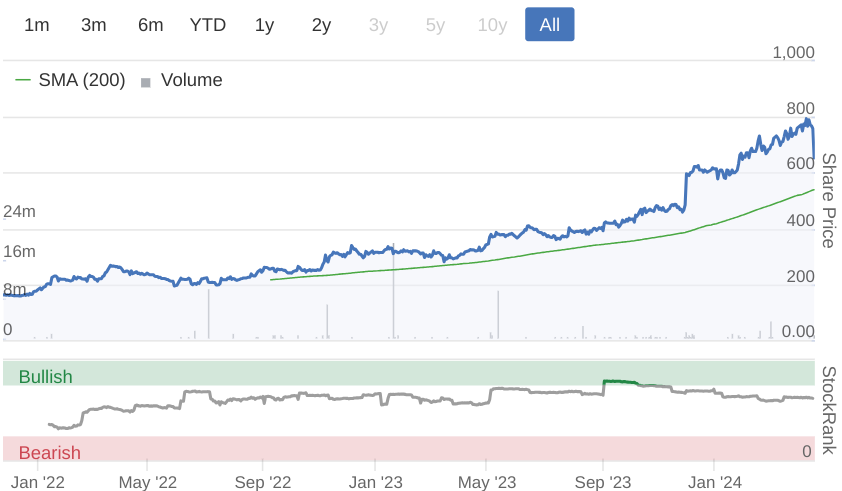
The context of today’s 14% fall is that this has been a very good float from Nov 2021. Is today’s fall a blip in an uptrend, or has the excitement come to a shuddering halt?
Ashtead Technology Holdings plc (AIM: AT.), a leading subsea equipment rental and solutions provider for the global offshore energy sector, announces its full-year results for the period ended 31 December 2023.
Some lovely numbers in the highlights table -
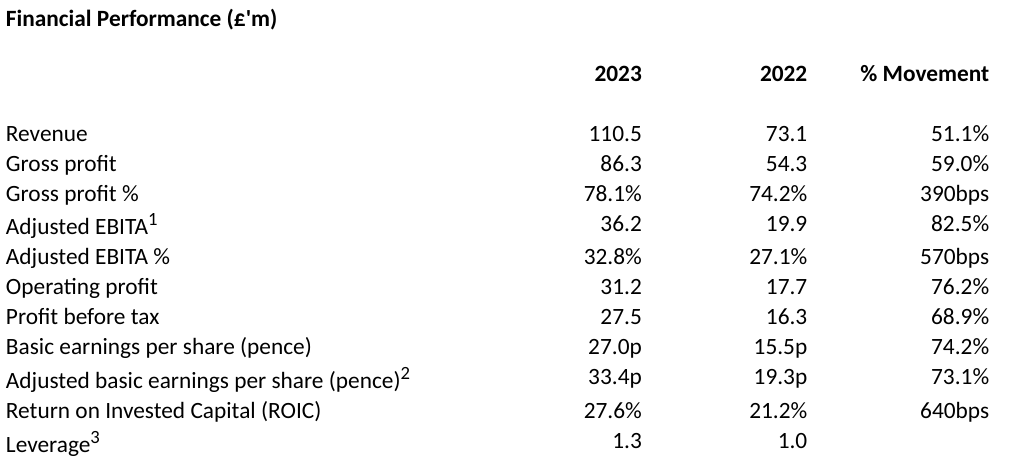
Really impressive organic revenue growth of 35%, with the rest being acquisitions.
Valuation - using adj EPS of 33.4p, at 652p currently, the 2023 PER is 19.5x - not expensive if it can keep growing at anything like the rate of growth in 2023.
The StockReport shows 29.7p broker consensus, so this could be a beat, if the figures are calculated on the same basis.
Note that finance costs have shot up from £1.46m to £4.0m as it's geared up with more bank debt.
Outlook - sounds fine, with more detail provided, the key bit says -
The Board is encouraged by the Group's performance in Q1 2024 and our full year 2024 expectation remains unchanged.
Broker updates - nothing is available to us. I wonder if one of the premium brokers might have slipped out some more caution on the outlook to their privileged clients? We’ll only find out later this week, if the broker consensus forecasts dip. But why would brokers lower estimates, given that AT.’s outlook comments say there’s no change in the outlook?
There’s an IMC webinar this Friday.
Balance sheet - not great. Taking off £95m intangible assets (goodwill & similar), gives only £3m NTAV. So the rapidly growing hire fleet is being funded entirely through increased debt.
You can decide for yourself whether that matters or not. Bulls would say that AT. generates a strong return on investments, so it makes sense to borrow more cheaply than the return it makes on those investments. Bears would point out that there’s no net tangible asset backing to protect the company if/when it runs into an industry downturn - oil & gas being a particularly volatile sector (although currently doing well, and with renewables also providing an additional boost through offshore wind farms).
Cashflow statement - looks good. It made £39m in post-tax, post finance costs operating cashflow, up about 20% on 2022 (2022 was boosted by favourable working capital movements that didn’t repeat in 2023, so the underlying increase is more than 20%).
The main outflows were £19.5m in capex - buying more equipment to hire out, and a whopping £51.2m in acquisitions of bolt on companies. That obviously leaves a big shortfall, which was plugged with a net increase of £36m in bank loans.
There seems to be loads of headroom on the bank facilities.
Going concern statement is clean, no issues there.
Paul’s opinion - these are really impressive numbers. I can’t see any reason why the share price would sell off 14% today. If I’ve missed anything, please leave a comment in the comments below.
Ashtead Tech looks an excellent niche business, that is clearly making hay whilst the wind blows! But high returns attract competition, and the good times don’t always last forever.
That said, after a pullback today, I’m finding the valuation overall quite reasonable, and with further expected increases in profits in 2024 (in part due to the acquisitions contributing further growth), I’m happy to up my view from amber to AMBER/GREEN.
Hollywood Bowl (LON:BOWL)
Down 1% to 333p (£570m) - H1 Trading Update - Paul - AMBER/GREEN
Hollywood Bowl Group, operator of the UK's and Canada's largest ten-pin bowling brands, is pleased to announce a trading update for the six months ended 31 March 2024.
I have a favourable preconception of BOWL shares, and it was on my top 20 ideas list for 2024, so I could have unconscious bias, you should bear in mind.
UK revenues (87% of the group total) were only up 1.3% on a like-for-like (LFL) basis (excludes new site openings) - that’s not great when inflation has been considerably higher for much of this period, especially wage costs which are likely to be significantly up due to living wage increases.
Canada is performing better with +8% LFL revenue growth.
Outlook - a bit too vague. We need a specific statement that it is trading in line with market expectations. It says that refurbishments and new sites are performing in line with expectations, but it ducks the question for group performance overall. That is bound to raise questions.
The Group is confident about the outlook for the business in FY2024 and although the economic backdrop remains challenging for consumers, remains focused on offering a high quality and great value for money experience, with broad appeal to all customer groups looking for leisure experiences to enjoy together.
Cash position remains healthy -
The Group had net cash of £41.4m at 31 March 2024. Its highly cash generative business model continues to enable further investment in growing the portfolio in the UK and internationally, through new centre openings, acquisitions and the rolling refurbishment and rebrand programme.
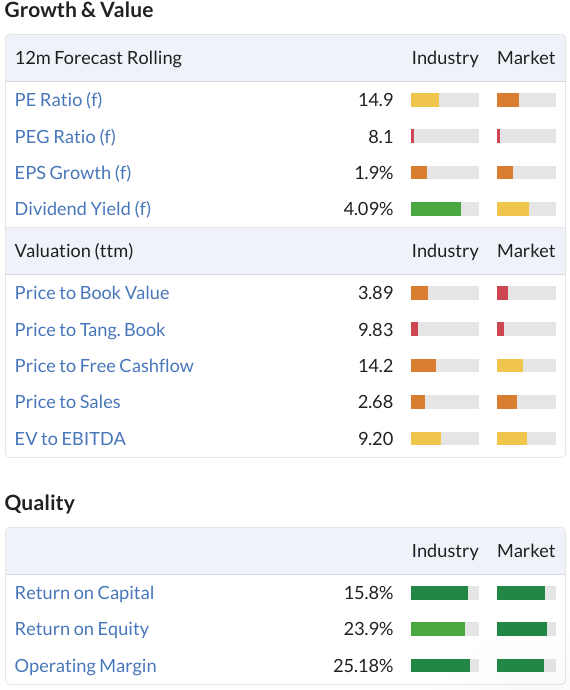
Paul’s opinion - I remain of the view that BOWL is a high quality business (see the scores below) at a reasonable price. So I remain GREEN. There’s a decent dividend yield of 4.1%. BOWL is self-funding new sites and acquisitions, so there could be a fairly reliable c.10% pa earnings growth to expect in future.
Shares have had a good run, and some might argue it’s now up with events. So I wouldn’t expect a major upward re-rating (unless someone bids for it, as happened with its smaller competitor Ten Entertainment).
I’ll moderate from GREEN to AMBER/GREEN, given the decent upward share price move at BOWL, and the only modest H1 LFL revenue growth.
Tclarke (LON:CTO)
Up 29% to 161p (£85m) - Recommended Cash Takeover - Paul - PINK (takeover bid)
Price: 160p cash + 4.525p final dividend.
Premium: 28% higher than last night’s close - a fairly standard c.30% takeover premium.
Buyer: is called Wider Regent Group -
The Wider Regent Group, which was established in 1995, is a leading supplier of gas and metering services to industrial and commercial customers in the UK. The Wider Regent Group provides services to large consumers of gas across a range of sectors including, leisure, care homes, manufacturing, food production and retail.
Paul’s opinion - this is a good outcome I think. I’ve followed CTO for many years, and even went on a site visit to one of its large clients which was fitting out a complex office building in London. It installs complex electrical and computer infrastructure into offices and other large buildings, operating on tiny operating margin of about 2%. It has to maintain skilled staff in downturns. It’s just not a very good business, and too small to be listed. That said, performance anticipated for 2024 and 2025 looks quite good, and the PER is very low. But it’s low for a reason - this type of business is only ever one bad contract away from disaster. I don’t think its divis are reliable either.
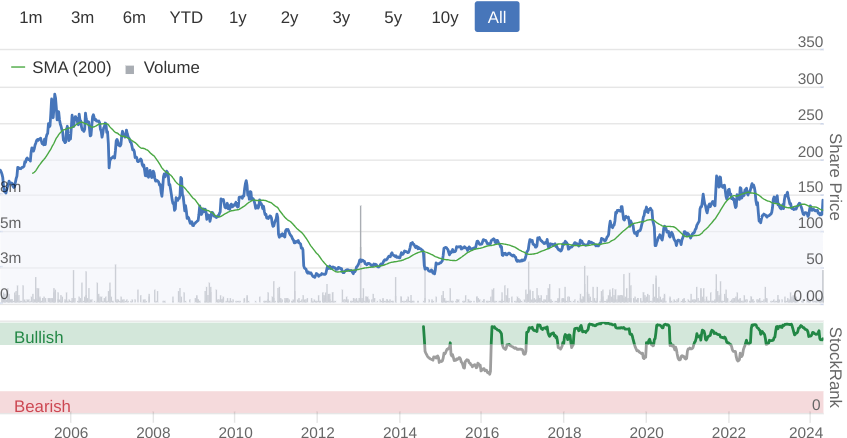
Shares have a weak 20-year track record -
Holders of the shares should be pleased with this outcome I think.
I’ve just noticed that Regent Gas is already the largest shareholder, with 21.5%.
The rest of the shareholder base looks very fragmented, and we’re seeing institutions actively encouraging small caps to put themselves up for sale, in order to create a liquidity event allowing them to exit.
Therefore I imagine this is a done deal. Possible upside? If someone else comes along with a higher counter-bid, as happened with Spirent Communications (LON:SPT) recently.
I wonder if the new owners will be quite so happy to give CTO Directors the wildly excessive remuneration that they've enjoyed in recent years?!
Porvair (LON:PRV)
Down 1% to 647p (£298m) - AGM Trading Update - Paul - GREEN
This is another share that’s on my top 20 share ideas for 2024. I’ve been really impressed with its strong long-term track record of self-funded growth, it’s a quality business at a fair price I think.
Shares are surprisingly illiquid for a c.£300m market cap company, due I think to it being tightly held by lots of long-term shareholders.
The current financial year is FY 11/2024.
I reviewed its last FY 11/2023 results here in Feb 2024.
Today’s update looks price neutral to me -
At the time of the results statement in early February the Board noted its optimism for 2024 and beyond, and this has not changed.
Opportunities afforded by recent acquisitions; strong order books in aerospace and petrochemical; and new product introductions at Seal Analytical are all developing as planned.
De-stocking in laboratory markets is easing and lead times are returning to more normal levels. Industrial consumable order patterns, while still weaker than the prior year, are now also steadier, with several large orders, including one for gasification spares, due to ship at the end of the year and into 2025.
As outlined in February, the Board expects a quieter first half of 2024 to be followed by a stronger second half, in line with market expectations.
CEO retirement - the highly regarded CEO is winding down after a remarkable 28 years on the Board! He certainly deserves more than an Elizabeth Duke carriage clock for his part in making this share a 10-bagger from the 2009 lows. I remember attending a presentation he gave to investors about 10 years ago, and can still recall how brisk & efficient he sounded, rattling off all the detail - exactly what I look for in a CEO, a hands-on entrepreneur.
Mind you checking the 2023 Annual Report, he can afford to buy his own carriage clocks after £1.3m total remuneration in 2023, and almost £1.0m in 2022. That’s about 5% of operating profit paid to the CEO, which is strikingly high, as we often find with small caps. Whilst the FTSE 100 Directors are accused of greed, their pay as a percentage of group profits is tiny compared with many small caps, including Porvair.
Paul’s opinion - I remain positive on Porvair shares. It’s not amazingly cheap, but bear in mind that the forecasts tend to drift upwards with Porvair. So the PER should turn out to be lower than it initially looks. There’s a nice mix of different sectors too, which tends to be a good shock absorber if any particular industries suffer an unexpected downturn.
I enjoyed this interview with fund manager Josh Northrop, who gave a good summary of why he likes Porvair, worth a listen as some of his other stock ideas were really interesting too.
PRV shares could attract a takeover bid I reckon. Nice high StockRank too is the icing on the cake.
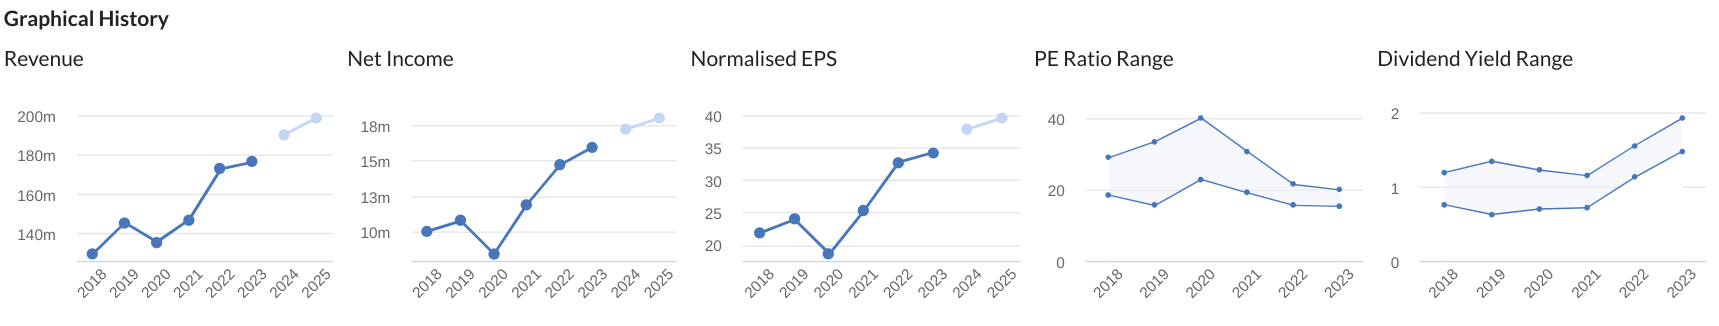
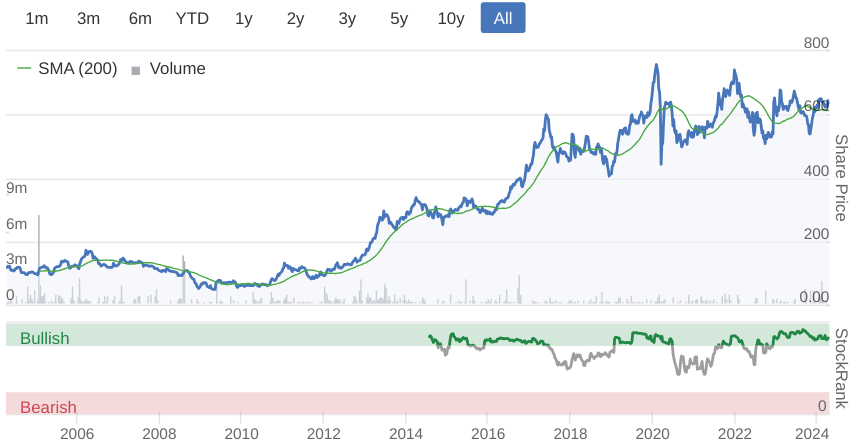
Impressive -
Sosandar (LON:SOS)
Down 11% to 12.25p (£30m) - FY Trading Update - Paul - AMBER
The ladieswear fashion brand, which originally was pure eCommerce, but has since broadened its strategy to include more wholesaling, and trial physical stores. It is also trying to move away from price discounting, towards more full price sales. So I’m expecting moderate revenue growth (if any), but improved margins.
FY 3/2024 update today -
Strong H2 with FY24 revenue growth of 9%, continued margin growth and strong cash position to execute store strategy
Revenue of £46.3m for FY 3/2024, and it’s trading around breakeven - not great, but things haven’t got any worse after the profit warning last year -
As a result of a substantial positive swing in PBT from H1 (£1.3m loss) to an expected profit of £1.1m in H2, FY24 will be broadly in line with market expectations* with a marginal loss of £0.2m expected to be reported for the year overall
* Sosandar believes that market expectations for the year ended 31 March 2024 are currently revenue of £46.8 million and PBT of £0.1 million.
H2 is the busier seasonal half, so I’m not reading too much into the above sequential half year improvement.
Net cash is very good at £8.3m, more than a quarter of the market cap, and bear in mind it’s not burning cash operationally any more. Although some of the cash is likely to be spent on opening physical stores.
Current trading - this sounds encouraging -
Post year-end, April trading has been strong with continued improvement in profitability driven in particular by gross margin
International expansion - seems to be going OK, but not madly exciting at this stage (my interpretation of the RNS!)
Physical stores - this will be very interesting, as the first physical store openings are imminent. Obviously they should trade well when new, so expect some gushing RNSs about how incredible and amazing the new store openings have been, in the coming months. That could be a catalyst for boosting the share price. However, what matters is the level of consistent trading the stores produce after they've been open for a while, which is usually lower after the honeymoon period ends.
Paul’s opinion - I think the market cap of £30m looks about right at this stage. Overall I think I’m warming to the new multi-channel strategy. Store openings are likely to consume a fair bit of the cash pile. I rate management here very highly. What they’ve achieved so far is almost impossible - creating a new brand from scratch, in an incredibly competitive sector. Yes it took lots of fundraisings to get there, but they managed it. Unfortunately, things have now stalled in terms of profitability at around breakeven, and the exponential growth story has really gone out of the window. So upside now looks a lot more pedestrian than it was. Even if the stores work, I’m struggling to see this business really scaling up, or making much profit anyway. So maybe c.£30m market cap is a fair valuation at this stage? I’ll go with AMBER, but will watch with interest to see how things develop.
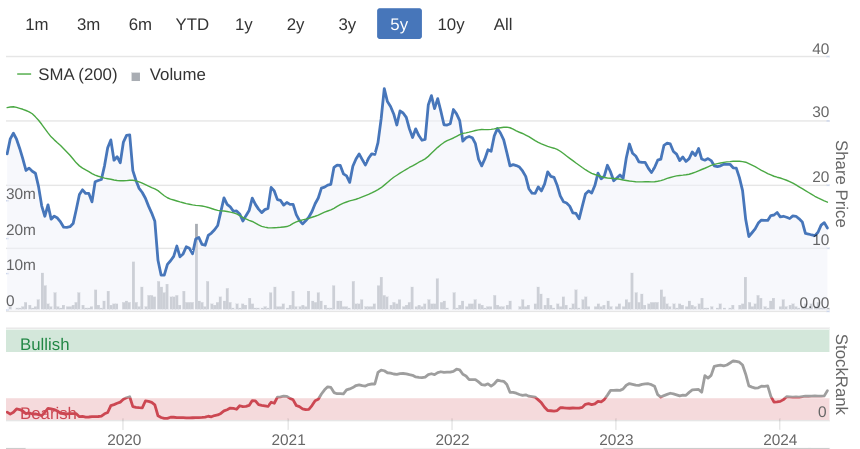
If I'd said to you 5 years ago that Sosandar would out-last Top Shop and (probably) SuperDry, you'd have called me a maniac.
Note that the share count has more than doubled over this 5-year period -
Graham’s Section:
Tatton Asset Management (LON:TAM)
Up 5% to 585p (£354m) - Trading update - Graham - GREEN
This asset manager has slipped my attention for too long, so let’s have a catch up today.
Roland covered its final results last June.
Please note that it’s not a fund manager making direct investments. Instead it provides managed portfolio services, investing in a range of active and passive funds.
Today we have a full-year update for the latest financial year, i.e. FY March 2024. Results will be in line with expectations.
The headlines are very impressive:
Record net inflows of £2.3 billion (18% of starting Aum)
Assets under management (including “assets under influence”) up 27% to £17.6 billion
The company had a three-year plan to reach £15 billion AuM by March 2024, a goal they have exceeded (partly because of acquisitions, although they would have exceeded the target even without the acquisitions made).
Mortgages - Tatton has a compliance consultancy business, Paradigm and a mortgage club, Paradigm Mortgages. They participated in £13.1 billion of mortgages in FY 2024, down 10% year-on-year. The broader mortgage market was down 29%, so this implies that they grew market share!
CEO comment excerpts:
As a management team, we are excited about the future market opportunity and the continued growth and adoption of MPS [GN note: Managed portfolio services] as a core investment proposition by the IFA community. We look forward to announcing our new medium-term AUM/AUI target when we release the full year results in June…
Tatton was “recognised in a recent Defaqto DFM survey as the preferred and most recommended DFM MPS provider” (i.e. discretionary fund management managed portfolio services).
Incidentally, Paul Hogarth is the founder, CEO and largest shareholder of Tatton - a combination I like to find in potential investments!
Estimates: Paul Bryant at Equity Development has raised his forecasts today and suggests that FY March 2025 could see AuM of £18.7bn (prev: £17.1bn), revenues of £42m (prev: £39.8m) and PBT of £18.3m (prev: £17.7m).
Graham’s view
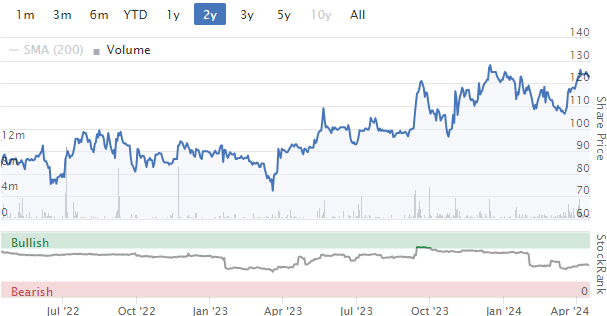
I’ve clearly not paid this one enough attention, as the share price has performed very nicely over the last couple of years:
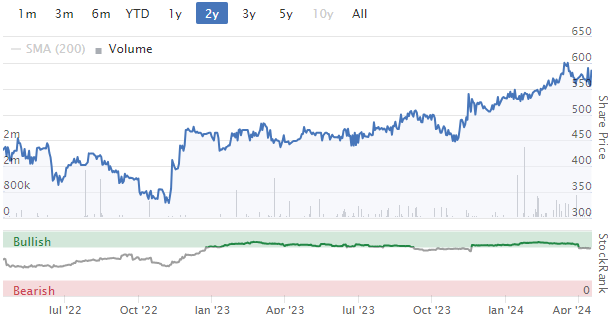
This puts it on a high earnings multiple and a modest dividend yield:
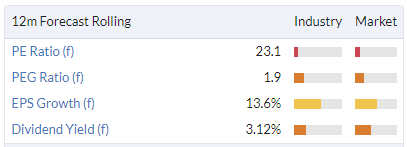
How could we justify paying this sort of multiple for Tatton?
Some reasons I could agree with:
It’s still led by its founder, who is very well aligned with other shareholders.
Very impressive AuM growth in difficult market conditions, suggesting that there are structural growth drivers (as argued by Equity Development).
Excellent quality metrics (see the StockReport).
If the survey mentioned in today’s update is to be believed, Tatton has the highest-rated MPS service in the market.
I am still tempted to retreat from Roland’s “GREEN” stance (when the share price was 460p). Over 100p higher today, it would be natural to switch to “AMBER”. But I’ll let this winner run a little longer.
At 650p, the stock would be trading at 25x forecast adj. EPS. I think I’d feel obliged to take a neutral stance there.
Equals (LON:EQLS)
Up 0.5% to 123.6p (£232m) - Final Results - Graham - AMBER
Equals (AIM:EQLS), the fast-growing payments group focused on the SME marketplace, announces its final results for the year ended 31 December 2023 (the 'year' or 'FY-2023') and an update on trading for the period from 1 January 2024 to 12 April 2024.
This in the midst of a long-running saga around whether or not it will get acquired. See Paul’s coverage in February and in March.
Today’s numbers (for FY December 2023) are terrific:
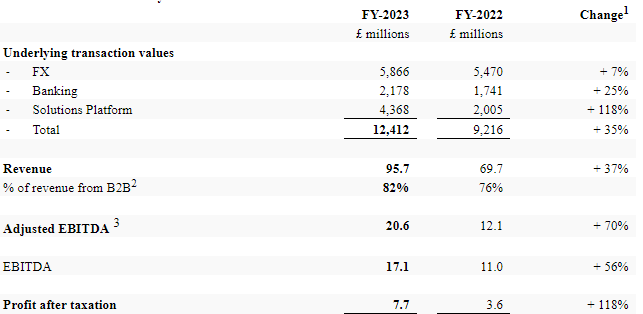
With numbers this good, surely the company could have a bright future if it retained its independence?
The company paid a maiden dividend in December (0.5p, value £0.9m) and has proposed a final dividend of 1p.
It finished the year with £18.7m cash.
Since we are already four months into 2024, let’s focus on the H1 trading update (up to 12th April 2024):
Revenue year-to-date £31.9 million, up 30%.
Revenues per working day £443k, up 27% vs. Q1-2023, up 5% vs. Q4-2023.
Cash of £21.6 million.
With such great momentum, again I have to wonder why the company was so interested to put itself up for sale? I suppose with bid interest coming through in recent months, there is the potential for a premium offer - but it’s still quite unusual for management to publicly go looking for that offer, when their standalone strategy appears to be working.
CEO comment:
We continued to grow strongly in 2023, achieving record levels of revenue, Adjusted EBITDA, and operational cash generation. This allowed us to continue to invest in the business and declare a maiden dividend. We also expanded internationally, broadened our product offering and hired greater talent to take the Group forward….
It’s easy to get confused when there are so many forex/payments companies to study. So let’s again turn to the CEO for a reminder of what makes Equals different (emphasis added):
The vision for the Group continues to be the simplification of global money movement for business customers. Equals achieves this through its B2B platforms, Equals Money being targeted at SME customers and Equals Solutions which targets larger corporate opportunities. The Group's growth potential is particularly strong given that the core building blocks of its platforms, namely own-name multi-currency IBANs and bank-grade connectivity and clearance, are highly complex and time consuming to replicate. This 'first mover' advantage was achieved by the investments made in previous years and will be continuously enhanced by the developments planned in the Group's technical roadmap combined with further investments into direct connectivity to payment networks.
Graham’s view
It’s easy to overlook the underlying business here, given the ongoing takeover situation. It makes it tricky to know what’s driving the share price: underlying business progress or deal speculation?
The next PUSU (put-up-or-shut-up!) deadline is tomorrow. So we will have to get an update then regarding whether or not a takeover is going ahead.
Personally, I agree with Paul that when talks drag on for a long time, the likelihood of a deal happening tends to diminish. But named parties are said to be interested in a takeover, and talks are ongoing, so who knows?
Estimates: the most recent Canaccord equity research note I can get my hands on (Sep 2023) upgraded forecasts and suggested that the current financial year, FY Dec 2024, would see revenues of £112m and adj. PBT of £23m.
For a fast-growing business, with net cash, the current £232m market cap doesn’t seem particularly demanding.
Quantitatively, therefore, it appears cheap vs. adjusted numbers.
Qualitatively, I still struggle to understand the USP of Equals’ products (this is my own fault, not the company’s). I’m also perplexed by the proactive search for a bidder when the company’s standalone strategy appears to be working.
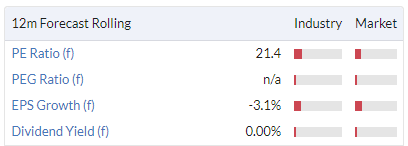
Therefore I’ll keep my AMBER view on this one for now. Using unadjusted numbers, the StockReport would agree with my cautious stance:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

149 comments
Many thanks abtan and timarr. Fantastic stuff and much appreciated.
Wise (LON:WISE)
To add some further thoughts to Timarr's vastly superior payment's knowledge and general commentary:
Note that Remitly do not offer business accounts - I'm not sure why they haven't moved into this lucrative space.
I only noticed because I did the maths on my transactions statement and couldn't work out why FX rates kept varying so much.
It turns out that I was using the card in Australia outside of business hours (and it was unclear on whether that was UK or Australian business hours - the company never confirmed when I asked.)
I searched extensively, but found nothing on their website indicating that there would be extra fees for using the Revolut card at specific times of the week.
I completely acknowledge that most people aren't as strange as me to want to delve into the details of their financial statements for tiny transactions, but I do question the long-term appeal of a company that isn't completely open about how much it charges its customers.
Contrast this with Wise and their relatively transparent approach to fees.
Of course, this was a few years ago and things may have improved.
Note that this is what the company is striving for, it's not there yet as, for example, it can't offer interest on Business Account cash balances, only cashback.
So putting the above into numbers using the latest figures:
- Latest Gross Interest was c4.2%,
- 1.0% is used for product development by Wise.
- 2.6% (80% * 3.2%) is given back to customers as either interest or cashback.
- 0.6% (20%* 3.2%) is taken as profit.
I like this. It seems fair.
And if interest rates fall I would hope that, whilst profits will be affected, it won't be as bad as many might expect, especially as customer cash balances continue to grow.
Let's say that I've made a mistake somewhere and it's actually closer to £400m.
The current market cap is £8.2b
This does not seem overly expensive for a growing company.
I look forward to seeing some director buys in the near future
Weighed down by debt, can Saga keep bailing out its sinking ship?
The Insurance and cruises company is facing some challenging times
Below is a very bearish article in The Times today on Saga
“Patrick Hosking. Financial Editor
Thursday 18th April
Like its customers, Saga is getting on a bit. The “over-50s superbrand”, as it likes to call itself, turns 73 this year. Super or not, on the basis of its results on Wednesday, it is by no means certain the company will make it beyond 75, let alone into its eighties or nineties.
It’s beginning to feel like a never-ending voyage of pain for the insurance and cruises group. There’s always some fresh squall to be navigated, though its successive captains invariably come up with a different wheeze to try to keep things afloat a bit longer.
The latest setback is in the core insurance broking division, where customer numbers are falling and margins are shrinking. Saga is now warning of a short-term impact to profits as it moves to price its household and car insurance premiums more competitively.
The new helmsman Mike Hazell, is, meanwhile, putting his hope in a “capital-light” strategy in which larger, richer insurers and cruise companies will be persuaded to shoulder the heavy lifting through so far unexplained “partnership deals.”
Analysts reckon Hazell is considering anything from licensing arrangements to sale-and-leaseback deals, some of them drastic balance sheet changes that could release large chunks of capital and so drive down debt, which at £637 million threatens to capsize the entire enterprise.
On the face of it, plenty of cash could be released: the cruise ships are in the books at £586 million while even after two writedowns in the space of a year, the broking side might be still be worth a few hundred million.
But the more Saga outsources its productive assets, whether ships or call centres, the more it becomes nothing but a brand name, a kind of Virgin for silver surfers. While there’s no doubt that cruise customers and package holidaymakers like the brand and the offering, that affection doesn’t extend to insurance. And every bit of outsourcing reduces the control Saga can impose on quality.
For those lamenting the declining interest in direct investment in the UK stock market by the public, the Saga saga might explain things a bit. The flotation in 2014 was fantastically successful in winning new shareholders, yet catastrophically bad at delivering them a return.
More than 700,000 people registered an interest in buying the shares and 200,000 paid out hard cash. That makes it by far the most popular UK initial public offering of the past ten years.
But the share price, after adjusting for restructurings, has since collapsed by 96 per cent. A £2 billion liner at float has shrunk to the size of a dinghy, with a market value of just £150 million. Dividends, which were the main attraction were ditched in 2020 and have never come back.
What has gone wrong? First, too much debt. The private equity groups Charterhouse, CVC and Permira floated the company with £700 million of borrowings at the time of the IPO. That reduced its room for manoeuvre and ability to invest in its core businesses.
• Saga seeks support as it sheds inherited private equity debt
Rising interest rates have now intensified the struggle. Saga will have the firepower to repay a maturing £150 million bond with a coupon of 3.375 per cent next month, but only by partly replacing it with an £85 million personal loan from chairman Sir Roger de Haan, who is charging interest of 10 per cent, almost three times as much, and yesterday agreed to extend the facility by another four months.
The crunch year now will be 2026, when Saga is required to pay back Sir Roger and find another £250 million to repay an unsecured bond.
Second, there’s been a near delusional hope in being able to diversify and extend the brand. Ten years ago, the sellers were suggesting that it was so potent that it could be successfully slapped on everything from nursing homes and domiciliary care businesses to investment products and retirement villages.
Even then, that looked optimistic. The company by that time had already had to unwind Saga-badged forays into energy supply and radio broadcasting. By 2019, an exasperated Patrick O’Sullivan, then chairman, admitted the former private equity owners had “over-egged the potential of the business”.
Even today, the management continue to imbue the brand with far more appeal than seems justified by reality. The plan today is to “explore ways to deepen the relationship” with the 7.2 million over-50s it has on its database. Yes, but how exactly? A previously trumpeted campaign to bind customers in with “members only” events has quietly been dropped.
Third, there have been a number of management mis-steps over the years. The decision to shift to three-year insurance policies was innovative at the time but proved disastrously mispriced as the cost of meeting claims rocketed, leaving Saga trapped in uneconomic contracts.
The company also looks to have been badly wrongfooted by the gilts market crisis in September 2022, with the staff pension scheme scrambling to raise cash to meet margin calls. The result is a widening of the deficit from £12 million to £48 million, though Hazell plays this down as an accounting anomaly only.
Saga has not had the greatest luck. Covid left its cruise ships empty for a while. It’s not the only general insurer to have been hit by claims inflation.
It is now uncomfortably reliant on 26 per cent shareholder De Haan, who was two years old when his father, Sidney, founded the business in 1951 as a way of filling empty hotels in Folkestone in the quiet season. Doubtless there’s an emotional pull to keep the business going, but he can’t be relied upon to keep bailing it out.
Retail investors who subscribed for the minimum investment of £1,000 ten years ago hardly have to worry any more. Their stakes are worth just £40 today making it barely worth the bother and cost of selling. And there is still hope of a bounce — given the way the cruises are selling so well.
As Jeremy Hunt prepares to sell NatWest shares to retail punters in a “Tell Sid” type marketing campaign designed to promote the benefits of direct share ownership, Saga is a timely reminder that not all Sids prosper.”
Has anyone looked at Wise (LON:WISE) figures?
"full-year revenue of GBP1.05 billion came in 1% below consensus."
The 10% fall looks very harsh, for a 1% miss. OK the shares have had a good run, looks like the market was expecting something better.
Wise (LON:WISE)
I'm a big fan of the company, as both a user and shareholder, and was happy with yesterday's update.
I'm not sure why the share price fell - perhaps the decrease in volume/customer again? - though to be honest I wasn't too bothered by this as there were so many other positives and I like the long term story.
---
One metric that I think is often overlooked is the amount of customer funds held in Wise accounts; c£13.3b, which was up 25% vs last year (£10.7b).
This is a clear indication of the increased use of the Wise ecosystem by its users - primarily Wise card spending - which is becoming an increasingly more important driver of revenue growth (Wise gets paid whenever an individual uses a Wise card.)
Indeed revenues excluding FX transfers and Interest Income made up 19% of revenues vs c. 5% in 2019 - that's quite an increase.
---
Net Interest income was up, despite an increasing proportion of Gross Income being given back to customers (26% vs 16% last year).
I like this focus on not being greedy with this revenue stream.
It avoids upsetting customers (important for keeping them using Wise's products), whilst also limiting the ramifications of the actions of central banks, obviously something that Wise has no control over.
---
Active Customer year-on-year growth was maintained at c30% - good to see.
---
Stocko is showing a market cap of c£12b, but that looks wrong (perhaps they are using the B shares in their share count figure, which I don't think is correct).
Google and the LSE are showing a market cap of c£8.5b and if the self-funded growth and positive cashflows continue then I would hope for a valuation significantly higher than this.
What could go wrong? Probably a lot! It's a competitive space with many players.
I always thought one of Wise's biggest attractions vs competitors was its highly profitable Business offering, but this seemed to have been slowing recently.
Hopefully this is about to change with the resumption of onboarding Business customers in Europe.
Business customers are far more profitable than individual ones, so fingers crossed there will be some material upside from this in due course.
---
I'd certainly be interested in hearing from other shareholder/users on their experience with Wise or their competitors.
Thanks
A
Hi Abtan, thanks for your very comprehensive reply.
I have held Wise (LON:WISE) for a while buying in too early.
I have used them to transfer money abroad, they seem the best option, I know many expats use them.
I don't have a card yet, I was put off by the fees, if withdraw over £200 pm, that is no good if have to pay local ATM fees as well. I use Chase Debit, which is free for foreign transactions or Barclays Rewards credit card, also no fees. Chase do give 1% back on certain transactions and also pay interest on any cash and 5.1% in their savings account, you can switch funds in seconds.
I may get a Wise card as seems more secure, you can lock when not using it.
Both my cards had to be stopped in 2022 after one trip abroad.
I did top up today as price went down to nearly 800p.
I think I'm struggling to see the competitive moat, from a consumer proposition perspective (both individuals and business) that Wise (LON:WISE) offers.
I am a customer myself, having a multi-currency account.
In the past, they had a moat, which was (1) better international transfers, and (2) when they launched their multi-currency accounts this was fairly unique.
However, there are several players now doing (1) and (2) competitively as well.
They do have a "moat" of their existing customer base. Banking is very sticky, of course. But I wonder how many of Wise customers use Wise as their primary financial institution? So stickiness is not as great as say, Lloyds/HSBC/Barclays/Santander/Natwest etc.
And their growth rate is still pretty decent. Especially in international markets as they roll out their currency accounts.
As they become bigger - will they not transition from being a "challenger, tech based" to "one of the incumbents" and attract similar low PE valuations?
I haven't researched enough about Wise to have a good view on their strategy and future growth drivers; but that's where I'd start looking, to see if it supports their current valuation, and be comfortable that there's enough double-digit growth years ahead for the valuation to make sense currently.
You've done well over the past year with Wise! Share price more than 50% up YoY.
I think I'm struggling to see the competitive moat, from a consumer proposition perspective (both individuals and business) that Wise (LON:WISE) offers.
Hi Boon
Their moat is in regulatory compliance (especially around AML), deep technical integration with the international payments ecosystem and increasing liquidity across major currency corridors. With 95% of the global retail cross-border market to go for, most of it transacted at fees ten times higher than what they offer and with a scalable infrastructure that can add transactions at minimal cost it's not hard to see where future growth come from.
With fees as low as they can offer undercutting them will be an expensive business - competitors can offer lower rates over major currency corridors for a while, but the margin will be tiny, if it exists at all. If I can transfer money instantly and reliably to Dubai at about 0.5% am I going to move for a tiny percentage improvement?
Possibly, going forward, they will need to increase marketing costs to build the user base - but most people, once they start using Wise, never look to go anywhere else so the user base is incredibly sticky. My colleagues - who are all payment nerds - won't use anything else, the range of functionality is ridiculous.
I try very, very hard to find the downside of all of my investments but I struggle with Wise. Cross-border payments are very, very hard: Wise do a fantastic job. Doesn't mean they're a good investment at this price, of course, that's for the individual to decide.
timarr
P.S. Wise target retail (consumers and SMEs) at the moment. Wholesale (i.e. businesses) is a market ten times the size. At some point, when they gain sufficient liquidity, that comes into play.
Wise (LON:WISE) Having regretted failing to take advantage of a very good share price 1-2 years ago, I thought to pounce upon the recent 20% drop. However, looking at the fundamentals I was surprised to see that neither earnings nor cash flow are expected to make particularly good progress in the next two years, FY25 and FY26, despite continued double digit revenue growth. I’m very happy to pay up for quality, and a 20+ x multiple of earnings is a reassurance rather than a deterrence. But in return I expect to see double figure earnings growth well into the future.
What am I missing? And do you see falling interest rates as a risk to profits artificially boosted by current rates?
Hi BnB
Well the comparisons are tough, and Wise's focus is on building the customer base. But from their Annual Report:
"Over the medium term, we continue to expect income growth of more than 20% (CAGR) and an adjusted EBITDA margin at or above 20%, and per the explanation above, the higher the interest rates, the higher our adjusted EBITDA margin is likely to be."
To be honest I don't take much notice of the teenage scribblers who constitute the analyst community. In any case, given the scale of the opportunity, I would far rather Wise spend the next few years continuing to invest to build the customer base and the network rather than worrying about profits.
But I was buying the stock at under £4 a couple of years ago, so I can afford to be sanguine.timarr
Thanks timarr. Those medium term targets imply considerable acceleration of growth from the mid-teens level forecast for the next couple of years but a significant diminution of the operating margin. If you don’t mind me asking, to what would you attribute the falling margins?
Hi BnB
I can only offer complete speculation I'm afraid. But three things come to mind:
There could be other things at play as well. Significant increases in marketing costs as it becomes harder to add customers, maybe? Also there will be competition along major currency corridors so they may need to run those as loss-leaders, which would certainly have an impact on margins - although they need to be careful not to attract too much attention from competition authorities.
All speculation I'm afraid. I'm extremely sceptical about my ability to predict the future with any exactitude (and I have a lot of evidence to support that contention) but my general view here is that cross-border payments are really hard and not well served, and most of the initiatves to deal with this are floundering due to the complexity. Meanwhile Wise are growing their market share while keeping their customers happy and are streets ahead of the competition in terms of coverage and functionality.
It's the sort of virtuous circle that leads to good things happening and I'm happy to be inside it. Something interesting will happen here, and with Käärmann holding 19% of the stock it's unlikely to be detrimental for other shareholders.
timarr
Thanks for your thoughts on this, timarr! Given me some food for thought.
On down days it’s worth noting which stocks have support. Either nobody selling or savvy buyers picking up cheap shares. Renold (LON:RNO) TP Icap (LON:TCAP) Macfarlane (LON:MACF) Avon Protection (LON:AVON) All on my radar to add or start a position. Jupiter Fund Management (LON:JUP) on my list to maybe cut. It looks unloved. TI Fluid Systems (LON:TIFS) also falling despite apparent good value. How long do you wait?
It is quite frustrating, the ones I want to top up or buy, don't fall back or very little. Then if I buy they will fall. Although a couple today did fall, Ashtead Technology Holdings (LON:AT.) and Porvair (LON:PRV) So I dud pick those up. Had sold out of Ashtead Technology Holdings (LON:AT.)
I hold or looking to buy all on your list. I have also Cohort (LON:CHRT) and Yu (LON:YU.) sold out of those, looking to buy back on a dip.
The high momentum shares are looking a bit peaky at the moment.
Re TI Fluid Systems (LON:TIFS) why did the directors not buy in the secondary placement? That rather puts me off. One director got a load of free shares today, another negative. So gone off it.
Re TI Fluid Systems (LON:TIFS) I saw Cockney Rebel say much the same on VOX markets. Starting to agree.
Dr Martens (LON:DOCS) Don’t hold but considering a position as it was over priced but so was Moonpig (LON:MOON) and there's been a decent rebound trade there .There could be value at some point.Brief synopsis of Dr Marten’s earnings call for any interested.Not too much of the financials here though.More strategy.Televised.Both CEO and CFO dressed all in black.No Saville Row suits here.
Sandals now make up circa 10% of sales.New head of design from Birkenstock Holding (NYQ:BIRK)
3 out of 4 boots the classic black boots.
Overall US boot market down obviously is the major current problem and not just for Dr Martens (LON:DOCS) .Refuse to discount most popular black pairs even for Black Friday but discounted some of the jazzier designs.Trying to maintain the premium feel of the brand like premium fashion brands with the consumer psychology that higher prices for premium products mean the product is more desired and connected to the actual worth of the product.Most of the financial problems coming from the US. obviouslyThe price point is pretty pricey and the customer is definitely not a Hermes International SCA (EPA:RMS) kind I’m imagining.Perhaps priced out for now in current US economic environment?
Collaborations with high fashion designers and premium brands important and all sold well, including Marc Jacobs the fashion designer and Supreme, high end/considered pretty cool (popular) like Northface once (still?), (skateboard brand bought by VF (NYQ:VFC) for a very pricey multiple a while back).Very important for brand image as if Doc Marten’s could really get in with the fashion crowd and with the network effect of online social media like Birkenstock’s did……. The brand could really take off and the price premium of a pair would really be justified imo.And not only increasing sales but could get a higher p/e rating.Worth a punt or not?!?Definitely not a tired brand like Superdry (LON:SDRY) though.
P.S. They also mentioned using influencers for their new product, 14xx! Good or bad or nothing?No idea!I know Abercrombie and Fitch had good success in the turnaround of their brand using influencers as part of their turnaround of their brand.I guess it depends which ones you use, how you pay them (free boots\food, fancy party maybe?) and on their individuals followers and analytics about them.DTC for them seems to be going well though.The company definitely needs to get the market strategy right in the US anyway.Get some boots on Kim Kardashian (or is she still cool enough?)!
The change of CEO at Porvair (Porvair (LON:PRV)) is a potential concern. After 26 years as CEO it should come as no surprise that Ben Stocks, 62, wants to retire. As Paul highlighted, Stocks has been an excellent CEO, and this has been reflected in Porvair’s long track record of self-funded double digit earnings growth and high Stockopedia rating.
However, the announcement of Stocks’ planned retirement comes only a fortnight after the abrupt resignation of Sarah Vawda, a non-exec director, who joined the Porvair board less than a year ago. It appears that Vawda, who comes from a big company background, did not see eye to eye with the rest of the Porvair board when it comes to the group’s long-term strategy.
Whilst there is no connection between Vawda’s resignation and Stocks’ impending retirement, which will not take place until a replacement is in place in early 2025, both suggest that Porvair’s long-term future as an independent company might be a little less certain than it was before Stocks announced his retirement.
Porvair two biggest shareholders probably hold the key. Giorgio Girondi, an Italian entrepreneur who heads UFI Filter Group, has been a long time shareholder with a 16.67% stake, whilst Long Path Partners, a US hedge fund, has recently emerged with a 8.42% stake in Porvair.
UFI is roughly twice the size of Porvair but has never shown any interest in acquiring the company. Long Path, by contrast, appears to be a more activist investor.
Uncertainty over the long-term intentions of Porvair’s two biggest shareholders could make the task of finding a replacement for Ben Stocks harder than it looks.
Blood in the streets
Bit of blood in the streets today so looks good time to double down on a few holdings was building into .
I was happy to buy a week ago some of these at 7% lower today I was questioning why I wasn’t adding when no fundamentals have changed .
Had a good word with myself and small top ups on 4 holdings all 5-7% cheaper than a week ago .
Both bowl fund and blame game fund positions .
James Taylor of M&G Investments talked about Alphawave IP (LON:AWE) , Tatton Asset Management (LON:TAM) & Team17 (LON:TM17) here.
&t=421sThis is an impressive set of numbers. I would be happy for the Company to remain private especially as the H1 forecasts for 2024 show the continued progress. Like Graham I am also concerned as to why they are actively searching for a bidder. Could it be a lack of finance to get to the next stage!
Hi CBi - just a kind reminder to mention the name of the company at the start of your message - cheers!
I went back several months and collected all (hopefully) the "Green" only shares which Paul and Graham had identified so that I could put them in a folio. Up to date until today at 1.00pm. NB some may have/ will change, so always re-check. For anybody interested here is the list:BAG, ASHM, ATG, BMY, CBOX, CARD, CAV, CER, CBG, CMCX, CHRT, DUKE, EYE, ESP, EQLS, FUTR, GMR, GHH, BOOT, HSW, HVO, IPX, IGP, IPF, JHD, JIM, JET2, JNEO, LUCE, MERC, MAB1, MSI, NICL, PAY, PEEL, POS, POLR, PMI, PRSR, REC, RNO, SUS, SDG, SAG, SNWS, SOM, SPSY, STEM, SUP, TAM, TIFS, TRST, ULTP, VLX, W7L, WATR, XPS, ZTF
Hi Funnymoney,
I collate all the SCVR colour coding every weekend onto this spreadsheet -
https://docs.google.com/spread...
Here's a screenshot -
Alphawave IP (LON:AWE) I hold but it is valued much more on us tech type multiples and exactly hitting at least annual target revenue numbers and providing growthy forecast is a big part of the game.I guess that's why they added 2025 forecasts too (bit far out though... sounds a bit potentially mystic meg/crystal bally and optimisitc even with order backlog commitments).If the market think revenue growth is disappearing naturally the share price will really tank here.
My comments first thing on Alphawave IP (LON:AWE) seemed to invoke lots of incredulity and I admit I haven’t spent any degree of time on this but my point was really this.
The changes in forecasts appear (and I appreciate I may have this wrong) to be related to pulling out of China. The market has been telling them to do exactly that over the last 2 years.
The new expectations should now be based solely on customers the market is happy with - ie creating a greater degree of certainty over financial position and forecasts going forward.
Those new (ex CHina) forecasts are for $100m ebitda and competitors trade on more than 10* EV/EBITDA (more like double from memory).
Anyway - not withstanding that can’t disagree with the comments about CFO getting financial communication in order - it does look a bit Mickey Mouse. They could signal this all a lot lot better. If you leave information gaps/voids then investors will always presume the worst.
Alphawave IP (LON:AWE)
The changes in forecasts appear (and I appreciate I may have this wrong) to be related to pulling out of China. The market has been telling them to do exactly that over the last 2 years.
Disagree are the change in forecasts not simply due to them previously saying sales would be higher than they really are ? we are talking about looking back into last year calendar year now trying to work out what sales were 4 months to 16 months ago - thats ridiculous on any level after their prior issues and new appointment of cfo who i would expected would nip that in the bud. Whatever was going on they shouldnt have been overstating their revenues surely !
Ref the worst - they are telling us now it is worse.
note there is a double whammy here - if i take sales out of 2023 calendar year and add into 2024 calnbedar year all other things being equal 2024 numbers should immediately benefit.
so if they are moving revenue out of 2023 and into 2024 and 2024 is not benefiting compared to prior expectations that is not great !!
this is not a void or a gap this is their inability to add up what exists and has existed for months.
Hi Paul,
Can you look at LON:ATG today please ? It has dropped over 13% today on news.
Thanks
Hi arshadte,
Can you look at LON:ATG today please ? It has dropped over 13% today on news.
I ran out of time today, this was the next share on my list, so I'll cover it tomorrow.
Regards, Paul.
DOCS. Another 2021 flotation that hit the skids. Chart goes from top left to bottom right in a straight line. It certainly leaves a bad taste in the mouth. It has a momentum score of 3, which I take as a colossal warning. Sigh. What a mess.
Despite the UK markets being undervalued, its interesting to note that when the S&P500 goes down (-1.2% last night), the UK market goes down even more (1.5% on the FTSE-All Share today). So, when the US market races ahead the UK doesn't and when the US catches a cold the UK catches a nastier one. This seems to happen time after time.
This is why we need to be careful until the toppy US valuations start reflecting reality, all in my view. Anyone else thinking the same?
As of yesterday the FTSE-All was up +1.35% the past month, whilst the S&P 500 was down -1.7% over the same period..
Yes. Absolutely. TSLA, for example, is feeling the pinch, and going to lay off 10% of its workers. As I said to my mate in America, it's slowly dawning on people that TSLA is a capital-intensive business operating in a big-ticket competitive cyclical sector. TSLA is on a PE of 37, Ford on a PE of 11. The way I figure it, TSLA could lose 2/3rds of it value right now and still not be cheap.
Despite the UK markets being undervalued, its interesting to note that when the S&P500 goes down (-1.2% last night), the UK market goes down even more (1.5% on the FTSE-All Share today). So, when the US market races ahead the UK doesn't and when the US catches a cold the UK catches a nastier one. This seems to happen time after time.
This is why we need to be careful until the toppy US valuations start reflecting reality, all in my view. Anyone else thinking the same?
This just sounds like an argument for owning the US with its vast pools of liquidity and literally hundreds of world-class companies - and dumping the UK, or at least shrinking your holdings. Your horror of US valuation multiples is keeping you out of the best businesses. You've been convinced the US is going to hell in a handcart thanks to the yield curve, yet its economy just keeps on keeping on. And you've missed 25% of equity gains since Oct 23 and 40% since Oct 22. If, as you seem eternally convinced from your regular posts, a fall for the US is due, surely that would be a buying opportunity for US stocks, not for more cheap rubbish over here.
Jamie Dimon is as concerned about the US market outside the magnificent 7 as some commentators are about the UK. Outside the magnificent seven, the US markets are in trouble as well. Furthermore, once you start digging into the guts of the US market, you find that the US markets are suffering the same malaise as we are here in the UK. In 1996, there were 7,300 listed companies on the US markets which has reduced to 4,300 today mirroring what we are seeing in the UK.
It is also worth noting that 80% of the increase in value in US markets over the past five years is due to expansion in the PE ratio, rather than any intrinsic growth in the business.
Having been very US, UK and northern European focused for the past 10 years, I am now looking more to India and SE Asia for the next 10 years. I also follow both GMO and Oaktree quarterly letters and both houses are moving funds out of the US market to the East.
India, Vietnam, and Indonesia all look interesting and on valuation grounds and corporate governance changes, Japan also looks highly investable. For me, China is not investable.
It pays to be humble and flexible in this business.
The stock market is shrinking and Jamie Dimon is worried | CNN Business
Jamie Dimon is as concerned about the US market outside the magnificent 7 as some commentators are about the UK
This is a straw man. I don’t care that the contingent of 7300 US-listed companies has become 4300. I care about the 100 great and durable companies that I own and the other 100 almost equally superb companies that I might replace them with as existing holdings get acquired or rotate out of favour. Meanwhile, India is as rewarding as the US, yes, but every bit as expensive. I agree that Vietnam and Indonesia look interesting but everyone has to avoid spreading too thinly. In addition to the USA, I cover all of Europe and have sizeable holdings in Japan. That’s enough diversification for me. As a result, the US is only just half my fund, significantly less than the global distribution.
How does one man keep track of 100 companies? When I worked in the City, I looked after about 25 companies and was kept busy. Would you not be better buying a smart ETF?
How does one man keep track of 100 companies?
It’s nearly 200. 100 are in the US.
It’s taken a number of years to build the fund. But a good proportion have been in place for a while. I can lean on plenty of analyst research from my bank and other sources. Quality companies with bulletproof balance sheets of the type I mostly own are much easier to understand and more comfortable to live with. I’m not competing for an extra edge in individual company analysis after all. I don’t care about beating any benchmark. I know which companies in which sectors I want to own and I’m buying on a 5-10 year, ideally forever, basis.
I enjoy reading company updates before I jump out of bed because it reproduces for me the thrill of the boardroom. But the market knows better than me, so I only need to investigate when the market takes umbrage at a TU, such as with Ashtead Technology Holdings (LON:AT.) this morning. Then, it took just a few minutes to work out the outlook was broadly in line and the price action simply betrayed disappointment that it wasn’t a raise. Also today, with Porvair (LON:PRV) there was nothing to contemplate other than coming back in 3 months for the next update. Over in the US, Unitedhealth (NYQ:UNH) is up on higher profits and an unchanged outlook when the market expected a cut. I’ll look at it again in 3 months. I doubt I’ll change any holdings tomorrow either. Or the next day.
Would you not be better buying a smart ETF?
Define better. It would not give me the same pleasure and my investment goal is not purely financial - I want to own companies that are shaping or anticipating the future.
Ashtead Technology Holdings (LON:AT.) seems a great example of how to use Stockos StockReport quick squiz. There are some big fish in this space so for me a takeover target, but the Value Red put me off plus flying way above its 200 dma. So a reversion to mean is a good time to put it on the watchlist.
Deep diving into what it's moat is I don't have the time.
If you can show me a smart ETF that mimicks BnB’s portfolio, I’d be happy to know of it. Based on the glimpses of its contents we get offered on here, I think I might buy it. Doubt there is such a thing, it’s clear a lot of time and thought has gone into it.
Haha. You’re too kind. Although holders of the BnB facsimile ETF wouldn’t have enjoyed Friday’s bonfire of the semiconductor stocks. Nvidia down 10% and that’s just one of more than 10 sector holdings, all badly crushed.
In the United States, the term Nifty Fifty was an informal designation for a group of roughly fifty large-cap stocks on the New York Stock Exchange in the 1960s and 1970s that were widely regarded as solid buy and hold growth stocks, or "Blue-chip" stocks. These fifty stocks are credited by historians with propelling the bull market of the early 1970s, while their subsequent crash and underperformance through the early 1980s are an example of what may occur following a period during which many investors ignore fundamental stock valuation metrics, to instead make decisions on popular sentiment.[1] Roughly half of the Nifty Fifty have since recovered and are solid performers, although a few are now defunct or otherwise worthless.
Jamie Dimon (of Greek descent by the way) has been saying for years not to touch Bitcoin!
My comment was in general about the much more efficient US market.
Birth of exchange traded products and their massive success has a lot to do with the fewer listed companies in both countries and across the world.
I agree it pays to be humble and flexible in this business.
All the best
I heard that, like, 30-40% of the US Russell 2000 (kinda like our mid-caps) make losses. That's a shocking percentage.
It is also worth noting that 80% of the increase in value in US markets
over the past five years is due to expansion in the PE ratio, rather
than any intrinsic growth in the business.
When Terry Smith started Fundsmith, the FCFY (free cashflow yield) of his holdings was around 6%. Now it's around 2-3%. Clearly his portfolio has benefited from multiple expansion. It is unlikely that he will be able to replicate his past performance over the next few years.
I'd also like to point readers to one of my favourite charts: the Wilshire Growth vs Value chart: https://www.longtermtrends.net... The chart indicates clearly that growth stocks are extremely stretched relative to value. No-one knows how long this will continue, but investors need to be aware that they are taking a lot of value risk by buying into growth stocks. When the trend reverses, it can reverse quickly. Caveat emptor.
Fundsmith has not performed very well the last 3 years. Smith made some big mistakes with PayPal Holdings (NSQ:PYPL) Adobe (NSQ:ADBE) and Intuit (NSQ:INTU) .
When there is a correction or crash, it will take UK small caps down as well, probably more than US growth, which will probably bounce back fairly quickly. The US market has shorter bear markets than here. I think a correction is due, not finding anything to buy in the US, have been selling. The time to buy is when stocks are down, see Alphabet (NSQ:GOOG) Apple (NSQ:AAPL) Microsoft (NSQ:MSFT) etc.
Yes, I agree, noticed that 30 years ago but there is far more growth in the US than here. Look at some of the high valued stocks such as NVIDIA (NSQ:NVDA) but the PEG is only 0.8 despite the rise in share price. Stockopedia has a VR of 1, I disagree with that. Whilst not cheap, it does compare favourably with stocks with much higher value ratings. Rolls-Royce Holdings (LON:RR.) does not even have a PEG, as profits are forecast to fall next year.
How does the UK compare to the US on PEG? Also most of the big US stocks don't have any debt and have loads of cash.
The US is 3.66% off the top versus 1.2% for the FTSE 100 and 1.7% for the All share. The exact comparison of trading days doesn't always work, particularly when US Banks and data miss followed by a Geopolitical event... creating volatility.
I would like to find some research in to market origins of inflows/outflows regarding age of investors.
I don't believe that American markets are fundamentally better and certainly not on value. Ofcourse they will be better value to the UK if the UK keeps being sold and US being bought. Our pension funds have led the way here which compounds the later.
The amount of UK companies being bought out only strengthens my opinion in our value.
The government privatisations "wheres Sid" etc brought the masses to investing. If the funds have left and the private investors are fewer then here we are.
I believe that the American markets are by far fundamentally better than the UK markets ; their growth, liquidity, spread, shareholding structure, analyst coverage, and quality cannot be compared with any other market in the world.
However, still plenty of opportunities in the UK market as well.
All the best
Sorry I mean companies themselves. As Howard Marks quote "It's not what you buy, it's what you pay. And success in investing doesn't come from buying good things, but from buying things well. And if you don't know the difference, you're in the wrong business."
I don't dissagree with what you say but growth, liquidity, spread and shareholding structure would be so much better if we were valued like the US.
For example ARM on fundamentals is the same company as when listed here but the valuation says otherwise.
But the US market has money flooding in all the time, our markets have the reverse, funds are having to sell shares as investors withdraw. The volumes are much higher in the US than here, companies are much larger. This affects liquidity and spreads. The situation here in small caps has got very difficult, it is hard to trade sometimes , no market.
You could replace US for tulip bulbs on this text. We do have a lot of value in the UK. Most people here would agree i believe otherwise who would be interested in what Paul and Graham say?
Hi Mark
Can you explain this in more detail please.
Which are the companies that you see value and the reasoning behind your assumption?
Thanks
Likewise (LON:LIKE)
Ex team from Headlam (LON:HEAD) owner led who are ripping through wholesale flooring distribution market. Not profitable yet but are capitalising on mistakes being made at Headlam. They have just added 11 new sales reps. Built in plenty of expansion space into present units so will become far more efficient as they go forward. They should be aiming for tunover £150m this time from £4m in 2018.
£22m of £40m assets is in freehold property. Market Cap £41.65
£200M is short term target sales looking at 5% margin. (But i believe much more turnover to come)
I could continue to bore you for hours but take a listen to Tony Brewer himself with Jeremy McKeown and James Wilson of Phonix Asset Management under In The Company of Mavericks episode 25.
Hope that helps Yiannos
See my comment above Yiannos1.
Yes indeed, when the US coughs the UK gets a cold or flu or even the black death.
Also one must remember things are usually cheap for a reason. Wisdom of crowds and all that.
Regards
Michael
Have to say I hard disagree with notion that 'things are cheap for a reason'. For years I thought this way and missed some massive opportunities. Now I just remind myself that with the combination of passive funds, momentum trackers and plain idiots, there's more scope for value than ever before.
I'm in the idiot camp.
Punted Coinbase Global (NSQ:COIN) to rise on the crypto halving event (which I though happened last weekend). Really need to keep off the wine when investing.
System1 (LON:SYS1) strong results again. Their addressable market is huge (predicting the performance of adverts using data analytics/AI); they have prestigious international clients. £30M T/O for the current year. Net cash £9M. The growth of their platform model is key here. Another Warpaint (Warpaint London (LON:W7L) like growth stock in the making? FY25 T/O estimated £34.5 but given the strong Q4 numbers and past history, they'll probably beat that. Sales growth trending around 15%. I hold.
spglet - on System1 (LON:SYS1) - where do you get +15% sales growth trend? Q4 numbers are +30% overall (and +37% if taking just the "core" Platform business).
I would argue that there could be an even further acceleration of growth from the +30% seen in Q4:
Lets say that "Improve Your" revenues could go from £4.9m in FY23 to £9m in FY24 (I think definitely doable). That would, in itself, contribute 13.7pp to overall revenue growth YoY. And that's not include the "Predict Your" growth, which as above I think could continue to grow 15-20%!
I will be running the rule through the numbers in the coming days myself, also added to the article list to-do for Substack, but happy to hold for now. Just a bit peeved that there seems to be inside information leakage... looking at the big rise in SP over the last week....!
(I hold in the Boon Fund)
Hi Boon, I agree the Q4 results indicate the higher levels as you say. I lifted the 15% figure from the Canaccord note that was published today. They say "We increase our FY24E forecasts for the guidance and upgrade FY25E, implying yoy sales growth of 15%, which we believe is achievable given the strong growth run rate."
I think the point here is that whatever the brokers say, System1 (LON:SYS1) seems to beat it at the moment.
I'm loving System1 (LON:SYS1) results too - started a new holding at 8am this morning and was delighted to pay less than a 10% premium on yesterday's price. Price has dropped back since (back to yesterday's price) - but not too worried. Could easily get taken out by a bigger player. Dynamics look very good in my opinion.
Bbc r4 today about 16m30s in.
C4X Discovery Holdings (LON:C4XD) I do not hold.
On uk markets. Cvc going to amsterdam. New report on aim. 76 cos delisted last year. Tanika Fricker : dont worry some went under some went to main market.
C4XD dr dix : my market cap would be 20 to 30 x higher in us so going there. Structural issues in uk aim healthcare no analysts or specialist funds so no market inlfrastructure. Slow demise of sector.
Private markets/ funds doing well.
small scale uk cos still there and still leading edge but they will all go to market in US.
My apologies for the incomplete note but thought it was interesting.
Funnily enough C4X Discovery Holdings (LON:C4XD) is up 20% today.
I did notice a while ago C4XD do have a drug for inflammatory bowel disease in their pipeline that they want to develop themselves that has a comparative Nasdaq company called Morphic Holding (NMQ:MORF) currently valued over there at $1.47 billion.And their pipeline is 1 similar class drug, α4β7 integrin inhibitor, in phase 2 trials.I was kinda guessing whether they are waiting for the right time to try list on the Nasdaq, as apart from a brief Spdr S&P Biotech Etf (PCQ:XBI) rally recently and a spate of competitive M&A big pahrma activity markets naturally aren't too keep on non profitable us pharma currently.And they will need more money somehow obviously.Could be an interesting punt but has some major controlling shareholders on the list.Although very risky and extremely expensive needing deep pools of liquidity, US markets do really reward the few pharma companies that produce great trial results for novel drugs that have the potential to be future blockbusters early on and some are even bought out then.Morphic Holding (NMQ:MORF) ended 2023 with $704.3 million in cash and equivalents; cash runway into second half of 2027 however.C4X Discovery Holdings (LON:C4XD) now have a much better balance sheet lately, however not sure if it's enough to totally fund a phase 1 trial alone currently.Perhaps they think it is and with good clinical results a Nasdaq listing would definitely be possible.
Renold (LON:RNO) - amidst a sea of blood red- there is a speck of blue. c2% rise as I write. Oversold IMO, I hold.
Some factors that might help understand current market movements:
Thank you Turbo
I wasn't sure why the market had spat its dummy out this morning. Capricious as usual, I am sure that very little has changed with the companies I invest in between yesterday's close and today. Hey ho!
In a land far far away .........
Some nut jobs in Tatooine ................
Attacked the Iron Dome.
The markets - "edgy they seem"
- but agree what the hell - as Ed maybe said 'best not to look too much at the news'.
Ashtead Technology Holdings (LON:AT.)
The first testing moment for shareholders. Yes I think the share price had got ahead of itself and mammoth expectations were going to be extremely difficult to be met. But if you believe these levels of ROCE and growth and runway ahead of it are all there for years to come (which I do) then it's tin hats on and hunker down time.
Fanciful thinking maybe, but I'm hoping this can continue to multi bag over the next 10/15 years like its parent company Ashtead or a Games Workshop or a Judges Scientific...never easy to hold on through these moments, just got to show some belief and nerves of steel.
Good luck to holders.
Ashtead Technology Holdings (LON:AT.) This is my largest holding, although it might not be by the end of the day! However, I remain optimistic regarding the future as they have plenty of growth to go for as you alluded to. The prospective P/E before today was 20 so it's perhaps not surprising they've taken a hit today after what looks like a miss on profits. I think what will be key is to see what the brokers pencil in for next year; currently, Stocko is showing eps for FY2024 of 37.1p. Ideally, I wouldn't want to see this reduced but we'll just have to wait and see. For what it's worth I'm not selling as I managed to buy at a lower price and so have a decent buffer.
Sosandar (LON:SOS) seems to be delivering on its strategy so far, though there’s a long way to go.
Revenue of £46.3m, up 9% year-on-year (FY23: £42.5m)
·
Improved gross margin of 57.6% (up from 56.1% in FY23) reflecting the planned reduction in certain price promotional activity ahead of a selective store roll out in the UK
·
As a result of a substantial positive swing in PBT from H1 (£1.3m loss) to an expected profit of £1.1m in H2, FY24 will be broadly in line with market expectations* with a marginal loss of £0.2m expected to be reported for the year overall
·
Strong cash generation in H2, resulting in an improved net cash position of £8.3m as at 31 March 2024 (£7.7m as at 31 December 2023)
·
Post year-end, April trading has been strong with continued improvement in profitability driven in particular by gross margin
But Sosandar (LON:SOS) PBT in H2 last year was £1.5m? So despite a good amount of revenue growth (+12% in H2), it looks like a reversal in profitability?
(this is me just looking at the headline levels in Stocko income report and the RNS today, without digging deeper into adjustments, store investment cost, etc)
Paul & Graham, any thoughts on Sosandar (LON:SOS) trading update today would be much appreciated.
I think it reads well. Improvement in H2 in terms of margins versus H1 meaning they'll manage to meet expectations, along with increasing cash balance during H2 that means "[physical store] rollout will be delivered entirely from our existing financial resources" .
Anyone have any views to why Ashtead Tech has dropped this morning, results look good to me
Paul/Graham, I see its a very busy day but if you get a chance to comment on #AT. over the next few days it would be appreciated
Consistently been ahead and rallied as if there was going to be another one. In line so people likely people taking profits and people shorting on the open anticipating people taking profits.
Ashtead Technology Holdings (LON:AT.) ... the share price outpaced exorbitant sales and profit expectations and has now fallen back. It is a long term hold for me and if I had some spare cash, I would be topping up.
VP (LON:VP.) - a total of zero shares traded in the first hour after today’s TU - since upgraded to a paltry 87 units. Now, there’s a calm reaction!
It shouldn't be listed. Take it private VP (LON:VP.)
Morning all. Full year results snapshot for Team17 (LON:TM17). As expected the operational issues within their Games Label ruined profits for the year. However they have been sorting out the issues with a restructuring effort underway. They are re-focussing on Indie games, which they have proven they are great at and have been cutting costs.
Revenue growth has been pretty decent and well above the industry average of 3%. They just need to return to profitability. Guidance for next year was in line, which looking at Stocko numbers is a reduction in revenue from this year. I expect this is due to re-focussing and cancelling certain projects, hopefully leaving the profitable ones.
I hold, so am biased, but I think the worst is behind for them.
Team17 (LON:TM17) (I hold too)
Thanks Phil - I haven't had a chance to go through the results in lots of detail but I broadly agree, seems like the worst is behind them, and they've taken the opportunity to wipe the slate clean and get the really quite considerable uglies out with the transition to the new CEO (looks like a whopping £32m impairment!?!)
People really seemed to really like Debbie Bestwick but I' m not sad to see her go. During her time the company was hit with some high profile complaints about the work culture and the acquisitions have been a mixed bag (putting it lightly, given the impairment going through the accounts, Games Label getting into a big mess and high profile community complaints about the direction of Hell Let Loose post-pricey acquisition.) Unfortunately, the calibre of the new guy is yet to be seen given his marketing / non-games company background.
I'm a little nervous about the 'return' to focusing on Indie games. In practice I'm not really sure what that means as I'm not aware of them releasing particularly large games this year. The biggest failure I'm aware of was Gord (released in Aug 2023) but still looked quite indie-ish to me. I also think competition is just as fierce at the lower end of the scale. I guess more games at lower cost-per-game skews the odds in the company's favour vs fewer, bigger bets. Could also be an acknowledgement that HLL hasn't gone fully to plan.
I do think the uglies today highlight the perils of investing in companies which capitalise so much development spend for it to pass through at a later date. It's complicated. Note 8 on amortisation and impairment is hefty. I think it's important to resist the feeling of 'thank god that's out the way, the bad decisions are in the past and they've learned from them.' There's every chance the upcoming games end up being unpopular - we have to trust that management is developing the right games, which isn't an easy task!
Thanks for your comments Jacxx, I agree with almost everything you've said. I'm unsure about the CEO change though as yet, Debbie Bestwick was one of the founders of the company & I think it is always a little risky when a founder takes a back seat. Time will tell though & hopefully the business will move onwards & upwards.
I think you're right with Hell Let Loose, I'm sure that game hasn't met expectations post acquisition. Maybe they had plans or ambitions to develop or publish some larger games as well, that they've now shelved. This line makes me think they were maybe looking at some larger games,
“Most notably, the Games Label has re-focussed back to its core Indie games roots, resulting in changes to games scouting and increased rigour around development spend. ”
I do think Indie games are lower risk, considering the time & financial input larger games take. Especially as Indie games can still sell huge numbers if they mange to break through, take Dredge for example. There's certainly plenty of risk in the game development industry & never any guarantee of a successful game.
I too am a shareholder, for the long term. I think the business has gone through a rough patch and I would hope is now on the other side of that. I hope to see the next two financial statements show their profit margins back to their historic levels. I am still accumulating.
Does anyone have any thoughts on Alphawave IP (LON:AWE) news today?
Looks like a bit of an odd reaction to Alphawave IP (LON:AWE) statement
2023 was a bit below - about 7% by looks of things but 2024 has started ahead of expectations. 2025 is guided at around $100m EBITDA so an $800m market cap looks an anomaly compared to similar US businesses.
Market has been saying it wants them out of China ever since they listed - now they are the market is punishing that too!!!
When I looked at this first thing I thought a 5-10% decline - 30% seems overdone to me.
We’re at different points here, David. I might be missing something - perhaps there are adjustments I have not taken into consideration- so do please set me straight, but I marked this down 35% on the TU.
FY24 fc EBITDA 109m is now explicitly 70m, FY25 fc EBITDA is reduced from 151m to 99m taking a prudent midpoint on the margin. 30% down is pretty generous!
Then one needs to consider the risk inherent in the huge disparity between the company’s EBITDA “bullshit profits” and its genuine PBT. When I look at the accounts of obvious comparator Synopsys (NSQ:SNPS, which I own, there is only a very small discrepancy between EBITDA and PBT. I have a rule of thumb which dictates that the larger the discrepancy between these two measures, the greater the discount that the shares should carry. Certainly at yesterday’s undisturbed price, that discount was nowhere near adequate, and despite today’s fall, with these brutal cuts in forecasts, I still don’t see a margin of safety.
The tech apparently is good, however, so maybe one day the company will lift off.
I agree, I think today's announcement was a bit of a shocker given they 'confirmed' FY23 forecasts as recently as 22 January 2024.
Positives
Negatives
Alphawave IP (LON:AWE)
Looks like a bit of an odd reaction to Alphawave IP (LON:AWE) statement
Huh todays statement is shocking - they have dropped top line estimates of sales ye 31/12/2023 by $37 mill today - 3.5 months after the end of the year and they still have spread of $15 mill and are providing only approximate numbers .
Based on their prior accounting woes they are showing they are a complete micky mouse outfit ref info they provide to investors - why were prior lessons not learnt ?
this company has been complete fluff from day 1 - if they are making decent actual profits thay are making every effort to mae it look like they are cluless and just providing stuff on the fly.
they appointed new CFO last October - i would have thought his number one priority would be to avoid a situation like has happened today - note it is reasonably clear he was dropped in at the deep end - his job though was to do it properly not wrong like how it was before.
#AWE Alphawave Semi historically has always said they are in-line, in-line throughout the year but then they drop a clanger at the year end to say they are behind and have missed their numbers. Not impressed and I've been a holder (now very tiny position) for years.
Added to that, the story has changed a number of times, and I think you have a picture of a company that maybe one day will be worth many times its current value if they end up with a product in heavy demand by the hyperscalers, but until then there is no visibility from a private investor point of view with a record of not-hitting their numbers.
They are blaming the miss and the forward guidance reduction on exiting China but surely they should have reflected this in the guidance 6-12 months ago.
I will exit my remaining tiny position once the SP recovers somewhat on the run up to the next results, not today.
Alphawave IP (LON:AWE) only back in January, there was a bullish update: http://newsfile.refinitiv.com/...
they did mention China but everything else seemed to be soaring, now 3 months later, this. Directors were buying lots of shares last year, not sold any. Do they know what is going on?
There was a problem last September, shares fell about 20%, l was not holding then.
Management credibility is fairly low now. Can we believe their forecasts anymore?
I don't hold, have been put off by the high PER. The miss seems fairly modest, but then growth companies can't afford to miss targets. The update mentions a jump in borrowings, but not the reason. Still, the price is looking a bit more reasonable.
Following the potential takeover of T Clarke I am interested in others thoughts on other possible takeover targets in the uk markets?
Tclarke (LON:CTO) Take over by Regent 160p + div if you hold, tempted to take the cash after the SAA fell through
Proactive Investors with one of the most apt typos of the year so far. Superdry (LON:SDRY) .
re Hostmore (LON:MORE) announcement today. You have quite an interesting situation into Q3/4 2024.
I would expect that the relationship agreement between TriArtisan and MFP Partners and TGI to be rather important. This will determine when they can sell down and on completion you will likely get some sort of cash exit. So thinking aloud and at the risk of triggering an awful deja vous .... completion will result in a much larger company and a likely share offer. It will also mean the issue of a circular and a pro forma business strategy for the combined group.
May I suggest this is likely to dwell on combined strengths and a path to value creation. Clearly we have some very successful franchise business models, not least Intercontinental Hotels (LON:IHG) and whilst I would not dream of comparing the two in terms of quality....we do have a road map ... for pushing towards asset light - royalty strong. The prize is obvious since asset light earnings multiples are much higher.
Being an optimistic equity investor by nature I am going to guess this business will be nicely primed to look as positive as possible in terms of FCF come completion. And the pitch will all be about sustainable growth in FCF in an asset light - capital light fashion....why... to try and improve the EBITDA rating from v low.... to better. This has the potential to disproportionately improve the price of Hostmore (LON:MORE) and since the existing rating is so low.... adverse trading developments are already reflected. The combined equity will be in the can't ignore category for small cap fund managers.
The biggest risk now is that the deal falls flat on its face for some reason - putting fizz back in the coke is the least of my concerns.
Equals (LON:EQLS) I hold
2023 finals announced which look impressive to my eye. Summarised by the CEO
"The advances the Group made in its offering, combined with improved Sales and Marketing capabilities, meant the Group significantly surpassed our expectations in the year, delivering the following strong headline financial performance:
· Transactions executed on the Group's platforms increased by 35% to £12.4 billion (FY-2022: £9.2 billion)
· Revenue increased by 37% to £95.7 million (FY-2022: £69.7 million)
· Adjusted EBITDA increased by 70% to £20.6 million (FY-2022: £12.1 million)"
and
"H1 FY-2024 Trading update
· Revenue in H1-2024 up to 12 April 2024 reached £31.9 million, up from £24.5 million in the same period in 2023, an increase of 30%
· The revenue from Solutions in the same period was £13.2 million, up 74% on the same period in 2023 of £7.6 million
· Revenues per working day up to 12 April 2024 were £443k, an increase of 27% over £350k per day in Q1-2023 and 5% higher than £422k per day achieved in Q4-2023
· Cash balances of £21.6 million as at 12 April 2024"
No word on the outcome of the long running Strategic Review which has been extended already.
Would appreciate coverage by Paul or Graham.
Equals Info on about revenue per employee and movement in cash would help here? (I sold EQLS, I hold ALPH)
Iirc there was a comment about revs per employee and they expect that to increase further this year.
We expect headcount to remain broadly stable at current levels in 2024. Accordingly, although revenue per head increased to £281k from £260k in the prior year, we would expect a further increase in 2024 given the investments we have made and the increased Target Addressable Market.
Equals (LON:EQLS)
Sorry not sure how to edit posts. further thoughts on Equals (LON:EQLS).
EMEU (Equals Europe), which could be a huge growth driver, only contributed 1.7m of revs in 2023 as it appears to have become operational towards the end of 23 ("Equals Money Europe - integration work completed on time to bring EMEU into operational status with local IBAN capability by the end of 2023").
Trading in '24 up to 12th April are 7.4m ahead of last year so just adding this onto the 23 revs gives 95.7 + 7.4 = 103.1m for FY24 assuming no more growth.
This would seem disingenuous and Equals also state that "In addition, headcount increased by the expansion via acquisition into Europe via EMEU, completed in July 2023, which will contribute to revenues more strongly in 2024."
FY24 Forecasts are 112m so it seems to me that this doesn't include allowance for EMEU and therefore potential for large upward revision (or not) depending on the adoption of EMEU.
Nice to see the positive start continue (and even slightly rise) with revs 28% higher to 15th March and then 30% higher to 12th April.
Also, not to forget solutions is powering forward and gross margins increased to 55% from 48%. If they continue at this growth the 95.7m revs turn to 124m in FY24.
I'm a holder. My slight gripe would be the lack of commentary on Europe Money (in the TU and results). The rest of the business is clearly doing well but perhaps EMEU is slower to build up and that's where another partner could help - who knows just my musings.
Editing can be done, up to 60 minutes, after you post it. At the bottom of your post, you should see a pen/pencil, click on that and you should be in edit. Not sure if that works on mobile phones.
Editing works on phones with large enough screens, if you turn them to landscape. Doesn’t work on tiny ones like my iPhone SE.
Paul can you look at Dr Martens (LON:DOCS) . Well in scvr territory now getting on for 90% down from float price! It was stupidly overvalued at some £6bn I remember, how did they get away with it
Still not sure it's good value - I interviewed there in 2022 and they couldn't even organise a piss up in a brewery, took 5 months for across several interviews that kept getting delayed or moved for them to decide on the job, dodged that bullet!
Positive trading updates from two of my very small starting position holdings today.
Cyanconnode Holdings (LON:CYAN) who have issued a “Revenue expected to materially exceed market expectations” statement. They are heavily involved in the roll out of smart meters in India and orders seem to be increasing fast. The company has also received orders from Thailand recently. This company was first brought to my attention by Gervais Williams.
The second was Sulnox (OFEX:SNOX) which issued the following statements in their trading update.
“· Unaudited Q4 revenues of £314,995, up 201% on Q3 (£104,572) and up 282% vs Q4 2023 (£82,546), continue the trend of improving revenues and another record trading quarter, driven by expanding marine sales and associated third party emission monitoring equipment (£85,934), as well as new and repeat sales in Asia.
· Unaudited full year to 31st March 2024 revenues were £555,290, almost triple the previous year (£203,061).
· Q1 has also started positively, with committed sales of c. £105k and a strong revenue pipeline as repeat orders are placed for Ghana and marine evaluations continue to grow in both number and wider usage across fleets.
· Unaudited year end cash balance of £2.15 million.”
I first came across this company at Mello and the interest here now has moved away from their initial focus on petrol and diesel in cars and lorries to shipping where there is a big demand for the reduction in emissions. They have trials ongoing with several shipping companies with large fleets.
Neither suitable for widows and orphans but both with interesting growth markets.
I think Sulnox will be returning to present this new strategy and other plans at our Mello conference next month. Still a few early bird tickets left Stockopedia | Mello2024 conference...22nd and 23rd May | By carmensfella
Sulnox (OFEX:SNOX) is likely to get properly launched in the shipping business because orders will come in small numbers of high value. Quite apart from reduction in emissions the claimed reduction in consumption can justify the costs on its own. Their success to date suggest the industry's tests support both the economy and pollution saving claims.
Similarly with land vehicles. The advent of E10 unleaded will do some damage to lots of engines over time (especially the older ones not designed to cope) is a good opportunity. I use the petrol additive. I haven't measured the claimed reduction in mpg (I live in London so it is hard to do objectively) but the car does seen to run more smoothly after a few tank-fills with the additive.
I hold the stock and hope to have the opportunity to speaking with them at Mello 2024.
Next 15 (LON:NFG) Solid results to YE 31 Jan 2024, with decent profit before tax of £80.3m, a good PE if they can keep around this level going forward.
Next 15 Group plc (AIM:NFG), the tech and data-driven growth consultancy, today announces its final results for the year ended 31 January 2024.
Financial results for the year to 31 January 2024
Year ended 31
January 2024
£m
Year ended 31
January 2023
£m
% change year on year
Adjusted results1
Net revenue
577.8
563.8
2.5%
Adjusted operating profit
121.1
114.2
6.1%
Adjusted operating profit margin
21.0%
20.2%
Adjusted profit before tax
117.9
112.5
4.8%
Adjusted diluted earnings per share (p)
81.6p
80.4p
1.5%
Statutory results
Net cash generated from operations
105.0
95.2
10.3%
Revenue
734.7
720.5
2.0%
Operating profit
77.1
67.2
14.7%
Profit before tax
80.3
10.1
Diluted earnings per share (p)
50.3p
1.5p
Gattaca plc (LON:GATC) Most recruiters have recently reported slow markets given economic uncertainty , particularly in perm , so no surprise in Gattaca’s outlook today. But their cash is nearly ¾ of mkt cap and even on reduced outlook for next year there is decent growth .
New research note here: https://www.equitydevelopment....
Hopefully some good news on Wednesday:
"UK Is Beating US on Inflation Fight And May Cut Rates Sooner
Britain is starting to rein in inflation at a quicker pace than the US, underscoring a divergence between the two economies that may allow the Bank of England to move sooner on cutting interest rates than the US Federal Reserve.
Official figures due out this week in the UK are likely to show that the Consumer Prices Index eased further in March while unemployment picked up as the nation starts to shake off a recession, a survey of economists shows. The US by contrast just reported an unexpected rise in inflation and a falling jobless rate, with the economy getting stronger."
Source: Bloomberg https://www.bloomberg.com/news...
Will cutting interest rates sooner than the us not lead to a weakening in the pound hence pushing inflation back up?
The exchange rate effect is very small. The interest rate effect is large.
1% drop in the ftse 100 to start the day
Porvair (LON:PRV)
Encouraging AGM statement, trading well with destocking in laboratory markets easing and lead times normalising.
Bens Stocks, CEO has indicated his intention to retire in 2025, it will be interesting to see who his successor is.
I attended the AGM and there was a quiet confidence emanating from Chairman, CEO and FD. The dreaded "second half weighting" is likely to be appropriate in their case, not least because of spares order in the Industrial division for gasification projects carried out some years ago. These spares orders are sporadic but lumpy when they do occur, and margin historically very good. Ben Stocks will want to leave on a high, and in my view this could be a very good year after ordinary looking H1, but always dyor.
Porvair (LON:PRV) I wonder why the sudden drop in share price, just after the AGM finished. Can buy now for 608p.
Tatton Asset Management (LON:TAM) - "AUM up 30% in FY24, record flows, forecasts raised"
AUM jumped £3.8bn or +30% in FY24, reaching £16.6bn on 31 Mar 24, 12% above our previous forecast of £14.7bn. Including 50%-owned 8AM Global, Assets Under Influence hit £17.6bn. Investment performance provided a tailwind, adding £1.5bn to AUM. But our key takeaway from Tatton’s hugely impressive last few years, is that it has designed and implemented a superior offering in platform-MPS with net flows consistently far higher than peers. That leadership looks even more pronounced in H2-24 with net flows of £1.4bn v £0.9bn in H1.
Forecasts increase on the jump in AUM, although Tatton has flagged that flows were elevated in H2 and unlikely to continue at quite the same level. Our fundamental value rises to 620p per share (prev. 580p). We will re-visit forecasts in June with final results and when Tatton presents an updated strategic growth target. We also flag growing trading volumes/interest in TAM shares.
Link to research: https://www.equitydevelopment....
VP (LON:VP.) "Resilient FY24, confident long-term outlook" (new research note) - Vp’s full year update highlights sector-leading results, once again benefiting from the diversity of its end markets and the quality of its specialist businesses.
With results expected to be broadly in line with expectations, we trim our FY24 PBT forecast by c.5% to £39.0m, a shade below the FY23 outturn (£40.2m). We consider this an impressively resilient performance set against a mixed market backdrop.
Under new leadership, a strategic refresh is underway and management is confident in long term prospects. In our view, the valuation is compelling (FY25E P/E of c7x). We reiterate our Fair Value estimate of 1090p per share.
Link to research report: https://www.equitydevelopment.co.uk/research/resilient-fy24-confident-long-term-outlook
Paul, any chance of you getting round to Norcros which I saw was on your list to catch up on yesterday?
Hi - just in case it's of interest / useful, we published a note on Norcros last week following their update: https://www.equitydevelopment....
thanks
Henry Boot (LON:BOOT) - interesting new deal announced today - selling near 500 homes to a Barratt subsidiary - should hopefully perk up the shares.
agreed. do you have any idea of value of near 500 plots. wonder why they didn't mention value, or indeed any value above book? they say it was 15% p.a. return - i don't see Boot as a quick flip company so this i'm assuming they have held for a long time. so then my question is how much have they re- valued? any thoughts? disc i hold
Can I extend a thank you to the reader on here who in late January/early February suggested to Paul to give up coffee to help with gastric reflux. I've been a long time sufferer, on medication for life and had surgery in 2013 yet still suffer.
I gave up coffee and the improvement is very noticeable. I clear my throat a lot less frequently and I no longer have coughing fits. (Very helpful for my spouse who struggles with the sound of me clearing my throat). Also, I feel less tired and sleep better even though I only used to drink caffeinated coffee before lunchtime, maybe 2-3 cups a day.
Whilst I wouldn't say I'm addicted I really do like the taste of coffee and miss it.
Hi Wildshot, that was me in response to Paul having trouble on his podcast. I'm so glad my little life hack helped you and it sounds like Paul's problem has reduced too. I've put a link to my post HERE, the main gist of which was drink more water instead of caffeinated drinks and alcohol. I've just checked the link and it just gets to the start of the page so control F and find my name.
Thanks Samsgrandad, after your prompt I drink a lot more water now, and it definitely helps, especially a pint of water with a Vit C tablet in it first thing every morning. We're all turning into old gits now aren't we LOL! ;-)
You're welcome Paul. I'm planning to live to 95 and die at the hand of a jealous husband so I have to keep everything in working order. So far, so good lol.
I suffered terribly too, partly due to a hiatus hernia. I’ve cured it and gone back to 3 real coffees a day, morning only (I gave up coffee for a year).
How? I don’t drink much booze. Alcohol no more than once a week, either draft beer or wine with added water. One pint or one/two glasses. I now dislike alcohol, when I used to love it, although I do like a pint.
I also strengthen tummy and muscles with moderate exercise, and try to follow a roughly Zoe compliant diet. End of problem.
I'm hoping you or Graham will find time to look at the seemingly ungenerous offer for T Clarke Paul. We're long time, twice round holders, rescued this time by Regent Acquisitions who've spotted value where investors haven't. Approx 28% premium to the 3 month price is hardly exciting but you've both pointed out it's management first, shareholders second habits.
Billington
Superb results .
I don’t hold but always look lovingly at it as it’s a steel manufacturer in Barnsley doing very well . Steel is real .
63m market cap
Circa 38m assets . 20 ish million cash and 13 million PBT .
Exceptional results with 50% growth.
If these results continue it’s a cash machine company that is ver undervalued .
.Rating looks wrong Be interesting if the market reacts accordingly .
Billington Holdings (LON:BILN)
Yes, very impressive results, slightly ahead of expectations.
PBT up an impressive 131% and EPS up 115% to 84.4.
Dividend of 33p, including special dividend of 20p.
No more debt and cash almost doubled.
The outlook across all segments positive, although they do flag a slow down in structural steel of about 5% for 2024, but growth resuming in 2026, but I interpret this as being at the industry level, not Billington specific.
The order books are at record levels and 2024 and 2025 revenue underpinned by recent 90m contract.
Also, there is lots of focus on improving efficiency to increase margins.
There is an investor meets company presentation later.
The only negative with this one is the low volume and high spread.
Also, very high director ownership is positive.
As a Stocksbridge lad this makes me happy
As a Donny lad, makes me happy too
Planetx - Be careful with the headline results on Billington Holdings (LON:BILN) : I seem to recall there is some one off trading that is not expected to repeat next year so I seem to remember that whilst the EPS for year just gone is 84p+ it is forecast to be back to around the 40p+ for next year. Still a decent growth but not quite the headline you might be expecting.
Doesn’t make it not cheap of course but something to check out.
Anyone still in XP Factory (LON:XPF)? - seems like good news today, 2 X holdings RNS - MFT Capital are out 14% of the company - they were a deferred consideration shares for the original acquisition of Boom Battle Bars in Nov 2021.
BGF capital are in with 13.5% of the company, hopefully getting rid of this overhang xpf will finally reach the bottom.
They look like a good ii to have on board
https://www.bgf.co.uk/about/
I think XP Factory (LON:XPF) did superbly well to expand their Boom Battle Bar estate in 2022.
But the estate has been largely in its current form since the end of 2022 and there is still no sign of meaningful profits or cash flow, either in historic numbers or forecasts. Central overheads and loss making sites seem to wipe out whatever profits the successful sites make.
For me, this is a wait and see stock.
Wow, MFT really crystallised a huge loss!
The SP was like 30p-35p in Nov21. Now sold out at below 13p. Even if they're not actively involved in the business now, the former owners have more "inside" knowledge of how BBB works...
Presume the sale wasn't due to lock-up expiring (should have expired long time ago?) so they have actively chosen to crystallise their loss in XP Factory (LON:XPF) at this share price.
EDIT: went to find the lock-up period, it was "The Consideration Shares are expected to be issued during the first half of 2023 and will be subject to a customary lock-in until 15 July 2023." so yeah, they've actively decided now is the right time to sell out...
Hostmore reversing into TGI Fridays !
Very interesting move with Hostmore the franchisee seemingly buying the licensor .
Looks a very smart deal although somewhat engineered.
Results in solution but instead of running restaurants and making 1980s burgers with flat coke and greasy chips they seemingly become the brand owner getting a nice royalty and someone else makes the overpriced overrated and out of date food .
On paper looks very interesting .
The issue is yet again you are dealing with a company and owners who have a bad history fir financial engineering and s who have previously shoved their tosh right up PI and borderline sold their trash in a nicely packaged up “special situation” with the Electra / hotters / TGI sham that was nothing more than a pump and dump of crap companies by a private equity group of greedy investors ditching their dross onto us .
That was a lesson for all of us at the peak of the bull run where we naturally fell hook line and sinker for it .
Whilst I think the Hostmore move looks very good I think we can be certain advisors and management will be getting big fees and looking after themselves, and maybe the likes of MILLS and Harwood will be having a piece of the cherry pie too .
I’d avoid .
And ultimately the food is still crap .
Buried in the detail of the Hostmore statement was the nugget that TGI fridays US corporate store revenue for Q1 was -23% LFL ! , so no wonder they are willing to sell for an attractive multiple of last year's EBITDA. It really looks like a brand on the verge of extinction, every franchise owner must be questioning why they are paying a big royalty
The issue is yet again you are dealing with a company and owners who have a bad history fir financial engineering and s who have previously shoved their tosh right up PI and borderline sold their trash in a nicely packaged up “special situation” with the Electra / hotters / TGI sham that was nothing more than a pump and dump of crap companies by a private equity group of greedy investors ditching their dross onto us .
Apologies but this comment isn't accurate. Electra Plc was a quoted private equity trust. The majority of the assets were sold at a premium to book resulting in a significant increase ( near 100%) increase in the share price. They failed to sell Hotters and TGI ....and therefore these assets were de-merged to Electra Plc shareholders. We then entered the Covid - post covid world. Your comments re Mills / Harwood are equally strange.
At a minimum, existing Hostmore (LON:MORE) shareholders seem to be getting a good deal. A principal concern with TGI UK has always been the restrictive nature of the brand agreement which will be absorbed in this deal. Those shareholders who have held on look like they will own a business with scope for a better future. Clearly both business need some love and not without issues... which is how we have arrived at the deal. On the face of it, as someone who has held on (and averaged down) I think it's a reasonable outcome.
The big risk is trading for the remainder of the year and as a Hostmore (LON:MORE) shareholder you now own less of the UK business which would appear to be doing better. Although you get a greater share of profit it does not come without risk. As an offset the Ch. Stephen Welker remains in place and a significant shareholder. The management appointments suggest no dramatic change of course just a change in financials. The issue of refinancing the debt for Hostmore (LON:MORE) would appear to have been put to bed.
For those that saw little point in selling the last 10% of a holding now have a route out which may be more fruitful. The opposite of a heavily discounted fund raise.
I think “they failed to sell Hotters and TGI”
So they engineering it into a special situation and dumped it onto a frothy stock market with some camouflaged narrative as opposed to “no one will buy these two dogs so you can have them cheap “.
I’m sure a better investor that all of us on here has said
”Private Equity Firms Are Typically Very Dishonest. .
The point you repeatedly miss is they didn't sell anything to anyone, the holders of Electra owned two assets - they were separated and given to shareholders.... it was already trading on the Stockmarket and therefore not dumped on anyone. The market valued it not private equity as you suggest. These two assets were less than 10% of the original portfolio that had risen 100% and cash returned from 2017. So for many long term Electra holders they were given a piece of paper likely 5% of their original in cost....and so even though it didn't work out, it was a rounding error.
None of this matters one jot today though. The important question is what the shares do from here. I completely understand why anyone doesn't want to commit fresh capital but it will be a very different prospect come Q3/4 .... and so you have to ponder if this is an interesting entry point. That is after all the name of the game. At the very least I suggest for holders, that small piece of paper in the bottom draw might be worth more than they think.
hi planetx
I think “they failed to sell Hotters and TGI”
So they engineering it into a special situation and dumped it onto a frothy stock market with some camouflaged narrative as opposed to “no one will buy these two dogs so you can have them cheap “.
That is exactly what happened.
A good friend of mine worked on a restructuring deal for Hotters prior to the de-merger. His opinion of the company at that time was very much in line with your 'dog' description.
Snazzy
Hi Paul,
would very much appreciate if you could review the annual numbers from Ashtead Technology Holdings (LON:AT.) this morning.
Outlook statement:
"Within oil and gas, 2023 has seen a 61% increase in offshore greenfield sanctioning committed capex compared to the average of the previous five years, with many of the projects being sanctioned in Norway and South America. Years of under investment in both existing and new developments have caught up with the industry. As a source of reliable energy, the offshore hydrocarbon industry will remain a key contributor to global oil and gas production under all probable energy transition scenarios, with continued investment in this industry being critical to supporting the demand for energy. Subsea expenditure will play a significant part in this market, with Rystad Energy forecasting Ashtead Technology's addressable market within the subsea oil and gas space to increase at a healthy 7% CAGR from 2023 to 2027.
It is therefore no surprise that offshore contractors are continuing to report increasing backlogs which have more than doubled since 2020. Whilst Ashtead Technology is not a backlog business, the backlogs of our customer base give us confidence in an increasing demand for our services for years to come.
The requirement for energy production from offshore sources is significant and is set to remain so for the foreseeable future, and the fungibility of Ashtead Technology's equipment and solutions across both the offshore wind and oil and gas markets makes for a compelling and robust proposition, enabling the Group to capture growth opportunities across both adjacent markets globally."
https://www.stockopedia.com/sh...
On the face of it, looks very good? (I hold)
many thanks!
Ashtead Technology Holdings (LON:AT.) looks good but the market does not like something, shares down to 649p. Now recovering.
Ashtead Technology Holdings (LON:AT.) Looks like they came up short on earnings: Stocko is showing forecast eps of 29.7 but today they announced eps of 27 (if I've read it correctly?)
I think all the "adjusted" figures are not helping. Possibly expectations were also quite inflated. One or two may have also decided to take profits first thing after an extended strong run in the recent past. Hard to know, but for now the "market has spoken" as they say ... difficult game this! :-)
Ashtead Technology Holdings (LON:AT.) Looks like they came up short on earnings: Stocko is showing forecast eps of 29.7 but today they announced eps of 27 (if I've read it correctly?)
Yes, but markets typically react more to the outlook than to the past performance. On this, the report was a little vague but not discouraging. My take is that the shares had risen so far above the levels reached at the last update that they”d simply got too far ahead of themselves and today’s fall is a rational deflating of the balloon.
Ashtead Technology Holdings (LON:AT.) I was heartened by steadily improving margins. They have increased Capex to £19M, and the headcount has gone up 25%. They are laying the foundations for further growth. This could lead to further progress going forwards, but of course it’s contingent on demand continuing to increase.
Fortunately, there are other firms in the sector to read across from.
Sigmaroc (LON:SRC)
Sigmaroc is one of my bigger holdings so I may be biased but a casual look at the stock can result in not appreciating what it really offers. Paul mentioned this when covering the AGM trading update last week saying he has not looked in detail. Another poster added that SRC have diluted shareholders and taken on a lot of debt. I’m posting this to emphasise that perhaps it’s worth taking the time to do more research before jumping to conclusions.
Yes, they have taken on a lot of debt but that’s because they had a once in a lifetime opportunity to corner the European market for lime and limestone. These two minerals are not only essential to many of our most needed products and food production, but they are almost certainly going to be in higher demand going forward. Why ? Because the increasing need to become carbon neutral or carbon negative requires lime. It’s “once in a lifetime” simply because CRH decided they wanted to dispose of assets regarded as non-core and those assets were exactly what SRC needed to create the scale to dominated their market.
I think SRC are a very progressive company with a management team that is an early adopter of beneficial technologies. Example - they installed Aqualung carbon capture equipment at a processing plant that allows them to recycle the carbon they have captured as carbon dioxide gas which has commercial value. Ultimately, they expect to be able to capture 100% of carbon emissions. See
https://carboncaptureworld.com/sigmarocs-first-carbon-capture-facility-launched-at-nordkalks-koping-site
Also the JV with ArcelorMittal to develop Europe’s first fully net-zero CO2 quicklime production for use in steel production and other applications, documented here
https://www.sigmaroc.com/case-study/creating-net-zero-lime
They pioneered a low carbon building product called Greenblock in 2021 which provides specifiers with a number of “green” products for construction. See https://www.sigmaroc.com/ventures/greenbloc
Most people may be surprised to learn that lime and limestone are not only natural carbon sinks but are also used in everyday life to provide products and services we need. Lime is a fundamental material to many industries and processes. For instance, lime is required to produce milk, purified water, paint, paper, metals, asphalt and more. Most people probably know that lime is used in agriculture to sweeten acid soils so that crops can be grown and to increase land usage, but how many know that glass manufacture and sugar production need lime? For a more comprehensive explanation of how this material is used see information on this web page
https://www.sigmaroc.com/lime-for-life
In short, there’s a lot more to SRC than meets the eye. If you are interested in finding out more, please take the time to dispel any preconceived ideas you may have.
Sigmaroc (LON:SRC)
Cannot but agree. As mentioned last week when replying to Paul one has to back the management team under Max Vermoken, that I have met on at least two occasions. They are very forward thinking and entrepreneurial. If they successfully integrate the CRH acquisitions, which I believe they will, the resulting free cash flow will enable a rapid reduction of the debt taken on to fund them.